



Automotive Steering Wheel Switch Market: The Real Drivers Behind 7.25% CAGR Growth Through 2032

The Automotive Steering Wheel Switch Market: Strategic Shifts and Commercial Opportunities
Market Overview and Core Challenges
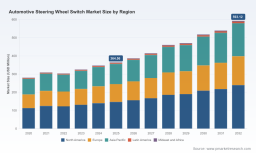
The automotive steering wheel switch market has transitioned from a mature, incremental product category into a strategically critical component of vehicle human-machine interface design. Valued at approximately $280.45 million in 2020, the market demonstrated steady historical growth, reaching $364.56 million by 2025. Forward projections indicate continued expansion through 2032, with the sector expected to surpass $590 million by the end of the forecast window. This trajectory reflects a compound annual growth rate of roughly 7.25 percent, signaling that steering wheel controls are no longer peripheral appendages but integral elements of modern vehicle architecture and driver interaction design.
Despite the favorable growth baseline, the industry faces structural inflection points that demand strategic recalibration. First, the rapid migration toward software-defined vehicles and automated driving functions is redefining what a steering wheel switch must accomplish. Traditional mechanical or single-function inputs are increasingly inadequate for managing complex feature sets, calibration routines, and real-time vehicle status information. Suppliers must now deliver interfaces that balance driver comfort, safety compliance, and digital integration without compromising tactile ergonomics or physical reliability.
Second, automotive electrification and shifting segment priorities are altering volume patterns across legacy and next-generation platforms. As internal combustion vehicle production volumes gradually stabilize or decline in key markets, the absolute addressable volume for conventional switch assemblies faces pressure. At the same time, electric vehicle architectures and autonomous-capable platforms require more sophisticated control clusters, creating a bifurcated demand landscape where volume growth depends on capturing advanced-interface orders rather than maintaining status-quo replacement rates.
Third, cost inflation and component integration complexity are reshaping margin structures. The addition of electronic sensing elements, haptic actuators, and integrated lighting modules into steering wheel assemblies has elevated material and labor costs, particularly in the aftermarket and replacement segments. Suppliers that rely on commoditized tactile switch designs are encountering price compression, while those capable of delivering multi-modal, software-updatable interfaces can preserve differentiation and pricing power. The net effect is a narrowing window for undifferentiated participation and a stronger premium for integration capability, validation rigor, and platform scalability.
Key Growth Drivers
Technological Innovation and Interface Evolution
The most decisive driver reshaping the market is the convergence of advanced sensing, haptics, and integrated electronics within the steering wheel itself. Touch sensor-based architectures now represent the dominant share of total market value, reflecting a broad industry preference for multi-function controls that reduce physical button clutter while enabling software-configurable layouts. This shift is not merely aesthetic. It reflects a deeper engineering requirement: steering wheel interfaces must support richer command sets for driver assistance features, infotainment management, vehicle personalization, and driving-mode selection without overwhelming the driver or compromising safety-critical tactile feedback.
Membrane Switch Market
Recent product and platform developments underscore this trajectory. In mid-2025, a modular control interface platform for steering wheel buttons was introduced, allowing customizable layouts and functionalities across vehicle models. This approach directly addresses OEM demand for scalable HMI design that can be reused across segments while accommodating regional or model-specific requirements. By early 2026, a foldable steering wheel concept featuring integrated controls and switches for autonomous driving applications was publicly unveiled, signaling that even form-factor innovation is being explored to accommodate different operational modes and cabin configurations. These developments illustrate that interface platforms are becoming modular, software-oriented, and increasingly adaptable to changing vehicle use cases.
Policy, Safety, and Regulatory Dynamics
Regulatory and safety expectations are becoming more influential in steering wheel switch design, particularly as automated functions and driver-monitoring systems gain prominence. The industry is observing a stronger emphasis on production-ready systems that can serve diverse vehicle segments, from urban passenger cars to luxury SUVs, while meeting evolving expectations for driver input reliability. Steer-by-wire architectures, for example, are moving into series production with modular designs intended to span multiple vehicle classes. This transition matters for switch suppliers because it reduces dependence on traditional mechanical linkage assumptions and opens the door to electronic control schemes that must meet stringent functional safety requirements.
At the same time, autonomous-oriented applications are pushing safety-critical controls to the forefront of design priorities. Foldable steering wheel concepts and advanced control layouts are being developed with driver input systems in mind, aligning with evolving ISO and broader regulatory expectations for systems that must remain usable, legible, and fail-safe under different driving modes. For suppliers, this environment rewards designs that can demonstrate compliance robustness, test repeatability, and clear differentiation between convenience controls and safety-relevant inputs.
Demand-Side Change and HMI Expectations
Consumer and enterprise expectations are increasingly centered on intuitive, adaptive, and personalized interfaces. In electric vehicles and software-defined vehicles, drivers expect continuous access to vehicle status, driving settings, driver assistance features, and media functions without excessive menu navigation. This behavior is fueling demand for multifunctional steering wheel switches that combine tactile reliability with electronic configurability. The trend is particularly pronounced where AI-integrated HMI concepts and biometric controls are being explored, as these applications require more nuanced input pathways and richer feedback loops than legacy switch designs can support.
The commercial implication is clear: vehicles that offer more coherent, customizable, and context-aware steering wheel interfaces are better positioned to support premium positioning, feature differentiation, and user retention. As a result, OEMs are increasingly treating steering wheel controls as part of a broader experience architecture rather than as isolated component purchases. This elevates the strategic importance of suppliers that can deliver integrated solutions rather than discrete switch assemblies.
Supply Chain and Cost Structure Realignment
Cost dynamics are becoming a strategic variable rather than a simple procurement concern. The integration of electronic components into functional switches has raised material and labor costs in certain segments, especially where replacement and aftermarket demands require more complex assemblies. At the same time, the broader industry has seen increased merger and acquisition activity among HMI suppliers, reflecting a push to consolidate engineering capabilities, accelerate platform development, and strengthen relationships with global OEMs. This consolidation pattern suggests that scale, cross-platform reuse, and integration depth are becoming more valuable than narrow component-level competition.
Suppliers are therefore facing a dual pressure: they must absorb higher engineering and validation costs associated with advanced interface designs while also demonstrating cost-efficient platform strategies that can be deployed across multiple vehicle models. The firms best positioned to navigate this tension are those that can reuse core architectures, standardize electronic submodules, and maintain flexible customization options without incurring prohibitive engineering duplication.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a relatively concentrated group of experienced suppliers, each pursuing different aspects of interface integration, tactile quality, and platform scalability. Concentration levels indicate that the top three participants account for roughly 27.5 percent of market revenue, while the top five reach approximately 35.8 percent. This structure suggests a market where incumbency, engineering heritage, and OEM trust still matter enormously, but where differentiation is increasingly tied to platform flexibility and next-generation HMI readiness.
Preh GmbH has built its position around multifunctional steering wheel switches with long-standing supplier relationships and a focus on customizable multi-function controls. Its strategic advantage lies in proven repeatability and the ability to serve established vehicle programs with configurable switch solutions that balance function density and manufacturability. Marquardt GmbH emphasizes precise, safe, and customizable switch designs with tactile feedback, paddles, and electronic controls suited to modern HMI needs. Its differentiation centers on control feel and reliability, which remain critical in safety-conscious vehicle programs where driver confidence in physical inputs is non-negotiable.
Automotive Steering Wheel Adjustment Motor Market
ZF Friedrichshafen AG approaches the segment through broader steering system integration, offering advanced switches and controls embedded within steering wheel systems, including capacitive HMI elements and steer-by-wire-compatible buttons. This positions the company to benefit directly from architecture changes that blur the line between steering hardware and interface electronics. Autoliv Inc. brings a safety-centered perspective, manufacturing steering wheels with integrated electrical controls, vibration motors, and functional switches for safety systems. Its recent focus on foldable steering wheel concepts for autonomous applications demonstrates a willingness to explore structural redesigns when safety and mode-dependent usability demand it.
Toyoda Gosei Co., Ltd. and DENSO Corporation add additional depth from the Japanese supply base. Toyoda Gosei develops steering wheel systems that combine switches, vibrating units, and grip sensors with ADAS compatibility and multifunction controls, aligning interface design with driver monitoring and assistance integration. DENSO contributes ergonomic switch modules and steering controls with tactile feedback intended for infotainment, driver assistance, and vehicle settings, reflecting a practical emphasis on usability across daily driving functions. These profiles show a market where multiple suppliers are pursuing overlapping but distinct value propositions.
The strategic evolution of the competitive landscape appears to be moving in three directions. First, integration is intensifying, as suppliers seek to offer complete steering wheel interface systems rather than isolated switch components. Second, platformization is accelerating, with modular architectures enabling faster customization and broader reuse across vehicle lines. Third, consolidation activity is increasing, suggesting that scale, cross-domain engineering, and the ability to serve global OEM programs are becoming more important for long-term positioning. New entrants face a steep challenge unless they bring a clearly differentiated technology, a compelling cost model, or specialized expertise in areas such as haptic feedback, sensor fusion, or autonomous-mode interface design.
Future Trends and Commercial Implications
Over the next three to five years, one major trend is likely to be the expansion of configurable, software-oriented steering wheel interfaces as a standard expectation rather than a premium option. As modular control platforms mature and OEMs seek to streamline development across model lines, suppliers that can deliver reliable base architectures with customizable overlays will be better positioned to capture recurring program wins. The commercial opportunity here lies in reducing per-program engineering duplication while preserving enough flexibility to accommodate regional preferences, segment requirements, and model-specific feature sets.
A second trend will be deeper integration between steering wheel controls and broader vehicle intelligence, including driver assistance functions, biometric inputs, and adaptive HMI behavior. This creates opportunities for suppliers that can combine tactile switch performance with sensing, feedback, and software integration in a coherent package. The challenge is that such integration raises validation complexity and can increase development risk, particularly where safety-critical functionality and convenience features must coexist without confusion. Firms that invest early in test frameworks, interface standards, and safety-aligned design processes are more likely to convert these opportunities into durable program positions.
A third trend is the continued shift toward multifunctional designs in electric and software-defined vehicle platforms, where interface density, personalization, and mode-dependent behavior matter more than in legacy applications. This shift favors suppliers capable of supporting higher content per wheel while managing cost and weight constraints. At the same time, it introduces uncertainty: if regulatory expectations change, if autonomous functionality adoption timelines shift, or if OEMs reassess feature content in response to pricing pressure, demand for high-complexity switch systems could moderate in some segments. Market participants should therefore treat advanced interface capabilities as a strategic asset, but not as a guarantee of uniform volume growth across all vehicle categories.
Taken together, these trends suggest that the most resilient commercial opportunities will belong to suppliers and investors who can align platform scalability with safety-aligned innovation. The market is unlikely to reward pure volume playbooks based on legacy switch designs. Instead, value creation will increasingly depend on the ability to provide integrated, adaptable, and compliance-robust steering wheel control solutions that can evolve as vehicle architectures and driver expectations continue to change.
PW Consulting Automotive & Machinery Research Center
Strategic Recommendations for Decision Makers
For Manufacturers and Technology Suppliers
Prioritize platform reuse and modular design strategies that allow rapid customization without duplicating core engineering effort. The most defensible position will come from offering a stable base architecture that can support multiple vehicle programs while accommodating differentiated layouts, feedback profiles, and electronic features. Equally important is strengthening validation and safety-aligned development processes, especially where capacitive inputs, steer-by-wire compatibility, or autonomous-mode controls are involved. Suppliers that can demonstrate repeatable compliance performance and lower integration risk will have an advantage in competitive OEM sourcing decisions.
For Investors and Strategic Buyers
Focus on suppliers with credible platform roadmaps, expanding integration capabilities, and evidence of cross-OEM flexibility rather than dependence on a narrow product niche. M&A activity is already intensifying among HMI suppliers, indicating that consolidation can accelerate platform development and broaden customer access. When evaluating opportunities, look for companies that can convert advanced interface concepts into manufacturable, cost-efficient solutions at scale. Technologies that appear promising in demonstration phases must ultimately prove their ability to support high-volume production, field reliability, and reasonable rework exposure before they can be considered durable investment themes.
For Procurement and OEM Strategy Teams
Treat steering wheel switch selection as a strategic HMI decision rather than a commodity sourcing exercise. Evaluate suppliers on the basis of platform longevity, customization capacity, tactile and safety performance, and the ability to support future feature expansion without full redesigns. Where possible, favor architectures that can accommodate evolving software-defined vehicle requirements and mode-dependent use cases, because these reduce the risk of future interface obsolescence. In parallel, monitor cost structures carefully, since rising electronic content and integration complexity can affect total lifecycle cost if aftermarket serviceability and replacement feasibility are not considered early in the design phase.
For decision makers seeking deeper segmentation data, detailed company profiles, and tailored scenario analysis across regions, vehicle types, and application categories, the full PW Consulting research report provides the additional granularity needed to translate these trends into specific program, investment, and sourcing decisions.
For detailed analysis of this topic, please visit the official page: Automotive Steering Wheel Switch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


