



HVDC Transmission System Market: Why 6.98% CAGR and Asia Pacific's 11.26M Lead 2026-2032 Growth

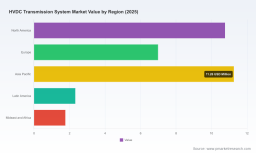
High-Voltage Direct Current Transmission: Strategic Shifts and Commercial Opportunities in a Decarbonizing Grid
The global high-voltage direct current (HVDC) transmission system market is navigating a period of structural expansion, driven by the accelerating need to move renewable energy across long distances and to interconnect increasingly complex power grids. With total market revenue reaching approximately USD 33.11 billion in 2025 and a projected compound annual growth rate of 6.98 percent through 2032, the sector is transitioning from a niche utility technology to a backbone infrastructure category. Historical growth from 2020 to 2025 reflects a steady climb from the low twenty-billion-dollar range to today’s scale, while the forecast window to 2032 points toward a market approaching the mid-fifty-billion-dollar mark. This trajectory is not simply a story of more projects; it reflects a fundamental rethinking of how electricity is generated, transmitted, and consumed in an era of variable renewables, digitalization, and tightening reliability expectations.
Yet scale alone does not guarantee smooth execution. The market is entering a phase where technology maturity, regulatory predictability, and supply chain resilience will separate winners from stragglers. Understanding the forces reshaping HVDC transmission requires looking past headline figures and examining the operational, commercial, and strategic dynamics that will determine which organizations capture value in the decade ahead.
Market Snapshot and the Challenges Defining the Next Phase
The current market environment is characterized by expanding project pipelines, a broadening geographic footprint, and an increasing mix of application types. HVDC is no longer confined to a single use case; it is being deployed for long-distance bulk power movement, cross-border and interregional interconnections, offshore wind integration, and city-center power infeed. The revenue base is growing steadily, and the forecast period suggests that growth will continue at a pace that outpaces many traditional transmission technology segments. Importantly, the market remains moderately concentrated, with the three largest players holding a combined share near 48.5 percent and the five largest close to 62.3 percent. This concentration indicates that scale, technological breadth, and project execution capability still matter enormously, but it also leaves meaningful room for specialized players and regional champions to compete on differentiated strengths.
Several challenges are shaping the pace and economics of HVDC deployment. First, the sector is contending with a transition from conventional line-commutated converter architectures toward voltage-source converter technologies in more applications, alongside the continued use of both platforms where each is best suited. This dual-technology landscape creates engineering complexity, procurement complexity, and differing cost structures. Second, project developers and system integrators are facing heightened scrutiny on grid stability, fault management, and control coordination as HVDC links are embedded into meshed and increasingly digitalized networks. Third, the execution environment is being tested by supply chain bottlenecks, particularly around assembled circuit breakers and other specialized components that are critical to HVDC converter stations and substation integration. These constraints can cascade into schedule risk and cost escalation if not managed with long lead-time planning and strategic sourcing.
A further challenge lies in balancing transmission ambition with regulatory and permitting realism. HVDC projects often span jurisdictions, involve multiple stakeholders, and require coordinated standards for planning, documentation, and interoperability. As transmission portfolios expand, the ability to align technical specifications with regulatory frameworks becomes a commercial differentiator, not just a compliance exercise. In this context, the market’s next phase will be defined less by raw demand and more by the quality of execution, the clarity of standards, and the resilience of supply chains.
Core Drivers Reshaping HVDC Transmission
Technology Innovation and the VSC-LCC Balance
Technology differentiation remains one of the most powerful forces in the HVDC market. Voltage-source converter systems have expanded the practical application envelope for HVDC by enabling tighter control of power flow, faster response characteristics, and improved integration with renewable generation and weak grids. At the same time, line-commutated converter systems continue to serve specific long-distance and bulk-power scenarios where their architecture offers compelling efficiency and scale characteristics. The result is a market in which technology choice is increasingly application-specific rather than universal.
Recent project activity illustrates how this technological balance is playing out in real deployments. Major HVDC contracts are being awarded for large transmission corridors that combine scale with reliability requirements, while parallel developments in converter hardware, control systems, and protective devices are pushing the performance envelope for both offshore and onshore links. The movement of large-scale HVDC transformer equipment across continents also signals the growing physical scale of individual project components, with implications for logistics, factory capacity, and localized support networks. These technology dynamics are not abstract; they determine which suppliers can respond quickly to complex specifications and which can deliver consistent performance across multiple project phases.
Policy and Regulatory Clarity as a Commercial Accelerant
Regulatory and standards development is becoming a meaningful driver of market confidence. As HVDC systems are planned across wider geographic and institutional boundaries, the availability of planning recommendations and documentation guidance helps reduce ambiguity for developers, equipment suppliers, and utilities. Standardized approaches to system planning can compress pre-development timelines, improve interoperability expectations, and support more predictable procurement processes.
At the same time, large-scale procurement signaling is shaping the commercial environment. Significant orders for high-voltage equipment across multiple vendors indicate that utilities and transmission developers are committing to capacity expansion at a scale that affects the entire value chain. This kind of demand signaling matters because it influences factory planning, component sourcing, and service capacity. When procurement commitments are visible and sustained, suppliers can invest with greater confidence; when they are fragmented or delayed, execution risk rises. Policy frameworks that support transmission expansion, interconnection, and renewable integration therefore act as a force multiplier for market growth, but only when they are accompanied by administrative processes that can convert ambition into contracted projects.
Demand-Side Shifts: Renewable Integration, Interconnection, and New Load Centers
Demand for HVDC is being reshaped by changes on both the supply and load sides of the grid. On the generation side, the continued build-out of renewable capacity is reinforcing the need for long-distance transmission and interconnection that can move power from resource-rich areas to load centers with lower curtailment and higher reliability. Offshore wind, in particular, remains a strong application driver for submarine and offshore HVDC links, while onshore renewable zones continue to stimulate bulk transmission requirements.
On the load side, the emergence of concentrated electricity demand in urban centers and the growing power requirements of digital infrastructure are adding new dimensions to transmission planning. City-center infeed projects demonstrate how HVDC can deliver large amounts of power into densely populated areas with reduced footprint and improved control compared with alternative approaches. At the same time, data center and AI-related load growth is prompting fresh attention to transmission capacity, reliability, and proximity to reliable generation. These demand-side shifts do not simply increase volume; they change the shape of the market by expanding the range of use cases and raising the importance of compact, controllable, and resilient transmission solutions.
Supply Chain, Cost Structure, and the Copper Equation
Cost and supply chain dynamics are increasingly central to commercial decision-making. HVDC cable costs are closely linked to the affordability of copper, and while demand trends have not exerted a disproportionate effect on regional copper requirements, diverging cost trajectories can still influence project economics and procurement timing. In practice, this means that cable and conductor sourcing strategies need to account for both material cost volatility and the lead-time realities of specialized manufacturing.
Electric Power Transmission Equipment Market
Beyond materials, assembled circuit breakers and other converter station components have emerged as a critical supply chain constraint in HVDC transmission projects. These are not commodity items; they require specialized assembly, testing, and integration. When such components become a bottleneck, the impact can ripple through project schedules, commissioning plans, and overall system availability. As a result, organizations that can secure reliable component supply, align factory capacity with project pipelines, and reducesingle points of failure in their sourcing strategy are gaining a tangible execution advantage. Cost competitiveness in HVDC is therefore increasingly about total project execution, not just sticker price.
Competitive Landscape: Positioning, Differentiation, and the Shape of Change
The HVDC market is contested by a mix of global technology leaders, cable and link specialists, and regional players with strong local execution capabilities. This diversity is healthy, but it also means that competitive advantage is increasingly defined by the ability to combine technology breadth, project delivery, and service capability in ways that match specific customer and application needs.
Among the most prominent participants, several strategic patterns stand out. Some suppliers emphasize symmetric monopole and bipole configurations for point-to-point, multi-terminal, and back-to-back applications, positioning themselves around flexible architecture choices and proven transmission platforms. Others differentiate through dual technology portfolios that span voltage-source and line-commutated converter systems, paired with advanced control and protection solutions for interconnections, offshore wind, and city-center infeed. This dual-platform approach allows such suppliers to match technology to application rather than forcing a single solution across all scenarios.
A distinct group of players focuses on converter technology and voltage-source converter systems for long-distance bulk power transmission and offshore applications. Their value proposition often centers on proprietary converter platforms, application-specific engineering, and accumulated project references in demanding environments. Meanwhile, utilities and transmission developers benefit from suppliers offering customized converter solutions with substantial installed capacity, since proven track record and global service reach can reduce perceived execution risk on large contracts.
The cable and link segment adds another layer of competition. Manufacturers of HVDC submarine and land cables, including complete transmission links, compete on cable design, manufacturing scale, and the ability to support subsea and overhead applications across transmission systems. Others specialize in dynamic subsea solutions for offshore wind and floating platforms, reflecting the growing complexity of maritime energy infrastructure. In this segment, differentiation often comes from materials expertise, production capacity, and the ability to integrate cable supply with broader transmission project delivery.
Regional dynamics are also shaping the field. Some suppliers are concentrating on HVDC solutions for energy superhighways and AI data center power infrastructure, aligning technology offerings with emerging demand patterns in their home markets and export opportunities. Others provide full converter station and transmission system solutions, often with strong positions in large domestic project markets and expanding international footprints. Equipment manufacturers delivering converter stations and HVDC hardware contribute additional scale and specialization, especially where local content expectations, service proximity, and cost competitiveness intersect.
Recent developments underscore how competitive positioning is being reinforced through execution. Large-scale city-center infeed projects have demonstrated the ability to deliver power to tens of millions of people, reinforcing the commercial case for HVDC in dense urban environments. At the same time, high-profile delivery milestones involving large HVDC transformer equipment have highlighted the logistical and manufacturing scale required to support major projects. Exhibition activity and product lineup showcasing also signal the importance of ecosystem engagement, where suppliers seek to present end-to-end capabilities rather than isolated components. In parallel, major contract awards for multi-gigawatt transmission corridors illustrate how competitive selection processes are concentrating value in the hands of suppliers that can combine technology, scale, and delivery confidence.
Looking at the market structure, the concentration level suggests that scale players will continue to hold significant influence, but the presence of multiple capable specialists indicates room for differentiation. The likely evolution is not a simple wave of consolidation, but a more nuanced pattern in which strategic partnerships, selective expansion, and capability bundling become more important than pure headcount or headline revenue. New entrants and regional specialists can still compete if they bring a strong fit with local demand, specialized cable or converter expertise, or differentiated service and financing models. However, they will need to navigate the same supply chain constraints and standards expectations as larger players, which raises the bar for execution discipline.
Forward Trends: The Next Three to Five Years
Trend 1: Application Diversification Will Redefine the Value Pool
Over the next few years, HVDC is likely to deepen its presence across a wider range of applications rather than simply adding more of the same project type. Long-distance transmission and interconnection will remain central, but city-center infeed, offshore integration, and demand-responsive transmission planning will continue to gain relative importance. This diversification matters commercially because it changes the winning capability set. Suppliers and developers that can tailor solutions to different technical and spatial constraints will be better positioned to capture value than those relying on a single platform or a narrow application focus.
The opportunity here is not only in equipment sales but in system-level value creation: planning support, control integration, commissioning, and long-term service. As use cases broaden, the ability to offer credible answers across multiple scenarios becomes a growth lever. The risk, however, is that application diversity can strain organizations that lack engineering flexibility or service depth, especially when each application imposes different performance, footprint, and reliability requirements.
PW Consulting
Trend 2: Standards, Planning, and Procurement Visibility Will Determine Execution Speed
A second trend is the growing importance of planning guidance, documentation practices, and procurement signaling in shaping project velocity. As HVDC systems are planned more systematically and equipment orders reach larger scales, the clarity of standards and the predictability of demand will influence how quickly suppliers can commit capacity and how efficiently developers can move from concept to contract. This is a practical commercial dynamic: when planning frameworks and procurement pipelines are visible, both sides can invest with greater confidence.
For businesses, this trend points to a need for stronger engagement in pre-development stages, more rigorous alignment on technical specifications, and earlier coordination with regulatory and standards processes. Organizations that contribute to planning credibility and demonstrate consistent documentation and interoperability practices are likely to earn trust that translates into competitive advantage. The uncertainty lies in the pace at which administrative and regulatory processes can keep up with technical ambition, particularly where multi-jurisdiction coordination is required.
Worldwide High Voltage System Market
Trend 3: Supply Chain Resilience Will Become a Strategic Differentiator
The third trend is the elevation of supply chain resilience from an operational concern to a strategic one. With assembled circuit breakers and other specialized components acting as critical constraints, and with material cost dynamics influencing cable economics, the ability to manage long lead items, factory capacity, and logistics will increasingly separate reliable delivery from costly delays. This is especially true for multi-gigawatt projects and large-scale converter station builds, where component availability can shape the entire program timeline.
Commercial opportunities will accrue to organizations that design resilient sourcing strategies, secure capacity commitments, and reduce exposure to single points of failure. At the same time, there is risk in over-reliance on narrow supplier bases or in underestimating the lead-time implications of specialized hardware. In the coming years, supply chain planning will be as commercially significant as technology selection for many HVDC programs.
Actionable Guidance for Decision-Makers
For manufacturers and technology providers, the priority is to align product portfolios with the application mix that is actually expanding, while simultaneously hardening supply chains for the components that most frequently constrain delivery. This means investing in converter technology breadth where it adds differentiation, but also treating cable, breaker, and transformer logistics as strategic capabilities rather than backend procurement tasks. Firms that can demonstrate credible execution across multiple applications, with clear standards alignment and service readiness, will be better placed to compete for large, complex programs.
For investors, the strategic signal is that growth will be real but unevenly distributed across applications, geographies, and business models. Projects that combine renewable integration, interconnection, and concentrated urban or data center demand are likely to offer stronger momentum than undifferentiated capacity expansion alone. In evaluating exposure, it is worth focusing on organizations with demonstrated technology fit, execution track record, and the ability to manage specialized supply chains. Valuations and return profiles will increasingly reflect execution quality and pipeline visibility, not just market-level growth.
For procurement teams and utilities, the imperative is to move earlier and deeper in technical coordination. Selecting HVDC solutions should be treated as a long-cycle partnership decision, where standards compatibility, documentation clarity, component availability, and service coverage influence total cost and schedule reliability as much as initial pricing. Early engagement with planning frameworks and multi-vendor coordination can reduce later friction, especially for large equipment packages and multi-terminal architectures. Procurement strategies that account for lead-time risk and material cost dynamics will be more resilient than those optimized on short-term price alone.
For organizations navigating this market, the most valuable intelligence is the kind that ties technology trends, regulatory signals, procurement activity, and supply chain constraints together into a usable operating picture. Segment-level detail, regional deployment patterns, and company-specific capability profiles can materially improve strategic timing and resource allocation. Comprehensive research that breaks down these layers in depth can help decision-makers move from broad market confidence to specific, well-supported action.
The HVDC transmission market is entering a phase where growth is supported by powerful structural drivers, but value capture will depend on precision: the right technology for the right application, the right standards alignment for the right jurisdictions, and the right supply chain resilience for the right project timeline. In that environment, the ability to read the market with granularity is not a luxury; it is a competitive necessity.
For detailed analysis of this topic, please visit the official page: HVDC Transmission System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


