



LED Strip Market 2032: Why a 9.6% CAGR Redefines the $11B Industry Strategy

The LED Strip Market: Strategic Trends and Commercial Opportunities Through 2032
The global LED strip market has entered a phase of sustained expansion, with total revenue reaching approximately $5.8 billion in 2025 and projected to approach $11 billion by 2032. The sector is expected to grow at a compound annual growth rate of 9.6 percent across the 2026 to 2032 forecast horizon, reflecting a combination of architectural modernization, smart home adoption, and industrial lighting upgrades. While the headline figures convey momentum, the operational realities behind them matter more to decision makers. Growth is uneven across applications, product architectures, and geographies, and the competitive landscape is shifting from volume-driven commoditization toward specification-driven differentiation. Understanding where value will accrue over the next several years requires a closer look at the forces shaping demand, the strategic moves of leading players, and the structural constraints that will test execution.
Market Snapshot and the Crossroads Ahead
A Market Accelerating but Not Uniformly
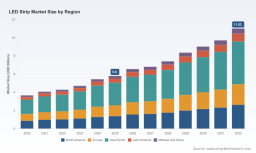
The trajectory from 2020 through 2025 shows a steady climb, with revenue moving from roughly $3.67 billion to $5.8 billion. The acceleration reflects post-pandemic construction activity, broader retrofit programs, and the rapid normalization of addressable lighting in both homes and commercial spaces. Projections through 2032 indicate continued upward movement, with the market surpassing $9 billion before the end of the decade and reaching $11.02 billion in 2032. This pace is notable, yet it masks divergent growth paths. Certain application segments, particularly industrial and automotive, are expanding on the back of interior customization, indicator lighting, and electrification-driven design cycles, while residential and commercial demand is shaped by renovation waves, aesthetic expectations, and energy efficiency mandates. The implication is that aggregate growth should not be mistaken for uniform opportunity; specification quality, channel access, and compliance readiness will determine which participants capture disproportionate value.
Three Structural Challenges Shaping Strategy
The first challenge is cost pressure tied to raw materials. Copper input costs rose by more than 36 percent in 2025, a move that directly affects conductor pricing in LED strip circuit boards and has already produced downstream consequences, including increased theft of copper components from installed or warehoused inventory. For manufacturers and distributors, this translates into margin compression and the need to revisit bill-of-materials design, supplier diversification, and inventory hedging. For buyers, it introduces greater price variability and a stronger incentive to lock in specifications early.
The second challenge is regulatory tightening around hazardous substances and safety certification. Three RoHS exemptions for lead in copper alloys, ceramics, and glass glazes are scheduled to expire on July 21, 2026, which will require supply chain adjustments across substrate, solder, and coating choices for LED strip producers. In parallel, UL certification remains a critical requirement for LED strips sold in the United States, and compliance is increasingly a baseline expectation rather than a differentiator. These requirements raise the cost of reformulation and testing, but they also create a moat for companies that can manage conformance at scale and a barrier for those that rely on loosely controlled sourcing.
The third challenge is the rising bar for optical performance in high-end applications. Color rendering index values of 90 or above, combined with a standard deviation of color matching below 3, are becoming standard expectations for specification-grade projects where color accuracy and consistency matter. Meeting these thresholds consistently across batches requires tighter process control, better binning, and more disciplined quality assurance. The market is therefore splitting between low-cost, general-purpose offerings and higher-specification products that command more stable margins and more defensible customer relationships.
Forces Reshaping Demand and Supply
Smart and Aesthetic Lighting as a Demand Catalyst
Consumer and commercial demand is increasingly driven by lighting that does more than illuminate. In residential settings, users want seamless color transitions, music synchronization, and integration into broader home automation ecosystems. In commercial spaces, facility owners and designers are prioritizing uniform appearance, tunable color, and control flexibility that supports both ambiance and energy management. This shift is visible in recent product launches that emphasize gradient effects, outdoor-rated formats, and AI-assisted scene creation, signaling that the value proposition is moving from hardware alone to experience and interoperability. For businesses, this means product roadmaps and channel strategies need to account for software, app ecosystems, and compatibility as core elements of the offering rather than add-ons.
Regulatory and Standards Pressure as a Strategic Variable
Standards and regulations are becoming a more active force in product strategy. The approaching expiration of the RoHS exemptions for lead in specific materials will require reformulation and supplier revalidation for many manufacturers, especially those with narrow supply bases or limited testing capacity. At the same time, safety certification expectations in the U.S. market continue to reinforce UL compliance as a gatekeeper for commercial sales. On the performance side, the expectation that premium applications meet CRI 90+ and SDCM under 3 raises the stakes for color consistency. Companies that invest early in compliant material strategies, robust certification processes, and tighter color control will be better positioned to win specification work and reduce the risk of late-cycle redesigns.
Supply Chain and Cost Dynamics
Beyond raw material volatility, the supply chain for LED strips is being reshaped by the need for higher density, better thermal management, and more consistent output. COB and high-density flexible architectures are gaining attention because they support smoother visual appearance and more controlled luminance, but they also place new demands on component sourcing and assembly precision. The broader effect is a move toward more selective sourcing and greater emphasis on reliability metrics such as energy efficiency, thermal performance, and documented certification. For large-volume buyers, this environment favors suppliers with transparent quality systems and stable lead times, while for smaller buyers it increases the importance of specification clarity to avoid performance drift across projects.
Competitive Landscape and Strategic Positioning
Premium Smart Ecosystems
Philips Hue continues to focus on premium smart LED strips with gradient, outdoor, and integrated home automation capabilities for decorative and architectural use. Its approach emphasizes ecosystem fit, brand trust, and design-sensitive applications where appearance and interoperability matter as much as raw output. Recent activity, including the launch of Flux gradient and Neon outdoor LED strips with staggered availability across Europe and the United States, suggests a continued push into higher-aesthetic and outdoor segments. The strategic value here lies in building recurring engagement through control platforms and use cases that extend beyond initial installation.
LED Display Market
Professional and Modular Systems
LEDVANCE is oriented toward professional and custom LED strip systems, combining drivers, profiles, and modular solutions for commercial, architectural, and industrial projects. Its participation in Light + Building 2026, with a focus on office, education, sports, and industry applications, underscores a strategy centered on specification-driven projects and system-level integration. In this space, differentiation comes from complete installation-ready solutions, predictable performance, and support for complex environments where design intent must be maintained across large surfaces or demanding operational conditions.
PW Consulting
Consumer-Facing Smart Entertainment Lighting
Govee is targeting the home decor and entertainment segment with smart RGBIC and COB LED strips, app-based control, music synchronization, and high-density seamless lighting. Its recent activity, including the introduction of Lumiblend+ color accuracy technology and an AI lighting bot at CES 2026, points to a clear emphasis on user experience, color quality, and software-driven functionality. This model competes on convenience, visual impact, and rapid feature iteration, appealing to users who prioritize immersive effects and easy setup over professional specification workflows.
LED Lighting Market
Performance and Specification-Grade Portfolios
OSRAM concentrates on high-performance LED strips and modules for automotive interior lighting, aftermarket, and entertainment applications, leveraging engineering credibility and application-specific performance. HitLights emphasizes premium high-density COB and linear LED strips with UL listing, energy efficiency, and professional-grade output for commercial and residential projects, aligning closely with specification requirements and safety compliance. Flexfire LEDs focuses on custom high-quality flexible LED strips and accessories for installers and DIY users, with an emphasis on durability and performance, and has recently moved toward strategic price reductions and bulk pricing programs to support project growth. Super Bright LEDs maintains a broad portfolio spanning flexible, color-changing, and COB options for commercial, industrial, and residential use, positioning around breadth and accessibility across multiple end markets.
How the Landscape Is Evolving
The market is showing both consolidation of value and fragmentation of positioning. On one side, leading players are sharpening their identities around ecosystem control, professional system integration, color performance, and compliance readiness. On the other, new entrants and established players alike are experimenting with smart features, COB architectures, and price-oriented programs to capture specific buyer segments. One recent signal is Flexfire LEDs’ announcement of strategic price reductions and a new bulk pricing program in early 2026, which illustrates how competitive intensity can push companies to adjust pricing structures to support project-scale demand. At the same time, the requirement for stronger color accuracy, safety certification, and material compliance is raising the floor for credible participation in higher-value segments. The net effect is a market in which winners are increasingly defined by the ability to combine performance consistency with the right commercial model for each application.
Three Trends Likely to Define the Next 3 to 5 Years
Performance Standards as the New Baseline
The expectation that high-end LED strip applications meet CRI 90+ and SDCM below 3 is likely to become more widespread, extending from premium architectural and retail settings into broader commercial specifications. As this standard diffuses, product portfolios that cannot consistently deliver tight color consistency will face pressure on price and reputation. The commercial opportunity lies in building repeatable binning, quality control, and documentation that allow suppliers to win repeatable specification work and reduce project risk for distributors and installers. The risk is that the performance bar keeps rising faster than process maturity in some segments, creating gaps between marketing claims and field performance.
Smart, Integrated, and Experience-Led Lighting
Over the next several years, LED strip solutions are likely to be judged increasingly on their integration into broader control ecosystems and their ability to deliver programmable, context-aware experiences. Features such as gradient effects, outdoor-rated formats, music or scene synchronization, and AI-assisted lighting control are moving from novelty to expectation in many consumer and light commercial scenarios. This shift opens opportunities for companies that can combine hardware quality with software value, interoperability, and easy post-installation management. The downside is that feature competition can compress margins if differentiation becomes superficial, so sustainable advantage will depend on reliability, compatibility breadth, and genuine use-case fit rather than feature count alone.
Compliance and Material Realignment as a Strategic Filter
The July 2026 expiration of the RoHS exemptions for lead in copper alloys, ceramics, and glass glazes will push manufacturers to adjust material choices and validate alternatives across the supply chain. Combined with the continued importance of UL compliance in the U.S. market and ongoing raw material volatility, this creates a period in which compliance readiness and sourcing resilience will separate scalable operators from more exposed ones. Businesses that proactively recalibrate formulations, certify changes early, and diversify critical inputs will be better placed to protect margins and avoid disruptions. The uncertainty lies in how quickly alternative materials can be qualified without compromising performance or cost, and whether broader commodity swings will intensify pressure on already tight supply chains.
What Decision Makers Should Do Now
For Manufacturers and Brand Builders
Product strategy should be anchored to performance credibility and compliance readiness rather than volume alone. That means prioritizing color consistency, documented safety certification, and material compliance roadmaps that anticipate the 2026 RoHS changes, while also deciding where to compete on ecosystem integration versus specification-grade reliability. Pricing strategy deserves equal attention: recent moves toward bulk pricing and strategic reductions suggest that project-scale demand will reward flexible commercial models, but those models should be built on cost structures that can absorb raw material volatility without eroding trust in specifications.
For Investors and Capital Allocators
The strongest value creation is likely to come from companies that can hold a defensible position in higher-specification segments while managing compliance and material risk efficiently. Look for evidence of tight quality control, certified product lines, and a clear narrative around the application mix, especially exposure to industrial, automotive, and professional commercial segments where performance requirements support more stable pricing. At the same time, monitor smart lighting players for signs that software, interoperability, and user experience are translating into durable engagement rather than one-time hardware sales. Raw material exposure, certification status, and channel strength are all useful filters for separating durable operators from those vulnerable to cost shocks and specification drift.
For Procurement and Channel Leaders
Specification clarity and compliance documentation should be treated as procurement essentials. Demand consistent performance data, certification evidence, and transparent material sourcing, especially when projects require CRI 90+ and tight color matching. Where possible, diversify approved suppliers across regions and product architectures to reduce exposure to single-source risk and copper-driven cost swings. For larger programs, early alignment on compliance timelines and bulk pricing structures can reduce uncertainty and protect project margins.
The LED strip market is expanding at a meaningful pace, but the attractive opportunities are concentrated in segments where performance, compliance, and user experience are becoming non-negotiable. Companies that align product development, sourcing, and commercial models with these shifts will be better positioned to capture durable demand through 2032, while those that rely on undifferentiated volume may face intensifying pressure from both cost dynamics and rising specification expectations. The full landscape is broader than any single product category or competitive move suggests, and the most useful next step is a detailed look at segment-level demand patterns, regional nuances, and the specific compliance and performance thresholds now shaping win conditions across applications.
For detailed analysis of this topic, please visit the official page: LED Strip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


