



Strain Gage Market 2026: Unpacking the 4.55% CAGR and $316.6M Growth Path to 2032

Navigating the Strain Gage Market: Strategic Trends and Commercial Opportunities Through 2032
The global strain gage market has entered a phase of steady, investment-backed expansion. From a base of approximately USD 163.15 million in 2020, the sector climbed to USD 230.12 million by 2025 and is projected to reach USD 316.6 million by 2032. This trajectory reflects a compound annual growth rate of roughly 4.55 percent, a pace that underscores consistent demand across industrial, aerospace, and automotive applications. For executives and strategic planning teams, the market presents a familiar pattern: mature technology platforms coexisting with incremental but meaningful shifts in application requirements, regulatory expectations, and integration models. The real question is no longer whether the market will grow, but where value will concentrate and which capabilities will separate profitable participants from marginal ones.
Market Landscape and Core Challenges
The current market structure reflects a combination of industrial modernization, infrastructure monitoring mandates, and the ongoing digitization of physical systems. Strain gages remain foundational measurement tools for stress analysis, load monitoring, and structural health assessment. Their presence across aerospace testing, automotive validation, and industrial manufacturing means that procurement cycles are tied to broader capital expenditure patterns, engineering program timelines, and compliance-driven testing requirements. Market growth during the historical window from 2020 to 2025 was supported by recovery in industrial production, expanded testing requirements, and renewed attention to structural integrity in critical infrastructure. The forecast period from 2026 to 2032 extends this trajectory, with the market expected to move toward the mid-300 million range as demand becomes more application-specific and more closely integrated with upstream system design.
Despite the clear expansion path, several operational and strategic challenges shape how participants compete. First, standardization and qualification requirements are tightening. Updated measurement standards for strain-based geotechnical and structural monitoring have introduced clearer expectations for installation practices, traceability, and data reliability. These standards reduce ambiguity in high-stakes applications, but they also raise the cost of non-compliance and increase the importance of repeatable installation and calibration procedures. Second, installation complexity and labor expertise continue to constrain throughput. Bonding strain gages to advanced composites, high-temperature substrates, or heterogeneous structures demands trained technicians, controlled environments, and disciplined process documentation. In applications where measurement error carries direct safety, warranty, or certification consequences, labor skill becomes a cost driver rather than a trivial implementation detail. Third, suppliers face pressure to balance product breadth with engineering depth. The market includes producers of foil gauges, wire gauges, semiconductor variants, weldable units, and integrated measurement accessories. Companies that span too many sub-segments risk dilution, while those that specialize too narrowly may miss opportunities in adjacent high-value applications.
For business leaders, the practical implication is that growth in this market is less about raw volume and more about qualification, reliability, and integration readiness. Procurement decisions increasingly weigh total measurement confidence, not just unit price. Engineering teams prefer suppliers that can support application-specific bonding methods, environmental resilience, and documentation that aligns with internal or external audit requirements. Companies that treat strain gages as commodity components may win occasional price-sensitive bids, but they will struggle to retain long-term positions in programs where measurement integrity is a gating factor.
Key Drivers Shaping Demand and competitive dynamics
Technology innovation and application-specific customization
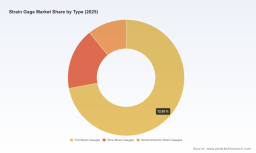
Technology advancement in this market is not dominated by disruptive product resets; it is driven by refinement, reliability, and fit-for-purpose engineering. Foil strain gauges continue to serve as the workhorse category because metallic foil elements offer stable performance, familiar handling, and cost predictability. Alloys such as copper-nickel and nickel-chromium remain common choices for resistive elements, enabling manufacturers to balance sensitivity, durability, and unit economics. At the same time, specialized variants extend the technology into harsher environments. High-temperature bondable gauges, waterproof weldable units, and composite-material-compatible formats address narrowband problems that generic products cannot reliably solve.
Recent industry activity reflects this customization trajectory. Product introductions have increasingly focused on expanding application-ready ranges rather than reinventing core sensing principles. In parallel, technical publications and workshop-based training efforts have reinforced the importance of proper installation, electrical connection practices, and measurement process discipline. These developments matter because the performance of a strain gage system is determined not only by the sensor itself but also by how it is mounted, wired, protected, and interpreted. In markets where customers are acquiring measurement capability for critical assets, suppliers that can deliver both the sensor and the process knowledge around it gain a meaningful advantage.
Policy, standards, and regulatory influence
Regulatory and standards activity is a growing force in how strain gage solutions are specified, validated, and deployed. New measurement standards have been introduced to define precise strain measurement practices for geotechnical monitoring and structural assessment. The adoption of these standards across regional and national bodies creates a clearer compliance path for infrastructure and civil engineering applications, while also raising the baseline expectation for documentation and reproducibility. For manufacturers and system integrators, this environment favors suppliers that already operate with quality management discipline and can demonstrate consistent production and testing practices.
Standardization also has a secondary effect on market structure. As measurement expectations become more explicit, end users are better able to compare offerings on technical merit rather than marketing claims. That tends to reward established performance characteristics, transparent specifications, and support ecosystems that help customers meet audit or certification requirements. In civil infrastructure, mining, and structural monitoring, where long-term data continuity matters, the ability to align with recognized measurement practices can be as important as sensor price.
Demand-side shifts in aerospace, automotive, and industrial manufacturing
Demand behavior across core application areas is evolving around validation intensity, safety assurance, and asset-life management. Aerospace continues to require strain measurement for structural testing, component qualification, and ongoing monitoring. Automotive development and production similarly depend on strain-based data for durability evaluation, load-path analysis, and quality assurance. Industrial manufacturing remains broad-based, with strain gages supporting load cells, process monitoring, machinery condition assessment, and experimental stress analysis.
What is changing is the context in which these measurements are used. Engineering programs increasingly treat strain data as part of a larger evidence chain linked to simulation, digital twin models, and ongoing asset monitoring. That integration raises expectations for sensor consistency, signal quality, and compatibility with broader data acquisition environments. Customers are also paying closer attention to total implementation effort, including mounting preparation, environmental protection, and post-installation calibration. In practice, this means strong demand continues for general-purpose products, but the highest-margin growth often accrues to suppliers that can address specific bonding conditions, environmental ranges, or measurement-system compatibility requirements.
Supply chain considerations and cost structure dynamics
The cost structure of strain gage production is shaped by material inputs, manufacturing precision, quality control, and application support. Foil-based products remain attractive because the core resistive elements rely on established metallic alloys that provide both cost efficiency and stable performance. That said, price competition alone does not determine outcomes in many end markets. Procurement teams in aerospace and infrastructure-related applications often prioritize traceability, environmental robustness, and supplier reliability over marginal unit-cost savings.
Labor and process costs also influence competitiveness. Installation on composites and other non-standard substrates can require specialized training and careful handling to avoid substrate damage or measurement error. When installation quality directly affects test validity or field performance, the cost of labor becomes a structural part of the value proposition rather than an external overhead item. Suppliers that reduce installation friction through product design, clear application guidance, or compatible accessory offerings can lower the total cost of deployment for customers, even if the sensor itself is not the cheapest option. This dynamic encourages differentiation based on ease of use, repeatability, and support documentation.
Competitive Landscape and Leading Strategies
The competitive field includes a blend of specialized sensor manufacturers, broader measurement and sensor groups, and distributors or solution providers that extend reach into end markets. A small number of companies hold a meaningful share of market value, while a long tail of regional and application-focused suppliers competes on specialization, service, and niche technical capability. This structure produces a market where leadership is earned through combination of product breadth, engineering credibility, and the ability to support customers through installation and interpretation challenges.
Worldwide Optical Strain Sensor Market
Several strategic positions are visible among leading participants. Micro-Measurements and Vishay Precision Group operate from a shared sensor heritage that spans general-purpose foil gauges, high-temperature variants, and semiconductor sensor lines. Their relevance in the market stems from the ability to address multiple performance tiers within a single supplier relationship, which is particularly valuable for engineering teams seeking consistent specifications across different test and production environments. Tokyo Measuring Instruments Laboratory has built a differentiated position through an extensive catalog of foil strain gage types, including high-temperature, weldable, and composite-material variants. That breadth allows the company to serve customers with diverse substrate and environmental requirements while maintaining a recognizable product architecture. Hottinger Brüel & Kjær emphasizes electrical foil strain gauges, cylindrical gauges, and integrated measurement systems for load cells, structural testing, and industrial applications, reflecting a strategy that connects the sensor to the broader measurement workflow.
TE Connectivity contributes a transducer- and sensor-oriented perspective, supplying strain gauge-based sensors for automotive, industrial, and general sensing applications. Its position illustrates how strain technology fits into larger electronic sensing portfolios, where integration with downstream signal conditioning and system design can matter as much as the sensing element itself. Omega Engineering and other distributors or solution providers expand market access by bundling sensors, load cells, and accessories into measurement and control systems, lowering the friction for customers who value ready-made configurations over component-level sourcing. Japanese manufacturers such as Kyowa Electronic Instruments add further specialization through foil, wire, weldable waterproof, and protector-type products for industrial and structural use. Similarly, companies like Hitec Products, GEOKON, Sensing Systems Corporation, and ME systeme GmbH focus on specific environment classes or application contexts, from hostile-environment weldable gauges to geotechnical instrumentation and mechanical engineering measurement chains.
The competitive trend is not simply consolidation or fragmentation; it is functional differentiation. Larger groups can leverage scale, multiple brands, and broader application coverage, while smaller specialists compete by solving specific installation, environmental, or documentation challenges that broader portfolios may treat only generically. Recent industry activity reinforces this pattern. New product ranges and technical publications have highlighted the ongoing importance of application-oriented strain gauge solutions, while standards adoption and training events have drawn attention to the operational discipline required for dependable measurements. For entrants and existing players alike, the most durable advantage is likely to come from being the supplier that reduces uncertainty across the full measurement chain, not just at the sensor level.
Future Trends and Commercial Implications
Trend 1: Standards-driven specification and higher qualification barriers
Over the next three to five years, measurement standards and associated qualification expectations are likely to become more embedded in procurement and engineering workflows. As standards for strain measurement are adopted across regional and national contexts, end users will increasingly expect suppliers to demonstrate consistent production quality, clear specification language, and documentation that supports audit and verification activities. This trend favors companies with robust quality management practices and well-defined application support. It also raises the cost of operating in high-compliance segments without the necessary process discipline.
The commercial opportunity here lies in aligning product portfolios with recognized measurement requirements and in offering implementation support that helps customers meet those requirements efficiently. Suppliers that can reduce the time and risk associated with qualification, installation, and reporting will be better positioned in infrastructure, civil engineering, and critical-structure applications.
Trend 2: Broader integration with monitoring systems and data workflows
Strain gages are increasingly part of larger monitoring and testing architectures rather than isolated point sensors. In infrastructure, mining, and structural integrity applications, strain measurement supports real-time observation of ground movement, load behavior, and structural condition. In aerospace and automotive contexts, strain data is used alongside simulation and validation workflows that demand repeatability and traceability. As a result, compatibility with data acquisition environments, signal conditioning, and system-level documentation becomes a more visible purchase criterion.
PW Consulting
This creates opportunities for suppliers that think beyond the sensor and consider how the device fits into installation, wiring, protection, and data interpretation. Product designs that simplify mounting, improve environmental protection, or align with common measurement setups can lower total project risk. The broader implication is that value will increasingly accrue to those who understand the customer’s measurement workflow and can reduce friction at multiple touchpoints.
Trend 3: Application specialization as a margin defense
Because the market is growing at a moderate, sustained pace, pure volume plays will face persistent margin pressure unless supported by scale or distribution advantages. A more reliable path to profitability is application specialization: targeting high-value use cases where measurement accuracy, durability, or certification support justifies a stronger value proposition. High-temperature environments, composite substrates, weldable waterproof configurations, and geotechnical instrumentation are all examples where specialized products can command greater relevance and pricing power than generic alternatives.
At the same time, specialization carries risk if a company overcommits to a narrow niche with volatile demand. The most resilient strategies combine deep capability in selected application areas with enough portfolio flexibility to serve adjacent use cases. For decision-makers, this means evaluating whether a given specialization is durable, whether the target application has structural demand drivers, and whether the supplier can support the customer beyond the sale through training, documentation, and technical service.
Strategic Actions for Decision-Makers
For manufacturers and product leaders
- Prioritize application-ready differentiation over undifferentiated product breadth. Focus engineering effort on the environments, substrates, and installation conditions where measurement reliability matters most.
- Strengthen quality management and specification clarity. As standards adoption increases, the ability to demonstrate consistent production and clear documentation becomes a competitive asset.
- Reduce total deployment friction. Develop accessories, application notes, and training support that help customers install and interpret measurements correctly, especially on composites and in harsh environments.
For investors and strategic backers
- Evaluate exposure to compliance-sensitive and infrastructure-linked applications. Segments where measurement standards and long-term data continuity matter may offer more defensible demand than purely price-driven volume markets.
- Assess portfolio fit rather than sensor count. A company’s value may depend less on how many gauge types it lists and more on how well its products map to durable application needs and integration requirements.
- Watch for consolidation among specialists and solution providers. As end users seek lower implementation risk and broader support, suppliers with strong technical credibility and distribution reach may become attractive acquisition or partnership targets.
For procurement and engineering leaders
- Evaluate total measurement confidence, not just unit price. Consider installation complexity, environmental durability, documentation quality, and compatibility with existing data acquisition workflows.
- Align supplier selection with internal qualification needs. Prefer suppliers that can support traceability, consistent production practices, and application-specific guidance, especially where measurement outcomes affect safety, certification, or long-term asset monitoring.
- Plan for labor and process costs. In applications involving composites or harsh conditions, budget for trained installation and proper process control, since measurement quality depends heavily on how the sensor is applied.
The strain gage market is expanding steadily, but the most important strategic questions are no longer about whether demand will grow. They are about where qualification, integration, and application specialization will concentrate value, and which suppliers can reliably reduce risk across the full measurement chain. For leaders evaluating entry, expansion, or sourcing strategy, detailed segment-level data, application-level demand signals, and company-specific positioning can sharpen those decisions considerably. Comprehensive market research providing deeper segmentation, competitive benchmarking, and scenario-based forecasts is available for teams that need to move from directional insight to actionable planning.
Polariscope Strain Viewer Market
For detailed analysis of this topic, please visit the official page: Strain Gage Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


