



Microwave Oven Market 2032: Why 3.5% CAGR Growth Trajectory Defies Expectations

Strategic Trends and Commercial Opportunities in the Microwave Oven Market (2025–2032)
Market Outlook: A Mature Appliance Sector in Transition
The microwave oven market has evolved from a quintessential convenience appliance into a more strategically nuanced segment within the broader kitchen appliance landscape. Valued at USD 8.5 billion in 2020, the sector reached an estimated USD 13.5 billion by 2025, reflecting steady expansion driven by consistent household demand and incremental product innovation. Projections through 2032 indicate a 3.5% compound annual growth rate, culminating in a market valuation approaching USD 17.21 billion. While these headline figures suggest a predictable growth trajectory, the underlying dynamics reveal a market navigating structural shifts in consumer behavior, regulatory uncertainty, and supply chain reconfiguration.
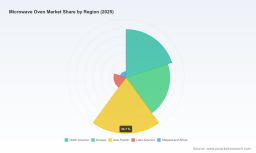
The growth narrative is not uniform across all dimensions. Regional performance varies significantly, with Asian Pacific markets continuing to anchor volume demand while North American and European segments exhibit more mature, replacement-driven consumption patterns. Product differentiation has also reshaped how manufacturers allocate capital and design roadmaps. Solo units maintain a dominant share, reflecting their affordability and prevalence in price-sensitive markets, while grill and convection variants capture premium positioning and multi-functionality demand. Similarly, residential applications overwhelmingly drive baseline volume, yet commercial installations represent a strategically distinct segment with different procurement cycles, durability requirements, and service expectations.
High Speed Oven Market
Key Challenges and Inflection Points
Despite the steady top-line trajectory, several friction points are reshaping how stakeholders approach the market. First, the recent policy landscape has introduced regulatory volatility. In May 2025, the U.S. Department of Energy proposed rescinding energy conservation standards for microwave ovens, effectively eliminating prior efficiency requirements. This move reduces compliance burdens for manufacturers but simultaneously removes a historical driver that had accelerated the phase-out of less efficient designs and influenced product architecture. While the change may lower near-term engineering costs, it also introduces uncertainty around future regulatory directionality and consumer perceptions of energy-conscious appliances.
Second, trade policy dynamics are creating cost pressure that ripples through pricing strategies and margin structures. Tariff actions on Chinese-origin goods in 2025 contributed to a measurable increase in core goods consumer prices, with continued effects extending through early 2026. For a category with substantial import-dependent component sourcing and finished goods manufacturing footprints in East Asia, these trade shifts are compressing supply chain flexibility and forcing manufacturers to weigh localized production, alternative sourcing, and pricing absorption more carefully.
Third, the market is approaching a functional saturation point in basic microwave cooking. As standalone heating appliances become commoditized in many households, growth increasingly depends on differentiated value propositions rather than volume replacement alone. This creates a strategic crossroads: manufacturers must decide whether to compete on cost efficiency in mature categories or invest in integrated solutions that address evolving kitchen workflows, space constraints, and connected living environments.
Core Drivers Shaping Market Trajectory
Technological Innovation and Design Evolution
Product innovation remains a central competitive lever, though the nature of innovation has shifted from incremental wattage and capacity upgrades toward integrated functionality and form-factor adaptation. Convection capabilities, air-fry combinations, and smart connectivity features are redefining how microwaves fit into modern kitchens. Leading manufacturers are embedding intelligent interfaces, remote diagnostics, and compatibility with broader smart home ecosystems, positioning microwave ovens not merely as heating tools but as nodes within integrated kitchen management. LG Electronics, for example, has continued advancing its Smart ThinQ platform alongside convection technology, reinforcing the trend toward app-enabled control and performance customization. Such developments appeal to consumers willing to pay a premium for convenience, consistency, and multi-cooking versatility.
At the same time, spatial constraints in urban housing and smaller-footprint living environments are driving demand for compact and flexible configurations. Sharp Corporation’s recent introduction of compact kitchen appliances, including new Convection Microwave Drawer™ Oven models, highlights how design innovation is responding to the need for built-in flexibility and space optimization. These developments illustrate that technology leadership in this market is increasingly defined by how well a product adapts to installation environments, culinary workflows, and aesthetic expectations rather than raw heating specifications alone.
Policy and Regulatory Environment
Regulatory shifts are acting as both a constraint and an enabler, depending on the manufacturer’s positioning and geographic exposure. The proposed rescission of energy conservation standards alters the compliance calculus for U.S.-facing products, potentially freeing engineering resources that would otherwise be directed toward efficiency optimization. However, this does not eliminate all regulatory oversight. The FDA continues to enforce radiation safety performance standards under 21 CFR 1030.10, requiring manufacturer certification and labeling. This framework ensures a baseline of product safety and consumer confidence but also imposes ongoing compliance obligations that influence product design, testing, and market entry timelines.
For global manufacturers, the divergence between evolving energy policy in some markets and persistent safety standards in others creates a patchwork of requirements. Companies must manage product configurations that can satisfy multiple regulatory regimes without sacrificing cost competitiveness or feature consistency. In practice, this regulatory complexity favors manufacturers with mature compliance infrastructure and the ability to modularize design platforms across regions.
PW Consulting
Demand-Side Shifts in Consumer and Commercial Behavior
On the demand side, microwave ovens are benefiting from broader lifestyle and housing trends that value convenience, speed, and multifunctional appliances. Urbanization, smaller household sizes, and time-constrained consumption patterns continue to reinforce reliance on fast-preparation appliances. At the premium end, consumers are increasingly looking for appliances that support varied cooking methods within a single footprint, which has helped sustain interest in convection and grill variants. In commercial environments, demand is shaped by operational efficiency, durability, and throughput requirements. Food service operators, institutional kitchens, and hospitality venues evaluate microwave systems through a different lens than residential buyers, prioritizing serviceability, consistent output, and integration with existing workflow equipment.
A notable demand-side development is the growing sensitivity to total cost of ownership rather than sticker price alone. While budget-conscious segments still favor basic solo models, buyers in higher-income and commercial segments increasingly weigh features, energy behavior, service availability, and brand reliability. This bifurcation is reinforcing segmentation strategies and making it more difficult for undifferentiated products to command share in competitive channels.
Supply Chain and Cost Structure Adjustments
Cost structures in the microwave oven market are being reshaped by a combination of input pricing, logistics volatility, and trade policy exposure. Tariffs on Chinese-origin goods have raised the price baseline for imported components and finished goods, affecting everything from magnetron sourcing to assembly and distribution. In response, manufacturers are recalibrating sourcing strategies, evaluating nearshoring or diversified supplier networks, and adjusting product mix to protect margins without alienating price-sensitive buyers. Midea Group’s ongoing catalog updates, including refreshed countertop and Versa Series offerings, reflect the type of portfolio management required to maintain channel relevance while navigating shifting cost dynamics.
Worldwide Combination Microwave Ovens Market
The supply chain imperative is not only about cost containment. It also involves resilience. Manufacturers with the ability to flex production footprints, maintain component buffers, and respond quickly to channel demand fluctuations are better positioned to manage the trade-offs between volume, margin, and lead time. This has elevated the strategic importance of manufacturing planning and logistics coordination as competitive differentiators in a segment where hardware innovation is sometimes incremental.
Competitive Landscape and Strategic Positioning
Incumbent Strength and Differentiation Paths
The market remains moderately concentrated, with the top three players accounting for roughly 45% of share and the top five approaching 60%. This concentration reflects the presence of large, globally active manufacturers capable of sustaining broad product portfolios, competitive pricing, and multi-channel distribution. Midea Group and Galanz function as major OEM and branded manufacturers, producing microwave ovens for multiple labels and retail channels. Their scale and manufacturing breadth enable them to serve both proprietary brand strategies and third-party sourcing relationships. Midea’s portfolio breadth, including countertop and Versa Series models, underscores a strategy built on product range and channel versatility, while Galanz similarly supports a mix of its own brand and retailer-supplied models.
On the branded premium and feature-differentiated side, LG Electronics and Sharp Corporation emphasize integrated technologies and specialized form factors. LG’s focus on built-in, countertop, and convection models with smart connectivity highlights an orientation toward modern kitchen integration and consumer-facing digital experience. Sharp’s emphasis on Convection Microwave Drawer™ ovens and other countertop and over-the-range models reflects a more architecture-oriented approach, appealing to installations where space, aesthetics, and built-in functionality matter. These differentiated paths show that incumbents are not competing solely on volume; they are also cultivating niches where design, functionality, and ecosystem alignment can support margin resilience.
Whirlpool Corporation and GE Appliances illustrate how established Western appliance groups maintain relevance through multi-brand portfolios and domestic manufacturing elements. Whirlpool’s offerings under Whirlpool, KitchenAid, and Amana brands span multiple consumer segments and price tiers, while GE Appliances has continued to emphasize countertop and built-in models with convection and air-fry options. For these players, brand trust, service networks, and retail relationships remain important assets, especially in markets where post-purchase support and consumer familiarity influence purchasing decisions.
Structural Evolution in the Competitive Field
The competitive landscape is likely to continue evolving along several axes. One is consolidation and selective partnership. Larger manufacturers may pursue channel expansion, regional manufacturing footprint adjustments, or targeted acquisitions to strengthen portfolio coverage or technology capabilities. Another is segmentation-driven specialization, where certain players concentrate on high-volume cost-competitive models while others invest in premium, connected, or built-in solutions. This divergence can create opportunities for new entrants or niche specialists that address underserved needs, such as compact urban installations, commercial-grade durability, or region-specific compliance and pricing requirements.
Recent product and catalog activity illustrates how firms are refining their positioning in real time. Sharp Electronics Corporation’s February 2026 launch of compact kitchen appliances, including a new Convection Microwave Drawer™ Oven, signals a continued push toward space-efficient and design-forward solutions. Midea Group’s March 2026 catalog updates, including compact countertop models and revised Versa Series offerings, demonstrate ongoing portfolio tuning to maintain relevance across channel and consumer segments. These moves are not isolated product events; they reflect broader strategic calibration in response to housing trends, channel demands, and cost pressures.
Forward-Looking Trends and Commercial Opportunities
Trend 1: Functional Integration as a Growth Lever
Over the next three to five years, microwave ovens are likely to gain share not by standing alone as simple reheating appliances, but by functioning as integrated cooking and convenience hubs. Convection, air-fry, and smart-control capabilities will increasingly become baseline expectations in higher-tier segments, while basic solo units remain volume drivers in price-sensitive markets. Commercial opportunity lies in product architectures that allow modular feature sets, enabling manufacturers to cover multiple price points without fragmenting engineering resources. For channel partners, this translates into clearer upsell pathways and stronger differentiation in showroom and online environments.
Trend 2: Space-Optimized and Installation-Focused Designs
As housing footprints shrink in many urban markets and renovation projects prioritize integrated cabinetry and flexible layouts, demand for compact, built-in, and drawer-style configurations is expected to grow. This trend favors manufacturers that can align product design with installation ecosystems and offer solutions that fit diverse kitchen architectures. Commercial opportunity extends beyond consumer retail into renovation channels, property development partnerships, and commercial fit-out procurement, where appliance compatibility and space efficiency influence purchasing decisions early in the project lifecycle.
Trend 3: Supply Chain Realignment and Regional Cost Strategy
Given ongoing trade policy exposure and component sourcing complexity, manufacturers are likely to continue diversifying production and sourcing strategies to protect margin and lead-time reliability. Commercial opportunity exists for firms that can demonstrate supply chain resilience, localized assembly options, or flexible sourcing models to buyers who are increasingly sensitive to availability risk and total cost of ownership. Investors and strategic partners should watch for shifts in manufacturing geography, supplier concentration, and channel pricing behavior, as these factors will influence category profitability more directly than headline demand growth alone.
Risks and Uncertainties
Several uncertainties could alter the pace or shape of growth. Regulatory directionality remains fluid, particularly where energy standards are being reevaluated, and future reinstatement or recalibration of efficiency requirements could change design priorities. Trade policy volatility can shift cost structures quickly, especially for categories with heavy import dependence. Additionally, competitive intensity in commoditized segments may compress pricing power, while premium differentiation depends on sustained consumer willingness to pay for features that are not yet considered essential. Finally, macroeconomic sensitivity in major residential markets can affect big-ticket appliance purchase cycles, making the category partly dependent on housing activity, remodeling spend, and discretionary income trends.
Strategic Recommendations for Decision-Makers
For Manufacturers and Brand Strategists
- Develop modular product platforms that can support solo, grill, and convection variants without duplicating engineering effort, allowing faster response to regional price and feature expectations.
- Align design roadmaps with space-constrained and built-in installation trends, including compact and drawer-style options, to capture renovation-driven and urban-living demand.
- Stress-test supply chain exposure to trade policy and component sourcing concentration, and evaluate diversified sourcing, regional assembly, or flexible logistics arrangements to protect margin and availability.
For Investors and Strategic Partners
- Evaluate category exposure by segmentation logic rather than aggregate market size alone; premium convection and smart-enabled segments may offer different risk-return profiles than high-volume solo units.
- Monitor regulatory and trade-policy developments closely, as changes can alter cost structures and compliance investment requirements with limited lead time.
- Prioritize companies with credible manufacturing flexibility, brand-channel strength, and the ability to manage multi-tier portfolios across cost-competitive and differentiated segments.
For Procurement and Channel Leaders
- Balance base-volume sourcing with differentiated SKUs that support margin and consumer upgrade paths, particularly where convection, air-fry, and compact configurations can command stronger positioning.
- Incorporate serviceability, warranty infrastructure, and installation compatibility into evaluation criteria, especially for commercial and multi-unit deployment scenarios.
- Track price and availability signals tied to component imports and trade measures, and adjust sourcing plans to reduce exposure to sudden cost shifts.
The microwave oven market is no longer moving solely on basic replacement demand. It is being reshaped by design innovation, regulatory recalibration, trade-linked cost dynamics, and evolving expectations around how appliances fit into modern kitchens and commercial operations. For decision-makers, the most valuable intelligence is not a single aggregate figure but a clear view of where differentiation is gaining traction, where cost pressure is reshaping margins, and how regulatory and supply chain variables may change competitive advantage over the next several years. Readers seeking deeper segmentation detail, regional dynamics, and customized strategic guidance can explore the full PW Consulting report for a more granular view of the market and its emerging opportunities.
For detailed analysis of this topic, please visit the official page: Microwave Oven Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


