



Automatic Tire Inflation System Market: Why 6.98% CAGR Changes Everything

The Automatic Tire Inflation System Market: Strategic Trends and Commercial Opportunities Through 2032
The global automatic tire inflation system (ATIS) market has entered a phase of steady, structurally driven expansion. Valued at approximately 215 million USD in 2025, the market has grown from roughly 163 million USD in 2020, reflecting a compound annual growth rate of 6.98 percent through 2032. This trajectory is not merely a function of incremental demand; it signals a broader transformation in how fleets, manufacturers, and regulators approach tire management. As operational costs rise and sustainability mandates tighten, ATIS has shifted from a niche add-on to a strategic component of vehicle architecture and fleet optimization.
The market's growth pattern reveals distinct inflection points. Revenue expanded modestly through 2022, then accelerated in 2023 and 2024, reaching 207.42 million USD before stabilizing near 215 million USD in 2025. This acceleration aligns with broader industry shifts: heavier emphasis on fuel efficiency, increased scrutiny of tire-related safety incidents, and the gradual integration of tire pressure management into connected vehicle ecosystems. Looking ahead, the forecast period through 2032 projects continued expansion, with revenue crossing 300 million USD by 2030 and approaching 344.8 million USD by 2032. The pace of growth will depend on how quickly adoption cascades from early-adopter segments into mainstream commercial and passenger vehicle applications.
Despite the positive trajectory, the industry faces several structural challenges that will shape competitive dynamics and investment decisions over the next decade.
Core Challenges and Inflection Points
One of the most significant hurdles is the uneven regulatory landscape. In many jurisdictions, ATIS remains an optional feature rather than a mandated requirement. This creates a paradox: the systems deliver measurable safety and efficiency benefits, yet compliance frameworks do not consistently incentivize adoption. Fleet operators weighing capital expenditures must weigh tangible operational savings against the absence of regulatory compulsion. The result is a market where adoption velocity depends heavily on demonstrable return on investment rather than compliance-driven demand.
A second challenge lies in integration complexity. Retrofitting existing fleets with automatic inflation systems requires compatibility with diverse valve assemblies, air supply configurations, and telematics platforms. For new vehicle manufacturers, embedding ATIS into chassis design demands coordination across engineering teams, supply chains, and certification processes. These integration frictions slow deployment cycles and increase upfront costs, particularly for mid-sized operators who lack the scale to negotiate customized solutions or absorb installation downtime.
A third inflection point is the evolving definition of system value. Early generations of ATIS focused primarily on maintaining target pressure levels. Today, the market increasingly expects intelligent monitoring, real-time diagnostics, and data integration with fleet management software. This shift raises the bar for competitors: companies that offer standalone mechanical or pneumatic solutions without connected capabilities risk marginalization as buyers prioritize systems that feed actionable insights into broader operational workflows.
Key Drivers Shaping Market Trajectory
The expansion of the ATIS market is being propelled by a convergence of technological, regulatory, demand-side, and supply chain forces. Understanding how these drivers interact is essential for stakeholders evaluating market entry, product development, or capital allocation.
Technology Innovation and Intelligent Monitoring
Advancements in sensor technology, wireless communication, and edge computing have transformed ATIS from a pressure-maintenance tool into a data-generating asset. Modern systems now incorporate integrated sensors that continuously monitor tire conditions, log performance metrics, and transmit information to centralized dashboards. This evolution matters because tire under-inflation remains a leading cause of premature wear, elevated fuel consumption, and roadside failures. By automating pressure correction and coupling it with visibility into tire health, these systems reduce manual inspection burdens and enable predictive maintenance strategies.
Recent developments illustrate this trajectory. In early 2026, RIX Industries received a 204,500 USD SBIR Phase I contract from the Federal Motor Carrier Safety Administration to prototype a Weight Equalization Smart Automatic Tire Inflation System. The project targets per-tire real-time pressure management, highlighting a growing emphasis on precision control and load-aware inflation logic. Such initiatives signal that innovation is moving beyond generic pressure maintenance toward context-sensitive algorithms that adapt to cargo distribution, terrain, and operating conditions.
Policy and Regulatory Environment
Regulatory signals are subtly reshaping the adoption calculus. While ATIS is not universally mandated, inspection frameworks and electronic compliance standards are creating an environment where properly functioning tire pressure management systems carry indirect advantages. For example, recent inspection guidance clarifies that an ATIS unit is not classified as required equipment on commercial motor vehicles, and a defective or alert-status system does not automatically trigger a violation. This regulatory posture reduces the compliance risk of adoption while preserving the operational case for installation. It also means that manufacturers must ensure their systems meet relevant electromagnetic compatibility and electronic equipment standards to avoid unintended certification hurdles.
PW Consulting Automotive & Machinery Research Center
Parallel compliance milestones reinforce this trend. Systems on the market have been documented as conforming to FCC Part 15 rules and Industry Canada RSS-210 for electronic equipment, while other centralized tire inflation platforms declare conformity to EMC directives, ISOBUS standards, and environmental resistance specifications. These compliance layers are not mere formalities; they reduce integration friction for fleets operating across borders and signal maturity to buyers who prioritize reliability and auditability.
Demand-Side Shifts in Fleet and Consumer Behavior
On the demand side, fleet operators are increasingly treating tire management as a lever for total cost of ownership reduction rather than a maintenance afterthought. Proper inflation directly influences fuel economy, tire lifespan, and unscheduled downtime. As freight margins remain constrained and labor shortages complicate roadside inspection routines, the economic argument for automated pressure management strengthens. Large trailer fleets that have already deployed ATIS on a significant scale report sustained benefits in keeping tires properly inflated and improving fuel efficiency, which reinforces the credibility of the technology among peer operators.
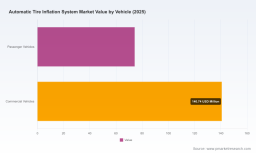
Passenger vehicle applications are also gaining attention, particularly as connected car platforms expand and consumers become more accustomed to vehicles that self-monitor and self-adjust. While commercial vehicles currently represent the larger revenue share, the passenger segment benefits from the same underlying logic: reduced wear, improved safety margins, and alignment with broader vehicle intelligence trends. The challenge for suppliers is to adapt system architectures to the cost, packaging, and user-experience expectations of passenger markets without sacrificing reliability.
Supply Chain and Cost Structure Evolution
Cost dynamics are being reshaped by component innovation and manufacturing scale. Sealing technologies, for instance, have advanced to the point where central tire inflation seals can self-adjust across terrains, reducing CO₂ emissions and extending tire life. Such improvements lower the total cost of ownership for end users while giving system manufacturers a tangible performance differentiator. At the same time, the broader push toward standardized electronic components and modular architectures is helping suppliers reduce integration complexity and accelerate time to market.
However, supply chain resilience remains a consideration. Systems that depend on specialized sensors, control modules, and custom pneumatic assemblies are exposed to component availability fluctuations and lead-time variability. Manufacturers that invest in component standardization, dual-sourcing strategies, and design-for-manufacturing principles will be better positioned to maintain pricing stability and delivery reliability as demand scales.
Competitive Landscape and Leading Strategies
The ATIS market is characterized by a moderately concentrated competitive structure, with the top three players holding approximately 31.4 percent of revenue and the top five accounting for roughly 38.7 percent. This concentration leaves meaningful room for specialized providers, regional players, and new entrants that can address underserved segments or bring differentiated technology. The competitive arena is not defined by a single winner-takes-all dynamic; rather, it rewards companies that combine technical credibility, integration ease, and compelling operational value propositions.
Strategic Positioning of Leading Players
Several established companies illustrate the diversity of successful strategic positioning. Aperia Technologies has focused on intelligent automatic tire inflation with integrated sensors designed for seamless data collection and reporting, targeting heavy-duty trucks and fleets. This approach positions the company at the intersection of pressure management and fleet analytics, appealing to operators who want actionable visibility alongside automated inflation.
Cummins, through its Meritor Tire Inflation System, has built scale by equipping more than one million trailers with technology that maintains proper tire inflation and reduces wear. The breadth of deployment provides a strong reference base and reinforces the system's status as a proven solution in the commercial trailer segment. Hendrickson International offers a tiered portfolio of tire pressure control systems, including CP, PRO, and PRO-LB automatic inflation models tailored for the trailer industry. This product ladder allows the company to address varying performance and budget requirements within a coherent brand framework.
Pressure Systems International has established a long-standing presence in the market, positioning itself as a global leader in automatic tire inflation systems with integrated TPMS capabilities. Its emphasis on decades of experience and combined inflation and monitoring functionality appeals to buyers seeking consolidated solutions. Rotex Automation brings a European footprint with a patented centralized tire inflation system installed on a significant share of trucks across the region, reflecting deep regional integration and familiarity with local operating conditions. Stemco complements this landscape by focusing on installation efficiency, offering toolkits that streamline trailer tire inflation system deployment, which reduces friction for operators and upfitters alike.
Market Evolution: Integration, Differentiation, and New Entrants
The competitive landscape is evolving along three overlapping directions. First, integration is becoming a decisive advantage. Suppliers that connect inflation hardware with telematics, maintenance platforms, and route-optimization software are creating stickier customer relationships and higher perceived value. Second, differentiation is increasingly tied to intelligent features rather than mechanical performance alone. Real-time pressure management, load-aware algorithms, and diagnostic reporting are becoming baseline expectations in commercial segments, pushing legacy-only offerings toward the periphery.
Third, the market is open to strategic new entrants, particularly those with strong funding pathways or specialized technology. The recent SBIR-funded prototype for a weight equalization smart inflation system exemplifies how targeted innovation can introduce novel capabilities that address specific operational pain points. While such projects are early stage, they signal that the barrier to introducing differentiated concepts remains manageable for well-positioned innovators. Over time, the market may see consolidation among larger platform providers acquiring niche technology, alongside continued fragmentation in regional or application-specific niches.
Future Trends and Commercial Opportunities
Looking ahead to the 2027–2032 window, three trends are likely to shape commercial opportunities and strategic priorities.
From Standalone Systems to Integrated Fleet Intelligence
Automatic tire inflation will increasingly be evaluated as part of a broader fleet intelligence stack rather than as an isolated hardware purchase. Buyers will expect systems that not only maintain pressure but also contribute data to maintenance scheduling, fuel reporting, and safety analytics. This trend creates opportunities for suppliers that invest in open APIs, interoperable data formats, and bundled service offerings. It also raises the stakes for companies that rely on closed architectures, as fleets favor solutions that plug into existing operational workflows.
Precision Control and Load-Aware Inflation Logic
A second trend is the move toward per-tire, condition-aware pressure management. As sensing accuracy improves and control algorithms become more sophisticated, systems will adapt inflation levels to cargo distribution, road surface, and dynamic loading conditions. This precision has direct commercial implications: it can extend tire life, reduce uneven wear, and improve fuel economy under variable operating conditions. Suppliers that can demonstrate measurable performance gains from smart inflation logic will have a stronger case in price-sensitive procurement environments.
Aftermarket Tire Pressure Monitoring System (TPMS) Market
Regional Expansion and Application Diversification
A third trend is the gradual expansion of ATIS adoption beyond mature commercial trailer markets into adjacent applications and regions. Centralized and continuous inflation architectures are finding relevance in off-road and specialized vehicle contexts, while passenger vehicle applications may grow as connectivity and self-diagnosis features become standard expectations. Regional growth will be uneven, shaped by local fleet composition, fuel cost sensitivity, and the pace of telematics adoption. Companies that can adapt system designs to regional operating conditions and cost structures will be better positioned to capture incremental demand.
Risks and Uncertainties
These opportunities are accompanied by risks that stakeholders should monitor. Regulatory frameworks could shift in ways that either accelerate adoption through mandates or introduce new compliance burdens that increase system cost. Supply chain disruptions affecting sensors, control modules, or pneumatic components could pressure margins and delay deployments. Additionally, if macroeconomic conditions compress fleet capital spending, the timeline for broader ATIS adoption may extend, particularly in price-sensitive segments where payback periods are closely scrutinized. Competitive pressure could also intensify if large platform providers bundle inflation capabilities with broader vehicle systems, altering the bargaining dynamics for standalone suppliers.
Actionable Guidance for Decision-Makers
The strategic implications of these trends differ by role, but several priorities apply across the board.
For Manufacturers and Technology Providers
Differentiate through intelligent integration rather than pressure maintenance alone. Invest in sensor accuracy, data interoperability, and installation efficiency, as these elements increasingly determine buyer preference. Standardize components where possible to improve supply chain resilience and reduce cost volatility. Consider targeted partnerships or acquisitions that add complementary capabilities, such as telematics interfaces, advanced sealing technologies, or region-specific installation expertise.
For Investors and Capital Allocators
Evaluate opportunities based on total cost of ownership value propositions and the capacity to scale installation and service networks. Companies with proven deployment volumes, clear compliance alignments, and modular architectures are better positioned to weather procurement cycles and supply variability. Watch for early-stage innovations that address load-aware control or terrain-adaptive sealing, as these features can become meaningful differentiators if they translate into measurable operational savings. Assess the pace of regional adoption carefully, as growth will be uneven and dependent on local fleet economics and telematics maturity.
For Fleet Operators and Procurement Teams
Prioritize systems that integrate with existing maintenance and telematics workflows, reducing the operational burden of data reconciliation and manual inspections. Evaluate installation toolkits and service support as part of the procurement decision, since deployment efficiency directly affects downtime and total cost. When comparing solutions, look beyond headline specifications to verify compatibility with valve configurations, air supply arrangements, and electronic compliance requirements relevant to your operating region. Consider pilot deployments in representative routes and load conditions to validate real-world performance before scaling.
Worldwide Automotive Tire Socks Market
The ATIS market is moving from a phase of incremental adoption to one where intelligent control, integration, and regional adaptation determine competitive advantage. Stakeholders who align product strategies, investment theses, and procurement criteria with these shifts will be better positioned to capture value as the market expands toward the mid-2030s. For decision-makers seeking deeper segmentation data, regional breakdowns, and customized scenario analysis, the full research report provides the detailed frameworks needed to translate these trends into precise commercial action.
For detailed analysis of this topic, please visit the official page: Automatic Tire Inflation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


