



Patient Data Management Systems Market 2026: Why 11.2% CAGR And ICU Adoption Redefine Growth

The Patient Data Management Systems Market: Strategic Trends and Commercial Opportunities Through 2032
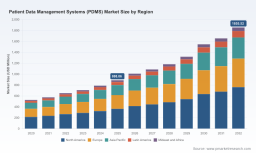
The global patient data management systems (PDMS) market has entered a phase of accelerated structural transformation. Valued at approximately 527.36 million USD in 2020, the market has grown to an estimated 888.06 million USD by 2025, reflecting a compound annual growth rate of 11.2 percent through the forecast horizon extending to 2032. By the end of that period, total market revenue is projected to surpass 1.85 billion USD. This trajectory is not merely a reflection of incremental IT spending; it signals a fundamental reorientation of how clinical data is captured, integrated, and operationalized across care settings.
The growth curve reveals distinct inflection points. The period from 2020 to 2023 delivered steady expansion, while the 2024 to 2025 window accelerated as hospitals confronted compounding pressures: staffing constraints, regulatory mandates, and the operational urgency of interoperable data flows. Projections for 2026 through 2032 indicate that revenue will compound at a pace that outpaces many traditional healthcare IT segments, driven by consolidation of clinical workflows, cloud migration, and the formalization of PDMS as regulated medical device infrastructure.
Yet the headline figures obscure a market that is actively reconstituting itself. Growth is uneven across deployment models, clinical environments, and geographic regions. Vendors are navigating a landscape where interoperability expectations, cybersecurity exposure, and regulatory classification requirements are reshaping procurement criteria. For executives and investors, the strategic question is no longer whether PDMS adoption will continue, but how value will be captured amid shifting integration standards, mounting security liabilities, and evolving reimbursement and funding mechanisms.
Market Snapshot: Scale, Trajectory, and Structural Tensions
The market's expansion from roughly 527 million USD in 2020 to nearly 888 million USD in 2025 reflects a compound growth rate of 11.2 percent, with forecasts extending to 2032 indicating a pathway toward 1.85 billion USD. This trajectory is anchored by several structural forces: the normalization of PDMS as a clinical documentation and device integration layer, the formalization of risk management and approval processes under hospital IT regulations, and the simplification of functional requirements within industry standards. Together, these factors have lowered adoption friction while simultaneously raising the baseline expectation for what a compliant, production-grade system must deliver.
PW Consulting
Concentration patterns further clarify the market's maturity. The leading vendors collectively account for approximately half of total revenue, with the top three and top five firms each representing roughly 50 percent of the market. This concentration suggests a landscape where established players hold significant share, yet the remaining half is distributed across regional specialists, niche integrators, and emerging cloud-native entrants. The implication for strategy is clear: scale advantages exist, but they are not insurmountable when differentiated clinical workflows, localized compliance needs, or cloud-first deployment models create openings for targeted positioning.
The current market is also defined by three interlocking challenges that are reshaping vendor and buyer behavior alike.
- Interoperability expectations are outpacing legacy integration architectures. Hospitals increasingly demand seamless connectivity across monitors, ventilators, infusion pumps, and electronic patient records, yet many installed bases were designed around single-function documentation rather than hospital-wide data orchestration.
- Cybersecurity and operational resilience have become procurement determinants. The exposure of cloud-based electronic patient record platforms to ransomware incidents has elevated security architecture, backup readiness, and incident response capabilities from technical considerations to board-level risk management criteria.
- Regulatory classification and funding mechanisms are simultaneously enabling and constraining adoption. PDMS are classified as medical devices requiring risk management and approval processes, while funding instruments such as hospital future acts have catalyzed deployments in specific regions. This dual dynamic accelerates certain rollouts while imposing compliance costs and timeline uncertainties elsewhere.
These tensions do not slow the market; they redistribute value. Vendors that can reconcile interoperability, security, and regulatory compliance within coherent deployment models are gaining negotiating leverage, while those relying on fragmented, point-solution messaging are facing longer evaluation cycles and more stringent proof-of-value requirements.
Key Drivers Shaping the Next Wave of Growth
The market's trajectory is being propelled by a combination of technological, regulatory, demand-side, and cost-structure forces. Each driver reinforces the others, creating a momentum loop that is likely to sustain double-digit growth through the late 2020s.
Patient Engagement Software Market
Technology innovation and integration maturity. The shift from isolated documentation tools to integrated clinical data layers is the most visible technological driver. PDMS platforms are increasingly expected to connect diverse bedside devices, normalize data streams, and feed structured information into broader hospital information and electronic patient record environments. Recent operational deployments illustrate this consolidation: centralized standardized documentation systems are now being implemented across multiple provincial hospitals, embedding PDMS into anaesthesia and intensive care workflows with the explicit goal of improving data quality and cross-hospital communication. At the same time, integration showcases at major industry events are emphasizing closed-loop processes that link media and documentation solutions directly into PDMS and hospital information systems, reducing manual handoffs and supporting continuity of care.
Policy and regulatory environment. Regulatory dynamics are acting as both a catalyst and a filter. PDMS are classified as medical devices and must undergo approval processes that include risk management under hospital IT regulations, which raises the barrier to entry for immature solutions but strengthens confidence in vetted platforms. At the same time, functional requirements for patient data management systems have been simplified in standards, lowering the implementation burden for baseline compliance. New guidelines, laws, and regulations are being directly integrated into PDMS standard content, meaning that vendors must treat regulatory updates as continuous product obligations rather than periodic certification events. This environment rewards platforms with disciplined change management and penalizes those that treat compliance as a static checklist.
Demand-side behavior and clinical workflow pressure. Hospitals are confronting staff shortages alongside budget constraints, which makes PDMS adoption less about optional digitization and more about workflow survival. Complex clinical environments require documentation, device traceability, medication management, and nutritional or pediatric percentile tracking without adding administrative burden. The demand signal is shifting accordingly: buyers are prioritizing systems that can centralize documentation, improve data quality, and reduce the cognitive load on clinical staff. This demand-side pressure is particularly acute in intensive care and anaesthesia settings, where device density and data volume make manual reconciliation impractical.
Cost structure and deployment model evolution. The cost equation is being reshaped by cloud transformation and the operational economics of platform maintenance. Cloud-based hospital information and electronic patient record systems are moving into production, with major medical centers completing launches and phasing out legacy platforms over multi-year transition windows. This shift alters total cost of ownership calculations, introducing subscription and hosting considerations while reducing on-premises maintenance overhead. However, it also introduces dependency on vendor security posture and continuity planning, as evidenced by incidents where ransomware attacks disrupted electronic patient record portals across a large share of hospital organizations using a specific platform. The cost conversation has therefore expanded from license and implementation to include resilience, data protection, and recovery readiness.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive field is anchored by a small group of established vendors with deep clinical integration expertise, complemented by regional specialists and integration-focused entrants. The leaders have built their positioning around distinct clinical use cases, device connectivity breadth, and the ability to embed PDMS within broader hospital information and monitoring environments.
German-based vendors illustrate the depth of specialization emerging in the market. One prominent player focuses on certified PDMS integrated with its hospital information system, emphasizing ICU device connectivity, medication management, nutritional balance, and pediatric percentile features. This configuration targets high-acuity environments where documentation precision and cross-referencing across clinical parameters are essential. Another German firm offers a PDMS suite integrated with acute care monitoring systems for ICU, operating room, and neonatal intensive care settings, with an emphasis on centralized data management, prescription traceability, and optimization of patient care. A third German provider centers its offering on anaesthesia and intensive care departments, delivering centralized documentation, improved data quality, and cross-hospital communication capabilities. These profiles share a common thread: they are designed for environments where device density, regulatory scrutiny, and data continuity requirements are highest.
In the Netherlands, a different integration philosophy is gaining traction. A vendor has advanced a hospital-wide electronic patient record solution with PDMS capabilities that communicate across monitors, ventilators, and infusion pumps throughout the facility. This approach reflects a broader enterprise integration mindset, where PDMS is treated as a connective layer within a unified digital infrastructure rather than a departmental add-on. The emphasis on hospital-wide device communication aligns with buyer expectations for fewer integration silos and more consistent data semantics across care units.
Recent developments illustrate how these positions are being reinforced and tested in practice. One vendor completed a PDMS deployment across anaesthesia and intensive care departments at a state hospital, extending a centralized standardized documentation model to multiple provincial hospitals. Another vendor's cloud-based hospital information and electronic patient record platform reached production at a major medical center, with a phased transition away from legacy systems extending through the following year. Concurrently, a ransomware incident affecting a widely used electronic patient record portal disrupted operations for a substantial portion of hospital organizations, underscoring the operational and reputational stakes tied to platform security. Integration-focused demonstrations have further highlighted the push toward closed-loop processes and point-of-care hardware and monitoring integration, signaling that PDMS is increasingly evaluated as part of a broader clinical technology ecosystem rather than a standalone documentation tool.
Patient Record Management Market
The market is evolving along three overlapping paths. First, consolidation pressure is growing as buyers prefer fewer, more capable platforms that can cover multiple departments and device types, reducing integration overhead and vendor management complexity. Second, differentiation is sharpening around clinical specificity, with vendors competing on anaesthesia, ICU, neonatal, and medication management capabilities rather than generic data capture. Third, new entrants and integration specialists are probing niches where cloud-native architecture, streamlined compliance updates, or specialized device interoperability can offset the incumbency advantages of larger players. The net effect is a market where share is defended through integration depth and compliance readiness, while growth is increasingly contested in segments where deployment model, security posture, and workflow fit matter more than brand recognition alone.
Forward Outlook: Three Trends That Will Define 2026 to 2032
The market's next phase will be shaped by the interaction of integration expectations, security realities, and regulatory continuity. Three trends are likely to dominate strategic planning for the coming years.
- Integration will become the primary value proposition, not a feature. As PDMS is expected to connect devices, documentation, and broader hospital information environments, the competitive advantage will shift from data capture to data orchestration. Platforms that can normalize device outputs, maintain consistent semantics across departments, and support cross-hospital communication will command stronger positioning. The opportunity lies in designing for interoperability as a default architecture, with standardized interfaces and continuous alignment to evolving functional requirements.
- Security and resilience will reprice risk and procurement criteria. High-profile disruptions to electronic patient record platforms have made cybersecurity a central element of vendor evaluation. Buyers will increasingly prioritize architectures with robust access controls, segmented operations, tested recovery processes, and transparent incident readiness. For vendors, the commercial implication is that security maturity may become a differentiator that shortens sales cycles for risk-averse buyers while exposing weaker platforms to prolonged scrutiny. The uncertainty is that threat landscapes and regulatory expectations will continue to evolve, requiring ongoing investment that may pressure margins if not managed efficiently.
- Regulatory integration will shift from periodic certification to continuous compliance. With new guidelines and regulations being embedded directly into PDMS standard content, vendors must treat compliance as an operational discipline. This dynamic favors platforms with structured update mechanisms, clear traceability between regulatory changes and product content, and the ability to demonstrate risk management continuity. The business opportunity is to reduce the lag between regulatory change and product readiness, which can become a decisive factor in public procurement and hospital IT approvals. The risk is that vendors unable to absorb this continuous load will face rework, delays, and competitive disadvantage.
These trends intersect with commercial models in ways that will matter for both suppliers and buyers. Deployment architectures will increasingly blend on-premises device connectivity with cloud-hosted record and documentation layers, creating hybrid environments that demand careful orchestration of data flow, access control, and maintenance responsibilities. Funding and regulatory incentives will continue to influence regional adoption patterns, making some geographies more responsive to near-term expansion while others remain constrained by budget cycles and implementation capacity. The overarching opportunity is to align product roadmaps and commercial narratives with the reality that PDMS is becoming a regulated, integrated, and security-sensitive component of clinical infrastructure rather than a discretionary IT enhancement.
Strategic Recommendations for Decision Makers
The market's trajectory offers distinct implications for manufacturers, investors, and procurement leaders. Each group faces a different set of priorities, but all benefit from treating PDMS as a continuously evolving clinical data and compliance platform rather than a static software purchase.
For manufacturers and platform vendors. Prioritize integration architecture and security readiness as core product investments, not ancillary capabilities. Buyers are evaluating device connectivity breadth, documentation centralization, and the ability to embed regulatory updates into standard content, so differentiation should be built around clinical workflow fit, interoperability reliability, and demonstrable risk management continuity. Where possible, position PDMS as part of a hospital-wide data strategy that reduces silos, supports cross-department documentation, and aligns with evolving electronic patient record environments. Continuous compliance mechanisms and transparent update practices can become meaningful commercial advantages in procurement cycles that increasingly weight regulatory maturity.
For investors and strategic backers. Focus on vendors whose value proposition is tied to integration depth, clinical specificity, and resilience rather than pricing alone. The concentration dynamics suggest that scale incumbents retain advantages, but the distributed share outside the leaders indicates room for differentiated platforms that address cloud migration, security maturity, and specialized workflows in anaesthesia, ICU, and neonatal settings. Monitor deployment milestones, platform transition timelines, and security incident responses as leading indicators of operational credibility. Be mindful that margin profiles can be affected by the ongoing investment required for compliance updates, integration maintenance, and security hardening, making operating discipline as important as growth potential.
For hospital leaders and procurement teams. Treat PDMS selection as a multi-year operational decision that should be evaluated against integration scope, security architecture, compliance continuity, and clinical workflow alignment. Favor platforms that can communicate across monitors, ventilators, infusion pumps, and electronic patient records without creating new documentation silos, and verify that risk management and approval processes are clearly defined and maintained. Weigh the total cost of ownership including hosting, maintenance, resilience, and incident recovery rather than focusing narrowly on initial implementation cost. Demand evidence of how regulatory updates are incorporated into standard content and how the platform supports centralized documentation with improved data quality across departments.
Timely, granular intelligence is essential because the market is changing on multiple fronts at once: integration expectations, security realities, regulatory content, and deployment models are all shifting within the same procurement and planning cycles. Detailed segment data, regional dynamics, and vendor-specific implementation patterns can materially affect go-to-market priorities, investment theses, and purchasing decisions. For decision makers who need deeper segmentation, competitive benchmarking, and customized scenario planning, PW Consulting's full research report provides extended data and tailored guidance to support execution.
For detailed analysis of this topic, please visit the official page: Patient Data Management Systems (PDMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


