



Cloud Gaming Market: Why 28.25% CAGR Redefines Gaming Infrastructure Through 2032

Cloud Gaming Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
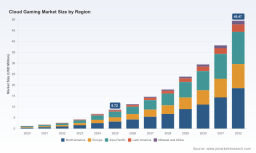
The cloud gaming market has transitioned from an experimental concept to a commercially viable sector over the past half-decade. From a base of $1.25 billion in 2020, the sector reached $8.72 billion by 2025, reflecting a compound annual growth rate of 28.25 percent. Forecasts project the market will surpass $11 billion in 2026 and scale to approximately $49.47 billion by 2032. This trajectory signals more than incremental adoption; it indicates a structural shift in how content is delivered, consumed, and monetized across consumer electronics and digital entertainment ecosystems.
Such rapid expansion, however, rests on fragile foundations. The industry currently confronts three critical challenges that will define competitive outcomes over the next several years. First, infrastructure scalability remains uneven. Delivering consistently high-fidelity experiences requires dense edge computing coverage and robust broadband capacity, yet network quality varies dramatically across geographies. Regions with advanced telecommunications infrastructure are experiencing accelerated adoption, while markets dependent on legacy networks face persistent latency and bandwidth constraints that undermine user retention.
Second, content economics and licensing complexity continue to pressure unit profitability. Cloud gaming platforms must negotiate rights agreements with publishers, manage localization requirements, and align game catalogs with regional preferences. These negotiations consume significant operational resources and create friction when attempting to scale service offerings globally. Platforms that rely heavily on licensed third-party titles face margin compression unless they can demonstrate clear value differentiation to rights holders.
Third, user acquisition costs and retention dynamics present a persistent challenge. While initial trial adoption has grown, converting free-tier or trial users into sustained subscribers requires continuous investment in service quality, exclusive content, and ecosystem integration. Churn remains elevated in markets where alternative entertainment options compete for disposable income and screen time. Platforms that fail to build sticky user relationships through hardware integration, social features, or personalized experiences risk cyclical reacquisition cycles that erode lifetime value.
Key Drivers Accelerating Market Growth
Technological Innovation and Streaming Optimization
Advances in encoding algorithms, GPU virtualization, and edge computing have substantially reduced the technical barriers that once limited cloud gaming viability. Modern streaming pipelines now deliver higher resolutions and frame rates with lower latency, widening the addressable device base beyond traditional gaming hardware. The integration of artificial intelligence into streaming optimization, demonstrated by recent platform enhancements from NVIDIA in early 2026, illustrates how algorithmic improvements can dynamically adjust quality parameters based on network conditions and device capabilities. These technical breakthroughs reduce the dependency on high-end local hardware and enable premium experiences on smartphones, tablets, and televisions that previously could not support demanding titles.
Policy and Regulatory Environment
The regulatory landscape is undergoing rapid reconfiguration, with implications for infrastructure investment and market entry strategies. In mid-2025, the Federal Communications Commission moved to eliminate net neutrality rules and remove broadband provider restrictions as part of a broader deregulatory initiative. This shift alters the competitive dynamics for content delivery, potentially reducing compliance burdens for cloud gaming operators while raising questions about long-term network neutrality and prioritization practices. Simultaneously, European policymakers are pursuing digital sovereignty objectives. The European Commission's March 2026 proposal for a Technological Sovereignty Package and the €75 million allocation to the EURO-3C federated telco-edge-cloud project signal a strategic push to strengthen regional cloud infrastructure autonomy. These initiatives create both opportunities for localized infrastructure partnerships and compliance complexity for operators navigating divergent regulatory regimes across continents.
Demand-Side Shifts in Consumer and Enterprise Behavior
Consumer expectations increasingly favor convenience, cross-device continuity, and instant access over ownership of discrete hardware. Gamers are demonstrating willingness to stream titles across smartphones, tablets, PCs, and connected televisions, reducing the threshold for entry into interactive entertainment. This behavior aligns with broader digital consumption trends where subscription access replaces one-time purchases, and where content libraries are expected to be available anywhere. Enterprise and educational sectors are also exploring cloud-based interactive environments for training, simulation, and collaborative applications, extending demand beyond consumer gaming and creating adjacent revenue streams for platforms that can adapt their streaming infrastructure to non-gaming use cases.
Gaming Market
Supply Chain and Cost Structure Evolution
Data center energy demand is reshaping operating cost calculations for cloud-intensive services. U.S. data centers are projected to nearly double their combined energy consumption from approximately 80 gigawatts in 2025 to 150 gigawatts by 2028. For cloud gaming operators, this trend translates into higher infrastructure costs unless mitigated through efficient cooling technologies, renewable energy sourcing, and workload optimization. Companies that invest in energy-efficient architectures and strategic power procurement will gain cost advantages that compound over time, particularly as scale increases and marginal compute costs become a more significant factor in service profitability.
Competitive Landscape and Leading Strategies
Strategic Positioning and Differentiation
The market features a mix of platform-scale incumbents, hardware-integrated operators, and specialized streaming providers. Microsoft has expanded Xbox Cloud Gaming access through device optimizations and Azure edge node improvements, broadening reach to existing hardware ecosystems while leveraging its subscription content library. This approach emphasizes ecosystem leverage, using cloud streaming as an extension of a broader gaming and services portfolio rather than a standalone revenue center. NVIDIA differentiates through technical performance, offering RTX-powered virtual GPUs that enable high-fidelity streaming at elevated resolutions and frame rates. Its recent platform enhancements focus on AI-driven quality optimization and broader device compatibility, positioning performance fidelity as a core value proposition for enthusiasts and performance-sensitive users.
Amazon Luna continues to integrate cloud gaming with Fire TV hardware, creating a direct streaming pathway for subscribers within a controlled device environment. This hardware-software alignment reduces friction for users already embedded in Amazon's consumer electronics ecosystem. Sony has pursued a parallel strategy by enabling cloud streaming of PlayStation titles to its Portal handheld device without requiring a console, effectively decoupling premium content access from dedicated gaming hardware. Blacknut has pursued a distribution-focused model, securing pre-installation partnerships on devices such as the Logitech G Cloud handheld, which provides immediate access to a large catalog of premium titles and reduces adoption barriers for hardware partners seeking to differentiate their products. Boosteroid operates as a multi-platform streaming service emphasizing broad device support and session quality, targeting users who prioritize accessibility across heterogeneous device environments rather than deep integration with a single hardware ecosystem.
Market Structure Evolution
Concentration trends indicate a maturing market where leading operators capture a disproportionate share of value. The top three providers account for approximately 57.3 percent of market revenue, while the top five reach 74.2 percent. This concentration reflects the advantages of scale in infrastructure investment, content licensing, and user acquisition. However, the landscape is not static. Hardware integration partnerships are creating niche entry points for specialized platforms, while telecommunications operators are beginning to bundle gaming services with network packages, as seen in recent 5G gaming offerings from European carriers. These developments suggest a trajectory toward both consolidation at the top and fragmentation at the edges, where device manufacturers, network providers, and regional platforms can carve out defensible positions through integration, localization, or niche performance specialization.
New entrants face steep barriers in content rights, infrastructure scale, and brand trust, but opportunities exist for operators that align cloud gaming with adjacent value propositions. Device manufacturers can use pre-installed streaming platforms to enhance hardware appeal. Telecoms can differentiate broadband offerings with optimized gaming pathways. Regional platforms can compete on localization, language support, and publisher relationships that global incumbents may prioritize less aggressively. The strategic question for each participant is whether to compete on scale, on integration depth, or on specialized performance and service quality.
Future Trends and Commercial Opportunities
Edge-Native Infrastructure and Network-Service Bundling
Over the next three to five years, cloud gaming success will increasingly depend on proximity-aware infrastructure and network-level service optimization. As 5G standalone networks expand and edge computing nodes proliferate, operators that coordinate streaming delivery with telecommunications partners will gain latency and reliability advantages. Bundled offerings that pair broadband or mobile plans with gaming subscriptions will lower acquisition costs and increase stickiness, particularly in markets where telecoms hold strong consumer relationships. Commercial opportunities will emerge for platforms that design their service architecture to leverage these partnerships, including co-branded packages, zero-rating arrangements where permissible, and network-aware quality scaling that adapts experience parameters to connection characteristics.
Hardware-Software Convergence and Ecosystem Lock-In
The boundary between cloud gaming services and consumer hardware will continue to blur. Handheld devices, smart televisions, and connected set-top boxes will increasingly ship with streaming platforms pre-integrated, reducing the friction of initial adoption and creating default access pathways. This convergence benefits hardware manufacturers seeking differentiation and service providers seeking scaled distribution. The commercial implication is clear: platforms that secure pre-installation or deep integration agreements with device makers will capture a larger share of incremental users, while those relying solely on app-store discovery or web-based onboarding will face higher acquisition costs and lower conversion rates. Strategic partnerships with hardware OEMs, including co-marketing and joint optimization efforts, will become a decisive competitive lever.
AI-Driven Personalization and Adaptive Streaming Economics
Artificial intelligence will play an expanding role in both user experience and operational efficiency. Adaptive streaming algorithms will optimize bitrate, resolution, and frame delivery in real time based on network conditions, device capabilities, and user preferences. On the content side, AI-assisted curation and recommendation systems will improve discovery, reducing the friction that leads to trial abandonment. These capabilities create opportunities to increase engagement and reduce churn without proportional increases in content licensing spend. However, the same technologies raise expectations for service quality, and platforms that lag in adaptive optimization may experience disproportionate user dissatisfaction as baseline expectations rise across the market.
Risk Factors and Uncertainties
Several uncertainties could alter the trajectory outlined above. Regulatory divergence between regions may complicate global service architectures, particularly as digital sovereignty initiatives encourage localized infrastructure requirements. Energy cost escalation for data centers could compress margins unless offset by efficiency gains or favorable power contracts. Content rights negotiations may become more expensive as publishers recognize the strategic value of cloud distribution and demand higher revenue shares or exclusivity terms. Finally, competitive intensity could trigger price compression in subscription tiers, forcing platforms to differentiate through performance, integration, or exclusive content rather than price alone. Operators that build diversified revenue streams and maintain flexibility in infrastructure and licensing strategies will be better positioned to navigate these variables.
Strategic Recommendations for Decision Makers
For Platform Operators and Device Manufacturers
Prioritize integration depth over standalone reach. Embedding cloud gaming capabilities into hardware product lines, operating system environments, or network service bundles creates inherent distribution advantages that pure software-play strategies struggle to replicate. Invest in adaptive streaming quality and device-specific optimization to ensure that the user experience meets expectations across heterogeneous conditions. Where possible, pursue partnerships with telecommunications providers to align service delivery with network capabilities and to access bundled customer acquisition channels. For hardware manufacturers, treat pre-installed streaming platforms as a product differentiator and negotiate terms that ensure catalog relevance and technical compatibility over the device lifecycle.
For Investors and Strategic Capital Allocators
Evaluate operators based on infrastructure efficiency, content licensing sustainability, and ecosystem integration rather than headline user growth alone. Metrics such as cost per streaming hour, retention curves by acquisition channel, and the proportion of revenue derived from integrated hardware or network partnerships offer clearer signals of durable competitive advantage than top-line subscriber counts. Favor business models that combine recurring subscription revenue with ancillary monetization paths, including hardware margins, network bundling fees, or enterprise and education extensions. Monitor regulatory developments in key regions, as digital sovereignty and infrastructure policies will influence where capital can be deployed most efficiently and which operators gain preferential access to local edge resources.
Gaming Laptop Market
For Procurement and Partnership Decision Makers
When selecting cloud gaming service providers or infrastructure partners, assess streaming reliability under variable network conditions, the flexibility of content catalogs, and the operator's ability to support multiple device form factors. Prioritize partners that demonstrate a clear roadmap for adaptive quality optimization and that maintain transparent performance reporting. For organizations exploring cloud gaming as a component of broader digital entertainment or training strategies, consider the long-term implications of vendor lock-in and negotiate terms that preserve portability and integration flexibility. Track infrastructure energy commitments and sustainability practices as indicators of long-term cost discipline and operational resilience.
PW Consulting
The cloud gaming market is entering a phase where differentiation will be determined less by the mere availability of streaming and more by the quality of integration, the efficiency of delivery, and the durability of user relationships. Decision makers who align their strategies with these structural drivers will be better positioned to capture value as the market scales toward the end of the decade. For organizations requiring detailed segmentation data, regional breakdowns, competitive benchmarking, and customized scenario analysis, comprehensive research resources are available to support deeper evaluation and strategic planning.
For detailed analysis of this topic, please visit the official page: Cloud Gaming Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


