



Cold Milling Machine Market: 6.26% CAGR and the Strategic Shifts Reshaping 2026–2032 Growth

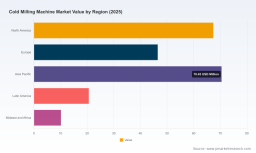
Strategic Trends and Commercial Opportunities in the Cold Milling Machine Market
The global cold milling machine market has entered a phase of sustained expansion, driven by aging infrastructure, tightening environmental mandates, and a strategic shift toward high-efficiency pavement rehabilitation. Valued at approximately $215 million in 2025, the market has grown at a compound annual growth rate of 6.26 percent over the 2020 to 2025 period and is projected to reach $345 million by 2032. This trajectory reflects more than cyclical road maintenance spending; it signals a structural transformation in how contractors approach surface rehabilitation, material recycling, and emissions compliance. The next seven years will be defined by technological differentiation, regulatory alignment, and regional demand rebalancing.
Reconciliation of Physical Infrastructure Reality and Environmental Mandates
The market's underlying growth is rooted in a pragmatic reality: governments and private developers cannot afford to rebuild entire pavement networks from scratch. Instead, they rely on cold milling as a targeted, cost-effective method to remove deteriorated layers, prepare binding surfaces, and recover reusable aggregates. This operational logic has remained consistent, but the execution environment has changed dramatically. Contractors now face overlapping pressures: tighter municipal budgets, stricter noise and emission limits at urban job sites, and client expectations for project completion times that align with modern logistics windows. Machinery that simply removes asphalt or concrete is no longer sufficient. The winning equipment must integrate precise depth control, consistent output, and verifiable sustainability metrics while maintaining operational flexibility across multiple pavement types.
At the same time, the market confronts fragmentation in adoption readiness. Developed regions with mature road networks are prioritizing fine milling, surface rehabilitation, and emissions-reduced operations. Emerging markets are still scaling basic rehabilitation capacity, often balancing imported high-performance equipment against domestically manufactured alternatives. Navigating this divide requires a clear view of where regulatory pressure converts into procurement behavior, and where cost sensitivity still dictates purchasing decisions.
Key Drivers Shaping Market Dynamics
Technological Innovation and the Automation of Precision Milling
The most consequential shift in the market is the transition from mechanical power to controlled, data-enabled precision. Modern cold milling machines increasingly embed intelligent drum speed regulation, grade and slope tracking, and operator-assist systems that reduce variability in cut depth and material consistency. These capabilities directly affect downstream paving quality and the efficiency of material recycling. When a milling pass produces predictable particle size and uniform surface preparation, contractors spend less time on corrective work and more time maintaining throughput.
Recent product introductions illustrate this trajectory. Wirtgen Group's W 210 XF and W 250 XF models, unveiled in early 2025, emphasize high-output milling combined with advanced automation. The W 250 XF was presented as a high-capacity platform with dual-engine architecture and refined milling technology, targeting large-scale rehabilitation where output and consistency determine project economics. Alongside larger platforms, the same manufacturer introduced the W 50 Re battery-electric small milling machine and an updated generation of recyclers designed for lower specific emissions. This pairing of large-scale high-power machines with compact electrified alternatives reflects a broader industry recognition: different job profiles require different power and control architectures, and electrification is entering the market not as a single solution but as a modular option.
From a commercial standpoint, automation is not merely a feature upgrade. It is becoming a procurement criterion. Contractors evaluating bids increasingly weigh whether a machine can reduce operator fatigue, improve cut consistency across long runs, and provide feedback loops that support maintenance planning. Equipment that integrates these functions into a coherent workflow offers a practical advantage in labor-constrained environments and in projects where site access limits the margin for error.
Worldwide Milling Machine Market
Regulatory Pressure and Emissions Compliance as Procurement Catalysts
Environmental regulation has moved from a compliance backdrop to an active determinant of machine selection. European and global frameworks continue to tighten carbon emission expectations for construction equipment, with enforcement and reporting requirements making real-time emissions visibility more valuable. In this environment, cold milling machines that generate transparent performance data and meet advanced emission standards are better positioned for public tenders and large contractor fleets.
Recent regulatory-aligned developments demonstrate how manufacturers are responding. Wirtgen's latest large milling machines incorporate EU Stage 5 and US EPA Tier 4f emission standards alongside real-time CO2 tracking through performance monitoring systems. Caterpillar's PM Series cold planers are designed around Tier 4 Final and Stage V compliant engines to support sustainable construction and reduce operating cost exposure tied to emissions compliance. Rather than treating emissions as an abstract requirement, leading manufacturers are connecting compliance to operating economics: fuel efficiency, maintenance intervals, and fewer regulatory disruptions on urban or sensitive job sites.
This dynamic matters for strategic planning because it introduces a second layer of value beyond raw capacity. Machines that document emissions performance, reduce specific fuel consumption, and support fleet reporting are easier to justify in tender processes where environmental scoring is part of the evaluation. Over the forecast period, this trend is likely to widen the gap between equipment that meets minimum compliance and equipment that actively supports sustainability reporting and cost control.
Demand-Side Shifts Toward Rehabilitation, Recycling, and Lifecycle Thinking
Demand is increasingly shaped by a lifecycle view of pavement assets rather than a replacement mindset. Municipalities, roadway authorities, and large contractors are focusing on rehabilitation strategies that extend service life, recover aggregates, and reduce the need for virgin material inputs. Cold milling sits at the center of this shift because it enables precise removal of distressed layers and produces milled material that can be reintroduced into recycling streams or base layers.
This demand evolution changes how buyers evaluate machines. Output capacity remains important, but it must be balanced against the ability to handle different materials, switch between coarse and fine milling tasks, and support downstream recycling workflows. Contractors operating in regions with high volumes of asphalt rehabilitation are prioritizing consistent milling quality and rapid setup changes, while concrete rehabilitation users need equipment that manages more abrasive surfaces and maintains drum performance over extended usage. The practical implication is that demand is fragmenting by application logic even as overall market volume rises.
A second demand-side pressure is job-site logistics. Urban rehabilitation projects increasingly require equipment that can operate within constrained access windows, minimize noise impact, and adapt to tighter footprints. This favors machines that combine maneuverability with reliable output and that can integrate into coordinated paving and recycling operations without becoming a bottleneck. In practical terms, the strongest commercial opportunities are emerging where cold milling equipment is sold not as a standalone tool but as part of an integrated rehabilitation process.
Supply Chain Realities and Cost Structure Reframing
Equipment economics are also being reshaped by supply chain considerations and operating cost structures. Engine availability, component sourcing, and the cost of maintaining compliance with evolving emission systems all influence total cost of ownership. High-horsepower platforms, in particular, depend on reliable engine supply and service networks that can support advanced exhaust aftertreatment and diagnostic systems. Any disruption in these areas affects uptime and can alter the attractiveness of certain machine architectures.
At the same time, fuel efficiency has become a direct commercial lever rather than a secondary benefit. Advanced drum speed control and optimized transmission systems can deliver measurable fuel savings, which matters in markets where operating costs are under scrutiny and where contractors run machines for long shifts. Fuel consumption is no longer just an engineering metric; it is a tender differentiator and a fleet budgeting variable. In that sense, cost structure is moving from a static procurement concern to a dynamic performance target.
Competitive Landscape and Strategic Positioning
The market is moderately concentrated, with the top three players holding approximately 24.6 percent of the market and the top five reaching around 26.2 percent. This level of concentration suggests that scale, brand recognition, and technology leadership are rewarded, but it also leaves meaningful room for differentiated regional participants, application specialists, and new entrants targeting specific job profiles or price-performance segments. Competition is increasingly defined less by raw size and more by the ability to deliver compliant, efficient, and operationally intelligent machines that match local demand patterns.
Wirtgen Group stands out for portfolio breadth and technology integration. Its lineup spans compact models to large platforms, with recent additions emphasizing automation, mill assist controls, and performance tracking for milling operations. The company's 2025 introductions, including the W 210 XF and W 250 XF, reinforce a high-performance large-machine strategy while its battery-electric small milling machine and updated recycler generation indicate a parallel push toward lower specific emissions and electrified compact equipment. The strategic signal is clear: the company is positioning across multiple power and scale points, using automation and emissions visibility as differentiators.
Caterpillar contributes a different kind of strength: large-engine reliability, emissions compliance, and telematics integration. Its PM Series half-lane cold planers, including models such as PM825 and PM620, are built around high-horsepower engines and Tier 4 Final compliance, with telematics support aimed at fleet management and operational efficiency. Caterpillar's positioning benefits from its broader construction equipment ecosystem, where service networks, parts logistics, and machine data integration can extend value beyond the cold planer itself. For contractors managing multiple asset types, that ecosystem appeal can be decisive.
Regional and application-focused players continue to shape competitive dynamics in specialized ways. Bomag, Dynapac, Volvo Construction Equipment, Sakai, Roadtec, and CMI Roadbuilding each maintain cold milling offerings aligned with particular operating profiles or regional expectations. Roadtec's RX Series cold planers, for example, were updated in early 2025 with higher-horsepower Caterpillar Tier 4 Final engines to target higher production and reliability. These participants often compete on feature-fit, service responsiveness, and application alignment rather than attempting to lead on sheer portfolio scale.
In Asia, SANY Group, XCMG Group, LiuGong, and Shantui represent a distinct competitive dynamic. Their SCM, XM, 5100-2/SM, and SM series machines demonstrate strong capability in road construction and infrastructure applications, with a focus on cost-effective high-performance equipment for local and export markets. The strategic implication is that competition is not only about premium features; it is also about whether manufacturers can balance compliance, durability, and price in ways that match the procurement realities of fast-growing infrastructure regions.
Several competitive trends are emerging. First, there is a clear convergence around compliance-driven engineering, with manufacturers treating emission standards and fuel efficiency as baseline expectations rather than optional enhancements. Second, product launches are increasingly paired with digital value propositions, whether through performance tracking, telematics, or operator-assist features. Third, the market is not consolidating into a single winner-takes-most pattern; instead, it is fragmenting by application, power architecture, and region. That means competitive advantage will depend on matching machine characteristics to specific procurement priorities, not simply on offering the largest or most expensive platform.
Future Trends and Commercial Implications
Electrification and Alternative Powertrains Will Expand by Job Profile
Electric and low-emission configurations are entering the market in targeted forms rather than as blanket replacements. Compact milling tasks, urban rehabilitation, and environments with strict site emissions limits are likely to be the earliest adoption zones. Over the next three to five years, expect battery-electric and hybrid-enabled machines to broaden where site constraints, noise restrictions, or localized sustainability requirements make conventional diesel operation less attractive. Commercial opportunity lies not just in selling an alternative powertrain but in defining the applications where it delivers a credible cost and operational case. Manufacturers and distributors that understand which job profiles justify electrified equipment, and how to support charging, deployment, and maintenance, will be better positioned to shape demand rather than react to it.
Cold Planers Market
Automation and Data Feedback Will Become Table Stakes for High-Value Tenders
Real-time milling control, grade support, and performance data capture are moving from premium differentiators to expected features in competitive procurement. As tender evaluation increasingly includes operating efficiency, emissions documentation, and process consistency, machines without meaningful data capabilities risk losing relevance in higher-value contracts. The commercial implication is that equipment value may shift from purchase price toward lifecycle performance and reporting utility. This favors manufacturers and service providers that can package machine performance with fleet diagnostics, maintenance insight, and verifiable operating metrics. It also creates an opening for service-led revenue models, where monitoring, diagnostics, and process optimization become part of the customer relationship.
Regional Demand Divergence Will Deepen Selection Logic
Market growth will not unfold uniformly. Regions with strict emission environments, mature rehabilitation practices, and dense urban projects will favor automated, compliant, and often electrified solutions. Regions focused on capacity expansion and cost efficiency will still reward durable, high-output machines that deliver reliable performance at a competitive total cost of ownership. This divergence means that successful commercial strategies will require regional calibration: product mix, service coverage, financing support, and application messaging all need to align with local procurement priorities. Companies that attempt a single global narrative across all markets will likely leave value on the table.
These trends carry uncertainty. Emissions frameworks may accelerate or shift implementation timelines. Electrification may progress faster in some geographies while remaining limited in others due to infrastructure and cost constraints. Fuel price volatility, component supply conditions, and changes in public infrastructure spending can all reshape the pace of adoption. Commercial planning should therefore treat these trends as directional indicators rather than fixed predictions, and build flexibility into product, service, and market-entry decisions.
Strategic Actions for Decision Makers
For manufacturers and equipment suppliers, the priority is to align product architecture with the real purchasing drivers of the next cycle. That means maintaining a credible path on emissions compliance, treating automation and data capture as core value elements instead of accessories, and explicitly mapping which machine sizes, power options, and features fit which applications and regions. Pricing and service strategies should reflect total cost of ownership, not only upfront specifications. Where feasible, offering bundled diagnostics, maintenance planning support, and emissions reporting capabilities can strengthen customer retention and differentiate offers in competitive bids.
PW Consulting Automotive & Machinery Research Center
For investors and strategic partners, the opportunity is to focus on the segments where regulatory pressure, rehabilitation demand, and technology adoption intersect most strongly. Equipment that combines compliance, fuel efficiency, and operational data is likely to command stronger positioning in tenders and fleet renewals. Vertical relevance matters as much as product specifications: distribution strength, service coverage, parts logistics, and the ability to support electrified or digitally integrated machines are becoming part of the investment thesis. Monitoring the pace of electrification adoption, the stability of emission compliance requirements, and regional procurement behavior will help identify where demand is real and where it is still aspirational.
For procurement leaders and contractors, the practical goal is to evaluate cold milling equipment against operational context rather than headline capacity alone. Project selection should consider cut precision, material recovery needs, site-access constraints, emissions documentation requirements, and the cost implications of fuel efficiency and maintenance intervals. When renewing fleets or entering multi-year rehabilitation programs, buyers benefit from specifying performance expectations that include consistency, reporting, and service support, not just milling width or engine power. Choosing equipment that fits the workflow reduces rework, improves scheduling predictability, and strengthens the business case for rehabilitation-focused projects.
In a market where specifications, compliance, and application fit increasingly determine winning offers, broad market awareness is useful but not enough. Detailed segmentation data, regional procurement patterns, competitive benchmarking, and product-level performance comparisons are what translate strategic direction into practical decisions. For that level of segmentation and actionable recommendation, interested parties can review the complete report.
For detailed analysis of this topic, please visit the official page: Cold Milling Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


