



Natural Astaxanthin Market: Why 9.1% CAGR & Shifting Demand Dynamics Redefine Growth

The Natural Astaxanthin Market: Strategic Trends and Commercial Opportunities
The natural astaxanthin sector has evolved from a niche antioxidant into a strategically significant ingredient market, driven by converging forces in health and wellness, aquaculture growth, and formulation innovation. Between 2020 and 2025, global revenue expanded from approximately 248.56 million to 372.0 million, reflecting a compound annual growth rate of 9.1 percent. Looking ahead to 2032, the trajectory points toward 686.45 million, with the forecast period (2026-2032) expected to sustain momentum as applications diversify and production systems mature. This growth is not uniform across sources, formats, or end-use categories, and the strategic value for decision-makers lies in understanding where scale, differentiation, and regulatory clarity intersect.
For executives, investors, and procurement teams, the market’s appeal rests on three characteristics: a rich antioxidant profile that commands premium positioning in human nutrition, a biologically active pigment that serves functional roles in animal health, and a supply base that is transitioning from fragmented cultivation to increasingly engineered production environments. Yet the sector is also navigating structural tensions around feedstock economics, regional regulatory divergence, and the balance between batch consistency and cost efficiency. The following analysis maps the current landscape, the forces reshaping it, the competitive postures defining it, and the strategic moves that will separate winners from followers over the next three to five years.
Market Snapshot and Core Tensions
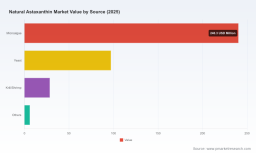
The macro picture is straightforward: demand is expanding, and the revenue curve is steepening as downstream applications broaden. What makes this market strategically interesting is not the headline growth alone, but the way value is distributed across production methods and form factors. Microalgae-derived astaxanthin represents the dominant share of the market, reflecting years of cultivation refinement and the ingredient’s positioning as a clean, plant-based antioxidant. Yeast-based routes account for a meaningful secondary share, offering distinct scalability and cost profiles. Smaller contributions come from krill and shrimp-derived sources, along with other niche inputs. The split matters because each source carries different cost structures, purity expectations, and application fit, which in turn shape pricing power and customer acquisition strategies.
On the formulation side, powder continues to lead in market share, underscoring its versatility across nutraceutical blends, feed premixes, and cosmetic bases. Oil-based formats remain important where bioavailability and sensory performance are priorities, while softgel and other consumer-ready forms occupy a smaller but growing niche as finished-product manufacturers seek convenience and perceived premium quality. Regionally, the market is balanced rather than concentrated in a single hub, with North America, Europe, and Asia Pacific each representing substantial demand centers, and Latin America plus the Middle East and Africa contributing more specialized but increasingly active demand. This geographic spread creates both diversification benefits and complexity in regulatory navigation.
Several structural tensions define the current inflection point. First, feedstock economics remain a persistent pressure point. Natural astaxanthin from Haematococcus pluvialis powder is the primary upstream feedstock for commercial production, with global output estimated at around 800 metric tons annually. This concentration creates sensitivity to cultivation yield, harvest timing, contamination risk, and energy inputs. Companies that can stabilize biomass supply and reduce per-unit production cost gain a durable advantage, but the pathway is capital-intensive and technically demanding.
Second, regulatory divergence is shaping where and how ingredients can be positioned. In the European Union, EFSA concluded in December 2025 that proposed uses of algal meal and oleoresin from Haematococcus pluvialis at levels exceeding the FEEDAP ADI of 0.034 mg/kg body weight per day cannot be established for non-food-supplement applications. At the same time, the powder with 5.0%–5.6% w/w ATX and oleoresin with 10%–12% w/w ATX has been restricted in the EU to food supplements since 1995 under novel food rules. These boundaries create a clear ceiling for certain feed and food uses in Europe, while simultaneously reinforcing the strategic importance of food supplement channels and premium nutraceutical positioning. AstaReal AB also submitted an application in December 2025 for novel food authorization covering algal meal, red viscous oleoresin, and water-dispersible formulations, signaling that the regulatory map is still being redrawn and that clarity, once achieved, can unlock new commercial pathways.
Third, the market is balancing scale against differentiation. With a CR3 of 42.5 percent and CR5 of 56.8 percent, the sector is moderately consolidated, but the room for regional specialists, formulation innovators, and application-specific suppliers remains meaningful. The tension lies in whether growth will be captured by producers who compete primarily on volume and cost, or by those who build defensible positioning through purity claims, traceability, application expertise, and regulatory readiness.
Key Drivers Reshaping the Market
Technology Innovation and Process Maturation
Production technology is moving from artisanal cultivation toward engineered control. Closed-system photobioreactors, improved strain performance, and tighter contamination management are reducing variability in biomass quality and astaxanthin yield. These advances matter because astaxanthin’s value proposition depends heavily on purity, isomer profile, and oxidative stability. Manufacturers that can deliver consistent specifications across batches gain credibility with formulators and finished-product brands, especially in nutraceuticals and cosmetics where claims and consumer trust are tightly linked to ingredient quality. At the same time, open-pond systems continue to play a role where cost efficiency and scale are paramount, particularly for feed-oriented volumes. The strategic question is not which system wins outright, but how each producer aligns technology choice with target applications and margin expectations.
Formulation technology is also advancing the commercial narrative. Water-dispersible and stabilized variants, beadlet integration, and oleoresin refinement expand the ingredient’s usability across matrices that historically posed dispersion or stability challenges. These improvements reduce formulation friction for customers and create opportunities for higher-value, application-tailored offerings rather than commodity-style transactions.
Policy and Regulatory Environment
Regulation is both a constraint and a catalyst. In Europe, the boundaries around feed and broader food uses are being clarified through EFSA opinions, which compresses certain expansion pathways while reinforcing the value of compliance-ready supply. In parallel, novel food authorization efforts signal potential future openings, especially if data packages support broader usage levels or new formulation types. For market participants, the strategic implication is that regulatory readiness is becoming a differentiator. Companies that proactively build dossiers, maintain documentation for traceability and safety, and align labeling and claims with regional requirements can move faster when opportunities open, and avoid disruption when restrictions tighten.
Beyond Europe, regulatory and certification dynamics in destination markets influence purchasing decisions in nutraceuticals, food and beverages, and aquaculture. Organic certification, GRAS status for food use, and contamination control documentation increasingly serve as gatekeeping criteria for buyers who need to defend ingredient choices to regulators, retailers, and end consumers. Regulatory alignment is therefore not simply a compliance exercise; it is a commercial enabler.
Demand-Side Shifts in Consumer and Enterprise Behavior
On the demand side, three shifts are particularly relevant. First, the nutraceutical segment continues to anchor demand for natural astaxanthin, supported by consumer interest in antioxidant support, eye health, skin health, and sports recovery formulations. This segment rewards clarity of benefit, clean-label positioning, and brand trust, which in turn favors suppliers that can provide documentation, consistency, and application support. Second, aquaculture and animal feed represent a large and growing demand pool, where astaxanthin’s functional role in pigmentation and health supports adoption in shrimp, salmon, and other species. Here, cost-per-unit performance, batch reliability, and regulatory compliance for feed applications are central, and pricing sensitivity is higher than in premium human nutrition. Third, cosmetics and food and beverage applications, while smaller in share, create high-visibility branding opportunities and can command premium positioning when combined with compelling sensory and stability attributes.
The broader behavioral trend is a move toward ingredients with documented origin, sustainable production stories, and transparency. Buyers are increasingly hesitant to treat natural astaxanthin as a interchangeable input; they want assurance that sourcing, extraction, and final specifications meet the requirements of their specific market and claim structure.
Fucoxanthin (CAS 3351-86-8) Market
Supply Chain and Cost Structure Evolution
Cost structure dynamics are shifting as production volumes scale and operational efficiency improves. Recent developments illustrate this clearly. In June 2025, Cyanotech Corporation reported meaningful improvement in gross margin for fiscal 2025, with increasing production volumes of BioAstin Hawaiian Astaxanthin driving lower per-unit costs. This is a useful signal that scale, when combined with process maturity, can translate into margin expansion rather than merely top-line growth. In May 2025, Beijing Gingko Group announced expansion of astaxanthin manufacturing facilities in Yunnan Province, including a new research laboratory to support its AstaZine natural astaxanthin line. Capacity expansion of this kind indicates confidence in demand durability and a push to strengthen both volume and technical capabilities. Meanwhile, in July 2024, Algatechnologies introduced AstaPure 5% natural astaxanthin for softgels, extending its product line with all-natural extracts. Moves like this show how suppliers are layering formulation-specific offerings onto core production capabilities to capture more value.
The broader supply chain implication is that advantage is increasingly determined by integrated control over cultivation, extraction, and finishing, or by strong partnerships that achieve the same effect. Fragmented, transactional supply chains create exposure to quality variation and price volatility, while integrated or closely coordinated models support specification reliability, margin retention, and faster response to customer needs. Energy costs, water management, and contamination control remain critical cost drivers, especially for microalgae-based systems, and will continue to separate efficient operators from less optimized ones.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The market’s competitive core includes a mix of established producers with proprietary cultivation and extraction systems, regional specialists with strong application focus, and larger nutrition and ingredient groups leveraging astaxanthin as part of broader portfolios. The strategic distinction lies less in participation alone and more in how each company constructs defensibility.
AstaReal Inc. operates with a clear brand-centered strategy around natural astaxanthin from Haematococcus pluvialis microalgae, supported by patented cultivation systems and contributions to standards development. Its emphasis on branded extracts, oleoresin, and powder across nutraceutical, cosmetic, and food applications reflects a premium, documentation-rich approach that targets customers seeking reliability and claim support.
Cyanotech Corporation has built a long-standing position around integrated Haematococcus pluvialis cultivation and extraction, with patented open-pond technology and GRAS certification for food use. Its BioAstin Hawaiian Astaxanthin line illustrates how regional identity, certification, and production scale can combine into a recognizable offering. Recent margin improvement tied to higher production volumes reinforces the value of scaling mature processes efficiently.
Algatechnologies Ltd. focuses on high-purity natural astaxanthin from closed-system cultivation, supplying premium extracts and oleoresin with strict contamination control for nutraceuticals, cosmetics, and aquaculture. Its emphasis on purity and controlled environments aligns with buyers who prioritize specification consistency and risk reduction, particularly in sensitive applications.
Beijing Gingko Group stands out as a large-scale producer of natural astaxanthin from Haematococcus pluvialis, offering certified organic biomass, powder, and extracts for global nutraceutical and feed markets. Its scale, ongoing facility expansion, and research investment position it to compete on volume, cost, and broad application coverage, while also building technical depth.
Algalif Iceland operates a large-scale photobioreactor facility and supplies sustainable Haematococcus-derived extracts under its own brand for premium nutraceutical applications. Its strategy highlights how geographic identity, controlled production, and sustainability narratives can support premium positioning in targeted downstream markets.
Fuji Chemical Industry contributes through natural astaxanthin manufacturing via its AstaReal subsidiary, providing high-purity extracts, beadlets, and formulations for human consumption and related applications. This reflects a formulation-oriented model that adds value through finished or semi-finished formats tailored to end-use requirements.
Divis Laboratories Limited participates as a supplier of natural astaxanthin extracts and derivatives, with focus on nutraceutical and cosmetic grades and sustainable sourcing. Its role illustrates the importance of specialty extraction and derivative capabilities in markets where customization and grade differentiation matter.
Astaxanthin (CAS 472-61-7) Market
Differentiation, Consolidation, and New Entry Dynamics
Differentiation is coalescing around several axes: purity and specification control, application-specific formulation support, regulatory readiness, sustainability and traceability claims, and the ability to scale without sacrificing consistency. The most resilient players tend to combine at least two of these strengths rather than competing on a single dimension. For example, a producer may pair controlled cultivation with strong documentation, or combine scale with brand and certification advantages that help customers justify ingredient choices to their own stakeholders.
The market is not moving toward extreme concentration in the near term, but selective integration is likely. Expect more partnerships between cultivation specialists and formulation or distribution networks, more regional capacity investments aligned with local demand and regulatory conditions, and more vertical coordination where producers seek to control feedstock, extraction, and finishing to protect margin and quality. At the same time, new entrants will continue to appear where they can offer a credible technology edge, a defensible sustainability story, or access to an underserved application. The barrier is not simply capital; it is the ability to deliver consistent quality, navigate regulatory complexity, and build buyer trust in a market where claims and contamination risk carry real consequences.
Future Trends and Commercial Opportunities
Over the next three to five years, several trends are likely to define the market’s evolution.
-
Application diversification with a premium core. Nutraceuticals will remain the anchor, but growth will increasingly come from better-matched formulations, stabilized variants, and application-specific grades that reduce customer friction and support stronger positioning. Cosmetics and food and beverage uses will remain smaller in share but can deliver outsized brand value when paired with sensory quality and regulatory compliance.
-
Regulatory clarity as a competitive filter. As novel food and feed-related assessments progress, the regulatory map will become clearer in some regions and more constrained in others. Companies that have already invested in documentation, safety data, and compliant positioning will be better placed to expand into newly authorized uses or defend existing channels when restrictions crystallize.
PW Consulting -
Margin improvement through scale and process control. The recent margin improvement reported by established producers suggests that scale, when combined with mature cultivation and extraction processes, can convert volume growth into profitability. Capacity expansions and research investments indicate that leading players are preparing for sustained demand rather than treating growth as a short-cycle opportunity.
-
Sustainability and traceability as purchase criteria. Buyers are increasingly weighing origin, energy and water intensity, and supply transparency. Producers that can substantiate sustainability claims and provide traceable batches will gain advantage in premium segments and in procurement environments where reputational risk matters.
These trends translate into concrete commercial opportunities. For producers, the opportunity lies in aligning capacity and technology with the applications that offer the best combination of margin, growth, and defensibility, rather than chasing all segments equally. For ingredient buyers and formulators, there is an opportunity to secure reliable supply of specification-consistent astaxanthin that supports stronger claims, cleaner labels, and more stable procurement costs. For investors, the appealing thesis centers on operators that combine process maturity, regulatory readiness, and application focus with a credible path to margin expansion as volumes scale.
Potential risks and uncertainties should not be understated. Feedstock availability and cultivation risk can affect supply consistency and pricing, particularly if contamination events or yield variability intensify. Regulatory outcomes may narrow certain applications in key regions, especially where feed and broader food uses face tighter limits. Competitive intensity could compress margins if supply expands faster than demand in specific formats or regions. And claim substantiation expectations may rise, increasing the cost of doing business for suppliers that cannot provide robust documentation and traceability. These risks do not negate the growth outlook, but they do mean that execution quality will determine who captures value.
Strategic Recommendations for Decision-Makers
For manufacturers and producers, the priority is to match technology and capacity strategy to the applications where differentiation is most defensible. If the target is premium nutraceuticals and cosmetics, investment in controlled cultivation, purity assurance, and documentation is likely to pay off more than pure volume expansion. If the target includes aquaculture and feed, the focus should be on cost efficiency, batch reliability, and compliance with regional feed rules, while preserving enough quality consistency to maintain customer trust. In both cases, formulation-specific offerings and finished or semi-finished formats can help capture more value than commodity supply alone.
For investors, the most compelling opportunities are likely to be found in operators that demonstrate a combination of process maturity, credible regulatory readiness, and a clear application focus. Capacity expansion is meaningful only when paired with the ability to convert volume into margin, and regulatory navigation is increasingly part of the valuation story. Due diligence should examine not just scale and geography, but also contamination control, documentation quality, formulation capability, and the durability of customer relationships in segments where specification consistency matters.
For procurement teams and formulators, the strategic move is to treat natural astaxanthin as a specification-driven ingredient rather than a interchangeable input. Locking in supply partnerships with suppliers that can provide consistent batches, transparent origin, and application support will reduce reformulation risk and strengthen claim confidence. Diversifying across sources and formats where appropriate can also mitigate exposure to regional regulatory shifts or feedstock constraints, especially when planning for longer-term product roadmaps.
The market’s next phase will reward participants who combine technical discipline with commercial clarity. As regulatory boundaries become sharper, production systems become more engineered, and buyers demand stronger documentation and sustainability assurance, the winners will be those who can deliver consistent quality at scale while aligning their offerings to the applications that matter most. For decision-makers seeking to move from broad market awareness to actionable planning, deeper segmentation, supplier benchmarking, and region-specific regulatory mapping will be essential. PW Consulting’s full research report on the natural astaxanthin market provides that level of detail, including segmented demand dynamics, competitive benchmarking, and tailored recommendations designed to support investment, sourcing, and product strategy decisions.
For detailed analysis of this topic, please visit the official page: Natural Astaxanthin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


