



Sodium Permanganate Market: Why 4.6% CAGR and Water Treatment Demand Change Everything

Sodium Permanganate Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
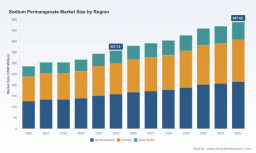
The global sodium permanganate market is navigating a period of structural transformation, defined by steady expansion against a backdrop of regulatory tightening, raw material volatility, and evolving end-use requirements. Over the historical period spanning 2020 through 2025, market revenue demonstrated consistent upward movement, reflecting both post-pandemic industrial recovery and sustained investment in critical infrastructure. The base year of 2025 marks an inflection point where demand growth has begun to outpace earlier cyclical patterns, driven by capital expenditure programs in water infrastructure and electronics manufacturing. The forecast window through 2032 projects a compound annual growth rate of 4.6 percent, suggesting that the market will continue to expand at a moderate but resilient pace, supported by long-cycle investments rather than short-term discretionary spending.
Scale alone, however, does not define the strategic landscape. The market exhibits a pronounced concentration profile, with the top three firms controlling approximately seventy percent of revenue and the top five firms capturing roughly three-quarters of total share. This structure implies limited competitive fragmentation, high barriers to entry around certification and distribution networks, and a pricing environment where incumbents can exert meaningful influence over contract terms. At the same time, concentrated markets are vulnerable to supply shocks and regulatory adjustments that can cascade quickly through the value chain. The current environment presents several interrelated challenges that decision-makers must address.
First, raw material cost volatility has become a persistent pressure point. Manganese-based inputs underpin sodium permanganate production, and recent pricing movements in related chemical streams have introduced margin uncertainty. Quarter-over-quarter increases in manganese sulfate pricing, linked in part to higher sulfuric acid costs, illustrate how upstream inputs can compress profitability even when end-market demand remains robust. Second, supply disruptions tied to mining operations have reinforced the fragility of raw material availability. Weather-related interruptions at manganese-producing sites have periodically tightened supply, pushing ore prices higher and creating timing mismatches between procurement cycles and production schedules. These dynamics elevate the strategic importance of supplier diversification, inventory planning, and long-term contracting.
Third, regulatory frameworks are reshaping competitiveness in ways that go beyond simple compliance. Designations that elevate high-purity manganese to a strategic material status introduce new considerations around supply security, traceability, and alignment with broader policy priorities. In practice, this means procurement decisions increasingly factor in resilience and continuity alongside price and quality. Organizations that can demonstrate certified supply chains, documented compliance, and stable sourcing arrangements gain an advantage in bidding environments where reliability carries tangible commercial weight. Taken together, these challenges do not threaten the market’s trajectory, but they do reward firms that treat supply chain resilience and regulatory readiness as core capabilities rather than operational afterthoughts.
Key Drivers of Market Change
Technological Innovation and Product Differentiation
Innovation in sodium permanganate markets is less about radical chemistry shifts and more about precision, purity, and application fit. High-purity grades have gained traction in end-use segments where contamination sensitivity is critical, particularly in electronics manufacturing and specialized industrial processes. The availability of purity levels approaching ultra-high specifications reflects a broader trend toward customization: buyers are increasingly unwilling to accept commodity-grade solutions when performance margins and process reliability are at stake. This shift favors suppliers capable of delivering consistent quality with rigorous documentation and testing regimes.
Sodium Percarbonate Market
In parallel, liquid-formulation expertise continues to differentiate incumbents in water treatment applications. NSF-certified grades and compliance with AWWA standards have become baseline expectations in municipal and government procurement, not optional enhancements. Suppliers that can provide certified products, clear safety data documentation, and application support are better positioned to secure long-term contracts. The strategic implication is clear: technical credibility and certification infrastructure now function as competitive moats. In a concentrated market, the firms that invest early in quality systems and application-specific grade development are more likely to preserve pricing power and customer loyalty over time.
Policy and Regulatory Environment
Policy developments are increasingly influencing where capital flows and how supply chains are evaluated. The elevation of high-purity manganese within critical raw materials frameworks has made supply security a strategic priority for downstream industries and public-sector buyers alike. When manganese is explicitly recognized as a material important to supply security, procurement teams and project developers pay closer attention to sourcing origins, price stability, and the continuity of available grades. This does not simply add a compliance layer; it changes the decision calculus for large-volume contracts and infrastructure programs.
Simultaneously, government support for domestic production capacity in battery-grade and industrial manganese streams signals a longer-term shift toward supply localization in key geographies. Grant programs and policy incentives aimed at building production facilities reflect a broader emphasis on reducing dependence on imported inputs for strategic applications. For sodium permanganate markets, this creates a dual effect. On one hand, policy-driven investment in manganese production capacity could improve long-term availability and moderate input cost volatility. On the other hand, transitional periods may still be marked by tightness, regional disparities, and competition for intermediate materials. Companies that maintain visibility into these policy dynamics can better time procurement commitments, capacity planning, and partnership structures.
Manganese Sulphate Market
Demand-Side Shifts in Water Treatment and Electronics
Demand growth continues to be anchored by water treatment applications, where sodium permanganate remains a valued oxidizing agent for odor control, iron and manganese removal, and broader oxidation processes. Infrastructure budgets, public health priorities, and tightening water quality standards all contribute to sustained procurement needs in this segment. Importantly, large municipal and government contracts often follow multi-year planning cycles, meaning demand in this area is relatively stable but highly dependent on certification compliance, specification alignment, and trust in supplier reliability. Contract awards that reference NSF and AWWA standards exemplify how procurement processes reward documented conformity and supply consistency.
In the electronics segment, demand is shaped by process sensitivity and purity requirements rather than volume alone. High-specification applications reward suppliers capable of delivering tightly controlled grades with comprehensive quality documentation. As electronics manufacturing continues to emphasize reliability and contamination control, the value proposition of specialty-grade sodium permanganate strengthens. The broader demand picture includes additional application areas that add incremental growth and diversify end-use exposure, reducing reliance on any single vertical. For commercial strategy, the key insight is that demand-side strength varies by segment quality thresholds, procurement structures, and certification dependencies. Success depends on matching product architecture to the specific requirements of each major application rather than treating the market as a homogeneous whole.
Supply Chain and Cost Structure Dynamics
Cost structures in this market are heavily influenced by manganese availability, chemical input pricing, and the logistics of specialized distribution. Recent quarter-over-quarter increases in manganese sulfate pricing illustrate how quickly input economics can shift, especially when driven by higher costs for essential precursor chemicals such as sulfuric acid. These movements affect not only production costs but also the timing of contract negotiations and the structure of pricing terms. In concentrated markets, suppliers with established sourcing relationships and inventory buffers may be better positioned to manage short-term volatility without passing all costs downstream.
Supply disruptions from manganese mining operations further complicate cost planning. When production interruptions occur due to environmental incidents or operational constraints, ore prices can rise and availability can tighten, forcing downstream producers and distributors to adjust procurement strategies. Events such as mine suspensions linked to cyclone damage have shown how quickly physical supply conditions can change. The result is a market where resilience is increasingly priced into sourcing decisions. Buyers are willing to pay for assurance, and suppliers that can offer dependable continuity, transparent documentation, and proactive risk management gain leverage. Over time, this dynamic rewards organizations that treat supply chain design as a strategic function, integrating supplier diversification, contractual flexibility, and scenario planning into everyday operations.
Competitive Landscape and Leading Strategies
The competitive structure of the sodium permanganate market is defined by a small group of established U.S.-based producers and distributors with strong positioning in water treatment, government procurement, specialty-grade supply, and bulk distribution. This concentration reflects the importance of certification, application expertise, and supply reliability. Rather than competing primarily on price, leading firms differentiate through product grades, compliance documentation, distribution reach, and customer relationships built around recurring contract cycles.
Carus Corporation stands out as a major producer and supplier of liquid sodium permanganate for water treatment applications, including NSF-certified grades. Its strategic positioning centers on alignment with municipal and industrial water treatment requirements, where certification and product consistency are decisive. By maintaining a focus on certified grades and application-oriented supply, the company reinforces its role in high-value public-sector and industrial procurement environments. In a market where contract awards increasingly reference NSF and AWWA standards, that certification-oriented posture is a meaningful competitive asset.
Hawkins, Inc. operates as a domestic manufacturer, blender, and distributor with a B2B-only sales model focused on municipal and government water treatment. Its strategy emphasizes local production and distribution reliability, targeting customers that prioritize continuity of supply and direct commercial relationships. The B2B-only orientation allows the firm to concentrate on specification-driven buyers rather than broader retail-style channels. This model supports stable demand attachment to public-sector and institutional customers where procurement processes favor established distribution partners with documented compliance capabilities.
Valudor Products, LLC supplies 40 percent sodium permanganate solution certified for water treatment with full safety data documentation. Its differentiation is rooted in product specification clarity and documentation completeness, which matter in procurement settings where compliance and transparency are non-negotiable. Suppliers that make safety data sheets and certification information readily accessible reduce friction in the purchasing process and strengthen trust with buyers who must satisfy internal and external audit requirements. In concentrated markets, even incremental improvements in documentation and specification clarity can influence supplier selection.
American Elements positions itself around high-purity offerings, providing sodium permanganate at purity levels up to 99.999 percent for commercial, research, and industrial uses. This strategy targets segments where purity thresholds drive value rather than cost minimization alone. High-purity specialization creates a different competitive logic: customers in electronics and advanced industrial applications often prioritize grade integrity and documentation over bulk commodity pricing. By focusing on ultra-high purity capability, the company serves demand that is less sensitive to commodity price fluctuations and more sensitive to performance assurance.
Rock Chemicals, Inc. operates as a trusted bulk supplier with emphasis on reliable sourcing and compliance documentation. Its positioning reflects a practical, reliability-first value proposition: customers in bulk procurement environments value consistency, sourcing transparency, and the ability to meet compliance requirements without administrative delay. In a market where raw material volatility and supply interruptions are real risks, that emphasis on dependable sourcing and documentation provides a practical competitive edge, especially for procurement teams seeking to reduce uncertainty in recurring supply contracts.
Recent procurement activity highlights how these competitive dynamics play out in practice. Contract awards such as the 2025 supply agreement for sodium permanganate under NSF and AWWA standards demonstrate that public-sector buyers continue to prioritize certified compliance and specification alignment. Such contracts reinforce the value of firms that can meet documented standards and sustain reliable delivery. In a concentrated market, these wins are not merely transactional; they signal a broader pattern where certification readiness and procurement compatibility shape share dynamics over multi-year horizons. The competitive landscape is likely to evolve through selective integration, deeper specialization by purity or application, and the continued importance of distribution and documentation capabilities. New entrants will face steep barriers unless they can credibly replicate certification infrastructure, supply reliability, and customer trust.
Future Trends and Commercial Opportunities
Looking ahead over the next three to five years, several interconnected trends are likely to shape commercial strategy in sodium permanganate markets. The first is a reinforcement of certification and compliance as competitive drivers. As water infrastructure procurement remains anchored in public-sector standards and industrial buyers demand documented traceability, firms with robust certification portfolios and clear application-specific grades will be better positioned to win and retain contracts. The opportunity here lies in strengthening application alignment, expanding certified grade availability where feasible, and reducing friction in the buyer’s compliance review process. Organizations that can provide clearly documented, specification-matched products will find it easier to command premium positioning in procurement cycles where risk avoidance matters.
A second trend is the continued tension between demand resilience and raw material volatility. Infrastructure spending and electronics-related demand are expected to provide underlying support, but input cost fluctuations tied to manganese sulfate pricing and mining disruptions will likely remain a recurring theme. This creates commercial opportunities for firms that can secure longer-term sourcing arrangements, build inventory buffers where appropriate, and design pricing structures that balance stability with flexibility. For buyers, the opportunity is to reduce exposure through diversification, strategic contracting, and clearer visibility into upstream pricing signals. For suppliers, the opportunity is to differentiate through reliability, documentation, and service quality in a market where continuity can be as valuable as unit price.
The third trend is the growing influence of strategic raw material policy on supply chain behavior. As manganese gains recognition within critical materials frameworks and public investment supports domestic production development, procurement and production strategies may gradually shift toward greater supply security, regional diversification, and alignment with policy priorities. This creates opportunities for firms that can articulate supply resilience, traceability, and continuity as part of their commercial value proposition. At the same time, transitional uncertainty may persist, particularly during periods when new capacity is being developed but has not yet stabilized availability. Decision-makers should therefore plan for a market environment where policy, sourcing, and pricing interact more closely than in the past.
These trends carry potential risks and uncertainties. Raw material price swings can compress margins or trigger renegotiation pressure if contracts lack flexibility. Regulatory changes can alter compliance expectations faster than product or documentation systems can adapt. Supply disruptions may expose overreliance on limited sourcing channels. In addition, market concentration means that shifts in the strategy or capacity of a small number of incumbents can affect overall availability and pricing dynamics. The commercial opportunity is not simply to forecast growth, but to build operational and commercial buffers that allow firms to respond decisively when conditions change.
Actionable Guidance for Decision-Makers
For manufacturers and producers, the priority is to reinforce differentiation through grade specialization, certification readiness, and supply reliability. Investment in high-purity capability, certified water treatment grades, and rigorous documentation can support premium positioning in application-sensitive segments. Equally important is proactive management of input costs and sourcing risk. Diversifying supplier relationships, maintaining visibility into manganese-related pricing trends, and structuring contracts with appropriate flexibility can protect margins without sacrificing customer trust. Manufacturers should also consider how application-specific support, technical documentation, and compliance clarity can reduce friction in customer qualification processes, especially where procurement cycles are long and specification-driven.
For investors, the market presents a profile of steady growth with concentrated leadership and strategic sensitivity to raw material and regulatory dynamics. Due diligence should focus on supply chain resilience, certification positioning, and exposure to input cost volatility rather than on top-line growth alone. Companies with strong compliance documentation, recurring government or municipal contracts, and credible sourcing strategies are better equipped to withstand disruptions and defend pricing. At the same time, investors should monitor the pace of policy-driven capacity development and any shifts in manganese availability that could affect cost structures or regional supply patterns. In concentrated markets, competitive advantage often depends on reliability and credibility as much as scale, so qualitative assessments of operational maturity can be as important as financial metrics.
For procurement teams and buyers, the strategic priority is to reduce exposure to volatility while preserving quality and compliance. Diversifying approved suppliers, aligning purchasing cycles with upstream cost signals, and prioritizing vendors with robust certification and documentation can improve contract stability. Where possible, long-term agreements should incorporate mechanisms that address raw material price movements without sacrificing service quality or specification integrity. Procurement strategies should also account for the increasing importance of supply security and continuity in public-sector and industrial environments, where auditability and reliability can outweigh marginal price differences. In this context, detailed segment-level intelligence on grade demand, certification dependencies, and sourcing risk can materially improve sourcing decisions.
For organizations seeking a more granular view of segment dynamics, regional demand patterns, and contracting trends, deeper analysis can clarify where value is created and where risk concentrates. A detailed research report can provide the segmented data, competitive mapping, and scenario context needed to support pricing, capacity, and sourcing decisions with greater precision. Given the pace of regulatory and raw material developments, timely access to structured market intelligence is not merely an analytical exercise; it is a practical input to strategy execution. For decision-makers who need to translate market signals into procurement, investment, or product strategy, a fuller examination of the data and competitive dynamics can help ensure that action plans are grounded in current conditions rather than assumptions.
PW Consulting Chemical & Energy Research Center
For detailed analysis of this topic, please visit the official page: Sodium Permanganate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


