



Shea Butter Market 2026: Beyond the 8.2% CAGR Story to 2032 Drivers

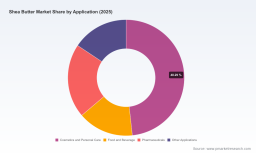
Strategic Trends and Commercial Opportunities in the Global Shea Butter Market
The global shea butter market has evolved from a niche ingredient in specialty cosmetics into a strategically significant commodity spanning personal care, food, and pharmaceutical applications. Valued at approximately USD 970.0 million in 2025, the market has demonstrated consistent expansion over the past five years, accelerating from USD 655.2 million in 2020. Forward projections indicate continued growth, with the market expected to surpass USD 1.6 billion by 2032, reflecting a compound annual growth rate of 8.2 percent through the forecast period ending in 2032.
This trajectory reflects more than incremental demand growth. It signals a structural shift in how shea butter is sourced, processed, regulated, and positioned across end-use markets. For executives and investors evaluating exposure to natural ingredients, the shea butter sector offers compelling upside, but it also presents a complex landscape shaped by regional policy interventions, supply chain reconfiguration, and evolving consumer expectations.
PW Consulting's market intelligence on this sector highlights that the opportunities ahead will not accrue uniformly. Companies that understand the interplay between production geography, processing capability, regulatory compliance, and application-specific demand will be best positioned to capture value. This analysis examines the current market structure, the forces reshaping competitive dynamics, and the strategic moves required to navigate the next phase of growth.
Market Landscape and Core Challenges
The shea butter market operates at the intersection of agricultural commodity trading and value-added specialty ingredients. Over the historical period from 2020 to 2025, the market expanded steadily, driven by rising demand for plant-based and naturally derived ingredients across cosmetics, food formulations, and pharmaceutical applications. The forecast period through 2032 projects continued expansion, with the market reaching an estimated USD 1.69 billion by the end of the forecast horizon.
While the top-line growth narrative is clear, the operational reality for market participants is more nuanced. Three structural challenges define the current inflection point.
Supply Chain Concentration and Raw Material Volatility
Shea butter production remains heavily concentrated in specific West and Central African regions, creating geographic dependency that introduces both price volatility and supply continuity risk. The crop's seasonal nature, combined with variable yields and the predominance of smallholder farming, means that raw material availability can fluctuate significantly between harvest cycles. This structural characteristic has historically forced downstream buyers to balance cost efficiency against supply security, often through long-term contracting or geographic diversification of sourcing portfolios.
Compounding this challenge, the gap between raw kernel availability and processed butter output creates bottlenecks. Entities that control refining and fractionation capacity can extract disproportionate value, while those dependent on spot-market purchases face margin compression during periods of tight supply. The market's medium concentration levels, with the top three firms holding a notable share and the top five firms controlling a larger portion of traded volume, indicate that scale and vertical integration confer meaningful advantages.
Regulatory and Policy Fragmentation
The regulatory environment for shea butter varies substantially by destination market and by application. Food-grade shea butter entering the European Union, for example, must comply with mandatory labeling requirements, hygiene standards, and hazard analysis and critical control points systems. Cosmetic and pharmaceutical applications impose their own quality and traceability expectations. This fragmentation increases compliance costs and creates barriers for smaller producers or exporters who lack the institutional capacity to navigate multiple regulatory regimes simultaneously.
More significantly, recent policy actions in key producing countries are reshaping the value-capture dynamics within the supply chain. Governments in the region are increasingly focused on capturing more domestic value by restricting raw nut exports and encouraging local processing. These interventions introduce both opportunity and disruption: they can stimulate investment in local refining infrastructure, but they also create short-term market dislocation, pricing uncertainty, and the need for buyers to renegotiate supply arrangements.
Quality Consistency and Standardization Gaps
Despite growing demand, the shea butter market continues to contend with variability in quality, purity, and processing standards across the supply base. Unrefined and raw variants, which represent a substantial portion of traded volume, differ widely in terms of moisture content, free fatty acid levels, and impurity profiles. For manufacturers in cosmetics and personal care, where consistency and stability are paramount, this variability complicates formulation and can increase quality control overhead. For food and pharmaceutical applications, the bar is even higher, requiring documented traceability and adherence to precise specifications.
Standardization is improving, but the pace is uneven. The presence of minimum price mechanisms tied to quality specifications in some producing markets reflects an effort to align incentives, but widespread adoption of uniform grading and certification remains a work in progress. Companies that invest in supplier qualification, incoming inspection protocols, and collaborative quality improvement with upstream partners can differentiate themselves, but this requires sustained commitment rather than transactional sourcing.
Key Drivers Reshaping the Market
Policy Interventions and the Shift Toward Domestic Value Addition
One of the most consequential developments in the shea butter market is the emergence of policy measures designed to retain more value within producing countries. In July 2025, a minimum price for raw shea kernels was established, set at GH₵9.01 per kilogram, with specific quality parameters covering moisture content, free fatty acids, and impurity levels. This mechanism creates a pricing floor linked to quality, aiming to provide more predictable returns for producers while incentivizing better grading practices.
Shortly thereafter, Nigeria implemented a ban on exports of raw shea nuts, with the stated objective of shifting from raw nut exports toward domestic production of refined shea butter, oil, and derivatives. The ban, initially set for a six-month review period, was reported to have triggered an immediate drop in domestic prices, reflecting the sudden redirection of supply within the local market. Analysts noted that Nigeria accounts for a significant share of global raw shea nut production, and that a substantial portion of that output had historically been exported in unprocessed form.
These policy moves are not isolated. They represent a broader trend among producing nations seeking to capture more value along the supply chain. For downstream buyers and processors, this means that sourcing strategies can no longer assume seamless access to raw materials at historical price levels. Instead, companies must evaluate opportunities to engage with local processing capacity, invest in partnership structures that align incentives, or factor in the cost of compliance with new trade and quality regimes.
Technological and Processing Advancements
Processing technology is a critical lever in the shea butter value chain. The distinction between raw, unrefined butter and refined, fractionated products is not merely a matter of purity; it reflects differences in application suitability, shelf stability, odor and color profile, and cost structure. Refinement and fractionation enable producers to tailor shea butter for specific end uses, including high-stability cosmetic formulations and food applications that require consistent functional properties.
Companies that have invested in refining infrastructure and value-added fractionation are better positioned to serve demanding customers in the food and cosmetic sectors. By converting raw kernels into standardized butter and derivative products, these entities can command higher margins and build longer-term supply relationships. Conversely, reliance on manual or low-scale processing limits the ability to meet the consistency and volume requirements of large industrial buyers.
The technological trajectory also includes improvements in quality testing, traceability systems, and process control. As destination markets impose more stringent requirements, the ability to document and verify product attributes becomes a competitive differentiator. Investments in laboratory capacity, certification, and digital traceability are increasingly relevant for suppliers aiming to access premium segments.
Consumer and Formulation Trends Driving Demand
On the demand side, the shift toward naturally derived, plant-based, and sustainably sourced ingredients continues to reshape formulations across cosmetics, personal care, food, and pharmaceutical products. Shea butter's profile as a multifunctional, naturally occurring lipid aligns with consumer preferences for clean-label and botanical ingredients. In cosmetics and personal care, it is valued for its emollient properties and is used across a range of products, from moisturizers and balms to hair care formulations.
In food and beverage applications, shea butter and its derivatives serve functional roles where stable, plant-based fats are required. The pharmaceutical segment utilizes shea butter in topical formulations and other applications where biocompatibility and consistency are important. Across these segments, the trend is not simply toward natural ingredients in general, but toward ingredients with documented provenance, consistent quality, and the ability to meet application-specific performance criteria.
This demand evolution has implications for how shea butter is positioned and priced. Buyers in premium segments are increasingly willing to pay for verified quality, traceability, and compliance documentation. At the same time, cost-sensitive applications continue to drive volume demand for more commodity-oriented grades. The coexistence of these demand tiers means that the market is not monolithic; success depends on matching product attributes to the right customer segments and application requirements.
Supply Chain Restructuring and Cost Dynamics
The cost structure of shea butter is influenced by multiple factors, including raw kernel pricing, labor and processing costs, logistics, and the cost of meeting regulatory and quality requirements. Recent policy changes in producing countries have introduced new variables into this equation. Minimum price mechanisms can stabilize producer income but may also affect the economics of export-oriented supply chains. Export restrictions on raw nuts redirect supply domestically, which can lower local raw material prices in the short term but also create uncertainty about future availability for international buyers.
For processors and converters, these dynamics create both pressure and opportunity. On one hand, sourcing disruptions and policy uncertainty can increase the cost of securing consistent supply. On the other hand, the push toward domestic processing creates openings for entities that can invest in refining capacity, enter into structured offtake arrangements, or provide technical and commercial support to local producers. The companies that navigate this environment effectively will be those that treat supply chain strategy as a dynamic capability rather than a static procurement function.
Cost dynamics also vary by region and application. Markets with strong local processing ecosystems may offer more predictable input costs for domestic manufacturers, while international buyers may face higher logistical and compliance costs. Understanding these regional and application-specific differences is essential for accurate margin planning and competitive positioning.
Competitive Landscape and Leading Strategies
The shea butter market features a diverse set of participants, from large multinational processors with established supply chains to regional specialists and origin-country producers focused on organic and manually processed products. The competitive landscape reflects different strategic choices regarding scale, vertical integration, product focus, and geographic reach.
Differentiated Strategic Positions
AAK operates with a clear focus on processing and exporting shea kernels and butter derivatives from West Africa, maintaining major supply chains that serve manufacturers in Europe and North America. This position emphasizes scale, supply chain reliability, and the ability to serve demanding downstream customers with consistent product flow. By controlling significant portions of the sourcing and export process, AAK can offer volume stability and quality assurance that are critical for large industrial buyers.
Loders Croklaan has built its positioning around refining shea kernels into crude butter and value-added fractions tailored for food and cosmetic applications. This strategy focuses on the midstream of the value chain, where processing expertise and fractionation capability create differentiation. By offering products that meet specific functional requirements, Loders Croklaan addresses customers who need more than commodity-grade butter, including those in food formulations and high-performance cosmetics.
Almond Oil Market
The Savannah Fruits Company represents a different model, emphasizing organic shea nut sourcing and manual processing at the village level. This approach is oriented around organic certification, rural livelihoods, and export of unrefined butter. The strategic value of this model lies in its alignment with sustainability and social impact expectations, as well as its ability to serve niche markets that prioritize origin authenticity and organic status. The trade-off is scale and consistency relative to larger industrial processors.
VedaOils operates in the wholesale and bulk export segment, focusing on organic and unrefined shea butter for cosmetic and personal care markets. This positioning targets cost-conscious buyers who still require organic or natural credentials, bridging the gap between premium certification and volume supply. The emphasis on wholesale and manufacturing allows VedaOils to serve a broad customer base while maintaining a focus on natural and organic attributes.
Market Structure Evolution
The competitive landscape is evolving along several dimensions. Consolidation pressure exists in segments where scale, refining capacity, and export infrastructure confer advantages. Larger processors with integrated supply chains and compliance capabilities are well placed to capture share from smaller, less capitalized players, particularly in food and pharmaceutical applications where regulatory requirements raise the bar for entry.
At the same time, differentiation and fragmentation persist in niches such as organic, fair-trade, and village-processed products. These segments reward brand story, certification, and direct relationships with producer communities. New entrants that can combine authenticity with reliable quality and documentation may find opportunities, especially as consumer and corporate procurement teams place greater weight on sustainability and provenance.
A third dynamic is the potential for vertical coordination between origin-country processors and downstream buyers. As producing countries encourage domestic refining, opportunities arise for partnerships that align local processing investment with long-term offtake commitments. Such arrangements can reduce supply risk for buyers while providing the capital and offtake certainty that local processors need to expand capacity. The extent to which this model scales will depend on policy stability, investment climate, and the willingness of both sides to commit over multi-year horizons.
Forward Trends and Strategic Implications
Trend 1: Deepening of Domestic Processing and Value Capture in Origin Countries
The policy direction evident in recent interventions points toward a sustained push for domestic processing in key producing countries. If export restrictions on raw nuts become more entrenched or are replicated in other markets, the supply chain will gradually shift toward more refined and fractionated products originating in the region. This creates opportunities for investors and companies that can support or participate in local refining capacity, quality infrastructure, and certification systems.
For downstream buyers, this trend implies that sourcing strategies will need to incorporate more engagement with origin-country processing ecosystems. Long-term contracts, joint ventures, or technical assistance arrangements may become more common as a way to secure supply and influence quality. The commercial opportunity lies in building resilient, multi-year relationships that align incentives across the value chain, rather than relying on spot-market transactions that are vulnerable to policy shocks.
Trend 2: Increasing Importance of Quality, Traceability, and Compliance Documentation
As destination market requirements tighten and application segments demand more consistent attributes, the value of quality assurance and traceability will continue to rise. Companies that can provide documented evidence of product characteristics, processing conditions, and supply chain integrity will be better positioned to access premium segments and command price premiums. This is particularly relevant for food and pharmaceutical applications, where regulatory expectations are highest.
The strategic implication is that investments in quality systems, certification, and traceability are not merely compliance costs; they are enablers of market access and differentiation. For suppliers, this means building the institutional capacity to meet varied requirements across customers and markets. For buyers, it means incorporating quality and documentation capabilities into supplier evaluation and development programs.
Mango Butter Market
Trend 3: Segmentation Between Commodity and Premium Value Chains
The shea butter market is likely to continue diverging into distinct value chains: one oriented toward volume, cost efficiency, and commodity-grade supply, and another oriented toward premium quality, certification, and application-specific performance. This segmentation mirrors broader trends in natural ingredients markets, where buyers increasingly differentiate between baseline commodity supply and value-added, verified products.
PW Consulting
For market participants, the strategic question is where to compete. Companies that operate primarily in the commodity tier will face pressure on margins and will need to compete on cost, reliability, and scale. Those that position in the premium tier will need to demonstrate consistent quality, relevant certifications, and the ability to meet specific formulation or regulatory needs. Hybrid strategies that span both tiers are possible but require operational sophistication to manage the different cost structures and customer expectations involved.
Risk Considerations
Several risks warrant attention. Policy uncertainty in producing countries could lead to further trade restrictions, price volatility, or shifts in export patterns that disrupt established supply chains. Quality and standardization gaps could persist, creating friction in premium segments and increasing the cost of quality assurance. Competition for supply could intensify as more players seek to secure processing capacity or long-term sourcing arrangements, potentially driving up input costs. Finally, demand-side preferences could shift if alternative natural ingredients gain traction or if formulation trends evolve in ways that reduce reliance on shea butter in certain applications.
These risks do not negate the growth outlook, but they underscore the importance of proactive strategy. Companies that monitor policy developments, diversify sourcing where feasible, invest in quality and traceability, and align product offerings with the right application segments will be better equipped to manage uncertainty while capturing growth.
Strategic Recommendations for Decision Makers
The shea butter market's growth trajectory and evolving structure create distinct imperatives for different types of stakeholders. The following recommendations are intended to guide strategic planning and resource allocation.
For Manufacturers and Processors
- Evaluate supply chain resilience in light of recent policy interventions. Companies dependent on raw kernel imports should assess the risk of export restrictions and consider diversifying sourcing geographies, developing alternative supply routes, or engaging with origin-country processors to secure refined supply.
- Invest in product positioning that matches application requirements. Align product grades, quality documentation, and processing attributes with the specific needs of cosmetics, food, or pharmaceutical customers. Where relevant, build capability in refinement and fractionation to access higher-value segments.
- Strengthen quality systems and traceability. Documented quality consistency and supply chain transparency will increasingly determine access to premium customers and compliance with destination-market requirements. Treat these capabilities as strategic assets rather than overhead.
For Investors
- Assess opportunities in origin-country processing and quality infrastructure. The policy push toward domestic value addition creates potential for investments in refining capacity, testing laboratories, certification support, and logistics that enable local processors to meet export-grade standards.
- Differentiate between commodity-scale plays and premium-segment opportunities. Investment theses should account for the distinct economics of volume-driven commodity supply versus certification-intensive, traceability-rich premium products. The risk-return profiles differ materially.
- Monitor policy trajectories and their second-order effects. Export restrictions, minimum price mechanisms, and quality-linked pricing can alter competitive dynamics quickly. Investors should factor policy risk into valuation assumptions and consider scenarios that reflect a range of possible regulatory outcomes.
For Procurement and Sourcing Leaders
- Move beyond transactional sourcing where supply security matters. For critical applications, structured relationships with suppliers, multi-year agreements, or collaborative quality development can reduce exposure to price shocks and supply interruptions.
- Incorporate policy and regulatory monitoring into sourcing strategy. Changes in origin-country policy, destination-market regulations, and quality requirements should be tracked systematically and integrated into supplier selection and contract design.
- Balance cost objectives with quality and compliance needs. In applications where consistency, documentation, and certification are essential, the total cost of ownership may favor suppliers with stronger quality systems, even if unit prices are higher. Procurement decisions should reflect this broader calculus.
Navigating the Next Phase
The shea butter market is entering a period in which growth potential and structural complexity are both increasing. The macro trajectory points to continued expansion, with the market progressing toward the USD 1.6 billion range by the early 2030s. Yet the path to capturing this growth is shaped by policy interventions in producing countries, the maturation of processing and quality infrastructure, and the evolving expectations of customers across cosmetics, food, and pharmaceutical applications.
Success in this environment requires more than awareness of top-line trends. It demands granular understanding of regional supply dynamics, the implications of policy changes for sourcing and pricing, the competitive positioning of key players, and the specific requirements of each application segment. The companies that thrive will be those that combine market-level insight with operational execution: securing resilient supply, delivering consistent quality, and aligning product offerings with the right customer tiers.
For decision makers seeking deeper segmentation data, regional supply analysis, competitor benchmarking, and customized strategic scenarios, a comprehensive research companion is available that extends the analysis presented here with detailed quantitative and qualitative coverage. Access to that level of granularity can materially improve the quality of sourcing decisions, investment theses, and competitive positioning in a market where the difference between generic exposure and targeted advantage is increasingly significant.
For detailed analysis of this topic, please visit the official page: Shea Butter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


