



Hemp Fiber Market: How 18.5% CAGR and Shifting Demand Redefine the 2032 Outlook

The Hemp Fiber Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Overview: A Sector in Rapid Transition
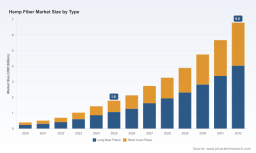
The global hemp fiber market has evolved from a niche agricultural byproduct into a strategically significant industrial commodity. Between 2020 and 2025, revenue expanded steadily, crossing the threshold from under half a billion USD to $1.8 billion. The trajectory suggests a compound annual growth rate of approximately 18.5 percent through 2032, with the market projected to reach $6.8 billion by the end of the forecast period. This expansion is not merely a continuation of historical growth patterns; it reflects structural shifts in material sourcing, regulatory clarity, and end-market demand that are reshaping the industry's fundamentals.
Several dynamics explain the acceleration. Production volumes have scaled meaningfully, as evidenced by U.S. fiber hemp open-field output reaching 67.3 million pounds in 2025, an 11 percent increase over the prior year, with an average value of $0.20 per pound. At the same time, regulatory frameworks are stabilizing after years of uncertainty. The USDA's decision to delay enforcement of the requirement that all hemp be tested by DEA-registered laboratories until December 31, 2026, provides a transitional window that reduces compliance pressure on producers in the near term. Furthermore, draft language in the 2026 Farm Bill clarifies the federal definition of industrial hemp as an agricultural commodity and signals a reduction in regulatory burdens for growers and processors. These developments collectively lower barriers to scale and encourage investment in processing infrastructure.
Despite the positive momentum, the sector faces three critical challenges that will determine which players capture value and which fall behind. First, consistent fiber quality remains elusive across supply chains. Variability in decortication methods, retting practices, and crop management leads to divergent grades of bast and core fibers, complicating downstream adoption in applications that require precise material specifications. Second, supply chain fragmentation persists. Many growers lack reliable off-take agreements, while processors struggle to secure steady volumes of consistent raw material. This mismatch creates price volatility and undermines long-term planning for manufacturers seeking to integrate hemp fiber into their product lines. Third, competition from established natural and synthetic alternatives continues to pressure cost parity. Hemp fiber must demonstrate not only environmental or performance advantages but also reliable economics that justify substitution in commercial settings.
Key Drivers: What Is Propelling the Market Forward
The market's trajectory is shaped by an intersection of technology, policy, consumer behavior, and supply chain restructuring. Each driver reinforces the others, creating a compound effect that favors companies able to align across multiple dimensions.
Technological Innovation in Fiber Extraction and Processing
Advancements in decortication and fiber refinement are among the most tangible drivers of market growth. Traditional mechanical separation methods often yield fibers with inconsistent length, strength, or surface characteristics, limiting their suitability for higher-value applications. Newer processing approaches, including low-impact mechanical and bio-assisted technologies, are improving the yield and quality of textile-grade bast fibers while reducing waste streams. Companies such as Canvaloop have introduced product lines that transform agricultural and bast waste into textile-grade hemp fibers and yarns, demonstrating that waste valorization can simultaneously address cost and sustainability objectives. Such innovations expand the addressable market by making hemp fiber viable for applications that previously required more expensive or less available alternatives.
Innovation is also evident in composite and construction material applications. Processors are developing material formulations that leverage hemp hurd and bast fiber for insulation, paneling, and lightweight automotive components. These formulations depend on consistent input quality, which incentivizes closer coordination between growers, decorticators, and end-product manufacturers. The trend toward integrated processing facilities reflects this reality, as vertical integration reduces the friction of coordinating multiple supply chain stages and allows for tighter quality control.
Policy and Regulatory Clarity as an Enabler
Regulatory uncertainty has historically constrained investment in hemp fiber infrastructure. The recent policy signals mark a shift toward greater predictability. The 2026 Farm Bill draft language that clarifies the federal definition of industrial hemp as an agricultural commodity reduces ambiguity for growers and accelerates onboarding of new production capacity. The USDA's enforcement delay on DEA-registered laboratory testing through the end of 2026 offers a practical relief window, giving processors and producers time to align compliance processes without immediate disruption. At the state level, requirements such as Virginia's retail hemp product registration, effective November 15, 2024, illustrate that subnational regulation remains a relevant consideration, particularly for companies distributing finished goods. Overall, the direction of policy is toward normalization, which supports more confident capital allocation and long-term planning.
Demand-Side Shifts Across Textiles, Automotive, and Construction
End-market demand is expanding beyond traditional niches. In textiles, brands and manufacturers are seeking regenerative and lower-impact fiber inputs to meet sustainability commitments and respond to consumer preferences. Hemp's attributes, including relatively low water intensity and the ability to grow with fewer chemical inputs, align with these priorities. In automotive composites, lightweighting and material strength drive interest in natural fiber reinforcements that can reduce vehicle weight and improve sustainability profiles. Construction materials represent another growth avenue, with hemp-based composites and hempcrete gaining traction for insulation, wall systems, and other building applications where thermal performance and carbon footprint are valued. Across these segments, the common thread is a preference for materials that can demonstrate both performance and credible sustainability credentials.
Supply Chain Reconfiguration and Cost Dynamics
Supply chains are being reconfigured to reduce dependence on fragmented, opportunistic sourcing. Vertically integrated operators are scaling decortication and processing capacity to secure more predictable input streams and to offer consistent product grades. This shift is significant because consistent supply is often more important to industrial buyers than marginal cost differences. At the same time, the cost structure is influenced by the economics of raw material production. With U.S. fiber hemp production valued at an average of $0.20 per pound in 2025, the sector continues to work toward cost levels that enable broader substitution. Improvements in yield, harvesting efficiency, and processing throughput will be central to closing any remaining gap with incumbent materials. Partnerships that link U.S. growers with international manufacturing hubs are also emerging as a strategic mechanism to access processing expertise and end-market demand simultaneously.
Competitive Landscape: Strategic Positioning and Evolution
The market remains relatively unconcentrated, with the top three firms accounting for approximately 25 percent of revenue and the top five for about 35 percent. This fragmentation indicates that scale advantages are still emerging and that positioning, rather than incumbency, will define winning strategies. Several distinct strategic archetypes are visible among leading participants.
Vertically integrated producers are building end-to-end control from cultivation through processing. Hemp Inc., with the largest U.S. decortication facility, exemplifies this approach, producing fiber for textiles, composites, and hempcrete. Vertical integration reduces dependency on third-party processors and enables tighter quality management, which is valuable for buyers requiring repeatable material specifications. Similarly, American Hemp, LLC has expanded decortication and processing capacity to serve textile, composite, and construction applications, signaling a focus on multi-application throughput rather than a single niche. This breadth can be advantageous when demand cycles differ across applications, as it allows capacity to be allocated where margins and orders are strongest.
Processors focused on technical fiber and export supply chains represent another strategic profile. IND HEMP, LLC decorticates U.S.-grown hemp straw to produce bales of technical bast fiber, premium refined or cottonized hemp fibers, and hurd in various particle sizes, serving both domestic and export markets. Its recent activities highlight the importance of partnership-driven expansion. In April 2026, the company signed a memorandum of understanding with Summit International Trading and Thien Phuoc Ramie Group to integrate U.S.-grown hemp fiber into Vietnam's textile manufacturing supply chain. A prior engagement at TechTextil North America 2025 in Atlanta, where the company showcased new hemp fiber solutions, indicates a deliberate effort to build visibility among textile industry buyers. These moves underscore a strategy that combines product differentiation with supply chain partnerships to access high-value textile markets.
Innovation-led processors are emerging around waste-to-fiber and low-impact technology. Canvaloop's November 2025 launch of a new line of textile-grade hemp fibers and yarns using low-impact waste-to-fiber technology illustrates how technology can redefine cost and sustainability profiles. By converting waste streams into marketable fiber, such companies can potentially lower input costs and improve margin resilience, while also appealing to buyers with strong sustainability mandates. This approach may also reduce competition for prime crop inputs, since it leverages material that might otherwise be discarded.
International players add geographic and application diversity. Ecofibre Ltd. produces and sells hemp-derived fibers and yarn for textiles and industrial applications, supplying both U.S. and Australian markets, which demonstrates cross-market operational capability. Dun Agro Hemp Group operates as a hemp fiber and grain processor and supplier for European and global markets, while Cavac Biomateriaux focuses on hemp fiber-based materials and composites for construction and industrial sectors in France. These firms highlight the global nature of demand and the importance of regional processing footprints to serve local construction, textile, and composite markets efficiently. Other U.S. processors such as BastCore, Inc., BaFa, and Konoplex LLC contribute to industrial and composite supply, reinforcing the breadth of the processing base and the ongoing specialization by application.
The competitive landscape is evolving along several axes. Integration is accelerating as processors acquire or build decortication capacity to secure inputs and ensure quality. At the same time, specialization is increasing, with firms differentiating by fiber type, application focus, or geographic market. New entrants are likely to continue arriving, particularly in regions where policy support and processing infrastructure align. The net effect is a market that is moving from fragmentation toward selective consolidation, but one in which multiple viable business models can coexist if they secure reliable supply, consistent quality, and clear customer value propositions.
Future Outlook: Trends That Will Shape the Next 3 to 5 Years
Three trends are likely to define the market's evolution through the early 2030s.
First, quality standardization and specification maturity will become increasingly important. As textile, automotive, and construction buyers integrate hemp fiber into regular procurement, they will require consistent grades, test data, and traceable supply. Processors that invest in quality systems, grading protocols, and documentation will be better positioned to secure long-term contracts, while those that supply inconsistent material will face marginalization. This trend favors operators with scale, integrated control, or strong technical partnerships, and it raises the bar for all participants.
PW Consulting
Second, geographic arbitrage and cross-border supply chain linkages will intensify. The integration of U.S.-grown fiber into manufacturing hubs in Asia, as illustrated by recent partnership activity, reflects a broader pattern of matching production regions with processing and fabrication expertise. Companies that can navigate logistics, customs, and qualityConsistency across borders will gain access to larger end markets and more diversified revenue streams. This trend also creates opportunities for regional processors that can serve as intermediaries, blending local feedstock with international demand.
Third, policy and compliance dynamics will continue to influence investment timing and operating costs. The current enforcement delay and the direction of the Farm Bill create a near-term environment that is more favorable for expansion, but state-level requirements and future federal rulemaking remain variables. Firms that build compliance flexibility into their operations, including adaptable testing and registration processes, will be less exposed to disruption if requirements tighten. The risk is that regulatory changes, while broadly constructive, could introduce new costs or administrative burdens that affect margins, particularly for smaller operators.
A related uncertainty is the persistence of cost gaps with incumbent materials. Even with strong demand, hemp fiber adoption will depend on achieving credible economics at scale. If processing yields, harvesting efficiency, or logistics costs do not improve sufficiently, adoption may remain selective rather than broad-based. This risk is particularly relevant in price-sensitive applications where sustainability benefits alone may not justify a premium.
Strategic Recommendations for Decision-Makers
For manufacturers evaluating hemp fiber integration, the priority is to secure reliable, specification-aligned supply before scaling product commitments. Engaging with processors that offer documented grades, consistent decortication output, and clear traceability will reduce the risk of quality variability disrupting production. Where possible, manufacturers should establish multi-source arrangements or partnership-based supply to mitigate dependence on a single chain, and they should validate performance in end-use conditions early to avoid late-stage rework or rejection.
For investors, the most compelling opportunities lie where processing capacity, quality control, and demand access converge. Vertically integrated operators with expanding decortication throughput, low-impact or waste-to-fiber technology, and established channels into textile, composite, or construction markets offer a combination of scale and differentiation. Investors should also monitor partnership activity that links feedstock origins to manufacturing hubs, since these arrangements can accelerate volume growth and reduce market risk. At the same time, due diligence should weigh regulatory exposure, state-level registration requirements for downstream products, and the pace of cost improvement relative to alternatives.
Hemp Market
For procurement and sourcing teams, the focus should be on total value rather than unit price alone. Hemp fiber's advantages in sustainability, weight reduction, and material performance can translate into downstream savings or brand value, but only if supply consistency and specification fit are confirmed. Procurement strategies should include technical trials, clear grading requirements, and contingency plans for supply variability, particularly during the transition from pilot to volume use. Building relationships with processors that demonstrate quality systems and transparent communication will reduce friction as volumes increase.
Across these audiences, the common imperative is to act with both urgency and discipline. The market is expanding quickly, and early positioning can secure access to supply, partnerships, and customer relationships that become harder to establish as the sector matures. At the same time, not all growth is equally valuable; the winners will be those who build defensible advantages in quality, supply reliability, and application fit rather than simply participating in volume expansion.
Hemp Seeds Market
For decision-makers seeking deeper segmentation data, company-level financials, regulatory timelines, and tailored scenario planning, a comprehensive research report can provide the granularity needed to translate these trends into concrete investment and sourcing decisions. The strategic direction is clear, but the details of segment economics, competitive capability, and regional readiness will determine execution success, making detailed intelligence a critical input for the next phase of planning.
For detailed analysis of this topic, please visit the official page: Hemp Fiber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


