



Magnetic Drill Press Market 2026: Why 6.2% CAGR and Infrastructure Spending Reshape Competition

The Magnetic Drill Press Market: Strategic Trends and Commercial Opportunities Through 2032
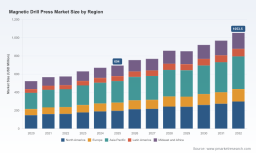
The magnetic drill press market has navigated a period of measured expansion, characterized by steady revenue growth, shifting regional footprints, and evolving product architectures. Between 2020 and 2025, the sector grew from roughly $522.77 million to approximately $694.0 million, reflecting a compound annual growth rate of 6.2 percent through the forecast horizon extending to 2032. By the end of the projection window, revenue is expected to approach $1.05 billion, signaling a market that is maturing but still capable of meaningful value creation. This trajectory is not driven by uniform demand across all segments. Instead, it reflects concentrated spending in specific types, applications, and geographies, alongside a competitive field where the top three firms capture about 55 percent of revenue and the top five hold approximately 67 percent. For executives and investors, the opportunity lies in understanding where growth is concentrating, what is reshaping cost and capability structures, and how established players are positioning themselves against nimble entrants and regional manufacturers.
Market Snapshot and Structural Realities
The market's size and pace are meaningful, but the more telling story is in its shape. Revenue expansion has been consistent rather than explosive, suggesting that adoption is broadening modestly while core end users continue to refresh and upgrade equipment. The regional distribution shows a market that is globally dispersed yet unevenly developed. Asia Pacific carries the largest revenue share, followed by North America, with Europe, Latin America, and the Middle East and Africa forming a more fragmented tail. This dispersion matters because it indicates that competitive dynamics, service requirements, and product preferences differ materially by region. A strategy that works in a mature, code-driven market may underperform in a price-sensitive, high-growth environment where portability and service responsiveness carry more weight than premium brand equity.
The type mix further clarifies where value is migrating. Pneumatic and air-powered systems command the largest revenue share, underscoring the continued relevance of shop and field setups that prioritize control, duty cycle, and integration with existing compressed-air infrastructure. Cordless and battery-powered units represent the next-largest block, reflecting the field's appetite for mobility and reduced setup friction. Electric and hydraulic offerings occupy smaller but important niches, often tied to specialized throughput needs or environments where power availability and precision are decisive. The application side reinforces a construction- and infrastructure-centric demand base, with general industrial use forming a meaningful but smaller layer. Together, these patterns suggest that the market is not a monolith; it is a collection of use cases with distinct buying criteria, lifecycle expectations, and replacement cadences.
Magnetic Pumps Market
Two structural realities frame the next phase. First, the market is moderately concentrated, which typically translates into visible brand leadership and channel leverage at the top, while leaving room for specialized players to win on application fit, regional service, or price-to-performance. Second, the growth path is likely to be uneven, shaped by project pipelines, equipment replacement cycles, and the relative cost of doing business in different regions. For decision-makers, this means that aggregate figures are useful for orientation, but segment-level dynamics determine where to invest, partner, or reposition.
Key Challenges and Inflection Points
The market is passing through a set of pressures that will separate resilient operators from those reliant on legacy assumptions. Three stand out.
First, input cost volatility is reshaping economics at the component and finished-goods level. Hot-rolled coil steel prices averaged around $851 per net ton during 2025, up from $772 in 2024, while busheling scrap prices averaged approximately $424 per long ton, above the ten-year average of $385. These movements affect both the cost base for manufacturers and the broader construction and industrial demand environment in which end users operate. When steel and scrap pricing trend upward, project budgets come under scrutiny, replacement decisions are delayed or reconsidered, and manufacturers face pressure to absorb costs without eroding margin. For magnetic drill press vendors, the challenge is twofold: manage bill-of-materials exposure while preserving the value proposition that justifies purchase in a cost-conscious buying climate.
Second, the magnet and motor supply chain is experiencing regulatory and price pressures that touch core product performance. Rare earth elements, including neodymium oxide, saw price increases exceeding 20 percent between 2024 and 2025. Since high-strength permanent magnets are central to holding force, portability, and usability on inclined or uneven surfaces, any sustained input cost escalation can influence design trade-offs. The designation of U.S. copper as a critical mineral by the U.S. Geological Survey in 2025 adds another layer of scrutiny for winding materials and electrical components. These dynamics do not necessarily disrupt production, but they raise the importance of sourcing resilience, material substitution research, and inventory planning. For buyers, they signal that lead times, warranty terms, and total cost of ownership may become more variable, especially for higher-specification units.
Third, the market is encountering an applicability inflection as crews demand lighter, more agile tools for confined and hard-to-reach work. Structural steel fabrication increasingly takes place in environments where footprint, maneuverability, and setup speed matter as much as raw capacity. This is prompting vendors to emphasize low-profile designs, switchable magnet systems, and compact kits that can operate where larger stationary machines cannot. The challenge is to deliver these benefits without sacrificing hole quality, duty cycle, or durability. Companies that solve this balance well are gaining traction in field-heavy roles, while those anchored to heavier, less adaptable platforms risk losing share in scenarios where access constraints dominate the buying decision.
Core Drivers Reshaping the Market
Demand and capability are being pulled in several directions at once. Four drivers stand out as particularly consequential.
PW Consulting
Technology innovation is the most visible. The transition toward brushless motor architectures, higher hole-per-charge performance in cordless kits, and more efficient magnet control is changing what field teams expect from a portable magnetic drill. DeWALT's promotion of 18V cordless magnetic drill press upgrade kits with brushless motors and high hole-per-charge capacity for professional jobsite use, highlighted in April 2026, illustrates the direction: customers are being asked to consider battery platforms not as compromises, but as capable, productive alternatives for structural steel work. Meanwhile, Champion Cutting Tool's field-tested promotion of the RB30 LittleBrute and SB35 SmartBrute in March 2026 emphasizes lightweight design for tight spaces and hard-to-reach areas, reinforcing the broader shift toward compact, application-tuned solutions. These product narratives matter because they signal to buyers that portability and performance can coexist, expanding the set of jobs where a magnetic drill is preferred over heavier alternatives.
Regulatory and material contexts are shaping design and sourcing strategies. The rare earth price increases and copper's critical mineral status are nudging manufacturers to consider magnet architecture efficiency, winding design, and supply diversification more seriously. Even where immediate substitution is limited, the direction of travel favors firms that can demonstrate supply transparency, steady availability, and design flexibility. In practice, this means that product roadmaps increasingly incorporate material risk as a design input rather than treating it as a procurement afterthought. For procurement teams, supplier credibility on sourcing and continuity is becoming a differentiator alongside price and feature sets.
Demand-side behavior is changing as project teams optimize for labor productivity and setup flexibility. In construction and infrastructure, crews are under pressure to reduce repositioning time, minimize auxiliary equipment, and maintain throughput in constrained sites. Magnetic drills that can be deployed quickly, repositioned easily, and operated safely on varied steel profiles address these priorities directly. Rajlaxmi Machine Tools' March 2026 launch of a 25mm capacity portable magnetic drilling machine with switchable magnet options, 20-25mm air versions, and custom center finder modules, fully manufactured in India, reflects a regional response to these needs. The move highlights how local manufacturing can tailor offerings to specific capacity ranges, magnet behaviors, and accessory combinations that align with regional job patterns and cost expectations.
Supply chain and cost structures are being re-evaluated across the value chain. Elevated steel and scrap prices affect not only manufacturers' bills of materials but also the broader construction and maintenance spending environment. At the same time, the concentration of revenue among leading firms suggests that scale, channel strength, and brand trust remain powerful advantages. Yet the presence of regional manufacturers and specialized entrants indicates that cost-efficient local production, focused application kits, and responsive service can create viable competitive positions. The net effect is a market where scale matters, but precision in segment targeting and supply discipline can be equally decisive.
Competitive Positioning and Market Evolution
The competitive field blends large multi-tool brands, specialized magnetic drill manufacturers, and regional producers with targeted application focus. Each group is pursuing a distinct path to relevance.
Large tool platforms such as DeWALT and Milwaukee Tool leverage broad professional distribution, battery ecosystems, and brand recognition to position magnetic drills as part of integrated jobsite tool sets. DeWALT's cordless and corded magnetic drill presses, including the DWE1622K and 20V MAX brushless DCD1623/DCD1624 models with up to 2-inch hole capacity in structural steel, are designed to fit within an existing cordless workflow. Milwaukee Tool's 18V FUEL and brushless magnetic drill presses and kits with high-torque annular cutter operation target on-site metalworking where torque, durability, and battery compatibility matter. The strategic logic here is ecosystem leverage: buyers who already standardize on a battery platform see incremental value in adding a magnetic drill that shares batteries, chargers, and field support.
Specialist manufacturers compete on application fit, capacity ranges, and accessory integration. Hougen Manufacturing's dedicated line of magnetic drills, including the HMD2X2 and HMD900 along with fabricator kits supporting 1.5-2 inch annular cutter capacity for structural steel fabrication, positions the company around deep familiarity with steel work and cutter compatibility. CS Unitec's portable magnetic drills in the MAB series, combined with annular cutters and core drill systems for industrial and underwater applications, extends the use case envelope into environments where corrosion resistance, specialized drilling, and portability intersect. Evolution Power Tools' portable magnetic drill presses for bridges, beams, and framework, built around a tri-spoke spindle and dovetail slides, target heavy structural work where rigidity and repeatable alignment are critical. Champion Cutting Tool's RB30 LittleBrute, SB35 SmartBrute, and AC35 MiniBrute low-profile magnetic drill presses lean into maneuverability and tight-space work, complementing the broader industry emphasis on compact designs.
European and Asia-based manufacturers bring different strengths. BDS Maschinen GmbH offers premium magnetic drilling machines with more than 30 models supporting twist drilling, core drilling, tapping, and reaming across 1.5-3 inch capacities, appealing to buyers who need a broader machining toolkit within a magnetic platform. Euroboor USA provides magnetic drilling machines and annular cutters for metalworking, construction, and maintenance, backed by ISO 9001:2015 certification, which matters for procurement teams that weight quality system maturity in supplier selection. WEISS MACHINERY CO., LTD integrates magnetic drilling machines with CNC and lathe platforms for oil, gas, and power generation applications, illustrating a more specialized, higher-value path where magnetic drilling is part of a larger precision manufacturing workflow rather than a standalone field tool.
The market is evolving along several axes. Consolidation pressure exists at the top, where brand leaders can compound advantages in distribution, aftermarket parts, and training. At the same time, differentiation is increasing at the application level, where capacity ranges, magnet behavior, cutter compatibility, and mobility features create distinct buying reasons. New and regional entrants, such as Rajlaxmi Machine Tools, are demonstrating that localized manufacturing and customized accessory packages can address specific capacity and magnet requirements efficiently. This does not imply that the market is fragmenting into chaos; rather, it is becoming more segmented, with clear winners in each slice based on fit, service, and total cost of ownership. For incumbents, the strategic question is whether to defend broadly through ecosystem strength or to deepen application specificity where margins and loyalty are strongest.
Three Trends Shaping the Next Three to Five Years
The next phase is likely to be defined by capability migration, sourcing discipline, and application-led segmentation.
First, cordless and battery-compatible magnetic drilling will continue to gain relevance in field-heavy environments. The direction of product promotion and engineering attention points toward brushless motors, improved hole-per-charge performance, and kits that align with existing platform ecosystems. The commercial implication is that buyers will increasingly compare magnetic drills not only on drilling capacity and magnet strength, but also on battery compatibility, runtime consistency, and integration with other jobsite tools. Manufacturers that can deliver reliable cordless performance without sacrificing structural steel capability will expand their addressable field use cases, while those that treat cordless as a lower-tier option risk ceding ground in mobile work.
Second, material sourcing and input cost management will become more central to product strategy and buyer evaluation. With rare earth prices up sharply and copper designated as a critical mineral, companies that can demonstrate supply resilience, transparent sourcing, and efficient magnet and motor design will have an advantage in tender evaluations and long-term planning. This trend also raises the importance of warranty terms, spare parts availability, and service responsiveness, since buyers will want assurance that performance and support remain stable even as input markets fluctuate. For investors, the companies that communicate supply discipline credibly and execute on it are better positioned to defend margins through cycles.
Third, application-specific segmentation will sharpen. The market is already showing distinct demand patterns across structural steel fabrication, bridges, beams, framework, underwater and industrial settings, and integrated CNC-intensive workflows. Over the next few years, success will increasingly depend on matching capacity, magnet behavior, cutter systems, and accessories to the job at hand. Low-profile, switchable-magnet, and tight-space designs will continue to find strong uptake where access is constrained, while higher-capacity, multi-function platforms will remain relevant where versatility and throughput justify the footprint. The commercial opportunity lies in building clear product narratives for each use case and ensuring that service, accessories, and training reinforce the fit. The risk is that broad, undifferentiated offerings lose relevance as buyers become more deliberate about matching tools to specific constraints and productivity targets.
Worldwide Micro Drill for PCB Market
Implications for Different Decision-Makers
Manufacturers and brand owners should treat application fit and supply resilience as strategic priorities, not operational details. That means sharpening product stories around mobility, cutter compatibility, and magnet performance for the jobs that matter most in each region, while also investing in sourcing transparency and material efficiency. Where battery ecosystems matter, integration and runtime credibility should be front and center. Where structural steel fabrication dominates, annular cutter capacity, setup speed, and stability on varied profiles should anchor the value proposition. Where specialized environments such as underwater or precision machining applications are in play, certification, accessory systems, and platform integration become the differentiators. The companies that succeed will be those that can articulate a clear fit for each major use case and back it with dependable service and parts availability.
Investors and strategic partners should focus on where scale and where specificity each create advantage. Scale players with strong distribution, brand trust, and battery or platform ecosystems are well placed to capture share in markets where buyers value integration and support. Specialist and regional manufacturers can create durable positions by aligning capacity ranges, magnet behaviors, and accessory packages to local job patterns and by delivering responsive service. The key is to assess whether a given player's strengths map to the segments where spending is concentrated and where replacement cycles are most active. In a market with moderate concentration and clear segmentation, both broad and narrow strategies can work, but only if they are executed with discipline and backed by credible supply and service arrangements.
Procurement teams and end-user organizations should evaluate magnetic drills against total job conditions rather than headline specifications alone. Magnet holding reliability on the actual steel profiles in use, setup and repositioning speed, cutter compatibility, battery platform fit if applicable, and service proximity all influence real-world productivity and cost. Given input cost volatility and critical mineral designations, supplier continuity, warranty clarity, and spare parts availability should carry more weight in selection. For teams operating in tight spaces or on varied structural work, low-profile and switchable-magnet options may deliver more value than larger stationary-class machines. For those in precision, integrated, or harsh-environment settings, certification, accessory breadth, and platform compatibility may matter more. The goal is to align the tool to the job, the site, and the support ecosystem, rather than optimizing for a single spec in isolation.
Where to Go Next
The magnetic drill press market is expanding at a steady pace, but the real leverage lies in understanding which types, applications, and regions are driving value, how input and regulatory pressures are reshaping design and sourcing, and where leading companies are placing their bets. The trends point toward greater mobility and battery integration, stronger emphasis on supply resilience and material efficiency, and sharper application-led segmentation. For organizations deciding where to compete, invest, or buy, these dynamics create both opportunity and the need for precise, current intelligence. Detailed segment-level sizes, regional trajectories, competitive share movements, and scenario-based outlooks can materially improve planning quality and reduce execution risk. For those seeking a deeper, data-rich view of the market, the full PW Consulting research report provides the granular breakdowns and customized guidance needed to translate these trends into concrete action.
For detailed analysis of this topic, please visit the official page: Magnetic Drill Press Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


