



Beer Market 2026: Beyond the 4.91% CAGR Story — What’s Really Driving Growth to $1.17T

Navigating the Evolving Beer Market: Strategic Trends and Commercial Opportunities Through 2032
The global beer market is undergoing a period of structural transformation. With total market value projected to reach $1,170.34 billion by 2032, expanding at a compound annual growth rate of 4.91 percent from a 2025 base of $860.0 billion, the sector demonstrates resilient demand but faces mounting pressure on margins, shifting consumer preferences, and evolving regulatory and cost environments. The historical trajectory from 2020 through 2025 reveals a market that has absorbed pandemic-era disruptions, reconfigured distribution models, and adapted to inflationary input costs, while maintaining steady expansion. Looking ahead to the forecast period of 2026 through 2032, growth will be less about uniform volume gains and more about strategic positioning across regions, categories, packaging formats, and trade channels. For executives, investors, and procurement leaders, the imperative is to understand where value will concentrate and how to respond to structural shifts rather than cyclical noise.
Three interconnected challenges define the current inflection point. First, the market exhibits moderate concentration, with the top three players capturing approximately 46 percent of revenue and the top five holding around 58 percent. This structure provides scale advantages to incumbents but also invites regulatory scrutiny, limits pricing flexibility in certain channels, and raises the bar for new entrants seeking distribution access. Second, cost structures are under persistent strain from raw material volatility and packaging expenses. Malt represents a significant share of production inputs, and barley dominates malt usage, while packaging costs disproportionately influence total cost of goods, particularly for producers reliant on metal containers. Third, the trade channel mix is rebalancing as on-trade recovery continues and off-trade growth reflects changing consumption occasions, creating uneven margin profiles and requiring differentiated go-to-market strategies. These dynamics do not signal contraction; they signal a redefinition of where profitability is generated and how competitive advantage is sustained.
Wine Market
Key Drivers Reshaping the Market
Technological Innovation and Production Efficiency
Innovation in brewing technology is moving beyond incremental process improvements to encompass capacity optimization, ingredient efficiency, and precision formulation. Recent capital deployment illustrates how major producers are aligning investment with product strategy. One global brewer allocated substantial funding across its US operations to strengthen manufacturing jobs and expand production of light and zero-alcohol variants, while a separate investment in an Ohio brewery targeted capacity expansion and local training programs. These moves reflect a broader pattern: technology investment is increasingly tied to specific portfolio priorities, including low- and no-alcohol products, consistent quality at scale, and labor productivity. Automation, data-driven scheduling, and advanced filtration and fermentation controls are enabling producers to manage variable input costs more effectively and reduce waste. For commercial leaders, the strategic question is whether technology spending is directed toward cost reduction alone or also toward enabling new product formats and faster iteration on flavor profiles and functional attributes.
Black Beer Market
Policy and Regulatory Environment
Regulatory shifts are reshaping cost structures and market access, particularly around trade policy and packaging requirements. Tariff dynamics have introduced both risks and relief. One major importer reported that the US government removed tariffs on certain beer imports in early 2026, altering the cost calculus for cross-border supply chains. At the same time, another producer projected meaningful tariff-related expenses for the year, compressing gross margin guidance. These divergent outcomes underscore that regulatory impacts are highly portfolio- and geography-specific. Beyond trade policy, packaging-related regulation and sustainability expectations are influencing material choices and supplier negotiations. Producers are re-evaluating container formats in light of cost, recyclability, and consumer perception, with metal packaging representing a substantial portion of total packaging spend and aluminum conversion adding significant expense. The strategic implication is that regulatory monitoring must become a continuous input to sourcing, pricing, and channel planning rather than a periodic compliance exercise.
Consumer Demand and Behavioral Shifts
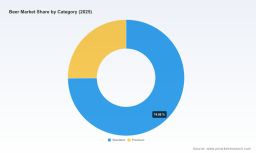
Demand patterns are evolving along multiple axes: moderation, premiumization, variety, and occasion-based consumption. Non-alcoholic and low-alcohol offerings continue to gain traction, with one international brewer reporting continued growth in this category alongside strength in premium segments. This trend is not limited to a single market; it reflects a broader consumer willingness to trade down on alcohol content while trading up on flavor, branding, and experience. At the same time, premiumization remains a durable force, with a meaningful share of revenue associated with higher-tier products, even as standard-tier beer continues to anchor volume in many markets. Consumers are also diversifying within traditional categories, sustaining strong preference for lager while opening space for ales, stouts, and specialty styles in specific channels and regions. For companies, the implication is that portfolio architecture must balance volume anchors with higher-margin differentiation, and that channel selection matters as much as product design because occasion and setting shape willingness to pay.
PW Consulting
Supply Chain and Cost Structure Realignment
Input cost dynamics remain a central driver of profitability. Barley and malt continue to anchor production economics, with malt accounting for a large share of raw material costs and barley comprising the majority of malt usage. This concentration makes procurement strategy, hedging, and supplier relationships critical levers. On the packaging side, metal cans represent a significant share of packaging dollars for major producers, and aluminum conversion adds a substantial premium to can expenses. Together, these factors create a cost environment where small improvements in yield, material utilization, and logistics can have outsized margin effects. Recent disclosures highlight that cans account for a significant portion of packaging costs, reinforcing the need to optimize container choice against channel requirements and consumer preferences. Companies that integrate sourcing, packaging engineering, and demand forecasting are better positioned to absorb volatility and protect gross margins without sacrificing market share.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The competitive field is anchored by globally scaled brewers and regionally focused players, each pursuing distinct strategies to defend and extend their positions. Anheuser-Busch InBev leverages a broad global brand portfolio and continues to invest in US manufacturing capacity, with capital directed toward both volume production and specific brands in the light and zero-alcohol space. Heineken N.V. has emphasized growth in non-alcoholic beer and premium segments, aligning product innovation with evolving demand while maintaining a presence across more than seventy markets. Carlsberg Group has focused on portfolio diversification and market share gains in Europe and emerging markets, using earnings guidance and annual reporting to signal disciplined expansion and category balance. Molson Coors Beverage Company combines mainstream American brands with craft and flavored offerings, using a dual structure to capture both volume and differentiation. Constellation Brands concentrates on imported beer strengths, benefiting from brand recognition and trade dynamics that favor cross-border portfolio positioning. The Boston Beer Company operates with a craft and flavored malt beverage orientation, using brand platforms and variety to compete in segments where differentiation and taste innovation matter.
These companies are not simply competing on scale; they are differentiating through portfolio mix, channel execution, and targeted investment. The leaders are aligning capacity and capital with product priorities, using financial reporting to reinforce credibility with investors, and adjusting to input and trade cost realities through sourcing and pricing discipline. The common thread is a shift from pure volume competition to a more nuanced game in which brand architecture, channel strategy, and cost control jointly determine outcomes.
Market Structure Evolution
The industry is experiencing both integration and fragmentation, depending on the segment and geography. At the top, moderate concentration suggests that scale advantages in procurement, distribution, and brand investment will persist, and that acquisitions or partnerships may be used to expand reach, add craft or specialty capabilities, or enter high-growth regions. At the same time, consumer demand for variety, local identity, and differentiated taste experiences continues to create space for smaller and mid-sized players, particularly in on-trade settings and specialty channels. New entrants and craft-oriented brands can gain traction by focusing on specific occasions, flavor innovation, and community-driven branding, but they face practical hurdles in distribution access, packaging cost efficiency, and marketing scale. The likely trajectory is a layered market in which global and regional leaders compete on breadth and efficiency, while smaller players compete on specificity and experience, with channel dynamics and local regulations shaping the boundaries of each contest.
Forward Outlook: Trends and Opportunities for 2026–2032
Premiumization and Moderation as Dual Engines
Over the next three to five years, premiumization and moderation are expected to remain intertwined growth drivers. Premium products will continue to capture disproportionate value growth, supported by consumers willing to pay more for quality, brand experience, and differentiated taste. Simultaneously, low- and no-alcohol options will expand their share in several markets, driven by health consciousness, social moderation trends, and improved product quality. The commercial opportunity lies in portfolio design that treats these as complementary rather than competing strategies. Companies that can offer credible premium choices while building distinct non-alcoholic lines, and that can position them appropriately across on-trade and off-trade channels, will be better placed to capture value across occasions. The risk is brand dilution or channel conflict if premium and moderation offerings are not clearly differentiated and supported by consistent messaging and distribution.
Packaging, Cost, and Sustainability Integration
Packaging strategy will increasingly function as a margin and positioning lever rather than a purely operational decision. Metal cans remain central to many producers, but their cost profile, including the impact of aluminum conversion, requires active management. Over the forecast period, expect more deliberate experimentation with container mixes, regional packaging preferences, and packaging efficiency initiatives that reduce waste and cost without compromising consumer experience. Sustainability expectations will further influence material choices and supplier negotiations, especially in markets where regulatory and consumer pressure is intensifying. The opportunity is to integrate packaging decisions with sourcing, channel strategy, and brand positioning so that cost, convenience, and environmental considerations reinforce rather than conflict with one another. The risk is reactive change that raises costs without delivering consumer or regulatory benefit, or over-indexing on a single format that leaves a producer exposed to input price swings.
Regional Divergence and Channel Rebalancing
Growth will not be uniform across regions. Asia Pacific, Europe, and North America represent substantial revenue bases with different consumption habits, regulatory environments, and channel structures. Latin America and the Middle East and Africa contribute meaningful value and offer varying growth paths shaped by local tastes, economic conditions, and distribution infrastructure. Within these regions, the balance between on-trade and off-trade will continue to shift as social habits, pricing, and convenience evolve. The strategic opportunity is to tailor product mix, packaging, and channel investment to regional realities rather than assuming a single global playbook. Companies that localize effectively, while maintaining core brand and quality standards, can capture disproportionate gains in markets where competitors rely too heavily on standardized approaches. The risk is underinvestment in region-specific capabilities or over-extension into markets where cost structures and channel economics do not support the intended return.
Actionable Guidance for Decision-Makers
For Manufacturers and Brand Leaders
- Align capital and capacity investments with clear portfolio priorities, ensuring that expansion supports specific brands and formats rather than diffuse volume goals.
- Integrate procurement, packaging engineering, and demand planning to manage malt and aluminum exposure, using hedging, supplier diversification, and yield improvements to protect margins.
- Design non-alcoholic and premium offerings as distinct strategic lines with dedicated positioning, channel selection, and quality standards to avoid internal competition and consumer confusion.
For Investors and Financial Stakeholders
- Evaluate companies on the coherence of their portfolio strategy, the quality of cost discipline in raw materials and packaging, and the resilience of their channel mix across on-trade and off-trade demand cycles.
- Monitor trade policy developments closely, since tariff relief and tariff exposure can shift margin trajectories quickly and asymmetrically across importers, domestic producers, and specific brand portfolios.
- Focus on the sustainability of growth by examining whether premium and moderation trends are supported by genuine product differentiation and distribution strength rather than short-term promotional activity.
For Procurement and Supply Chain Leaders
- Treat malt, barley, and aluminum container costs as interconnected levers, and build sourcing strategies that combine long-term supplier relationships, flexibility in specification, and scenario planning for price volatility.
- Coordinate packaging choices with channel and regional requirements, balancing cost efficiency against consumer expectations, sustainability goals, and regulatory considerations.
- Incorporate trade and tariff intelligence into supply chain design, including routing, inventory positioning, and contract terms, to reduce exposure to policy-driven cost shocks.
The commercial landscape ahead will reward organizations that treat market intelligence as a continuous input to strategy rather than a periodic checkpoint. Detailed segmentation data, regional breakdowns, and scenario analysis can sharpen planning around portfolio mix, pricing, channel allocation, and sourcing, especially in a market where growth is steady but value creation is increasingly selective. For leaders seeking deeper granularity on regional dynamics, category shifts, packaging economics, and competitive moves through 2032, the full research report provides the detailed framework and segmented data needed to translate these trends into concrete decisions.
For detailed analysis of this topic, please visit the official page: Beer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


