



Optical Films Market 2026: What the 7.1% CAGR and $399M Peak Really Mean

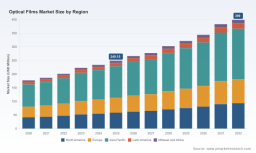
Optical Films Market: Strategic Trends and Commercial Opportunities Through 2032
The global optical films market has entered a phase of disciplined expansion, with revenue projected to grow from approximately $249.15 million in 2025 to $399.0 million by 2032, translating to a compound annual growth rate of 7.1 percent over the forecast horizon. This trajectory reflects a market that has moved past the post-pandemic normalization period and is now being reshaped by structural shifts in display design, end-user expectations, and supply chain architecture. From 2020 through 2025, annual revenue climbed steadily, crossing the $200 million threshold in 2022 and maintaining momentum through 2024 before accelerating into the 2025 baseline. The forward-looking path suggests that growth will not be linear; instead, it will be punctuated by technology adoption cycles, regional capacity realignment, and incremental premiumization in high-performance film segments.
For executives and investors, the most salient takeaway is that optical films are no longer a commodity layer in display manufacturing. They have become a functional differentiator that influences luminance efficiency, color accuracy, modular flexibility, and sustainability compliance. The market’s expansion is being underwritten by a concentrated competitive environment, with the top three players collectively holding roughly 35 percent of revenue and the top five approaching 45 percent. Such concentration does not imply stagnation; rather, it signals that scale players are leveraging capital intensity, process engineering, and application-specific customization to protect margins while smaller entrants focus on niche material science or regional distribution advantages.
Worldwide Optical Composite Film Market
Navigating the Current Inflection Points
The market is currently navigating a cluster of overlapping challenges that are redefining how optical films are developed, sourced, and deployed. First, the industry is confronting a transition from volume-driven LCD-centric demand toward mixed-display environments that include OLED, mini-LED, and emerging augmented reality interfaces. This shift places pressure on film architectures that were optimized for traditional backlighting and polarizer stacks, requiring manufacturers to reconfigure material formulations and coating processes without sacrificing throughput. Second, supply chain resilience has moved from a tactical concern to a strategic imperative. Periods of material constraints and extended lead times have forced producers to reconsider stocking strategies, dual-sourcing arrangements, and the geographic placement of conversion capacity. Third, regulatory and trade dynamics are adding new layers of cost and complexity. Tariffs and export restrictions on specialty chemicals, combined with sustainability mandates tied to recycling and material traceability, are compressing negotiable margins and rewarding companies that can internalize compliance rather than treat it as an external overhead.
These inflection points are not insurmountable barriers; they are filters. Companies that treat them as purely operational problems will see erosion in differentiation, while those that embed resilience and compliance into product architecture will find new pricing and partnership leverage.
Key Drivers Reshaping the Optical Films Landscape
Technology Innovation as a Margin and Function Catalyst
Material and process innovation remains the dominant engine of market evolution. Recent product introductions illustrate how rapidly the industry is moving toward thinner, more flexible, and higher-transmittance film architectures. In May 2025, 3M Corporation launched a new line of ultra-thin polarizing films designed for next-generation flexible OLED displays, signaling a direct response to the demand for lighter, more form-factor adaptable screens. Around the same period, LG Chem Ltd. introduced a recyclable, eco-friendly optical film portfolio aimed at reducing environmental impact across consumer electronics, demonstrating that performance and end-of-life considerations are increasingly being engineered together rather than traded off. These developments are not isolated product announcements; they reflect a broader shift in which film properties such as haze control, transmittance, mechanical durability, and recyclability are becoming explicit purchase criteria for display integrators and brand owners.
The strategic implication is straightforward: technology leadership in optical films is shifting from generic brightness enhancement or polarizer functionality toward application-specific stacks that integrate optical performance with manufacturability and environmental compliance. Manufacturers that can validate film behavior under flexible substrates, higher refresh rates, or new optical path designs will capture premium positioning and longer product cycles.
Policy, Regulation, and the Compliance Premium
Policy and regulatory pressure is accelerating a reevaluation of material inputs, production footprint, and trade routing. Increased tariffs and export restrictions on specialty chemicals used in optical film production have complicated international trade, while sustainability mandates and recycling requirements are adding further cost considerations to film pricing. These forces are particularly pronounced where optical films used in displays intersect with high-volume, tariff-sensitive trade lanes. The result is a market in which compliance is becoming a competitive variable: suppliers that can demonstrate material traceability, lower-hazard formulations, and localized production capabilities are increasingly able to secure preferred-supplier status with downstream assemblers and brands that face their own regulatory and reporting obligations.
For decision-makers, this driver reframes cost management. The cheapest input is no longer the cheapest over the product lifecycle if it introduces compliance exposure, customs uncertainty, or reputational risk. Investments in material substitution, supplier qualification, and regional manufacturing are increasingly justified by risk mitigation as much as by unit-cost savings.
Demand-Side Shifts Across Consumer and Industrial Use Cases
Demand is being reshaped by simultaneous changes in how consumers interact with displays and how enterprises deploy visual interfaces. Smartphones continue to anchor a substantial share of optical film consumption, but the character of that demand is evolving as devices prioritize thinner form factors, higher display efficiency, and adaptive optical tuning. 텔레비션 and desktop monitors and laptops contribute significant volume, yet they are being supplemented by higher-value applications where optical film performance directly influences user experience or functional reliability. Automotive display applications, although smaller in absolute scale, are growing in strategic importance as digital cockpits, heads-up displays, and integrated cabin interfaces become more sophisticated. These applications impose stricter requirements for thermal stability, durability, and optical consistency across wide temperature ranges, which in turn filters the supplier base toward manufacturers with strong process control and qualification capabilities.
The broader demand trend is a migration from uniform, mass-market film specifications toward segmented requirements that reward application engineering. Suppliers that can align film properties with the operating conditions and regulatory profiles of specific end-use categories will find more stable demand and fewer price-only competitions.
Supply Chain Reconfiguration and Cost Structure Pressures
Cost structures are under pressure from multiple directions. Fluctuations in raw material prices, particularly for polymers such as PET and TAC, directly influence film pricing, while sustainability mandates and recycling requirements add further cost considerations. In response, manufacturers have faced material shortages and extended lead times, prompting investment in localized production and strategic stockpiling to stabilize output and pricing. At the same time, the tariff environment is reshaping the economics of cross-border distribution, especially where high-value optical film families are exposed to elevated duties and trade friction. These pressures are encouraging a broader reassessment of where final film conversion should occur relative to resin supply, panel assembly, and end-market consumption.
The commercial opportunity embedded in this driver is the emergence of more regionalized, orchestration-heavy supply chains. Companies that can coordinate resin sourcing, conversion capacity, and finished-film distribution with greater granularity will be better positioned to smooth lead times, reduce exposure to tariff shocks, and offer customers more predictable delivery performance.
Competitive Landscape and Strategic Positioning
Profiles of Core Incumbents
The competitive set is anchored by companies that blend material science depth with application-specific commercialization. 3M Company continues to emphasize highly engineered optical films optimized for mobile electronics and display systems, including brightness enhancement and polarizer films, and its May 2025 product launch for flexible OLED underscores a push into next-generation form factors. LG Chem Ltd. positions itself around recyclable eco-friendly optical films and advanced photopolymer films for high-efficiency optics and displays, with its February 2025 portfolio release reinforcing a sustainability-forward narrative that aligns with brand-level compliance priorities. Samsung SDI Co., Ltd. develops and supplies optical films including polarizing and display composite films for LCD and OLED panels, linking film capability directly to panel-level integration. Zeon Corporation manufactures ZeonorFilm optical films with high transmittance and low haze for polarizer stacks and touchscreens, focusing on optical clarity attributes that matter in precision display stacks.
Toray Industries, Inc. produces plastic optical films for display and electronic applications, including specialized optical components, extending its materials breadth into tailored display roles. Eastman Chemical Company has expanded optical films manufacturing capacity for applications in displays and electronics, with its April 2025 facility expansion in South Korea highlighting a deliberate Asia-Pacific capacity build. Nitto Optical Co., Ltd. specializes in optical films for advanced display and electronic module requirements, emphasizing interface-level performance. Toyobo Co., Ltd. offers optical films and related display materials for consumer electronics and industrial use, broadening the functional scope of its material portfolio.
Strategic Differentiation and Competitive Dynamics
Across this group, differentiation is emerging along several axes rather than a single generic advantage. One axis is application engineering: suppliers that can tune optical films to specific display architectures, thermal environments, or interface requirements are creating stickier customer relationships and reducing exposure to commoditization. Another axis is sustainability and compliance: recyclable films and lower-impact material choices are increasingly relevant where downstream brands must meet environmental targets and reporting expectations. A third axis is geographic and manufacturing agility: capacity additions in Asia Pacific and localized production footprints are being used to reduce lead-time volatility and to navigate tariff exposure more effectively.
The market structure is evolving through selective integration and targeted divergence. Larger incumbents are likely to continue consolidating scale advantages in high-volume film families while investing in specialized lines for premium applications. At the same time, the environment is conducive to specialized entrants that can deliver differentiated material properties, regional service density, or compliance-ready sourcing, even if they do not compete on total volume. The most probable outcome is a layered competitive landscape in which scale players defend broad intervals and specialized players capture high-margin pockets tied to demanding applications and fast-moving display technologies.
Recent Developments as Strategic Signals
Several recent moves illustrate how incumbents are translating strategy into action. The May 2025 launch of ultra-thin polarizing films for flexible OLED displays indicates a direct bet on form-factor evolution and the accompanying optical requirements of bendable and lightweight screen designs. The April 2025 manufacturing expansion in South Korea reflects a deliberate alignment of capacity with regional demand concentration and possibly with panel-assembly geography. The early-2025 introduction of a recyclable, eco-friendly optical film portfolio signals that sustainability is being operationalized as a product attribute rather than treated as a corporate messaging layer. And partnership activity around customized optical films for heads-up displays and augmented reality applications points to the growing relevance of non-traditional display contexts, where optical films must perform under different viewing geometries, illumination conditions, and durability demands.
These developments collectively suggest that the market is moving toward tighter coupling between film properties, application requirements, and compliance expectations. Suppliers that can coordinate these dimensions within a single product strategy are likely to secure more durable positions than those competing primarily on price or generic specification.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
1. Premiumization Through Application-Specific Optical Stacks
The most durable trend is the continued shift toward optical films engineered for specific display platforms and operating environments. As flexible OLED, mini-LED, and advanced automotive displays gain wider deployment, film suppliers will face rising expectations for transmission efficiency, mechanical resilience, thickness reduction, and compatibility with new panel architectures. This trend creates commercial opportunity for manufacturers that can validate performance under application-specific conditions and offer coordinated solutions rather than standalone film reels. The risk is that premiumization can fragment demand if too many bespoke specifications dilute scale benefits, so disciplined portfolio management will be essential.
2. Regional Capacity Realignment and Supply-Chain Orchestration
Trade friction, tariff exposure, and the need for more predictable lead times are likely to accelerate regional capacity adjustments and closer integration between resin supply, film conversion, and downstream assembly. Over the next three to five years, expect more capacity located closer to key demand clusters and more deliberate buffer strategies for critical inputs. The opportunity lies in building supply networks that can absorb shocks without overcapitalizing in the wrong geographies. The uncertainty comes from the pace and direction of trade policy, which can alter the economics of regionalization faster than internal planning cycles can adapt.
Worldwide Window Films Market
3. Sustainability as a Design Variable, Not a Compliance Afterthought
Recyclable films, lower-impact polymer choices, and traceability requirements are becoming embedded in sourcing decisions, especially where downstream brands face external sustainability reporting or internal material targets. This trend opens space for suppliers that can demonstrate verifiable environmental attributes alongside consistent optical performance. The commercial upside is stronger qualification outcomes and longer-term contracts with customers that prioritize compliance and brand risk reduction. The caution is that sustainability claims must be backed by credible process controls and material documentation, because superficial positioning is unlikely to withstand scrutiny from sophisticated buyers.
PW Consulting Information & Electronics Research Center
Strategic Implications for Decision-Makers
For Manufacturers and Material Suppliers
Focus on application engineering and validation as a source of differentiation rather than relying solely on scale or price. Build the capability to prove film behavior in flexible, high-efficiency, and automotive-grade contexts, and align product roadmaps with the display platforms that are most likely to adopt thinner, more efficient, and more durable optical layers. Use regional capacity and sourcing choices to reduce tariff and lead-time exposure, but ensure that localization decisions are supported by data on resin availability, conversion economics, and customer geography rather than driven by short-lived policy headlines.
For Investors and Capital Allocators
Assess exposure not only to total market growth but to the mix shift toward higher-value film families and demanding applications. Track capacity additions and partnership activity as indicators of where incumbents believe demand will concentrate, and pay attention to compliance-oriented product launches as potential differentiators that can support pricing resilience. Favor business models that combine technical depth with the ability to serve application-specific requirements, because those attributes are more likely to translate into durable margins than volume-only positioning.
For Procurement and Sourcing Leaders
Treat optical film sourcing as a multi-variable decision that includes optical performance, qualification risk, tariff exposure, and environmental compliance. Diversify supply where feasible, but do so with an explicit strategy for lead-time stability and material traceability rather than simply adding nominal second sources. Where possible, engage suppliers early in display design cycles to align film selection with performance and compliance goals, because late-stage substitution often carries higher cost and risk than coordinated specification.
Where to Go Next
The optical films market is expanding at a measured but meaningful pace, and the competitive advantage will increasingly belong to organizations that can integrate material performance, application engineering, and supply-chain resilience into a coherent commercial strategy. The trends outlined here point to a market in which premiumization, regional capacity realignment, and sustainability-driven design are not peripheral themes but central drivers of value creation. For teams that need a fuller picture of segment dynamics, regional splits, application-level momentum, and detailed company benchmarking, the complete PW Consulting research report provides the deeper data set and tailored scenarios required to support concrete planning decisions.
For detailed analysis of this topic, please visit the official page: Optical Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


