



Tonneau Covers Market: Why 5.8% CAGR and $314M Size Redefine Competition

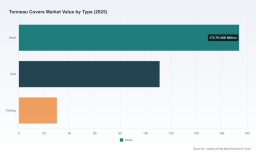
Tonneau Covers Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot and Core Challenges
The global tonneau covers market has entered a phase of steady, compounding growth, driven by durable demand for truck bed protection, utility optimization, and aesthetic customization. Measured in millions of USD, the market expanded from roughly $243.0 million in 2020 to approximately $314.99 million in 2025, reflecting a compound annual growth rate of 5.8 percent across the 2020–2025 period. The trajectory continues upward through the forecast horizon, with projected revenue reaching $460.85 million by 2032. This expansion signals more than cyclical fluctuations; it points to structural demand supported by pickup truck utilization patterns, aftermarket customization culture, and incremental upgrades in materials and locking mechanisms.
Despite the favorable growth path, the market faces a handful of inflection points that could reshape competitive dynamics and margin profiles over the next several years. These challenges are not isolated operational issues; they are systemic forces that require strategic repositioning rather than incremental adjustments.
Tariff and trade policy uncertainty represents the most immediate pressure point. A cluster of U.S.-based manufacturers filed antidumping and countervailing duty petitions against imports of truck bed covers from China, prompting federal trade investigations and raising the prospect of revised duty structures. For a market where import exposure varies across product categories and supply chains, this development introduces pricing volatility, sourcing reconfiguration costs, and potential short-term inventory tightness. Companies that rely on globally distributed components or finished-cover imports must evaluate exposure not only at the customs line but also across logistics, lead times, and customer price sensitivity.
Material cost and engineering trade-offs form a second structural challenge. Tonneau covers span a spectrum from soft roll-up designs to hard folding and retractable systems, each balancing weight, durability, ease of installation, bed accessibility, and aesthetics. Rising costs for polymers, aluminum, and specialized coatings can compress margins or force repositioning of price points. At the same time, performance expectations continue to rise: customers increasingly seek low-profile profiles, stronger locking architectures, weather sealing, and features that accommodate toolboxes or specialized bed configurations without sacrificing convenience.
Finally, channel and customer fragmentation adds complexity. Demand flows through both OEM integration and aftermarket channels, each with distinct procurement cycles, specification requirements, and margin structures. Aftermarket buyers often prioritize installation simplicity, resale value, and visible product differentiation, while OEM arrangements require reliability validation, integration timelines, and volume consistency. Managing brand positioning, inventory, and service support across these channels calls for disciplined segmentation and channel-specific value propositions.
Key Demand Drivers
Technological Innovation and Product Architecture
Product innovation continues to be a primary engine of market expansion. Advances in hard-folding mechanisms, retractable roll systems, and reinforced latch designs have broadened the functional appeal of tonneau covers beyond basic bed protection. Manufacturers are increasingly emphasizing full-bed access, low-profile contours, and heightened security features, reflecting a shift from commodity coverage to integrated utility solutions. The introduction of flip-up and trifold hard variants demonstrates how mechanical design can address contractor workflows, recreational towing setups, and daily driver convenience simultaneously. Pre-launch interest in newly presented premium models indicates that differentiated engineering can generate meaningful pull before broad retail availability, signaling that design-led innovation remains a viable path to share gains.
Policy and Regulatory Dynamics
Trade policy is emerging as a decisive factor in sourcing strategy and competitive positioning. The recent filing of antidumping and countervailing duty petitions by a coalition of domestic manufacturers has triggered federal investigations into truck bed cover imports from China. Beyond the immediate legal process, this signals a broader environment in which domestic producers are actively seeking to reshape the competitive baseline through trade remedies. For industry participants, the implications extend past headline tariff rates. Sourcing roadmaps, inventory buffers, pricing architectures, and even product mix decisions may need to adapt to a landscape where import costs, lead times, and supply continuity are less predictable. Companies with flexible manufacturing footprints and diversified supplier bases are better positioned to absorb policy shocks while preserving margin integrity.
Demand-Side Shifts in Consumer and Commercial Behavior
Demand patterns reflect evolving truck ownership use cases. For consumer buyers, tonneau covers increasingly serve as both functional equipment and visual customization elements, contributing to bed security, weather resistance, and vehicle appearance. For commercial operators and contractors, the value proposition tilts toward durability, fast access, load protection, and compatibility with work-related accessories. The durable appeal of truck platforms in North America underpins consistent aftermarket demand, while regional variations in vehicle mix and purchasing power influence product preferences. This dual demand structure supports a market where both lifestyle-oriented and work-oriented buyers contribute to growth, but it also requires clear messaging and product tiering to avoid diluting brand equity across segments.
Supply Chain and Cost Structure Evolution
Cost structures are being reshaped by a combination of input price dynamics, logistics complexity, and the strategic response to trade actions. Manufacturers that can optimize material selection, streamline installation-friendly designs, and localize key production steps gain an advantage in managing volatility. At the same time, the aftermarket channel places a premium on packaging, instructions, and support assets that reduce installation friction and return rates. In this environment, operational efficiency is not only a margin safeguard but also a customer experience driver. Companies that invest in predictable fulfillment, clear compatibility information, and robust warranty support can differentiate even in a market where product forms are increasingly familiar.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a set of established manufacturers with strong brand portfolios, multi-brand architectures, and deep aftermarket presence. Several of the leading names operate under shared corporate umbrellas, enabling portfolio breadth across folding, rolling, retractable, and hard-cover categories. This structure creates advantages in distribution reach, cross-brand merchandising, and the ability to address multiple price tiers and use cases within a single organizational framework. At the same time, other independent premium-focused manufacturers compete through design innovation, contractor-oriented feature sets, and pre-launch market engagement that builds anticipation ahead of full commercial release.
Leading players generally pursue differentiation along a few recognizable axes. One is mechanical performance and warranty assurance, where folding and retractable systems are positioned around strength, durability, and repeated-use reliability. Another is aesthetic and usability refinement, including low-profile profiles, clean bedlines, and accessories that complement toolbox installations or specialized bed layouts. A third is channel execution, where strong aftermarket distribution and installer relationships help convert product specifications into retail demand. Companies that combine product credibility with clear installation advantages and consistent availability tend to hold an edge in a market where purchase decisions are influenced by both function and convenience.
Truck Tonneau Covers Market
Market structure appears to be moving toward a blend of consolidation and specialized differentiation. Portfolio consolidation under multi-brand 소유 structures allows broader coverage of product types and customer segments, while independent premium entrants continue to pursue niche leadership through targeted launches and distinctive mechanical concepts. This duality suggests that scale and reach will remain important, but they will not automatically determine outcomes. Newer models that generate early buyer interest and articulate a clear use-case advantage can secure positioning even in a crowded category. The presence of multiple brands under common ownership also raises the importance of internal segmentation discipline, ensuring that each brand maintains a coherent identity rather than competing against itself across price points and features.
Worldwide LED Tube Covers Market
Recent developments illustrate how competitive momentum is being built. A coordinated trade case effort by a group of prominent domestic manufacturers highlights a strategic attempt to influence the import environment and protect domestic production economics. Simultaneously, premium manufacturers have used industry events and pre-order campaigns to validate demand for next-generation designs, with early interest signals suggesting that innovative trifold and flip-up concepts can attract committed buyer attention before full launch. These moves underscore two parallel strategies in the market: one focused on shaping the external competitive environment, and another focused on capturing demand through product novelty and launch execution.
Forward Outlook: Trends Shaping 2026–2032
Several trends are likely to define the market over the next three to five years. The first is continued product architectural diversification. Hard folding, retractable, and soft roll-up formats will coexist, but incremental improvements in sealing, locking, ease of operation, and bed access will matter increasingly for share shifts. Premium trifold and flip-up designs that combine strength with convenient access are poised to gain traction among buyers who need frequent bed usage without sacrificing coverage. As these designs mature, expectations for fit, finish, and compatibility across popular truck platforms will rise, rewarding manufacturers that invest in platform-specific engineering and clear fitment guidance.
The second trend is a more contested and policy-sensitive import environment. The outcome of ongoing trade investigations could alter relative cost structures and redirect sourcing strategies. Even without dramatic policy changes, the mere prospect of duties and investigations encourages buyers and sellers to reconsider exposure, buffer inventory, and evaluate domestic or near-domestic alternatives. This creates both risk and opportunity: companies with adaptable supply chains can use the transition period to strengthen carrier relationships, negotiate better terms, and reinforce brand trust through reliability, while those with concentrated import dependence may face margin and availability pressure.
The third trend is channel-specific value creation. As the market grows toward the upper range projected for the early 2030s, success will increasingly depend on how well manufacturers and distributors align product portfolios with channel realities. Aftermarket demand will reward installation-friendly designs, clear compatibility information, and strong retail visibility. OEM-adjacent opportunities will favor proven durability, integration timing, and specification consistency. In both paths, brands that articulate a crisp value proposition and support it with dependable fulfillment and service will be better positioned to convert market growth into sustained share gains.
Potential risks and uncertainties should be factored into planning. Policy outcomes remain uncertain, and the timing or scope of any duty measures could differ from current expectations. Input cost volatility may continue to pressure margins, particularly for products that rely heavily on specific metals or polymer grades. Consumer and commercial demand could also shift with broader truck sales patterns, economic conditions, and regional purchasing behavior. Finally, competitive intensity may increase as brands refine portfolios and new entrants test differentiated concepts, raising the bar for launch execution and ongoing product refresh cycles.
PW Consulting
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to align product architecture with clear use-case advantages while building operational flexibility. Engineering investments should target the features that most influence purchase decisions in each segment, such as full-bed access, weather sealing, locking confidence, and installation simplicity. At the same time, sourcing and inventory strategies should be reviewed for exposure to shifting trade conditions, with an emphasis on optionality, lead-time reliability, and margin resilience. Strong fitment data, installer support assets, and warranty clarity can convert product quality into channel confidence, which is especially valuable when buyers face installation or compatibility questions.
For investors, the market offers a constructive growth backdrop, but selectivity matters. Favorable expansion through the forecast period is supported by durable truck-culture demand and ongoing product innovation, yet the most attractive exposures will likely be those with defensible brand positioning, channel strength, and the ability to manage trade-related volatility. When assessing opportunities, it is useful to look beyond top-line growth potential and examine how well a company can sustain margins under changing cost structures, how diversified its product portfolio is across folding, retractable, and soft categories, and whether its launch cadence and pre-market engagement generate genuine demand pull. Early signals from new premium launches suggest that differentiated designs can create near-term momentum, but durability of that advantage will depend on execution quality and follow-through across the full product lifecycle.
For procurement teams and channel partners, the focus should be on predictability and compatibility. Evaluating suppliers on fitment reliability, installation support, and fulfillment consistency can reduce downstream friction and protect customer satisfaction. As trade dynamics evolve, maintaining visibility into sourcing origins and inventory buffers can help avoid disruption. Procurers should also consider how product choice aligns with end-customer expectations in their specific region and customer mix, since the balance between lifestyle-driven and work-driven demand can vary meaningfully across markets. Building a shortlist of suppliers that can support multiple cover types and provide clear warranty and compatibility information can improve both operational stability and sales confidence.
For organizations that need to move quickly with detailed, segment-level decision data, a comprehensive research report can provide the granularity required to translate market direction into concrete plans. Detailed breakdowns of product types, application channels, regional demand patterns, and competitive positioning enable more precise forecasting, sourcing choices, and launch prioritization. In a market where trade policy, product innovation, and channel execution are all shifting at once, timely access to structured intelligence can help teams calibrate investment, inventory, and messaging with greater confidence.
For detailed analysis of this topic, please visit the official page: Tonneau Covers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


