



Oligonucleotide Pool Library Market: How 12.35% CAGR & CRISPR Demand Reshape Strategy

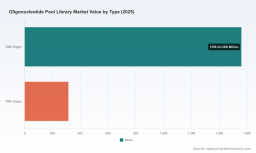
Strategic Trends and Commercial Opportunities in the Oligonucleotide Pool Library Market
Market State and Core Challenges
The oligonucleotide pool library market has evolved from a specialized research enabler into a strategic infrastructure layer for synthetic biology, functional genomics, and precision therapeutics. Over the past five years, the sector has demonstrated sustained momentum, with market valuation climbing from approximately $880 million in 2020 to $1.875 billion in 2025. Forward projections indicate continued expansion, reaching an estimated $4.2 billion by 2032 and reflecting a compound annual growth rate of 12.35 percent across the 2026–2032 forecast horizon. This trajectory signals a market transitioning from early adoption curves into mainstream scientific and commercial workflows, where oligonucleotide pools are no longer optional research tools but foundational inputs for discovery pipelines and manufacturing processes.
The pace of growth, however, is not uniform across the value chain. Demand is increasingly concentrated around applications that require high complexity, low error rates, and scalable production formats. Target capture workflows, CRISPR/Cas9 design libraries, and gene synthesis programs continue to absorb the largest shares of commercial activity, while library preparation and adjacent use cases are gaining relevance as sequencing and diagnostic platforms become more decentralized. The geographic distribution of activity reflects mature demand centers alongside rapidly expanding research ecosystems, creating a multi-speed environment where supply readiness, regulatory familiarity, and scientific capability vary significantly by region.
At the same time, the industry is navigating several structural challenges that will shape competitive outcomes over the next decade. First, cost volatility in core synthesis inputs remains a persistent pressure point. Phosphoramidite building blocks and related reagents have experienced recurring price fluctuations, introducing uncertainty into unit economics and forcing suppliers to balance margin protection with customer retention. Second, the market is not yet fully consolidated, with competitive intensity spread across established manufacturers and specialized entrants. A moderately fragmented landscape can drive innovation and customization, but it also creates pricing ambiguity and service inconsistency that buyers must navigate carefully. Third, the regulatory trajectory for oligonucleotides is becoming more defined, particularly as synthetic libraries move closer to diagnostic, therapeutic, and commercial applications. Evolving guidance on manufacturing practices, characterization, and quality control is raising the bar for documentation, reproducibility, and compliance, especially for organizations scaling production beyond research-grade environments.
Oligonucleotide Purification Market
These dynamics create a market that is expanding rapidly, but not without friction. The central question for industry participants is no longer whether demand will continue to grow, but how effectively they can manage input risk, align service models with emerging application requirements, and position themselves within a competitive field that is likely to become more structured over time.
Key Drivers of Market Change
Technological Innovation and Synthesis Scaling
The most direct driver of market growth is the continued refinement of oligonucleotide synthesis and library construction technologies. Chip-based and array-based synthesis approaches have expanded the practical limits of pool size, complexity, and turnaround time, enabling researchers and developers to move from small custom batches to large-scale library formats without proportionally increasing cost or lead time. At the same time, improvements in sequence design, error correction, and pool QC workflows have reduced the operational overhead associated with library deployment. This matters because the commercial value of oligonucleotide pools is increasingly tied not just to raw production capacity, but to the reliability and usability of the final product in downstream applications.
Recent industry activity reflects this technological emphasis. Twist Bioscience, for example, has built its market positioning around array-based oligonucleotide pool libraries for gene synthesis, gene editing, and synthetic biology applications, illustrating how synthesis platform differentiation can become a commercial identity. IDT has similarly expanded its relevance by offering custom DNA and RNA oligonucleotide pools tailored to library preparation, CRISPR, and multiplex sequencing workflows. These profiles are not merely product descriptions; they signal a broader shift in which suppliers are competing on application fit, throughput, and integration with customers’ experimental pipelines rather than on price alone.
PW Consulting Health Care Research Center
Regulatory Maturation and Quality Expectations
Regulatory and quality infrastructure is becoming an increasingly important market driver, particularly as oligonucleotide pools move from purely academic contexts into environments where reproducibility, traceability, and consistency carry higher stakes. The EMA’s draft guideline on the development and manufacture of oligonucleotides addressed manufacturing processes, characterization, specifications, and analytical control, signaling a more formal expectation around how oligonucleotides should be produced and documented. Although initially framed around broader development pathways, such guidance has practical implications for pool manufacturers because it raises the baseline for process discipline and quality assurance.
In parallel, regulatory attention in the United States has included focus on generic oligonucleotide challenges, such as quality assessment and immunogenicity considerations for synthetic oligos. These developments do not necessarily slow demand, but they do change the cost of entry and the value of established manufacturing practices. Organizations that can demonstrate robust QC, clear specifications, and dependable documentation are better positioned to serve customers who face increasing internal or external scrutiny. In that sense, regulatory maturation is acting as both a compliance requirement and a competitive filter.
Demand-Side Shifts in Research and Commercial Pipelines
Demand for oligonucleotide pool libraries is increasingly shaped by how scientific and commercial organizations structure their discovery and validation workflows. CRISPR/Cas9 design libraries remain a major demand anchor, reflecting continued investment in gene editing and functional genomics. At the same time, target capture and gene synthesis applications are expanding as researchers and developers seek more efficient routes to screening, validation, and construct generation. The broader trend is toward libraries that can support multiplexed, high-throughput experiments without sacrificing specificity or interpretability.
This demand evolution is also visible in pricing and product structuring. Commercial offerings increasingly reflect tiered or scale-sensitive pricing models, with costs varying substantially depending on pool size and specification. That pattern indicates a market in which buyers are not simply purchasing synthetic material; they are negotiating access to capacity, complexity, and service levels. As a result, demand-side behavior is pushing suppliers to think more carefully about portfolio design, minimum order structures, and the trade-off between flexibility and scale.
Supply Chain and Cost Structure Pressures
No discussion of market drivers is complete without acknowledging the fragile cost structure underlying oligonucleotide production. Phosphoramidite chemistry remains central to synthesis, and ongoing increases in raw material costs have introduced volatility that affects pricing, lead times, and planning assumptions. This is not a transient issue. Raw material dependencies can create exposure to broader supply chain disruptions, which in turn influence how suppliers price risk, manage inventory, and negotiate long-term agreements.
Recent pricing adjustments by service providers illustrate how these pressures translate into commercial decisions. Updates to oligonucleotide synthesis service pricing have been attributed to rising raw material costs and external factors, reinforcing the idea that input economics are actively reshaping market pricing behavior. For buyers, this means procurement strategies need to account for more than unit price; they must consider stability, forecasting alignment, and the durability of supplier relationships under cost pressure. For manufacturers, the challenge lies in balancing pass-through costs with the need to remain competitive, especially when multiple vendors are vying for the same application-driven demand.
Competitive Landscape and Leading Strategies
The competitive environment in this market is defined by a mix of established molecular biology suppliers, synthesis-focused manufacturers, and specialized library providers. Entities such as Twist Bioscience, IDT, Agilent Technologies, CustomArray, LC Sciences, Synbio Technologies, Daicel Arbor Biosciences, GenScript, Dynegene Technologies, General Biosystems, and Creative Biogene each bring distinct positioning to the market, often anchored in specific applications, formats, or workflow advantages.
A few patterns stand out. One is the emphasis on application-specific differentiation. Some suppliers position strongly around gene synthesis and synthetic biology workflows, while others focus on library preparation, CRISPR-related libraries, in-situ hybridization, or targeted sequencing support. This specialization matters because oligonucleotide pools are rarely interchangeable from the customer’s perspective; the value of a pool often depends on how well it fits the experimental design, screening format, or validation pathway.
Another pattern is the importance of scale and synthesis format. Companies leveraging chip-level or array-based synthesis often emphasize throughput and library size as core value propositions, which can be especially attractive for large-scale gene synthesis or functional genomics programs. Others compete by offering custom services, flexible ordering, or strong support for niche applications. In practice, this creates a landscape where some leaders compete on volume and process efficiency, while others compete on customization and service depth.
The market is also characterized by moderate concentration, with leadership shared across multiple firms rather than dominated by a single player. That structure has implications for strategy. For incumbents, the priority is often to deepen application relevance, improve process reliability, and protect margins in the face of input cost volatility. For newer or smaller entrants, the opportunity frequently lies in serving underserved workflows, regional demand, or specialized library formats that larger suppliers may not prioritize. For buyers, the practical takeaway is that supplier selection should be driven by workflow compatibility and service reliability as much as by headline pricing.
Market evolution is likely to proceed along two simultaneous paths: consolidation among players seeking scale, manufacturing efficiency, or broader workflow integration, and differentiation among those targeting specific application segments or technical niches. Recent licensing and technology-sharing activity, such as agreements involving exNA oligonucleotide technology and related reagents for research use, suggest that strategic partnerships and IP-enabled access are becoming more relevant alongside pure manufacturing competition. In a market where performance, quality, and cost are all contested, access to enabling technology can be as important as production capacity.
Future Trends and Commercial Opportunities
Over the next three to five years, several trends are likely to shape the direction of the oligonucleotide pool library market and create distinct commercial opportunities.
One major trend is the continued alignment of library supply with high-value application clusters. Demand will likely remain strongest where oligonucleotide pools directly enable screening throughput, gene editing design, target validation, and construct generation at scale. Suppliers that can package synthesis capability with application-aware design support, QC consistency, and predictable turnaround will be better positioned to capture recurring demand from organizations that rely on libraries as part of standard workflows. The commercial opportunity here is not simply to sell more pools, but to become embedded in the operational rhythm of research and development teams.
A second trend is the growing importance of cost discipline and supply resilience. As raw material volatility persists and pricing becomes more sensitive to external cost pressures, both suppliers and buyers will need stronger planning frameworks. For suppliers, this may mean more structured pricing tiers, improved inventory and feedstock strategy, and clearer communication around cost drivers. For buyers, the opportunity lies in moving from transactional purchasing to more strategic sourcing, including multi-supplier planning, forecast sharing, and evaluation of total workflow cost rather than per-pool price alone. Organizations that handle this transition well can reduce exposure to price shocks while maintaining access to the library formats they need.
A third trend is the broadening of quality and regulatory readiness as commercial differentiators. As guidance continues to develop and applications become more consequential, documentation, reproducibility, and process control will carry increasing weight. Companies that invest early in quality systems, characterization rigor, and transparent specifications may gain access to more demanding customer segments and higher-value projects. Conversely, suppliers that treat quality as a secondary concern may find their addressable market narrowing as customer expectations rise.
These trends carry risk as well. Demand growth could be uneven if certain application areas mature faster than others, or if technology shifts alter the need for specific pool formats. Input cost volatility could compress margins or disrupt planning if supply chains remain vulnerable. Regulatory expectations could increase overhead for smaller operators, potentially accelerating consolidation or raising barriers for new entrants. The net effect is a market with strong upside, but one in which advantage will increasingly belong to players who can manage risk while delivering dependable, application-aligned products.
Oligosaccharide Market
Implications for Decision-Makers
Different stakeholders in this market face distinct strategic priorities, but all can benefit from a clearer view of where demand, cost, and competition are heading.
For manufacturers and service providers, the priority should be to sharpen application alignment and strengthen operational resilience. This includes evaluating which library formats and workflows offer the best combination of demand durability and margin potential, while also reassessing exposure to raw material volatility and lead-time variability. Suppliers that can offer predictable quality, transparent pricing logic, and reliable delivery will have an advantage as customers become more deliberate about vendor selection. It also means paying attention to technology access and partnerships, since differentiation may increasingly come from proprietary synthesis methods, QC capabilities, or specialized library designs rather than from scale alone.
For investors, the useful question is less about whether the market will grow than about where value will accrue within it. The strongest opportunities are likely to be found in companies that can demonstrate durable demand linkages, defensible synthesis or service advantages, and the ability to manage cost volatility without eroding competitiveness. At the same time, it is worth watching for consolidation signals, pricing behavior, and regulatory shifts that could change the relative position of incumbents and entrants. In a market with moderate concentration and strong application specialization, due diligence should focus on workflow relevance, quality infrastructure, and the sustainability of unit economics under cost pressure.
For procurement teams and research organizations, the strategic imperative is to treat oligonucleotide pool sourcing as a workflow decision rather than a commodity purchase. Evaluating suppliers should include attention to application fit, error profiles, turnaround reliability, documentation standards, and the credibility of pricing in the face of raw material volatility. Building a sourcing strategy that balances flexibility with stability can reduce the risk of disruption while improving the consistency of experimental outcomes. Where possible, organizations should also consider forecasting and planning collaboration with suppliers, since cost and capacity dynamics are increasingly intertwined with commercial pricing.
For readers seeking a more detailed view of segmentation dynamics, competitive positioning, pricing structures, and regional demand patterns, the full market research report provides a deeper evidence base and more granular scenario analysis. In a market moving this quickly, the value of detailed intelligence lies in its ability to turn broad trends into specific decisions about suppliers, investment exposure, procurement strategy, and product development priorities.
For detailed analysis of this topic, please visit the official page: Oligonucleotide Pool Library Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


