



Pharmaceutical Grade Sodium Chloride: Asia Pacific’s 67% Share and 5.6% CAGR Reshape Growth

Pharmaceutical Grade Sodium Chloride Market: Strategic Trends and Commercial Opportunities in a Shift-Driven Landscape
Market Snapshot: Growth Trajectory and Structural Realities
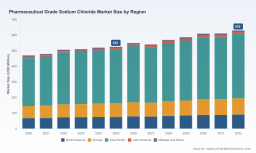
The pharmaceutical grade sodium chloride market has settled into a steady expansion phase, with revenue reaching approximately $525 million in 2025 and projected to approach $630 million by 2032. The implied compound annual growth rate of 5.6 percent reflects a market that is growing not through explosive demand surges, but through gradual capacity additions, formulation complexity, and sustained healthcare consumption across mature and emerging regions alike. Historical data from 2020 through 2025 shows a relatively smooth upward trajectory, punctuated by modest step changes rather than sharp inflection points, suggesting that core demand drivers have remained resilient even as feedstock costs, logistics, and regulatory expectations have shifted.
What makes this market structurally interesting is its concentration profile. The top three players account for roughly 28.5 percent of revenue, while the top five capture about 35.2 percent. That level of fragmentation, combined with steady growth, signals a landscape where scale advantages exist but are not insurmountable. Regional and application splits reveal clear concentration patterns: the Asia Pacific region represents the largest revenue pool, while the market is bifurcated by type between active pharmaceutical ingredient grade sodium chloride and hemodialysis grade material. On the application side, injections and hemodialysis dominate the demand base, with oral rehydration salts, osmotic agents, and other uses contributing meaningful but smaller shares. Rather than focusing on individual share percentages, the strategic takeaway is that high-value clinical applications and large-volume therapeutic uses are pulling the market in different directions, each with distinct quality, logistics, and margin expectations.
Several structural challenges and transition points are shaping how participants navigate this growth. First, regulatory scrutiny around impurity profiles, traceability, and batch documentation continues to intensify, especially for materials used in parenteral and dialysis applications where patient safety margins are narrow. Second, cost volatility in energy, purification inputs, and distribution has compressed margins for suppliers that lack integrated quality systems or flexible sourcing models. Third, regional demand growth is uneven, with mature markets facing price discipline and capacity rationalization, while high-growth regions require localized compliance readiness, consistent specification management, and stronger technical support. These dynamics mean that growth alone is not enough; suppliers must convert volume into dependable, specification-grade supply with clear quality differentiation.
Key Drivers Reshaping Demand and Competitive Positioning
Technical Innovation in Purification and Controlled Manufacturing
Advances in purification technology, crystallization control, and analytical verification are redefining what suppliers can reliably deliver at pharmaceutical grade. Improvements in trace metal control, endotoxin management, and particle size consistency have become increasingly important for injection-grade and dialysis-grade applications, where even minor deviations can affect downstream processing or clinical performance. Manufacturers that have invested in closed-loop handling, validated cleaning protocols, and robust quality documentation are better positioned to serve customers who require tight specification adherence across multiple batches. For buyers, this shift means that technical capability is increasingly evaluated not just by certificate compliance, but by the consistency of lot-to-lot performance, the transparency of testing, and the supplier’s ability to support troubleshooting when formulations are adjusted.
Worldwide Pharmaceutical Grade Calcium Hydroxide Market
The innovation curve also extends to packaging, storage, and transport conditions that preserve material integrity. Moisture control, contamination prevention, and shelf-life stability are gaining attention as supply chains become more distributed and inventory strategies more cautious. This matters because pharmaceutical grade sodium chloride is often treated as a commodity input, yet its downstream use can be highly sensitive. Suppliers that align processing improvements with practical logistics and documentation benefits are creating a more defensible value proposition than those competing purely on price.
Regulatory and Policy Environment: Stricter Expectations, Higher Barriers
Policy and regulatory expectations continue to evolve in ways that raise the quality bar and increase the cost of market entry for lower-capability players. Pharmaceutical grade materials sit at the intersection of industrial chemical production and healthcare compliance, which means they are subject to rigorous documentation, quality system expectations, and increasingly detailed impurity surveillance. In practical terms, this environment favors suppliers that can demonstrate controlled manufacturing, reliable audit readiness, and clear traceability from raw source to finished batch. It also reinforces the importance of harmonization across regions, since multinational buyers increasingly seek consistent specifications regardless of sourcing location.
The regulatory backdrop is not solely a constraint; it is also a competitive filter. As compliance expectations rise, suppliers with mature quality infrastructure and experienced regulatory support gain an advantage in securing long-term supply agreements, especially with larger pharmaceutical and dialysis operators that prioritize supply reliability over spot pricing. At the same time, buyers are becoming more discerning about vendor qualification, testing protocols, and change-control management, which raises the stakes for suppliers that treat quality systems as administrative rather than operational capabilities.
Demand-Side Evolution: Clinical Complexity, Volume Growth, and Formulation Strategy
On the demand side, the market is being shaped by a combination of steady clinical consumption and evolving formulation needs. Injections and hemodialysis applications remain central demand pillars because sodium chloride is integral to solution preparation, dilution, and dialysis fluid composition. As healthcare delivery expands and treatment volumes increase, especially in regions scaling hospital infrastructure and outpatient services, demand for dependable pharmaceutical grade material continues to grow. At the same time, formulation strategies are becoming more nuanced, with manufacturers seeking materials that integrate smoothly into multi-component preparations and meet tighter internal quality standards.
Another demand-side development is the growing emphasis on supply assurance. Buyers are less willing to accept variability in lead times, specification consistency, or documentation completeness, particularly when production downtime or batch deviation carries high cost or clinical risk. This is changing purchasing behavior: procurement teams are placing more weight on supplier reliability, technical responsiveness, and continuity planning than on headline price alone. The result is a market where differentiated service and quality assurance can support stronger commercial positioning, especially when tied to long-term supply arrangements.
PW Consulting Chemical & Energy Research Center
Supply Chain and Cost Structure: Energy, Sourcing, and Logistics Pressure
Cost structures in this market are influenced by energy usage, purification requirements, source material variability, and distribution complexity. Because pharmaceutical grade sodium chloride requires controlled processing and verification, it is more sensitive than industrial-grade equivalents to fluctuations in operating costs and transport conditions. Suppliers that can manage energy intensity, source consistent inputs, and minimize handling risk gain a margin advantage, while those exposed to fragmented sourcing or less controlled processing face greater volatility.
Logistics further complicates the cost picture. Pharmaceutical-grade materials often require careful storage, contamination control, and documentation handoffs across borders or regions. In markets where import dependence is high or where regulatory clearance adds time and cost, lead-time reliability becomes a commercial differentiator. This environment pushes companies toward either regional sourcing strategies, integrated production and supply models, or stronger partnerships with distributors that can support compliance and traceability requirements. The broader implication is that cost competitiveness in this market is increasingly about operational discipline and supply continuity, not simply unit pricing.
Competitive Landscape: Positioning, Differentiation, and the Shape of Consolidation
Established Players and Differentiated Strategies
The competitive field includes a broad set of global and regional players with distinct strategic orientations. Large diversified chemical and salt producers bring advantages in scale, sourcing breadth, and distribution reach. Their positioning often emphasizes dependable volume supply, multi-region availability, and established quality systems that support pharmaceutical customer qualification. For these companies, the opportunity lies in converting broad salt-production expertise into a controlled pharmaceutical-grade offering that can compete on reliability as well as cost.
Alongside these broader players, specialized producers and regional manufacturers focus on tighter specification control, local compliance readiness, and closer technical engagement with buyers. Their differentiation typically comes from product consistency, responsive documentation, and the ability to serve specific customer segments such as injection preparation, hemodialysis fluids, or regional formulation needs. These companies often compete by demonstrating that they can reduce variability and support tighter integration into customer processes, which is valuable when procurement teams prioritize risk reduction over purely transactional pricing.
A third group of participants operates with a niche or application-specific orientation, serving laboratory, specialty formulation, or highly regulated use cases where documentation, purity thresholds, and batch control are paramount. Their commercial leverage often depends on technical trust, reproducibility, and the ability to maintain stringent handling standards. In a market where the top three and top five players hold only modest combined shares, these specialized positions can remain viable if they deliver clearly differentiated quality and service.
How Leading Companies Are Structuring Advantage
Across the competitive set, several strategic themes recur. One is the focus on controlled processing and quality documentation as a commercial asset. Suppliers that can show consistent impurity control, validated manufacturing practices, and complete traceability are better positioned to win and retain pharmaceutical customers who treat material qualification as a multi-year decision rather than a periodic purchase. Another theme is the alignment of product grades with end-use requirements. Because API-grade and hemodialysis-grade sodium chloride serve different functional and regulatory contexts, companies that clearly articulate grade-specific capabilities and test data can reduce friction in buyer evaluation and strengthen their positioning in targeted segments.
A third recurring strategy is the use of technical service as a differentiator. Suppliers that provide formulation support, specification clarity, troubleshooting assistance, and reliable change-control communication can create stickier customer relationships. This is especially relevant in applications where sodium chloride must integrate with other ingredients or where patient-facing formulations demand high consistency. In practice, competitive advantage is increasingly built on the combination of material quality, documentation reliability, and the supplier’s ability to reduce operational risk for the buyer.
Market Evolution: Fragmentation, Selective Consolidation, and New Entrants
The market’s concentration profile suggests ongoing fragmentation rather than dominance by a small number of incumbents. That structure creates space for both consolidation and new entry, depending on capabilities and regional positioning. Consolidation is likely to occur where scale, quality infrastructure, and regional coverage can be combined to serve multinational buyers more efficiently. In contrast, new entrants may find footholds by addressing specific quality, specification, or service gaps that larger suppliers do not fully cover, particularly in regions where localized compliance and technical support are valued.
A practical evolution to watch is the growing importance of regional supply resilience. Buyers in multiple markets are increasingly attentive to sourcing diversification and continuity risk, which can benefit suppliers that offer dependable local or near-local supply with appropriate quality credentials. At the same time, multinational procurement standards are pushing the market toward greater consistency in documentation and testing expectations, which may pressure smaller players without strong quality systems. The net effect is a landscape where competitive success depends less on claiming general market presence and more on demonstrating reliable performance in the specific grade, application, and region that matters to the customer.
Looking Ahead: Three Trends That Will Shape the Next Three to Five Years
Trend One: Quality and Traceability Become Commercial Differentiators
Over the next several years, pharmaceutical grade sodium chloride is likely to be evaluated less as a routine chemical input and more as a quality-sensitive component whose consistency, documentation, and traceability directly affect buyer risk. As regulatory and internal quality expectations rise, suppliers with stronger analytical verification, controlled handling, and transparent batch records will be better positioned to secure long-term agreements and command more stable pricing. For manufacturers and procurement teams, this trend means that supplier selection should increasingly weigh quality reliability and documentation completeness alongside cost and lead time.
Trend Two: Regional Demand Growth Will Redefine Sourcing Strategies
Demand growth will remain uneven across regions, with larger revenue pools continuing to attract attention while high-growth areas require more localized readiness. This will encourage suppliers to develop region-specific quality alignment, distribution responsiveness, and technical support capacity. For buyers, the strategic implication is that sourcing decisions may increasingly balance global consistency with regional resilience, especially where supply interruptions or specification mismatches carry high operational risk. Companies that can provide predictable supply in the right region, with appropriate pharmaceutical-grade credentials, will have an advantage in winning disciplined, long-cycle procurement relationships.
Trend Three: Capacity, Cost Discipline, and Margin Pressure Will Separate Operators
As the market grows at a moderate pace, the competitive battleground will shift toward operating efficiency and cost discipline. Energy usage, purification intensity, logistics overhead, and waste control will matter more as buyers become more price-aware and suppliers compete for share in a fragmented market. Operators that can manage cost structures without compromising pharmaceutical-grade consistency will be better positioned to protect margins, while those with weaker process control may face pressure to lower prices or lose qualification status. The risk is that cost-cutting efforts erode the very quality attributes that justify pharmaceutical-grade positioning in the first place, so the winning approach will likely combine efficiency with rigorous quality assurance rather than sacrificing one for the other.
Sodium Chloride Injection Market
Risks and Uncertainties to Monitor
Several uncertainties could alter the pace or shape of growth. Regulatory expectations may tighten further in ways that raise compliance costs or change documentation requirements, especially for materials used in sensitive clinical applications. Cost volatility in energy and logistics could compress margins and shift sourcing preferences faster than suppliers can adapt. Demand patterns may also evolve if healthcare delivery models change, if formulation strategies shift away from certain uses, or if alternative sourcing models alter how buyers qualify and manage suppliers. Finally, regional supply disruptions or trade friction could expose vulnerabilities in concentrated sourcing strategies, making diversification and continuity planning more important than ever.
Actionable Guidance for Decision-Makers
For manufacturers and suppliers, the priority is to treat pharmaceutical-grade consistency as a growth lever rather than a compliance checkbox. Investing in purification control, analytical verification, and documentation reliability can improve qualification success and support longer contract cycles. Equally important is clarifying grade-specific capabilities so that customers can quickly see which applications a supplier is best equipped to serve. Companies that align product quality, technical support, and regional availability will be better positioned to convert steady market growth into durable share gains.
For investors, the key is to distinguish between suppliers that are scaling volume and those that are building defensible pharmaceutical-grade capability. Growth in this market is real, but value creation will favor operators with strong quality systems, controlled cost structures, and the ability to retain customers through reliability rather than price alone. Investment diligence should therefore focus on manufacturing discipline, regulatory readiness, traceability, and the company’s capacity to serve high-value applications without compromising specification integrity.
For procurement and supply chain leaders, the strategic imperative is to evaluate suppliers on a broader set of criteria than unit price alone. Lead-time reliability, lot-to-lot consistency, documentation completeness, change-control responsiveness, and continuity planning all matter when sodium chloride feeds into injections, dialysis fluids, or other sensitive applications. Diversifying supply where appropriate, qualifying suppliers with strong quality systems, and maintaining clear specification expectations can reduce operational risk while preserving cost discipline.
Given the range of regional, technical, and regulatory variables shaping this market, detailed segment-level data and tailored supply-chain assessment can make a meaningful difference in planning. For decision-makers seeking deeper visibility into volume patterns, application-specific demand, grade-level positioning, and supplier qualification dynamics, a more comprehensive market review can help translate these trends into concrete sourcing, investment, and production decisions.
For detailed analysis of this topic, please visit the official page: Pharmaceutical Grade Sodium Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


