



Vacuum Aluminum Plating Machine Market CAGR Insights: What Fuels the 8.9% Growth

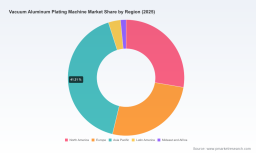
The Strategic Shift in the Vacuum Aluminum Plating Machine Market: Trends and Commercial Opportunities Through 2032
The vacuum aluminum plating machine market is entering a decisive growth phase, driven by the convergence of environmental mandates, technological maturation, and shifting industrial demand patterns. Valued at approximately 302.9 million USD in 2025, the market has expanded from 180.1 million USD in 2020, reflecting a compound annual growth rate of 8.9 percent through 2032. By the end of the forecast period, total market revenue is projected to reach 547.4 million USD. This trajectory signals more than incremental expansion; it points to a structural realignment in how manufacturers approach surface finishing, metallization, and coating processes. Understanding the forces shaping this landscape is essential for executives, investors, and procurement leaders who must navigate capital allocation, compliance timelines, and competitive positioning.
Market Landscape and Core Challenges
The market's growth narrative is anchored in steady incremental gains across the 2020 to 2025 period, followed by an acceleration in the forecast horizon. Revenue climbed from 180.1 million USD in 2020 to 222.16 million USD in 2022, then to 247.73 million USD in 2023 and 275.44 million USD in 2024. The 2025 baseline of 302.9 million USD sets the stage for a forecast continuum that moves from 320.57 million USD in 2026 to 368.52 million USD in 2027, 397.15 million USD in 2028, 430.25 million USD in 2029, 467.26 million USD in 2030, 501.88 million USD in 2031, and 547.4 million USD in 2032. This progression underscores a market that is expanding beyond early adoption cycles into broader industrial integration. Yet the headline figures mask underlying friction points that decision-makers must address.
Structural Complexity and Process Variability
One of the most persistent challenges in this market lies in the inherent variability of vacuum aluminum plating processes. Aluminum metallizing requires precise handling of metal wire, vacuum chamber fixtures, and controlled deposition environments. The loading and unloading phases remain labor-intensive, introducing moderate unit costs and operational bottlenecks. Facilities that scale production without standardizing workflow design often encounter throughput inconsistencies, yield fluctuations, and maintenance overhead that erode margin expectations. For manufacturers evaluating equipment investments, the challenge is not simply acquiring a plating system but integrating it into a cohesive production architecture that minimizes manual intervention while maintaining coating quality.
Regulatory Pressure and Compliance Timelines
A second critical challenge stems from tightening environmental and emissions regulations. Revisions to the EPA Clean Air Act and amendments to the EU Volatile Organic Compound Directive have intensified the push toward solvent-free coating processes. Vacuum technology has emerged as a preferred pathway to eliminate solvent emissions and reduce hazardous waste generation. Simultaneously, China's National Emission Standards and the California Air Resources Board have accelerated the replacement of wet coating systems with vacuum-based aluminum plating equipment. These regulatory shifts are not abstract; they carry concrete infrastructure implications. Heavy capital investment ranging from 500,000 USD to 5 million USD per facility is required for equipment upgrades to meet environmental compliance deadlines. Organizations that delay planning for these transitions risk operational disruptions, retrofit penalties, and competitive disadvantage as peers capture early compliance benefits.
Market Concentration and Competitive Pressure
The market remains moderately concentrated, with the top three players accounting for 54.2 percent of revenue and the top five holding 67.8 percent. This concentration reflects the technical expertise, capital intensity, and regulatory navigation capabilities required to compete effectively. However, concentration also creates pressure on smaller participants and new entrants to differentiate through niche applications, regional service networks, or specialized 코팅 architectures. Companies that cannot match the process reliability, compliance readiness, or application breadth of leading suppliers face margin compression and customer attrition. The strategic question for mid-tier and emerging players is whether to pursue consolidation, focus on underserved segments, or invest in technological features that command premium positioning.
Key Drivers of Market Evolution
Technology Innovation and Process Optimization
Technological advancement is a primary engine of market growth, particularly in the areas of vacuum deposition precision, automation integration, and coating durability. Next-generation vacuum coating machines are increasingly designed to optimize industrial coatings for both performance and sustainability. Features such as enhanced vacuum pump systems, real-time video monitoring, and upgraded generation architectures enable tighter process control, reduced defect rates, and broader application flexibility. The recent introduction of high vacuum metal deposition machines with forensic-grade monitoring capabilities illustrates how equipment sophistication is expanding beyond traditional industrial use into precision and specialized finishing contexts. These innovations lower the total cost of ownership over time by improving yield consistency and reducing rework, making vacuum aluminum plating more attractive relative to legacy wet coating methods.
PW Consulting Automotive & Machinery Research Center
Policy and Regulatory Tailwinds
Regulatory developments are transforming compliance from a cost center into a market catalyst. Mandates that require the elimination of solvent emissions and the reduction of hazardous waste are directly favoring vacuum-based metallization over conventional electroplating and wet coating. The substitution effect is visible across multiple industrial verticals, where manufacturers are replacing older systems with vacuum aluminum plating equipment to meet emission standards while maintaining surface quality. Policy-driven demand is not uniform across regions, but the directional trend is clear: jurisdictions with stringent air quality and volatile organic compound frameworks are accelerating equipment replacement cycles. This regulatory momentum creates a predictable demand pipeline for manufacturers that can demonstrate compliance-ready configurations and documented emission reductions.
Demand-Side Shifts in Packaging and Electronics
Demand patterns are evolving as downstream industries prioritize lightweighting, aesthetic differentiation, and functional coating performance. Packaging applications continue to represent a substantial share of market activity, driven by the need for barrier properties, visual appeal, and durable surface finishes on plastic and film substrates. Electronics applications also contribute significantly, where aluminum metallization supports reflectivity, conductivity, and protective coating requirements for components and enclosures. Consumer and enterprise expectations for premium finishes, corrosion resistance, and consistent appearance are pushing manufacturers to adopt vacuum plating processes that deliver repeatable results at scale. The shift is not merely about replacing one coating method with another; it is about aligning surface engineering capabilities with product performance targets and brand positioning.
Supply Chain and Cost Structure Dynamics
Cost structures in vacuum aluminum plating are influenced by raw material inputs, equipment intensity, and labor workflow design. Aluminum metallizing requires metal wire and vacuum chamber fixtures, which establish a moderate baseline for unit costs. At the same time, the labor-intensive nature of loading and unloading processes creates opportunities for automation and workflow redesign. Suppliers and end-users alike are scrutinizing the balance between upfront capital expenditure and operational efficiency. Facilities that invest in streamlined material handling, standardized fixture designs, and integrated process controls can reduce per-unit labor exposure and improve throughput. Conversely, organizations that treat equipment acquisition as a standalone purchase without addressing surrounding process architecture often experience cost overruns and productivity gaps. The evolving cost dynamic favors integrated solutions that combine deposition technology with workflow optimization.
Competitive Landscape and Strategic Positioning
The competitive field features a mix of established equipment suppliers and regional specialists, with a notable presence of Chinese manufacturing firms alongside U.S.-based technology providers. This distribution reflects both the global nature of coating demand and the concentration of vacuum equipment production capacity in key industrial corridors. Company strategies differ in emphasis, with some players focusing on broad application coverage across automotive lighting, trim, and decorative functional coatings, while others concentrate on PVD thermal evaporation, multi-arc vacuum coating, and roll-to-roll metallizing for plastics and films. The diversity of product portfolios indicates a market where differentiation is achieved through application expertise, equipment architecture, and service support rather than price alone.
Differentiation Through Application Focus and Process Capability
Leading suppliers distinguish themselves by aligning equipment capabilities with specific end-use requirements. One U.S.-based provider emphasizes sputtering and evaporation metallization systems for high-brightness reflectors, automotive lighting, interior and exterior trim, and decorative functional coatings, positioning its offerings around performance consistency and broad application coverage. Several Chinese manufacturers pursue complementary strategies, with some specializing in magnetron sputtering, resistance evaporation, and cathodic arc ion coating equipment tailored for aluminum metallizing and vacuum metalizing lines. Others focus on web and roll-to-roll metallizing for aluminum evaporation on plastics and films, or on aluminum and silver mirror production lines using vacuum coating equipment. This segmentation of expertise enables suppliers to address distinct customer priorities, from decorative finishes to functional barrier coatings.
Recent Developments and Product Evolution
Recent product activity reinforces the trend toward higher precision, broader finish options, and enhanced process control. In early 2026, a major Chinese supplier released details on decorative PVD chrome and color coating equipment positioned as alternatives to traditional electroplating, signaling continued expansion into premium finish markets. Later that year, the same company highlighted optimization of industrial coatings using next-generation PVD vacuum coating machines focused on durability and sustainability. The launch of a high vacuum metal deposition machine with upgraded generation features, including high vacuum pumps and video monitoring, further demonstrates how equipment portfolios are evolving to serve both industrial and specialized forensic applications. These developments indicate that competitive differentiation is increasingly tied to feature maturity, application versatility, and the ability to support sustainability-oriented coating outcomes.
Plating Equipment Market
Market Structure Dynamics and Entry Pathways
The market structure suggests both consolidation pressure and opportunities for targeted entry. High concentration among leading players raises barriers for general-purpose competitors, but it also creates space for specialists serving niche coating requirements, regional service demands, or cost-sensitive application segments. New entrants that can demonstrate reliable deposition performance, compliance-ready designs, and streamlined integration support may capture share in underserved pockets, particularly where existing suppliers face capacity constraints or where local service responsiveness is valued. At the same time, consolidation remains a plausible trajectory as larger players seek to broaden application coverage, strengthen regional presence, and accumulate process expertise. The evolving landscape rewards companies that clearly define their strategic niche rather than competing broadly on specification sheets alone.
Forward Outlook: Trends and Opportunities to 2032
Accelerated Equipment Replacement Cycles Driven by Compliance
Over the next three to five years, regulatory-driven replacement of wet coating systems is expected to sustain demand for vacuum aluminum plating equipment. As compliance deadlines approach across multiple jurisdictions, facilities will need to coordinate capital planning, installation, and process validation within constrained windows. This creates opportunities for suppliers that can offer structured upgrade pathways, compliance documentation support, and phased deployment models. The commercial implication is clear: organizations that anticipate regulatory timelines and align equipment procurement with facility planning will secure better pricing, smoother integration, and earlier attainment of compliance benefits. The risk lies in underestimating lead times and retrofit complexity, which can compress installation schedules and increase lifecycle costs.
Automation and Workflow Integration as Margin Levers
Automation and workflow integration will become increasingly central to competitive advantage. As labor-intensive loading and unloading processes are identified as cost and variability drivers, manufacturers will look for equipment configurations that reduce manual handling, standardize fixture changeovers, and improve throughput predictability. The trend favors solutions that combine deposition technology with material handling design, process monitoring, and user interface improvements. Companies that proactively redesign workflow architecture around vacuum plating lines can convert moderate unit costs into more stable margin profiles. The uncertainty is that automation investments must be calibrated to production volume and product mix; over-investment in features that do not match actual throughput needs can weaken return profiles.
Expansion of Premium and Functional Finish Applications
A third trend points to growing demand for premium decorative finishes and functional coatings that go beyond basic aluminum metallization. The market is seeing interest in color coating alternatives to electroplating, enhanced durability features, and specialized deposition capabilities that serve precision and forensic contexts. This expansion opens commercial pathways for suppliers that can demonstrate finish quality, repeatability, and application flexibility. For end-users, the opportunity lies in leveraging advanced coating options to differentiate products, meet performance specifications, and respond to consumer expectations for appearance and durability. The risk is that premium finish claims must be supported by consistent process results; without robust quality control, differentiation can quickly erode in competitive bidding environments.
Vacuum Coating Machines Market
Strategic Recommendations for Decision-Makers
For Manufacturers Evaluating Equipment Investments
Manufacturers should approach vacuum aluminum plating equipment decisions as part of a broader process and compliance strategy rather than as isolated capital purchases. Priorities include mapping regulatory timelines to facility upgrade windows, evaluating workflow automation potential, and selecting equipment configurations that align with specific application requirements. It is advisable to compare suppliers not only on deposition specifications but also on integration support, service responsiveness, and demonstrated compliance readiness. Facilities that pilot process changes on a controlled line before full-scale deployment can reduce integration risk and refine throughput expectations.
For Investors Assessing Sector Exposure
Investors should focus on companies with clear application differentiation, credible compliance narratives, and evidence of process innovation that lowers total cost of ownership. Market concentration suggests that leadership positions are defensible, but growth opportunities are not limited to incumbents; specialized suppliers serving niche coating needs or regional service gaps may present attractive exposure. Due diligence should examine the alignment between product roadmaps and regulatory momentum, as well as the extent to which automation and workflow features are translating into customer adoption. Caution is warranted where equipment claims exceed demonstrated process consistency or where upgrade cycles depend on uncertain compliance enforcement timing.
For Procurement and Sourcing Teams
Procurement teams should prioritize total lifecycle value over initial equipment price, incorporating considerations such as compliance documentation, maintenance complexity, material handling efficiency, and service availability. Requesting application-specific performance data and validating it against internal quality targets can reduce the risk of mismatched procurement. Where possible, structuring evaluations around pilot runs and workflow simulations provides a clearer picture of throughput, labor exposure, and defect rates than specification reviews alone. Engaging suppliers early in facility planning also helps align installation schedules with compliance deadlines and production targets.
The vacuum aluminum plating machine market is positioned for sustained expansion, but the distribution of value will depend on how effectively participants navigate regulatory timelines, process complexity, and competitive differentiation. Decision-makers who combine forward planning with detailed segment-level intelligence will be better equipped to identify high-probability opportunities and avoid costly misalignment. For those seeking deeper segmentation data, company-level benchmarks, and tailored strategic recommendations, the full market research report provides a more granular view of the dynamics shaping this sector through 2032.
For detailed analysis of this topic, please visit the official page: Vacuum Aluminum Plating Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


