



Agricultural Inoculants Market: Why 10.41% CAGR Redefines Industry Growth

The Agricultural Inoculants Market at an Inflection Point: Strategic Trends and Commercial Opportunities Through 2032
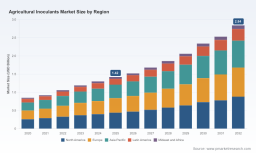
The agricultural inoculants market has moved decisively from a niche biological input category to a structural component of modern crop production. Between 2020 and 2025, global revenue expanded from approximately USD 0.85 billion to USD 1.42 billion, reflecting consistent double-digit momentum even as broader agribusiness cycles faced volatility. Looking ahead through 2032, the trajectory points toward a USD 2.84 billion endpoint, supported by a compound annual growth rate of 10.41 percent. This expansion is not simply a function of incremental adoption; it reflects a deeper recalibration in how producers, policymakers, and input suppliers approach soil biology, nutrient efficiency, and crop protection.
What makes this period distinctive is the convergence of biological efficacy with commercialization scale. Inoculants are no longer evaluated solely as substitutes for conventional inputs. They are increasingly positioned as productivity multipliers that enable reduced synthetic fertilizer use, improved stress resilience, and alignment with sustainability programs. That shift in value proposition is reshaping product architectures, partnership models, and go-to-market strategies across the sector.
For decision-makers, the immediate question is less about whether the market will grow and more about who captures disproportionate value in a space that is simultaneously fragmenting by application specificity and consolidating around integrated biological platforms.
Core Challenges and Market Inflection Points
Despite the favorable growth backdrop, the industry faces structural tensions that will separate durable players from transient entrants.
Biostimulants Market
First, consistency of biological performance remains the defining commercial hurdle. Live microorganisms must survive formulation, storage, application timing, and variable field conditions while delivering measurable yield or nutrient-use improvements. Products that perform reliably in controlled trials can disappoint under real-world heterogeneity. This creates a credibility gap that slows repeat purchases and complicates retailer recommendations. Companies that can demonstrate repeatable performance across geographies and seasons are building a moat that premium positioning and broader adoption increasingly require.
Second, the market is navigating a regulatory environment that is simultaneously enabling and constraining. In some jurisdictions, biologicals are being streamlined into sustainable-input frameworks that encourage substitution away from purely chemical programs. In others, strict product-category definitions limit the organisms, claims, and formulations that can be marketed. The European Union’s Regulation 2019/1009, for example, anchors biofertilizer marketing to a defined set of microbial genera and mycorrhizal fungi. Such rules create clarity for compliant products but also raise barriers for portfolios that depend on broader strain sets or novel delivery claims. Firms must treat regulatory design not as a fixed backdrop but as an active variable in product strategy.
Third, the sector is confronting a commercialization bottleneck. Strong institutional interest and pilot programs do not automatically translate into widespread adoption at scale. Extension services, agronomic support, and dealer education determine whether inoculants are treated as high-potential tools or as optional add-ons. USDA’s Partnerships for Climate-Smart Commodities allocated substantial funding to soil microbiome enhancement projects, and the USDA National Institute of Food and Agriculture has supported extension coverage for microbial inoculant technologies in organic and regenerative farming systems. These initiatives expand awareness and trial, yet they also underscore that adoption depends heavily on local agronomic translation. The market’s next phase will reward players who can convert research momentum into repeatable field-level execution.
What Is Really Driving Growth
The market’s upward path is being shaped by four reinforcing forces rather than a single tailwind.
Technology innovation is the most visible driver. Advances in strain selection, formulation stability, and microbial function are expanding what inoculants can deliver beyond traditional nitrogen fixation. Gene-edited nitrogen-fixing microbial technologies are moving from experimental concepts to commercial realities, with recent large-scale farm trials indicating operational efficiency gains and improved returns in specific crops. This matters commercially because it signals that biologicals can be engineered with greater functional predictability, which in turn supports premium pricing, tighter crop positioning, and stronger farmer confidence.
Policy and sustainability frameworks are second. Organic certification land in North America and Europe expanded at roughly 8.2 percent annually between 2020 and 2025, increasing demand for biological inputs permitted within those systems. At the same time, public programs tied to climate-smart practices are encouraging soil-health investments that favor microbiome-based tools. For manufacturers and distributors, this means the addressable base is widening in two directions: regulated specialty systems that explicitly require biological compatibility and mainstream acreage seeking input efficiency and compliance with sustainability commitments.
Demand-side behavior is changing too. Producers are increasingly managing for total input economics rather than isolated yield gains. With nutrient costs and application complexity under scrutiny, microbial solutions that improve nutrient-use efficiency, support soil function, or reduce reliance on specific chemical programs become more attractive. The buyer mindset is shifting from “Does this product work in ideal conditions?” to “Does this product improve my margin profile across variable conditions?” That reframing creates more room for multi-benefit inoculant platforms, especially those aligned with seed treatment, in-furrow placement, or soil health programs.
Supply chain and cost structures are evolving as well. Biological manufacturing requires refrigeration, stabilization, carrier materials, and stringent quality control. As demand scales, companies are investing in production reliability, shelf-life management, and regional distribution capacity. These investments raise the operational bar but also reinforce differentiation. Players with more robust formulation science and logistics can offer more dependable delivery, which is increasingly important as inoculants move from early adopters to broader mainstream use.
Competitive Landscape and the Battle for Positioning
The leadership group in agricultural inoculants is defined less by a single product and more by how companies integrate biologicals into broader crop portfolios, formulation capabilities, and customer reach. The competitive field includes multinational crop-science organizations, specialized biologicals companies, and region-focused innovators.
Large diversified players are positioning inoculants as an extension of seed treatment and crop protection strategies. Their advantage lies in distribution scale, agronomic networks, and the ability to bundle biological solutions with established seed and crop programs. BASF SE anchors its approach around integrated crop protection with Bacillus biocontrol lines and nitrogen-fixing inoculants such as Nodulator PRO for corn and soybean. Bayer AG emphasizes seed treatment and microbial inoculant solutions within its Crop Science division. Syngenta Group Co., Ltd. integrates microbial inoculants into its wider crop protection and seed portfolio, using biologicals to reinforce broader system offerings rather than stand-alone biological sales alone.
Specialized biologicals companies are competing through functional focus and product depth. Novonesis A/S brings bacterial and fungal inoculants aimed at nutrient uptake and soil health across field crops. Lallemand Inc. and Premier Tech Ltd. extend microbial inoculant offerings into cereals, vegetables, horticulture, and crop nutrition. These companies often compete on formulation know-how, strain expertise, and close relationships with growers and dealers who value biological specificity.
PW Consulting
A newer set of innovators is pushing performance boundaries through advanced strain engineering and precision-oriented application. Corteva, Inc. advances its Utrisha N nitrogen-fixing platform alongside biologicals designed for seed-treatment-first crop solutions. Pivot Bio, Inc. has moved gene-edited nitrogen-fixing microbial technologies into commercial launches for cereals and cotton, following large-scale farm trials that emphasized improved returns and operational efficiency. Groundwork BioAg Ltd. focuses on mycorrhizal inoculants for crop nutrition, Verdesian Life Sciences LLC on nutrient-use-efficiency microbial inoculants and biostimulants, and XiteBio Technologies Inc. on microbial inoculant technologies tied to precision agriculture. Together, these companies illustrate a shift from broad biological categories toward more targeted claims and functional reliability.
Regional and application specialists are also shaping the market. Bioceres Crop Solutions Corp. offers crop solutions that include microbial inoculants for sustainable agriculture, with a footprint that ties biologicals to broader field-crop needs. Valent BioSciences LLC and Koppert Biological Systems B.V. concentrate on biologically oriented pest and crop management, while Koppert’s microbial biologicals fit within integrated pest and crop management programs. This mix of global scale, functional specialization, and regional depth is producing a competitive environment where differentiation is increasingly tied to formulation, compatibility, agronomic support, and claims substantiation.
The market is not consolidating into a single model. Instead, it is evolving in two directions at once. One direction favors integration: larger crop-science organizations embedding biologicals into seed and protection systems to increase attachment rates and cross-selling. The other favors specialization: companies that can make stronger, more defensible claims in specific crops, functions, or farming systems. New entrants continue to appear where there is credible strain science, a clear use case, and a route to distribution. The likely outcome is a layered competitive structure in which a few broad platforms coexist with a growing set of crop- and function-specific solutions.
Three Strategic Trends to Watch Over the Next Three to Five Years
The next phase of market development will likely be shaped by three interlocking trends.
First, biological products will move from generic “microbial input” positioning to more defined functional categories with clearer agronomic claims. As formulation stability improves and strain-level performance is better characterized, companies will increasingly sell around specific outcomes such as nutrient-use efficiency, stress buffering, or compatibility with reduced-input systems. For businesses, this implies greater importance in claim validation, trial design, and agronomic messaging. The winners will be those who can match product capability with credible, repeatable field evidence rather than broad category hype.
Second, distribution models will become more specialized. Seed-applied biologicals, in-furrow systems, and soil-applied formulations each demand different handling, timing, and agronomic advice. This will push manufacturers and distributors to build crop-specific commercial architectures rather than relying on uniform product buckets. Partnerships with seed companies, dealers, and extension networks will matter more because adoption is increasingly determined by how well a biological fits into season-long decision-making. Companies that invest in compatibility testing, application guidance, and localized support will have an advantage in converting trials into repeat purchases.
Third, sustainability-linked programs and regulatory definitions will continue to influence product design and market access. Funding tied to climate-smart commodities, regenerative practices, and organic systems is expanding the incentive to adopt microbiome-based tools, while regulatory frameworks are sharpening the boundary between approved biological categories and broader biostimulant or soil amendment claims. This creates both opportunity and constraint. Firms that design products with regulatory clarity, organic compatibility, and sustainability reporting in mind can unlock access to higher-growth segments. At the same time, companies should expect that market access may vary by region and that product claims will face greater scrutiny as biologicals move from niche to mainstream.
Risks and Uncertainties That Could Reshape the Outlook
The growth path is promising but not guaranteed. Biological performance variability remains the central risk. If field-level inconsistency persists across a meaningful share of products, adoption could plateau at a level below the premium pricing needed to sustain aggressive investment. Price sensitivity is another factor. In periods of compressed farm margins, biologicals that are viewed as additive costs without clear economic payoff may lose ground to lower-cost alternatives.
Regulatory divergence could also create uneven market conditions. Product definitions that favor a narrow set of organisms in one region may limit portfolio flexibility, while other regions may move more quickly toward broader biological-use frameworks. This can privilege companies with adaptable formulation strategies and multi-claim capability while challenging those dependent on a single regulatory interpretation.
Finally, scaling biologicals requires more than scientific promise. Manufacturing reliability, cold-chain or stabilization requirements, carrier availability, and quality control can impose cost structures that erode margins if not managed carefully. Companies that underestimate the operational complexity of commercial-scale biological production may find that early market enthusiasm does not translate into sustained profitability.
Worldwide Biological Silage Inoculants Market
Actionable Implications for Decision-Makers
For manufacturers and product developers, the strategic priority is to strengthen the link between formulation science and commercial reliability. Investments that improve shelf stability, consistency across lots, and compatibility with existing application systems will likely generate more commercial leverage than product breadth alone. Crop-specific claim development, supported by rigorous field validation, can also help differentiate in a category where credibility is a key purchase driver. Where possible, designing products with regulatory clarity and sustainability-program alignment in mind can open access to higher-value segments without relying on generic biological positioning.
For investors, the attractive opportunities are shifting from category-level growth narratives to company-level execution quality. The more durable bets will likely be on firms that can demonstrate repeatable performance, scalable manufacturing, and defensible distribution relationships. Portfolio strategies that distinguish between broad biological platforms and highly targeted functional solutions may outperform undifferentiated exposure to the category. Monitoring commercialization milestones, trial-to-adoption conversion, and regulatory positioning can provide earlier signals than headline revenue alone.
For procurement teams and agribusiness purchasers, the focus should be on total agronomic and economic fit rather than isolated product features. Evaluating inoculants through the lens of application compatibility, season-long performance, dealer support, and compatibility with sustainability or certification requirements will produce better outcomes than short-listing based on label claims alone. Pilots tied to measurable operational metrics, with clear criteria for scale-up, can reduce adoption risk while building internal evidence for repeat purchasing and program design.
The agricultural inoculants market is entering a phase where strategy is less about recognizing momentum and more about aligning product design, commercial execution, and regulatory positioning with how biologicals are actually used in the field. The companies and organizations that make those choices deliberately are best positioned to convert a growing market into durable competitive advantage. For readers seeking a more granular view of segment dynamics, regional demand patterns, competitive benchmarks, and scenario-based sizing across the forecast period, the full PW Consulting study provides the detailed breakdowns and customized frameworks needed to support investment, product, and procurement decisions at a more granular level.
For detailed analysis of this topic, please visit the official page: Agricultural Inoculants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


