



BMC Market: Why 4.9% CAGR Through 2032 Changes Everything

Navigating the Bulk Molding Compounds Market: Strategic Shifts and Commercial Opportunities Through 2032
The Bulk Molding Compounds (BMC) market has moved past a period of steady expansion and entered a phase defined by structural reconfiguration, margin pressure, and accelerating material innovation. From 2020 through 2025, the sector recorded consistent revenue growth, culminating in a base-year valuation of approximately $2,622 million in 2025. Forward projections indicate that the market will reach roughly $3,652 million by 2032, supported by a compound annual growth rate of 4.9 percent. This trajectory reflects more than incremental demand; it signals a maturing ecosystem where traditional material advantages are being tested by cost volatility, regulatory shifts, and substitution threats from advanced thermoplastics and engineered thermosets. Decision-makers across manufacturing, procurement, and capital allocation must understand how these dynamics are reshaping competitive positioning and where durable value creation lies.
Market Structure and Core Challenges
A Mature Ecosystem with High Double-Digit Margins Under Pressure
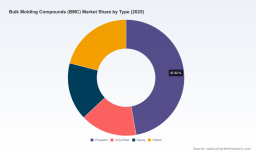
The BMC market remains moderately concentrated, with the top three players capturing roughly 40 percent of global revenue and the top five extending that share to approximately 45 percent. This concentration suggests that scale, formulation expertise, and specialized compounding capabilities continue to matter, but it also indicates that there is meaningful room for specialized suppliers, regional players, and application-focused innovators. The revenue base is split across several material families, with polyester-based compounds representing the largest share, followed by epoxy and vinyl ester formulations, while a diverse group of specialty and blended systems occupies a notable portion of the portfolio. Application-wise, electrical and electronics end-use segments and automotive and transportation applications account for the largest demand pools, with building and construction and other industrial applications forming secondary but stable demand layers. Rather than treating these splits as static categories, it is more useful to view them as competing demand centers where formulation performance, cost, and regulatory compliance determine which material system wins in a given application.
Three Defining Challenges at the Current Inflection Point
First, raw material volatility continues to challenge production economics. Unsaturated polyesters, glass fibers, mineral fillers, and various additives are highly sensitive to crude oil movements, petrochemical supply interruptions, and regional energy pricing. When feedstock costs swing sharply, compounding margins compress quickly unless suppliers have secured long-term agreements, adjusted formulations dynamically, or passed through costs without disrupting volume. This environment rewards manufacturers that can protect cost predictability through formulation flexibility and supply diversification.
Second, environmental and regulatory pressure is reshaping formulation requirements, especially in transportation and electronics. Stricter emission targets, recyclability expectations, and chemical management frameworks are pushing developers toward lower-weight compounds, improved flame performance without brominated or otherwise restricted chemistries, and more recyclable or lower-impact resin systems. Compliance is no longer a peripheral consideration; it is becoming an integral part of qualification cycles and customer specifications, particularly where vehicle lightweighting, energy efficiency, and sustainability reporting intersect.
Sheet Molding Compound (SMC) Market
Third, substitution risk from advanced thermoplastics and hybrid composite strategies is intensifying in certain application areas. Where processing speed, design flexibility, or recyclability is prioritized, engineers increasingly evaluate alternatives to conventional BMC. This does not diminish the role of BMC overall, but it sharpens the requirement for differentiation. Suppliers that only compete on price or generic performance are more exposed, while those that can demonstrate superior electrical insulation, chemical resistance, flame performance, or cost-to-function value in a specific use case retain stronger positioning.
Worldwide Thermoset Molding Compounds Market
Key Drivers Reshaping Demand and Competitive Dynamics
Technical Innovation and Formulation Breakthroughs
The market is being shaped as much by incremental formulation advances as by headline product launches. Improvements in flexural and tensile performance, better dimensional stability, enhanced surface finish, and more consistent processing behavior are expanding the range of parts that can be produced efficiently through compression and transfer molding. At the same time, development efforts are increasingly oriented toward multifunctional compounds that combine flame resistance, electrical insulation, and mechanical durability in a single system, reducing the need for secondary treatments or coatings. Recent operational moves illustrate this shift. IDI Composites International opened a new 120,000-square-foot global headquarters and manufacturing facility in Noblesville, Indiana, dedicated to BMC production and research and development. This type of investment signals a focus on integrated scale, faster formulation iteration, and application-specific development rather than commoditized production alone.
PW Consulting
Policy and Regulatory Direction
Regulatory frameworks are accelerating reformulation priorities across multiple regions. The EU Circular Economy Action Plan and REACH-related chemical management expectations are encouraging more eco-friendly and recyclable compound development, while tighter emission and efficiency standards in the automotive sector are driving demand for lighter, higher-performance molded components. These policies influence not only what can be sold, but how quickly new formulations can be qualified, how suppliers document compliance, and which chemistries remain viable in long-term contracts. In practice, regulatory momentum is converting sustainability from a marketing attribute into a design constraint that shapes resin selection, filler choices, and end-of-life considerations.
Demand-Side Shifts in Electrical, Automotive, and Industrial Applications
On the demand side, electrification and vehicle efficiency goals are expanding the need for lightweight, thermally stable, and electrically insulating components in transportation. In electrical and electronics applications, the push for compact enclosures, reliable insulation, and improved flame performance supports continued use of BMC where dimensional stability and cost-effectiveness matter. Meanwhile, industrial and building applications continue to rely on BMC for corrosion-resistant fittings, utility components, and custom molded parts that benefit from replicable geometry at moderate production volumes. A common thread across these end-use segments is the growing preference for suppliers that can reduce qualification time, offer consistent lot-to-lot performance, and support application engineering rather than simply ship resin systems.
Supply Chain and Cost Structure Realignment
Cost structures remain tied to petroleum-derived feedstocks and fiber supply dynamics, making margin management a strategic discipline rather than an operational afterthought. Volatility in unsaturated polyester resin pricing, fillers, and fibers affects cost predictability across the value chain and encourages suppliers to rethink sourcing models, blend strategies, and inventory planning. Companies that adapt by expanding approved raw material options, adjusting filler ratios without sacrificing performance, or regionalizing supply to reduce freight and tariff exposure are better positioned to maintain stable pricing and service levels. This realignment also favors suppliers that can provide transparent cost narratives and flexible commercial terms, especially in applications where total installed cost and lifecycle reliability matter more than unit price alone.
Competitive Landscape and Leading Strategies
How Leading Players Differentiate
The competitive field includes a mix of application-focused compounders, regionally rooted manufacturers, and larger resin and materials firms that leverage broader chemistry portfolios. IDI Composites International positions itself around dedicated BMC production for automotive, electrical, and industrial applications, with an emphasis on integrated manufacturing and development capacity. Mar-Bal, Inc. concentrates on thermoset compounding for electrical and industrial molded parts, where consistent electrical performance and reliable molding behavior are central to customer selection. Menzolit operates as a global producer spanning BMC and sheet molding compounds, serving automotive, electrical, and transport sectors with a focus on formulation breadth and application engineering. Resonac, formerly known as Showa Denko, brings advanced material engineering capabilities to high-performance BMC applications, supporting customers that require specialized thermal, electrical, or mechanical characteristics. Polynt SpA contributes a general-purpose compound portfolio alongside related thermoset systems, offering a balance of availability, consistency, and formulation range. Hexion Inc. leverages its thermoset resin expertise to supply BMC for industrial and automotive uses, benefiting from resin chemistry depth and downstream application support.
Strategic Positioning and Differentiation Levers
Across these players, the most effective differentiation tends to emerge from three overlapping capabilities. The first is formulation agility: the ability to tailor resin chemistry, fiber architecture, and additive packages to the exact requirements of an application while maintaining consistency. The second is application engineering and qualification support: helping customers reduce time to production through material selection guidance, processing recommendations, and predictable performance data. The third is supply reliability: dependable delivery, inventory availability, and cost transparency that reduce total program risk for OEMs and tier suppliers. Companies that combine these capabilities tend to hold stronger positions even in a market where concentration is moderate and switching costs can appear lower than they actually are once qualification and performance history are factored in.
Structural Trends in Market Configuration
The market structure appears to be moving through a phase of selective consolidation alongside continued niche specialization. Larger investments in integrated facilities, such as dedicated headquarters and manufacturing centers, point toward economies of scale and more centralized development. At the same time, regional suppliers and application specialists remain relevant where local service, rapid response, and custom formulation are valued. New entry is possible but challenging because qualification cycles, performance consistency, and customer confidence create real barriers, even though formulation IP, niche application access, and regional cost advantages can still support targeted entry. The likely outcome is not a simple shakeout but a layered market in which broad-scale suppliers compete on consistency and cost, while specialists compete on performance, application fit, and engineering support.
Forward Outlook: Trends and Commercial Opportunities
Trend 1: Formulation-as-a-Differentiator Becomes Central
Over the next three to five years, BMC suppliers are likely to compete increasingly on tailored performance packages rather than generic compound categories. Expect more emphasis on lightweighting, flame performance within evolving regulatory expectations, improved electrical reliability, and processing stability that lowers scrap and cycle-time variability. The commercial opportunity lies in embedding formulation support earlier in the design process. Suppliers that can influence material selection during component development, rather than responding only after specifications are fixed, will capture stronger value and longer customer relationships.
Trend 2: Regionalization and Supply Resilience Gain Strategic Weight
Sourcing and production footprints are likely to become more deliberately regionalized or multi-nodal to reduce exposure to feedstock shocks, logistics disruption, and tariff uncertainty. For customers, this creates an opportunity to diversify approved suppliers and negotiate contracts that balance cost, availability, and technical support. For manufacturers, the opportunity is to build capability that can serve regional demand with consistent quality, faster lead times, and clearer cost structures. The companies that can demonstrate resilience without sacrificing performance will be better positioned to retain volume during periods of market volatility.
Trend 3: Sustainability Requirements Move Into Spec-Driven Selection
Sustainability expectations are shifting from broad brand messaging toward specification-level criteria, especially in automotive and electrical applications. This creates a need for documented material attributes, clearer pathways for recyclability or end-of-life handling, and chemistry choices aligned with evolving regulatory expectations. The commercial opportunity is for suppliers that can translate sustainability goals into measurable performance and compliance data, enabling customers to justify material decisions in both engineering and procurement reviews. The principal risk is that overly generic sustainability claims will lose credibility if they are not supported by formulation details, testing evidence, and supply-chain traceability.
Actionable Implications for Decision-Makers
For Manufacturers and Compounders
Prioritize formulation flexibility and application engineering as core competitive assets. Build the ability to adjust resin, fiber, and additive combinations without compromising certification or performance consistency, and invest in capability that shortens qualification cycles for customers. Where possible, regionalize key supply and production capacity to improve lead-time reliability and reduce exposure to feedstock and logistics volatility. Differentiate through measurable processing benefits, such as lower scrap rates, predictable cycle times, and stable lot performance, rather than competing primarily on headline price.
For Investors and Capital Allocators
Evaluate exposure based on formulation depth, application mix, and supply-chain resilience rather than scale alone. Favor business models that combine margin protection through diversified raw material sourcing with demand visibility from long-cycle automotive, electrical, or industrial programs. Watch for signs that competitors are moving up the value chain through R&D investment and integrated facilities, because these moves can reshape regional pricing power and share dynamics. Be attentive to substitution risk in applications where thermoplastics or hybrid strategies are gaining traction, and assess whether target companies have credible responses in the form of lighter weight, higher performance, or cost-to-function advantages.
For Procurement and Engineering Leaders
Treat supplier selection as a total-cost and risk decision rather than a unit-price comparison. Evaluate compound performance in the context of processing reliability, qualification speed, flammability or electrical requirements, and long-term availability. Diversify approved suppliers where feasible to reduce exposure to single-source disruption, and seek partners that can provide transparent cost narratives and formulation support during component design. Where regulatory and sustainability expectations are increasing, request documented evidence of material attributes, compliance alignment, and any relevant end-of-life considerations so that sourcing decisions remain defensible across engineering, procurement, and compliance reviews.
Conclusion
The BMC market is entering a period in which growth is no longer enough on its own to secure advantage. The combination of feedstock volatility, evolving regulatory expectations, and increasing demand for application-specific performance is rewarding suppliers that can integrate formulation expertise, supply resilience, and engineering support into a coherent offering. For companies and investors operating in this space, the strategic imperative is to move beyond generic positioning and toward differentiated value that can withstand cost pressure and substitution risk. More granular segmentation detail, regional demand patterns, and customized scenario analysis can help decision-makers translate these trends into specific sourcing, investment, and development choices. For teams that require deeper end-use breakdowns, formulation-level comparisons, or a tailored assessment of regional opportunity, a detailed commercial study can provide the additional structure needed to turn these market signals into precise action.
For detailed analysis of this topic, please visit the official page: Bulk Molding Compounds (BMC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


