



Nursing Bras Market: How 8.1% CAGR and Wireless Surge Redefine Growth Through 2032

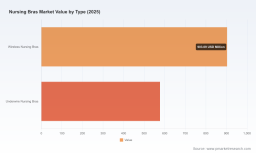
Navigating the Nursing Bras Market: Strategic Trends and Commercial Opportunities Through 2032
The nursing bras market has entered a phase of structurally accelerated growth, reshaping how apparel manufacturers, healthcare-adjacent brands, and retail distributors approach maternal wellness categories. Valued at approximately $1.1 billion in 2020, the market expanded to roughly $1.48 billion by 2025, reflecting a compound annual growth rate of 8.1 percent through the 2026–2032 forecast window. By 2032, total revenue is projected to approach $2.5 billion. This trajectory is not merely a function of population growth; it signals a broader cultural and functional shift in how maternal wear is designed, distributed, and valued. For executives and investors, the category represents a high-velocity niche where comfort, material science, and inclusive sizing converge with rising healthcare awareness and evolving postpartum lifestyles.
Bra Cups Market
1. Market Reality and Core Challenges
A Category Outgrowing Its Traditional Ambitions
The market’s expansion from 2020 through 2025 was steady rather than explosive, but the underlying composition shifted meaningfully. Revenue growth accelerated as wireless designs gained share over traditional underwire constructions, and as lactation-specific demand outpaced pregnancy-only applications. The base-year footprint in 2025 sits at roughly $1.48 billion, with the forecast arc pointing toward consistent mid-to-high single-digit annual gains. Such growth rates place nursing bras among the faster-appreciating segments within the broader intimate apparel and maternal care landscape.
Despite the positive macro picture, the industry faces structural pressure points that will define competitive positioning over the next several years. First, standardization remains elusive. Size inclusivity, fabric elasticity, and closure mechanisms vary widely across price tiers, creating friction for consumers who seek predictable comfort across pregnancy, nursing, and pumping phases. Second, supply chain complexity is rising. Producing nursing bras that accommodate inclusive sizing demands specialized labor for custom fabric cutting and sewing across global networks. This constraint elevates lead times and compresses margins for brands that cannot optimize cut-and-sew workflows or secure reliable material suppliers. Third, regulatory and compliance expectations are tightening. Material safety certifications such as Oeko-TEX® directly influence supplier qualification and product clearance, forcing brands to embed compliance into procurement rather than treating it as a post-production checkbox. These challenges are not insurmountable, but they reward operators who invest early in design standardization, supplier qualification, and demand forecasting.
2. Key Drivers Shaping the Next Phase
Material Innovation and Hands-Free Functionality
The most visible driver is the shift toward wireless, seamless, and hands-free configurations. Consumers increasingly favor wireless nursing bras for convenience, and hands-free pumping styles have seen higher adoption in the United States. This preference is not cosmetic; it reflects a functional demand for garments that support milk expression while minimizing disruption to work, travel, and daily routines. Recent product validations underscore the commercial pull of this trend. In June 2025, the Sublime® Hands-Free Pumping & Nursing Bra was recognized as Nursing Bras and Tanks Product of the Year at the Baby Innovation Awards, signaling that hands-free engineering has moved from niche experimentation to award-recognized category leadership. A year earlier, in July 2024, a maternity and nursing bra launched with ultra-soft fabric designed for versatile pregnancy-to-nursing use, illustrating how brands are compressing multiple life stages into single SKU architectures. These developments show that innovation is no longer confined to closure mechanisms; it now spans fabric hand-feel, stretch recovery, and integrated pumping support.
For businesses, the implication is clear: product roadmaps that treat nursing bras as basic apparel will lose share to designs that combine lactation functionality with everyday wearability. Fabric selection, seam placement, and strap engineering are becoming core differentiators rather than secondary specifications.
Policy, Reimbursement, and Healthcare Alignment
The policy environment is adding a subtle but meaningful layer of demand support. In the United States, breastfeeding support programs may provide partial reimbursement for specialized nursing bras under certain health insurance plans. While reimbursement is not universal and often depends on plan design and documentation, it introduces a pathway that lowers effective out-of-pocket cost for targeted consumers. This dynamic encourages brands to think beyond pure retail velocity and consider how product positioning, documentation, and clinical-adjacent messaging can align with employer and insurer wellness programs.
At the same time, material regulation continues to shape sourcing decisions. Oeko-TEX® safety standards for materials in nursing bras directly influence supplier certifications and product compliance, making textile sourcing a strategic gate rather than a commodity exercise. Brands that pre-qualify compliant fabric mills and maintain transparent traceability will face fewer launch delays and fewer compliance-related setbacks.
Demand-Side Shifts: Inclusive Sizing and Lifestyle Integration
Demand is being reshaped by a consumer base that expects garments to accommodate body changes without forcing trade-offs between support and comfort. Maternity and postpartum wear is no longer treated as a temporary category; it is increasingly integrated into broader lifestyle wardrobes. Women seek bras that transition from pregnancy through lactation, that suit busty fits, and that remain aesthetically neutral enough for everyday use. This expectation is pushing manufacturers to expand size ranges, reinforce support slings, and reduce visible hardware that disrupts the garment’s silhouette.
The price spectrum also reveals how demand is segmenting. Entry-level nursing bras from mass retailers range from roughly $16.99 to $20, while premium offerings from specialist brands exceed $50. This gap is not merely a pricing artifact; it reflects divergent value propositions. Mass-tier products compete on accessibility and basic functionality, whereas premium players compete on fabric softness, seamless edges, inclusive fit, and specialized pumping support. Brands that can articulate and deliver a clear point of difference within the premium tier are capturing willingness to pay that mass offerings cannot easily replicate.
Supply Chain and Cost Structure Pressures
On the supply side, labor and material orchestration are becoming critical cost levers. Nursing bra production requires specialized labor for custom fabric cutting and sewing to meet inclusive sizing demands across global supply chains. This specialization constrains the ability to scale through generic cut-and-sew partners, and it raises the importance of supplier relationships, pattern engineering, and yield optimization. Brands that invest in modular pattern families, fabric standardization where possible, and disciplined inventory planning will be better positioned to manage cost volatility without sacrificing fit or compliance. Conversely, operators that rely on fragmented sourcing and ad hoc sizing expansion will face margin erosion and inconsistent quality.
3. Competitive Landscape and Leading Strategies
Strategic Positioning Across the Value Chain
The competitive set spans specialist maternal brands, broader intimate apparel players, and equipment-centric companies that have extended into wearable support. Several themes emerge from recent activity. Specialist brands are leaning into wireless, seamless, and hands-free designs with inclusive sizing that spans pregnancy and postpartum. One Oceanside-based brand has concentrated on wireless, seamless, hands-free nursing and pumping bras with easy nursing access, stretchy fabrics, and inclusive sizing from pregnancy through postpartum. Its July 2024 launch of a maternity and nursing bra with ultra-soft fabric for versatile pregnancy-to-nursing use, followed by a September 2024 bundle collaboration with a lactation equipment partner for a nursing and wearable pumping bra bundle, illustrates a strategy that blends product versatility with ecosystem partnership.
In Australia, a maternity-focused brand emphasizes full-coverage, seamless nursing bras and maternity lingerie with supportive slings and style for busty and everyday wear. This positioning targets consumers who want coverage and support without sacrificing appearance, a segment that often remains under-served by minimalist designs. In Canada, another brand offers body silk seamless nursing bras, everyday wireless styles, and maternity apparel with emphasis on comfort and size-inclusive fit, reinforcing the broader industry tilt toward seamless construction and fit breadth. In the United States, a New Jersey-based designer creates combo maternity, nursing, and pumping bras with modern, stylish closures and premium fabrics for active and postpartum moms, showing that closure aesthetics and fabric premiumization can coexist with functional versatility.
A Denver-based brand provides ultra-soft, hands-free pumping and nursing bras with innovative designs and wide size ranges for comfort during feeding, a configuration that directly addresses the hands-free adoption trend noted earlier. European players continue to anchor on support and seam engineering. A German brand offers specialized nursing bras in seamless and underwire styles with seamless edges and enhanced support for breastfeeding, while a Swiss company provides maternity and nursing bras with quick-dry technology, breathable zones, and integrated pumping support. These offerings demonstrate that support, moisture management, and pumping integration remain viable differentiators even as wireless designs gain momentum.
How Leaders Differentiate
Across these players, differentiation clusters around a few repeatable advantages. The first is functional integration: hands-free pumping compatibility, quick-dry or breathable zones, and closures that balance accessibility with security. The second is fit architecture: inclusive sizing, supportive slings, and stretch-managed fabrics that accommodate fluctuating bust size without sacrificing shape. The third is aesthetic assimilation: seamless edges, neutral styling, and fabrics that feel more like everyday basics than specialized medical-adjacent garments. Brands that combine two or more of these advantages tend to command stronger positioning and more resilient pricing.
Partnerships are also becoming strategic. The September 2024 collaboration between a lactation equipment maker and a specialist bra brand produced a nursing and wearable pumping bra bundle designed for enhanced feeding convenience. This type of alliance links garment functionality with expression equipment, creating a combined solution that can improve customer retention and cross-category visibility. As the category matures, similar partnerships with employers, insurance-adjacent programs, and retail channels may become more common.
Market Structure and Evolutionary Pressures
Market concentration indicates a moderately consolidated landscape, with the top three firms holding approximately 52 percent of revenue and the top five closer to 78 percent. This structure suggests that scale players have meaningful influence over channel access, sourcing leverage, and brand visibility. At the same time, the presence of strong specialist brands and regional players indicates room for targeted differentiation, especially where fit, fabric, and functionality are executed with precision. The likely trajectory is not a race to pure consolidation but a bifurcated market: scaled brands compete on breadth, distribution, and bundled solutions, while specialists compete on design depth, material comfort, and segment-specific fit. New entrants will find the most traction by solving a specific consumer pain point—hands-free usability, size-inclusive support, or premium fabric hand-feel—rather than by entering as generic alternatives.
4. Future Trajectory: Trends and Commercial Opportunities
Wireless and Hands-Free as Baseline Expectations
Over the next three to five years, wireless and hands-free designs are likely to transition from growth segments to baseline expectations in many markets. Adoption is already strongest where convenience and dual-use functionality matter most, and as more employers normalize flexible lactation routines and more consumers prioritize wardrobe continuity, the demand for bras that support nursing and pumping without compromising daily wear will keep rising. The commercial opportunity lies in product architectures that reduce SKU complexity while expanding use-case coverage. Brands that can deliver a single platform with adjustable support, reversible styling cues, and compatible pumping integration will capture efficiency gains and improve consumer retention across life stages.
Regional Momentum and Channel Reconfiguration
Geographically, the market is broad but uneven. North America anchors a large share of revenue, reflecting strong retail footprint, established maternal care awareness, and reimbursement-adjacent pathways. Europe contributes a substantial base with a focus on support, seam quality, and compliance-driven material sourcing. Asia Pacific represents a meaningful and growing footprint, where expanding maternal care awareness, e-commerce penetration, and urbanization are broadening access to specialized nursing wear. Latin America and the Middle East and Africa together form smaller but developing demand pools, often shaped by retail distribution, cultural acceptance, and channel availability.
For businesses, the strategic implication is that growth will not come from a single region executing identically. North America may reward hands-free innovation and bundle partnerships; Europe may reward compliance-forward sourcing and support engineering; Asia Pacific may reward size-inclusive assortments and digitally native distribution. Companies that align product, channel, and sourcing to regional preferences will extract more value than those that treat the market as uniform.
Premiumization, Fit, and Compliance as Margin Anchors
A second medium-term trend is premiumization anchored in fit and compliance rather than branding alone. As entry-level price points remain anchored in the teens and premium offerings sit above $50, the margin opportunity for specialist brands depends on proving functional and tactile superiority. Consumers are willing to pay for garments that genuinely reduce discomfort, accommodate sizing changes, and integrate lactation needs without feeling specialized in a clinical sense. Simultaneously, compliance-driven material expectations will increasingly act as a margin protector for prepared brands, since certified sourcing reduces the risk of reformulation, delayed launches, and reputational friction. Companies that treat compliance and fit as design inputs—not downstream checks—will be better positioned to sustain premium pricing and lower returns.
The principal uncertainty is consumer volatility across the pregnancy-to-postpartum window. Purchase timing is clustered, body changes are rapid, and satisfaction is highly sensitive to fit and function. Overproduction in the wrong sizes or styles can quickly erode inventory health, while underinvestment in inclusive sizing can limit addressable demand. Brands that pair disciplined demand forecasting with modular pattern families and flexible fabric sourcing will navigate this volatility more effectively.
5. Strategic Guidance for Decision-Makers
For Manufacturers and Brand Operators
First, compress the product architecture. Where possible, design modular platforms that span pregnancy, nursing, and pumping with adjustable support elements, so that development investment yields multiple sellable configurations without fragmenting inventory. Second, treat fabric and closure engineering as core IP. Hands-free compatibility, seamless edges, stretch recovery, and moisture management are no longer nice-to-haves; they are the attributes that justify premium pricing and reduce fit-related returns. Third, embed compliance into sourcing. Pre-qualify material suppliers for relevant safety certifications and maintain traceability that can support faster approvals and fewer redevelopment cycles. Finally, standardize inclusive sizing through disciplined pattern engineering rather than ad hoc expansions, because specialized labor for custom cutting and sewing is a scarce and costly resource that rewards repeatable, yield-optimized workflows.
For Investors
Look for operators that demonstrate functional differentiation with commercial proof, not just design ambition. Award recognition for hands-free pumping and nursing bras, successful product transitions from pregnancy into lactation, and bundled partnerships with lactation equipment providers are indicators that a product strategy is resonating with real usage patterns. Favor businesses that show control over compliant material sourcing, disciplined SKU breadth, and pricing power above the entry tier without relying solely on brand nostalgia. Evaluate channel mix carefully: digitally native reach, selective retail partnerships, and alignment with employer or insurance-supported wellness programs can compound growth more efficiently than broad but shallow distribution.
For Procurement and Channel Leaders
Prioritize assortments that balance accessibility with functional depth. Entry-level price points remain important for volume, but premium-tier SKUs with verifiable comfort, inclusive fit, and pumping compatibility are where basket value and repeat purchase potential increase. For specialty retail and e-commerce, curated bundles that pair nursing bras with compatible pumping accessories can improve conversion and reduce post-purchase support friction. For wholesale and distribution, align regional assortments to local preferences: emphasize hands-free and versatile designs where convenience dominates, and prioritize support engineering and compliance-forward materials where those attributes carry greater weight.
PW Consulting Information & Electronics Research Center
The nursing bras market is moving from a niche maternal category to a functionally sophisticated segment with wider lifestyle relevance. Growth is sustained, but the value is shifting toward operators who can integrate comfort, compliance, inclusive fit, and lactation functionality into coherent product platforms. Detailed segment-level sizing, regional channel dynamics, and company-specific benchmarking can sharpen execution further, and fuller research is available for teams that need granular data and tailored recommendations.
Worldwide Breastfeeding Accessories Market
For detailed analysis of this topic, please visit the official page: Nursing Bras Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


