



Residential Elevators Market: Why 5.45% CAGR and Region Shifts Redefine Growth

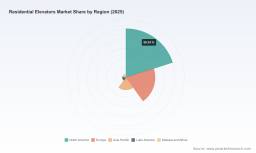
The Quiet Infrastructure Boom: Strategic Dynamics in the Residential Elevators Market
What was once considered a luxury reserved for ultra-high-net-worth estates has steadily evolved into a mainstream accessibility and lifestyle feature across global housing markets. The residential elevators sector is expanding through a combination of demographic shifts, accessibility awareness, and incremental technological maturation. Valued at approximately 224.17 million USD in 2025, the market has followed a short-term plateauing pattern before resuming steady growth, with a projected compound annual growth rate of 5.45 percent spanning the 2026 through 2032 forecast window. Historical trajectories from 2020 to 2025 reveal an industry that absorbed pandemic-era construction volatility, recalibrated to shifting housing demand, and now operates in a period where growth is increasingly tied to product differentiation and installation agility rather than raw volume expansion alone.
Market concentration remains moderately fragmented, with the top three operators capturing roughly 38.7 percent of total revenue and the top five accounting for approximately 52.1 percent. This distribution signals a sector where incumbents hold meaningful share through regional service networks and brand recognition, yet still leave substantial room for specialized entrants, retrofit-focused innovators, and regional manufacturers that can address localized housing stock and code variations. The structural balance between established players and agile newcomers defines how value is captured across product tiers and end-user segments.
Identifying the Structural Inflection Points
Three overlapping challenges are reshaping how manufacturers, dealers, and end-users approach residential vertical mobility. The first revolves around material cost volatility and tariff exposure. Steel and component pricing pressures have altered margin structures across the value chain, pushing manufacturers to reconsider sourcing strategies, standardize sub-assemblies, and adjust pricing models without sacrificing installation timelines. The second challenge is regulatory alignment. Residential elevator installations increasingly sit at the intersection of safety certification, regional building codes, and insurance expectations. As standards evolve and jurisdictions tighten inspection and maintenance requirements, companies that fail to synchronize design, documentation, and service readiness face longer approval cycles and elevated compliance risk. The third challenge is installation friction in existing housing stock. Many target homes were not designed with vertical circulation in mind, making shaft construction, pit requirements, and spatial reconfiguration a decisive factor in purchase decisions. The market is therefore rewarding solutions that reduce structural intrusion, shorten project timelines, and simplify dealer sequencing.
Worldwide Bucket Elevators Market
These pressures are not purely defensive. They function as filters that separate commoditized pricing competition from value-based differentiation. Players that can balance material resilience, code-ready engineering, and low-disruption installation are increasingly positioned to command premium share and stronger service margins.
Key Drivers Reshaping Demand and Competitive Positioning
Technology Innovation and Product Architecture
Product design is shifting from purely mechanical reliability toward space-efficient, installation-light architectures. Pitless and shaft-free configurations, modular assembly approaches, and low-footprint vertical platforms are gaining traction in retrofit scenarios where homeowners and builders prioritize minimal structural alteration. Alongside hardware evolution, control interfaces, smoother ride calibration, and quieter operation are becoming baseline expectations rather than optional upgrades. These features influence not only purchase decisions but also long-term service contracts and repeat installations across multi-property owners and accessibility-focused housing programs.
Recent product and market activity illustrates how manufacturers are translating engineering improvements into commercial positioning. In early 2026, Garaventa Lift showcased its LUMA home elevator at a major industry trade event and was recognized among the event’s must-see products, reinforcing the commercial relevance of contemporary design alongside functional performance. Savaria expanded North American production capabilities through a new assembly and shipping facility in South Carolina, signaling a deliberate move to reduce lead-time risk and strengthen regional fulfillment. Residential Elevators updated its 2025 catalog to refresh product offerings and configuration drawings, a seemingly routine action that actually reflects how manufacturers use catalog clarity and specification readiness to accelerate dealer quoting and homeowner decision-making.
Regulatory and Standards Environment
Safety standards and installation mandates are becoming more explicit, with significant implications for engineering documentation, service protocols, and regional market access. In the United States, ASME A17.1 remains mandatory for residential elevator installation, alteration, service, repair, testing, and maintenance, creating a unified baseline for compliance and inspection readiness. In Canada, CSA B355 governs residential elevator safety standards and influences design, testing, and ongoing certification requirements. Meanwhile, ISO 8100-1/2 standards are set to launch in March 2026, replacing EN 81-20/50 with a 36-month transition period. This transition introduces both harmonization opportunities and compliance timing risk, especially for companies operating across multiple regions or exporting equipment that must satisfy evolving certification pathways.
From a commercial standpoint, regulatory clarity can be a competitive advantage when paired with proactive documentation and service infrastructure. Manufacturers that invest early in compliance mapping, installer training, and maintenance tracking tend to shorten project approval cycles and reduce post-installation liability exposure. Conversely, delays in aligning product specifications with updated standards can translate into stranded inventory, rework, or regional market hesitation.
Demand-Side Shifts in Housing and Accessibility
Demand is increasingly shaped by two parallel narratives: aging-in-place accessibility and the premiumization of multi-level residential design. For single-family homes, vertical accessibility is no longer viewed exclusively through a medical or mobility-assist lens; it is also framed around universal design, long-term home value, and lifestyle flexibility. Multi-family buildings and other applications represent a smaller but strategically important share of demand, often driven by affordability housing retrofits, accessibility compliance, and property value enhancement in denser residential settings. Across these segments, the decision-making unit is expanding beyond the homeowner to include remodelers, occupational therapists, accessibility consultants, and property managers, all of whom influence specification and procurement timing.
Elevators Market
This broadening stakeholder map is changing how products are sold and specified. Installers and dealers that can articulate total project cost, disruption reduction, code alignment, and after-installation service are gaining stronger positioning than those competing primarily on equipment price. The market is rewarding clarity of scope and predictable installation outcomes.
PW Consulting Automotive & Machinery Research Center
Supply Chain and Cost Structure Realignment
Material costs, logistics, and labor availability continue to influence pricing architecture and project feasibility. Steel cost increases, partly driven by tariff exposure and supply chain disruptions, have raised input expenses for residential elevator manufacturing and impacted broader material expenses across the sector. These pressures are prompting a reevaluation of bill-of-materials strategy, inventory buffering, and regional sourcing. For dealers and installers, the cost structure shift also affects project quoting stability, which makes standardized configurations and modular components more attractive than heavily bespoke builds in price-sensitive segments.
The commercial implication is straightforward: resilience in supply planning is increasingly a margin protection strategy. Companies that strengthen supplier diversification, improve demand forecasting, and align product families to common sub-components are better equipped to manage cost variability while preserving competitive pricing and delivery reliability.
Competitive Landscape and Strategic Differentiation
How Leading Players Are Positioning
The competitive field combines established elevator expertise with specialized residential-focused innovators. Savaria manufactures traditional and panoramic residential elevators for North American homes, using its regional manufacturing scale and product breadth to support broad market coverage. Inclinator specializes in fully customizable residential elevator solutions, positioning around design flexibility and tailored residential applications. Garaventa Lift produces custom home elevators, including the Elvoron series and LUMA models, and has reinforced its market visibility through trade recognition and product-focused outreach. Stiltz Lifts offers modular, shaft-free residential elevators designed for compact home installations, an approach that directly addresses the retrofit and space-constraint demand segment. PVE manufactures pitless vacuum-based residential elevators such as the PVE30, PVE37, and PVE52 series, leveraging a distinctive technology narrative to differentiate from conventional mechanical systems. Residential Elevators operates as a full-service provider manufacturing custom residential elevators in the USA, emphasizing end-to-end execution and domestic production. Cambridge Elevating leads in residential elevator design and installation with models such as Elmira and Heritage, combining design credibility with installation capability. AmeriGlide offers hydraulic and drum-mechanism residential elevators for accessibility-focused homes, targeting a demographic and functional use case where reliability and ease of use are central. Nibav Lifts provides air-driven, pitless residential home elevators for small homes and retrofits, aligning with lightweight installation needs. Otis offers Gen2 residential elevator systems for luxury and high-rise homes, bringing broader elevator heritage and premium positioning into the residential segment.
These profiles reveal a market where differentiation is built on a few recurring axes: installation footprint, customization depth, technology narrative, service reach, and regional production capability. No single formula dominates. Instead, firms are choosing where to compete on convenience, where to compete on engineering prestige, and where to compete on total installed cost and service continuity.
Market Structure Evolution: Consolidation Pressure and Niche Expansion
The moderate concentration levels suggest that consolidation is possible but not inevitable. Larger players with national service networks and multi-product portfolios can capture cross-selling opportunities and standardize installation workflows. At the same time, specialized manufacturers with distinct installation advantages or technology profiles can sustain strong niches by solving specific homeowner pain points, particularly in retrofit scenarios. New entrants and smaller regional firms continue to find openings where installation simplicity, faster delivery, or localized code familiarity create meaningful value. The result is a market that is neither fully consolidated nor highly atomized, but rather stratified by application complexity and installation context.
Over the next several years, this stratification is likely to sharpen. Companies that can deliver consistent installation outcomes, maintain code compliance across regions, and reduce material and labor exposure will be better positioned to expand share. Pure price competition will remain a risk for undifferentiated offerings, especially where material volatility and labor constraints compress margins for all but the most efficient operators.
Forward Outlook: Trends Shaping the Next Three to Five Years
Installation-First Product Strategy as a Growth Lever
Future growth will depend as much on how easily a system can be integrated into existing homes as on the mechanical performance of the elevator itself. Solutions that minimize shaft work, reduce pit requirements, and accelerate commissioning will likely capture disproportionate attention in retrofit-heavy markets. This trend benefits manufacturers that can standardize installation kits, simplify dealer training, and provide predictable project scopes. The commercial opportunity lies in turning installation efficiency into a pricing umbrella: when disruption is lower and timelines are shorter, homeowners and remodelers are more willing to proceed, and dealers can handle higher project throughput with less site risk.
Standards Convergence and Compliance as a Market Filter
As safety and performance standards transition and align across regions, the ability to demonstrate compliance will increasingly influence procurement decisions, especially for multi-region dealers and developers. Companies that proactively map product documentation, service procedures, and maintenance tracking to updated standards will reduce friction in quotation, approval, and ongoing service. This creates a twofold opportunity: tighter compliance posture can shorten sales cycles, and it can also support premium positioning for projects where safety assurance, insurance alignment, and long-term service reliability are decisive. The uncertainty lies in transition timing and regional interpretation, which may create short-term unevenness in demand as dealers and inspectors adapt.
Regional Production and Supply Resilience as Margin Defense
Regional manufacturing expansion and supply chain recalibration are likely to remain strategic priorities as companies seek to contain material cost exposure and improve delivery predictability. Domestic or near-market assembly can reduce logistics complexity and improve responsiveness to local specification requirements. This trend does not automatically guarantee cost leadership, but it can support more stable quoting, faster turnaround, and stronger relationships with regional dealers and installers. The associated risk is capital intensity and execution complexity: facility expansion and sourcing realignment must be matched with demand forecasts and inventory discipline to avoid overcapacity or uneven utilization.
Actionable Implications for Decision Makers
For Manufacturers and Product Leaders
- Prioritize installation-light architectures and modular product families that reduce structural disruption and simplify dealer quoting, especially for retrofit and small-home segments.
- Strengthen standards readiness ahead of regulatory transitions by aligning design documentation, installer training, and service tracking with the evolving certification landscape.
- Diversify sourcing and standardize common sub-components to protect margins against steel and material cost volatility while preserving delivery reliability.
For Investors and Strategic Capital
- Evaluate companies on total installed-solution capability, including service reach, compliance readiness, and regional fulfillment, rather than on equipment specifications alone.
- Watch for acquisition and partnership signals where a strong product profile is paired with weak installation or service infrastructure, as this gap often defines the next value-creation opportunity.
- Monitor regional capacity expansion for evidence of scaled demand durability and margin resilience, not just capacity addition in isolation.
For Procurement, Dealers, and Property Stakeholders
- Compare proposals on total project scope, installation disruption, code alignment, and ongoing service obligations, not solely on equipment price.
- Specify configurations that reduce structural modification requirements where feasible, as this can improve project predictability and homeowner acceptance.
- Include long-term maintenance and inspection readiness in the evaluation criteria, since post-installation compliance and service continuity increasingly shape total cost and risk.
From Market Context to Strategic Clarity
The residential elevators market is moving through a phase where growth is no longer driven by a single macro tailwind but by a combination of product practicality, compliance alignment, and supply resilience. That combination favors organizations that can translate engineering, installation, and regulatory readiness into a coherent commercial offering. For decision makers evaluating product roadmaps, investment targets, or procurement strategy, the most useful next step is to examine how these dynamics interact within specific regions, applications, and competitive positions.
A fuller segmentation view, company-level benchmarking, and scenario-based projections can sharpen those choices by connecting broad market direction to the operational and commercial details that actually determine outcomes. Detailed market maps and custom strategic recommendations are available through the complete PW Consulting residential elevators research report, which expands on the structural trends, competitive positioning, and regional dynamics discussed here.
For detailed analysis of this topic, please visit the official page: Residential Elevators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


