



EAS System Market Beyond 4.66% CAGR: Shifts Redefining Security by 2032

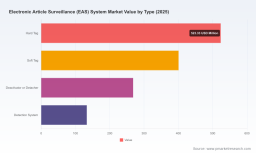
Strategic Trends and Commercial Opportunities in the Electronic Article Surveillance (EAS) System Market
The Electronic Article Surveillance (EAS) System Market has evolved from a simple theft-deterrence mechanism into a foundational component of retail loss prevention and inventory intelligence. Valued at 1,325.0 million USD in 2025, the market has grown steadily from 1,081.5 million USD in 2020, reflecting a compound annual growth rate of 4.66% projected through 2032. This trajectory is not merely a reflection of rising retail sales; it signals a structural shift in how retailers, manufacturers, and supply chain operators approach security, compliance, and operational efficiency. As the market expands toward 1,820.14 million USD by 2032, stakeholders must recognize that EAS is no longer a standalone hardware purchase—it is an integrated technology stack shaped by regulation, labor economics, and data analytics.
The growth pattern reveals a mature but still evolving landscape. Despite consistent revenue expansion, the market faces mounting pressure to justify capital expenditure through measurable operational outcomes. Retail environments are experiencing unprecedented shrinkage, while labor shortages and wage inflation are forcing operators to reconsider legacy security models. In this context, EAS systems are being evaluated not only on detection reliability but on their ability to reduce false alarms, integrate with broader store networks, and provide actionable insights that extend beyond the exit door. The market’s forward path will be defined by how quickly technology providers, component suppliers, and end users can align on interoperability, data sharing, and source-tagging adoption.
Key Challenges and Inflection Points
One of the most pressing challenges is the false-alarm burden that has historically undermined EAS reliability. Traditional detection systems often misread tagged items or environmental interference, creating operational frustration and eroding staff confidence in security infrastructure. Retailers are increasingly unwilling to deploy systems that require constant manual overrides or that disrupt the customer experience at entrances. This has accelerated demand for intelligent detection architectures that can distinguish between genuine tag activations and benign signal events, a shift that is reshaping product development priorities across the industry.
A second inflection point centers on the shifting economics of retail labor. Workforce constraints and rising wage costs are making manual tag application and in-store security monitoring less sustainable. Retailers are under pressure to reduce labor-intensive processes while maintaining or improving loss prevention outcomes. This dynamic is pushing the market toward upstream tagging strategies and automated detection solutions that minimize in-store handling. When tagging responsibility moves closer to manufacturing or distribution, the value proposition of EAS changes from a reactive security tool to a proactive supply chain enabler.
A third challenge lies in the fragmentation of tagging standards and interoperability expectations. As more retailers, brands, and suppliers adopt source-tagging requirements, the need for consistent encoding, chip compatibility, and system responsiveness becomes critical. Inconsistent tag formats or detection protocols can create blind spots, increase integration costs, and slow deployment at scale. The market is therefore entering a phase where technical compatibility and industry coordination are as important as raw detection performance.
Key Drivers of Market Change
Technology Innovation and Intelligence Integration
The most significant driver of market evolution is the infusion of intelligence into EAS hardware and tag ecosystems. Detection systems are increasingly incorporating edge processing and analytics capabilities that improve signal discrimination and reduce false alarms. This transition is transforming EAS from a binary alarm mechanism into a data-generating component of store operations. Recent deployments of edge-AI smart antennas have demonstrated meaningful reductions in false-alarm rates across large store networks, illustrating how software-defined improvements can enhance the value of existing detection infrastructure.
At the component level, miniaturization and chip advancements are expanding the range of products that can be tagged without compromising packaging, aesthetics, or sterilization requirements. Smaller inlays and labels enable tagging in categories that were previously difficult to secure, including cosmetics, pharmacy items, and healthcare products. These advances are particularly relevant for retailers and brand owners seeking to broaden protection coverage while maintaining a positive shopper experience. The combination of smarter detection and more versatile tagging is creating a feedback loop: better tags improve system accuracy, and better systems increase the return on tagging investment.
Regulatory and Compliance Pressure
Regulatory developments are reshaping the market by mandating or incentivizing source tagging and traceability. Policy frameworks that require product-level identification are pushing manufacturers and suppliers to embed tags earlier in the value chain. This shift reduces the labor burden on retailers while improving inventory visibility and enabling gray-market detection. Compliance-driven tagging also strengthens the case for interoperable encoding standards, as fragmented tag data can undermine the intended benefits of traceability and loss prevention.
In parallel, large retail chains are issuing supplier mandates that effectively set de facto industry standards. When major retailers require RFID-enabled EAS tags in categories such as home goods and electronics, they accelerate adoption across the supply base and create scale effects that lower component costs over time. These mandates also shift the commercial conversation from whether to tag to how to tag efficiently, consistently, and in ways that are compatible with downstream detection systems.
Demand-Side Shifts in Retail and Loss Prevention
Shrinkage trends are fundamentally altering demand patterns for EAS solutions. Retailers are reporting sharp increases in shoplifting incidents compared with pre-pandemic levels, which intensifies the need for reliable, scalable security infrastructure. At the same time, loss prevention is no longer viewed purely as a cost center. Retail executives are increasingly interested in systems that can contribute to inventory accuracy, operational insights, and customer flow management. This broader value proposition supports investment in EAS technologies that integrate with existing store networks and provide analytics beyond simple alarm events.
The demand picture is also being shaped by category expansion. While apparel and fashion accessories remain a core application area, growth is emerging in grocery, pharmacy, and cosmetics segments where product value, return rates, and theft vulnerability create strong adoption incentives. As detection systems become more adaptable and tags more discreet, EAS is moving into environments where traditional hard tags were impractical, widening the addressable market and encouraging cross-category deployment strategies.
Supply Chain and Cost Structure Dynamics
Cost structures in the EAS market are being influenced by upstream sourcing, chip availability, and the economics of large-scale tagging programs. Supplier mandates and standardized encoding guidelines are helping to create more predictable demand for inlays, labels, and detachers, which can improve production efficiency and reduce per-unit costs over time. At the same time, the shift toward hybrid RFID-EAS deployments is changing procurement models, as retailers and integrators evaluate total cost of ownership rather than hardware price alone.
Another important dynamic is the growing role of software and analytics in system value. As detection hardware becomes more standardized, differentiation increasingly comes from integration capabilities, cloud-based reporting, and loss-insight tools. This means that supply chain decisions now extend beyond physical components to include data architecture, compatibility with store IT environments, and the ability to support multi-site deployment with minimal customization. Companies that can align component supply with software-enabled services are better positioned to capture recurring value in a market where capital equipment purchases are increasingly tied to operational outcomes.
Competitive Landscape and Leading Strategies
Strategic Positioning of Major Players
The competitive environment is defined by a mix of detection-system specialists, tag and label suppliers, and broader retail technology providers. Leaders are differentiating not only through detection technology but through ecosystem breadth, integration depth, and the ability to translate EAS data into operational insights. Several strategic positions are emerging:
- Precision-calibrated detection with analytics overlays is becoming a strong differentiator for companies that can reduce false alarms while extracting category-level shrink insights from existing infrastructure.
- RFID-centric EAS platforms are gaining traction where item-level recognition, open-entrance detection, and cloud software integration are prioritized, especially in retailers seeking unified visibility across security and inventory functions.
- Tag and inlay suppliers are expanding their role by offering sterilization-compatible labels, compact HF/NFC inlays, and chip configurations optimized for EAS compatibility, enabling wider adoption in sensitive product categories.
- Multi-technology providers are positioning around flexibility, offering RF, AM, and RFID options within a single ecosystem to serve retailers with varied store formats and legacy equipment.
These positions reflect a market where hardware performance is necessary but not sufficient. Differentiation is increasingly tied to deployment scalability, data interoperability, and the ability to support both loss prevention and inventory intelligence objectives.
Recent Developments Shaping the Field
Recent product launches and deployment activity illustrate how the market is moving toward smarter, more integrated EAS solutions. Sensormatic Solutions introduced a category-level shrink insights ecosystem that leverages existing EAS infrastructure for intelligent loss-prevention analytics, signaling a shift toward software-driven value creation on established hardware footprints. Nedap expanded its RFID-based EAS footprint through large-scale store rollouts and a pan-European grocery deployment, reinforcing the appeal of item-level recognition and open-entrance detection in high-traffic retail environments.
Avery Dennison has been active in broadening the tag ecosystem with compact inlays, enhanced chip compatibility, and sterilization-ready RFID inlays for healthcare applications. These developments matter because they extend EAS feasibility into categories that require careful handling, small form factors, or compatibility with processing methods that previously limited tagging options. Collectively, these moves show a market where detection, tagging, and analytics are converging rather than evolving in isolation.
Rf Eas Label Market
Market Structure and Evolution Trends
Market concentration remains moderate, with leading players holding meaningful but not dominant shares. This creates room for both consolidation and specialized differentiation. Over the next several years, three structural trends are likely to shape the landscape:
- Integration and platformization will accelerate as retailers prefer fewer vendor relationships that can deliver detection, tagging, and analytics within a coherent architecture.
- Component specialists will continue to gain influence where miniaturization, sterilization compatibility, and chip-level compatibility create clear advantages in high-value or sensitive categories.
- New entrants and niche providers may find opportunities in edge-AI antennas, interoperability services, and vertical-specific solutions, particularly where legacy systems create upgrade bottlenecks.
The overall effect is a market that is becoming more solution-oriented. Winners will be those who can demonstrate measurable reductions in false alarms, labor efficiency, and shrink visibility while supporting the tagging standards and IT integration requirements that modern retail operations increasingly expect.
Future Trends and Commercial Opportunities
From Detection to Intelligence-Led Loss Prevention
Over the next three to five years, EAS systems are likely to be evaluated increasingly on their ability to generate actionable intelligence rather than simply trigger alarms. Edge processing, analytics dashboards, and integration with store data environments will turn detection points into sources of shrink insight, category comparison, and operational feedback. The commercial opportunity here lies in offerings that help retailers convert existing infrastructure into measurable loss-prevention improvements without requiring full hardware replacement. Providers that can package analytics with detection hardware, or enhance legacy systems through software upgrades, will be well positioned to capture demand from cost-conscious retailers seeking performance gains.
PW Consulting
Upstream Tagging and Ecosystem Standardization
Source tagging is expected to deepen as supplier mandates, compliance requirements, and labor economics continue to push tagging earlier in the supply chain. This creates opportunities for tag manufacturers, inlay developers, and integration partners who can deliver compatible, durable, and cost-effective tagging at scale. Standardization efforts around encoding and interoperability will further reduce deployment friction and support cross-retailer consistency. Companies that align their product portfolios with emerging tagging standards and can demonstrate compatibility with major detection systems will benefit from broader adoption and repeat procurement cycles.
Category Expansion and Hybrid Deployments
Growth is likely to broaden beyond traditional apparel and fashion as EAS becomes viable in grocery, cosmetics, pharmacy, and healthcare contexts. Miniaturized tags, sterilization compatibility, and hybrid RFID-EAS architectures will enable protection in categories where detection was previously limited. For retailers and integrators, this opens new deployment models that combine loss prevention with inventory accuracy and customer flow insights. The opportunity lies in designing category-specific tagging and detection strategies that balance security, aesthetics, and operational practicality.
Risks and Uncertainties
Despite the positive trajectory, several uncertainties merit attention. If false-alarm performance or interoperability issues persist, retailer confidence in large-scale EAS investments could slow. Regulatory requirements may also evolve in ways that change tagging obligations or compliance costs, creating short-term disruption for suppliers and retailers adjusting their sourcing strategies. Labor market conditions will continue to influence the economics of in-store tagging and monitoring, meaning that adoption speed may vary by region and retail format. Finally, as analytics become more central to EAS value, data privacy, IT integration complexity, and vendor lock-in concerns could affect purchasing decisions, particularly in consolidated retail environments.
Strategic Implications for Decision-Makers
For Manufacturers and Technology Providers
Companies operating in the EAS market should prioritize interoperability, false-alarm reduction, and analytics compatibility as core product priorities. The ability to support standardized encoding, integrate with major detection platforms, and offer software-enabled insights can differentiate a portfolio in a market where hardware specifications alone are increasingly insufficient. Investment in miniaturization, sterilization-compatible labeling, and chip configurations that align with prevailing EAS requirements will also expand addressable categories and strengthen supply chain partnerships.
Electronic Shelf Label (ESL) Market
For Investors
Investment attention should focus on providers that demonstrate a clear path from hardware to recurring value through analytics, integration services, and scalable tagging ecosystems. Businesses that can monetize intelligence layers, reduce deployment friction, and support upstream tagging requirements are better positioned to capture long-term growth than those dependent solely on equipment replacement cycles. It is also important to monitor consolidation signals, standardization progress, and large retailer mandates, as these factors can reshape competitive dynamics and margin structures across the value chain.
For Retailers and Procurement Leaders
Procurement decisions should evaluate EAS investments against total operational impact, including false-alarm reduction, labor efficiency, inventory visibility, and compatibility with existing store IT environments. Source-tagging requirements and supplier mandates should be factored into vendor selection, as upstream compatibility can materially affect deployment speed and ongoing maintenance costs. Hybrid and multi-technology options may be appropriate where store formats, product mixes, or legacy systems vary, but standardization and integration should remain central to avoid fragmented deployments that increase complexity without delivering proportional benefits.
The market’s trajectory suggests that the most valuable decisions will be those aligned with broader retail operating models rather than isolated security purchases. Stakeholders that act early on interoperability, intelligent detection, and upstream tagging strategies will be better prepared to manage shrink, labor constraints, and compliance expectations as the market moves toward 2032.
For decision-makers seeking detailed segmentation data, competitive benchmarks, and customized scenario planning, the full PW Consulting research report provides a deeper examination of regional dynamics, application trends, and vendor-level positioning. Access to the complete study can help translate these strategic themes into specific procurement, investment, and product-development choices tailored to your operating context.
For detailed analysis of this topic, please visit the official page: Electronic Article Surveillance (EAS) System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


