



Category: Chemical & Materials
Nicotinamide Mononucleotide (NMN) Market: Strategic Outlook for 2026 — A PW Consulting Brief
As PW Consulting’s lead industry analyst, I present a concise, decision-oriented primer on the Nicotinamide Mononucleotide (NMN) market designed to inform executive choices in 2026. This briefing synthesizes historical performance (2020–2025), our base-year calibration (2025), and forward-looking dynamics through the 2026–2032 forecast window. It demonstrates why NMN is moving from niche ingredient to scalable commercial category, and — crucially — where boards, corporate strategy teams, and investors should focus as 2026 unfolds.
Nicotinamide Mononucleotide (NMN) Market
Executive snapshot
- The NMN market has evolved rapidly, expanding from a modest specialty ingredient in 2020 to a mainstream commercial category by 2025. Our base-year assessment places total industry revenue at USD 400.0 Million (2025 base year).
- We project accelerated adoption through the forecast horizon, reaching roughly USD 960.0 Million by 2032, equivalent to a compound annual growth rate (CAGR) of 13.8% over 2026–2032.
- Market concentration is moderate: the top three and top five players account for a minority share of industry revenue (CR3 ~25%; CR5 ~28%), indicating fragmentation with opportunities for consolidation and differentiation.
Why this briefing matters for 2026 decision-makers
2026 will be a tactical inflection year. The market size is already substantial and growing rapidly: our model forecasts the market rising from USD 400.0 Million in 2025 to approximately USD 463.41 Million in 2026, underscoring meaningful near-term expansion. For corporate leaders, this creates a narrow window to lock in supply, secure regulatory clarity, and establish positioning before competitive intensity and channel saturation increase.
Nicotinamide Mononucleotide (NMN) Market
Macro drivers and market trajectory
- Demand Drivers — A confluence of consumer health interest, aging-related positioning, and expanded retail and DTC channels has accelerated uptake. The nutrition, cosmetics, and specialty health segments are converging on NMN as both functional ingredient and differentiator.
- Supply-side Evolution — Manufacturing approaches (including enzymatic and high-purity processes) and the scaling of GMP-compliant capacities are reducing unit-cost variability and enabling larger B2B contracts. Expect supply to become more elastic through 2026 but pressure on premium-grade inventories may persist in the near term.
- Regulatory Clarity — 2025 ended with several pivotal regulatory developments (detailed below) that materially improve the legal certainty for manufacturers and brands. That clarity lowers the hurdle for mainstream distribution, but also raises the bar for compliance and documentation.
Regulatory inflection — what changed and why it matters
Late-2025 regulatory decisions have reshaped the playing field and will be a dominant factor in 2026 strategy:
Nicotinamide Mononucleotide (NMN) Market
- U.S. regulatory posture: The FDA issued a series of response letters in 2025 restoring NMN’s allowable status in the dietary supplement pathway after prior ambiguity. Notably, several ingredient-specific notifications (NDIs) were reaffirmed, reversing earlier exclusions and effectively reopening market access that had been constrained in prior years. For companies selling into or sourcing from the U.S. market, this reinstatement reduces legal tail-risk and enables relaunch and scale-up efforts with renewed confidence.
- Australia and exclusivity dynamics: A recent regulator granted a limited market exclusivity window tied to a specific applicant for listed medicines. This demonstrates divergent jurisdictional approaches — some regulators are clarifying permissibility while introducing temporary protections for early filers. Companies must therefore map jurisdictional timing precisely when planning market-entry or exclusivity strategies.
- Implication for 2026: Regulatory certainty reduces one form of risk but increases competitive urgency. Firms that have dossiers, quality documentation, and chain-of-custody data prepared will be able to accelerate distribution and capture demand before late entrants close the gap.
Competitive landscape — tactical takeaways
The industry currently combines pioneering specialists, vertically integrated suppliers, and early brand-led entrants. Key players to watch (assessed for strategic intent, capabilities, and recent moves):
- EffePharm Ltd (Hong Kong) — Known for clinically-proven NMN raw material and a focus on pharmaceutical-grade powder. Their clinical evidence and positioning make them a preferred supplier for brands wanting substantiation-driven claims.
- MIRAILAB BIOSCIENCE Inc. (Tokyo) — Early mover in finished NMN supplements and cosmetics; leveraging e-commerce channels for rapid geographic expansion. Their direct-to-consumer experience provides go-to-market lessons for players targeting fast-growth retail and online channels.
- SyncoZymes (Shanghai) — Significant because of its early FDA NDI approvals and role in the most recent regulatory reinstatements. Their dossier-first approach produces durable market access advantages in jurisdictions that require premarket submissions.
- Longevir (Netherlands-based operations) — European enzymatic-process manufacturer focusing on high-purity NMN for B2B supply. Their process and regional footprint make them a strategic partner for European brands seeking localized sourcing and compliance alignment.
Recent tactical events to factor into 2026 plans include: multinational regulatory reinstatements in late 2025, exclusive windows tied to pre-market applicants in some jurisdictions, and a wave of market launches and platform expansions by early supplement brands. These events accelerate commercialization and compress decision timelines for partnerships, manufacturing contracts, and clinical investments.
Strategic options for 2026 — path choices by corporate archetype
Depending on your company’s role — ingredient supplier, finished-product brand, or investor — the right 2026 playbook differs. We distill practical options below.
- Ingredient suppliers and manufacturers
- Prioritize regulatory completeness: accelerate dossier finalization and NDI-equivalent filings where relevant to lock in market access and reduce barriers to large B2B deals.
- Scale selectively: use staged capacity expansions tied to confirmed offtake agreements to avoid margin erosion from excess supply.
- Differentiate on quality and traceability: clinical proof points and pharmacopeial-grade evidence command premium positioning.
- Finished-product brands (DTC, retail, and cross-border)
- Secure supply contracts with quality clauses and price-protection mechanisms to protect margins as demand spikes.
- Invest in compliant claims and clinical substantiation that align with the regulatory state in targeted markets; regulatory reinstatements enable faster launches but increase scrutiny of health claims.
- Optimize channel mix: combine e-commerce pilots with selective retail rollouts to manage inventory and consumer education costs.
- Private equity and strategic investors
- Look for consolidation plays: fragmentation and moderate CR concentrations imply opportunities for roll-ups of regional manufacturers and specialized brand assets.
- Prioritize assets with regulatory-readiness and documented supply chains — these reduce transformation timelines and valuation risk.
Operational and commercial risks to mitigate in 2026
- Regulatory divergence across jurisdictions — build a compliance roadmap with prioritized filings and contingency plans.
- Price volatility linked to purity tiers and production methods — adopt flexible procurement and hedging strategies.
- Claims and clinical evidence requirements — align marketing with available substantiation and plan incremental clinical investments where claims matter for premiumization.
- Supply-chain traceability — implement QR-driven batch transparency and third-party testing to support retailer and consumer confidence.
What PW Consulting’s full NMN Market report delivers
For companies preparing strategic moves in 2026, our full study goes well beyond this strategic primer. It contains:
- Detailed historical and forecast revenue models (2020–2032) calibrated at ingredient, formulation, and finished-product levels;
- Segment-level analysis and scenarios (regional, product-type, and application splits) with sensitivity testing for regulatory and supply shocks;
- Vendor due-diligence dossiers, benchmarking metrics, and supplier scorecards to inform procurement and M&A decisions;
- Playbooks and timelines for regulatory filings across major jurisdictions, including risk matrices and recommended mitigation steps;
- Commercial templates for offtake agreements, quality clauses, and pricing frameworks designed for 2026 negotiations.
Note: This brief intentionally omits granular regional and application split figures to preserve the value of the full report and ensure readers obtain the precise segment data, tables, and exportable models available in the complete deliverable.
Closing — a 2026 checklist for leadership
- Confirm supply agreements with traceable quality and price-protection terms this quarter.
- Validate regulatory positioning: complete or update dossiers where necessary to exploit recent reinstatements and prevent market interruptions.
- Prioritize investment in clinical signals or third-party verification if premium claims will underpin your go-to-market strategy.
- Prepare for selective consolidation: target opportunities where regulatory readiness and production scale create fast synergies.
The NMN market is maturing fast: from USD 120.0 Million in 2020 to USD 400.0 Million in 2025, and expected to exceed USD 460 Million in 2026 as the category moves into broader consumer channels. The trajectory to roughly USD 960.0 Million by 2032 at a 13.8% CAGR presents material upside — but only for players who act decisively on supply, compliance, and evidence. PW Consulting’s full NMN Market report arms leaders with the granular data, supplier intelligence, and execution templates required to convert this market opportunity into durable competitive advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Nicotinamide Mononucleotide (NMN) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Magnetics Powder Core Market to Reach USD 1,265.5M by 2032 at 6.39% CAGR
By PW Consulting, 2026-07-08
Magnetics Powder Core Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused, actionable preview of our full Magnetics Powder Core Market study. This briefing is designed to show the analytical depth and strategic utility of the complete report while deliberately withholding granular segmentation figures so that corporate leaders are compelled to consult the full study for transaction-ready intelligence.
Magnetics Powder Core Market
Why this market matters in 2026
Powder magnetic cores are a quietly strategic input across power conversion, energy generation, automotive electrification, and consumer electronics. Our market synthesis shows a clear, sustained expansion: the global market grew from USD 540.42 Million in 2020 to USD 820.27 Million in 2025 and is forecast to reach USD 1,265.50 Million by 2032. The forecast period (2026–2032) carries a compound annual growth rate (CAGR) of 6.39% — a trajectory that places powder cores at the intersection of long-cycle infrastructure investment (renewables, grid modernization) and fast-cycle product innovation (EV inverters, high-frequency power supplies).
Magnetics Powder Core Market
What this trajectory means for 2026 corporate strategy
-
Time-window for capability investment: The market’s steady CAGR implies that 2026 is a tactical inflection point. Firms that commit to higher-precision manufacturing, tighter material specs, and higher-throughput lines now will capture disproportionate share as demand for specialized grades accelerates.
Magnetics Powder Core Market -
Procurement and cost risk management: Rising demand and recent upstream volatility mean raw-material sourcing will be a primary differentiation. Strategic buyers should be moving from spot purchasing to multi-layered contracts, hedging strategies, and, where defensible, upstream partnerships or minority investments in key powder producers.
-
Product roadmaps tied to system-level value: For OEMs, decisions about adopting advanced powder-core grades should be made against system-level benefits (efficiency, thermal performance, miniaturization) and not merely bill-of-material cost — the full report includes scenario-level TCO models to prove this case.
Supply-side dynamics shaping strategy
Several near-term supply-side developments are shaping the input economics and regulatory risk profile for powder-core players:
-
Regulatory compliance: The EU Directive 2024/1785 on dust and powder emissions is materially increasing compliance overhead for iron powder production and downstream processing. Compliance timelines and enforcement granularity vary across markets; 2026 procurement strategies must factor in compliance-driven capacity shifts and related capex.
-
Capacity builds and concentration in feedstock: Chinese producers are scaling capacity for carbonyl iron powder at scale (capacity additions measured in the tens of thousands of metric tons), and large chemical producers such as BASF have added targeted capacity expansions. These moves compress feedstock margins in some channels while creating regional overhangs that can depress prices seasonally.
-
Raw-material volatility: Iron ore price swings and higher prices for high-purity inputs and carbonyl compounds have introduced cost volatility into manufacturing. Firms with optimized conversion yields, alternative alloy pathways, or access to secured feedstock will enjoy a 2026–2028 cost advantage.
Competitive map and practical implications
The market is commercially fragmented but exhibits pockets of specialized dominance. Our competitive landscape assessment — distilled from company profiles, product portfolios, and technology roadmaps — yields the following practitioner-oriented observations.
-
Large, diversified incumbents: Companies like TDK Corporation and VACUUMSCHMELZE preserve competitive advantage through vertical R&D, integrated magnetics platforms, and global manufacturing footprints that support automotive and industrial-grade qualifications. Their advantage is in scale, qualification credentials, and breadth of grades.
-
Specialist performers: Firms such as Magnetics (Mag-Inc) and Micrometals have entrenched positions in power-supply and communications niches because of product families engineered for distributed gap designs and RF applications. Their intimate customer relationships make them attractive partners or acquisition targets for companies looking to bolt-on product-level capabilities.
-
Regional low-cost producers: Several China-based manufacturers provide high-volume, cost-competitive supply but vary in quality and qualification maturity. For buyers pursuing scale at lower unit cost, Asia-based partners remain essential — but they carry regulatory and compliance considerations that must be managed.
-
High-reliability and aerospace-focused suppliers: Arnold Magnetic Technologies and similar firms supply specialized cores for high-reliability applications (aerospace, defense) where qualification cycles and traceability requirements create pricing insulation and premium margins.
Market concentration metrics underline these dynamics: the top three suppliers account for a moderate share of market activity, while the top five materially extend that concentration. The result is a market where nimble specialists can win design-ins, but scale and qualification are prerequisites for platform-level contracts.
Report contents — operationally oriented, decision-ready modules
Our full Magnetics Powder Core Market report is organized to directly inform capital allocation, sourcing strategies, product development, and M&A decisions. Key modules include:
-
Market forecast suite: Base, upside, and stress scenarios for 2026–2032 with sensitivity to raw-material pricing, regulatory compliance costs, and adoption curves in electric mobility and renewables.
-
Supply-chain heat maps: Tiered supplier listings, geographic risk scoring, transport and lead-time overlays, and regulatory touchpoints required for cross-border procurement.
-
Cost-to-serve and manufacturing cost curves: Bottom-up cost models by grade and form factor, break-even analyses for capacity expansions, and conversion-efficiency levers.
-
Technology readiness and substitution matrix: Comparative performance of MPP, sendust, high-flux, Fe-Si and advanced nanocrystalline powders for typical system-level KPIs (losses, saturation, temperature coefficients), with recommended product roadmaps for OEM integration.
-
Regulatory and environmental compliance playbook: Implementation timelines for dust/powder directives, expected capex and opex impacts, and practical compliance checklists by manufacturing process.
-
M&A and partnership screening: A prescriptive target-identification framework, valuation heuristics for specialty powder-core firms, and case studies on successful tuck-ins and strategic alliances.
-
Supplier performance templates: Scorecards for technical quality, delivery reliability, environmental compliance, and business continuity — ready for immediate use in vendor rationalization exercises.
Actionable recommendations for 2026
-
Lock down feedstock resilience: Immediate priority for manufacturing and OEM procurement teams should be to secure multi-year agreements or equity participation in feedstock suppliers where conversion economics are favorable. Short-term spot exposure is risky given recent feedstock price swings.
-
Accelerate qualification work with specialists: To shorten time-to-market for next-generation power electronics, start concurrent qualification programs with specialist powder-core suppliers. This reduces integration risk and creates supplier lock-in.
-
Model regulatory scenarios into capital planning: Incorporate compliance-cost scenarios from the EU Directive and similar national rules into 3–5 year capex plans. For vendors with cross-border supply, compliance timing will drive near-term competitive shifts.
-
Pursue layered supply strategies: Combine a primary qualified supplier (for high-reliability grades) with secondary regional partners to balance cost and resilience. The report’s supplier heat maps and scorecards are built to operationalize this strategy quickly.
-
Evaluate M&A as a speed-to-market mechanism: Where in-house development timelines conflict with product launch dates, targeted acquisitions of niche powder-core specialists deliver quick access to grades and customer channels. Use our valuation heuristics to screen targets.
-
Invest in conversion efficiency R&D: Small improvements in powder-to-core conversion yield, binder chemistry, and sintering control translate to meaningful margin gains across forecast horizons.
How to use the full report
This preview outlines the strategic terrain; the full PW Consulting report equips leaders with the numbers, models, and tactical blueprints necessary to execute. It contains the granular segmentation, supplier-by-supplier dossiers, and downloadable financial templates that boards, corporate development teams, and procurement leaders need to translate insight into action. We intentionally withhold those segmented data tables here to preserve their transaction utility — they are available in the complete study and our advisory packages.
Next steps
If your 2026 planning cycle includes sourcing, product-development, or inorganic-growth decisions tied to powder magnetic cores, PW Consulting can provide tailored briefings, scenario workshops, and a prioritized implementation roadmap anchored to the full dataset. Schedule an engagement to receive the complete report, the confidential segmentation analytics, and the operational toolset you will need to convert market projection into competitive advantage.
— PW Consulting, Senior Strategy Advisor & Head Industry Analysis
For detailed analysis of this topic, please visit the official page: Magnetics Powder Core Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Food Grade Lubricants Market to Reach USD 706.9 Million by 2032 at 6.98% CAGR
By PW Consulting, 2026-07-08
Food Grade Lubricants Market — Strategic Outlook for 2026 Decision‑Makers (PW Consulting)
This briefing introduces PW Consulting’s comprehensive Food Grade Lubricants Market study (base year 2025). It synthesizes the macro trajectory, regulatory inflection points, supply‑chain shocks, and competitive moves that will determine winners and losers through the 2026 planning cycle and across our 2026–2032 forecast horizon. At the macro level the market reached approximately USD 438.7 Million in 2025 and, driven by rising demand for certified, high‑performance and sustainable formulations, is projected to expand at a compound annual growth rate (CAGR) of 6.98% over 2026–2032, reaching roughly USD 706.9 Million by 2032. This note outlines why that growth matters to boardrooms in 2026, what practical intelligence the full report delivers, and the strategic plays executives should prioritize now.
Food Grade Lubricants Market
Why this study is mission‑critical for 2026 decisions
- Regulatory convergence and tightening: 2025–2026 saw important regulatory movement — most notably the introduction of new certification expectations for MOAH‑free materials and an update to the FDA lubricant guidance in 2026 — raising the compliance bar for formulations and supplier documentation. These changes increase certification costs and shorten acceptable lead times for reformulation.
- Upstream raw‑material volatility: Feedstock dynamics are reshaping cost and availability. Capacity expansions for polyalphaolefins in 2025 and material cost increases for key base oils (a later multi‑year rise in the cost base since 2022) change the economics of synthetic versus mineral and bio‑based offerings. Procurement and product costing must be recalibrated accordingly.
- Market growth concentrated in quality‑sensitive segments: Demand is accelerating where incidental food contact, hygiene, and lifecycle performance matter most — driving buyers toward certified synthetics, bio‑based options and PFAS‑free chemistries. This creates premiumization opportunities for suppliers with validated certifications and service capabilities.
- Fragmented supplier landscape with strategic differentiation: A mix of global majors, regional formulators and niche innovators means competitive advantage increasingly rests on certification credentials, formulation IP, and after‑sales lubrication management services rather than price alone.
What the report delivers — practical, executable intelligence
The full PW Consulting report is organized to convert market intelligence into action plans for 2026 budgeting, sourcing and product strategy. Highlights include:
Food Grade Lubricants Market
- Executive synthesis: clear implications for revenue, margin and investment choices across the 2026 planning window.
- Top‑down market sizing and verified forecast (2026–2032) that anchors scenario planning — including an evidence‑based base case aligned with the 6.98% CAGR and upside/downside sensitivity models.
- Demand driver mapping: breakdowns of hygiene, safety and sustainability requirements by end‑use class and buyer persona, and the operational triggers that prompt lubricant specification changes.
- Regulatory tracker and compliance playbook: a dynamic register of certification standards (NSF, ISO 21469, FDA guidance updates, HACCP/GMP implications), likely near‑term amendments, and a step‑by‑step path to minimize time‑to‑market for reformulated products.
- Upstream supply and cost analytics: base‑oil cost modeling, impact of PAO capacity ramps, and procurement levers (long‑term contracts, indexation, strategic inventory) to protect margins under volatility.
- Competitive capability matrix and vendor archetypes: scored profiles of market participants across formulation capability, certification portfolio, geographic reach, and aftermarket services.
- Commercial playbooks: GTM segmentation, value‑based pricing templates, and distributor vs direct sale decision frameworks for 2026 expansion.
- M&A and partnership roadmaps: target archetypes, valuation sensitivity to certification assets, and integration checklists for bolt‑on deals to close capability gaps quickly.
- Implementation sprints: 90‑day and 12‑month action plans for R&D reprioritization, supplier qualification, and channel activation.
Competitive landscape — how incumbents and challengers are repositioning
The competitive field is heterogeneous. Global energy and chemical majors maintain a strong position through broad formulation platforms and the ability to secure regulatory approvals at scale, while specialist formulators and lubrication service providers compete on certification breadth, niche chemistries and field support. Notable industry moves in the recent 18 months illustrate the tempo of competition and the strategic choices available:
Food Grade Lubricants Market
- Leading oil and chemical producers continue to leverage scale and approvals to supply synthetic food‑grade lubricants suited for high‑temperature and incidental contact applications. These companies focus on aligning product ranges with NSF and updated FDA expectations.
- European and North American specialists emphasize certification depth (ISO 21469, HACCP/GMP) and value‑added services such as lubrication management systems for OEMs and processors, reinforcing sticky customer relationships.
- Niche innovators are differentiating on sustainability and chemistry: bio‑based formulations, PFAS‑free solutions, and multifunctional products that combine release agent and lubrication properties. Recent market entries and updates underscore the R&D trajectory toward safer, multi‑functional chemistries.
- Upstream investments, such as the 2025 expansion of low‑viscosity PAO capacity in Europe, change raw material supply dynamics and favor producers that secure advantaged feedstock access.
Recent commercial and technology developments of note (illustrative, not exhaustive): product introductions combining release and lubrication functions; major capacity expansions for synthetic feedstocks; expansion of NSF certification programs that reshape acceptable formulation ingredients; and the public release of new product safety documentation updates aligning with evolving standards. These moves underline that technical credentials and certified documentation are now as strategically important as price or distribution reach.
Strategic implications and recommended actions for 2026
Companies that treat 2026 as a transition year — preparing for tighter regulation, higher certification costs and persistent feedstock volatility — will capture outsized share through 2032. Our recommended priorities:
- Certification first, commercial second: Map certification requirements to target customers and prioritize investment in the subset of approvals that unlock high‑value business (NSF, ISO 21469, MOAH‑free verification where applicable).
- Hedge raw materials strategically: Use a mix of long‑term contracts, index‑linked pricing, and selective vertical integration (or strategic JV exposure to advantaged PAO supply) to stabilize margins.
- Product portfolio rationalization: Eliminate low‑margin legacy SKUs, prioritize multi‑function and bio‑based formulas, and accelerate reformulation roadmaps where regulatory risk is rising.
- Service and systems play: Differentiate with lubrication management services, certification support packs, and digital condition monitoring to convert specifications into recurring revenue.
- M&A when time‑to‑market is critical: Acquire certified small‑scale formulators to obtain documentation and market access quickly rather than building from scratch.
- Commercial sophistication: Adopt value‑based pricing for performance and certification value, and design channel incentives that reward compliance and inventory stewardship.
- Governance and risk management: Build a regulatory early‑warning process and compliance checklist to ensure rapid turnover of safety data sheets and approvals after standard changes.
How PW Consulting accelerates 2026 outcomes
Our engagement model converts insight into deliverables you can deploy immediately:
- Custom dashboards tied to your P&L showing the impact of base‑oil price swings and certification timelines on EBITDA.
- Supplier and formula heat maps that surface immediate requalification priorities and alternative sourcing routes.
- RFP and contract templates for long‑term feedstock purchase agreements and toll manufacturing arrangements.
- Regulatory gap analysis and a certification funding model that quantifies ROI on certification investments and speed‑to‑market trade‑offs.
- Due‑diligence support and integration plans for bolt‑on acquisitions that accelerate entry into certified, premium product segments.
Note: this introduction intentionally omits the report’s granular segmentation tables and competitive share matrices. Those detailed breakdowns — including end‑use and regional demand splits, SKU‑level pricing, and supplier market shares — are available in the full PW Consulting report and interactive dataset. That level of detail is often decisive when sizing investments, structuring bids, or negotiating supply agreements.
Next steps: For procurement directors and product heads preparing 2026 budgets, the immediate actions are to (1) run a rapid certification gap assessment against your top 20 SKUs, (2) stress‑test your feedstock contracts against a 20–30% price shock, and (3) identify two near‑term inorganic targets or technology partners to secure certification or formulation IP. PW Consulting can execute these diagnostics in an accelerated 6–8 week sprint with board‑ready recommendations and executable templates.
To access the full intelligence set — including the segmented demand model, vendor scorecards, and downloadable financial stress tests that underpin the 6.98% CAGR and the 2026–2032 forecast line — visit our report page or contact PW Consulting’s Food Grade Lubricants practice directly. The decisions you make in 2026 will lock in the performance trajectory to 2032; this study gives you the map and the tactical instruments to act with confidence.
For detailed analysis of this topic, please visit the official page: Food Grade Lubricants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pharmaceutical Blister Packaging Market to reach USD 32.6 Billion by 2032
By PW Consulting, 2026-07-08
Pharmaceutical Blister Packaging Market — 2026 Strategic Preview
As PW Consulting’s senior strategic advisor and chief industry analyst, I present a concise but rigorous preview of our new Pharmaceutical Blister Packaging Market study. This article is written for executives, procurement leaders, product and regulatory strategists, and private investors who must make high-stakes decisions in 2026. It highlights the market’s trajectory, competitive dynamics, regulatory fault lines, and the practical implications that should shape corporate action this year — while intentionally withholding core sub-segment datapoints to preserve the full report’s commercial value and direct readers to the source for granular inputs and models.
Pharmaceutical Blister Packaging Market
Market trajectory: the headline numbers that matter
The blister packaging market for pharmaceuticals has moved from a post‑pandemic recovery into a structurally higher-growth phase. Our baseline sizing shows the global market expanding from roughly USD 14.5 billion in 2020 to approximately USD 19.6 billion in 2025, and we forecast growth to continue to around USD 32.6 billion by 2032 — a compounded annual growth rate (CAGR) of about 7.7% across the 2026–2032 forecast window. These headline metrics reflect secular demand for secure unit-dose formats, continued growth in oral solid-dose volumes in many therapy areas, and accelerating replacement and sustainability-driven upgrades across pharmaceutical primary packaging portfolios.
Pharmaceutical Blister Packaging Market
Why 2026 is a decisive year for executives
- Regulatory inflection points are actionable now. European and U.S. regulatory initiatives — from packaging waste directives to heightened quality scrutiny of repackaged unit-dose blisters — have moved from policy drafts into enforceable frameworks or focused regulatory attention. Companies that align packaging design, material selection, and quality systems to the new expectations this year will avoid costly retrofits and market-access friction.
- Sustainability is reshaping supplier selection and product specs. Buyers are no longer evaluating barrier performance in isolation. Recyclability, recycled content, and life‑cycle carbon implications are explicit procurement criteria. Early adopters of validated PVC‑free and post‑consumer‑content films are already converting proof-of-concept into commercial orders.
- Material and logistics risk is non‑trivial. Geopolitical disruptions and concentrated raw-material supply chains mean that dual-sourcing strategies, long‑lead-time contracts, and flexible converter relationships should move from contingency plans to operational priorities in 2026.
Strategic implications for 2026 decision-making
To translate the market trajectory into superior outcomes, leadership teams should prioritize four synchronized actions this year:
Pharmaceutical Blister Packaging Market
- Embed regulatory and sustainability requirements into product roadmaps. Treat upcoming packaging rules and public procurement preferences as product design constraints. This means revalidating barrier performance under new material footprints, auditing supply chains for recycled content claims, and documenting interchangeability where conversions from cold‑form to thermoform, or PVC to PVC‑free systems, are proposed.
- Adopt a modular sourcing architecture. Implement a mix of global strategic suppliers for scale and regional specialty suppliers for resilience. Lock in supply through multi-year offtakes for critical films and foils, while preserving optionality for rapid material substitution driven by regulatory or cost shocks.
- Prioritize pilot-to-scale pathways for sustainable solutions. Innovations such as lightweight cold‑form cavities and pharmaceutical‑grade films with post‑consumer recyclate are moving rapidly from lab to line. Allocate controlled CAPEX to de‑risk scale trials (process qualification, packaging line compatibility, stability studies) so sustainability transitions do not stall at validation gates.
- Refresh quality governance for unit‑dose and repackaging operations. Regulators are scrutinizing impurity, dissolution, and assay stability in repackaged blister packs. Strengthen sampling regimes, stability protocols, and supplier audits to reduce regulatory risk and preserve market trust.
What the competitive landscape means for buyers and investors
The sector is neither atomized nor monopolistic. Market concentration metrics indicate a market where a handful of global players capture substantial share, yet a broad base of specialized converters and material suppliers retain influence over innovation and niche capabilities. This duality creates both negotiating leverage for large buyers and acquisition opportunities for firms seeking capability densification.
- Amcor plc (Zürich, Switzerland) — A leader in thermoform blister systems that has been commercializing PVC‑free offerings and lower‑carbon lidding solutions. Amcor’s commercial traction demonstrates how sustainability-oriented product architectures can move quickly from R&D into production. ( https://www.amcor.com/)
- Gerresheimer AG (Düsseldorf, Germany) — A specialist with deep expertise across glass and polymer blister formats for pharmaceutical primary packaging, favoring development partnerships with pharma innovators. ( https://www.gerresheimer.com/)
- West Pharmaceutical Services, Inc. (Exton, Pennsylvania, USA) — Focused on advanced components and delivery systems, with capabilities that intersect both blister and parenteral packaging design. ( https://www.westpharma.com/)
- AptarGroup, Inc. (Crystal Lake, Illinois, USA) — Supplier of protection technologies and delivery adjuncts that increasingly matter to drug formulators looking for integrated packaging‑plus‑drug delivery solutions. ( https://aptar.com/)
- Schott AG (Mainz, Germany) — Engaged in polymer-based blister systems with a development emphasis on compatibility with complex pharmaceutical formulations. ( https://www.schott.com/)
- ALPLA Group (Hard, Austria) — Innovator in plastic blister formats with a strong converter footprint in key end‑markets. ( https://www.alpla.com/)
- CCL Industries Inc. (Toronto, Canada) — Niche leader in specialty blister films, foils, and printed packaging, driving differentiation through substrate and print capability. ( https://www.cclind.com/)
- ACG Worldwide (Mumbai, India) — Provider of cold‑form materials and machinery; recent product introductions target lightweighting and barrier efficiency for cost-sensitive markets. ( https://www.acg-world.com/)
Recent vendor moves — lightweight cold‑form designs, commercially ordered PVC‑free thermoform systems, and the first pharmaceutical‑grade films with significant post‑consumer recycled content — show that the innovation pipeline is both commercial and sustainability-driven. For buyers, this elevates the importance of supplier roadmaps: do suppliers have validated scale, documented stability data, and regulatory support for novel substrates?
Regulatory and raw‑material dynamics to watch in 2026
- Packaging waste regulation (EU and beyond). New packaging rules increase pressure to minimize materials and document recyclability. Even where quality exemptions exist, regulators expect documented justification and continuous improvement plans.
- Pharmaceutical sector regulation and quality focus. U.S. and EU authorities have increased scrutiny on repackaging and unit‑dose stability. These inspections influence QMS requirements, batch release testing, and supplier qualification depth.
- Raw‑material availability and price volatility. Shipping bottlenecks and geopolitical factors continue to disrupt supply of films, foils, and paperboard. This increases the value of backward integration, strategic stocks, and geographically distributed supply networks.
What’s in the full PW Consulting report (practical content highlights)
The full study is a practitioner’s toolkit designed to convert market intelligence into tangible actions. It includes:
- Detailed market sizing and validated forecasts (2020–2032) with scenario and sensitivity models for material price, regulatory stringency, and adoption curves.
- Segment‑level drivers and decision matrices that identify which product lines and geographies will drive margin expansion vs. margin compression under alternative futures.
- Raw‑material and input‑cost analysis, supplier cost‑to-serve benchmarking, and negotiation playbooks for multi‑tier procurement.
- Technology and sustainability adoption maps, including timelines for thermoform vs. cold‑form migration, recycled‑content integration, and viable recycling routes for blister waste.
- Vendor scorecards and comparative profiles (commercial reach, R&D pipeline, regulatory footprint, and conversion risk) for major players and fast‑growing regional specialists.
- M&A, J‑V, and capital allocation guidance: where strategic consolidation unlocks scale, and where bolt‑on acquisitions accelerate technical capability.
- Operational checklists for line conversion pilots, stability study protocols tailored to novel substrates, and an executive dashboard for monitoring regulatory changes and supplier KPIs.
Immediate actions we recommend for 2026
- Commission a rapid supplier capability audit focused on sustainability claims, validated stability data, and dual‑sourcing feasibility for critical substrates.
- Run controlled production pilots for at least one alternative packaging substrate (PVC‑free or high‑recyclate film) with full stability and process qualification to avoid late-stage surprises.
- Deploy a scenario‑based procurement strategy that ties contract tenor, optionality, and price escalation clauses to specific regulatory triggers and raw‑material indices.
- Establish a cross‑functional governance forum (Regulatory, R&D, Procurement, Quality, and Manufacturing) to approve packaging changes within a timeline compatible with market launches and regulatory windows.
Concluding perspective
The blister packaging sector in 2026 sits at the intersection of persistent demand growth, accelerating sustainability expectations, and evolving regulatory scrutiny. The market’s structural growth creates attractive opportunities for incumbents and new entrants who can pair material innovation with regulatory foresight and supply‑chain resilience. For decision‑makers, the imperative is clear: convert strategic intent into validated operational programs now to capture share and avoid reactive costs later.
PW Consulting’s full Pharmaceutical Blister Packaging Market report provides the granular models, vendor analytics, and implementation playbooks required to act with confidence. This preview has been designed to signal the strategic fault lines and near‑term priorities; the complete study contains the specific sub‑segment data, pricing models, and vendor scorecards you will need to operationalize the recommendations above.
For detailed analysis of this topic, please visit the official page: Pharmaceutical Blister Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Copper Foil Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
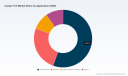
PW Consulting’s Copper Foil Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes market-scale trajectories, supply-chain dynamics, technology maturation, and policy shocks that will shape commercial choices in 2026. At a headline level, the industry has expanded from a multi-billion-dollar base in 2020 to an estimated USD 8.3 billion in 2025 and is projected to grow to roughly USD 14.0 billion by 2032 — a compound annual growth rate (CAGR) of 7.9% over the forecast horizon. Market structure remains moderately concentrated (CR3 ≈ 35%; CR5 ≈ 55%), creating both windows for scale capture by incumbents and opportunities for nimble entrants to carve differentiated positions.
Copper Foil Market
Why this matters to boardrooms in 2026
- Timing of investment. The sector is entering an investment-intensive phase driven by battery electrification, flexible electronics and high-density printed circuit board (PCB) requirements. Boards considering plant expansion, technology upgrades, or upstream integration need to align capex timetables with a mid-decade inflection in demand and tightened environmental enforcement.
- Policy and trade volatility. Recent regulatory actions and trade measures have created an elevated risk premium on cross-border sourcing, intellectual property exposure, and cost pass-through strategies. Procurement and commercial teams must update playbooks accordingly.
- Operational sustainability as a value lever. Recycled-content certification and wastewater compliance are moving from compliance checkboxes to competitive differentiators — impacting offtake negotiations, customer selection, and ESG disclosures.
Market trajectory and what the headline numbers conceal
The aggregate growth profile is clear: robust demand foundations are supporting near‑double‑digit pockets of growth within the broader 7.9% CAGR. However, the aggregate figures mask important heterogeneity across product form factors, end-use intensity, and value-chain positions. For example, precision foils for next-generation batteries command different margin and capex dynamics than commodity-grade foils used in standard PCB laminates.
Copper Foil Market
PW Consulting’s modelling layers topline growth with bottom-up plant economics and scenario stress tests. We deliberately withhold granular regional, type and application-level revenue tables from this public briefing to preserve the full commercial value of the segmentation model. Subscribers to the full report receive an interactive model that decomposes demand by application mix, foil type, and logistical cost drivers — an essential tool for sizing production expansions, pricing corridors, and contract negotiations.
Copper Foil Market
Dynamics shaping 2026 strategy
- Raw material and processing economics. A notable industry development: benchmark copper processing terms moved to historically low levels in early 2026, compressing some upstream treatment-and-refining margins. This shift alters feedstock cost pass-through behavior, creating near-term margin relief for processors but also raising questions about feedstock security and long-term price normalization.
- Trade and tariff shocks. In mid-2025 several high-profile trade interventions dramatically altered the calculus for import-dependent supply chains. Companies that had optimized for lowest landed cost are now evaluating alternative scenarios that prioritize trade resiliency over marginal procurement savings.
- Environmental regulation and plant-level compliance. Stricter effluent limits and electroplating discharge standards in key manufacturing jurisdictions have already forced temporary suspensions and multi-million-dollar remediation programs at mid‑sized facilities. The capital and timeline implications of compliance upgrades should be baked into any expansion or relocation decision in 2026.
- IP and trade investigations. Investigations into unfair trade practices and IP concerns have created uncertainty for cross-border partnerships and licensing in target markets. Commercial teams should adopt layered risk assessments when structuring supply contracts and technology transfers.
- Sustainability certifications. Certification of electrodeposited foils as 100% recycled in early 2025 signals a material shift: recycled-content credentials are moving from marketing claims to procurement filters for large OEMs, particularly in battery supply chains.
Technology and product evolution — where differentiation will arise
Product evolution is bifurcating along performance and sustainability axes. High-performance, thin-gauge foils for advanced batteries and flexible electronics demand tighter process control, greater R&D intensity, and smaller but higher-value plant footprints. Conversely, rolled and commodity foils remain volume plays with pressure on yield improvements and logistics optimization. Proprietary coating, surface treatment, and roll-to-roll equipment capabilities are becoming critical barriers to entry for the high-margin end of the market.
Equipment and process suppliers — including established vendors that provide manufacturing lines and process know-how — will continue to be value-capture points. Buyers should evaluate long‑term maintenance contracts, upgrade pathways, and spare-part ecosystems as part of total-cost-of-ownership calculations.
Competitive landscape — strategic map (selected firms)
The sector includes a mix of integrated miners, specialized foil producers, and regional champions. Key players noted in the market include long-standing Japanese and Korean leaders with deep expertise in electrolytic and high-performance grades; emerging capacity additions in Southeast Asia; and a small but strategically important North American manufacturing presence. While we do not disclose company-level market shares in this preview, the competitive dynamics can be summarized in three strategic archetypes:
- Tier‑A incumbents: firms with global reach, technology IP in high-performance foils, and established OEM relationships. These actors are positioned to capture growth in battery and advanced electronics segments through incremental capacity and premium product differentiation.
- Regional specialists: companies focused on local supply continuity, agility, and tailored product portfolios for domestic electronics and industrial users. They exploit lead times and local regulatory familiarity to compete effectively against exports.
- New-capacity entrants and equipment integrators: firms that couple manufacturing capability with process equipment supply, enabling rapid deployment of niche production lines for thin-gauge or recycled content foils.
Two recent corporate developments crystallize the above: (1) a major electrodeposited foil supplier announced significant capacity expansion in Taiwan and Malaysia to meet specialized demand, and (2) a leading electrodeposited-foil producer achieved validated recycled-content certification for several product grades. Both moves highlight diverging strategic plays — scale-up for performance segments, and certification-led differentiation for sustainability-conscious offtakers.
What PW Consulting’s full study provides (practical deliverables)
Executives who need to act in 2026 will require more than high-level forecasts. Our full report delivers:
- Interactive demand model (2020–2032) with scenario toggles for technology adoption, electrification pace, and trade policy shocks.
- Supplier scorecards that assess operational cadence, techno‑commercial fit, ESG posture, and contract-readiness.
- Plant-level capex and unit-cost benchmarks, including sensitivity to feedstock pricing, labor, energy, and wastewater treatment investments.
- Tariff and trade-impact simulations that quantify landed-cost differentials and break-even on nearshoring versus offshore sourcing alternatives.
- M&A and JV target screening with valuation ranges and integration risk maps for prioritized geographies and technology niches.
- Regulatory compliance matrix and remediation playbooks for jurisdictions enforcing stricter discharge and emissions rules.
- Roadmap for product innovation and a prioritized R&D investment timetable aligned to customer adoption curves and procurement windows.
Strategic implications and recommended actions for 2026
- Re-assess sourcing strategies now, not later. The combination of trade measures and regional regulatory enforcement compresses time to secure alternative suppliers or to onshore capacity. Start supplier dual‑sourcing pilots with contractual clauses that protect IP and mitigate tariff exposure.
- Prioritize ESG-capital investments that unlock commercial premiums. Certification of recycled-content and demonstrable wastewater compliance can materially improve procurement outcomes with large OEMs and reduce regulatory interruption risk.
- Match capex to market microstructure. Avoid blanket capacity expansions. Use the report’s plant-level models to identify which foil grades and manufacturing footprints deliver the fastest payback under conservative demand scenarios.
- Design M&A playbooks around technology and market access, not just volume. Targets that provide access to differentiated thin-gauge technology, proprietary coatings, or validated recycled-content supply chains will command premium strategic value.
- Hedge feedstock risk tactically. While benchmark processing terms recently moved to unusual lows, volatility remains. Procurement teams should combine short-term hedges with strategic partnerships upstream to secure feedstock continuity.
Next steps — how to use the full study in 2026 planning cycles
PW Consulting recommends three immediate actions for leadership teams:
- Procurement & risk: run the tariff and landed-cost scenario module against your supplier roster to quantify first-order P&L impacts and identify 90-day mitigation priorities.
- Operations & engineering: use the plant-level cost model to validate any pending greenfield or brownfield capex decision under conservative demand and environmental cost assumptions.
- Corporate development: screen acquisition targets using our M&A filters that prioritize technology fit, customer overlaps, and regulatory exposure; engage our transaction advisory team for targeted diligence.
Conclusion and how to access the intelligence you need
The copper foil market entering 2026 is defined by durable demand growth, pockets of high-margin technical demand, and an increasingly complex regulatory and trade environment. The headline CAGR and topline projections provide confidence in growth direction, but competitive advantage will be won through precise timing of investments, disciplined supplier strategy, and rapid action on environmental compliance and certification.
This preview intentionally omits detailed regional and application-level revenue breakdowns and the full set of modelling outputs — those elements are available in the full PW Consulting Copper Foil Market report and interactive dashboard. For executives requiring operationally actionable intelligence to underpin 2026 capex, sourcing, or M&A decisions, access to the full models and supplier scorecards is essential.
Contact PW Consulting’s copper-foil practice to request the complete report, the Excel modelling package, and to schedule a tailored workshop that translates the findings into a 90‑day action plan for your company.
For detailed analysis of this topic, please visit the official page: Copper Foil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Needle Coke Market to Reach USD 517.9M by 2032 (5.0% CAGR)
By PW Consulting, 2026-07-08
Needle Coke Market 2026: Strategic Preview for Corporate Decision‑Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise yet rigorous preview of our full Needle Coke Market study — the playbook executives will use to make high‑stakes decisions in 2026. This is a “trailer”: it demonstrates the analytical depth and strategic framing you should expect, while reserving detailed segment-level tables and granular numbers for the full report.
Needle Coke Market
Executive snapshot: Why needle coke matters in 2026
Needle coke is a critical upstream feedstock for two rapidly converging value chains: high‑performance graphite electrodes for electric arc furnace (EAF) steelmaking, and anode materials for lithium‑ion batteries powering the EV transition. After steady growth through the early 2020s, the global needle coke market reached approximately USD 370 million in our base year (2025). Our forecast shows continued expansion at a 5.0% CAGR across the 2026–2032 horizon, pushing the market well over the half‑billion dollar mark by 2032 under the base case.
Needle Coke Market
For 2026 decision cycles, this is not simply a commodity story about incremental demand. It is a strategic pivot: supply chain composition, feedstock sourcing, decarbonization pathways, and geopolitical trade policy will jointly determine whether companies capture margin expansion, suffer volatile pricing, or lose strategic access to downstream OEMs.
Needle Coke Market
What’s driving the market in 2026 — the dynamics executives must monitor
-
Demand confluence and supply tightness: Electric vehicle battery build‑outs and continued adoption of EAF steel have synchronized demand timing, creating acute short‑term pressure points. Market observations in early 2026 show price upticks tied to both sectors, and production schedules are being challenged by refinery maintenance windows that reduce supply availability.
-
Feedstock volatility and quality premiums: The economics of petroleum‑derived feedstocks versus coal‑tar pitch feedstocks remain differentiated by quality characteristics required for anode versus electrode applications. Feedstock availability and refinery decant oil quality swings are driving upstream cost variability that transmits to downstream manufacturers.
-
Regulatory and trade policy shocks: Recent trade measures affecting synthetic graphite imports have already introduced tariff‑driven dislocations in downstream anode supply chains. These policy levers can rapidly re‑route demand and impose new sourcing premiums, prompting strategic insourcing or long‑term contracting.
-
Decarbonization and circularity pressures: Buyers — particularly battery and steel OEMs — are increasingly rewarding low‑CO2 feedstocks and recycled inputs. New product initiatives that integrate recycled feedstocks or lower carbon intensity often command a price premium and can alter the competitive calculus for producers willing to invest or partner on feedstock decarbonization.
Implications for 2026 corporate strategy
-
Supply diversification vs. vertical integration: Firms that depend on uninterrupted needle coke supply must choose between diversifying suppliers and forging deeper upstream integration through long‑term offtake agreements, tolling arrangements, or ownership stakes in coke production. Recent multi‑year supply agreements and large capacity expansions announced in 2025–2026 illustrate both paths in practice.
-
CapEx timing and plant configuration: The market’s 5% projected CAGR does not translate to uniform demand across all product grades. Executives should align capacity investments with likely quality‑driven demand trajectories for battery‑grade versus electrode‑grade products. Scenario‑based capex planning — with trigger points tied to feedstock spreads and policy changes — is essential to avoid stranded assets or under‑utilized facilities.
-
Contracting and price risk management: Short‑term price spikes due to refinery outages and concentrated demand windows argue for a blend of short and long‑term contracts, indexed pricing mechanisms, and option‑style supply arrangements. Hedging strategies must account for feedstock quality premiums and potential tariff disruptions in downstream markets.
-
ESG and customer access: Access to premium downstream customers increasingly hinges on measurable carbon outcomes and traceability. Producers that can credibly demonstrate lower lifecycle emissions or incorporate recycled feedstocks will secure advantageous long‑term offtake terms.
Competitive landscape — who matters and why
The needle coke industry combines global refiners, specialist carbon producers, and vertically integrated electrode manufacturers. Market concentration metrics show a moderately fragmented global supply base, indicating meaningful room for strategic consolidation and market share maneuvering.
-
Phillips 66 (Houston, Texas) — a major petroleum‑derived needle coke producer with refinery‑integrated flows and visible recent investments. Strategic moves include large capacity expansions and long‑term supply agreements aimed at securing demand from fast‑growing anode and graphite anode plants.
-
GrafTech International (Brooklyn Heights, Ohio) — an example of vertical integration where a proprietary plant supplies electrode production, and product innovation emphasizes lower‑CO2 variants incorporating recycled feedstocks to service low‑emissions steelmaking customers.
-
ENEOS, Petrocokes Japan (Sumitomo group), Mitsubishi Chemical, POSCO MC, and C‑Chem — regional leaders with a mix of petroleum‑ and coal‑tar‑based capabilities. These players are strategically important for their access to regional feedstocks, downstream relationships with battery manufacturers, and joint ventures that bridge technology and capacity.
Recent corporate developments in late‑2025 and early‑2026 — such as multi‑hundred‑million dollar capacity expansions, multi‑year supply contracts for anode projects, and product launches that claim lower carbon intensity — validate the strategic moves we have modeled in our scenarios. These dynamics create both risks and pathways for new entrants, incumbent producers, and downstream integrators.
What the PW Consulting Needle Coke Market report contains (practical, implementable outputs)
Our full study is action‑oriented and designed to support boardroom and operational decisions in 2026. Key deliverables include:
-
Market sizing and multi‑scenario forecasts (base year 2025; historical 2020–2025; forecast 2026–2032) with clear assumptions and sensitivity ranges tied to EV adoption curves, EAF steel conversion rates, and feedstock availability.
-
Supply‑side intelligence: plant‑level capacity maps, utilization benchmarks, and a proprietary supply curve that ranks existing and announced capacity by feedstock type, quality profile, and carbon intensity.
-
Demand modelling: build‑out paths for graphite electrode and battery anode demand under multiple EV manufacturing scenarios, including explicit linkage of material grades to downstream conversion yields.
-
Price drivers and scenario analysis: modeled impacts of refinery outages, feedstock price swings, and tariff shocks on mid‑cycle spot and contract pricing, with hedging toolkits and suggested contract structures.
-
Competitive and partnership playbooks: company profiles, capability matrices, M&A screens, and JV design templates tailored to integrate feedstock security, low‑carbon claims, and regional supply needs.
-
Operational checklists: capex staging recommendations, ramp‑up risk mitigation plans, and quality control protocols to align product output with high‑value downstream specifications.
-
Regulatory and trade risk register: geographies and policies to monitor, impact matrices, and contingency plans for tariff or import restriction scenarios.
Note: this preview omits segment‑level revenue breakdowns and regional/application shares — these are available in the full report to preserve strategic value for subscribers and clients.
How strategic teams should use this study in 2026
-
Portfolio prioritization: Use our supply‑curve and demand scenarios to rank projects by NPV under multiple price and policy scenarios. Identify projects that require acceleration versus those that should be deferred or structured as flexible tolling arrangements.
-
Procurement and contracting playbook: Align purchasing teams with suggested contract templates and timing triggers to secure feedstock quality and volume without overpaying during cyclical peaks.
-
M&A and partnership screening: Apply our M&A criteria and scorecards to identify targets that close strategic gaps — whether feedstock access, geographic reach, or low‑carbon credentials.
-
Operational readiness: Implement our ramp‑up checklists for new capacity, and stress‑test supply chains against the maintenance and outage patterns we observed in early 2026.
Risk checklist — top items to watch in 2026
-
Short‑term supply shocks from refinery maintenance scheduling, which can precipitate price spikes during critical battery and EAF production windows.
-
Trade policy volatility that may abruptly alter the economics of importing synthetic or natural graphite materials, incentivizing reshoring or long‑term domestic supply commitments.
-
Feedstock quality disruptions that raise yield losses in downstream anode conversion or electrode manufacture, impacting delivered unit economics.
-
Failure to articulate credible low‑carbon credentials, which risks exclusion from premium offtake agreements as downstream buyers codify ESG thresholds into procurement.
Conclusion — the strategic value for 2026 decisions
In 2026, needle coke is no longer a niche commodity for carbon specialists; it is a strategic raw material sitting at the intersection of electrification, steel decarbonization, and geopolitics. Our base‑year analysis (2025) and market projection to 2032 — guided by a 5.0% CAGR under the base case — provide executives with the quantitative foundation to model exposure, prioritize investments, and design resilient supply chains.
If your organization is preparing capex approvals, negotiating multi‑year offtakes, evaluating acquisitions, or refining procurement and ESG strategies in 2026, the full PW Consulting Needle Coke Market report contains the operational detail, scenario models, and tactical playbooks you will need. This preview deliberately holds back segment‑level tables and granular regional/application breakdowns — those elements are available in the complete report to ensure clients retain competitive advantage.
Next steps
-
Contact PW Consulting to schedule a one‑hour briefing where we will walk through tailored scenarios for your portfolio, and provide a roadmap for implementing our recommendations into 2026 planning cycles.
-
Download the full report for plant‑level supply mapping, contract templates, price‑sensitivity matrices, and the proprietary dataset that underpins the forecasts.
For detailed analysis of this topic, please visit the official page: Needle Coke Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Coil Coatings Market to reach USD 5,584M by 2032 at 4.81% CAGR (2026-2032)
By PW Consulting, 2026-07-08
Coil Coatings Market: Strategic Briefing for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a targeted executive introduction to our comprehensive Coil Coatings Market study (base year: 2025; historical window: 2020–2025; forecast: 2026–2032). This briefing distills the study’s strategic value for 2026 planning cycles—highlighting structural market movement, competitive dynamics, regulatory and technology inflection points, and the practical, decision-ready outputs that clients will find indispensable. The full dataset and drill-downs are available on our report page for teams needing transaction-level intelligence and segment-level sensitivities.
Coil Coatings Market
Why this market matters in 2026
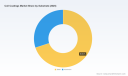
The coil coatings market is in a steady growth phase underpinned by durable demand from building & construction, industrial manufacturing, and household appliances. On a macro scale, the market expanded from a 2020 base into a 2025 market size (base year) and is projected to continue growing through our 2026–2032 forecast horizon at a compound annual growth rate (CAGR) of 4.81% (USD Million basis). Under our central case, the global market moves from a mid‑2020s base (reported in USD Million) toward a materially larger market by 2032, reflecting both volume growth and the premiumization of higher‑performance, low‑emission coating systems.
Coil Coatings Market
Interpreting the growth signal
- Growth is broad-based but uneven: macro demand drivers (urbanization, renovation cycles, energy-efficiency retrofits) support recurring demand while pockets of accelerated adoption are driven by regulatory and sustainability requirements.
- Premiumization is real: energy-curable chemistries, chromate‑free systems, and more durable resin families are commanding value capture that outstrips simple volume growth—making product mix as important as tonnage for 2026 planning.
- Industry structure favors scale plus specialization: concentration metrics indicate a competitive market where global leaders coexist with strong regional and niche players—creating both consolidation opportunities and carve-out targets for disciplined acquirers.
Market dynamics: raw materials, regulation and technology
Three dynamics will shape decisions through 2026 and beyond:
Coil Coatings Market
- Raw material volatility: Upstream feedstocks—polymers, pigments (notably titanium dioxide), and specialty resins—remain the primary margin lever. Recent supply-side shocks (output cuts and power shortages in key producing regions) have produced quarter-to-quarter oscillations that affect both procurement strategies and short‑term pricing. Effective hedging and longer-term supplier contracts are no longer optional for manufacturers seeking stable margins.
- Regulatory tightening and chemistry migration: There is an industry-wide push to low‑VOC and chromate‑free chemistries, particularly where coatings interact with building and automotive standards. This trend is forcing formulators to invest in reformulation programs, certification processes, and documentation to meet increasingly stringent environmental requirements—creating winners among firms that can accelerate validated, compliant offerings to market.
- Energy‑curable and renewable-driven curing: EB and UV curing technologies are maturing as both performance and sustainability levers. Compared with thermal cure systems, energy‑curable routes reduce energy consumption, water use, and CO2 emissions in production—opening operational cost savings and sustainability credentials that are resonating with OEMs and specifiers.
Competitive landscape: what the leading players are doing
The market is populated by multinational coatings leaders, specialty formulators, and regionally dominant suppliers. Notable strategic activities to watch include:
- Beckers Group (Germany): Focused on advanced sustainable coil systems with a high proportion of sales dedicated to building & construction and industrial applications. Their investments in a Sustainable Innovation Center and partnerships to commercialize EB-cured solutions demonstrate a two‑pronged play: technology leadership plus customer co‑development.
- PPG Industries (United States): Innovating around energy‑curable product lines and low‑emission chemistries—efforts like the DuraNEXT energy‑curable portfolio reflect a broader industry pivot to faster, cleaner curing platforms that improve line productivity and carbon profiles.
- The Sherwin‑Williams Company (United States): Expanding via strategic European acquisitions and capability additions to broaden their coil extrusion and protective coatings footprint—an M&A-led approach to fill capability gaps and accelerate entry into adjacent regional markets.
- AkzoNobel, Nippon Paint, BASF, Axalta and leading regional players: These firms are leveraging portfolio breadth (resins, additives, formulated systems) or specialty materials to provide integrated solutions. BASF’s upstream resin and additive position means they influence formulation economics and performance trade-offs; AkzoNobel’s brand-led offerings emphasize architectural and low‑VOC systems.
- Regional champions (Kansai, KCC, JSW, Yung Chi): These firms combine local production scale with targeted export strategies—serving customers who balance cost with compliance and delivery lead times.
Recent company moves—product launches in energy‑curable systems, capability‑building acquisitions, and strategic partnerships with steel producers—highlight a market where technology differentiation and vertical collaboration are accelerating. For 2026, a winning strategy will likely combine R&D investments in sustainable chemistries, secured upstream supply, and selective inorganic expansion to plug distribution or manufacturing gaps.
What PW Consulting’s report delivers (practical, actionable content)
Our full study was designed as a decision tool for 2026 strategic planning, M&A screening, and operational playbooks. Key deliverables include:
- Scenario-based demand models: Probabilistic forecasts through 2032 that allow you to stress-test volumes and pricing under alternative macro, raw material, and regulatory scenarios.
- Price & margin sensitivity matrices: Analyze how feedstock swings and product‑mix shifts affect EBITDA at plant and corporate levels—critical input for procurement and commercial negotiation strategies.
- Technology ROI calculators: Benchmarks for EB/UV adoption versus traditional thermal cure lines, including payback windows that incorporate energy costs, throughput, and sustainability benefits.
- Supplier and competitor scorecards: Multi-dimensional assessments of capability, geographic footprint, product breadth, and go‑to‑market strength—useful for partnerships, joint ventures, or carve‑out targets.
- Commercial playbooks: End‑use specific go-to-market strategies (channel models, specification engagement, value-based pricing) for building & construction, appliances, and industrial customers.
- M&A due‑diligence toolkits: Standardized checklists, integration risk checkers, and synergy templates tuned to coil coatings transactions.
- Regulatory and compliance compendium: A practical guide to emerging low‑VOC and chromate‑free requirements across major markets, and the certification pathways that buyers will expect in 2026.
Strategic imperatives for 2026 planning
Based on our analysis, decision-makers should prioritize the following actions in 2026:
- Lock in raw material access and diversify supplier risk: Implement multi‑tier sourcing and strategic hedges for pigments and specialty resins to protect margins against quarter‑to‑quarter shocks.
- Accelerate adoption or partnership around energy‑curable platforms: Evaluate EB/UV investments not just on direct OEE gains but on their role in decarbonization and customer procurement hurdles.
- Move up the value chain through formulation IP: Differentiate with low‑VOC, long‑life coatings that command premium pricing and reduce warranty exposure.
- Be selective on M&A: Target assets that fill capability gaps (e.g., regional footprint, EB‑curing capability, upstream resin relationships) rather than aggregating volumes alone—our CR metrics point to room for consolidation but also to persistent fragmentation that favors focused acquirers.
- Embed sustainability into commercial value propositions: Buyers increasingly specify cradle‑to‑gate footprint; suppliers who can document energy, water, and carbon reductions will win specification** lead**s.
How to deploy this research in 90 days
We designed practical, short‑cycle workstreams aligned to the needs of C‑suite and business unit leaders:
- 90‑day procurement fast track: Use our price sensitivity matrices and supplier scorecards to renegotiate tier‑1 contracts and stabilize margins.
- Product roadmap sprint: Run a 60–90 day go‑to‑market pilot for an energy‑curable product line with a selected OEM partner using our ROI calculator and field validation templates.
- M&A screening blitz: Apply our diligence checklist to a prioritized shortlist of targets and produce a 30‑day valuation and integration thesis for the executive committee.
Closing: the strategic premium of granular intelligence
The coil coatings space is moving from a commodity posture toward a differentiated, sustainability‑led market. For 2026, success will be defined by the firms that convert macro tailwinds and regulatory pressure into defensible product premium and operational edge. PW Consulting’s report combines market‑level trajectory (CAGR and USD Million market sizing across our historical and forecast windows), competitive intelligence, and pragmatic tools to convert insights into executable strategy. We intentionally present synthesis and frameworks here—core segment-level cells, supplier deep dives, and transaction-ready datasets are gated on the full report page to preserve the tactical intelligence that drives commercial advantage.
PW Consulting stands ready to help translate this research into tailored growth programs, M&A diligence, and operational transformation roadmaps. Access the full study for the detailed tables, scenario files, and supplier models that enable decisive action in 2026.
For detailed analysis of this topic, please visit the official page: Coil Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EMD Market to Hit USD 321M by 2032, Growing at 7.44% CAGR
By PW Consulting, 2026-07-08
Electrolytic Manganese Dioxide (EMD) Market — 2026 Strategic Preview
PW Consulting presents a forward-looking briefing on the Electrolytic Manganese Dioxide (EMD) market built to inform executive decision-making in 2026. This is a high-fidelity, practitioner-focused “trailer” designed to demonstrate the depth of our analysis and to surface the strategic questions every C-suite and deal team should be asking today. To preserve the commercial value of our full study, we deliberately withhold granular segment-level tables and provider-specific volumes in this preview — the full dataset and modeling are available in the complete report.
Electrolytic Manganese Dioxide (EMD) Market
Market trajectory at a glance
The EMD market is recovering from cyclical pressures and repositioning itself as a growth-facing specialty-materials sector. On an aggregate basis, our market model shows steady expansion from the 2025 base year, with a compound annual growth rate (CAGR) of approximately 7.44% across the 2026–2032 forecast window. That growth trajectory translates into a materially larger total market by 2032, reflecting a combination of end-market demand for higher-purity battery grades, incremental industrial applications, and product substitution dynamics.
Electrolytic Manganese Dioxide (EMD) Market
Historical performance (2020–2025) signals two important structural characteristics: (1) resilience to short-term commodity cycles as battery-related, high-purity EMD commands premium pricing; and (2) an emerging bifurcation between legacy primary-battery demand and new high-performance grades tailored to rechargeable chemistries. These dynamics underpin the forecasted growth and, crucially, the shape of the opportunity set for 2026 strategic choices.
Electrolytic Manganese Dioxide (EMD) Market
Why this study matters for 2026 strategic decisions
- Procurement and sourcing optimization: Buyers must reconcile near-term tariff and trade noise with medium-term supply tightening in high-purity grades. Optimizing contracts, multi-sourcing strategies and hedging approaches in 2026 will materially impact cost of goods sold through 2027–2029.
- Capex and capacity planning: Producers evaluating new electrolytic lines or retrofits need to align greenfield and brownfield investments with the forecast growth profile and grade shifts. Our report provides stepwise scenario models that translate demand growth into required capacity under differing conversion and yield assumptions.
- M&A and partnership playbook: The consolidation window for strategic bolt-ons — especially for players aiming to secure battery-grade feedstocks or to enter non-China supply corridors — will be defined in 2026. The report identifies attractive deal archetypes and valuation sensitivity to raw-material and regulatory risk.
- Pricing strategy and contract design: Integrated suppliers and traders should redesign contracts to reflect quality differentials, energy-intensity premiums, and volatility linked to manganese ore cycles. We provide contract templates and escalation clauses tied to clear indices and events.
- Regulatory and trade risk management: With evolving antidumping reviews and tariff actions, corporate compliance and geopolitical scenario planning are now core components of commercial strategy. The right set of contingency plans reduces both operational and reputational exposures.
Key market dynamics to watch in 2026
- Feedstock and cost pass-through: Manganese ore remains the critical upstream input. Supply moves in steel-centric markets — particularly those driven by Chinese infrastructure cycles — continue to create episodic price swings. These swings transmit to EMD production costs with varying lag depending on feedstock contracts and inventory practices.
- Trade policy and antidumping scrutiny: Recent policy actions have increased trade risk. Notably, additional ad valorem tariffs on some EMD imports and ongoing antidumping sunset reviews in the United States are elevating the risk of trade interruptions or abrupt price adjustments for U.S.-facing supply chains. These developments necessitate proactive sourcing diversification and duty-mitigation strategies.
- Capacity and quality competition: Several new investments and partnerships in 2024–2025 increased available volumes of battery-grade and high-purity EMD. Simultaneously, producers are commercializing less energy-intensive manufacturing routes for new grades. The result is a two-track competitive dynamic: cost leaders defending volume contracts, and premium suppliers capturing high-value rechargeable-battery demand.
- ESG and decarbonization pressure: Battery customers increasingly demand lower-emissions input materials. Process electrification, renewable energy sourcing, and lower-carbon manufacturing claims are becoming procurement differentiators.
Recent industry developments (signals)
- Aug 2025 — GEM Co Ltd announced a capacity expansion targeted at meeting battery-sector demand in Asia.
- Sep 2025 — Manganese Metal Company entered a strategic supply partnership with a leading battery manufacturer to deliver high-purity EMD.
- Jul 2025 — Tianjin Dingsheng unveiled an environmentally friendlier EMD grade produced via a less energy-intensive process.
- Regulatory timeline — Throughout 2025–2026, U.S. trade authorities advanced reviews and tariff measures tied to EMD imports, reinforcing the need for companies to integrate trade contingencies into commercial planning.
Competitive landscape — what the market structure means
The EMD supply base remains fragmented relative to many other battery-material value chains. Market-concentration metrics indicate a moderate share held by the largest firms, with the three- and five-firm concentration ratios reflecting room for both regional champions and new entrants to influence pricing and specification standards.
- Tosoh Corporation — A global supplier with established facilities in Japan and Europe and a reputation for battery-grade EMD. Its integrated footprint and global customer relationships make it a bellwether for premium-grade supply and industrial best practices.
- Vibrantz Technologies — Focused on high-purity, battery-grade production with a multi-site global footprint; well-positioned on quality-sensitive rechargeable markets.
- Borman Specialty Materials — A key non-China producer supplying both battery and industrial EMD demand, relevant to buyers seeking alternative supply corridors.
- Guizhou Redstar, CITIC Dameng, Xiangtan (China-based players) — These firms represent domestic-scale production depth and continue to drive technology iteration and cost improvements in China’s value chain.
- MOIL Limited — The notable domestic producer in India with strategic importance for local battery manufacturers and for regional import substitution strategies.
- Cegasa (Spain) and Manganese Metal Company (South Africa) — Provide European and southern-hemisphere supply options, respectively, often serving quality- and sustainability-sensitive buyers.
For buyers and investors, the distribution of global capacity implies meaningful room for competitive advantage through sourcing optimization, grade-specific contracts, and selective downstream integration.
What our full report delivers (practical content)
PW Consulting’s comprehensive EMD market study is structured to be immediately actionable for decision-makers. The full report includes:
- Proprietary demand model (2020–2032) with scenario toggles for grade mix, battery adoption curves, and industrial demand elasticity.
- Supply-side capacity map and build-out scenarios, including detailed commissioning timelines and regional supply-risk indicators.
- Supplier scorecards with technology, quality, ESG, and commercial-readiness assessments (proprietary scoring system).
- Pricing and margin models with sensitivity analyses to ore-price shocks, energy-cost swings, and tariff scenarios.
- M&A and partnership framework identifying attractive targets, valuation benchmarks, and integration risk matrices.
- Contract templates and procurement playbooks tailored to primary-battery, lithium-ion, and industrial customers.
- Regulatory-impact simulations incorporating ongoing antidumping reviews and tariff pathways.
These deliverables are purpose-built to convert market intelligence into boardroom decisions — from negotiating long-term offtakes to sizing brownfield investments to designing risk-mitigating trading strategies.
Recommended 2026 actions — a short playbook
- For battery manufacturers: Reassess grade-specific supply commitments and negotiate flexible offtake clauses that preserve optionality as lithium-ion chemistries evolve.
- For EMD producers: Prioritize quality differentiation and energy-efficiency investments; fast-followers should evaluate strategic partnerships to secure feedstock and capture downstream margin.
- For traders and distributors: Invest in quality assurance and logistics offerings that shorten time-to-market for premium grades; structure hedges for tariff exposure.
- For private equity and corporates: Use 2026 to pre-position for consolidation opportunities; prioritize targets with differentiated technology, captive feedstock or strategic customer contracts.
- For policymakers and industrial planners: Consider the strategic implications of localized EMD capacity for battery value-chain resilience, and calibrate trade policy to balance domestic industry growth with global supply-chain stability.
Concluding perspective
The EMD market in 2026 is at an inflection point — moving from a predominantly commodity-oriented base into a more nuanced, grade-differentiated specialty market shaped by battery electrification, regulatory shifts, and an intensifying focus on production footprint and emissions. The next 12–24 months will determine which players scale profitably and which will be marginalized by changing quality requirements and trade dynamics.
PW Consulting’s full EMD study provides the quantitative backbone and the tactical playbooks required to navigate that transition. For executives building strategy for 2026 and beyond, the difference between reacting and leading will depend on access to granular scenario outputs, supplier assessments, and contract-level instruments — elements we reserve for the complete report.
Contact PW Consulting or visit our report page to obtain the full dataset, proprietary models, and the actionable recommendations that will shape smart decisions in 2026.
For detailed analysis of this topic, please visit the official page: Electrolytic Manganese Dioxide (EMD) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
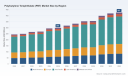
Polybutylene Terephthalate (PBT) Market — A Strategic Briefing for 2026 Decision-Makers
As organizations plan capital allocation, sourcing strategies, and product roadmaps for 2026, understanding the trajectory of the Polybutylene Terephthalate (PBT) market is essential. PW Consulting’s latest market study — anchored on a 2025 base year and projecting through 2032 — shows a resilient growth profile (CAGR of 5.2% across 2026–2032) and a clear inflection from a mid-cycle recovery into a structurally growing market. This briefing summarizes the strategic implications of that trajectory and highlights the operational intelligence executives need now; detailed segment tables and proprietary models are reserved for the full report.
Polybutylene Terephthalate (PBT) Market
Market snapshot and what it means for strategy
PBT’s addressable market has expanded meaningfully since the start of the decade, reflecting steady end-market demand and renewed investment by major producers. On a consolidated basis, the market has grown from the mid-hundreds (USD Million) at the start of the decade to a 2025 base that underpins our forward-looking scenario set; under the central forecast the industry reaches a materially larger size by 2032. That path — underpinned by a 5.2% CAGR for the forecast period — signals that PBT will remain an attractive segment for differentiated polymer players and downstream compounders targeting higher-margin engineered applications.
Polybutylene Terephthalate (PBT) Market
For leadership teams, the implications are straightforward: plan for growth, but plan differently across value chain roles. Producers face both opportunities (premium grade development, regional capacity optimization) and risks (feedstock volatility, regulatory compliance). Downstream customers and compounders must reassess supplier footprints, validate high-performance grades for electrification and E&E applications, and accelerate qualification cycles.
Polybutylene Terephthalate (PBT) Market
Dynamics shaping near-term (2026) choices
- Demand catalysts: Electrification in transportation, increasing electronic content per vehicle, and ongoing growth in electrical & electronics markets are steady demand pillars. These trends favor higher-performance PBT grades with proven thermal and electrical properties.
- Feedstock environment: The primary feedstock, 1,4-butanediol (1,4-BD), exhibited generally weak price movement in Asia during 2025 due to downstream oversupply — a force that can temporarily improve margins for polymer makers but also encourages opportunistic capacity additions.
- Regulatory and compliance headwinds: New and expanding chemical regulations — notably provisions restricting certain persistent, bioaccumulative and toxic substances — are changing additive selection and formulation roadmaps, with compliance timelines extending into 2026 and beyond. This requires product stewardship and early reformulation strategies.
- Trade and pricing dynamics: Regional trade measures (including tariffs on Asian-sourced resins affecting North America in 2025) and supplier-level price actions (e.g., engineered materials price adjustments announced in 2026) are raising the premium on supply-chain resilience and contractual protections.
What the report delivers — actionable, not academic
PW Consulting’s PBT market study is structured to inform operational and strategic choices across five categories of client need. The deliverables are practical: market sizing and validated demand curves (historical 2020–2025 and forecast 2026–2032); a supply-side atlas of capacities and utilization dynamics; a feedstock and cost pass-through model; regulatory impact matrices; and a scenario-driven strategic playbook.
- Quantified market sizing and rigorous forecasting methodology (base year 2025, multiple scenarios across 2026–2032).
- Supply-side diagnostics: plant-level capacity analysis, utilization trends, and likely bottlenecks under defined demand scenarios.
- Raw material and pricing intelligence with hedging levers and supplier negotiation tactics.
- Regulatory & compliance roadmaps, including TSCA-driven reformulation risks and recommended mitigation measures.
- Competitive positioning templates, supplier scorecards, and M&A screening frameworks focused on the PBT value chain.
Note: while the study provides comprehensive segment-level insights, this briefing intentionally omits proprietary subsegment tables and region/application breakouts — those data are available in the full report and client appendices.
Competitive landscape: incumbent advantages and disruptive threats
The market is characterized by a mix of large, diversified chemical majors and specialized compounders. Measured concentration metrics indicate that the top three and top five firms hold a meaningful but not dominant share of global supply — a structure that enables both cooperative and competitive strategic moves:
- CR3 and CR5 concentration indicators point to a sector with clear market leaders yet sufficient fragmentation for nimble players to pursue regional or product-focused growth strategies.
- Incumbent multinationals maintain competitive advantages through global asset footprints, broad product portfolios, and customer trust in established brand grades and certifications (e.g., UL, VDE, medical and food-contact clearances).
- Mid-sized compounders and regional producers can compete on speed-to-market, customized formulations, and close integration with OEMs.
Representative company profiles illustrate these dynamics:
- BASF SE — A global integrated player with established PBT branded systems and announced capacity expansions in India aimed at capturing regional demand growth; their positioning combines base resin production with compound capabilities.
- Celanese Corporation — A technology-focused producer offering recognized branded PBT grades with multiple regulatory approvals; recent pricing actions underscore its role in shaping market pricing dynamics for engineered materials.
- DuPont de Nemours, Inc. — A major supplier of PBT resins and compounds with a track record in automotive and healthcare markets, including high-CTI (comparative tracking index) grades suited to electrical insulation needs.
- Evonik Industries AG — Provides licensed PBT compounds designed for direct food and medical device contact, illustrating how regulatory credentials can create higher-value niches.
- LANXESS AG — Focused on compound solutions for electrical/electronics, automotive and e-mobility, demonstrating the role of specialized compound portfolios in higher-growth applications.
Recent developments and short-term watchlist (to inform 2026 decisions)
- Supplier-level capacity actions: regional capacity build-outs (notably in India) are changing regional supply dynamics; executives should model localized oversupply vs. export push scenarios.
- Commercial strategy moves: engineered materials price increases announced for 2026 reflect attempts to recover margin and manage feedstock pass-throughs; buyers should reassess contracting windows and indexation clauses.
- Regulatory compliance: new restrictions on certain additives require near-term product stewardship interventions — reformulation timelines and testing budgets must be prioritized.
- Trade measures: tariffs and trade policy shifts will continue to influence regional competitiveness and logistics costs; scenario planning for alternative sourcing corridors is recommended.
Strategic imperatives for 2026 by role
- Producers (integrated & merchant resin makers): Prioritize selectivity in capacity additions — favor specialty grades and compounding capabilities over broad commodity expansion. Secure feedstock arrangements with flexible terms and invest in compliance-ready additive portfolios.
- Compounders & Masterbatchers: Accelerate R&D on high-performance, compliant formulations (food/medical, high-CTI, flame-retardant without restricted additives). Invest in qualification pipelines with OEMs to shorten lead times.
- OEMs (automotive, E&E, consumer appliances): Diversify supplier base and qualify redundant sources to mitigate tariff and supply disruptions. Update specification frameworks to account for regulatory-driven ingredient substitutions.
- Investors & M&A teams: Evaluate consolidation plays among mid-tier compounders and assess bolt-on opportunities that provide regulatory certifications or regional manufacturing footprints.
Scenario planning and the levers that move outcomes
Our scenario framework shows that the market outlook is sensitive to four primary levers: feedstock price trends, regulatory tightening (especially additive restrictions), pace of automotive/electronics electrification, and trade policy shifts. Executives should run decision trees that stress-test capital projects, pricing models, and supplier contracts against combinations of these levers. The full report includes a ready-to-deploy scenario model with sensitivity matrices for margin, utilization and NPV impacts under alternate assumptions.
Why PW Consulting’s PBT study should be in your 2026 planning toolkit
- Proprietary synthesis of market-sizing data, plant-level supply mapping and credible demand drivers — calibrated to a 2025 base and extending through 2032 with a 5.2% CAGR central view.
- Action-oriented recommendations and implementation playbooks that translate insight into procurement clauses, R&D roadmaps, and M&A screening criteria.
- Regulatory and feedstock risk assessment that connects compliance timing with product and procurement decisions.
- Competitive benchmarking and supplier scorecards enabling rapid prioritization of strategic partners.
This briefing has intentionally showcased the kind of analysis and strategic framing you can expect from our full study while withholding proprietary segment-level tables and granular regional/application breakdowns. Those subsegment insights — critical for procurement tenders, capex approvals, and SKU-level margin modeling — are included exclusively in the full Polybutylene Terephthalate (PBT) Market report.
For teams preparing 2026 budgets, supplier strategies, or investment memoranda, PW Consulting’s PBT study provides the scenario-tested intelligence necessary to move from insight to action. Access to the full dataset and modelling workstreams is available through our report portal and advisory services; contact our industry team to arrange a briefing tailored to your decision timetable.
For detailed analysis of this topic, please visit the official page: Polybutylene Terephthalate (PBT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Zinc Oxide Market to Reach USD 7,766.25M by 2032 with 5.3% CAGR — PW Consulting Insight
By PW Consulting, 2026-07-08
Zinc Oxide Market: Strategic Outlook for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused briefing designed to orient executive teams and investment committees contemplating moves in the zinc oxide value chain during 2026. This preview synthesizes the market’s macro trajectory, competitive dynamics, regulatory and sustainability pressures, and the practical, decision‑grade tools the full Zinc Oxide Market report delivers. The intent is to demonstrate analytical depth and actionable insight while preserving the granular segment intelligence contained in the full study — the information you will need to execute transactions, capital projects, or product launches with confidence.
Zinc Oxide Market
Macro snapshot: Where the market stands and where it’s headed
Using 2025 as the base year, our historical analysis (2020–2025) captures a steady recovery and re‑rating of zinc oxide demand across industrial and specialty applications. The global zinc oxide market expanded through the first half of the decade and reached an inflection point in 2025. Looking forward, our scenario‑based forecasting (2026–2032) projects a compound annual growth rate (CAGR) of 5.3% under a baseline macro scenario, reflecting continued industrialization, premiumization in personal care, and emerging battery-related demand.
Zinc Oxide Market
What this means operationally: executives should expect demand to strengthen in the medium term but with episodic price volatility driven by feedstock and processing cost swings. Our base‑case forecast provides year‑by‑year topline trajectories and alternative scenarios that illustrate upside from accelerated electrification or downside from regulatory constraints in key feed applications.
Zinc Oxide Market
Why this matters for 2026 decision cycles
- Capital allocation timing: At a moderate CAGR, returns on new greenfield projects are sensitive to commissioning timing and cost discipline. Small shifts in start‑up schedules or raw material pricing materially change IRR profiles in the zinc oxide business.
- Product strategy: Demand is bifurcating between commodity industrial grades and higher‑margin specialty grades (high‑purity, nano, pharma/food). Firms that can credibly convert R&D into commercially scaled specialty products capture structural margin uplift.
- Supply risk and price backdrop: Early‑2026 price moves signaled tightening supply and rising production costs. Firms without secured feedstock or flexible tolling/contracting options face margin pressure during episodic price spikes.
- Regulatory and reputational exposure: Zinc oxide remains permitted in critical regulated uses (for example, certain cosmetic and pharmaceutical applications), while prior regulatory actions on agricultural/animal‑feed uses in some jurisdictions underscore execution risk for firms dependent on those channels.
Dynamics shaping strategy in 2026
- Raw material and cost pressures: Price escalation observed in Q1 2026 underscores the need for granular cost‑to‑serve models and flexible procurement strategies.
- Regulatory landscape: Continued inclusion of zinc oxide in recognized regulatory lists for food and topical pharmaceutical use preserves important end‑market windows, but prior restrictions on veterinary applications in jurisdictions such as the EU/UK highlight the need for regulatory scenario planning.
- Sustainability and low‑carbon production: European initiatives to scale biomass‑powered refining demonstrate both a technology pathway and a market signal: customers and regulators increasingly value low‑carbon metal‑chemical supply. This creates first‑mover advantage opportunities for producers investing in decarbonized processes.
- Market structure: The industry remains fragmented: a broad set of regional and specialty producers compete alongside a smaller cohort of firms investing in high‑value formulations. Fragmentation creates acquisition and partnership opportunities for firms pursuing scale or technical leadership.
What the PW Consulting report delivers — operationally focused content
The full Zinc Oxide Market study is engineered to inform executable decisions, not just to describe the market. Key deliverables include:
- Integrated demand model: A bottom‑up demand model spanning 2020–2032 with alternative scenarios (baseline, accelerated electrification, regulatory contraction) and sensitivity levers you can adjust to test bespoke company assumptions.
- Supply and capacity mapping: Facility‑level mapping (process route, grade capabilities, start‑up timelines) and an operational capacity utilization model designed to stress‑test greenfield and brownfield investments.
- Price and cost curve analysis: Forward price decks under multiple macro permutations, and detailed cost curves by process type to identify sustainable margin bands and break‑even thresholds for new projects.
- Regulatory and product compliance framework: A checklist of jurisdictional requirements for food, pharmaceutical and personal care uses, including practical compliance pathways and timeframes for certification.
- Sustainability playbook: Technical and commercial assessment of low‑carbon production routes, capex/break‑even case studies, and supplier selection criteria for renewable feedstocks and energy inputs.
- Commercial and go‑to‑market toolkits: Offtake contracting templates, pricing negotiation playbooks, and guidance for moving from sample commercialization (e.g., nano formulations) to scalable supply agreements.
- M&A and partnership screening model: A scoring framework tailored to the zinc oxide value chain that evaluates target fit across technology, feedstock access, regulatory exposure, and logistics risk.
Competitive landscape — strategic implications (select players)
The market is populated by a mix of regional champions, specialty innovators, and integrated chemical groups. Several strategic archetypes emerge:
- Regional market leaders with process mastery: Firms that operate legacy French‑process plants and serve industrial demand benefit from deep customer relationships in rubber, ceramics and chemicals. Their strength is scale and reliability in commodity supply, but they face margin erosion unless they capture higher added‑value niches.
- Specialty innovators: Companies commercializing high‑purity and nano grades are positioned to capture premium pricing in cosmetics, premium sunscreens, and emerging battery chemistries. Successful commercialization requires tight quality control and clear regulatory positioning.
- Fast‑growing domestic producers: Producers in high‑growth regions continue to expand capacity to meet local industrialization needs, often supported by favorable feedstock economics and proximity to end‑markets.
- Decarbonization pioneers: Firms investing in low‑carbon refining and biomass integration are creating differentiated product claims that open procurement conversations with OEMs and formulators focused on Scope 3 emissions.
Representative strategic moves observed through 2025–2026 underscore these archetypes. Notable activities include a large greenfield project approval in India targeting significant zinc chemicals capacity (expected to begin operations in the near term), the commercialization acceleration of a high‑transparency nano zinc oxide product for premium suncare, and a European scale‑up of biomass‑powered refining to produce low‑carbon zinc oxide. Collectively, these moves signal that capacity additions will be targeted, often technology‑led, and geographically strategic.
Key strategic questions for leadership teams in 2026
- Should we prioritize capacity expansion for commodity industrial grades or allocate capital to scale specialty, higher‑margin grades?
- Can we secure feedstock and tolling relationships that de‑risk price volatility, or should we pursue vertical integration into upstream zinc intermediates?
- Is there a viable route to differentiate on low‑carbon credentials that customers will pay for, and what is the expected payback period for biomass or electrified process investments?
- Which regulatory scenarios pose the greatest commercial risk to our portfolio, and how should we hedge those risks through product diversification or geographic exposure?
- Where do M&A or offtake partnerships deliver the fastest path to scale and technical capability, and what are the realistic valuation ranges for attractive targets?
How the full report supports execution
The complete PW Consulting Zinc Oxide Market report includes the datasets, models, and decision templates necessary to convert these strategic questions into executable plans. Subscribers receive editable financial models, scenario dashboards, and a prioritized list of actionable next steps tailored to three corporate archetypes: incumbent industrial producer, specialty chemical developer, and new entrant/financial sponsor. To respect the need for confidentiality and to maintain the value of the proprietary segment analytics, the preview you are reading intentionally omits granular regional and application split figures — these are provided in the subscriber materials along with source‑level verification.
Immediate priorities for 90‑day action plans
- Run the supply‑side stress test included in the report to evaluate how a 6–12 month increase in feedstock costs alters cashflow under different product mixes.
- Initiate technical validation projects for any nano or high‑purity grades you intend to commercialize; fast‑track regulatory certification planning early to avoid time‑to‑market delays.
- Engage sustainability engineering partners to produce a high‑level decarbonization roadmap and an investment case for biomass or electrification pilots.
- Screen strategic partnership targets using the M&A scoring framework to identify candidates offering immediate scale, feedstock access, or specialty know‑how.
PW Consulting’s Zinc Oxide Market report is expressly designed to convert market intelligence into defensible decisions. If your 2026 planning cycle includes capex approval, new product commercialization, or M&A activity in the zinc oxide space, the full report supplies the validated data, scenario tools, and commercial playbooks to act with clarity and speed.
For access to the full dataset, editable models, and market segmentation detail required to finalize investment or commercial commitments, please consult the source distribution channel for the complete report and subscriber resources.
For detailed analysis of this topic, please visit the official page: Zinc Oxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


