



Category: Chemical & Materials
PW Consulting: Denim Market to expand at 5.8% CAGR, reaching USD 125,602M by 2032
By PW Consulting, 2026-08-02
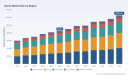
Denim Market 2026 Outlook: Strategic Imperatives for Decision‑Makers
As PW Consulting’s lead industry analyst, I present a concise strategic primer that frames the commercial and operational choices companies must make in 2026. Our Denim Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes primary interviews, proprietary models, and triangulated public data to deliver an actionable playbook for brands, mills, retailers, private equity, and input suppliers. The global denim market entered 2025 at approximately USD 85 billion (base year) and, under the structural scenarios modeled in this report, expands at a 5.8% compound annual growth rate through 2032 — reaching roughly USD 125.6 billion by the end of the forecast horizon. Those headline numbers set the context; the decisions you take in 2026 will determine whether you capture disproportionate upside or become collateral to industry consolidation and re‑positioning.
Denim Market
Why this report matters for 2026 decisions
-
It translates macro momentum into decision-ready options. We move beyond trend charts to quantify the operational, procurement, and commercial moves that unlock margin and resilience in year‑one of the new cycle.
Denim Market -
It balances near‑term tactical moves (raw material hedging, production sequencing) with medium‑term strategic choices (capex prioritization, M&A targets, go‑to‑market segmentation) that will shape market share through 2032.
Denim Market -
It provides scenario‑based risk assessments for the most disruptive variables in 2026: cotton supply volatility, regulatory tightening on chemical use and circularity, and accelerated premiumization driven by brand strategies.
Market trajectory and the forces that will shape 2026
The denim market’s mid‑decade expansion reflects a blend of persistent apparel demand, premiumization, and material innovation. After rising from a lower base through 2020–2025, the market’s path into 2026 and beyond is characterized by steady volume recovery in mature markets, faster demand elasticity in premium and sustainable segments, and incremental share gains for differentiated fabric technologies. The market’s concentration remains relatively low (top‑three firms control roughly 12.5% and top‑five about 18%), underscoring room for competitive repositioning, roll‑up strategies, and regional specialization.
Three structural dynamics matter most for 2026 planning:
-
Raw material and sourcing volatility: Cotton still constitutes the majority of denim composition globally, and observed production dynamics—both cyclical and structural—are producing frequent short windows of supply disruption. Companies must plan around cotton availability, evolving tariff regimes, and the growing emphasis on blended and alternative fibers to reduce dependency.
-
Regulatory and standards tightening: Standards bodies and certification schemes have raised the bar. Recent updates impose mandatory due diligence, stricter chemical and climate criteria, and increased circularity expectations—impacts that are already affecting procurement, compliance costs, and supplier qualification timelines.
-
Product and value‑chain innovation: From biodegradable stretch technologies to linen blends and closed‑loop finishing, the pace of fabric innovation is amplifying opportunities for premiumization and margin capture. At the same time, brands are using premium product launches to signal sustainability leadership and to validate higher price points.
Competitive landscape — how incumbents are repositioning
The denim ecosystem is a mix of vertically integrated mill groups, regional specialists, and global apparel players leaning into fabric procurement as a strategic lever. A few firm‑level themes stand out:
-
Vertical integration and scale: Large integrated producers are leveraging scale to internalize sustainability programs, accelerate recycled blends, and offer brands a single‑stop solution from yarn to finished fabric. Their scale produces negotiating leverage with brands during periods of raw material stress.
-
European technical differentiation: Several European mills focus on high‑value niches — selvedge, specialty finishes, and biodegradable stretch — creating premium product ladders that brands can monetize through limited‑edition and higher‑margin collections.
-
Strategic consolidation: Recent transactions demonstrate the industry’s appetite for consolidation that expands manufacturing footprints and global sales networks. Such moves change buyer‑supplier dynamics and create new pathway options for cross‑market distribution.
Representative strategic profiles included in the full analysis:
-
Arvind Limited – a vertically integrated producer operating at scale, increasingly focused on recycled and organic blends to service global brand partners.
-
Candiani S.p.A. – European mill with a premium, innovation‑led agenda (notably biodegradable stretch and linen blends) that targets the high‑end selvedge market.
-
Raymond UCO Denim and Nandan Denim – regional leaders emphasizing premium fabric collections and eco‑process credentials to meet growing domestic and export demand.
-
Cone Denim – a legacy U.S. mill whose recent change of ownership has broadened its international reach and manufacturing integration prospects.
-
Bextex and House of Gold – specialists delivering performance blends and custom grades that address niche brand requirements.
-
Levi Strauss & Co. – as both large fabric buyer and brand innovator, its product expansion into higher‑priced selvedge lines and rigorous supplier environmental disclosure requirements is shaping the procurement agenda industry‑wide.
Operational levers — a practical playbook for 2026
We translate the implications above into binary actions for four stakeholder groups. Below are prioritized, high‑impact moves tested against PW Consulting’s scenario models:
-
For manufacturers: Prioritize investment in low‑cost decarbonization and chemical management at scale (these reduce compliance risk and shorten supplier onboarding cycles); modularize capacity for premium vs. commodity runs; and create a short list of certified input suppliers to accelerate customer qualification.
-
For brands and retailers: Re‑engineer sourcing strategies to include hybrid sourcing (near‑shoring for agility + offshore for scale), require standardized environmental module reporting from suppliers, and pilot premium limited runs to validate price elasticity while building sustainable product credentials.
-
For investors: Target asset roll‑ups that create contiguous value chains (spinning mills through finishing) or invest in differentiation technologies (biodegradable stretch, circular finishing) that have clear payback under stricter regulatory scenarios.
-
For raw material suppliers and service providers: Offer bundled mitigation products (index‑linked cotton contracts, inventory finance, traceability as a service) to capture share of rising risk premium in the supply chain.
Concrete 12–24 month actions we recommend for priority value capture: accelerate supplier Higg/FEM compliance roll‑outs, execute small strategic capex to enable linen and recycled blends, formalize cotton‑sourcing contingencies, and launch consumer‑facing premium capsules that tie to mill‑level sustainability narratives.
What the full PW Consulting Denim Market report delivers
The full report is designed as an execution toolkit for 2026. It contains:
-
Proprietary market sizing and a verified forecast model (2026–2032) with scenario switches for raw material, regulatory, and demand shocks.
-
Competitive benchmarking and strategic scorecards for manufacturers and brands — including capability maps, go‑to‑market fit matrices, and a prioritized M&A target list.
-
Operational diagnostics: cost build‑ups for weaving/dyeing/finishing, chemical and water‑use KPIs, and plant retrofit playbooks with capex/ROI analysis.
-
Commercial playbooks for premiumization and sustainability monetization (pricing models, promotional tactics, limited‑edition rollouts).
-
Interactive sensitivity dashboards that let you stress test outcomes against cotton price spikes, tariff shifts, and faster regulatory tightening.
Importantly, to preserve the report’s standalone commercial value we have intentionally withheld granular regional and application breakdowns from this preview. The full intelligence set includes detailed splits, channel matrices, and supplier‑level volume and revenue estimates that operational teams will use to calibrate budgets and sourcing commitments for 2026.
Final note — where to focus in 2026
In an industry where material science, regulation, and brand storytelling intersect, leaders will be those who pair technical differentiation with supply‑chain resilience. Whether you are a mill upgrading finishing lines, a brand launching a premium sustainable capsule, or an investor evaluating consolidation targets, the decisions you make in 2026 about supplier qualification, capital allocation, and product positioning will compound across the forecast period.
PW Consulting’s Denim Market report is structured to convert those decisions into measurable outcomes. For access to the full dataset, segmented models, and the executable playbooks referenced above, please visit our report page or contact our advisory team to schedule a briefing based on your organization’s priorities.
For detailed analysis of this topic, please visit the official page: Denim Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Ferro Chrome Market 2026: Strategic Intelligence for Confident Decisions
As PW Consulting’s senior industry analyst, I present a concise, high-impact preview of our comprehensive Ferro Chrome Market study (base year 2025). This briefing is crafted as a strategic “trailer”: it reveals the analytical depth and decision-ready frameworks you will find in the full report while deliberately withholding granular cell-level tables and proprietary segmented data. Use this note to validate the report’s relevance to your 2026 planning cycle and to prioritise the chapters you will want to unlock for transaction work, sourcing optimisation, and portfolio strategy.
Ferro Chrome Market
Why this study matters for 2026 decisions
-
Macro clarity at a transitional inflection: the global ferro chrome market—measured on a revenue basis—has expanded steadily through the 2020–2025 period and reached a clearly defined base in 2025. Our forecast through 2032 embeds realistic demand assumptions and shows the market progressing to a materially larger size by 2032 at a compound annual growth rate of 4.28% (forecast period 2026–2032). That near‑term predictability matters when you are sizing investments, negotiating long-term offtakes, or setting capex timelines.
Ferro Chrome Market -
Concentration and competitive tension: market concentration is meaningful and creates strategic levers. The top tier of producers capture a material share of global supply, generating pricing power and supply-side flexibility that buyers and investors must explicitly model.
Ferro Chrome Market -
Policy and resource dynamics are creating bifurcated opportunity sets. Energy costs, trade measures, and raw-material controls are re-shaping competitive advantage—creating winners for incumbent integrated producers and opening niches for low-carbon and specialty product providers.
What you will gain from the full PW Consulting study
-
Actionable demand-supply models calibrated to 2020–2025 history and stress-tested across 2026–2032 scenarios. We provide a deterministic base case, two alternate demand paths and supplier-side capacity trajectories that reflect announced projects and realistic execution risks.
-
Price sensitivity and margin maps keyed to electricity and coke/coal input swings, enabling quick “what-if” analyses for procurement and price-hedging strategies.
-
Investment playbooks for greenfield smelting, brownfield upgrades, and decarbonisation retrofits—comparing IRR and payback under multiple power-cost and carbon-price regimes.
-
M&A and JV diagnostic toolkit: target-screening criteria, valuation multipliers for ferroalloys assets, and integration red flags derived from our company-level due diligence templates.
-
Supplier risk scorecards and contingency planning templates that map geopolitical, regulatory and feedstock disruption vectors to likely time-to-recovery and financial impact.
-
Commercial contracting playbook: recommended clauses for long-term offtake that balance volume security, quality baselines (carbon content, chromium equivalents), and indexation to feedstock and energy indexes.
High-level market trajectory: what the numbers tell us
Our base-year calibration and forward scenarios show a market that has recovered and consolidated following cyclical pressures earlier in the decade. The 2020–2025 historical series provides robust context for near-term trends; the forecast period (2026–2032) reflects steady expansion at a mid-single-digit growth rate (CAGR 4.28%). For executives prioritising 2026 capital allocation and supply contracts, this means predictable demand growth that can justify staged capacity additions, provided project execution and energy sourcing are de‑risked up front.
Competitive landscape: strategic implications for operators and buyers
The industry list includes fully integrated miners-and-smelters, regional champions, and stainless steel-integrated producers. Across this spectrum we observe three clear strategic archetypes and corresponding implications:
-
Integrated low-cost operators with captive ore and power. These players retain the strongest margin protections during input-price shocks and are best positioned to pursue export-driven growth or to act as swing producers during tight markets. Their strategic moves focus on capacity utilisation, mine-to-smel logistics, and securing long-term power.
-
Regionally concentrated specialists with smelting scale but limited upstream control. These firms must prioritise feedstock resilience and flexible product mixes (high-carbon vs medium/low-carbon grades) to retain market share. For buyers, these suppliers can be attractive for short- to mid-term offtakes where lead times and quality differentiation matter.
-
Stainless-steel integrated players and specialty-grade producers. Integration into downstream stainless operations creates product capture and R&D synergies—especially relevant as demand for low‑carbon and enriched-chrome grades grows. Investors should evaluate the value of proprietary alloy grades and green premium potential when assessing these targets.
Recent industry developments underscore these archetypes in action: several established producers have announced capacity restarts or expansions contingent on improved power economics; others are investing specifically in lower‑carbon product lines and pilot plants to capture premium segments.
Regulatory and raw-material context: key vectors that change player economics
-
Raw-material availability: global chromite ore production remains concentrated geographically. Changes in ore export policy, notably export restrictions by some producing countries, materially alter the upstream economics for smelters without captive ore—raising the value of integrated mining assets.
-
Trade and safeguard measures: recent trade actions and region-specific import controls are increasing transaction complexity for cross-border buyers and forcing nearer-shoring decisions for certain markets. These measures are shorter-term shocks and longer-term structural constraints—both require differentiated commercial playbooks.
-
Energy and decarbonisation: power costs and carbon policy have moved from being “cost considerations” to strategic determinants of competitiveness. Producers with captive or renewable-heavy power portfolios have clear advantage in unit cost and can credibly market lower-carbon product variants that attract premiums in stainless and specialty markets.
-
Critical-minerals policy: strategic mineral designations by consuming countries add a geopolitical layer; sourcing strategies now need to incorporate national-security screening and potential incentives for domestic processing.
Strategic priorities for executives in 2026
-
De-risk power exposure before committing to large-scale capex. Prioritise power contracts, captive renewables or grid-relief conditionality as a gating item for any new furnace or expansion.
-
Lock optionality into offtake agreements. Structure take-or-pay with flexible volume bands and quality-adjustment clauses tied to alloy grade to protect both producers and buyers against grade shifts and downstream demand variance.
-
Accelerate pilot investments in low-carbon and enriched ferrochrome grades where downstream customers signal willingness to pay green premia—this is where differentiation will matter most over the medium term.
-
Evaluate acquisitions of upstream feedstock or minority stakes in mine-to-smel projects in jurisdictions with stable ore policies to secure feedstock and reduce supply-chain volatility.
-
Build scenario-backed playbooks for rapid response to export restrictions or tariff shocks—especially for players with significant cross-border exposure.
Competitive moves to watch in 2026
-
Capacity restarts and expansions in regions where energy policy improves—these will influence pricing cycles and create windows for opportunistic procurement or short-term hedges.
-
Investments into low-carbon production by stainless steel-integrated firms and specialty alloy manufacturers—these moves will define premium product availability and create segregation in pricing structures.
-
National policy shifts affecting ore export rules or critical-minerals lists—these can create abrupt changes in commercial advantage and should be monitored continuously.
What the full report provides beyond this preview
-
Proprietary, downloadable models: fully unlocked demand-supply tables, supplier capacity build schedules, and price-sensitivity dashboards ready for “plug and play” corporate planning.
-
Segment-level analytics and dashboards: detailed regional, product-type and application segmentation with trade flows and elasticities (note: this preview intentionally omits those cell-level figures to preserve the research’s exclusive value).
-
Company dossiers with capability maps and acquisition-ready diligence checklists aligned to each major producer’s asset footprint and announced projects.
-
Operational playbooks for decarbonisation, energy optimisation and quality assurance that translate into measurable EBIT impact scenarios.
Closing—how to use this briefing in your 2026 planning
Use this note to frame the strategic trade-offs you face in 2026: growth versus resilience, vertical integration versus contractual flexibility, and premium-product development versus volume scale. The ferro chrome market’s projected mid-single-digit expansion through 2032 provides the macro upside; the differentiator for will-be winners will be supply security, energy cost management, and timely product differentiation.
For CFOs, the report’s financial templates speed decision cycles. For supply-chain leaders, the supplier risk matrices become procurement playbooks. For corporate development teams, our M&A filters and valuation comparators are ready to apply to active target lists.
Access the full PW Consulting Ferro Chrome Market study to obtain the underlying models, granular segmentation, and executable tools that convert the trends described here into 2026 action. Our detailed datasets and scenario outputs are intentionally gated to preserve their strategic value—contact PW Consulting to unlock the complete package and a tailored briefing for your executive team.
For detailed analysis of this topic, please visit the official page: Ferro Chrome Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sugar-Coated Tablets Market to hit USD 1,053.25M in 2026 (5.6% CAGR)
By PW Consulting, 2026-08-02
Sugar Coated Tablets Market: Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, high-signal preview of our full Sugar Coated Tablets Market study. This briefing is designed to orient executive teams and corporate development functions as they prepare 2026 investment, manufacturing, and portfolio decisions. It demonstrates the analytical depth and actionable framing contained in the full report while deliberately withholding granular segment-level data to encourage direct access to the complete study for transaction- or program-level decisions.
Sugar Coated Tablets Market
Market snapshot: scale, trajectory, and concentration
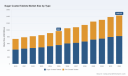
The sugar coated tablets market exhibited steady expansion through the 2020–2025 base period tracked in our study, growing from a mid-single-hundred-million USD market in 2020 to a reported market size of USD 969 million in 2025 (base year). Under our consensus-driven scenario, the market is set to extend that momentum into the forecast window (2026–2032) with a compound annual growth rate (CAGR) of 5.6%, reaching an estimated USD 1.43 billion by 2032. Early 2026 projections show the market moving past the USD 1.05 billion mark—an inflection that makes 2026 a pivotal planning year for both incumbent manufacturers and new entrants.
Sugar Coated Tablets Market
Market concentration is moderate: the top three firms account for roughly one-third of the market, while the top five approach mid-forties in share. This structure creates strategic space for specialized players (e.g., contract coaters, equipment suppliers) and differentiated incumbents to carve defensible niches, particularly where service models, manufacturing capability, or cost position provide clear advantages.
Sugar Coated Tablets Market
Why this matters for 2026 corporate decisions
- Portfolio prioritization: The growth outlook is robust enough to justify selective reinvestment in sugar coating capability for companies seeking taste-masking, brand differentiation, or patient-adherence solutions. However, film coating has displaced sugar coating in many formulations; the decision to invest should be driven by product lifecycle, margin profile, and regulatory complexity rather than headline market growth alone.
- Manufacturing footprint & CMO strategy: The multi-layer sugar coating process increases tablet size and production complexity compared with many film-coated alternatives. Organizations assessing in-house capacity versus outsourcing should weigh setup cost, takt-time impacts, and quality control burdens—particularly for products requiring shellac-based undercoats or specialized polishing agents. Contract manufacturers with demonstrated sugar-coating expertise will capture meaningful share from firms that prefer to outsource complexity.
- M&A and partnership timing: With moderate concentration and ongoing demand across pharmaceutical and OTC categories, 2026 is a favorable window for bolt-on acquisitions or long-term supply partnerships that deliver immediate manufacturing scale or regulatory know-how. Premiums should reflect execution risk around formulation transfers and the need for accelerated process validation.
Regulatory, reimbursement and raw-material dynamics
- FDA expectations: FDA guidance on oral solid dosage forms continues to emphasize physical attribute consistency (size, shape, disintegration/dissolution) and specific attention to shellac-based undercoats in aged samples. Firms should budget for expanded stability testing and robust comparability packages when altering coating processes or transferring manufacturing.
- Reimbursement nuances: In select national formularies, sugar-coated and uncoated options may be treated equivalently for reimbursement. Manufacturers targeting public procurement channels should model pricing and substitution risk accordingly—particularly in markets where formulary guidance creates pressure on premium-priced coated formats.
- Raw material & production inputs: Sugar coating processes rely on sucrose-based syrups, talcum, colorants and polishing agents (e.g., wax). These inputs influence unit economics through material cost, batch yields and equipment throughput. Price or quality volatility in key ingredients can materially affect margins, particularly for high-volume generics and export-oriented producers.
Competitive landscape: what leading players signal
The competitive field includes global pharma majors, high-volume generic houses, and a spectrum of specialist suppliers and contract coaters. The full report profiles firms ranging from Pfizer, Novartis and J&J to regional generics such as Aurobindo, Sun Pharma and Cipla, as well as specialized contract and equipment providers. A few high-level strategic observations:
- Global innovators and brand owners (e.g., Pfizer, Novartis, J&J, Sanofi, GSK): These firms leverage sugar coating primarily where patient compliance, taste masking or brand identity justify the complexity. Their activity signals continued demand for coated formats in selected therapeutic areas (e.g., cardiovascular, pain management, certain specialty indications), where differentiation supports pricing and formulary positioning.
- Large generics players (e.g., Aurobindo, Teva, Sun Pharma, Cipla): These manufacturers use sugar coating in portfolios where cost-competitive production and global distribution scale matter. For them, sugar-coated lines are typically deployed for high-volume, price-sensitive markets and for legacy molecules where coating preserves interchangeability with originator formulations.
- Specialists and CMOs (e.g., LTS Lohmann, Contract Coating Inc., contract suppliers): Outsourced coating services capture customers seeking to avoid capital outlay and to secure faster time-to-market. They also act as strategic partners for mid-sized pharma firms and nutraceutical brands.
- Equipment and ancillary suppliers: Firms supplying coating pans, polishing systems and process controls are critical nodes for operational efficiency. Investment in modern coating technology reduces cycle time, improves uniformity and lowers defect rates—advantages that translate directly into cost per finished unit.
Collectively, these players create a market dynamic where scale, regulatory track record, and specialized manufacturing capability determine competitive advantage more than raw demand growth alone.
Operational and commercial playbook for 2026
- Prioritize quick wins: For firms with existing sugar coating capability, prioritize line balance, process analytical technologies (PAT) for in-process monitoring, and targeted reformulation to reduce coating cycles. These measures improve throughput without large capital expenditure.
- Outsource selectively: New product introductions and small-volume specialty medicines are often better suited to CMOs with sugar coating expertise. Negotiate long-term offtake or capacity reservation clauses to de-risk supply for critical SKUs.
- Regulatory-first transfers: Any manufacturing transfer must include an FDA-aligned stability and equivalence plan, with explicit tests for shellac undercoat performance and aged dissolution profiles. Build regulatory contingencies into project timelines and valuations.
- Supply chain hedging: Lock multi-sourcing for key coating inputs and model the margin impact of ingredient inflation across scenarios. Where feasible, standardize on coatings that reduce batch variability and raw-material sensitivity.
Risks, mitigants and red flags
- Technological displacement: The continuing shift toward film coating in many formulations compresses long-term demand for sugar coating. Mitigate by focusing on segments where sugar coating offers unique patient or manufacturing benefits (e.g., certain legacy products, specific organoleptic requirements).
- Regulatory enforcement and comparability failure: Failure to meet FDA expectations on physical attributes or aged dissolution can result in costly recalls or market withdrawals. Treat comparability studies and stability testing as primary gating items.
- Consolidation risk: Moderate concentration means that successful roll-ups or strategic alliances among larger players could squeeze margins for small independent coaters—plan exit or scale strategies accordingly.
What the full PW Consulting report delivers (practical, transaction-ready content)
Our full Sugar Coated Tablets Market study expands this strategic preview into detailed, operationally actionable intelligence, including:
- Independent market sizing and validated forecasts through 2032 with scenario analysis and sensitivity to raw-material and regulatory outcomes;
- Manufacturing cost benchmarks, throughput and capex models for greenfield versus retrofit coating lines;
- Regulatory playbooks for process transfer, stability packages, and comparability dossiers that align with FDA expectations;
- Commercial models for pricing and tender competitiveness in public formulary environments;
- Comprehensive competitor dossiers and M&A screening tools, including target prioritization criteria and integration risk checklists;
- Supplier maps and contract manufacturing scorecards to accelerate partner selection.
These deliverables are designed to be directly applied to 2026 board-level decisions—whether you are evaluating capacity investments, preparing an acquisition bid, negotiating long-term CMO contracts, or redesigning your coating strategy to protect margins amid raw-material volatility.
Call to action
For firms that require a targeted briefing or a tailored annex (e.g., cost model for a specific manufacturing line, acquisition target assessment, or regulatory risk summary for a planned transfer), PW Consulting offers modular fast-track engagements calibrated to board decision timelines in 2026. The full report contains the granular segment models and appendices that we have intentionally held back here to preserve the “trailer” effect of this preview. Contact our engagement team to receive the complete study or a customized executive workshop.
Delivering pragmatic strategic clarity—PW Consulting.
For detailed analysis of this topic, please visit the official page: Sugar Coated Tablets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: All-Vanadium RFB Ion Exchange Membrane Market Set to Grow at 15.7% CAGR
By PW Consulting, 2026-08-02
Ion Exchange Membrane for All‑Vanadium Redox Flow Battery Market — Strategic Preview for 2026 Decision‑Makers
As organizations map capital allocation, supplier strategies, and technology roadmaps for 2026, understanding the economics and risk profile of ion exchange membranes (IEMs) for all‑vanadium redox flow batteries (VRFBs) is mission‑critical. This report preview synthesizes the practical intelligence PW Consulting delivers in its full study: robust market sizing and forecasting, actionable supplier and technology benchmarking, regulatory impact matrices, and pragmatic implementation playbooks designed to support C‑suite and procurement decisions across utilities, energy storage OEMs, industrial off‑takers, and advanced materials suppliers.
Ion Exchange Membrane of All-Vanadium Redox Flow Battery Market
Market snapshot that matters to strategic planners
- Base year and temporal scope: The study anchors on 2025 with a detailed historical review covering 2020–2025 and forward forecasts through 2032.
- Growth trajectory: The IEM market for all‑vanadium systems is on a sustained growth path with a compound annual growth rate (CAGR) of 15.7% across the forecast window, reflecting both rising VRFB deployments and continuing materials innovation.
- Size context: From the post‑pandemic baseline to 2025 the market demonstrated consistent expansion; our forward model anticipates a multi‑fold increase by 2032 as commercial projects scale and new membrane formats enter supply chains.
- Market structure: Competitive intensity is moderate — the three largest participants account for a meaningful share of supply, while the top five concentration remains well below oligopoly levels, signaling room for new entrants and differentiated materials strategies.
Why the numbers translate into strategic imperatives for 2026
Two simultaneous forces are compressing decision windows for energy storage purchasers and membrane suppliers in 2026. First, macro demand growth and project pipelines are accelerating procurement cycles; second, regulatory and reputational scrutiny around perfluorinated chemistries is amplifying compliance complexity. Together these forces convert what looks like an operational sourcing choice into a cross‑functional strategic decision.
Ion Exchange Membrane of All-Vanadium Redox Flow Battery Market
- Procurement and supply risk: High growth means lock‑in risk for membrane supply. Buyers that defer prequalification of alternative membrane chemistries or fail to secure long‑lead agreements risk schedule slippage for utility‑scale VRFB deployments.
- Regulatory and compliance urgency: New and evolving PFAS reporting and restriction frameworks—spanning US TSCA rule amendments, interim EPA reporting deadlines, and EU drinking water directives—create compliance timelines that intersect procurement contracts and product specifications in 2026. Organizations must anticipate reporting obligations and potential import/product restrictions affecting perfluorinated membranes.
- Technology differentiation as a commercial lever: Membrane performance drives stack efficiency, balance‑of‑plant sizing, and lifetime economics. Small improvements in ion selectivity and crossover reduction translate into outsized system‑level savings over typical VRFB lifecycles.
What the full report provides (practical, transaction‑ready content)
PW Consulting’s full study goes beyond headline figures to equip teams with executable outputs, including:
Ion Exchange Membrane of All-Vanadium Redox Flow Battery Market
- Scenario‑based demand forecasting and sensitivity models — tailored to different policy and deployment uptake trajectories — that can be dropped into capital planning tools.
- Supplier due diligence templates and scorecards capturing manufacturing footprint, per‑product performance metrics, lead times, and contractual clauses to mitigate regulatory exposure.
- Procurement playbooks for membrane specification harmonization (performance vs. compliance tradeoffs), inventory buffers, and contract structures to de‑risk 2026 deliveries.
- Technology roadmaps and R&D prioritization frameworks that quantify ROI for membrane improvements (e.g., reduced vanadium crossover, thickness vs. conductivity optimization, and non‑perfluorinated alternatives).
- Regulatory impact matrices with timelines and recommended mitigations for PFAS‑related rules across key jurisdictions.
Competitive landscape: who shapes the membrane market and why it matters
The market is characterized by a mix of materials specialists, battery OEMs integrating membranes into whole systems, and regional manufacturers optimizing for local supply chains. Our competitive analysis synthesizes public filings, product launches, and technical data to map supplier capabilities against strategic buyer needs.
- CAPLINQ Corporation (Livonia, MI, USA) — Focused producer of perfluorinated cation exchange membranes designed specifically for VRFB stacks. Recent product updates and the introduction of anion exchange membrane variants underscore a deliberate effort to expand technical breadth and offer custom formats to stack integrators.
- VRB Energy (Victoria, BC, Canada) — Developer of vertically integrated VRFB systems with proprietary low‑cost membrane technology. Their approach emphasizes system‑level cost reduction and long‑life electrolytes, positioning them as an important reference for levelized cost of storage comparisons.
- Sumitomo Electric Industries, Ltd. (Tokyo, Japan) — Global industrials player offering advanced VRFB systems incorporating optimized membranes for utility‑scale applications; recent product launches and awarded contracts illustrate successful commercialization pathways for membrane‑centered performance gains.
- Ningbo VET Energy Technology Co., Ltd. (Ningbo, China) — Regional manufacturer producing membranes optimized for chemical stability and extended service life, representing an alternative supply source for APAC OEMs targeting price‑performance tradeoffs.
- Chemours Company (Wilmington, DE, USA) — Established supplier of Nafion perfluorosulfonic acid membranes widely used across electrochemical applications. Their products serve as a benchmark for performance—and a focal point for regulatory scrutiny given the industry conversation on perfluorinated materials.
Recent corporate developments are informative for 2026 strategy: Sumitomo’s marketed next‑generation VRFB systems and subsequent contract wins indicate accelerating demand for higher‑performance membrane assemblies; CAPLINQ’s publication of detailed specifications and custom fabrication options signals increasing commercial transparency and supplier readiness to support scaled deployments.
Regulatory dynamics and their operational consequences
Regulatory trends in 2025–2026 materially alter the compliance and cost calculus for membrane selection:
- US TSCA and EPA reporting requirements for perfluorinated materials create near‑term documentation and supply‑chain visibility obligations for manufacturers and importers. Several deadlines relevant to small manufacturers and article importers fall into 2026–2027 and will influence sourcing decisions and the acceptability of perfluorinated membranes in procurement specifications.
- EU water‑related directives introduce monitoring expectations that indirectly affect membrane manufacturing and end‑of‑life stewardship for membrane separators used in industrial processes.
- Multi‑state legislative activity in the US has produced a patchwork of PFAS rules that increase compliance complexity for suppliers and OEMs operating across jurisdictions.
Consequence: companies that do not incorporate regulatory readiness into supplier selection expose themselves to retrofit costs, supply interruptions, and reputational risk. The full PW Consulting study provides a granular regulatory readout and contract clause templates to address these exposures.
Strategic recommendations for 2026 decision cycles
- Prioritize dual‑track sourcing: qualify both incumbent perfluorinated membrane suppliers and emerging non‑perfluorinated or modified membrane providers to mitigate single‑source and regulatory risks.
- Embed regulatory covenants into supplier agreements: require transparency on PFAS content, compliance documentation, and change‑control notice periods to avoid downstream surprises.
- Invest in performance‑based procurement: link price to demonstrated in‑stack performance (crossover, conductivity, durability) and total cost of ownership metrics rather than unit price alone.
- Accelerate field validation partnerships: fund joint pilots with membrane developers to shorten qualification timelines and secure preferential supply commitments as capacity scales.
- Use scenario planning to stress‑test capital plans: incorporate alternate adoption curves driven by regulatory shocks or accelerated storage demand to protect project economics.
Where this teaser stops — and the full study begins
This preview demonstrates the strategic depth and practical orientation of PW Consulting’s full report while deliberately withholding detailed segmentation and raw tables that underpin procurement and M&A decisions. The comprehensive study includes:
- Disaggregated demand by region, application, and membrane type with interactive sensitivity controls;
- Vendor scorecards with manufacturing footprint, technical KPIs, and commercial terms;
- Contract templates, supplier transition playbooks, and a prioritized R&D agenda tied to ROI.
For executives and commercial teams preparing 2026 budgets and contractual strategies, the report acts as an end‑to‑end decision support package: from identifying where membrane performance materially alters system economics, to negotiating clauses that manage PFAS‑related legal and reputational risk.
Next steps — an operational checklist for 90‑day action
- Run immediate supplier due diligence on primary membrane vendors and capture PFAS compliance evidence.
- Prioritize pilot agreements with at least one alternative membrane technology provider to validate lifecycle economics.
- Update procurement templates to include regulatory reporting obligations and change‑of‑material notification timelines.
- Convene a cross‑functional task force (procurement, legal, sustainability, engineering) to align on a membrane selection matrix for projects scheduled in 2026–2027.
PW Consulting’s full report furnishes the data, models, and playbooks required to act on these steps with confidence. If your 2026 capital allocation and supplier strategies rely on VRFB deployments, gaining access to the complete intelligence will materially shorten your decision cycle and reduce execution risk.
For detailed analysis of this topic, please visit the official page: Ion Exchange Membrane of All-Vanadium Redox Flow Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
NdFeB Market 2026 Strategic Preview — A Pw Consulting Director’s Brief
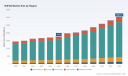
This preview synthesizes the critical strategic implications from PW Consulting’s latest NdFeB Market study (base year 2025; historical window 2020–2025; forecast horizon 2026–2032). Our model shows the global NdFeB market accelerating from an estimated USD 1,775 million in 2025 to roughly USD 3,030 million by 2032 at a compound annual growth rate of 7.78%. For executives planning capital allocation, supply‑chain redesign, or M&A through 2026, the directional signals below are what we consider non‑negotiable inputs to practical strategy.
NdFeB Market
Executive snapshot: what the numbers mean for 2026 decision cycles
-
Momentum and scale: The mid‑2020s mark a transition from incremental to structural growth in NdFeB demand. Our topline trajectory — nearly doubling market value across the forecast window — reflects accelerating end‑market adoption (notably mobility and energy), combined with purposeful policy and industrial investments to onshore production capacity.
NdFeB Market -
Decision timing: Firms allocating capex in 2026 must weigh multi‑year paybacks against a tightening raw‑material backdrop and surging green‑tech demand. Early entrants who secure feedstock and manufacturing capacity before mid‑2026 will capture outsized commercial optionality; late movers will face higher entry costs and lower negotiation leverage.
NdFeB Market -
Margin and risk pressure: Price volatility in rare‑earth feedstock since early 2025 has materially elevated input cost risk. Scenario planning around sustained elevated neodymium/praseodymium pricing is now essential in capital and procurement approvals.
Why this study matters: the practical outputs that inform 2026 choices
-
Dynamic demand model: A bottom‑up demand forecast at device and vehicle level that converts product adoption curves into tonnage and revenue impacts across 2026–2032 — designed to stress test investment cases and product roadmaps.
-
Supply‑chain heatmap: A multi‑node view of feedstock, alloying, magnet production and assembly that flags single‑point failures, regulatory chokepoints and relocation opportunities for near‑term resilience builds.
-
Cost and capacity curves: Comparative unit‑cost profiles and utilization thresholds for sintered vs. bonded production routes, with sensitivity to Nd/Pr pricing and energy costs — useful as inputs to make‑vs‑buy and internal plant optimization decisions.
-
Regulatory and policy tracker: Consolidated view of export controls, subsidies, and critical‑material mandates (including EU recycling requirements and US DPA funding) that influence sourcing, eligibility for public incentives and long‑range planning.
-
Commercial playbooks: Tactical recommendations across procurement hedging, strategic partnerships, recycling investments, and M&A prioritization, plus vendor scorecards and negotiation levers tailored to OEMs and magnet producers.
Market dynamics and strategic implications
-
Feedstock fragility and pricing: The market is operating under a new normal of elevated Nd/Pr pricing. For 2026 budgeting, treat rare‑earth pricing as a primary risk factor; incorporate at least two stress scenarios (prolonged high prices and episodic export curbs) into all project IRR calculations.
-
Policy is market shaping: Since April 2025, a wave of export controls and licensing on certain rare‑earth elements has altered trading patterns and accelerated localization incentives. Concurrent government funding programs in the U.S. and Europe materially shorten the timeline for viable domestic projects. The practical takeaway: eligibility for public funding materially improves project economics and should influence siting and partnership decisions.
-
Recycling and circularity are now strategic levers: Regulatory moves — for example, minimum recycling requirements for new vehicles — create both compliance obligations and supply opportunities. Firms that can operationalize rare‑earth recovery at scale will secure margin and sourcing resilience advantages by the late 2020s.
-
Technology route choices matter: Sintered and bonded NdFeB routes serve different performance and cost points. Our report offers a detailed crosswalk of application performance vs. production cost, which should be applied to product portfolio decisions and CAPEX allocation in 2026.
Competitive landscape — who shapes the market today
The NdFeB ecosystem is a mixture of legacy magnet specialists, emerging domestic champions, and integrated miner‑to‑magnet entrants. Strategic posture varies across vertical integration, technology differentiation and geographic footprint. Key market actors examined in our study include:
-
MP Materials — repositioning from rare‑earth mining to integrated magnet production with significant US campus investments; a near‑term source of domestically produced NdFeB capacity.
-
Vacuumschmelze GmbH — long‑standing technological expertise in advanced magnetic materials, now scaling with industrial plants targeted at high‑performance applications.
-
Neo Performance Materials — expanding commercial production capacity in Europe with new plants designed to serve regional demand and reduce logistics exposure.
-
USA Rare Earth, Arnold Magnetic Technologies, Electron Energy Corporation and regional specialists — each contributes niche capabilities from sintered production to application‑specific engineering solutions.
-
Magnequench, Bunting and contract manufacturers — provide bonded powders, assemblies and supply chain flexibility for OEMs who prioritize quick time‑to‑market over vertical integration.
-
Asia OEMs and manufacturers — remain critical capacity providers and technology developers; the competitive response from Asian producers continues to shape cost baselines and service expectations.
Recent capacity and policy moves underline how fast the competitive picture is shifting: major investments announced or commissioned in 2025–2026 are already reshaping regional balances and negotiating leverage. Our full company scorecards and capacity timeline map these moves to mid‑cycle pricing and availability outcomes — essential for procurement and M&A scenarios but deliberately omitted from this preview.
Actionable strategy framework for 2026
-
Procurement: Move from spot tactics to structured offtake and hedging. Secure contractual optionality with tier‑1 magnet producers and incorporate recycling flows into long‑term contracts.
-
Industrial investment: Prioritize modular, scalable manufacturing deployments and require feedstock supply tests before greenfield commitments. Take advantage of government funding windows but plan for co‑investment to de‑risk timeline slippage.
-
Product strategy: Reassess magnet content in new product introductions under three cost scenarios. For high‑volume mobility platforms, design families that can accept multiple magnet grades to preserve flexibility.
-
M&A and partnerships: Target recycling specialists, alloy‑processing technology owners, and regional capacity providers to accelerate integration and supply assurance. Smaller, technology‑rich targets may yield better risk‑adjusted returns than capital‑intensive greenfield builds.
Key risks and scenarios to monitor
-
Prolonged export controls or further tightening of dual‑use policies could compress global arbitrage and raise substitution incentives.
-
Persistently high Nd/Pr prices may accelerate substitution R&D but also impair adoption curves for some cost‑sensitive applications in the short term.
-
Rapid capacity additions in response to public funding can create cyclical oversupply in the medium term if demand does not keep pace, pressuring margins for commodity magnet grades.
-
Regulatory shifts on recycling and traceability (already active in key markets) may reorder supplier selection criteria and add compliance costs; early compliance readiness is a competitive advantage.
What’s inside the full report (practical deliverables)
-
Complete demand and revenue model (2020–2032) with device‑level drivers and sensitivity levers;
-
Supply mapping and capacity timeline, including commissioned, announced and likely projects;
-
Company scorecards, vendor due‑diligence templates and procurement negotiation playbooks;
-
Regulatory impact matrix and funding eligibility guide for U.S. and EU programs;
-
Recycling cost curves, break‑even analyses and implementation roadmaps for OEMs and recyclers;
-
Three forward scenarios with quantified outcomes (base, upside, downside) and decision triggers for 2026–2028 capital and procurement choices.
We intentionally withhold segment‑level breakdowns and the detailed company financial models in this preview to preserve the integrity of the original research and to ensure readers engage directly with the full report for transaction‑grade intelligence.
Final note for 2026 planners
NdFeB magnets are no longer a niche raw material concern; they are a strategic input whose availability, cost and regulatory treatment will materially affect product architectures, supply‑chain footprints and national industrial policy outcomes through the 2030s. The window for securing advantaged positions in 2026 is narrow: investors and procurement leaders who combine near‑term supply guarantees, recycling pathways and policy funding alignment will minimize exposure and maximize upside.
Access the full Pw Consulting NdFeB Market study for the complete models, company scorecards, and the decision toolbox required to operationalize these insights in 2026.
For detailed analysis of this topic, please visit the official page: NdFeB Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hot Rolled Coil (Flat) Market to Reach USD 435.5B by 2032 at 4.1% CAGR
By PW Consulting, 2026-08-02
Hot Rolled Coil (Flat) Market: Strategic Outlook for 2026 — A PW Consulting Preview
This preview synthesizes the strategic implications of our full Hot Rolled Coil (Flat) Market study and explains how the report should be used by corporate leadership, procurement teams, and investors making 2026 decisions. It is intentionally data-driven at the macro level to establish factual grounding while withholding the granular segment tables and model outputs that are reserved for subscribers. The base year for our analysis is 2025, historical coverage runs 2020–2025, and our forecast window runs 2026–2032.
Hot Rolled Coil (Flat) Market
Why this report matters for decisions in 2026
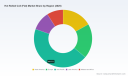
The hot rolled coil (HRC) market is on a multi-year growth trajectory that is both steady and strategically significant. After an expansion through 2020–2025 that lifted global market size materially (from an estimated market base in 2020 to a substantially larger base in 2025), our forecast projects a compound annual growth rate (CAGR) of approximately 4.1% across 2026–2032. That trajectory implies meaningful scale effects for producers, suppliers and large consumers: by the end of our forecast window the market is projected to be materially larger than in 2025, creating both capacity stress points and opportunity for value capture through differentiation, cost control, and trade positioning.
Hot Rolled Coil (Flat) Market
For 2026 specifically, executives should treat the market as one characterized by elevated mid-cycle volatility: supply constraints and logistics costs are driving price spikes in certain regions, while demand remains resilient across core downstream sectors. The strategic questions for 2026 are therefore not just “grow or defend,” but “where to allocate capital, inventory and risk appetite to maximize margin and reduce exposure to policy and feedstock shocks.”
Hot Rolled Coil (Flat) Market
Key macro and policy drivers shaping HRC in 2026
- Trade policy and tariffs: Rapid shifts in trade policy are a dominant short-term force. In North America, Section 232 measures were reintroduced and strengthened in 2025, producing a material change in import dynamics and prompting domestic price discipline. In Europe, safeguard measures in 2025 tightened import liberalisation and altered trade flows through mid-2026. These policy moves amplify the importance of regional supply positioning and near-term orderbook management.
- Raw material volatility: Benchmark feedstock prices moved sharply in early 2026 following supply disruptions. Premium Australian hard coking coal reached multi-year highs in February 2026, and met-coal export interruptions contributed to a >50% uplift in benchmark prices from 2025 levels through March 2026. For steelmakers with BF‑BOF exposure this translates into direct input-cost pressure; for EAF-based producers the impact is mediated by scrap and electricity market dynamics but remains non-trivial.
- Logistics and transport cost inflation: Rising freight and inland transport costs for iron ore and scrap added upward pressure on production costs in key manufacturing basins in Q1 2026, making supply-chain design and freight optimization immediate levers to protect margins.
- Operational disruptions: Mill outages and force majeure events (notably significant hot-strip mill interruptions in 2025) compressed near-term availability and amplified spot-market price moves, reinforcing an environment where nimble orderbook management and contingency sourcing matter.
Supply‑side dynamics and pricing behavior
The market in 2026 displays a two-track pricing regime: contract-negotiated volumes that reflect longer-term relationships and spot volumes that are highly sensitive to capacity tightness and policy-induced order flow. Leading domestic producers in North America have demonstrated pricing discipline during early 2026, with several consecutive price increases reported in the spot channel (weekly moves tracked by industry sources reached sub‑to mid‑four-digit $/ton levels for HRC in Q1–Q2 2026). That behavior, combined with capacity announcements and orderbook controls from major integrated producers, signals a market where suppliers can exercise leverage in tight regions while interconnected global flows remain responsive to tariff and logistical dislocations.
Market concentration metrics indicate a moderate degree of concentration among the largest producers. This structure supports regional price leadership but leaves room for nimble mid‑tier players to capture local advantage through service, inventory and value‑added processing.
Competitive landscape — what leading producers are doing
- Nucor Corporation (North America): Millennial‑era nimbleness via EAF/minimill model and a strategic push on low‑embodied carbon steel gives Nucor flexibility in feedstock sourcing and product mix. Recent reported price increases and spot price leadership in early 2026 reflect its ability to manage inventories and exercise regional price discipline.
- Cleveland‑Cliffs Inc. (North America): As a large flat‑rolled supplier with integrated capabilities, Cleveland‑Cliffs is focusing on capacity management and orderbook discipline to protect margins amid tariff‑driven domestic demand. Public commentary shows an emphasis on sustaining pricing while managing customer relationships in a constrained environment.
- Steel Dynamics & U.S. Steel (Domestic specialists): Both emphasize flexible processing and downstream value-add services—differentiation that pays in markets where delivery reliability and product readiness command premiums.
- Global integrated exporters (ArcelorMittal, Tata, Posco, JSW, Hyundai Steel, China Baowu): These players balance export flows and domestic commitments, with production scale allowing them to react to regional policy shifts. China Baowu’s volume position remains strategically important for global availability; similarly, Asian producers’ proximity to growing regional demand is a structural advantage.
Tactically, leading firms are pursuing one or a combination of: capacity optimisation, orderbook discipline and price signalling, regional footprint realignment, product‑level differentiation (surface/chemistry), and early moves into low‑carbon premiums. The firms that combine robust cost control with credible decarbonisation pathways will be best placed to capture premium demand as buyers begin to value low‑embodied steel.
What the full PW Consulting report contains — practical, executable content
Our full study goes beyond narrative to provide tools and templates that executives can use immediately in 2026. Highlights include:
- Granular demand models (by region and end‑use) and an interactive dashboard that lets you test volume sensitivity under alternate macro scenarios. Note: detailed regional and application splits are omitted from this preview to preserve the full analytical value of the report.
- Price and cost‑curve analysis for HRC producers (feedstock, conversion, freight, and tariff pass‑through impacts) with scenario toggles for key shocks such as coking coal or freight spikes.
- Company scorecards and a quantified competitive positioning matrix that synthesises capability (scale, product range, EAF vs integrated footprint), commercial posture, and decarbonisation readiness.
- Procurement playbooks and contract templates for negotiating 2026 supply terms under tariff volatility, including short‑term vs. long‑term allocation strategies and inventory optimisation rules tied to working‑capital constraints.
- M&A and capacity planning frameworks with candidate screening criteria and valuation sensitivities based on multiple price and policy scenarios.
- Risk registers and mitigation checklists for mill outages, logistics shocks, and regulatory shifts, together with prioritized operational contingencies.
How to convert these insights into 2026 actions
- Short‑term procurement: Reassess the balance of contracted vs. spot purchases. Where domestic suppliers demonstrate pricing discipline and delivery reliability, consider locking strategic volumes while preserving optionality for upside price moves.
- Price and commercial strategy: If you are a producer, signal disciplined pricing backed by firm orderbook management; if you are a buyer, diversify supplier mix and build conditional inventory triggers tied to feedstock and freight indicators.
- Capital allocation: Prioritize investments that reduce feedstock exposure (scrap capacity, recycling), improve product value‑add, or shorten lead times. Defer non‑strategic greenfield spends until tariff clarity and feedstock trends stabilise.
- M&A and partnership screening: Target assets that close gaps in regional access or product capability rather than those that merely add scale in over‑supplied corridors.
- Decarbonisation and premium positioning: Start pricing low‑embodied products as differentiated offerings and align procurement policies to secure preferential supply from EAF/minimill producers where possible.
- Risk governance: Implement real‑time signal tracking for policy announcements, port congestions, and feedstock price triggers, and pre‑authorize contingency purchases within defined bands to avoid reactive, high‑cost sourcing.
Final word — why the details matter and next steps
This preview sets the strategic contours for 2026: an HRC market experiencing steady longer‑term growth at roughly 4.1% CAGR through 2032, but subject to near‑term volatility from tariffs, feedstock shocks and logistics cost inflation. The choices companies make in 2026 about contracts, inventory, capacity and capital allocation will materially affect margin trajectories for the next five years.
For executives who need the playbook—detailed regional and application splits, company scorecards, scenario tables and executable contracts—our full report provides the granular data, workbook models and strategic templates required to act decisively. To access the report, dashboards, and an executive briefing with PW Consulting’s senior industry team, please visit our Hot Rolled Coil (Flat) Market page or contact your PW Consulting representative to arrange a briefing and demo of the underlying models.
For detailed analysis of this topic, please visit the official page: Hot Rolled Coil (Flat) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oilfield Chemicals Market to Reach USD 39.06B by 2032 at 5.6% CAGR
By PW Consulting, 2026-08-02
Oilfield Chemicals Market 2026: Strategic Imperatives for Executive Decision‑Making
Executive preview
As PW Consulting's latest Oilfield Chemicals Market study reaches its base year of 2025, the market stands at an inflection point. After recovering through 2020–2025, the global oilfield chemicals market is projected to continue expanding at a steady compound annual growth rate (CAGR) of 5.6% over the 2026–2032 forecast window, rising from an observed market value in 2025 to a materially larger global market by 2032. For boards, corporate strategy teams, and private investors planning moves in 2026, this report is designed as an operational playbook: it translates macro momentum into prioritized choices—portfolio, supply chain, regulatory readiness, and M&A—that deliver measurable competitive advantage.
Oilfield Chemicals Market
Why 2026 is a strategic hinge year
The market’s medium‑term trajectory reflects a recovery and modernization phase following pandemic and commodity cycles. Annualized growth of 5.6% is not merely a headline: it signals sustained demand across drilling, production, and enhanced recovery activities and underpins investment cases for incremental capacity, technical service expansion, and product innovation. Equally important, the industry is being reshaped by three converging forces—regulatory tightening, feedstock volatility, and a fragmented competitive landscape—which make 2026 the last practical year to consolidate strategic initiatives before competitive positions crystallize in the latter half of the decade.
Oilfield Chemicals Market
Macro picture in one glance
- Base and historical frame: the study uses 2025 as the base year and documents trends across 2020–2025 to isolate structural shifts from transitory cycles.
- Forecast horizon: 2026–2032 provides seven years of scenario‑based projections that balance supply‑side inertia and demand elasticity around oilfield activity levels.
- Market dynamics: steady expansion—backed by a 5.6% CAGR—creates both runway and urgency for strategic investment.
Key growth drivers and pockets of commercial opportunity
Four drivers will determine winners in 2026 and beyond:
Oilfield Chemicals Market
- Operational intensity in core basins. Sustained drilling and production in major basins will keep demand for specialty chemistries resilient. Companies with rapid technical field support and localized inventories convert activity into repeatable revenue.
- Product substitution under regulation. Tightening controls on hazardous chemistries (notably PFAS and other regulated substances) are accelerating demand for lower‑toxicity alternatives—creating an innovation premium for manufacturers who can demonstrate compliance and performance in parallel.
- Supply‑chain risk premium. Feedstock disruptions—illustrated by barite and bromine price volatility—are raising landed cost uncertainty. Firms that can de‑risk through dual sourcing, nearshoring, or vertical integration will capture margin and availability advantages.
- Services‑led differentiation. Bundled offerings—chemistry plus digital monitoring, on‑site treatment, and predictive dosing—are increasingly the route to higher gross margins and stickier customer relationships.
Risks and regulatory headwinds to quantify in 2026 planning
- Compliance cost escalation. EPA and REACH controls are reshaping permissible use profiles and lifecycle obligations for several chemical classes. Compliance engineering should be budgeted as a line item and integrated into product roadmaps.
- Raw‑material shocks. Short‑term supply shocks for critical feedstocks amplify procurement risk and necessitate scenario planning for raw‑material price pass‑through and substitution pathways.
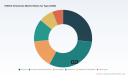
- Market fragmentation and price pressure. Low‑to‑moderate market concentration (a CR3 in the mid‑20s and CR5 in the low‑30s) indicates a fragmented supplier base where regional or niche players can sustain price competition; scale and technical services become the differentiator.
Competitive landscape: capability clusters and strategic actions
The industry is populated by a mix of multinational chemical majors, specialist formulators, and service operators. Three capability clusters are emerging:
- Integrated chemical majors (broad R&D, global manufacturing footprint): These players leverage scale to serve multiple oilfield applications and to amortize regulatory compliance investments.
- Service-focused energy companies (chemistry plus field services): Firms that combine chemistry with wellsite services and digital optimization increasingly win multi‑year contracts from operators prioritizing uptime and lifecycle costs.
- Regional specialists and distributors: Agile, cost‑competitive suppliers maintain relevance in basin‑level supply chains, particularly where quick delivery and local technical support matter.
Recent corporate moves underscore these dynamics: a major European chemicals spin‑out (Versalis Oilfield Solutions) re‑orienting a dedicated oilfield business; targeted acquisitions that fold Permian‑focused production chemistry into global distributor platforms; and sustainability certifications at specialty polymer facilities. These discrete events reveal two broader strategic impulses—consolidation where scale meets service, and certification/innovation where regulatory pressure creates differentiation.
Practical actions for C‑suite and business unit leaders in 2026
Translate market growth into commercial results with a prioritized, implementable agenda:
- Reassess portfolio through a three‑lens filter: regulatory exposure, margin resilience under raw‑material stress, and service‑ability (ability to be sold as a bundled solution). Prune or invest accordingly.
- Accelerate compliance‑by‑design. Invest now in alternative chemistries and third‑party certifications to avoid last‑minute product withdrawal or expensive reformulations.
- Secure supply‑chain optionality. Negotiate long‑term feedstock arrangements, identify local substitutes, and build contingency inventory for critical inputs subject to price spikes.
- Pursue targeted M&A and alliances. Look for tuck‑ins that provide basin access, technical service capabilities, or proprietary low‑tox formulations. Given market concentration metrics, bolt‑on acquisitions can meaningfully improve regional share without chasing global scale immediately.
- Monetize services. Reprice contracts toward value‑based models—performance guarantees, uptime‑linked fees, and outcome‑based dosing—rather than commodity throughput.
- Invest in field analytics. Small investments in monitoring and predictive dosing yield outsized returns through reduced chemical consumption and longer contract tenure.
What the PW Consulting report delivers to enable these actions
Our full study is intentionally operational. It goes beyond static forecasts to equip leaders with the tools necessary to execute in 2026:
- Proven scenario toolkits that translate macro forecasts into revenue and margin maps for specific strategic moves (capacity expansion, M&A, product exits).
- Regulatory impact matrices that quantify compliance cost trajectories across major jurisdictions and identify immediate product liabilities and reformulation priorities.
- Supply‑chain resilience playbooks that prioritize feedstock risk mitigation steps and evaluate vertical integration trade‑offs at realistic capex levels.
- Commercial playbooks for service bundling, including contract design templates and pricing frameworks that protect margins while delivering operator value.
- A competitive intelligence annex profiling leading players—both multinationals and regional specialists—with capability assessments and recent strategic moves that matter for 2026 planning.
How to use the analysis: three immediate workstreams
- Strategic planning sprint (30–90 days): use our scenario templates to stress‑test near‑term capex and product investment choices under alternative feedstock and regulatory scenarios.
- Operational resilience program (90–180 days): implement prioritized supply‑chain hedges, certification roadmaps, and pilot substitutions for regulated chemistries.
- M&A and commercial execution (180–365 days): deploy the competitive intelligence and valuation anchors in the report to pursue bolt‑on acquisitions or joint ventures that close capability gaps.
Bottom line for 2026 decision makers
The oilfield chemicals market offers reliable growth and clear arbitrage for firms that proactively manage regulatory transition and feedstock volatility while differentiating through service and technical capability. The 5.6% CAGR through 2032 underpins an attractive investment horizon, but the real prize accrues to companies that execute three things well in 2026: (1) convert regulation into product advantage through early reformulation and certification; (2) secure supply‑chain optionality to stabilize margins; and (3) rebase commercial models toward services and outcomes.
Next steps
PW Consulting’s full report contains the granular decision support teams will need in 2026: scenario models, risk heat maps, supplier scorecards, and proprietary competitive profiles. The executive summary above is crafted as a strategic “trailer” that surfaces the key levers—without disclosing the granular subsegment allocations and region/application splits that underpin tactical execution. Reach out to access the complete dataset and the interactive tools that enable immediate translation of the 2026 strategy into operational plans.
For detailed analysis of this topic, please visit the official page: Oilfield Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fire Retardant Plywood Market Outlook: 5.8% CAGR (2026–2032) — PW Consulting
By PW Consulting, 2026-08-02
Fire Retardant Plywood Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present an executive preview of our new Fire Retardant Plywood Market study — a focused strategic briefing designed to inform high-stakes decisions throughout 2026. This preview follows a “trailer” approach: it demonstrates the analytical depth and operational relevance of the full study while intentionally withholding proprietary subsegment tables and pricing matrices to encourage direct engagement with the full deliverable.
Fire Retardant Plywood Market
Why this research is essential for 2026 planning
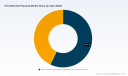
The fire-retardant plywood market is in a transitional growth phase driven by code modernization, intensified wildfire risk, and increasing demand for safer engineered-wood construction. Our analysis tracks a measured but steady expansion: the market grew from a baseline in 2020 through the industry’s 2025 base year and is projected to continue rising into the early 2030s under a mid-single-digit compound annual growth rate. Practically, the market’s trajectory from the 2020 starting point to the 2025 base year and onward to the 2032 forecast window signals predictable volumetric expansion alongside pressures on input costs and certification demands.
Fire Retardant Plywood Market
For any executive making product, procurement, or M&A choices in 2026, the study provides: (a) an evidence-based lens on near-term capacity and demand balance, (b) an operational view of where margin compression is most likely, and (c) a set of tactical moves to preserve or extend competitive positioning as the market scales.
Fire Retardant Plywood Market
What the full report delivers — a practical toolkit
- Market sizing and validated forecast (historical window 2020–2025; forecast 2026–2032) with scenario sensitivity to input-cost shocks and code-change acceleration.
- Demand-driver intelligence: building-code adoption, wildfire mitigation retrofits, multi-family and commercial construction trends, and product substitution risks.
- Cost and margin models: raw-material cost pass-through templates (including chemical feedstock volatility), mill-level margin benchmarks, and finished-goods pricing sensitivity.
- Regulatory and compliance matrix that maps ICC and AWPA standards to product claims and lab-testing protocols (including the most relevant high-temperature and pressure-treatment standards).
- Supply-chain risk dashboard: timber supply constraints, chemical feedstock volatility, treatment capacity bottlenecks, and logistics choke points.
- Competitive landscape playbook: company profiles, capability comparisons, channel strategies, and a five-cluster consolidation assessment (CR metrics included).
- Product and go-to-market playbooks: differentiation levers, certification roadmaps, specification centric selling points, and digital channel strategies for distributors and OEMs.
- Transaction and partnership guidance: M&A target screening criteria, JV structures for captive treatment capacity, and the commercial terms that matter in long-term off-take agreements.
- Implementation templates: procurement hedging playbooks, sample contract language to protect against feedstock price escalation, and a testing/validation checklist for new product launches.
Key market dynamics shaping 2026 decisions
Several industry dynamics will materially influence strategy in 2026:
- Regulation and compliance acceleration. Code updates and more prescriptive acceptance criteria are raising certification as a necessary entry barrier. The study maps which high-temperature and pressure-treatment standards are becoming prerequisites for mainstream specifiers and which voluntary certifications are gaining market traction.
- Upstream chemical volatility. Ammonium polyphosphate and boron-based retardants remain exposed to fertilizer and industrial-chemical cycles. Companies that lack active hedging strategies or alternative sourcing risk margin erosion when chemical commodity swings occur.
- Timber supply constraints. Forest-management restrictions, disease control measures and harvest limitations in key sourcing regions are constraining mill throughput. This dynamic is elevating the value of capacity control — whether through long-term wood supply contracts, upstream integration, or partnerships with timber owners.
- Consolidation and concentration. The market displays signs typical of a maturing specialty-material sector: established treatment specialists and chemical suppliers command outsized share and distribution reach, creating advantages for those with scale and integrated distribution networks.
- Product innovation and specification shifts. New grades with modified reinforcement and waterproofing, plus premium product lines validated by real-world stress testing, are accelerating specification shifts in both retrofit and new-build segments.
Competitive landscape — strategic implications of the core players
The market’s competitive texture is defined by specialty treatment houses, mill producers with treated product lines, and chemical suppliers providing formulation technology. Key firms in our coverage illustrate the strategic positions you should be assessing:
- Hoover Treated Wood Products (Harrisburg, PA) — a specialist with proprietary pressure-impregnated brands focused on both interior and exterior structural applications. Hoover’s recent distribution expansion and updated design guidance underscore a scale-and-specification strategy: broaden channel reach while codifying product use cases to reduce spec friction.
- Chesapeake Plywood (Baltimore, MD) — a distributor/fabricator that operates at the intersection of supply and place-based specification. Distributors and fabricators hold leverage where code-compliance documentation and local inventory accelerate project wins.
- Roseburg (Medite FR) (Roseburg, OR) — a mill-level manufacturer of fire-rated wood panels and MDF. Vertical manufacturers with their own treatment or panel lines can manage margin by controlling conversion steps, but must invest in certification and testing to sustain premium positioning.
- Garnica (Duraply, Spain with US operations) — an international producer that brings full-panel fire resistance treatments and alternative species into regional markets. Cross-border producers can exploit species and treatment differences as differentiation tactics for price and performance-conscious buyers.
- Koppers Performance Chemicals — a raw-material supplier providing high-temperature retardant formulations. Chemical suppliers shape the economics of FRTW production; their innovation cycles and supply commitments are a critical lever for manufacturers.
Market concentration is material: our CR metrics show the top three players control a substantial share and the top five an even larger portion. This structure implies that strategic moves — such as expanding distribution partnerships, securing preferential chemical supply, or investing in lab-based certification — can create asymmetric advantages.
Recent movements worth watching
- Product innovation: new reinforced grades and waterproof premium lines introduced in 2025 signal that product differentiation — not just price — will be a primary battleground. These introductions have been validated with real-world testing protocols that shorten the spec-adoption curve.
- Distribution and channel consolidation: strategic distribution agreements in late 2025 and early 2026 illustrate how treatment specialists are broadening physical presence to capture project-level procurement.
- Industry guidance updates: manufacturer-released design and construction guides that incorporate both code and sustainability guidance are increasingly used by specifiers to reduce ambiguity in product selection.
2026 strategic playbook — actionable moves
- Procurement and raw-material strategy: implement active hedging or dual-sourcing for key retardant chemistries; evaluate long-term supplier agreements with built-in indexation to protect margins during commodity swings.
- Certification and product positioning: accelerate investments in the certifications that matter to specifiers and code authorities; publish application-specific design guides to reduce installation risk and shorten specification cycles.
- Channel and partnership design: pursue targeted distribution partnerships where on-the-ground inventory and spec support create project wins; consider co-branded regional product offerings with local fabricators.
- Portfolio and R&D allocation: prioritize innovations that combine fire performance with weight reduction, moisture resistance, and sustainability claims; consider pilot launches in controlled retrofit or modular-building channels before broad rollouts.
- M&A and capacity moves: screen targets that deliver treatment capacity, specialty chemical formulations, or timber control; use CR concentration data to evaluate the competitive impact of any consolidation.
What we intentionally withhold here — and how to get the rest
In keeping with the “trailer” format, this preview demonstrates the analytical framework and decision-oriented outcomes from our full study without releasing the granular regional splits, application-share tables, product-level pricing grids, or proprietary financial models that form the core of the research deliverable. These elements are available in the full report and in custom briefings that we provide to clients seeking transaction support, go-to-market plans, or procurement redesign.
For leadership teams planning capital allocation, procurement renegotiation, or product launches in 2026, the full study provides the detailed segment economics, scenario models, and contract templates necessary to operationalize the strategic priorities summarized above.
Next steps
- Request the full report for access to complete segment-level modeling, price-sensitivity matrices, and the supply-chain risk toolset.
- Book a 60-minute strategic briefing with our industry team to align the findings to your corporate objectives and receive a tailored action map for 2026.
PW Consulting’s Fire Retardant Plywood Market study translates a complex set of regulatory, supply-chain, and commercial variables into a focused roadmap for decision-makers. Use this preview to orient your 2026 strategy; engage with our team to convert insight into prioritized, executable actions that protect margin and capture growth as the market matures.
For detailed analysis of this topic, please visit the official page: Fire Retardant Plywood Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Guerbet Alcohols Market to Grow at 4.9% CAGR, Reaching $1,648M by 2032
By PW Consulting, 2026-08-02
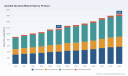
Guerbet Alcohols Market — Strategic Imperatives for 2026
As PW Consulting’s Senior Industry Analyst, I present a concise, decision-focused preview of our full Guerbet Alcohols Market research. This briefing synthesizes the structural trends, competitive shifts, regulatory pressures, and supply‑side dynamics that will shape commercial outcomes in 2026 and beyond. Consider this a high-fidelity trailer: it demonstrates the analytic depth and the levers that matter for executive decisions while reserving the full segment-level tables and proprietary scenario models for the complete report.
Guerbet Alcohols Market
Market trajectory at a glance
The Guerbet alcohols market has moved from an approximate USD 900 Million in 2020 to roughly USD 1,175 Million in the base year 2025, reflecting steady recovery and structural demand growth across personal care, industrial and specialty applications. Our baseline projection for the 2026–2032 forecast window assumes a compound annual growth rate (CAGR) of 4.9% — driving the market toward a mid‑high single‑digit expansion path and an overall market size approaching USD 1,648 Million by 2032 under our core scenario.
Guerbet Alcohols Market
What these topline numbers conceal — and what the full report reveals — is a multi‑speed market. Growth in high‑value, regulated applications (e.g., personal care and pharmaceutical intermediates) sits alongside pockets of cyclicality and capacity volatility in industrial and lubricant end‑uses. Understanding which pockets will expand and which will compress is essential for capital allocation, pricing strategy and product positioning through 2026.
Guerbet Alcohols Market
Report contents — what you will get (operational focus)
- Verified market sizing and trend analysis (historical 2020–2025; base year 2025; forecast 2026–2032) with sensitivity testing to feedstock price, regulatory tightening, and bio‑feedstock adoption.
- Demand‑side segmentation by product family, application cluster and region, built on primary interviews and company disclosures (note: this briefing omits the detailed splits that are available in the full report).
- Supply landscape, including installed capacities, recent expansions, mothballing events and utilization curves for incumbent producers.
- Competitive scorecards for leading suppliers with strategic positioning, product portfolios, and route‑to‑market diagnostics.
- Regulatory and sustainability matrix: REACH/FDA impact assessment, high‑purity compliance pathways and LCA benchmarking.
- Commercial playbooks: pricing playbooks, customer segmentation, margin optimization, and M&A/asset play scenarios.
- Actionable risk heatmaps and three tactical scenarios (Downside, Base, Upside) with trigger points for capital deployment or consolidation.
The full dataset includes downloadable model files and an appendix of primary sources useful for diligence or post‑merger integration planning.
Competitive landscape — synthesis and implications
The Guerbet alcohols value chain is characterized by a tiered supplier base: established multinational chemical houses, regional specialty producers, and an emerging set of bio‑feedstock entrants. Our market concentration analysis indicates the top three players account for a majority share of industry revenues, while the top five push market share concentration materially higher — a structure that supports disciplined pricing but leaves room for targeted disruption.
- BASF SE (Ludwigshafen) — strong technology and surfactant linkage; product breadth across cosmetic intermediates and alkoxylates positions BASF to capture premium personal care demand. Recent partnering activity to scale fermentation routes underscores a strategic move toward renewable pathways.
- Sasol Limited (Johannesburg/Lake Charles) — legacy capability in Guerbet grades with an integrated hydrocarbons value chain. Sasol’s recent asset rationalization and mothballing actions reflect near‑term margin optimization in response to cyclical oversupply.
- Evonik Industries AG (Essen) — capacity expansion to service personal care and specialty chemical end‑markets indicates a targeted growth posture toward higher‑margin segments.
- Regional specialty players (New Japan Chemical, Kisco, Kokyu, Jarchem, Dowpol) — provide technical depth in automotive, coatings and niche industrial applications; they often act as agile suppliers for formulators needing tailored grades and certification support.
Recent market developments amplify two competing forces: on one hand, capacity rationalization (e.g., mothballing of large units) reduces near‑term supply pressure and can support margins; on the other, new, smaller bio‑based facilities and biotech partnerships introduce incremental capacity with a sustainability premium that may reshape buyer preferences. The net effect for 2026 will be selective margin recovery in premium channels and continued price sensitivity in commodity industrial streams.
Regulation, sustainability and feedstock dynamics
Regulatory regimes are a gating factor for market participation. Chemical safety frameworks such as the European Commission’s REACH and complex U.S. regulatory pathways for cosmetic and pharmaceutical applications create a high bar for documentation, testing and supplier traceability. For buyers and producers alike, compliance investments drive higher entry costs but also create differentiation for certified high‑purity grades.
At the same time, sustainability is a growing procurement filter. Manufacturers with reformulated offerings that eliminate controversial feedstocks (for example, moving away from palm oil derivatives to alternative oils or fermentation‑derived alcohols) gain access to premium personal care and pharmaceutical contracts. Industry activity — partnerships to scale fermentation routes and announcements of bio‑based facilities — suggests a near‑term bifurcation between conventional petrochemical routes and renewably sourced supply chains.
Implications for 2026 decision‑makers — recommended moves
Executives planning 2026 strategies should treat Guerbet alcohols as a portfolio decision with discrete levers for value creation. Below are prioritized actions based on the report’s analysis.
- Short term (0–12 months):
- Run utilization and margin diagnostics across your asset base; identify low‑margin grades to rationalize or convert to higher‑value derivatives.
- Accelerate regulatory readiness: secure necessary dossiers and third‑party testing for REACH/FDA sensitive applications to prevent lost sales as buyers tighten supplier lists.
- Negotiate flexible off‑take and tolling arrangements with specialty producers to manage demand volatility without committing large capital.
- Medium term (12–36 months):
- Pursue targeted M&A or lease opportunities for underutilized plants made available through mothballing events; these can often be reconditioned at lower cost than greenfield capacity.
- Invest in bio‑feedstock partnerships or tolling agreements to secure renewable routes and claim sustainability premiums in personal care and pharma channels.
- Differentiate via product innovation — focus on alkoxylation and ester derivatives that command higher margins and tighter customer lock‑in.
- Longer term (through 2032):
- Design a dual‑supply strategy: maintain conventional capacity for price‑sensitive industrial customers while scaling renewable offerings for regulated, premium markets.
- Embed LCA and traceability into product specifications to align with evolving procurement standards and to preempt regulatory shifts.
- Build scenario‑based capital plans tied to feedstock price bands and regulatory tightening — use our sensitivity models to define investment trigger points.
How PW Consulting can support execution
Our full Guerbet Alcohols Market report delivers the granular segment tables, regional and application splits, supplier capacity maps, and the financial models you will need to operationalize the recommendations above. PW Consulting also offers bespoke services including:
- Acquisition target screening and diligence using our supplier scorecards and price/margin models.
- Regulatory readiness audits and dossier development programs for REACH and FDA pathways.
- Feedstock sourcing strategies and contract negotiation support for renewable feedstock offtake.
- Scenario planning workshops that convert model outputs into portfolio decisions tied to explicit KPIs.
To preserve confidentiality of our proprietary segmentation and to drive follow‑through by stakeholders, the detailed product‑ and application‑level splits, full regional datasets and downloadable financial models are available only in the full report package. If you are preparing capital plans, negotiating strategic partnerships, or evaluating M&A in 2026, accessing those tables will materially shorten decision cycles and reduce execution risk.
Closing
The Guerbet alcohols market in 2026 presents managers with a classic strategic trade‑off: invest selectively to capture premium, regulated demand and the sustainability premium, or rely on cost and scale to serve cyclical industrial pockets. Our topline projections show a steady growth trajectory (CAGR ~4.9% over the forecast period) but the outcome for individual players will depend on regulatory readiness, feedstock strategy, and targeted capability investments. PW Consulting’s full report and advisory services translate these high‑level signals into executable moves — contact us to obtain the complete dataset and scenario models.
For detailed analysis of this topic, please visit the official page: Guerbet Alcohols Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ferrite Beads Market to Reach USD 1,180 Million by 2032, Growing at 6.8% CAGR
By PW Consulting, 2026-08-02
Ferrite Beads Market 2026: Strategic Preview for C-Suites and Product Leaders
As PW Consulting’s senior strategy advisor and lead industry analyst, I present a concise, decision‑oriented preview of our new Ferrite Beads Market study. This briefing is written to inform 2026 strategic choices — from procurement and product planning to M&A and supply‑chain resilience — while preserving the granular intelligence that makes the full report a must‑have. Consider this a high‑quality trailer: substantive, evidence‑based, and calibrated to provoke the right questions. The detailed segment tables, supplier scorecards and price curves remain accessible only in the complete report.
Ferrite Beads Market
Why this research matters for 2026 decisions
-
Timing: The research uses 2025 as the base year with a 2026–2032 forecast horizon — the interval when many electronics OEMs will finalize roadmaps for next‑generation EV platforms, 5G infrastructure refreshes, and AI‑centric edge devices.
Ferrite Beads Market -
Scale and growth clarity: The ferrite beads market has shown steady expansion through the 2020–2025 historical window and continues on a clear growth path. Our topline sizing demonstrates a sustained compound annual growth rate (CAGR) of 6.8% across the forecast period, offering a predictable macro backdrop for capital allocation and sourcing decisions.
Ferrite Beads Market -
Actionability: The study translates market dynamics into executable options — supplier hedging strategies, design decisions that lower EMI risk without cost inflation, and categories ripe for consolidation — enabling quicker, lower‑risk choices in 2026.
Market trajectory: what the topline tells you
Measured in USD Million, the ferrite beads market has increased materially since 2020 and continues to expand under the influences of electronics miniaturization, rising EMI sensitivity in high‑speed digital systems, and stronger automotive electrification requirements. With a base year of 2025, our forecast to 2032 captures both cyclical and structural drivers — from short‑term supply pressures to multi‑year secular demand. The steady 6.8% CAGR reflects a market that is neither niche nor commoditized: it is large enough to sustain global OEM supply programs and specialized enough that design, qualification and supplier selection still yield meaningful differentiation.
Demand drivers and technology inflection points
-
Miniaturization + Performance: As designers pack more functionality into smaller form factors, ferrite bead selection becomes a tradeoff between footprint, impedance profile and insertion loss. The evolution toward multilayer and high‑impedance chip formulations is reshaping BOM decisions.
-
Automotive and Safety: Vehicle electrification and advanced driver assistance systems (ADAS) place new constraints on EMI control, qualification (AEC‑Q standards) and high‑current handling, shifting some development resources toward automotive‑grade bead technologies and supplier partnerships.
-
High‑frequency, High‑speed Digital: 5G infrastructure, edge compute nodes and next‑gen SoCs increase the frequency bands where beads are required. Recent supplier application notes and board guidelines from major IC vendors have tightened selection criteria, making early engagement between component and system teams essential.
-
Design for Manufacturability (DfM): The push for higher assembly yields and automated optical inspection compatibility is favoring certain package styles and handling characteristics, which influence supplier scorecards beyond pure electrical performance.
Supply chain, raw materials and regulatory tailrisks
Strategic procurement in 2026 must account for an elevated risk profile in raw materials and policy intervention. Updates to critical minerals lists and related U.S. government measures announced in late 2025 and early 2026 have re‑rated materials complexity for magnetic and ceramic components. Those developments, combined with documented workforce and infrastructure constraints in downstream processing, imply potential bottlenecks in the inputs used for ferrite ceramics and conductor materials.
-
Regulatory attention: Recent federal actions highlight a shift toward securing processed critical materials through new trade negotiation frameworks and investment incentives. These interventions could raise near‑term sourcing costs while creating opportunities for vertically integrated suppliers.
-
Labor and capacity: Workforce scarcity and limited processing capacity for certain magnetic compounds create a higher probability of episodic supply tightness. Buyers should expect supplier lead times and qualification timelines to fluctuate, making dual‑sourcing and strategic stocking more valuable.
Competitive landscape — who matters (and why)
The market sits at a moderate concentration level: the top three players hold a meaningful share of industry revenue, while the top five further extend that influence. This concentration profile indicates a balance — suppliers have scale advantages, but nimble regional players and specialized manufacturers still capture targeted design wins. The report’s supplier modules provide a granular lens on capacity footprints, cost structures, quality certifications, and roadmap alignment — the kind of detail that transforms vendor selection from a checkbox exercise into a competitive lever.
-
Global scale and broad portfolios: Established multinational component manufacturers continue to dominate high‑volume chip ferrite supply, leveraging broad passive‑component portfolios and global manufacturing footprints to meet OEM qualification needs and logistics expectations.
-
Specialists and niche innovators: Several regional firms focus on custom form factors, axial beads for cable applications, or wire‑on‑ferrite solutions — strengths that matter when system constraints require nonstandard EMI approaches or rapid prototyping.
-
Recent product and design guidance: Noteworthy market activity through late 2025 and into 2026 (e.g., high‑current automotive bead launches and updated application notes from major IC and component vendors) is forcing a re‑rating of supplier technical leadership and application support capabilities.
What the full report contains (practical tools inside)
Our full study goes beyond narrative. It equips decision‑makers with work‑ready assets tailored for 2026 execution cycles, including:
-
Topline market sizing and short‑term forecast scenarios to stress‑test procurement plans against optimistic, base and downside demand cases.
-
Supplier scorecards that combine technical capability, cost‑to‑serve, qualification lead time and geopolitical exposure into a single procurement decision matrix.
-
Design decision frameworks and an application‑level buyer’s checklist that translate EMI performance needs into prioritized bead selection criteria (impedance targets, current handling, package tradeoffs).
-
Supply‑chain playbooks: dual‑sourcing templates, inventory hedging models and nearshoring versus global aggregation financial comparisons.
-
Risk dashboards: critical‑material exposure analysis, regulatory scenario planning, and a quantified sensitivity matrix to raw‑material price shocks.
-
M&A and partnership guidance: acquisition targets by strategic fit, integration risks, and valuation levers for bolt‑on consolidation in manufacturing or distribution.
Note: to preserve the commercial value of our proprietary work, this preview omits the granular regional and application split tables, price elasticity models, and supplier cost curves — data included in the full deliverable.
Tactical recommendations for 2026 — actions executives can take now
-
Re‑prioritize qualification lanes: Fast‑track automotive and high‑current part qualifications where design wins are strategically important and where supply rigidity can impede product launches. Leverage updated application notes from major IC vendors to shorten iteration cycles.
-
Operationalize dual‑sourcing for critical SKUs: Where long‑lead items or proprietary formulations exist, establish alternative sources and pre‑negotiated consignment agreements to protect launch timelines.
-
Embed material‑risk clauses in long‑term contracts: Given evolving critical minerals policies, include renegotiation triggers and shared‑cost mechanisms for raw‑material pass‑throughs to limit downside exposure.
-
Invest in early supplier co‑engineering: Gain differentiation by engaging suppliers for optimized multilayer or high‑impedance bead designs that reduce downstream PCB rework and EMI-related field failures.
-
Evaluate targeted M&A: Mid‑market consolidation opportunities exist where suppliers combine specialty form factors with manufacturing scale; use our acquisition scorecard to prioritize targets by integration value.
How procurement and engineering teams should use the report
Engineering teams will find the report’s design‑to‑spec matrices immediately useful for reducing trial cycles. Procurement and S&OP leaders can apply the scenario models to align inventory policies with corporate risk tolerance. Finally, strategy and corporate development teams can use our market sizing and concentration measures to model acquisition synergies or green‑field manufacturing investments with clearer ROI horizons.
Recent market signals to watch
-
Supplier innovation: Track launches of high‑current, AEC‑qualified chip beads and new high‑frequency series targeted at space‑constrained automotive and 5G applications — these signal where premium pricing and qualification moat are forming.
-
Design guidance convergence: Updated board and application notes from leading semiconductor and system suppliers are tightening bead selection norms; early adoption reduces rework risk during prototype to production transitions.
-
Policy momentum: New U.S. and international critical‑material policies will reshape supplier risk premiums and may accelerate regional supply‑chain investment; active monitoring is essential for contracts and sourcing strategy.
Final word — why you should read the full report
For 2026, ferrite beads are no longer a purely tactical, low‑value part — they are a lever for product reliability, regulatory compliance and supply‑chain resilience. Our full study converts the topline growth signal and competitive nuance into executable plans: supplier shortlists, negotiation playbooks, engineering selection matrices, and near‑term scenario analyses. If your 2026 decisions hinge on ensuring first‑time‑right product launches, avoiding EMI‑related field incidents, or protecting margins from material and policy shocks, the full report supplies the intelligence you need.
PW Consulting’s complete Ferrite Beads Market report contains the withheld granular segmentation, price models and supplier financials referenced above. For access to the full dataset and a tailored advisory session aligned to your product or procurement roadmap, please visit our report page.
For detailed analysis of this topic, please visit the official page: Ferrite Beads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


