



Category: Healthy Lifestyle
Protein Bars Market Hits $5.6B in 2025, Forecast to $8.8B by 2032 at 6.7% CAGR: PW Consulting
By PW Consulting, 2026-09-07
Strategic Intelligence for the Protein Bars Market: Navigating Growth Trajectories and Competitive Dynamics Through 2032
The global protein bars market stands at a critical inflection point where historical momentum intersects with transformative innovation, shifting consumer preferences, and an increasingly complex regulatory and competitive landscape. Our latest market research report provides a comprehensive, data-grounded framework designed specifically for executives, investors, and strategic planners who must make high-stakes decisions throughout the 2026-2032 horizon. This article serves as a strategic preview of the report's core analytical architecture, highlighting the market's structural evolution, the competitive forces reshaping category boundaries, and the operational intelligence embedded within our methodology. For decision-makers seeking actionable foresight rather than retrospective summaries, the full publication delivers the granular segmentation, pricing elasticity models, supply chain mapping, and scenario-based forecasting required to secure competitive advantage in a category where marginal improvements in formulation, distribution, and brand positioning directly translate into market share gains.
Municipal Signs Market
Macro Growth Architecture: Trajectory, Velocity, and Forecast Horizon
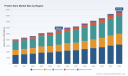
The protein bars category has demonstrated sustained expansion across the historical tracking window, evolving from a niche fitness supplement into a mainstream nutrition vehicle that spans athletic performance, weight management, on-the-go snacking, and specialized dietary lifestyles. Our retrospective analysis documents a consistent upward revenue progression, with the overall market size advancing from approximately 4,066.56 million USD in 2020 through a series of compounded annual increases to reach 5,606.68 million USD in 2025. This historical baseline establishes a clear pattern of resilient demand, even as macroeconomic volatility, inflationary pressures on raw material inputs, and shifting retail channel dynamics periodically tested margin stability across tier-one and tier-two manufacturers.
Quail Meat and Eggs Market
Looking forward, the forecast period extending from 2026 through 2032 signals a structural continuation of this growth trajectory. The projected market valuation expands to 6,032.85 million USD in 2026, progresses through 6,215.18 million USD in 2027 and 6,710.79 million USD in 2028, and ultimately reaches 8,775.52 million USD by the close of 2032. This forward arc is anchored by a compound annual growth rate of 6.7 percent, a velocity that signals healthy category expansion without the speculative overheating characteristic of immature segments. For corporate strategists, this CAGR carries operational implications that extend far beyond headline revenue figures: it informs capital allocation for manufacturing capacity, dictates timing for product pipeline introductions, shapes retail buyer negotiations, and provides a reference frame for evaluating whether internal sales targets are aligned with market-level expansion or whether a company must rely on share capture to outperform the baseline.
Address, Commercial & Residential Signs Market
The report's forecasting architecture does not rely on extrapolated trend lines alone. Instead, it integrates demand-side indicators, channel mix evolution, ingredient cost cycles, and regional adoption curves into a scenario-weighted model that isolates deterministic growth drivers from cyclical noise. Decision-makers using the full publication will find that the forecast horizons are explicitly stress-tested against alternative assumptions around discretionary spending elasticity, private label penetration, and ingredient substitution dynamics. This level of methodological transparency ensures that strategic plans built upon the report's outputs remain robust across multiple operating environments rather than collapsing when a single assumption shifts.
Competitive Landscape: Key Players, Portfolio Strategies, and Differentiators
The protein bars market remains characterized by a concentrated yet fiercely contested competitive environment. Our analysis maps the positioning, operational footprint, and strategic behavior of leading participants whose portfolio decisions directly influence category standards, pricing floors, and consumer expectations. The market concentration metrics indicate that the top three players collectively capture approximately 28.4 percent of total category revenue, while the top five firms hold roughly 34.2 percent. This concentration profile suggests that while scale advantages matter, the market is not so heavily consolidated that innovation, niche positioning, or regional distribution strength cannot meaningfully alter a company's trajectory. The presence of significant headroom for mid-tier and emerging brands reinforces the strategic importance of differentiated product architecture and targeted channel deployment.
Kellogg Company, headquartered in Battle Creek, Michigan, continues to leverage the RXBAR brand as a premium differentiation vehicle, emphasizing minimalist ingredient lists and high protein content that appeal to consumers skeptical of over-processed formulations. Clif Bar & Company, based in Emeryville, California, maintains momentum through Clif Builders and CLIF BUILDERS lines, pairing organic ingredient positioning with ongoing flavor innovation that broadens appeal beyond traditional sports nutrition audiences. ONE Brands, operating under Hershey's umbrella in Philadelphia, Pennsylvania, focuses on ONE Protein Bars with functional nutrition and high-protein formulations, drawing on broader confectionery and snacking capabilities to optimize flavor delivery and supply chain scale. Simply Good Foods Company, located in San Diego, California, sustains a reputation for Quest Nutrition protein bars that lean into high-protein, low-sugar profiles, targeting calorie-conscious and macro-tracking consumers who demand precise nutritional accounting.
Premier Nutrition Corporation, based in San Francisco, California, competes with Premier Protein bars designed around convenient on-the-go formats and high protein levels, reinforcing alignment with busy urban consumers and workplace snacking occasions. KIND LLC, headquartered in Los Angeles, California, offers KIND protein bars built from whole food ingredients with high protein and natural flavors, positioning itself at the intersection of clean-label expectations and functional nutrition. Hearthside Food Solutions, in Downers Grove, Illinois, operates as a co-packer and contract manufacturer supplying protein bars for private label and branded clients, giving it a distinctive strategic vantage point: it benefits from diversified demand while enabling other brands to scale production without heavy fixed-cost exposure. General Mills, in Minneapolis, Minnesota, supplies GHOST Protein Bars through partnership arrangements, producing high-protein bars with layered formats that resonate with lifestyle-oriented and gaming-adjacent audiences. Nestlé S.A., headquartered in Vevey, Switzerland, manufactures Garden of Life and other protein bars with organic and plant-based options, leveraging global sourcing capabilities and sustainability messaging to appeal to health-conscious and ethically motivated consumers.
Glanbia Plc, based in Kilkenny, Ireland, functions as a key supplier of dairy and protein ingredients for the protein bars market, placing it upstream in the value chain and giving it visibility into raw material cost trajectories, ingredient innovation pipelines, and formulation trends that ripple downstream to finished-product manufacturers. Mars Incorporated, headquartered in McLean, Virginia, produces protein bars with functional nutrition and high-protein formulations, extending its broader snacking and confectionery infrastructure into the performance nutrition segment. The interplay between ingredient suppliers, established branded players, contract manufacturers, and partnership-based entrants creates a competitive web where vertical integration, co-manufacturing flexibility, and license or collaboration models all serve as viable strategies.
Recent Developments: Innovation Tempo and Product-Level Execution
The pace of product innovation in the protein bars category has accelerated markedly since early 2026, reflecting a broader industry shift toward flavor parity with conventional snacks, functional ingredient layering, and texture engineering. RAW Nutrition, in February 2026, executed a retail launch of candy-bar-inspired protein bars delivering 18-21g of protein with just 1-5g of added sugar across four flavors, signaling a deliberate attempt to bridge indulgent taste expectations with macro-compliant nutrition. Perfect Snacks followed in March 2026 with a new Protein + Prebiotics line that pairs 20g of protein, prebiotic fiber, and an absence of artificial sweeteners or what the brand characterizes as junk ingredients, reinforcing the clean-label and gut-health adjacency that increasingly matters to premium consumers. Quest Nutrition, also in March 2026, debuted Stacks multi-layered protein bars in flavors such as Salted Caramel and Brownie a la Mode, debuting on Amazon before expanding into retail, a channel sequencing strategy that underscores the continued importance of direct-to-consumer and marketplace testing as a low-risk validation pathway before broader distribution.
LÄRABAR entered the protein segment in March 2026 with LÄRABAR Protein bars offering 10-12g of plant-based protein, a soft chewy texture, and flavors inspired by the original LÄRABAR lineup, effectively using brand equity from a familiar snack architecture to lower adoption friction for consumers new to protein-fortified options. In May 2026, CLIF BUILDERS extended its high-protein lineup with a White Fudge OREO-flavored protein bar, illustrating how established brands continue to mine recognizable flavor cues to drive repeat purchase and broaden flavor cardinality without diluting nutritional positioning. Collectively, these developments point toward a category that is no longer satisfied with functional parity alone; instead, successful entrants and incumbents are engineering consumption experiences that replicate the sensory appeal of conventional confectionery and snacks while preserving the protein density and sugar control that originally anchored consumer trust.
Strategic Market Dynamics: Regulation, Labeling Risk, Ingredient Innovation, and Trade Architecture
The operational environment for protein bars manufacturers and investors has grown more nuanced as regulatory scrutiny, labeling accuracy disputes, and ingredient science intersect with everyday commercialization decisions. Our report devotes substantial analytical attention to the regulatory and litigation context that can affect brand trust, reformulation timelines, and consumer perception. Notably, David Protein has faced a class action lawsuit filed in January 2026 alleging that protein bar labels misrepresent calories and fat content, with actual values allegedly exceeding FDA safe-harbor limits. Complementary consumer testing conducted by ConsumerLab in 2025 on David Protein bars confirmed discrepancies in fat content, attributed in part to a plant-based fat alternative labeled as fat. These developments highlight a broader compliance risk theme: as protein bars occupy shelf space alongside conventional snacks and meal replacements, the expectation for label integrity intensifies, and measurement methodology, rounding conventions, and ingredient classification choices become commercially significant rather than purely technical.
From a trade and import perspective, the HS Code for protein bars remains a practical tool for US import classification and tariff determination under 10-digit HTS structures, an operational detail that matters for companies managing cross-border sourcing, private label imports, and multi-region distribution networks. Simultaneously, packaging and labeling compliance monitoring conducted across 2025-2026 reports has not identified new packaging taxes or nutritional labeling mandates specific to protein bars, suggesting that near-term regulatory pressure is more likely to manifest through enforcement of existing labeling standards and litigation risk than through sweeping new category-specific mandates. The report synthesizes these dynamics into a practical risk matrix, enabling teams to anticipate reformulation triggers, label review priorities, and supplier auditing emphasis without overreacting to speculative regulatory headlines.
Report Content Architecture: Operational Intelligence Embedded Across Sections
The full market research report is structured to move beyond high-level sizing and trend commentary, delivering a modular content architecture that supports distinct decision workflows across strategy, sales, procurement, and investor relations. The report opens with a comprehensive market overview and segmentation layer that maps the category across product type, application intensity, and geographic footprint, establishing the foundational structure through which revenue drivers, substitution patterns, and adoption velocities are analyzed. Rather than presenting segments as static snapshots, the report treats them as dynamic systems, tracing how consumer migration between high-protein, moderate-protein, and lower-protein formats responds to pricing, taste leadership, and functional claim credibility.
The competitive landscape section extends beyond brand profiles to examine portfolio architecture, channel prioritization, manufacturing and co-packing arrangements, ingredient sourcing dependencies, and partnership or licensing models that shape each player's offensive and defensive capabilities. This enables readers to identify where scale advantages are durable, where niche positioning remains defensible, and where contract manufacturing or white-label pathways lower the barrier to entry for new formulations. The report's dynamics section integrates demand-side behavioral shifts, distribution channel evolution, regulatory and labeling considerations, raw material cost exposure, and flavor and texture innovation trends into a unified operating environment assessment. This synthesis is particularly valuable for teams that must articulate to internal stakeholders why certain initiatives are prioritized over others, since it ties market-level signals directly to strategic sequencing.
Pricing and revenue architecture receive focused treatment through scenario-based analysis that relates volume growth, value optimization, and channel mix changes to overall market expansion. Rather than relying on single-point estimates, the report models plausible outcome ranges and identifies the variables most likely to move results, giving decision-makers a framework for sensitivity testing their own internal plans. The research methodology and data sources are disclosed with enough granularity to establish credibility while preserving confidentiality around proprietary inputs, ensuring that the analysis can be defended in investment memos, board discussions, or commercial negotiations.
Why This Research Matters for 2026 Decision-Making
For executives planning through 2026 and beyond, the strategic value of this research lies in its capacity to convert market-level signals into decision-grade intelligence. The 6.7 percent CAGR and the projected expansion from approximately 6,032.85 million USD in 2026 to 8,775.52 million USD by 2032 do more than describe a growing category; they define the scale of the opportunity and the urgency of disciplined execution. Companies that treat the protein bars market as a commodity shelf segment risk ceding share to competitors who invest in flavor leadership, clean-label credibility, functional differentiation, and channel-specific positioning. Conversely, organizations that can align product architecture with the right protein intensity, price tier, and consumption occasion can capture disproportionate value even in a moderately concentrated market where the top three and top five players hold 28.4 percent and 34.2 percent of revenue, respectively.
The report also supports more granular questions that emerge during planning cycles: which product types and application intensities are expanding fastest, which geographic regions are showing the strongest demand momentum, how are leading brands sequencing product launches across retail and digital channels, and what operational risks around ingredient sourcing, labeling accuracy, and import classification could affect margin or brand trust. By embedding these questions within a structured analytical framework, the research helps teams move from reactive interpretation of news flow to proactive scenario planning. Recent launches from RAW Nutrition, Perfect Snacks, Quest Nutrition, LÄRABAR, and CLIF BUILDERS are not treated as isolated headlines but as indicators of where consumer expectations are migrating and which sensory and nutritional trade-offs are proving commercially viable.
Leadership teams evaluating market entry, portfolio extension, capacity investment, or partnership opportunities will find that the report's research architecture is designed to reduce uncertainty at the moments that matter most: before committing to a formulation strategy, before negotiating retail placement or private label terms, before scaling co-manufacturing capacity, and before communicating growth expectations to investors or boards. The combination of historical validation, forward-looking scenario analysis, competitive profiling, and dynamics mapping provides a single reference point that aligns cross-functional teams around a shared understanding of the category's direction.
Conclusion: Accessing the Full Strategic Intelligence
This article has outlined the report's analytical scope, the market's growth architecture, the competitive and innovation dynamics shaping the category, and the operational intelligence embedded within the research. The figures presented here establish the macro context: a category expanding from 5,606.68 million USD in 2025 toward 8,775.52 million USD by 2032, guided by a 6.7 percent CAGR and supported by sustained demand across high-protein formulations, meal replacement applications, sports nutrition use cases, and snack-oriented consumption occasions. Yet the real strategic leverage lies in the details that sit beneath these headline numbers: segment-specific growth differentials, regional adoption patterns, pricing and channel sensitivities, competitive positioning nuances, and the evolving regulatory and ingredient landscape that will determine which brands thrive on execution rather than mere presence.
To access the full segmentation data, detailed competitive profiles, scenario models, and operational recommendations that can be applied directly to 2026 planning cycles, we invite you to explore the complete Protein Bars Market market research report. The source publication provides the depth, precision, and decision-oriented structure necessary for teams that need more than a market overview—they need a strategic roadmap calibrated to the realities of a category where growth is real, competition is intense, and consumer expectations are rising faster than ever.
For detailed analysis of this topic, please visit the official page: Protein Bars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hair Dryer Market Hits $1,004M in 2025, Projects 6.98% CAGR Through 2032
By PW Consulting, 2026-09-07
Navigating the Thermal Revolution: Strategic Imperatives in the 2026 Hair Dryer Market
Executive Overview: A Market in Transition
The global hair dryer industry is undergoing a profound structural shift, moving beyond simple thermal tools toward sophisticated beauty technology ecosystems. As we enter 2026, the convergence of advanced material science, consumer wellness trends, and complex regulatory landscapes is redefining competitive advantage. This analysis draws from PW Consulting's latest comprehensive market research to outline the strategic landscape for stakeholders aiming to capitalize on emerging opportunities.
Aerospace and Defense Consulting Services Market
Market growth has been robust over the past half-decade, reflecting both post-pandemic recovery in personal care spending and the continuous upgrade cycle in beauty appliances. Revenue streams have expanded significantly, with the global market valuation reaching approximately **$1,004 Million in 2025**. Our forecasts indicate sustained momentum, projecting the market to ascend to **$1,046.98 Million by 2026** and further to **$1,598.0 Million by 2032**. This trajectory underscores a Compound Annual Growth Rate (CAGR) of **6.98%** during the forecast period from 2026 to 2032.
Worldwide Curved Escalator Market
Such growth is not merely a function of volume but is driven by value addition. The transition from basic drying mechanisms to intelligent heat control, ionic conditioning, and serum-infusing capabilities suggests that the average transaction value is increasing. For enterprise strategists, this signals a shift in focus from mass-market penetration to premiumization and technology differentiation as primary revenue levers.
Light-cured Glass Ionomer Cement Market
Market Structure and Segment Dynamics
Understanding the architectural composition of the market is critical for resource allocation. The industry is segmented by connectivity type and application use-case, each exhibiting distinct growth drivers and consumer behaviors. While the corded segment remains the dominant revenue contributor, reflecting entrenched consumer habits and reliability expectations, the cordless segment represents the battleground for future growth. The shift toward portability and travel-friendly designs is accelerating, necessitating heavy investment in battery density and heat management technologies without compromising performance.
In terms of application, the individual consumer segment currently outweighs the professional segment, driven by at-home salon trends and enhanced disposable incomes. However, the professional tier remains a critical anchor for brand credibility. Innovation often trickles down from professional-grade tools to consumer lines, meaning that B2B relationships with salons and stylists are increasingly vital for shaping consumer perception. Companies that fail to maintain a strong presence in professional channels risk obsolescence in the consumer mindshare.
Competitive Landscape and Strategic Positioning
The market is moderately concentrated, characterized by a mix of legacy appliance giants and disruptive technology companies. The top three competitors hold a combined market share of **35.0%**, while the top five firms collectively command **42.0%**. This structure implies a significant opportunity for agile players to capture share through niche innovation, though the dominance of key incumbents ensures that scale and brand equity remain formidable barriers to entry.
PW Consulting's report provides a granular deep dive into the strategies of the market's key architects:
- Dyson Limited (Singapore): Dyson remains the benchmark for premium positioning. Their focus on the Supersonic r™ series exemplifies their strategy of integrating intelligent heat control with precision styling attachments. By treating the hair dryer as a precision engineering product rather than a commodity, they have successfully segmented the high-end market.
- Koninklijke Philips N.V. (Netherlands): Philips continues to leverage its heritage in health and wellness, emphasizing eco-friendly and nurturing hair dryer lines. Their strategy centers on energy-efficient technologies that appeal to the growing segment of environmentally conscious consumers, balancing performance with sustainability claims.
- Conair Corporation (United States): Conair maintains strong relevance through the InfinitiPRO series, bridging the gap between consumer accessibility and professional styling needs. Their focus on advanced ionic and styling technologies allows them to compete effectively across multiple price points, ensuring broad market coverage.
- Panasonic Holdings Corporation (Japan): Panasonic is innovating at the intersection of beauty and technology with its nanoe™ and ELMISTA collections. The recent introduction of the ELMISTA Beautifying Hair Dryer, developed in collaboration with Milbon, highlights a strategy of co-creation to deliver salon-quality serum application directly through the device.
- Revlon (United States): Revlon leverages its strong brand recognition to offer professional and consumer hair dryers featuring ceramic and ionic options. Their approach focuses on delivering perceived salon benefits at accessible price points, maintaining a loyal consumer base through consistent product refreshes.
Recent activity confirms that this competitive set is far from static. In early 2026, Laifen Technology unveiled the Wave Pro and Swift 4 hair dryers at CES 2026. These launches feature 4th-generation brushless motors and portable designs, signaling an aggressive push from emerging Chinese manufacturers into the global premium space. This development, alongside Dyson's March 2025 launch of the Supersonic r™ with advanced heater technology and Panasonic's refreshing of its nanoe™ collection in May 2025, indicates that the pace of product innovation is accelerating. Companies that cannot match the cadence of feature releases risk rapid commoditization.
Regulatory Complexity and Supply Chain Implications
Strategic planning for 2026 and beyond must account for an increasingly fragmented regulatory environment. Compliance is no longer a back-office function but a determinant of market access and brand reputation. Our research highlights several critical developments that should inform procurement, product design, and export strategies.
Safety standards are tightening, particularly in the United States. The U.S. Consumer Product Safety Commission has issued warnings and recalls regarding hair dryers lacking adequate immersion protection devices, citing electrocution risks. Notably, in August 2025, recalls were issued for Empower Brands (Spectrum Brands) Remington hair dryers, and by October 2025, consumers were warned to stop using specific units from online marketplaces like DHGate and Wish.com. These actions underscore the liability risks associated with supply chain opacity and the necessity for rigorous component validation, especially for brands sourcing through complex e-commerce channels.
Trade policy dynamics are also reshaping cost structures. In 2026, Vietnam applied a 0% import duty on hair dryers sourced from China and ASEAN countries under the ACFTA and ATIGA agreements, while simultaneously imposing a 25% preferential duty on units from the United States. For multinational corporations, this creates a compelling incentive to regionalize supply chains. Manufacturing or sourcing from ASEAN jurisdictions can offer significant tariff advantages in key emerging markets, whereas direct exports from the U.S. face heightened cost friction.
Furthermore, sustainability mandates are becoming operational realities. India mandates Extended Producer Responsibility (EPR) certificates under the E-Waste Management Rules 2022, alongside the Foreign Manufacturer Certification Scheme for all imported hair dryers. This requires foreign manufacturers to establish local compliance infrastructure and take accountability for product end-of-life management. Similar trends are likely to spread across other jurisdictions, making EPR integration a prerequisite for long-term market presence in high-growth regions like Asia Pacific and Latin America.
The Strategic Value of PW Consulting's Market Research
In this environment of rapid innovation and regulatory flux, intuition is insufficient. Decision-makers require a data-backed compass to navigate the hair dryer market. PW Consulting's latest market research report is designed specifically to meet the demands of 2026 enterprise strategy. It moves beyond high-level aggregates to provide the actionable intelligence necessary for precise decision-making.
The report serves as a foundational tool for several critical business functions:
- Product Portfolio Optimization: By analyzing the performance and trajectory of different product categories, stakeholders can identify which solution sets are ripe for expansion and which are facing saturation. The report provides the evidence base needed to decide between doubling down on premium ionic technologies or investing in cost-efficient cordless designs.
- Competitive Intelligence: Understanding the specific product moves of key players like Dyson, Panasonic, and Laifen allows companies to anticipate market gaps. The report analyzes recent product launches and collaborations, offering insights into competitor roadmaps and potential vulnerabilities that can be exploited.
- Market Entry and Expansion Strategy: With detailed segmentation data, companies can evaluate the attractiveness of specific regions and application sectors. The report helps identify where regulatory barriers are manageable and where consumer willingness to pay aligns with proposed value propositions, reducing the risk of costly market entry errors.
- Risk Mitigation: The inclusion of regulatory analysis and safety recalls provides a framework for assessing compliance risks. Companies can use this information to audit their own product lines and supply chains, ensuring they meet the stringent requirements of markets like the U.S. and India.
Access to the full dataset is essential. While this overview highlights the macro trends and key players, the complete report contains the nuanced data required to build financial models, set production targets, and negotiate supplier contracts. The ability to benchmark internal performance against market standards and to pinpoint high-growth sub-segments can provide the marginal advantage needed to outperform in a competitive landscape.
Conclusion: Preparing for 2026 and Beyond
The hair dryer market in 2026 is defined by a tension between established dominance and disruptive potential. The revenue projections show a clear upward curve, but capturing share requires more than participation; it demands strategic foresight. Companies must navigate the trade-offs between corded reliability and cordless convenience, manage the complexities of multi-jurisdictional regulation, and keep pace with the technological arms race evident in the latest product launches from Dyson, Panasonic, and new entrants.
The moderation of market concentration suggests that there is room for innovation to reshape the hierarchy. However, the barriers created by brand loyalty, regulatory compliance, and technological sophistication mean that successful entry or expansion requires a well-resourced and informed approach. PW Consulting's comprehensive market research offers this insight. We invite you to access the full report to unlock the detailed segmentation data, regional growth drivers, and deep-dive competitor profiles that will form the backbone of your 2026 strategic plan.
*The complete market analysis, including detailed regional breakdowns, application-specific revenue forecasts, and extensive competitor benchmarking, is available in the full PW Consulting Hair Dryer Market Research Report. Contact our team or visit the source webpage to download the executive summary and secure access to the full intelligence suite.*
For detailed analysis of this topic, please visit the official page: Hair Dryer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fat Filled Milk Powders Market Hits $4.83B in 2025, Growing at 8.92% CAGR Through 2032
By PW Consulting, 2026-09-07
Strategic Intelligence in the Fat Filled Milk Powder Market: Navigating Growth and Volatility Through 2032
The global dairy ingredients sector stands at a critical inflection point, driven by shifting consumer preferences, volatile input costs, and an increasingly complex regulatory landscape. Fat Filled Milk Powder (FFMP) has emerged as a pivotal commodity within this ecosystem, offering a cost-effective alternative to whole milk powder while delivering consistent functional properties for industrial and consumer applications. As we move beyond the base year of 2025, understanding the trajectory of this market is no longer optional for stakeholders aiming to secure competitive advantage. This article serves as an introduction to our comprehensive market research study, designed to equip executives, supply chain managers, and investors with the actionable intelligence needed to navigate the forecast period from 2026 to 2032.
Electric Heating Coasters Market
The strategic importance of FFMP lies in its versatility. By blending skimmed milk powder with vegetable fats, manufacturers can tailor fat content to specific requirements, making it indispensable across bakery, confectionery, dairy processing, and nutritional formulations. However, the value proposition extends beyond mere substitution. It encompasses supply chain resilience, margin optimization, and adherence to evolving food safety standards. Our latest research delves deep into these dimensions, providing a granular view of where value is created, where risks accumulate, and how leading entities are positioning themselves against a backdrop of macroeconomic uncertainty and regional disparities.
Gynecological Swabs Market
Market Trajectory: From Historical Recovery to Accelerated Expansion
Examining the historical performance of the FFMP market reveals a story of steady recovery and structural growth. Between 2020 and 2025, the market demonstrated resilience despite global disruptions, with revenues climbing consistently as industrial demand rebounded and formulation strategies adapted to cost pressures. The data indicates that the market valuation reached significant milestones by the end of the base period, setting a robust foundation for the upcoming forecast cycle.
Lead Component Insertion Machine Market
Looking ahead, the growth momentum is expected to intensify. Our analysis projects a compound annual growth rate (CAGR) of 8.92 percent over the forecast period extending to 2032. This trajectory suggests that the market will surpass key valuation thresholds, reflecting sustained demand from end-use industries and expanding production capabilities in key geographies. The revenue outlook indicates a clear upward curve, with valuations expected to scale substantially by the early 2030s. Such growth is not merely a function of volume expansion but also reflects value addition through premiumization in specific applications and the strategic integration of FFMP into broader dairy ingredient portfolios.
It is crucial for decision-makers to recognize that this growth is not uniform. Regional dynamics, regulatory shifts, and raw material price fluctuations will create pockets of opportunity and risk. The forecasted expansion underscores the need for proactive strategic planning, whether in capacity investment, supply chain diversification, or market entry strategies. Stakeholders who align their roadmaps with these projected trends will be better positioned to capture value as the market matures.
Segmentation Insights: Drivers and Application Landscape
The FFMP market is shaped by distinct segmentation drivers that influence pricing, demand elasticity, and strategic focus. Understanding the interplay between product types and application sectors is essential for optimizing portfolio strategy and identifying high-growth niches.
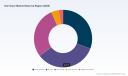
From a product perspective, the market is structured around variations in fat content and processing methods, which cater to different functional requirements. Full cream variants continue to hold significant relevance for applications demanding rich texture and flavor, while partially skimmed and skimmed options serve segments where protein content and lower fat profiles are prioritized. Each variant presents distinct cost structures and margin profiles, influenced by the price of skimmed milk powder and vegetable oils used in the filling process. The balance between these inputs directly impacts production economics, making hedging strategies and supplier relationships critical components of operational excellence.
On the application side, demand is distributed across multiple industrial and consumer-facing sectors. Bakery products represent a major consumption channel, leveraging FFMP for texture, moisture retention, and cost efficiency in large-scale production. Confectionery applications utilize the ingredient for flavor enhancement and structural properties in chocolate and coated products. Dairy product manufacturers incorporate FFMP to standardize fat levels and improve consistency in recombined milk, yogurts, and beverages. Additionally, the infant nutrition segment, while smaller in volume, commands high scrutiny regarding nutritional quality and regulatory compliance, reflecting the sensitive nature of this application. Each application segment carries unique growth drivers, regulatory requirements, and competitive dynamics that warrant dedicated strategic attention.
Regional Dynamics and Supply Chain Realities
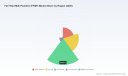
Geographical distribution of FFMP production and consumption reveals pronounced disparities that shape trade flows and investment priorities. Certain regions dominate in terms of production capacity and export volumes, while others serve as high-growth consumption hubs driven by urbanization, rising disposable incomes, and expanding food processing industries. The interplay between these regions creates a complex web of supply dependencies and market opportunities.
In major producing regions, the focus has been on scaling efficiency, adopting advanced drying technologies, and integrating vertically to control input costs. Export-oriented strategies are prevalent, with producers targeting distant markets where FFMP offers a compelling value proposition against local whole milk powder supplies. Meanwhile, emerging consumption regions are witnessing increased demand as food manufacturers seek to optimize formulation costs without compromising on sensory attributes. This dichotomy highlights the importance of regional market intelligence for companies evaluating expansion, partnership, or sourcing strategies.
Supply chain resilience is a recurring theme in the current landscape. Disruptions in logistics, fluctuating currency values, and regional policy changes can abruptly alter the cost-benefit equation of FFMP trade. Producers and buyers alike must navigate these variables with agility, leveraging long-term contracts, diversified sourcing bases, and real-time market monitoring to mitigate exposure. The regional narrative is not static; it evolves with infrastructure development, trade agreement updates, and shifts in agricultural output, all of which are meticulously analyzed in our full report.
Competitive Landscape: Key Players and Strategic Positioning
The FFMP market is characterized by a mix of large multinational dairy cooperatives, specialized ingredient suppliers, and regional producers. While the market concentration metrics indicate a relatively fragmented environment at the top, with the combined share of leading firms reflecting room for further consolidation or niche dominance, individual players leverage distinct advantages to compete.
Lakeland Dairies Co-operative Society Ltd, headquartered in Cavan, Ireland, exemplifies the cooperative model, producing and supplying FFMP as an economical substitute for whole milk powder across dairy drinks, yoghurts, and beverage whiteners. Its position is underpinned by regional milk supply and a focus on cost-competitive industrial solutions. In the United States, Dairy Farmers of America, Inc. manufactures and supplies FFMP as a key dairy ingredient for industrial and foodservice applications, capitalizing on scale and integrated supply chains to serve broad domestic and export markets.
In Europe, Arla Foods amba, based in Denmark, produces high-quality FFMP under recognized brands such as Dano, utilizing skimmed milk and vegetable fat to deliver nutrition for beverages and baking applications. Its brand equity and quality standards provide a competitive edge in markets where consumer trust and specification precision are paramount. FrieslandCampina N.V., headquartered in the Netherlands, stands as a leading producer of FFMP and Lactimilk variants, catering extensively to industrial applications with a focus on consistency and functional performance. These European players benefit from established dairy infrastructures and access to diverse raw material sources.
Regional specialists also play a vital role. Kaskat Dairy, based in Poland, manufactures and supplies FFMP including instant and low, medium, and high protein variants tailored for beverages and yogurt. Its product range illustrates the trend toward customization, where manufacturers differentiate through protein content and solubility features to meet specific client requirements. The competitive landscape is thus defined not only by volume and price but also by technical service, product customization, and reliability of supply. Companies that invest in R&D, quality assurance, and customer collaboration are better equipped to retain and expand their client base in a price-sensitive environment.
Recent Developments and Industry Dynamics Shaping Decision-Making
The FFMP market does not operate in a vacuum. Recent events and structural shifts in related commodity markets are reshaping the strategic calculus for all participants. One notable development occurred in April 2026, when StoneX announced the launch of FFMP as the first contract in a new OTC dairy derivatives suite with Expana for trading. This initiative signals growing financialization and risk management interest in the commodity, providing market participants with new tools to hedge price volatility and manage exposure. The introduction of such derivatives can enhance price discovery and liquidity, but it also requires stakeholders to develop sophistication in trading and risk analytics.
Earlier in November 2025, Laktopol was identified as a leading manufacturer of Instant FFMP with strong export demand, highlighting the ongoing relevance of instantized products in global trade. Instant variants command premium positioning due to their ease of use and rapid dispersion in beverages, aligning with trends in convenience and ready-to-mix applications. Export demand strength suggests that certain producers are successfully capturing international market share, leveraging product differentiation and reliable supply credentials.
Underlying these corporate developments are macro-level dynamics that exert continuous pressure on costs and compliance. The vegetable oil price index rose 17.1 percent above 2024 levels in 2025, directly affecting the input cost structure for FFMP production. Since vegetable fat is a critical component in the filling process, such price movements can compress margins for producers who have not secured favorable input contracts or passed costs through to buyers. Simultaneously, EU skim milk powder exports were revised to 420,000 tons for 2025, down 5.0 percent from 2024, indicating tighter supply conditions for the skimmed base material. These supply-side adjustments ripple through the value chain, influencing production planning and pricing power.
Quality and regulatory scrutiny have also emerged as critical themes. Investigations have linked pesticide residue contamination in FFMP to specific Irish dairy firms supplying West Africa markets, with one product found to contain excess fat and insufficient protein. Reports further indicate that EU and UN Food and Agriculture Organisation food codes of practice were breached by a Lakeland Dairies FFMP product supplied to Africa due to fat and protein imbalance. These incidents underscore the reputational and compliance risks inherent in cross-border dairy trade, particularly where regulatory oversight may vary. In response, Irish dairy firms received substantial public funding for FFMP trade missions to West Africa markets, illustrating the strategic importance of these regions and the support mechanisms available to promote exports. However, such funding and market access must be balanced with rigorous quality management to sustain long-term trust and market presence.
What the Full Study Delivers: Operational Intelligence for Execution
Our comprehensive market research report goes beyond high-level trends to provide the operational intelligence required for execution. The study is structured to support strategic planning, risk assessment, and opportunity capture across multiple dimensions of the FFMP value chain.
Central to the report is a detailed demand and supply analysis that maps production capacities, capacity utilization trends, and consumption patterns across key geographies. This analysis helps identify imbalances, surplus regions, and deficit markets, enabling stakeholders to optimize sourcing and distribution strategies. The report also provides a thorough pricing analysis, examining historical price movements, cost drivers, and the impact of input volatility on end-product pricing. Understanding these dynamics is essential for negotiating contracts, setting pricing strategies, and forecasting margin trajectories.
The study includes an in-depth competitive benchmarking section that profiles key market participants, assessing their product portfolios, geographic footprints, strategic initiatives, and recent developments. This benchmarking allows companies to gauge their positioning relative to peers, identify gaps in their offerings, and uncover potential collaboration or acquisition targets. Additionally, the report delves into regulatory and compliance frameworks, highlighting food safety standards, certification requirements, and regional trade policies that affect market access. For companies operating in or targeting markets with heightened scrutiny, this section offers practical guidance on maintaining compliance and mitigating risk.
Application-specific insights are provided to help stakeholders tailor their go-to-market strategies. By dissecting demand drivers, formulation trends, and customer requirements across bakery, confectionery, dairy, and nutrition segments, the report enables targeted product development and marketing efforts. Supply chain and logistics considerations are also addressed, with analysis of transportation costs, storage requirements, and import-export dynamics that influence total landed cost and service levels. Finally, the report incorporates scenario planning and risk assessment tools, allowing users to model the impact of variables such as input price shocks, policy changes, and demand fluctuations on their business outcomes.
Strategic Recommendations for the 2026 Planning Cycle
As organizations finalize their plans for 2026 and beyond, several strategic imperatives emerge from the current market landscape. First, margin management must be a top priority given the volatility in vegetable oil and skimmed milk powder prices. Companies should evaluate hedging instruments, long-term supply agreements, and formulation flexibility to buffer against input swings. The availability of new OTC derivatives for FFMP may offer additional avenues for risk mitigation, provided internal teams have the capability to utilize them effectively.
Second, quality assurance and compliance infrastructure require continuous investment. The recent incidents involving fat-protein imbalance and residue concerns highlight that product integrity is non-negotiable, especially when supplying sensitive markets or applications. Robust testing protocols, transparent sourcing, and adherence to international food codes can protect brand reputation and ensure uninterrupted market access. Third, regional strategy should be reassessed in light of shifting supply dynamics and trade support mechanisms. Markets with strong export demand and supportive public funding may present growth opportunities, but they also demand careful due diligence on regulatory expectations and quality benchmarks.
Fourth, product differentiation through customization can create defensibility in a competitive market. Offering instantized variants, tailored protein levels, or specialized functional attributes allows suppliers to move beyond commodity competition and build stronger customer relationships. Finally, market intelligence must be institutionalized. Regular monitoring of capacity announcements, policy updates, and competitor moves ensures that strategies remain aligned with evolving realities. Our full report is designed to serve as a foundational resource for this ongoing intelligence effort, providing the data, analysis, and insights needed to make informed decisions.
Conclusion: Positioning for Sustainable Value Creation
The Fat Filled Milk Powder market presents a compelling blend of growth potential and complexity. With a projected CAGR of 8.92 percent through 2032 and a market trajectory that reflects sustained industrial demand, the sector offers significant opportunities for those who can navigate its nuances. Yet, realizing this potential requires more than optimism; it demands rigorous analysis, proactive risk management, and strategic agility. The interplay of input cost volatility, regulatory scrutiny, regional disparities, and competitive dynamics creates an environment where informed decisions can make a decisive difference.
Our market research study provides the depth and breadth of insight necessary to transform uncertainty into actionable strategy. By integrating historical performance, forecast projections, segmentation analysis, competitive profiling, and real-time industry developments, the report equips stakeholders with a holistic view of the market landscape. We invite you to explore the full study to access the detailed data, region-specific breakdowns, and application-level intelligence that will support your planning and execution. In a market where margins, compliance, and supply chain reliability are constantly tested, having the right intelligence is the first step toward sustainable value creation.
For detailed analysis of this topic, please visit the official page: Fat Filled Milk Powders (FFMP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pan Masala Market Hits $272.45M USD in 2025, Forecasted 6.25% CAGR to 2032
By PW Consulting, 2026-09-07
# Pan Masala Market Strategic Outlook 2026: Navigating Growth, Regulation, and Competitive Shifts
Executive Summary: The Strategic Imperative for 2026
The Pan Masala industry stands at a critical inflection point in 2026. As regulatory frameworks tighten and consumer preferences evolve, stakeholders require more than surface-level data to navigate the coming years. This article serves as a strategic preview to our comprehensive market research report, designed to equip executives, investors, and policy analysts with the contextual intelligence needed to make informed decisions. The following analysis synthesizes historical performance, forward-looking projections, and the dynamic competitive landscape to highlight where value will be created—and where risks lie—over the forecast period.
Emtricitabine and Tenofovir Disoproxil Fumarate Tablets Market
Our latest study covers the historical trajectory from 2020 through the base year of 2025, extending a detailed forecast horizon to 2032. This long-view approach allows decision-makers to distinguish between temporary market fluctuations and structural shifts. The insights presented here underscore the necessity of aligning supply chain strategies with emerging compliance mandates while capitalizing on shifting consumption patterns across key demographic segments.
circRNAs Treatment Market
Market Trajectory and Macroeconomic Drivers
The revenue landscape for the Pan Masala sector has demonstrated resilience over the past half-decade. Analyzing the historical data from 2020 to 2025 reveals a market that has navigated volatile raw material costs and shifting demand curves to deliver consistent growth. In 2020, the market size stood at approximately 235.45 Million USD. By the base year of 2025, this figure had climbed to 272.45 Million USD. This progression underscores a sector that, despite external pressures, maintains a steady upward trajectory.
Logistics Transportation Market
Looking forward, the forecast period from 2026 to 2032 indicates an acceleration in value generation. Projections suggest the market will reach 355.63 Million USD by 2030. The compound annual growth rate (CAGR) for the forecast period is estimated at 6.25 percent. This growth rate is significant for a mature consumer goods sector, implying that underlying drivers such as population growth, urbanization, and changing palate preferences are continuing to expand the total addressable market.
Several macroeconomic dynamics are fueling this expansion. A notable supply-side factor is the performance of the areca nut sector. Data indicates that areca nut exports from India increased by over 20 percent in 2024. This surge supports the core ingredient supply chain for Pan Masala production, potentially mitigating some volatility in input costs compared to previous cycles. For manufacturers, this signals a potentially more stable procurement environment, though logistics and export demand must still be monitored closely.
However, growth cannot be viewed in isolation from the regulatory environment. The dynamics of the market are being reshaped by recent government interventions. As of February 2026, the Legal Metrology (Packaged Commodities) Rules mandate complete declarations on all Pan Masala packages. This includes Mandatory Price Print (MRP), Net Quantity, Month and Year of Manufacture, and Unique Selling Proposition (USP) details, regardless of package quantity. This regulation increases compliance overheads but also standardizes consumer information, potentially benefiting larger players with robust quality control systems.
Furthermore, fiscal policies have tightened. New HSNS (Health Security and National Security) Cess structures were introduced in February 2026. This cess is capacity-based, requiring payment linked to installed manufacturing machines, alongside a GST rate of 40 percent on the retail selling price. These measures are designed to curb consumption and generate revenue, but they fundamentally alter the cost structure for manufacturers. Strategic planning now must account for these levies in pricing models and margin calculations. Additionally, draft Food Safety and Standards (Packaging) Amendment Regulations proposed in April 2026 suggest further restrictions on packaging materials, adding another layer of operational consideration for 2026 and beyond.
Competitive Landscape and Concentration Dynamics
The Pan Masala market is characterized by a high degree of concentration, which has significant implications for market entry strategies and competitive positioning. Our analysis indicates that the top three players command a combined market share of 78.45 percent. When expanding the view to the top five entities, the concentration rises to 92.67 percent. This oligopolistic structure suggests that barriers to entry are substantial, whether due to distribution networks, brand equity, or regulatory compliance capabilities.
Within this concentrated environment, specific corporations have defined their niches through product differentiation and brand heritage. The Dharampal Satyapal Group (DS Group), headquartered in Noida, Uttar Pradesh, maintains a dominant presence through its flagship Rajnigandha brand. Recent activities highlight their focus on premium positioning; in July 2025, DS Group launched a new Television Commercial (TVC) for Rajnigandha centered on craftsmanship and quality. This marketing push aligns with their portfolio of premium and saffron-coated offerings, signaling an intent to capture higher value segments despite regulatory headwinds.
Manikchand Group, based in Pune, Maharashtra, offers a contrasting strategic approach. Their portfolio includes the RMD and Manikchand brands, with a notable emphasis on herbal and tobacco-free variants. This diversification suggests a response to health consciousness among certain consumer cohorts and potentially positions them to navigate regulatory scrutiny differently than traditional tobacco-containing products. Similarly, Godfrey Phillips India Ltd. in Mumbai continues to leverage the Pan Vilas brand alongside their broader tobacco and pan masala product range, utilizing established distribution channels to maintain volume.
Kothari Products Ltd., located in Kanpur, Uttar Pradesh, remains a key player through the Pan Parag brand. Their focus extends to a broader mouth freshener portfolio, allowing them to cross-sell and maintain relevance across different consumer touchpoints. Meanwhile, Pan Bahar Products Private Limited, established in New Delhi in 1962, relies on long-standing consumer trust in their mouth fresheners and pan masala products. Their longevity highlights the importance of brand heritage in a market where trust and habitual consumption drive loyalty.
The high concentration levels imply that innovation and compliance efficiency are the primary levers for the incumbents to defend their market share. For new entrants or smaller regional players, the path to growth likely lies in niche segments or specific geographic pockets where the top five players have less density, though the 40 percent GST and capacity-based cess may pressure margins across the board.
Segmentation and Consumption Patterns
Understanding how the market splits across regions, types, and applications is vital for targeting strategies. While the aggregate numbers show growth, the distribution of value varies significantly. The Asia Pacific region represents a substantial portion of the revenue, reflecting the cultural embeddedness of the product in key markets like India. North America and Europe also contribute, though their shares differ, indicating varying levels of diaspora consumption and niche market presence. Latin America and the Mideast and Africa regions, while smaller in aggregate value compared to Asia Pacific, still represent active markets where distribution networks are expanding.
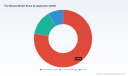
In terms of product type, the market is bifurcated primarily between Packaged Pan Masala and Loose Pan Masala. Packaged variants dominate the revenue share, which aligns with the regulatory push for standardization. The requirement for complete declarations on packages favors the organized sector over loose, unbranded variants. This shift suggests a continued migration of consumers toward branded, packaged options where quality assurance and regulatory compliance are visible. The "Others" category also holds share, representing specialized or regional variants that do not fit standard classifications.
Application-wise, Personal Consumption is the primary driver of revenue. The bulk of market activity stems from individual end-users purchasing for direct consumption. Commercial Distribution, while smaller in comparison, represents a critical channel for hospitality sectors, retail outlets, and bulk buyers. The "Others" application segment captures ancillary uses or specific institutional channels. For strategic planners, the dominance of Personal Consumption means that brand marketing, packaging appeal, and point-of-sale visibility remain paramount. However, changes in Commercial Distribution channels due to taxation or hospitality industry shifts can also impact overall volume flow.
Strategic decisions regarding where to allocate marketing spend or distribution resources should be informed by these segmentation dynamics. For instance, shifting regulatory burdens on packaging may disproportionately affect loose variants, potentially accelerating the shift toward packaged goods. Companies must decide whether to compete on volume in the mass market or on margins in premium packaged segments, keeping in mind the 6.25 percent CAGR target requires capturing value across these splits.
Strategic Priorities for Stakeholders in 2026
Navigating the 2026 landscape requires a multi-pronged approach. For existing manufacturers, compliance is no longer optional but a core component of operational strategy. The dual impact of the Legal Metrology Rules and the HSNS Cess means that production capacity planning must be recalibrated. Manufacturers need to assess whether their installed machine capacity triggers higher cess payments and whether the cost of compliance can be absorbed or must be passed on to consumers via pricing adjustments.
Supply chain resilience is another priority. With areca nut exports showing strong growth, securing consistent raw material supply is favorable, but global logistics and potential export demand spikes from other regions could influence local availability and pricing. Building robust supplier relationships and potentially diversifying sourcing regions could mitigate risks associated with single-source dependencies.
For investors and analysts, the high market concentration suggests that betting on the top tier players may offer more stability, given their ability to absorb regulatory costs and leverage existing distribution. However, the 6.25 percent CAGR indicates room for growth, possibly through innovation in product variants such as tobacco-free options or premium packaging that justifies higher price points under the new GST regime.
Marketing strategies must also evolve. The new regulations require clear declarations on all packages. This level of transparency can be leveraged by premium brands to emphasize quality and safety, distinguishing themselves from lesser-known variants. The recent TVC launch by DS Group exemplifies how brand storytelling around craftsmanship can reinforce premium positioning. Competitors may need to adopt similar narrative strategies to maintain relevance in a crowded, high-tax environment.
Furthermore, the draft regulations on packaging materials proposed by FSSAI in 2026 indicate that sustainability and material safety will become increasingly important. Companies that proactively adapt their packaging to meet these upcoming standards may avoid disruption later and appeal to environmentally conscious consumers, adding a non-price competitive advantage.
Conclusion: Accessing Deep-Dive Intelligence
The Pan Masala market in 2026 is defined by a tension between steady growth drivers and intensifying regulatory constraints. The transition from a 272.45 Million USD market in 2025 to a projected 410.67 Million USD by 2032 offers significant opportunity, but realizing this value requires precise navigation of the new tax structures, packaging mandates, and competitive concentration. The high barrier to entry, evidenced by the 92.67 percent CR5 concentration, means that strategic moves by the leading players will likely set the tone for the entire industry.
This article has provided a high-level overview of the market dynamics, key players, regulatory shifts, and segmentation trends. However, successful execution requires granular data that goes beyond macro trends. Strategic decisions regarding specific regional entry points, detailed cost modeling under the new cess structures, and precise competitor benchmarking demand a deeper level of intelligence.
To fully equip your organization for the challenges and opportunities of the 2026-2032 forecast period, we invite you to access the complete Pan Masala Market Research Report. The full study provides detailed segmentation data, exhaustive competitor profiles, and scenario-based modeling that will allow you to quantify risks and identify specific growth vectors tailored to your strategic objectives. Download the complete report to gain the comprehensive intelligence needed to lead in this evolving market.
For detailed analysis of this topic, please visit the official page: Pan Masala Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Titanium Dental Implants Market to Grow at 6.1% CAGR Through 2032
By PW Consulting, 2026-09-07
Titanium Dental Implants Market: Strategic Intelligence for 2026 Leadership
Executive Overview: Navigating the Next Growth Cycle
The global dental implant sector is entering a decisive phase of maturation, driven by aging demographics, rising adoption of immediate-loading protocols, and continuous material science innovation. As senior leadership teams map out capital allocation, product portfolio strategies, and geographic expansion for 2026 and beyond, the Titanium Dental Implants Market stands out as both a stability anchor and a growth engine. Our latest Titanium Dental Implants Market research synthesizes five years of historical tracking with a forward-looking forecast horizon, delivering the kind of calibrated intelligence that boards, commercial teams, and R&D leaders require when committing to long-cycle capital deployment.
Trocar Catheter Market
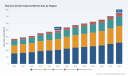
From a base year perspective in 2025, the titanium implant segment has sustained a consistent upward trajectory. Historical tracking from 2020 through 2025 demonstrates a clear compounding pattern of revenue expansion, while the extended forecast window through 2032 outlines a measured but structurally sound growth path. The sector is projected to navigate a compound annual growth rate of 6.1 percent across the forecast period, a figure that reflects both incremental volume gains and value realization through premium surface engineering, digital integration, and procedure-specific system design.
Removable Toilet Height Raiser Market
For executive decision-makers, the strategic question is no longer whether titanium implants will continue to dominate implant dentistry, but how to time investments, differentiate offerings, and manage competitive exposure in a market where consolidation pressure, reimbursement complexity, and regulatory rigor are intensifying simultaneously. This research is designed to answer that question with operational precision.
Video Conference Recording Software Market
Market Architecture and Trajectory: Reading the Growth Signal
Historical Momentum and Forecast Framing
The market’s historical footprint reveals a resilient demand base that has weathered pricing scrutiny, supply chain variability, and shifting clinical preferences without losing structural momentum. Over the 2020 to 2025 period, revenue progression reflects sustained clinician confidence in titanium’s mechanical reliability, biocompatibility, and long-term restorative performance. The base year valuation of 494.69 million USD in 2025 marks a meaningful step up from the 2020 starting point of 369.62 million USD, underscoring a sector that has moved beyond early adoption dynamics and into a phase where procedural volume, clinical efficiency, and product segmentation are primary growth levers.
Looking ahead, the forecast path extends from 2026 through 2032, with revenue projections scaling toward 750.30 million USD by the end of the forecast horizon. This progression is not simply a mechanical extrapolation; it reflects the compounding effects of improved surgical workflows, growing acceptance of full-arch rehabilitation, and continued refinement of implant surface technology. Critically, the 6.1 percent CAGR across this multi-year window indicates that growth will remain dependent on both new patient acquisition and upgraded clinical adoption patterns rather than a single disruptive catalyst.
Leaders evaluating market entry, SKU rationalization, or regional prioritization should treat this trajectory as a structural signal. It implies continued opportunity for differentiated titanium platforms, particularly where clinicians seek shortened treatment timelines, improved soft-tissue responses, and materials that can withstand high functional load while maintaining aesthetic outcomes.
Value Creation Around the Core Titanium Segment
Titanium implants remain the foundational material category in implant dentistry because they combine proven osseointegration performance with flexible prosthetic compatibility. Within the broader market architecture, titanium systems are distributed across multiple clinical types and procedural pathways, each with distinct adoption drivers and revenue dynamics. The dominant share captured by endosteal systems reflects their entrenched role in routine bone-level and tissue-level placements, while subperiosteal and other specialty configurations continue to serve more complex anatomical indications.
From an application standpoint, single-stage and two-stage procedural approaches remain central to market participation. Single-stage workflows are increasingly favored in contexts where clinician efficiency, patient convenience, and digital planning convergence are priorities. Two-stage protocols retain relevance in cases requiring staged bone management or where biological optimization is paramount. These procedural distinctions matter because they influence implant design choices, surface treatment strategies, purchase unit economics, and the way manufacturers position their systems to clinical networks.
For strategy teams, the key insight is that the titanium market is not a uniform commodity space. It is a layered ecosystem where procedural preferences, surgeon training, case complexity, and practice economics shape which products win in a given setting. Our research breaks down these layers so that commercial leaders can match portfolio strategy to real-world adoption patterns instead of relying on broad category assumptions.
Competition and Strategic Positioning: Who Shapes the Market
Incumbent Leadership and Competitive Concentration
The competitive landscape is defined by a concentrated group of multinational manufacturers, each pursuing distinct value propositions around surface chemistry, thread geometry, platform modularity, and digital compatibility. Market concentration remains substantial, with the largest three competitors holding approximately 45.2 percent combined share and the top five reaching roughly 62.5 percent. This concentration reflects the advantages of scale in regulatory compliance, surgeon education, clinical evidence generation, and global distribution infrastructure.
Straumann Group continues to anchor its positioning on the Straumann Dental Implant System, with titanium and TiZr alloy options supported by surface treatments such as SLActive that are designed to accelerate osseointegration across tissue-level and bone-level applications. Its Swiss-based manufacturing heritage and broad clinical acceptance give it enduring relevance in premium and performance-oriented segments.
Nobel Biocare maintains a strong identity around TiUnite surface titanium implants and All-on-4 systems for full-arch restorations, emphasizing precision placement and long-term stability. For practices focused on comprehensive rehabilitation and repeatable full-arch outcomes, this system represents a clinically recognizable reference point.
ZimVie has built its profile around T3, T3 Pro, TSX, and short titanium implants, integrating hybrid surfaces to support immediate molar cases and tissue preservation objectives. Its January 2026 introduction of the TSX Surgical Kit for modular titanium implant systems illustrates how incumbents are continually expanding clinical versatility through procedural toolkits as well as implant hardware.
Dentsply Sirona markets the EV implant family and Ankylos systems with titanium options, aligning its portfolio with digital integration across single-tooth and full-arch workflows. In August 2025, the company released a new Implant Product Selection Guide on its U.S. e-commerce platform, a move that reflects an increasingly digital and guidance-driven purchasing environment.
Hiossen focuses on immediate-loading titanium implants alongside digital engine systems, targeting single-unit, partial, and full-arch cases. Its product architecture appeals to practices seeking streamlined immediate function pathways and compatible digital instrumentation. MegaGen Implant contributes another competitive angle through AnyRidge and BLUEDIAMOND titanium implant systems, leveraging advanced thread designs for initial stability and mechanical strength. Osstem Implant further diversifies the field with KS series titanium implants and one-piece abutment structures designed for durable posterior and general applications.
Beyond these larger-scale players, regional and mid-tier manufacturers contribute meaningful variety and price differentiation. BioHorizons offers Tapered Internal and full-arch titanium implants with Laser-Lok and conical connections for aesthetic and immediate-loading outcomes, and in May 2026 released SmartShape Healers, anatomically shaped scannable healing abutments for titanium implants. Surcam Dental manufactures Grade 4 and Ti-6Al-4V Grade 5 titanium implants and prosthetics under FDA 510(k) clearance, while Acrotec Medtech serves as a component and implant supplier to other manufacturers with FDA registration and ISO 13485 compliance.
This competitive mix matters because success in the titanium implant market is increasingly determined by combination factors: material specification, procedural compatibility, digital traceability, and the credibility of clinical support. Our report examines these dimensions in detail to help leaders determine where differentiation is achievable and where scale or partnership models are more appropriate.
Operational and Regulatory Realities Shaping Strategy
Compliance, Clearance, and Quality Systems
Any serious go-to-market or expansion plan must account for the regulatory environment that governs titanium implant commercialization. In the United States, titanium dental implants require 510(k) clearance for marketing, which shapes product launch timing, documentation requirements, and the ability to introduce materially modified designs. At the same time, manufacturers must comply with ISO 13485:2016 quality management systems and FDA 21 CFR 820, creating an operational baseline that influences cost structure, supplier qualification, and production controls.
Sterility assurance remains an equally important compliance dimension. Implants are typically packaged with validated sterility assurance levels aligned to ISO 11135, reinforcing the importance of validated packaging, sterilization, and distribution controls throughout the supply chain. For companies evaluating contract manufacturing, vertical integration, or new facility investments, these standards are not optional details; they are strategic constraints that determine speed to market and long-term operational resilience.
Reimbursement and Cost Dynamics
Pricing and payment pathways are another decisive competitive factor. Titanium dental implants generally average between 1,500 and 4,000 dollars per implant depending on system design, procedural complexity, and clinical setting. That wide range reflects more than material cost alone; it encompasses surgical planning, restorative integration, clinician training, practice overhead, and patient financing expectations. Leaders must understand where their product sits within this value band and what clinical or logistical attributes justify positioning above or below the typical range.
Reimbursement conditions also influence adoption speed and patient affordability. Original Medicare does not cover dental implants, including titanium fixtures, which means a substantial portion of the U.S. patient base relies on private insurance, out-of-pocket payment, or third-party financing. This reality shapes demand elasticity, the attractiveness of premium versus value-tier systems, and the importance of practice-level financial counseling and patient education. In markets where reimbursement is fragmented or limited, manufacturers that can improve procedural efficiency and reduce total episode cost may gain meaningful purchase preference even without altering the underlying implant material.
Why This Research Matters for 2026 Decision-Making
Turning Market Structure into Actionable Strategy
Data alone does not guide strategy; interpretation does. This Titanium Dental Implants Market research translates market size, forecast trajectory, segmentation behavior, and competitive dynamics into a decision-ready framework. It is built for teams that need to answer practical questions: which procedural categories offer the strongest near-term pull, where titanium systems face substitution pressure or differentiation opportunity, how regulatory requirements affect launch sequencing, and what market concentration implies for pricing discipline and channel strategy.
The analysis integrates current industry context so that executives can assess market movement with realistic constraints in mind. Reimbursement limitations, regulatory clearance requirements, quality-system obligations, and implant-level cost ranges are treated as strategic parameters rather than background notes. Likewise, recent product events such as Dentsply Sirona’s enhanced implant selection guidance on its U.S. e-commerce platform, ZimVie’s TSX Surgical Kit introduction, and BioHorizons’ release of scannable healing abutments are evaluated as indicators of how manufacturers are competing on workflow, usability, and digital compatibility—not just hardware.
This combination of forward-looking forecast data, segmentation logic, competitive profiling, and operating-environment context allows strategy leaders to prioritize with greater confidence. Whether the objective is portfolio optimization, market entry, partnership identification, or regional expansion, the research is structured to reduce ambiguity around where value is being created and how competitive advantage can be sustained.
What the Report Delivers for Commercial and R&D Teams
Organizations using this research can expect a comprehensive operating picture, including detailed historical and forecast revenue development across the forecast period, along with the underlying structural drivers that shape adoption. The report examines segmentation behavior across implant type and procedural application without reducing the market to blunt averages, helping teams understand how different practitioner settings, case types, and clinical goals influence demand patterns.
The competitive section maps the positioning strategies of major participants, highlighting how incumbents and challengers are investing in surface treatment, thread geometry, modularity, digital integration, and procedural support. It also places recent product launches and catalog releases in context, so that readers can interpret product activity as part of a competitive rhythm rather than as isolated announcements.
Regulatory and quality-system considerations are addressed with practical attention to clearance pathways, manufacturing compliance expectations, and sterilization standards that affect commercialization timing and supply chain design. Cost and reimbursement dynamics are framed so that leaders can assess affordability, pricing strategy, and patient payment pathways as part of the broader demand equation.
Importantly, the full study goes further than the market-level indicators summarized here. It provides the kind of segment-level granularity and scenario framing that supports internal planning, investment committee discussion, and cross-functional alignment between commercial, regulatory, and product teams. Detailed regional nuances, application-level revenue breaks, and precise competitive share structures are developed within the full report to support precise strategic choices.
Looking Ahead: Building Advantage in a Concentrated, Regulation-Intensive Market
Titanium implants are likely to remain central to implant dentistry for the foreseeable future, but the market’s growth will be earned through clinical credibility, workflow compatibility, and operational discipline rather than material prevalence alone. Companies that succeed in 2026 and beyond will be those that can align product architecture with real procedural demand, navigate regulatory and quality expectations efficiently, and position themselves against a concentrated set of well-resourced competitors without relying on undifferentiated price competition.
This Titanium Dental Implants Market research is designed to support that challenge. It offers leadership teams a grounded, data-informed view of where the market is heading, how the competitive field is shaping up, and which operational realities must be built into strategy from the start. For organizations seeking to make more informed decisions about product investment, commercial targeting, and long-horizon growth, the complete report provides the deeper segmentation, competitive detail, and forecast structure needed to act with confidence.
For detailed analysis of this topic, please visit the official page: Titanium Dental Implants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Organic Soy Lecithin Market Hits $50M in 2025, Projected to Reach $80.42M by 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for the Organic Soy Lecithin Market Through 2032
The global shift toward clean label formulations and plant-based functionalities has positioned organic soy lecithin as a critical ingredient across food, feed, and personal care supply chains. As consumer demand for verified organic inputs intensifies, manufacturers and procurement leaders face a complex landscape defined by evolving regulatory frameworks, tightening raw material availability, and concentrated supplier markets. PW Consulting’s latest Organic Soy Lecithin Market report provides a comprehensive, data-backed roadmap for navigating these dynamics from 2026 through 2032. This article outlines the strategic architecture of the study and highlights the analytical frameworks designed to support executive decision-making in procurement, product development, and market expansion.
Boot & Shoe Fabrics Market
Market Trajectory and Base Year Context
The organic soy lecithin market has demonstrated consistent upward momentum over the past half-decade. Revenue expanded from approximately 38.1 million USD in 2020 to an estimated 50.0 million USD in 2025, reflecting sustained adoption across multiple end-use sectors. The forecast period from 2026 to 2032 projects continued growth, with the market expected to reach roughly 80.4 million USD by the terminal year. This trajectory corresponds to a compound annual growth rate of 7.1 percent, underscoring the ingredient’s expanding role in premium and certified organic product portfolios.
Enterprise Unified Storage Market
The historical baseline from 2020 through 2025 reveals a market that has matured beyond early-adopter phases into a more structured commercial environment. Growth during this window was supported by broader consumer interest in plant-derived emulsifiers, increased formulation complexity in food and beverage categories, and rising preference for non-GMO and certified organic inputs. The forecast window builds on this foundation, but introduces new variables that require strategic foresight rather than linear extrapolation. Supply chain reconfiguration, regulatory compliance costs, and raw material price volatility will shape margin structures and sourcing strategies in ways that demand scenario-based planning.
Kitchen Brushes Market
For enterprise planners, the 2026 starting point is particularly relevant. Early forecast figures indicate market revenue approaching 53.5 million USD, with progressive expansion through the latter half of the decade. The pace of growth suggests that capacity allocation, supplier qualification, and specification standardization will become increasingly important differentiators. Organizations that align their sourcing and formulation strategies with verified supply pathways will be better positioned to capture value as certification requirements and traceability expectations tighten globally.
Segment Architecture and Application Landscape
The market is structured across multiple segmentation dimensions that reflect both physical form preferences and end-use demand patterns. Product formats span liquid, powder, and granular variants, each serving distinct processing requirements and formulation constraints. Liquid lecithin remains the dominant format by revenue contribution, driven by its ease of integration in continuous processing lines and compatibility with beverage and confectionery applications. Powder and granular forms occupy complementary roles, particularly where moisture control, shelf stability, or dry-blend compatibility are prioritized.
Application demand is distributed across several key categories, with food and beverages representing the largest share of market revenue. This segment benefits from direct consumer-facing formulation trends, including clean label emulsification, texture optimization, and lipid-derived functional benefits. Animal feed represents the second major application channel, where lecithin functions as a nutrient carrier and emulsifying aid in specialized feed matrices. Cosmetics and personal care applications contribute a meaningful demand stream, leveraging lecithin’s emulsification, moisturization, and formulation stabilization properties. Pharmaceuticals and related nutraceutical channels add further demand, particularly where bioavailability and excipient functionality are critical. Additional application categories round out the demand base, supporting specialized industrial and formulation uses.
Type-based segmentation interacts closely with application requirements. Liquid forms are often preferred in high-volume food processing environments, while de-oiled powder variants are selected for dry mixing, encapsulation, and formulations requiring reduced lipid content. Granular formats serve niche processing needs where controlled flow characteristics or specific dispersion profiles are required. The report examines these format-application interactions in detail, mapping processing preferences against end-use performance requirements and identifying where substitution dynamics may influence procurement decisions.
Regional distribution reflects uneven demand intensity and differing regulatory environments. North America, Europe, and Asia Pacific represent the largest revenue pools, each shaped by local certification standards, formulation conventions, and supply chain maturity. Latin America and the Middle East and Africa contribute additional demand, with growth trajectories influenced by expanding food manufacturing capacity, evolving feed industry requirements, and increasing import dependence for certified organic inputs. The study provides a structured regional comparison that emphasizes relative market size, demand drivers, and sourcing implications without reducing complex market behavior to simplistic share declarations.
Competitive Landscape and Supplier Archetypes
The organic soy lecithin market exhibits a moderately concentrated competitive structure. CR3 concentration stands at 62.0 percent, while CR5 concentration reaches 75.0 percent, indicating that a relatively small group of specialized producers and supply aggregators accounts for a substantial portion of market revenue. This concentration has strategic implications for procurement resilience, pricing negotiation, and qualification lead times. Buyers must balance the advantages of working with established, certified suppliers against the risks of over-reliance on a limited supplier base, particularly as organic soybean availability fluctuates and regulatory documentation requirements increase.
Several companies illustrate the dominant supplier archetypes in this market. Clarkson Specialty Lecithins operates as a dedicated North American producer of certified organic and non-GMO soy lecithin in liquid and de-oiled powder forms, using water-based mechanical extraction from organic soybeans. Its profile reflects a specialist model focused on certified organic integrity and regional supply continuity. Lecico GmbH, based in Hamburg, manufactures organic soy lecithin in liquid and de-oiled forms alongside phospholipids, with certifications spanning food, feed, and nutraceutical applications. This positioning highlights a European manufacturing base oriented toward multi-application certification and ingredient functionality.
Lecitein Limited, headquartered in the United Kingdom, supplies and manufactures organic soy lecithin in liquid and powder formulations, with organic certifications targeted at global food and personal care markets. Its commercial model emphasizes export-facing supply and cross-market certification alignment. Scoular Company, based in Chicago, supplies soy lecithin in liquid and dry forms, including non-GMO and GMO-free variants sourced from soybeans for food, feed, and industrial use. Scoular’s role demonstrates the importance of broad commodity sourcing capability alongside certified variant offerings. Natural Sourcing, LLC, operating in the United States, provides certified organic soy lecithin liquid and powder with non-GMO options for personal care and food formulations, reflecting a sourcing-and-supply model that bridges ingredient authenticity with formulation flexibility.
Beyond these specialist and supply-focused players, recent industry developments illustrate how larger agribusiness and supply chain integrators are expanding their organic lecithin capabilities. In March 2026, Archer Daniels Midland Company established an organic soy lecithin supply chain using identity-preserved organic soybeans from certified US and Brazilian farms, targeting the organic food manufacturing segment. This move signals a strategic push into identity-preserved sourcing and downstream ingredient value capture. In May 2026, ADM implemented a strategic partnership with a leading organic soybean farming cooperative in Asia-Pacific to expand supply chain capabilities and ensure consistent quality of organic soy lecithin. These developments underscore a broader trend in which integrated sourcing networks, identity-preserved certification, and regional cooperative partnerships are becoming central to supply reliability.
For buyers and competitors alike, the strategic question is not simply who supplies the market, but how certification integrity, extraction methodology, regional sourcing footprint, and application-specific quality consistency interact to create supplier advantage. The report evaluates these dimensions across the competitive set, focusing on sourcing reliability, certification coverage, format capability, and alignment with major application channels.
Regulatory, Raw Material, and Supply Chain Dynamics
Market participation in organic soy lecithin increasingly depends on the ability to navigate regulatory complexity and raw material variability. On the regulatory front, the implementation of EU Organic Regulation 2018/848 requires stricter traceability and import controls for organic lecithin, increasing compliance costs and documentation burdens for suppliers and buyers operating in or exporting to European markets. In parallel, EU Deforestation Regulation compliance costs, effective from December 2025, are requiring additional documentation for Brazilian soybean-derived lecithin exports. These requirements do not merely add administrative overhead; they reshape qualification timelines, supplier onboarding processes, and the relative attractiveness of different origin geographies.
In the United States, raw material dynamics are introducing additional pressure on organic and non-GMO supply. U.S. non-GMO soybean planting declined 16 percent in 2024 compared to 2023, with only 4 percent of total soy acres dedicated to non-GMO production. This contraction constrains the organic and identity-preserved raw material base that underpins certified organic lecithin supply. At the same time, the U.S. soybean farm price forecast rose to 11.40 dollars per bushel for the 2026/27 marketing year season, up from 10.40 dollars per bushel in 2025/26. Higher input costs, combined with tighter ending stocks forecast at 310 million bushels for 2026/27, down 30 million bushels from the revised 2025/26 projection, suggest that raw material pricing and availability will remain central variables for margin planning.
These dynamics create a market environment in which pricing is influenced not only by demand growth but also by certification stringency, origin eligibility, and farm-level supply constraints. Buyers must assess whether supply agreements provide sufficient security around identity-preserved organic inputs, whether documentation processes can withstand evolving import controls, and whether formulation specifications allow flexibility across liquid, powder, and granular formats without compromising functional performance. The report incorporates these dynamics into a structured analysis of market risk factors, compliance exposure, and supply chain resilience strategies.
The interplay between regulation and raw material economics also affects regional sourcing strategies. Origin selection increasingly involves trade-offs among certification compatibility, traceability documentation, logistics cost, and functional consistency. For companies with European market exposure, EU organic and deforestation-related compliance requirements may influence supplier selection and origin diversification. For North American procurement teams, tighter non-GMO planting and higher soybean price forecasts may increase the importance of long-term identity-preserved contracts and multi-format supplier relationships. The study provides decision frameworks that translate these macro-level pressures into actionable sourcing and formulation considerations.
What the Report Delivers for Strategic Decision-Making
This market study is designed to support practical executive use rather than passive information consumption. The analysis integrates historical performance, forecast trajectory, segmentation structure, competitive profiles, and regulatory-raw material dynamics into a coherent decision-support framework. The following elements represent the core components of the report’s operational value:
- Structured market sizing and forecast logic covering the base year, historical period, and 2026 to 2032 outlook, with explicit attention to growth drivers, demand shifts, and format-application interactions.
- Segment-level analysis across product type, application, and region that clarifies where demand concentrates, how formats align with processing needs, and which channels present the strongest expansion potential.
- Competitive profiling of key suppliers and supply-chain integrators, focusing on certification coverage, extraction and processing approaches, regional footprint, and application alignment.
- Recent development tracking, including supply chain expansion initiatives and partnership-driven sourcing models that illustrate how major players are reshaping organic soy lecithin availability.
- Regulatory and raw material context that connects compliance requirements, organic and non-GMO acreage trends, soybean price forecasts, and ending stock projections to sourcing risk and margin exposure.
- Strategic implications for procurement, product development, and market entry, including guidance on supplier qualification, format selection, origin diversification, and documentation readiness.
The report is structured to help leaders answer practical questions: Which application channels offer the most defensible growth under current regulatory and raw material conditions? How should procurement teams balance concentration risk against certification reliability? Which format choices align with specific processing environments and formulation goals? Where do recent supply chain expansions and partnership models change the competitive calculus for buyers and rivals? By addressing these questions within a unified analytical framework, the study supports more confident planning across R&D, procurement, sales, and corporate strategy functions.
Why This Study Matters for 2026 Decisions
The 2026 decision environment for organic soy lecithin is defined by simultaneous forces: steady demand growth, concentrated supplier structures, tightening certification and traceability requirements, and raw material cost and availability pressures. In this environment, qualitative assumptions are insufficient. Procurement strategies must account for identity-preserved supply integrity, formulation teams must evaluate format substitution without sacrificing functional performance, and commercial leaders must assess where regulatory exposure alters the attractiveness of specific origin markets and supplier relationships.
PW Consulting’s Organic Soy Lecithin Market report provides the analytical depth required to navigate these choices. It combines forecast discipline with competitive and regulatory context, enabling organizations to translate market growth into actionable plans. The study is particularly relevant for companies seeking to secure reliable certified supply, evaluate entry or expansion opportunities in food, feed, personal care, or pharmaceutical applications, and understand how recent supply chain developments and compliance requirements are reshaping the competitive landscape.
For readers seeking the full set of market size figures, segmentation detail, competitive assessments, and scenario-based implications, the complete report offers the comprehensive intelligence necessary for rigorous strategic planning. The analysis presented here highlights the structure and strategic logic of the study; the full document delivers the detailed data and decision frameworks needed to operationalize these insights across procurement, R&D, and commercial strategy.
As organic certification expectations rise and supply chains become more documentation-intensive, the organizations that succeed will be those that combine market awareness with supplier qualification rigor, format flexibility, and compliance readiness. This report is designed to support exactly that combination, giving decision-makers a clear, evidence-based foundation for the choices that will shape their organic soy lecithin positioning through 2032.
For detailed analysis of this topic, please visit the official page: Organic Soy Lecithin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Aquarium Market to Hit $6.32 Billion by 2032 at 6.98% CAGR
By PW Consulting, 2026-09-07
Navigating the Currents: Strategic Intelligence for the Global Aquarium Market in 2026 and Beyond
Setting the Stage: A Market Poised for Sustained Growth
The global aquarium sector stands at a critical inflection point. As we move deeper into 2026, the industry is no longer viewed merely as a niche hobbyist segment but as a resilient, diversified market driven by health and wellness trends, ornamental aquaculture expansion, and evolving commercial hospitality demands. For corporate strategists, investors, and product developers, understanding the directional flow of this market is essential. The difference between reactive supply chain adjustments and proactive portfolio positioning often comes down to the fidelity of the underlying intelligence.
Scanning Laser Ophthalmoscopy (SLO) Market
Our latest comprehensive research on the Aquarium Market provides the structural backbone needed to navigate this complex landscape. Drawing on historical data from 2020 through 2025 and projecting forward through 2032, the analysis captures both the steady accumulation of value over the past half-decade and the accelerated momentum expected in the coming years. The market has demonstrated remarkable consistency, expanding from a baseline of approximately 3,193 million USD in 2020 to an estimated 3,972 million USD by 2025. This trajectory reflects not just recovery from earlier disruptions but a fundamental broadening of demand vectors.
Chlorhexidine Gluconate Liquid Soap for Hand and Skin Disinfection Market
Looking ahead, the forecast period from 2026 to 2032 paints a picture of compounding opportunity. The market is projected to reach roughly 4,151 million USD in 2026, climbing steadily to surpass 6,322 million USD by the end of the forecast window. Driving this expansion is a compound annual growth rate of 6.98 percent, a figure that underscores the sector's ability to outperform broader consumer discretionary averages in specific sub-segments while maintaining broad-based stability. For leadership teams evaluating capital allocation, entry modes, or product-line extensions, this growth profile signals a market that rewards patience, precision, and a clear grasp of structural tailwinds.
Four Burner Gas Stove Market
Why 2026 Demands a Re calibrated Strategic Lens
The year 2026 is not simply another step along a linear growth curve. It represents a convergence of shifting consumer preferences, supply chain recalibration, and regulatory scrutiny that collectively redefine competitive advantage. Firms that continue to rely on legacy assumptions about regional demand or material preferences risk misallocating resources in a market where the payoff for accuracy is increasingly pronounced.
Several macro forces are reshaping the decision-making environment. On the consumer side, the post-pandemic emphasis on home environment enhancement has matured into a more sophisticated demand for integrated, aesthetically cohesive water features that blend seamlessly with modern interior design. Simultaneously, commercial operators in hospitality, corporate spaces, and public institutions are treating aquariums as experiential assets that drive dwell time, brand differentiation, and guest engagement. These dual engines are pulling the market in complementary directions, creating opportunities for vendors who can straddle both residential and commercial value chains with tailored offerings.
On the supply and operational side, the emphasis on sustainability and ethical sourcing is moving from a peripheral concern to a boardroom priority. Initiatives such as the Marine Aquarium Market Transformation Initiative, supported under the Global Environment Facility, are actively promoting sustainable sourcing of marine ornamentals, signaling that compliance and traceability will increasingly influence market access and brand reputation. At the same time, regulatory dialogues continue to evolve, with recent policy engagements, such as the National Aquarium's call for public comment on proposed Endangered Species Act changes in late 2025, highlighting the growing intersection of ornamental trade and conservation policy. For market participants, these developments are not abstract background noise; they are early indicators of the compliance frameworks and sourcing standards that will shape procurement strategies throughout the forecast period.
What This Research Delivers: An Operational Blueprint
Our market study is designed to translate high-level trends into actionable intelligence. The report moves beyond descriptive snapshots to build a structured, decision-ready analytical framework that spans the full value chain. It is built for functional leaders who need to answer concrete questions: How should product portfolios be weighted across material types? Which application segments offer the most defensible growth in the near term? Where do competitive densities create both threats and partnership opportunities?
The analysis dissects the market along multiple dimensions, providing a granular view of how demand is distributed and how that distribution is likely to shift. At the broadest level, the overall market size and growth trajectory set the context, but the real strategic value lies in understanding the composition beneath that headline number. Readers will find detailed segmentation that maps revenue flows across material categories, application environments, and geographic regions, allowing teams to stress-test assumptions and align resource deployment with the segments that match their core competencies.
Beyond segmentation, the report incorporates a deep competitive landscape review. Rather than treating major players as isolated brand snapshots, the analysis situates them within the operational and strategic logics that define their market positions. Profiles examine product focus, geographic footprints, and value proposition differentiation, giving readers a clear sense of where incumbents derive their edge and where openings exist for new entrants or expanding players. Recent developments are integrated to show how alliances, distribution agreements, and product launches are actively reshaping the field, ensuring that the competitive picture reflects current momentum rather than static history.
The study also contextualizes market dynamics through the lens of regulation, sustainability, and industry collaboration. By weaving in the latest policy signals and multi-stakeholder initiatives, the report equips decision-makers to anticipate compliance requirements, assess reputational risk, and identify strategic partnerships that align with evolving standards. This is not theoretical context; it is a practical layer of intelligence that feeds directly into sourcing, market entry, and product development roadmaps.
Decoding the Competitive Arena: Leaders, Niches, and Alignment
The competitive structure of the aquarium market is characterized by a blend of global incumbents with broad portfolios and specialized operators that command strong reputations within particular sub-segments. Our analysis highlights ten core companies whose strategies and product orientations collectively illustrate the diversity of value creation in the sector.
At one end of the spectrum are firms with wide-ranging care and system offerings. Companies such as API Fishcare and Seachem Laboratories anchor significant portions of the market through filtration technologies, water care treatments, and accessory ecosystems that support both novice and advanced users. Tetra and sera bring similarly broad perspectives, though their strategic emphasis differs: Tetra's portfolio centers on water care, aquarium kits, and fish products with a strong consumer-facing presence, while sera focuses on fish foods, treatments, filter media, and technical water-care solutions across aquariums, ponds, and terrariums. These broad-based players often serve as default references for retailers and hobbyists, making distribution reach and brand trust critical competitive assets.
Other firms pursue highly specialized positions that command premium loyalty within focused communities. Red Sea has built a strong identity around reef aquarium systems, with an integrated emphasis on lighting, pumps, dosers, skimmers, reef salt, coral food, supplements, and test kits. Aqua Design Amano distinguishes itself through the philosophy and engineering of nature aquarium systems, supported by specialized lighting and CO2 supply products that appeal to enthusiasts invested in planted and naturalistic setups. Innovative Marine targets saltwater enthusiasts with stands, starter kits, and accessories, while Coralife has carved out visibility through BioCube nano reef aquariums, lighting, filtration, and marine salt mixes designed for compact, accessible marine environments. On the custom side, Custom Aquariums serves buyers seeking tailored glass fish tanks and DIY setups, addressing a segment where personalization and build quality drive purchasing decisions.
Geographic and distribution strategies add another layer of complexity. Aquarium Industries, based in Australia, operates extensively in ornamental fish breeding and the wholesale supply of aquarium products, including a significant role in sera distribution. The relationship between sera and Aquarium Industries exemplifies how partnership and distribution alignment can reshape regional availability. In mid-2025, the two organizations announced exclusive cooperation in Australia, with the first sera delivery arriving in June 2025 and fish food and care products subsequently becoming available through Aquarium Industries and its stocklists across the country. This kind of targeted distribution launch matters because it demonstrates how global product portfolios can be localized through strategic partnerships, expanding reach without requiring each brand to build independent wholesale infrastructure from scratch.
Taken together, the competitive landscape reflects a market where breadth and depth can both create advantage, depending on the segment and geography. The reported market concentration figures reinforce this interpretation. With a CR3 of 24.6 percent and a CR5 of 26.2 percent, the market is relatively fragmented at the top, indicating that no small group of firms dominates the total value pool. This fragmentation is strategically significant: it suggests room for specialized players to thrive, for regional leaders to gain share through distribution and service quality, and for larger portfolios to compete on assortment and convenience. It also means that competitive intelligence must be segment-sensitive, because share dynamics and pricing power vary meaningfully across material types, applications, and geographies.
Reading Between the Lines: What the Headline Numbers Really Signal
The aggregate growth path of the market is compelling, but its strategic meaning becomes clear only when linked to the structural composition underneath. The segmentation data reveals how demand is distributed across the core dimensions that matter most to product planning and go-to-market strategy.
On the material side, the market is anchored by a dominant category that reflects long-standing consumer and installer preferences, with a substantial share of total revenue flowing through that channel. Complementary material categories also command meaningful presence, indicating that buyers are not locked into a single default option across all use cases. This balance suggests that material choice is increasingly tied to application requirements, aesthetics, installation context, and total cost of ownership rather than habit alone. For manufacturers and suppliers, the implication is that product development and inventory strategy should be calibrated to the specific demands of each material segment, including the service, durability, and design expectations that accompany it.
The application split further illuminates where value is being created. Residential demand constitutes a large proportion of total market revenue, reflecting the enduring pull of home aquariums as both hobbyist projects and interior enhancements. Commercial applications, while smaller in total share, represent a distinct and strategically important demand stream with different purchasing cycles, specification requirements, and value propositions. Commercial buyers often prioritize reliability, maintenance support, integration with larger spatial designs, and compliance with institutional standards. Recognizing the operational differences between these application environments is essential for firms that intend to serve both without diluting focus or misaligning their sales and service models.
Regional distribution adds yet another layer of strategic nuance. The data indicates that North America and Europe together account for the majority of revenue, reflecting mature hobbyist cultures, established retail and specialty channels, and strong commercial installation ecosystems. Asia Pacific, Latin America, and the Middle East and Africa collectively represent substantial additional demand, though their profiles differ in terms of retail infrastructure, ornamental supply chains, and growth momentum. For firms evaluating expansion, the key takeaway is that regional strategy cannot be uniform. Channel development, partner selection, product mix, and pricing architecture must be adapted to local purchasing behavior and regulatory expectations. Our report preserves these regional distinctions as decision variables rather than collapsing them into a single global average, because the strategic implications are too significant to obscure.
Beneath the segmentation itself is the broader growth arithmetic. With the market expected to expand from just over 4,150 million USD in 2026 to more than 6,322 million USD by 2032, the cumulative value added across the forecast period is considerable. This is not only a question of top-line expansion; it is a question of where incremental value accrues and how competitive positions will evolve as the pie grows. In a market with moderate concentration, growth can create opportunities for multiple winners if they are aligned with the right segments, channels, and value propositions. The risk is that firms chase the aggregate number without mapping it to the segments and geographies that best fit their capabilities, leading to diluted execution and missed share gains.
Implications for Capital Allocation, Product Strategy, and Market Entry
The strategic value of this research lies in its ability to reduce uncertainty at the moments when choices are hardest. For portfolio managers, the segmentation and growth mapping provides a basis for prioritizing investment across material types, application environments, and regions. Instead of treating the market as a monolith, teams can model scenarios that reflect the actual distribution of demand and the relative attractiveness of each segment given their existing assets, manufacturing capabilities, and distribution relationships.
For product and innovation leaders, the analysis supports more disciplined roadmapping. Understanding which material and application combinations drive the largest revenue pools helps clarify where incremental improvement, premiumization, or ecosystem building is likely to yield the strongest returns. It also helps identify where hybrid solutions might matter, such as products that bridge care and systems, or accessories that enhance both residential aesthetics and commercial maintainability. In a market where incumbents like Red Sea, API Fishcare, sera, Aqua Design Amano, Seachem, Tetra, Coralife, and Innovative Marine each hold strong positions through distinct product logics, new or extending players need a clear theory of differentiation. This study supplies the context needed to make that theory specific rather than generic.
For distribution and market entry planning, the competitive and regional profiles sharpen the assessment of channel economics and partnership opportunities. The example of the sera and Aquarium Industries cooperation illustrates how distribution alignment can unlock regional availability efficiently. For firms considering new geographies or new retail formats, the report's regional and competitive detail helps answer practical questions about where established players already defend strong positions, where fragmentation leaves room for agile entrants, and where partnerships may be more effective than standalone build-outs.
For risk and compliance planning, the integration of regulatory and sustainability context is especially important. The ongoing work around sustainable sourcing of marine ornamentals and the continued evolution of policy discussions affecting ornamental trade mean that sourcing integrity and documentation will increasingly influence market access and brand perception. Firms that embed these considerations into procurement, supplier selection, and product claims early will be better positioned than those that treat them as retrospective adjustments. The research frames these issues not as peripheral concerns but as core elements of long-term competitiveness.
Looking Forward: Turning Intelligence into Advantage
The aquarium market in 2026 is defined by both momentum and complexity. Growth is real and structurally supported, but the path to capturing it is not uniform. Success depends on seeing the market in its segmented reality, understanding the strategic logic of the leading players, and anticipating the regulatory and sustainability shifts that will shape procurement and positioning over the coming years.
Our full study is designed to give decision-makers the resolution they need to act with confidence. It connects the macro trajectory to the segment-level detail, the competitive map to recent developments, and the regulatory backdrop to practical planning choices. The result is a research asset that can be used across strategy, product, sales, and supply chain functions without forcing teams to reconstruct the underlying logic from fragmented sources.
The insights summarized here are intended to establish the analytical foundation and demonstrate the depth of the full report. The complete version expands on every dimension discussed above, offering the detailed segmentation views, competitive profiles, regional breakdowns, and dynamic scenario framing that leadership teams need to translate market potential into concrete decisions. For organizations ready to move beyond high-level direction and into precise, evidence-based strategy, the full research provides the missing layer of clarity.
About PW Consulting
PW Consulting delivers industry intelligence and strategic advisory services for businesses operating in complex, fast-evolving markets. Our research combines rigorous data analysis with practical commercial context, helping clients align investment, product, and market-entry decisions with the realities of demand, competition, and regulation. This Aquarium Market study reflects our ongoing commitment to producing actionable, decision-ready intelligence for executives, investors, and operational leaders.
For detailed analysis of this topic, please visit the official page: Aquarium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hand Magnets Market Surpasses $215 Million in 2025, Projected to Hit $292.6 Million by 2032 at 4.5% CAGR According to PW Consulting
By PW Consulting, 2026-09-02
Redefining Manual Material Handling: The Strategic Imperative for Hand Magnets in 2026
Executive Summary: Navigating a Maturing Magnetic Tools Market
As industrial operations worldwide pivot toward greater automation, stricter safety protocols, and resilient supply chains, the hand magnets market finds itself at a critical inflection point. What was once considered a commoditized category of workshop tools has evolved into a strategically significant segment within the broader industrial lifting and material handling ecosystem. Our latest market research, covering historical performance from 2020 through 2025 and extending a detailed outlook to 2032, provides enterprise leaders with a rigorously structured intelligence framework to navigate procurement, product development, and competitive positioning in the years ahead.
Hand Magnets Market
The narrative of this market is no longer defined by simple volume growth. It is increasingly shaped by material cost volatility, geopolitical trade realignments, engineering standardization, and the growing convergence between manual handling tools and semi-automated workcell architectures. For executives making capital allocation, sourcing, and market entry decisions in 2026, the ability to separate transient pricing noise from structural demand drivers is essential. This research has been designed to provide exactly that clarity.
Hand Magnets Market
Market Trajectory and Growth Cadence: What the Numbers Reveal
The global hand magnets market has demonstrated steady, resilient expansion over the past half-decade, moving from an estimated 170.0 million USD in 2020 to approximately 215.0 million USD by 2025. This progression reflects a compound annual growth trajectory of 4.5 percent, a pace that signals consistent institutional demand rather than speculative boom cycles. Looking forward, the forecast window from 2026 to 2032 maps a continued upward path, with revenue projections advancing toward the high 290 million USD range by the close of the forecast period.
Hand Magnets Market
These figures are not merely retrospective scorecards. They encode operational signals that procurement leaders, engineering directors, and strategy teams can translate into actionable planning. The steady expansion underscores an environment where end-users are standardizing on magnetic handling solutions, replacing ad hoc or improvised lifting methods with purpose-built, ergonomically designed tools that reduce labor strain, minimize part damage, and support repeatable shop-floor workflows. For manufacturers and distributors, the growth cadence suggests that demand is broadening across multiple verticals, even as specific segments accelerate at different rates depending on regional industrial activity, capital expenditure cycles, and regulatory pressures.
Importantly, the market’s forward profile indicates that growth will be distributed unevenly across product architectures, applications, and geographies. Permanent magnet technologies continue to anchor a significant share of the revenue base, reflecting their durability, lower operational overhead, and suitability for repetitive manual handling tasks. Electromagnetic and hybrid switchable solutions occupy narrower but strategically important niches where controllability, load release, and integration with powered workflows are prioritized. Understanding where each architecture adds value—and where switching costs, certification requirements, or end-user training requirements create friction—is central to any credible 2026 planning process.
Segmentation Archetypes: Mapping Demand by Technology, Use Case, and Geography
The structure of demand in this market can be parsed through three lenses: product architecture, application environment, and regional operating conditions. Each lens reveals distinct commercial realities that strategy teams must account for when evaluating market opportunities, pricing architecture, and channel strategy.
At the technology level, permanent magnet hand tools dominate volume because they align with the core purchasing logic of many industrial buyers: low maintenance, immediate operational readiness, and predictable total cost of ownership. Electromagnetic variants, while representing a smaller share of the overall revenue base, appeal to applications that require load release precision, selective engagement, or periodic deactivation during handling workflows. Hybrid switchable designs sit at the intersection of these two paradigms, offering transitional capabilities that are particularly relevant for facilities seeking to improve safety compliance while maintaining manual handling flexibility. The strategic takeaway for 2026 is not which technology is universally superior, but how each maps to specific labor models, load characteristics, and compliance expectations.
From an application standpoint, the market draws demand from a diversified set of industrial and infrastructure contexts. Heavy industrial manufacturing environments remain the largest anchor of consumption, driven by the need to retrieve ferrous parts, manage scrap during machining operations, and move small components across workbenches and production lines without resorting to manual grasping or improvised tools. Construction and engineering applications follow as a significant consumption pool, where magnetic retrievers and handheld lifters support steel component handling, site cleanup, and on-site material sorting. Automotive repair and service ecosystems contribute another meaningful layer of demand, particularly in environments where technicians must efficiently clear fasteners, small brackets, and residual ferrous debris from work areas. Scrap recycling operations, meanwhile, depend on magnetic hand tools for rapid segregation of ferrous material from mixed waste streams, making handheld magnets an enabling technology in circular-economy workflows.
Regionally, the market displays a multi-polar structure rather than a single dominant geography. North American demand reflects a mature industrial base with strong emphasis on safety compliance, tool standardization, and replacement cycles in established manufacturing and service networks. European consumption is shaped by dense engineering infrastructure, stringent workplace safety expectations, and a strong presence of specialized industrial tooling distributors. Asia Pacific represents a broad and expanding demand center, propelled by manufacturing scale, construction activity, and growing adoption of ergonomic and productivity-enhancing hand tools across both formal industrial sites and decentralized workshop environments. Latin America and the Middle East and Africa together constitute smaller but strategically relevant consumption zones, often tied to mining-adjacent operations, infrastructure build-outs, and industrial modernization initiatives. The commercial implication for 2026 is that regional strategy cannot rest on a single narrative; each geography requires its own prioritization logic, channel approach, and product mix calibration.
Competitive Landscape and Enterprise Positioning
The competitive field in hand magnets is characterized by a blend of specialized manufacturers, regional producers, and multi-vertical industrial tool suppliers. The market remains relatively fragmented at the top, with the largest three participants holding an estimated 28.5 percent combined share and the top five accounting for approximately 38.2 percent. This concentration pattern indicates that while scale players exist, there is still meaningful room for differentiated positioning based on application specialization, geographic coverage, distributor relationships, and product reliability.
Several enterprises illustrate the strategic diversity in the market. Magnetool Inc., based in Troy, Michigan, focuses on multi-lift hand magnets and tubular hand magnets designed to pick up and transport loose metal parts, chips, and small ferrous items in industrial settings. Its product orientation highlights the value of repeatable part retrieval and shop-floor cleanliness in high-volume manufacturing environments. OneMonroe, also located in Rochester Hills, Michigan, offers a wider portfolio of hand magnets, magnetic hand tools, retrievers, and portable lifting magnets for material handling and industrial applications, emphasizing breadth and versatility across work-cell scenarios. In India, Jaykrishna Magnetics Pvt. Ltd. has built a manufacturing profile around separating scattered iron materials such as nails, bolts, and wires from workshop floors, reflecting the market’s emphasis on debris management and floor safety in lower-cost, high-density workshop environments. Walmag Magnetics, operating from the Czech Republic, produces MC series hand magnets for manual handling of steel sheets, plates, and loads up to 90 kg or more, underscoring the importance of load capacity and operator control in metal fabrication and handling workflows.
Bunting Magnetics, headquartered in Newton, Kansas, provides permanent magnetic lifters and hand-controlled lifting magnets for safe handling of ferrous loads, with a positioning that speaks directly to safety compliance and controlled load transfer. Kumar Magnet Industries, another Ahmedabad-based manufacturer, concentrates on hand magnets and T-handle magnets for industrial separation and pickup of ferrous materials, reinforcing the demand for ergonomic, purpose-built retrieval tools in production and maintenance contexts. Collectively, these companies illustrate how product design, load ratings, ergonomics, and application focus differentiate offerings even within a broadly similar category.
A notable recent development that signals the market’s broader industrial linkages is the March 2026 partnership between Arnold Magnetic Technologies and USA Rare Earth, structured as a mutual sales and distribution agreement aimed at expanding domestic supply of high-performance magnets. While not a hand magnet manufacturer partnership in the strictest sense, this move reflects a strategic push to secure the upstream magnet supply chain and reduce dependency on constrained external sources. For hand magnet producers and downstream buyers, such upstream realignments matter because they influence the availability, cost stability, and specification flexibility of the permanent magnet materials embedded in end products.
Macroeconomic and Technical Forces Reshaping Demand
Market growth does not occur in a vacuum. Several forces are actively reshaping how procurement teams, engineering groups, and product strategists evaluate hand magnets in 2026.
Raw material dynamics are among the most immediate. Neodymium pricing has reached elevated levels, with market data indicating prices near 965,000 CNY per metric ton as of mid-2026, reflecting year-over-year increases driven by sustained magnet demand. Because rare earth elements, particularly neodymium and praseodymium, account for a major portion of costs in permanent hand magnets using NdFeB materials, price volatility in these inputs directly affects product margins, minimum order economics, and the financial attractiveness of alternative material configurations. Procurement strategies that fail to account for input-cost sensitivity risk either eroding margin through fixed-price commitments or encountering periods of supply hesitation when raw material movements become abrupt.
Trade policy and export controls have further amplified supply chain complexity. Chinese export restrictions on NdFeB magnets and related materials, implemented in 2025, continue to reverberate through global supply chains for magnet-dependent products. For hand magnet manufacturers, this translates into a need to diversify sourcing channels, evaluate substitution pathways where performance tolerances allow, and plan for potential lead-time variability in spec-driven buyer engagements. For industrial buyers, it adds a layer of strategic importance to supplier diversification, safety stock planning, and the evaluation of domestic or near-shore manufacturing options where available.
On the demand side, macro-level industrial trends are reinforcing the relevance of magnetic hand tools. Increasing industrial automation does not eliminate manual handling; in many facilities, it redefines it. Workcells that integrate automated primary processing often still rely on human operators for intermediate retrieval, part clearing, and spot handling between automated stations. In parallel, rising safety standards place greater emphasis on tool-assisted lifting, reduced manual strain, and controlled load management. These dynamics support demand for efficient manual handling tools like hand magnets in manufacturing and recycling environments, particularly where ergonomic improvement, floor safety, and process repeatability are prioritized alongside throughput.
What the Research Covers: An Operational View of the Analysis
This market research is built to support practical decision-making rather than abstract market description. It provides a structured assessment of historical performance, forward demand projections, and the qualitative forces that will shape segment behavior over the forecast period. The analysis is organized to help strategy, sourcing, and commercial teams answer a set of operational questions that recur in 2026 planning cycles.
At the core of the research is a top-down market sizing framework that traces revenue evolution from 2020 through 2025 and extends the model across the 2026–2032 forecast horizon. This temporal structure allows users to test sensitivity around replacement cycles, capacity expansion in industrial facilities, and regional demand pacing without relying on single-point assumptions. The segmentation architecture is developed to differentiate product types, application contexts, and regional consumption patterns in a way that supports prioritization decisions. Rather than presenting isolated sub-segment headlines, the analysis is designed to show how demand drivers interlock—for example, how application mix shapes regional growth profiles, or how technology preferences shift depending on load requirements and safety expectations.
The research also incorporates competitive intelligence that maps the positions of key participants, their product orientations, and the strategic implications of recent developments in the broader magnet supply chain. This includes an examination of how upstream supply actions, material pricing movements, and trade policy constraints alter the operating environment for manufacturers and buyers alike. In addition, the study integrates macro trend context, linking industrial automation momentum, safety standardization, and recycling-driven material segregation needs to demand behavior for manual handling tools.
A defining feature of the report is its focus on actionable interpretation. The analysis is intended to help users identify where demand is likely to remain stable, where it may accelerate, where substitution or redesign may become economically advantageous, and where supply-side constraints could influence sourcing strategy. For commercial teams, this means better segmentation targeting, pricing strategy, and channel prioritization. For product and engineering teams, it means clearer signals about where ergonomic design, load ratings, release mechanisms, and material configuration may matter most. For senior leadership, it means an evidence base for make-versus-buy, supplier diversification, and geographic investment decisions.
Why This Research Matters for 2026 Decision-Making
The strategic value of this research lies in its ability to convert broad market growth into operational intelligence. A headline CAGR and long-term revenue projection are useful only if they can be connected to the decisions that executives face in the current planning cycle. In 2026, that connection is especially important because the hand magnets market is being influenced by forces that are simultaneously technical, geopolitical, and operational.
First, material cost exposure requires a more disciplined approach to product configuration and sourcing. Organizations that rely heavily on permanent magnet designs must evaluate whether their product roadmaps, contract structures, and inventory strategies are resilient to rare earth price fluctuations and supply-channel disruptions. Second, the evolving trade environment makes supplier geography a strategic variable, not merely a logistics detail. Evaluating where magnets and finished tools are manufactured, how distribution is structured, and which suppliers offer redundancy or substitution flexibility can materially affect operational continuity. Third, the demand environment is increasingly shaped by workflow modernization. As facilities improve safety standards and integrate more semi-automated handling patterns, they are likely to favor tools that reduce manual strain and support consistent part and material management, creating opportunities for differentiated product positioning.
This research provides the necessary context to approach these challenges with confidence. It clarifies where growth is structurally anchored and where it is more sensitive to external conditions. It distinguishes between segments that are likely to respond to broad industrial expansion and those that depend on more specific operational triggers. It also frames competitive dynamics in a way that helps participants understand where scale, specialization, or geographic coverage may provide durable advantage.
Looking Ahead: Strategic Next Steps for Industry Stakeholders
The hand magnets market is entering a phase where success depends less on recognizing that demand is growing and more on interpreting how that growth is composed. For manufacturers, the priority is to align product portfolios with the practical requirements of end-users—load capacity, ergonomics, release control, material durability, and compliance-friendly design—while managing exposure to raw material cost volatility and supply-chain constraints. For distributors and channel partners, the opportunity lies in matching product recommendations to application environments, building inventory strategies that account for regional demand pacing, and strengthening relationships with buyers who are standardizing their handling toolsets. For enterprises making procurement decisions, the key is to evaluate suppliers not only on unit price, but on consistency, load performance, safety alignment, and the resilience of their upstream material sourcing.
Given the multi-layered nature of these decisions, a detailed and current market intelligence foundation is indispensable. The complete research provides the granular segmentation data, regional breakdowns, application-level revenue distribution, and competitive depth required to turn high-level trends into specific commitments. Readers seeking the full quantitative landscape, sub-segment analysis, and detailed strategic implications are encouraged to access the full report on the source page, where the complete market model, segmentation structures, and company-level insights are available for review.
In a market defined by steady growth, changing material economics, and evolving workplace safety expectations, the organizations that act with the most precise information will be best positioned to capture value in 2026 and beyond. This research is designed to provide that precision.
For detailed analysis of this topic, please visit the official page: Hand Magnets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Report Forecasts Oat Beta-Glucan Powder Revenue To Reach 866.64 Million USD By 2032 With 6.85% CAGR
By PW Consulting, 2026-09-02
Strategic Intelligence for the Oat Beta-Glucan Powder Market: Navigating Growth, Regulation, and Competitive Dynamics in 2026
Executive Overview: Why This Analysis Matters Now
The global landscape for oat beta-glucan powder is undergoing a structural transformation. What was once a niche functional ingredient has matured into a commercially significant category, driven by converging consumer health trends, regulatory validation, and expanding application architectures across food, beverage, dietary supplements, and personal care. For executive teams, procurement leaders, and R&D strategists, the question is no longer whether beta-glucan ingredients will capture market share, but how to position portfolios, supply chains, and go-to-market strategies to capitalize on a growth trajectory that is both robust and highly differentiated.
Oat Beta-Glucan Powder Market
Our latest Oat Beta-Glucan Powder Market research study is designed specifically for decision-makers operating in the 2026 horizon and beyond. Rather than offering a static snapshot, the report delivers a dynamic, scenario-aware framework that maps historical momentum against forward-looking indicators. It equips organizations with the analytical granularity needed to evaluate partnership opportunities, assess competitive pressure, anticipate regulatory shifts, and allocate investment capital with precision. This article serves as a strategic preview of the study's scope, methodology, and core insights, illustrating how the full report can be operationalized to support high-stakes business decisions throughout the forecast period.
Oat Beta-Glucan Powder Market
Market Trajectory: Scaling Momentum Across the Forecast Window
The market has demonstrated consistent upward movement over the historical review window, with total revenue expanding from approximately 478.0 million USD in 2023 to 545.0 million USD in 2025. This trajectory reflects sustained adoption across multiple end-use channels and a broadening recognition of oat beta-glucan's functional properties, particularly its role in supporting cardiovascular wellness, glycemic management, and gut health. The momentum is projected to carry forward through the forecast horizon, with the overall market size expected to reach 582.33 million USD in 2026 and continue expanding toward 866.64 million USD by 2032.
Oat Beta-Glucan Powder Market
At the core of this growth path is a compounded annual growth rate of 6.85 percent, a figure that signals steady, investable expansion rather than a speculative spike. For strategic planners, this CAGR is more than a headline metric; it is a baseline for modeling capacity planning, demand forecasting, and pricing architecture. The study situates this macro trajectory within a detailed analytical structure that connects volume-based assumptions with value-based realities, allowing readers to test sensitivities around input costs, formulation shifts, and regional demand variability without relying on oversimplified projections.
Strategic Value for 2026 Decision-Making
Entering 2026, organizations face a market environment characterized by both opportunity and complexity. The expansion of functional food and beverage portfolios, the continued integration of soluble fiber into dietary supplement regimens, and the emergence of beta-glucan applications in cosmetics and personal care all point to a diversifying demand base. At the same time, the market's maturation introduces heightened scrutiny around ingredient quality, processing standards, regulatory compliance, and supply chain resilience.
This study is built to convert that complexity into actionable intelligence. It provides a structured basis for evaluating where incremental growth is most achievable, which segments are consolidating or fragmenting, how pricing dynamics may evolve, and what competitive responses are likely as key players refine their product architectures and geographic reach. Decision-makers can use the full report to:
- Benchmark current portfolio positioning against evolving demand patterns and application trends
- Identify high-conviction segments for capacity expansion, formulation innovation, or partnership development
- Assess the strategic implications of regulatory developments on product claims, market access, and consumer trust
- Evaluate supply-side vulnerabilities, including raw material cost exposure and concentration risk within the competitive landscape
- Frame entry, expansion, or re-positioning strategies with a clear view of how total market size and segment-level dynamics interact over the medium term
By anchoring analysis in a rigorous market model rather than anecdotal signals, the report enables leadership teams to move from reactive observation to proactive strategy. The 2026 outlook is particularly important for organizations that must align procurement, R&D, and commercial execution with a market that is growing steadily but also becoming more segmented in terms of grade, application, and regional demand profiles.
Report Scope and Operational Content: What Decision-Makers Can Expect
The full study is designed as an end-to-end strategic toolkit. It begins with a comprehensive market definition and sizing architecture, establishing a clear baseline from which all forward-looking analysis is derived. From there, the report moves into a multi-layered examination of segmentation dynamics, competitive positioning, regulatory and technology drivers, and supply chain considerations. The emphasis throughout is on practical relevance: each section is structured to support specific decision contexts rather than to provide abstract commentary.
Key operational components of the study include:
- A detailed assessment of market size evolution across the historical review period and the full forecast window, with transparent methodology that supports sensitivity testing and internal modeling
- An examination of how different grade categories and application channels contribute to overall demand, framed to help readers understand where concentration risk and diversification opportunity coexist
- A competitive landscape analysis that maps company profiles, product architectures, geographic footprints, and recent strategic activities against the broader market structure
- A review of regulatory and scientific developments that are shaping claim substantiation, consumer perception, and market access across key jurisdictions
- An evaluation of raw material and input dynamics, including the relationship between oat quality parameters, processing capability, and cost structures
- Strategic implications and forward-looking scenarios that translate quantitative trends into decision-ready recommendations
Importantly, the report avoids treating segmentation as a static list of shares. Instead, it contextualizes how segment performance interacts with regional demand patterns, formulation requirements, and competitive behavior, giving readers a dynamic view of where growth is being generated and how that generation may shift over time. This approach is essential for organizations that need to make allocation decisions without relying on overly aggregated or prematurely granular data points.
Competitive Landscape: Profiles, Positioning, and Strategic Signals
The market's trajectory is being shaped by a set of companies that combine ingredient expertise, processing capability, and targeted application focus. Our research profiles the most strategically relevant players, examining how their product architectures, geographic presence, and recent activities reflect broader market dynamics. Rather than treating competition as a simple ranking, the study evaluates each company's positioning in the context of grade differentiation, functional claim support, supply chain strategy, and expansion intent.
Among the organizations analyzed, several distinct strategic postures emerge. Lantmännen Biorefineries, based in Sweden, produces PromOat oat beta-glucan with beta-glucan content levels reaching up to 34 percent, alongside soluble oat bran fibre derived from Nordic oats. Its portfolio is structured to serve food, beverage, and supplement applications, with gluten-free and organic variants extending its reach into specialty formulation requirements. The company also offers Avenacare for cosmetics applications, underscoring a cross-application approach that aligns with the market's gradual diversification. In recent activity, Lantmännen Biorefineries participated in Fi Europe 2025, highlighting sustainable oat ingredients and drawing attention to shifting demand patterns for beta-glucan applications. The company also joined an export delegation to Asia in September 2025 to promote quality oat ingredients, signaling a deliberate focus on geographic expansion and demand cultivation in higher-growth regions.
Garuda International, headquartered in the USA, offers B-CAN 70 percent Oat Beta-Glucan, a high-concentration soluble oat fiber with gluten-free options available. Its ingredient is GRAS affirmed for use in foods, beverages, and nutraceuticals, a positioning that supports broad application flexibility and reduces regulatory friction in formulation development. This type of grade-concentration differentiation is strategically significant because it gives formulators a higher-potency input while maintaining compliance pathways that are familiar to food and supplement developers.
Givaudan, based in Switzerland, markets OatWell oat beta-glucan-rich prebiotic fibre, including formats such as BG28 with 28 percent beta-glucan content. Its focus is oriented toward functional foods and the associated health benefit narratives around gut, heart, and blood glucose health. The company's approach illustrates how ingredient suppliers increasingly align product architecture with benefit communication, not only to support technical formulation but also to strengthen commercial storytelling for end brands.
Ceapro Inc., operating from Canada, specializes in CP Oat Beta Glucan Liquid and related extracts using patented processes. Its emphasis spans personal care, cosmetics, and potential nutraceutical applications, highlighting the broadening relevance of oat beta-glucan beyond traditional food and supplement channels. This kind of application extension is an important indicator of how ingredient suppliers are building optionality into their portfolios as demand matures across adjacent categories.
GreenField Natural Ingredients, headquartered in Poland, produces oat beta-glucan fibre in the form of soluble powder from Avena Sativa. It offers conventional, gluten-free, and organic qualities tailored to the food and baking industry, reflecting a practical alignment with industrial formulation requirements and clean-label expectations. The company's profile demonstrates how regional sourcing, grade versatility, and application-specific processing can combine to serve a steady demand base in established food manufacturing channels.
Bioway Industrial Group Ltd, based in China, manufactures high-quality oat beta-glucan powder using advanced extraction technologies, with certifications supporting food and supplement use. Its presence points to the growing importance of production capability, processing sophistication, and certification pathways in shaping competitive reliability, particularly for organizations that prioritize supply continuity and specification consistency.
Taken together, these profiles reveal a competitive field that is neither fully consolidated nor highly fragmented. The study's concentration analysis situates this landscape within a measurable structure, noting that the top three companies account for approximately 34.5 percent of market revenue, while the top five represent about 46.2 percent. This level of concentration suggests a market where scale, processing expertise, and application-specific differentiation matter, but where meaningful room for specialized players and regional challengers also remains. For strategic planners, that balance has direct implications for partnership selection, competitive benchmarking, and the evaluation of entry or expansion feasibility.
Market Dynamics: Regulation, Raw Material Economics, and Strategic Implications
No strategic assessment of this market is complete without addressing the forces that influence both demand credibility and supply economics. Two dynamics stand out for their relevance to 2026 planning.
On the regulatory and scientific front, recent activity has reinforced the credibility pathway for oat beta-glucan ingredients. In January 2026, EFSA evaluated a health claim for oat beta-glucans related to the reduction of postprandial glucose peak, with panel adoption reported in February 2026. This type of regulatory engagement matters because it shapes the boundary between marketing narrative and substantiated claim language, influences formulation priorities, and affects how confidently brands can build product positioning around functional benefits. For ingredient suppliers and end-product manufacturers alike, the evolving claim environment is a strategic variable that can alter competitive advantage depending on how quickly organizations integrate new scientific validation into their communication and product architectures.
On the supply side, raw material economics are introducing a meaningful layer of cost and quality management into the market. Oat prices rose to approximately 380 USD per bushel in May 2026, with recent monthly gains of around 17 percent amid supply dynamics. This input pressure does not affect all product streams equally. Specialty high beta-glucan oats command price premiums over standard feed-grade oats due to quality parameters such as beta-glucan content. As a result, the relationship between raw material cost, specification integrity, and processing efficiency becomes a critical strategic concern, particularly for grade differentiation, margin management, and long-term supply agreements. The study incorporates these dynamics to help readers understand how cost structures may influence pricing behavior, formulation choices, and supplier selection, without reducing the analysis to a simple input-cost narrative.
These dynamics also intersect with the market's broader segmentation logic. As demand continues to develop across food and beverage, dietary supplements, and cosmetics and personal care, the value of consistent quality, regulatory alignment, and application-specific processing becomes more pronounced. Organizations that can navigate raw material variability while maintaining specification reliability and claim support are better positioned to defend margins and capture share in a market where growth is steady but increasingly dependent on differentiation rather than volume alone.
Why the Full Study Is Essential for Strategic Execution
The macro trajectory, competitive profiles, regulatory context, and supply-side pressures described here represent only the surface layer of the market's strategic landscape. The full Oat Beta-Glucan Powder Market research study goes further by linking these elements into a coherent decision framework. It provides the analytical depth required to evaluate how total market size evolution interacts with segment-level demand behavior, how competitive concentration shapes pricing and partnership options, and how regulatory and raw material developments may alter the risk-reward profile of specific growth initiatives.
For executives and analysts operating in 2026, the study is designed to reduce uncertainty in three practical ways. First, it offers a transparent sizing and forecasting structure that supports internal modeling rather than imposing a single fixed outlook. Second, it maps the competitive field in a way that highlights strategic posture, capability alignment, and recent activity, enabling more informed sourcing, benchmarking, and positioning decisions. Third, it integrates regulatory and input-cost dynamics into the broader market narrative, helping organizations anticipate how credibility, cost, and quality parameters will interact as the market continues to expand toward 2032.
Conclusion: Positioning for the Next Phase of Market Expansion
The oat beta-glucan powder market is entering a phase in which growth is supported by both structural demand and an increasingly sophisticated competitive and regulatory environment. Total market size has risen steadily across the historical period and is projected to continue expanding through the forecast window, with a compounded annual growth rate that signals durable momentum. At the same time, the market's evolution is being shaped by grade differentiation, application diversification, raw material cost dynamics, and regulatory developments that influence how benefits are communicated and validated.
For organizations seeking to act decisively in 2026, the strategic imperative is to move beyond high-level growth narratives and engage with the mechanics of how value is being created, concentrated, and contested. Our full market study is built to support that engagement. It provides the depth, structure, and forward-looking context needed to translate market intelligence into portfolio strategy, supply chain planning, competitive positioning, and investment prioritization. The preview outlined here offers a foundation; the complete report delivers the operational intelligence required to turn that foundation into executable strategy.
For detailed analysis of this topic, please visit the official page: Oat Beta-Glucan Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Oncolytic Adenovirus Market Poised to Surpass $900 Million by 2032 with 14.5% CAGR Driven by Solid Tumor Treatments
By PW Consulting, 2026-09-02
The Oncolytic Adenovirus Market at an Inflection Point: Strategic Intelligence for the 2026 Decision Cycle
The oncology landscape is undergoing a structural recalibration. As immune checkpoint inhibitors mature and targeted therapies face diminishing returns in late-line settings, the clinical community is increasingly turning toward viral vectors that can turn a patient's own tumor microenvironment into an in situ vaccine. Oncolytic adenoviruses occupy a distinctive place in this shift. They are not merely cytotoxic agents replicating within malignant cells. They are engineered platforms that combine selective oncolysis with transgene delivery, immune priming, and, in several late-stage programs, the potential for durable responses in indications long considered immunologically cold.
Oncolytic Adenovirus Market
For executives, investors, and R&D strategists, the translational promise of oncolytic adenoviruses must be paired with a disciplined commercial evaluation. The market is no longer a speculative biology story. It is a quantifiable growth ecosystem with defined therapeutic franchises, regulatory precedents, and manufacturing realities that shape go-to-market feasibility. The new PW Consulting research on the Oncolytic Adenovirus Market is designed to convert this complexity into a decision-ready architecture. It sits at the intersection of clinical trajectory, competitive positioning, regulatory pathway analysis, and commercial sizing, giving leadership teams the clarity required to allocate capital, prioritize partnerships, and sequence development or acquisition strategies through 2032.
Oncolytic Adenovirus Market
This article previews the strategic logic behind the study and the operational insights embedded within it. It is not a substitute for the full report. Rather, it establishes why the market is entering a decisive phase in 2026 and why a data-backed, rather than anecdote-driven, approach is now essential for organizations operating in oncolytic virotherapy, immuno-oncology, or adjacent therapeutic areas.
Oncolytic Adenovirus Market
Why 2026 Is a Defining Year for Oncolytic Adenovirus Strategy
The market's trajectory through the forecast period reflects more than a generic expansion curve. It captures a sector moving from early clinical proof-of-concept toward late-stage validation, regulatory alignment, and the first real commercial rollouts beyond a single approved regional product. The overall market size has already crossed meaningful thresholds, with historical growth setting the stage for a forecast period that compounds at a robust double-digit rate. This is not incremental movement. It is the kind of momentum that rewards organizations which can identify the right indication mix, the right platform differentiation, and the right commercial pathway before competing capital floods into late-stage programs.
For strategic planning, the key observation is that growth is being shaped by clinical maturation and regulatory design rather than by undifferentiated demand. Programs are advancing with adaptive trial designs, repeat-dosing considerations, and regulatory engagement that influences both development speed and eventual commercial access. The convergence of these factors means that 2026 is not simply another forecast year. It is a year in which late-stage data readouts, regulatory interactions, and early commercial precedents begin to clarify which platforms will define the next wave of oncolytic adenovirus franchises.
A market research study that is strategically useful must therefore do more than report top-line numbers. It must help leadership interpret what the numbers imply for competitive positioning, therapeutic area allocation, and the operational barriers that determine whether a clinical asset can become a commercial franchise. That is the framing PW Consulting uses throughout the analysis: market size is the starting point, not the conclusion.
From Clinical Promise to Commercial Architecture: What the Study Covers
The research is built for decision-makers who need to move beyond high-level interest and into operational prioritization. It provides a structured evaluation of the oncolytic adenovirus ecosystem, with a focus on the elements that shape investment, partnership, and product strategy. The study integrates historical performance, forward-looking sizing, segmentation logic, competitive profiling, and the practical dynamics that influence market viability.
One of the central strengths of the analysis is its insistence on connecting therapeutic design to commercial outcome. The report examines how platform characteristics, armed transgene strategies, selectivity mechanisms, and delivery approaches affect both clinical differentiation and downstream commercial positioning. This is particularly relevant because oncolytic adenoviruses are not a monolith. They span genetically modified vectors, replication-competent platforms, and chimeric constructions, each with distinct development profiles and commercial implications. Understanding the strategic weight of each category is essential for portfolio planning, partnership screening, and competitive benchmarking.
Equally important, the report does not abstract the market into a single aggregate. It structures the analysis around the therapeutic and geographic contexts that matter for strategic allocation. This is where the study becomes operationally valuable: it helps leaders determine where momentum is concentrated, where adoption pathways differ, and where late-stage programs are likely to influence near-term market dynamics versus longer-term franchise formation.
The analysis also incorporates the practical execution barriers that frequently determine whether a promising candidate translates into a viable commercial asset. Manufacturing scale-up for adenovirus vectors, downstream purification yields, GMP-compliant supply chain capacity, and the specialized role of contract development and manufacturing organizations all influence development timelines and cost structures. Reimbursement trajectories and the existing precedent set by approved oncolytic adenovirus use in combination regimens further shape the commercial calculus. These are not peripheral concerns. They are determinants of speed, margin, and market access.
To support decision-making at multiple levels of the organization, the study is structured to answer a set of commercially critical questions:
- Which platform categories are carrying the strongest momentum, and what is the strategic rationale behind their positioning?
- How do therapeutic-area dynamics differ across solid tumor treatment, hematological malignancies, and other indications in terms of adoption logic and value creation?
- Where is regional activity concentrated, and what does that imply for licensing, partnership, and market entry priorities?
- Which companies are advancing programs likely to influence the competitive landscape through late-stage data, regulatory progress, or early commercial presence?
- What execution challenges in manufacturing, regulatory design, and reimbursement should be integrated into a realistic commercial model?
By organizing the landscape in this way, the research enables more than situational awareness. It supports choice architecture: where to invest, what to monitor, which partnerships to pursue, and how to sequence strategic moves as clinical and regulatory milestones land.
A Market Defined by Concentration, Momentum, and Mature Contenders
Strategic interpretation of this market requires an honest assessment of its competitive structure. The ecosystem is not fragmented in the way many emerging oncology segments are. A meaningful share of market value and developmental attention is concentrated among a set of companies with distinct platform strategies, clinical programs, and regulatory positioning. This concentration has direct implications for partnership timing, competitive benchmarking, and the speed at which late-stage readouts can reshape assumptions.
The presence of both research-stage innovators and an already commercialized product creates an unusual market dynamic. On one side, several companies are working to expand the clinical evidence base for oncolytic adenoviruses in combination regimens and novel solid tumor settings. On the other, a long-approved recombinant oncolytic adenovirus in China has established a commercial precedent for combination use in specific oncology indications. That coexistence matters. It means the market is simultaneously being shaped by forward-looking clinical development and by a real-world reference point that can inform reimbursement, combination strategy, and regional adoption.
From a strategic viewpoint, the competitive story is not simply a list of companies. It is a set of differentiated development theses that leadership must be able to interpret. In this landscape, the most relevant patterns include:
- The maturation of biomarker-anchored or indication-specific programs advancing toward pivotal data and regulatory submission planning.
- Platform engineering strategies designed to overcome barriers such as tumor stroma density, immune evasion, and delivery constraints in difficult solid tumor environments.
- Late-stage trials evaluating combination approaches with checkpoint inhibitors, chemotherapy, or cell therapy, reflecting the recognition that monotherapy may not fully unlock commercial potential.
- Regulatory engagement around adaptive and repeat-dosing designs, which can affect trial speed, evidence generation, and the shape of eventual approval pathways.
- Early commercial presence in specific regions that provides practical insight into combination use, indication expansion, and reimbursement behavior.
Each of these themes has consequences for strategic planning. A company evaluating in-licensing, partnership, or competitive response must understand not just who is advancing, but what each program's clinical theory and regulatory trajectory imply about the future value pool. The report builds that comparative understanding systematically, so decision-makers can separate genuine franchise potential from early clinical noise.
What Leadership Needs to Know About Competitive Positioning
Competitive intelligence in this sector must be precise and forward-looking. It is not enough to catalog programs; leadership needs to interpret the strategic implications of late-stage progress, regulatory status, and platform design. The study includes detailed company profiling to support that interpretation, with a focus on programs that are likely to exert influence on the market over the forecast horizon.
Several profiles illustrate the breadth of strategic approaches now shaping the field. One set of companies is advancing oncolytic adenovirus candidates in indications with significant unmet need and clear combination rationale, with late-stage data and regulatory engagement beginning to clarify the path toward potential approval and commercialization. Another set is developing engineered platforms that emphasize the immune-stimulating payload and the possibility of synergy with checkpoint blockade or other modalities. A third group is pursuing indications where the virus must overcome particularly challenging delivery or microenvironment constraints, requiring specialized engineering and trial design. Alongside these, a regionally established product provides a long-term commercial reference point that continues to inform adoption logic and combination use in its market.
This diversity is strategically important because it reveals how the market is being built from multiple angles rather than a single winning mechanism. Some programs are competing on indication-specific clinical evidence, others on platform flexibility, and others on the speed with which they can move from pivotal data to regulatory submission planning. For investors and corporate strategists, the implication is that competitive advantage may emerge from different sources depending on the target indication, the reimbursement environment, and the partnership model being pursued.
Recent developments reinforce the importance of timing. Late-phase trial data, subgroup analyses, and regulatory alignment discussions are beginning to reshape expectations for selected programs. These events do not merely move individual assets; they influence the market's narrative about feasibility, speed to approval, and the likelihood that oncolytic adenovirus therapies can become durable commercial franchises in multiple indications. The study integrates these developments into its competitive analysis so that leadership can assess not just what happened, but what it means for future positioning.
The Execution Reality Behind the Numbers
Commercial ambition must be tested against execution constraints. In the oncolytic adenovirus space, the gap between a well-supported clinical program and a viable commercial product is shaped by manufacturing, regulatory, and reimbursement realities that the study examines directly.
Manufacturing is a critical operational theme. Adenovirus vector production is not a trivial scale-up exercise. Downstream purification, yield optimization, and supply chain consistency for GMP-grade material can have a direct impact on development timelines, cost profiles, and the ability to support multi-region clinical and commercial demand. Specialized CDMOs and standardized production platforms help address these constraints, but the operational burden remains a strategic consideration, particularly for programs that intend to move into pivotal studies and potential commercialization. The report highlights these dynamics to ensure that market opportunity is interpreted alongside the practical requirements for delivery.
Regulatory engagement is equally important. The sector is seeing alignment on trial design elements such as repeat dosing macrocycles and adaptive approaches, which can influence the speed and evidentiary structure needed for progression. Regulatory designations that expedite development and review can also affect the competitive calculus, especially when multiple programs are advancing in related indications. These elements are not background details. They affect how quickly a therapeutic hypothesis becomes a commercial reality and which programs are best positioned to capture value first.
Reimbursement and combination use patterns further shape the commercial environment. Where oncolytic adenovirus therapies are already embedded in combination regimens, the market has a more concrete reference point for adoption, pricing logic, and indication expansion. In other settings, the commercial case may depend on the strength of monotherapy or combination evidence, the emergence of supportive real-world data, and the willingness of payers and providers to adopt a new modality. The analysis incorporates these considerations so that strategy is built on commercial realism rather than clinical optimism alone.
How to Use This Research for 2026 Decision-Making
The immediate value of the study lies in its ability to support concrete strategic actions. For corporate development teams, it provides a structured basis for assessing partnership targets, licensing opportunities, and competitive vulnerability. For R&D leadership, it helps prioritize indication selection and combination strategy by mapping clinical momentum against commercial feasibility. For investors and strategy functions, it offers a disciplined framework for interpreting market growth, concentration, and the timing of value inflection points.
The most effective use of the research is to treat it as a planning instrument, not just an information source. That means using it to answer questions such as:
- Where does our current portfolio or pipeline stand relative to the programs and platform strategies most likely to shape the next wave of commercial value?
- Which therapeutic areas and regions present the highest strategic relevance for our capabilities, assets, or access advantages?
- What manufacturing, regulatory, and reimbursement assumptions should be embedded in realistic financial and operational planning?
- Which competitive developments should trigger near-term action, and which should be monitored for longer-term repositioning?
By answering these questions with data-backed context, leadership can move from general market interest to a specific strategic agenda. That agenda may involve accelerating a late-stage asset, pursuing a targeted partnership, reallocating internal resources toward a higher-conviction indication, or building a competitive response plan for a platform likely to influence future value pools.
A Strategic Window That Will Not Remain Open Indefinitely
The oncolytic adenovirus market is entering a phase in which evidence, regulation, and early commercial precedent will increasingly determine which strategies succeed. Growth is not merely a function of scientific enthusiasm. It is being shaped by the interaction of clinical maturation, platform differentiation, regulatory alignment, and execution capability. Organizations that understand these drivers in advance will be better positioned to allocate resources, sequence partnerships, and respond to competitive moves as the forecast period unfolds.
The full PW Consulting Oncolytic Adenovirus Market study is designed to provide the granularity required to act on this insight. It expands on the macro trajectory, segmentation logic, competitive profiles, and market dynamics summarized here, and it translates them into a practical framework for decision-making through 2032. For leaders evaluating where to commit capital, talent, and partnership attention in 2026, the detailed analysis offers the kind of structured intelligence that turns market interest into a disciplined strategy.
To access the complete data sets, segmentation breakdowns, competitive profiles, and operational context behind this preview, visit the full report page to retrieve the complete intelligence package and integrate it into your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Oncolytic Adenovirus Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


