



Category: Healthy Lifestyle
PW Consulting Agrochemical Active Ingredients Market Hits 78500 Million USD in 2025 with 3.8 Percent CAGR Forecast to 101918 Million by 2032
By PW Consulting, 2026-09-02
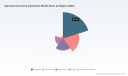
Agrochemical Active Ingredients Market: Strategic Outlook 2026–2032
The global agrochemical active ingredients sector stands at a critical inflection point. As producers and stakeholders navigate post-pandemic supply realignments, regulatory transitions, and the accelerating demand for sustainable crop protection, understanding the structural trajectory of the active ingredients market has become a strategic imperative rather than a routine planning exercise. This analysis synthesizes the latest available intelligence to frame the commercial and operational landscape that will define decision-making throughout the 2026–2032 horizon.
Agrochemical Active Ingredients Market
For executive teams, procurement leaders, and R&D strategists, the question is no longer whether demand will grow, but how the composition, geographic distribution, and competitive intensity of that growth will reshape portfolio economics. The following overview establishes the macroeconomic architecture of the market, outlines the operational and competitive dimensions captured in our full research publication, and demonstrates why precise, forward-looking intelligence is essential for capital allocation and product strategy in the year ahead.
Agrochemical Active Ingredients Market
Macroeconomic Foundations and Growth Trajectory
The agrochemical active ingredients market has demonstrated consistent expansion across the historical reference window, with total industry revenue progressing from approximately 72,800 million USD in 2023 to 75,600 million USD in 2024, and further to 78,500 million USD in 2025. This sustained upward movement reflects entrenched global demand for yield protection, pest and disease management, and the structural pressures on agricultural productivity driven by land constraints and climate variability.
Agrochemical Active Ingredients Market
Looking forward, the forecast period spanning 2026 through 2032 projects a compound annual growth rate of 3.8 percent. Under this trajectory, market revenue is expected to reach 81,483 million USD in 2026, advance to 84,579 million USD in 2027, and continue expanding toward 87,793 million USD in 2028. By 2029, the sector is projected to cross the 91,129 million USD threshold, with 2030 anticipated at 94,592 million USD, 2031 at 98,186 million USD, and a terminal forecast of 101,918 million USD by 2032. All figures are expressed in USD millions, providing a standardized reference for cross-border investment and M&A valuation models.
This growth path is not uniform across all segments or geographies. The composition of demand, the pricing dynamics of key molecule classes, and the regional weight of procurement will shift materially over the forecast window. Understanding which categories capture incremental share, where manufacturing footprints are consolidating or diversifying, and how external cost pressures alter margin structures requires a granular, scenario-tested analytical framework that goes beyond headline revenue figures.
Structural Segmentation and Portfolio Architecture
The market’s revenue base is distributed across three primary structural dimensions that collectively define how active ingredients are positioned, sourced, and commercialized. Examining these dimensions at a strategic level reveals where innovation pipelines, supply chain resilience, and pricing power will converge.
Chemical Class Distribution and Use-Case Alignment
The active ingredients landscape is anchored by herbicides, insecticides, and fungicides, each serving distinct agronomic functions and responding to different regulatory, resistance, and formulation trends. Herbicides continue to command the largest share of total market value, reflecting their central role in broad-acre crop management and weed resistance management programs. Insecticides represent a substantial secondary pillar, driven by expanding integrated pest management adoption and the need for targeted control solutions in both field crops and high-value horticulture. Fungicides complete the core triad, with demand closely tied to disease pressure cycles, climate patterns, and the ongoing push toward preventive crop protection strategies.
Beyond the top-level split, the real strategic value lies in understanding how these classes interact with regional cropping patterns, resistance management protocols, and the pace at which new molecular entities or differentiated formulations gain regulatory traction. Our full publication deconstructs these relationships without exposing the precise allocation percentages that would reveal commercially sensitive positioning.
Application Verticals and Crop-System Demand
Demand for active ingredients is organized around core application verticals that mirror global agricultural production priorities. Cereals and grains form the foundation of volume consumption, supported by their dominance in staple food systems and the scale of acreage under treatment. Fruits and vegetables represent a high-value, quality-sensitive segment where protection intensity, residue management, and pre-harvest intervals shape product selection. Oilseeds and pulses constitute another significant demand cluster, with usage patterns influenced by rotation practices, pest complexes, and regional dietary and industrial demand for protein and oil content.
Each vertical imposes different requirements on molecule performance, formulation compatibility, and application timing. For manufacturers and formulators, mapping these application dynamics against regional cropping calendars and resistance trends is essential for anticipating shifts in competitive positioning.
Geographic Concentration and Sourcing Patterns
The geographic distribution of market value reflects divergent agricultural intensity, regulatory maturity, and supply chain structures across regions. Asia Pacific anchors a substantial portion of global demand, supported by extensive arable land, diversified cropping systems, and rapidly modernizing agricultural inputs markets. Latin America follows as a major consumption zone, with strong herbicide and insecticide demand tied to large-scale row crop production and export-oriented agriculture. North America contributes a significant share shaped by advanced precision application practices, high regulatory standards, and integrated crop protection ecosystems. Europe maintains a mature but more constrained demand profile, heavily influenced by tightening chemical registration frameworks and sustainability mandates. The Middle East and Africa represents a smaller but evolving share, with growth trajectories dependent on irrigation investment, import dynamics, and localized formulation capacity.
These regional patterns are not static. Tariff adjustments, raw material availability, manufacturing relocations, and regulatory approvals continuously reshape where value is captured and where procurement risks accumulate.
Competitive Intensity and Strategic Positioning
The active ingredients market is characterized by a concentrated core of multinational innovators and a broad base of specialized manufacturers and generic suppliers. The top five players collectively account for approximately 55.4 percent of total market revenue, indicating a moderately concentrated environment where scale, regulatory pipelines, and formulation differentiation play decisive roles in maintaining margin resilience.
Bayer AG’s Crop Science division continues to operate as a major producer of herbicides, fungicides, and insecticides for global crop protection, leveraging an integrated portfolio and extensive distribution networks. BASF SE develops and manufactures a wide range of crop protection active ingredients, with a strong emphasis on fungicides, herbicides, and insecticides that support its broader agricultural solutions platform. Syngenta AG remains a global leader across crop protection active ingredients, seeds, and integrated solutions, maintaining a wide-ranging portfolio that addresses herbicides, insecticides, and fungicides across multiple cropping systems. Corteva Agriscience provides innovative active ingredients in crop protection, sustaining a competitive position through continuous product development and targeted agronomic offerings. FMC Corporation specializes in agricultural sciences with a clear focus on insecticide, herbicide, and fungicide active ingredients, supporting both proprietary and differentiated product lines.
The competitive field also includes strong regional and specialized players. UPL Limited produces and supplies a broad portfolio of generic and differentiated agrochemical active ingredients globally, enabling cost-efficient access across multiple markets. Sumitomo Chemical Co., Ltd. develops and manufactures crop protection active ingredients, including insecticides and plant growth regulators, with a technically oriented product strategy. Nufarm Limited operates as a manufacturer and supplier of off-patent agrochemical active ingredients and formulations, positioning itself around value-engineered solutions and registration flexibility. ADAMA Ltd. focuses on generic crop protection active ingredients and differentiated formulations, using formulation technology to address resistance and performance challenges. PI Industries provides custom synthesis and manufacturing of agrochemical active ingredients and intermediates, serving as an important partner in the upstream and contract manufacturing ecosystem.
Recent operational moves illustrate how these companies are adapting to regulatory, technical, and market pressures. In May 2025, ADAMA Ltd. received U.S. registration for the Temper More herbicide, which incorporates proprietary formulation technology designed to address resistant weed populations. In late October 2025, Syngenta secured over 1,200 synthetic crop protection product approvals, including new actives targeting rice production systems, reinforcing its regulatory pipeline in key staple crops. In June 2025, Corteva Agriscience entered a multi-year R&D partnership with Micropep Technologies to advance peptide-based biocontrols, signaling a strategic tilt toward novel modes of action and biologically derived solutions.
These developments are not isolated events. They reflect a broader competitive logic in which registration velocity, resistance management, formulation differentiation, and partnerships with emerging technology platforms increasingly determine which portfolios capture premium positioning versus those that compete primarily on cost.
Market Dynamics: Cost Pressures, Regulation, and Supply Chain Realignment
The operational environment for active ingredients is being reshaped by a combination of input cost volatility, trade policy adjustments, and regulatory momentum. These forces do not merely affect short-term pricing; they alter the economics of molecule selection, manufacturing location decisions, and the relative attractiveness of conventional chemical pathways versus sustainable alternatives.
Raw material cost pressures have been particularly acute. Conflict conditions in West Asia contributed to a 15–20 percent increase in raw material prices for agrochemicals in early 2026, placing upward pressure on procurement budgets and compressing margins for manufacturers with limited sourcing flexibility. At the same time, natural gas costs constitute an estimated 70–80 percent of production expenses for nitrogen-based inputs, making energy markets a dominant driver of output cost volatility. For nitrogen-dependent molecule classes and related intermediates, fluctuations in gas pricing can rapidly translate into shifts in operating margins and pricing strategy.
Trade and tariff dynamics add another layer of complexity. Increased U.S. tariffs on Chinese active ingredients have raised import costs, and industry analysis indicates that aggregate farm input costs are expected to rise by 4–6 percent by 2026 as a result. This dynamic affects not only finished product pricing but also the competitive balance between domestically sourced and imported active ingredients, especially in markets where registration pathways and formulation requirements create switching friction.
On the regulatory front, EU and global pressure continues to intensify around certain chemical active ingredients, accelerating the shift toward sustainable alternatives. This trend is not simply a compliance issue; it influences pipeline prioritization, portfolio renewal cycles, and the long-term economic viability of molecules facing heightened scrutiny. Companies that anticipate registration risk and proactively diversify into lower-risk chemistries or complementary biological solutions are better positioned to maintain continuity of supply and customer confidence.
Together, these dynamics create a market environment in which strategic planning must account for scenario variability rather than relying on a single baseline. Procurement strategies, inventory buffers, contract structures, and R&D sequencing all need to be evaluated against a range of plausible cost and regulatory pathways.
What the Full Study Delivers
Our comprehensive Agrochemical Active Ingredients Market research is designed to convert these macro and competitive signals into operational intelligence. The publication moves beyond headline sizing to provide a structured, decision-oriented view of how the market is likely to evolve across the 2026–2032 forecast window.
The study includes a detailed revenue trajectory analysis anchored to historical baselines and forward projections, enabling benchmarking of internal forecasts against market-level expectations. It maps the segmentation architecture across chemical class, application vertical, and regional distribution, with sufficient granularity to identify where demand growth is concentrated and where substitution or pricing pressure may emerge. The competitive assessment evaluates the strategic posture of leading innovators, generic specialists, and contract manufacturing partners, highlighting differentiation levers, pipeline momentum, and the implications of recent registrations, partnerships, and formulation breakthroughs.
Operational and risk dimensions are treated as integral components of the analysis. The report examines raw material exposure, energy cost sensitivity, tariff and import cost impacts, and regulatory direction across major jurisdictions, linking these factors to practical implications for sourcing, pricing, and product mix. It also incorporates scenario-based considerations that help decision-makers test the resilience of their portfolios under different cost, regulatory, and demand environments.
For corporate strategy, M&A, and investment teams, the study provides a coherent framework for evaluating which active ingredient categories, application segments, and geographic paths offer the most defensible growth and margin prospects. For commercial and R&D leaders, it offers context on where resistance management, formulation innovation, and regulatory approvals are likely to shape competitive outcomes.
Why This Intelligence Matters for 2026 Decision-Making
The 2026 decision environment will be defined by the interaction of steady structural demand growth and episodic cost and regulatory disruption. A market expanding at a 3.8 percent CAGR over the forecast period can still produce sharp divergence in profitability and competitive strength depending on how companies manage input exposure, registration risk, and portfolio composition.
Organizations that approach active ingredients strategy with only aggregate demand figures risk misallocating capital to segments where growth is modest, margins are compressed by cost pressure, or regulatory headwinds are intensifying. Conversely, teams that understand the layered structure of the market—how chemical classes align with application verticals, how regional demand interacts with sourcing and tariff dynamics, and how competitor pipelines are evolving—can make more informed choices about where to invest, where to protect, and where to partner.
This is particularly important as the industry absorbs the effects of raw material inflation, energy-driven production cost sensitivity, and shifting regulatory expectations. The companies that succeed will be those that can reconcile long-term demand visibility with short-to-medium-term cost and compliance volatility, using detailed market intelligence to reduce uncertainty rather than simply reacting to it.
Positioning for the Forecast Window
The agrochemical active ingredients market will continue to expand through 2032, but the path of that expansion will be uneven across categories, applications, and regions. Strategic advantage will belong to organizations that can read the market with precision, align their portfolios with durable demand drivers, and build resilience against cost and regulatory shocks.
The full research publication provides the depth required to make those decisions with confidence. It consolidates historical context, forecast trajectories, segmentation structure, competitive profiles, and operational risk factors into a single analytical reference built for executive use. For teams planning capital deployment, portfolio renewal, sourcing strategy, or market entry in 2026 and beyond, the objective is not simply to know that the market is growing, but to understand where value is forming, where pressure is accumulating, and how to position accordingly.
Detailed segmentation data, regional and application-level revenue breakdowns, and complete competitive profiling are available in the full report. Access to the complete intelligence package ensures that strategic planning is grounded in the full structure of the market rather than in partial indicators, enabling more rigorous scenario planning and more disciplined resource allocation as the sector moves through the 2026–2032 cycle.
For detailed analysis of this topic, please visit the official page: Agrochemical Active Ingredients Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Gene-Editing Transfection Chemical Market to Reach $1.65 Billion by 2032 with 8.25% CAGR
By PW Consulting, 2026-09-02
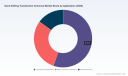
Strategic Horizon: Navigating the Gene-Editing Transfection Chemical Market Through 2032
The landscape of genetic medicine is undergoing a structural transformation, driven by the rapid translation of CRISPR-Cas9 and other gene-editing technologies from basic research into clinical and commercial applications. At the heart of this transition lies a critical enabling technology: transfection chemicals. These reagents, designed to deliver nucleases, plasmids, mRNA, and ribonucleoproteins into target cells, have evolved from laboratory utilities into strategic assets that dictate the efficiency, safety, and scalability of gene-editing workflows. For executives, investors, and R&D leaders operating in the biotechnology and pharmaceutical sectors, understanding the trajectory of the gene-editing transfection chemical market is no longer optional. It is a prerequisite for informed capital allocation, pipeline prioritization, and competitive positioning. This article outlines the strategic context surrounding the market through 2032, drawing on comprehensive industry data and competitive intelligence to illuminate the forces that will shape decision-making in 2026 and beyond.
Gene-Editing Transfection Chemical Market
Market Trajectory and the Scale of Opportunity
Between 2020 and 2025, the global market for gene-editing transfection chemicals demonstrated a consistent upward trajectory, expanding from a baseline of approximately 639.28 million USD to a projected 950.0 million USD. This growth reflects a compound annual growth rate of 8.25 percent across the historical observation window, signaling sustained demand acceleration rather than cyclical fluctuation. Looking forward, the forecast period extending through 2032 indicates continued momentum, with revenue projections climbing toward 1654.56 million USD by the end of the decade. Such expansion is not merely a function of incremental research spending. It is fundamentally anchored in the commercialization of cell and gene therapies, the scaling of biomanufacturing operations, and the institutionalization of genome editing as a standard modality in therapeutic development pipelines. Companies that recognize this inflection point early will be better positioned to capture value across the reagent lifecycle, from raw material sourcing to downstream application support.
Gene-Editing Transfection Chemical Market
Segmentation Dynamics and Strategic Implications
The market architecture reveals distinct demand concentrations that carry direct implications for product development, sales strategy, and partnership formation. North America currently commands a dominant share of overall revenue, reflecting the region's deep concentration of biotechnology firms, academic research infrastructure, and early-stage clinical development activity. Europe and Asia Pacific follow as substantial regional markets, each characterized by unique regulatory environments, manufacturing footprints, and research funding models. Latin America and the Middle East and Africa, while smaller in absolute terms, represent emerging nodes of activity where localized partnerships and technology transfer initiatives may unlock future growth.
Gene-Editing Transfection Chemical Market
Within the product portfolio landscape, cationic lipids stand out as the leading category, capturing a significant portion of total revenue. This dominance aligns with their widespread adoption in lipid-based delivery systems optimized for CRISPR-Cas9 and related editing modalities, where high transfection efficiency and manageable cytotoxicity are paramount. Polymers constitute the next major category, offering complementary delivery mechanisms that appeal to specific cell types and experimental conditions. Electroporation reagents and specialized delivery platforms occupy additional segments, catering to applications that demand non-viral, high-throughput, or manufacturing-grade delivery solutions.
Application-side distribution further clarifies where value is being created. Therapeutic development represents the largest end-use category, underscoring the market's alignment with clinical and commercial pipeline activity. Basic life science research maintains a substantial share, serving as a consistent demand baseline that stabilizes market dynamics even during periods of clinical trial volatility. Biomanufacturing rounds out the application landscape, reflecting the growing need for reproducible, scalable transfection workflows in the production of viral vectors and gene-modified cell therapies. Executives evaluating market entry or expansion must recognize that these segments do not operate in isolation; they intersect through shared raw material requirements, overlapping customer bases, and converging regulatory expectations.
Competitive Landscape and Enterprise Positioning
The competitive environment is characterized by a mix of established life science suppliers and specialized reagent developers, with a moderate degree of market concentration. Leading participants have built positions by aligning product portfolios with the practical demands of gene-editing workflows, emphasizing efficiency, low toxicity, and compatibility across diverse cell types. Thermo Fisher Scientific, headquartered in Waltham, Massachusetts, continues to reinforce its portfolio through offerings such as Lipofectamine CRISPRMAX and Lipofectamine 3000, reagents optimized for high-efficiency delivery in CRISPR applications. In March 2025, the company expanded its capabilities with the launch of the Lipofectamine 3000X reagent, designed to support high-throughput gene editing and scalable manufacturing processes. This move illustrates a broader industry pattern: incumbents are progressively shifting from research-grade formulations toward solutions that bridge discovery and production.
Mirus Bio, based in Madison, Wisconsin, has carved a focused niche around its TransIT-X2 Dynamic Delivery System and related TransIT reagents, which support the delivery of CRISPR ribonucleoproteins, plasmids, and mRNA within gene-editing workflows. In April 2025, Mirus Bio highlighted additional capabilities at the Cell & Gene Tech Expo, presenting the TransIT-VirusGEN and RevIT AAV Enhancer solutions aimed at gene therapy manufacturing workflows. Such appearances at industry exhibitions signal a strategic emphasis on visibility within the manufacturing and commercialization segments, where developers seek reliable delivery tools that integrate into complex production environments.
Polyplus, operating under Sartorius in Strasbourg, France, supplies jetOPTIMUS, jetPRIME, and FectoVIR reagents tailored for high-efficiency DNA and RNA delivery in CRISPR genome editing and viral vector production. Merck KGaA, through its MilliporeSigma division in Darmstadt, Germany, markets X-tremeGENE and related transfection reagents that address gene expression and CRISPR editing requirements. OZ Biosciences, located in Marseille, France, specializes in ProDeliverIN CRISPR for Cas9 protein and ribonucleoprotein delivery, alongside RmesFect CRISPR and PolyMag CRISPR reagents designed for genome-editing specificity. Promega Corporation, headquartered in Madison, Wisconsin, offers FuGENE 4K and FuGENE HD reagents that enable efficient DNA delivery in CRISPR and related applications while maintaining low cytotoxicity profiles. Lonza Group AG, based in Basel, Switzerland, provides Nucleofector technology and reagents that support non-viral gene-editing delivery for cell and gene therapy manufacturing. Bio-Rad Laboratories, based in Hercules, California, contributes gene delivery systems and electroporation technologies compatible with CRISPR workflows.
Recent developments further illustrate how competition is intensifying around throughput, scalability, and workflow integration. In February 2026, MaxCyte Inc. launched the ExPERT DTx platform, a 96-well electroporation system designed for high-throughput discovery workflows in gene editing. This launch highlights a growing demand for parallelized delivery solutions that can accelerate screening and optimization without sacrificing reproducibility. Collectively, these corporate activities point to a market where differentiation is increasingly tied to the ability to deliver consistent performance across research, preclinical, and manufacturing environments.
Regulatory Dynamics and Manufacturing Standards
Regulatory frameworks are exerting a decisive influence on how transfection chemicals are developed, qualified, and deployed. Guidance issued by the FDA classifies gene-editing products incorporating human genome editing components as gene therapies, which in turn requires specific chemistry, manufacturing, and controls considerations for delivery methods, including chemical transfection. This regulatory posture elevates transfection reagents from ancillary consumables to integral components of product quality and patient safety narratives. Furthermore, current cGMP standards for transfection reagents in cell and gene therapy manufacturing emphasize purity, safety, and consistency for clinical and commercial use. These requirements create a compliance-driven filter that shapes supplier qualification, procurement protocols, and internal quality assurance strategies.
From a raw material perspective, specialized cationic lipids and polymers used in transfection reagents represent key high-purity inputs with stringent quality requirements for GMP production. As regulatory scrutiny intensifies and manufacturing scales increase, the ability to secure and validate high-quality raw materials becomes a meaningful competitive factor. Companies that can demonstrate robust supply chains, documented purity standards, and consistent batch-to-batch performance will be better equipped to support clients navigating clinical translation and commercial production. For strategic planners, regulatory dynamics should be treated not as a peripheral compliance issue but as a central variable in market entry timing, product qualification roadmaps, and partnership structuring.
Operational Intelligence Embedded in the Full Report
The full market research study offers a structured, execution-oriented view of the gene-editing transfection chemical landscape, designed to support decision-making across R&D, commercial, and corporate development functions. The analysis integrates historical data from 2020 through 2025 with a forward-looking forecast period extending to 2032, enabling executives to evaluate both retrospective trends and projected demand pathways. Segmentation analysis provides clarity on how revenue is distributed across regions, product types, and applications without obscuring the strategic trade-offs that arise from differing growth rates, customer profiles, and competitive intensity.
Competitive profiling extends beyond company descriptions to examine product positioning, recent launches, trade show activations, and workflow-specific strengths. This approach helps readers assess where incumbents are reinforcing their advantages and where gaps may exist for new entrants or partnership-driven strategies. In addition, the report incorporates regulatory context, raw material considerations, and manufacturing standards as integral parts of the market narrative rather than isolated appendices. By embedding these dimensions within the core analysis, the study enables readers to connect market size projections with the operational realities that determine whether those projections can be realized in practice.
The report is structured to support a range of strategic use cases. For product leaders, it offers a basis for prioritizing formulation development, application targeting, and migration from research-grade to manufacturing-compatible portfolios. For commercial teams, it clarifies where demand is concentrated and how regional and application-level dynamics influence sales channel design. For corporate development and investment functions, it provides an evidence-based view of market concentration, competitive positioning, and the regulatory environment that shapes valuation assumptions and partnership logic. Readers seeking deeper quantitative breakdowns, company-by-company benchmarking, and scenario-based interpretation will find the detailed sections of the full report essential for translating high-level trends into actionable plans.
Decision Architecture for 2026 and Beyond
As organizations plan for 2026, the most valuable strategic question is not whether the gene-editing transfection chemical market is growing, but how to align internal capabilities with the specific drivers of that growth. Therapeutic development remains the dominant application driver, which means that companies serving clinical-stage programs must be prepared for heightened expectations around reproducibility, documentation, and regulatory alignment. At the same time, basic life science research continues to provide a stable foundation of demand, offering a buffer against clinical pipeline volatility and an early indicator of emerging delivery needs. Biomanufacturing represents a high-value growth vector, where scale, process consistency, and GMP-compatible reagent characteristics increasingly determine supplier selection.
Market concentration data indicates that the top three competitors account for approximately 35.5 percent of revenue, while the top five collectively represent about 52.8 percent. This level of concentration suggests that scale players hold meaningful advantages in distribution, customer relationships, and portfolio breadth. However, it also implies that targeted differentiation, specialized application support, and regional or workflow-specific expertise can still create viable positioning for focused participants. Strategic decisions should therefore consider whether to compete directly on breadth, partner to extend capabilities, or concentrate on high-value niches where technical performance and regulatory readiness are decisive.
Looking to 2032, the forecast trajectory implies a market that will continue to expand in both absolute terms and functional importance. The companies that benefit most will likely be those that treat transfection not as a commodity supply challenge but as a strategic enabler of gene-editing value chains. That means investing in products and services that bridge discovery throughput with manufacturing reliability, building regulatory-aware quality systems, and cultivating customer relationships that span the transition from early research to clinical and commercial deployment. Executives who evaluate their positioning against these long-term requirements will be better prepared to capture growth while managing the risks inherent in a rapidly evolving regulatory and competitive environment.
Strategic Conclusion
The gene-editing transfection chemical market sits at the intersection of scientific innovation, therapeutic commercialization, and regulatory evolution. Its growth from 2020 through 2025 and its projected expansion through 2032 reflect an industry that is moving beyond experimental proof-of-concept into sustained operational demand. The distribution of revenue across regions, product types, and applications reveals where value is concentrated today, while recent product launches, exhibition activity, and regulatory guidance highlight how competition and compliance are reshaping market expectations. Market concentration data further underscores the importance of scale, differentiation, and workflow alignment in determining who captures disproportionate value.
For decision-makers preparing for 2026, the strategic imperative is to translate market awareness into concrete capabilities: product relevance, regulatory readiness, supply reliability, and application-specific support. The full market research report provides the depth required to support those decisions, offering granular segmentation detail, competitive benchmarking, and forward-looking analysis that extend well beyond the high-level overview presented here. Readers seeking the complete dataset, extended company profiles, and detailed regional and application-level breakdowns are encouraged to access the source report for the comprehensive intelligence needed to inform strategic planning, investment prioritization, and market execution.
For detailed analysis of this topic, please visit the official page: Gene-Editing Transfection Chemical Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Air Purifying Headphones Market to Grow at 14.5 Percent CAGR Reaching 387 Million USD by 2032 Driven by Asia Pacific and Online Retail
By PW Consulting, 2026-09-02
The Convergence of Audio and Air: Strategic Rationale for the Air Purifying Headphones Market Report
The intersection of personal audio and personal health technology has historically been a niche curiosity, but recent market signals indicate a structural shift. As urban pollution baselines persist and consumer willingness to adopt wearable wellness tools expands, the air purifying headphones category has moved from conceptual prototypes to commercially viable hardware. For executives evaluating adjacent hardware, audio ecosystems, or environmental health products, the 2026 entry point demands a clear-eyed assessment of where scale is forming, where adoption friction remains, and which competitive moves are redefining the category. Our latest Air Purifying Headphones Market research is built to provide that assessment, translating macro momentum into operational intelligence that can inform portfolio planning, go-to-market sequencing, and competitive positioning through the forecast horizon.
Air Purifying Headphones Market
The strategic relevance of this research is rooted in timing. Base-year calibration for 2025 supports a market trajectory that expands from a 2025 revenue base of approximately USD 150.0 million to a 2026 estimate of USD 171.75 million, before continuing to climb through the end of the forecast period. The compound annual growth rate across the 2026 to 2032 window is projected at 14.5 percent, a pace that signals more than speculative interest. It points to a category progressing toward mainstream hardwareeconomics, provided manufacturers can resolve the trade-offs between purification performance, audio quality, wearability, and price architecture. This is precisely the environment in which concise narrative forecasts become insufficient, and a structured evidence base becomes necessary for decisions about capacity planning, channel mix, and product roadmap priorities.
Air Purifying Headphones Market
Why 2026 Is a Decision Point, Not Just a Forecast Year
From a strategic planning perspective, 2026 serves as a pivot year because the category is shedding early-adopter experimentation and entering a phase where competitive differentiation will be determined by execution details rather than novelty. The growth from 2025 to 2026 reflects more than incremental demand; it indicates that certain regions, channels, and connectivity configurations are beginning to pull disproportionate weight in total demand. Rather than treat those pulls as abstract trends, leadership teams need to understand how they interact with product design, certification pathways, and supply commitments. Our research addresses that need by connecting market size progression with segmentation architecture, distribution behavior, and competitive concentration, so decision-makers can test assumptions about where growth will be captured and by whom.
Air Purifying Headphones Market
The market is also advancing in a context where consumer behavior is shifting toward dual-purpose wearables. Air quality concerns and urban noise exposure are increasingly treated as simultaneous daily problems, not separate lifestyle issues. That convergence is reshaping the value proposition for headphones and earbuds, encouraging designs that combine active noise control with particulate mitigation in a single device. The result is a market where function migration matters as much as feature disclosure. Companies that only evaluate this category through an audio lens may underestimate the procurement drivers behind purification performance, while companies approaching it purely as a health device may undervalue the audio expectations that govern mainstream adoption. The research is designed to bridge those two lenses and translate them into commercially usable judgments.
What the Air Purifying Headphones Market Research Covers
The report is structured to support practical decision-making rather than abstract market description. It opens with a demand foundation that traces the evolution of the category from 2020 through the base year, then extends forward across the forecast period to 2032. The historical arc is deliberately included because growth patterns from the prior five years reveal how quickly the category moved from specialized prototypes to commercial availability, and where adoption concentrated during that ascent. That context is essential for interpreting the forward projection, since growth in a category this young depends heavily on the reproducibility of earlier demand drivers and the durability of early use cases.
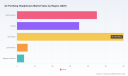
From there, the analysis moves into segmentation that breaks the market down by region, connection type, and distribution channel. These breakdowns are presented in a way that helps leadership teams assess where revenue is forming and how delivery paths are changing. The regional view provides a comparative frame for evaluating where market activity is most concentrated and where expansion may open next. The connection-type view distinguishes between wireless and wired configurations, recognizing that the balance between these sub-segments affects design priorities, battery strategies, cost structures, and consumer expectations. The distribution-channel view addresses the purchasing paths that matter most to commercial planning, including how online retail momentum compares with offline retail presence and what that balance implies for brand visibility, sell-through velocity, and margin strategy.
In addition to segmentation, the report includes a competitive and concentration analysis. Market concentration is a critical variable in a hardware category this young, and the data show a high degree of consolidation at the top of the field. The report examines this concentration to clarify how much of the market is already being contested by a small set of players, and what that implies for entry timing, differentiation requirements, and partnership considerations. Alongside that, the research includes competitive profiles that go beyond corporate descriptions to capture product positioning, technological approach, and market signaling. These profiles help teams understand not just who is competing, but how they are competing, which is essential for anticipating moves in product launches, channel expansion, and messaging.
The Competitive Landscape: Scale Players, Product Experimentation, and Category Pioneers
No market assessment of this category is complete without a clear view of the competitive field, because in a young hardware market, early player behavior often sets the template for later entrants. The report places particular emphasis on companies that have shaped category definitions and public perception. One prominent reference point is ible Technology Inc., headquartered in Taipei, Taiwan, whose public-facing product narrative centers on wearable ionic air purification integrated with noise-canceling earbuds and earphones. Its Airvida T1 and T1S series illustrate a design philosophy in which negative ion generation is used to address PM2.5, pollen, allergens, and bacteria while the same form factor simultaneously delivers Bluetooth audio and active noise cancellation. This dual-purpose architecture is illustrative of the category's central promise: that purification and personal audio can coexist in a single wearable without reverting to separate protective equipment.
The competitive picture also includes global hardware players whose participation signals both the seriousness of the category and the difficulty of scaling it. Dyson, based in Malmesbury, United Kingdom, previously entered this space with the Dyson Zone over-ear air-purifying headphones, which combined electrostatic filters with a directed clean-air visor and active noise cancellation. That product line was discontinued in mid-2025, with remaining stock potentially available through select retailers but no new manufacturing continuing. The discontinuation does not erase Dyson's relevance to the category; rather, it provides an important strategic case study. For market participants, the Dyson Zone episode helps define the boundary between aspirational product storytelling and durable commercial execution, and it underlines the importance of wearable ergonomics, filter replacement economics, and consumer willingness to accept a more complex wearable form factor.
The report also tracks recent developments that reveal how the competitive field is evolving. In January 2026, ible Technology Inc. presented the Airvida T1S wearable air purifier with noise-canceling earbuds at CES, with a stated focus on allergy and pollution concerns. This kind of show-floor positioning is significant because it demonstrates continued public reinforcement of the category's use cases and an intent to keep the wearable air purification concept visible among adjacent consumer technology audiences. Prior recognition also matters: the Airvida T1 received the 2024 Taiwan Excellence Award for a wearable air purifier integrated with in-ear Bluetooth noise-canceling earbuds. Awards and exhibition activity do not by themselves prove commercial durability, but they provide useful indicators of how manufacturers are trying to establish credibility and differentiate in a crowded hardware environment.
Market Dynamics That Shape Adoption and Execution
Behind the headline trajectory lies a set of dynamics that determine whether growth can be sustained and monetized. One of the most important is the convergence of consumer habit with product form. The core appeal of air purifying headphones is that they combine two protection functions into one device, which reduces the perceived burden of carrying separate masks or bulky equipment. That value proposition is especially relevant for urban commuters and allergy sufferers who face daily exposure to noise and air pollution. When the wearable form is acceptable and the performance claims are believable, the category can function as a convenience purchase as much as a health purchase. That dual motivation is central to demand stability, because convenience lowers the barrier to everyday use, while health framing supports premium positioning and repeat purchase in replacement-driven categories.
Another key dynamic involves product standard and performance communication. With ionic air purification in wearable devices, manufacturers have described generation levels on the order of up to 30 million ions per cubic centimeter for PM2.5 and allergen reduction, alongside claims of about 99.9 percent removal efficacy for certain particles and pathogens. These specifications matter because they influence purchasing decisions, retailer confidence, and regulatory posture. In a category where performance claims are central to the value proposition, credibility is not a marketing detail; it is a commercial precondition. Teams evaluating the market need to understand how performance communication interacts with consumer trust, what forms of verification are relevant, and where overstatement could create reputational or compliance exposure.
Certification and regulatory posture form a third dynamic layer. Wearable air purifier products in this space have been associated with multiple certifications, including SNQ Symbolic of National Quality awards in the epidemic prevention category in Taiwan, which relate to safety and efficacy in air pollutant and bacteria removal. Certification status is increasingly important because consumers, distributors, and downstream partners are more likely to scrutinize whether a device's claims are supported by recognized standards. In that sense, regulatory and certification signals can act as both a trust accelerator and a barrier to entry, depending on the maturity of a product portfolio and the time required to secure appropriate validation. The report incorporates these factors so that commercial planning can reflect not only demand potential but also the timelines and credibility requirements that shape execution.
Demand Patterns, Segmentation Signals, and Operational Implications
The segmentation architecture in the research is intended to help teams interpret where the market is forming and how that formation affects operating choices. The regional picture indicates that demand is not evenly distributed, and that imbalance matters for manufacturing planning, market entry sequencing, and channel investment. The connection-type split between Bluetooth wireless and wired configurations also provides a practical signal, because connectivity preference affects battery design, audio architecture, and cost framing. A heavier tilt toward wireless aligns with mainstream headset expectations, but it also raises the importance of battery life, charging behavior, and connectivity reliability as purchasing criteria. Meanwhile, the presence of wired configurations in the mix suggests that price-sensitive segments or specific use cases may continue to value tethered designs, especially where purification function is the primary purchase driver rather than audio convenience.
The distribution-channel view adds another operational layer. The comparison between online retail and offline retail is not merely about channel share; it is about the way products reach consumers and how brands build credibility. Online retail channels often support faster iteration, wider regional reach, and more controlled messaging, while offline retail can offer tactile demonstration, immediate purchase, and visibility in environments where air quality or audio performance is a salient purchase concern. Understanding how these channels interact can influence decisions about launch sequencing, retail partnerships, and merchandising strategy. In a category where performance claims and wearability both matter, the channel experience can be as important as the product specification.
Market concentration is the final structural element that shapes strategy. A market with high concentration among leading players means that competitive response, brand recognition, and channel relationships are likely to be contested terrain. For new entrants, that raises the bar for differentiation and suggests that unaided imitation of existing products is unlikely to generate durable advantage. For incumbents, it underscores the importance of defending share through product refinement, certification posture, and channel execution rather than relying on category novelty alone. The report addresses these concentration dynamics so that leadership teams can assess whether the market is open enough for targeted disruption or already tight enough to reward only sharply differentiated offerings.
How to Use This Research for 2026 Strategy
The value of the report is less in the macro numbers themselves than in the way those numbers are connected to decision-relevant variables. For product leadership, the research offers a basis for evaluating whether to invest in air purification as a differentiating feature, how to balance purification claims with audio expectations, and what form factors are likely to meet consumer acceptance. For commercial and channel teams, the segmentation and distribution analysis supports choices about where to prioritize launch activity, which retail environments warrant investment, and how online versus offline presence should be weighted. For corporate strategy and competitive intelligence functions, the concentration analysis and company profiles provide a framework for anticipating competitor behavior, especially in a category where the leading players are actively reinforcing the concept through exhibition presence, awards, and targeted messaging.
The report is also designed to help teams test assumptions before committing resources. If a company believes that demand will be led primarily by allergy and pollution-motivated users, the research allows that hypothesis to be examined against segmentation behavior and use-case evidence. If a company assumes that wireless will dominate the connection-type mix, the analysis helps frame the trade-offs involved in that assumption, including the design and battery implications that follow. If a company is considering acquisition, partnership, or licensing strategies, the competitive concentration and product positioning data provide a structured lens for evaluating where leverage may exist and where the field is already crowded.
What the Full Report Unlocks
This article is intended as a strategic preview, not a substitute for the complete study. The full report expands each macro signal into a detailed analytical framework, with historical-to-forecast progression, segmentation interpretation, distribution-channel behavior, competitive profiles, and concentration analysis presented in a format built for internal planning and external briefing. It also provides the operational context needed to translate market momentum into concrete actions, whether those actions involve product roadmap timing, channel strategy, certification planning, or competitive positioning in a category that is still defining itself.
The Air Purifying Headphones Market is advancing on the strength of a convergence argument that is easy to describe but harder to execute. The next several years will reward organizations that can discriminate between genuine adoption drivers and passing novelty, and that can convert that discrimination into product and channel decisions. Our full research is designed to support exactly that process by combining market scale, growth trajectory, segmentation logic, and competitive structure into one integrated view. For leaders preparing 2026 decisions and planning through 2032, the complete report offers the evidence base needed to move from category interest to actionable strategy.
For detailed analysis of this topic, please visit the official page: Air Purifying Headphones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Floating Dredging Hose Market to Reach USD 548 Million by 2032 with 5.2% CAGR
By PW Consulting, 2026-09-02
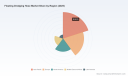
Navigating the Currents: Strategic Intelligence for the Floating Dredging Hose Market (2026–2032)
The global maritime and mining infrastructure sectors stand at a critical juncture. As urbanization accelerates, seaborne trade volumes expand, and coastal protection becomes a geopolitical priority, the demand for reliable, high-performance fluid handling solutions has never been more acute. At the center of this supply chain lies the floating dredging hose—a critical component that ensures the seamless transfer of abrasive slurries during capital projects, maintenance operations, and land reclamation initiatives.
Floating Dredging Hose Market
PW Consulting is proud to introduce our latest comprehensive market research report: Floating Dredging Hose Market Analysis and Strategic Outlook 2026–2032 . This document is not merely a data compilation; it is a strategic navigation tool designed for executives, procurement leaders, and investor relations teams who must make high-stakes decisions in a volatile economic environment. As we move through 2026, understanding the interplay between raw material cost pressures, geopolitical supply chain shifts, and engineering innovation is paramount. This article serves as a strategic preview of the intelligence contained within the full report, outlining the macro-economic trajectories and competitive dynamics that will define the next seven years.
Floating Dredging Hose Market
Macro-Economic Trajectory and Market Valuation
The floating dredging hose market has demonstrated remarkable resilience and growth over the past half-decade. Our analysis tracks the market revenue from 2020 through the base year of 2025, projecting forward with a detailed forecast period extending to 2032. The data indicates a consistent upward trajectory in market value, reflecting the health of the underlying dredging and mining sectors.
Floating Dredging Hose Market
In 2020, the market established a baseline revenue figure of USD 295.0 Million. Over the subsequent years, the industry absorbed various global disruptions while maintaining growth momentum. By the base year of 2025, the market has expanded to USD 385.0 Million. This growth is not incidental; it is driven by foundational shifts in global trade logistics and infrastructure development. Looking ahead, our forecast models project the market to breach the USD 400 Million threshold in 2026, reaching approximately USD 400.26 Million.
The compound annual growth rate (CAGR) for the forecast period (2026–2032) is calculated at 5.2%. While this figure represents a steady, mature growth rate rather than speculative hyper-expansion, it underscores the essential nature of dredging infrastructure. By 2032, the market is projected to reach USD 548.0 Million. For strategic planners, this trajectory suggests a market that is large enough to support significant investment but competitive enough to require precise segmentation and differentiation strategies. The revenue unit throughout this analysis is maintained in USD Million to ensure consistency in financial modeling and ROI calculations.
Key Growth Drivers and Industry Context
To understand the sustainability of this growth curve, one must look beyond the headline numbers. Our research identifies several macro-trends that act as tailwinds for the floating dredging hose sector.
- Port Expansion and Navigational Deepening: Seaborne trade continues to grow, necessitating deeper channels and expanded port capacities to accommodate larger vessels. This activity accounts for a major share of global dredging demand. As channels are deepened, the reliance on floating hoses for discharge and suction operations increases proportionally.
- Land Reclamation and Coastal Protection: Driven by population growth and rapid urbanization, particularly in emerging economies, land reclamation projects remain a key driver for dredging equipment. These projects require durable hosing solutions that can withstand continuous operation in marine environments.
- Mining and Resource Extraction: The need for efficient slurry transport in mining operations continues to support demand for heavy-duty floating hoses, linking the dredging market closely to commodity cycles.
However, growth is not without friction. The industry is currently navigating significant raw material volatility. Natural rubber, a primary material in floating dredging hoses alongside SBR and other synthetics, saw global benchmark prices around USD 1.92/kg in early 2026. There is upward pressure on these costs due to supply constraints. Furthermore, the US Producer Price Index for Rubber and Plastics Hose and Belting Manufacturing reached 346.867 in April 2026. These indicators suggest that margin management and supply chain contracting will be critical themes for 2026 and beyond, a nuance fully explored in our report.
Segmentation Dynamics: Product Types and Applications
Strategic decision-making requires more than top-line revenue figures; it demands an understanding of where value is generated within the value chain. Our report provides a granular breakdown of the market by product type and application, allowing clients to identify their specific niche within the broader ecosystem.
Product Type Analysis
The market is primarily driven by established material technologies, though innovation is shifting the balance. Our segmentation analysis covers the three dominant categories prevalent in the industry.
- Rubber Hoses: Traditional rubber remains the backbone of the industry due to its flexibility, durability, and resistance to abrasion. This segment continues to hold significant weight in the overall revenue mix, favored for its proven performance in harsh slurry environments.
- Reinforced Composite Hoses: As operational pressures increase and distances for slurry transport extend, reinforced composite options are gaining traction. These products offer enhanced strength-to-weight ratios and are often selected for specialized high-pressure applications.
- Plastic and PE Hoses: While representing a smaller portion of the high-value market, plastic and polyethylene options serve specific use cases where cost-efficiency and chemical resistance are prioritized over extreme wear resistance.
Our report details the revenue contribution and growth rates of each type without exposing the full proprietary dataset. We analyze how material cost fluctuations, such as the aforementioned rubber price benchmarks, differentially impact each segment. For instance, manufacturers heavily reliant on natural rubber compounds may face different margin pressures compared to those utilizing synthetic alternatives or composite structures.
Application-Based Insights
Equally critical is the breakdown by application. Different dredging activities impose different requirements on hose performance, longevity, and deployment logistics.
- Capital Dredging: This segment involves large-scale projects such as new port construction or major land reclamation. It typically requires high-capacity hoses capable of handling continuous, heavy-duty operation over extended project lifecycles. This is often the highest value segment in terms of volume per project.
- Maintenance Dredging: Ports and waterways require ongoing maintenance to remain navigable. This segment offers recurring revenue opportunities driven by the need for reliable equipment that can be deployed quickly for periodic cleaning and sediment removal.
- Land Reclamation: Distinct from pure capital dredging, this application focuses on creating new land mass. It demands hoses that can manage high volumes of slurry discharge in specific coastal configurations.
The full report provides a deep dive into the revenue splits and growth trajectories for each application vertical. We examine how regional infrastructure budgets and environmental regulations influence the mix of capital versus maintenance spending, thereby altering the demand profile for specific hose configurations.
Regional Landscape and Supply Chain Considerations
Geography plays a decisive role in market access and competitive positioning. Our analysis maps the market revenue across key global regions, highlighting where demand is concentrated and where manufacturing hubs are located.
The Asia Pacific region represents a significant portion of global market revenue, driven by intense infrastructure development and a robust presence of both dredging contractors and hose manufacturers. Europe follows as a mature market with strong emphasis on high-performance, engineered solutions, often linked to stringent environmental and safety standards. North America maintains a steady demand profile supported by port infrastructure and mining activities. The Middle East and Africa, along with Latin America, contribute to the global total with specific project-driven demand spikes often tied to resource extraction or port modernization initiatives.
While we refrain from disclosing specific regional percentage splits in this preview, the full report quantifies the revenue contribution of each region. This data is essential for companies deciding on manufacturing localization, distribution networks, and sales force deployment. Understanding where the demand centers are—and how they correlate with manufacturing bases in countries like China, Germany, Sweden, and the USA—is vital for supply chain optimization.
Competitive Landscape and Strategic Positioning
The floating dredging hose market is characterized by a mix of established global industrials and specialized regional manufacturers. Our report provides detailed profiles of key companies, analyzing their product portfolios, recent developments, and strategic positioning.
Market concentration data indicates a moderately consolidated environment. The top three companies hold a combined market share of approximately 45%, while the top five account for around 60%. This suggests that while there is room for specialized players, scale and brand reputation remain significant barriers to entry.
Profiles of Key Industry Players
Our research includes comprehensive operational profiles of leading entities that define the current competitive baseline.
- Trelleborg AB (Sweden): Recognized as a leading supplier of floating dredging hoses with systems used on major global reclamation projects. They have recently offered redesigned RockFloat and FloatLine hoses aimed at extended lifetime in cutter and discharge applications, signaling a focus on product lifecycle and durability.
- Salem-Republic Rubber Co. (USA): A custom manufacturer specializing in large-bore dredging hoses, including floating, suction, and discharge variants. Their focus on heavy-duty wear-resistant constructions with custom rubber compounds positions them strongly in the North American and specialized project markets.
- The Weir Group plc (Linatex) (Scotland): Provides Linatex heavy-duty floating dredge hoses with internal flotation options. Their solutions are custom-engineered for abrasive slurries in mining and dredging operations worldwide, leveraging strong brand equity in fluid handling.
- ContiTech AG (Continental) (Germany): Manufactures industrial dredging and floating hoses using high-performance rubber compounds for marine and slurry applications. Their integration into a larger industrial conglomerate provides supply chain stability and R&D depth.
- JinYuan Rubber Manufacturing (JYM Hose) LTD (China): A Chinese manufacturer of industrial rubber hoses including dredging hoses for construction, mining, and marine sectors. ISO9001 certified with exports to multiple regions, representing the growing export capacity of Asian manufacturers.
- Hebei Orient Rubber & Plastic Co., Ltd (Orientflex) (China): Produces dredging hoses including floating variants for port, dock, and slurry discharge applications, catering to both domestic and international infrastructure needs.
- CDSR Technology Co., Ltd (China): Specializes in floating dredging hoses and marine rubber hoses for dredging operations, focusing on technical specialization within the marine sector.
- Hebei Zebung Rubber Technology Co., Ltd (China): A manufacturer of high wear-resistant rubber dredge hoses including floating types for large dredgers. Recently, in July 2025, they completed a delivery of floating dredging hoses for water conservancy projects highlighting marine-grade pressure resistance.
Recent Market Developments
The competitive landscape is dynamic, with companies actively signaling their capabilities through product deliveries and exhibition participation. For example, in February 2025, Sinopulse showcased dredging hoses including floating types as part of a 2025 global exhibition tour. Such activities are not merely marketing; they are strategic moves to secure presence in emerging markets and demonstrate compliance with international standards. Our report analyzes these events to gauge corporate intent and market expansion strategies.
For procurement managers, understanding the difference between a global integrator like Trelleborg or Weir and a specialized manufacturer like Salem-Republic or CDSR is crucial. The choice often depends on the specific project requirements, lead time sensitivities, and the need for custom engineering versus off-the-shelf solutions. Our full report provides a comparative framework to assist in vendor selection and risk assessment.
The Strategic Value of This Report for 2026 Decision Making
In an era where data is abundant but actionable intelligence is scarce, the PW Consulting Floating Dredging Hose Market Report is designed to reduce uncertainty. The value proposition for your organization extends across several critical business functions.
Procurement and Supply Chain Resilience
With raw material indices showing volatility—such as the rubber PPI reaching 346.867 and natural rubber prices hovering near USD 1.92/kg—procurement strategies cannot rely on historical costing models alone. This report provides the market context needed to negotiate long-term supply contracts, anticipate price hikes, and evaluate supplier stability. By understanding the market growth trajectory and the key players' manufacturing locations, companies can build more resilient supply chains that mitigate geopolitical and material risks.
Market Entry and Expansion Planning
For manufacturers considering expansion into new regions or product categories, the segmentation data is invaluable. Knowing which application segments are growing fastest and which regions offer the highest revenue potential allows for targeted investment. Whether it is entering the capital dredging segment in Asia Pacific or focusing on maintenance dredging in Europe, the report provides the foundational data to build a business case.
Investment and M&A Due Diligence
Investors and strategic acquirers need to understand the market size, growth rate (CAGR 5.2%), and concentration levels (CR3 45%, CR5 60%) to evaluate potential targets or market opportunities. The report outlines the competitive landscape, highlighting which companies are gaining share through innovation (e.g., extended lifetime hoses) and which are expanding through exhibition and delivery networks. This qualitative and quantitative overlay supports more informed valuation and integration planning.
Risk Management and Regulatory Compliance
The dredging industry is increasingly subject to environmental regulations and safety standards. Our report touches upon the industry context regarding land reclamation and coastal protection, areas where regulatory scrutiny is high. Understanding the market drivers in these sectors helps companies anticipate compliance requirements and adapt their product offerings accordingly. For instance, the shift towards hoses with extended lifetimes reduces waste and operational downtime, aligning with sustainability goals that are becoming central to project bidding.
Conclusion: Positioning for the Future
The period from 2026 to 2032 promises to be a defining era for the floating dredging hose market. As the market moves from a baseline of USD 385.0 Million in 2025 toward a projected USD 548.0 Million in 2032, the opportunity for growth is clear. However, capturing that growth requires more than passive participation. It demands a sophisticated understanding of material cost dynamics, regional demand shifts, and the competitive maneuvers of key players like Trelleborg, Weir, Salem-Republic, and the growing cohort of specialized Asian manufacturers.
This preview has outlined the structural bones of the market: the growth trajectory, the segmentation logic, the competitive field, and the macro-economic headwinds. Yet, the true power of this research lies in the details that must be strategically deployed within your organization. The specific revenue splits, the granular regional forecasts, and the deep-dive company analyses are the tools that will differentiate a reactive organization from a proactive market leader.
We invite you to access the full Floating Dredging Hose Market Analysis and Strategic Outlook 2026–2032 report. Inside, you will find the complete dataset, detailed methodology, and the specific intelligence required to navigate the currents of this essential industry. Let PW Consulting be your partner in charting the course for profitable growth in the dredging sector.
For detailed analysis of this topic, please visit the official page: Floating Dredging Hose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Clean Indicator Market Report Projects USD 250M Value in 2025, Expecting 6.15% CAGR Toward USD 379.63M by 2032 with North America Leading
By PW Consulting, 2026-09-02
The Strategic Imperative of Cleaning Verification: Navigating the 2026 Cleaning Indicator Market Landscape
Introduction: The Silent Guardian of Patient Safety
In the high-stakes ecosystem of medical device reprocessing, the efficacy of cleaning protocols serves as the fundamental cornerstone of infection prevention. While sterilization often garners the majority of regulatory and clinical attention, the preceding cleaning stage determines the success of the entire sterilization cycle. Residual bioburden, proteins, and soil on surgical instruments can shield microorganisms from sterilizing agents, rendering the process ineffective and posing severe risks to patient safety. Consequently, the market for cleaning indicators—specialized tools designed to verify the cleaning performance of washer-disinfectors and ultrasonic baths—has evolved from a compliance checkbox into a critical component of quality assurance infrastructure within Central Sterile Supply Departments (CSSD) and healthcare facilities globally.
Cleaning Indicator Market
As we move into 2026, healthcare providers, procurement officers, and infection control practitioners face a complex decision matrix. The industry is witnessing a convergence of stricter regulatory expectations, technological advancements in synthetic test soils, and a growing body of peer-reviewed evidence regarding routine monitoring methods. Our recently released comprehensive market study on the Cleaning Indicator Market is designed to illuminate this landscape, offering data-driven clarity to stakeholders aiming to optimize their reprocessing workflows and mitigate compliance risks. This article provides a strategic overview of the market's trajectory, competitive dynamics, and regulatory forces, underscoring the essential value of our full report for enterprise-level decision-making.
Cleaning Indicator Market
Market Trajectory: Sustained Growth Amidst Evolving Standards
The Cleaning Indicator Market has demonstrated remarkable resilience and upward momentum over the past half-decade, reflecting the healthcare sector's intensified focus on hygiene and instrument reprocessing standards. Our analysis tracks consistent revenue expansion across historical years and projects a robust forecast period extending through 2032. The market has already expanded significantly from 2020 to 2025, with total revenue reaching 250.0 million USD in the base year of 2025. This foundational growth sets the stage for a forecast period where the market is anticipated to rise to 269.81 million USD in 2026 and continue its ascent toward 379.63 million USD by 2032.
Cleaning Indicator Market
Driving this expansion is a sustained Compound Annual Growth Rate (CAGR) of 6.15 percent over the forecast period. This rate underscores a steady, structural increase in demand rather than a fleeting market spike. Several macro-level factors contribute to this trajectory. First, the global volume of surgical procedures continues to rise, directly increasing the throughput of instruments requiring reprocessing and, by extension, the consumption of cleaning verification tools. Second, healthcare administrators are increasingly recognizing that cleaning validation is not merely a technical requirement but a strategic investment in reducing surgical site infections and avoiding costly recalls or regulatory penalties. Third, the shift toward more sophisticated washer-disinfector technologies necessitates compatible, high-performance indicators that can accurately challenge these systems across a range of soil types and cleaning cycles.
Our report delves deep into the mechanics of this growth, analyzing how different segments contribute to the overall market velocity. While the revenue breakdown across chemical, biological, and enzymatic solutions, as well as applications within hospitals, dental clinics, and diagnostic centers, reveals distinct adoption patterns, our full analysis provides the granular segmentation data required to identify high-opportunity niches. For example, the dominance of certain application sectors reflects the high volume of instruments processed in large healthcare facilities, while the varying adoption rates of indicator types highlight the ongoing debate between traditional biological challenges and newer synthetic alternatives. Stakeholders accessing our complete intelligence can pinpoint exactly where capital allocation and product development resources will yield the highest returns in specific sub-markets.
Navigating the Competitive Arena: Key Players and Innovation Hubs
The competitive landscape of the Cleaning Indicator Market is characterized by a mix of established multinational corporations and specialized manufacturers with deep technical expertise. The market exhibits a moderate level of concentration, with the top three competitors holding a combined market share of 48.2 percent and the top five firms accounting for 62.5 percent. This concentration suggests that while large players exert significant influence through scale and brand recognition, there remains ample room for innovation and differentiation among smaller, agile entities. Our report provides a detailed competitive profiling of the key companies shaping this ecosystem, offering insights into their product portfolios, strategic positioning, and recent developments.
STERIS stands as a formidable presence in the market, headquartered in the United States. The company offers specialized solutions such as the T-EZ PRO Cleaning Indicator and the VERIFY All Clean Test Washer Indicator. These products are engineered for routine monitoring of automated washer-disinfectors, utilizing both blood-based and synthetic test soils to provide comprehensive verification options. STERIS's strength lies in its ability to supply robust, reliable indicators that integrate seamlessly into existing CSSD workflows, appealing to large hospital networks seeking consistency and ease of use.
Belimed , based in Switzerland with US operations in Ladson, SC, brings a focus on sustainability and performance. Their Belimed Protect Cleaning Indicator (BPCI) utilizes a synthetic recyclable substrate, offering a modern alternative for washer-disinfector cleaning process verification. This approach aligns with the broader industry trend toward environmentally conscious solutions without compromising on the rigorous challenge levels required for effective monitoring. Belimed's emphasis on recyclable substrates positions them as an attractive option for facilities prioritizing sustainability goals alongside operational efficiency.
In Europe, gke , headquartered in Germany, maintains a strong reputation for technical compliance and scientific rigor. The company supplies the RI Cleaning Indicator, which employs sheep blood on stainless steel carriers, alongside other cleaning process indicators designed for washer-disinfectors and ultrasonic baths compliant with ISO 15883 standards. gke's recent activities highlight their commitment to advancing industry knowledge. In July 2025, they published a study in the PLOS ONE Journal detailing a test method for selecting suitable cleaning indicators for routine monitoring in CSSD. Furthermore, in January 2026, gke updated their product catalog with enhanced offerings for RI Cleaning Indicators and holders, reinforcing their dedication to ISO 15883 compliant monitoring. These developments underscore the importance of evidence-based testing methods, a theme that our report explores extensively.
From Latin America, Terragene , based in Argentina, contributes to the market with its Chemdye Splat washing indicators. These products utilize synthetic test soil inks for the routine control of cleaning processes in washer-disinfectors and ultrasonic cleaners. Terragene's presence demonstrates the global reach of cleaning indicator solutions and the diverse preferences for soil types across different regions. Similarly, Crosstex (Cantel Medical) , headquartered in the United States, offers a Cleaning Verification Test (CV Test) featuring stainless steel carriers and sheep blood-based soils. Their products are designed for washer-disinfector monitoring per ISO 15883, catering to facilities that require traditional biological challenge methods to validate cleaning efficacy.
Sterintech , operating from India, provides cleaning indicators tailored for Operating Theater (OT) and CSSD applications. Their offering reflects the growing demand in emerging healthcare markets where cost-effectiveness, reliability, and accessibility are paramount. By including Sterintech in our competitive analysis, we highlight how regional manufacturers are addressing specific local needs while adhering to global quality standards.
Beyond company profiles, our report analyzes the strategic implications of recent industry events. For instance, the December 2025 guidance release by Hygiene Diagnostics on selecting the right cleaning indicators for medical device reprocessing, which emphasizes validation and challenge levels, signals a maturing market where end-users are becoming more discerning. This guidance encourages facilities to look beyond generic specifications and evaluate indicators based on their ability to simulate real-world soiling and withstand the mechanical and chemical stresses of modern cleaning equipment. Our full report utilizes such developments to forecast how competitive dynamics will shift as manufacturers respond to evolving user expectations and regulatory pressures.
Strategic Dynamics: Regulation, Technology, and the ISO 15883 Framework
The market's evolution is inextricably linked to the regulatory and technical environment governing washer-disinfector performance. A central pillar of this framework is the ISO 15883 series, including Part 5:2021, which establishes performance requirements and test methods with quantitative acceptance criteria for demonstrating cleaning efficacy. This standard provides the benchmark against which washer-disinfectors and, by extension, the cleaning indicators used to test them must be evaluated. However, a nuanced challenge exists within this landscape: while ISO 15883 defines how cleaning efficacy should be demonstrated, there is no specific international standard that regulates the resistance or performance thresholds of commercial cleaning indicators themselves. As noted in industry analysis via peer-reviewed comparisons from 2023 to 2025, this gap leads to manufacturer-specific challenge levels, creating variability in how different indicators perform under identical conditions.
This regulatory asymmetry presents both a risk and an opportunity for market participants. For healthcare facilities, the lack of a unified standard for indicator challenge levels necessitates a more rigorous approach to selection. Procurement teams must evaluate indicators not just on brand reputation but on their test soil composition, carrier materials, and documented performance data. The use of test soils such as sheep blood, proteins, and polysaccharides on stainless steel carriers, as documented in manufacturer technical data sheets from STERIS, gke, and Crosstex, aims to simulate real instrument soiling in CSSD applications. Yet, the variability in soil preparation, application methods, and the mechanical resistance of the soil can significantly impact the outcome of cleaning tests. Our report dissects these technical nuances, guiding readers on how to interpret manufacturer claims and align indicator selection with their specific equipment and workload profiles.
Furthermore, the industry is seeing a push toward standardized selection methodologies, as exemplified by the recent test method publication from gke. This trend suggests that the market is moving toward greater scientific consensus on how to validate routine monitoring protocols. For manufacturers, this environment rewards those who invest in robust validation data, transparent challenge level descriptions, and educational resources that help customers navigate the complexity of cleaning verification. Competitive advantage will increasingly belong to companies that can demonstrate the reliability of their indicators across a breadth of soil types and cleaning conditions while providing the technical support necessary for effective implementation.
The dynamics section of our report also explores how regulatory trends influence regional market adoption and product innovation. While ISO standards provide a global baseline, local regulations and accreditation requirements can vary, affecting the demand for specific indicator types. For instance, regions with stringent infection control audits may see higher demand for indicators that provide clear, quantifiable pass/fail criteria suitable for documentation. Conversely, markets focused on cost optimization may prioritize durable, recyclable synthetic indicators that reduce consumable waste. Understanding these localized dynamics is crucial for multinational healthcare groups and suppliers operating across multiple jurisdictions.
Actionable Intelligence: What the Full Report Delivers
Understanding the macroeconomic trends and competitive actors is only the first step. To make informed decisions in 2026, stakeholders need detailed segmentation data, granular regional analysis, and forward-looking insights into technological disruptors. Our comprehensive report goes far beyond high-level summaries, offering a toolkit of actionable intelligence designed to support strategic planning, product development, and market entry strategies.
The report provides a deep dive into segmentation splits, allowing readers to assess the relative size and growth potential of key market categories. We analyze the By Region breakdown to identify geographic hotspots and maturity levels, from established markets with high adoption rates to emerging regions with expanding healthcare infrastructure. This regional intelligence helps companies tailor their distribution networks and marketing efforts to local demand drivers. We also examine the By Type segmentation, comparing the market footprint and growth trajectories of Chemical Indicators, Biological Indicators, and Enzymatic Cleaning Indicators. This analysis reveals how the preference for specific indicator types is evolving in response to performance requirements, cost considerations, and sustainability initiatives. Additionally, the By Application split offers a detailed view of revenue contributions from Hospitals and CSSD, Dental Clinics, and Diagnostic Centers, highlighting how different facility types prioritize cleaning verification based on instrument complexity and regulatory exposure.
Critically, our report includes detailed regional segmentation data that breaks down market size and growth rates for each geographic area, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. This level of granularity enables stakeholders to pinpoint high-growth corridors and assess competitive intensity in specific territories. Similarly, the application-level segmentation provides specific revenue figures for each end-use sector, empowering readers to benchmark their own performance and identify underserved or over-served segments. The type-level segmentation offers precise breakdowns that clarify the relative commercial strength of chemical, biological, and enzymatic solutions, guiding product portfolio decisions and R&D investments.
For manufacturers and investors, the report's competitive analysis section offers more than just company profiles. We evaluate market positioning, product innovation pipelines, and strategic moves, providing a framework for assessing competitive threats and partnership opportunities. The inclusion of recent developments, such as the PLOS ONE study, updated product catalogs, and hygiene guidance releases, ensures that readers are aware of the latest shifts in industry discourse and technical standards. We also analyze the implications of the moderate market concentration, discussing how the balance between market leaders and niche players affects pricing power, innovation speed, and customer lock-in.
Healthcare administrators and procurement leaders will find value in the operational insights embedded throughout the report. We discuss how to interpret cleaning indicator performance data, align indicator selection with ISO 15883 compliance goals, and build robust monitoring protocols that withstand audit scrutiny. The report addresses the practical challenges of test soil variability, the importance of validating challenge levels for specific washer-disinfector models, and the role of indicators in supporting overall quality management systems. By synthesizing technical, regulatory, and commercial perspectives, our analysis serves as a comprehensive reference for optimizing cleaning verification strategies.
Conclusion: Empowering Data-Driven Decisions in a Critical Market
The Cleaning Indicator Market stands at the intersection of patient safety, regulatory compliance, and operational efficiency. As the market expands from 250.0 million USD in 2025 toward an anticipated 379.63 million USD by 2032, with a CAGR of 6.15 percent, the window for strategic action is open but narrowing. Organizations that fail to grasp the nuances of cleaning verification risk compliance gaps, inefficient resource allocation, and heightened vulnerability to infection control failures. Conversely, those who invest in deep market intelligence can secure a decisive advantage, aligning their product offerings, procurement practices, and quality protocols with the evolving realities of the reprocessing landscape.
Our full market research report is designed to be that decisive resource. It transforms raw data and industry observations into a coherent strategic narrative, offering the segmentation depth, competitive clarity, and dynamic analysis necessary to navigate the complexities of 2026 and beyond. Whether you are a manufacturer seeking to refine your product roadmap, a healthcare provider aiming to fortify your CSSD operations, or an investor evaluating market opportunities, the insights contained within this study are tailored to elevate your decision-making process.
To access the complete dataset, detailed regional and application breakdowns, and the full competitive intelligence profile, we invite you to secure a copy of our latest Cleaning Indicator Market research report. The future of cleaning verification is being shaped by rigorous standards, technological innovation, and a growing emphasis on evidence-based monitoring. Ensure your organization is equipped with the intelligence required to lead, not just follow, in this critical and rapidly evolving market.
For detailed analysis of this topic, please visit the official page: Cleaning Indicator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Laminated Pastries Market to Reach $6.5 Billion by 2032 with 5.5% CAGR from 2025 Base Year
By PW Consulting, 2026-09-02
Strategic Intelligence for the Laminated Pastries Market: Navigating the 2026 Landscape
Executive Summary: The Imperative for Precision Market Intelligence
In an era where margin compression, supply chain volatility, and rapidly shifting consumer palates intersect, the laminated pastries category demands more than generic industry forecasts. Decision-makers across retail bakery, foodservice, manufacturer, and investment portfolios require granular, forward-looking intelligence to allocate capital, engineer product pipelines, and position distribution networks against structural shifts. Our newly released Laminated Pastries Market research delivers precisely that framework. Built on a rigorous multi-year historical baseline and extended through a seven-year forecast horizon, this study transforms macroeconomic signals into actionable strategic pathways. The 2026 edition arrives at a critical inflection point: production investments are resetting capacity baselines, ingredient cost structures are recalibrating, and category boundaries are blurring as hybrid formats transition from novelty to staple. Companies that rely on fragmented data or lagging indicators will find themselves navigating blind. The full research report supplies the analytical rigor and segment-level clarity required to execute with confidence.
Laminated Pastries Market
Structural Resilience and Growth Trajectory: What the Numbers Reveal
The laminated pastries market has demonstrated remarkable structural resilience despite the turbulence of recent years. Historical tracking from 2020 through 2025 reveals a consistent upward cadence, interrupted only briefly by transient supply shocks, yet quickly returning to its growth orbit. Following a measured rebound period, valuation trajectories have stabilized and accelerated into the current baseline year, establishing a robust foundation for forward projections. The forecast window extends through the early 2030s, projecting a compound annual growth rate of 5.5 percent. This trajectory reflects compounding demand drivers rather than cyclical spikes, underscoring the category's maturation into a steady growth engine within the broader bakery ecosystem. Revenue forecasts at the close of the projection period point to a substantially expanded market footprint, signaling sustained commercial opportunity for well-positioned operators.
Laminated Pastries Market
Such macro-level momentum masks nuanced regional and channel dynamics that only a detailed decomposition can illuminate. Different geographic footprints exhibit divergent growth velocities, shaped by local consumption habits, retail modernization rates, and competitive density. Distribution architectures are similarly fragmenting, with traditional mass retail, convenience-oriented formats, specialty retail, and digital fulfillment each claiming distinct roles in the end-to-end consumer journey. Type-level performance further reflects varying degrees of technological investment, ingredient optimization, and brand positioning. Access to these disaggregated dimensions enables leadership teams to model scenario-based expansions, identify whitespace opportunities, and anticipate where capacity or shelf-space investments will yield the highest risk-adjusted returns.
Laminated Pastries Market
Competitive Architecture: How the Incumbents Are Shaping the Field
The competitive landscape of the laminated pastries market is defined by a blend of global ingredient and solution providers, regional production specialists, and vertically integrated retail-foodservice operators. Foundational players such as CSM Bakery Solutions and PURATOS Group anchor the upstream value chain, delivering dough formulations, clean-label emulsions, and technical innovation that lower the barriers for downstream manufacturers and branded product developers. Midstream and downstream specialists like Dawn Food Products, Rich Products Corporation, and Europastry S.A. bridge formulation and execution, supplying frozen and par-baked formats engineered for consistent quality across high-volume and labor-constrained environments. Companies such as Aryzta AG and Lantmännen Unibake straddle the production and brand interface, combining European-inspired artisanal heritage with scalable manufacturing capabilities and increasingly sustainability-forward product lines.
Broader bakery conglomerates including Grupo Bimbo and General Mills extend market reach through multi-brand portfolios, leveraging established distribution networks and consumer-facing familiarity to capture share across retail and foodservice channels. The aggregate market concentration remains relatively fragmented at the top tier, with the leading entities holding a combined share that leaves substantial room for regional champions, niche innovators, and channel-specific specialists to compete effectively. This structural openness rewards companies that can differentiate through operational efficiency, ingredient transparency, format hybridization, or targeted channel penetration.
Recent Competitive Moves: Capital, Innovation, and Format Evolution
Investment activity through late 2025 and early 2026 illustrates how incumbents are responding to both cost pressures and demand evolution. In January 2026, Aryzta AG announced a substantial euro-denominated investment in a new bakery plant in Portugal, explicitly oriented toward supplying laminated products to quick-service restaurant channels. This capacity addition signals a strategic bet on the continued institutionalization of laminated pastries in fast-paced foodservice ecosystems. Earlier, in the spring of 2025, Lantmännen Unibake committed to a significant production investment in its Örebro facility, expanding capacity while embedding sustainability features into laminates production, reflecting a dual emphasis on scale and responsible manufacturing. On the product innovation side, CSM Ingredients advanced reduced-fat and clean-label emulsions tailored for baked and laminated applications, directly addressing the long-standing tension between indulgent texture expectations and health-conscious labeling requirements.
Equally instructive is the market observation captured in late 2025 regarding hybrid laminated dough formats, such as the crookie phenomenon, transitioning into permanent bakery staples rather than remaining ephemeral social media trends. This shift carries profound implications for SKU architecture, production scheduling, and shelf-space management. Companies that treat hybrid formats as transient fads risk missing durable consumption behavior changes, while those that integrate them into core portfolios with disciplined cost-to-serve modeling can capture incremental growth without compromising category coherence. The full report dissects how these strategic moves interlock with broader supply chain, pricing, and distribution dynamics.
Macro-Force Reconfiguration: Inputs, Costs, and Operational Pressure Points
The economics of laminated pastries production are materially shaped by input cost structures, regulatory environments, and labor market conditions. Butter continues to represent a dominant share of ingredient expenses, accounting for a substantial portion of total input costs in laminated formulations. Differentiated pricing forecasts indicate European butter markets are expected to trend toward moderated levels through 2026, creating potential cost relief for producers in that geography while underscoring the volatility that remains in dairy-linked inputs. Soft wheat flour pricing, meanwhile, has maintained relative stability with expectations of gradual upward movement into 2026, a dynamic that warrants proactive procurement and hedging strategies for operators sensitive to flour as a primary cost driver.
Regulatory shifts have introduced additional cost friction. Tariff actions implemented in 2025 have elevated input costs for bakeries across multiple geographies, with measurable impacts on imported dairy and cocoa-dependent components commonly used in pastry formulations. Labor cost structures further complicate margin management, particularly in regions where wage rates and staffing scarcity converge. In markets such as Texas, labor represents a substantial share of gross revenue, with skilled bakers commanding wage bands that have risen amid persistent worker shortages. These compounding factors heighten the value of operational levers such as par-baked and frozen formats, reduced-labor preparation solutions, and ingredient optimization that preserves sensory profiles while moderating cost intensity.
The report maps these input dynamics directly onto segment-level cost modeling, regional exposure assessments, and channel-specific margin architectures. By quantifying how raw material volatility, tariff-induced cost pass-through, and labor scarcity interact across different product types and distribution pathways, the analysis equips teams to design procurement calendars, renegotiate supplier terms, and reconfigure production footprints with greater precision.
Inside the Report: What Decision-Makers Will Find
Beyond the headline trajectory, the research provides a structured, decision-oriented toolkit designed for cross-functional use. The analysis framework covers demand segmentation by region, product type, and distribution channel, enabling readers to isolate growth engines, identify concentration risks, and benchmark performance relative to category averages. Historical baselines reconcile observed market evolution with structural drivers, while the forward projection integrates demand elasticity, capacity expansion timelines, and channel shift assumptions into a coherent seven-year outlook.
The competitive profiling extends beyond company summaries, examining strategic positioning, technology adoption patterns, geographic coverage, and response mechanisms to input and regulatory pressures. Innovation roadmaps, capacity investment timelines, and format hybridization trends are synthesized to reveal where competitive advantage is likely to accrue. Procurement and cost frameworks connect ingredient pricing arcs, labor economics, and tariff exposure to operational scenarios, allowing readers to stress-test margin resilience under multiple input environments. Distribution and channel analysis examines how hypermarket and supermarket dominance, convenience store penetration, specialty bakery positioning, and online retail growth interact to shape end-market access.
For executives, the report is structured to support capital allocation decisions, SKU portfolio rationalization, channel expansion planning, and competitive benchmarking. For product development and supply chain teams, it provides context on ingredient substitution feasibility, format engineering trade-offs, and capacity alignment with demand growth. For investment and strategy functions, it delivers a defensible baseline against which to evaluate market entry, partnership targeting, and acquisition rationale. All segment-level quantification, regional breakdowns, and channel-specific modeling remain within the full report, accessible through the source publication.
Strategic Takeaways for the 2026 Planning Cycle
The laminated pastries market is entering a phase in which growth is less about broad category tailwinds and more about precise alignment between product architecture, input economics, channel strategy, and competitive positioning. Several strategic priorities emerge for the current planning cycle.
- Capacity investments must be calibrated to demand distribution, not just aggregate market size. Understanding where growth concentrates by region, type, and channel enables firms to avoid overbuilding in low-velocity segments while capturing high-velocity nodes with the right format and service model.
- Ingredient cost management requires both tactical procurement and portfolio-level formulation strategy. Butter and flour dynamics interact with labeling requirements and consumer expectations, making clean-label emulsion innovation, reduced-fat architecture, and prudent hedging complementary rather than competing levers.
- Channel strategy must reflect the fragmentation of purchase pathways. While traditional mass retail remains dominant, convenience formats, specialty bakery positioning, and online fulfillment are reshaping how consumers access laminated pastries, demanding differentiated pack sizes, freshness windows, and service expectations.
- Format hybridization is no longer a marketing curiosity; it is a portfolio consideration. The migration of hybrid laminated dough formats into permanent staples requires disciplined SKU governance, production flexibility, and clear positioning so that innovation supplements rather than fragments the category.
- Competitive positioning depends on differentiation that is economically sustainable. With the top-tier concentration leaving room for regional and niche players, success increasingly hinges on operational reliability, ingredient transparency, labor-efficient formats, and targeted channel relationships rather than scale alone.
Conclusion: Moving from Awareness to Advantage
The laminated pastries market is large, structurally growing, and increasingly complex to navigate without detailed intelligence. Macro momentum provides a favorable backdrop, but durable advantage will belong to organizations that translate that momentum into segment-specific actions, cost-aware product engineering, and distribution strategies that reflect how consumers actually buy. This research is designed to serve as the analytical foundation for those decisions, connecting historical behavior, competitive maneuvering, input economics, and forward projections into a coherent planning instrument.
The full report expands each dimension with the depth required for executive review, cross-functional alignment, and investment-grade scenario modeling. Segment-level quantification, regional exposure mapping, channel-specific growth decomposition, and detailed competitive profiling are presented in full within the source publication. For teams preparing for the 2026 decision cycle, the complete intelligence package offers the clarity needed to move beyond directional awareness and into precise strategic execution.
For detailed analysis of this topic, please visit the official page: Laminated Pastries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects 8.52 Percent Growth for Customized Fixed Dentures Market to Reach 29930 Million by 2032
By PW Consulting, 2026-09-02
Strategic Intelligence for 2026: Navigating the Customized Fixed Dentures Market Growth Trajectory
The global dental prosthetics industry is undergoing a structural transformation driven by digital workflows, advanced material sciences, and an aging demographic that increasingly demands permanent, high-functioning solutions over traditional removable alternatives. As we enter 2026, the customized fixed dentures segment stands at a critical inflection point. Market intelligence released by PW Consulting provides enterprise decision-makers with a rigorous analytical framework to capitalize on this momentum. This research is designed not merely as a historical retrospective but as a forward-looking strategic compass, aligning corporate planning with the compounding economic realities of the 2026-2032 forecast period.
Customized Fixed Dentures Market
Our latest Customized Fixed Dentures Market study synthesizes over half a decade of historical performance with multi-year projections to deliver actionable intelligence. The analysis demonstrates a market that has expanded from approximately 11.24 billion USD in 2020 to an estimated 16.90 billion USD in 2025. This trajectory underscores sustained adoption across clinical and commercial channels. Looking ahead, the market is projected to accelerate toward 29.93 billion USD by 2032, reflecting a compound annual growth rate of 8.52 percent. For executives and investors, this growth rate signals more than steady demand; it highlights a sector where technological integration, supply chain optimization, and patient-centric product design are actively reshaping competitive moats.
Customized Fixed Dentures Market
Market Expansion Dynamics and the Strategic Imperative for 2026
Understanding why this market expands at an 8.52 percent CAGR requires looking beyond surface-level demand metrics. The transition from conventional removable prosthetics to implant-supported fixed restorations is being driven by predictable clinical outcomes, improved patient quality of life, and the economic appeal of long-term value retention. Dental service organizations and private practices are increasingly standardizing full-arch fixed protocols, which fundamentally alters procurement cycles, material specifications, and digital infrastructure requirements.
Customized Fixed Dentures Market
Our report deconstructs this expansion by examining the underlying revenue architecture. Total market size assessments are contextualized within historical baselines from 2020 through 2025, allowing stakeholders to isolate cyclical fluctuations from structural growth. The 2026 baseline projection of 18.24 billion USD establishes a clear starting point for the forecast horizon, while subsequent yearly estimates highlight where capital allocation and capacity planning should be prioritized. By mapping these macroeconomic indicators to operational realities, strategy teams can anticipate procurement timing, capacity scaling, and R&D investment with greater precision. The analysis deliberately avoids granular percentage breakdowns at the segment level, ensuring that high-level strategic direction remains accessible while the detailed numerical matrices remain exclusive to the full report download.
A central theme emerging for 2026 is the convergence of clinical efficacy and digital manufacturing efficiency. Practices that have integrated intraoral scanning, computer-aided design, and computer-aided manufacturing into their fixed denture workflows are seeing measurable reductions in chairside time and remake rates. These operational efficiencies ripple through the supply chain, influencing demand for high-strength materials, specialized abutment components, and proprietary restorative systems. Our market research offers a granular view of how these technology adoption curves intersect with revenue growth, enabling procurement leaders and product managers to align inventory strategies with clinical adoption trends.
Core Report Architecture and Operational Deliverables
This study is engineered for cross-functional deployment. Rather than offering a static statistical summary, the report provides a modular intelligence package that supports strategic planning, competitive benchmarking, and market entry assessment. The content architecture is built around several operational pillars:
- Historical analysis covering 2020 to 2025, establishing verified baseline performance and identifying inflection moments in procurement behavior, material preference shifts, and regional deployment patterns.
- Forecast modeling spanning 2026 through 2032, incorporating scenario-adjusted projections that account for supply chain normalization, regulatory clearance timelines, and evolving reimbursement environments.
- Product-level landscape mapping that disaggregates revenue by restorative categories, enabling manufacturers and distributors to identify where volume concentration and margin opportunities are forming.
- Material-driven analysis examining the comparative positioning of zirconia, ceramic and glass-ceramic systems, metal-ceramic platforms, and composite resin solutions within fixed prosthetics applications.
- Geographic performance frameworks that evaluate mature, high-penetration markets against emerging regional demand centers, highlighting infrastructure readiness and clinical workflow maturity.
- Competitive profiling of leading dental technology and implantology organizations, including product architecture, digital workflow integration, and recent commercialization milestones.
- Regulatory and reimbursement intelligence, including guidance on FDA Class II material clearances, ISO manufacturing standards, and coding frameworks that influence payer interactions in key territories.
Each pillar is designed to convert data into decisions. The report's segmentation logic supports pricing strategy refinement, product line rationalization, and partnership identification. Market share concentration metrics reveal the degree of consolidation within the sector, helping stakeholders assess competitive intensity and potential acquisition or collaboration pathways. Rather than presenting isolated figures, the study embeds every data point within its operational context, ensuring that revenue estimates and structural insights are interpreted through the lens of clinical viability, manufacturing feasibility, and commercial execution.
Competitive Landscape: Innovation, Clearances, and Positioning
The customized fixed dentures space is defined by a diverse operator set spanning implant hardware manufacturers, restorative material suppliers, and digital dentistry solution providers. Competitive advantage increasingly derives from the ability to offer integrated workflows that reduce fabrication complexity while maintaining biomechanical performance. Several established players have anchored their strategies around immediate full-arch protocols and digitally enabled customization.
Glidewell Dental has built a notable footprint by offering customized Locator fixed implant prostheses and screw-retained hybrid dentures in materials such as BruxZir Zirconia for full-arch fixed restorations. Its operating model reflects a broader industry shift toward fully engineered restorative kits that streamline clinical delivery. Dentsply Sirona has emphasized digital workflow integration through concepts such as SmartFix, enabling immediate fixed full-arch restorations alongside customized fixed dental prostheses. This positions the company at the intersection of prosthetic hardware and practice-facing digital infrastructure. Institut Straumann AG continues to advance personalized implant-borne full-arch fixed restorations and customized prosthetics through its Pro Arch fixed solutions, reinforcing a premium positioning around implant-prosthetic compatibility and clinical standardization.
Nobel Biocare remains closely associated with the All-on-4 treatment concept for immediate fixed full-arch prostheses on four implants, a protocol that has shaped clinical adoption pathways and downstream demand for customized restorative products. Ivoclar Vivadent complements these implant-centric approaches by supplying materials and systems for customized fixed dental prostheses, including zirconia and ceramic options that address esthetic and durability requirements. Zimmer Biomet extends the competitive field with solutions for customized implant-supported fixed dentures and full-arch restorations, contributing to the broader ecosystem of implant-prosthetic integration. The competitive picture also includes digital manufacturing specialists such as 3D Systems through its NextDent division and SprintRay, both of which are advancing additive manufacturing pathways for fixed prosthetic applications.
Recent commercialization activity reinforces how rapidly the technology frontier is moving. In July 2025, 3D Systems announced the full commercial release of an FDA-cleared NextDent jetted denture solution for multi-material monolithic customized dentures, emphasizing efficiency gains in fabrication workflows. This followed a September 2024 510(k) clearance for multi-material monolithic jetted denture solutions using NextDent Jet materials for customized fixed prosthetics. Those milestones illustrate how additive manufacturing is transitioning from prototype-level experimentation to clinically validated, regulatory-cleared production. In the same timeframe, Formlabs secured FDA clearance for Premium Teeth Resin intended for temporary crowns and bridges up to seven units in customized fixed applications, expanding the material palette available to digitally driven restorative workflows.
Beyond equipment and material suppliers, clinical service models are also gaining recognition for same-day permanent restorations. In January 2025, Nuvia Dental Implant Center was named the 2025 Dental Implant Restoration Company of the Year for same-day permanent zirconia fixed teeth solutions. Such recognition reflects the market's growing emphasis on patient throughput, immediate functionality, and high-strength materials that can support accelerated treatment timelines.
Regulatory, Material, and Reimbursement Forces Shaping Strategy
Strategic planning in the fixed dentures sector cannot ignore the regulatory and reimbursement environment. FDA 510(k) clearances are required for Class II dental resins and materials used in customized fixed denture prosthetics, including 3D printing materials such as NextDent and OnX Tough 2. This regulatory architecture directly influences time-to-market for new materials, the pace of innovation in digital denture fabrication, and the risk profile of product development pipelines. Companies that can align material science with established clearance pathways gain a meaningful advantage in commercial readiness.
Manufacturing standards are equally consequential. ISO-certified facilities are standard for producers of customized fixed dentures to ensure quality and biocompatibility. This requirement elevates the importance of production discipline, traceability, and quality assurance, particularly for organizations scaling output to meet rising demand. The emphasis on standardized manufacturing reinforces market concentration dynamics and raises the barrier to entry for new competitors lacking robust operational infrastructure.
On the reimbursement side, coding frameworks influence how fixed denture solutions are positioned within dental fee schedules. CDT codes such as D6110 through D6117 apply to implant or abutment-supported fixed dentures for edentulous arches in US dental fee schedules. These coding pathways affect practice economics, patient affordability, and the rate at which full-arch fixed restorations are adopted as standard-of-care options. Our report integrates these dynamics into the broader market environment so that strategic teams can assess revenue realization risk and identify markets where reimbursement clarity supports faster adoption.
Material selection also continues to shape competitive differentiation. Zirconia is a primary high-strength material for customized fixed dental prostheses, offering superior fracture resistance compared to earlier ceramics. This performance profile supports its expanding role in full-arch and multi-unit fixed applications, especially where long-term durability and esthetic predictability are both required. The interplay between material performance, digital fabrication capability, and clinical protocol design is a recurring driver of market segmentation trends. By examining these forces holistically, the report helps stakeholders understand where product development efforts should be concentrated and which manufacturing competencies will be most valuable through 2032.
Strategic Implications for 2026 Decision-Making
The 2026-2032 outlook creates a clear mandate for proactive positioning. Market growth of 8.52 percent annually is not merely a forecast; it is an indicator of where capacity, partnerships, and product roadmaps must be aligned now. Organizations that treat the fixed dentures segment as a conventional commodity category risk underinvesting in digital integration, material innovation, and workflow standardization. Conversely, enterprises that use detailed market intelligence to anticipate procurement cycles, clinical protocol expansion, and regulatory clearance timing can secure stronger margins and more defensible market positions.
For manufacturers and distributors, the strategic priorities include assessing where product portfolios must evolve to support full-arch fixed demand, which material systems should be prioritized for development or acquisition, and how digital manufacturing partnerships can reduce lead times while improving consistency. For dental service organizations and practice groups, the focus shifts to evaluating technology investments that reduce restorative turnaround, standardizing prosthetic workflows that improve case acceptance, and understanding how reimbursement structures shape patient economics. For investors and market entry teams, the opportunity lies in identifying segments where concentration is still forming, where regulatory clearance momentum signals commercial readiness, and where regional demand is outpacing local supply infrastructure.
In every case, high-level market sizing is only the starting point. The strategic advantage comes from understanding how revenue is distributed across product categories, how material and manufacturing choices shape competitive differentiation, and how regional deployment maturity affects go-to-market timing. That level of insight is embedded in the full research release and is intended to support board-level planning, product strategy, and operational forecasting across the forecast horizon.
Moving from Insight to Action
The Customized Fixed Dentures Market research provides a structured foundation for 2026 strategy development. It contextualizes historical performance from 2020 through 2025, projects the market toward 29.93 billion USD by 2032, and maps the competitive and regulatory forces that will influence execution along the way. By translating these dynamics into operational guidance, the report enables stakeholders to move beyond broad growth expectations and into targeted planning for capacity, product architecture, and market prioritization.
Full segmentation data, regional revenue distributions, detailed competitive profiling, and scenario-based projections are provided in the complete report. This depth is essential for teams that need to convert market trajectory into concrete commercial decisions. Readers seeking the complete analytical package, including the numerical breakdowns that support segmentation, material, regional, and concentration assessments, are encouraged to access the full report directly. The macro growth narrative presented here establishes the strategic context; the complete dataset delivers the execution intelligence required to act on it with confidence.
For detailed analysis of this topic, please visit the official page: Customized Fixed Dentures Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Immersive Script Killing Market Hits $5.2 Billion in 2025, Projects 16.7% CAGR to Reach $15.3 Billion by 2032
By PW Consulting, 2026-09-02
The Immersive Script Killing Market: A Strategic Outlook for Enterprise Decision-Makers in 2026
The global entertainment landscape is undergoing a profound transformation, shifting from passive consumption to active, participatory experiences. At the forefront of this evolution is the Immersive Script Killing Market, a sector that has rapidly matured from a niche subculture into a significant revenue generator. For corporate strategists, investors, and operational leaders, understanding the trajectory of this market is no longer optional; it is a critical component of anticipating future consumer behavior and leisure spending patterns.
Immersive Script Killing Market
This article serves as an executive preview of the comprehensive market research recently released by PW Consulting. Our analysis covers the historical performance and future projections of the script killing industry, encompassing both offline immersive venues and online interactive platforms. The data indicates a robust expansion phase, driven by demographic shifts, technological integration, and cross-cultural adaptation of narrative gaming formats. As we look toward the forecast period extending through 2032, the implications for businesses across hospitality, entertainment, and corporate training sectors are substantial.
Immersive Script Killing Market
Market Trajectory and Growth Dynamics
The financial momentum behind the immersive script killing sector is undeniable. Based on our aggregated data, the global market revenue has shown consistent year-over-year growth since 2020. Starting from a baseline of 1.8 billion USD in 2020, the market climbed to 5.2 billion USD by 2025. This historical performance sets a strong foundation for the forecast period. Projections indicate that revenue will continue to accelerate, reaching approximately 6.09 billion USD in 2026 and scaling significantly to 15.3 billion USD by 2032.
Immersive Script Killing Market
The Compound Annual Growth Rate (CAGR) during the forecast period is estimated at 16.7 percent. This rate suggests that the industry is not merely recovering from pandemic-era disruptions but is entering a sustained growth cycle. Such momentum implies that capital allocation toward immersive entertainment infrastructure is likely to yield favorable returns over the medium to long term. However, growth is not uniform across all vectors. The expansion is heavily influenced by the interplay between physical venue availability and digital platform accessibility.
For decision-makers, this trajectory signals a widening addressable market. The jump from 5.2 billion USD in 2025 to over 15 billion USD by 2032 represents a tripling of market size within a seven-year window. Companies that position themselves to capture value in this ecosystem must understand the drivers behind this valuation. It is not simply about ticket sales; it is about the ecosystem of scripts, props, venue operations, and recurring consumer engagement.
Segmentation and Operational Models
The market is primarily divided into two operational models: offline venues and online platforms. While offline experiences currently dominate the revenue share, the online segment is evolving rapidly, especially in regions where physical infrastructure is still developing. The offline model relies heavily on dedicated spaces, professional facilitation, and high-quality props, creating a high-touch entertainment experience. This segment is particularly attractive for real estate and hospitality ventures looking to diversify revenue streams through experiential offerings.
Conversely, the online platform segment offers scalability and lower overhead, allowing for broader reach without the constraints of physical location. This duality creates a complex landscape where hybrid models are beginning to emerge. Our research delves into the specific revenue contributions of each model, analyzing how they complement rather than cannibalize each other in mature markets.
Application-wise, the industry serves multiple verticals. Leisure entertainment remains the primary driver, catering to individuals and groups seeking social experiences. However, corporate team building and educational training are emerging as significant secondary segments. The narrative structure of script killing games makes them adaptable for soft skills training, conflict resolution scenarios, and collaborative problem-solving exercises. This diversification reduces reliance on purely recreational spending and opens B2B revenue channels that are less susceptible to economic downturns.
Geographic Dynamics and Regional Nuances
Geographically, the market exhibits distinct characteristics based on regional maturity and cultural adoption. Asia Pacific currently holds the largest share of market revenue, reflecting the early adoption of script killing formats in countries like China. The density of venues and the depth of consumer engagement in this region set the benchmark for global expansion. North America and Europe follow, showing steady growth as English-language adaptations gain traction.
Latin America and the Middle East and Africa represent emerging frontiers. While current revenue contributions from these regions are smaller, they possess high growth potential as urbanization increases and disposable income rises. Our detailed report breaks down the specific market sizes for each region, providing granular data that investors can use to assess risk and opportunity in specific territories. However, it is crucial to note that regional success is not merely a function of population size but of cultural readiness and regulatory environments.
In mature markets, the focus shifts to differentiation and premiumization. In emerging markets, the focus is on infrastructure development and consumer education. Understanding this distinction is vital for companies planning international expansion or supply chain localization.
Competitive Landscape and Key Players
The competitive environment is fragmented yet increasingly consolidated among top performers. Our analysis identifies a Cr3 of 14.5 percent and a Cr5 of 21.8 percent, indicating that while no single entity dominates the entire market, a handful of key players command significant influence. This concentration suggests room for consolidation and strategic partnerships.
In the United States, companies like The Murder Mystery Company and Rabbit Hole Recreation Services are pivotal. The Murder Mystery Company specializes in fully guided interactive performances for private and corporate events, leveraging professional actors to enhance immersion. Their recent collaboration with high-profile venues, such as the Philippe Chow restaurant event in April 2026, highlights a strategy of integrating script killing with premium dining and social experiences. Similarly, Rabbit Hole Recreation Services operates dedicated studios in Colorado, focusing on English-language immersive experiences with custom props and lighting. Their active participation in major industry events like Gen Con and the MetaGames conference in 2025 underscores their commitment to community building and standards establishment.
In the United Kingdom, Red Herring Games provides a complementary model by specializing in game kits and scripts for home and group play. This product-focused approach lowers the barrier to entry for consumers who prefer self-facilitated experiences, expanding the total addressable market beyond venue-dependent users.
The Asian market, particularly China, features a dense ecosystem of providers. Companies such as 9985 Jubensha, Heytan, Qingqingtalk, and Jiutu Thinking form the backbone of the domestic industry. These entities control extensive narrative portfolios and venue support networks. The competition in this region is intense, driving innovation in narrative quality but also compressing margins. Script costs for venue operators in China have risen due to this competition, emphasizing the need for unique, high-quality content to stand out.
Internationally, Suspense Studio (KMS Games) based in Singapore is playing a crucial role in bridging the gap. By developing original English-language scripts and adapting the immersive role-playing format for international markets, they facilitate the cross-border flow of intellectual property. Their product launches in early 2025 aimed at broader international adoption signal a trend toward standardization of the format across languages.
Strategic partnerships and licensing agreements are becoming common. Companies with strong IP portfolios are looking to license scripts to venues abroad, while venue operators seek exclusive content to drive repeat visitation. The competitive advantage lies not just in volume, but in the quality and uniqueness of the narrative experience.
Industry Dynamics and Regulatory Considerations
The market does not operate in a vacuum. Regulatory frameworks and consumer habits significantly shape the operational landscape. In China, authorities have implemented script review and filing requirements for Jubensha content to address concerns over violent or supernatural themes. This regulatory oversight ensures content safety but also adds a layer of compliance cost and time for developers. Companies operating in or exporting to this region must navigate these requirements carefully to avoid disruptions.
Consumer habits also dictate strategy. Data suggests that over 70 percent of Jubensha consumers in China are under 30 years old. This demographic is highly social, often participating in group experiences multiple times per month. This frequency indicates a habit-forming behavior rather than a one-off novelty. For businesses, this means retention strategies and loyalty programs are as important as customer acquisition. The young demographic is also digitally native, expecting seamless booking, social sharing capabilities, and high production values.
Market entry strategies for Western audiences are evolving. English-language adaptations and dedicated studios are expanding in the US, UK, Singapore, and Europe. This expansion is not merely translating scripts but adapting cultural nuances to resonate with local sensibilities. The success of these adaptations depends on understanding local humor, pacing, and social dynamics. A script that works in Shanghai may not resonate in San Francisco without significant localization effort.
Furthermore, the high competition in key markets drives an emphasis on unique, high-quality narratives. Generic scripts are becoming commoditized. The value proposition is shifting toward exclusive, high-production experiences that cannot be easily replicated. This pushes investment toward creative development and prop technology.
Strategic Implications for 2026 and Beyond
For enterprise decision-makers, the insights from this market research translate into several actionable strategic avenues. First, the growth trajectory suggests that immersive entertainment is a viable diversification strategy for hospitality and real estate portfolios. Integrating script killing venues into mixed-use developments or entertainment districts can drive foot traffic and increase dwell time.
Second, the B2B potential in corporate team building and education should not be overlooked. The structural elements of script killing align well with training objectives. Developing specialized packages for corporate clients can open high-margin revenue streams that are less volatile than leisure entertainment.
Third, the cross-cultural expansion offers opportunities for IP licensing and technology transfer. Companies with proprietary content or facilitation technology can explore partnerships with venues in emerging markets. Conversely, operators in mature markets can license proven scripts to reduce development risk.
Fourth, regulatory compliance and content safety are becoming competitive differentiators. Operators who proactively adhere to guidelines and ensure content appropriateness can market themselves as safe environments for families and corporate groups, expanding their customer base beyond the core young adult demographic.
Conclusion
The Immersive Script Killing Market is at an inflection point. The combination of strong historical growth, a robust forecast CAGR, and evolving consumer habits creates a compelling case for strategic engagement. However, the complexity of the landscape—spanning diverse regions, regulatory environments, and operational models—requires deep due diligence.
This overview provides a high-level synthesis of the market's potential. Yet, to make informed investment or operational decisions, leaders need access to the granular data underlying these trends. Specific segmentation values, detailed regional breakdowns, and precise competitive profiling are essential for building a viable business case.
PW Consulting's full report offers this depth. It contains the specific market size figures for each region, the exact revenue splits by application and type, and comprehensive profiles of the key companies shaping the industry. It also details the recent developments and strategic moves that will define the competitive landscape in the coming years.
We invite stakeholders to access the full Intelligence Suite to leverage these insights for their 2026 strategic planning. Understanding the nuances of this market is the first step toward capturing its value. The growth is real, the demand is expanding, and the window for strategic positioning is open now.
For detailed analysis of this topic, please visit the official page: Immersive Script Killing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Forecasts Solo Dining Market to Hit 95.8 Billion USD by 2032 as Asia Pacific Leads with 19.72 Billion in 2025
By PW Consulting, 2026-09-01
The Solo Dining Revolution: Unlocking Strategic Value in an $87 Billion Market Trajectory Through 2032
The landscape of global food consumption is undergoing a profound structural shift. For decades, the restaurant and packaged food industries were designed around the assumption of sharing, group bundling, and family-sized portions. Today, a different reality defines the marketplace. The solo dining market has evolved from a marginal niche into a dominant force that is reshaping supply chains, store layouts, digital interfaces, and meal formulation strategies. As organizations plan their capital allocation and product roadmaps for the remainder of the decade, understanding the mechanics of this shift is no longer optional. It is a core requirement for sustainable competitive advantage.
Solo Dining Market
This article previews the strategic foundation of PW Consulting’s latest market research, which delivers a comprehensive assessment of the solo dining sector across the forecast period of 2026 through 2032. The study is engineered to convert complex consumer behavior data, macroeconomic pressures, and competitive moves into actionable intelligence for executives, investors, and operations leaders. The following overview outlines the analytical architecture, the market momentum driving the sector, the competitive dynamics redefining industry boundaries, and the practical frameworks contained within the full deliverable.
Solo Dining Market
The Strategic Imperative for 2026 Decision-Makers
The year 2026 represents a critical inflection point. Corporate strategy teams are operating under a volatile mix of cautious consumer spending, anticipated food price inflation, and rapid technology adoption. According to the USDA Economic Research Service, food prices are projected to increase by 2.9 percent in 2026, with food-away-from-home prices climbing 3.6 percent. Simultaneously, food-at-home prices are predicted to rise 2.4 percent, reinforcing trading-down behaviors and forcing brands to justify every unit of value delivered to the consumer. In this environment, solo dining emerges not merely as a lifestyle preference but as a high-precision vehicle for margin optimization, frequency growth, and customer retention.
Solo Dining Market
Industry signals from late 2025 and early 2026 confirm that solo consumption has already integrated itself into the operating logic of major players. The National Restaurant Association’s 2026 State of the Restaurant Industry report identifies solo dining preferences as a primary driver of sales projections, while Toast’s December 2025 trends analysis documented a 22 percent spike in solo diner reservations year-over-year, prompting widespread restaurant adaptations for single seating. These are not isolated anecdotes. They are leading indicators of a structural reconfiguration that will define portfolio performance through 2032.
PW Consulting’s research is designed to answer the questions that matter to 2026 planners: Where should capital flow to capture the next wave of solo occasion growth? Which service models and ordering technologies are generating the most durable unit economics? How should brands position single-serve offerings to defend against inflationary erosion while still capturing the self-care premium that solo consumers increasingly expect? The full report provides the quantitative scaffold and qualitative strategy needed to navigate these decisions, while this preview establishes the context and scope of the analysis.
Market Trajectory and Growth Dynamics
The historical record from 2020 to 2025 demonstrates that solo dining has moved from recovery-phase anomaly to sustained mainstream behavior. The sector progressed from a base of $38.45 billion in 2020 through successive annual expansions, reaching $43.01 billion in 2021, $47.00 billion in 2022, $50.34 billion in 2023, $54.40 billion in 2024, and $58.50 billion in 2025. This progression reflects a compounding growth pattern that persisted through inflationary cycles and shifting dining formats.
The forward trajectory reinforces the strategic significance of the category. The forecast period spanning 2026 through 2032 projects an expansion to a market revenue level calculated in billions of USD, with a compound annual growth rate of 7.32 percent. The year-by-year forecast depicts a consistent upward slope: $65.08 billion in 2026, $68.28 billion in 2027, $71.68 billion in 2028, $75.52 billion in 2029, $78.65 billion in 2030, followed by a pronounced acceleration leading to $91.91 billion in 2031 and $95.80 billion in 2032. This pattern signals that solo dining will not plateau at current levels but will compound at a pace that outpaces broader food service growth and demands dedicated resource allocation.
The survey of market concentration provides additional insight into competitive intensity. The sector remains moderately fragmented at the top tier, with the top three players accounting for 15.4 percent of revenue and the top five firms reaching 22.1 percent. This concentration profile indicates that while category leaders have meaningful scale, there is substantial room for niche specialists, regional operators, and vertically integrated convenience players to capture differentiated share by solving unique pain points in the solo occasion. The absence of an overwhelming monopoly structure also means that strategic positioning, single-serve innovation, and experience design can still move market outcomes for agile entrants.
Deep Dive into the Report’s Operating Framework
The research is built to translate high-level trajectory into granular, decision-ready intelligence. Below is a structured overview of the operational content delivered in the full report, demonstrating how the analysis moves from macro signals to tactical execution.
Demand Behavior and the Self-Care Pricing Premium
The report quantifies how solo occasions differ fundamentally from group dining in check structure, motivation, and price elasticity. Recent industry analysis shows that over half of solo occasions produce checks in the $10 to $30-plus range, as diners increasingly treat solo meals as self-care rather than mere necessity. This behavior reframes the pricing conversation. Solo consumers are not universally price-sensitive; many are willing to pay a premium for convenience, portion certainty, ambiance suited to individual use, and perceived personal value. The research disaggregates these spending profiles by occasion type, meal part, and daypart, enabling operators to identify where premium capture is viable and where value engineering must preserve frequency.
Ordering Technology and the Friction-to-Value Ratio
Technology adoption in solo dining is not about digitization for its own sake. It is about reducing the friction that makes solo consumers second-guess their purchase decision. The report evaluates the performance of distinct ordering technology pathways, including kiosk and tablet ordering, mobile app integration, and manual counter service. The analysis examines throughput, error rates, upsell effectiveness, and the psychological comfort of solo users at each touchpoint. Because solo diners often value speed, autonomy, and minimal social friction, the technology stack that supports their journey has a direct impact on average check size and repeat visit cadence. The full study maps these technology segments against service model performance and regional deployment maturity, helping leaders prioritize integrations that will yield the highest operational return.
Service Model Architecture and Single-Serve Economics
The report dissects the performance of the major service models that now anchor solo consumption. Quick service restaurants continue to play a central role by offering single-portion meals, value menu items, and app-based ordering optimized for on-the-go consumption. Fast casual dining contributes by blending quality perception with the flexibility of customizable single orders. Full-service restaurants are adapting through reservation system changes, single-seating layouts, and menu engineering that reduces the psychological awkwardness of dining alone. Grab-and-go convenience expands the occasion set by delivering immediate, portable single-serve options.
The analysis goes beyond descriptive segmentation. It evaluates portion-controlled economics, ingredient yield efficiency, packaging cost per unit, waste reduction potential, and the trade-offs between freshness perception and shelf-stability. For packaged food suppliers and meal-kit providers, the research covers single-serve formulation, perfectly-portioned ingredient design, and minimal-waste packaging strategies that align with cautious consumer spending and trading-down behaviors. This end-to-end view allows organizations to assess where single-serve execution strengthens margin and where it introduces cost structure risk.
Competitive Landscape and Strategic Positioning
The solo dining market has attracted a diverse set of players, each engineering a distinct response to the single-portion occasion. The competitive field spans quick-service giants, convenience store networks, digital meal delivery platforms, and packaged food manufacturers. The report profiles these companies along the dimensions that matter most to strategic planning: occasion capture, single-serve product architecture, technology integration, and geographic reach.
- McDonald’s Corporation anchors the quick-service segment with quick-service single-portion meals, value menu items, and app-based ordering designed for solo and on-the-go consumption. Its scale and digital ordering maturity make it a benchmark for how single-serve value architecture can be operationalized at global volume.
- Yum! Brands, encompassing KFC and Pizza Hut, has formalized the strategic importance of the solo occasion through its first-ever food trends report, highlighting 52 percent growth in solo orders since 2021 and the fact that solo occasions now comprise 47 percent of QSR occasions, with solo diners spending more on self-care meals. This development signals a deliberate pivot toward customizable single orders and personal pan options positioned as self-care.
- Starbucks Corporation dominates the solo beverage and light meal category through single-serve drinks, grab-and-go items, and cafe seating designed for individual use. Its model demonstrates how environment design and product sizing can reinforce repeat solo consumption without relying on group sharing logic.
- Seven & i Holdings, the parent of 7-Eleven, and FamilyMart UNY Holdings illustrate how convenience retail has become a primary solo dining channel. These companies specialize in extensive single-serve ready-to-eat meals, snacks, and microwavable options, as well as single-portion bento boxes, onigiri, and convenience foods targeted at solo consumers. Their shelf layout, refrigerated placement, and packaging design are optimized for instant decision-making by solo shoppers.
- Nestlé S.A. and Kraft Heinz Company represent the packaged food layer, producing single-serve packaged foods, ready meals, portion-controlled products, single-serve snacks, sauces, and meal components for home and on-the-go solo dining. Their formulations and packaging sizes directly shape the at-home solo occasion and influence the broader meal construction behavior of one-person households.
- Factor, HelloFresh, and Blue Apron address the prepared meal and meal-kit domains with single-serve positioning. Factor delivers prepared, single-serve ready-to-heat meals specifically positioned for solo diners with portion-controlled options. HelloFresh offers meal kits for one with perfectly-portioned ingredients designed for solo cooking and minimal waste. Blue Apron provides flexible single-serve and oven-ready meals, including a dedicated line for solo households. Together, these providers illustrate the spectrum from fully prepared to partially assembled single-serve solutions, each targeting different convenience thresholds and cooking engagement levels.
The competitive analysis also incorporates the most recent market-moving developments that contextualize 2026 planning. Yum! Brands’ December 2025 trends report underscored the 52 percent growth in solo orders since 2021 and the 47 percent share of QSR occasions, setting a new benchmark for how aggressively quick-service operators must adapt their product and packaging architecture. Toast’s December 2025 trends report reinforced the behavioral shift at the restaurant level, documenting a 22 percent spike in solo diner reservations and prompting adaptation strategies for single seating. More recently, the National Restaurant Association’s February 2026 industry report integrated solo dining preferences into its sales projections, confirming that solo consumption is now embedded in the industry’s forward-looking demand assumptions.
Market Structure and the Opportunity for Differentiated Positioning
The moderately fragmented concentration profile of the market, with the top three firms at 15.4 percent and the top five at 22.1 percent, means that the competitive environment is dynamic enough to reward targeted innovation. Solo dining is not a category where a single operating model dominates. The presence of strong quick-service, coffee and cafe, convenience retail, packaged food, and meal-kit players indicates that the occasion is served through multiple channels depending on time pressure, cooking intent, price sensitivity, and desired level of personalization. For new entrants and established players alike, the strategic question is not whether to participate but how to design a single-serve proposition that occupies a defensible position relative to these alternatives.
Macroeconomic and Regulatory Dynamics Shaping 2026 Planning
No forward strategy is complete without an honest assessment of the cost and pricing environment. The USDA Economic Research Service forecasts that all food prices will increase 2.9 percent in 2026, with food-away-from-home prices rising 3.6 percent. Food-at-home prices are predicted to increase 2.4 percent in 2026 amid cautious consumer spending and trading-down behaviors. These forecasts have direct implications for solo dining. Operators must balance the self-care premium that solo consumers are willing to pay against the reality of rising input and labor costs. Packaging, portion control, and menu architecture that deliver perceived value without eroding margin will be critical.
At the same time, consumer habits continue to reshape demand patterns. Solo dining reservations in the US have risen, with searches for solo dining increasing significantly and 21 percent of diners typically dining out alone. This behavioral baseline implies that the addressable occasion pool is already substantial and growing. Brands that reduce the friction of solo dining, from reservation systems that accommodate single seats to menu presentations that avoid the stigma of smaller orders, will benefit from improved conversion and higher basket retention. The report integrates these behavioral and cost dynamics into a cohesive set of strategic scenarios, allowing leaders to test how pricing adjustments, portion resizing, and technology investments perform under differing inflationary and consumer confidence assumptions.
What Executives Gain From the Complete Research
The full deliverable extends well beyond the macro trajectory and competitive profile summarized here. It provides the detailed segmentation architecture that maps regional and service model performance, the ordering technology breakdowns that reveal where investment yields the strongest frequency and check-size effects, and the competitive benchmarking that shows where single-serve execution is creating durable advantage versus where it remains a table-stakes feature. The analysis is structured so that strategy, operations, and finance teams can each extract the inputs required for their planning cycles.
Readers who engage with the complete report will obtain a working view of where solo dining growth is most concentrated, which service models are generating the most efficient unit economics, how technology deployment influences solo consumer satisfaction and repeat behavior, and how to position single-serve offerings in a cost environment that is pressuring both away-from-home and at-home consumption. The report also details the most recent company-level developments and their strategic implications, ensuring that planning is anchored in current market reality rather than lagging indicators.
The solo dining market is no longer a peripheral trend. It is a compounding growth engine reshaped by self-care spending, technology-enabled convenience, and a consumer base that increasingly expects portion certainty and frictionless service. Organizations that treat solo dining as a strategic category, rather than a logistical afterthought, will be better positioned to capture the forward growth reflected in the market trajectory and to defend against the cost pressures that will intensify through 2026 and beyond. This research is designed to equip decision-makers with the clarity and confidence to act on that opportunity.
For detailed analysis of this topic, please visit the official page: Solo Dining Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Ice Cubers Market to Reach 3.85 Billion USD in 2025 with 6.5 CAGR Through 2032
By PW Consulting, 2026-09-01
The Frozen Frontier: Strategic Insights for the Ice Cubers Market Through 2032
In the rapidly evolving landscape of commercial refrigeration and foodservice infrastructure, few assets are as universally critical yet operationally nuanced as the commercial ice cuber. As we navigate the post-pandemic recovery and subsequent stabilization of global hospitality and industrial sectors, the demand for reliable, high-volume ice production has transitioned from a back-of-house utility to a front-line strategic consideration. At PW Consulting, we recognize that understanding the trajectory of the Ice Cubers Market is no longer just a matter of procurement; it is a fundamental component of capital expenditure planning, supply chain resilience, and competitive positioning for 2026 and beyond.
Ice Cubers Market
This article serves as a strategic primer to our newly released comprehensive market intelligence report. While the following analysis highlights the macroeconomic currents and structural shifts defining the industry, the complete dataset, granular segmentation, and proprietary competitive matrices are reserved for our clients. The insights below are designed to demonstrate the depth of our research rigor, empowering decision-makers to appreciate the complexity of the market before diving into the full financial models and strategic recommendations available in our core publication.
Ice Cubers Market
Macro Trajectory: Growth Dynamics and Market Valuation
The global market for ice cuber equipment has demonstrated remarkable resilience over the last half-decade. Our longitudinal analysis, covering the historical period from 2020 through 2025, captures a sector that not only recovered from early supply chain disruptions but accelerated its expansion as foodservice capacities normalized and industrial cold chain requirements tightened. The valuation metrics indicate a steady upward climb, with the market footprint expanding significantly as commercialization rates increased across developed and emerging economies.
Ice Cubers Market
Looking toward the forecast horizon, the trajectory remains robustly positive. Our projections for the period extending to 2032 suggest a compound annual growth rate (CAGR) of 6.5 percent. This growth is not merely a function of population expansion but is driven by structural upgrades in hospitality infrastructure, the proliferation of quick-service restaurant concepts requiring specialized ice formats, and the continuous modernization of healthcare facilities where ice dispensing systems are critical for patient care and hygiene. By the end of the forecast period, the aggregate revenue generated by cube ice machinery is expected to reach significant heights, underscoring the asset class as a stable investment vehicle within the broader cold chain ecosystem.
For strategic planners, the implication of a sustained 6.5 percent CAGR is clear: the window for early adoption of next-generation efficiency technologies is narrowing. Companies that delay capital allocation into this segment risk encountering higher operational costs later, particularly as energy mandates tighten and refrigerant compliance becomes more rigorous. The market size evolution reflects a shift from commodity-grade production to specialized, high-efficiency units that offer lower total cost of ownership over their lifecycle.
Competitive Landscape and Strategic Concentration
The competitive architecture of the ice cuber market is characterized by a mix of established multinational conglomerates and specialized niche manufacturers. Our analysis of market concentration reveals a moderately fragmented environment, where the top three players hold a CR3 of 31.5 percent, and the top five extend their collective share to 40.2 percent. This concentration level suggests that while dominant players set the standard for reliability and technological integration, there remains ample room for specialized entrants to capture value through innovation in specific ice types or regional service networks.
Key incumbents such as Hoshizaki Corporation continue to leverage their global manufacturing footprint, with production capabilities spanning Japan and the United States, to maintain supply chain redundancy. Similarly, Manitowoc Ice, as part of a larger diversified portfolio, utilizes its scale to offer comprehensive cube ice systems tailored for extensive foodservice operations. Scotsman Ice Systems and Ice-O-Matic have cemented their positions by focusing on the quality and variety of cube outputs, ranging from full cubes to gourmet clear formats, often serving high-end hospitality clients where ice clarity and melt resistance are premium selling points.
Regional dynamics also play a pivotal role in competitive positioning. European manufacturers like Brema Ice Makers bring decades of specialization to the table, offering distinct product lines that cater to specific thermal requirements. Meanwhile, specialized industrial players such as North Star Ice Equipment address the high-capacity demands of seafood processing and heavy-duty industrial applications, a segment that requires distinct engineering tolerances compared to standard retail units. Follett Ice and Cornelius, Inc. further diversify the landscape by integrating ice production with dispensing systems, a crucial feature for healthcare environments and self-service retail contexts where contactless access is increasingly valued.
The presence of KOLD-DRAFT, known for its unique horizontal evaporator technology producing pure square cubes, highlights how proprietary technology can sustain a strong brand identity even within a competitive field. These companies collectively define the operational standards of the industry, driving the adoption of NSF/ANSI compliant materials and designs that ensure sanitation and durability.
Material Dynamics and Regulatory Pressures
Strategic decision-making in 2026 must account for the evolving cost structures of raw materials and the tightening grip of regulatory compliance. The construction of commercial ice cuber units relies heavily on stainless steel, chosen for its corrosion resistance and adherence to stringent hygiene protocols. Recent sector analysis indicates that prices for relevant stainless steel grades experienced declines of up to 16 percent in early 2026 across key Asian and European markets. This fluctuation offers a temporary window for manufacturers and large-scale buyers to optimize procurement costs, potentially easing the pressure on unit pricing or margin expansion.
However, the volatility in metal markets remains a risk factor. Benchmark indicators for steel rebar and associated alloys continue to show modest monthly increases, with fluctuations tied to the pricing of nickel and chromium essential for stainless variants. Stakeholders must monitor these commodity trends closely, as they directly impact the Bill of Materials for equipment manufacturing.
Beyond materials, regulatory frameworks are reshaping product design. The mandate for energy efficiency and the transition toward R290 refrigerant compliance are no longer optional considerations; they are design constraints that dictate the viability of new models in hospitality and foodservice sectors. Equipment that fails to meet these efficiency standards faces not only regulatory barriers but also growing resistance from cost-conscious operators seeking to reduce utility overheads. Furthermore, NSF/ANSI standards continue to drive the specification of high-grade stainless steel and efficient internal designs, ensuring that compliance is synonymous with quality and long-term reliability.
Operational Segments and Application Drivers
The utility of ice cuber systems spans a diverse array of applications, each with distinct volume requirements and operational priorities. The largest share of demand originates from the foodservice sector, where ice is integral to beverage service, display preservation, and food safety. In this segment, the focus is on high-throughput capacity and ease of maintenance to minimize downtime during peak service hours. Healthcare applications represent another critical pillar, where ice dispensing systems are utilized for therapeutic purposes, patient hydration, and general facility sanitation, requiring units that prioritize hygiene and reliability over sheer speed.
Retail environments utilize cube ice for display cases and consumer self-service, demanding aesthetic considerations alongside performance. Industrial applications, while representing a smaller volume segment in terms of unit count, require robust equipment capable of handling extreme duty cycles, often bridging the gap between standard commercial cubers and specialized flake or scale ice production depending on the specific cooling needs of the process.
While specific regional breakdowns and precise application splits are detailed within our proprietary full report, it is evident that the interplay between these segments drives the overall market rhythm. For instance, a surge in hospitality reopening in a specific geography may disproportionately benefit foodservice-focused manufacturers, while industrial investments in cold chain logistics may spur demand for heavy-duty equipment providers. Understanding the weighting and growth potential of each application vertical is essential for targeting capital deployment and sales strategies effectively.
Furthermore, the product type segmentation reveals a preference for cube ice machines as the dominant category, driven by their versatility in drinks and displays. However, complementary technologies such as flake and nugget ice machines maintain relevance in specific niches where texture or rapid cooling is prioritized. The coexistence of these product types suggests that a one-size-fits-all procurement strategy is rarely effective; instead, a portfolio approach that matches machine capabilities to specific application needs yields the best operational results.
Recent Industry Activity and Market Signals
The market's vibrancy is further evidenced by recent activity at major industry trade exhibitions and product launches. In early 2026, significant participation at events such as the Canton Fair and the NRA Show highlighted the continued interest in commercial cube ice systems. Companies showcased updated solutions emphasizing connectivity, energy savings, and modular designs. These exhibitions serve as barometers for industry sentiment, revealing a collective push towards modernization and the integration of smart monitoring capabilities that allow operators to track production levels and maintenance needs remotely.
Such events also underscore the global nature of the supply chain. Exhibitions in Asia and North America demonstrate that innovation is not geographically siloed. Manufacturers are increasingly presenting solutions that cater to international compliance standards, ensuring that a unit deployed in one region can meet the regulatory and operational expectations of another. This globalization of product standards simplifies the supply chain for multinational operators but also intensifies competition, as regional players must now compete with global benchmarks for quality and efficiency.
Strategic Recommendations for 2026 Decision-Makers
As organizations prepare their budgets and strategic plans for the remainder of 2026 and the coming years, several actions warrant immediate attention. First, procurement strategies should account for the cyclical nature of raw material costs. While recent declines in stainless steel prices offer opportunities, locking in contracts with manufacturers who demonstrate supply chain stability is prudent. Second, capital allocation should favor units that are pre-aligned with R290 refrigerant standards and high energy efficiency ratings. The total cost of ownership calculation must extend beyond the purchase price to include ten-year energy consumption and maintenance profiles.
Third, competitive positioning requires a clear understanding of the market concentration. While the market is not an oligopoly, the top-tier players set the expectations for service levels and warranty support. Engaging with vendors who can demonstrate robust service networks is critical, particularly in regions where on-site support for downtime reduction is a key performance indicator. Finally, product selection should be tightly coupled with application requirements. Investing in high-capacity industrial units for a light-duty retail application, or vice versa, results in capital inefficiency. Our detailed segmentation analysis helps clarify these matching exercises, ensuring that capacity investments are right-sized for demand forecasts.
Conclusion: Accessing the Full Intelligence
The Ice Cubers Market presents a compelling opportunity for stakeholders who can navigate its technical, regulatory, and competitive complexities. The projected growth to 2032, underpinned by a steady CAGR and expanding application bases, signals a healthy demand environment. However, extracting maximum value from this market requires more than general industry awareness; it demands precise data on regional sizing, competitive share shifts, and granular application economics.
This overview has provided a high-level synthesis of the forces shaping the industry, from macro growth trends to material cost fluctuations and the strategic positioning of key manufacturers. Yet, the depth required to formulate precise investment theses and operational roadmaps resides in the comprehensive data tables, scenario analyses, and detailed company profiles found in our full market research publication. For executives seeking to secure a competitive advantage, the complete report offers the granularity necessary to move from insight to action. We invite you to access the full Ice Cubers Market research portal to unlock the complete dataset and proprietary strategic intelligence that will define your success in this frozen frontier.
For detailed analysis of this topic, please visit the official page: Ice Cubers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


