



Category: Healthy Lifestyle
PW Consulting: Espresso Market Hits $16.17 Billion in 2025, 5.7% CAGR to 2032
By PW Consulting, 2026-09-16
Executive Preview: Navigating the Espresso Coffee Market in 2026 and Beyond
The global espresso coffee market stands at a pivotal inflection point. As consumer preferences shift towards premiumization, convenience, and sustainability, stakeholders across the value chain require a precise navigation tool to separate transient trends from structural growth drivers. PW Consulting's latest comprehensive market research on the Espresso Coffee Market offers exactly that: a data-backed strategic compass designed for enterprise decision-makers operating in a complex, high-growth environment.
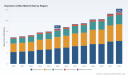
This market study, anchored in a rigorous historical analysis spanning 2020 to 2025 and projecting forward through the 2026 to 2032 forecast period, provides an unvarnished look at the revenue dynamics shaping one of the world's most beloved beverage categories. With total market revenue valuation expanding from approximately 12.26 billion USD in the base year of 2020 to a projected 23.84 billion USD by 2032, the trajectory is unmistakable. The intervening years tell a story of resilient demand, with revenue climbing to 14.5 billion USD in 2023 and further to 14.93 billion USD in 2024, before reaching an estimated 16.17 billion USD in 2025. Our forecast models project this momentum to sustain, with the market advancing to 16.95 billion USD in 2026 and scaling toward 18.36 billion USD in 2027. The compound annual growth rate over the forecast horizon is calculated at 5.7 percent, signaling steady, compounding expansion rather than volatile spikes.
Espresso Coffee Market
For corporate strategists, regional directors, and investment committees, this report serves as a critical intelligence asset. It moves beyond superficial headline figures to interrogate the underlying mechanics of growth, competitive positioning, and structural headwinds. What follows is a curated overview of the analytical depth, practical utility, and market context contained within this publication.
A Multi-Dimensional Analytical Framework
The research is structured to deliver actionable clarity across the primary axes that govern strategic planning. Rather than presenting a flat revenue projection, the study disaggregates the market along dimensions that directly inform operational priorities, product portfolio decisions, and market entry strategies. The segmentation architecture examines value distribution across geographic territories, product typologies, and consumption application channels. Each segment is contextualized with demand drivers, saturation indicators, and growth velocity differentials, enabling readers to identify where capital deployment will yield the highest marginal returns.
Our analysis of the product landscape distinguishes between the hardware and consumables dynamics that define the category. The equipment dimension encompasses espresso machines, where precision engineering, durability, and feature sets drive procurement cycles across both residential and commercial environments. The beverage dimension captures the recurring revenue streams associated with espresso-based products, where brand loyalty, formulation quality, and packaging innovation dictate share shifts. By mapping the interplay between these two pillars, the report highlights cross-segment opportunities, such as bundled equipment-and-consumable offerings, subscription models, and white-label partnerships.
Equally critical is the application-channel perspective. The market bifurcates into at-home consumption and commercial outlets, each governed by distinct purchasing behaviors, price elasticity thresholds, and distribution architectures. Home consumption continues to benefit from lifestyle shifts that prioritize café-quality experiences in domestic settings, while commercial venues navigate a post-pandemic operational landscape characterized by labor optimization, throughput demands, and experiential differentiation. The study dissects these channels with granularity, identifying sub-segments where margin structures diverge and where infrastructure investments must be calibrated to local competitive intensity.
Geographically, the report maps revenue footprints across all major regions, providing a comparative view of market maturity, growth acceleration, and structural entry barriers. Decision-makers gain insight into which territories are exhibiting relative under-penetration versus those approaching saturation, allowing for differentiated go-to-market playbooks. Whether evaluating sourcing strategies, distribution network expansion, or localized product adaptation, the geographic intelligence herein supports evidence-based resource allocation.
Espresso Machines Market
Competitive Dynamics and Strategic Positioning
Concentration is a defining feature of this category. The top three participants command a combined market share of 57.3 percent, while the top five hold 68.4 percent of total industry revenue. This level of concentration indicates that scale advantages, brand equity, and distribution infrastructure confer significant defensive moats, yet it also signals that targeted disruptors can capture meaningful share by exploiting niche demand or delivery innovation. Our report profiles the leading incumbents in detail, examining their headquarters bases, core competencies, and strategic postures.
Nespresso, headquartered in Switzerland, operates as a specialized provider of espresso coffee pods and machines, with a pronounced focus on premium espresso extraction and a subscription-integrated revenue model. Starbucks Corporation, based in the United States, remains a major provider of ready-to-drink and at-home espresso-based beverages and equipment, leveraging its global retail footprint to anchor brand presence across multiple consumption occasions. Luigi Lavazza S.p.A., an Italian producer, emphasizes high-quality Arabica in its espresso bean, capsule, and machine portfolio, catering to consumers who prize origin character and consistency. Illycaffè, also based in Italy, specializes in single-origin espresso beans and professional-grade equipment optimized for espresso brewing, positioning itself at the intersection of authenticity and performance.
Peet's Coffee, headquartered in the United States, supplies espresso roast beans and ready-to-drink espresso drinks, maintaining a strong foothold in segments that value intensity and roast-forward flavor profiles. Rocket Espresso, an Italian manufacturer, produces commercial and professional espresso machines and grinders certified for precise espresso extraction, serving operators who demand repeatability and technical fidelity. OutIn, an Italian producer, has gained traction with portable electric espresso machines designed for on-the-go espresso brewing, reflecting the growing consumer appetite for mobility and convenience. Flair Espresso, based in the United States, manufactures manual lever espresso machines and accessories for home and professional espresso preparation, appealing to enthusiasts and baristas who prioritize tactile control. Eversys, headquartered in Italy, develops compact professional espresso machines with automated menus for versatile espresso-based beverages, addressing the operational efficiency needs of high-volume environments.
Beyond firm-level profiles, the research systematically tracks recent competitive moves that recalibrate the market. In May 2026, OutIn executed a global debut of the Cup of OutIn and participated in the World of Coffee San Diego 2026 with dual booths, reinforcing its commitment to portability and consumer-facing visibility. Also in May 2026, Rocket Milano s.r.l. launched the Gravo Grinder, featuring grind-by-weight technology and a single-shot mode, an advancement that signals intensifying engineering competition at the professional equipment tier. In April 2026, Flair Espresso introduced the Flair 49 Pro manual espresso machine with a 49mm portafilter and stainless brew path, illustrating continued innovation in the manual segment. Earlier in March 2026, Nguyen Coffee Supply launched its first product, Ground Espresso, sourced and roasted in Vietnam, demonstrating how origin diversification is opening new flavor and sourcing narratives in the espresso market.
These developments are not isolated product announcements; they are indicators of where competitive intensity is concentrating and which attribute sets are gaining currency among buyers. The report's competitive analysis integrates these events into a wider assessment of share dynamics, partnership opportunities, and threat vectors, enabling leadership teams to anticipate rather than react.
Macroeconomic and Operational Backdrop
No strategic assessment is complete without anchoring market projections in the material conditions that influence cost structures, supply reliability, and regulatory compliance. Our research synthesizes the latest external intelligence to frame the operating environment with precision and foresight.
On the raw material front, coffee commodity pricing and crop expectations directly affect input costs for roasters, capsule manufacturers, and beverage producers. The International Coffee Organization reported that the ICO Composite Indicator Price averaged 266.24 US cents per pound in April 2026, a 2.7 percent decrease from March 2026. This moderation in pricing provides temporary relief on input costs, but also requires producers to manage futures hedging and procurement timing carefully. Concurrently, the USDA Foreign Agricultural Service projected Brazil's 2026/27 coffee crop at a record 71.9 million bags, up 14 percent from 2025/26. A larger Brazilian harvest has implications for global supply adequacy, price volatility, and origin diversification strategies, particularly as buyers balance cost efficiency against quality and traceability expectations.
Regulatory developments are equally consequential. The European Union Deforestation Regulation mandates full supply-chain traceability for coffee imports by late 2025, compelling market participants to invest in provenance documentation, supplier audits, and digital traceability platforms. Organizations that proactively build compliance capabilities will mitigate disruption risk, while those that defer face potential shipment delays, reputational exposure, and market access constraints. In parallel, the U.S. Food and Drug Administration does not require a Nutrition Facts label for plain roasted coffee beans, a regulatory distinction that affects labeling strategy, consumer communication, and product differentiation in jurisdictions where transparency expectations are rising.
Operational standards further shape the competitive landscape. The Specialty Coffee Association Certified Espresso Machines program for 2025-2027 lists Rancilio, Faema, and LaCimbali as certified manufacturers, a designation that carries weight in commercial procurement decisions. Certification influences vendor selection in hospitality, office, and retail environments where reliability, service support, and performance consistency are non-negotiable. Our analysis incorporates these standards as qualitative filters that affect commercial-channel demand and equipment segment growth.
Practical Utility for Executive Decision-Making
This report is designed to be a working document, not a static snapshot. across its chapters, readers will find a suite of practical analytical tools that translate market intelligence into executable strategy. The segmentation breakdowns enable scenario planning by allowing teams to model revenue sensitivity under varying assumptions about channel mix, price points, and geographic penetration. The competitive profiling supports benchmarking exercises, revealing adjacencies for partnership, acquisition targets for capability enhancement, and whitespace opportunities for new product development.
The industry dynamics section provides a consolidated view of cost-side and compliance-side factors, helping procurement, supply chain, and legal teams align sourcing calendars, supplier contracts, and traceability investments with regulatory timelines and commodity cycles. This integration is critical for organizations that must balance margin protection with brand integrity and market access requirements.
Furthermore, the report's forward-looking forecast horizon, extending through 2032, supports investment committee deliberations by quantifying the durability of demand trends. Whether the objective is to size a new market entry, justify capital expenditure on equipment manufacturing capacity, or evaluate the long-term attractiveness of a regional distribution network, the modeling framework provides the evidentiary basis for confident decision-making. By distinguishing between cyclical fluctuations and secular shifts, the analysis reduces the risk of misallocating resources to short-lived opportunities.
Readers will also find strategic implications surfaced explicitly throughout the report. Where quality premiums are expanding, where convenience is trumping origin storytelling, where portable formats are cannibalizing traditional consumption occasions, and where professional-grade equipment certification is becoming a procurement prerequisite, the research offers interpretation and recommended posture. The goal is not merely to inform, but to equip leadership teams with a clear line of sight from market signal to strategic response.
Why This Research Matters in 2026
The current moment demands a disciplined, evidence-led approach to strategy. Consumer expectations are rising across taste, sustainability, and convenience simultaneously. Equipment buyers are demanding greater precision and automation. Regulators are tightening traceability requirements. Commodity markets are experiencing shifting harvest dynamics and price moderation that complicate procurement planning. In this environment, assumptions are expensive, and generic market narratives are insufficient.
PW Consulting's Espresso Coffee Market research delivers the granularity, contextualization, and forward lens required to navigate these complexities. Total revenue projections, growth rates, segmentation differentials, and competitive intelligence are woven together to create a coherent narrative that speaks directly to strategic priorities. The study is built for executives who need to justify investment decisions, align cross-functional teams, and respond to competitors with agility and foresight.
To access the complete dataset, detailed segmentation analysis, full competitor profiles, and the comprehensive forecast tables that underpin this preview, we invite you to visit the source webpage where the full report is available. The complete intelligence package extends far beyond the highlights presented here, offering the depth and precision your organization requires to act with confidence.
In an industry defined by both tradition and rapid innovation, informed strategy is the decisive advantage. This research provides the foundation for that strategy, and we look forward to equipping your team with the insights necessary to shape outcomes in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Espresso Coffee Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mosquito Control Service Market to Hit $99.66M by 2032, CAGR 6.98%
By PW Consulting, 2026-09-16
Strategic Intelligence for a Growing Defensive Market: Inside the PW Consulting Mosquito Control Service Market Report 2026
As urban density increases, climate patterns shift, and public health expectations rise, mosquito control has evolved from a seasonal nuisance service into a structured, regulated, and commercially significant industry. For executives planning capital allocation, service expansion, M&A screening, or operational optimization in 2026, the market demands more than headline figures. It demands a clear map of how value is created, where concentration risk sits, and which operational levers will determine margin performance over the next forecast cycle.
PW Consulting’s newly released Mosquito Control Service Market research is designed for that purpose. This article previews the strategic architecture of the study, explains why its framework should inform 2026 decision-making, and outlines the analytical dimensions that matter most to operators, investors, and public-sector procurement leaders.
Why 2026 Is a Decision inflection Point
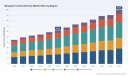
The market has already crossed a meaningful scale threshold. Building from a 2025 base year perspective and extending through a 2026 to 2032 forecast horizon, the industry shows a steady growth trajectory that rewards disciplined strategy rather than reactive expansion. Historical movement from 2020 through 2025 reflects consistent commercialization, while the forward path indicates continued expansion at a compound annual growth rate of 6.98 percent.
For leadership teams, that trajectory matters because growth alone does not guarantee profitability. The operational reality of mosquito control is labor-intensive, chemically and mechanically complex, and increasingly shaped by regulatory scrutiny. Technicians must be trained for larvicide and adulticide applications, service schedules must align with seasonal biology and weather patterns, and pricing models must absorb volatility in raw material costs for equipment and treatment materials. In that environment, the strategic question is not simply whether demand will rise, but which service models, customer segments, and regional plays will convert growth into durable economics.
Mosquito Control Service Market
This is where the report’s structure becomes valuable. Instead of presenting growth as a single line item, it frames the market as a set of intersecting choices: service type, application context, regional operating conditions, and competitive positioning. Those choices determine both exposure and opportunity.
What the Research Delivers
The study is built to support operational and commercial decision-making rather than simple market awareness. It combines top-down market sizing with bottom-up segmentation logic, allowing readers to assess where demand is forming and how service providers are structuring their offerings in response.
Within the analysis, the market is examined across three primary dimensions:
- Service type, including chemical control service, mechanical control service, and biological control service, each with distinct cost structures, repeat-purchase dynamics, and customer expectations.
- Application context, spanning government programs, residential demand, commercial properties, and industrial environments, where procurement behavior, service frequency, and pricing sensitivity differ materially.
- Regional operating environments, where climate, public health infrastructure, municipal budgeting, and regulatory posture shape both demand and competitive intensity.
These segmentation lenses are paired with concentration analysis that helps stakeholders understand how fragmented or consolidated the competitive field is, and what that implies for pricing power, customer acquisition, and barrier-to-entry assumptions.
Equally important, the report is designed to connect quantitative structure with qualitative industry dynamics. It addresses the operational inputs that often determine whether growth is profitable: specialized labor requirements, the impact of raw material price fluctuation on production and service costs, and the way regulatory processes influence both provider behavior and end-customer adoption. By integrating those factors into the market narrative, the research supports scenario planning rather than static budgeting.
Competitive Landscape: Scale, Specialization, and Strategic Positioning
The mosquito control field contains a mix of global pest management organizations, specialized service operators, equipment-focused providers, and public-health-oriented contractors. That mix matters because competition in this market is not purely price-based. It is also defined by service coverage, regulatory readiness, treatment methodology, and the ability to serve different customer classes at scale.
Several established names anchor the broader pest management and mosquito control landscape. Rentokil Initial plc operates across multiple regions with comprehensive mosquito control services, including larvicide and adulticide applications for residential, commercial, and public health clients. Rollins, Inc. offers mosquito control service packages built around EPA-registered products for residential and commercial properties. Ecolab Inc. delivers mosquito control solutions within a broader pest management portfolio, including specialized treatments. Terminix International, Inc. integrates mosquito control into its wider pest management offerings for homeowners and businesses. Clarke Mosquito Control Products specializes in mosquito control equipment and services, with larvicide and adulticide application systems.
Alongside these larger platforms, a set of more targeted operators illustrates the diversity of business models in the market. Mosquito Squad focuses on residential mosquito control using integrated pest management approaches. Vector Disease Control International provides services specifically for municipalities, mosquito abatement districts, counties, and state entities. Mosquito Joe offers mosquito control services and misting systems for residential properties. Mosquito Authority delivers service for residential and commercial clients using EPA-registered products. Arrow Exterminators includes mosquito control within its broader pest management offerings.
Mosquito Control Market
For strategists, the competitive takeaway is not simply that these companies exist, but that the market supports multiple viable entry and expansion models. Some players compete through scale and multi-region coverage. Others compete through specialized public-sector relationships, residential-focused branding, or equipment-and-service combinations. Understanding how those models perform under different demand and cost conditions is central to evaluating market entry, partnership opportunities, or acquisition targets.
The report uses this competitive context to examine concentration and positioning in a way that helps stakeholders interpret where customer switching behavior is likely to be strongest, where service differentiation is most defensible, and where regional or segment-specific expertise can create meaningful advantage.
Recent Market Activity and the Shape of Industry Dynamics
Market structure is only part of the story. In 2026, the industry is also being shaped by product innovation, municipal program decisions, and regulatory conversations that directly affect operating assumptions.
On the product and technology side, recent activity shows continued refinement in treatment options and application systems. For example, MGK announced the launch of Troika® Farm and Livestock Aerosol insecticide for mosquito control in February 2026, signaling continued development in specialized treatment categories that intersect with agricultural, livestock, and broader vector management needs.
At the same time, local government behavior remains a critical demand signal for the industry. In May 2026, the City of Arlington, Texas announced its 2026 mosquito control plans, including targeted ground spraying and larvicide applications. That kind of program planning matters because public-sector procurement cycles, service scopes, and budget priorities can influence both short-term activity and the longer-term baseline for regional demand.
The same period also illustrates the budget variability that operators must anticipate. In April 2026, the Village of Roscoe adjusted its program by reducing $25K from the mosquito control program budget for the 2026 season. While individually localized, such decisions reflect the fiscal pressure points that can affect program continuity, service frequency, and the balance between public and private demand.
These developments are not isolated news items. They reveal an industry in which operational decisions are tightly linked to biological risk, public funding cycles, and regulatory interpretation. That is why the research gives substantial attention to dynamics rather than size alone.
The Operational and Regulatory Forces Shaping 2026 Economics
Several underlying forces will shape how the market performs for providers, customers, and investors over the forecast period.
One is labor specialization. Mosquito control service requires trained technicians for larvicide and adulticide applications, and that requirement affects scalability, service quality, and cost structure. Providers that can recruit, train, and deploy specialized labor efficiently are better positioned to manage seasonal peaks and maintain consistent service standards.
Another is input cost volatility. Fluctuating prices of raw materials affect overall production costs for mosquito control equipment and materials. Because these inputs feed directly into treatment economics, pricing strategies and margin planning need to account for cost variability rather than assume stable conditions.
Regulatory context is equally important. The industry continues to operate within an evolving approval and permitting environment. For example, the EPA registration review for naled as a mosquito adulticide has been ongoing under the Pesticide Registration Improvement Act, which underscores the importance of monitoring active ingredient approvals and compliance pathways.
In parallel, advocacy efforts have highlighted the cost and administrative burden associated with overlapping environmental permitting requirements. In 2026, the American Mosquito Control Association advocated for passage of the PERMIT Act to reduce duplicative Clean Water Act permitting burdens on mosquito control programs. Related positioning has emphasized that mosquito control applications should be exempt from duplicative Clean Water Act permits to minimize costs and bureaucracy. For operators and public agencies alike, these debates are not abstract. They can influence program design, operating cost, and the practical feasibility of certain treatment approaches.
The report integrates these factors so that readers can interpret market growth in the context of what is operationally achievable and commercially sustainable. That is a critical distinction for anyone making investment, pricing, or expansion decisions in 2026.
How the Report Helps You Decide in 2026
The strategic value of this research lies in its ability to connect market size, segmentation logic, competitive structure, and dynamic operating pressures into a single decision-oriented framework. For different audiences, that framework supports different kinds of action.
For service providers, the analysis helps clarify where to prioritize service types, how application segments differ in demand behavior, and which competitive positioning strategies are most consistent with cost realities and regulatory constraints. For investors and corporate development teams, the concentration and segmentation structure provides context for evaluating fragmentation, consolidation potential, and the defensibility of specific business models. For public-sector and procurement stakeholders, the report offers a broader market backdrop that can inform budgeting assumptions, vendor evaluation, and program planning.
Because detailed regional values, application splits, type-based splits, and segment-level monetary figures are reserved within the full study, this preview is intentionally scoped to explain the analytical logic rather than reproduce the complete dataset. That approach reflects a practical reality: the market is complex enough that raw numbers alone are not sufficient. Decision-makers need the framework that explains what the numbers imply, where the trade-offs are, and how to use the data in planning.
What Is Inside the Full Study
The complete report expands on the previewed structure with detailed market sizing across the 2020 to 2025 historical period and the 2026 to 2032 forecast window. It provides segmentation analysis by region, by type, and by application, along with concentration metrics that help characterize competitive structure. Beyond the core numbers, the study examines the operational, regulatory, and input-cost forces that shape market execution, and it places the major providers in context with recent industry developments that illustrate how the market is evolving in real time.
The objective of the full document is to give users a usable intelligence base: enough granularity to support segment evaluation and competitive benchmarking, and enough contextual analysis to support planning under uncertainty.
Conclusion
Mosquito control service is no longer a narrow seasonal market. It is a growing, operationally demanding, and increasingly regulated industry where growth must be interpreted through cost structure, service type, application context, and competitive positioning. The 2026 to 2032 outlook reflects continued expansion, but the real strategic opportunity lies in understanding where that expansion is most profitable and how competitive intensity is likely to evolve.
PW Consulting’s Mosquito Control Service Market report is built for that task. It translates macro growth into decision-relevant structure, situates major players within a realistic competitive landscape, and connects market data to the operational and regulatory forces that determine execution quality. For leaders navigating 2026 strategy, the study offers a structured basis for prioritizing segments, evaluating competitors, and planning for the dynamics that will shape performance over the forecast period.
For detailed analysis of this topic, please visit the official page: Mosquito Control Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Steam Water Heater Market Hits $88.5M in 2025, Rises at 3.1% CAGR to $109.8M by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Steam Water Heater Market: Navigating Growth and Complexity in 2026
As organizations align capital allocation with long-term operational resilience, the steam water heater sector demands more than headline figures. The latest market research from PW Consulting offers a rigorous, decision-ready view of an industry undergoing steady revenue expansion, shifting manufacturing economics, and evolving compliance expectations. Built on a multi-year historical baseline and extended through a forward-looking forecast window, this study is designed to help executives, procurement leaders, and engineering strategists separate structural opportunity from transient market noise.
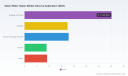
The report anchors its analysis in a base year of 2025 and evaluates historical performance from 2020 through 2025 before projecting trends across the 2026 to 2032 forecast period. Over this horizon, the market is expected to advance at a compound annual growth rate of 3.1 percent, with revenues measured in USD millions. This trajectory reflects a landscape where demand continues to build incrementally rather than erupt, rewarding players who can optimize product portfolios, regional execution, and cost structures in tandem. Total market revenue has demonstrated a consistent upward path across recent years, and the forecast horizon suggests continued accumulation of value as commercial, institutional, and industrial buyers prioritize reliable hot water delivery, energy efficiency, and safety-compliant engineering.
For decision-makers, the strategic value of this research lies in its ability to convert macro momentum into actionable intelligence. Rather than presenting a static snapshot, the study maps how growth is distributed across product architectures, application environments, and geographies, while also examining the competitive forces shaping pricing, innovation, and market entry. In a sector where subtle differences in heat exchanger design, response time, installation footprint, and compliance documentation can determine win rates, the report functions as a navigation tool for portfolio planning, channel strategy, and risk mitigation.
Executive Snapshot: Market Scale, Trajectory, and the 2026 Decision Context
The current market environment is defined by measured expansion, not volatility. Historical data from 2020 to 2025 shows a sector that has recovered and strengthened, with revenue rising from the mid-$70M range into the high-$80M range by 2025. Looking ahead, the forecast period indicates that this momentum will carry forward, reaching new revenue plateaus as the market matures. The implied CAGR of 3.1 percent signals a steady, cumulative growth path that rewards disciplined execution more than aggressive betting on a single segment or geography.
This pattern matters because it shapes how companies should think about capacity, inventory, and investment timing. In a market growing at a moderate but reliable pace, the winners are typically those who can align product availability with end-user procurement cycles, manage input cost pressure without sacrificing margin, and anticipate regulatory shifts before they become binding constraints. The research provides the structural context needed to make those choices with greater confidence, especially as firms prepare for the operational and strategic demands of 2026 and beyond.
Equally important is the way growth is distributed. The study explores how different product types, end-use settings, and regional markets contribute to overall performance, giving readers a clear sense of where demand is concentrated and where downstream opportunities may emerge. By avoiding oversimplified conclusions and instead mapping the interplay between technology, application, and location, the report enables stakeholders to prioritize the segments and strategies most relevant to their own business models.
Steam Dryer Market
Report Architecture: What Decision-Makers Will Find Inside
The study is structured to support both strategic planning and tactical execution. It begins with a full market overview that establishes historical context, defines key performance parameters, and frames the forecast logic. From there, the analysis moves into segmentation that breaks the market down by product type, application, and region, providing a layered understanding of demand drivers without reducing them to oversimplified averages.
The product-type analysis examines distinct heating architectures and their respective value propositions. The report explores how instantaneous designs, semi-instantaneous configurations, and storage-based systems each address different operational requirements, installation constraints, and performance expectations. This portion of the study helps readers understand which product families align with specific use cases, how design choices affect throughput and temperature control, and where engineering differentiation is most likely to influence purchasing decisions.
The application dimension adds another layer of practical insight. The research evaluates demand patterns across buildings and hotels, hospitals, food and beverage industrial environments, schools, and other end-use categories. By examining how steam water heaters are deployed in each setting, the report highlights the operational priorities that matter most to buyers, including reliability, hygiene considerations, process heating needs, and space limitations. This application-level view is especially useful for manufacturers and distributors seeking to tailor messaging, configuration offerings, and service support to the realities of each vertical.
Regional analysis completes the segmentation framework by mapping demand geography and identifying where commercial and industrial activity is most concentrated. Rather than treating regions as uniform blocks, the study considers how local infrastructure, procurement practices, and adoption patterns shape market performance. This enables readers to assess where existing presence is strongest, where expansion may be most viable, and how regional dynamics interact with broader global trends.
Competitive Arena: Who Is Shaping the Category
The steam water heater market is characterized by a concentrated group of established manufacturers, each competing through engineering specificity, application expertise, and product reliability. The report includes detailed profiles of leading organizations that collectively define much of the current competitive landscape.
Armstrong International, based in Three Rivers, Michigan, is recognized for its Constantemp series of instantaneous steam water heaters, which use helical coil heat exchangers to support precise temperature control in commercial and industrial applications. AERCO International, Inc., headquartered in Blauvelt, New York, focuses on high-efficiency semi-instantaneous steam water heaters and condensing boilers optimized for commercial buildings and healthcare environments. Elge Technologies LLC, with U.S. operations connected to its Swedish base, produces vertical shell-and-coil steam water heaters that emphasize space efficiency and high performance for industrial and commercial use.
Patterson-Kelley, located in East Stroudsburg, Pennsylvania, offers indirect-fired and semi-instantaneous steam water heaters, including the P-K Compact series designed for commercial process heating. PVI Industries, based in Fort Worth, Texas, supplies instantaneous and semi-instantaneous models with compact designs intended for domestic and commercial applications. Graham Corporation, in Batavia, New York, manufactures Heliflow heat exchangers and packaged MicroMix II instantaneous steam-fired hot water heaters. Hubbell Heaters, headquartered in Stratford, Connecticut, produces indirect and semi-instantaneous steam water heaters serving industrial, marine, and commercial applications.
The study also situates these players within a broader competitive context by examining market concentration and the strategic implications of an environment where leading participants hold a meaningful share of total activity. This concentration shapes negotiation dynamics, channel access, and the degree to which new entrants or niche innovators can gain traction. In such a landscape, competitive advantage often depends on product reliability, application-specific engineering, and the ability to navigate installation and compliance requirements with clarity.
Market Dynamics: Regulation, Inputs, and Competitive Velocity
Beyond product and competition, the report integrates the external forces that are actively reshaping market behavior. One of the most immediate pressures comes from raw material economics. In early 2026, U.S. steel traded near $960 per short ton, contributing to tank and cylinder price adjustments of up to 10 percent effective March 1, 2026. For manufacturers and distributors, this translates into cost volatility that can affect pricing strategies, margin planning, and inventory timing. The study discusses how input cost trends influence product economics and what they mean for organizations that must balance competitiveness with sustainable profitability.
Regulatory timing is another critical factor. The U.S. Department of Energy enforcement for updated efficiency standards on water heaters has been delayed until October 6, 2027. This postponement creates a transitional window during which manufacturers and buyers must prepare for eventual compliance requirements while operating under current rules. The report explores the strategic implications of that delay, including how it affects product roadmaps, specification decisions, and the pace of technology adoption across commercial and industrial segments.
Safety and compliance documentation remain equally important. All steam water heater installations must comply with ASME U-1 forms and manufacturer installation guidelines for safety and performance. In addition, industrial hot water boiler and steam water heater units require manufacturer data reports and U-1 forms submitted to owners. These requirements underscore that compliance is not a peripheral concern but a core part of market participation. The research examines how documentation, installation standards, and performance verification influence purchasing confidence, project execution, and long-term operational risk.
The competitive environment is also being reinforced by continued product and channel activity. At AHR Expo 2026, Rinnai America Corporation debuted new commercial electric tank water heaters, while Bradford White introduced the eF Series Turbo commercial high-efficiency gas water heaters in larger BTU configurations. These exhibitions signal ongoing investment in commercial water heating categories and highlight how trade shows, product launches, and visible technology refreshes contribute to market momentum. For participants in the steam water heater space, such activity matters because it shapes buyer expectations, draws attention to adjacent product innovations, and influences the broader conversation around efficiency and performance.
Why This Study Matters for 2026 Strategy
The 2026 decision environment calls for research that is both precise and practical. Leaders need more than aggregate market numbers; they need a framework for interpreting where growth is coming from, how competitive pressure is forming, and which operational variables will most affect margin and execution. This study is built for that purpose.
First, it helps organizations evaluate portfolio fit. By clarifying how different product types and applications contribute to demand, the report supports more informed decisions about specification focus, configuration development, and go-to-market prioritization. Second, it provides a structured view of regional performance, enabling companies to assess where their footprint aligns with market activity and where targeted expansion or channel strengthening may be warranted. Third, it places cost and regulatory dynamics within the same analytical frame as product strategy, helping executives anticipate discontinuities rather than react to them after they arrive.
Steam Water Heater Market
The research is also designed to support scenario thinking. Because the forecast extends over multiple years and is grounded in a detailed historical baseline, it gives readers a basis for evaluating how changes in steel costs, efficiency enforcement timing, installation requirements, and competitive launches could alter planning assumptions. That kind of forward visibility is especially valuable in a market where small shifts in compliance timing, input pricing, or application demand can have outsized effects on quarterly performance.
From Insight to Action: How to Use This Research
To get the most value from the study, organizations should use it as a connective tissue between strategy, sales, and operations. Executive teams can draw on the market overview and competitive profiles to set long-term priorities and understand the structural forces shaping the category. Commercial leaders can use the segmentation analysis to refine target accounts, align product messaging with application needs, and identify where specific product architectures are most relevant. Procurement and supply chain teams can incorporate the cost and compliance sections into sourcing discussions, inventory planning, and contract negotiations. Engineering and product teams can use the application and product-type detail to assess where design refinement or configuration flexibility could improve win rates and customer satisfaction.
The report also functions as a reference point for internal alignment. In markets where multiple stakeholders influence purchasing decisions, a shared and credible understanding of demand patterns, competitive positioning, and regulatory timing can reduce friction and improve execution speed. By presenting the market in a structured, evidence-based way, the study helps teams speak from a common foundation rather than isolated assumptions.
Next Steps
The full Steam Water Heater Market research provides a deeper, more granular view of the trends summarized here, including detailed segmentation analysis, competitive profiles, and forward-looking market scenarios. For executives and project leaders preparing for 2026 planning cycles, the complete report offers the level of detail required to turn strategic questions into executable decisions.
To access the full dataset, segmentation breakdowns, and extended competitive intelligence, visit the source page for the complete PW Consulting market research package.
For detailed analysis of this topic, please visit the official page: Steam Water Heater Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Synthetic Fibre Rope Market to Hit $2,610M by 2032, Driven by 6.5% CAGR
By PW Consulting, 2026-09-16
Strategic Navigation in a High-Growth Synthetic Fibre Rope Market: A 2026 Decision-Maker's Brief
The synthetic fibre rope sector stands at a critical inflection point. As global industrial operations demand higher performance, greater durability, and increasingly sustainable load-bearing solutions, the market has evolved from a commodity-adjacent category into a technology-driven ecosystem. Our recently published market research on the Synthetic Fibre Rope Market delivers a comprehensive, forward-looking intelligence framework designed specifically for executive teams planning capital allocation, supply chain restructuring, and competitive positioning across the 2026–2032 horizon.
This article serves as a strategic preview of the full study. It outlines the macroeconomic trajectory, highlights the operational and competitive dimensions covered in depth, and explains why the report's analytical architecture is calibrated to support high-stakes decision-making in the current year. The objective is not to replicate existing trade summaries, but to equip strategists, procurement leaders, and corporate planners with the conceptual scaffolding required to assess where the market is heading, who will shape its contours, and which structural variables will define profitability in the next cycle.
The Trajectory: Why 2026 Matters for Capital Allocation
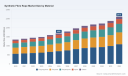
The global synthetic fibre rope market has demonstrated consistent expansion over the past half-decade, with total revenue growing from approximately 1,347 million USD in 2020 to an estimated 1,688 million USD in 2025. The forecast period extends through 2032, with projected revenue reaching roughly 2,610 million USD by the final forecast year. This trajectory reflects a compound annual growth rate of 6.5 percent, a figure that may appear moderate on its own but carries substantial structural implications when viewed through the lens of industrial demand intensity, raw material volatility, and regional capacity reconfiguration.
Synthetic Fibre Rope Market
For executives evaluating 2026 investment priorities, the key insight is not simply that the market is expanding, but that the composition of that expansion is shifting. High-performance synthetic variants are capturing incremental share in applications where failure risk, weight sensitivity, or corrosion resistance justify premium pricing. Meanwhile, conventional grades continue to anchor high-volume, cost-sensitive segments. Understanding which end-use categories are driving volume versus value, which materials are experiencing input-cost pressure, and how regional manufacturing footprints are adapting to logistics and sustainability mandates requires a granular view that only a structured market study can provide. The report dissects these layers systematically, enabling leadership teams to separate cyclical noise from durable demand shifts.
Inside the Research: Analytical Architecture and Operational Utility
The study is organized around a multi-dimensional analytical framework designed to translate complex market signals into actionable intelligence. Rather than presenting static snapshots, the research maps the interplay between material technology, application requirements, regional dynamics, and competitive behavior across the forecast window. The structure is deliberately built for cross-functional use: procurement teams can benchmark input exposure, R&D groups can evaluate material substitution pathways, sales leadership can align territory strategies with regional demand intensities, and corporate development teams can assess partnership, acquisition, or capacity-expansion opportunities.
Core analytical components include:
- Material-level performance and cost dynamics. The report examines how different synthetic families are positioned across performance tiers, weight-to-strength profiles, chemical resistance characteristics, and price sensitivity thresholds. It tracks how premium-grade materials compete against established conventional options, particularly in segments where total cost of ownership, not unit price, determines adoption.
- Application-driven demand mapping. End-use requirements vary dramatically across marine, industrial, energy, construction, and specialized technical sectors. The study evaluates the distinct performance criteria, procurement cycles, and regulatory environments shaping demand in each application cluster, helping readers anticipate where volume growth will be most concentrated and where specification upgrades will drive mix improvement.
- Regional market structure and supply chain considerations. Demand intensity, manufacturing presence, logistics constraints, and local regulatory frameworks differ meaningfully across geographies. The report contextualizes these differences to support localization decisions, import/export strategy, and regional partnership selection without reducing the analysis to oversimplified share rankings.
- Competitive positioning and strategic group analysis. The study profiles the operational focus, technological orientation, and market footprint of leading participants, enabling readers to understand where differentiation is being created, how certification and compliance capabilities affect purchasing decisions, and which collaborative or consortium-based initiatives are reshaping industry standards.
- Pricing context and input-cost exposure. Given the substantial cost differentials between synthetic and natural alternatives, as well as between conventional and high-performance synthetics, the research provides pricing context that helps procurement and finance teams model inventory exposure, capital expenditure sensitivity, and supplier negotiation leverage.
The full report goes further by integrating these dimensions into a coherent forecast model, allowing decision-makers to test assumptions around volume growth, material substitution, and regional expansion under varying macroeconomic and regulatory scenarios.
Competitive Landscape: incumbents, Specialists, and Standards Bodies
The synthetic fibre rope market is characterized by a blend of established manufacturers, technology-focused specialists, and regional producers with deep application expertise. Industry concentration is meaningful: the three largest participants account for approximately 62.5 percent of market revenue, while the top five collectively represent around 75.0 percent. This concentration shape has strategic implications. It suggests that pricing power, specification influence, and relationship-driven procurement remain significant in many end-use segments, while simultaneously leaving room for agile specialists to capture niche positioning through performance innovation, certification strength, or application-specific engineering support.
Several companies exemplify the competitive diversity shaping the sector today. Samson Rope Technologies, based in the United States, has built a reputation around high-performance synthetic ropes spanning polyester, nylon, and high-modulus polyethylene, with emphasis on lifting, rigging, marine, and safety applications. Teufelberger Holding AG, headquartered in Austria, supplies fiber ropes and high-performance synthetic rope solutions across marine, forestry, arborist, and industrial contexts. Lanex, operating from the Czech Republic, maintains a traditional manufacturing base serving marine, yachting, rescue, military, and industrial applications. Yale Cordage, also U.S.-based, focuses on advanced braiding techniques and high-tech synthetic rope systems for energy, marine, medical, and research environments. Unirope, based in Canada, emphasizes certified lifting and rigging synthetic rope products aligned with ISO 9001 and LEEA standards. Cortland Limited serves energy, subsea, marine, medical, and research sectors with high-tech ropes, slings, and strength members. In Europe, Oliveira has combined fiber rope and steel wire rope production since the early nineteenth century and remains active in EUROCORD, while COTESI and BADINOTTI, both Italian producers, participate in the same European association and serve industrial and marine applications.
These profiles matter because competitive advantage in this market is rarely determined by volume alone. Procurement teams in marine, energy, construction, and industrial settings often weigh certification credibility, technical support capacity, material consistency, and supply reliability alongside price. The report examines how such differentiators are translating into market positions and where consolidation, collaboration, or technology licensing may alter the landscape over the forecast period.
Recent Developments Shaping Strategic Assumptions
Several recent industry movements reinforce the need for updated decision frameworks in 2026. Price-environment observations from early 2026 indicate that synthetic ropes typically command substantial premiums over natural fiber alternatives, with cost ranges per meter varying widely by material class. Polypropylene and polyester remain positioned at lower price points relative to high-performance options, while ultra-high-molecular-weight polyethylene and similar advanced fibers occupy a significantly higher cost band. For large-scale operators managing substantial rope inventories across utility, marine fleet, or construction operations, these differentials have direct implications for working capital intensity and inventory strategy.
On the innovation and sustainability front, a notable product partnership announced in April 2026 brought together a high-tech rope producer and a protective materials specialist to develop a green synthetic rope manufactured in the United States. This type of collaboration signals growing investor and customer interest in reducing the environmental footprint of synthetic load-bearing products without sacrificing performance, and it underscores how regional manufacturing claims can become part of the value proposition in certain procurement contexts.
At the industry-organizational level, EUROCORD continues to serve as a focal point for synthetic rope producers in Europe and beyond. Recent annual meetings and newsletter activity have drawn participation from multiple established manufacturers, with emphasis on standards, industry updates, and collective positioning on material availability and sustainability. This institutional activity matters because standards alignment, quality expectations, and regulatory awareness increasingly influence specification decisions in marine, industrial, and energy applications. The study incorporates these dynamics to help readers understand how advocacy, standardization, and consortia participation can affect both competitive behavior and procurement requirements over time.
In parallel, broader material-market context indicates that fossil-based synthetic feedstocks have seen volume increases, alongside heightened attention to the availability and sustainability trajectory of biobased alternatives. For rope manufacturers and downstream buyers alike, this signals that input sourcing strategies, supplier diversification, and material substitution roadmaps will remain central to cost management and reputational positioning.
What the Full Study Enables
The complete research publication is designed to convert the themes outlined above into a practical decision-support toolkit. Readers can expect detailed baseline estimates, forward projections, and structured segmentation analysis that illuminate where growth is accumulating and how value is migrating across materials, applications, and regions. The study also provides competitive profiles, recent strategic developments, and industry-institution activity that help map the evolving rules of competition. Importantly, it frames pricing and input-cost dynamics in a way that supports scenario planning rather than static assumptions, recognizing that synthetic rope procurement is frequently a balance between performance assurance, total cost of ownership, and supply resilience.
For organizations making 2026 decisions on capacity, supplier selection, product development, regional entry, or market expansion, the report offers a consolidated reference point that reduces reliance on fragmented sources and ad hoc estimates. It is structured to be referenced by multiple functions simultaneously, with enough depth to support board-level narrative building and enough operational specificity to inform procurement, sales, and engineering planning.
Conclusion: Positioning for the Next Cycle
The synthetic fibre rope market is growing, but more importantly, it is re-composing. Growth is not uniformly distributed across materials, applications, or regions, and the premium-versus-value dynamic is reshaping both supplier strategy and buyer evaluation criteria. In this environment, the strategic question is no longer simply whether to participate, but how to position for the segments, specifications, and supply-chain configurations that will generate the most durable returns through 2032.
Synthetic Concrete Fibers Market
The full market research provides the depth, structure, and forward framing required to answer that question with confidence. For executives seeking to align capital, procurement, and competitive strategy with the next phase of market development, the study offers a rigorous starting point for 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Synthetic Fibre Rope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lymphedema Pneumatic Compression Market Hits $1.29B in 2025, Poised for 7.0% CAGR
By PW Consulting, 2026-09-16
Strategic Outlook: Navigating the Pneumatic Compression Devices for Lymphedema Market in 2026 and Beyond
The global landscape for pneumatic compression devices designed for lymphedema management is undergoing a structural transformation. As healthcare systems shift from reactive acute care to proactive chronic disease management, the demand for non-invasive, home-enabled therapeutic interventions has accelerated. Our latest research on the Pneumatic Compression Devices for Lymphedema Market provides a rigorous, data-grounded framework for executives, investors, and clinical strategy teams to navigate this growth trajectory with precision. This article sets the stage for the full report, outlining the macro forces, competitive realities, regulatory shifts, and strategic imperatives that will define decision-making through 2032.
A Market Reshaped by Volume, Velocity, and Value
The historical trajectory of this market tells a clear story of steady, compounding expansion. Between 2020 and 2025, global revenue climbed from approximately 925 million USD to nearly 1,300 million USD, reflecting a consistent upward curve driven by rising prevalence of chronic venous insufficiency, increased oncology survivorship rates, and broader adoption of conservative compression therapies as first-line interventions. The momentum does not slow in the forecast period. Projected to reach roughly 1,400 million USD in 2026, the market is positioned to accelerate further, with forward estimates indicating a climb toward 2,070 million USD by 2032. This trajectory translates to a compound annual growth rate of approximately 7 percent across the full forecast horizon, a pace that outstrips many adjacent durable medical equipment segments and underscores a durable demand cycle rather than a cyclical surge.
Pneumatic Compression Devices for Lymphedema Market
The growth is not merely a function of more units sold. It reflects a fundamental repositioning of pneumatic compression within clinical workflows. Hospitals, outpatient clinics, and home care environments each play distinct roles in the patient journey, yet the segmentation of revenue across these settings reveals an increasingly balanced ecosystem. Similarly, the product landscape continues to differentiate along the lines of segmented and non-segmented architectures, each addressing different clinical protocols and patient compliance profiles. The full report deconstructs these dynamics in depth, mapping how clinical efficacy, reimbursement alignment, and manufacturing economics intersect to shape where value accrues.
Competitive Architecture: Specialization, Differentiation, and Clinical Credibility
The supplier landscape is defined by a focused set of manufacturers that have built commercial and clinical moats around specific compression methodologies, garment engineering, and patient-access pathways. Rather than a commoditized price war, the market rewards companies that can demonstrate differentiated pressure profiles, ease of home use, and robust supporting evidence. Our competitive analysis profiles the leading participants and examines how their product strategies align with emerging reimbursement and clinical guidelines.
- Bio Compression Systems has established a strong foothold in the sequential compression segment with its Sequential Circulator line, emphasizing non-peristaltic pumping technology and multi-chamber garments tailored for lymphedema and chronic venous insufficiency. Their positioning reflects a long-standing focus on reproducible pressure delivery and clinical familiarity.
- Mego Afek, through its Lympha-Press and Lympha-Press Optimal systems, offers pneumatic compression pumps and garments that target lymphedema, venous insufficiency, and related conditions. The company’s international footprint and modular garment design position it to serve both clinical and home-based pathways across diverse reimbursement environments.
- Tactile Medical has carved out a distinctive presence in the home care segment with its Flexitouch and Flexitouch Plus advanced intermittent pneumatic compression systems. By pairing sophisticated compression sequencing with patient-centric garment engineering, the company addresses the compliance and usability challenges that often determine long-term adherence in at-home therapy.
- Neomedic’s Powerpress Unit Sequential Circulator continues to serve as a clinically oriented option for lymphedema and edema management, with distribution and product focus aligned to providers seeking reliable, prescription-grade compression solutions.
- Huntleigh Healthcare brings a broad diagnostics and care portfolio to the space, with its LymphAssist Professional and Hydroven 12 intermittent pneumatic compression systems and multi-chamber garments. Their presence highlights the intersection of diagnostic-led clinical decision-making and therapeutic device deployment.
- EEZCare Medical, through its EzLymph and EzLymph M pneumatic compression pumps, reflects the growing geographic diversification of the supply base, expanding manufacturing and distribution capacity to serve regional demand while maintaining clinical functionality.
- Koya Medical operates at the edge of the traditional pneumatic category with its Dayspring non-pneumatic active compression device, illustrating how adjacent technologies are expanding the broader conversation around chronic edema and lymphedema management. Its differentiated modality serves as a reminder that competitive pressure in this market extends beyond direct pneumatic substitutes to alternative compression philosophies.
The report does not stop at company descriptions. It examines how these players compete on clinical documentation, service networks, DME channel partnerships, and product line extensions. Concentration metrics indicate that while incumbents hold meaningful share, the market remains sufficiently open to well-positioned entrants that can align product performance with payer expectations and provider workflows.
Worldwide Mobile Whole Body Pressure Therapy Apparatus Market
Regulatory, Reimbursement, and Clinical Evidence: The Inflection Points That Matter
The commercial trajectory of pneumatic compression devices for lymphedema is inseparable from the policy and clinical environment. In 2026, decision-makers must operate within a tightening but clarifying framework of coverage criteria, device classification, and evidence expectations. Medicare’s national coverage architecture continues to anchor much of the reimbursement landscape, with coverage pathways tied to documented therapeutic need and conservative management prerequisites. All FDA-cleared pneumatic compression devices for lymphedema are regulated as Class II devices under a defined product code, and maintaining ISO 13485 certification remains a baseline requirement for quality management across manufacturers. These structural requirements shape not only market entry but also ongoing compliance, distributor relationships, and contracting risk.
The reimbursement code framework adds further granularity to commercial planning. Coverage under the durable medical equipment benefit relies on distinct HCPCS codes differentiated by segmental and gradient characteristics. This coding structure directly influences how devices are positioned, priced, and prescribed, and it creates natural segmentation in purchasing behavior. Payers increasingly assess clinical appropriateness through prior authorization and utilization management reviews. Recent activity signals a more active oversight environment: Medicare began initiating prior-authorization reviews for pneumatic compression devices effective in mid-April 2026, a policy shift with immediate operational implications for providers, DME suppliers, and device manufacturers alike.
At the same time, clinical evidence is strengthening the long-term rationale for intermittent pneumatic compression in lower extremity lymphedema management. Updated clinical directives and community care guidance have reinforced the role of sustained compression therapy where conservative measures alone are insufficient. Major payers have also revisited their coverage criteria, with recent guideline reviews updating clinical utilization parameters for pneumatic compression pumps. Together, these developments create a dual dynamic: heightened administrative scrutiny paired with stronger clinical endorsement for appropriate patient populations.
Why This Report Matters for 2026 Decision-Making
For executives planning capacity, pricing, channel strategy, and clinical positioning, the strategic question is no longer whether the market is growing, but where the growth is most defensible and how to capture it. This research is designed to translate macro momentum into actionable intelligence. It provides a structured view of historical performance, forward projection, and the operational levers that determine commercial outcomes in a market sensitive to reimbursement rules, clinical adoption, and product differentiation.
The report is built for practical use. It examines the full revenue arc across the forecast period, identifies the structural drivers behind the projected 7 percent compound growth, and situates that growth within the interplay of segmented and non-segmented device architectures. It maps the distribution of demand across home care, hospital, and clinic settings without reducing the story to a single channel narrative, because real-world adoption is shaped by referral pathways, DME logistics, and clinical protocols that vary by setting. It also breaks down regional performance in a way that highlights where mature demand, emerging adoption, and pricing dynamics create distinct strategic opportunities.
Equally important, the analysis integrates the competitive landscape with regulatory and reimbursement realities. It shows how prior authorization requirements, DME coding structures, coverage determinations, and quality certification expectations influence purchasing behavior, channel economics, and market entry timing. For device manufacturers, this means understanding which product features are most likely to satisfy payer and provider criteria. For distributors and DME providers, it means anticipating administrative burden and aligning service models accordingly. For investors, it means separating durable expansion from short-term policy noise.
What You Will Find Inside
- A complete historical and forecast revenue trajectory with the analytical context behind the growth curve, including the forces shaping the 2026 base and the acceleration path through 2032
- A detailed segmentation review across device type, care setting, and geography, with interpretation of how each segment’s economics and adoption drivers differ
- A competitive profile of the core participants, with emphasis on product architecture, clinical positioning, distribution strategy, and differentiation relative to adjacent modalities
- A synthesized analysis of regulatory and reimbursement dynamics, including device classification, coding structure, coverage prerequisites, prior authorization developments, and clinical evidence trends
- Strategic implications for product strategy, channel design, market entry, and pricing in a market where clinical credibility and reimbursement alignment increasingly determine commercial success
The full report delivers the complete dataset, scenario analysis, and segment-level interpretation needed to move from awareness to action. It also includes the most current policy and clinical developments as they evolve, ensuring that strategy is anchored to the operational reality of 2026 rather than outdated assumptions.
Positioning for the Next Phase of Growth
The Pneumatic Compression Devices for Lymphedema Market is entering a phase where scale matters, but precision matters more. Companies and investors that understand the interplay between clinical evidence, reimbursement architecture, competitive differentiation, and care-setting economics will be better equipped to allocate resources and shape long-term positioning. The macro forecast points to a market approaching the 2 billion USD threshold by the end of the forecast window, but the strategic value lies in understanding how that total is constructed and where competitive advantage can be built within it.
This research is intended as a decision-grade resource: rigorous enough to support executive planning, detailed enough to inform product and commercial strategy, and current enough to reflect the fast-moving policy environment. For teams evaluating product portfolios, market entry, partnership structures, or investment exposure, the full market report provides the foundation required to act with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Pneumatic Compression Devices for Lymphedema Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Refrigerator Water Filters Market to Reach $3.9B by 2032, 5.9% CAGR; PW Consulting Report
By PW Consulting, 2026-09-16
Navigating the Next Era of Refrigerator Water Filters: Strategic Intelligence for 2026 and Beyond
The global appliance ecosystem is undergoing a quiet but decisive transformation. As consumers place greater emphasis on water quality, health consciousness, and appliance longevity, the refrigerator water filter segment has evolved from a routine replacement component into a strategic battleground defined by certification compliance, subscription-based service models, and intensifying competition between original equipment manufacturers and certified aftermarket players. Our newly released market research provides a comprehensive, data-grounded assessment of this landscape, offering enterprise leaders a clear framework for capital allocation, product positioning, and long-term competitive strategy.
This introduction outlines the core strategic value of the study, highlights the operational and regulatory forces currently reshaping the market, and previews the analytical depth available in the full report. For decision-makers operating in 2026, understanding where the market has been and how it is structurally positioned to evolve is no longer optional. It is a prerequisite for sustainable growth.
Water Filters Market
Market Evolution and Strategic Context
Over the past half-decade, the refrigerator water filter market has demonstrated consistent, structural expansion. Drawing on historical revenue tracking and forward-looking projections, our analysis captures a market that has steadily advanced from approximately $2.15 billion in 2020 to an estimated $2.65 billion in 2025, with continued upward momentum projected through the end of the forecast period. The trajectory reflects more than cyclical demand. It signals a durable shift in consumer expectations around integrated appliance functionality, coupled with increasingly stringent quality and safety benchmarks that collectively reinforce replacement frequency and brand loyalty.
The forecasted period extends through the early 2030s, with an estimated compound annual growth rate of 5.9 percent. This rate suggests a mature but still expanding segment, where growth will be driven less by sudden volume surges and more by sustained replacement cycles, geographic penetration, technology adoption, and service-oriented business models. For executives, this profile carries important implications. It indicates that competitive advantage will increasingly depend on supply chain efficiency, certification readiness, channel strategy, and the ability to convert transactional purchases into recurring revenue streams. The full report maps these dynamics in granular detail, but the overarching message is clear: the market is consolidating around compliance-driven quality and service continuity, and companies that treat filters as commoditized accessories will find themselves outpaced by those who embed filtration into broader product ecosystems and customer engagement strategies.
Regulatory Framework and Certification as Competitive Moats
One of the most consequential forces shaping the refrigerator water filter landscape is the tightening regulatory and certification environment. Industry guidance has increasingly clarified that listings on major retail platforms must demonstrate compliance with NSF/ANSI 42 for material safety, structural integrity, and performance reduction claims. Where manufacturers make additional health-effect or emerging-contaminant claims, NSF/ANSI 53 and NSF/ANSI 401 become relevant. This is not merely a technical footnote. It is a commercial gatekeeper.
Independent testing and certification by accredited organizations remain central to market access and consumer trust. Filters that fail to meet structural integrity or contaminant reduction requirements face heightened risk of discontinuation or recall, a reality that makes verification and documentation essential components of product lifecycle management. In practical terms, certification has become a brand asset and a barrier to entry. Companies that maintain rigorous compliance can command stronger shelf presence, retail partnership confidence, and customer retention, while those that treat certification as an afterthought expose themselves to reputational and operational risk.
At the same time, compliance has introduced real cost pressure. Replacement filters have experienced a notable increase in material and labor costs since 2020, driven in part by the need to meet evolving NSF standards for lead reduction and emerging contaminants. This cost trajectory shapes pricing architecture, margin planning, and the economics of aftermarket substitution. The complete study evaluates how manufacturers and distributors are navigating these pressures through product engineering, scale efficiencies, and value-tier positioning, but the strategic takeaway is already evident: regulatory compliance is redefining the cost floor of the category, and the winners will be those who integrate compliance into design and procurement strategies rather than treating it as an end-of-line checklist.
Competitive Landscape: OEMs, Aftermarket Innovators, and Retail Displacement
The competitive dynamics of this market are defined by a structured interplay between appliance OEMs, certified aftermarket specialists, and retail ecosystems that are beginning to mediate the replacement experience. Several large players anchor the segment through brand-integrated filtration programs, while a growing set of aftermarket providers compete on compatibility, certification, and pricing. The result is a market with meaningful concentration but still enough fragmentation to reward companies that execute sharply on channel strategy and customer retention.
Whirlpool Corporation and its EveryDrop brand illustrate a tightly integrated OEM approach. By manufacturing and distributing genuine refrigerator water filters designed for Whirlpool, KitchenAid, and related appliances, the company leverages installed base compatibility and ongoing replacement programs, including subscription-style replenishment. This model aligns filter sales with broader appliance ownership and builds predictable revenue through repeat purchases. LG Electronics follows a similar logic with its certified filter portfolio, emphasizing lead reduction standards and maintenance programs that include scheduled filter replacement. Samsung Electronics complements this competitive set with integrated filtration solutions engineered for water and ice systems, where model-specific compatibility and certification requirements reinforce OEM lock-in. GE Appliances rounds out the OEM perspective with genuine filters designed to reduce chlorine, lead, PFOA/PFOS, and other contaminants across its refrigerator models, reinforcing the value of appliance-specific ecosystems.
Against this OEM foundation, aftermarket participants have carved out a credible presence by offering NSF-certified compatible replacements. Ecolife Technologies, Inc., operating through its Waterdrop brand, distributes aftermarket filters that align with major OEM platforms including Samsung, LG, Whirlpool, and GE. Aqua Crest and SpiroPure similarly focus on certified replacement options designed for standard OEM housings and widely used refrigerator models. These companies illustrate a market dynamic in which compatibility, certification clarity, and distribution reach can offset the absence of native appliance manufacturing. They also highlight an important strategic question for incumbents: how to defend installed-base loyalty while responding to the pragmatic demand for cost-effective, certified alternatives.
Recent industry developments underscore how quickly the channel itself is evolving. In early 2026, Lowe's Companies, Inc. launched a HomeCare+ subscription service that includes annual refrigerator water filter replacement as part of associate-powered in-home maintenance for MyLowe's Rewards members. This move signals a broader push toward service-led retention models, where filter replacement becomes part of a broader home-care experience rather than an isolated point purchase. Around the same time, Waterdrop expanded its aftermarket refrigerator water filter catalog with additional SKUs targeting Samsung, LG, Whirlpool, and GE models, accompanied by updated NSF listings. These initiatives reflect two parallel trends: the growing importance of subscription and maintenance programs, and the continued expansion of certified aftermarket choice within retail channels.
What the Full Study Delivers for 2026 Decision-Making
The complete market research is designed to translate industry complexity into operational clarity. Rather than stopping at headline market size and growth rate, the study builds a practical decision framework that leaders can use to evaluate risk, prioritize investment, and refine go-to-market strategy. The analysis is structured to support cross-functional teams, from product development and procurement to sales, marketing, and investor communications.
At the core of the report is a detailed assessment of market size evolution and forward projections, anchored in historical performance and a clearly defined forecast horizon. This provides a reliable baseline for scenario planning, demand forecasting, and capacity alignment. The study then examines the structural composition of the market across product architecture and end-use context, helping readers understand where revenue is concentrated, how replacement behavior varies across environments, and which segments are most sensitive to certification, pricing, and compatibility considerations. These breakdowns are intentionally developed as strategic lenses rather than static snapshots, enabling readers to identify where competitive pressure is intensifying and where differentiation remains achievable.
The competitive portion of the research profiles leading participants and maps the forces that shape their positioning. By integrating company profiles, brand strategy signals, and recent developments, the report provides context for interpreting share dynamics, channel influence, and the strategic implications of OEM-versus-aftermarket competition. It also evaluates how service models, retail partnerships, and subscription-oriented offerings are changing the economics of replacement demand. This is particularly valuable for organizations considering whether to enter adjacent distribution channels, launch replenishment programs, or reposition their product tiers in response to cost and compliance shifts.
Another major strength of the study is its treatment of the regulatory and certification environment as a market driver rather than a compliance footnote. The report connects certification requirements to commercial outcomes, including retail eligibility, consumer trust, product lifecycle risk, and cost structure. It also addresses the practical reality that certification failures can trigger discontinuation or recall risk, reinforcing the importance of verification, documentation, and quality assurance in product planning. For companies operating in or entering this market, these insights support more resilient product architectures and more credible market-facing claims.
Finally, the study integrates material and cost considerations into the broader market narrative. By examining how compliance demands and input-cost trends have influenced the economics of replacement filters, the report offers a basis for pricing strategy, margin management, and value proposition design. This is essential for organizations trying to balance affordability with certification credibility, especially as aftermarket competition expands and OEM loyalty programs become more sophisticated.
Strategic Implications for Market Participants
For executives evaluating the refrigerator water filter market in 2026, several strategic priorities emerge from the landscape described in this study. First, certification readiness is a strategic differentiator, not just a technical requirement. Companies should treat compliance as a core element of product design, supplier selection, and retail positioning, because it directly affects distribution access, consumer confidence, and risk exposure.
Second, the shift toward service-connected replacement models is creating new opportunities for recurring revenue and customer lock-in. Subscription programs, maintenance integrations, and retail-led home care offerings are redefining how filter replacements are purchased and valued. Organizations that can align filtration with broader appliance ownership experiences or home maintenance relationships will be better positioned to capture lifetime value from installed bases.
Third, aftermarket competition is maturing, and compatibility with certified standards is increasingly central to its credibility. This creates both a challenge and an opportunity for OEMs and distributors. On one side, certified alternatives can pressure margin and loyalty; on the other, they validate the category's importance and can expand total demand by lowering barriers to replacement. The strategic response depends on whether a company competes through ecosystem integration, cost efficiency, channel strength, or a combination of all three.
Fourth, cost pressures tied to compliance and material inputs warrant ongoing attention in product planning and pricing architecture. As the market continues to expand, the ability to manage these economics without compromising certification credibility will separate resilient operators from those forced into reactive pricing moves.
Closing the Intelligence Gap
The refrigerator water filter market is no longer defined solely by appliance cycles and replacement schedules. It is increasingly shaped by certification standards, subscription-enabled retention, retail service models, and the growing credibility of aftermarket alternatives. For leaders operating in this environment, strategic clarity depends on more than directional trends. It requires a detailed understanding of how market size, segmentation, competitive positioning, and regulatory dynamics interact over time.
This research study was built to provide that understanding. It offers a comprehensive view of historical performance, projected growth, competitive structure, and the operational forces that will define the next several years of category development. The full report expands on every dimension introduced here with greater analytical depth, enabling teams to translate market intelligence into tangible decisions around product strategy, channel investment, compliance planning, and customer retention. For organizations preparing for 2026 and the forecast window ahead, the opportunity is to move from awareness to action with the kind of structured intelligence that supports durable competitive advantage.
Refrigerator Water Filters Market
For detailed analysis of this topic, please visit the official page: Refrigerator Water Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hairbrush Market to Reach USD 4,043.68 Million by 2032, Growing at 6.75% CAGR
By PW Consulting, 2026-09-16
Navigating the Next Wave: Strategic Intelligence for the Global Hairbrush Market Through 2032
The global hairbrush market is entering a decisive phase of expansion, driven by shifting consumer grooming habits, material innovation, and intensifying competitive positioning across both mass and premium segments. For executives, product developers, and market strategists operating in personal care, beauty tools, or retail distribution, understanding the trajectory of this category is no longer optional. It is a prerequisite for capital allocation, product roadmapping, and channel strategy. Our latest Hairbrush Market research report delivers a comprehensive, data-grounded view of the industry landscape, equipping decision-makers with the structural intelligence needed to act confidently throughout the 2026–2032 forecast horizon.
The category has demonstrated consistent growth over the past half-decade, with historical revenue climbing from approximately $2,150.5 million in 2020 to a projected $2,600.0 million in 2025. Looking ahead, the market is positioned to expand at a compound annual growth rate of 6.75 percent, reaching an estimated $4,043.68 million by 2032. This trajectory reflects more than a straightforward volume trend. It signals a structural evolution in how consumers interact with hair care tools, how manufacturers differentiate through material and design innovation, and how retail ecosystems are reshaping accessibility and premiumization simultaneously. The strategic question for industry participants is no longer whether the category will grow, but how to position portfolios, supply chains, and go-to-market models to capture disproportionate value within that growth curve.
Our report is engineered to translate this macro momentum into actionable strategy. Below is a structured overview of the analytical framework, competitive intelligence, and market dynamics contained within the full study.
A Multi-Dimensional Analytical Architecture
Effective strategic planning requires more than top-line projections. The study is built around a layered segmentation and dynamics framework that enables teams to isolate growth drivers, assess margin potential, and identify white-space opportunities without relying on aggregate assumptions. The analysis spans product architectures, material composition, application environments, end-user profiles, and regional commercial structures, allowing readers to cross-reference demand patterns against manufacturing capabilities and channel realities.
By product, the report evaluates how distinct brush formats are performing across consumer and professional use cases, mapping functional differentiation against price positioning and repeat-purchase behavior. By material, the analysis tracks the accelerating transition toward synthetic and organic compositions, examining cost structures, sustainability positioning, and consumer acceptance. By application, the study separates personal grooming demand from professional salon and service-channel requirements, highlighting divergent purchasing criteria, durability expectations, and purchasing cycles. By end user, the framework disentangles demand contribution across women, men, and children, providing a clearer picture of demographic-driven product development priorities.
Regional coverage is equally granular. The research maps commercial activity across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, assessing how distribution maturity, retail infrastructure, and localized grooming preferences shape revenue concentration and growth pacing. Rather than presenting static share tables, the report interprets regional performance as a function of market access, competitive density, and consumer readiness for premium and specialty offerings. The result is a decision-ready map that helps organizations prioritize expansion pathways, partnership targets, and inventory strategies with greater precision.
What Is Inside the Report: Operational Intelligence for Real-World Decisions
This study is designed for practitioners who need to move from insight to execution. Beyond market sizing and forecast modeling, the report integrates supply-side considerations, demand-side behavior, regulatory context, and competitive signaling into a unified reference point. Key operational components include:
- Historical performance reconstruction from 2020 through 2025, establishing baseline momentum and identifying inflection points that shaped current market structure.
- Forecast modeling through 2032, with scenario-aware projections that account for material cost volatility, retail channel shifts, and product innovation cycles.
- Segment-level demand analysis across product types, materials, applications, and end users, enabling portfolio alignment and feature prioritization.
- Regional commercial assessment that contextualizes growth opportunities against distribution reach, competitive saturation, and consumer purchasing behavior.
- Competitive benchmarking of leading manufacturers and brand players, with attention to positioning, product philosophy, and channel orientation.
- Tracking of recent corporate developments, including retail partnerships, product line extensions, and limited-edition launches that reveal how established players are testing demand and refreshing brand equity.
- Macro and regulatory overlays covering material sourcing trends, consumer safety notices, tariff classification considerations, and sustainability-driven product design shifts.
By consolidating these elements, the report enables teams to answer practical questions: Which product attributes are gaining traction with premium consumers? Where do professional and personal use cases diverge in purchasing logic? How are material choices influencing both cost structure and brand perception? Which regional markets offer the most favorable balance of demand growth and competitive accessibility? The full dataset and interpretive commentary provide the resolution required to answer these questions with confidence.
Competitive Landscape: Positioning, Differentiation, and Strategic Signaling
The hairbrush market is characterized by a blend of heritage craftsmanship, salon-focused performance engineering, mass-market accessibility, and emerging OEM/ODM supply capacity. Our competitive analysis examines how leading companies are carving out distinct value propositions while navigating overlapping consumer expectations around durability, styling performance, and increasingly, sustainability.
At the premium and heritage end of the spectrum, firms such as G.B. Kent & Sons PLC and Mason Pearson continue to anchor their offerings in handmade construction, traditional techniques, and premium material selection. Their market presence underscores a persistent consumer appetite for longevity, grooming quality, and brand authenticity. Denman and Tangle Teezer represent a different strategic axis, emphasizing styling precision, detangling performance, and patented design features that address hair health and breakage reduction. Babyliss and Olivia Garden extend the professional-performance narrative into salon-grade tools, with product development focused on styling efficiency, ceramic and thermal capabilities, and innovative bristle technologies.
Mass-market and retail-oriented players, including Conair and Wet Brush, demonstrate how broad distribution, accessible price points, and periodic collaborative or patterned releases can sustain high visibility and repeat purchase flow. Wet Brush's recent retail activity illustrates this approach clearly, including a limited-edition hair accessories collection developed in partnership with Mackenzie-Childs and curated detangling brushes positioned for Target, alongside new patterns and limited-edition offerings introduced through its own retail channels. Tangle Teezer's release of a Zodiac-themed Ultimate Detangler collection further highlights how design-led product drops are being used to refresh attention and reinforce brand distinctiveness. Meanwhile, sustainability-oriented entrants and private-label enablers such as Bass Brushes and Tek Brushes reflect the growing relevance of eco-friendly bamboo, natural fiber, FSC-certified wood, and custom manufacturing services for brands seeking differentiated sourcing narratives.
On the supply and customization side, manufacturers such as Junyi Beauty and JSIU Beauty illustrate the expanding role of OEM/ODM capabilities in the category. Their full-range brush and comb portfolios, combined with customization services, support brand owners who want to move faster on product development or tailor specifications to specific retailer and consumer requirements. Creative Pro Hair Tools and Krest round out the landscape by reinforcing salon-focused and thermal-styling applications, demonstrating that professional channels continue to value performance reliability and specialized tool design.
Makeup Brushes Market
This competitive mosaic matters because it reveals where value is being created and defended. Heritage and craftsmanship support premium pricing. Detangling and breakage-reduction claims support category expansion into health-conscious grooming. Retail partnerships and design drops support volume and visibility. Custom manufacturing supports speed-to-market and brand-specific differentiation. Understanding how these strategies interact is essential for companies evaluating entry, expansion, or portfolio repositioning.
Market Dynamics: Material Shifts, Safety Oversight, and the Sustainability Imperative
Beyond competitive positioning, the market is being shaped by several overlapping dynamics that influence product design, sourcing strategy, and risk management. One of the most consequential is the accelerating integration of eco-friendly materials into brush production. Recycled plastics and FSC-certified wood are increasingly used to meet consumer preferences, and this shift is not merely cosmetic. It affects material sourcing, production workflows, brand storytelling, and retailer compliance expectations. Our report analyzes how these material transitions are influencing segment performance and what they imply for cost planning and product roadmap decisions.
Sustainability is further reinforcing premium and vegan product line extensions across major brands. Olivia Garden's launch of the NewCycle Styling Brushes collection, made with recycled materials and vegan bristles, is a clear example of how environmental positioning is being embedded into core product architecture rather than treated as a peripheral initiative. At the same time, premium and sustainable brushes are gaining traction because of rising awareness of hair health and grooming in personal care routines. Consumers are increasingly evaluating tools not just for styling outcomes, but for how they support hair integrity, comfort, and long-term care. This behavioral shift has direct implications for feature prioritization, packaging claims, and channel messaging.
Regulatory and safety considerations also remain relevant. In May 2025, the U.S. Consumer Product Safety Commission issued warnings regarding certain hair dryer brushes lacking immersion protection devices, highlighting shock hazards. While this action targeted a specific product category, it serves as a broader reminder that electrical and thermal grooming tools face heightened scrutiny. For manufacturers and brand owners, the implication is clear: safety engineering, compliance documentation, and transparent product communication are strategic assets, not administrative afterthoughts.
Trade and classification conditions add another layer of operational context. Under current tariff classification, hair brushes fall under HS 96032930, with no additional ERGA OMNES duties imposed. For companies managing cross-border sourcing, export planning, or multi-region distribution, understanding classification structure helps reduce ambiguity in cost modeling and supply chain configuration.
Hairbrush Market
Taken together, these dynamics illustrate a market in which product innovation, compliance discipline, and sustainability positioning are becoming inseparable from commercial performance. Companies that treat these factors as integrated strategic levers are better positioned to manage risk while capturing demand shifts.
Why This Research Matters for 2026 Decision-Making
The 2026 outlook is a pivotal moment for strategic planning. Historical growth has established a credible demand base, but the next phase of expansion will likely be uneven across segments, materials, and regions. Organizations that rely on broad category narratives risk misallocating resources or overlooking high-value niches. Our report is structured to help teams avoid that trap by providing a detailed, interconnected view of where growth is concentrated, how competitive advantage is being built, and which external forces are shaping sourcing and product strategy.
For product teams, the study offers a foundation for feature prioritization, material selection, and application-specific design choices. For commercial leaders, it supports channel strategy, retail partnership evaluation, and regional expansion planning. For corporate development and investor-facing teams, it provides a structured basis for assessing market concentration, competitive intensity, and long-term value creation potential. The inclusion of recent launches, partnership activity, and regulatory signals further ensures that the analysis remains current and operationally relevant rather than purely retrospective.
Access the Full Intelligence Package
The excerpt above outlines the strategic framework and market logic behind our latest Hairbrush Market research. The complete report goes much further, delivering detailed segmentation analysis, regional performance interpretation, competitive profiling, forecast breakdowns, and the underlying data needed to support investment, procurement, and product strategy decisions. For organizations that need to move from high-level awareness to precise execution, the full study provides the resolution and depth required to act with confidence.
To explore the complete dataset, segmentation insights, and competitive analysis in full, visit the source report page and access the comprehensive intelligence package designed for 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Hairbrush Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SerDes Market Hits $900M in 2025, 13.7% CAGR to $2.2B by 2032
By PW Consulting, 2026-09-16
Navigating the SerDes Market: Strategic Intelligence for 2026 and Beyond
In the rapidly evolving landscape of high-speed data transmission, the Serial Deserializer (SerDes) market stands as a critical infrastructure backbone for modern digital ecosystems. As enterprises across healthcare, automotive, and industrial sectors demand higher bandwidth and lower latency, the strategic implications of SerDes architecture have never been more pronounced. At PW Consulting, we recognize that understanding the macro-economic trajectory of this sector is not merely an academic exercise but a vital component of capital allocation and technology roadmapping for 2026 and beyond.
This article serves as an executive preview to our latest comprehensive market research release. Our objective is to outline the strategic value this intelligence offers to decision-makers who must anticipate shifts in supply chain dynamics, competitive positioning, and technological adoption rates. The data covered herein spans a robust historical period from 2020 through the base year of 2025, with a detailed forecast extension through 2032. This longitudinal view allows stakeholders to model risk and opportunity with a granularity that short-term forecasts simply cannot provide.
Macro-Economic Trajectory and Growth Indicators
The foundational metric for any strategic investment decision is a clear understanding of market scale and velocity. Based on rigorous analysis of historical performance and forward-looking indicators, the SerDes market has demonstrated a resilient growth pattern over the past half-decade. From approximately 500.0 USD Million in 2020, the market size expanded steadily to reach 900.0 USD Million by 2025. This trajectory underscores the increasing reliance on high-speed serial links as a fundamental component of modern electronic design.
Looking forward into the forecast period extending to 2032, the momentum is projected to accelerate. The market is expected to breach the 1 billion USD Million mark during 2026, reaching 1005.28 USD Million. This growth is not linear; it reflects compounding technological demands and the proliferation of connectivity-enabled devices. By the end of the forecast window in 2032, the overall market size is anticipated to reach 2200.0 USD Million.
This expansion is underpinned by a strong Compound Annual Growth Rate (CAGR). For the period covering 2026 through 2032, the analysis indicates a CAGR of 13.7 percent. This rate of growth suggests that the SerDes market is outpacing many broader semiconductor segments, driven by specific high-demand verticals. For strategists, this percentage is a key indicator of where R&D budgets should be prioritized to capture emerging value pools. It signals a market that is not only expanding but doing so at a pace that warrants aggressive attention from both chipset manufacturers and system integrators.
It is crucial for leadership teams to note that this currency-denominated revenue is tracked in USD across all units of Million. Consistency in reporting standards ensures that cross-border investments and partnerships are evaluated on a comparable basis. The data provided in our full report eliminates ambiguity, allowing CFOs and strategic planners to model revenue projections without the friction of currency conversion assumptions or unit discrepancies.
Operational Intelligence Within the Report
A market report is only as valuable as the actionable intelligence it contains. Our research goes beyond surface-level sizing to provide deep operational insights that directly impact engineering and supply chain strategy. We understand that in the semiconductor industry, the difference between success and obsolescence often lies in the details of supply chain volatility and regulatory compliance.
SerDes Market
One significant area of focus in our analysis is the impact of raw material costs on production economics. Recent industry data indicates that aluminum-based raw materials used for PCB substrates in SerDes components have incurred significant cost increases. This volatility stems from global supply chain disruptions that have persisted through 2025. For procurement officers and production managers, understanding the magnitude of this cost pressure is essential for margin protection. Our report contextualizes these material constraints within the broader manufacturing cost structure, helping organizations factor supply chain risk into their vendor selection processes.
Furthermore, the human element of semiconductor fabrication cannot be overlooked. Our analysis highlights that skilled semiconductor fabrication labor in Asia accounts for approximately 25 percent of SerDes manufacturing costs. This labor dynamic influences where companies choose to manufacture and source components. As geopolitical tensions and labor availability shift, understanding this cost composition helps firms optimize their manufacturing footprint. The report provides the necessary context to evaluate whether near-shoring or maintaining Asian-based fabrication offers better long-term value propositions given the cost structures involved.
HSMT SerDes Chip Market
Infrastructure requirements are another critical pillar of our research. Advanced data center infrastructure, particularly within healthcare facilities, requires low-latency SerDes links for real-time imaging systems. This specific technical requirement drives demand patterns that differ from standard commercial data centers. Our report dissects these infrastructure needs, allowing technology leaders to tailor their connectivity solutions to the rigorous latency and reliability standards demanded by critical sectors like healthcare imaging.
Competitive Dynamics and Market Concentration
The SerDes market is characterized by a high degree of concentration among leading players, creating a complex competitive environment where partnerships and licensing agreements are as valuable as proprietary hardware. Our analysis details a market structure where the top three entities hold a CR3 of 72.0 percent, and the top five extend this concentration to a CR5 of 78.0 percent. This level of concentration indicates significant barriers to entry and suggests that established players possess considerable leverage over pricing and technology standards.
Prominent organizations shaping this landscape include Texas Instruments, headquartered in Dallas, Texas, USA. They offer high-speed SerDes solutions such as the DS90UB954, targeting industrial, automotive, and healthcare data transmission applications. Their presence underscores the importance of versatile solutions that can span multiple verticals. Similarly, Broadcom Inc., based in San Jose, California, USA, provides products like the BCM87412 for networking and data centers, extending into healthcare systems. Their strategy highlights the intersection of networking infrastructure and specialized medical applications.
Intel Corporation, located in Santa Clara, California, USA, supplies the Intel Agilex I-Tile SerDes for high-performance data transmission in healthcare and industrial sectors. Their focus on high-performance transmission aligns with the growing demand for compute-heavy workflows. Marvell Technology, also in Santa Clara, delivers PAM4 400G SerDes solutions that support cloud, 5G, and healthcare connectivity needs. This specific technical implementation indicates a market moving toward higher density and speed protocols to handle increased data loads.
On the intellectual property front, Synopsys Inc. from Mountain View, California, licenses DesignWare 112G SerDes IP for custom semiconductor designs, including those for healthcare and medical devices. Cadence Design Systems, based in San Jose, provides SerDes PHY IP for SoC development in similar sectors. These IP licensing models represent a distinct revenue stream and competitive dynamic compared to physical component manufacturing. Lattice Semiconductor, headquartered in Hillsboro, Oregon, USA, offers an Avant platform with leading 25 Gb/s SERDES for mid-range FPGA applications, including healthcare. This demonstrates that even within FPGA markets, specialized SerDes capabilities are a key differentiator.
International players also exert significant influence. NXP Semiconductors, based in Eindhoven, Netherlands, manufactures components for automotive and healthcare data interfaces. Analog Devices, in Wilmington, Massachusetts, USA, provides high-speed solutions supporting healthcare and 5G applications. ON Semiconductor, from Scottsdale, Arizona, USA, supplies products for industrial, automotive, and medical device connectivity. Finally, STMicroelectronics, located in Geneva, Switzerland, offers solutions for automotive and healthcare sensor fusion systems. The geographic diversity of these headquarters reflects the global nature of the supply chain, even amidst concentration risks.
Regulatory Frameworks and Sector-Specific Drivers
Technology deployment does not occur in a vacuum; it is heavily influenced by regulatory environments and reimbursement structures. Our report integrates these external forces to provide a holistic view of market viability. For instance, ISO 13485 certification for SerDes components in medical devices is required for all healthcare applications. This regulatory hurdle creates a barrier to entry that favors established players with robust quality management systems. It also dictates the timeline for new product introduction in the medical sector, requiring strategists to plan for compliance lead times.
Simultaneously, reimbursement models play a crucial role in demand generation. Medicare and private payers reimburse for healthcare devices incorporating high-speed SerDes connectivity. This financial incentive effectively subsidizes the adoption of higher-cost, higher-performance connectivity solutions in the medical field. For companies targeting the healthcare vertical, understanding the alignment between reimbursement policies and hardware specifications is a key driver of commercial success. Our research highlights how these financial flows support the wider adoption of advanced SerDes architectures in life-critical systems.
These dynamics vary significantly by application focus. While the full report breaks down value by application, it is evident that sectors like Data Centers and Automotive represent substantial value pools, driving the need for robust interfaces. The interplay between regulatory compliance, reimbursement availability, and technical performance creates a complex matrix that engineers and business developers must navigate. Our analysis provides the necessary context to understand which combinations of regulation and reimbursement create the most favorable conditions for market entry or expansion.
Strategic Implications for 2026 Decision-Making
As we move into 2026, the strategic implications of these findings are profound for enterprise leadership. The projected growth to 1005.28 USD Million in 2026 and beyond suggests that SerDes technology will remain a priority investment area. Companies that delay integration or fail to secure reliable supply chains may find themselves at a competitive disadvantage as bandwidth requirements escalate.
For procurement and supply chain executives, the cost volatility associated with raw materials and labor costs necessitates a diversified sourcing strategy. Relying on a single region or supplier type exposes the organization to risks highlighted by the aluminum substrate cost increases and the significant labor cost component in Asian fabrication. Diversification and strategic inventory management become imperative to mitigate these variables.
For technology strategists and R&D leaders, the competitive landscape defined by high market concentration suggests that partnerships may be more fruitful than outright competition for new entrants. Leveraging IP cores from leaders like Synopsys or Cadence, or collaborating with established component manufacturers like TI or Broadcom, may offer faster time-to-market than attempting to develop proprietary high-speed links from scratch. The CR3 and CR5 metrics serve as a reality check on the feasibility of independent development in this saturated space.
Furthermore, the regulatory aspect regarding ISO 13485 certification cannot be an afterthought. Product roadmaps must incorporate compliance testing early in the design phase. The correlation between reimbursement policies and hardware capabilities also suggests that value propositions should be built around the performance benefits that justify higher costs and qualify for reimbursement. Marketing and sales strategies should reflect this alignment to maximize adoption rates in healthcare and other regulated sectors.
Conclusion and Access to Full Intelligence
The SerDes market is entering a phase of accelerated expansion defined by high growth rates, concentrated competition, and rigorous regulatory demands. The data points from 2020 through the 2032 forecast provide a clear narrative of a sector vital to the future of high-speed connectivity. However, the macro-level view only scratches the surface of the complexities involved in successful market participation.
To fully leverage these insights for your organization's specific context, access to the complete dataset, segmentation details, and proprietary analysis is required. Our full report offers granular breakdowns that allow for precise modeling and risk assessment tailored to your operational needs. We invite you to visit our source webpage to download the complete study. There, you will find the detailed segmentation splits and specific regional and application data that inform the broader trends discussed here, enabling you to make fully informed strategic decisions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: SerDes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AntiMicrobial Wound Dressing Market 5% CAGR to Hit $230.5M by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Antimicrobial Wound Dressing Market: Navigating Growth and Complexity in 2026
Executive Overview: The Imperative for Decision-Makers
The global landscape for antimicrobial wound dressings is undergoing a significant transformation, driven by an aging population, the rising prevalence of chronic conditions such as diabetes, and an increased emphasis on infection control within healthcare settings. For executives, investors, and strategic planners, understanding the nuances of this market is no longer optional; it is a critical component of risk management and revenue forecasting. Our latest market research provides a comprehensive 360-degree view of this sector, offering the granular intelligence required to make informed decisions throughout the 2026 fiscal year and beyond.
This report serves as a strategic compass. It moves beyond superficial industry summaries to deliver actionable insights into market sizing, competitive positioning, regulatory hurdles, and technological innovations. As we enter the forecast period, the ability to distinguish between temporary market fluctuations and long-term structural shifts will define competitive advantage. The following analysis highlights the key themes and data points encapsulated in our full study, demonstrating why this intelligence is vital for your organization's roadmap in 2026.
Market Trajectory and Revenue Potential
The financial outlook for the antimicrobial wound dressing sector indicates steady expansion over the coming years. Based on historical data from 2020 through 2025, the market has demonstrated resilience and consistent value appreciation. The base year valuation establishes a solid foundation for projecting future earnings, with the total market size reflecting the cumulative demand across various healthcare facilities and home care settings.
Our forecast model extends from 2026 to 2032, utilizing a compound annual growth rate that underscores the sector's stability. While specific regional or product-level breakdowns are reserved for the full report to maintain strategic confidentiality, the macro trajectory suggests that revenue opportunities will expand significantly. The growth is not merely linear; it is influenced by adoption rates in emerging markets and the premiumization of wound care products in established economies. Stakeholders need to understand where these value pools are accumulating to allocate resources effectively.
Historical performance data reveals a pattern of gradual increases in market valuation, punctuated by periods of accelerated adoption often linked to regulatory changes or breakthrough product launches. The forecast period anticipates this momentum to continue, suggesting that companies positioned correctly now will capture disproportionate value as the market matures. The revenue unit metrics provide a clear lens through which to evaluate potential investment returns and market entry strategies.
Competitive Landscape: Leaders and Innovators
The market structure is characterized by a mix of established multinational medtech corporations and specialized niche players. Concentration ratios indicate that a significant portion of market value is held by key incumbents, yet there remains ample room for disruption through innovation. Understanding the specific offerings and strategic moves of these core companies is essential for benchmarking and differentiation.
Major players such as Solventum, Smith + Nephew, Mölnlycke Health Care, Convatec, Coloplast, Integra LifeSciences, Urgo, and Hartmann dominate the current landscape. Each brings distinct technological advantages to the table. For instance, Solventum leverages its legacy in material science with silver-coated fiber technologies designed for infection management. Smith + Nephew continues to strengthen its portfolio with advanced silver technologies targeted at chronic and surgical wounds, emphasizing evidence-based outcomes.
Mölnlycke Health Care has carved a niche with silicone-based foam dressings that integrate antimicrobial silver, specifically addressing exuding wounds. Similarly, Convatec focuses on hydrofiber technologies impregnated with silver to manage bioburden in advanced wound care scenarios. Coloplast and Integra LifeSciences contribute through diverse portfolios that include biologics and securement dressings aimed at reducing infection risks. Urgo and Hartmann round out the competitive field with specialized alginate and silicone border dressings that cater to infected or at-risk wound profiles.
Antimicrobial Suture Market
Recent developments highlight the dynamic nature of this competition. In early 2026, strategic partnerships and regulatory milestones are reshaping the playing field. For example, collaborations aimed at expanding access in key geographic regions signal a shift towards localization and faster market penetration. Furthermore, innovation in pain management alongside antimicrobial efficacy is becoming a differentiator. Companies that successfully integrate patient comfort with infection control are likely to gain loyalty among clinicians and patients alike. Participation in major industry conferences also indicates where key players are directing their R&D focus, such as sustainability and advanced material science.
Regulatory and Reimbursement Dynamics
Navigating the regulatory environment is one of the most challenging aspects of the antimicrobial wound dressing market. Compliance requirements vary by region and product classification, impacting time-to-market and operational costs. Our report provides detailed analysis on how regulatory frameworks influence product design and commercialization strategies.
Recent regulatory signals suggest tighter oversight on certain device classifications. For instance, proposals regarding the classification of specific antimicrobial dressings under 510(k) requirements imply that manufacturers must maintain rigorous quality standards and documentation. Additionally, billing codes for impregnated gauze dressings containing iodinated agents or chlorhexidine remain critical for reimbursement under Medicare, directly affecting sales viability in the US market. Adherence to manufacturing standards such as ISO 13485 is non-negotiable for medical device production, and our research details how certification status impacts supplier selection and market confidence.
Reimbursement policies are equally influential. Changes in physician fee schedules can alter the economic calculus for healthcare providers adopting new wound care technologies. Recent final rules have reclassified certain skin substitutes and cellular tissue products, potentially affecting the pricing models for advanced antimicrobial options. Understanding these reimbursement shifts is crucial for forecasting demand and planning pricing strategies. Our report dissects these complex policy changes to help you anticipate their impact on your product pipeline and market access plans.
Segmentation and Application Drivers
The demand for antimicrobial wound dressings is driven by specific clinical needs across various wound types. While the full report contains detailed segmentation data, it is important to recognize the broad categories fueling growth. Chronic wounds represent a significant portion of the demand, with conditions such as diabetic foot ulcers and venous leg ulcers requiring prolonged treatment protocols that often incorporate antimicrobial agents to prevent infection.
Pressure ulcers and surgical or traumatic wounds also contribute substantially to volume. The choice of dressing material—whether hydrogel, foam, collagen, or alginate—depends on the wound exudate level, depth, and infection risk. Our analysis connects product attributes with clinical outcomes, helping stakeholders understand which solutions are gaining traction in specific therapeutic areas. The availability of raw materials, such as silver-impregnated non-woven fabrics and alginate fibers, remains a foundational element of supply chain stability. Monitoring these input markets is part of our broader supply chain risk assessment.
Regional variations in disease prevalence and healthcare infrastructure create distinct opportunity zones. While North America and Europe currently represent mature markets with high adoption rates of advanced dressings, Asia Pacific and other emerging regions offer growth potential as healthcare access expands. Our geographic analysis goes beyond simple revenue figures to explore the underlying drivers of adoption in each territory, including local regulatory environments and reimbursement landscapes.
Actionable Insights for the 2026 Fiscal Strategy
To capitalize on the opportunities identified in this market, organizations must move beyond passive observation. Our research provides a framework for proactive strategy formulation. We recommend that decision-makers focus on three core areas during the 2026 planning cycle.
- Supply Chain Resilience: Given the reliance on specific raw materials like silver and specialized fibers, securing stable supply lines is paramount. Our report evaluates supplier dependencies and suggests diversification strategies to mitigate risk.
- Regulatory Preparedness: With evolving classification standards and coding updates, maintaining compliance is an ongoing effort. We outline the necessary steps to align product portfolios with current and anticipated regulatory requirements.
- Innovation Alignment: The market is responding positively to products that offer dual benefits, such as infection control combined with pain management or enhanced healing times. Aligning R&D investments with these clinical demands can accelerate product uptake.
The competitive intensity measured by concentration ratios suggests that while the market has leaders, there is space for agile players to carve out niches. Success depends on precise targeting of high-growth segments and robust partnerships. Our report details the competitive moves observed in recent months, providing a playbook for how to respond to rival strategies.
Conclusion: Leveraging Intelligence for Market Leadership
The antimicrobial wound dressing market presents a compelling case for strategic investment and careful planning. The convergence of demographic trends, technological innovation, and regulatory evolution creates a complex environment where information is power. Our comprehensive market research report is designed to equip you with the specific data and analysis needed to navigate this landscape with confidence.
By accessing the full study, you will gain entry to detailed segmentation tables, forecasts tailored to specific regions and product categories, and deep-dive profiles of competitors. This is not merely a summary of past performance but a predictive tool for shaping future success. We invite you to review the complete findings to refine your strategic position and ensure your organization is prepared for the opportunities and challenges of the forecast period.
Antimicrobial Wound Dressing Market
For executives seeking to secure market share and optimize portfolio performance in 2026, the time to act on these insights is now. The data speaks clearly to the direction of the market; the strategic response must be equally decisive. Engage with our full report to transform raw data into winning strategy.
For detailed analysis of this topic, please visit the official page: Antimicrobial Wound Dressing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Blue Light Glasses Market to Hit $3.77B by 2032 with 8% CAGR
By PW Consulting, 2026-09-16
Strategic Vision 2026: Navigating the Blue Light Blocking Glasses Market Amidst Regulatory Shifts and Digital Wellness Trends
The global landscape for eyewear is undergoing a significant transformation, driven by the ubiquity of digital screens and a heightened consumer awareness of eye health. As we move into 2026, the Blue Light Blocking Glasses Market stands at a critical juncture where technological innovation intersects with complex trade dynamics. This article serves as an introduction to PW Consulting's comprehensive market research report, designed to equip industry stakeholders with the actionable intelligence needed to navigate this evolving terrain. The following analysis outlines the macroeconomic trajectory, competitive intensity, and regulatory headwinds that will define strategic decision-making in the coming year and beyond.
Market Trajectory and Growth Dynamics
Our latest analysis indicates a robust expansion phase for the blue light blocking eyewear sector. Based on a historical review spanning from 2020 to 2025 and projections extending through 2032, the market demonstrates a consistent upward trend. The revenue trajectory shows a growth from approximately 1,500 million USD in 2020 to an estimated 2,200 million USD in 2025. Looking forward, the forecast period from 2026 to 2032 suggests continued momentum, with market valuation expected to reach nearly 3,770 million USD by the end of the forecast window.
The Compound Annual Growth Rate (CAGR) during the forecast period is projected at 8.0 percent. This rate signals a healthy expansion that outpaces many traditional optical segments, underpinned by the permanent shift toward remote work, increased screen time among various demographics, and the mainstreaming of preventive health measures. For business leaders, this growth rate is not merely a statistic; it represents the speed at which market share opportunities are evolving and the urgency required to adapt product lines and distribution channels.
Strategic Implications of Market Size
The scale of this market offers ample room for diversification. However, growth is not uniform across all vectors. The increasing penetration of digital devices across all age groups suggests that demand will remain resilient, yet price sensitivity and brand differentiation will become more pronounced as the market matures. Companies that rely solely on volume without addressing specific consumer pain points regarding sleep quality, eye strain, or aesthetic appeal may find themselves squeezed by more specialized competitors.
Competitive Landscape and Key Players
The market structure is characterized by a mix of premium niche players and broader eyewear retailers integrating blue light filtering as a standard feature. Our report provides detailed profiles of the principal entities shaping this landscape. Understanding the positioning of these key companies is vital for any strategic assessment.
Corporate Profiles and Technological Differentiation
Several core companies define the current competitive boundaries. Felix Gray, headquartered in New York, positions itself in the premium segment with proprietary lens technology that claims to filter significantly more harmful blue light while maintaining lens clarity. Their strategy targets screen users focused on both eye strain reduction and sleep improvement. Similarly, Swanwick Sleep manufactures Swannies, utilizing science-backed lenses designed to block a high percentage of blue-weighted light, with a specific focus on circadian rhythm support and sleep quality.
On the technology-intensive end, GUNNAR Optiks, based in Carlsbad, specializes heavily in the gaming and computer usage niche. Their patented lens technology is designed to block a substantial portion of blue light, catering specifically to users with prolonged screen exposure. In contrast, JINS, based in Tokyo, offers a more integrated approach with JINS SCREEN lenses available on both prescription and non-prescription frames, emphasizing everyday eye strain reduction in both digital and artificial lighting environments.
The market also sees significant volume driven by affordable online retailers and optical chains. Zenni Optical, based in New Jersey, provides accessible options through their Blokz brand, incorporating polymer-based HEV filtering into standard lenses. EyeBuyDirect and GlassesUSA follow a similar direct-to-consumer or online retail model, offering customizable styles and price tiers that democratize access to blue light protection. Pixel Eyewear rounds out the competitive set with a focus on productivity, designing frames for professionals who prioritize reduced eye fatigue during work hours.
Concentration and Market Power
Our analysis highlights a moderate level of market concentration. The top three companies are estimated to hold a significant portion of the market share, while the top five expand that dominance further. This concentration suggests that while barriers to entry exist, there is still space for agile players who can identify underserved niches or offer superior value propositions. However, for larger incumbents, maintaining this share will require continuous investment in lens technology and brand loyalty programs.
UV and Blue Light Blocking Material Market
Regulatory Environment and Cost Pressures
No strategic plan for 2026 is complete without addressing the regulatory and tariff landscape. The economics of importing optical products have shifted notably recently, impacting margin structures across the supply chain. Industry sources indicate that Section 301 tariffs on Chinese imports for optical products, including blue light blocking glasses, have increased total duties on Chinese-origin frames and lenses to ranges between 27.5 percent and 33.5 percent as of March 2025.
Furthermore, additional government measures imposed in February 2025 introduced a 10 percent tariff on eyewear imports. These compounded duties directly affect the cost basis for imported goods, forcing companies to make difficult decisions regarding pricing strategies, inventory stocking, and supply chain diversification. Manufacturers relying heavily on Asian supply chains must evaluate the risk exposure of their cost structures. Successful navigation of this environment may require shifting sourcing locations, absorbing costs to maintain market share, or leveraging domestic manufacturing capabilities where feasible.
Blue Light Blocking Glasses Market
Segmentation and Demand Drivers
Understanding where demand originates is crucial for targeted marketing and product development. The market is segmented across regions, types, and applications, each with distinct growth drivers. While global expansion is evident, mature markets in North America and Europe continue to show strong demand driven by high digital penetration and disposable income. Meanwhile, the Asia Pacific region presents a high-growth opportunity fueled by increasing smartphone and computer usage rates alongside rising health consciousness.
In terms of product type, the split between non-prescription and prescription glasses reflects the dual nature of consumer demand. Non-prescription options cater to the general wellness audience seeking protection without vision correction, while prescription segments integrate blue light filtering into standard vision care, offering convenience and comprehensive eye health solutions. The application side reveals diverse use cases. Digital device users represent the largest cohort, driven by everyday screen exposure. Gamers constitute a significant specialized segment requiring high-performance lenses for prolonged sessions. Students and other categories also contribute to the demand pool, each requiring tailored messaging and product features.
Our full report delves deeper into the specific volume contributions and revenue splits of these segments without exposing the granular data here. However, it is clear that a one-size-fits-all approach is insufficient. Brands must align their inventory and marketing narratives with the specific needs of gamers, professionals, students, or general wellness consumers to maximize conversion and retention.
Operational Insight and Strategic Utility
This market research report is designed to be more than a collection of statistics. It serves as a strategic toolkit for executives, product managers, and investors. The document includes a thorough examination of supply chain dynamics, consumption patterns, and the technological benchmarks set by leading lens manufacturers. By analyzing the interplay between consumer behavior and regulatory constraints, the report offers a roadmap for risk mitigation and opportunity capture.
Key operational insights include an assessment of how tariff fluctuations impact landed costs and the subsequent pricing power of various brands. We also analyze the effectiveness of different marketing channels in reaching the core demographics, from digital-native advertising for gamers to clinical partnerships for prescription segments. The report evaluates the sustainability of current growth rates against potential market saturation points in mature regions.
Conclusion: Preparing for 2026 and Beyond
The Blue Light Blocking Glasses Market is poised for substantial growth, but the path forward is fraught with complexities. The combination of an 8.0 percent CAGR, evolving consumer expectations around health and aesthetics, and the pressure of increasing import duties creates a challenging environment for unprepared players. Strategic agility is paramount. Companies must balance the drive for volume with the necessity of margin protection in the face of tariff hikes.
Success in 2026 will belong to organizations that can accurately forecast demand shifts, optimize their supply chains against regulatory volatility, and differentiate their offerings in a crowded marketplace. Whether leveraging premium technology claims like those of Felix Gray and GUNNAR, or driving accessibility through models like Zenni and EyeBuyDirect, the strategic imperative is clarity of purpose and depth of market understanding.
This overview provides a snapshot of the market dynamics at play. To access the full depth of data, including precise segmentation revenue figures, detailed company benchmarking, and region-specific forecasts, we invite you to explore the complete PW Consulting market research report. This intelligence is essential for crafting a resilient strategy that capitalizes on the opportunities of the next forecast period while safeguarding against emerging risks.
For detailed analysis of this topic, please visit the official page: Blue Light Blocking Glasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


