



Category: Healthy Lifestyle
PW Consulting: Novel Drug Delivery Market to Hit $213.89B by 2032, CAGR 5.7%
By PW Consulting, 2026-09-16
Navigating the Next Frontier: Strategic Insights into the Novel Drug Delivery Systems Market for 2026 and Beyond
The pharmaceutical landscape is undergoing a paradigm shift, driven by the urgent need to enhance patient compliance, improve therapeutic efficacy, and enable decentralized care models. At the forefront of this transformation is the Novel Drug Delivery Systems Market. As we move through 2026, this sector represents more than just technological innovation; it is a critical battleground for competitive advantage, portfolio optimization, and long-term revenue stability. Our latest comprehensive market research report, "Novel Drug Delivery Systems Market: Strategic Forecast 2026–2032," provides the intelligence necessary for stakeholders to navigate this complex environment.
This article serves as a strategic primer to the full study, outlining the macroeconomic trajectory, competitive dynamics, and structural challenges that define the industry. While visibility into high-level trends is essential, the granularity required for actionable decision-making demands deeper access. The following analysis highlights the strategic value embedded within our full dataset, helping executives understand where to focus resources for maximum impact.
Worldwide Novel Vaccine Delivery Systems Market
Macroeconomic Trajectory and Growth Dynamics
Understanding the top-line market potential is the first step in strategic planning. The Novel Drug Delivery Systems Market has demonstrated resilience and consistent expansion over the past decade, transitioning from a niche interest to a core component of pharmaceutical value chains. Our analysis of historical performance from 2020 through 2025 reveals a steady upward curve, culminating in a robust market valuation at the end of the base year. This historical momentum sets the stage for the forecast period, where compound growth is expected to accelerate as technologies mature and regulatory pathways become clearer.
For 2026, the market is positioned to cross significant thresholds. The initial forecast year marks a transition point where early adopters begin to reap returns on substantial research and development investments made during the previous lifecycle. Looking further ahead to 2032, the projection indicates sustained expansion, suggesting that novel delivery mechanisms will not remain a supplemental strategy but will instead become integral to next-generation therapeutics. The Compound Annual Growth Rate (CAGR) calculated for the forecast period underscores a moderate yet reliable growth trajectory, characteristic of a maturing high-value sector.
However, aggregate figures only tell part of the story. The true strategic opportunity lies in understanding how this growth is distributed across segments, geographies, and technology types. Market concentration remains high, indicating that skimming strategies require precise positioning rather than broad market appeals. For detailed breakdowns of revenue pools by specific technology type, application area, product form factor, and regional hubs, our full report provides the segmented revenue tables necessary for accurate bottom-up modeling.
Novel Drug Delivery Systems Market
Segmentation: Where Value is Concentrated
Strategic resource allocation depends on identifying high-value niches. The market is fragmented across various delivery technologies and therapeutic applications, each with distinct adoption curves and reimbursement challenges. In our full research study, we dissect the market into detailed segments to reveal where profit pools are deepest and competition is most ferocious.
- By Technology Type: Controlled release and targeted delivery systems continue to dominate the value chain, reflecting the industry's focus on pharmacokinetic optimization. However, emerging categories such as transdermal and inhalation systems are gaining traction due to their alignment with home-care trends.
- By Therapeutic Application: Chronic disease management represents the largest revenue driver. Oncology remains a critical pillar due to the need for precise dosing and reduced systemic toxicity. Cardiovascular and diabetes segments follow closely, driven by the demand for patient-friendly administration methods that improve adherence.
- By Product Form: The shift from traditional injectables toward advanced carriers like liposomes and nanoparticles is evident. Microspheres and patches are also carving out significant shares, particularly in markets demanding sustained release profiles.
- By Region: Established markets in North America and Europe continue to hold substantial revenue share, leveraging mature regulatory frameworks and high healthcare expenditure. Meanwhile, the Asia Pacific region presents a high-growth opportunity, fueled by generic formulation advancements and increasing local manufacturing capabilities.
While these categories provide a framework, the specific revenue contributions, growth rates, and relative market shares for each segment are detailed exclusively in the downloadable dataset. Accessing these specific figures allows firms to benchmark their pipeline against the most lucrative segments and identify white spaces before competitors do.
Competitive Landscape and Innovation Hubs
The market is characterized by a mix of established pharmaceutical giants and agile technology specialists. Our competitive analysis maps the strategic moves of key players who are reshaping the delivery ecosystem through acquisitions, partnerships, and novel product launches. Success in this environment requires more than just product efficacy; it requires connectivity, patient-centric design, and robust supply chain resilience.
Technology Enablers and Specialists: Companies like Satio, Inc. are pushing the boundaries of home-based care. Their Digital SatioRx system exemplifies the trend toward telehealth-enabled settings, utilizing a low-cost, motor-driven applicator with hollow microneedle cartridges for intradermal delivery. This approach aligns with broader regulatory pushes, such as ARPA-H SBIR contracts, which support the development of novel intradermal systems to enable home-based care with reduced costs. Similarly, ZIM Laboratories Limited focuses on proprietary technology-based solutions for oral formulations, including taste-masked powders and oral thin films for sustained release, addressing compliance issues in generic markets. SQ innovation contributes to the wearable device landscape with reusable infuser systems for subcutaneous administration of heart failure drugs.
Big Pharma and Biologics: Established players are leveraging novel delivery to extend the lifecycle of blockbuster therapies. Johnson & Johnson has been active with IMAAVY™, a monoclonal antibody approved for subcutaneous administration in generalized myasthenia gravis. In 2025, they secured FDA approval for this formulation, and by early 2026, they submitted supplemental applications for additional indications like warm autoimmune hemolytic anemia. Argenx is similarly expanding its footprint with FcRn blocker monoclonal antibodies, utilizing hyaluronidase for subcutaneous delivery. Recent approvals in 2026 have expanded label indications to include all adult patients with generalized myasthenia gravis, signaling strong commercial momentum.
Manufacturing and Digital Integration: The integration of digital health with drug delivery is a key differentiator. Merck KGaA recently received recognition for a connected autoinjector system that integrates smart injection devices with cloud-based data and patient mobile apps. This convergence of hardware and digital monitoring addresses payer resistance by generating real-world data to support coverage decisions. Bayer AG is exploring cellular therapies using implantation techniques for Parkinson's disease, highlighting the diversification into cell-based delivery methods.
The competitive intensity is underscored by high market concentration levels. A small number of entities control a significant portion of the market value, making market entry challenging without distinct technological advantages or strategic partnerships. Our full report profiles these companies in detail, analyzing their pipeline strategies, recent developments, and potential market share trajectories.
Industry Dynamics and Structural Challenges
Navigating the growth trajectory requires a clear understanding of the headwinds and tailwinds influencing market expansion. Our analysis identifies several critical dynamics that will shape decision-making in 2026 and beyond.
Regulatory Environment: The regulatory landscape is becoming more accommodating for innovation, yet complexity remains. In 2025, FDA novel drug approvals included dozens of new drugs, with multiple novel delivery systems advancing through priority review designations and accelerated pathways. This suggests a favorable environment for well-prepared submissions. However, regulatory clarity varies by region and technology type, requiring nuanced go-to-market strategies.
Reimbursement and Evidence Generation: Payers are increasingly resistant to reimbursing newer platforms without strong clinical evidence. The sector analysis indicates that real-world data is becoming a prerequisite for coverage decisions regarding advanced delivery systems. Companies must plan for robust post-market surveillance and data generation to ensure commercial viability. High development spending and specialized materials also result in elevated production costs compared to conventional formulations, pressuring margins unless premium pricing can be justified.
Supply Chain and Cost Pressures: Global supply disruptions and API availability challenges have caused backlogs impacting the production and availability of novel drug delivery systems. These logistical constraints can delay launches and increase operational costs. Firms must evaluate supply chain resilience as part of their strategic planning, considering geographic diversification and inventory management strategies.
Strategic Imperatives for 2026 Decision-Makers
As organizations plan their moves for the remainder of the decade, several strategic imperatives emerge from our research. First, investment in patient-centric delivery technologies that enable home care and improve adherence is likely to yield higher returns as healthcare systems shift toward value-based care. Second, digital integration is no longer optional; connected devices that provide data feedback loops will be critical for satisfying payer requirements and differentiating products. Third, collaboration between technology specialists and pharmaceutical developers will be essential to navigate the high costs and regulatory hurdles associated with novel platforms.
The window for establishing market leadership in specific niches is narrowing. With market concentration remaining high and major players actively expanding their indications and technologies, late entrants face significant barriers. Early movers who secure intellectual property, establish reimbursement pathways, and build supply chain resilience will be best positioned to capture the projected growth through 2032.
Accessing Detailed Intelligence
This overview provides a high-level strategic context, but effective execution requires granular data. To support precise financial modeling, competitive benchmarking, and segmentation analysis, organizations need access to the full dataset underlying this study. Our complete report offers detailed revenue figures, CAGR calculations for every sub-segment, and deep-dive profiles of key market players and their specific technologies.
For leaders ready to translate market intelligence into actionable strategy, the full "Novel Drug Delivery Systems Market: Strategic Forecast 2026–2032" study is available for review. Secure access to the complete database to unlock the specific numbers and insights required to drive your enterprise forward in this evolving landscape.
For detailed analysis of this topic, please visit the official page: Novel Drug Delivery Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ursodeoxycholic Acid Market to Reach $1.1B by 2032 with 10.2% CAGR
By PW Consulting, 2026-09-16
Navigating the Ursodeoxycholic Acid Drug Product Market: Strategic Intelligence for 2026 and Beyond
The global landscape for hepatology therapeutics is undergoing a period of significant recalibration, driven by evolving regulatory frameworks, patent expirations, and a growing prevalence of chronic liver conditions. At the center of this shift stands Ursodeoxycholic Acid (UDCA), a compound that has long maintained its position as a foundational therapy. For pharmaceutical executives, investors, and strategic planners, understanding the trajectory of this market is no longer optional; it is a critical component of portfolio optimization and competitive positioning. Our latest comprehensive market research report offers a granular examination of the UDCA drug product landscape, designed specifically to equip decision-makers with the actionable intelligence required to navigate the complexities of 2026 and the subsequent forecast period through 2032.
A Market on a Defined Growth Trajectory
The macroeconomic signals for the UDCA drug product market are unmistakable. Drawing on historical data spanning from 2020 through 2025, our analysis tracks a consistent upward arc in global revenue, measured in millions of US dollars. The baseline established in recent years reflects a compound annual growth rate that underscores sustained demand across multiple therapeutic areas. As we pivot into the forecast window of 2026 to 2032, the projection indicates a robust expansion that will reshape revenue pools and alter the calculus for market entry, capacity planning, and partnership strategies.
This growth is not merely a function of population expansion or generic substitution. It is being propelled by a confluence of factors: the chronic nature of primary biliary cholangitis, which demands long-term patient adherence and stable reimbursement pathways, and the ongoing utilization of UDCA as a first-line intervention under established FDA guidelines. Furthermore, the anticipated dominance of the generics segment, expected to command a substantial share of the market in 2026 following a wave of patent expirations, introduces a new dynamic of price pressure and volume-driven economics. Understanding how these forces interact requires more than top-line figures; it demands a dissection of the underlying structural drivers that our report meticulously maps out.
What Is Inside: A Blueprint for Operational and Strategic Execution
Our market research is structured to move beyond abstract trends and deliver concrete, operational utility. The report provides a multi-dimensional view of the UDCA drug product ecosystem, encompassing historical performance, forward-looking projections, and a detailed breakdown of the competitive and regulatory environment. Below is a preview of the core components that will enable your organization to translate market intelligence into decisive action.
- Historical and Forecast Revenue Analysis: A year-by-year examination of global revenue performance from 2020 through 2032, highlighting inflection points, growth acceleration, and the projected scale of the market as it approaches the end of the decade. Readers will gain clarity on the magnitude of the opportunity and the temporal windows most relevant to investment and capacity decisions.
- Segmentation Dynamics: A deep dive into the primary axes that define the market: dosage form, therapeutic application, and geographic distribution. The report evaluates how tablets and capsules compete for share, how indications such as gallstones and primary biliary cholangitis drive distinct demand profiles, and how regional markets are evolving in response to local regulatory, reimbursement, and supply chain conditions.
- Competitive Landscape and Corporate Profiles: An in-depth assessment of the leading integrated producers, generic suppliers, and specialized manufacturers shaping the market. Each profile includes geographic footprint, product positioning, and strategic implications for partnership, acquisition, or competitive defense.
- Recent Developments and Regulatory Intelligence: A curated timeline of pivotal events, including accelerated approvals for combination therapies targeting primary biliary cholangitis, new generic product launches, and updates to reimbursement and standard-of-care guidance. These developments are analyzed for their near-term and medium-term impact on market dynamics.
- Industry Context and Structural Forces: An examination of the reconcentration metrics that reveal the degree of market consolidation, alongside an assessment of supply chain considerations, raw material dynamics, and the reimbursement environment that underpins long-term patient access.
The Competitive Arena: Key Players and Strategic Positioning
The UDCA drug product market is characterized by a mix of established integrated manufacturers, global generic giants, and regional specialists. Our report provides detailed profiles of the companies that are actively shaping supply, pricing, and innovation within this space, offering a framework for evaluating competitive threats and partnership opportunities.
Among the most prominent participants is ICE Pharma, an Italy-based integrated producer that has built a significant presence in UDCA bile acid derivatives. With manufacturing capabilities spanning Europe, Latin America, Asia, and Oceania, and a distribution network that reaches over fifty countries, ICE Pharma exemplifies the globalized, vertically integrated model that can command respect in both branded and generic segments. For organizations evaluating supply chain resilience or seeking regional market access, ICE Pharma's footprint offers a case study in scale and geographic diversification.
Teva Pharmaceuticals, headquartered in Israel, represents a major force in the generic UDCA space, with an active supply of USP tablets and capsules. As one of the world's largest generic pharmaceutical companies, Teva's involvement signals both the maturity of the UDCA market and the ongoing relevance of high-volume, cost-competitive manufacturing. Similarly, Sun Pharmaceutical Industries Ltd, a leading Indian generic supplier, has reinforced its commitment to the market through recent product launches, underscoring the strategic importance of India as a production hub and the intensifying competition among generic manufacturers.
Daewoong Pharmaceutical, based in South Korea, adds another dimension to the competitive landscape as a supplier of UDCA drug products, including once-daily formulations. Formulation innovation and patient-centric dosing regimens are increasingly important differentiators, and Daewoong's presence highlights the potential for regional manufacturers to compete on convenience and adherence. In India, Mankind Pharma and Octavius Pharma Pvt. Ltd continue to be active manufacturers and suppliers of UDCA tablets, capsules, and API, reflecting the dense and competitive Indian manufacturing ecosystem that plays a critical role in global supply. Meanwhile, in the United States, Willow Birch Pharma and Lannett Company serve as active suppliers and manufacturers of generic UDCA products, catering to domestic demand and navigating the nuances of the US regulatory and reimbursement environment.
Ursodeoxycholic Acid Drug Product Market
Our report goes beyond company descriptions to analyze how these players interact within a market that, based on our concentration metrics, exhibits a moderate level of consolidation. With a focused analysis of market share distribution and the strategic implications of competitive density, decision-makers can better assess barriers to entry, the feasibility of niche positioning, and the potential for consolidation or partnership-driven growth.
Market Dynamics: Regulation, Reimbursement, and Supply Chain Forces
The structural underpinnings of the UDCA market are defined by a set of regulatory and reimbursement realities that create both stability and pressure. UDCA remains the standard first-line therapy for primary biliary cholangitis under FDA guidance, with no substantive changes reported through 2025. This continuity reinforces the compound's central role in treatment protocols and supports predictable demand over the long term. At the same time, the chronic nature of the disease drives sustained patient adherence, which in turn bolsters the case for consistent reimbursement coverage. For market participants, this dynamic translates into a durable revenue base, but also into heightened scrutiny of pricing, access, and the value proposition relative to emerging adjunct therapies.
On the supply side, the generics segment is anticipated to hold a significant majority share of the market in 2026, a shift driven by patent expirations on branded products and the resulting price pressure. This transition has profound implications for manufacturing strategy, margin expectations, and competitive differentiation. Companies that can optimize production efficiency, secure reliable API sourcing, and navigate regulatory compliance with agility will be best positioned to capture volume in a increasingly price-sensitive environment. Our report explores these supply chain and raw material dynamics in detail, offering insights into the operational levers that can determine success as the market tilts further toward generics.
Recent regulatory and commercial developments add further texture to the landscape. In 2024, the FDA granted accelerated approval for elafibranor for primary biliary cholangitis in combination with ursodeoxycholic acid, and shortly thereafter, accelerated approval for seladelpar in combination with ursodeoxycholic acid. These milestones, achieved by major pharmaceutical companies, signal a growing emphasis on combination and adjunct treatment paradigms for primary biliary cholangitis. While UDCA remains the foundational therapy, the emergence of combination approaches could reshape treatment pathways, create new co-marketing opportunities, and influence the competitive positioning of standalone UDCA products over time. Additionally, the recent launch of generic UDCA drug products by Sun Pharmaceutical Industries Ltd in late 2024 illustrates the ongoing pace of generic entry and the need for continuous monitoring of product availability, pricing shifts, and geographic rollout strategies.
Strategic Implications for 2026 Decision-Making
As organizations prepare for 2026, the UDCA drug product market presents a blend of opportunity and complexity that demands a disciplined strategic approach. The forecast period through 2032 suggests a market that will continue to expand materially, but the distribution of that growth across dosage forms, indications, and regions will not be uniform. Companies that rely on aggregate market figures alone risk missing the granular shifts that determine whether a product, a market entry, or a partnership will succeed or underperform.
Ursodeoxycholic Acid Market
For manufacturers, the anticipated dominance of the generics segment in 2026 underscores the importance of cost leadership, supply chain robustness, and regulatory agility. For branded and specialized players, the opportunity may lie in formulation differentiation, patient support programs, combination strategies, or targeted regional expansion where competitive density is lower. For investors and strategic advisors, the concentration metrics and competitive profiles provide a lens through which to evaluate market access, barriers to entry, and the potential for consolidation or vertical integration.
Reimbursement dynamics and the chronic disease context further emphasize the need for a long-term perspective. Patient adherence and sustained coverage create a relatively stable demand floor, but they also heighten the importance of demonstrating value, managing pricing expectations, and aligning with payer and provider priorities. The introduction of combination therapies and the evolving treatment landscape for primary biliary cholangitis add another layer of strategic consideration, as organizations must anticipate how new regimens may complement, compete with, or redefine the role of UDCA in standard care.
Why Comprehensive Intelligence Matters
The decisions that will shape your organization's position in the UDCA drug product market over the next several years depend on a clear, evidence-based understanding of the forces at play. Aggregate trends provide direction, but they do not replace the need for detailed segmentation, competitive profiling, regulatory tracking, and scenario analysis. Our full market research report delivers that depth, equipping stakeholders with the data and context required to make informed choices about capacity, product strategy, geographic focus, partnership structures, and competitive responses.
We invite you to access the complete report to explore the full scope of our analysis, including the specific regional and application-level insights, detailed company assessments, and forward-looking projections that will support your strategic planning for 2026 and beyond. In a market defined by both continuity and change, the organizations that thrive will be those that invest in the intelligence needed to act with precision, anticipate shifts before they become disruptive, and align their capabilities with the most promising avenues for growth.
For detailed analysis of this topic, please visit the official page: Ursodeoxycholic Acid Drug Product Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Modular Carpet Tiles Market to Reach $17.29B by 2032, Growing at 5.12% CAGR
By PW Consulting, 2026-09-16
Navigating the Modular Carpet Tiles Market: Strategic Intelligence for 2026 and Beyond
The global flooring landscape is undergoing a structural transformation, driven by evolving workplace requirements, stringent sustainability mandates, and a renewed emphasis on circular material flows. Within this complex environment, modular carpet tiles have emerged as a critical solution for facility managers, architectural specifiers, and commercial real estate developers. As organizations align their procurement strategies with 2026 operational targets, understanding the precise trajectory of this segment is no longer optional. This executive overview introduces our latest market research on the Modular Carpet Tiles Market, outlining why a data-driven, forward-looking intelligence framework is essential for overcoming near-term volatility and capturing long-term value.
A Market Reaching a Strategic Inflection Point
Drawing on six years of historical tracking and a seven-year forward projection, our analysis reveals a market exhibiting consistent, compounding expansion. Between 2020 and 2025, global revenue crossed significant thresholds, with the baseline year registering $12.15 billion. The momentum continues unabated: 2026 is positioned at $13.01 billion, followed by a steady climb that places the market at $17.29 billion by 2032. This trajectory translates to a forecast compound annual growth rate of 5.12 percent, a figure that underscores durable demand rather than cyclical recovery.
For executives, these numbers carry more than macroeconomic relevance. They signal a market where growth is being unevenly distributed, shaped by product architecture, regional procurement policies, and the accelerating institutionalization of environmental product declarations. The reality is that aggregate expansion masks divergent performance across flexible and rigid formats, across commercial and residential end-use channels, and across regulatory jurisdictions that increasingly dictate which suppliers can scale efficiently. Navigating this landscape requires a granular comprehension of where capital is being deployed, which specifications are winning specification approvals, and how trade frameworks are recalibrating cost structures.
What Our Research Delivers: Operational Intelligence for 2026 Decision-Making
The full study is structured to convert macro indicators into actionable strategic playbooks. Rather than presenting static snapshots, the report maps the operational levers that will define competitive positioning over the 2026–2032 horizon. Key components include:
- A comprehensive sizing and forecasting model that decomposes historical performance and projects forward revenue across the entire modular carpet tiles ecosystem, enabling demand planning and capacity allocation with precision.
- Deep-dive segmentation analysis that evaluates product architecture, end-use deployment patterns, and regional consumption profiles, allowing leadership teams to isolate the highest-yield growth corridors and adjust portfolio emphasis accordingly.
- A competitive benchmarking framework that profiles major manufacturers, dissects their product pipelines, sustainability positioning, and commercial execution strategies, giving executives a clear view of where market share is being contested.
- A regulatory and certification tracker that monitors environmental product declarations, cross-border duty structures, and countermeasure tariffs, helping procurement and compliance teams anticipate cost shifts and specification friction before they impact margins.
- Sustainability and circularity mapping that evaluates advances in bio-based backings, recycled content integration, and take-back programs, aligning product development roadmaps with the specifications now dominating institutional tenders.
- Scenario-based guidance for 2026, offering leadership teams tested frameworks to adapt pricing, supply chain routing, and regional market entry strategies amid shifting trade policies and evolving end-user expectations.
Each section is engineered to support concrete decisions: whether evaluating a manufacturing expansion, repositioning a commercial sales force, adjusting logistics partnerships, or preparing for tender specifications that now require verified lifecycle documentation.
Carpet Tiles Market
Competitive Landscape: How Leading Players Are Positioning for the Next Cycle
The modular carpet tiles arena is characterized by a concentrated but highly dynamic competitive field. Our analysis tracks a core cohort of established manufacturers whose product architectures, sustainability commitments, and regional footprints actively shape market directionality. Understanding their strategic posture is essential for any organization planning capacity, pricing, or specification targeting in 2026.
Interface, headquartered in Atlanta, Georgia, continues to anchor its portfolio on modular carpet tiles featuring TacTiles installation systems and CQuest Bio backing technologies. The company’s operational philosophy is tightly coupled with its Mission Zero commitments and the ReEntry recycling program, positioning environmental accountability as a core commercial differentiator rather than a compliance add-on. Mohawk Industries, also based in Calhoun, Georgia, deploys modular offerings across the EcoFlex ONE, Matrix, and NXT lines, pairing commercial resilient flooring expertise with multiple optimized environmental product declarations that streamline specification in regulated procurement environments. Tarkett, operating from Méru, France, extends its modular carpet tile and plank portfolio with the Quiet Edit collection and circular solutions incorporating DESSO backing, specifically engineered for open-plan commercial spaces where acoustic performance and material circularity intersect.
EF Contract Flooring, based in the United States, manufactures the Advance and Nexus modular carpet tile families, utilizing PVC backing systems while maintaining EPD-compliant sustainable pathways that align with institutional procurement thresholds. Tapibel, headquartered in Belgium, emphasizes design flexibility and standardized 50x50 cm formats, delivering sustainable collections that bridge commercial and residential applications without sacrificing specification versatility. Shaw Contract, rooted in Dalton, Georgia, complements its modular carpet tile product line with broadloom options, reinforcing a USA-made performance flooring narrative that resonates with commercial buyers prioritizing supply chain reliability and localized manufacturing.
Recent corporate activity underscores how rapidly competitive positioning is evolving. In mid-2025, EF Contract Flooring refreshed the Nexus modular carpet tile environmental product declaration, updating version and validity dates to maintain compliance through 2029. Shortly thereafter, Interface issued a tufted modular carpet tile declaration for CQuest Bio backing, securing validity through 2030 under a recognized European certification body. EF Contract Flooring also advanced its Advance modular carpet tile documentation with an EPD appendix that remained active well into 2025. By early 2026, Tapibel published its 2026–2027 collection catalog, reinforcing its focus on sustainable modular formats and forward-looking design portfolios.
These movements are not isolated product announcements. They reflect a broader industry recalibration where documented lifecycle performance, material transparency, and portfolio agility are becoming decisive factors in specification wins and regional expansion. The full report quantifies how these developments influence share shifts, pricing tolerance, and the speed at which competitors can capture high-value commercial tenders.
Market Dynamics: Regulation, Certification, and the Redefinition of Trade Flows
The operational environment for modular carpet tiles is being reshaped by a convergence of policy instruments and certification requirements that directly affect cost structures, market access, and specification velocity. Our research integrates these dynamics into a cohesive framework so that executives can anticipate disruption rather than react to it.
Trade policy has emerged as a particularly sensitive variable for North American and cross-border supply chains. Current guidance confirms that US-origin modular carpet tiles classified under HS 5704 can qualify for a zero percent duty rate when imported into Canada under CUSMA/USMCA provisions, provided they satisfy applicable rules of origin. Yet this advantage operates alongside countermeasure measures: Canada has applied a temporary 25 percent tariff on certain US carpets, effective from March 2025. For manufacturers and distributors, this dual reality creates a complex compliance overlay where product classification, country of origin documentation, and final destination routing can materially alter landed cost and margin predictability.
Modular Carpet Tiles Market
Simultaneously, environmental product declarations have transitioned from voluntary differentiation to baseline expectation. Multiple manufacturers updated or issued EPDs throughout 2025, including Interface’s CQuest Bio backing declaration and EF Contract Flooring’s Nexus modular documentation. In Europe, Interface modular carpet tiles are now declared under EN 15804+A2, with issue dates tracked through September 2025. This regulatory and certification cadence matters because it determines which suppliers can efficiently participate in public tenders, institutional fit-outs, and corporate sustainability programs that increasingly demand verified environmental data as a precondition for evaluation.
Beyond compliance, product innovation continues to align with changing spatial requirements. Tarkett’s Quiet Edit carpet tile collection, for example, leverages repurposed materials aesthetics to serve commercial open spaces, reflecting a broader shift where visual identity, acoustic performance, and circular content are evaluated together during specification. These dynamic layers—trade rules, certification timelines, and product narrative evolution—are mapped in detail within the report, with scenario analysis illustrating how shifts in any one variable can cascade through pricing, share, and regional allocation strategies.
Why 2026 Demands a Different Decision Framework
The 2026 outlook is not simply another year in a growth curve. It represents a period in which historical assumptions about demand uniformity, sourcing flexibility, and specification tolerance are being tested simultaneously. Organizations that rely on aggregated market narratives will miss the structural divergences that determine actual performance. The modular carpet tiles market is expanding, but the value creation is increasingly tied to identifiable drivers: documented environmental performance, adaptive product formats, and supply chains capable of navigating overlapping trade and certification requirements.
This report is designed to give leadership teams a clear, quantitative, and strategically actionable foundation. It connects the $13.01 billion entry point of 2026 to the broader 2032 trajectory of $17.29 billion through a disciplined analytical lens, while deliberately preserving the detailed regional, application, and product-level breakdowns for the full intelligence package. That intentionality reflects how high-stakes decisions are made: executives need the directional confidence that the headline numbers provide, but they also require the granular evidence that supports resource allocation, partnership selection, and market-entry sequencing.
Access the Complete Strategic Intelligence
For senior executives, procurement leaders, and strategy teams preparing for the 2026–2032 cycle, the full study delivers the depth required to move from observation to execution. It provides the segmented forecasting detail, competitive scenario mapping, regulatory and certification tracking, and sustainability alignment analysis needed to shape pricing strategy, portfolio prioritization, and regional expansion plans with confidence.
To request the complete Modular Carpet Tiles Market research and gain access to the full dataset, segmentation breakdowns, and proprietary competitive assessments, visit the official research portal. The complete report is structured to serve as a decision-ready intelligence asset, enabling your organization to act on the market’s direction with precision rather than assumption.
For detailed analysis of this topic, please visit the official page: Modular Carpet Tiles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Poultry Breeding Equipment Market to Hit $609.8M by 2032 at 5.54% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the Poultry Breeding Equipment Market: A 2026 Outlook
The global poultry industry stands at a critical inflection point. As protein demand scales and production systems modernize, the machinery underpinning breeding operations has evolved from a operational necessity to a strategic asset. For executives, investors, and supply chain leaders operating in animal agriculture, understanding the trajectory of poultry breeding equipment is no longer optional. It is a prerequisite for capital allocation, competitive positioning, and long-term resilience. This industry insight introduces our latest comprehensive market research, designed specifically to equip decision-makers with the analytical rigor required for 2026 planning and beyond.
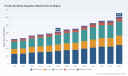
Poultry Breeding Equipment Market
Why 2026 Demands a Reset in Equipment Strategy
The past half-decade has reshaped the economics of poultry breeding. Historical performance from 2020 through 2025 demonstrates a consistent upward trajectory, with total market valuation climbing from 321.5 million USD to 420.0 million USD. This growth was not merely cyclical; it reflects structural shifts in automation adoption, biosecurity prioritization, and the consolidation of breeding operations around standardized, high-throughput environments. Looking forward, the forecast period spanning 2026 to 2032 projects a compound annual growth rate of 5.54 percent. By the close of the forecast window, market revenue is expected to surpass 600 million USD.
These figures are more than macroeconomic indicators. They signal a maturing equipment ecosystem where incremental efficiency gains translate directly into margin protection. Flocks are growing larger, turnaround cycles are tightening, and regulatory scrutiny around disease control has intensified. Equipment procurement decisions made in 2026 will lock in operational characteristics for the next seven to ten years. A feeder system, climate control array, or incubation line selected today dictates throughput capacity, labor dependency, and vulnerability to biological stressors. Strategic buyers must therefore evaluate equipment not as isolated capital expenditures, but as integrated components of a long-term production architecture.
What This Research Delivers: Operational Intelligence Over Abstract Projections
Our market study is structured to bridge the gap between high-level industry narratives and floor-level execution. Rather than offering a single growth curve, the report deconstructs the market across multiple analytical dimensions, each calibrated to answer specific strategic questions. The segmentation framework examines equipment categories including incubation systems, hatching infrastructure, and breeding management platforms, allowing readers to isolate capital intensity, technology readiness, and adoption velocity within each functional area. Application-level analysis further distinguishes between broiler breeding and layer breeding operations, acknowledging that feed conversion targets, cycle lengths, and environmental control requirements diverge significantly between the two production models.
Regional dynamics are mapped with equal precision. The research captures how procurement patterns, infrastructure maturity, and policy environments differ across major geographic corridors. Readers will find contextual guidance on where equipment demand is being pulled by capacity expansion, where it is being pushed by modernization of legacy facilities, and where regulatory or logistical friction is reshaping procurement timelines. This geographic lens is essential for manufacturers evaluating market entry, distributors planning inventory positioning, and end-users benchmarking regional best practices against their own operational baselines.
Beyond segmentation, the report integrates forward-looking modeling that stress-tests growth assumptions against plausible macroeconomic and industry-specific variables. Sensitivity scenarios address fluctuations in feed input costs, shifts in labor availability, and the pace of automation penetration across different farm sizes. By presenting these scenarios side by side, the study enables leadership teams to identify which equipment investments remain robust under downside conditions and which carry elevated exposure to external shocks.
Competitive Landscape: Differentiation, Velocity, and Strategic Positioning
The poultry breeding equipment sector is characterized by a concentrated yet highly active competitive field. Our analysis tracks the strategic postures of leading manufacturers whose product portfolios and deployment footprints shape market standards. Roxell, headquartered in Belgium, has carved a specialist position through automated feeding, drinking, nesting, and climate systems tailored specifically for broiler breeder environments. Big Dutchman, based in Germany, operates as a global leader in smart poultry production equipment, offering integrated feeding, housing, and climate control solutions that emphasize data connectivity and breeder management efficiency. VAL-CO, operating from the United States, focuses on watering systems, feeding architecture, and environmental control equipment designed for the practical demands of commercial breeder farms.
The competitive field also includes Facco from Italy, which provides complete turnkey poultry equipment solutions encompassing breeding systems and integrated farm layouts. TEXHA, based in Slovakia, manufactures both cage-based and cage-free equipment configurations, reflecting the industry's ongoing navigation between conventional and alternative housing philosophies. Hightop Group, headquartered in China, has expanded its footprint as a manufacturer of fully automatic poultry farming equipment, including dedicated breeder systems that combine scale economics with automation features. Together, these players illustrate a market where differentiation emerges from engineering specialization, regional service networks, and the ability to package equipment into cohesive operational ecosystems rather than standalone machines.
Recent corporate activity underscores the pace of strategic execution. In March 2025, Big Dutchman completed the installation of comprehensive poultry production systems at a Hungarian broiler breeder farm, a deployment that highlights the industry's preference for integrated solutions capable of streamlining breeder management across multiple production variables. By March 2026, the same company showcased its newest equipment innovations at the PEAK trade show powered by the Midwest Poultry Federation, signaling continued investment in product iteration and direct engagement with North American procurement audiences. Meanwhile, Facco confirmed its attendance at VIV Europe 2026 in Utrecht, Netherlands, positioning itself to present the latest poultry equipment developments to a concentrated European buyer base. These events are not isolated press items; they are indicators of where engineering priorities are being demonstrated, where sales channels are being reinforced, and how manufacturers are aligning product roadmaps with regional demand clusters.
Regulatory Forces and Biosecurity as Equipment Design Drivers
Equipment selection in poultry breeding cannot be divorced from the regulatory and biosecurity environment. The National Poultry Improvement Plan establishes sanitation procedures for hatchery equipment, including incubators and hatchers, to ensure the integrity of disease-free breeding stock. Under these standards, hatchery equipment must be cleaned and disinfected after each set or transfer, reinforcing a operational reality that equipment design, material selection, and access geometry directly influence compliance feasibility.
For procurement teams, this translates into a practical evaluation criterion: how readily can a system be sanitized without compromising throughput, and how do design choices affect the labor and chemical costs associated with routine disinfection protocols? Equipment that integrates smooth surfaces, removable components, and clear access pathways reduces the friction of compliance, while systems that complicate sanitation routines introduce hidden operational costs and biosecurity risk. The report examines how manufacturers are responding to these requirements through engineering choices and how end-users can factor compliance burden into total cost of ownership calculations.
Beyond sanitation, the broader regulatory context influences ventilation standards, climate control precision, and environmental monitoring integration. As breeding operations face increasing expectations around traceability, animal welfare, and disease containment, equipment that supports data capture and environmental consistency gains strategic value. The research connects these regulatory dynamics to procurement timing, vendor selection criteria, and lifecycle planning, ensuring that compliance considerations are treated as design inputs rather than afterthoughts.
How to Use This Study for 2026 Decision-Making
This market research is designed for operational deployment, not passive reading. Capital planning teams can use the segmentation and forecasting framework to prioritize equipment categories that align with their production mix and growth targets. Procurement leaders can benchmark regional demand patterns against supplier coverage, identifying gaps where localized service capacity or inventory positioning may create competitive advantage. Manufacturers and distributors can leverage the competitive landscape analysis to refine product roadmaps, assess white-space opportunities, and calibrate partnership or channel strategies against the positioning of established players.
The study also supports risk governance. By mapping growth assumptions against operational sensitivities, leadership teams can distinguish between investments that are structurally aligned with industry momentum and those that depend on narrow favorable conditions. The inclusion of biosecurity and regulatory context further ensures that equipment acquisitions are evaluated through the lens of long-term operational resilience, not just upfront pricing or specification checklists.
Detailed regional breakdowns, application-level revenue distributions, company-level capability assessments, and scenario-modeling outputs are reserved for the full report. These components are built to support specific procurement timelines, investment committee reviews, and strategic planning cycles. The executive summary presented here establishes the analytical foundation and directional evidence; the complete study delivers the granular intelligence required to translate strategy into executed decisions.
Next Steps: Accessing the Full Intelligence Package
The poultry breeding equipment market is expanding with structural consistency, but the dispersion of opportunity across equipment types, applications, and regions requires precise navigation. Our full market research report provides the segmented data, competitive profiling, regulatory context, and forward-looking modeling needed to ground 2026 decisions in evidence rather than assumption. For executives seeking to allocate capital, refine vendor selection, or position operations for the next phase of industry modernization, the complete study offers the depth and structure necessary for confident action.
To access the full report, including detailed market size trajectories, segmentation intelligence, competitive benchmarks, and scenario analyses tailored for strategic planning, visit the source page to request the complete intelligence package.
Worldwide Bee Breeding Equipment Market
For detailed analysis of this topic, please visit the official page: Poultry Breeding Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Frozen Pizza Market Hits $21.5B in 2025, Projected to Reach $34.4B by 2032
By PW Consulting, 2026-09-16
Navigating the Frozen Pizza Landscape: A 2026 Strategic Imperative
The global frozen pizza market stands at a critical inflection point. As consumer habits shift, supply chains face volatility, and regulatory frameworks tighten, understanding the trajectory of this staple convenience food category is no longer optional for executives—it is essential. Our latest comprehensive market research report provides a detailed roadmap of the Frozen Pizza Market, offering the granular intelligence required to navigate the complexities of the 2026 economic landscape and beyond.
This article serves as a strategic overview of the key dynamics shaping the industry, highlighting the macroeconomic forces and competitive pressures identified in our full study. However, to truly capitalize on the opportunities ahead, decision-makers must engage with the complete dataset. The following insights outline the scope of our analysis and demonstrate why this report is an indispensable tool for strategic planning in 2026.
Macro Demand Curve: Validation of Growth from 2020 to 2032
The historical performance of the frozen pizza sector demonstrates remarkable resilience and steady expansion. Between 2020 and 2025, the market navigated pandemic-induced consumption spikes, subsequent normalization, and inflationary pressures. This period established a robust baseline for future forecasting. According to our analysis, the global revenue reached approximately $21.5 billion in the base year of 2025, following a consistent upward trajectory from $16.3 billion in 2020.
Looking forward, the market is projected to sustain a healthy Compound Annual Growth Rate (CAGR) of 5.5 percent through the forecast period of 2026 to 2032. By the end of this forecast window, the market valuation is expected to approach $34.5 billion. This growth is not merely a function of population increase; it is driven by evolving convenience demands and product innovation that keeps frozen pizza relevant in a crowded quick-meal landscape.
- Base Year Strength: 2025 closed with significant momentum, setting the stage for double-digit absolute growth in the immediate term.
- Forecast Stability: The 2026 to 2032 projection accommodates potential economic fluctuations while maintaining a bullish outlook on core demand drivers.
- Valuation Thresholds: Crossing key revenue milestones in the late forecast period signals maturity and opportunity for premiumization.
While these top-line figures provide a high-level health check, our full report delves into the underlying volume and value drivers that vary significantly by product configuration and geographic deployment, details of which are reserved for subscribers seeking actionable intelligence.
Consumer Preferences and Product Architecture
The architecture of the frozen pizza market is defined by critical segmentation dimensions that dictate manufacturing strategies and retail placements. Consumer preferences are no longer monolithic; they are increasingly differentiated by dietary requirements and taste profiles. Our research dissects these preferences across key axes such as crust typology and topping composition, revealing where manufacturers are gaining traction and where saturation points are approaching.
On the crust front, the market exhibits clear leaders in terms of volume adoption, with thin crust varieties commanding a significant share of consumer attention. However, thick crust and stuffed crust options maintain loyal followings, particularly in specific retail channels and regional demographics. The strategic balance between these formats influences production line configuration and ingredient sourcing. Similarly, the topping segment analysis highlights the interplay between traditional meat-based options, vegetable-forward alternatives, and cheese-focused innovations.
The rise of specific dietary needs has also reshaped the competitive landscape. Demand for plant-based, gluten-free, and organic offerings is no longer a niche consideration but a core component of product portfolios for several major players. Understanding the revenue share and growth rate of these specific sub-segments is vital for capacity planning and marketing allocation. Our report quantifies these splits precisely, allowing stakeholders to identify which product configurations offer the highest margin potential in the current cost environment.
- Crust Dynamics: Analysis of Thin, Thick, Stuffed, and Other crust types relative to price points and regional taste profiles.
- Topping Trends: Evaluation of Vegetable, Meat, Cheese, and Other topping categories against nutritional trends and cost volatility.
- Dietary Innovation: Assessment of gluten-free and plant-based lines as demi-market drivers.
Competitive Landscape and Enterprise Strategies
The frozen pizza industry is characterized by a mix of global giants, regional specialists, and agile niche players. Market concentration metrics indicate a moderately consolidated environment, with the top three entities controlling a significant portion of total revenue and the top five firms commanding an even larger share. Understanding the strategic positioning of these key companies is crucial for assessing competitive threats and partnership opportunities.
Major branded producers continue to leverage extensive distribution networks and brand equity to maintain volume leadership. For instance, large-scale manufacturers focus on expanding their SKU counts to cover various price points and dietary needs. In June 2025, one such major brand introduced over 50 new frozen food SKUs, including gluten-free and plant-based varieties, signaling a strategy of diversification to capture convenience-driven consumers.
Conversely, specialized manufacturers are carving out sustainable niches through organic, plant-based, and gluten-free offerings. Companies like Amy's Kitchen Inc. and Daiya Foods Inc. exemplify the shift toward ethical and dietary-specific production, while others like Dr. Oetker and McCain Foods Ltd. balance branded products with private-label manufacturing services, adding flexibility to their revenue streams.
However, the operational landscape is not without risk. Recent events underscore the importance of supply chain integrity and safety protocols. In mid-2026, significant recalls highlighted vulnerabilities in production oversight. Champion Foods LLC voluntarily recalled certain batches of Motor City Pizza Co. 5 Cheese Bread due to potential Salmonella contamination, while Bakkavor recalled Basil Pesto and Mozzarella frozen pizzas distributed via HelloFresh due to possible metal fragments. These incidents serve as stark reminders of the operational risks inherent in food manufacturing and the reputational stakes involved.
Our full report provides detailed profiles on all major market participants, including Nestlé S.A., General Mills Inc., and Schwan Food Company, analyzing their recent developments, strategic moves, and potential vulnerabilities. This competitor intelligence is synthesized to help you benchmark your capabilities and identify gaps in the market.
Frozen Pizza Market
Raw Material Pressures and Macroeconomic Inputs
Profitability in the frozen pizza sector is heavily influenced by input cost volatility. In 2026, manufacturers are grappling with fluctuating prices for key agricultural commodities. According to data from the USDA Economic Research Service, farm-level wheat prices increased 1.9 percent from March 2026 to April 2026 and were 7.9 percent higher in April 2026 than in April 2025. This upward trend in grain costs directly impacts dough production and overall COGS.
Dairy costs also present a critical variable. The average weighted price for mozzarella cheese in SY 2026 is recorded at $1.8444 per kilogram. As cheese is a primary value driver and ingredient in most frozen pizza formulations, this pricing structure affects both premium and value-tier products differently. Managing these input costs requires sophisticated hedging strategies and supply chain negotiations, elements that are thoroughly examined in our procurement analysis section.
Furthermore, broader macroeconomic conditions, including labor costs and logistics expenses, continue to pressure margins. Companies that can optimize their production efficiency and negotiate favorable ingredient contracts will be better positioned to absorb these costs without eroding consumer affordability. Our report models these cost pressures against revenue growth scenarios to project net margin trends for the forecast period.
Regulatory Headwinds and Compliance Standards
Regulatory environments are becoming increasingly stringent, particularly regarding nutrition labeling and food safety. In May 2025, the FDA proposed a front-of-package nutrition labeling scheme requiring simplified labels for saturated fat, sodium, and added sugars on most packaged foods. This initiative aims to empower consumers with quicker nutritional insights but may necessitate packaging redesigns and reformulations for products that exceed specific thresholds.
Cross-border considerations are equally important. Canada implemented front-of-package nutrition symbols that became fully mandatory for packaged foods exceeding saturated fat, sugars, or sodium thresholds effective January 1, 2026. Additionally, prepared frozen foods labeling rules now require specific best-before usage and nutrition facts for categories including frozen fried foods, dumplings, rice products, and noodles effective April 1, 2026.
Frozen Potatoes Market
Compliance with these evolving regulations is not just a legal necessity but a competitive differentiator. Brands that proactively adapt their labeling and formulations can mitigate regulatory risk and enhance brand trust. Our report details the impact of these regulatory changes on market dynamics, offering a compliance roadmap for manufacturers operating in North America and globally.
Strategic Outlook and Recommendations for 2026
Navigating the frozen pizza market in 2026 requires a multi-faceted approach. Success depends on balancing cost management with product innovation, ensuring regulatory compliance while maintaining brand appeal, and addressing diverse consumer needs without diluting core value propositions. The market growth outlined in our forecast suggests that the pie is expanding, but capturing a larger slice requires precise execution.
Strategically, firms should consider the following focus areas derived from our analysis:
- Portfolio Optimization: Align product mix with the highest growth sub-segments identified in the segmentation analysis, particularly where dietary trends meet established taste preferences.
- Supply Chain Resilience: Mitigate raw material volatility through diversified sourcing and long-term contracts, especially for wheat and dairy ingredients.
- Regional Penetration: Leverage the strong performance in mature markets while identifying high-potential regions for expansion, understanding local taste and cost sensitivities.
- Risk Management: Implement rigorous quality control systems to prevent recalls and protect brand equity, learning from recent industry incidents.
Our comprehensive market research study provides the data backbone for these strategies. From detailed segmentation splits to company-specific profiles and regulatory impact assessments, the full report equips stakeholders with the tools needed to make informed decisions.
To access the complete analysis, including precise regional valuations, crust and topping revenue splits, and deep-dive competitor assessments, we invite you to secure your copy of the Frozen Pizza Market Report today. Don't navigate the future on assumptions—arm your strategy with definitive intelligence.
For detailed analysis of this topic, please visit the official page: Frozen Pizza Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Functional Sugar Market Hits $2.47B in 2025, Projected 6.2% CAGR to $3.81B by 2032
By PW Consulting, 2026-09-16
The Functional Sugar Market: Navigating the 2026 Growth Curve
The global landscape for functional sugars is undergoing a structural transformation. As consumer demand shifts steadily toward clean-label, low-calorie, and gut-health-supporting ingredients, manufacturers are recalibrating their portfolios to capture value in a high-growth segment. Our latest market research positions stakeholders to make informed decisions with a clear view of the macroeconomic trajectory and the competitive forces shaping the industry. Between 2020 and 2032, the market is projected to expand from 1.85 billion USD to 3.81 billion USD, reflecting a compound annual growth rate of 6.2 percent over the forecast period. This sustained expansion signals a durable shift rather than a transient trend, driven by regulatory approvals, supply chain maturation, and a broadening base of applications across food, beverage, and dietary supplement formats.
For executives evaluating capital allocation, product development pipelines, or market entry strategies in 2026, the window to act is narrowing. The pace of innovation among leading ingredient suppliers has accelerated, and the regulatory environment continues to evolve in ways that reward early movers with validated health claims and scalable production capabilities. This report distills those dynamics into a decision-ready framework, giving you the context needed to prioritize investments where demand signals are strongest and competitive pressure is most acute.
A Market on the Rise: Key Trajectory Signals for 2026
The historical record demonstrates a consistent upward climb. From 2020 through 2025, revenue grew each year, reaching 2.47 billion USD by 2025. Looking ahead, the forecast extends through 2032 and outlines a path that carries the total toward 3.81 billion USD. The progression is not uniform; it reflects a combination of volume growth, value-added formulations, and expanding geographic reach. By 2026, the market is expected to cross the 2.69 billion USD mark, establishing a new baseline for the decade ahead.
Several underlying drivers support this trajectory. First, the post-pandemic consumer emphasis on preventive health has elevated the role of gut microbiome support and metabolic stability as key purchase drivers. Functional sugars that deliver prebiotic benefits or moderate glycemic responses are increasingly embedded in everyday products, from breakfast cereals and snack bars to ready-to-drink beverages and capsule-based supplements. Second, manufacturing innovation has reduced the cost premium historically associated with specialized sweeteners, allowing brands to integrate functional sugars without sacrificing price competitiveness. Third, ingredient sourcing strategies are adapting to supply side realities; for example, EU sugar beet prices navigated a period of increase in the early 2020s before stabilizing in 2024 and softening during the first half of 2025, while USDA forecasts projected U.S. sugar production at a record 9.42 million short tons in the 2025/26 season. These supply factors influence cost structures and regional sourcing decisions, and they are examined in detail within the report to help procurement teams anticipate volatility.
Within this context, the buildup in capacity by major players is particularly noteworthy. Tate & Lyle expanded allulose production capacity by 35 percent in March 2025 to improve supply availability for low-calorie sweeteners, and Cargill has advanced fermentation-based functional sugar solutions that improve production efficiency for dietary supplement and food manufacturers. These moves signal confidence in sustained demand, but they also raise the bar for competitors and purchasers alike: access to premium functional sugars will increasingly depend on long-term partnerships and secured supply chains.
Rising from 1.85 Billion to 3.81 Billion: What the Growth Curve Means for Strategy
A market moving from 1.85 billion USD in 2020 to a projected 3.81 billion USD in 2032, at a CAGR of 6.2 percent, invites a straightforward question: where is the greatest value-creation potential concentrated, and how should organizations align their capabilities to capture it? The growth curve is not just a number; it is a signal of demand elasticity, category readiness, and regional maturity. As the base expands, differentiation becomes essential. The strongest performers are likely to be those that combine science-backed ingredient claims with consistent supply, regulatory compliance, and formulation flexibility.
Our analysis confirms that market leadership is fragmented rather than consolidated, a structural feature that creates room for niche positioning and targeted partnerships. The top three players collectively account for 34.5 percent of revenue, while the top five hold 49.2 percent. No single entity dominates, and the spacing between leading firms allows specialized suppliers to build durable presence in distinct applications or geographies. This dynamic is reinforced by the entry of regional and specialty manufacturers that bring formulation depth, localized sourcing, and proprietary processing methods. For brands evaluating suppliers, the implication is clear: supplier selection should weigh technical capability, claim substantiation, and capacity reliability alongside price.
The report frames these market-level signals in a way that supports scenario planning. Executives can use the trajectory data to model revenue ranges under different adoption timelines, assess the timing of product launches relative to regulatory milestones, and identify segments where the margin opportunity is widening fastest. Because the forecast spans multiple years, it also exposes inflection points where capacity additions or regulatory changes could alter competitive positioning, making now an ideal moment to review your roadmap against the data.
Competitive Landscape: How Tier-1 Innovators Are Defining the Next Wave
A resilient competitive field has emerged around functional sugars, with incumbents leveraging scale and specialists competing on formulation intelligence and claim support. The companies featured in this research represent a cross-section of strategies: some focus on core sweeteners with documented metabolic benefits, others emphasize fiber-based ingredients for digestive health, and several invest in sustainability as a differentiator. The report profiles each and compares their capabilities, recent moves, and positioning.
Tate & Lyle, headquartered in London, offers functional sugars including allulose and isomaltulose for blood sugar management and prebiotic benefits in dietary supplements and beverages. Its capacity expansion in allulose underscores a bet on consumer appetite for low-calorie, glycemic-friendly sweeteners. C.argill, based in Wayzata, provides fermentation-based functional sugar solutions with improved production efficiency for dietary supplement and food manufacturers, a route that can reduce cost and improve consistency. Ingredion, located in Westchester, launched a next-generation prebiotic sugar ingredient in January 2026 that improved digestive health performance by 24 percent for premium supplement formulations, an example of how formulation advances can accelerate adoption in higher-margin categories. ADM, in Chicago, supplies natural functional sugar ingredients to global beverage and food companies for North American operations, emphasizing broad reach and operational reliability. BENEO, in Karlsruhe, specializes in chicory root-derived functional carbohydrates and fibers for blood sugar management and sugar reduction, with regulatory recognition such as the FDA GRAS Notice 1242 for short-chain fructooligosaccharides issued in June 2025, which exempted specified uses from premarket approval.
On the plant-based and fiber side, Roquette Frères, in Lestrem, develops plant-based functional sugar and fiber ingredients for food, beverage, and supplement applications, and released its 2026 sustainable actions report in June 2026 highlighting biodiversity and nature initiatives in functional ingredient production. Tereos Group, in Origny-Sainte-Benoite, produces functional sugar solutions from beet and cane sources for sweetening and health-focused food products. Cosucra Groupe Warcoing, in Warcoing, extracts chicory root fibers such as PISANE™ as functional ingredients for sustainable nutrition and sugar alternatives. Nexira, in Rouen, supplies natural acacia and botanical extracts as functional ingredients for blood sugar control in supplements. In the low-calorie sweetener space, Samyang Corporation, in Seoul, manufactures allulose as a next-generation low-calorie functional sugar sweetener for beverages and snacks, while Matsutani Chemical Industry, in Itami, develops FIBERSOL® soluble dietary fiber and allulose for prebiotic and sugar-reduction applications.
Functional Chewing Gum Market
Across these players, three themes recur: diversification of sweetness and fiber platforms, investment in processing and capacity, and a sharper focus on validated health outcomes. The report maps these strategies to the segments and applications where they are most relevant, giving buyers a comparative lens to evaluate partnerships and procurement options with greater precision.
Functional Sugar Market
Segmentation Drivers: Ingredient Types, Application Breadth, and Regional Dispersion
The functional sugar market is not monolithic; it spans multiple ingredient types, application areas, and regional ecosystems, each with its own growth logic and competitive dynamics. The analysis segment the market by type, application, and region to surface where momentum is building and which combinations are likely to outperform.
By type, the market includes oligogaccharide, inulin, sugar alcohols, and other specialty categories. Oligosaccharides and inulin anchor the prebiotic narrative, while sugar alcohols and next-generation low-calorie sweeteners address glycemic management and calorie reduction. The "others" category captures emerging botanicals and fiber blends that continue to gain traction in premium formulations. The report examines each category substantively, without disclosing segment-level revenue shares, to help formulation teams match ingredient properties to functional goals and cost constraints.
By application, the breadth is broad and expanding. Food and beverage remain the largest usage base, where functional sugars are embedded in everyday products to deliver taste, texture, and health positioning. Dietary supplements constitute a significant and growing channel, where claims around digestive health and metabolic support are increasingly central to product identity. Pharmaceuticals and other applications contribute additional demand, often governed by stricter specifications and quality standards. The research outlines the differentiators across these applications, including regulatory requirements, formulation compatibility, and the strength of consumer demand signals, to guide category strategy and packaging decisions.
By region, the dispersion reflects differences in consumer preferences, regulatory frameworks, and supply infrastructure. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each present distinct opportunities and constraints. The report provides qualitative context on regional momentum drivers and sourcing patterns, again withholding exact split percentages, so that readers can calibrate their geographic focus to the most relevant growth engines without pre-judging local execution challenges.
Two regulatory developments frame part of this regional picture. EFSA extended the use of isomalto-oligosaccharide as a novel food under Regulation (EU) 2015/2283, a step that broadens the application canvas for certain prebiotic ingredients in Europe. In parallel, FDA granted GRAS notice 1242 for short-chain fructooligosaccharides from BENEO for use in certain foods, exempting those specified uses from premarket approval and simplifying formulation pathways. Together, these moves illustrate how regulatory milestones can unlock new product possibilities and influence regional prioritization.
Formulation and Sourcing Realities: What Operational Teams Need to Know
Turning market opportunity into commercial reality requires attention to the mechanics of formulation and sourcing. Functional sugars must perform not only as health-forward ingredients but also as contributors to taste, mouthfeel, stability, and shelf life. Each category presents trade-offs. Oreosaccharide and inulin can deliver prebiotic functionality and fiber content, but their behavior in different matrices varies; sugar alcohols offer sweetness profiles and glycemic moderation, yet their inclusion levels must be managed carefully; allulose and related low-calorie sweeteners can replicate sugar-like taste with lower caloric impact, but supply availability and cost remain important considerations for high-volume programs.
From a sourcing standpoint, the ability to secure consistent quality and volume is increasingly tied to supplier investment in processing efficiency and capacity. Cargill's fermentation-based solutions, for instance, reflect a broader industry shift toward more efficient production routes that can support scale without sacrificing quality. Meanwhile, sustainability is moving from a narrative element to an operational one: Roquette's 2026 sustainable actions report underscores biodiversity and nature initiatives as part of functional ingredient production, a signal that procurement teams may increasingly evaluate suppliers on environmental performance alongside cost and reliability. The report details the operational considerations relevant to each major ingredient route and supplier type, helping teams weigh formulation goals against supply continuity and total cost of ownership.
Regulatory alignment is another operational thread. The EU sugar beet price trajectory, the record U.S. sugar production forecast, and the evolving status of novel food approvals all influence cost structures and formulation options. By synthesizing these variables, the research equips teams to anticipate changes and adjust sourcing strategies before they become reactive.
Turn Insights into 2026 Decisions: The Full Intelligence Awaits
The functional sugar market is positioned for a sustained run of growth, with a clear upward trajectory, an active competitive field, and a regulatory environment that continues to open new possibilities. The report translates these macro trends into actionable intelligence, covering market sizing across historical and forecast years, segmentation by type, application, and region, competitive profiling of leading and emerging players, and the latest industry developments that could affect sourcing, formulation, and go-to-market timing in 2026 and beyond. It is designed to support multiple use cases: portfolio planning, supplier selection, market entry evaluation, pricing strategy, and long-range scenario modeling.
Because the decision space is competitive and time-sensitive, partial visibility carries risk. The report delivers the full segmentation detail, including regional breakdowns, application splits, and type-level analysis, alongside company comparisons and regulatory context, so that your team can act with precision. The complete intelligence is available on the source page; accessing it will give you the granular data needed to benchmark opportunities, validate assumptions, and set priorities for the year ahead.
Now is the moment to align your strategy with the data. As the market moves toward the 2026 baseline and beyond, organizations that combine strong formulation insight with reliable supply and clear health claims will be best placed to capture value. The research provides the foundation; your next step is to secure the full intelligence and translate it into concrete actions.
For detailed analysis of this topic, please visit the official page: Functional Sugar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: PC Gaming Peripheral Market to Hit $5.63B by 2032, 5.3% CAGR Through 2032
By PW Consulting, 2026-09-16
The 2026 PC Gaming Peripheral Market: Strategic Intelligence for Corporate Decision-Making
The global PC gaming peripheral market stands at a critical inflection point. As hardware capabilities converge with evolving player expectations, competitive differentiation is no longer driven by incremental feature upgrades alone. It requires a rigorous understanding of demand shifts, supply chain vulnerabilities, pricing architecture, and the strategic positioning of incumbents and challengers. Our newly published PC Gaming Peripheral Market research report delivers exactly that: a comprehensive, forward-looking intelligence framework designed to support executive decision-making throughout 2026 and beyond.
Drawing on a historical analysis spanning 2020 through 2025 and a detailed forecast horizon extending to 2032, this study maps the structural forces that will shape revenue allocation, product roadmaps, regional expansion strategies, and procurement planning. The market has demonstrated consistent resilience, with total industry revenue reaching approximately 3,924.19 million USD in 2025 and climbing to an estimated 4,176.38 million USD in 2026. Over the full forecast period, the sector is projected to expand at a compound annual growth rate of 5.3 percent, ultimately approaching 5,633.12 million USD by 2032. These figures are not merely retrospective indicators. They represent a baseline against which product portfolio investments, channel partnerships, and geographic prioritization must be stress-tested.
This report is engineered for leaders who require actionable clarity rather than high-level speculation. Below, we outline the strategic architecture of the study, the competitive contours it maps, and the macroeconomic and regulatory pressures that will define market execution in 2026.
Why This Research Matters for 2026 Strategic Planning
Enterprise decisions made in 2026 will be judged against a market environment defined by three simultaneous pressures: shifting consumption patterns across gaming modalities, tightening component availability, and intensifying competition among established peripheral manufacturers. Executive teams cannot afford to treat these dynamics as isolated risks. They must be modeled together.
Our analysis frames the market as a system of interdependent variables. Revenue growth, for instance, is not distributed uniformly across usage contexts or hardware categories. Instead, value creation is increasingly concentrated in segments where performance fidelity, latency optimization, and creator-oriented ergonomics intersect. The report dissects these intersections without relying on surface-level categorization, enabling strategy teams to identify where incremental R&D spend will yield disproportionate returns and where legacy product lines may face structural decline.
Equally important, the forecast model accounts for the macroeconomic and regulatory turbulence that has reshaped electronics supply chains over the past twelve months. Raw material constraints, trade policy adjustments, and semiconductor input costs have moved from peripheral concerns to central planning variables. The study integrates these factors into scenario-based guidance, allowing procurement, manufacturing, and pricing teams to evaluate margin sensitivity under multiple supply disruption pathways.
For organizations evaluating market entry, portfolio consolidation, or regional scaling, the report functions as a decision-validation instrument. It does not simply describe what is happening; it clarifies where strategic leverage exists and which assumptions require continuous monitoring as the forecast window progresses.
Inside the Report: Operational Intelligence Built for Execution
The study is structured to move seamlessly from macro market architecture to execution-level detail. Rather than presenting static tables in isolation, the analysis embeds quantitative baselines within strategic narratives that can be directly translated into planning workflows.
The core deliverables include:
PC Gaming Peripheral Market
Gaming Mouse & Keyboards Market
- Market sizing and trajectory modeling anchored in a transparent historical baseline and extended across a multi-year forecast window, with explicit treatment of the 5.3 percent compound growth pathway and its inflection points.
- Demand decomposition across hardware categories , including headsets, mice, keyboards, gamepads, and ancillary peripheral subcategories, with attention to performance segmentation, pricing tiers, and adoption velocity.
- Application-linked consumption mapping that distinguishes how revenue flows across competitive esports environments, casual gaming usage, and streaming and content creation workflows, highlighting divergent feature priorities and purchase cycles.
- Regional demand architecture that captures where consumption is concentrated, how growth momentum differs across markets, and which geographic corridors present the most viable expansion candidates under current economic conditions.
- Competitive benchmarking and strategic positioning analysis that evaluates brand differentiation, performance claims, ecosystem lock-in potential, and product cadence among the leading manufacturers shaping market direction.
- Supply-side and regulatory context integration , connecting component sourcing pressures, export control developments, and tariff-related cost shifts to practical implications for procurement timing, input substitution, and margin management.
Each section is written to support cross-functional use. Product managers can extract priority feature sets and segmentation logic. Commercial leaders can align channel strategy with regional demand intensity. Finance and operations teams can use the scenario framing to model downside exposure from input cost volatility. This breadth ensures that the report does not sit idle as a reference document; it becomes an active input to quarterly planning, capital allocation, and market-response strategy.
Competitive Landscape: Positioning, Product Cadence, and Strategic Signal
The market’s competitive structure is defined by a concentrated set of influential players, each pursuing distinct value propositions while operating within the same performance-driven consumer expectations. The report examines the strategic posture of several core companies whose product decisions are actively shaping category standards and buyer expectations.
Corsair Gaming Inc., headquartered in Milpitas, California, continues to anchor its offering around high-performance keyboards, mice, headsets, gaming chairs, and custom PC components aimed at both gamers and creators. Its portfolio strategy emphasizes performance coherence across input devices and supporting ecosystem elements, giving it relevance in segments where system-level integration matters.
Razer Inc., based in San Jose, California, directs its peripheral lineup toward esports-optimized gaming mice, keyboards, headsets, and accessories centered on low-latency performance. The company’s product narrative is tightly coupled to competitive play requirements, making responsiveness and precision central to its market identity.
Logitech International S.A., headquartered in Lausanne, Switzerland, maintains a broad gaming peripheral presence through its Logitech G series, spanning gaming mice, keyboards, headsets, and controllers designed for both competitive and casual players. Its scale and brand recognition provide a strong platform for cross-segment appeal, while its product roadmap increasingly reflects nuanced performance segmentation.
SteelSeries A/S, operating from Copenhagen, Denmark, focuses its lineup on Arctis headsets, Apex keyboards, and Rival mice optimized for competitive esports. Its positioning reflects a disciplined emphasis on tournament-grade performance characteristics and player-facing comfort features that align with intensive usage cycles.
Turtle Beach Corporation, based in San Diego, California, has extended its footprint through Command Series keyboards, mice, and gaming audio peripherals designed for PC and console crossover appeal. This cross-platform orientation broadens its addressable audience while reinforcing its audio-centric heritage.
HyperX, a division of Kingston Technology Corporation and headquartered in Fountain Valley, California, contributes to the market through Cloud series headsets, keypads, and accessories focused on immersive PC gaming audio. Its product identity has long been associated with comfort, durability, and audio consistency, giving it a distinctive place within the broader headset and accessory conversation.
These companies do not compete in a vacuum. Their product announcements, positioning choices, and feature priorities send clear market signals. Recent developments in 2026 illustrate how rapidly the category is evolving. In April 2026, Turtle Beach Corporation unveiled the Command Series ecosystem of PC gaming keyboards and mice at multiple price points, emphasizing high-speed performance and precision for gaming and content creation. Logitech International S.A. announced the G512 X gaming keyboard with TMR analog switches, mechanical options, and customizable layouts intended to enable tuned performance in PC gaming. Corsair Gaming Inc. introduced the Night Sword B2 wireless gaming mouse at Computex, highlighting extended battery life and high-performance PC gaming input.
The strategic implication is consistent: competition is being fought at the level of latency, switch technology, wireless efficiency, ergonomic tuning, and ecosystem breadth. Our report translates these announcements into competitive intelligence by assessing what each move reveals about underlying product strategy, target segmentation, and potential market-share reallocation.
Market Dynamics in 2026: Regulation, Materials, and the Cost of Precision
The trajectory of the PC gaming peripheral market cannot be separated from the environment in which its components are sourced and manufactured. In 2026, supply-side constraints and trade policy have become first-order planning considerations rather than background noise.
One of the most consequential supply dynamics involves gallium and related materials. China accounted for 99 percent of the world’s low-purity primary gallium supply, and export controls on gallium, germanium, and related materials have affected semiconductor and electronics components across multiple downstream categories. Compounding this, China imposed an outright prohibition on exports of gallium, germanium, antimony, and superhard materials to the United States effective December 2024, with the ban suspended until November 2026 while licensing remains active. For peripheral manufacturers, this creates a planning environment in which input availability, approval workflows, and sourcing diversification must be evaluated well ahead of product build cycles.
Simultaneously, semiconductor-related trade measures have introduced additional cost variability. In January 2026, the U.S. Department of Commerce implemented a 25 percent ad valorem tariff on specified advanced semiconductor chips, affecting upstream components for peripheral electronics. This development followed a broader Section 232 investigation initiated in April 2025 into semiconductor imports and manufacturing equipment, with a report issued in December 2025 and 25 percent tariffs applied in January 2026. The practical consequence is that precision electronics used in high-performance peripherals face an elevated and potentially fluid cost structure, which can influence pricing architecture, margin planning, and the timing of new product introductions.
China’s broader rare earth export controls have also extended into the supply chain. In January 2026, controls were expanded to samarium, gadolinium, and lutetium compounds, raising costs for high-temperature magnets used in precision components across electronics supply chains. Since these materials support performance-critical mechanisms inside advanced peripheral hardware, even modest cost escalation can affect the economics of feature-rich designs.
These dynamics do not just alter short-term input costs; they reshape the strategic calculus of product development. Companies must decide whether to absorb cost pressure, pass it through selectively, redesign around constrained materials, or accelerate supplier diversification. The report integrates these considerations into a market dynamics framework that links raw material exposure, regulatory timing, and component sourcing strategy to commercial outcomes.
Concentration in the competitive structure adds another layer of context. The market remains moderately fragmented at the top, with the top three firms holding approximately 28.0 percent of revenue and the top five firms accounting for about 34.0 percent. This concentration level indicates that while leading brands exert meaningful influence, there is still room for differentiated positioning, niche performance propositions, and regional or application-specific gains. The report examines how this concentration interacts with product cadence, brand equity, and channel strength to determine which players can defend share and which vulnerabilities may open under supply or pricing stress.
What Decision-Makers Will Gain
The objective of this study is to convert complex market signals into a clear strategic lens. Readers will gain a stronger ability to:
- Evaluate which hardware categories and application segments present the most durable growth opportunities through 2032.
- Identify where performance specifications, input reliability, and wireless efficiency are becoming table stakes rather than differentiators.
- Understand how regulatory and materials-related pressures may affect cost structures and product launch timing across 2026 and the surrounding forecast period.
- Assess the strategic posture of key competitors and interpret recent product launches as signals of broader market direction.
- Align regional expansion assumptions with where demand intensity and growth momentum are most likely to persist.
In practical terms, the report is designed to reduce uncertainty in portfolio planning, sharpen competitive response timing, and support more resilient procurement and pricing decisions. It gives executive teams a shared factual foundation on which to debate entry, expansion, consolidation, and innovation priorities.
Obtain the Full Strategic Blueprint
The overview presented here captures the architecture of the analysis and the strategic questions the study is built to answer. It does not expose the detailed segmentation values, regional splits, application-level revenue distribution, or category-specific market sizing that form the analytical core of the report. Those findings are where the most precise planning insights reside, and they are reserved for the full version of the study.
For teams preparing product strategy, commercial planning, sourcing decisions, or competitive positioning for 2026, the complete report provides the depth required to move from directional confidence to execution-ready intelligence. We invite strategy, product, and commercial leaders to access the full PC Gaming Peripheral Market research to obtain the granular forecasts, competitive benchmarks, and scenario analysis needed to support high-stakes decisions throughout the forecast window.
For detailed analysis of this topic, please visit the official page: PC Gaming Peripheral Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hollow Fiber Dialyzer Market to Reach $10.71M by 2032, Driven by 5.7% CAGR
By PW Consulting, 2026-09-16
Strategic Horizons: The Hollow Fiber Dialyzer Market Outlook 2026–2032
The global renal care landscape is entering a phase of disciplined expansion, driven by aging demographics, the rising prevalence of chronic kidney disease, and continuous innovation in extracorporeal purification technologies. For healthcare executives, supply chain strategists, and investment professionals, understanding the trajectory of the hollow fiber dialyzer market is no longer optional—it is a strategic imperative. Our latest market research provides a rigorous, multi-dimensional analysis of the sector, mapping historical performance against a forward-looking forecast window that extends through 2032. This article outlines the strategic architecture of the report, highlights the operational intelligence embedded within, and explains why these insights are essential for enterprise decision-making in 2026 and beyond.
Market Trajectory: Navigating a Mid-Growth Expansion Cycle
Over the past half-decade, the hollow fiber dialyzer sector has demonstrated steady, resilient revenue growth. Historical data from 2020 through 2025 reveals a consistent upward curve, with total market value advancing from approximately 5.5 billion USD to 7.26 billion USD. This historical run reflects stable procurement patterns, sustained clinical adoption, and incremental improvements in manufacturing efficiency. Looking ahead, our forecast model projects the market to reach 7.56 billion USD in 2026, with growth compounding steadily toward 8.54 billion USD by 2028 and continuing to 10.71 billion USD by 2032.
The forecast period is anchored by a compound annual growth rate of 5.7 percent, a trajectory that balances realistic demand expansion with structural headwinds and tailwinds. This rate is neither aggressive nor stagnant; rather, it reflects a market that is maturing but still capable of meaningful volume and value expansion. For strategic planners, this mid-growth profile suggests a landscape where competitive differentiation, operational scalability, and product-grade positioning will determine market capture more than broad macroeconomic swings. The report dissects this trajectory across multiple analytical lenses, ensuring that readers can separate cyclical fluctuations from structural shifts and calibrate their roadmaps accordingly.
Structural Segmentation: Where Value Accrues and How to Capture It
Segment-level analysis forms the analytical backbone of the report. The market is examined through three primary dimensions—product type, application setting, and geographic distribution—each offering distinct implications for pricing strategy, capacity planning, and channel development. Within the product architecture, the analysis contrasts low-flux and high-flux hollow fiber configurations, highlighting how membrane permeability, biocompatibility, and clearance performance shape clinical preference and procurement behavior. High-flux variants continue to command a larger share of the value pool, reflecting their alignment with contemporary dialysis protocols that prioritize middle-molecule removal and long-term patient outcomes.
Application segmentation examines how procurement flows across hospital networks, dedicated clinic centers, and other care environments. The report maps the operational characteristics of each setting, from volume throughput and sterilization logistics to procurement cycle lengths and reimbursement alignment. Geographic analysis, meanwhile, provides a regional snapshot of demand intensity and growth readiness. North America and Europe maintain substantial demand footprints, supported by established reimbursement pathways and mature clinical infrastructure. Asia Pacific represents a high-potential corridor where expanding healthcare access, rising treatment volumes, and localized manufacturing are reshaping competitive dynamics. Latin America and the Middle East and Africa contribute complementary demand streams, with growth trajectories closely tied to capacity building and import-dependent supply chains.
Importantly, the report does not reduce these segments to static percentages. Instead, it frames them as strategic zones where pricing elasticity, channel access, and product-grade positioning can be optimized. Readers will gain a clear understanding of which segment characteristics create margin opportunities, which require volume-driven playbooks, and where cross-segment synergies can be engineered through portfolio architecture and supply chain design.
Competitive Architecture: The Tenacity of an Oligopolistic Core and the Rise of Contenders
The hollow fiber dialyzer market exhibits a concentrated competitive structure. Our analysis captures a combined market share for the leading three participants at approximately 68.5 percent, with the top five entities collectively accounting for around 75 percent of total revenue. This concentration underscores the importance of scale, regulatory navigation, and sustained R&D investment in maintaining market positioning. At the same time, the remaining share dispersion leaves meaningful room for specialized entrants, regional manufacturers, and technology-focused innovators to capture niche demand or differentiated product niches.
The report profiles the core competitive set in detail. Nipro Corporation continues to advance its high-flux polysulfone and cellulose triacetate portfolios, including the ELISIO™-HX and Cellentia™-H families, which are engineered for both chronic and acute hemodialysis applications. Baxter International Inc. reinforces its presence through polyethersulfone high-flux configurations such as the HiF series and Revaclear, emphasizing consistency and broad compatibility across dialysis platforms. Fresenius Medical Care AG & Co. KGaA maintains a widely deployed polysulfone-based Optiflux series, serving hospital and home hemodialysis environments with established clinical familiarity. Toray Medical Co., Ltd. contributes the Filtryzer series, combining PMMA and polysulfone materials with advanced biocompatibility and adsorption characteristics. B. Braun Melsungen AG focuses on polysulfone hollow fiber designs that emphasize reduced blood cell trauma and strong biocompatibility for extracorporeal procedures. Asahi Kasei Medical Co., Ltd. develops advanced polysulfone and related high-flux configurations targeting improved clearance performance. Nikkiso Co., Ltd. integrates high-flux hollow fiber dialyzers with its broader dialysis systems, supporting chronic kidney disease therapy workflows. On the regional supply frontier, Jiangxi Sanxin Medtec Co., Ltd. produces disposable polysulfone and PC high-flux options, including PC High Flux series and PES membranes, while LEPU Medical Technology Co., Ltd. expands its PP series and OCI-HD line across low-flux to high-flux polysulfone configurations. Althin Medical AB rounds out the competitive landscape with capillary hollow fiber designs such as the A-15 HEMODIALYZER, cleared for hemodialysis use.
This competitive profile is not presented as a static roster. The report evaluates each entity’s strategic posture, product-grade positioning, regional reach, and innovation cadence, enabling readers to assess where incumbency advantages are strongest and where disruption is most plausible. Strategic planners will find actionable guidance on partnership opportunities, competitive response playbooks, and whitespace identification.
Industry Dynamics and Regulatory Tailwinds Shaping 2026 Strategy
Market outcomes are ultimately governed by the interaction of technology, regulation, reimbursement, and supply economics. The report integrates these forces into a cohesive dynamics framework, drawing on current regulatory standards, reimbursement behavior, raw material trends, and sterilization requirements. ISO 8637-1 continues to define essential performance expectations for hollow fiber haemodialysers, including blood area integrity testing, establishing a baseline for compliance and quality assurance across manufacturers. At the same time, FDA 510(k) clearance pathways require demonstrable substantial equivalence for new dialyzer designs, encompassing both membrane and potting materials. This regulatory architecture rewards manufacturers that can streamline design verification, maintain robust documentation, and align innovation with established equivalence frameworks.
Reimbursement conditions remain a critical enabler of adoption. Medicare and commercial insurance programs provide adequate coverage for single-use hollow fiber dialyzers, reinforcing procurement stability and enabling growth in home hemodialysis settings. This reimbursement backdrop supports service expansion strategies and encourages manufacturers to design products that fit both facility-based and decentralized care models. On the supply side, polysulfone and polyethersulfone raw material costs have declined between 8 and 12 percent over the past five years, reflecting expanded production capacity and improved procurement economics. These cost dynamics improve margin potential and lower barriers to product-grade upgrades, allowing companies to invest in higher-performance membranes without proportionally escalating cost structures.
Sterilization and shelf-life considerations also shape product design and logistics planning. High-flux hollow fiber dialyzers are typically gamma or moist heat sterilized for single-use application, with standard shelf-life expectations around three years to preserve non-pyrogenic status. This parameter influences inventory strategy, distribution planning, and packaging decisions, especially for manufacturers operating across multiple regions with differing cold-chain and storage norms. The report translates these technical and regulatory variables into operational implications, helping readers evaluate where process optimization can yield cost advantages and where compliance requirements may constrain speed-to-market.
Hollow Fiber Dialyzer Market
Recent Developments Illuminating Competitive Velocity
Recent corporate activity underscores how quickly the competitive tempo is shifting. In early 2026, Outset Medical, Inc. secured FDA clearance for its next-generation Tablo hemodialysis system, the first to incorporate the strictest cybersecurity guidance, supporting the use of hollow fiber dialyzers within connected systems. This milestone signals a broader convergence between device hardware and digital integration, a trend with direct implications for product compatibility, data workflows, and downstream service models. In mid-2025, Byonyks received FDA clearance for its X1 automated peritoneal dialysis cycler, enabling integration with hollow fiber dialyzers in home therapy settings and reinforcing the push toward decentralized care.
On the incumbent side, Fresenius Medical Care obtained FDA approval in 2024 for expanded high-flux membrane production capacity and next-generation disposable dialyzers with markedly reduced toxin retention. Nipro Corporation introduced enhanced polysulfone hollow fiber structures that improved ultrafiltration consistency and increased compatibility with a significant share of automated dialysis systems. Baxter International advanced biocompatible membrane dialyzers that reduced inflammatory response indicators and improved efficiency in extended treatment sessions. These developments illustrate how competitive advantage is increasingly tied to membrane engineering, workflow compatibility, and clinical outcome differentiation. The report situates each milestone within a broader competitive narrative, helping readers distinguish between isolated product announcements and structural shifts in capability and positioning.
Inside the Report: Content Architecture Built for Decision-Makers
The full market research is designed to translate complex data into executable strategy. It opens with a comprehensive market overview that establishes baseline definitions, scope boundaries, and methodological transparency. From there, the analysis moves into historical performance mapping, showing how the market evolved through 2025 and what that evolution reveals about underlying demand drivers. The forecast section projects revenue pathways through 2032, accompanied by scenario commentary that helps leadership test vulnerability to input cost changes, regulatory adjustments, and demand shocks.
Dialyzer Market
Segment chapters provide granular views of type, application, and regional dynamics without overwhelming readers with noise. Each chapter connects segment behavior to strategic choices—where to invest in capacity, how to structure pricing, and which customer segments warrant tailored product configurations. The competitive landscape section delivers company profiles, positioning maps, and development timelines, enabling benchmarking and response planning. A dedicated dynamics chapter synthesizes regulatory, reimbursement, raw material, and sterilization factors into an integrated framework, showing how each variable influences cost, speed, and market access.
The report also incorporates recent corporate developments, FDA clearances, product launches, and production expansions, tying them back to market-level implications. For executives who need to brief cross-functional teams, the structure supports quick extraction of relevant insights, while for analysts who require depth, the underlying segmentation logic and trend framing provide a reliable foundation for further modeling. Visitors to the source page will find the complete dataset, detailed segmentation charts, and the full competitive intelligence suite that cannot be summarized in a single overview.
Strategic Implications for 2026 Enterprise Decision-Making
For organizations operating in or adjacent to the renal care sector, the 2026 decision environment demands clarity on three fronts: demand durability, competitive exposure, and operational leverage. The market’s projected growth path suggests durable demand, but durability alone does not guarantee capture. The concentrated competitive structure means that incumbents will continue to defend share through scale, regulatory compliance, and incremental product enhancements. At the same time, the raw material cost environment and reimbursement stability create conditions where well-executed entrants and regional players can expand footprint through differentiated membrane technology, application-specific configurations, and channel partnerships.
Enterprise leaders should use the report to stress-test portfolio mix, assess where high-flux demand is most resilient, and determine whether home therapy and clinic-center expansion represent authentic growth vectors in their target geographies. Supply chain and procurement teams can use the segmentation and dynamics analysis to align inventory planning with sterilization requirements, shelf-life parameters, and regional distribution realities. Commercial teams can leverage competitive profiles to refine positioning, anticipate competitor moves, and identify customer segments where compatibility, clearance performance, or biocompatibility offer tangible purchase advantages.
Conclusion: From Insight to Action
The hollow fiber dialyzer market is expanding within a disciplined growth corridor, shaped by clinical demand, regulatory rigor, reimbursement stability, and continuous membrane innovation. The strategic question for 2026 is not whether the market will grow, but how organizations will position themselves to convert that growth into sustainable share, margin, and capability. Our market research is built to support that conversion, offering a structured, data-grounded view of where value is created and how competitive advantage can be protected or extended.
To access the full segmentation breakdown, complete regional and application analysis, detailed company profiles, and the comprehensive forecast model, visit the source page for the Hollow Fiber Dialyzer Market report. The complete intelligence suite provides the depth required to translate market-wide trends into precise, defensible action plans for 2026 and the years ahead.
For detailed analysis of this topic, please visit the official page: Hollow Fiber Dialyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medication Adherence Packaging Market Hits $212.78M in 2025, Projects 5.54% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Next Wave: Strategic Imperatives in the Medication Adherence Packaging Systems Market
The global pharmaceutical supply chain is undergoing a quiet but profound transformation. As healthcare systems worldwide grapple with rising chronic disease burdens, aging demographics, and the escalating cost of non-adherence, the packaging that delivers medication has evolved from a passive container into an active therapeutic intervention. For executives, investors, and product strategists, understanding the trajectory of the Medication Adherence Packaging Systems Market is no longer a niche curiosity. It is a strategic necessity. Our latest research release maps this evolution with precision, offering a decision-grade lens into how the sector will perform from 2026 through 2032.
The market has demonstrated consistent momentum over the past five years, driven by a convergence of regulatory pressure, reimbursement realignment, and technological maturation. Historical performance data reveals a sector that has navigated supply chain volatility, shifting care delivery models, and early-stage digital integration without losing its growth trajectory. As organizations prepare their 2026 capital allocation and product roadmaps, this research provides the structural clarity required to separate signal from noise.
Market Trajectory and Structural Growth Drivers
The Medication Adherence Packaging Systems Market has expanded from a baseline of roughly 163 million USD in 2020 to approximately 212 million USD by 2025, reflecting a compound annual growth rate that underscores steady, secular demand rather than speculative hype. Forecasts project the market will reach approximately 222 million USD in 2026, with continued expansion toward the 313 million USD range by 2032. This growth is not merely a function of volume; it is rooted in fundamental shifts in how medications are prescribed, dispensed, and monitored.
Several structural forces are accelerating this trajectory. First, healthcare payers and providers are increasingly recognizing that adherence failures represent a hidden tax on clinical outcomes and budget efficiency. Specialty medications, which command premium pricing and complex administration protocols, have claimed a disproportionate share of total drug expenditures in recent years, intensifying the need for packaging systems that reduce dosing errors, simplify refill cycles, and enable remote monitoring. Second, the decentralization of care is reshaping distribution endpoints. As more patients receive chronic therapy outside traditional hospital walls, packaging solutions must bridge the gap between clinical oversight and home-based self-management. Third, digital integration is transitioning from experimental add-on to core architecture. Packaging systems that couple physical dose organization with connectivity, data capture, and clinician-facing dashboards are rapidly becoming the expected baseline rather than the premium tier.
These dynamics create a market environment where growth is both broad and uneven. The research dissects how revenue generation is distributed across packaging formats, care settings, and geographic corridors, revealing where demand is most concentrated and where whitespace opportunities persist. Crucially, the analysis isolates the operational and regulatory factors that determine which manufacturers can scale efficiently and which face margin compression or compliance friction.
Segmentation Architecture and Application Realities
Understanding how the market fragments is essential for product positioning, pricing strategy, and channel selection. The research breaks down the landscape across three primary dimensions: packaging type, end-use application, and regional deployment. Each dimension carries distinct commercial implications.
Packaging Typology and Format Economics
The market is anchored by two broad packaging philosophies: unit-dose systems and multi-dose systems. Unit-dose formats continue to dominate in environments where dose-level precision, traceability, and dispensing control are paramount. These systems are closely aligned with institutional workflows, automated pharmacy line operations, and clinical protocols that require individual dose accountability. Multi-dose formats, by contrast, address convenience, patient experience, and longitudinal adherence tracking. They are increasingly favored in ambulatory care, retail pharmacy fulfillment, and home-based regimens where reducing pill burden and simplifying refill synchronization drive compliance.
The research examines how these formats compete, complement, and increasingly converge through hybrid designs. It also evaluates the capital intensity, throughput requirements, and software dependencies that differentiate the two categories, enabling stakeholders to assess which format aligns with their target customer economics and service models.
Care Settings and End-Use Demand Profiles
Demand is not uniform across points of care. Hospitals represent a substantial and process-driven segment, where adherence packaging is integrated into medication administration workflows, barcoded verification systems, and closed-loop dispensing environments. Retail pharmacies function as a critical distribution node, translating prescription volume into patient-facing compliance tools while navigating space constraints, workforce limitations, and margin pressures. Home care constitutes a rapidly expanding frontier, fueled by remote patient monitoring programs, aging-in-place initiatives, and the shift of chronic therapy management away from acute settings.
Each application segment presents distinct purchasing criteria. Institutional buyers prioritize integration, validation, workflow efficiency, and regulatory alignment. Retail and community pharmacy buyers focus on throughput, packaging flexibility, and patient retention value. Home care stakeholders increasingly emphasize usability, connectivity, and support for caregivers. The report maps these demand profiles to product capabilities, helping manufacturers and investors calibrate feature roadmaps and go-to-market strategies.
Regional Corridors and Deployment Patterns
Geographically, the market reflects uneven maturity, differing reimbursement environments, and localized pharmacy infrastructure. North America remains a dominant demand center, supported by established pharmacy networks, chronic disease prevalence, and early adoption of connected adherence tools. Europe exhibits strong institutional and community pharmacy demand, shaped by national health system structures and evolving digital health frameworks. Asia Pacific represents a high-potential corridor where expanding pharmaceutical access, urbanization, and growing awareness of adherence-linked outcomes are creating new deployment opportunities. Latin America and the Middle East and Africa contribute additional growth vectors, often driven by specific public health programs, private pharmacy expansion, and targeted chronic care initiatives.
Worldwide Medicine Packaging Adhesive Market
Rather than presenting a flat regional snapshot, the research evaluates how local regulatory regimes, distribution density, reimbursement pathways, and care delivery norms shape adoption velocity. This allows clients to prioritize market entry, partnership models, and localization investments with a realistic view of where traction is achievable and what friction points must be addressed.
Competitive Landscape and Strategic Positioning
The Medication Adherence Packaging Systems Market is characterized by a concentrated but dynamically evolving player base. Market concentration metrics indicate that leading participants command meaningful share, yet the space remains open to innovation-driven entrants, especially where digital adherence, automation, and software-enabled workflows create differentiation. Understanding the strategic posture of key incumbents is critical for assessing partnership opportunities, acquisition targets, and competitive threats.
Established Players and Capability Profiles
Medicine-On-Time LLC has built a reputation around multi-dose compliance packaging and customizable adherence workflows for pharmacies and care settings. Its offering centers on structured compliance packaging and software-enabled configuration, positioning it as a partner for organizations seeking to standardize adherence interventions while preserving flexibility across patient populations.
Parata Systems LLC operates at the intersection of automation and packaging format versatility. Its automated blister card and pouch packaging systems are designed to support both single-dose and multi-dose regimens, appealing to pharmacy operations that need throughput, consistency, and scalable deployment across varying prescription volumes.
Omnicell, Inc. brings a broader institutional footprint, combining medication blister card packaging, cup-style adherence formats, and automated dispensing systems tailored to patient-specific multi-dose regimens. Its strength lies in environments where adherence packaging must integrate tightly with dispensing control, inventory management, and clinical workflow oversight.
AARDEX Group represents a distinct digital adherence angle. Its MEMS-enabled packaging and monitoring devices span oral, injectable, and other routes, supported by software platforms intended for clinical trial and patient monitoring contexts. This positions the company at the convergence of packaging, adherence measurement, and data-rich oversight, an increasingly important axis as outcomes-based reimbursement and decentralized trials gain traction.
Recent Developments and Innovation Signals
The competitive field is not static. Recent product launches demonstrate how manufacturers are layering connectivity and cloud-enabled intelligence into adherence tools. In April 2025, Centor Inc. and Gerresheimer AG introduced a smart weekly pill organizer built on LTE and cloud technology, designed to support real-time medication intake monitoring without requiring patient app pairing. This type of development signals a broader shift toward low-friction connectivity, where adherence data can be captured and transmitted without imposing additional burden on patients. For competitors, such moves raise the bar on usability and data accessibility while also reshaping expectations among pharmacy buyers, care providers, and payer-aligned programs.
Medication Adherence Packaging Systems Market
Regulatory and Reimbursement Dynamics
No strategic assessment of this market is complete without addressing the regulatory and reimbursement scaffolding that shapes commercialization. Certain medication adherence packaging systems and blister cards require FDA 510(k) clearance prior to commercialization, meaning time-to-market, validation pathways, and regulatory strategy are integral to competitive positioning. At the same time, digital adherence packaging and devices are increasingly expected to align with frameworks such as FDA 21 CFR Part 11 and ICH GCP compliance, particularly in clinical trial and monitoring contexts where data integrity and auditability are non-negotiable.
Reimbursement dynamics further influence adoption economics. Specialty medications have accounted for a substantial share of total drug expenditures in recent years, reinforcing the financial case for adherence interventions that reduce waste, improve persistence, and support better outcome tracking. However, reimbursement structures vary widely by region, payer type, and care setting. The research analyzes how these reimbursement pressures interact with packaging investment decisions, highlighting where value demonstration, health economics evidence, and integration with care programs can accelerate adoption.
What the Research Delivers
This market research is designed as an operating document for strategic planning, not a static summary. It synthesizes historical performance, forward forecasts, segmentation detail, competitive intelligence, and regulatory context into a coherent decision framework. Stakeholders will find practical value across several dimensions.
- Forecasted market size and growth trajectory across the 2026 to 2032 horizon, anchored in historical baselines and trend analysis
- Segment-level breakdowns by packaging type, application setting, and regional deployment that reveal where demand concentrates and where differentiation matters most
- Competitive profiles that map incumbent capabilities, technology orientations, and strategic focus areas
- Regulatory and reimbursement context that clarifies clearance requirements, compliance expectations, and economic adoption drivers
- Recent product and technology developments that indicate where innovation is heading and how customer expectations are shifting
- Analytical frameworks to support market entry, portfolio prioritization, partnership evaluation, and investment timing
Importantly, the report is structured to support specific business questions: which packaging formats align with target segments, how care setting economics shape purchasing behavior, where regional deployment is most viable, and how digital adherence capabilities are reshaping competitive advantage. The objective is to give executives and analysts a credible foundation for 2026 planning without resorting to generic market commentary.
Why This Research Matters for 2026 Decision-Making
The 2026 decision environment will reward organizations that can align packaging strategy with care delivery realities, regulatory readiness, and digital adoption curves. Companies that treat adherence packaging as a purely mechanical category risk underpricing the strategic value of workflow integration, data capture, and patient experience. Organizations that over-index on connectivity without addressing clearance timelines, reimbursement proof points, or pharmacy workflow constraints will struggle to convert innovation into commercial traction.
This research helps bridge that gap. It provides the macro context needed to set portfolio direction, the segmentation insight required to target the right customers, and the competitive understanding necessary to anticipate moves by entrenched players and emerging challengers. For manufacturers, it informs feature prioritization and capacity planning. For investors, it clarifies where growth is durable versus cyclical. For healthcare and pharmacy stakeholders, it offers a benchmark for evaluating vendor claims and adoption readiness.
Ultimately, the Medication Adherence Packaging Systems Market is entering a phase where scale, precision, and intelligence must coexist. The organizations that succeed will be those that understand not only how large the opportunity is, but how it is constructed, where value is created, and what evidence is required to convert potential into adoption.
Access the Full Intelligence
The excerpts above provide a strategic preview of the market landscape and the analytical depth available in the full report. To move from high-level direction to actionable planning, stakeholders need the complete segmentation values, forecast tables, competitive benchmarks, regional deployment analysis, and regulatory context contained in the full study. The complete research package delivers the granular data and structured conclusions necessary to support investment memos, product roadmaps, partnership evaluations, and market-entry strategies.
For decision-makers preparing for 2026 and beyond, this report offers a disciplined view of where adherence packaging is headed and how to position for the opportunities that follow. Access the full report to retrieve the detailed market size trajectories, segmentation splits, competitive assessments, and scenario-ready insights needed to make informed, evidence-based decisions.
For detailed analysis of this topic, please visit the official page: Medication Adherence Packaging Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Healthcare Furniture Market Hits $708M in 2025, Projects 5.41% CAGR Through 2032
By PW Consulting, 2026-09-16
Strategic Horizons in Healthcare Furniture: Navigating Growth, Compliance, and Competitive Shifts Through 2032
The global healthcare furniture market stands at a critical inflection point. As care delivery models evolve, facility design standards tighten, and capital allocation decisions grow increasingly scrutinized, the physical environment of healthcare spaces is no longer a secondary consideration. It has become a strategic lever that influences patient outcomes, staff retention, operational efficiency, and long-term asset depreciation. Our latest market intelligence assessment, covering historical performance from 2020 through 2025 and projecting forward across the 2026 to 2032 forecast horizon, provides executives, procurement leaders, and product strategists with a structured framework to navigate this complex landscape.
The research is engineered not as an abstract macro exercise, but as an operational decision-support tool. It translates trajectory signals, regulatory shifts, and competitive realignments into actionable intelligence that can inform product roadmaps, facility investment phasing, supply chain positioning, and market entry or expansion strategies. For organizations preparing capital deployments, specification portfolios, or manufacturing capacity adjustments in 2026, the report functions as a calibrated compass rather than a static snapshot.
Macro Trajectory and the Strategic Imperative for 2026 Decision-Making
Over the past half-decade, the sector has demonstrated steady expansion, reflecting sustained investment in care infrastructure, aging facility fleets, and the ongoing modernization of clinical and support environments. Historical revenue progression from the early 2020s through the base year of 2025 illustrates a market that has consistently advanced despite episodic supply chain friction, labor cost pressures, and procurement recalibration. That momentum carries directly into the forecast window, where the trajectory points toward sustained growth at a compound annual rate of 5.41 percent across the 2026 to 2032 period.
Healthcare Flooring Market
For executives planning multi-year commitments, this growth rate is not merely a directional indicator. It signals the pace at which demand will compound across product categories, care settings, and geographies, influencing everything from raw material procurement and manufacturing capacity planning to channel partnerships and specification cycles. The forecast period also captures a structural transition: as healthcare systems balance clinical modernization against constrained operating budgets, furniture procurement is increasingly evaluated through total cost of ownership, lifecycle durability, infection-control compatibility, and staff workflow optimization rather than upfront unit cost alone.
The research unpacks these trajectory dynamics in a way that supports scenario planning. Readers will find forward-looking revenue pathways mapped across the full forecast horizon, alongside the contextual drivers that shape demand elasticity, specification lead times, and replacement cycles. By anchoring 2026 planning decisions to a rigorously constructed outlook, organizations can reduce blind spots around capacity timing, regional allocation, and product mix optimization.
Beyond Headline Numbers: The Operational Depth of the Report
The intelligence architecture within this study is designed to move decisively beyond top-line metrics. While the report captures the full historical arc from 2020 and projects performance through 2032, its core value lies in the granular analytical layers that translate market movement into operational guidance. The study systematically evaluates how demand is distributed across product categories, care environments, and regional markets, providing a clear picture of where volume concentrates, where growth is accelerating, and where substitution or consolidation dynamics are reshaping procurement behavior.
Specifiers and manufacturers will find particular utility in the product-type and application analyses, which illuminate shifting priorities in patient room configuration, caregiver support environments, diagnostic adjacencies, and ambulatory or homecare-adjacent settings. Rather than presenting truncated category snapshots, the report contextualizes each segment within broader operational realities: throughput demands, cleaning and disinfection protocols, ergonomic requirements, footprint constraints, and the growing expectation that furniture actively supports infection-prevention workflows and staff resilience.
Regional demand patterns are examined with equal rigor. The analysis captures how mature markets with entrenched facility renewal cycles compare against emerging demand centers where infrastructure expansion, capacity additions, and modernization investments are reconfiguring procurement pipelines. This regional layering is essential for organizations evaluating export strategies, local assembly or sourcing decisions, specification influence, and channel partnerships. The report deliberately avoids superficial share comparisons, instead focusing on the underlying drivers that determine where sustained revenue opportunity is likely to materialize and where competitive intensity will require differentiated positioning.
Competitive Landscape: Incumbents, Positioning, and Strategic Realignment
The competitive environment in healthcare furniture is defined by a mix of established workplace and healthcare-focused manufacturers, category specialists, and full-facility solution providers. Several players shape the structural dynamics of the market, each with distinct design philosophies, manufacturing footprints, and end-user value propositions.
Steelcase continues to anchor its healthcare offerings around patient seating, waiting environments, examination spaces, and modular casegoods engineered for care settings. Its portfolio reflects a strong emphasis on environmental psychology, flexibility, and specification-grade design that aligns clinical function with patient and visitor experience. Haworth approaches the category with a pronounced focus on caregiver ergonomics, mobile cart ecosystems, height-adjustable workstations, and modular spatial solutions that support both patient-facing and staff-oriented areas. This caregiver-centric lens positions the company well within facilities prioritizing workflow efficiency and staff sustainability.
Hillrom contributes a diversified hospital furniture lineup spanning overbed tables, patient room casegoods, sleeper sofas, and recliners tailored to care environments. Its product architecture aligns closely with the practical demands of inpatient settings, where durability, adjustability, and infection-compatible surfaces are paramount. Spec Furniture has built its reputation on durable seating, overbed tables, patient room casegoods, and cafeteria tables serving hospitals and broader facilities, giving it a strong operational-fit profile for high-use care environments. Carolina extends its reach across patient rooms, staff areas, and full-facility environments, constructing product systems intended to support both healing environments and operational throughput. Trinity Furniture rounds out the competitive set with traditional and transitional wood furniture solutions, including seating and tables designed for patient rooms, behavioral health contexts, and general care facilities.
The market structure reflects meaningful concentration at the top tier, with the three largest players collectively accounting for a substantial share of industry revenue and the top five expanding that footprint further. This concentration matters for procurement strategy, specification influence, pricing expectations, and negotiation leverage. At the same time, the presence of specialized and regional manufacturers sustains competitive pressure in high-use categories and facility-specific applications, ensuring that incumbents must continually justify differentiation through design, service, delivery reliability, and lifecycle performance.
Recent corporate and standards developments further reshape the landscape. The acquisition of Spec Furniture by Flokk in April 2026 signals an intentional expansion of presence in the U.S. healthcare market for seating and tables, consolidating capability and distribution reach at a moment when facility demand remains robust. Simultaneously, the publication of BIFMA G8.1-2026 in February 2026 introduces updated guidance on furniture surface design and durability for cleaning, sanitizing, and disinfecting. For manufacturers and specifiers alike, this standard reframes performance expectations and creates a new reference point for product development, materials selection, and specification documentation.
Healthcare Furniture Market
Market Dynamics Shaping Capital Allocation and Specification Decisions
The operational environment for healthcare furniture is being reshaped by intersecting forces that directly impact procurement timing, specification criteria, and investment prioritization. Regulatory and standards evolution is one of the most consequential. The February 2026 BIFMA guideline on furniture surfaces, cleaning durability, and disinfection compatibility raises the bar for how products must perform in active care environments. This development matters not only for product design teams, but also for purchasing leaders who must validate that specified furniture meets evolving infection-control expectations without compromising aesthetics, flexibility, or lifecycle economics.
Reimbursement and procurement policy dynamics add another layer of complexity. The American Hospital Association has pushed for exemptions from CMS-approved vendor requirements for non-clinical items, including office furniture, signaling that healthcare systems are actively seeking relief from administrative and supply-chain constraints that elevate cost and slow acquisition cycles. This advocacy underscores a broader tension: facility leaders need to upgrade and replace furniture to support care quality and staff retention, yet many operate under procurement frameworks and budget pressures that complicate long-planned capital projects.
Labor economics further complicate the investment equation. The American Hospital Association’s 2025 Health Care Workforce Scan highlighted that hospitals contended with high labor expenses exceeding $42.5 billion during the 2021 to 2023 period, constraining discretionary investment in facility upgrades, including furniture. When operating costs surge, facility modernization can be deferred, but deferral carries its own risk: aging furnishings, workflow friction, and environmental wear can compound operational strain and negatively affect staff experience. The report examines how this cost-pressure environment influences replacement cycles, specification trade-offs, and the growing preference for solutions that demonstrate measurable support for staff efficiency and durability under heavy use.
Taken together, these dynamics create a market where differentiation is increasingly tied to performance evidence, compliance alignment, total cost of ownership, and the ability to support both patient-centered design and caregiver workflow. Organizations that anticipate these shifts and align product development, specification support, and procurement messaging accordingly will be better positioned to capture demand as budgets normalize and facility renewal accelerates.
Why This Research Matters for 2026 Strategy Execution
The strategic value of this report lies in its translation of market trajectory, competitive positioning, and environmental dynamics into practical decision inputs. For manufacturing and product leaders, the research supports portfolio rationalization, material and surface engineering priorities, and category focus decisions in the context of updated durability and cleaning-performance expectations. For commercial and channel teams, it clarifies where specification influence is strongest, which applications are expanding fastest, and how regional demand patterns should inform capacity allocation and market-entry sequencing. For procurement and facilities executives, it provides a structured basis for evaluating replacement timing, total cost of ownership, compliance alignment, and supplier diversification strategies.
The analysis also serves as a strategic alignment tool for organizations evaluating partnerships, acquisitions, or capability expansion. By mapping concentration patterns, category leadership dynamics, and recent corporate activity such as the Flokk-Spec Furniture transaction, the report helps decision-makers assess where consolidation pressure may intensify and where differentiated positioning can create durable advantage. Similarly, the inclusion of regulatory and reimbursement developments ensures that strategic plans account for the policy environment that will shape specification behavior and procurement feasibility across the forecast period.
Most importantly, the research is structured to support executive decision-making under uncertainty. The 2026 to 2032 forecast window captures a period in which healthcare systems are likely to continue balancing modernization goals against operational cost realities. Organizations that approach this environment with rigorous demand visibility, a clear understanding of competitive and standards-driven shifts, and a disciplined view of where value will be captured will be better equipped to make capital, product, and market decisions that hold up over multiple planning cycles.
Accessing the Full Intelligence Framework
This overview has outlined the strategic contours of the healthcare furniture market and the analytical approach underpinning our latest research. It has also highlighted the competitive, regulatory, and cost-environment dynamics that will shape procurement and product strategy in 2026 and beyond. Yet the full decision-support value of the study resides in the comprehensive segmentation depth, forecast continuity, competitive profiles, and scenario-ready datasets that extend well beyond the macro narrative.
Organizations seeking to translate these insights into concrete product, procurement, and growth decisions can access the complete report, which delivers detailed segmentation coverage, forward revenue pathways, competitive benchmarking, and the supporting analytical architecture required for operational planning. For teams responsible for capital allocation, specification strategy, manufacturing planning, or market positioning, the full research provides the granularity needed to move from directional confidence to execution-ready strategy.
For detailed analysis of this topic, please visit the official page: Healthcare Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


