



Category: Healthy Lifestyle
PW Consulting: Laboratory Animal Housing Cage Market to Reach $307.5M in 2025, Grow at 4.45% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for Decision-Makers: The Global Laboratory Animal Housing Cage Market in 2026
The laboratory animal housing cage market sits at the intersection of biopharma innovation, regulatory evolution, and operational efficiency. For executives, procurement leaders, and R&D strategists, understanding the trajectory of this specialized infrastructure market is not merely an operational concern—it is a strategic imperative. Our latest comprehensive market research on the Laboratory Animal Housing Cage Market provides a rigorous, data-driven foundation for 2026 decision-making, mapping historical performance, forecasting growth through 2032, and dissecting the competitive, regulatory, and technological forces that will shape procurement strategies, facility investments, and partnership opportunities in the coming years.
This article serves as a strategic preview of the full study. It outlines the analytical architecture, highlights the macro market trajectory, contextualizes the regulatory and competitive landscape, and demonstrates how the complete report translates complex intelligence into actionable frameworks for enterprise planning.
Market Trajectory: From Baseline to Forecast Horizon
The market has demonstrated resilient, structurally supported growth over the historical reference period, reflecting sustained demand from research institutions, contract research organizations, and pharmaceutical developers. Our analysis establishes a clear baseline trajectory, with market revenue climbing from approximately 247.8 million USD in 2020 to 307.5 million USD in 2025. This progression underscores a market that has absorbed operational disruptions, adapted to evolving husbandry standards, and continued to expand in line with broader life sciences investment cycles.
Looking ahead, the forecast window from 2026 through 2032 projects continued expansion, with an estimated CAGR of 4.45 percent. The forward curve suggests that demand will be driven by a combination of facility modernization, heightened emphasis on animal welfare and reproducibility, and the gradual uptake of advanced housing architectures across regions and research applications. By 2032, the market is positioned to cross 400 million USD in annual revenue, a threshold that signals both mature adoption in established markets and meaningful growth momentum in emerging research ecosystems.
Importantly, this trajectory is not uniform. The interplay of regional research intensity, species-specific housing requirements, and material-technology preferences introduces structural variation across market segments. The complete report quantifies these variations with disciplined granularity, allowing decision-makers to align procurement roadmaps and capital allocation with the most relevant demand vectors for their operational footprint.
Report Architecture: From Macro Trends to Operational Playbooks
The full study is designed to function as a decision-support instrument rather than a static data repository. Its architecture moves from macro market structure to segment-level dynamics, then to competitive positioning, regulatory mapping, and forward-looking scenario analysis. Each section is anchored by customizable modeling inputs, enabling clients to stress-test assumptions against their own facility portfolios, geographic exposure, and research pipelines.
Key analytical components of the report include:
- Macro market sizing and forecast modeling across the 2020–2032 horizon, with explicit base-year calibration and scenario sensitivity around adoption velocity and capital expenditure cycles.
- Segment-level demand mapping that distinguishes between housing material architectures, species and application categories, and regional research infrastructure profiles, allowing organizations to isolate the demand pools most relevant to their product or service strategy.
- Competitive landscape assessment covering ten leading suppliers, with company profiles, product-system specializations, and a timeline of recent commercial and strategic moves that signal where the market is heading.
- Regulatory and compliance mapping that translates directives, accreditation requirements, and institutional guidance into operational implications for cage design, ventilation standards, sanitation schedules, and environmental control.
- Inventory of industry dynamics and ecosystem signals, including trade engagement, educational program expansion, partnership activity, and product-introduction cadence, that together reveal the cadence of innovation and market entry.
By structuring the analysis in this way, the report enables executives to answer practical questions: where is demand most concentrated, which housing platforms are gaining traction, how do compliance requirements translate into procurement specifications, and which supplier capabilities are becoming differentiators rather than table stakes.
Regulatory Dynamics as a Demand Catalyst
Regulatory and accreditation frameworks are not peripheral constraints; they are structural drivers of housing specification, replacement cycles, and facility upgrade spending. Across major research jurisdictions, animal welfare standards, environmental control expectations, and reproducibility mandates are progressively tightening, compelling institutions and service providers to align infrastructure with documented compliance requirements.
The complete report synthesizes multiple layers of regulatory context into an actionable dynamics section. This includes how requirements for environmental enrichment, temperature stability, humidity control, and minimum cage dimensions influence housing system design and procurement specifications. It also addresses how accreditation frameworks and institutional oversight create consistent demand for certified housing solutions that support animal welfare, biosecurity, and research reproducibility. Furthermore, the analysis maps sanitation frequency expectations and microenvironmental monitoring protocols, showing how modern individually ventilated cage architectures can align with operational efficiency targets while maintaining compliance.
For strategic planners, the regulatory dimension is best understood as a forcing function. As institutions seek to harmonize welfare standards with throughput goals and environmental control precision, investment flows toward housing systems that integrate ventilation performance, sanitation durability, and compatibility with monitoring or tracking technologies. The report quantifies the magnitude of these influences and maps them to realistic procurement and capital planning horizons.
Competitive Landscape: Ten Anchors and a Shifting Innovation Frontier
The market is characterized by meaningful concentration among established suppliers, with a closely contested field of specialized manufacturers competing on system architecture, durability, compliance alignment, and digital integration. The report profiles ten core companies, each with distinct positioning across plastic and metal housing platforms, individually ventilated cage systems, large-animal housing solutions, and specialty accessories or environmental control equipment.
Laboratory Animal Housing Cage Market
Several competitive themes emerge from the profile set. First, a growing emphasis on modular, reusable, and high-density housing platforms reflects the pressure to optimize facility space while maintaining throughput and welfare standards. Second, the integration of RFID census compatibility, ergonomic handling features, and digital ventilation control points toward an operational shift from static housing to data-enabled environment management. Third, durability claims around repeated autoclave cycling and multi-species versatility are becoming material evaluation criteria for procurement teams weighing lifecycle cost against upfront specification.
The full report situates these profiles within a structured competitive analysis, including concentration metrics that illustrate the degree of market consolidation and the strategic implications for sourcing strategy, supplier diversification, and partnership development. Rather than presenting company information in isolation, the study maps competitive capabilities against the demand segments they serve, helping clients identify where incumbents hold structural advantages and where whitespace may exist for differentiated offerings or specialized contracting models.
Worldwide Animal Workstation Market
Recent Commercial and Strategic Signals
Competitive dynamics are not static; they are continuously reshaped by trade engagement, partnership formation, product introductions, and educational outreach. The report captures a curated set of recent developments that reveal how leading suppliers are positioning themselves for the next phase of market growth.
Several patterns stand out in the recent activity set. Trade-show participation and conference presence continue to function as core visibility channels, with leading firms showcasing next-generation housing systems, ventilation platforms, and husbandry-integrated equipment to research and facility audiences. At the same time, educational programming is increasingly used not only for brand visibility but also to deepen engagement around husbandry best practices and housing equipment integration, reinforcing long-term relationships with research communities.
On the product and partnership side, recent moves indicate a strategic pivot toward AI-enabled monitoring integrations, ergonomic and reusable housing designs, and RFID-compatible census systems. These developments suggest that suppliers are responding to facility-level pressures around space utilization, operational consistency, and data-driven animal management. For procurement and R&D leaders, the signal is clear: housing decisions are increasingly inseparable from broader facility technology strategies.
The complete report integrates these developments into a timeline and competitive-context framework, allowing clients to interpret commercial activity not as isolated announcements but as indicators of strategic direction, capability investment, and likely future specification trends.
Implications for 2026 Enterprise Decision-Making
As organizations plan for 2026 and beyond, the Laboratory Animal Housing Cage Market presents both operational leverage points and strategic choices. The forecast trajectory implies sustained demand, but the value of the market research lies in its ability to convert that broad expectation into segment-specific, regulation-aware, and competition-grounded guidance.
For facility operators and institutional buyers, the report informs specification decisions, replacement-cycle planning, and supplier evaluation by linking compliance requirements and welfare expectations to housing architecture choices. For equipment and system suppliers, it clarifies where differentiation is accruing—whether through ventilation performance, durability, digital integration, or multi-species versatility—and how competitive concentration shapes go-to-market positioning. For investors and strategic partners, the study provides a structured view of demand geography, material and application preferences, and the cadence of innovation activity that underpins near-term commercial opportunities.
The analysis also supports scenario planning. Because the market is shaped by research funding cycles, regulatory interpretation, and facility modernization timing, decision-makers benefit from models that test how changes in adoption velocity, compliance stringency, or regional research intensity alter demand outcomes. The full report embeds this flexibility into its forecasting and segmentation structure.
Why the Complete Study Matters
A preview can establish direction, but operational decisions require specificity. The complete Laboratory Animal Housing Cage Market research delivers the detailed segment breakdowns, regional demand context, application-level sizing, material-technology splits, and supplier-level competitive inputs that executives need to move from directional confidence to precise planning. It pairs quantitative rigor with qualitative insight, ensuring that forecasts are grounded in observable market structure and that competitive interpretation is tied to documented product, partnership, and event activity.
Most critically, the study is built to be used. Its segmentation logic, competitive mapping, and regulatory-context synthesis are designed to inform procurement specs, sourcing diversification, capital planning, and product strategy. For organizations operating in biomedical research, contract services, or laboratory infrastructure, the report transforms a complex, regulation-shaped market into a navigable strategic map.
Access the Full Intelligence
This preview has outlined the analytical scope, the macro trajectory, the regulatory and competitive context, and the decision-making value of the study. The full report extends this foundation into detailed segment breakdowns, supplier-level competitive analysis, and customizable forecasting frameworks that allow your organization to align strategy with the most relevant demand signals.
To access the complete dataset, segment-level intelligence, and competitive profiles that underpin this analysis, request the full report through our official research portal. The complete study provides the depth, granularity, and applied frameworks required to support confident 2026 planning and multi-year capital and sourcing decisions.
For detailed analysis of this topic, please visit the official page: Laboratory Animal Housing Cage Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Sea Water Nasal Spray Market to Hit $344.4M by 2032, 6.7% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Sea Water Nasal Spray Market: Navigating Growth and Regulatory Complexity in 2026
The global sea water nasal spray market stands at a critical inflection point as we move through 2026. What was once a niche segment within the broader respiratory care and over-the-counter pharmaceutical landscape has matured into a structured, regulation-driven industry with clear growth trajectories. For executive teams, procurement leaders, and strategic planners, understanding the nuances of this market is no longer optional. It is a prerequisite for capital allocation, portfolio expansion, and competitive positioning.
This article serves as a strategic preview of PW Consulting's latest comprehensive market research on the Sea Water Nasal Spray Market. Rather than offering superficial summaries, this research is designed to equip decision-makers with the operational clarity needed to navigate a market shaped by tightening regulatory frameworks, shifting reimbursement dynamics, and an increasingly consolidated competitive landscape. The following analysis outlines the macro-level momentum, the structural forces redefining industry playbooks, and the granular operational insights contained within the full report.
Market Momentum: A Decade of Reinforced Growth Trajectory
The historical record from 2020 through 2025 tells a consistent story of resilience and incremental expansion. Revenue across the global sea water nasal spray market climbed steadily from approximately 173.4 million USD in 2020 to an estimated 220.5 million USD by 2025. This trajectory reflects more than post-pandemic recovery patterns; it signals a structural shift in consumer and clinical preferences toward non-pharmacological respiratory interventions, saline-based hygiene routines, and pediatric ENT care solutions that prioritize minimal side-effect profiles.
Looking forward, the forecast period spanning 2026 through 2032 projects sustained momentum, with the market expected to reach approximately 344.4 million USD by the end of the forecast horizon. This expansion is underpinned by a compound annual growth rate of 6.7 percent, a figure that places the category above many traditional OTC segments but below the hypergrowth rates of novel biologics. For strategic planners, this middle-ground growth profile carries an important implication: the market rewards operational efficiency, regulatory compliance, and disciplined brand positioning far more than it rewards speculative capacity expansion.
It is worth noting that the growth curve is not uniform across all horizons. The early forecast years show measured acceleration, while later periods reflect compounded adoption in emerging clinical pathways and retail channels. Companies that treat this as a linear growth story risk misallocating resources. The full research decodes the pacing of this expansion across different commercial contexts, giving leadership teams the ability to time inventory commitments, marketing investments, and partnership negotiations with greater precision.
Structural Forces Redefining the Competitive Landscape
No market analysis is complete without a clear view of the forces that determine who wins share and who gets squeezed out. In the sea water nasal spray segment, three overlapping dynamics are reshaping the playing field: regulatory classification, reimbursement access, and manufacturing cost pressures.
Regulatory Classification and Compliance Burden
Under the EU Medical Device Regulation 2017/745, nasal spray medical devices are classified as Class IIa. This classification is not merely a bureaucratic label; it carries direct operational consequences. Manufacturers must maintain post-market clinical follow-up studies to demonstrate established performance and safety data over time. The burden of continuous evidence generation favors players with established clinical infrastructures and penalizes those who treat regulatory compliance as a one-time checkpoint.
On the other side of the Atlantic, the FDA's guidance for industry on nasal spray and inhalation solutions reinforces sterility as a non-negotiable baseline. All aqueous-based sea water nasal spray products must be manufactured and labeled as sterile, with validated sterility assurance and preservation effectiveness. For unit-dose formats, sterility maintenance is ensured through validated manufacturing processes and expiration dating designed to prevent microbial contamination. These requirements create a high barrier to entry for new formats and geographic expansion, while simultaneously raising the operational cost of compliance for incumbents.
Reimbursement Pathways and Access Economics
Reimbursement dynamics add another layer of complexity. In multiple European nations, physiological sea water nasal sprays receive partial or full reimbursement coverage when prescribed for chronic rhinosinusitis or recurrent acute sinusitis through hospital pharmacy channels. This pathway creates a dual-demand environment: consumer-driven retail purchases coexist with clinically prescribed, reimbursement-backed consumption. Companies that understand how to position products across both channels, and how to navigate the documentation requirements that unlock reimbursement, gain a structural advantage in volume and margin stability.
Material Cost Pressures and Sourcing Realities
Raw material economics also exert pressure on affordability and margin architecture. Sea water source acquisition costs have tightened affordability for manufacturers, particularly for hypertonic and isotonic formulations derived from clean Brittany coast sources. The geographic concentration of premium sourcing locations means that supply chain resilience, long-term extraction agreements, and cost-pass-through strategies are now central to competitive positioning. The full report details how leading players are restructuring their sourcing strategies to protect margins without compromising the purity standards that clinicians and regulators demand.
Competitive Landscape: Concentration, Capabilities, and Recent Moves
The market's competitive structure reflects moderate consolidation. The top three players command a combined share of approximately 32.5 percent, while the top five extend that concentration to 48.2 percent. This distribution indicates a market where leading incumbents hold meaningful but not insurmountable advantages, leaving room for specialized players and regional challengers to compete on formulation quality, clinical evidence, and channel access.
Key Players and Strategic Footprints
Several French and European manufacturers anchor the competitive core, each with distinct strategic orientations:
- Sofibel SAS has built its positioning around targeted offerings for the sea water nasal spray market, with recent emphasis on clinical validation. A multicentre clinical trial completed in October 2024 evaluated Stérimar Blocked Nose and Stop & Protect Baby nasal sprays for nasal congestion in infants aged 3 to 48 months. This study underscores a broader industry shift toward evidence generation in pediatric use cases, where safety perception and clinical endorsement drive repeat purchase behavior.
- Laboratoires Gilbert SAS continues to reinforce its presence through the Marimer brand, aligning product development with the segment's demand for physiologically aligned sea water formulations. Its strategy reflects a consistent focus on formulation integrity and channel distribution that spans both pharmacy and retail environments.
- Urgo Group leverages its Humer brand to compete in a space where respiratory comfort and nasal hygiene intersect. The group's broader OTC portfolio provides cross-promotion opportunities and distribution leverage, allowing it to bundle sea water nasal spray offerings within wider consumer health journeys.
- Quinton Marine Water Biotechnology Laboratory operates at the intersection of marine biotechnology and nasal care, emphasizing the biological properties of marine water in its product philosophy. This positioning appeals to consumers and clinicians who value the mineral and trace-element profile associated with marine-sourced solutions.
- Gerolymatos International S.A. has emerged as a particularly active strategic mover. In October 2025, the company completed the sale of its Italian affiliate Foltene Laboratories SRL, a transaction that expanded its portfolio of sea water-based nasal sprays under private label. This move illustrates a growing trend: companies are using affiliate restructuring and private-label expansion to broaden reach without incurring the full cost of standalone brand building in every market.
The strategic implications of these profiles are explored in depth within the full research, where each player's product architecture, clinical investments, and channel tactics are mapped against market share dynamics and regional demand patterns.
Operational and Clinical Developments Shaping 2026 Decision-Making
Beyond structural forces, recent operational events provide a real-time window into how leading players are investing for the medium term.
In February 2025, Sterimar launched the new Stérimar Baby Microspray Nasal Hygiene product, an initiative that was recognized with an award for Best Nasal Spray Hygiene under the Baby category. Product-line extensions in the infant and child segments carry outsized strategic importance because early-life adoption often translates into long-term brand loyalty and household repeat purchase patterns. The award recognition also signals that competitive differentiation in this segment is increasingly tied to usability, delivery mechanism design, and parent-facing safety messaging.
Gerolymatos International S.A. further reinforced its clinical credibility in May 2026, when a real-world survey was published on the efficacy of Sinomarin hypertonic sea water nasal drops for infants with ENT conditions in hospital settings. The publication, appearing in the Journal of Clinical Investigation and Medical Case Reports, adds to the growing body of real-world evidence that manufacturers are using to support reimbursement arguments, prescriber confidence, and differentiation from less-documented competitors. The full report examines how such clinical outputs are being integrated into go-to-market strategies and what they mean for future evidence-generation roadmaps.
What the Full Research Delivers for Strategic Planning
Market summaries can signpost direction, but they rarely provide the operational granularity that executives need to act. PW Consulting's full Sea Water Nasal Spray Market research is built to bridge that gap. The report moves beyond headline figures to deliver a structured, decision-ready anatomy of the market.
Comprehensive Market Sizing and Forecast Architecture
The research provides a detailedRevenue trajectory across the historical window of 2020 through 2025 and the forecast period of 2026 through 2032, all denominated in USD million. Rather than presenting growth as a single line, the analysis decomposes the trajectory into context-rich explanations of what is driving acceleration, what is constraining it, and where inflection points are likely to appear.
Segment-Level Intelligence Without the Noise
A major strength of the report is its treatment of segmentation. The analysis examines type-based distinctions across isotonic, hypertonic, and hypotonic sea water nasal sprays, explaining how each formulation category serves different clinical intents, consumer preferences, and pricing dynamics. It also explores application-based demand patterns across infants, children, and adults, highlighting how usage contexts shape packaging choices, delivery mechanisms, and marketing messaging. Regional demand architecture is similarly unpacked, giving planners a clear view of where volume concentrates, where growth is emerging, and where market maturity is reshaping competition. Importantly, the full report presents these segmentations in a way that supports scenario planning rather than static target-setting.
Competitive Profiling and Strategic Event Tracking
Beyond market structure, the research delivers company-level intelligence on the key players shaping the category. Each profiled enterprise is assessed for its strategic orientation, product architecture, and recent operational moves. The report also tracks meaningful events, such as product catalog releases, clinical study completions, product line expansions, and affiliate transactions, and interprets what these events signal about future capacity, evidence generation, and market access strategies.
Regulatory and Reimbursement Navigation
Given the Class IIa classification under EU MDR and the sterility expectations articulated in FDA guidance, the report dedicates substantial attention to regulatory navigation. It translates regulatory requirements into operational implications, helping teams understand what post-market clinical follow-up demands, sterility validation, and labeling expectations mean for time-to-market, cost structures, and audit readiness. The reimbursement section maps where physiological sea water nasal sprays gain partial or full coverage, what conditions trigger access, and how hospital pharmacy channels influence demand stability.
Sea Water Nasal Spray Market
Sourcing, Cost, and Margin Dynamics
The research also addresses the material cost environment, particularly the tension between premium sea water sourcing and affordability constraints. By examining how acquisition costs affect formulation strategies and pricing architecture, the report equips pricing leaders and supply chain planners with the context needed to design cost-pass-through mechanisms, protect margin pools, and evaluate sourcing diversification options.
Saline Nasal Mist Market
Why This Research Matters for 2026 Decisions
The 2026 decision environment demands more than directional confidence. It requires an understanding of how regulatory compliance costs interact with reimbursement opportunities, how clinical evidence translates into prescriber and consumer trust, how sourcing constraints shape margin architecture, and how competitive concentration influences the room available for new entrants or regional expansion.
PW Consulting's Sea Water Nasal Spray Market research is designed for leaders who need to answer concrete questions: Where should portfolio investment be directed across formulation types? How should companies position for reimbursement access in European hospital pharmacy channels? What competitive responses are likely from incumbents already investing in clinical studies and product-line extensions? How should pricing and sourcing strategies adapt to tightening acquisition costs?
The full report provides the structured answers, supported by data-rich market sizing, segmentation analysis, competitive profiling, and regulatory context. It is built to support scenario planning, investment prioritization, and strategic positioning in a market that rewards disciplined execution over speculative expansion.
For executives and strategy teams planning their next moves in the sea water nasal spray category, the complete research offers the depth required to convert market intelligence into actionable strategy. The macro trajectory is clear; the operational path to capturing value within that trajectory is what the full report is built to clarify.
For detailed analysis of this topic, please visit the official page: Sea Water Nasal Spray Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Total Artificial Heart Market Hits $76M in 2025, Projected to Reach $161M by 2032 at 11.5% CAGR
By PW Consulting, 2026-09-16
Strategic Horizons in Total Artificial Heart Market: A 2026 Decision Framework
The landscape of advanced heart failure treatment is undergoing a structural shift. As surgical techniques mature and patient demographics evolve, the demand for durable mechanical circulatory support continues to outpace traditional transplant availability. For executives, investors, and clinical strategy leaders, the Total Artificial Heart market represents both a complex regulatory challenge and a high-conviction growth opportunity. Our latest research publication dissects this ecosystem with the granularity required to map out actionable pathways through 2032.
This article serves as a strategic preview of the full report. It highlights the macro trajectory, competitive inflection points, and structural dynamics that will define capital allocation and product development decisions in 2026. The detailed segmentation matrices, regional revenue breakdowns, and application-specific forecasts remain reserved for the complete intelligence package, ensuring that our clients receive a comprehensive, uncompromised view when they access the full dataset.
Market Trajectory and Growth Architecture
The Total Artificial Heart market has demonstrated consistent expansion over the past half-decade, recovering from early pandemic-era disruptions and accelerating as clinical protocols stabilize. The macroeconomic foundation of this growth is anchored in a clear upward revenue curve. From a baseline in the mid-40 million USD range in 2020, the market advanced to approximately 76.0 million USD by 2025, reflecting an environment where clinical adoption, favorable reimbursement frameworks, and iterative device engineering have reinforced one another.
Looking toward the forecast horizon, the market is projected to reach 82.2 million USD in 2026, with a sustained compounding trajectory that pushes total revenue past 161.0 million USD by 2032. This expansion is underpinned by a forecasted CAGR of 11.5 percent, a rate that signals more than incremental volume growth. It indicates a structural broadening of clinical indications, deeper penetration in established centers of excellence, and the gradual entry of next-generation electromechanical platforms into commercial pathways.
For corporate strategists, understanding the timing and shape of this curve is essential. Growth is not distributed uniformly across the forecast window. The 2026 to 2028 period marks a consolidation and scaling phase, where early commercial adopters and regulatory approvals begin translating into recurring procedural volume. Beyond 2029, the market trajectory steepens, driven by expanded destination therapy protocols, evolving bridge-to-transplant algorithms, and the commercialization of devices designed to reduce long-term complications. Our full analysis isolates these inflection intervals, allowing leadership teams to synchronize R&D pipelines, manufacturing capacity, and market access strategies with precise temporal demand signals.
Competitive Landscape and Innovation Frontiers
The Total Artificial Heart arena is defined by a concentrated yet rapidly evolving competitive field. Market leadership has historically been anchored by a single dominant platform with the broadest regulatory clearance and the most extensive clinical track record. This incumbent profile remains the only FDA- and Health Canada-approved total artificial heart for bridge-to-transplant use in the United States and Canada, supported by a substantial implant base exceeding 2,100 procedures. Its continued relevance is reinforced by durable reimbursement coverage, including CPT codes for implantation and replacement that are recognized by major private payers, Medicare, and state Medicaid programs for bridge-to-transplant indications.
However, the competitive architecture is no longer a one-player narrative. Industry momentum is increasingly shaped by differentiated engineering philosophies and targeted regulatory strategies. BiVACOR has emerged as a notable innovator, leveraging MAGLEV technology to pursue a next-generation total artificial heart platform. Its clinical progression has been accelerated by regulatory milestones, including FDA Breakthrough Device Designation and acceptance into the FDA Total Product Life Cycle program, positioning it as a key watchpoint for executives tracking the convergence of magnetic levitation engineering and circulatory support. Parallel developments are evident in the European market, where CARMAT has advanced its Aeson platform into commercial supply following CE-mark recognition under updated Medical Devices Regulation requirements. With more than 100 implants achieved, the Aeson family contributes to a broader geographic and technical diversification of the global supply base.
The competitive field also includes emerging entrants whose clinical and preclinical data are beginning to influence procurement expectations. Recent announcements underscore the pace of real-world evidence generation and iterative design optimization. A significant clinical outcome communication highlighted a successful four-year bridge-to-transplant case using an established total artificial heart platform, with the patient ultimately receiving a donor heart after extended support duration. This outcome reinforces the growing confidence in long-duration mechanical support as a reliable bridge strategy. In parallel, an independent in vitro study published by a developing entrant demonstrated that its device generated approximately half the hemolysis observed in a legacy pneumatic platform, pointing toward a clinically meaningful reduction in blood damage. These developments matter because hemocompatibility, durability, and operational simplicity increasingly determine procurement preferences as centers compare long-term risk profiles across competing systems.
Market concentration data further illuminates competitive strategy. The top three participants account for a modest share of total revenue, and the top five collectively remain below a thirty percent threshold. This relatively fragmented structure suggests that while incumbency and regulatory clearance provide meaningful advantages, the market is open to differentiated innovation, targeted geographic expansion, and specialist center adoption. For strategists, this means competitive positioning must be built on a combination of clinical evidence, regulatory agility, reimbursement fluency, and service-and-support excellence rather than scale alone.
Structural Dynamics Shaping 2026 Decisions
Market growth in 2026 is not solely a function of device availability. It is shaped by intersecting regulatory, reimbursement, and clinical workflow dynamics that determine how quickly new technologies can move from approval to routine use. On the regulatory front, the United States continues to operate under a framework where only one total artificial heart platform currently holds FDA approval for bridge-to-transplant indication. This concentration of cleared options influences hospital procurement pathways, clinical trial design, and the strategic timing of competitor submissions. At the same time, regulatory engagement in other regions is advancing, as seen with updated CE marking under MDR requirements for a European platform, signaling that multinational commercialization strategies must be calibrated to region-specific evidentiary and documentation expectations.
Reimbursement architecture remains a decisive commercial variable. Broad coverage for implantation and replacement procedures under major payer categories has reduced a key barrier to adoption for bridge-to-transplant use. Yet, as destination therapy use expands and longer support durations become more common, payer scrutiny around cost-effectiveness, patient selection criteria, and downstream care pathways is likely to intensify. Decision-makers in 2026 must therefore evaluate not only device performance but also the total economics of care delivery, including hospitalization patterns, complication management, and post-implant service infrastructure.
Clinical adoption is also being reshaped by data streams that compare platform performance on outcomes that matter to transplant programs and advanced heart failure centers. Hemocompatibility, support duration, reliability, and adverse event profiles increasingly differentiate otherwise similar devices. As published evidence accumulates around reduced hemolysis and extended bridge-to-transplant durability, procurement committees will weigh these attributes alongside surgical familiarity and institutional experience. This environment favors suppliers that can pair robust clinical evidence with clear value communication and dependable service networks.
What the Full Report Delivers
The complete Total Artificial Heart Market researchstudy translates the macro trajectory and competitive context into an operational intelligence framework designed for 2026 planning. The analysis is structured to support market entry assessments, portfolio prioritization, partnership evaluation, and regional expansion planning. Rather than offering high-level commentary, the report builds an evidence-linked narrative that connects device technology evolution, regulatory milestones, reimbursement realities, and center-level adoption patterns to the financial and strategic implications for stakeholders.
- Comprehensive market sizing and forecast architecture spanning the historical reference period through 2032, with segmentation designed to support demand modeling and scenario planning.
- Technology and platform evaluation that frames pneumatic, electric, and other device categories in terms of engineering design, clinical positioning, and adoption readiness without oversimplifying trade-offs.
- Competitive profiling of leading and emerging participants, including headquarters location, regulatory status, clinical track record, and innovation direction, enabling benchmarking and partnership screening.
- Deep-dive analysis of market dynamics, including regulatory pathways, payer coverage behavior, procedural coding context, and clinical workflow factors that influence procurement timing.
- Regional and application-oriented insight structures that allow teams to evaluate where procedural volume, reimbursement access, and center readiness align with commercial objectives.
- Recent development tracking, including clinical outcome announcements, in vitro performance comparisons, and regulatory designations, integrated into a forward-looking interpretation of market momentum.
Importantly, the full report preserves confidentiality on sensitive segment proportions and localized revenue splits. This ensures that clients receive a complete analytical framework while detailed share distributions and region-specific figures remain part of the controlled intelligence deliverable. The result is a decision-ready document that supports internal alignment, investor communications, and executive planning without prematurely disclosing proprietary segmentation values.
Implications for 2026 Strategy
For organizations operating in or evaluating entry into advanced heart failure device markets, 2026 is a year of positioning. The convergence of durable bridge-to-transplant outcomes, evolving destination therapy considerations, and differentiated device technologies is expanding the scope of strategic options. Yet, the market also demands disciplined interpretation of regulatory status, reimbursement coverage, and real-world performance data. Companies that can distinguish between headline momentum and actionable evidence will be better placed to allocate resources, time product launches, and build credible value narratives for clinical and payer audiences.
Total Artificial Heart Market
Artificial Heart Lung Machines Market
Several strategic priorities emerge from the current environment. First, evidence generation and clinical engagement must remain central, because procurement decisions increasingly depend on comparative performance data and long-duration support outcomes. Second, regulatory strategy should be treated as a multi-market undertaking, with attention to the distinct clearance and certification expectations that shape commercial readiness across regions. Third, service delivery, training, and hospital workflow integration are becoming competitive differentiators as procedural volume grows and centers compare total cost of care rather than device price alone. Fourth, partnership and licensing opportunities may accelerate as organizations seek to combine engineering innovation with established clinical networks and market access capabilities.
The growth rate implied by the forecast period suggests that early movers who align their capabilities with the right indications, geographies, and service models can capture disproportionate value as the market scales. At the same time, the fragmented competitive structure indicates that differentiation remains achievable for new and emerging participants who can demonstrate compelling clinical and operational advantages. The full report is designed to help leaders test these assumptions against detailed data, assess potential entry points, and construct plans that are robust across multiple demand and regulatory scenarios.
Access the Complete Intelligence
The Total Artificial Heart Market researchstudy provides an integrated view of market size, segmentation architecture, competitive dynamics, and regulatory-reimbursement context, structured for immediate application in 2026 strategic planning. This preview has outlined the broad growth trajectory, the competitive and innovation landscape, and the structural forces that will shape adoption and commercialization decisions. It has intentionally omitted the detailed segment proportions and regional revenue distributions that form the analytical backbone of the full publication.
For decision-makers who require precise market sizing, segmentation splits, and scenario-ready forecasts to support budgeting, market entry analysis, and portfolio strategy, the complete report offers the depth needed to move from directional insight to execution-ready intelligence. Accessing the full dataset will enable your team to evaluate where growth is concentrated, how platform technologies compare across clinical and commercial dimensions, and which market dynamics are most likely to influence your positioning through 2032.
For detailed analysis of this topic, please visit the official page: Total Artificial Heart Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Smart Doorbell Market to Hit $1.88B by 2032 at 17.9% CAGR, Says PW Consulting Report
By PW Consulting, 2026-09-16
Navigating the Smart Doorbell Market: Strategic Intelligence for 2026 and Beyond
The smart doorbell market has evolved from a niche accessory into a cornerstone of the broader connected home and physical security ecosystem. As we move deeper into 2026, enterprises, investors, and technology strategists must look beyond surface-level adoption narratives and understand the structural forces shaping revenue trajectories, competitive positioning, and regulatory readiness. Our latest market research delivers precisely that analytical architecture. Built on a rigorous historical foundation spanning 2020 through 2025 and extended through a detailed forecast window to 2032, this study transforms fragmented industry signals into a cohesive decision-making framework. For executive teams navigating product roadmaps, channel strategy, or M&A evaluation, the report functions as both a compass and a calibration tool.
Macro Trajectory and the 2026 Inflection Point
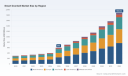
The market's expansion over the past half-decade demonstrates a consistent upward arc, but the true strategic significance lies in how momentum accelerates rather than merely sustains. Historical revenue climbed steadily from approximately $300 million in 2020 to $401.26 million in 2024, reflecting mature consumer electronics adoption curves and incremental smart home penetration. The 2025 baseline of $595 million marks a pronounced step-change, signaling that market maturation has triggered a new growth regime rather than a plateau. Looking ahead, our forecast maps a clear trajectory toward $710.07 million in 2026, accelerating through $1.005 billion around 2028, and ultimately approaching $1.884 billion by 2032.
Underpinning this expansion is a forecasted compound annual growth rate of 17.9 percent across the 2026 to 2032 horizon. For strategic planners, this figure is not merely a growth statistic; it is a timing signal. An expansion rate at this level implies that early-mover advantages in ecosystem integration, manufacturing scale, and regional compliance infrastructure will compound rapidly. Enterprises that treat 2026 as a baseline planning year rather than a continuation of prior-year assumptions will find themselves either capturing disproportionate share or scrambling to retrofit capabilities under tighter margin conditions.
Competitive Architecture: Differentiating in a Crowded Field
The smart doorbell landscape is defined by a diverse set of players, each anchoring their offerings to distinct technological philosophies and ecosystem strategies. Analyzing these positions is essential because competitive advantage in this category no longer stems from hardware specifications alone; it emerges from how product architecture aligns with customer retention models, subscription economics, and interoperability expectations.
Amazon-owned Ring continues to leverage its dominant consumer footprint through both battery-powered and wired video doorbells, emphasizing two-way audio, package detection, and seamless integration within the Amazon retail and services ecosystem. Its scale and brand recognition create a persistent reference point against which rivals measure market entry and feature parity. Meanwhile, TP-Link has pushed differentiation through its Tapo series, offering dual-powered 2K+ video doorbells with AI detection while explicitly addressing a growing consumer preference for no-subscription cloud options.
Ubiquiti Inc. occupies a different strategic niche. The UniFi G4 Doorbell Pro targets prosumer and integrated security environments with advanced package detection, an integrated chime, and tight coupling with the UniFi Protect ecosystem. This positioning reflects a broader market split between mass-market plug-and-play solutions and infrastructure-oriented deployments that value centralized management. REOLINK follows a similar practical differentiation path, offering WiFi and PoE models with 2K+ resolution, local NVR storage, and AI features that eliminate recurring subscription dependencies.
In the residential and smart-home automation segment, Lumi United Technology Co., Ltd. has advanced its Aqara Video Doorbell G4 with facial recognition capabilities, local storage architecture, and HomeKit Secure Video support. This aligns with a consumer base that prioritizes privacy, interoperability within Apple-centric households, and reduced reliance on third-party cloud infrastructure. Anker Innovations Co., Ltd. has pursued a complementary strategy through its eufy Video Doorbell E340 and related models, featuring a dual-camera setup and local storage to appeal to users seeking broader field coverage without recurring fees.
Amazon's Blink brand continues to extend its reach with an emphasis on long battery life, two-way talk, and Alexa integration, while SimpliSafe, Inc. connects its Video Doorbell Pro to professional monitoring and no-contract security system compatibility, effectively bridging DIY smart home devices with traditional security service expectations. Arlo Technologies, Inc. rounds out this competitive field with its 2K Video Doorbell emphasizing wide-angle lens design, color night vision, and Arlo Secure cloud storage.
What makes this competitive mosaic strategically significant is that rivalry no longer operates along a single axis. Differentiation now spans power architecture, storage philosophy, ecosystem lock-in versus openness, professional monitoring compatibility, and privacy-conscious design. The winners in 2026 and beyond will be those capable of aligning product architecture with a clearly defined customer segment rather than attempting to dominate across all dimensions simultaneously.
Market Dynamics: Regulation, Supply Chain, and the Compliance Premium
The operational environment surrounding smart doorbells is increasingly shaped by regulatory and structural forces that reward preparedness and penalize reactive design. Spectrum management remains a foundational consideration, as FCC regulation continues to govern spectrum allocation for Wi-Fi and Bluetooth in smart doorbell devices, requiring manufacturers to prevent interference across the 2.4 GHz and 5 GHz bands. For hardware engineering and product certification teams, this is not a background detail; it is a design constraint that directly affects time-to-market, regional deployment flexibility, and interoperability performance.
Doorbell Market
Data protection requirements have become equally central to commercial strategy. GDPR and data sovereignty laws now require end-to-end encryption and local storage options for smart doorbell video feeds within the European Union. This regulatory posture shifts the competitive calculus for vendors targeting European customers. Companies that have embedded privacy-by-design architectures and local storage pathways into their product roadmaps can position those capabilities as market access enablers, whereas those retrofitting compliance under deadline pressure face both technical and reputational friction.
Cybersecurity management standards further reinforce this compliance premium. The widespread adoption of ISO/IEC 27001 standards across smart home devices, including video doorbells, signals that enterprise-grade security governance is becoming table stakes rather than a differentiator reserved for specialized verticals. For market participants, this means that product security, certification readiness, and transparent data handling are increasingly intertwined with brand trust and channel acceptability.
On the manufacturing and cost side, sector analysis indicates that assembly and testing labor costs for smart doorbell hardware are elevated in regions with skilled electronics manufacturing supply chains. This dynamic has strategic implications for sourcing decisions, margin planning, and product localization. Companies must weigh the trade-offs between manufacturing proximity, labor cost structures, quality consistency, and logistics efficiency, especially as competition intensifies and pricing pressure increases in the mass-market segment.
A recent product-launch signal further illustrates how these dynamics play out in real time. In May 2026, Blink debuted a second-generation video doorbell featuring an expanded field of view and enhanced person detection. This release demonstrates how incumbents continue to iterate on core detection quality and visual coverage to defend share, while also reflecting the broader industry push toward more accurate on-device intelligence. For competitors, such launches are both an operational benchmark and a reminder that feature escalation alone will not sustain differentiation without clear segmentation and ecosystem alignment.
What the Full Research Delivers: Operational Intelligence, Not Just Forecasts
A market summary can establish direction, but enterprise decision-making requires structured, actionable detail. Our Smart Doorbell Market research is designed to convert high-level trajectory into implementable intelligence across product, commercial, and risk functions. The report maps historical performance and forward-looking forecasts within a consistent methodological framework, allowing readers to validate growth assumptions against segmented demand drivers, regional adoption patterns, and application-specific purchasing behavior.
Beyond aggregate sizing, the study dissects how the market is structured across type-based and application-based demand, giving strategists visibility into where wired and wireless architectures are gaining traction and how residential versus commercial use cases shape product requirements, pricing tolerance, and channel expectations. Regional demand distribution is similarly examined to identify where growth concentration, competitive intensity, and compliance environments diverge, enabling more precise go-to-market prioritization rather than broad, undifferentiated global assumptions.
The report also includes competitive profiling that goes beyond corporate descriptions. It situates each key player within a strategic context, connecting product features, ecosystem integration, storage and subscription philosophy, and monitoring or security compatibility to the segments they are best positioned to serve. This approach allows business leaders to benchmark their own product strategy against peer positioning, identify white-space opportunities, and anticipate where competitive pressure is likely to intensify.
Equally important, the research integrates regulatory and operational dynamics into the market narrative rather than treating them as peripheral footnotes. By examining the interplay between spectrum regulation, data sovereignty expectations, cybersecurity standards, and manufacturing cost structures, the study helps organizations assess readiness across multiple dimensions simultaneously. For product teams, this means clearer visibility into design constraints and certification pathways. For commercial teams, it means more realistic margin modeling and market-entry sequencing. For leadership, it means a consolidated view of where operational risk and strategic opportunity converge.
Why This Research Matters for 2026 Decision-Making
Markets that expand at a double-digit CAGR do not reward passive observation. They reward organizations that can convert structural growth into targeted execution. In the smart doorbell category, 2026 sits at a point where historical momentum, regulatory maturation, and competitive fragmentation intersect. The companies that navigate this inflection successfully will be those that treat product strategy, compliance architecture, and segmentation discipline as interconnected rather than sequential concerns.
Our research is built for that challenge. It is intended for executives who need to evaluate whether to deepen existing product lines, enter adjacent segments, restructure supply and cost assumptions, or reposition against ecosystem-driven competitors. It is also intended for investors and advisors who require a defensible view of where demand is concentrating, which competitive models are proving durable, and which operational hurdles will separate scalable players from those constrained by compliance gaps or misaligned product philosophy.
Smart Doorbell Market
The complete report provides the segmented data, competitive benchmarking, regional breakdowns, and forward-looking scenario structure necessary to move from strategic intent to operational plan. If your team is preparing for 2026 planning cycles, channel allocation, product roadmap prioritization, or competitive response planning, the full study offers the granularity required to make those decisions with confidence.
The market trajectory is clear. The strategic question is how precisely your organization intends to meet it.
For detailed analysis of this topic, please visit the official page: Smart Doorbell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Preclinical Tomography Market to Hit $490.93M by 2032, Growing at 9.14% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Preclinical Tomography System Market Through 2032
The preclinical imaging sector is entering a decisive inflection point. Over the past half-decade, tomographic platforms have evolved from specialized academic tools into core infrastructure for drug discovery, toxicology, and translational biology. For executive teams, capital allocators, and R&D leaders, understanding this trajectory is no longer optional. It is a prerequisite for informed investment, pipeline prioritization, and competitive positioning. Our newly published research on the Preclinical Tomography System Market captures this transformation with granular precision, mapping historical performance, forward-looking forecasts, competitive dynamics, and regulatory shifts that will shape enterprise decisions well into the next decade.
Preclinical Tomography System Market
This article offers a strategic preview of the study, illustrating how the analysis connects macro-level market evolution to actionable, boardroom-ready insights. While the full report delivers exhaustive segment-level data, vendor benchmarks, and scenario modeling, the following overview demonstrates the analytical depth, operational relevance, and decision-support architecture that define our methodology.
Historical Trajectory and Forward Growth Architecture
The market has demonstrated consistent expansion from 2020 through the base year of 2025, building on sustained adoption across research institutions, hospital-affiliated laboratories, and pharmaceutical discovery units. Revenue progression over this six-year window reflects compounding demand for high-resolution, in vivo imaging that reduces reliance on terminal histopathology and accelerates iterative study design. The revenue baseline established at the end of 2025 provides a stable foundation for the projection phase, which extends through 2032.
Over the forecast horizon, the market is projected to advance at a compound annual growth rate of 9.14%, measured in USD millions. This trajectory is not purely linear; it reflects accelerating replacement cycles, broader integration of multimodal tomography platforms, and increasing procurement standardization across enterprise research portfolios. The forward curve captures both volume-driven expansion and value migration toward higher-resolution, workflow-integrated systems that reduce total cost of ownership while improving data reproducibility.
For decision-makers, the strategic implication is clear. Budget planning, capital expenditure approval, and vendor evaluation must account for a market that is scaling steadily rather than experiencing speculative spikes. Forecasting through 2032 enables procurement leaders to model phased rollout strategies, R&D directors to align imaging capacity with pipeline timelines, and investors to assess long-term demand resilience across therapeutic and academic end-users.
Structural Drivers Reshaping Procurement and Research Workflows
Several structural forces are converging to amplify demand for preclinical tomography systems. First, the industry-wide shift toward in vivo, longitudinal imaging is reducing study attrition and improving translational fidelity. High-resolution micro-CT and emission tomography platforms now enable repeated measurements in the same subject, supporting pharmacokinetic modeling, bone and dental microarchitecture assessment, soft tissue characterization, and disease progression tracking with greater statistical confidence.
Second, regulatory expectations around imaging biomarkers are becoming more prescriptive. Guidance from major health authorities increasingly positions tomographic imaging as essential for pharmacokinetic and toxicity assessments within investigational new drug frameworks. Parallel recommendations emphasize standardized protocols for good laboratory practice compliance, reproducible data generation, and multimodal assessment strategies for novel therapeutics, including gene therapies and cellular products. For sponsors and contract research organizations, these expectations elevate imaging from a supportive technique to a compliance-critical workflow component.
Third, ethical and documentation requirements governing animal model usage continue to tighten. Legislative frameworks in the United States and European Union impose rigorous oversight on preclinical animal studies, which in turn incentivizes adoption of imaging platforms that enable fewer subjects, richer datasets, and stronger documentation trails. Institutions that standardize on validated tomography systems are better positioned to satisfy oversight requirements while preserving research throughput.
Finally, workflow integration and multimodal convergence are reshaping procurement criteria. End-users increasingly evaluate systems not only on raw resolution, but on interoperability with reconstruction software, informatics pipelines, automated analysis modules, and multi-modality configurations that combine structural and functional imaging. This evolution favors vendors that deliver compact benchtop performance alongside enterprise-grade scalability, clinical compliance alignment, and continuous software enhancement.
Competitive Positioning and Recent Market Developments
The competitive landscape is concentrated, with leading vendors differentiating through hardware innovation, regulatory milestones, and ecosystem partnerships. Three organizations illustrate the strategic directions currently shaping the market.
Bruker Corporation
Headquartered in Billerica, Massachusetts, Bruker has expanded its preclinical imaging portfolio with advanced micro-CT platforms designed for high-resolution in vivo imaging of small animals and biological samples. Its product lineage, including the X4 POSEIDON, SKYSCAN 1273, and SKYSCAN 2214 CMOS Edition systems, targets detailed structural imaging across bone, dental, and soft tissue applications. In February 2025, Bruker launched the X4 POSEIDON advanced X-ray microscope with micro-CT functionality, delivering compact benchtop performance and enhanced image quality for preclinical life-science workflows. This release reinforces a broader competitive shift toward high-performance systems that fit within constrained laboratory footprints while preserving research-grade imaging fidelity.
SCANCO Medical AG
Based in Bassersdorf, Switzerland, Scanco Medical maintains a focused presence in preclinical micro-CT through platforms engineered for in vivo small-animal studies. Its vivaCT 80 in vivo micro-CT scanner is positioned around a large field-of-view and high-resolution imaging capability, supporting longitudinal study designs and detailed structural assessment. Scanco’s strategy reflects sustained emphasis on specialty preclinical imaging where resolution, reproducibility, and workflow consistency carry outsized importance for academic and translational research teams.
Mediso Medical Imaging Systems
Operating from Budapest, Hungary, Mediso has built its competitive identity around multimodal tomography systems that combine structural and functional imaging for molecular preclinical research. The nanoScan family encompasses preclinical PET/CT, SPECT/CT, and multi-modality configurations designed to support molecular imaging applications. In December 2025, Mediso received FDA 510(k) clearance for the AnyScan 3.0 NM Scanner Family, encompassing PET/CT and SPECT/CT systems suitable for preclinical research applications. This regulatory milestone is strategically significant because emission tomography clearances increasingly hinge on recognized performance and safety standards, raising the barrier to entry for new competitors while strengthening the compliant positioning of established vendors.
Beyond these core players, the broader ecosystem includes partnerships and collaborations that expand imaging infrastructure and co-develop advanced workflows. For example, a December 2024 strategic collaboration between Nikon Metrology and Taipei Medical University established a joint micro-CT imaging center and initiated co-development of advanced preclinical imaging workflows. Moves of this kind signal growing institutional investment in shared imaging capacity, standardized acquisition protocols, and cross-functional research integration.
Regulatory and Compliance Architecture as a Market Catalyst
Regulatory and ethical frameworks are no longer peripheral considerations; they are shaping product requirements, procurement criteria, and time-to-deployment. Clearance pathways for emission computed tomography systems, including recent submissions for preclinical scanner families, reference compliance with recognized standards for performance and safety. These expectations influence not only vendor validation processes but also institutional purchasing decisions, where demonstrable compliance reduces operational risk and supports smoother study approval.
Simultaneously, guidance around imaging biomarkers in preclinical studies is pushing organizations toward standardized protocols that support GLP compliance and reproducible data in drug development submissions. Updated international guidelines for preclinical imaging emphasize multimodal assessment strategies for novel therapeutics, reinforcing the value of platforms that can integrate structural, functional, and molecular readouts within consistent workflows. For sponsors, CROs, and academic centers, this translates into stronger demand for systems that minimize protocol variability and help maintain auditable documentation across study phases.
The interaction between regulatory evolution and procurement strategy is particularly important for enterprise buyers. When evaluating platforms, organizations increasingly consider not just immediate imaging performance, but also long-term alignment with evolving standards for safety, biomarker validation, multimodal integration, and animal welfare documentation. In this environment, the ability to forecast which system architectures will remain compliant and adaptable through the end of the decade becomes a genuine competitive advantage.
Why This Research Matters for 2026 Decision-Making
Market intelligence in this sector must do more than describe growth. It must help leadership teams anticipate capital needs, align technology roadmaps, and interpret competitive signals with confidence. Our Preclinical Tomography System Market study is designed for that practical purpose, translating historical performance and forward projections into structured decision support for 2026 and beyond.
The report provides comprehensive coverage across the full market architecture, including revenue evolution from historical years through the forecast horizon, segment-level breakdowns by region, system type, and application, and competitive profiling of key participants. It examines procurement drivers, regulatory catalysts, technology adoption patterns, and the implications of recent product launches, clearances, and strategic collaborations. Importantly, the analysis is organized to support use cases that matter to executives: budget allocation, vendor evaluation, capacity planning, partnership assessment, and risk-adjusted market entry or expansion strategy.
Several elements distinguish the study from generic market summaries. First, the forecast structure enables multi-year planning under a consistent growth framework, allowing organizations to model different adoption and replacement scenarios rather than relying on point estimates. Second, competitive profiling connects product offerings to real-world strategic moves, including benchtop performance innovations, multimodal system expansions, and regulatory clearances that alter market access dynamics. Third, regulatory context is woven directly into market dynamics, helping readers understand why compliance, standardization, and documentation requirements are influencing demand patterns and procurement cycles.
For 2026 specifically, the research supports several high-value actions. R&D and imaging operations leaders can use the forecast and segmentation framework to justify phased capital deployment and align imaging capacity with pipeline milestones. Procurement teams can benchmark system types and end-user application demand to refine request-for-proposal criteria and evaluate total cost of ownership across competing platforms. Business development and corporate strategy teams can interpret competitive moves, partnership activity, and regulatory timing to anticipate market consolidation, identify white-space opportunities, and prepare for evolving buyer expectations.
By integrating macro growth trends with operational realities, the report helps transform uncertainty into structured planning. Readers gain clarity on how revenue progression, system type adoption, application demand, and regional dynamics interact over the forecast period, while maintaining the flexibility to stress-test assumptions according to internal priorities and research pipelines.
What the Full Study Delivers
While this preview outlines the strategic framework, the complete report provides the detailed intelligence required for precise execution. The full analysis includes:
- Historical market sizing and forward projections through the end of the forecast period, expressed in consistent revenue units to support budget modeling and scenario comparison.
- Segment-level breakdowns that help clarify where demand is concentrated across geography, system type, and end-use application, enabling targeted planning without exposing enterprise strategy to one-size-fits-all assumptions.
- Competitive assessments that connect vendor portfolios, recent launches, regulatory developments, and collaboration activity to actionable positioning insights.
- Regulatory and compliance analysis that contextualizes clearance requirements, imaging biomarker expectations, GLP considerations, and animal welfare documentation within procurement and workflow decisions.
- Strategic interpretation of market concentration and competitive dynamics, helping readers understand how leadership positions, differentiation levers, and ecosystem partnerships shape near-term competition.
This is precisely the type of evidence base that supports confident decisions in 2026, when organizations must reconcile accelerating imaging adoption with compliance expectations, budget discipline, and the need to future-proof laboratory infrastructure.
Moving from Insight to Action
The Preclinical Tomography System Market is expanding with measurable momentum, but the real strategic challenge lies in interpreting that momentum correctly. Growth alone does not dictate successful investment; the value comes from understanding where demand is forming, which system architectures are gaining traction, how regulatory requirements are reshaping procurement, and which competitive moves signal longer-term positioning shifts.
Our research is built to answer those questions with discipline and specificity. It offers the analytical structure needed to plan capital deployment, refine vendor selection, align imaging strategy with R&D timelines, and anticipate compliance-driven changes in buyer behavior. For executives who need more than broad market narratives, the full report delivers the depth, segmentation, and competitive intelligence required to act decisively.
Computed Tomography System Market
To access the complete market analysis, detailed segment data, and executive-ready strategic recommendations, visit the full report page and secure the comprehensive intelligence package designed for 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Preclinical Tomography System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Intranasal Drug Delivery Devices Market to Hit $3,435.95M by 2032, 8.98% CAGR
By PW Consulting, 2026-09-16
Navigating the 2026 Landscape: Why Strategic Intelligence on Intranasal Drug Delivery Devices Matters
The global landscape for intranasal drug delivery devices is undergoing a structural transformation. As therapeutic pipelines increasingly target rapid onset, patient-centric administration, and alternative routes to systemic circulation, device engineering has moved from a supporting function to a core strategic differentiator. For executive teams, innovation directors, and market access strategists, understanding the mechanics of this shift is no longer optional. The decisions made in 2026 around platform selection, partnership structuring, and regulatory positioning will directly shape commercial viability through the end of the decade.
This article outlines the strategic rationale behind our latest market research release and demonstrates how granular, forward-looking intelligence can be translated into actionable corporate strategy. The analysis aligns with a forecast horizon spanning 2026 through 2032, anchored in a five-year historical baseline that captures the market’s acceleration from 2020 onward. Rather than offering high-level abstractions, the research is structured to support capital allocation, product roadmap planning, and competitive positioning with precision.
Macro Trajectory and the 2026 Decision Context
The market’s growth arc over the past half-decade has been defined by consistent expansion and rising structural complexity. Revenue progression from the early 2020s through the 2025 base year reflects sustained commercial adoption, alongside incremental breakthroughs in formulation-device compatibility. Looking forward, the trajectory points toward a compound annual growth rate that underscores both the market’s maturation and its ongoing capacity for value creation. The implication for 2026 decision-makers is clear: growth is no longer a lagging indicator but an active planning parameter that shapes R&D investment cycles, commercial scaling timelines, and partnership economics.
At this stage, the market’s scale and momentum create a dual imperative. Organizations must simultaneously defend existing device portfolios while evaluating next-generation platforms that address unmet clinical needs, such as improved deposition consistency, dry powder handling, and nose-to-brain targeting. Navigating this tension requires more than industry headlines. It demands a structured view of how device architectures, regulatory pathways, and reimbursement environments intersect across therapeutic categories.
Structural Shifts Defining Competitive Positioning
Several interrelated dynamics are reshaping how companies evaluate intranasal delivery opportunities. Regulatory frameworks continue to evolve, with classification pathways and clearance mechanisms influencing time-to-market for both established and novel device configurations. At the same time, reimbursement environments are creating differentiated commercialization pathways, particularly where approved nasal spray products and clinical-use devices benefit from established coverage structures. These dynamics are not isolated; they interact with manufacturing scale-up requirements, device reliability expectations, and formulation constraints.
Saline Nasal Mist Market
For device manufacturers and biopharma partners alike, the strategic challenge lies in anticipating where regulatory and reimbursement clarity will create entry opportunities, and where device differentiation will become the decisive commercial lever. Reports that map these forces against actual device types, application categories, and regional adoption patterns equip leadership teams with the context needed to prioritize resource deployment with confidence.
What the Research Delivers: Operational Depth for Real-World Strategy
Our newly released study is designed to convert market complexity into decision-ready intelligence. Rather than stopping at headline figures, the research examines the structural components that determine where value is created and captured across the intranasal delivery ecosystem. The analysis is built to support cross-functional planning, enabling teams to compare platform strategies, assess adoption trajectories, and evaluate competitive pressure points with a shared evidence base.
- Comprehensive market sizing and forward projections that define the revenue environment through 2032, providing a clear quantitative frame for investment and commercialization planning.
- A device-centric segmentation lens that distinguishes between multi-dose systems, unit-dose systems, and other delivery configurations, enabling platform-level benchmarking and portfolio alignment.
- An application-focused view that maps device deployment across therapeutic use cases, supporting formulation strategy, indication prioritization, and target product profile development.
- Regional market assessment that contextualizes geographic adoption patterns without reducing the analysis to superficial share breakdowns, helping teams gauge where infrastructure, clinical practice, and channel readiness differ.
- Competitive profiling of leading device manufacturers and development partners, including capabilities, platform focus, and recent strategic activity that signals where the market is heading.
- Regulatory and reimbursement context that ties device classification, clearance pathways, and coverage dynamics to commercialization feasibility.
- Scenario-ready interpretation for planning around partnerships, licensing, manufacturing scaling, and device adoption in both branded and generic-adjacent environments.
Competitive Landscape: Device Capability as Strategic Currency
The companies shaping this market are increasingly competing on platform versatility, formulation compatibility, and speed of execution. The leading device manufacturers and development organizations in this space reflect a market that values precision delivery, scalability, and integration across the drug-device lifecycle. Their strategic activity provides an early signal of where device innovation is concentrating and how commercial partnerships are being structured.
Aptar Pharma continues to reinforce its position as a broad-platform provider, offering single-dose, two-dose, and multi-dose nasal spray pump solutions designed for liquid and powder formulations. Its recent utilization in a Phase II clinical study for an investigational nasal spray illustrates how device performance is increasingly tied to clinical-stage credibility and downstream commercialization readiness. In parallel, the market is seeing targeted expansion from specialists and innovators. Teleflex remains associated with mucosal atomization devices that support atomized intranasal delivery, an approach that has become relevant in specific clinical and emergency-use contexts.
Bespak brings a strong focus on drug-device combination products, spanning multi-dose aqueous nasal sprays and specialized unit-dose systems. Silgan Dispensing contributes additional dispensing and pump technology designed for intranasal delivery, reinforcing the importance of mechanical precision in everyday administration. Hovione represents the integrated CDMO angle, linking API-to-device solutions with single-use dry powder devices and emphasizing how development partnerships can shorten device-platform qualification cycles. Kindeva Drug Delivery adds further combination-product depth across nasal spray and MDI-type delivery configurations, while Nemera engages with dry powder and drip-dose-style platforms that connect intranasal delivery to broader nose-to-brain applications. Aero Pump rounds out the competitive field with spray pump and device engineering geared toward precise delivery needs.
Recent 2026 developments reinforce how rapidly strategic activity is accelerating. Zeteo Biomedical introduced metered-unit-dose dry powder and biologics delivery devices intended for nasal and nose-to-brain administration, highlighting the growing importance of precision dosing in emerging formulation categories. Nemera’s partnership expansion to strengthen intranasal applications demonstrates how platform fit is becoming a deliberate partnership criterion. At the same time, Hovione’s announcements around integrated intranasal drug delivery platform availability point to a broader trend in which commercial readiness and device accessibility are increasingly bundled together as value propositions.
These moves matter because the market’s concentration profile indicates that a relatively small group of participants holds a substantial share of industry revenue. That concentration creates both pressure and opportunity. New entrants and incumbent challengers must determine whether to compete through platform differentiation, niche clinical applications, regional strength, or partnership leverage. Without detailed device-level and application-level analysis, those decisions risk being misaligned with actual market economics.
Where 2026 Strategy Meets Tactical Execution
As organizations plan for the remainder of this year and beyond, several strategic questions repeatedly surface. Should a company prioritize a multi-dose platform for chronic or repeat-use settings, or build capability around unit-dose and specialized delivery formats that support simplified administration and controlled dispensing? How should device strategy align with formulation ambitions, especially in dry powder, biologic, and rapid-onset rescue scenarios? Which partnership models will accelerate device qualification, manufacturing readiness, and market access without compromising differentiation?
The answer to each question depends on more than general market growth. It depends on how device adoption, therapeutic demand, and commercial viability intersect across segments and regions. A comprehensive research framework allows leadership to test assumptions, compare platform economics, and identify where competitive exposure is highest. It also supports more disciplined conversations with internal R&D, external partners, and commercialization teams by replacing speculation with evidence-based reference points.
The highest-value applications of this research typically emerge in three areas. First, in portfolio strategy, where organizations need to decide which device architectures deserve incremental investment and which require redesign or exit. Second, in partnership and outsourcing planning, where companies evaluate device suppliers, CDMOs, and combination-product collaborators based on capability fit and development timelines. Third, in commercial and regulatory sequencing, where device classification, clearance expectations, and reimbursement readiness influence launch planning and indication prioritization.
Intranasal Drug Delivery Devices Market
In each case, the value lies not in a single number but in the relationship between numbers, segment characteristics, and strategic context. That is precisely the level of analysis required for 2026 planning and beyond.
Why the Full Report Is the Strategic Next Step
Market summaries can establish direction, but they rarely provide the resolution needed for investment decisions, partnership evaluation, or product roadmap alignment. This study is built to close that gap. It combines forward-looking market sizing with device-type, application, and regional context, then ties that structure to competitive activity and regulatory dynamics. The result is an evidence base that can be used to benchmark positioning, test new market entries, and align cross-functional teams around a shared view of opportunity.
For executives evaluating where to commit resources in 2026, the full research offers the practical detail needed to move from strategic hypothesis to operational plan. The complete dataset, segmentation breakdown, and competitive interpretation are available through the original report page, where the full analysis can be reviewed in the context of your organization’s specific priorities.
Conclusion: Intelligence as a Competitive Discipline
Intranasal drug delivery devices are no longer a niche consideration. They are an integral part of how faster onset, improved patient experience, and alternative delivery pathways are being commercialized across multiple therapeutic areas. The companies that succeed in this environment will be those that combine platform technology with disciplined market interpretation. Strategic clarity in 2026 will depend on access to structured, decision-grade intelligence that connects growth dynamics, competitive behavior, and commercial feasibility.
The full research release provides that foundation. For teams seeking to align product strategy, partnership models, and market entry planning with the realities of an expanding and increasingly sophisticated market, the complete analysis is the essential next step.
For detailed analysis of this topic, please visit the official page: Intranasal Drug Delivery Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: E-Liquids Market Hits $1.125B in 2025, Projects 12.58% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Vapor Shift: Strategic Intelligence for the 2026 E-Liquids Market
The global e-liquids market stands at a critical inflection point. As regulatory frameworks tighten and consumer preferences evolve, understanding the precise trajectory of this sector is no longer optional—it is a prerequisite for sustainable growth. Our latest market research publication offers a comprehensive roadmap for navigating the complexities of the e-liquids landscape from 2026 through 2032. This report is designed not merely as a data repository, but as a strategic asset for decision-makers who need to anticipate shifts rather than react to them.
For industry stakeholders, the difference between market participation and market leadership often comes down to the quality of intelligence available at the point of decision. The following analysis outlines the macro-economic environment, the competitive architecture, and the regulatory currents shaping the sector, demonstrating why deep-dive research is essential for capital allocation, product development, and market entry strategies in the coming year.
Macro-Economic Trajectory and Growth Fundamentals
The historical performance of the e-liquids market demonstrates a robust upward trend, reflecting the continued shift away from traditional combustion products toward vaporized nicotine delivery systems. Between 2020 and 2025, the sector experienced consistent expansion, building a substantial revenue base that sets the stage for the forecast period. Current estimates place the total market valuation at USD 1,125.0 Million in 2025, marking a significant increase from the 2020 baseline.
Looking forward, the growth momentum is projected to accelerate. Our forecast models indicate that the market will reach USD 1,265.53 Million in 2026, continuing to climb steadily toward a projected valuation of USD 2,470.0 Million by 2032. This trajectory is underpinned by a Compound Annual Growth Rate (CAGR) of 12.58 percent during the 2026-2032 forecast period. Such a rate suggests that the e-liquids sector will continue to outpace many traditional consumer goods categories, driven by innovation in device compatibility, flavor profiling, and evolving regulatory approvals that legitimize specific product categories.
For strategic planners, these figures represent more than just top-line growth; they indicate a maturing market where consolidation and specialization are becoming key drivers. The sheer scale of the projected revenue unit expansion over the next six years implies significant opportunities for players who can secure supply chain stability and navigate the varying compliance landscapes across different jurisdictions.
Market Structure and Concentration Dynamics
One of the most critical aspects of strategic planning in this sector is understanding the competitive density. The market is not uniformly distributed; rather, it exhibits a high degree of concentration among key players. Current analysis reveals a CR3 (Concentration Ratio of the top three firms) of 62.0 percent, while the CR5 extends to 78.0 percent. This level of concentration highlights the dominance of established tobacco giants and specialized nicotine technology firms that have secured significant market share through brand recognition, regulatory approvals, and distribution networks.
This concentration has profound implications for new entrants and existing mid-sized players. It suggests that while the total addressable market is growing, the pathway to capturing share requires distinct differentiation. Companies cannot simply rely on volume; they must offer unique value propositions, whether through proprietary flavor technologies, superior hardware integration, or specialized OEM/ODM manufacturing capabilities. The gap between the top-tier concentrated firms and the long tail of the market is where strategic agility becomes most valuable.
Our research delves into the specific structural dynamics that allow certain entities to maintain these high concentration levels while others struggle to gain footholds. Understanding the barriers to entry, the cost structures of compliant manufacturing, and the distribution leverage held by incumbents is vital for any organization considering M&A activity or organic expansion.
Competitive Landscape and Key Players
The competitive environment is a mix of established multinational tobacco corporations and specialized e-liquid manufacturers. This duality creates a complex ecosystem where traditional smoke-free portfolios intersect with agile, niche liquid producers. Our report profiles the strategies and operational focuses of the industry's pivotal companies.
Major multinational entities such as Philip Morris International Inc., British American Tobacco PLC, Imperial Brands PLC, and Japan Tobacco International are heavily invested in the e-vapor space. These companies integrate e-liquids into broader smoke-free business portfolios, leveraging their existing distribution channels and regulatory expertise to maintain market presence. Their approach often focuses on standardized, compliant products that align with global regulatory trends.
On the other side of the spectrum are specialized manufacturers and technology developers. JUUL Labs Inc. and Logic Technology Development LLC have historically focused on specific delivery systems and cartridge formats, emphasizing authorized variants and specific flavor profiles. NJOY LLC continues to push pod formats designed for ease of use and nicotine delivery efficiency. Meanwhile, specialized manufacturers like Hangsen have carved out a significant role as world-leading OEM/ODM partners, providing solutions to markets across over 86 countries. This highlights a crucial supply-side dynamic: the reliance of many brands on specialized manufacturing partners to scale production while adhering to quality guidelines.
Independent premium brands such as Ruthless Vapor, Mister-E-Liquid, and Vape Base Ltd also play a crucial role in shaping consumer preferences, particularly in the flavored e-liquid segment. These companies often lead in flavor innovation and community engagement, setting trends that larger conglomerates may later adopt or regulate around. Our analysis examines how these different tiers of competitors interact, compete for shelf space, and navigate the varying regulatory requirements that define their respective operational zones.
Regulatory Environment and Industry Dynamics
No strategic discussion of the e-liquids market is complete without addressing the regulatory environment, which remains the single most significant variable affecting market access and profitability. As of May 2026, the regulatory landscape is characterized by a patchwork of authorizations and duties that vary significantly by region.
In the United States, the FDA continues to be the gatekeeper. As of May 2026, the FDA has authorized 45 ENDS products, representing the only ones legally marketed in the United States. This tight control over market entry creates a high barrier for new products but provides stability for those who secure authorization. Recent developments underscore this reality; in June 2025, the FDA granted premarket authorizations to Swedish Match North America, Inc. for tobacco-flavored e-liquid products. Furthermore, in May 2026, the FDA authorized the marketing of four Glas ENDS products featuring e-liquid pods with non-tobacco and non-menthol flavors. This authorization is particularly significant as it signals a potential pathway for flavor diversity under strict compliance conditions, a key area of interest for consumer growth.
Across the Atlantic, the UK has introduced new fiscal measures. On 01 April 2026, the UK HMRC opened applications for the Vaping Products Duty of £2.20 per 10ml on all vaping liquids. This duty imposes a direct cost on production and distribution, which will inevitably influence pricing strategies and margin structures for companies operating in or exporting to the UK market. Strategic budgeting for 2026 and beyond must account for these duty implications to avoid margin erosion.
State-level actions also contribute to the complexity. The Virginia Annual Report on Liquid Nicotine and Nicotine Vapor Products, published in February 2026, records 13 manufacturers certified and $380,000 in revenue collected, indicating active state-level monitoring and taxation. Similarly, Arkansas requires manufacturers to certify compliance with directory rules for vapor products and e-liquid products, with penalties for non-compliance starting November 2025. These fragmented regulatory requirements necessitate a robust compliance infrastructure that our report details extensively.
Industry Activity and Capacity Expansion
Despite regulatory headwinds, industry activity remains vigorous. Corporate strategies reflect a commitment to growth and capacity building. In February 2026, VPZ announced a multi-million-pound investment to expand e-liquid manufacturing capacity and launch new retail locations. This move signals confidence in the long-term demand for compliant vaping products and highlights the importance of physical retail presence alongside manufacturing scalability.
Trade activity also continues to facilitate commercial connections. The Total Product Expo in April 2026 featured a dedicated e-liquids and vapes category with significant commercial activity for independent retailers. Such events are critical nodes in the supply chain, where manufacturers connect with distributors and retailers to secure shelf space and negotiate terms for the upcoming fiscal year. Our market research captures the sentiment and transaction trends observed at these key industry gatherings, providing qualitative context to the quantitative data.
E-cigarette Market
Strategic Value of the 2026 Market Research
Given the interplay of high market concentration, rapid growth projections, and a shifting regulatory moat, generic market data is insufficient for high-stakes decision-making. This report provides the granular intelligence required to transform uncertainty into strategy.
Our analysis goes beyond surface-level metrics to explore the segmentation splits that drive revenue. We examine the performance of different product types, including Pre-Filled and Bottled E-Liquids, and analyze how application preferences such as Tobacco, Fruit, and Menthol flavors influence purchasing behavior in different regions. However, the specific weightings and regional revenue distributions are detailed within the full report to maintain competitive confidentiality and ensure that subscribers receive the most actionable, non-public insights.
The core value of this research lies in its operational applicability. For investors, it offers a clear view of where capital is flowing and which segments offer the highest risk-adjusted returns. For manufacturers, it identifies gaps in the supply chain and opportunities for OEM/ODM expansion. For distributors and retailers, it highlights the flavor profiles and product formats that are gaining traction in compliant markets.
Readers are encouraged to access the full source webpage to retrieve the complete segmentation data, detailed company profiles, and specific regional forecasts. Only through the comprehensive dataset can organizations build the precise financial models and market entry plans required to succeed in this high-growth, high-regulation environment. The summary provided here establishes the strategic necessity of the research; the full document delivers the executional intelligence.
Conclusion
The e-liquids market is poised for substantial expansion over the next six years, but the path to capturing this value is fraught with regulatory and competitive challenges. With a projected market size nearing USD 2,470.0 Million by 2032 and a CAGR of 12.58 percent, the opportunity is significant. However, success will belong to those who can navigate the FDA authorization landscape, adapt to duties like the UK Vaping Products Duty, and compete effectively within a market where the top five players already control 78.0 percent of the share.
E-Liquids Market
PW Consulting's latest market research equips stakeholders with the necessary tools to make informed decisions. By integrating historical performance data, current regulatory facts, and competitive profiles, this report serves as a foundational document for strategic planning in 2026. We invite you to review the complete findings on our website to fully leverage this intelligence for your organization's growth objectives.
For detailed analysis of this topic, please visit the official page: E-Liquids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Luxury Sunglasses Market Hits $14.45B in 2025, Set for 4.59% CAGR Through 2032
By PW Consulting, 2026-09-16
The Strategic Imperative: Navigating the Luxury Sunglasses Market in 2026
The global accessory landscape is undergoing a subtle but profound transformation. Within this shift, the Luxury Sunglasses Market stands out as a beacon of resilience and sustained growth. For brand leaders, investors, and supply chain strategists, understanding the nuance of this sector is no longer optional; it is a critical component of long-term portfolio management. As we move through 2026, the intersection of timeless design, technological integration, and complex regulatory environments defines the operational terrain.
PW Consulting's latest comprehensive market research offers a detailed map of this terrain. This report is not merely a collection of statistics; it is a strategic toolkit designed to inform decision-making across product development, regional expansion, and competitive positioning. By analyzing historical trajectories and forecasting future trends, we provide the intelligence necessary to capitalize on emerging opportunities while mitigating the risks inherent in a fragmented market.
The following insights outline the current state of the industry and demonstrate why access to granular data is the ultimate competitive advantage in the coming fiscal years.
Macro Growth Trajectory and Market Valuation
The financial architecture of the luxury eyewear sector reveals a steady upward trend. Our analysis covers historical performance from 2020 through the base year of 2025, extending with precision into the forecast period of 2026 to 2032. This longitudinal view allows stakeholders to contextualize recent volatility against long-term growth patterns.
In 2025, the global market reached a valuation of approximately 14.45 billion USD. Looking ahead, the market is projected to expand to 14.95 billion USD in 2026, continuing its climb toward nearly 19.78 billion USD by 2032. This expansion reflects a Compound Annual Growth Rate (CAGR) of 4.59 percent over the forecast period. While these headline figures indicate healthy momentum, the drivers behind this growth are multifaceted, influenced by consumer behavior shifts, economic conditions, and product innovation.
For executives, the implication is clear: the market is large enough to support diverse strategies but competitive enough to demand precise execution. The steady CAGR suggests that organic growth is achievable, but capturing market share requires more than passive participation. It requires an understanding of where value is being created and how supply chain constraints might alter profitability margins.
The Competitive Landscape: Consolidation and Innovation
The luxury sunglasses sector is characterized by a moderate to high level of concentration. Our research indicates that the top three players hold a significant portion of the market revenue, while the top five firms command an even larger share. This concentration highlights the dominance of major conglomerates that manage multiple licensed and owned brands, though niche players continue to carve out premium positions through craftsmanship and brand heritage.
Several key companies define the current competitive hierarchy:
- EssilorLuxottica (Paris, France): As a market leader, this entity controls a vast portfolio including Ray-Ban, Oakley, and licensed luxury brands such as Tom Ford, Oliver Peoples, and Dolce & Gabbana. Their strategy blends mass appeal with high-end licensing.
- Marcolin Group (Italy): A crucial player in the production and distribution of designer luxury sunglasses, notably holding strong associations with Tom Ford eyewear.
- De Rigo Rem (Italy): Specializes in manufacturing and licensing luxury eyewear, with notable presence in brands like Police and Lozza.
- Safilo Group (Italy): Known for producing licensed luxury sunglasses for prestigious houses such as Gucci, maintaining strong ties to fashion heritage.
- Garrett Leight (United States): Represents the artisanal end of the market, designing and selling handcrafted luxury sunglasses with a focus on premium materials.
- Oliver Peoples (United States): Under EssilorLuxottica ownership, this brand continues to offer premium luxury sunglasses, leveraging its independent heritage within a larger corporate structure.
Strategic activity among these players is intensifying. For example, in March 2026, EssilorLuxottica extended its long-term licensing agreement with Dolce & Gabbana, securing development, production, and worldwide distribution rights for prescription frames and sunglasses. Simultaneously, they unveiled the first Oliver Peoples x Jil Sander sunglasses collection, featuring titanium and acetate frames with crystal lenses handmade in Japan. These moves signal a dual strategy: consolidating established luxury licenses while pushing the boundaries of material and fashion collaborations. Furthermore, the expansion of AI glasses portfolios, such as new Ray-Ban Meta optical styles for prescription wearers, indicates a convergence of wearable technology and traditional luxury aesthetics.
Market Dynamics and Regulatory Headwinds
No strategic plan is complete without accounting for external forces. The operational environment in 2026 is shaped by significant regulatory developments, particularly regarding trade policy. Recent updates from The Vision Council highlight substantial shifts in duty rates affecting the optical industry.
Imports of optical products from China have faced updated duty rates, with sunglasses encountering combined rates reaching 154.5 percent. This figure includes base duties, Section 301 tariffs, and reciprocal tariffs enacted in 2025. Such levels drastically impact landed costs and require immediate adjustments in pricing strategies and sourcing logic. In response to these pressures, major industry participants like EssilorLuxottica have implemented price increases in the US market to offset tariff impacts on imports from China and Thailand.
However, the regulatory landscape remains fluid. A 90-day pause on newly implemented country-specific reciprocal tariff increases was announced by the US Administration for countries that have not retaliated, effective April 2025. While this pause offers temporary relief, the underlying trade tensions suggest that supply chain diversification is no longer just a best practice but a necessity for risk mitigation. Companies relying heavily on single-source manufacturing hubs face elevated exposure, making the case for nearshoring or multi-regional production capabilities more compelling than ever.
Segmentation Insights: Where Value Resides
Understanding the composition of the market is vital for targeted investment. Our report dissects the market across three primary dimensions: Region, Type, and Application. While the aggregate numbers tell a story of growth, the segmentation data reveals where the profitability engines are located.
The market is distributed across major geographic zones, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents distinct consumer behaviors. For instance, mature markets in Europe and North America continue to drive volume through established luxury channels, while Asia Pacific represents a dynamic zone of growing affluence and brand consciousness. Navigating these regional differences requires more than a one-size-fits-all approach; it demands localized marketing strategies and distribution partnerships that resonate with specific cultural nuances.
Product type segmentation further illustrates the evolution of consumer preference. The market is divided between Polarized, Non-polarized, and Other Types. The performance of polarized lenses reflects a growing demand for functional luxury, where eye protection and visual clarity are prioritized alongside style. Meanwhile, the non-polarized segment maintains a stronghold in fashion-forward contexts where aesthetics take precedence.
Application-based segmentation highlights the dual identity of luxury sunglasses. The Fashion application dominates the landscape, underscoring the role of eyewear as a critical accessory in personal style and identity. Sports and Other applications, while smaller in relative value, represent high-growth niches where performance materials and specialized designs command premium pricing. Recognizing the balance between these applications allows brands to allocate R&D resources effectively, ensuring they meet the demands of both the runway and the racecourse.
Luxury Sunglasses Market
The Strategic Value of Granular Intelligence
Headline figures and company profiles provide the context, but the true power of this research lies in the details that are not immediately visible. Strategic decisions regarding pricing elasticity, channel mix, and inventory management require access to specific volume data, share percentages, and trend velocity metrics.
For example, knowing the exact revenue split between regions helps determine where to prioritize expansion capital. Understanding the precise share of polarized versus non-polarized types informs product roadmap prioritization. Identifying the specific growth rate of the fashion application segment versus sports allows for nuanced marketing budget allocation. This report provides those specific data points, enabling clients to move beyond general assumptions to evidence-based planning.
Furthermore, the interplay between tariff structures and segmentation is critical. A tariff impact might affect one region or product type more severely than another. Only with detailed data can a company model these scenarios accurately and prepare contingency plans. The inclusion of recent developments, such as specific partnership extensions and product launches, also provides a benchmark for evaluating competitor aggression and innovation cycles.
The market concentration data served as a warning and an opportunity. For new entrants or smaller brands, the high concentration among the top players suggests high barriers to entry in mainstream luxury. However, the persistence of niche brands like Garrett Leight shows that differentiation through material quality and brand storytelling remains a viable path. The research helps identify the white spaces where concentration is lower and potential for disruption exists.
Looking Ahead: Actionable Intelligence for 2026 and Beyond
As we progress through 2026, the Luxury Sunglasses Market will continue to be shaped by the tension between heritage and innovation. Brands must honor the craftsmanship that defines luxury while integrating new technologies and adapting to regulatory shifts. The forecast period extending to 2032 offers a long-term view, allowing companies to plan beyond quarters and focus on sustainable growth.
Sunglasses Market
The data indicates that the market will continue to expand, reaching nearly 20 billion USD by the early 2030s. However, capturing this value requires agility. Supply chain resilience, pricing strategy adjustments, and brand differentiation are the pillars of success in this environment. Companies that rely on outdated assumptions about trade flows or consumer preferences risk margin erosion and loss of relevance.
PW Consulting's Luxury Sunglasses Market Research is designed to equip stakeholders with the clarity needed to navigate these complexities. By providing a comprehensive view of market size, segmentation, competitive dynamics, and regulatory impacts, we enable leadership teams to make informed choices. The insights contained within this report are not just observations; they are the foundation for strategy.
To fully leverage this intelligence, stakeholders must access the complete dataset. The intersection of macro trends and micro-segmentation data reveals the specific pathways to growth that headline numbers cannot show. We invite decision-makers to explore the full report to unlock the detailed analytics required to outmaneuver competitors and secure a dominant position in the evolving luxury eyewear landscape.
For detailed analysis of this topic, please visit the official page: Luxury Sunglasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Paraffin Wax Market Hits $9.65B in 2025, Forecasts 5.6% CAGR to $14.13B by 2032
By PW Consulting, 2026-09-16
Paraffin Wax Market Intelligence Report: Strategic Forecasts and Competitive Dynamics 2026–2032
The global paraffin wax market stands at a pivotal inflection point as industries navigate shifting regulatory frameworks, evolving material specifications, and intensifying competitive pressures. Our latest market research deliverable provides executives, procurement leaders, and strategic planners with a comprehensive, data-anchored foundation for navigating the 2026 landscape and beyond. This introduction outlines how the study translates macro trajectories into actionable intelligence, positioning decision-makers to capture growth while mitigating structural risks across supply chains, product development, and geographic expansion.
Market Trajectory and Long-Term Growth Architecture
Historical performance across the 2020–2025 cycle demonstrates consistent demand expansion, with revenue progressing from roughly 7.35 billion USD at the start of the period to 9.65 billion USD by the 2025 baseline. This steady ascent reflects sustained utilization across traditional and specialized channels, underpinned by incremental capacity adjustments and broadening downstream adoption. Our forward-looking model extends through 2032, projecting a compound annual growth rate of 5.6 percent that lifts market revenue toward 14.13 billion USD by the final forecast year.
Forecast intervals for 2026 through 2030 illustrate a measured but uninterrupted climb, with each successive period capturing incremental value creation driven by refined manufacturing outputs, medical and laboratory-grade adoption, and packaging-related consumption. The trajectory is neither linear nor uniform across categories, which is precisely why our analytical framework isolates the structural drivers that will determine which participants secure margin resilience and which face compression from commoditization or compliance overhead.
Structural Segmentation: Where Value and Complexity Intersect
The market’s composition is shaped by three interlocking dimensions—product refinement thresholds, geographic distribution networks, and end-use deployment patterns. Fully refined and semi refined variants each command substantial share, yet their operational implications diverge sharply when evaluated against purification standards, melting-point stability, and downstream processing requirements. The residual category further reflects niche utilization pathways that often depend on specialized formulation parameters.
Geographic revenue concentration reveals mature demand centers alongside emerging corridors that are gradually scaling procurement volumes. Advanced industrial ecosystems continue to anchor baseline consumption, while regions in early-stage capacity building and import-dependent supply structures present differentiated growth risks and partnership opportunities. Application demand inherits this same structural complexity, with traditional usage streams maintaining broad volume presence, packaging-related requirements expanding through regulatory and sustainability mandates, and cosmetics and personal care segments leveraging refined waxes for formulation stability and user experience enhancements.
Our segmentation analysis deliberately avoids superficial percentage breakdowns in favor of a systematic evaluation of substitution thresholds, compliance friction points, and regional procurement behaviors. These outputs equip leadership teams with the granularity necessary to prioritize resource allocation, calibrate capacity commitments, and identify the applications or locations where competitive moats can be constructed before saturation accelerates.
Competitive Landscape and Strategic Positioning
The market’s competitive architecture reflects a blend of specialized medical-grade suppliers, histology-focused consumables manufacturers, and broader industrial producers that influence pricing, availability, and technical standard-setting across the value chain. A set of established entities illustrates the bifurcated nature of current competition. Companies such as WR Medical Electronics Co., Epredia, Polysciences Inc., CellPath Ltd., Poth Hille & Co. Ltd., Citotest Scientific Co. Ltd., and Biosharp each occupy distinct nodes within the ecosystem, balancing formulation precision, laboratory compatibility, and distribution reach.
The medical and laboratory-focused segment demonstrates particular intensity as procurement teams increasingly prioritize traceability, standardized documentation, and adherence to quality management expectations. Suppliers in this space differentiate not merely through volume, but through grade consistency, application compatibility, and the ability to support regulated workflows without introducing contamination risk or processing delays. Meanwhile, broader refining and chemical enterprises continue to shape availability dynamics by aligning upstream process modernization with specialty wax output, effectively influencing both cost structures and supply reliability for downstream converters and end manufacturers.
Our competitive analysis maps product portfolio breadth, geographic servicing capabilities, and strategic realignment activities to expose where consolidation pressure is likely to intensify. The report details how firms are positioning their refinement capabilities, laboratory-grade portfolios, and compliance documentation against buyer expectations, and identifies the structural advantages that separate market leaders from price-takers in multi-source procurement environments.
Recent Industry Developments Reshaping Market Momentum
Recent operational and product-level moves underscore the market’s transition toward higher specification demands and more disciplined supply practices. Product delivery activity in the medical-grade space has highlighted the importance of reliable cross-border fulfillment for hospital pathology departments and third-party testing laboratories, reinforcing the need for logistics consistency and batch traceability. Concurrently, major refining and petrochemical organizations have advanced facility upgrades and modernization initiatives designed to expand specialty wax output, signaling supply-side investment in higher-value production streams rather than bulk commodity routing alone.
Product portfolio expansions have also targeted low-carbon and specialized application pathways, reflecting buyer sensitivity to sustainability considerations in packaging and medical device contexts. Parallel catalog and specification updates within the therapeutic and professional-use segment demonstrate continued alignment with recognized quality and regulatory expectations, ensuring that refill options and device-compatible inputs maintain compatibility with established compliance standards. These developments collectively illustrate a market in which technical differentiation, documentation rigor, and capacity alignment increasingly determine commercial outcomes.
Paraffin Wax Market
Worldwide Paraffin Phase Change Material (PCM) Market
Regulatory, Material, and Operational Dynamics
Market behavior cannot be separated from the compliance environment and operating cost structures that shape procurement decisions. Paraffin wax applications used in occupational therapy and related therapeutic settings operate within defined classification frameworks that distinguish first-aid heat treatments from procedures requiring formal medical recordkeeping, influencing how providers structure procurement and usage protocols. At the same time, any paraffin wax destined for medical device consumables or histology workflows must satisfy international quality and traceability expectations, with ISO 13485 serving as a critical benchmark for documentation, quality control, and supply chain accountability.
Material cost and operational considerations further complicate segment economics. Facilities engaged in medical-grade or histology-related utilization must account for sanitization protocols, disposable liner requirements, and routine replacement cycles, all of which contribute to total cost of ownership beyond base material pricing. Medical-grade paraffin wax itself is characterized by elevated purity, stable melting behavior, and favorable permeability, attributes that directly support tissue embedding, slide preparation, and cellular pathology workflows. These technical and compliance factors interact with procurement strategy, making specification clarity and supplier qualification decisive variables in vendor selection and long-term contracting.
Strategic Decision Framework for 2026 and Beyond
Translating market intelligence into competitive advantage requires a structured approach that aligns market trajectory with internal capability and risk tolerance. Our report is designed to support that translation across three core planning dimensions. First, it delivers a decision-grade forecast architecture that connects baseline momentum to multi-year projections, enabling leadership teams to evaluate capacity timing, inventory positioning, and regional prioritization with greater confidence. Second, it breaks down segmentation complexity in a way that reveals substitution pathways, specification sensitivity, and demand concentration patterns without relying on superficial splits that obscure operational realities.
Third, the study incorporates competitive and developmental intelligence to help organizations anticipate supplier behavior, gauge consolidation risk, and identify partnership or sourcing opportunities before shift patterns become fully priced into the market. Combined with regulatory and operating-cost context, this provides a practical basis for scenario planning across procurement, product development, and market-entry decisions. In an environment where quality documentation, traceability, and application compatibility increasingly determine commercial viability, the ability to distinguish structural growth from temporary fluctuation is a strategic necessity.
Report Scope and Analytical Coverage
This research deliverable is structured to support both executive briefing and operational planning. It integrates historical performance, forward projections, segmentation logic, competitive profiling, and recent development tracking into a single analytical framework that can be applied across strategy, procurement, and business development functions. The study includes detailed examination of refinement categories, application pathways, and regional demand dynamics, along with supplier positioning that highlights differentiation drivers, compliance alignment, and distribution reach.
It also incorporates development tracking across facility modernization, portfolio expansion, product delivery activity, and specification updates, allowing readers to connect discrete events with broader market momentum. Operational and regulatory context is embedded throughout, ensuring that market sizing and competitive assessment are interpreted within the practical constraints that shape end-use requirements and total cost considerations. The result is a comprehensive reference document designed to support high-stakes decisions in a market where precision, traceability, and strategic timing increasingly define competitive outcomes.
Organizations seeking to align near-term sourcing and product decisions with longer-horizon growth trajectories will find the full dataset, segmentation architecture, and competitive mapping essential to disciplined planning. This report provides the analytical foundation required to convert market momentum into defensible strategy throughout the 2026–2032 cycle.
For detailed analysis of this topic, please visit the official page: Paraffin Wax Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Wood Pallet Market to Reach $19.99 Billion by 2032 at 4.58% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Wood Pallet Market: Navigating Growth and Complexity in 2026 and Beyond
The global supply chain ecosystem relies heavily on the humble yet critical wood pallet. As we move through 2026, industry stakeholders face a landscape defined by steady expansion, regulatory evolution, and intense competitive consolidation. PW Consulting is proud to introduce our latest comprehensive market research on the Wood Pallet Market, a study designed to equip decision-makers with the foresight needed to thrive in a maturing industry. This report serves as more than a static snapshot; it is a dynamic strategic tool built to clarify investment paths, operational risks, and long-term growth opportunities across the forecast horizon.
Wood Pallets Boxes Packaging Market
Our analysis covers the historical trajectory from 2020 through 2025 and projects performance through 2032. The overarching story is one of reliable, compounded growth. The market has demonstrated consistent revenue expansion over the past half-decade, reaching a valuation of approximately 14.61 billion USD in 2025. Looking ahead, the forecast period indicates a continued upward trend, with the market expected to grow to 14.91 billion USD in 2026 and further accelerate toward a 19.99 billion USD valuation by 2032. This trajectory is underpinned by a forecasted CAGR of 4.58 percent, signaling a healthy demand environment driven by foundational logistics needs and evolving supply chain configurations. Such macroeconomic indicators provide the baseline for strategic planning, yet understanding the nuances behind the aggregate numbers is where true competitive advantage lies.
Navigating the Competitive Arena
The market structure reveals a landscape dotted with both dominant integrated players and specialized niche operators. Concentration metrics indicate that the top three competitors hold 42.0 percent of the market share, while the top five entities command 55.0 percent. This level of concentration suggests that while scale advantages are significant, there remains substantial room for specialized providers to capture value through customization, service quality, and regional expertise.
Leading the charge among major manufacturers is PalletOne Inc., based in Bartow, Florida. As the largest new wood pallet manufacturer in the United States, PalletOne offers a comprehensive suite of services spanning lumber sourcing to finished products, including new and recycled pallets, custom crates, and repair services. A recent development underscores the aggressive consolidation shaping the sector: in April 2026, UFP Industries acquired John Rock to expand PalletOne's footprint in the northeast. This move highlights a strategic push to deepen regional density and logistical efficiency, a trend that enterprises must monitor closely when evaluating supplier stability and market entry barriers.
On the other side of the operational spectrum, Millwood Inc. exemplifies the scale of processing and distribution. With an annual throughput of 200 million pallets, Millwood supplies new and recycled pallets to national accounts, leveraging over 40 years of engineering and manufacturing experience. Such scale allows for significant cost efficiencies and reliability, making it a critical benchmark for assessing operational standards in the industry.
International players are also redefining the competitive boundaries. Falkenhahn AG continues to innovate within the EPAL and wooden pallet solutions space, while PGS Group in France provides standard and custom wooden pallets and packaging solutions, emphasizing versatility in European markets. Meanwhile, Challenger Pallet focuses on sustainability-driven offerings, including custom and heat-treated pallets, alongside repaired and remanufactured options. Their commitment to new tree planting partnerships reflects a broader industry shift toward environmental stewardship that is increasingly influencing procurement criteria.
Regional specialization remains a potent strategy. Wooden Pallets LTD, operating out of Silsbee, Texas, produces over 15,000 pallets daily across facilities in Texas and Louisiana, demonstrating the enduring importance of localized production to meet demand fluctuations. Troymill Wood Products in Ohio serves the wholesale pallet and lumber market with a strong emphasis on compliance, offering in-house heat-treated pallets that meet ISPM-15 standards for export shipments. Similarly, Kamps Pallets distinguishes itself through enterprise-wide sustainability initiatives, including Zero Waste Certification, highlighting how environmental credentials are becoming a core component of brand value and operational efficiency.
Regulatory and Sustainability Dynamics
The strategic landscape for 2026 is heavily influenced by a complex web of regulations and sustainability imperatives. Compliance is no longer merely a checkbox; it is a market access requirement and a driver of innovation. A pivotal regulatory development is the entry into force of the EU Deforestation Regulation (EUDR). For large companies, compliance is required by December 30, 2025, with small companies following by June 30, 2026. New pallets, classified under HS code 4415, now require a due diligence statement proving deforestation-free origin. This regulation introduces new layers of traceability and documentation that will reshape sourcing strategies and cross-border trade flows.
Simultaneously, ISPM-15 compliance remains mandatory for export pallets. Manufacturers and exporters must ensure that wooden pallets are heat-treated and stamped to meet international phytosanitary requirements. Companies like Troymill Wood Products have built their value proposition around this compliance, offering in-house treatment capabilities that streamline the export process. As global trade volumes recover and reconfigure, the ability to navigate phytosanitary standards efficiently becomes a critical differentiator for logistics providers and pallet suppliers alike.
Advocacy and industry collaboration are yielding tangible results. In May 2026, the National Wooden Pallet and Container Association secured a significant victory by obtaining an exclusion for wooden pallets from California's new Extended Producer Responsibility (EPR) scheme. This outcome demonstrates the power of collective industry action in shaping regulatory frameworks to ensure that wood pallets, which are inherently reusable and recyclable, are not unfairly burdened by waste management policies designed for other materials. Furthermore, in February 2025, the Pallet Foundation awarded a historic grant to the National Wooden Pallet and Container Association to advance U.S. softwoods research. This investment in material science underscores the industry's commitment to optimizing raw material utilization and enhancing performance characteristics.
Segmentation and Structural Insights
Understanding the structural composition of the market is essential for targeted strategy. While specific regional and application breakdowns are detailed in the full report, the broader segmentation patterns reveal clear areas of focus. The market is divided across distinct product types, including softwood pallets, hardwood pallets, and a growing segment of recycled and engineered wood pallets. Each category presents unique value propositions, cost structures, and application suitability.
Softwood continues to dominate as a raw material backbone. Historical data indicates that softwood lumber accounted for a substantial majority of the lumber used in U.S. wooden pallet and container production. This reliance reinforces the importance of sustainable forestry management and supply chain resilience for softwood suppliers. In terms of dimensions, the 48 x 40 pallet size held a dominant new pallet market share historically, reflecting standardization benefits and compatibility with existing logistics infrastructure. However, the demand for custom sizes and specialized configurations persists in specific industrial and manufacturing contexts.
The application landscape spans diverse sectors, including logistics and transportation, manufacturing, retail and e-commerce, food and beverages, and other specialized uses. Each vertical imposes distinct requirements regarding durability, hygiene, load capacity, and handling cycles. For example, the retail and e-commerce segment often demands high volumes of standardized pallets to support rapid distribution, while manufacturing may require tailored solutions for specific machinery or production line constraints. The report delves deeply into these application dynamics, helping clients identify high-growth niches and understand the competitive intensity within each segment.
Operational Resilience and Waste Management
Sustainability metrics and waste management data provide critical context for the circular economy narrative. Contrary to perceptions of high waste generation, industry data reveals that only a small fraction of wood landfilled by municipal solid waste landfills and construction and demolition landfills consists of wood pallets. This statistic speaks to the high recovery, reuse, and recycling rates inherent in the pallet ecosystem. Companies with robust repair and remanufacturing capabilities, such as Challenger Pallet and Kamps Pallets, are well-positioned to capitalize on these circular flows, reducing material costs and enhancing environmental profiles. The shift toward recycled and engineered wood pallets is not just a sustainability trend; it is an economic opportunity to leverage alternative material streams and extend asset lifecycles.
Why This Report is Essential for 2026 Decision-Making
The Wood Pallet Market research from PW Consulting is designed to translate these complex dynamics into actionable intelligence. The report provides a granular examination of market size, growth trajectories, and segmentation structures that enable precise market sizing and forecasting for corporate planning teams. Beyond the numbers, we analyze the competitive profiles of key players, their strategic moves, and the implications of recent developments such as the UFP Industries acquisitions and the regulatory victories by industry associations.
Wood Pallet Market
Stakeholders will gain access to detailed assessments of regulatory risks, including the implications of EUDR and ISPM-15, along with guidance on compliance pathways. The study also explores raw material dynamics, regional demand drivers, and the evolving role of sustainability in procurement decisions. By mapping the competitive concentration and identifying the strategic positioning of leaders like PalletOne, Millwood, Falkenhahn, and others, the report offers a clear view of the barriers to entry, partnership opportunities, and potential threats.
We invite industry executives, investors, and supply chain leaders to leverage this comprehensive intelligence to sharpen their strategic focus. The full report contains the complete segmentation data, deep-dive regional analysis, detailed company profiles, and comprehensive forecasts that are essential for making informed decisions in 2026 and preparing for the years ahead. Access the full market research to unlock the detailed insights and secure a competitive edge in the evolving wood pallet landscape.
For detailed analysis of this topic, please visit the official page: Wood Pallet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


