



Category: IT & Electronics
PW Consulting: Paid Micro Short Drama Market to Reach USD 5,157.65M by 2032 (CAGR 22.45%)
By PW Consulting, 2026-07-13
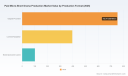
Paid Micro Short Drama Production Market — Strategic Preview for 2026 Decisions
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused preview of our latest market study on Paid Micro Short Drama Production. This market, measured on a 2025 base, has transformed from a niche experimental format in the early 2020s into a fast-scaling commercial ecosystem. Our topline: the global paid micro-short drama market expanded from a few hundred million dollars in 2020 to roughly USD 1.25 billion in 2025 and is forecast to continue growing at a robust compound annual growth rate of 22.45% through the 2026–2032 period, crossing multi-billion-dollar scale by the end of the forecast horizon.
Paid Micro Short Drama Production Market
This article is intentionally constructed as a “trailer” — it surfaces the analytical frameworks, strategic implications, and high-conviction recommendations you need to shape 2026 decisions, while withholding the granular segmentation tables and line-item benchmarks that are available in the full report.
Paid Micro Short Drama Production Market
Why executives must treat paid micro-dramas as a strategic priority in 2026
-
Attention economics at mobile scale: Consumers increasingly allocate discrete viewing sessions to vertical, episodic narratives that fit commutes and micro-moments. The format’s native simplicity accelerates discovery and repeat engagement, making retention strategies more tractable than many long-form alternatives.
Paid Micro Short Drama Production Market -
Monetization diversity: The category has proven multiple viable revenue paths — per-episode micropayments, coin-based unlocks, hybrid subscriptions, branded sponsorships, and licensing to OTT ecosystems. The report empirically maps where each archetype performs best against audience cohorts and content genres.
-
Production economics reconfigured by tooling: AI-assisted pipelines and compact shoot teams have materially compressed time and cost-to-market, enabling higher volume experimentation and experimentation at lower financial risk. At the same time, premium live-action productions remain a clear route to breakout titles and IP creation.
-
Platform and partnership plays: Telcos, social media ecosystems, dedicated apps and traditional OTTs are all vying for distribution. The competitive dynamics differ by partner archetype — platform owner economics, data access, and promotional mechanics vary in ways that directly affect unit economics and go-to-market choices.
What the PW Consulting report delivers (practical, decision-ready content)
-
Robust market sizing & forecast methodology that explains assumptions, sensitivity testing, and scenario outputs tied to consumer adoption, monetization uplift, and content supply dynamics.
-
Production economics playbook that models typical vertical microdrama shoots, AI-assisted workflows, and premium shoots — including break-even frameworks, margin levers, and unit economics by monetization archetype.
-
Go-to-market frameworks for studios and platforms: channel selection checklists, launch sequencing, sample promotional calendars, and CPA/LTV modeling templates.
-
IP and licensing toolkit: decision trees for original-IP vs. licensed adaptation vs. brand-sponsored commissioning, with contract templates and revenue split heuristics.
-
Operational playbooks for AI integration, talent contracting under new guild rules, regulatory compliance, and content moderation processes — practical checklists to deploy at studio scale.
-
Competitive landscaping and strategic benchmarks covering leading producers, platform operators and production service hubs, supplemented by anonymized financial comparators and KPI dashboards.
-
M&A and investment screening frameworks: target prioritization (capability gaps, content libraries, distribution reach), valuation heuristics and post-acquisition integration playbooks.
-
Ten actionable case studies and three model build-outs (studio-first, platform-first, brand-first) with sample P&L templates and sensitivity analyses.
Competitive landscape — what leading players are doing and why it matters
The ecosystem is populated by a mix of vertically integrated platform-producers, export-oriented studios, AI-native newcomers and legacy entertainment houses pivoting to vertical formats. Our analysis groups companies by strategic intent: platform-led distribution champions, production-focused exporters, AI-first efficiency innovators, and premium content houses targeting international audiences.
-
Platform-led producers: Companies that combine an owned app with production capabilities are optimizing for lifetime value (LTV) via subscription and coin-based mechanics. Their differentiator is direct-to-consumer data, which translates to more precise user segmentation and retention levers.
-
Export and localization specialists: Certain producers concentrate on rapid overseas traction by translating and localizing vertical series. Their competitive edge is cultural adaptation and distribution partnerships that unlock cross-border monetization.
-
AI-native innovators: A new cohort deploys end-to-end AI workflows to compress time-to-market dramatically. These entrants are proving that high-volume, lower-cost experimentation can rapidly uncover engaging IP, though they also face creative perception and regulatory labeling headwinds.
-
Premium international houses: Some studios bring traditional Hollywood production values to vertical formats, aiming for global hits that command higher price points and licensing fees.
Representative names illustrate these archetypes (profiles and full competitive matrix are in the main report):
-
A leading app-owner that pairs episodic vertical content with coin unlocks and subscriptions to drive engagement and cross-border growth. Their model shows how platform control plus aggressive content investment can scale audience value.
-
A major Beijing-based producer and platform operator that emphasizes translated and localized series for overseas markets, demonstrating the exportability of well-crafted micro-dramas.
-
Studios expanding regional slates with proven chart performance in targeted Asian markets, deploying festival and trade-show slates to drive licensing deals.
-
AI-first teams that delivered fully AI-produced multi-episode titles in weeks, proving a new creative-production vector for English and global audiences.
-
Traditional production houses adapting Hollywood techniques for vertical formats and securing strategic investment from major studios to scale internationally.
Regulatory, labor and production dynamics to monitor
-
Regulatory labeling and review for AI-generated content: Authorities in multiple markets have introduced labeling requirements and content review mechanics for AI-derived productions. Compliance is non-negotiable for broad distribution and platform partnerships.
-
Talent and guild frameworks: Industry guilds have begun updating contracts specific to microdrama productions. Studios should embed guild-compliance into budgeting and casting playbooks to avoid strikes and reputational risk.
-
Production cost structure bifurcation: Two production pathways are prominent — compact, rapid live-action shoots and AI-assisted or AI-native production. Each has distinct risk-return profiles; the right mix depends on your IP ambitions and scale goals.
Strategic imperatives and tactical moves for 2026
-
Build a diversified monetization portfolio — don’t rely on a single revenue stream. Test coin mechanics, episodic bundles, subscription hybrids and brand-funded series in controlled pilots to establish elasticities and LTV baselines.
-
Prioritize platform partnerships that offer promotional equity and data access. A slightly lower upfront fee that comes with first-party data often outperforms a higher-fee, data-limited deal for long-term LTV.
-
Invest in a modular production stack that allows rapid switching between AI-assisted and live-action workflows. Standardize reusable assets and talent pools to reduce per-episode friction.
-
Develop IP-first pipelines even when launching as single-season microdramas. IP agility — the ability to scale winning titles into localized spins or longer-form adaptations — is a primary value multiplier.
-
Operationalize regulatory and guild compliance now. Build labeling, consent and residual processes into contracts and content workflows to avoid distribution delays later.
-
Set clear KPIs: trial-to-paid conversion, weekly active user retention for micro-sessions, average revenue per paying user, and content churn rates. Use these to drive content commissioning and promotional spend decisions.
Critical risks and scenario triggers
-
Regulatory tightening on AI or cross-border content could increase compliance costs and slow go-to-market plans.
-
Union negotiations and emerging talent minimums for microdramas could raise baseline production costs if not anticipated.
-
Platform concentration risk: overdependence on a single distribution partner materially increases commercial risk; maintain diversified outlet strategies.
-
Creative fatigue: as volume increases, discoverability and differentiation will decide winners. Investment in storytelling craft and audience analytics is non-negotiable.
Next steps and how to use this preview
If your 2026 capital allocation, content slate planning or partnership strategy intersects with paid micro short dramas, the full PW Consulting report provides the granular segmentation, region- and format-level forecasts, deal benchmarks, anonymized unit-economy models, and a detailed competitive matrix you’ll need to operationalize decisions. Use the frameworks in this preview to prioritize test investments and to build an informed brief for rapid pilots; then consult the full report to size investments and negotiate partner terms with confidence.
PW Consulting is issuing tailored briefings for executive teams, investor committees and content strategy units through Q3 2026. Our team can overlay your assets onto the market map, stress-test monetization scenarios, and produce an acquisition screening shortlist or a pilot design playbook tuned to your objectives.
For decision-makers who need to move from curiosity to commitment in 2026: adopt a test-and-scale mindset, secure diversified distribution, operationalize AI and regulatory compliance in tandem, and design for IP optionality. The market’s growth trajectory is clear; the winners will be those who combine disciplined economics with creative ambition.
— PW Consulting, Senior Strategic Advisor & Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: Paid Micro Short Drama Production Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cloud Backup System Market to Reach USD 15,083M by 2032 at 11.25% CAGR
By PW Consulting, 2026-07-13
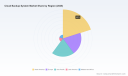
Cloud Backup System Market — Strategic Preview for 2026 Decision Makers
Executive snapshot
As enterprises plan capital and operating budgets for 2026, cloud backup is no longer a point product; it is a strategic capability that intersects cybersecurity, compliance, sustainability and service continuity. Our new PW Consulting study positions the Cloud Backup System market as a dynamically expanding sector — growing from a mid-single-digit billion-dollar base in the early 2020s to an addressable market that crosses the multi‑billion‑dollar threshold by the end of the decade. Specifically, the market expanded from approximately USD 5.78 billion in 2023 to roughly USD 7.15 billion in 2025, and under a central forecast scenario it grows at a compound annual growth rate (CAGR) of 11.25% to reach about USD 15.08 billion by 2032.
Cloud Backup System Market
Why this study matters for 2026 decisions
-
Budget prioritization: With an 11.25% CAGR baked into our baseline forecast, cloud backup budgets will compete with adjacent investments (e.g., DR orchestration, data governance and cyber insurance). Procurement teams need a defensible rationale for spend allocation that ties to recovery time objectives (RTOs), regulatory exposure and total cost of ownership (TCO).
Cloud Backup System Market -
Vendor selection and partnership strategy: The market is mixed — a set of large cloud platform incumbents and a vigorous set of specialised vendors. Our concentration analysis shows the top three vendors account for a meaningful but not dominant share of market revenues (market concentration metrics are included in the full report). This balance creates opportunities for both scale players and focused specialists, depending on an organisation’s risk profile and operational model.
Cloud Backup System Market -
Policy and sustainability alignment: Energy and infrastructure constraints — and new reporting mandates — mean backup architecture decisions have implications beyond recovery performance. Expect procurement requirements in 2026 to include energy efficiency and data locality clauses alongside SLAs and cybersecurity controls.
Market trajectory and strategic implications
The mid‑2020s are a hinge point. Demand for cloud backup is being driven by several converging forces: an acceleration of SaaS and cloud-native workloads; rising ransomware and data‑integrity threats; and regulatory pressure on data sovereignty and operational resilience. Over the forecast horizon, we see three macro trajectories that buyers and providers must plan for simultaneously:
-
Volume and cadence: Data volumes continue to rise, and business recovery expectations compress backup cadences. Providers that can deliver efficient, frequent backups without linear cost increases will displace legacy models.
-
Platform convergence: Backup functionality is folding into broader data management and cyber resilience stacks. Expect acquisitions and broadened product roadmaps as vendors pursue one‑stop solutions for backup, recovery, detection and compliance.
-
Infrastructure friction: Real-world constraints — from rising data center construction costs to electricity consumption metrics that are now regulated in multiple jurisdictions — will shape where and how backups are stored and replicated.
Competitive landscape — what the leading players signal for 2026
The competitive set includes hyperscalers, legacy enterprise software vendors and a cadre of cloud‑native specialists. Our analysis highlights tactical themes illustrated by recent vendor moves:
-
Hyperscaler integration and native services. Major cloud platforms continue to expand native backup and recovery services as part of their cloud ecosystems, emphasizing automated policy orchestration, multi‑region availability and deep platform integration. For enterprise buyers, this increases the attractiveness of “backup as an integrated service” but raises questions about cross‑cloud portability and vendor lock‑in.
-
Feature parity and differentiation. Established backup specialists are racing to embed cybersecurity primitives (e.g., immutable vaults, air‑gap architectures, ransomware scanners) alongside governance controls to serve enterprise compliance needs. Recent product updates from vendors have notably extended ransomware detection coverage and multi‑cloud scanning capabilities.
-
Partnership ecosystems and recognition plays. Strategic alliances between infrastructure and data management vendors are becoming a primary route to scale. Recognition and partner awards reflect who the hyperscalers are choosing to co‑deliver resilience solutions — an important market signal for buyers selecting partners for large deployments.
-
Consolidation pressure and survivorship. Mid‑tier consolidation will likely continue as vendors pursue breadth (adding data management, DR orchestration and cloud cost optimisation) or depth (specialising in SaaS backup, endpoint protection or immutable cloud vaults).
Recent vendor trends to watch
-
Expanded cybersecurity integration: Vendors are not only backing up data but scanning for integrity deviations and embedding recovery playbooks that align with incident response.
-
Higher-frequency and multi‑region recovery capabilities: Faster snapshot cadences and multi‑region vaulting are moving from advanced options to buyer expectations, particularly for critical compute and database workloads.
-
Platform partnerships: Advances in partner programs and co‑engineering efforts are accelerating product maturity for hybrid and cloud‑native deployments.
-
Continuous product iteration: Regular releases are reducing feature gaps between hyperscaler-native services and specialist vendors, making product evaluation a live exercise instead of a point‑in‑time check.
Regulatory, cost and infrastructure pressures shaping supplier and buyer choices
External forces materially affect the economics and design of backup architectures:
-
Energy and reporting mandates: Regulatory frameworks now require reporting of power and water efficiency metrics for data centers in some major markets. This increases the importance of PUE/WUE considerations in backup site selection and may shift preferences toward efficient object storage strategies and cold‑tier policies.
-
Data sovereignty and privacy: Increasingly, local regulation drives demand for regionally co‑located or edge backup nodes. Buyers must reconcile data residency requirements with the operational benefits of centralised multi‑region vaults.
-
Infrastructure costs: Rising data center construction and power costs raise the economic threshold for storing large volumes on-premises, accelerating adoption of cloud‑centric and hybrid models that optimise for both cost and recovery SLAs.
What the PW Consulting report delivers (practical, actionable content)
We designed this study as an execution toolkit for technology leaders, procurement teams and corporate strategists. Key deliverables include:
-
Market sizing and scenario models — with a clear baseline and alternate scenarios that stress inflation, energy shocks and rapid RTO compression.
-
Vendor universe and comparative scorecards — covering functional capability, cyber resilience, multi‑cloud support and commercial models.
-
Operational playbooks — recovery runbooks, SLA negotiation checklists, and implementation migration paths for lift‑and‑shift, hybrid and native reintegration approaches.
-
TCO and procurement frameworks — including example cost models that incorporate energy and data egress dynamics, and contract amendment templates to protect buyers against vendor lock‑in.
-
Regulatory impact assessments — jurisdictional analysis templates that translate data sovereignty and energy reporting rules into actionable architecture decisions.
-
Strategic options matrix — acquisition targets, partnership archetypes and capability investment priorities based on buyer risk appetite and cloud maturity.
Note: The public preview intentionally omits granular subsegment breakdowns and regional percentage splits. Those detailed tables, vendor scorecards and downloadable models are available in the full report and interactive dashboard.
How to use the study in your 2026 planning cycle
-
Quarterly roadmaps: Use our cadence and cost scenarios to stress test your operating plan and to create contingency budgets aligned with different threat and regulation outcomes.
-
Vendor shortlisting: Start with our high‑level vendor archetypes and pair them with the scorecard to arrive at a 3‑vendor shortlist for technical proofs of concept (POCs).
-
Procurement and legal alignment: Incorporate the report’s recommended clauses on data portability, immutable storage and energy efficiency into RFPs and master agreements.
-
M&A and partner scouting: Leverage our strategic options matrix to identify bolt‑on acquisitions and partnership targets that accelerate time‑to‑market for resilience features.
Final perspective — the decision lens for 2026
Cloud backup is maturing from commodity storage to a strategic resilience discipline. For 2026, boards and technology executives should evaluate investments through three lenses: operational resilience (Can we recover within business tolerances?), regulatory alignment (Can we prove compliance and data locality?), and economic sustainability (Do our backup architectures scale without untenable increases in energy or capital cost?).
PW Consulting’s Cloud Backup System Market study provides both the macro market trajectory and the tactical playbooks to answer these questions. The preview above is designed to orient your leadership team; the full report contains the granular datasets, vendor scorecards and downloadable models required to execute a defensible 2026 strategy. For access to the complete analysis and interactive tools, please visit our research page.
For detailed analysis of this topic, please visit the official page: Cloud Backup System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Closeouts Market to Reach USD 454.0B by 2032 at 6.85% CAGR — PW Consulting Insight
By PW Consulting, 2026-07-13
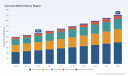
Closeouts Market — 2026 Strategic Brief
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present this executive introduction to our forthcoming Closeouts Market research — a strategic primer intended to orient C-suite leaders, corporate strategists, and private equity investors preparing decisions in 2026. This brief demonstrates the depth of our analysis, highlights the critical forces reshaping the closeouts ecosystem, and outlines the concrete decision levers companies must master. In keeping with the “trailer” principle, we intentionally surface high‑level findings and strategic implications while reserving core subsegment tables and granular breakdowns for the full report and interactive datasets on our source page.
Closeouts Market
Market trajectory: clarity at the macro level
Our base-year analysis (2025) and historical review (2020–2025) underpin a forward-looking forecast spanning 2026–2032. The global closeouts market is on a sustained expansion path, driven by structural overstock generation, accelerating secondary channels, and increasing buyer sophistication. At the macro level, the market expands from the mid‑hundreds of billion USD range in 2023–2025 into a larger market by 2032 under a compound annual growth rate of 6.85%. To provide a sense of scale, our topline trajectory moves from the mid‑200s Billion USD in the early 2020s to a market size exceeding four hundred Billion USD by the end of the forecast period — a growth pattern that demands strategic reorientation by incumbents and new entrants alike.
Closeouts Market
Why this matters for 2026 corporate decisions
- Liquidity as a competitive lever: With elevated overstock levels driven by conservative retail inventory strategies and several high‑profile bankruptcies, the ability to convert slow‑moving inventory into cash faster than peers is a sustainable advantage.
- Channel economics are shifting: Digital auction platforms, B2B marketplaces and programmatic liquidation enable more granular price discovery and selective recovery strategies, altering the return profile of closeouts compared with traditional wholesale and auction channels.
- Policy and cost headwinds: Ongoing U.S. tariff dynamics on consumer imports are affecting landed costs and cross‑border arbitrage economics, creating both risk and opportunity for players who can actively manage regulatory pass‑through and sourcing flexibility.
- Consolidation opportunities: Market concentration is low relative to many consumer‑goods sectors (our concentration metrics show the top three firms account for less than one‑quarter of market share and the top five still represent a minority). This fragmentation leaves room for scale players to consolidate supply relationships and capture disproportionate recovery margins.
What the full report delivers — practical, transaction‑ready content
The full Closeouts Market report is designed to be a working tool for 2026 strategies. Its principal deliverables include:
Closeouts Market
- Robust market model: A reconciled topline model from 2020 through 2032 with scenario outputs, sensitivity analyses, and an extensible spreadsheet that allows teams to test custom assumptions.
- Channel playbooks: Detailed playbooks for online liquidation platforms, auction-based channels, and secondary retail partnerships — including cost-to-serve templates, recommended lot sizing and lot composition strategies, and margin improvement levers.
- Operational diagnostics: KPIs and benchmarking tools for condition grading, disposition velocity, recovery percentiles, and logistics cost drivers — enabling rapid diagnostics of opportunity gaps across a portfolio.
- M&A and partnership roadmap: Criteria matrices and valuation frameworks for roll-up plays, platform acquisitions, and exclusive supplier partnerships, complete with integration checklists and synergy capture plans.
- Regulatory and tariff playbook: Scenario modelling for tariff pass‑through, inventory reclassification tactics, and customs optimization steps to protect margins under shifting trade regimes.
- Digital transformation guide: Tactical guidance on pricing algorithms, condition‑scoring automation (vision and data ingestion), fraud detection, and marketplace UX improvements that demonstrably lift realized recovery rates.
- Sustainability and resale strategy: ESG-aligned frameworks for maximizing asset reuse, refurbish-and-resell flows, and responsible disposal options that reduce reputational and regulatory exposure.
Competitive landscape — where the money flows and who to watch
The competitive map of the closeouts industry combines native online marketplaces, auction specialists, pallet and truckload wholesalers, and mixed merchandise distributors. Notable operators profiled in our research include:
- Direct Liquidation (United States) — An industry leader that partners with national retailers and manufacturers to channel name‑brand overstock, returns and surplus through auction and wholesale routes.
- B-Stock (United States, bstock.com) — A specialized online wholesale marketplace connecting professional buyers with large‑scale overstock and returns from major retailers and e‑commerce platforms.
- Liquidation.com (United States, liquidation.com) — An auction‑centric platform with deep volumes in surplus consumer goods from broad retailer and manufacturer networks.
- BULQ (United States, bulq.com) — A supplier of palletized liquidation inventory focused on predictable lot profiles for resellers and secondary retailers.
- Overstock Trader, Total Surplus Solutions, Countryside Closeouts, Kole Imports, Global Distributors, UpLiquidation — A set of national wholesalers and distributors that participate across B2B channels, private sales and bulk distribution networks.
Our concentration metrics are revealing: the top three firms capture under 20% of the market and the top five sit below one quarter. That market fragmentation is a double‑edged sword — it lowers barriers to entry for specialized, tech-enabled challengers while presenting attractive consolidation and scale-up economics for strategic acquirers. In practice, the most successful players combine deep supplier relationships (retail and manufacturer), proprietary demand pools (repeat buyer networks), and data-enabled pricing engines.
Key 2026 strategic plays — prioritized, actionable, measurable
Based on our analysis and fieldwork through Q1 2026 (including insights from industry events such as ASD Market Week), we recommend leaders prioritize the following plays and metrics:
- Secure diversified supply corridors: Build direct procurement agreements with retailers and manufacturers, include first‑look clauses on returns, and develop a special situations desk to source distressed inventory from bankruptcy estates.
- Invest in digital price discovery: Deploy dynamic auction mechanisms and machine learning pricing models that optimize lot composition and timing to maximize recovery, with A/B testing across platforms to quantify uplift.
- Reconfigure logistics for reverse flows: Create regional consolidation hubs and hub‑and‑spoke reverse supply chains to reduce handling and accelerate conversion to sale — measure improvements in inventory velocity and landed disposal costs.
- Hedge regulatory exposure: Implement tariff‑aware sourcing and pass‑through policies, and run scenario stress tests on landed cost sensitivity as part of quarterly commercial reviews.
- Monetize data: Package buyer demand signals, condition insights and price discovery history into value‑added services for suppliers — a new revenue stream and a sticky supplier lock‑in mechanism.
- Pursue tuck‑ins with clear synergy paths: Focus M&A on targets that deliver immediate operational leverage (buyer pools, warehouse footprint, tech capabilities), and use our integration scorecards to prioritize deals by payback speed.
- Embed ESG and consumer‑facing provenance: Leverage refurbishment, certification, and provenance tracking to access premium secondary channels and reduce disposal liabilities.
How to use this research in your 2026 planning cadence
Applying the report is practical and repeatable across investment and operating agendas:
- For portfolio companies: use our benchmarking tools in Q1 planning to set KPI targets (recovery %, inventory days, average lot price) and to construct three plausible scenarios for 2026 operational budgets.
- For corporate strategists: map supplier and buyer relationships against the competitive map to identify exclusivity opportunities and strategic partnerships where margin pools are concentrated.
- For private equity and M&A teams: apply our valuation multiples and synergy templates to target screening, and use the report’s diligence checklist to accelerate deal execution.
Sources, scope and a final note on access
The insights summarized here draw from a blended evidence base: reconciled market models, primary interviews with platform operators and large buyers, supply chain datasets, public filings, and field intelligence gathered at industry gatherings (including ASD Market Week, March 2026). We explicitly model tariff and trade scenarios aligned with public economic analysis and industry filings to reflect current policy uncertainty.
In line with the “trailer” principle, this brief intentionally omits detailed regional and product‑category splits, company‑level share tables, and the full set of downloadable models. Those granular datasets, along with interactive dashboards and the complete methodological appendix, are available in the full Closeouts Market report on our source page. Accessing that content will provide the subsegment economics and deal‑level detail necessary to execute any of the strategic plays outlined above with confidence.
PW Consulting’s Closeouts Market report is built to be operational: a living toolkit for 2026 decisions. If your team is preparing to reposition supply chains, pursue platform M&A, or monetize secondary inventory flows this year, this research will be the backbone of those efforts.
For detailed analysis of this topic, please visit the official page: Closeouts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SMD Common Mode Chokes Market Poised for 6.5% CAGR Through 2032
By PW Consulting, 2026-07-13
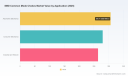
SMD Common Mode Chokes Market — Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a concise, strategy‑oriented preview of our full SMD Common Mode Chokes market study. This briefing synthesizes the macro trajectory, competitive posture, supply‑side stress points and the practical decision levers that will matter most to executives planning investments and commercial moves in 2026. Our report uses 2025 as the base year and models the market across 2026–2032 with a compounded annual growth rate (CAGR) of 6.5%. The SMD common mode choke market is estimated at roughly USD 850 million in 2025 and is projected to expand to the order of USD 1.32 billion by 2032 — a steady, structurally supported growth path rather than a short‑lived spike.
Smd Common Mode Chokes Market
Why SMD Common Mode Chokes deserve boardroom attention in 2026
-
Fundamental role in electrification and connectivity: As vehicle electrification, renewable generation, power conversion and high‑speed data infrastructures accelerate, the demand for effective EMI/EMC suppression at the component level becomes a gating factor for system performance and regulatory compliance. SMD common mode chokes sit at the intersection of these trends.
Smd Common Mode Chokes Market -
Technology and thermal constraints are creating premium segments: Higher current ratings, lower insertion loss, and smaller footprints are simultaneously demanded in power‑dense applications. That technical squeeze favors suppliers with advanced core materials, tooling and thermal design capabilities.
Smd Common Mode Chokes Market -
Regulatory and compliance tailwinds: Global EMC and power quality standards (including industry benchmarks used in power applications) raise the cost of rework and time‑to‑market for non‑compliant designs, increasing the value of validated, certified components.
-
Market scale and resilience: The market’s mid‑single‑digit CAGR and near doubling over the longer horizon point to a stable, investible segment where disciplined product and supply strategies can generate differentiated returns.
Interpreting the macro trajectory: what a 6.5% CAGR means in practice
-
Measured expansion rather than hypergrowth: With a base near USD 850 million in 2025 and a forecasted increase into the low‑billion range by 2032, the market offers steady volume growth and incremental pricing opportunities. This environment rewards operational excellence, targeted product development, and selective vertical integration rather than speculative capacity bets.
-
Timing of investment: Product roadmaps and qualification cycles should be aligned to capture the mid‑cycle demand lift expected in the first half of the forecast window (2026–2029) while planning for differentiated offerings for advanced end uses through 2030–2032.
-
Risk‑adjusted returns: The trajectory supports investment in yield improvement, higher‑current and high‑temperature rated variants, as well as in materials R&D for cores and winding techniques that reduce cost-per‑function over the forecast period.
Supply‑side dynamics and actionable risk mitigation
-
Material concentration and lead times: Ferrite cores and specialized nanocrystalline cores are critical inputs. Standard lead times for nanocrystalline cores typically sit in the 8–12 week band and can extend to 16–22 weeks during constrained periods. Copper and ferrite price volatility, influenced by broader commodity and geopolitical dynamics, directly compress margins.
-
Operational levers for procurement teams: We recommend a layered sourcing posture — strategic long‑lead contracts for core materials, validated secondary suppliers for copper and ferrite, and safety stock calibrated to product criticality. Design teams should prioritize substitute‑friendly choices and modular designs to enable component-level flexibility.
-
Manufacturing footprint considerations: Asia‑Pacific remains a primary production hub. However, near‑market capacity expansion or strategic local sourcing for high‑volume automotive and industrial programs can shorten qualification cycles and reduce logistics risk.
Competitive landscape — concentrated but diverse
-
Market concentration: Our analysis shows a moderate level of concentration at the top. The top three suppliers account for a meaningful share of the market, and the top five consolidate just over half of market value. This structure produces pockets of supplier power while still leaving room for differentiated entrants.
-
Strategic profiles to watch:
- TDK Corporation (Tokyo): Strength in high‑current surface‑mount solutions for power electronics and industrial drives, including series rated for very high currents and reflow compatibility.
- Murata Manufacturing (Kyoto): Broad SMD/SMT portfolio focused on EMC compliance across a wide span of sizes and ratings — strength in miniaturized, high‑reliability options.
- YAGEO Group (Pulse Electronics) (Taipei): Targeted high‑current parts for DC/DC and power lines, expanding options for 20–25A class needs.
- Bourns , Vishay , Schaffner , Eaton , Littelfuse , Sumida , and Coilcraft : each occupies niches in automotive‑grade, industrial, power management and high‑frequency suppression, with varying strengths in qualification, thermal performance and integrated protection features.
-
Recent competitive moves: Leading suppliers continue to introduce higher‑current SMD choke families and variants optimized for reflow and automotive temperature profiles. These launches are consistent with end‑market demand for compact, robust EMI solutions in power and telecom segments.
Implications for product and go‑to‑market strategy
-
Portfolio prioritization: Invest selectively in higher‑margin, higher‑current, and automotive‑qualified SKUs. Commodity, low‑margin variants require scale and cost leadership; differentiated parts can be priced to reflect design‑in value and shortened BOM risk for customers.
-
Customer‑centric qualification programs: Offer turnkey qualification packages (thermal, vibration, EMC certification) to shorten OEM adoption cycles. Co‑engineering and early sample provisioning will be effective for winning design slots in 2026 programs.
-
Channel and inventory strategies: For suppliers and distributors, blended inventory models — combining consigned safety stock for key customers with dynamic replenishment for lower‑tier accounts — mitigate the dual challenge of lead time volatility and demand seasonality.
-
M&A and partnerships: The structure rewards bolt‑on acquisitions that add material expertise (core materials, winding automation) or expand qualification capabilities, particularly in the automotive and industrial ecosystems.
What the full PW Consulting report delivers — practical, actionable assets
-
Forecast models with scenario toggles: Our model projects base, upside and constrained scenarios across 2026–2032 and allows users to stress test inputs such as commodity inflation, lead‑time extensions and adoption waves in EV/renewable sectors.
-
Supplier scorecards and capability maps: Comparative analysis of technology depth, manufacturing footprint, certification status and recent product launches for the major vendors.
-
Commercial playbooks: Win themes for suppliers, procurement negotiation scripts for OEM buyers, and go‑to‑market approaches for distributors and EMS partners.
-
Supply chain playbook: Recommended dual‑sourcing architectures, inventory sizing heuristics tied to lead‑time bands, and a decision tree for when to vertically integrate versus contract out specialized core production.
-
Data workbooks: Underlying spreadsheets, price and cost‑sensitivity tables, and an interactive dashboard summarizing the market by type, region and application. Note: This preview intentionally omits granular region‑ and application‑level splits to preserve the commercial value of the full dataset; the complete breakdowns are available in the paid report.
Executive checklist for 2026
-
Align R&D roadmaps to high‑current and high‑temperature variants that will capture premium segments over the next three years.
-
Negotiate multi‑year material agreements for ferrite and nanocrystalline cores, with explicit clauses for lead‑time guarantees and price pass‑throughs.
-
Prioritize qualification efforts for automotive and industrial customers where longer qualification cycles translate to higher switching costs.
-
Use the market concentration dynamics to evaluate competitive M&A or strategic alliances that close capability gaps swiftly.
-
Implement a demand‑sensing inventory strategy to reduce obsolescence while ensuring supply for high‑value design wins.
Final note — why PW Consulting’s study matters now
The SMD common mode choke market presents a stable growth runway with pockets of technical and commercial differentiation where capable players can extract superior returns. Our 2026‑focused guidance translates the macro projection (CAGR 6.5%, base year 2025) into executable actions across product development, sourcing, operations and M&A. This preview is designed to establish the strategic frame; the full PW Consulting report contains the granular segmentation, supplier scorecards and downloadable models that decision makers need to convert insight into action. For firms targeting design‑in wins, supply resilience, or bolt‑on capability expansion in 2026, the detailed intelligence in the full report becomes a practical planning asset.
For detailed analysis of this topic, please visit the official page: Smd Common Mode Chokes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Data Center Battery Backup Market set to grow at 8.15% CAGR through 2032
By PW Consulting, 2026-07-13
Data Center Battery Backup Unit Market: Strategic Imperatives for 2026 Decision-Makers
As hyperscale deployments, AI workloads and stricter availability SLAs reshape data center economics, battery backup units (BBUs) have moved from commoditized insurance to strategic infrastructure. PW Consulting’s latest market study—anchored on 2025 as the base year and projecting through 2032—translates these tectonic shifts into an actionable decision framework for CIOs, data center operators, and procurement teams in 2026. Our analysis synthesizes historical trends, near‑term market forces and plausible technology paths to help you prioritize capital, mitigate supply‑chain exposure and design resilient power architectures.
Data Center Battery Backup Unit Market
Why this study matters for 2026 planning
-
Timing: 2026 is a pivot year. Capital allocations made now will determine the next 5–10 years of UPS and BBU lifecycle costs, compatibility with emerging architectures, and the ability to support bursty AI loads.
Data Center Battery Backup Unit Market -
Clarity: Our report converts macro growth and concentration dynamics into procurement priorities—without forcing buyers to wade through raw spreadsheets. We balance market sizing with scenario-ready playbooks that are immediately deployable.
Data Center Battery Backup Unit Market -
Risk management: We integrate supplier concentration, raw material exposure and regulatory developments into practical mitigation strategies for procurement, logistics and engineering teams.
Market trajectory and what it means
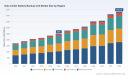
Data center BBUs have exhibited steady expansion over the past half‑decade and continue to accelerate as operators pursue higher resiliency and energy‑optimized designs. The market expanded from a base measured in 2020 and reached an evaluated size in 2025 that sets the foundation for robust growth. Our forecast through 2032 implies a compound annual growth rate of 8.15% across the 2026–2032 window, with the market more than doubling in value relative to the early 2020s under several demand scenarios.
Two implications flow directly from this trajectory. First, vendors that can demonstrate scalable manufacturing, predictable lifecycle economics and validated high‑temperature or high‑cycle chemistries will capture disproportionate share. Second, buyers who postpone strategic supplier qualification risk facing longer lead times and higher TCO as raw‑material and tariff dynamics crystallize.
Technology and supply‑chain dynamics reshaping choices
Decision-makers in 2026 must balance four intertwined technology considerations: energy density vs. safety, cycle life vs. upfront cost, system modularity vs. integration risk, and thermal management vs. footprint. Lithium‑ion chemistries—particularly iron‑based formulations—have become the default when space and fast recharge are priorities, while advanced lead variants retain relevance where proven long‑duration reliability and cost predictability are dominant requirements.
Supply‑chain realities are an equally decisive layer. China’s dominant role in certain cell and cathode production, concentrated LFP output and cross‑border tariff policies are creating asymmetric sourcing risk for western buyers. In parallel, cell‑level pricing trends in 2026 place data center‑grade LFP at a cost profile that materially changes installed BESS economics versus traditional chemistry selections. Finally, equipment lead times—exacerbated by long procurement cycles for transformers and other heavy electricals—mean project timelines can be driven more by upstream constraints than by on‑site construction pace.
Competitive landscape — who matters and why
The market displays moderate concentration: a cluster of established power system OEMs and specialized battery manufacturers account for a meaningful portion of capacity, but the remainder is served by regional vendors and newer entrants. This structure creates opportunities for strategic partnerships, co‑development and competitive sourcing.
-
EnerSys (Reading, PA) — Strengths: deep heritage in industrial lead‑acid and advanced TPPL solutions optimized for high‑temperature operation and grid‑support features. Strategic posture: defending legacy enterprise accounts while piloting lithium platforms to broaden addressable markets.
-
C&D Technologies (Columbus, GA) — Strengths: long track record in VRLA and pure lead AGM solutions tailored to UPS ecosystems. Strategic posture: leveraging century‑long customer relationships in colocation and enterprise segments to maintain installed base lock‑in.
-
Saft (France) — Strengths: turnkey lithium systems and utility‑scale integration capabilities. Strategic posture: positioning for large, energy‑storage‑centric installations where system integration and lifecycle services command premium pricing.
-
Schneider Electric (France) — Strengths: modular UPS platforms with integrated lithium battery options and strong software for energy management. Strategic posture: selling holistic solutions that blur the line between UPS vendor and data center energy architect.
-
Eaton (Ireland) — Strengths: high‑efficiency UPS families and proven lithium integrations. Strategic posture: competing on reliability and global service footprint to win enterprise and hyperscale projects.
-
Vertiv (USA) — Strengths: integrated rack and facility solutions with an emphasis on efficiency. Strategic posture: pushing into AI‑optimized offerings via partnerships and targeted product collaborations.
-
Mitsubishi Electric (Japan) — Strengths: industrial grade UPS platforms compatible with a range of battery chemistries; deep OEM ties in APAC markets. Strategic posture: offering resilient hardware stacks favored by mission‑critical operators.
-
ABB (Switzerland) — Strengths: modular, high‑power systems aimed at AI‑ready and large‑scale data centers. Strategic posture: competing for the upper end of the market where scale and advanced integration matter most.
Recent market moves reinforce two themes. First, product innovation targeted at AI workloads and high‑density racks is accelerating—new silicon‑carbon anode systems and liquid‑cooled rack UPS variants recently announced point to shrinking footprint and higher thermal demands. Second, incumbents continue to defend installed bases with trials and gradual lithium adoption, rather than abrupt migration away from legacy chemistries.
Recent signals that matter to procurement and strategy teams
-
New product architectures designed for AI platforms are reducing space requirements and changing installation constraints—impacting how operators plan capacity per rack and per pod.
-
Supply‑side reporting in 2026 shows strong residual demand for tried‑and‑tested lead solutions across certain market pockets, even as lithium trials expand—underscoring the need for differentiated supplier strategies.
-
Trade policies and raw‑material geographies are actively reshaping total cost models; tariffs and concentrated cathode production are creating pockets of elevated sourcing cost and lead‑time risk.
Strategic actions for 2026 — a practical playbook
With the market dynamics above, organizations should consider a prioritized set of actions in the next 12–18 months:
-
Segment your demand by risk‑profile: Separate mission‑critical loads that require proven chemistries from fungible capacities where newer, denser solutions can be piloted. This reduces disruption risk while permitting controlled innovation.
-
Qualify dual‑track suppliers: Maintain a shortlist that includes legacy battery specialists and systems integrators with lithium capabilities. Insist on demonstrable lifecycle testing and local service coverage in RFPs.
-
Lock in logistics and lead‑time clauses: For projects with long electrical procurement cycles, incorporate milestone‑based delivery windows and alternative sourcing triggers into contracts to hedge transformer and cell scarcity.
-
Adopt scenario TCOs, not capex-only comparisons: Model battery decisions across total lifecycle costs, including energy arbitrage potential, maintenance, replacement intervals and disposal liabilities under multiple grid and tariff futures.
-
Design for modularity and future upgrades: Specify UPS and battery racks that allow cell chemistry swaps and capacity expansions with minimal civil works—this preserves optionality as technology economics shift.
-
Invest in supplier transparency: Require BOM‑level sourcing maps for critical components and periodic audits to understand exposure to material concentration risks.
What’s inside PW Consulting’s full report (select, actionable deliverables)
-
Consolidated market sizing and medium‑term forecasts with sensitivity bands and demand scenarios tailored to enterprise, colocation and hyperscale segments.
-
Technology profiles comparing lifecycle metrics, safety tradeoffs and retrofit pathways for lead‑acid variants, lithium chemistries and emergent anode/cathode technologies.
-
Vendor capability matrices and pragmatic vendor selection frameworks that map product features to operator priorities (resiliency, TCO, sustainability, footprint).
-
Supply‑chain risk maps highlighting critical nodes, tariff exposure and mitigation options including dual sourcing, inventory hedging and local assembly strategies.
-
Procurement playbooks, sample RFP language and contract terms designed to protect schedule, margins and performance across multi‑year deployments.
-
Scenario planning modules—ready to slot into capital planning and corporate risk registers—covering price shocks, regulatory shifts and technology disruptions.
Note: while this overview articulates macro growth, competitive positioning and strategic recommendations, the full report contains the detailed segmentation, vendor scorecards and granular regional and application breakouts that many organizations require to execute procurement and architecture changes. Those datasets are intentionally gated to preserve the integrity of competitive intelligence and to enable tailored client engagements.
Conclusion — how to use this study in 2026
For executives and technical leaders, the choice is simple: use 2026 to convert uncertainty into optionality. Our market forecast and strategic framework indicate a sustained expansion of the data center BBU market at an annualized pace consistent with double‑digit pressures on capacity and integration needs. Organizations that pair rigorous supplier qualification, modular‑first designs and scenario‑based TCO assessments will avoid costly mid‑life retrofits and preserve agility as chemistries and policies evolve.
PW Consulting’s report is designed to be a short path from market understanding to operational action. To access the full dataset, vendor‑level assessments and procurement templates that underlie these recommendations, visit our report landing page or contact our consulting team for a customized briefing.
For detailed analysis of this topic, please visit the official page: Data Center Battery Backup Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Off-Grid Solar Street Light Market $2.45B (2025) at 7.95% CAGR to $4.19B by 2032
By PW Consulting, 2026-07-13
Off-Grid Solar Street Light Market: Strategic Outlook for 2026 Decision‑Makers
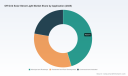
As governments, utilities, municipal planners and private investors recalibrate infrastructure spend for a post‑pandemic, decarbonizing world, off‑grid solar street lighting has moved from a niche resilience play to a mainstream deployment choice. PW Consulting’s latest market study—anchored on 2025 as the base year—captures that transition with a data‑driven growth model and an action‑oriented playbook for 2026 strategic decisions. The global market reached approximately USD 2,450 million in 2025 and, at a compound annual growth rate of 7.95% through our forecast window, is set on a multi‑year expansion trajectory that materially changes procurement, manufacturing and service models for incumbents and new entrants alike.
Off-Grid Solar Street Light Market
Why this report matters now
-
Timing and inflection: 2026 is a crossroads year—technology cost curves, supply‑chain reconfiguration, macro incentive changes and urbanization dynamics converge to create both risks and asymmetric opportunities for players across the value chain.
Off-Grid Solar Street Light Market -
Decision‑quality intelligence: Boards and executive teams need more than directional insight. They require modelled scenarios, supplier scorecards, procurement playbooks and near‑term revenue/ margin sensitivity analysis to prioritize capital allocation in 2026.
Off-Grid Solar Street Light Market -
Competitive advantage: The segment’s market concentration remains moderate, creating room for rapid share shifts via product innovation, financing structures and service differentiation. Our study translates that dynamic into tactical steps for OEMs, integrators and project owners.
What the study delivers (practical, executable content)
-
Robust market sizing and growth modelling: A transparent top‑down and bottom‑up blend that documents historical performance (2020–2025) and projects through 2032, complete with sensitivity runs tied to material and policy scenarios.
-
Demand‑side segmentation framework: Application, procurement style and buyer economics. We map typical decision drivers for municipal, residential/rural and commercial clients and align them to deployment pathways.
-
Supply‑chain and cost curve analysis: Component cost baselines, manufacturing bottlenecks and logistics breakouts that expose where margin pressure will occur under different raw‑material trajectories.
-
Vendor scorecards and benchmarked field performance: Comparative assessments across reliability, up‑time, warranty structure, software/analytics capability and total cost of ownership.
-
Procurement and financing playbooks: Bid templates, O&M contracting models, life‑cycle costing and pay‑for‑performance structures designed to accelerate public tenders and PPPs.
-
Regulatory and incentive scenarios: Practical checklists and decision triggers for navigating changing tax credits, ITC timelines and regional procurement requirements.
-
Commercialization and go‑to‑market templates: Channel stratification, partner archetypes and near‑term product roadmap recommendations to defend margin while expanding addressable markets.
Data‑driven context that will shape near‑term strategy
-
Macro growth: The market’s trajectory—driven by both nascent urban projects and rural electrification initiatives—creates a clear runway for players that can scale production and localize services while preserving margin discipline.
-
Raw material trends: Ongoing adjustments in polysilicon pricing and battery‑component markets materially affect BOM (bill of materials) sensitivity. For example, industry publications indicate polysilicon prices remain under pressure in key manufacturing hubs, and cathode material pricing for LiFePO4 chemistry has seen mid‑cycle adjustments—both dynamics that rewrite cost projections for battery‑heavy product architectures.
-
Policy shifts: Recent changes to residential tax credits in major markets and the timing windows associated with commercial investment tax credits create protocol and timing challenges for project sponsors. Our report codifies these timelines into invocation checklists that protect project economics.
-
Unit economics and price bands: Commercial‑grade off‑grid systems are transacted across a broad unit‑price range depending on specification and battery capacity. Understanding where a particular product sits in that range is essential for correct channel placement and margin targeting.
-
Concentration and competitive dynamics: Market concentration metrics show a fragmented competitive landscape with the top few suppliers accounting for a modest share of the industry—an environment conducive to consolidation, strategic partnerships and selective vertical integration.
Competitive landscape — who to watch
Our competitive analysis focuses on the companies shaping technology, procurement and service expectations in 2026. We evaluate product architecture (integrated all‑in‑one vs. split systems), software and power‑management sophistication, manufacturing footprint and after‑sales capability. Representative players include:
-
Fonroche Lighting America (USA) — notable for resilient all‑in‑one systems and AI‑driven power management tailored to off‑grid applications.
-
SEPCO Solar Electric Power Company (USA) — established in high‑power, remote and municipal systems with decades of experience in commercial off‑grid lighting.
-
Greenshine New Energy (USA) — a commercial‑grade systems manufacturer; recent corporate developments have reshaped its operational footprint.
-
Solar Lighting International (USA) — high‑lumen commercial solutions with a track record in parking and roadway applications.
-
Sunna Design (France) — advanced energy management systems for commercial and industrial off‑grid lighting.
-
EnGoPlanet, Streetleaf, ClearWorld and Solar Street Lights USA (USA) — each focused on different mixes of sustainability credentials, made‑in region attributes and service models.
-
HeiSolar (China) — a major manufacturer with scale advantages in off‑grid intelligent lighting and related components.
We include recent strategic moves and deployments in the public domain—product launches optimized for arterial applications, asset acquisitions that consolidate production, and project deployments in emerging markets—that illustrate the execution playbook incumbents use to defend and grow share. These vignettes are contextualized against our scenario models.
Actionable 90‑day priorities for 2026
-
Lock in procurement hedges: Given volatile input materials, prioritize dual‑sourcing for batteries and PV modules and secure price collars for critical components to protect near‑term margins.
-
Rationalize product portfolio: Weed out SKUs that stretch service economics; emphasize modular all‑in‑one platforms where field serviceability and remote power‑management can stand as value propositions.
-
Invest in data‑led O&M: Telemetry and predictive maintenance pay off quickly in off‑grid systems; build or partner for analytics stacks that reduce uptime risk and warranty leakage.
-
Localize nodes of production and service: Tactical localization reduces logistics cost and shortens installation cycles for public‑sector tenders.
-
Design flexible financing offerings: Incorporate OPEX leasing, performance guarantees and blended public‑private financing to widen the buyer funnel.
-
Monitor M&A and partnership windows: Use the moderate market concentration to pursue tuck‑ins that add service, battery expertise or regional sales coverage.
How PW Consulting preserves the signal and where we intentionally hold back
To support executive decision‑making we surface rigorous modelling, vendor benchmarking and deployment economics. In this introductory briefing we intentionally demonstrate analytical depth while withholding select proprietary segmentation tables, detailed regional and application breakdowns, and full price decks—these are gated within the complete report and proprietary dashboards. This “trailer” approach ensures executives can assess the study’s strategic relevance quickly while directing technical teams to the full dataset for procurement and implementation workstreams.
Next steps — translating insight into 2026 outcomes
-
For executives: convene a cross‑functional review (product, supply chain, finance and sales) around the report’s 90‑day priority roadmap and align funding to the highest ROI initiatives.
-
For procurement heads: request the report’s supplier scorecards and BOM sensitivity tables to inform the next RFP cycle.
-
For investors and M&A teams: use our scenario analyses to stress‑test valuations and identify near‑term consolidation targets.
PW Consulting’s full Off‑Grid Solar Street Light Market study contains the complete datasets, proprietary segmentation, vendor scorecards and downloadable model files that underpin the recommendations summarized here. If your organization is preparing bids, revising product strategy, or vetting investments for 2026, the full report and its interactive dashboards are designed to convert strategic intent into executable plans with measurable ROI.
For detailed analysis of this topic, please visit the official page: Off-Grid Solar Street Light Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Broadband MLCCs Market to Reach USD 3,566.95 Million by 2032 at 7.5% CAGR
By PW Consulting, 2026-07-13
Broadband Multilayer Ceramic Capacitors Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a synthesis of the Broadband Multilayer Ceramic Capacitors (MLCCs) market that is engineered to inform corporate strategy in 2026. This briefing distills actionable implications from our full market study (base year 2025; historical analysis 2020–2025; forecast horizon 2026–2032) while deliberately preserving the granular subsegment matrices reserved for subscribers. The goal: demonstrate analytical depth, surface the strategic inflection points, and highlight where executive attention and investment will generate disproportionate value — without disclosing the proprietary segment-level figures contained in the complete report.
Broadband Multilayer Ceramic Capacitors Market
Market Trajectory and What It Means for 2026 Plans
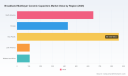
Our topline sizing places the broadband MLCC market on a sustained expansion path, with overall market revenue increasing from approximately USD 1.86 billion in 2023 to about USD 2.15 billion in 2025. Under a 7.5% compound annual growth rate (CAGR) across the 2026–2032 forecast window, the market is projected to exceed USD 3.56 billion by 2032. This growth is not uniform — it is driven by structural demand in high-frequency communications, defense/aerospace requirements for high-reliability components, and rising integration of broadband RF front-ends across consumer and infrastructure applications.
Broadband Multilayer Ceramic Capacitors Market
For executives planning capital allocation in 2026, two takeaways are immediate: first, absolute market growth is robust enough to justify selective capacity and product investments; second, the winners will be those who align product roadmaps and supply chains to high-reliability, high-frequency use cases rather than competing solely on commodity price.
Broadband Multilayer Ceramic Capacitors Market
Competitive Landscape — Positioning and Playbooks
The supply side of broadband MLCCs is concentrated. Our market concentration metrics show that the top three suppliers capture a substantial majority of market share, and the top five account for an even larger portion of revenue. That concentration shapes bargaining power, distribution dynamics, and partnership opportunities in 2026.
- Passive Plus Inc. — Known for a dedicated broadband MLCC series spanning ultra-miniature to mid-size cases and frequency coverage into the multi-gigahertz band. Their capability to offer drop-in replacements and a focused product line makes them an attractive partner for OEMs seeking quick time-to-market with minimal redesign.
- KYOCERA AVX — A technology leader on ultra-broadband RF capacitors, with recent product line extensions that increase voltage ratings and broaden library options for optical communications and RF front ends. Their scale and R&D cadence position them as a strategic supplier for systems integrators and tier-1 infrastructure vendors.
- Dalian Dalicap Technology — A regional specialist emphasizing low insertion loss and high-frequency MLCCs. Their cost and production footprint provide an alternative supply route for firms managing regional content and lead-time risk.
- Johanson Technology — High-Q MLCC offerings geared to RF and microwave markets; their focus on low ESR/low loss parts serves demanding wireless and high-frequency applications where performance premiums are accepted.
- Presidio Components — Specializes in custom and patented broadband DC-blocking solutions for RF, microwave, space, and military markets; a natural partner for defense primes and satellite subsystem OEMs that require bespoke, high-reliability components.
Recent corporate moves underscore competitive dynamics relevant to tactical choices in 2026. Notably, KYOCERA AVX extended its ultra-broadband series early in 2026 to include higher-voltage, smaller-form options targeted at optical and RF front-end customers; Passive Plus amplified market visibility with a presence at IMS Boston in mid-2026. These activities reflect a market where product breadth, qualification velocity, and trade-show / technical engagement continue to differentiate suppliers.
Supply-Chain and Cost Dynamics that Will Shape 2026 Decisions
Three non-cyclical dynamics dominate near-term supplier economics and procurement strategy:
- Raw-material pressure: Barium titanate, the primary dielectric for MLCCs including broadband variants, registered a market value approaching USD 1.87 billion in 2025. Continued electronics demand and specialized dielectric formulations are exerting upward pressure on B2B procurement costs.
- Price re-basing: Major component manufacturers announced markup actions in 2026 for high-end MLCCs—reflecting a repricing trend tied to material, capacity, and substrate constraints. Buyers should assume a new price floor for premium RF-capable parts and incorporate that into 2026 cost models.
- Lead-time elongation and capacity inertia: Delivery windows for high-voltage and high-capacitance MLCCs expanded significantly in early 2026, in some cases extending to ~20 weeks. Concurrently, regulatory and permitting friction has delayed greenfield capacity additions, with new facilities forecast not to materially relieve constraints until late 2026 or beyond.
These dynamics mean procurement strategies in 2026 must balance near-term security of supply with long-term cost discipline. Tactical levers include early long-lead purchasing, strategic buffering of critical SKUs, qualification of dual suppliers across geographies, and negotiated tiered pricing aligned to volume commitments.
Where Value is Being Created — Application and Technology Themes
Three application vectors are creating the majority of incremental broadband MLCC demand:
- Network infrastructure and high-bandwidth communications — as network operators and optical system vendors push toward higher frequencies and broader bandwidths, demand for capacitors that preserve signal integrity increases.
- Defense, aerospace, and space systems — mission-critical reliability at high frequencies commands premium pricing and longer qualification cycles; suppliers with space/defense heritage are positioned to capture this demand.
- Automotive and industrial electrification — the proliferation of radar, connectivity modules, and power-dense electronics in mobility and automation introduces growing volumes of broadband-capable MLCCs, though procurement in these markets is often price and qualification sensitive.
For product strategy in 2026, firms should prioritize high-frequency performance, thermal and voltage robustness, and electromagnetic consistency across frequency bands. Investments in qualification labs and accelerated reliability testing will reduce time-to-market friction for premium applications.
Practical Contents of the Full PW Consulting Report
The full study delivers a practical suite of deliverables designed for immediate operationalization by product, procurement, and corporate development teams. Key inclusions are:
- Top-down and bottom-up market sizing with year-by-year revenue estimates (historical 2020–2025 and forecast 2026–2032).
- Scenario-based forecasts driven by demand shocks, price normalization, and capacity ramp timelines.
- Qualitative and quantitative segmentation across types, applications, and regions (note: detailed subsegment tables and supplier-level revenue splits are available in the paid report).
- Supplier benchmarking matrix: technology capability, form-factor breadth, qualification timelines, and supply-risk scoring.
- Supply-chain risk analysis: raw material exposure, lead-time mapping, and mitigation playbooks.
- Commercial guidance: pricing negotiation frameworks, go-to-market templates for partnership-led growth, and M&A targets guided by strategic fit and technology overlap.
- Appendices with primary interview excerpts, test-lab benchmarking protocols, and a repository of OEM qualification requirements by application vertical.
Strategic Imperatives for 2026
From the intersection of market trajectory, supplier concentration, and supply-chain constraints, PW Consulting derives five strategic imperatives for firms with exposure to broadband MLCCs in 2026:
- Prioritize supplier qualification for premium MLCCs. Given elongated lead times and price re-basing, early technical qualification and strategic supplier commitments are essential to secure production continuity for high-value programs.
- Differentiate via application-tailored roadmaps. Commoditization risk is high in lower-performance MLCCs; conversely, systems that demand low ESR, low insertion loss, and wideband stability will continue to command margins. Align R&D to those tolerances.
- Hedge raw-material exposure. Negotiate multi-year contracts or explore material substitution pathways where feasible to mitigate barium titanate-driven cost volatility.
- Build scenario-based procurement playbooks. Incorporate a tiered approach combining buffer stocks, alternate suppliers, and contractual price bands to manage both price and availability risk.
- Scan the M&A and alliance landscape. Given the concentration of the market and the strategic value of specialty MLCC IP, consider bolt-on acquisitions or minority investments to accelerate access to qualified parts and reduce time-to-certification for key programs.
Final Observations — Where to Focus in Q1–Q4 2026
2026 will be a year of execution rather than discovery. The market’s growth path is clear at the macro level — the challenge for executives is to convert macro tailwinds into defensible revenue and margin expansion. Tactically, prioritize supplier qualification, secure critical SKUs for launch windows, and treat raw-material contracts as strategic assets. On the commercial front, focus on bundling component performance claims with system-level design wins to capture the premium available in high-frequency applications.
This briefing is designed to help you set priorities and frame board-level discussions. For the complete segment-level analytics, supplier revenue breakdowns, and executable procurement templates — including the granular matrices and appendices used to derive the recommendations above — please consult the full PW Consulting Broadband MLCC Market Report. The full report contains the proprietary intelligence and data models necessary to translate these high-level imperatives into operational plans, supplier scorecards, and investment case decks for 2026.
For detailed analysis of this topic, please visit the official page: Broadband Multilayer Ceramic Capacitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cross-Domain E/E Market to Reach USD 24,835M by 2032 (16.55% CAGR)
By PW Consulting, 2026-07-13
Automotive Cross-Domain E/E Architecture Market — Strategic Briefing for 2026 Decision-Makers
As vehicles evolve from distributed electronic control units to software-defined, compute-centric platforms, the cross-domain Electrical/Electronic (E/E) architecture becomes the strategic fulcrum for OEMs, Tier‑1 suppliers, semiconductor vendors and software houses. PW Consulting’s new Automotive Cross Domain E/E Architecture Market study (base year 2025) synthesizes primary research, supply‑chain modeling and scenario analysis to translate this technical transition into action‑able commercial choices for 2026.
Automotive Cross Domain E E Architecture Market
Why this research matters for 2026
- Macro momentum: The market is tracking high‑teens compound annual growth through the forecast window (2026–2032), reflecting accelerated adoption of zonal and centralized architectures, consolidation of cross‑domain compute, and rapid software monetization opportunities.
- Decision timing: 2026 is the inflection year for many program architectures coming out of concept into production intent. Procurement windows, ECU consolidation roadmaps and software platform lock‑ins will be determined this year; a missed architectural decision can lock a program for 5–7 years.
- Regulatory and safety constraints: Vehicle cybersecurity and lifecycle software update requirements (UNECE WP.29 R155/R156 and ISO/SAE 21434) are no longer theoretical risks — they are procurement prerequisites. Compliance choices will materially affect supplier selection and total cost of ownership (TCO).
- Concentration and leverage: Industry concentration is moderate — the top three suppliers control a meaningful share of the market, and the top five an even larger portion — creating bargaining dynamics that buyers and investors must anticipate when structuring contracts or evaluating M&A targets.
Market trajectory in brief
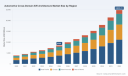
Our consolidated market model (Million USD, 2020–2032) shows a clear progression from early consolidation in the 2020s to scaled deployments by the early 2030s. The study uses 2025 as the base year and projects market expansion driven by hardware consolidation, higher‑value software stacks and recurring revenue for OTA and feature upgrades. With a multi‑year CAGR in the mid‑teens, enterprises should plan for rapid supplier selection cycles and capital allocation to software and compute hardware that can support evolving cross‑domain workloads.
Automotive Cross Domain E E Architecture Market
What’s inside the report — practical deliverables
- Executive synthesis: One‑page investment thesis and a 3‑axis decision matrix for OEMs to evaluate “zone vs domain vs centralized” strategies by vehicle segment and program cadence.
- Market sizing & dynamics: Bottom‑up TAM and SAM models, reconciled with supplier shipment data and OEM program roadmaps. (Note: granular regional, component and vehicle‑type splits are included in the report body and data tables — this briefing intentionally omits those line items to preserve the study’s value.)
- Scenario analysis: Three validated scenarios (Consolidation, Hybrid Acceleration, and Software‑First) with sensitivity testing against semiconductor supply risk, regulatory tightening and OTA monetization uptake.
- Competitive landscaping: Detailed supplier profiles, capability heatmaps, go‑to‑market archetypes and a CRx analysis to highlight concentration risks and partnership leverage points.
- Technology & integration playbooks: Practical roadmaps for compute placement, zonal I/O architectures, service orchestration layers, middleware selection and secure update pipelines aligned with UNECE and ISO/SAE standards.
- Commercial frameworks: Contract templates, supplier scorecards, reference TCO models, and a negotiation checklist for platform & HPC procurements that reflect real program timelines.
- M&A & corporate strategy guidance: Valuation drivers for software platforms, integration risk checklists, IP due diligence templates and post‑merger integration milestones focused on cross‑domain capabilities.
- Risk & compliance toolkit: Cybersecurity maturity scoring, functional safety alignment, and an implementation checklist for CSMS (R155) and software update management (R156) readiness.
Methodology and evidence base
- Primary research: Structured interviews with OEM architecture leads, Tier‑1 program managers, semiconductor OEMs and system integrators across major automotive markets.
- Supply‑side modeling: Bill‑of‑materials and program cadence models built from supplier data and production ramp timelines.
- Technical validation: Architecture walk‑throughs and software stack assessments informed by lab demos and technology cars from Tier‑1s and silicon suppliers.
- Regulatory alignment: Cross‑checking with UNECE WP.29 and ISO/SAE 21434 obligations to ensure practical compliance pathways are embedded in the recommendations.
Competitive landscape — what incumbents and challengers are doing
The cross‑domain E/E architecture race is characterized by incumbents leveraging scale in hardware and system integration, while software‑centric challengers push platform modularity. Our report includes independent profiles of leading players, with strengths and strategic plays summarized below:
Automotive Cross Domain E E Architecture Market
- Robert Bosch GmbH (Germany) — A systems integrator with deep experience in cross‑domain vehicle computers and zone‑oriented E/E architectures. Bosch’s approach emphasizes consolidation across powertrain, chassis, ADAS and infotainment into high‑performance computing fabrics.
- Continental AG (Germany) — Active in server‑based E/E architectures with zone control units (ZCUs) and high‑performance computers. Recent implementations demonstrate integrated cockpit and vehicle functions in technology vehicles, and the company has moved toward series introductions in multiple regions.
- Aptiv PLC (Ireland) — Promoting a Smart Vehicle Architecture that separates I/O from compute via zone controllers. Aptiv is advancing cross‑domain software infrastructure with cloud‑native platform announcements that target software‑defined vehicle use cases.
- ZF Friedrichshafen AG (Germany) — Focused on high‑performance domain controllers and zonal solutions that integrate vehicle motion, chassis and safety functions, positioning itself as a motion and safety systems integrator for compute‑centric platforms.
- DENSO Corporation (Japan) — Pursuing domain and zonal controller offerings as part of a broader vehicle electronics portfolio, leveraging tight OEM relationships in electrification and thermal management to extend system-level value.
- Valeo SE (France) — Concentrating on electrification and ADAS integration components that enable cross‑domain functions, with a particular focus on sensor fusion and domain‑level orchestration.
- Magna International Inc. (Canada) — Delivering electronics and systems for E/E transitions, with an emphasis on scalable power and control solutions for evolving vehicle architectures.
- NXP Semiconductors (Netherlands) — Providing processors and SoCs tuned for zonal and cross‑domain compute, enabling deterministic, real‑time cross‑domain functions in automotive environments.
- Infineon Technologies AG (Germany) — Supplying microcontrollers and power semiconductors that underpin zonal controller platforms and cross‑domain compute nodes, with an emphasis on functional safety and power efficiency.
Recent catalytic developments (select examples)
- Continental implemented a cross‑domain High‑Performance Computer in a technology vehicle, showcasing integrated cockpit and vehicle functions — signaling readiness for series architectures.
- Continental also announced series introductions of zone control units for several OEM programs, reflecting a transition from demonstration to production intent.
- Aptiv highlighted a cloud‑native LINC software platform positioned as cross‑domain infrastructure for software‑defined vehicles, underscoring software‑first supplier strategies.
Strategic implications and recommended actions for 2026
- Treat architecture decisions as strategic platform bets: Establish cross‑functional governance (procurement, architecture, cybersecurity, legal) to evaluate platform lock‑in and migration paths before final vendor selection.
- Negotiate for modularity and IP rights: Insist on defined interfaces, partitioned software stacks and access rights to enable future portability and multi‑supplier strategies.
- Embed regulatory compliance in procurement KPIs: Supplier selection must include validated CSMS processes, secure update capabilities and demonstrable ISO/SAE 21434 alignment.
- Prioritize software monetization and OTA readiness: Build commercial models that capture recurring revenue while balancing customer experience and cyber risk exposure.
- Plan for concentration risk: With the top suppliers holding a significant market share, buyers should design multi‑tier sourcing strategies and consider strategic partnerships or minority investments to secure capability access.
- Design TCO over the program lifecycle: Capital costs are a fraction of the lifetime cost; incorporate software maintenance, cybersecurity, OTA operations and end‑of‑life support into investment cases.
How to use this study in your 2026 planning cycle
- Shortlist vendors using our supplier scorecards and run two fast‑track technical audits aligned with your program timelines.
- Use the scenario models to stress‑test business cases under semiconductor shortage, stricter cybersecurity regulation, and higher OTA penetration.
- Adopt the integration playbook for your next program design freeze to reduce harness complexity and accelerate validation cycles.
- Leverage the M&A and IP due diligence modules if you’re evaluating buy‑side moves to close capability gaps quickly.
Final note — what you’ll gain and where to find the details
PW Consulting’s Automotive Cross Domain E/E Architecture Market study converts technical complexity into boardroom decisions. It combines market sizing, supplier intelligence, regulatory risk mapping and practical implementation tools designed for executives who must commit budgets and define program architectures in 2026. This briefing highlights the study’s strategic value while reserving the granular regional, component and vehicle‑type splits for the full report and downloadable datasets.
For program‑level templates, supplier scorecards, the complete dataset and executable playbooks, access the full report on our website and schedule a briefing with our lead analysts to align the findings with your 2026 roadmap.
For detailed analysis of this topic, please visit the official page: Automotive Cross Domain E E Architecture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Intelligent Control Market to Reach USD 257.9B by 2032 at 8.52% CAGR
By PW Consulting, 2026-07-13
Intelligent Control Market 2026: Strategic Imperatives for Executive Decision-Making
As PW Consulting’s Chief Industry Analyst, I present a directional brief on the Intelligent Control Market designed to orient senior executives making capital, technology and M&A decisions in 2026. This market is no longer a niche engineering domain: it sits at the confluence of industrial digitalization, energy transition, and resilience planning. Our full market research provides the detailed, operational intelligence teams need—this introduction surfaces the strategic implications, demonstrates the analytic depth behind our conclusions, and intentionally withholds granular segment-level figures to preserve the value of the complete study.
Intelligent Control Market
Market trajectory: scale, pace and strategic timing
From a global perspective, the intelligent control market has moved from a mature, steadily expanding industry into a phase of accelerated adoption. Measured on our 2025 base year, the global market grew from approximately USD 105.0 billion in 2020 to USD 145.5 billion in 2025. Our forecast projects continued expansion as the sector internalizes advanced analytics, digital twins and AI-enabled control strategies—reaching an estimated USD 155.8 billion in 2026 and extending toward the late-decade horizon with compound annual growth of roughly 8.5% across the 2026–2032 forecast window, culminating in a market size in the mid-hundreds of billions by 2032.
Intelligent Control Market
These macro dynamics matter for corporate strategy. A sustained CAGR near 8.5% implies that selective investments in intelligent control systems will yield outsized operational leverage over a typical five- to seven-year planning cycle. The key question for 2026 is not whether to adopt intelligent control capabilities, but how to sequence investments across brownfield modernization, greenfield design, and digital-native operations to convert technology adoption into measurable margin and resiliency gains.
Intelligent Control Market
What the market structure means for buyers and investors
The competitive landscape is characterized by established industrial automation majors and a diverse set of specialist vendors. The market shows moderate concentration — the top three global vendors control a significant minority share, while the top five collectively hold just over half of the market. That structure generates important strategic implications: leading vendors provide scale, integration depth and broad R&D pipelines, while smaller specialists offer rapid innovation and sector-specific expertise. Savvy buyers must orchestrate multi-vendor strategies that combine platform stability with best-of-breed innovations.
For investors, this fragmentation suggests different risk-reward profiles. Platform leaders offer predictable revenue streams and cross-selling potential into services and software; niche vendors can produce high growth but require careful diligence on customer concentration, defensible IP and integration pathways.
Vendor competitive dynamics: leaders, differentiators and near-term moves
-
Siemens AG (Munich, Germany) — Siemens continues to anchor its value proposition on model predictive control (MPC) and digital twin-enabled process optimization. Recent recognition of leadership in MPC underscores the sustained R&D momentum and brand advantage it brings to process industries seeking predictive plant optimization.
-
ABB Ltd (Zurich, Switzerland) — ABB emphasizes platform-level intelligent automation with AI-enhanced distributed control capabilities. Their strength is systems integration across electrification and automation stacks, a key factor for energy- and grid-interfacing deployments.
-
Rockwell Automation Inc. (Milwaukee, USA) — Rockwell’s ControlLogix line and recent product introductions position it as the vendor of choice for manufacturers moving toward unified control architectures that blend OT robustness with IT-style manageability.
-
Schneider Electric SE, Emerson, Honeywell, Mitsubishi Electric, Yokogawa and specialists such as Intelligent Control Systems — Each of these firms brings differentiated strengths: energy management platforms, process optimization suites, cyber-hardened controllers, motion synchronization, and domain-specific economizers. The competitive edge increasingly hinges on bundled services, cloud/edge orchestration, and cybersecurity capabilities.
Recent vendor activity underscores this orientation. In 2025, product launches and innovation recognitions—such as a high-profile MPC award and new controller introductions—highlight vendor strategies that combine enhanced functionality with cybersecurity and motion/edge processing advances. These moves accelerate buyer considerations around upgrade cycles and integration sequencing in 2026.
Regulatory and standards context: constraints or catalysts?
Regulatory frameworks and technical standards are central to practical adoption. Industry-accepted standards such as the ISA/IEC 62443 series for industrial cybersecurity, IEC 61131 for programmable controllers, and safety standards like ISO 13849 / IEC 62061 shape procurement specifications, vendor selection and compliance budgets. In 2026, executives should factor these standards into total cost of ownership (TCO) calculations and risk assessments—noncompliance is not merely a technical issue but an operational and reputational one.
Technology stack and the computational bottleneck
Intelligent control systems increasingly rely on real-time analytics, physics-informed models and digital twin simulations. That reliance elevates the computational profile of deployments; edge-cloud hybrid architectures have become the standard approach to manage latency, resiliency and data sovereignty trade-offs. For decision-makers, this means evaluating platform partners not only on control algorithm performance but on their edge computing roadmap, data management architecture, and capabilities for orchestrating digital twins in production environments.
What our full report provides—practical, transaction-ready insight
The full PW Consulting Intelligent Control Market report is designed for executives and program leads who must move from strategy to execution in 2026. Key components include:
- Strategic frameworks — Investment prioritization matrices tuned to corporate goals (cost reduction, throughput, emissions, resilience), with scenario-based decision trees for greenfield vs. brownfield pathways.
- Vendor evaluation toolkit — Structured scorecards that combine technical, commercial and organizational criteria (including cybersecurity maturity and service economics) to compare major platforms and specialists.
- Implementation playbooks — Stepwise guidance for pilot selection, data readiness, integration sequencing, and change management to convert pilots into production at scale.
- TCO and ROI models — Configurable financial templates that capture capital, integration, lifecycle maintenance, software subscriptions and potential operational upsides—calibrated to reflect current market pricing dynamics.
- Risk register and mitigation controls — Practical mitigations for cybersecurity, safety compliance, and supply-chain disruption that can be embedded into procurement contracts and SLAs.
- Market and M&A intelligence — Profiles of incumbent leaders and high-potential challengers, M&A activity signals, and technology pockets that merit bolt-on investment or partnership for rapid capability scaling.
We intentionally keep sensitive sub-segment figures and full regional/application splits within the paid report—this preserves the actionable value for subscribers and supports confidential use in board-level strategic plans.
For executives: five actionable 90-day steps
- Conduct a rapid capability gap assessment that maps current control assets to desired outcomes (efficiency, emissions, uptime). Use lightweight TCO inputs to prioritize two pilot sites.
- Define a multi-vendor integration strategy that preserves choice for best-of-breed analytics and retains platform stability for core process control—stipulate cybersecurity conformance to ISA/IEC 62443 in RFPs.
- Lock in edge-cloud architecture principles that balance latency, resilience and data governance—evaluate partners on demonstrated digital twin orchestration capabilities.
- Adjust procurement vehicle to support outcomes —favor performance-linked commercial models for software and services where possible to align vendor incentives with operational KPIs.
- Establish an M&A scout list focused on AI-enabled control algorithms, domain-specific controllers, and specialists with defensible IP or customer anchors for rapid capability infusion.
How PW Consulting’s research supports your 2026 roadmap
Our market research synthesizes longitudinal market sizing, vendor benchmarking, technical deep-dives and implementation playbooks into a single deliverable tailored for decision-makers. The report’s forecasts—starting from a 2025 base year—give buyers and investors a defensible planning envelope for 2026 budgeting cycles and beyond. We combine quantitative projections with qualitative insights that explain why certain technologies drive more value in specific industrial contexts, and we provide the procurement, legal and operational templates that turn strategy into executed programs.
If your executive team is preparing capital allocation, a transformation roadmap, or an acquisition thesis for intelligent control capabilities in 2026, PW Consulting’s full report is the operational toolset you will use to align board-level ambition with shop-floor execution. The document contains the granular segmentation, regional and application-level analytics, and vendor scorecard data that underpin the high-level guidance presented here—information intentionally withheld in this preview to protect the report’s proprietary value.
Next steps
This briefing is intended to catalyze immediate action. For teams that require a tailored executive briefing, scenario modeling, or vendor diligence support aligned to the 2026 planning horizon, PW Consulting offers advisory engagements that leverage the full Intelligent Control Market dataset and implementation playbooks. Contact our practice leads to schedule a strategy session and access the complete report with all regional and application-level detail.
For detailed analysis of this topic, please visit the official page: Intelligent Control Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Closed Caption Services to Reach USD 550M by 2025, 8.2% CAGR Forecast
By PW Consulting, 2026-07-13
Closed Caption Services Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As organizations plan budgets, technology roadmaps, and compliance programs for 2026, the closed caption services market has moved from niche accessibility function to a strategic layer touching content distribution, audience engagement, and regulatory risk management. PW Consulting’s latest market study (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes quantitative market sizing with operational playbooks and vendor intelligence to guide executive decisions in the year ahead. This article previews the report’s strategic value while withholding proprietary segment-level detail — a deliberate “trailer” to demonstrate depth and drive readers to the full research for complete datasets and models.
Closed Caption Services Market
Macro view: a steady, commercializing market
Demand for closed captioning is no longer driven solely by compliance. Between 2023 and 2025, the total market expanded from roughly USD 470 million to USD 550 million, and our forecast anticipates continued growth at an 8.2% compound annual growth rate across the 2026–2032 horizon. That trajectory implies meaningful scale: by the end of the forecast window the market approaches the USD 1‑billion mark, driven by a mix of automated and human-mediated services, rising live-streaming volumes, and broader adoption across corporate and public sectors.
Closed Caption Services Market
- Growth drivers: regulatory pressure, expanding streaming and broadcast inventories, accessibility commitments from education and enterprise buyers, and improved economics for AI-assisted workflows.
- Operational headwinds: higher cloud and data‑center energy costs, labor availability for trained captioners, and the complexity of live captioning at scale.
- Market structure: relatively fragmented — the top three and top five vendors account for modest shares of overall revenue — creating differentiated opportunities for focused differentiation and regional consolidation.
Why this matters for 2026 decision-makers
Several dynamics converge in 2026 that elevate captions from a compliance checkbox to a strategic lever. Executives who treat captioning as a procurement line item risk missing upside in engagement and brand safety, and underestimating regulatory and infrastructure costs.
Closed Caption Services Market
- Regulatory inflection: US and international rulemaking and enforcement cycles are accelerating. A notable compliance milestone is the requirement for “readily accessible” closed caption display settings on consumer devices and multichannel video programming distributors (MVPDs) — with compliance timelines that demand action plans now. Organizations must reconcile product, firmware, and UX roadmaps with captioning policy to avoid late-stage remediation costs.
- Cost of delivery: cloud-hosted workflows and real-time processing are sensitive to data-center energy price volatility. With projected increases in data-center energy demand and rising electricity intensity, cloud-based captioning providers and their customers should re-evaluate cost models and contract terms to protect margins.
- Labor and capability: despite automation advances, high-quality captioning — especially for live events, complex terminology, or regulated broadcasts — continues to require skilled human captioners. Workforce supply projections indicate tight replacement and recruitment dynamics for roles such as court reporters and simultaneous captioners.
- Competitive differentiation: content owners can translate accessibility into measurable engagement gains — improved searchability, higher watch-time for videos with captions, and better ad monetization outcomes for indexed content.
What the PW Consulting report delivers (practical components)
Our research is designed as an operational brief for teams charged with procurement, engineering, compliance, and content strategy. Key deliverables include:
- Market sizing and validated forecast model (2026–2032) with scenario variants tied to regulatory outcomes and automation adoption curves.
- Vendor scorecards and capability matrices covering accuracy, turnaround, live capability, language coverage, accessibility compliance, SLA structures, and typical contract constructs.
- Pricing benchmarking and total cost of ownership (TCO) templates that account for cloud processing, storage, and incremental energy exposure.
- Regulatory tracker with timelines, jurisdictional impacts, and risk heat maps for device manufacturers, MVPDs, broadcasters, and OTT platforms.
- Implementation playbooks for enterprise buyers: pilot design, quality thresholds, hybrid automation/human routing logic, and change management for caption display settings and UX.
- Scenario-based ROI calculators that quantify revenue/engagement upside from captions, cost trade-offs between automation and human workflows, and break-even timelines for investments in in‑house vs. outsourced capabilities.
Competitive landscape: vendor archetypes and strategic implications
The market combines legacy broadcast specialists, human‑centric service providers, and fast-moving AI-enabled entrants. Understanding vendor archetypes is critical when crafting sourcing strategies — particularly where live captioning, regulated broadcast, or multilingual subtitling are priorities.
- Premium human-first specialists: Providers that emphasize human quality guarantees and tight compliance are natural partners for broadcasters, educational institutions, and regulated corporate communications. Their value proposition centers on accuracy SLA, editorial oversight, and robust QC workflows.
- Automated/AI-native operators: These vendors prioritize low latency, scalability, and integrated transcription/translation pipelines. They are attractive to high-volume digital media platforms and corporates seeking rapid, cost-effective captioning, particularly for archived and user-generated content.
- Hybrid integrators: Vendors that combine AI engines with human post-editing can achieve a balance of cost and quality, useful for use cases that can tolerate small accuracy trade-offs but still require reliable compliance and branding consistency.
- Nonprofit and public-service actors: Organizations with mission-driven mandates and deep public-sector experience offer specialized services for government, education, and accessibility-first deployments.
Representative firms in the landscape illustrate these archetypes: premium human-centric vendors focused on broadcast accuracy and accessibility; AI-enabled platforms driving scale for live and recorded captioning; long-established captioning houses with national news and program expertise; and nonprofit entities anchoring public-service captioning. Each brings distinct go-to-market approaches, contract norms, and target buyer segments — covered in detailed vendor profiles and comparison matrices in the full report.
Regulatory and market shocks to factor into 2026 plans
Our market scenarios reflect recent and near-term events that will materially influence strategy:
- Device/display accessibility rulemaking: Requirements around caption settings’ proximity, discoverability, previewability, and persistence force product teams to integrate caption UX as a first-order requirement — not an afterthought.
- Policy shifts in network regulation: Judicial and legislative activity affecting net neutrality and related broadband policies can reshape distribution economics for OTT players and, indirectly, caption delivery costs and prioritization.
- Infrastructure cost pressures: Rapid increases in data-center energy demand add a layer of operational risk for cloud-dependent captioning pipelines; clients and vendors should consider hybrid architectures and long-term capacity agreements to mitigate price shocks.
- Vendor innovation and product launches: New in-room, personal-device captioning solutions and real-time translation services demonstrate how captioning can be embedded into live events and audience workflows — opening upsell opportunities for AV integrators and platform partners.
Actionable playbook for 2026
PW Consulting recommends a short set of priority moves for executives preparing for 2026:
- Map regulatory exposure: perform a targeted compliance audit focused on device-level UX and distribution channels; create an action plan to meet “readily accessible” display settings by the relevant compliance deadlines.
- Re-run TCO with energy and latency stress tests: stress pricing models under elevated cloud energy costs and identify cost‑efficient routing for live vs. archived captioning.
- Pilot hybrid workflows: design 60–90 day pilots that evaluate automated captioning with human post‑edit on representative content types, measuring accuracy, turnaround, and downstream engagement uplift.
- Negotiate vendor SLAs with operationally relevant metrics: include uptime for live streams, time‑to‑correction, accuracy measurement methods, and penalties/incentives tied to measurable accessibility outcomes.
- Invest in caption-first UX: product and design teams should embed discoverability and personalization of captions (size, language, placement) into product backlogs to drive user satisfaction and regulatory alignment.
Why PW Consulting’s full report is strategic for 2026
This preview highlights why closed captioning deserves board-level attention in 2026. The full PW Consulting report pairs validated market numbers and scenario-models with operational artifacts — scorecards, contract templates, implementation checklists, and ROI models — that allow leaders to convert the market’s growth and regulatory signals into defensible investment choices. Given the market’s fragmentation and the diversity of vendor approaches, the decision advantage in 2026 will accrue to organizations that combine regulatory foresight, technical due diligence, and pragmatic procurement frameworks.
To access the proprietary segmentation, vendor scoring, and the downloadable forecast model that underpin these strategic recommendations, please refer to the complete Closed Caption Services Market report on PW Consulting’s publication page.
For detailed analysis of this topic, please visit the official page: Closed Caption Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


