



Category: IT & Electronics
PW Consulting: TV ODM Market 3.8% CAGR to 2032; Asia‑Pacific leads at USD 19,084M
By PW Consulting, 2026-07-13
TV ODM Market 2026: Strategic Preview for Boardrooms and Procurement Leaders
Executive summary
As companies prepare budgets and strategic plans for 2026, the TV ODM market presents a mix of steady growth, concentrated supplier power, and episodic cost shocks. Our PW Consulting market research—anchored to a 2025 base year and a 2026–2032 forecast horizon—projects a compound annual growth rate (CAGR) of 3.8% through the forecast window. The global TV ODM market reached roughly USD 42,500 Million in 2025 and is expected to continue expanding under modest, demand-driven dynamics and periodic supply-side pressures.
Tv Odm Market
This short briefing is designed as a “trailer” of the full study: it demonstrates the analytical depth and the practical value delivered to decision-makers, while deliberately withholding the granular segment tables and regional splits that sit inside the full report. If you need those detailed breakdowns, supplier scorecards, and downloadable models, the full release provides them.
Tv Odm Market
Why this market matters for 2026 decisions
-
Capital allocation: With market growth modest but persistent, executives must choose between volume-driven investments (capacity and scale) and margin-focused plays (higher-value displays and feature-rich smart TVs). The full report maps these trade-offs across multiple scenarios so CFOs can stress-test capex decisions against panel-price volatility and potential trade-policy headwinds.
Tv Odm Market -
Supply resilience: TV panels and associated ICs remain the dominant cost drivers in TV manufacturing; panels can represent roughly two-fifths or more of BOM cost. Short-term price spikes for large-size panels and memory components materially alter supplier economics and contract terms. Procurement teams need clear playbooks for hedging and for negotiating pass-through clauses—tools that are included in our full study.
-
Competitive positioning: Market concentration is material—leading OEM/ODM groups capture a substantial share of shipments—which affects negotiation leverage, lead times, and the strategic value of single-supplier relationships. The study quantifies concentration dynamics and provides a supplier-prioritization framework for strategic sourcing.
Market trajectory and the near-term drivers
The TV ODM industry is neither in rapid disruption nor in stagnation; it is maturing. Our historical view (2020–2025) and forecast (2026–2032) show a market that absorbs technological transitions—Mini-LED, QLED, OLED and AI-enabled smart stacks—while volumes move with end-market demand and replacement cycles. The steady CAGR of 3.8% disguises meaningful tactical volatility: episodic panel price steps, regional policy shifts, and a push toward higher-margin differentiated SKUs create windows of both risk and opportunity.
Key near-term drivers to watch in 2026 include raw-material and IC cost inflation (we observed early-2026 panel price upticks for larger formats), regulatory moves on trade policy that may affect component flows, and continued capacity expansion among leading ODMs and panel makers. These factors combine to create a market environment where timing and supplier mix can materially affect 2026 P&L outcomes.
What the full report delivers (practical outputs)
-
Scenario-based revenue and cost models calibrated to a 2025 base and extended through 2032—useful for board-level forecasts and sensitivity testing.
-
Supplier heatmaps and a risk-scored OEM/ODM shortlist that translate concentration metrics into procurement action items (RFP priorities, dual-sourcing thresholds, and contingency partners).
-
Contract negotiation playbook including clauses for price pass-through, capacity reservations, and IP protection for white-label and licensed-brand relationships.
-
Capex and capacity overlay: where new or ramped factories change delivery risk by product family and lead time—presented as decision trees rather than headline region shares.
-
M&A and partnership decision frameworks that link synergies to integration complexity and payback under different panel-price regimes.
-
Supply-chain stress tests and recommended inventory strategies for different risk appetites—from “cost-minimal” to “resilience-first”.
Competitive landscape: who matters and why
The TV ODM ecosystem blends pure-play contract manufacturers with major display groups and large EMS houses. Several firms stand out because of scale, geographic footprint, or strategic moves that influence the marketplace in 2026.
-
MOKA (TCL MOKA) — Emerged as a turnkey ODM partner for advanced smart-TV platforms. Its close integration with established supply chains enables rapid go-to-market for licensed brands and supports high-volume launches with integrated software stacks—an attractive proposition for OEMs seeking to outsource both hardware and platform services.
-
AMTC — Focused on international markets, with strategic factory expansions intended to serve North America and global retail channels. Their capacity plays and trade-lane orientation make them a candidate for brands prioritizing logistics efficiency.
-
HKC — A top-tier contract supplier and panel partner with recent greenfield commissioning adding meaningful production capability. For customers needing scale and proven supplier relationships with retailer-facing brands, HKC is a primary option.
-
Express Luck — Rapidly expanding production parks designed to scale ODM shipments; attractive for mid-size brands that need flexible MOQ and swifter ramp profiles.
-
TPV Technology, BOE VT, Foxconn, Innolux, and other tier-one suppliers — These players combine OEM, panel manufacturing, and EMS strengths. Their role varies from full turnkey ODM to component supplier and contract assembly partner. Understanding which role a supplier prefers is critical when negotiating IP, warranty, and after-sales responsibilities.
-
Smaller, highly agile ODMs — They serve niche customers with shorter lead times and extreme SKU flexibility; useful for pilots and test-market launches that might be uneconomic with large-scale suppliers.
Our full report contains strategic profiles and decision matrices for each named player, including governance structures, preferred customer types, and contract negotiation levers. The preview intentionally omits the granular supplier scorecards and capacity tables to preserve the incentive to access the full dataset.
Supply-chain and cost dynamics to model in 2026
-
Panel-cost sensitivity: Display panels are the single largest line item in TV BOMs. Even modest unit-price moves for 65–75 inch panels or memory can swing margins enough to require contract re-pricing or promotional adjustments. The research supplies a panel-price shock model you can plug into your P&L.
-
Tariff and trade risk: Policy conversations in key markets introduce execution risk for cross-border sourcing. We model tariff-tail scenarios and their impact on landed cost, and provide sourcing decision rules that align with different corporate risk tolerances.
-
Concentration and lead-time risk: With a meaningful share of volumes held by a few large suppliers, single-point failures or capacity reallocations can create supply squeezes. The report includes supplier-reallocation playbooks and contingency sourcing pathways.
Strategic actions recommended for 2026
-
Embed scenario planning into procurement cycles: Run at least three scenarios (baseline, panel-price spike, and tariff shock) before committing to multi-year supply contracts or new product launches.
-
Prioritize supplier segmentation by strategic value, not just price: Reserve long-term capacity with 1–2 strategic partners while keeping agile suppliers on shorter, higher-margin projects.
-
Negotiate flexible cost-pass-through mechanisms and capacity reservation terms that protect margins without permanently locking in unfavorable rates.
-
Localize where it reduces trade risk: For brands with exposure to tariff scenarios, selectively shifting assembly or component sourcing closer to end markets can be defensible despite higher fixed costs.
-
Invest in platform and software differentiation: With hardware margins under pressure, owning or licensing smart-TV platforms and user experiences becomes a durable source of differentiation and aftermarket revenue.
How to use this report in your 2026 planning cycle
Boards, CEOs, and procurement leads will find the report most valuable when it is used as an input to three canonical decision processes: capex approval, supplier consolidation/expansion planning, and product portfolio optimization. Each of these processes benefits from the report’s scenario outputs, supplier heatmaps, contract clauses and cost-shock templates.
If your role is supply-chain, use our stress-test tools to validate safety-stock and lead-time assumptions. If your role is corporate development, use the M&A playbooks and valuation sensitivity matrices to test acquisition rationales under different panel-price and demand scenarios.
Conclusion and next step
The TV ODM market in 2026 is an arena of steady growth complicated by episodic cost drivers and a concentrated supplier base. Decisions made in the next 6–12 months—about capex, supplier strategy, and product differentiation—will determine who gains margin and who absorbs cost pressure. Our full market report provides the segment-level breakdowns, supplier scorecards, downloadable models, and negotiation playbooks necessary to translate insight into action. For access to the complete datasets and operational toolkits, please follow the link to the full TV ODM Market release.
For detailed analysis of this topic, please visit the official page: Tv Odm Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
cfDNA Testing Market: Strategic Preview for 2026 — A PW Consulting Executive Trailer
As PW Consulting’s Senior Strategy Advisors and Chief Industry Analysts, we present a focused preview of our comprehensive Cell‑Free DNA (cfDNA) Testing Market study — the analytical foundation executives need to make high‑stakes decisions in 2026. Built on a robust base year of 2025 and a multi‑scenario forecast window through 2032, the study synthesizes clinical, commercial, regulatory and technology vectors that will determine winners and laggards in this fast‑evolving field.
Cfdna Testing Market
Why this study matters now
-
Rapid market expansion: The global cfDNA testing market has moved from a mid‑single‑billion dollar industry in 2020 to a multi‑billion dollar market in 2025, and our forecast through 2032 models continued double‑digit growth (compound annual growth rate of 13.6%). This trajectory is material to product roadmap, capacity planning and financing decisions.
Cfdna Testing Market -
Cross‑sector strategic inflection: cfDNA sits at the intersection of diagnostics, therapeutics (companion diagnostics & MRD), and precision prenatal care. Strategic choices made in 2026 — investments in assays, platform partnerships, and reimbursement strategy — will drive revenues and clinical adoption patterns across the forecast period.
Cfdna Testing Market -
Operational urgency: Clinical lab capacity, specialized labor, NGS throughput and regulatory compliance constraints create near‑term execution risks that can blunt long‑term upside if not addressed now.
Market trajectory at a glance (what the numbers tell you)
-
Historical momentum: The market advanced notably across 2020–2025 as adoption of non‑invasive prenatal testing (NIPT), oncology liquid biopsy, and transplant dd‑cfDNA monitoring accelerated in clinical practice.
-
Base year and outlook: Using 2025 as the analytical pivot, our consolidated market model projects consistent expansion through 2032 under a central scenario that assumes continued clinical validation, incremental reimbursement wins, and steady technology price declines supported by scale.
-
Implication: For corporate planners, the scale of the opportunity—from the 2025 baseline into the 2030s—justifies near‑term investments in platform robustness, regulatory dossiers, and commercial channels, but only if supported by detailed subsegment economics and scenario testing (available in the full report).
Key dynamics shaping strategic choices
-
Technological convergence: Improvements in NGS chemistry, digital PCR, and AI‑driven interpretation (including multi‑modal models for MRD) are shifting value from raw sequencing to analytics and longitudinal data assets. Recent industry activity illustrates this: leading players announced next‑generation whole‑genome assays and AI‑enabled MRD risk stratification in early 2026, indicating a race to differential clinical utility.
-
Clinical adoption vectors: The clinical community is expanding cfDNA use beyond screening into diagnostic, monitoring and treatment‑selection contexts. Adoption cadence is heterogenous by use case — some applications are already standard of care in specialty centers while others remain in clinical validation. This creates staggered commercialization windows that must inform sequencing of product launches and reimbursement efforts.
-
Regulatory & reimbursement environment: Adjustments to clinical guidelines and payer coverage policies have lowered commercial friction for certain dd‑cfDNA applications and prenatal screening pathways. However, payer acceptance for broader oncology screening and some novel prenatal indications remains conditional on real‑world outcomes and cost‑effectiveness evidence.
-
Labor and compliance intensity: High‑skill laboratory labor, CLIA/CAP requirements, and sensitive genomic data handling are persistent cost drivers and operational constraints. Strategic moves toward automation, centralized reference lab partnerships, or CAP/CLIA‑certified network expansion materially change margin profiles.
-
Competitive choreography: The market blends vertically integrated assay developers, platform suppliers, and large lab networks. Commercial dynamics are affected as instrument providers and reagents vendors enable smaller labs, while integrated diagnostics companies and national laboratories leverage scale and payer relationships.
What the PW Consulting report delivers (practical outputs for 2026 action)
-
Validated market sizing and a transparent forecasting model covering 2020–2032 with scenario toggles for adoption, pricing erosion and reimbursement timelines so you can stress‑test investment returns.
-
Commercial playbooks for each major use case — prenatal, oncology (screening and MRD), and transplant — including go‑to‑market sequencing, payor engagement templates, and partner archetypes.
-
Competitive landscape maps and capability heatmaps for technology providers, clinical labs and platform suppliers; actionable supplier shortlists for outsourcing, co‑development and M&A.
-
Regulatory and reimbursement dossier tracker aligned to regional policy changes and clinical guideline schedules that will drive 12–36 month windows for market access.
-
Operational readiness playbook: lab capacity modeling, cost‑per‑test sensitivity analysis, staffing plans and automation investment cases to reduce unit economics pressure.
-
M&A and partnership prioritization: target filters, valuation heuristics and integration risk assessments to inform deal sourcing and negotiation leverage.
Competitive landscape — strategic implications (select profiles)
-
Natera: A multi‑assay player with footprint across prenatal, oncology MRD and transplant monitoring. Strengths include portfolio breadth, longitudinal data assets and recent investments in whole‑genome cfDNA assays and AI‑driven MRD stratification. Strategic risk: balancing capital allocation across distinct business models while defending clinical claims.
-
Guardant Health: Focused oncology liquid biopsy specialist, leveraging strong clinical partnerships and commercialized platforms for tumor profiling and cancer screening. Competitive edge lies in oncology datasets and payer relationships; challenge is expanding beyond core oncology while preserving clinical validity.
-
Illumina & Thermo Fisher: Platform and consumables enablers. Their strategic value to markets is high through scale, instrument footprint and reagent ecosystems. For adopters, alignment with one of these suppliers affects per‑test economics and scale‑up timelines.
-
CareDx and specialized transplant players: Deep domain expertise and clinically validated dd‑cfDNA offerings create stickiness with transplant centers. Reimbursement clarity in certain jurisdictions has accelerated use, although transplant markets are smaller and require targeted commercialization models.
-
BillionToOne and innovative startups: Rapid product expansion in prenatal and liquid biopsy niches is changing the innovation front. These players are potent acquisition targets for larger labs and platform vendors seeking fill‑in capabilities.
-
Large lab networks (Labcorp, Quest) and diversified diagnostics majors (Roche, Myriad): Their advantages are scale, clinical lab networks and payer negotiation power; they often act as both buyers of platform technology and direct competitors in clinical services.
Strategic imperatives for executives in 2026
-
Prioritize clinical evidence generation that maps to payer decision criteria — not all validation studies yield the same commercial benefit. Design trials to directly address clinical utility and economic endpoints for target payers.
-
Lock downstream value: Invest earlier in data architectures and longitudinal repositories to monetize MRD and monitoring applications through subscription or outcomes‑based pricing models.
-
Optimize lab footprint with hybrid models — combine centralized reference centers for complex assays with local rapid‑turnaround hubs for point‑of‑care needs to balance margin and access.
-
Use partnerships offensively: OEM deals with sequencing suppliers, co‑development with academic centers, and commercial alliances with national labs can shortcut market access and scale.
-
Prepare for consolidation: With an expanding opportunity but uneven margins across use cases, targeted M&A will be an efficient route to fill capability gaps (analytics, CLIA capacity, payer contracts).
Outlook & what to watch through 2032
-
Expect accelerating clinical adoption in specific high‑value niches (e.g., MRD and transplant monitoring) and continued evolution of prenatal screening workflows as assays broaden scope and lower cost per actionable result.
-
Technology winners will be those who marry scalable lab operations with proprietary analytics and data assets; instrument suppliers will continue to influence price points and throughput ceilings.
-
Regulatory and reimbursement developments remain the single largest near‑term swing factor. Executives must maintain active payer and policy engagement to de‑risk rollout timelines.
We crafted this executive trailer to demonstrate the strategic depth of the full PW Consulting cfDNA Testing Market study and to show how the analysis supports immediate 2026 decisions — from capital allocation and product prioritization to M&A and commercial operations. For the full dataset (detailed regional and application segmentation, pricing models, vendor scorecards and the complete scenario model for 2026–2032), access the full report and interactive forecast tools on our site.
Contact PW Consulting to schedule a bespoke briefing: we will walk your leadership through the model, stress‑test your hypotheses, and deliver a tailored implementation roadmap that converts the forecast into measurable business outcomes.
For detailed analysis of this topic, please visit the official page: Cfdna Testing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Security MCU Market Set to Grow at 8.2% CAGR to ~USD 8,897M by 2032
By PW Consulting, 2026-07-13
Security Microcontroller (MCU) Market — Strategic Outlook for 2026 Decision-Makers
As organizations re-anchor product roadmaps and procurement strategies for 2026, the security microcontroller (MCU) market is both a growth engine and a point of strategic vulnerability. PW Consulting’s latest Security Microcontroller MCU Market study (base year 2025) shows the global market expanding at a compound annual growth rate (CAGR) of 8.2% across our forecast horizon. From an estimated USD 5,124.5 Million in 2025, the sector is projected to approach the USD 8.9 billion range by 2032. These headline dynamics underline why security MCUs should be elevated from a line‑item technical requirement to a board‑level strategic priority.
Security Microcontroller Mcu Market
Why 2026 Is a Strategic Inflection Point
-
Demand and complexity are rising in parallel. Use cases across automotive, IoT, financial services, consumer electronics and industrial/healthcare are deepening security requirements—from root-of-trust and secure boot to tamper detection and crypto agility. The result is growth that is broad-based across end markets, not confined to a single vertical.
Security Microcontroller Mcu Market -
Supply‑side pressures have become a structural factor. Semiconductor capacity constraints and a renewed focus on advanced-node allocation for AI workloads have pushed lead times and supplier pricing, creating procurement fragility for security MCU roadmaps.
Security Microcontroller Mcu Market -
Regulatory and geopolitical shifts — especially export controls and cross‑border compliance regimes — are introducing sourcing complexity that materially affects vendor selection, qualification cycles and certification timelines.
What This Means for 2026 Corporate Decisions
Executives must treat security MCUs as more than a component purchase. Decisions made in 2026 will determine product differentiation, time-to-market and downstream lifecycle costs for years. At a minimum, leadership teams should be asking:
-
How resilient are our supply agreements against sustained lead‑time inflation and periodic price shocks?
-
Do our product roadmaps require native support for post‑quantum or quantum‑resistant algorithms, and what is the certification pathway to prove compliance?
-
Are our cybersecurity and system‑safety requirements aligned with the specific MCU trust architectures (hardware secure elements, TEEs, or security‑enabled standard MCUs) we plan to deploy?
-
Is our vendor strategy optimized for technical fit, supply security and regulatory exposure?
Market Structure and Competitive Landscape
The market shows a moderate concentration profile: the top three suppliers account for roughly 48.6% of market revenue, while the top five approach the low‑60s percent range. This structure creates a dual strategic dynamic—large vendors offer scale, certification roadmaps and system compatibility, while second‑tier vendors can be agile partners for niche functionality or bespoke cryptography.
Key incumbents we track include established semiconductor houses that blend secure elements, cryptographic acceleration, and industry‑specific MCU families. Their strategies vary from deep platform play (secure elements for payment and identity) to broad MCU roadmaps that balance security, performance and power for embedded applications. Recent market activity highlights both product innovation and ecosystem shifts:
-
Major vendors continue to refresh MCU lines with higher security assurance levels, TrustZone-like isolation, and hardware crypto engines to meet certification requirements.
-
Product launches in early 2026 emphasized SESIP/PSA level certifications and tamper protections targeted at industrial and IoT segments—an indicator that security assurance is moving from “nice to have” to procurement gate.
-
Emerging deployments of post‑quantum implementations in secure microcontrollers signal that early adopters are already fielding quantum‑resilient capabilities. This shifts the upgrade conversation from theoretical to operational.
Recent Industry Disruptors and Their Strategic Implications
-
Product introductions that combine modern MCU cores (e.g., Arm Cortex‑M series) with SESIP/PSA Level 3 capabilities compress the certification burden for OEMs and speed adoption—organizations that pre‑qualify these platforms will win time‑to‑market.
-
Publicized price increases by several leading suppliers in 2026 have materially altered TCO models. Buyers must rework bill‑of‑materials sensitivity models and consider hedging strategies (longer contracts, multi‑sourcing, or design flexibility) to protect margin and schedule.
-
Export control updates and persistent U.S.–China tensions mean that vendor footprint and manufacturing origin are now criteria in supplier selection. For many regulated verticals, provenance and supply‑chain transparency are non‑negotiable.
Practical Contents of the Full Report (Executive‑to‑Operational)
PW Consulting’s full study is designed to be operationally actionable for teams ranging from CISO and CTO to NPI managers and procurement. The report features:
-
Top‑line market sizing and a detailed, scenario‑based forecast through 2032—anchored to 2025 as the base year and aligned with current industry noise factors.
-
Segment growth drivers and adoption curves by architecture type and end‑market (note: detailed split tables are intentionally withheld here to preserve the report’s exclusivity).
-
Vendor profiles and comparative matrices focused on security architecture, certification readiness, roadmap cadence, and supply‑chain exposure.
-
Procurement playbooks and contracting templates that address price volatility, lead‑time guarantees and production ramp scenarios.
-
Technology adoption frameworks—how and when to incorporate post‑quantum readiness, TEE integration, secure element offload, and lifecycle key management into existing product families.
-
Regulatory and compliance checklists aligned to major markets and certification pathways, plus a practical risk scoring system to prioritize mitigation activities.
-
Go‑to‑market and M&A heatmaps that identify partnership and acquisition targets to accelerate capability delivery without prolonged internal development cycles.
Strategic Playbook — Recommendations for 2026
-
Elevate security MCU selection to strategic sourcing: establish multi‑vendor qualification lanes, include provenance clauses, and negotiate indexed pricing tied to commodity and node‑allocation indicators.
-
Adopt modular security architectures: decouple cryptographic functionality via secure elements or pluggable TEEs to enable in‑field algorithm upgrades and extend product lifecycles.
-
Prioritize certification alignment early: embed certification milestones into NPI roadmaps to avoid late‑stage rework and market entry delays.
-
Hedge technology risk with pilot programs for post‑quantum implementations where product lifetime or regulatory exposure justifies early investment.
-
Rebalance supplier portfolios: combine scale suppliers for core high‑volume platforms with specialized partners for differentiated security needs or regional compliance requirements.
Risk Matrix — What Keeps Boards Awake
-
Supply continuity: advanced node allocation and memory shortages may extend lead times and compel design workarounds.
-
Price volatility: supplier price actions in 2026 have shown that BOM assumptions can change rapidly; reforecasting and scenario planning are essential.
-
Regulatory shock: sudden policy shifts or export controls can require last‑minute supplier changes with certification and functional trade‑offs.
-
Technical obsolescence: without upgradeable crypto frameworks, long‑lived products risk being non‑compliant or insecure mid‑lifecycle as threat models evolve.
Why PW Consulting’s Intelligence Matters for 2026
Our study combines quantitative market modeling—anchored to a 2025 base—with qualitative, deal‑level intelligence and vendor due‑diligence. The market’s projected CAGR of 8.2% is more than a growth rate; it reflects shifting security postures across multiple verticals, the industrialization of cryptographic services at the edge, and the maturation of certification ecosystems. The top‑line figures are the starting point—this research translates them into executable actions for procurement, product, and security leadership.
Importantly, this article follows a deliberate “preview” design: we present the strategic narrative and high‑level metrics to establish the market context, while preserving the report’s detailed subsegment matrices, vendor share tables, and transaction playbooks behind the full study. Those granular data assets—critical for contract negotiations, financial planning and detailed product design—are available via the full PW Consulting report.
Next Steps for Executives
-
Schedule a strategy workshop: align procurement, product and security teams around a prioritized MCU action plan with scenario‑based contingencies for cost and supply shocks.
-
Commission a supplier risk audit: map current and alternate MCU sources against certification, pricing elasticity and geopolitical exposure.
-
Pilot quantum‑resilient implementations for products with extended lifecycles or high regulatory risk.
-
Download the full report for the detailed breakdowns, vendor matrices, and templates required to operationalize the recommendations presented here.
For 2026, treating security microcontrollers as a strategic asset — not a commoditized component — will determine winners and laggards across connected devices, financial infrastructure and safety‑critical systems. The PW Consulting report equips leaders with the data, scenario workstreams and vendor intelligence necessary to make those high‑stakes decisions with confidence.
For detailed analysis of this topic, please visit the official page: Security Microcontroller Mcu Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Multiaxial Optical Position Sensor Market Set to Expand at 6.7% CAGR Through 2032
By PW Consulting, 2026-07-13
Multiaxial Optical Position Sensor Market: Strategic Snapshot for 2026 Decisions
Executive teaser
As a concentrated yet dynamic segment within motion sensing and machine perception, the multiaxial optical position sensor market is transitioning from component-driven commoditization toward systems-level differentiation. PW Consulting’s new study — anchored on a 2025 base year and projecting through 2032 — quantifies this transition and translates it into decision-ready implications for executives planning 2026 investments. The market, which grew steadily through 2020–2025 and is forecast to expand at a compound annual growth rate (CAGR) of 6.7% over 2026–2032, is set to move from approximately USD 450 million in 2025 to roughly USD 709 million by 2032. Below we map where strategic value will concentrate and how leaders should act; detailed sub-segment and financial schedules are reserved for the full report to preserve competitive advantage.
Multiaxial Optical Position Sensor Market
Why this matters for 2026 strategic planning
- Acceleration of automation and robotics projects elevates demand for high‑accuracy, multi-axis optical positioning in factory floors and semiconductor fabs.
- Regulatory pressure in automotive safety and environmental monitoring is increasing demand for integrated, certified sensing subsystems rather than standalone components.
- Advances in sensor modalities (CMOS image-based solutions, direct Time‑of‑Flight modules, laser displacement) are shifting value toward sensor fusion and software-defined positioning.
- Supply-side risks — notably constrained access to high‑purity optical materials — create an immediate need for procurement strategy and resilience planning.
What the PW Consulting study delivers (practical components)
Designed as a playbook for corporate strategy teams, the report blends market quantification with executable initiatives. Key deliverables include:
Multiaxial Optical Position Sensor Market
- Transparent market sizing and methodology covering 2020–2025 historicals and a 2026–2032 forecast horizon (CAGR 6.7%).
- Demand-driver analysis across technology, regulation, and application ecosystems, identifying the commercial inflection points most relevant to 2026 decisions.
- Technology roadmaps and R&D prioritization matrices for photodiode variants, CMOS image‑sensor approaches, and dToF/LiDAR derivatives.
- Competitive landscaping and capability matrices profiling incumbent suppliers, emergent specialists, and platform players.
- Supply‑chain risk maps with mitigation options (dual-sourcing scenarios, strategic inventory policies, nearshoring playbooks).
- Commercial playbooks: pricing sensitivity, channel strategy, systems integration offers, and aftermarket service monetization models.
- M&A screening and diligence templates focused on capability fills (e.g., optical IP, signal-processing software, ruggedized packaging) rather than headline market share alone.
- Regulatory scenario planning and compliance checklists for automotive and aerospace certification paths.
Market dynamics at a glance
The market’s momentum is broadly stable and predictable at the macro level: after rising through the early 2020s, the total industry value reached about USD 450 million in 2025. Our base-case projection anticipates expansion to roughly USD 709 million by 2032, reflecting a 6.7% CAGR across the forecast window. That growth is unevenly sourced — driven by capital spending in industrial automation and semiconductor equipment, higher-spec adoption in defense and aerospace, and new integrations into automotive subsystems. Importantly, the industry structure exhibits moderate concentration: the three largest suppliers account for a material share of market value while the top five combine a clear majority, leaving meaningful room for specialized challengers and targeted acquisitions.
Multiaxial Optical Position Sensor Market
Competitive landscape — profiles and strategic signposts
The competitive set spans component suppliers, embedded-systems vendors, and full-solution integrators. Each archetype implies different strategic moves and risks:
- Specialized fiber‑optic and rugged-sensor players: Firms with deep expertise in fiber optic position sensing bring strong value propositions for EMI-immune, harsh-environment use cases. Their path to growth is often vertical: extend into system integration, service contracts, and certificated assemblies for defense and nuclear sectors.
- Industrial sensor platforms: Broad automation suppliers that offer multi-purpose optical sensors can leverage global channels and systems relationships, particularly in factory automation and logistics. Their advantage lies in distribution scale and standards influence.
- Component and semiconductor suppliers: High-precision optoelectronics firms and Si component houses are pushing innovations in dToF and CMOS-based position sensing. Their competitive edge depends on IP, process scale, and the ability to co-design modules with OEMs.
Representative players illustrate these archetypes: a US-based specialist known for fiber-optic absolute sensors, European and Asian industrial sensor houses with broad automation portfolios, global conglomerates offering SMART non‑contact position sensors across airborne and automotive platforms, optoelectronic component leaders advancing dToF capability, and high-precision laser‑based vendors focused on manufacturing metrology. Recent market activity — including product launches and dToF showcases — signals an intensifying technology race and increased interest from systems OEMs.
Supply-chain and regulatory headwinds
Two systemic risks require immediate attention in 2026 planning cycles:
- Raw-material constraints: Shortages of high‑purity silica and germanium have emerged as near‑term constraints for optical sensor manufacturing, particularly affecting producers with concentrated APAC supply chains. Tactical responses include material substitution R&D, secured long‑term offtake agreements, and regional diversification.
- Regulatory acceleration: Stricter safety mandates in automotive and expanded environmental monitoring obligations are raising the bar for sensor qualification and lifecycle compliance. This trend favors suppliers who can demonstrate certified system-level solutions and robust traceability.
2026 strategic imperatives — actions that create disproportionate value
For executives allocating capital and organizational focus in 2026, we recommend a prioritized set of moves aligned to horizon, cost of delay, and competitive defensibility:
- Lock supply and diversify: Negotiate contract provisions with critical-material suppliers, establish dual sourcing for high‑purity optical inputs, and explore near‑term inventory strategies to buffer production.
- Prioritize system-level differentiation: Move up the value chain by pairing sensors with calibration software, edge signal processing, and standardized integration kits that reduce OEM time‑to‑integration.
- Invest selectively in dToF and high‑resolution CMOS pathways: Where end markets require range, speed, or small-form integration, allocate R&D and JV funding to accelerate time-to-market for these modalities.
- Pursue capability-focused M&A: Target acquisitions that fill gaps in packaging, thermal stabilization, or software fusion rather than chasing large scale alone; integration speed is the critical metric.
- Adopt flexible commercial models: Offer bundled hardware + analytics subscriptions and certified integration services to capture recurring revenue and raise switching costs.
- Stress-test regulations and geopolitics: Build scenario playbooks that quantify demand shifts under tightening automotive standards and potential trade-policy disruptions.
How PW Consulting helps
Our engagement options range from a compact strategic briefing to full due‑diligence and implementation support. Clients receive a blend of quantitative datasets, hands‑on playbooks, and executive workshops designed to convert the market’s projected USD growth and 6.7% CAGR into prioritized, measurable initiatives. The full report contains the granular regional and application splits, supplier-level revenue profiles, and confidential financials needed to underwrite M&A and capex decisions — data withheld from this summary to preserve your competitive insight.
Closing — next steps
For leadership teams planning 2026 resource allocations, the multiaxial optical position sensor market presents a timely choice: accept component-level competition or invest to capture system-level returns enabled by dToF, CMOS, and integrated software. PW Consulting’s full market study provides the confidential sub‑segment analytics, target lists, and quantified scenarios necessary to move from strategic intent to executable roadmaps. To access the complete dataset and a tailored advisory session, consult the report page or contact our industry team.
For detailed analysis of this topic, please visit the official page: Multiaxial Optical Position Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Construction Management Software Market: Strategic Outlook for Enterprise Decision-making in 2026
As organizations plan capital programs, technology procurements, and M&A strategies for 2026, the Construction Management Software market presents both a clear growth trajectory and a set of structural shifts that will determine winners and losers. This briefing, prepared by PW Consulting’s industry practice, synthesizes market sizing, competitive dynamics, regulatory drivers, and practical decision frameworks that senior executives and procurement leads need to act with confidence. The full report contains granular segment tables, regional splits, and vendor scorecards — this introduction previews the strategic implications while deliberately withholding detailed segment-level figures to encourage targeted access to the underlying data package.
Construction Management Software Market
Market trajectory and what it means for 2026 planning
Using 2025 as the base year, our top-line market sizing traces a clear, compounding growth pattern across the last half-decade and into the coming planning horizon. The market expanded steadily from the start of the historical window (2020) through 2025 and is forecast to continue doing so across 2026–2032 at an industry compound annual growth rate of approximately 8.99%. Under PW Consulting’s baseline forecast the market reaches a materially larger scale by the end of the forecast window, reflecting sustained digitalization, cloud adoption, and the materialization of AI-enabled workflow automation.
Construction Management Software Market
For enterprise decision-makers, three immediate takeaways follow from this profile. First, procurement windows in 2026 should account for accelerating feature development — particularly around AI and BIM integration — meaning multiyear contracts should include explicit upgrade, integration, and exit clauses. Second, investment cases for deployment (cloud-first vs hybrid/on-premise) must incorporate regulatory and data-residency constraints that are now non-negotiable in several jurisdictions. Third, the expanding market creates more attractive M&A and partnership opportunities, but only to the extent buyers can operationalize integrations quickly and capture network effects across projects.
Construction Management Software Market
Competitive structure and strategic positioning
- Market concentration and competitive behavior. The market exhibits moderate concentration: a small set of global platform vendors lead with broad enterprise suites while numerous specialist vendors continue to capture niche demand. This structure drives a dual strategy for incumbents — deepen platform hooks through integrations and AI, and protect core revenue by building partner ecosystems.
- Vendor archetypes and what they signal to buyers. From enterprise-grade suites offering project portfolio and resource optimization to focused solutions for residential builders and field-level execution, vendor capabilities cluster into: (a) enterprise scheduling/portfolio platforms, (b) BIM and design-construction integrators, (c) field execution and safety tooling, and (d) horizontal ERP modules for construction finance. Understanding which archetype aligns to your company’s operating model is a first-order decision for 2026.
- Notable vendor dynamics observed in early 2026. Leading vendors have accelerated both product integrations and AI investments. Several platform providers announced integrations and acquisitions in Q1–Q2 2026 that underscore a race to embed automation, risk detection, and document intelligence directly into construction workflows. Partnerships between document specialists and platform vendors are reducing friction in AEC collaboration, while enterprise vendors continue to prioritize scalability and portfolio-level analytics.
Who we track (selected profiles)
- Procore Technologies — a cloud-native platform focused on end-to-end project coordination, document control, and increasingly AI-enabled automation to improve field-to-office workflows.
- Autodesk — integrating design-to-construction workflows with BIM-first platforms that unify design and construction execution, increasingly positioning Forma and Construction Cloud as a single continuum.
- Oracle — enterprise-grade scheduling and portfolio management capabilities, integrating Primavera heritage with cloud-scale analytics for large capital programs.
- Trimble — a systems integrator approach combining scheduling, financials, and on-site risk-management tools, with recent moves to enhance AI-powered document and compliance capabilities.
- Bentley Systems — infrastructure-focused BIM and simulation capabilities that prioritize complex engineering workflows and lifecycle analytics.
- Buildertrend and CMiC — representative examples of specialist-to-enterprise players addressing residential/light commercial and integrated ERP needs respectively.
The full report contains vendor scorecards, go-to-market maps, and a timeline of strategic product releases that explain how each supplier’s roadmap maps to buyer pain points. This summary intentionally omits the detailed rank ordering and numeric scorecards to preserve the value of the complete dataset.
Regulatory and industry forces that will shape procurement in 2026
- Data residency and privacy: GDPR-era requirements, particularly in the EU, have forced cloud vendors to rearchitect multi-tenant delivery and deploy regionally isolated data centers. Procurement teams must now evaluate not only functional fit and TCO but also contractual commitments around data localization, breach notification SLAs, and auditability.
- Sustainability mandates: Whole-life carbon assessments embedded in building performance directives are creating demand for BIM-integrated modules that can capture embodied carbon and material lifecycle metrics. Expect sustainability reporting to be a requirement in public tenders and a buyer differentiator for private owners.
- Professional standards and digital competency: Industry bodies are codifying expectations for digital capabilities on capital projects, meaning vendors that embed compliance workflows and auditable decision trails will command a premium in regulated or high-accountability projects.
- Digital adoption acceleration: Professional institutions in several markets are actively promoting digital transformation. Procurement strategies should anticipate faster adoption curves among teams that receive formal institutional backing and training subsidies.
Practical, action-oriented deliverables in the full report
PW Consulting’s full study is designed to be operational from day one. Key deliverables include:
- A transparent market-sizing methodology, with historicals (2020–2025) and base-year assumptions (2025) feeding the 2026–2032 forecast scenario suite.
- Scenario analyses (baseline, accelerated digital adoption, and recession stress) to stress-test vendor selection and capex timing.
- Vendor scorecards and migration pathways that translate product capabilities into implementation roadmaps for enterprise buyers.
- TCO and ROI templates that integrate licensing, integration, training, and change management costs across short- and multi-year horizons.
- Regulatory and data-residency mapping by jurisdiction to support contract terms and hosting decisions.
- AI readiness frameworks and a prioritization matrix that identifies which workflows yield the highest near-term automation ROI.
- M&A and partnership screening criteria targeted at both strategic acquirers and private equity sponsors seeking bolt-on targets.
- Procurement artifacts: RFP/RFI templates, scoring rubrics, and negotiation playbooks tailored to construction technology purchases.
- Case studies and implementation checklists that surface common failure modes and mitigation approaches for first 90–180 days post-go-live.
How to use this research to make better 2026 decisions
- Design procurement for optionality: Given rapid feature evolution, structure contracts to preserve strategic flexibility — modular scopes, performance milestones tied to capability delivery, and clear exit clauses to prevent lock-in.
- Prioritize data strategy: Align hosting choices with regulatory exposure and future M&A plans. Where cross-border project execution is critical, require vendors to demonstrate multi-jurisdictional data controls and audit trails.
- Adopt a capability-first sourcing approach: Rather than buying point solutions for isolated pain points, prioritize platforms that can demonstrate end-to-end value for your dominant workflows (e.g., design-construction handover, site safety capture, or cost-accounting continuity).
- Prepare for AI as an operational lever: Shortlist vendors by demonstrable automation outcomes (reduction in rework, time saved in submittal processing, predictive risk signals) and require proof-of-value pilots before enterprise roll-out.
- Make sustainability and compliance non-negotiables: Embed carbon-assessment capabilities and traceable audit trails into procurement criteria for projects subject to whole-life assessment or public-sector requirements.
- Factor implementation capacity into selection: The difference between a tool and a transformation is adoption. Insist on clear change-management plans, training accelerators, and local implementation partners in vendor proposals.
Why this matters now
The market’s steady growth and the acceleration of feature-level innovation mean 2026 is a pivot year: organizations that establish robust integration architectures, strong data governance, and AI-forward pilot programs will capture outsized benefits as platforms institutionalize across project portfolios. Conversely, entities that treat construction software as a commodity risk repeated re-procurement cycles, fractured data, and missed productivity gains.
PW Consulting’s full report converts the macro trajectory — historical validation through 2025 and an 8.99% CAGR outlook through 2032 — into executable steps: vendor shortlists, negotiation levers, technical due diligence checklists, and deployment timelines. For teams building capital planning proposals, technology roadmaps, or acquisition theses for 2026, these instruments are designed to shorten decision cycles and reduce execution risk.
Next steps
This briefing is a strategic preview. The complete report includes the full segmentation, regional and application-level forecasts, downloadable vendor scorecards, and ready-to-use procurement templates. To access the detailed datasets, segmentation tables, and the evidence base behind the projections, please visit the PW Consulting research page or contact our industry practice for a tailored briefing and live walk-through of the models.
For detailed analysis of this topic, please visit the official page: Construction Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ground Handling Services Market to Reach USD 56.8B by 2032 at 7.9% CAGR
By PW Consulting, 2026-07-12
Ground Handling Services Market — Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s senior strategic advisor and lead industry analyst, I present a focused briefing on the ground handling services market designed to inform executive choices in 2026. This preview synthesizes our latest market modelling (base year 2025) and competitive intelligence into a practical, decision‑oriented narrative. Readers will gain the strategic context and prioritized actions needed to navigate a market that is expanding steadily yet experiencing structural change driven by regulation, digitalization, and shifting carrier economics.
Ground Handling Services Market
Market at a glance: growth trajectory and structural cues
The ground handling services market has rebounded strongly from the pandemic trough. Our historical series shows expansion from roughly USD 24 billion in 2020 to USD 33.5 billion in 2025. Looking forward, the market is forecast to grow at a compound annual growth rate (CAGR) of 7.9% during 2026–2032, reaching approximately USD 56.8 billion by 2032. This growth profile reflects a blend of passenger recovery, sustained uplift in air cargo flows, and steady outsourcing demand from carriers and airports.
Ground Handling Services Market
Two structural features are particularly important for strategy in 2026: first, meaningful concentration among scale incumbents that capture a large share of revenue; second, accelerating non‑linear value drivers — notably technology platforms, regulatory compliance regimes, and new commercial contracting practices — that are re‑shaping unit economics across service lines.
Ground Handling Services Market
Why this study matters for decisions in 2026
- Regulatory inflection points: New EU and UK requirements for the provision and oversight of ground handling services are moving from consultation to enforcement. These rules introduce certification, compliance and self‑declaration steps with near‑term deadlines, forcing providers and their airline partners to re‑engineer governance, training and audit trails.
- Commercial pressure and margin re‑rating: Airlines are revisiting outsourcing models, pricing structures and performance metrics. Contract renegotiations and route network changes are creating winners and losers among established providers and regional specialists.
- Technology and operational transformation: Investments in resource optimization, baggage reconciliation systems, and shared data platforms are creating a two‑speed market: operators who digitize capture productivity gains rapidly while laggards face margin compression.
- Cargo and ancillary growth vectors: E‑commerce tailwinds and growth in freighter operations are producing outsized revenue opportunities, but also require different asset mixes, skillsets and throughput models compared with passenger handling.
Report scope — practical outputs you can apply immediately
Our full research is structured to move beyond benchmarking and into operational and commercial playbooks. Key deliverables include:
- Top‑down market sizing (2020–2025 historical, 2026–2032 forecast) with scenario buckets for faster/slower recovery paths.
- Segmentation by region, service type and application (kept at a high level here to preserve proprietary granularity in the full report).
- Provider profitability matrix, cost‑per‑turn models and normalized SG&A overlays for peer comparison.
- Service‑level KPI benchmarks (turnaround times, baggage mishandling rates, ramp productivity) and a digital‑adoption maturity model for operations teams.
- Regulatory compliance checklist and an implementation timeline tied to EU/UK milestone dates, designed for use in operational readiness programs.
- Commercial playbook: bid‑defense templates, contract clause prioritization, and scenario‑based price modelling for tenders and renegotiations.
- M&A and partnership decision framework — target archetypes, valuation sensitivities and integration checklists — tailored to mid‑market and strategic bolt‑on transactions.
Competition: strategic positioning and recent moves
The market is shaped by global integrators, regionally dominant players and specialist technology providers. Understanding each archetype’s playbook is critical for strategic responses.
- Swissport International AG — A scale leader with a broad global footprint and multi‑certification profile. Recent contract wins and regional rollouts demonstrate a continued emphasis on large‑scale network expansion and contract consolidation with global and flag carriers. For incumbents and challengers alike, Swissport’s strategy underscores the importance of combined scale and standardized, certificated operations when competing for major airline agreements.
- dnata — An integrated services operator with a strong base in the Middle East. dnata’s model blends ground handling with cargo and travel services, offering resilience through diversification and long‑term airline partnerships. Their approach is instructive for operators seeking to deepen vertical integration and cross‑sell ancillary services.
- Worldwide Flight Services (WFS) — A specialist in both ground and cargo operations with focused growth in high‑throughput nodes. WFS highlights the commercial leverage available from aligning cargo capabilities with freighter network growth and logistics customers.
- Menzies Aviation — A prominent competitor that is actively investing in next‑generation operational technologies. Recent rollouts of advanced baggage reconciliation and resource planning systems signal a strategy of performance differentiation via digital enablement and targeted airline partnerships.
- Aviapartner and regional specialists — Independent providers that maintain deep local relationships at major hubs. Their agility in tailoring service levels and pricing remains a strategic advantage in contested tenders where incumbents may be constrained by scale and cost structures.
- 5Continents and regional-focused operators — Anchored in specific geographies, these players reveal opportunities in markets with under‑served capacity or where regulatory complexity favors local providers.
- SITA — A pivotal technology partner, supplying data platforms and operational solutions that increasingly sit at the center of collaborative airport ecosystems. For many operators, engaging with platform providers like SITA is less a back‑office choice than a strategic necessity to access airline/airport data and to enable industry‑level interoperability.
Market concentration metrics confirm an environment where the leading few capture the majority of revenue, creating high barriers to scale. Nevertheless, the combination of regional specialization, technology partnerships, and performance‑led contracting continues to open pockets of opportunity for focused entrants and well‑executed roll‑ups.
Top strategic implications and prioritized actions for 2026
Executives should translate the market realities into a clear set of near‑term and medium‑term initiatives. Our recommendation framework breaks down into coherent, actionable priorities:
- Regulatory readiness (immediate to 12 months): Establish a cross‑functional compliance program that maps EU/UK requirements against your operating procedures, contracts and training curricula. Use a risk‑based approach to prioritize certifications and self‑declaration paths.
- Digitize to defend margins (0–24 months): Prioritize investments that deliver clear unit‑cost reductions (resource scheduling, digital ramp coordination, baggage RFID/BRS). Pilot small, measurable deployments before scaling across hubs.
- Commercial re‑engineering (0–18 months): Revisit contract structures to align incentives around on‑time performance, asset utilization and ancillary upsides. Develop tailored bid strategies for large network contracts versus opportunistic regional tenders.
- Targeted M&A and partnerships (12–36 months): Use M&A to fill capability gaps (technology, cargo handling, regional access) rather than to chase scale alone. Consider JV structures for rapid market entry where regulatory or labor dynamics make outright acquisition risky.
- Workforce and labor strategy (ongoing): Invest in training, multi‑skilling and accredited competency systems to meet both regulatory requirements and the flexibility needed for peak recovery periods.
- Sustainability and energy transition (18–48 months): Begin aligning fleet and ground equipment replacement plans with decarbonization trajectories — this will increasingly influence contract awards and airport concession terms.
Operational playbook — three horizons
- Quick wins (0–6 months): Standardize SOPs, tighten KPIs on mishandling and turnaround delays, and launch low‑cost digitization pilots at high‑volume gates.
- Build capability (6–24 months): Deploy scalable resource optimization platforms, certify training programs for compliance, and negotiate technology partnerships with platform providers.
- Strategic re‑positioning (24–36 months): Execute selective bolt‑on acquisitions, develop cross‑border service bundles aligned to airline network strategies, and institutionalize continuous improvement via data‑driven operations centers.
Getting the full picture
This preview highlights the strategic themes that will shape successful ground handling strategies in 2026. The full PW Consulting report contains the detailed segmentation, proprietary unit‑cost models, KPI dashboards and regulatory checklists that executives and transaction teams need to operationalize these recommendations. Our analysis intentionally provides high‑level direction here while reserving granular splits, scenario worksheets and model inputs for the full study to preserve exclusivity and to ensure decision‑grade utility.
For leaders preparing budgets, negotiating multi‑year contracts, or evaluating acquisitions in 2026, this research converts macro growth and regulatory change into concrete choices — enabling you to prioritize investments, structure partnerships, and defend margins as the market scales toward the USD 50+ billion horizon signaled in our forecasts. Contact PW Consulting to access the full dataset, regional breakdowns and executable playbooks used to underpin this strategic briefing.
For detailed analysis of this topic, please visit the official page: Ground Handling Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Data Center White Box Servers Market Poised for 12.5% CAGR to USD 369.75M by 2032
By PW Consulting, 2026-07-12
Data Center White Box Servers Market: Strategic Imperatives for 2026 Decision-Making
As enterprises and cloud providers plan capital allocations and technology road maps for 2026, the white box server market is no longer a niche engineering play — it is a strategic lever that shapes cost, performance and regulatory posture across global data center estates. PW Consulting’s latest market study frames that transition with data-driven clarity: the market has expanded meaningfully in the first half of the decade and, under our base-case forecast, is set to sustain a double-digit growth trajectory through 2032 (12.5% CAGR during 2026–2032), moving from roughly USD 162.1 million in 2025 to an expected USD 369.8 million by 2032.
Data Center White Box Servers Market
Why this matters to corporate leaders in 2026
-
Capitalization and unit economics: Organizations evaluating server refresh cycles in 2026 must treat white box procurement as an instrument for lowering per-workload cost while preserving the flexibility to accelerate AI and high-performance workloads.
Data Center White Box Servers Market -
Strategic differentiation: For hyperscalers and large enterprise cloud consumers, white box strategies enable vertically-aligned system designs — optimizing thermal envelopes, power delivery and compute-to-memory ratios for specific AI and analytics workloads.
Data Center White Box Servers Market -
Regulatory and sovereignty risk: New data sovereignty and localization pressures increase the strategic value of flexible, locally-sourced white box solutions that can be rapidly deployed in regionally compliant configurations.
Market trajectory and what it signals
The market’s multiyear growth is being driven by three intersecting vectors: accelerating adoption of AI/GPU-optimized servers, continued hyperscaler demand for cost-effective scale, and a rising enterprise appetite for purpose-built infrastructure that avoids vendor lock-in. These forces are forcing procurement teams and CTOs to reassess total cost of ownership frameworks — not only raw purchase price but lifecycle energy consumption, serviceability, and upgrade pathways. The reported concentration metrics indicate a market where a handful of OEM/ODMs exert significant influence, yet the balance leaves room for specialized providers and system integrators to carve durable niches through engineering differentiation and customer intimacy.
Immediate operational imperatives for 2026
-
Embed energy and thermal models into acquisition decisions. Electricity can represent a material share of data center operating expense, and AI workloads are driving above-market growth in energy consumption. Procurement teams must require validated PUE-adjusted energy models, and financial decision-makers should stress-test CAPEX against multiple energy-cost scenarios.
-
Design for modular upgradeability. Choose white box platforms that separate compute, GPU sleds, and storage so that incremental upgrades (e.g., new-generation accelerators) do not trigger full-node replacement.
-
Localize where regulation demands it. Stringent data sovereignty requirements in certain jurisdictions are creating a near-term need for locally-assembled or locally-certified white box stacks — plan footprint and partner strategies accordingly.
-
Shortlist vendors by co-engineering capability, not just price. For AI and accelerated computing, performance tuning and cooling architecture often determine ROI. Include co-development clauses and performance acceptance tests in RFPs.
Competitive landscape — patterns and strategic takeaways
The supplier landscape presents three archetypes that buyers should actively balance in their portfolios:
-
Large-scale OEM/ODM integrators that enable hyperscale economics and manufacturing depth. These players provide scale ops, platform engineering and ecosystem access that supports aggressive deployment schedules and co-development for unique workloads.
-
Specialist system integrators and white-box vendors that prioritize customization, energy efficiency and post-sales support. These firms excel at tailored configurations, rapid prototyping and sustainability-focused designs.
-
Regional and channel-focused suppliers who provide faster lead times for localized requirements and who can be pivotal where data sovereignty and rapid deployment are primary drivers.
Recent strategic moves underscore these dynamics. A leading DCBBS provider announced a major domestic manufacturing and testing expansion in 2026 — a decision that signals how supply-chain resilience and on-shore capacity are becoming strategic differentiators. For buyers, the implication is that supplier selection must weigh manufacturing footprint and logistics alongside technical fit.
Risk landscape and regulatory context
-
Regulatory scrutiny and planning: National agencies are actively examining constraints to data center growth and resilience as compute demand surges. Expect evolving guidance around siting, resilience, and security that will factor into long-term infrastructure planning.
-
Energy cost volatility: Electricity remains a substantial portion of operating expense. Scenario planning should include energy cost increases and intensified grid stress as AI workloads scale — this affects both TCO and site-selection logic.
-
Data localization and sovereignty: Increasingly stringent jurisdictional requirements can force architecture changes late in the procurement cycle. Mitigate by establishing local fulfillment pathways and configurations that can meet certification demands without redesigning the base platform.
How PW Consulting’s report supports 2026 strategic choices
Our full study is built for the executive and the operator alike. It blends historical trend analysis (2020–2025), a detailed forecast through 2032, and scenario-based stress tests that convert market projections into actionable decision inputs for 2026 planning cycles. Key deliverables include:
-
Decision-grade financial models — TCO calculators that capture procurement, deployment, energy, maintenance and upgrade costs across realistic lifecycle horizons.
-
Procurement playbooks — RFP templates, vendor scorecards, and acceptance-test protocols designed specifically for white box server acquisitions with GPU and dense rack formats.
-
Deployment scenarios — region- and workload-tailored blueprints that translate market growth forecasts into capacity-planning recommendations across short, medium and long-term horizons.
-
Vendor analysis and go-to-partner roadmaps — comparative profiles, strengths matrices and recommended engagement models for leading OEMs, ODMs and system integrators.
-
Risk register and mitigation pathways — covering energy, supply chain, regulatory and technology obsolescence risks, with prioritized mitigation actions and monitoring KPIs.
-
M&A and partnership screening — a shortlist methodology for identifying bolt-on engineering firms, regional assemblers or niche integrators that accelerate strategic goals.
Practical recommendations for 2026 planning cycles
-
Adopt a portfolio approach to sourcing. Balance long-cycle OEM agreements for baseline capacity with short-cycle specialist partnerships for strategic workloads and edge sites.
-
Make energy performance a contractual metric. Include energy and cooling performance guarantees and remediation clauses tied to measured workload efficiency.
-
Pilot before scale: contract small pilot clusters for critical AI workloads to validate end-to-end performance, manageability and upgrade paths before committing to large rollouts.
-
Lock-in supply resilience: ensure contracts include options for local assembly, alternative component routing and defined lead-time SLAs for critical components such as accelerators and PSUs.
-
Embed sovereignty compliance: implement pre-approved region-specific configurations that can be deployed rapidly to meet regulatory requirements without full engineering cycles.
How to use the study in corporate governance and budgeting
Boards and CFOs can use the report to stress-test capital plans and align IT procurement with broader enterprise risk appetite. CIOs and CTOs should convert our scenario outputs into prioritized acquisition roadmaps and capacity triggers tied to business KPIs (revenue per rack, latency SLAs, compute elasticity profiles). Procurement leaders will find our templates useful for reframing negotiations: shifting discussions from unit price to validated lifecycle cost and performance outcomes.
Limitations and where to go for the granular data
To preserve strategic value for active procurement and competitive positioning, this article intentionally summarizes the study’s strategic insights without reproducing the detailed segmentation tables, per-region splits, or application-level revenue breakdowns. The full report includes granular market segmentation, vendor share tables, pricing curves by configuration, and region-specific deployment scenarios — essential raw material for executing the recommendations above.
Closing: the practical edge for 2026
For organizations that treat infrastructure as a strategic asset, 2026 is a decisive year. The white box server market’s sustained growth and changing supplier dynamics create both risk and opportunity. Tactical moves made now — from revised procurement specifications to local assembly partnerships and energy-aware purchase commitments — will materially influence cost trajectories, time-to-market for AI initiatives, and regulatory compliance. Our study converts market intelligence into executable steps so that leaders can make those moves with confidence.
For the full dataset, supplier scorecards, RFP templates and the scenario-oriented TCO models referenced here, consult the complete PW Consulting report. Access to the full intelligence will equip your 2026 planning cycle with the granular inputs necessary to operationalize the strategic directions outlined above.
For detailed analysis of this topic, please visit the official page: Data Center White Box Servers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Private Tutoring Market Poised for 4.75% CAGR (2026–2032)
By PW Consulting, 2026-07-12
Private Tutoring Market — 2026 Strategic Preview
Why this preview matters for 2026 decision-makers
As organizations plan investments, partnerships, and product strategies for 2026, the private tutoring market presents a distinct blend of steady expansion and structural change. Our PW Consulting base-year assessment (2025) observes that the market has expanded meaningfully since 2020 and — under conservative assumptions — is projected to grow at a 4.75% compound annual growth rate through the 2026–2032 forecast window. Translating that trajectory into practical planning: the market that stood at the low hundreds of million USD five years ago is on a path to mid-hundreds of million USD by the end of the forecast horizon. That macro trend creates predictable demand pressure while leaving plenty of room for differentiated players to capture outsized returns.
Private Tutoring Market
This preview highlights the strategic implications of that growth path without disclosing the full tables, subsegment splits and granular regional allocations that are contained in the complete PW Consulting Private Tutoring Market report. Think of this as the strategic trailer: enough evidence of rigor to act, but intentionally not the proprietary datasets that power investment-grade decisions.
Private Tutoring Market
Market dynamics that will determine winners in 2026
- Demand stabilization with pockets of acceleration.
After a period of rapid digital adoption and episodic policy shocks, demand is maturing. Growth is driven by persistent parental and institutional willingness to invest in learning outcomes, with the fastest commercial potential concentrated where convenience, measurable outcomes, and accredited quality intersect.
Private Tutoring Market - Labour economics are a structural constraint.
Median annual tutor wages highlight the cost component for many operating models. Labour cost dynamics will determine pricing bands, margin levers and the attractiveness of automation or platform-mediated scale for different business models.
- Regulation remains a strategic risk and a moat.
Decades-long policies in multiple jurisdictions have limited or constrained teacher-provided private tutoring, and landmark interventions — most notably regulatory shockwaves in certain large markets — demonstrate how quickly operating landscapes can shift. Regulatory foresight and compliance capability are prerequisites for scalable expansion.
- Data privacy and tutor quality certification are buyer-deciding factors.
Institutional buyers and more sophisticated parents increasingly select providers on demonstrable privacy compliance and verified tutor credentials. Firms that embed these features into their product proposition enjoy higher conversion and retention.
- AI and product innovation are the new oxygen.
AI-driven personalization, automated lesson diagnostics, and guided practice engines materially raise per-student outcomes while enabling higher utilization of tutor time. Recent vendor launches demonstrate how quickly feature gaps can be closed by focused investment.
Competitive landscape — what we evaluated
Our analysis synthesizes public disclosures, proprietary interviews, and primary market modeling to profile a broad cross-section of incumbents and challengers. The market displays moderate concentration: the top three firms command a meaningful share of revenue, and the top five firms approach half of the market — a structure that rewards scale and differentiated distribution.
- Digital-first platforms: Companies that built marketplace or platform models have advantages in matching efficiency, variable cost structures, and data capture. They compete on matching algorithms, platform trust signals, and monetization architectures.
- Franchise and center-based operators: These players continue to capture demand where local trust and hands-on delivery matter. Expansion strategies are often franchise-led and can deliver rapid unit growth where brand, training, and local marketing are strong.
- Test-prep and admissions specialists: Brands with reputation in high-stakes testing leverage premium service lines and bundled offerings to secure higher ARPU (average revenue per user) customers.
- Hybrid operators: Firms combining in-person centers with online delivery are experimenting with dual-channel economics to optimize tutor utilization and market reach.
We evaluated leading participants across these archetypes — including global platform providers, established franchise networks, and specialist test-prep firms — to extract strategic patterns. Each profile in the full report contains an assessment of go-to-market, monetization, unit economics, recent strategic moves and an M&A posture snapshot.
Recent developments that matter for 2026 planning
- Significant franchise acceleration by franchise-led educators signals renewed appetite for physical expansion where unit economics support it.
- AI-enabled product launches from marketplace incumbents demonstrate how personalization and learner analytics are being embedded into core propositions.
- Ownership changes at established online tutoring providers illustrate both strategic repositioning and the continued investor interest in scalable digital tutoring assets.
What the full PW Consulting report delivers (practical, operational, decision-ready)
The full report is designed for boards, corporate strategy teams, private equity sponsors, and product leaders who need executable guidance. Key deliverables include:
- Market sizing & conservative-to-optimistic forecasts by year (base-year 2025 and forecast 2026–2032) with sensitivity analyses.
- Segment economics and pricing benchmarks (institutional vs consumer channels), with modeled LTV:CAC and break-even timelines for representative business models.
- Go-to-market playbooks for three archetypes: platform marketplaces, franchised centers, and integrated hybrid operators — each with tactical KPIs, channel budgets, and pilot templates.
- Regulatory risk matrix and mitigation pathways tailored to priority expansion markets.
- Product feature prioritization framework emphasizing AI personalization, compliance controls, and measurement systems that drive renewals.
- M&A screening tools and an actionable shortlist methodology that identifies targets by revenue profile, margin expansion potential, and integration risk.
- Operational playbooks for tutor recruitment, certification programs, and quality assurance that align with institutional purchasing criteria.
- Scenario planning playbooks with trigger-based decision rules for accelerating or pausing expansion under regulatory, macroeconomic, or competitive stress.
To preserve the strategic value of our proprietary work—and to serve as a call to action for stakeholders seeking transaction-ready intelligence—we do not reproduce detailed subsegment tables or regional/application percentage breakdowns in this preview. Those granular insights, including full-year-by-year tables and downloadable models, are available in the complete PW Consulting publication.
Strategic actions for 2026 — where to focus
- Prioritize product levers that increase measurable outcomes:
Invest in AI-driven lesson personalization, outcome tracking dashboards, and tutor enablement tools that demonstrably lift test scores or course completion. These are the features that convert higher-value buyers and justify premium pricing.
- Embed compliance and credentialing into the commercial proposition:
Develop audit-ready privacy controls and tutor certification pathways. Institutional buyers increasingly treat these as pre-requisites, not differentiators.
- Choose an expansion mode that fits economics:
Franchise expansion can scale presence quickly where local brand matters; marketplaces scale faster with lower capital intensity. Hybrid approaches can unlock incremental reach but require disciplined integration to avoid margin erosion.
- Design M&A to buy capabilities, not just customers:
Targets that bring proprietary curriculum, validated outcome data, or superior local operations are more accretive than acquisitive plays that only increase topline volume.
- Measure the right KPIs:
Track tutor utilization, repeat-purchase rate, LTV:CAC by channel, average session yield, and a regulatory-risk index. These metrics should feed a quarterly dashboard used by the leadership team to pivot quickly.
- Run focused growth experiments:
Pilot bundles (micro-subscriptions, outcomes guarantees, school co-delivery) in 1–2 markets before scaling — use clearly defined decision gates tied to unit economics improvement.
Conclusion — the opportunity and the ask
The 2026 strategic horizon for private tutoring is one of measured opportunity: predictable overall growth, evolving buyer sophistication, and clear technological pathways to improve outcomes and margins. Success will accrue to firms that combine rigorous outcome measurement, disciplined unit economics, and regulatory foresight.
PW Consulting’s full Private Tutoring Market report contains the detailed tables, regional and application splits, company scorecards, and downloadable financial models necessary to operationalize these recommendations. For boards, PE investors and growth teams preparing 2026 plans, that level of granularity will be essential — and it is intentionally gated to ensure our clients receive transaction-grade intelligence.
Next steps
- Contact PW Consulting to request the full report and the accompanying financial models for scenario testing.
- Use the preview insights above to prioritize a short list of pilots and an M&A screening hypothesis for Q1 2026.
- Adopt the KPIs enumerated here as the core of your weekly growth and compliance dashboard.
For detailed analysis of this topic, please visit the official page: Private Tutoring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Online Exam Proctoring Market to Hit USD 2.75B by 2032, 15.5% CAGR
By PW Consulting, 2026-07-12
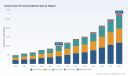
Online Exam Proctoring Market 2026: Strategic Preview for Corporate Decision-Makers
As organizations accelerate the digitization of assessment and certification, online exam proctoring has transitioned from a niche convenience to a core component of credentialing, compliance testing, and high-stakes assessment strategies. This preview synthesizes the essential strategic implications of PW Consulting’s new Online Exam Proctoring Market study (base year 2025, forecast 2026–2032) and explains why C‑suite and procurement leaders must treat proctoring capability as a 2026 strategic priority.
Online Exam Proctoring Market
Executive snapshot
The proctoring market has entered a rapid growth phase. Our macro model shows market value rising from under USD 500 Million in 2020 to approximately USD 1.0 Billion in 2025, with a compounded annual growth rate of 15.5% through the forecast window. By 2032 the sector is projected to exceed USD 2.7 Billion—an expansion driven by rising remote certification volumes, regulatory acceptance of remote testing, and continuous improvements in AI‑enabled monitoring and secure delivery infrastructure.
Online Exam Proctoring Market
Why this matters for 2026 decision cycles
- Strategic risk management: Organizations that postpone a clear proctoring strategy face escalating compliance and reputational risks. Remote assessment is no longer experimental; it is embedded in core business processes for hiring, licensing, and internal compliance testing.
- Vendor selection impacts total cost of ownership and downstream agility. Proctoring tools touch identity verification, data protection, LMS integration, and candidate experience; vendor choices made in 2026 will shape operational costs and legal exposure for years.
- Competitive differentiation. Employers and credentialing bodies that optimize remote assessment processes reduce time‑to‑credential and improve candidate throughput—advantages that compound across talent pipelines and commercial certification programs.
Market dynamics shaping 2026 plays
Four dynamics are decisive for vendors and buyers:
Online Exam Proctoring Market
- Regulatory & privacy headwinds
Data protection regimes—most notably GDPR and a growing number of biometric privacy statutes—are enforcing stricter controls over video, facial recognition, and voice data. These frameworks require demonstrable data minimization, purpose limitation, and, increasingly, explicit consent flows. Organizations must evaluate vendors against privacy‑by‑design criteria and prepare for jurisdictional constraints on certain biometric modalities.
- Security and public‑sector assurance
Public‑sector procurement is moving toward cloud assurance frameworks. Recent vendor certifications and readiness designations are signaling a bifurcation: suppliers that can demonstrate formal cloud security posture and government‑grade accreditation will dominate public tenders and large enterprise deals.
- Infrastructure realities
Reliable proctoring depends on consistent upstream and downstream bandwidth and resilient streaming technologies. Minimum bandwidth expectations and proctor‑side capacity planning are operational constraints—especially for large, synchronous exams. Adaptive low‑bandwidth streaming and smart session management will be key differentiators for deploying at scale in variable connectivity environments.
- AI and trust trade‑offs
Automated proctoring and advanced analytics reduce human review costs but raise explainability, bias, and appealability concerns. Buyers must balance automation benefits with transparent human‑in‑the‑loop processes, vendor explainability commitments, and defensible incident review workflows.
Competitive landscape — what to watch
The vendor field combines legacy test‑delivery specialists, AI‑first entrants, and assessment platform integrators. Our qualitative analysis of leading players yields five tactical points for 2026 procurement and strategy teams:
- PSI — A contender with strong assessment heritage that is accelerating into secure cloud proctoring. Recent enterprise and public‑sector certifications and partnership renewals underscore a positioning toward regulated, high‑assurance customers. For buyers targeting government or large credentialing programs, certification posture and auditability are decisive.
- Honorlock & Proctorio — Firms emphasizing AI detection and device‑level analytics. These solutions appeal where scale and low marginal cost per session matter most, but buyers must validate detection accuracy, false positive handling, and privacy safeguards, especially where biometric processing is contested.
- ProctorU & Examity — Firms with established live‑monitoring and hybrid offerings; attractive to organizations prioritizing candidate experience and a human‑verified audit trail. They remain relevant where due‑process and candidate appeal channels are important.
- Respondus & LockDown approaches — Browser‑level control remains a staple for reducing surface‑area risk in LMS ecosystems. These technologies are complementary to AI monitoring—particularly in high‑volume academic deployments—and procurement should plan for browser‑lock strategies as part of multi‑layered defense.
- Specialists & integrators (Inspera, OctoProctor, ProctorTrack, Constructor, Examus, Meazure Learning) — These vendors differentiate through LMS/assessment platform integrations, biometric identity verification, or flexible deployment models (including bring‑your‑own‑proctor). Decision frameworks in our report help buyers assess fit based on use case: academic testing, professional certification, or corporate compliance exams.
Recent market signals (implications for 2026)
- Certifications and government readiness are accelerating: vendors obtaining cloud security designations demonstrate the premium attached to public‑sector trust. Expect procurement cycles in government and regulated industries to favor certified providers.
- Milestone volumes reported by several providers indicate growing operational scale. Scalability questions now emphasize multi‑proctor concurrency planning and incident resolution SLAs rather than mere feature parity.
- Regulatory incidents and evolving privacy case law will continue to shape permissible technical architectures (for example, approaches that avoid raw biometric retention will gain preference).
What our full study delivers — practical, purchaseable intelligence
PW Consulting’s full report is designed as an executive‑to‑operational playbook. It contains:
- Market sizing and trajectory (2020–2032) with scenario analysis that isolates demand drivers and sensitivity to regulatory shocks.
- Vendor scorecards and quadrant mapping against commercial, security, and privacy dimensions—intended to accelerate RFP short‑listing without re‑inventing evaluation criteria.
- Actionable procurement assets: RFP templates, decision matrices, and contract clauses for data protection and incident management tailored to proctoring engagements.
- Deployment playbooks covering on‑premises vs cloud tradeoffs, hybrid architectures, bandwidth and proctor staffing models, and candidate experience optimization recipes.
- ROI and TCO models calibrated to common use cases (academic testing, certification, corporate compliance), enabling CFOs to model financeable adoption pathways.
- Privacy impact assessment templates and a technical checklist for adaptive streaming, encryption at rest/in transit, and biometric minimization strategies.
Strategic recommendations for 2026
- Treat proctoring as a cross‑functional program: Combine legal, IT, assessment design, and procurement into a single governance forum. This reduces the risk of mismatched requirements (e.g., strong proctoring tech with insufficient privacy controls).
- Prioritize vendor certification and auditability: If you serve regulated populations or bid on public tenders, select vendors with demonstrable security credentials and transparent audit logs.
- Design for contested outcomes: Establish clear appeal workflows, human review thresholds, and explainability SLAs before scaling automated proctoring to high‑stakes assessments.
- Benchmark candidate experience alongside detection metrics: High churn in candidate completion rates often traces back to fragile connectivity assumptions or intrusive UX; invest in pilot cohorts that mirror the lowest‑bandwidth regions you serve.
- Modularize your architecture: Build an assessment stack where browser lockdown, identity verification, and monitoring modules can be swapped without re‑engineering the LMS—this preserves negotiation leverage and enables rapid compliance adjustments.
Final note — this preview versus the deep dive
This article highlights why proctoring decisions in 2026 must be strategic rather than tactical. The full PW Consulting study supplies the granular models, vendor benchmarking, and operational toolkits necessary to convert insight into executable programs—without forcing procurement teams to start from first principles. For teams preparing procurement rounds, migration plans, or compliance roadmaps, our full report provides the segmented intelligence and appendices that operational leaders use to sign contracts and mobilize delivery teams.
To access the complete dataset, vendor assessments, scenario models, and deployment checklists that underpin these conclusions, please refer to the primary report release on PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Online Exam Proctoring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Semiconductor Electrostatic Chuck Market to grow at 5.1% CAGR
By PW Consulting, 2026-07-12
Semiconductor Electrostatic Chuck Market — Strategic Outlook for 2026 Decision-Makers
The semiconductor electrostatic chuck (ESC) market is entering a period where incremental technology improvements, supply-chain friction, and customer qualification dynamics will determine winners and losers. This briefing synthesizes the directional intelligence from PW Consulting’s latest market study to equip executives, procurement leaders, and product strategists with the decision levers that matter in 2026. We intentionally provide a high-resolution strategic view while withholding granular segment- and region-level splits to preserve the full analytical value of the underlying research and motivate targeted follow-up.
Semiconductor Electrostatic Chuck Market
Market snapshot: position and trajectory
Between 2020 and 2025 the ESC market expanded from roughly USD 764.5 Million to approximately USD 975.65 Million, reflecting steady demand tied to wafer processing and advanced-node ramp activity. With a 2026–2032 forecast CAGR of 5.1%, the market is projected to pass the USD 1,000 Million threshold in the near term and approach a materially larger market by 2032. This growth profile is neither explosive nor stagnant — it is the kind of sustained, modest expansion that rewards disciplined strategic plays in manufacturing scale, IP differentiation, and supply resiliency.
Semiconductor Electrostatic Chuck Market
Why this research matters for 2026 decisions
-
Timing capital allocation: With demand growth predictable but not exponential, 2026 is a year to be surgical about CapEx. The right move is to prioritize modular investments and supplier co-development agreements that preserve optionality for advanced-node or high-mix fabs rather than committing to large, inflexible lines.
Semiconductor Electrostatic Chuck Market -
Supplier and qualification strategy: ESCs remain subject to long qualification timelines at leading-edge fabs (commonly 12–24 months). Procurement teams must start second-source qualification cycles in 2026 if they aim to change or diversify suppliers by 2028. Our research highlights qualification as a gating issue that directly constrains pricing power and supplier entry.
-
Risk-adjusted sourcing: The market concentration is meaningfully skewed toward a small set of established equipment and ceramics suppliers (the study reports a top-three concentration and a top-five concentration that underline high incumbent power). For decision-makers, this implies negotiating beyond price — seek technical co-engineering, longer-term material commitments, and shared risk models.
-
R&D and product positioning: Incremental improvements in hold force, thermal uniformity, and plasma resistance are the primary differentiators today. Investments in these areas deliver outsized commercial returns when paired with process integration partnerships at strategic fabs.
Core dynamics shaping the market
-
Technology evolution: ESC design is progressing along three axes — electrostatic performance, thermal management, and contamination control. Suppliers are introducing innovations ranging from RF-optimized and cryogenic-compatible chucks to hybrid ceramic-polymer constructions that reduce mass and improve alignment. These refinements translate to tighter process windows and higher switching costs for fab operators.
-
Materials and supply pressure: High-purity aluminum nitride, specialty oxides, and advanced coatings are critical inputs. The supplier base for certain high-grade materials is geographically concentrated, creating exposure to geopolitical tensions, tariffs, and export controls — a factor that must be priced into sourcing and inventory strategies.
-
Regulatory and trade environment: Export controls and technology decoupling between major markets are introducing permit and compliance layers that complicate cross-border procurement. In this environment, localized manufacturing or qualifying domestic secondary suppliers can be a value-preserving strategy.
-
Fabs’ qualification inertia: Long qualification timelines blunt price volatility and raise the bar for new entrants. The implication for incumbents is protection; for challengers, it means investing in pilot partnerships and shared integration risk to shorten adoption hurdles.
Competitive landscape — strategic profiles and tactical moves
The competitive field mixes global equipment OEMs with specialized ceramics and materials houses. The leading suppliers combine system-level integration capabilities with materials expertise, producing an incumbent advantage that extends beyond product specifications.
-
Applied Materials, Inc. — As a major equipment OEM, Applied Materials leverages platform integration to offer ESC modules bundled with etch, CVD and PVD tools. Their recent product initiative focuses on higher hold force and improved thermal uniformity, which can shorten customer integration cycles. For suppliers and buyers alike, partnering with platform OEMs remains a high-leverage way to accelerate process qualification.
-
Tokyo Electron Limited (TEL) — TEL is positioning RF-optimized ESCs for sub-3nm and advanced fabrication. Their approach emphasizes process uniformity and thermal stability, making them a preferred option for advanced-node ramp customers and a formidable competitor on performance-sensitive applications.
-
Lam Research Corporation — Lam has invested in cryogenic-compatible ESCs and cold-resistant ceramics to address etch processes used in 3D NAND and advanced nodes. Their focus on application-specific materials engineering underscores how niche capabilities can secure design wins in segments with extreme environment requirements.
-
Ceramics and materials specialists (Kyocera, NTK CERATEC, NGK, Sumitomo Osaka Cement, Tsukuba Seiko, TOTO, Shinko, Creative Technology) — These suppliers concentrate on high-purity ceramics, coatings, and process-specific chuck features like dual-zone control, plasma-repellent surfaces, and self-cleaning capabilities. Several have expanded product lines or capacity recently, reflecting steady OEM demand for differentiated materials.
-
Entegris — As a materials and components supplier, Entegris occupies a unique positional advantage by providing integrated materials and contamination-control solutions that complement ESC performance, particularly in high-purity process environments.
Recent product launches from major OEMs and material-house expansions (notably launches in early 2025 and product-line growth in 2024) reinforce that vendor competition is centered on performance gains and integration depth rather than on commoditized pricing.
Practical, actionable insights for 2026
-
Start immediate dual-sourcing pilots for any ESCs that will be qualified in the 2027–2028 window. Qualification lead times mandate that decisions made in 2026 determine supplier flexibility in 2028.
-
Negotiate supplier agreements that include technical co-development clauses and reciprocal IP milestones. These clauses convert a supplier relationship into a competitive barrier for rivals and shorten cycle times for iterative product improvements.
-
Lock in strategic material supply contracts with clauses for capacity reservation or priority allocation to mitigate geopolitical disruption risks for specialty ceramics and coatings.
-
Invest selectively in in-house testbeds to accelerate qualification and reduce dependency on fab time for early-stage validation. Even modest capital trade-offs that enable quicker validation can yield outsized commercial advantages.
-
Embed scenario planning into procurement and product roadmaps. Model permutations of export-control intensity, tariff shocks, and supply interruptions to stress-test supplier portfolios and inventory policies.
-
Assess M&A or strategic JV opportunities with specialized ceramics houses if your strategy requires rapid vertical integration or secured access to niche materials and coatings.
What the full report delivers (practical elements)
PWC’s full Semiconductor Electrostatic Chuck Market report contains operationally focused deliverables designed for immediate use by corporate strategy, procurement, and R&D teams. Highlights include:
-
A detailed TAM and SAM view with year-by-year market sizing and scenario-based forecasts calibrated to device node and fab investment cycles.
-
Vendor heatmaps and supplier scorecards that evaluate technical differentiation, qualification timelines, capacity constraints, and supply-chain exposure.
-
Actionable go-to-market playbooks for OEMs, materials suppliers, and system integrators, including partnership and pricing strategies for 2026–2028.
-
Risk matrices and mitigation roadmaps for raw-material concentration, trade policy shifts, and long customer qualification cycles.
-
Operational models for inventory optimization and contract design to protect margins under varying supply-disruption scenarios.
Note: while this briefing summarizes strategic implications and market trajectory, it intentionally omits granular regional and application splits and certain proprietary competitive metrics. Those detailed tables, interactive dashboards, and supplier-level revenue models are available in the full report and are essential for executable procurement and investment plans.
Call to action
For organizations that must make capital, procurement, or product decisions in 2026, coupling scenario-adjusted forecasts with supplier-level intelligence is non-negotiable. PW Consulting’s full study provides the granular segmentation and supplier analytics required to convert directional insight into executable strategy. Contact PW Consulting to obtain the complete dataset, vendor scorecards, and implementation playbooks that translate the broad market signals summarized here into prescriptive action.
For detailed analysis of this topic, please visit the official page: Semiconductor Electrostatic Chuck Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


