



Category: IT & Electronics
PW Consulting: DDoS Protection Market Hits $2.15B in 2025, Projected 13.83% CAGR to $5.38B by 2032
By PW Consulting, 2026-09-16
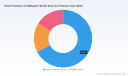
Navigating the New Perimeter: Strategic Imperatives in the 2026 DDoS Protection and Mitigation Market
The cybersecurity landscape of 2026 is defined by a fundamental shift in how enterprises conceptualize their network boundaries. As digital transformation accelerates and hybrid work models become entrenched, the attack surface has expanded exponentially. Distributed Denial of Service (DDoS) attacks have evolved from mere nuisances into sophisticated weapons capable of crippling critical infrastructure, disrupting supply chains, and eroding consumer trust. In this high-stakes environment, investing in robust DDoS protection is no longer a discretionary IT expense but a core component of enterprise risk management. Our latest market research offers a comprehensive lens through which to view this rapidly evolving sector, providing the intelligence necessary for strategic decision-making in the coming years.
This report serves as a critical compass for stakeholders navigating the DDoS Protection and Mitigation Market. By analyzing historical trajectories and forecasting future growth, we uncover the underlying forces driving demand. The research is designed not merely to report numbers but to contextualize them within the broader operational and technological realities facing Chief Information Security Officers (CISOs), procurement leaders, and investors. Understanding the market dynamics allows organizations to align their security postures with business resilience goals, ensuring that protection mechanisms scale effectively alongside digital ambitions.
Market Trajectory and Growth Dynamics
The historical data from 2020 to 2025 indicates a steady and significant expansion in the sector, reflecting the increasing frequency and complexity of cyber threats. The market has demonstrated resilience and consistent upward momentum, driven by the universal need for uptime and availability. Our analysis projects this trajectory to continue robustly through the forecast period ending in 2032. The compound annual growth rate (CAGR) underscores the velocity of this expansion, signaling sustained investment across the industry value chain.
Such growth is not uniform across all vectors. It is propelled by the convergence of several macro factors. First, the proliferation of Internet of Things (IoT) devices provides attackers with larger botnets, necessitating more advanced mitigation capabilities. Second, the shift toward cloud-native architectures requires protection layers that are equally elastic and distributed. Third, regulatory pressures are forcing organizations in critical sectors to adopt stricter resilience standards. These dynamics collectively create a fertile ground for market expansion.
For enterprise decision-makers, this growth trajectory implies that the window for implementing foundational security measures is narrowing. Delaying investment in DDoS mitigation exposes organizations to escalating risks as attack volumes increase. The market data suggests that solutions must be scalable to handle future threat landscapes. Investing now positions organizations to leverage mature technologies rather than scrambling for ad-hoc solutions during a crisis. The financial magnitude of the market reflects the critical value businesses place on continuity.
Key Report Contents and Operational Insights
Our research goes beyond high-level figures to provide actionable intelligence. The report is structured to guide strategic planning across multiple dimensions. One primary focus is the breakdown of deployment models. Understanding the trade-offs between cloud-based, hybrid, and on-premises solutions is vital for architecture planning. Each model offers distinct advantages regarding latency, control, and scalability. The analysis details how organizations are balancing these factors to achieve optimal protection without sacrificing performance.
Similarly, the report examines protection types, dissecting the market by network-based, application-based, and host-based solutions. This segmentation is crucial because attacks target different layers of the stack. A comprehensive security strategy often requires a layered approach. By understanding the prevalence and effectiveness of each protection type, leaders can construct a defense-in-depth strategy that closes gaps. The research highlights where investments are flowing and which technologies are gaining traction based on efficacy and ease of integration.
Furthermore, the study addresses the operational realities of managing DDoS protection. This includes the growing emphasis on automation and real-time response. Manual mitigation is no longer sufficient given the speed of modern attacks. The report explores how vendors are integrating threat intelligence and automated rulesets to reduce response times. It also considers the human element, discussing the skills required to manage these systems and the potential impact on operational overhead. For procurement teams, this section offers criteria for evaluating vendor capabilities beyond marketing claims.
DDoS Protection and Mitigation Market
Competitive Landscape and Vendor Ecosystem
The market features a diverse mix of established giants and specialized security firms. Our analysis profiles key players who are shaping the competitive dynamics. Companies such as Akamai Technologies and Cloudflare have set high bars with their global anycast networks and dedicated protection platforms. Akamai focuses on robust behavioral defense across deployment options, while Cloudflare emphasizes integrated CDN scrubbing and bot defense. These firms represent the scale required to absorb massive volumetric attacks.
Other significant contributors include Imperva and Radware, which offer multi-layered protection services covering networks, applications, APIs, and DNS. Imperva leverages automated mitigation and threat intelligence to provide comprehensive coverage. Radware is notable for its hybrid approach, combining on-premise appliances with cloud scrubbing centers to deliver adaptive real-time mitigation. Their recent initiatives highlight the industry's move toward low-latency solutions and AI-driven security platforms, ensuring scalable application security enforcement without compromise.
Network infrastructure specialists like NETSCOUT and F5 Networks also play pivotal roles. NETSCOUT's Arbor portfolio targets enterprise-scale volumetric attacks with specialized perimeter defense tools. F5 integrates DDoS protection within its broader distributed cloud services, combining WAF and bot mitigation in a multi-cloud SaaS platform. Specialized vendors like Corero Network Security focus on high-performance distributed defense for service providers and enterprises, expanding their reach into new regions to address localized threats. The competitive landscape is characterized by continuous innovation, partnerships, and infrastructure expansion, such as the recent increase in global scrubbing capacity by telecommunications providers.
Industry Dynamics and Strategic Drivers
Several external factors are influencing the market dynamics beyond pure technology competition. Regulatory environments are becoming stricter. For instance, mandates in regions like the European Union require operators in critical sectors to meet specific resilience standards and reporting requirements within tight timeframes. This regulatory pressure compels organizations to adopt certified or compliant DDoS mitigation strategies, driving demand for solutions that can demonstrate adherence to these standards.
Infrastructure costs and energy considerations are also entering the conversation. Data center electricity demand is a growing concern, potentially affecting operational costs for hosting security infrastructure. Mitigation services that are energy-efficient or leverage optimized fiber optic transmission can offer long-term cost advantages. Additionally, the physical resilience of data centers is under scrutiny, as cybercrime-related attacks have historically caused unplanned outages. Ensuring that protection services are housed in resilient facilities is part of the broader due diligence process.
The rise of specialized use cases, such as gaming and real-time communications, is driving niche innovation. Recent product launches indicate a focus on low-latency mitigation for specific protocols, ensuring that security does not degrade user experience. Partnerships between security vendors and telecom providers are expanding reach and capacity, creating a more interconnected defense ecosystem. These developments suggest that the market is maturing from a commodity service into a specialized utility critical for digital operations.
Strategic Value for 2026 Decision-Makers
For leaders navigating 2026, this research provides the evidence base needed to justify security investments. The data supports the argument that DDoS protection is a foundational requirement for digital business. By understanding the market size and growth rates, CFOs and CEOs can contextualize security budgets within the broader risk profile of the organization. The segmentation analysis helps CTOs decide where to allocate resources, whether toward cloud migration, hybrid architectures, or specialized application layer defenses.
The competitive profiling allows procurement teams to benchmark vendor offerings. Knowing the specific strengths of players like Akamai, Cloudflare, Imperva, and others enables more informed RFPs and negotiations. It helps organizations avoid vendor lock-in by understanding the differentiated value propositions in the market. Furthermore, awareness of recent developments, such as regional expansions and infrastructure upgrades, informs decisions about service level agreements and geographic coverage.
Ultimately, this report is designed to transform uncertainty into strategy. The DDoS Protection and Mitigation Market is growing, but so are the threats. Making informed choices now ensures that security architecture supports business growth rather than hindering it. The insights contained within this study are intended to empower stakeholders to build resilience that lasts beyond the current threat cycle.
To access the full depth of this analysis, including detailed segmentation data, comprehensive vendor profiles, and granular forecast models, we invite you to explore the complete report. The full intelligence package provides the specific metrics and strategic recommendations required to execute your security roadmap with confidence. Discover the detailed data behind the trends and equip your organization with the knowledge to secure its digital future.
Worldwide Military Cyber Weapons Market
For detailed analysis of this topic, please visit the official page: DDoS Protection and Mitigation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: ITSM Market Hits $215M in 2025, Projected 16.45% CAGR Through 2032
By PW Consulting, 2026-09-16
The ITSM Software Market in 2026: Navigating Autonomous Service Delivery and Strategic Alignment
The landscape of IT Service Management (ITSM) software is undergoing a profound transformation in 2026, driven by the convergence of artificial intelligence, evolving compliance mandates, and the relentless push toward operational efficiency. As enterprises grapple with increasing data subject requests and the need for faster resolution times, the choice of ITSM platform has become a critical strategic decision rather than a mere operational tactic. This market research report provides a comprehensive examination of the ITSM software market, offering decision-makers the intelligence required to navigate this complex ecosystem with confidence.
Understanding the trajectory of this market is essential for stakeholders involved in digital transformation, IT operations, and service delivery strategy. The shift from traditional ticketing systems to autonomous, AI-driven service management platforms is redefining value propositions and competitive dynamics. This article serves as an introduction to our latest deep-dive analysis, highlighting the macro trends, competitive forces, and operational dynamics that are shaping the future of ITSM through 2032.
Macro Market Trajectory and Growth Dynamics
The ITSM software market has demonstrated consistent expansion over the past half-decade, reflecting the critical dependency organizations have on robust service management frameworks. Historical data from 2020 through 2025 shows a steady climb in revenue, indicating that investment in service management tools is viewed as a foundational element of enterprise infrastructure. As we move into the forecast period spanning 2026 to 2032, the growth trajectory accelerates, underpinned by the widespread adoption of cloud-based solutions and the integration of generative AI capabilities into core ITSM workflows.
Projections for the coming years suggest that the total market size will reach new thresholds, with significant year-over-year growth expected throughout the forecast period. This expansion is not merely a function of inflation or headcount growth but represents a structural shift in how IT services are delivered and consumed. Organizations are increasingly willing to invest in platforms that offer autonomous capabilities, reducing the burden on human agents while improving service levels. The compound annual growth rate observed in this market underscores the urgency for businesses to evaluate their current tooling against future-state requirements.
Strategic decision-makers must recognize that the market is maturing rapidly. Early adopters of advanced ITSM solutions are already reporting tangible benefits in terms of ticket deflection and resolution speed, creating a competitive pressure for others to modernize. Ignoring these trends risks falling behind in operational efficiency and service quality. Our report provides the necessary context to understand where the market stands today and where it is headed, enabling leaders to time their investments appropriately.
Software Asset Management Managed Service Market
Core Market Dynamics and Operational Pressures
Several key dynamics are exerting pressure on the ITSM market, compelling organizations to seek more sophisticated solutions. Labor costs remain a primary concern, as AI-powered ITSM platforms enable substantial ticket deflection and faster resolution times, reducing the reliance on specialized human labor for routine tasks. This shift allows IT teams to focus on higher-value initiatives while automated systems handle the volume of standard requests.
Simultaneously, data privacy and compliance requirements are intensifying. Enterprises are experiencing a dramatic increase in data subject requests, which drives demand for ITSM platforms equipped with built-in compliance features and audit-ready capabilities. The ability to manage these requests within a governed workflow is becoming a differentiator for vendors and a necessity for buyers.
Infrastructure trends further influence the market, with cloud-based ITSM solutions enabling scalable multi-cloud and hybrid deployments. Real-time service visibility and adherence to service level agreements are critical in these distributed environments. Furthermore, regulatory frameworks such as ITIL v4 and ISO standards are widely adopted to standardize service processes, with AI enhancements ensuring compliance even in autonomous workflows.
Pricing structures vary significantly across the landscape, ranging from entry-level options for mid-market platforms to premium enterprise tiers with advanced AI features. Understanding these cost structures relative to value delivery is crucial for budget planning and vendor selection.
Segmentation and Deployment Strategies
The market is segmented by deployment type, application functionality, and regional adoption. Cloud-based ITSM solutions have gained significant traction, offering the flexibility and scalability required for modern IT operations. These solutions support real-time visibility and multi-cloud management, which are essential for enterprises operating across diverse infrastructure environments. On-premises options remain relevant for organizations with specific compliance or data sovereignty requirements, though the trend favors cloud adoption for its ease of updates and integrated intelligence.
In terms of application functionality, core modules such as incident management, configuration management, asset management, and change management form the backbone of ITSM operations. Incident management remains a primary focus, as rapid resolution is key to maintaining business continuity. Configuration and asset management are critical for maintaining an accurate view of the IT environment, while change management ensures that updates and modifications are executed with minimal risk. Additional functional areas continue to evolve, supporting specialized needs within the broader service management framework.
Regional dynamics also play a role in market adoption, with North America leading in market size, followed by Europe and Asia Pacific. Latin America and the Mideast and Africa represent emerging growth areas. Each region presents unique challenges and opportunities regarding regulatory compliance, infrastructure readiness, and vendor presence. Our report details these regional nuances to help global organizations tailor their strategy accordingly.
Competitive Landscape and Strategic Positioning
The competitive landscape is characterized by a mix of established enterprise platforms and agile mid-market solutions. Market concentration is notable, with a significant share held by leading vendors. ServiceNow stands out as a leading enterprise ITSM platform, leveraging an AI-driven autonomous workforce and full ITIL-aligned service management. Recent developments include the launch of the Autonomous Workforce with AI specialists for Level 1 service desk operations and the introduction of Otto as a unified enterprise AI experience. These innovations expand the capabilities for governed autonomous work across systems, setting a high bar for enterprise competitors.
BMC offers BMC Helix ITSM, focusing on AI-enabled proactive service management, change management, and multi-cloud capabilities. Atlassian provides Jira Service Management, which integrates DevOps and unified IT operations within the Atlassian ecosystem, recently releasing updates with portal improvements and asset management enhancements. Ivanti delivers Ivanti Neurons for ITSM, featuring a modern UI, agentic AI, and workflow automation for proactive service delivery, with recent releases enhancing conversational AI frameworks and system-wide summarization.
Freshworks provides Freshservice, an AI-powered ITSM platform tailored for the mid-market with quick deployment and AI assistance. ManageEngine offers ServiceDesk Plus, a unified platform with AI assistant capabilities for SMB and enterprise IT service management. Microsoft integrates ITSM capabilities with Microsoft 365 and Dynamics for seamless enterprise service delivery. Broadcom maintains CA Service Desk Manager for proactive IT service management and automation. Honeywell utilizes ServiceNow-powered ITSM solutions for enterprise-scale operations and compliance in industrial and manufacturing sectors.
Each vendor brings a distinct value proposition, and the choice often depends on existing ecosystem investments, scale requirements, and specific functional needs. Understanding the strengths and recent moves of these key players is vital for making informed procurement decisions.
Comprehensive Report Coverage
This market research report offers an exhaustive analysis of the ITSM software market, designed to equip stakeholders with actionable intelligence. The contents include detailed historical data and forecast figures, enabling precise planning and budgeting. The report dissects the market by type, application, and region, providing clarity on where growth is concentrated without merely listing superficial statistics.
Competitive profiling is a core component, with deep dives into the product offerings, strategic positioning, and recent developments of key market participants. We analyze recent product launches and feature releases to illustrate the direction of innovation. For instance, the integration of autonomous AI workforce capabilities and conversational AI frameworks represents a shift toward proactive rather than reactive service management.
Furthermore, the report contextualizes these findings within broader industry dynamics, including labor cost implications, compliance pressures, infrastructure trends, and pricing models. This holistic view ensures that readers understand not just the numbers, but the forces driving them. The analysis is structured to support strategic planning, vendor selection, and investment justification.
Strategic Implications for 2026 Decision-Makers
For decision-makers in 2026, the implications of these market trends are clear. First, the integration of AI into ITSM is no longer optional for enterprises seeking to optimize costs and improve service quality. Platforms that offer autonomous capabilities and governed workflows provide a distinct advantage in managing the increasing volume of service requests.
Second, compliance and data privacy must be central considerations in vendor selection. With the surge in data subject requests, platforms that offer audit-ready features and robust governance are essential for mitigating risk. Third, the shift toward cloud-based deployment enables greater agility and scalability, aligning ITSM capabilities with modern infrastructure strategies.
IT Service Management (ITSM) Software Market
Finally, understanding the competitive landscape helps organizations avoid vendor lock-in and negotiate better terms. Knowing the strengths of each major player allows for a more tailored fit between organizational needs and platform capabilities. This report serves as a guide to navigate these complexities, ensuring that technology investments align with broader business objectives.
Conclusion
The ITSM software market is poised for continued growth and innovation, driven by technological advancements and evolving operational demands. Organizations that proactively assess their service management strategies and adopt platforms aligned with future trends will be better positioned to succeed. This report provides the comprehensive intelligence needed to make those strategic decisions with confidence. Access the full analysis to gain deep insights into market size, segmentation nuances, competitive dynamics, and actionable recommendations for navigating the ITSM landscape through 2032.
For detailed analysis of this topic, please visit the official page: IT Service Management (ITSM) Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Thyristors Market Hits $1,461M in 2025, Driven by 4.1% CAGR to 2032
By PW Consulting, 2026-09-16
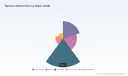
Powering Critical Infrastructure: The Strategic Imperative of the Global Thyristors Market Outlook 2026–2032
In the architecture of modern electricity, few components are as quietly indispensable as the thyristor. From grid stabilization to high-power industrial drives, these semiconductor switches dictate the reliability of systems that societies and economies depend on daily. As we enter 2026, the thyristors market stands at a decisive inflection point, shaped by evolving power demands, supply chain recalibrations, and accelerating deployment in renewable energy and mobility. For executives navigating capital allocation, product roadmaps, and sourcing strategies, the difference between reactive planning and competitive advantage lies in rigorous, forward-looking intelligence.
This insight introduces our latest thyristors market research, a comprehensive study designed to equip decision-makers with the analytical depth required to act confidently across the 2026–2032 forecast horizon. Rather than offering static snapshots, the report translates macroeconomic signals, technology shifts, and competitive maneuvers into actionable strategic frameworks.
Market Trajectory: From Recovery to Sustained Expansion
The global thyristors market has demonstrated consistent growth over the past half-decade, reflecting the ongoing electrification of industrial processes, the modernization of power transmission networks, and the proliferation of power electronics across consumer and automotive applications. Historical data from 2020 through 2025 reveals a market that has steadily expanded, reaching approximately USD 1,461.0 Million in 2025. This trajectory underscores not only demand resilience but also the component's entrenched role in mission-critical power control environments.
Looking ahead, the forecast period from 2026 to 2032 projects a robust expansion pathway, with the market anticipated to reach approximately USD 1,936.5 Million by 2032. This growth corresponds to a compound annual growth rate of 4.1 percent, a pace that signals steady, structurally supported demand rather than a short-lived cyclical spike. The implication for strategic planners is clear: thyristor-enabled solutions are being woven more deeply into long-cycle infrastructure and industrial automation investments, creating multi-year revenue visibility for suppliers and system integrators alike.
Yet, headline figures only tell part of the story. The real strategic value lies in understanding where growth concentrates, which applications drive incremental volume, and how regional dynamics influence sourcing and localization. Our analysis unpacks these layers without oversimplifying them, giving leaders a nuanced map of opportunity rather than a single aggregated number.
What the Research Delivers: Actionable Intelligence for 2026 Decision-Making
Our thyristors market study is structured to address the practical questions that arise in boardrooms, engineering reviews, and procurement discussions. The report provides a multidimensional view of the market, combining quantitative forecasting with qualitative analysis of technology roadmaps, demand catalysts, and competitive positioning. Key areas of coverage include:
- Macro-market sizing and growth projections across the base year and forecast horizon, anchored in a transparent methodology that allows for scenario testing.
- Segment-level analysis by product type, application, and geographic region, illuminating which categories are expanding fastest and why.
- Demand driver assessment covering grid modernization, industrial automation, renewable integration, e-mobility, and power conversion needs.
- Supply-side dynamics, including manufacturing capacity trends, raw material trajectories, lead-time behavior, and cost structure sensitivities.
- Competitive landscape profiling that maps the strategic moves of leading incumbents and emerging challengers across the value chain.
- Technological and regulatory context, highlighting how material availability, wafer economics, and policy shifts affect downstream planning.
The objective is not to overwhelm with data but to distill complexity into decision-ready formats. Executives can use the study to evaluate market entry assumptions, benchmark regional exposure, refine product portfolio priorities, and anticipate supply continuity risks. For procurement and operations leaders, the report surfaces practical indicators that inform contracting, inventory strategy, and supplier diversification.
Competitive Landscape: Establishing Position in a Concentrated Arena
The thyristors market is characterized by a notably concentrated competitive structure, with a small group of established players commanding a substantial share of total revenue. This concentration has important strategic implications. It suggests that scale, technological breadth, application-specific expertise, and long-standing customer relationships remain powerful moats. At the same time, it signals that competitive differentiation increasingly comes from portfolio completeness, performance in extreme operating conditions, and the ability to support specialized end markets.
Leading participants reflect a diverse set of strategic orientations. Some competitors focus on high-power solutions spanning thyristors, GTOs, IGCTs, and diodes, serving grid, traction, renewables, and e-mobility applications with broad current and voltage ranges. Others specialize in bipolar thyristor discs and pulse-power devices manufactured in-house, emphasizing low thermal resistance and high-voltage capability for demanding industrial and pulsed-power environments. Additional players concentrate on mission-critical power modules for aerospace, defense, and space applications, or on discrete SCR and TRIAC devices for motor control, lighting, heating, and general industrial systems.
The field also includes semiconductor manufacturers integrating thyristors and related modules into broader power conversion and automotive portfolios, alongside specialists providing SCR thyristors and AC switches for industrial and consumer power control. Discrete device producers serving alternative energy, lighting, and industrial use cases further round out the landscape, while companies focused on power discrete thyristors and TRIACs address automotive, consumer, and industrial power management needs. Collectively, these players demonstrate that the market is not monolithic; it is a mosaic of overlapping capabilities, each shaped by distinct technological strengths and customer segments.
Importantly, competitive dynamics are not static. Recent developments illustrate how capital commitments and policy support can reshape production capacity and innovation pacing. For example, a significant funding agreement finalized in mid-2026 provides targeted investment to expand domestic manufacturing and R&D for power modules, including thyristors. Such moves matter because they influence regional supply resilience, cost trajectories, and the speed at which new capabilities reach the market. In a concentrated environment, even a single major capacity or R&D announcement can alter bargaining dynamics and competitive expectations across the value chain.
Industry Dynamics: Lead Times, Raw Materials, and Cost Signals
Beyond company-level activity, broader industry dynamics are shaping how organizations plan for 2026 and beyond. One critical factor is lead-time behavior for discrete components. In the second quarter of 2025, lead times for discrete components, including thyristors, held steady or increased slightly, reaching approximately 26 weeks. For sourcing teams and system designers, this is more than a logistical statistic; it affects inventory buffers, project timelines, and the feasibility of just-in-time models in high-reliability applications. The persistence of extended lead times reinforces the importance of supplier collaboration, demand forecasting accuracy, and multi-source strategies where technically feasible.
Worldwide Thyristor Protectors Market
On the materials side, silicon wafer shipments rose 5.4 percent in 2025, with new record shipments forecast for 2028. This trend is supportive for the supply of foundational inputs used in thyristor production, helping to moderate certain cost pressures over the medium term. However, material availability does not automatically translate into stable end-device economics. Upstream costs remain sensitive to node-specific manufacturing economics and specialized wafer pricing. In 2026, advanced-node wafer costs increased by 3 to 10 percent, with 2 nm wafers reaching approximately USD 30,000 per wafer. While thyristor technologies do not uniformly depend on leading-edge nodes, these broader semiconductor cost dynamics influence overall material expense expectations, capital investment decisions, and pricing strategies across the power semiconductor ecosystem.
Together, these dynamics highlight a market where planning must account for both demand-side momentum and supply-side friction. Effective strategy requires a holistic view: aligning product roadmaps with likely lead-time envelopes, evaluating how wafer and material trends affect cost assumptions, and monitoring capital investments that could alter regional supply balances. The report integrates these factors to help leaders stress-test their assumptions under realistic operating conditions.
Strategic Takeaways for 2026 and Beyond
As organizations set priorities for the coming years, several strategic themes emerge from the market landscape:
- Demand durability is anchored in infrastructure and industrial use cases. The thyristors market's growth is closely tied to long-cycle investments in power transmission, industrial automation, and renewable integration. Teams should evaluate how these durable demand streams align with their sales coverage, service capabilities, and product support models.
- Portfolio breadth and application specialization create differentiation. With a concentrated competitive field, firms that can combine high-power capabilities, thermal performance, and application-specific support are better positioned to defend margins and capture complex requirement sets.
- Supply continuity is a strategic variable, not just an operational concern. Lead-time persistence and material cost movements require proactive planning, including scenario-based inventory policies, supplier diversification, and close monitoring of capacity investments.
- Regional context matters for sourcing and market access. Different regions present distinct demand profiles and supply dynamics. Understanding where demand is intensifying and how local production or policy initiatives may evolve can inform market prioritization and risk management.
- Capital and policy developments can shift competitive expectations. Major funding commitments and domestic production expansions can affect cost structures, lead times, and supplier relationships. Keeping pace with such developments helps organizations anticipate changes rather than react to them.
Why This Research Matters Now
The 2026–2032 outlook period is not a routine forecast window; it is a planning horizon in which today's assumptions will shape tomorrow's competitive position. The thyristors market is expanding at a measured but meaningful pace, supported by broad-based application demand and an increasingly strategic view of power electronics across industries. In this environment, theorganizations that excel will be those that pair market awareness with disciplined execution: selecting the right segments, anticipating supply constraints, and aligning product and sourcing strategies with where value is actually created.
Our study is designed to support exactly that kind of decision-making. It offers the analytical rigor required to justify investment choices, the segmentation detail needed to prioritize resources, and the competitive context necessary to understand where pressure points and opportunities lie. Most importantly, it is built to be practical—translating complex market forces into clear implications for product planning, procurement, sales strategy, and risk management.
Thyristors Market
Explore the Full Intelligence
The information summarized here is intended to provide a credible preview of the depth and direction of our research. Many of the most actionable insights—the detailed segmentation values, region- and application-level breakdowns, company-specific strategic assessments, and scenario-based projections—are reserved for the full report. Those details are essential for translating high-level trends into precise operational decisions, and they are available in the complete study.
To access the full thyristors market research, including comprehensive sizing, segmentation analysis, competitive profiles, and forward-looking strategic recommendations for 2026 and beyond, please visit the report page on our website. There you will find the complete dataset and analysis needed to support confident, evidence-based decisions in a market where timing, positioning, and supply awareness matter more than ever.
For detailed analysis of this topic, please visit the official page: Thyristors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Cs Beam and Hydrogen Maser Clocks Market Hits USD 40M in 2025, Projects 6.98% CAGR
By PW Consulting, 2026-09-16
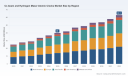
Navigating the Precision Timing Revolution: Strategic Insights into the Cs Beam and Hydrogen Maser Atomic Clocks Market (2026–2032)
In an era where nanosecond precision dictates the reliability of global navigation, telecommunications, financial trading, and critical infrastructure, atomic clock technology has evolved from a specialized scientific instrument into a strategic asset class. The Cs beam and hydrogen maser atomic clocks market stands at a pivotal inflection point as nations, defense contractors, and telecommunications operators confront mounting threats from GNSS disruptions, space-based timing degradation, and escalating cybersecurity vulnerabilities. This comprehensive market intelligence study, anchored in historical performance from 2020 through 2025 and projecting forward to 2032, provides decision-makers with the analytical rigor required to navigate a highly concentrated yet rapidly commercializing landscape. By examining macro trajectory, competitive dynamics, technological substitution patterns, and regulatory catalysts, this report equips strategic planners, procurement leaders, and investment committees with actionable foresight for 2026 and beyond.
Market Trajectory and Structural Foundations
The market has demonstrated consistent expansion over the historical review period, climbing from 25.0 million USD in 2020 to an estimated 40.0 million USD in 2025. This growth trajectory reflects a compound annual growth rate of approximately 6.98 percent across the forecast window extending through 2032, with revenue projections indicating a continued upward arc driven by next-generation timing infrastructure, sovereign GNSS resilience initiatives, and the proliferation of precision-dependent applications in telecommunications and space exploration. The forecast period reveals a market that is scaling steadily rather than experiencing volatile spikes, underscoring the deliberate, engineering-intensive nature of atomic clock deployment and the long lifecycle characteristics of primary reference timing systems. By 2032, total market revenue is expected to surpass 60 million USD, illustrating sustained institutional and commercial demand for frequency standards that deliver unparalleled long-term stability and traceability to international timekeeping frameworks.
Several structural factors underpin this expansion. First, the growing deployment of optical cesium beam architectures and enhanced hydrogen maser platforms is broadening the addressable market beyond traditional national metrology laboratories and defense enterprises into commercial data centers, power grid synchronization networks, and next-generation telecommunications infrastructure. Second, the industry’s shift toward sovereign timing capabilities has accelerated procurement cycles, as governments and critical infrastructure operators seek to reduce reliance on vulnerable satellite-based timing signals. Third, the maturation of manufacturing ecosystems and the establishment of dedicated production lines for high-performance hydrogen masers are gradually improving supply chain reliability, reducing lead times, and expanding the commercial viability of these precision instruments. Together, these drivers create a durable growth foundation that strategic stakeholders can leverage to align product roadmaps, capacity planning, and partnership strategies.
Competitive Landscape and Strategic Positioning
The market exhibits a moderate-to-high concentration profile, with the top three participants collectively commanding a significant share of total revenue and the top five firms accounting for approximately half of the overall market. This concentration reflects the capital-intensive nature of precision timing research, the stringent certification requirements associated with primary frequency standards, and the long-standing intellectual property positions held by established players. However, the competitive environment is not static. Recent corporate developments underscore a sharp focus on manufacturing scalability, product diversification, and strategic deployment of atomic clock systems in high-stakes operational contexts.
- Microchip Technology Inc., headquartered in Chandler, Arizona, continues to reinforce its leadership in cesium beam frequency standards and active hydrogen maser solutions. The company’s MHM-2020 active hydrogen maser and 5071B cesium beam frequency standard have become reference architectures for metrology, telecommunications, and satellite applications requiring accuracies at the 5×10⁻¹³ level. In April 2026, the company inaugurated a new manufacturing facility in Tuscaloosa, Alabama, purpose-built to expand MHM-2020 production capacity, reduce delivery lead times, and address rising demand for independent timing systems in national infrastructure protection programs.
- Oscilloquartz SA, based in Neuchâtel, Switzerland, has extended its footprint through the OSA 3230 series of optical cesium beam atomic clocks and hydrogen maser solutions engineered for enhanced short-term stability via its ESTU module. The firm serves telecommunications, defense, and precision timing customers seeking compact, high-reliability architectures that bridge the performance gap between legacy cesium systems and premium hydrogen masers.
- Safran Electronics & Defense, operating from Paris, France, has emerged as a decisive player in spaceborne and ground-based atomic clock deployments. The Space Hydrogen Maser (SHM) powered the ESA ACES atomic clock ensemble aboard the International Space Station, achieving record stability for global timekeeping and deep-space applications. In September 2025, an all-European maser active hydrogen maser was deployed at the ESA New Norcia deep-space ground station in Australia, marking the first fully European ultra-precise maser operation for interplanetary missions and signaling a broader push toward sovereign timing sovereignty in deep-space communications.
- Adtran Inc., headquartered in Huntsville, Alabama, has strengthened its positioning through the integration of Oscilloquartz optical cesium beam clocks with ESTU modules, delivering hydrogen-maser-comparable short-term stability for data centers, power utilities, and defense PNT (positioning, navigation, and timing) applications. In June 2025, Adtran launched the Oscilloquartz OSA 3200 SP and OSA 3250 enhanced primary reference clocks, cost-effective optical cesium beam solutions with a 10-year lifespan and improved holdover capabilities designed to support telecom and infrastructure modernization efforts.
These developments reflect a competitive environment characterized by parallel strategies: vertical expansion into dedicated manufacturing capacity, cross-company technology integration, space mission validation, and product launches targeting cost-sensitive yet performance-critical segments. For buyers and partners, this landscape presents both consolidation opportunities and fragmentation risks. Organizations that map the competitive dynamics with precision can anticipate supply shifts, evaluate vendor lock-in exposure, and identify collaborative pathways that align with long-term timing resilience objectives.
Industry Dynamics: Regulation, Certification, and Technological Substitution
The market’s trajectory is increasingly shaped by regulatory milestones, standardization activities, and certification events that redefine performance benchmarks and procurement criteria. A notable catalyst occurred in April 2025, when the National Institute of Standards and Technology certified the NIST-F4 cesium fountain atomic clock as the new U.S. primary frequency standard, calibrated against hydrogen masers to improve UTC traceability and metrology applications. This certification effectively signals the transition away from legacy HP 5071A models in national metrology laboratories and establishes a new reference baseline that influences downstream procurement specifications across government and commercial sectors.
Simultaneously, the ESA ACES mission’s selection of Safran’s Space Hydrogen Maser in April 2025 underscores the strategic importance of exceptional short-term frequency stability for spaceborne applications. The deployment of an all-European maser active hydrogen maser at the New Norcia deep-space ground station in September 2025 further illustrates how certification and mission validation are converging to support sovereign deep-space tracking and GNSS resilience. These events are not isolated achievements; they represent structural shifts in how timing infrastructure is evaluated, deployed, and protected against environmental and geopolitical disruptions.
On the commercial side, Adtran’s June 2025 launch of Oscilloquartz optical cesium beam clocks with ESTU modules demonstrates a deliberate push to deliver hydrogen-maser-comparable short-term stability for Western defense and telecom PNT systems at a more accessible cost profile. This product evolution reflects a broader industry dynamic: the compression of performance gaps between cesium beam and hydrogen maser technologies, driven by module-level enhancements, improved holdover characteristics, and extended operational lifespans. As these dynamics mature, procurement teams must reassess the traditional dichotomy between cost and stability, particularly when evaluating deployment scenarios that demand rapid recovery from signal loss, long-duration holdover, or stringent synchronization tolerances.
Cs beam and Hydrogen Maser Atomic Clocks Market
What This Research Delivers: Operational Intelligence for 2026 Decision-Making
This market research study is designed as a decision-support toolkit rather than a static data summary. It provides a multi-layered examination of the Cs beam and hydrogen maser atomic clocks market, translating complex technical, commercial, and regulatory interdependencies into structured intelligence that can be operationalized across strategy, procurement, R&D, and investment functions. The report integrates historical performance data, forecast modeling, segment-level analysis, and competitive profiling to deliver a comprehensive view of market directionality and actionable differentiation points.
Core Analytical Components
- Macro market sizing and forecast modeling that contextualizes historical growth from 2020 through 2025 and projects revenue expansion through 2032, enabling scenario-based planning for capacity allocation, investment prioritization, and demand forecasting.
- Segment-level evaluation across technology types and regional markets, offering insight into how cesium beam and hydrogen maser architectures are positioned relative to one another, where adoption momentum is concentrating, and which demand drivers are most influential in shaping procurement strategies.
- Competitive profiling of incumbent and emerging participants, including corporate headquarters, product portfolios, accuracy and stability specifications, application footprints, and recent strategic developments that signal shifts in manufacturing scale, technology roadmaps, and market emphasis.
- Regulatory, certification, and standardization tracking that maps the impact of metrology lab transitions, space mission deployments, ground station operations, and product certifications on downstream procurement requirements and vendor qualification criteria.
- Market concentration and structural analysis that evaluates the implications of top-three and top-five share distribution for pricing dynamics, supply chain resilience, and partnership opportunities in a market where incumbency and certification heritage carry significant weight.
- Application-driven demand assessment that connects timing performance requirements to end-use environments—including telecommunications synchronization, defense PNT resilience, power grid stability, data center infrastructure, satellite operations, and deep-space communications—enabling stakeholders to align product strategy with real-world operational constraints.
Each component is constructed to support practical decision-making. Procurement leaders can use the segmentation and competitive profiling modules to evaluate supplier qualification criteria, benchmark performance specifications, and anticipate supply continuity risks. R&D and product management teams can leverage the regulatory and certification tracking sections to align development roadmaps with evolving metrology standards and space mission validation pathways. Strategy and corporate development functions can draw on the concentration analysis, regional demand signals, and technology substitution dynamics to identify partnership targets, geographic expansion priorities, and investment allocation frameworks.
Strategic Imperatives for 2026 and Beyond
As the market advances toward 2032, several strategic imperatives emerge for organizations operating within or adjacent to the precision timing ecosystem. First, sovereign timing resilience is transitioning from a policy aspiration to an operational requirement, and organizations that proactively align their timing infrastructure with independent, high-stability atomic clock solutions will be better positioned to mitigate GNSS disruption risks and comply with evolving national security and critical infrastructure mandates. Second, the convergence of optical cesium beam enhancements and hydrogen maser performance characteristics is reshaping the value proposition across price-performance tiers, requiring buyers and suppliers alike to reassess specification thresholds, total cost of ownership, and lifecycle support commitments. Third, manufacturing capacity expansions and dedicated production lines are gradually improving supply reliability, but lead time management, component sourcing, and qualification lead times remain critical considerations for deployment planning.
Fourth, space mission validation and deep-space ground station deployments are establishing new reference points for performance and reliability, creating pull-through effects that influence terrestrial procurement specifications and vendor evaluation criteria. Fifth, market concentration implies that strategic partnerships, long-term supply agreements, and dual-sourcing strategies may be necessary to balance performance requirements with supply chain resilience. Organizations that integrate these imperatives into their planning cycles will be better equipped to navigate a market that rewards technical precision, regulatory alignment, and strategic foresight in equal measure.
Conclusion: From Insight to Action
The Cs beam and hydrogen maser atomic clocks market is defined by its technical rigor, its growing strategic importance, and its steady expansion from specialized metrology and defense applications into broader commercial and infrastructure domains. The historical performance from 2020 through 2025 establishes a credible growth baseline, while the forecast through 2032 signals a market that continues to scale in response to sovereign timing initiatives, space mission deployments, telecommunications modernization, and critical infrastructure synchronization requirements. Competitive dynamics remain shaped by incumbency, certification heritage, and manufacturing scale, yet recent facility expansions, product launches, and mission validations demonstrate that the landscape is actively evolving.
For executives, procurement leaders, and strategic planners, the imperative is clear: precision timing is no longer a backend technical consideration but a front-line resilience priority. This market research study provides the structured intelligence required to translate that priority into informed decisions—whether those decisions involve vendor selection, technology roadmap alignment, geographic demand assessment, or investment prioritization. To access the full segmentation analysis, regional demand breakdowns, detailed competitive profiles, and forecast scenario modeling that underpin these strategic conclusions, stakeholders are invited to explore the complete report on our platform, where the complete intelligence is available to support your 2026 planning cycle and beyond.
Rubidium Atomic Clock Market
For detailed analysis of this topic, please visit the official page: Cs beam and Hydrogen Maser Atomic Clocks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Serial Device Server Market to Reach $317.3M by 2032 at 6.5% CAGR
By PW Consulting, 2026-09-16
Beyond Connectivity: Unlocking Strategic Value in the Serial Device Server Market (2026–2032)
The Critical Infrastructure Layer in a Legacy-Heavy World
Serial device servers sit at the intersection of legacy industrial hardware and modern IP networks—a position that makes them indispensable for enterprises managing brownfield automation, remote telemetry, and multi-vendor equipment integration. As industries accelerate their transition toward secure, centralized, and cloud-ready architectures, the devices that bridge RS-232, RS-422, and RS-485 endpoints to Ethernet and Wi-Fi backbones are experiencing sustained demand. Our newly released Serial Device Server Market research provides a comprehensive commercial and technical intelligence layer designed to inform capital allocation, product roadmap decisions, and competitive positioning through 2032.
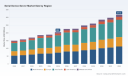
The market’s trajectory reflects a structural shift rather than a temporary cycle. Revenue reached an estimated 205.0 million USD in the base year of 2025, up from approximately 188.99 million USD in 2024 and 185.99 million USD in 2023, following a consistent upward path from 150.0 million USD in 2020. This growth curve underscores the durability of serial-to-Ethernet conversion in industrial control, data acquisition, remote management, and point-of-sale ecosystems, even as IT departments invest heavily in all-IP alternatives. The forecast period from 2026 to 2032 projects a compound annual growth rate of 6.5 percent, with total revenue anticipated to rise from roughly 225.84 million USD in 2026 to 317.3 million USD by 2032. These figures are not merely projections—they form the foundation for capacity planning, vendor negotiation, and risk-adjusted investment strategies.
For decision-makers navigating procurement cycles, product development, or market entry, this research delivers what high-level summaries cannot: a granular view of demand drivers, technology migration patterns, regulatory touchpoints, and the competitive behaviors shaping pricing, feature sets, and channel influence. The analysis is deliberately structured to support executive-level prioritization while preserving the depth required by engineering, supply chain, and regulatory teams.
Structural Demand Drivers: Why Serial Device Servers Remain Strategically Resilient
A central theme emerging from our analysis is the persistence of serial protocols in environments where reliability, determinism, and cost-effective interoperability outweigh the pull of full IP replacement. Industrial control systems, data acquisition networks, remote management deployments, and point-of-service infrastructure all rely on serial interfaces for legacy compatibility, field-hardened performance, and simplified wiring topologies. Rather than displacing these devices, modernization initiatives are increasing their strategic value by demanding secure gateways, centralized fleet management, and protocol-agnostic bridging.
Several dynamics are reinforcing this demand profile. First, the coexistence of operational technology and information technology stacks means that serial endpoints must be integrated into network architectures without disrupting uptime or requiring wholesale equipment replacement. Second, security expectations have evolved from basic connectivity to encrypted serial-to-IP tunnels, centralized authentication, and audit-ready management interfaces. Third, environmental and transportation-grade certifications are becoming gating factors in bidding processes for public infrastructure, manufacturing automation, and outdoor telemetry deployments. These factors collectively elevate the serial device server from a simple connectivity add-on to a programmable gateway component within broader edge networks.
The research also examines how network infrastructure economics influence deployment velocity. Ethernet interface cards and fiber-optic infrastructure remain primary cost drivers in serial device server network deployments, which means total cost of ownership is shaped not only by the gateway hardware itself, but by the surrounding physical layer, cabling, and integration labor. This reality has important implications for procurement strategy, vendor bundling, and the evaluation of modular platforms such as SFP-based hot-swappable designs that can delay or reduce physical-layer reinvestment.
Market Size, Growth Trajectory, and What the Numbers Really Signal
The macro-level trajectory provides a reliable anchor for strategic planning. After expanding from 158.23 million USD in 2021 and 170.18 million USD in 2022, the market crossed the 185 million USD threshold in 2023 and continued its ascent to 205.0 million USD in 2025. The short-term forecast indicates 225.84 million USD in 2026, followed by a slight moderation in year-over-year momentum before resuming steady growth to 227.25 million USD in 2027, 248.41 million USD in 2028, 260.47 million USD in 2029, 285.73 million USD in 2030, 298.04 million USD in 2031, and 317.3 million USD in 2032.
For strategy teams, the more important takeaway is the shape of this curve. The data suggests a market that is not only growing but maturing in its demand patterns: growth is increasingly tied to secure management, ruggedized industrial form factors, modular network compatibility, and certification readiness. Companies that treat serial device servers as commoditized pass-through hardware risk underpricing value-added features and missing higher-margin opportunities in industrial automation, remote fleet management, and hazardous-location deployments. Conversely, organizations that align product roadmaps with the specific integration requirements of brownfield environments can capture disproportionate share in segments where interoperability and compliance create meaningful barriers to substitution.
Our research deliberately avoids oversimplified regional or application-level breakdowns in this overview because the strategic value lies in how those segments interact with pricing, certification requirements, and channel dynamics. The full report details how demand clusters across geographies and application types, which subsegments are growing fastest in absolute and relative terms, and where saturation risk or substitution pressure is most likely to emerge.
Competitive Landscape: Differentiated Platforms in a Concentrated Environment
Market concentration provides an early signal of competitive intensity. The three largest players account for approximately 52.8 percent of revenue, while the five largest reach about 64.7 percent. This distribution indicates a market with established incumbents, meaningful product differentiation, and room for specialized challengers that compete on security, ruggedization, or form-factor innovation. Understanding how the leading vendors position their offerings is essential for both competitive benchmarking and partnership evaluation.
Pepperl+Fuchs, headquartered in Mannheim, Germany, emphasizes serial device server solutions aimed at industrial automation and transportation integration. Its ICDM-RX/TCP series delivers DIN-rail mounted RS-232/422/485 to Ethernet conversion with TCP/UDP socket services, and the inclusion of NEMA TS2 certification options expands its relevance for transportation-grade and industrial Ethernet environments. A product update in August 2025 extended this family with additional NEMA TS2 certification options, reinforcing the company’s focus on compliance-sensitive deployments.
Comtrol, operating as Pepperl+Fuchs Comtrol with headquarters in Twinsburg, Ohio, USA, focuses on secure serial-to-IP gateways. The DeviceMaster PRO/RTS/Serial Hub family supports COM/TTY/TCP configurations and has been strengthened with enhanced SSL/SSH encryption. In March 2025, the company updated the series with SSL/SSH management and serial data stream encryption for secure serial-to-IP connectivity, a move that reflects rising security expectations in industrial and enterprise edge contexts.
Digi International, based in Minneapolis, Minnesota, USA, continues to position its Digi Connect EZ TS and Connect SP series as secure serial device servers for legacy-to-IP conversion. The portfolio’s RealPort drivers and centralized management capabilities support organizations seeking to standardize remote access and device administration across distributed installations. In May 2026, Digi launched Digi Connect EZ TS 4-port and 8-port secure serial device servers with enhanced centralized management for modern IP network transitions, signaling continued investment in fleet management and migration-friendly architectures.
Moxa, headquartered in Taipei, Taiwan, targets industrial RS-232/422/485 to Ethernet conversion with the NPort 5100/5110 and IA5000 series. These platforms emphasize surge protection and hazardous-location certifications, making them relevant for demanding field environments. A February 2025 update improved the NPort IA5000-G2 DIN-rail and IA5000A industrial series with enhanced surge protection for hazardous environments, reinforcing Moxa’s focus on durability and compliance in industrial settings.
Advantech, also based in Taipei, Taiwan, offers the EKI-1521/1522/1524 series of industrial Ethernet/serial device servers with virtual COM support and LAN redundancy. This positioning speaks to customers who prioritize operational resilience, seamless device emulation, and network failover in automation and control environments.
Patton, headquartered in Gaithersburg, Maryland, USA, introduced a notable infrastructure-oriented product in April 2025 with the launch of the Connect-IT CIT-SFP SFP-based hot-swappable RS-232/422/485 serial device server for legacy-to-IP bridging. The SFP-based approach addresses network flexibility and physical-layer economics by enabling modular fiber or copper connectivity without full hardware replacement, an increasingly important consideration as deployment costs are scrutinized.
Silex Technology, based in Tokyo, Japan, provides the SD-300/SD-320 series of wired and wireless RS-232 serial device servers for Ethernet and Wi-Fi network connectivity. This wireless extension broadens the addressable use cases for serial endpoints where cabling constraints or temporary deployments make Wi-Fi connectivity advantageous.
Sealevel Systems, headquartered in Liberty, South Carolina, USA, focuses on the SeaLINK series of Ethernet serial servers supporting up to 16 RS-232/422/485 ports for industrial data acquisition and control systems. The multi-port architecture is particularly relevant for centralized monitoring and control applications that must aggregate many serial endpoints without proliferating gateway devices.
PLANET Technology, also headquartered in Taipei, Taiwan, offers the ICS-2100T/2200T/2400T series of industrial 1/2/4-port RS-232/422/485 to Fast Ethernet serial device servers with wide-temperature operation. This wide-temperature capability supports deployment in environments where thermal extremes would disqualify commercial-grade hardware.
The competitive picture is not just about product portfolios; it is about how vendors translate certification readiness, security, modularity, and environmental hardening into defensible pricing and customer lock-in. The research maps these positioning strategies and identifies the operational implications for buyers evaluating total cost of ownership, support requirements, and lifecycle compatibility.
Regulatory, Certification, and Deployment Dynamics That Shape Commercial Outcomes
Regulations and certifications are not side conditions; they are commercial gating factors that influence bid eligibility, deployment timelines, and regional expansion feasibility. In the United States, all active manufacturers of serial device server products must comply with FCC Part 15 rules for unintentional radiators to prevent harmful interference, a requirement that can affect design choices, testing cycles, and market entry sequencing. In the European Economic Area, serial device server equipment sold into the market requires CE marking under relevant EMC and safety directives, adding conformity assessment obligations that influence product planning and documentation.
Serial Device Server Market
Safety and industrial-use certifications further shape procurement and engineering decisions. Industrial serial device server models are commonly UL 61010-1 listed for safety in laboratory and industrial use, an assurance that matters in environments where equipment must meet recognized electrical safety standards. For transportation and public infrastructure applications, NEMA TS2 certification addresses spectrum and environmental compliance requirements, making it a strategic differentiator for vendors pursuing bids in transit and municipal deployments.
Together, these regulatory and certification layers contribute to a market in which product compliance is a source of competitive advantage rather than a back-office task. The report integrates these dynamics into the broader analysis of market behavior, showing how certification roadmaps, testing lead times, and regional conformity requirements interact with product launches, distributor selection, and customer segment prioritization.
What the Report Delivers: Operational Intelligence for 2026 Decisions
This research is designed as a decision-support instrument rather than a static market summary. It combines market sizing and growth projections with actionable qualitative analysis across segmentation, competitive behavior, and deployment dynamics. The core deliverable includes a structured assessment of external and embedded serial device server categories, an exploration of application-side demand patterns across industrial control systems, data acquisition, remote management, point-of-sale systems, and other use cases, and a detailed view of regional demand distribution without reducing the analysis to simplistic percentage tables.
Beyond segmentation, the report examines product evolution patterns, including secure serial-to-IP gateways, DIN-rail industrial form factors, multi-port aggregation platforms, SFP-based hot-swappable bridging, wide-temperature operation, surge protection for hazardous environments, and wireless serial connectivity. It also addresses the commercial significance of centralized management, virtual COM compatibility, LAN redundancy, RealPort-style driver ecosystems, and encryption frameworks such as SSL/SSH. These feature dimensions are analyzed in relation to pricing architecture, differentiation potential, and customer acceptance in regulation-sensitive or environment-sensitive deployments.
Competitive analysis extends beyond product descriptions to include launch timing, update cadence, and strategic intent. Recent developments illustrate how the market is evolving: Patton’s April 2025 launch of the CIT-SFP SFP-based hot-swappable serial device server for legacy-to-IP bridging; Digi International’s May 2026 launch of Digi Connect EZ TS 4-port and 8-port secure serial device servers with enhanced centralized management; Comtrol’s March 2025 update to the DeviceMaster PRO/RTS series with SSL/SSH management and serial data stream encryption; Pepperl+Fuchs’ August 2025 extension of the ICDM-RX/TCP family with NEMA TS2 certification options; and Moxa’s February 2025 update to the NPort IA5000-G2 and IA5000A series with enhanced surge protection for hazardous environments. These events are not isolated product news; they reflect broader strategic bets on security, modularity, ruggedization, and compliance-enabled market access.
How to Use This Research for 2026 Planning
For executives and analysts, the report offers a practical framework for several high-stakes decisions. Procurement leaders can use the segmentation and competitive analysis to structure vendor evaluations around security, management, ruggedization, and certification readiness rather than unit price alone. Product and engineering teams can reference the technology migration patterns to prioritize virtual COM, centralized management, encryption, and modular network compatibility in roadmaps. Business development teams can identify where certification requirements and environmental hardening create entry barriers that protect incumbents or where wireless and multi-port platforms open new addressability. Risk and compliance teams can integrate FCC Part 15, CE marking, UL 61010-1, and NEMA TS2 considerations into market-entry and sourcing plans with a clearer view of lead times and documentation requirements.
The analysis also supports scenario planning by connecting market growth, concentration levels, and infrastructure cost realities to potential shifts in pricing, bundling, and channel influence. Because Ethernet interface cards and fiber-optic infrastructure remain primary cost drivers in network deployments, total project economics often depend on how serial device server platforms align with existing or planned physical-layer investments. The report provides the context needed to evaluate whether modular, hot-swappable, or multi-port solutions offer better lifecycle economics in specific deployment profiles.
Conclusion: From Market Data to Decision Advantage
The Serial Device Server Market is growing within a 6.5 percent CAGR framework and is projected to move from 225.84 million USD in 2026 to 317.3 million USD by 2032, but the strategic opportunity lies in understanding why that growth is happening, where value is being captured, and how competitive and regulatory forces shape customer choices. This research translates those dynamics into an actionable intelligence base for procurement, product strategy, market entry, and competitive positioning.
SerDes Market
The overview above establishes the analytical direction and the breadth of coverage, while the full report provides the structured detail required to support discrete decisions across regions, applications, product types, and competitive scenarios. For teams preparing for 2026 planning cycles, the complete analysis offers the missing layer between high-level market narratives and operational execution—enabling more confident capital allocation, vendor selection, and roadmap prioritization in a market where connectivity, compliance, and industrial reliability all converge.
For detailed analysis of this topic, please visit the official page: Serial Device Server Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Home Security Market Hits $67M in 2025, Projects 8.92% CAGR Growth Through 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Modern Defender: Inside the 2026 Home Security Market
The residential security landscape has fundamentally shifted. Where once the market was defined by simple alarm panels and reactive monitoring, it is now a complex ecosystem of AI-driven surveillance, interconnected smart home automation, and nuanced consumer preferences between professional installation and do-it-yourself flexibility. For executives, investors, and strategic planners, navigating this evolution requires more than surface-level observation. It demands rigorous, data-backed intelligence that connects historical momentum with forward-looking forecasting. Our newly released Home Security Market research report provides exactly that blueprint, offering a comprehensive lens into the forces shaping the industry from 2026 through 2032.
This analysis is not merely a collection of figures. It is a strategic decision-making framework designed to help organizations anticipate demand shifts, evaluate competitive positioning, and allocate capital with precision. By synthesizing historical performance data with projected growth trajectories, the report equips stakeholders with the contextual depth required to operate confidently in an increasingly automated and regulation-sensitive market.
A Market in Structured Expansion
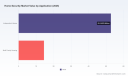
Over the past five years, the home security sector has demonstrated consistent, compounding growth. Historical revenue data from 2020 through 2025 reveals a steady upward trajectory, with the market expanding from a baseline of 42.36 million USD to a projected 67.32 million USD by the close of 2025. This growth reflects sustained consumer investment in residential protection, driven by rising urbanization, increased connectivity, and a broader cultural shift toward proactive home management.
Looking ahead, the forecast period from 2026 to 2032 indicates that this momentum will not only continue but accelerate in strategic pockets. The market is projected to reach 73.17 million USD in 2026, with annual figures climbing steadily toward a projected 122.8 million USD by 2032. Underlying this expansion is a compound annual growth rate of 8.92%, a metric that signals durable, long-term demand rather than cyclical volatility. For corporate strategists, this growth curve translates into clear implications: sustained product development cycles, expanding go-to-market opportunities, and the necessity of agile infrastructure planning to accommodate scaling consumer adoption.
Structural Composition and Application Realities
Beneath the aggregate growth figures lies a layered segmentation structure that defines how value is distributed across the market. Hardware-centric categories continue to anchor the industry, with cameras and monitoring systems representing the largest share of market activity. This dominance is logical, as visual verification remains the cornerstone of modern threat detection and consumer confidence. Alarms and sensors form the second major pillar, providing the foundational layer of intrusion detection and environmental monitoring that complements camera networks. A smaller but strategically significant segment is occupied by locks and access control, a category whose relevance is expanding as smart entry solutions integrate seamlessly with broader residential automation ecosystems.
On the application side, the market reflects distinct residential deployment patterns. Independent homes continue to represent the primary adoption channel, capturing the majority of system installations and upgrade cycles. Multi-family housing constitutes a meaningful secondary segment, driven by property management requirements, centralized monitoring demands, and the growing emphasis on tenant safety in dense urban environments. Understanding how these application dynamics interact with regional deployment realities and pricing sensitivities is essential for any organization designing targeted product bundles or channel strategies.
While the structural outline is clear, the precise allocation of market share across regions, product types, and end-use applications contains critical nuance that can only be fully leveraged through the complete dataset. The report's detailed segmentation breakdowns reveal the exact magnitude of regional performance, the proportional weight of each product category, and the application-level demand patterns that inform inventory planning, pricing architecture, and geographic expansion priorities. These granular insights are deliberately reserved for the full publication, ensuring that stakeholders who require actionable precision have a direct pathway to the complete intelligence.
Competitive Architecture and Strategic Positioning
The home security market is characterized by a concentrated competitive landscape, with the top three firms accounting for approximately 62 percent of total market share and the top five firms collectively commanding roughly 72 percent. This concentration underscores the strategic importance of differentiation, technological innovation, and service integration in maintaining or expanding market position. The leading participants operate across a spectrum of business models, ranging from professionally installed, fully monitored residential systems to flexible, consumer-centric DIY platforms that emphasize no-contract flexibility and wireless deployment.
ADT, headquartered in Florham Park, New Jersey, continues to lean into professional monitoring, professional installation, and AI-powered smart home security systems. Its market approach emphasizes end-to-end service delivery and continuous enhancement of intelligent detection capabilities. Vivint, based in Lehi, Utah, competes through professionally installed, fully integrated smart home security and automation systems paired with ongoing monitoring, positioning itself at the intersection of security and holistic home automation. Ring LLC, operating from San Jose, California, has carved a distinct niche with video doorbells, cameras, and AI-powered alarm systems that serve both DIY users and customers seeking professional monitoring options.
SimpliSafe, headquartered in Boston, Massachusetts, has built its identity around DIY wireless security systems with professional monitoring options and no-contract plans, appealing directly to consumers who prioritize flexibility and uncomplicated deployment. Alarm.com, based in Reston, Virginia, operates as a platform and software backbone for professional monitoring, video security, and integrated alarm systems, enabling a broad ecosystem of service providers and residential deployments. Brinks Home Security, located in Scottsdale, Arizona, delivers professional home security systems with monitoring and smart home integrations, reinforcing the traditional service-led model with modern connectivity features.
Further down the competitive field, Abode Systems in San Francisco focuses on wireless DIY smart home security systems with Apple Home integration, catering to users embedded in specific smart ecosystem environments. Eufy Security, based in San Diego, California, emphasizes battery-powered AI cameras, doorbells, and all-in-one security kits, targeting consumers who value portability, low-maintenance hardware, and integrated detection intelligence. Johnson Controls, headquartered in San Antonio, Texas, brings institutional-grade engineering to the residential space through upgraded security panels and integrated residential systems with monitoring, bridging commercial-grade reliability with home-use scalability.
Recent Developments Shaping Market Trajectory
The strategic posture of these market participants is actively evolving, and several high-impact developments from early 2026 illustrate how quickly the competitive battlefield is shifting. In February 2026, ADT acquired Origin AI to expand its smart home capabilities, leveraging AI-based Wi-Fi sensing technology that detects motion without cameras or wearables. This move signals a clear strategic intent to diversify detection modalities, reduce hardware dependency, and embed intelligence into the ambient environment of the home.
Home Security Market
Alarm.com executed a series of platform-level enhancements in the first quarter of 2026. In March, the company expanded its video security portfolio with new AI capabilities and flexible camera solutions, broadening its addressable use cases for professional installers and end users alike. Earlier in April, Alarm.com modernized legacy security systems by introducing an enhanced Universal Communicator designed to improve interoperability across heterogeneous device ecosystems. These initiatives reflect a broader industry theme: the transition from isolated, single-point installations toward unified, interoperable platforms that simplify monitoring, reduce integration friction, and increase system lifespan.
Johnson Controls reinforced its residential and small business security positioning in March 2026 by launching upgrades to its DSC PowerSeries Neo 5 and IQ Panel 5 systems, demonstrating continued investment in panel modernization and user interface refinement. Meanwhile, Ring LLC expanded its consumer hardware lineup in March with a new battery-powered smart doorbell series featuring 2K and 4K video models, highlighting the ongoing demand for high-resolution, wire-free entry-point monitoring. Collectively, these actions reveal a market in which incumbents and specialists alike are racing to enhance detection sophistication, improve deployment flexibility, and extend the functional boundaries of residential security.
Infrastructure, Regulation, and the Broader Operating Environment
Strategic planning in home security cannot occur in isolation from the external conditions that shape deployment economics and regulatory compliance. Infrastructure dynamics are exerting measurable pressure on expansion models. Recent assessments indicate that deployment costs for fiber-to-the-home networks have increased by more than 10 percent, driven by rising materials and labor expenses. With operation and maintenance averaging around 53 USD annually per home passed, connectivity-dependent security solutions must account for escalating back-end cost structures when evaluating service scalability, monitoring reliability, and long-term pricing assumptions.
Regulatory context adds another layer of strategic complexity. Recent judicial and administrative developments have reshaped the broadband classification debate, with a 2025 appellate ruling holding that the FCC lacks authority to classify broadband as a telecommunications service under Title II. This legal landscape intersects with earlier regulatory actions, including the April 2024 FCC vote on service reclassification, and carries implications for how connectivity-dependent security products, cloud-based monitoring, and video transmission services are governed, priced, and delivered. In parallel, global data transmission realities remain heavily reliant on subsea fiber-optic infrastructure, which carries an overwhelming share of intercontinental and transoceanic digital communications. These structural dependencies remind market participants that residential security is increasingly intertwined with the resilience, latency, and regulatory status of broader communication networks.
These environmental factors do not simply represent background noise. They influence vendor selection, monitoring architecture, consumer adoption thresholds, and the cost profile of networked security solutions. The full report integrates these dynamics into actionable scenarios, helping decision-makers model how infrastructure cost shifts and regulatory uncertainty could affect product roadmaps, channel economics, and service-level commitments over the forecast horizon.
What the Full Report Delivers for Enterprise Decision-Makers
This market study is structured to move beyond high-level trends and into the operational detail that executives, product leaders, and investment teams require. The complete report delivers a multi-dimensional view of the home security market, combining quantitative forecasting with qualitative competitive assessment and environmental context. It provides the analytical foundation needed to answer pressing strategic questions: which deployment models are gaining traction, how intelligent detection capabilities are reshaping consumer expectations, where regional demand intensity is concentrated, and how leading players are positioning their portfolios against one another.
The publication includes detailed segmentation analysis, historical and projected revenue trajectories, competitive profiling, recent corporate and product developments, and a structured examination of the regulatory and infrastructure variables that influence market execution. Each section is designed to support specific decision functions, from product roadmap prioritization and channel strategy refinement to M&A screening and market entry evaluation. By connecting macro-level growth signals with micro-level competitive intelligence, the report offers a single, coherent reference point for organizations operating across the residential security value chain.
For strategists who need precise regional performance figures, exact product-type valuations, and granular application-level breakdowns to inform investment committees or executive briefings, the full dataset is essential. These detailed splits are compiled within the complete report and are intended to provide the specificity required for scenario modeling, pricing strategy, and targeted geographic expansion planning.
Strategic Next Steps
The home security market is entering a phase in which growth, technology integration, and external operating conditions will increasingly determine which organizations capture durable share and which are left reacting to market shifts. With a projected compound annual growth rate of 8.92 percent and a clear trajectory toward sustained expansion through 2032, the opportunity landscape is substantial, but it will be captured by those who plan with precision.
Smart Home Security System Market
Our full Home Security Market research report is now available for leaders who require complete intelligence rather than summary-level conclusions. It provides the detailed segmentation, competitive profiling, and environmental analysis needed to convert market momentum into executable strategy. For decision-makers ready to move from observation to action, the complete report offers the depth, clarity, and strategic framing necessary to navigate one of the most dynamic residential technology sectors in the current market environment.
For detailed analysis of this topic, please visit the official page: Home Security Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DDoS Protection Market Hits $2.15B in 2025, Projects 13.83% CAGR to $5.38B by 2032
By PW Consulting, 2026-09-07
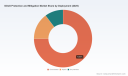
Strategic Imperatives in the 2026 DDoS Protection and Mitigation Landscape
Executive Overview
The cybersecurity ecosystem in 2026 is defined by a relentless arms race between defenders and adversaries. As digital transformation accelerates across every industry sector, the surface area for attack expands in parallel. Among the most persistent and disruptive threats facing Chief Information Security Officers today is the Distributed Denial of Service (DDoS) attack. What was once considered a nuisance has evolved into a sophisticated instrument of geopolitical coercion, extortion, and competitive sabotage. PW Consulting presents this comprehensive market research to dissect the economic and technological architecture of DDoS Protection and Mitigation, offering enterprise leaders the intelligence required to navigate a high-stakes environment.
Mini LED Vehicle Display Market
This analysis serves not merely as a snapshot of current expenditures but as a strategic roadmap for the forecast period spanning 2026 through 2032. By understanding the trajectory of capital allocation, technology adoption, and competitive maneuvering, organizations can transform their security posture from reactive survival to proactive resilience. The following insights distill the core findings of our latest study, highlighting the macroeconomic drivers, the shifting competitive dynamics, and the operational considerations that will define success in this domain.
TFT Liquid Crystal Materials Market
Market Trajectory and Financial Performance
The VDDOS Protection and Mitigation market has demonstrated robust and consistent growth over the past half-decade, reflecting the essential nature of these services. Historical data from 2020 to 2025 indicates a steady upward climb in revenue, driven by increasing awareness of threat vectors and the tangible costs associated with downtime. The market has progressed from a valuation of approximately 1.61 billion USD in 2020 to an estimated 2.15 billion USD by the base year of 2025. This progression underscores a fundamental shift: security budgets are no longer discretionary but are instead foundational to business continuity.
Hollow Glass Window Market
Looking toward the forecast horizon, the momentum shows no signs of deceleration. Projections indicate the market will reach 2.42 billion USD in 2026, continuing its expansion to exceed 5 billion USD by 2032. This growth is underpinned by a compound annual growth rate (CAGR) of 13.83 percent through the end of the forecast period. Such a rate places DDoS mitigation among the faster-growing segments within the broader cybersecurity infrastructure landscape. For financial planners and IT strategists, this trajectory suggests that sustained investment will be necessary to keep pace with the evolving sophistication of attack mechanisms. The integration of these services into broader cloud architectures and the rising frequency of volumetric attacks ensure that demand will remain inelastic relative to economic fluctuations.
It is important to note that these figures represent the aggregate global market. The distribution of this value across different geographical zones and deployment models reveals further complexity. Organizations must look beyond the headline numbers to understand how specific regional dynamics and operational preferences influence total cost of ownership and efficacy. Detailed breakdowns of regional revenue contributions and specific deployment splits are critical for tailoring local strategies, and these granular insights are fully elaborated within the complete market research publication.
Market Dynamics: Drivers Forces and Restraints
Several interrelated factors are propelling the expansion of the DDoS protection market. The primary driver remains the escalating scale and frequency of attacks. Adversaries are leveraging larger botnets composed of compromised Internet of Things devices and cloud instances, enabling them to generate traffic volumes that threaten even well-engineered network perimeters. Furthermore, the motivation behind these attacks has diversified. Nation-state actors utilize DDoS as a tool of hybrid warfare, while criminal syndicates employ it for ransomware extortion and smokescreening during data breaches. This diversity in threat origin requires enterprises to adopt protection strategies that are equally versatile.
Infrastructure evolution is another critical driver. As enterprises migrate workloads to public and hybrid cloud environments, the traditional perimeter dissolves. This necessitates a shift from hardware-centric mitigation to scalable, software-defined protection that can span multiple environments without introducing significant latency. The requirement for always-on availability, particularly for digital-native businesses and critical service providers, mandates that mitigation capabilities be integrated directly into the content delivery and application layers. Consequently, the market is seeing a convergence of DDoS protection with broader web application firewall (WAF) and bot management services, creating bundled solutions that offer unified threat management.
However, the market does face headwinds that warrant strategic consideration. Operational costs associated with high-throughput scrubbing centers and the energy consumption of data center infrastructure are rising. Recent analysis suggests that data center electricity demand could potentially affect electricity rates if that demand leads to a meaningful change in the local utility's costs. This creates a secondary financial pressure on service providers, which may trickle down to pricing models for enterprise customers. Additionally, cybercrime-related DDoS attacks have caused unplanned data center outages, highlighting the physical realities of digital threats. These events serve as reminders that mitigation is not just about software rules but also about physical infrastructure resilience and redundancy.
Regulatory environments are also reshaping the landscape. In the European Union, the European Union Agency for Cybersecurity mandates operators in 18 critical sectors to meet resilience and 24-hour reporting requirements. Such mandates compel organizations to adopt certified mitigation capabilities and maintain rigorous incident response protocols. Compliance is no longer optional; it is a license to operate for many critical industries. To explore how these regulatory pressures vary by region and how they impact specific vertical market segmentations, stakeholders are encouraged to review the detailed sector analysis provided in the full report.
Technology Architecture Segmentation
The market is broadly categorized by how protection is deployed and the layer at which mitigation occurs. Deployment models have evolved as organizations seek to balance control, scalability, and cost. Cloud-based solutions currently represent a significant portion of the market, reflecting the industry-wide shift toward cloud-native architectures. These solutions offer the advantage of elastic scalability, allowing mitigation capacity to expand instantly in the face of massive volumetric attacks without requiring customers to procure additional hardware.
Hybrid models remain relevant for organizations with specific regulatory or latency requirements. These approaches combine the scalability of the cloud with the immediate response capabilities of on-premises appliances. On-premises deployment, while representing a smaller share of the market, persists in environments where data sovereignty or ultra-low latency is paramount. The choice between these models often depends on the specific risk profile of the organization and its architectural maturity. Detailed analysis of the revenue distribution across cloud-based, hybrid, and on-premises segments, along with the implications for procurement strategy, is available in the comprehensive segmentation chapter of the study.
Protection type segmentation further refines the market view. Network-based protection focuses on the infrastructure layer, filtering malicious traffic before it reaches application servers. This is essential for mitigating volumetric attacks that aim to saturate bandwidth. Application-based protection operates at the Layer 7 level, distinguishing between legitimate user requests and sophisticated application-layer attacks. Host-based solutions provide a final line of defense at the operating system level. As attacks become more targeted, the reliance on a single protection type is diminishing. Multi-layered strategies that integrate network, application, and host-based defenses are becoming the standard for high-security environments. The specific revenue attributable to each protection type and the growth rates associated with each layer are detailed within the full research document, providing clarity on where innovation spending is concentrated.
Competitive Landscape and Strategic Positioning
The competitive environment in the DDoS Protection and Mitigation market is characterized by a mix of established security vendors, cloud hyperscalers, and specialized network defense firms. Market concentration metrics indicate a moderately concentrated industry, where the top three companies hold a CR3 of 34.5 percent and the top five companies account for a CR5 of 42.0 percent. This structure suggests that while there are dominant players, there is still ample room for niche players and regional specialists to compete on differentiation.
Akamai Technologies continues to leverage its extensive distributed network to offer robust defense. Their Prolexic DDoS protection platform emphasizes behavioral defense and offers flexible deployment options including in-cloud, on-premise, and hybrid configurations. With dedicated infrastructure for both network and application layer attacks, Akamai positions itself as a comprehensive solution for large enterprises requiring global reach and deep expertise.
Cloudflare has carved out a strong position by integrating DDoS protection directly into its global anycast network. Their approach relies on automated L3/L4/L7 mitigation rulesets and CDN-integrated scrubbing, which allows for real-time bot and botnet defense. This integration simplifies operations for customers who already utilize Cloudflare for content delivery, creating a sticky ecosystem where security and performance are managed through a single pane of glass.
Imperva focuses on a multi-layered doctrine that covers networks, applications, APIs, and DNS. Their services emphasize automated mitigation backed by threat intelligence, appealing to organizations that need to secure complex application architectures including microservices and API gateways. Radware offers a distinct value proposition through its hybrid on-premise appliances and cloud scrubbing centers. Their adaptive real-time mitigation for L3/L4/L7 attacks and application security is supported by continuous innovation, such as the recent partnership expansion with Chief Telecom to launch the Godshield Pro DDoS protection service in Taiwan. This move highlights the industry trend toward regional partnerships to deliver high-performance, low-latency mitigation for local enterprises.
NETSCOUT Systems brings a legacy of network visibility to the table with their Arbor DDoS protection portfolio. Including Arbor Edge Defense, Arbor Cloud, and Threat Mitigation System, their suite is designed for perimeter and enterprise-scale volumetric attacks. F5 Networks contributes to the competitive field with Silverline DDoS protection and F5 Distributed Cloud Services, offering an integrated WAF and bot mitigation capabilities within a multi-cloud SaaS platform. Corero Network Security targets service providers and enterprises with their SmartWall real-time DDoS mitigation solutions, focusing on high-performance distributed defense.
Recent developments illustrate the dynamism of this competitive arena. Amazon Web Services launched a DDoS Protection feature for game developers via Amazon GameLift Servers, providing UDP-based proactive mitigation without manual byte matching and negligible latency. This demonstrates how cloud providers are embedding security into specific developer tools to capture niche markets. GTT Communications expanded global DDoS scrubbing capacity to 4 Tbps with new mitigation centers in São Paulo, Hong Kong, and Miami, signaling a race to increase capacity and reduce latency geographically. Radware also introduced Alteon Protect, an expansion of their AI-driven cloud security platform for scalable application security enforcement. These moves highlight a market where companies are constantly expanding capacity, entering new regions, and integrating AI to stay ahead of threat actors. Corero Network Security expanded real-time DDoS protection services into Pakistan and nearby regions via partnership with Beyond Technology MEA, exemplifying the push for global coverage. Stakeholders seeking a complete competitive benchmarking analysis, including detailed profiles of all key companies and their specific strategic moves, should refer to the full competition chapter of this report.
Forward Outlook 2026 to 2032
As we look toward the remainder of the decade, the DDoS Protection and Mitigation market is poised for continued evolution. The forecast period through 2032 suggests a market valuation trajectory that will likely reshape procurement strategies. The convergence of security and network functions, driven by the adoption of SASE and secure access service edge architectures, will likely blur the lines between traditional DDoS mitigation and broader network security operations.
Innovation in mitigation technology will likely focus on reducing the human burden of management. Automated response systems that can distinguish between legitimate traffic spikes and malicious floods without manual intervention will become a baseline requirement. Additionally, the integration of threat intelligence feeds that anticipate attack patterns before they materialize will add value to premium service tiers. As the threat landscape incorporates more artificial intelligence on the attacker's side, defenders will need equally sophisticated AI-driven defense mechanisms to maintain parity.
For enterprise decision-makers, the implications are clear. Continuing to rely on fragmented security tools will increase risk and operational overhead. The strategic value lies in selecting partners and platforms that offer integrated visibility and scalable mitigation capacity. Investing in education and incident response planning is equally critical, as technology alone cannot prevent all disruptions. The detailed scenario analysis and forecast models contained in our full study provide the quantitative backing needed to justify these investments and allocate resources effectively across the 2026 to 2032 timeline.
Conclusion
The DDoS Protection and Mitigation market represents a critical component of the modern cybersecurity infrastructure. With a robust growth trajectory, evolving competitive dynamics, and increasing regulatory pressures, the sector offers both challenges and opportunities for industry participants. Understanding the macro trends and the specific capabilities of market leaders is essential for crafting a resilient security strategy.
This overview provides a glimpse into the depth of analysis available in the complete PW Consulting market research report. To access granular data on regional revenue splits, detailed segmentation percentages, specific company market shares, and comprehensive sales channel analysis, we invite you to explore the full publication. The complete intelligence gathered here is designed to empower your organization with the actionable insights necessary to thrive in an increasingly hostile digital environment.
For detailed analysis of this topic, please visit the official page: DDoS Protection and Mitigation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Thyristors Market to Reach $1.94 Billion by 2032 with 4.1% CAGR
By PW Consulting, 2026-09-07
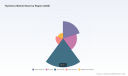
Strategic Intelligence for the Power Semiconductor Era: Unlocking the 2026 Thyristors Market Opportunity
Executive Summary
The global power semiconductor landscape is undergoing a structural transformation, driven by the intensifying electrification of industrial infrastructure, the expansion of renewable energy grids, and the relentless push for energy efficiency across automotive and consumer platforms. Within this ecosystem, the thyristor market stands as a critical enabler of high-power control, voltage regulation, and robust power conversion. For enterprise leaders, procurement directors, and strategic planners navigating the 2026 horizon, making informed capacity, sourcing, and R&D decisions requires more than headline figures. It demands a meticulously constructed intelligence framework that maps historical trajectories, isolates forward-looking growth vectors, and decodes the competitive maneuvers shaping the supply chain.
Anti-sink Protective Glue Market
PW Consulting's latest market research on the Thyristors Market delivers precisely that level of analytical rigor. Built upon a comprehensive historical baseline spanning 2020 through 2025 and projecting forward through 2032, this study translates complex macroeconomic shifts, regional demand asymmetries, and technological inflection points into actionable strategic guidance. The research is designed to serve as a decision-making compass, enabling organizations to anticipate supply constraints, optimize inventory architectures, evaluate partnership opportunities, and align product roadmaps with emerging application demands. What follows is a strategic preview of the intelligence contained within this report, engineered to demonstrate the depth of our analytical methodology while reserving the granular, segment-specific data points for the complete publication.
Vacuum Truck Parts Market
Market Trajectory: From Baseline Recovery to Sustained Expansion
The thyristors market has demonstrated remarkable resilience and steady upward momentum across the evaluation window. Historical data from 2020 through 2025 reveals a consistent expansion trajectory, with the global market overcoming early-cycle volatility to establish a robust growth platform. The base year of 2025 crystallizes this recovery, positioning the market at a decisive inflection point as it transitions into the 2026-2032 forecast period.
Subway Accessories Market
Our modeling indicates that the market will continue its measured but meaningful ascent throughout the forecast horizon, underpinned by a compound annual growth rate (CAGR) of 4.1%. This growth rate, while steady, reflects the specialized nature of thyristor technology: these devices are not consumer-driven commodities but mission-critical components embedded in high-inertia infrastructure projects, heavy industrial conversions, and long-cycle power transmission upgrades. The gradual yet persistent growth pattern underscores the importance of long-term capacity planning and strategic inventory positioning for organizations operating in this space.
Companies that merely track aggregate market size will miss the nuanced signals that dictate competitive advantage. Our research dissects the underlying growth mechanics, identifying the precise macroeconomic drivers, application-side demand surges, and regional procurement shifts that will dictate market velocity in 2026 and beyond. Understanding these mechanics is essential for firms seeking to time their investments, adjust production schedules, or enter new geographic territories with precision rather than speculation.
Structured Intelligence: What the Report Delivers
The Thyristors Market research is constructed around a multi-dimensional analytical architecture designed to answer the complex questions that executives face when allocating capital and designing supply strategies. The report moves beyond superficial sizing exercises to deliver a layered intelligence package that covers the entire value chain.
At its core, the study provides an exhaustive segmentation analysis that breaks down market dynamics across multiple axes. By examining how demand distributes across different voltage classifications, application verticals, and geographic territories, the report reveals which segments are acting as primary growth engines and which are undergoing structural recalibration. This segmentation intelligence is critical for firms deciding where to concentrate R&D resources, how to structure their product portfolios, and which customer pipelines warrant aggressive sales and technical support investments.
Furthermore, the research incorporates a detailed competitive landscape assessment that evaluates the positioning, technological capabilities, and strategic moves of the industry's leading players. Rather than presenting a static roster of manufacturers, the analysis maps each company's product architecture, voltage and current handling ranges, target application focus, and geographic manufacturing footprint. This competitive mapping allows readers to identify white-space opportunities, anticipate competitor responses to market shifts, and evaluate potential acquisition or partnership targets through a rigorous strategic lens.
The report also integrates a comprehensive dynamics section that contextualizes market behavior within the broader industry environment. This includes analysis of supply chain latency patterns, raw material procurement trends affecting silicon wafer availability and pricing, and regulatory or macroeconomic developments that influence upstream manufacturing costs. These dynamics are not peripheral concerns; they directly impact lead time negotiations, inventory carrying costs, and ultimately the total cost of ownership for firms integrating thyristor components into their systems.
Finally, the research synthesizes these findings into forward-looking strategic implications. Rather than leaving readers to interpret raw data, the study translates analytical outputs into actionable recommendations for capacity expansion, geographic market entry, supplier diversification, and technology roadmap alignment. This synthesis is what distinguishes the publication from a conventional market sizing exercise and positions it as a strategic decision-support tool.
Competitive Landscape: Navigating a Concentrated, Capability-Driven Arena
The thyristors market exhibits a pronounced concentration profile, with a relatively small cohort of established manufacturers commanding the majority of market share. This concentration is not incidental; it reflects the high technological barriers to entry, the specialized manufacturing processes required for high-power semiconductor devices, and the long-term qualification cycles that industrial and infrastructure customers demand before integrating new suppliers into their systems.
Within this concentrated environment, competitive differentiation is achieved through portfolio breadth, voltage and current rating capabilities, material science expertise, and the ability to serve mission-critical applications with rigorous reliability standards. The research profiles a select group of companies that define the market's competitive architecture, each bringing distinct technological strengths and application specializations to the landscape.
Leading European and Japanese manufacturers have entrenched themselves in the high-power segment, offering comprehensive portfolios that span full-bridge thyristors, gate turn-off thyristors (GTOs), integrated gate commutated thyristors (IGCTs), and complementary diode solutions. These players typically focus on large-scale grid applications, traction systems, renewable energy integration, and e-mobility platforms, leveraging decades of high-voltage engineering expertise and extensive qualification track records. Their product ranges often cover extreme current and voltage specifications, positioning them as preferred suppliers for utility-scale infrastructure and heavy industrial conversion projects.
Concurrently, specialized manufacturers in the United Kingdom and the United States have carved out strategic positions in the bipolar thyristor disc segment and mission-critical application domains. These firms emphasize in-house manufacturing capabilities, low thermal resistance architectures, and bespoke solutions for pulsed-power, phase-control, and asymmetric bypass applications. Their competitive edge often lies in the ability to deliver highly customized components for defense, space, aerospace, and advanced industrial power conversion systems where off-the-shelf alternatives cannot meet stringent reliability or performance thresholds.
On the discrete component side, major American and global semiconductor firms compete in the medium and lower voltage segments, focusing on silicon-controlled rectifier (SCR) and TRIAC solutions for motor controls, lighting, heating systems, and industrial power management. These companies leverage broad distribution networks, established relationships with OEM design engineers, and integrated product ecosystems that combine thyristors with complementary control ICs and power management components. Their growth strategies frequently center on expanding application coverage in consumer electronics, automotive power management, and alternative energy integration, where volume-driven demand patterns differ markedly from the project-based procurement cycles of the high-power segment.
German and Dutch manufacturers further enrich the competitive landscape by offering silicon and silicon carbide-based thyristor modules alongside traditional discrete solutions. These players target power conversion, automotive, and industrial applications, with product architectures designed to address the increasing thermal and efficiency demands of modern power electronics. Their module-based offerings often appeal to system integrators seeking compact, high-density solutions that simplify board-level design while maintaining robust power handling capabilities.
This fragmented-yet-concentrated competitive structure creates both challenges and opportunities. The high barrier to entry protects incumbent margins but also means that new entrants or expanding competitors must invest heavily in manufacturing infrastructure, qualification processes, and application-specific engineering support. Our research analyzes how these competitive dynamics are evolving, identifying which companies are strengthening their positions through capacity investments, technology upgrades, or strategic partnerships, and where potential market share displacement may occur as application demands shift.
Industry Dynamics in 2026: Supply Chain Pressures, Material Economics, and Readiness Signals
The operational environment for thyristor manufacturers and integrators in 2026 is shaped by a confluence of supply chain behaviors, raw material economics, and upstream cost dynamics that collectively influence pricing strategy, production scheduling, and procurement risk management.
Lead time dynamics remain a critical variable for the industry. Discrete component procurement cycles, including those for thyristors, have exhibited steady to slightly extended lead times, reflecting the complex balance between manufacturing capacity utilization, customer order forecasting, and inventory buffering strategies. As of the second quarter of 2025, lead times for these components reached approximately twenty-six weeks, a benchmark that continued to influence procurement planning and production scheduling into 2026. Organizations that fail to account for these extended procurement horizons risk project delays, cost overruns, and compromised system integration timelines. The research evaluates how these lead time patterns are reshaping buyer-seller negotiations, inventory strategies, and supplier qualification processes across key application verticals.
Raw material economics present a parallel layer of strategic consideration. Silicon wafer shipments demonstrated a notable increase in 2025, with industry forecasts pointing toward new shipment records by 2028. This expansion in wafer supply is a critical enabler for thyristor production, as it directly influences the availability and cost structure of the foundational material required for device fabrication. However, the relationship between wafer availability and final component pricing is mediated by manufacturing yields, process complexity, and the specific voltage and current ratings demanded by end applications. The report contextualizes these material supply trends within the broader production economics of thyristor manufacturing, helping readers anticipate how wafer market trajectories may influence component pricing, capacity utilization, and supplier competitiveness over the forecast period.
At the same time, upstream cost pressures are intensifying in adjacent semiconductor segments, with advanced-node wafer costs rising in the 2026 timeframe. While thyristor fabrication does not directly compete for advanced logic-node wafers, the broader semiconductor manufacturing ecosystem is interconnected, and generalized cost escalation across material sourcing, specialty chemicals, and manufacturing equipment can ripple into power semiconductor production economics. The research assesses the extent to which these upstream cost dynamics are affecting thyristor manufacturers' input cost structures and how companies are responding through pricing adjustments, material substitution strategies, or manufacturing efficiency initiatives.
These dynamics are not isolated data points; they are strategic signals that inform capacity planning, supplier diversification, inventory buffering, and long-term contract negotiations. The report integrates these industry dynamics into a cohesive analytical framework, enabling readers to model various supply-demand scenarios and prepare contingency strategies that protect operational continuity and margin integrity.
Strategic Implications for 2026 Decision-Makers
For enterprises operating in or adjacent to the thyristors market, the intelligence contained in this research translates into several critical strategic imperatives for 2026 and the ensuing forecast period. First, the steady but structurally nuanced growth trajectory demands that capacity and investment decisions be calibrated to segment-specific demand patterns rather than aggregate market trends. Organizations that allocate resources based on broad market growth rates risk misaligning production capabilities with the application verticals and voltage classifications that are actually driving incremental demand.
Second, the concentrated competitive landscape requires a deliberate approach to supplier engagement and portfolio strategy. Firms that rely on a narrow supplier base for critical power control components face elevated risk if lead time extensions, material cost escalations, or competitor capacity constraints disrupt supply continuity. The research provides the competitive and capability mapping needed to evaluate alternative suppliers, assess second-source qualification pathways, and structure procurement relationships that balance cost efficiency with supply resilience.
Third, the industry dynamics surrounding lead times, wafer supply, and upstream cost pressures necessitate a more sophisticated approach to inventory management and contract structuring. Organizations must determine optimal safety stock levels, negotiate lead time guarantees or penalty frameworks where appropriate, and evaluate long-term supply agreements that lock in favorable terms before competitive demand intensifies further. The analysis within the report equips procurement and supply chain leaders with the scenario-based intelligence needed to design these strategies with confidence.
Fourth, the application-side demand evolution presents both expansion and transition risks. As industrial, automotive, renewable energy, and power transmission sectors increasingly integrate advanced power control architectures, the specifications and qualification requirements for thyristor components are evolving. Companies that anticipate these specification shifts and align their product development or sourcing strategies accordingly will capture disproportionate value, while those that react only after demand patterns have solidified may face margin compression or exclusion from high-growth pipelines. The report's application segmentation analysis illuminates these demand trajectories, enabling technology and product strategy teams to make proactive rather than reactive decisions.
Why This Research Matters Now
The 2026 thyristors market represents a pivotal moment for strategic decision-making. The convergence of steady macroeconomic growth, evolving application demands, concentrated competitive dynamics, and shifting supply chain conditions creates an environment where informed strategy can generate meaningful competitive advantage, while reliance on outdated assumptions or surface-level market intelligence can lead to costly misalignment.
This market research was designed to meet the exacting standards of enterprise strategists, procurement directors, technology leaders, and investment analysts who require more than superficial market summaries. It delivers the depth, structure, and strategic synthesis needed to navigate a complex and specialized market with confidence. By combining rigorous historical analysis, forward-looking segmentation intelligence, detailed competitive profiling, and contextualized industry dynamics, the study provides a comprehensive foundation for 2026 decision-making and beyond.
The preview presented here offers a strategic overview of the analytical approach and the core intelligence dimensions contained within the report. However, the full strategic value of this research resides in the detailed segmentation breakdowns, regional and application-specific growth vectors, precise competitive positioning maps, and granular scenario analyses that cannot be fully replicated in a high-level summary. These core data elements are engineered to support precise operational planning, investment modeling, and supplier strategy development, and they are available in their complete form within the full publication.
For organizations seeking to align their 2026 capacity plans, procurement architectures, technology roadmaps, and market entry strategies with the realities of the thyristors market, accessing the complete research is an essential next step. The full report provides the unfiltered intelligence, segment-level quantification, and strategic recommendations required to translate market awareness into decisive, value-creating action.
Accessing the Complete Intelligence
The complete Thyristors Market research publication includes exhaustive segmentation analysis across all voltage classifications, application verticals, and geographic territories, alongside detailed competitive profiling, capacity and investment tracking, and scenario-based market projections through 2032. It is structured to serve as both a strategic reference document and a practical decision-support tool, with clear linkages between analytical findings and actionable business implications.
Readers interested in the full breadth of this intelligence, including the precise segment valuations, growth concentration patterns, competitive capability matrices, and regional demand forecasts that underpin the strategic narrative, are encouraged to access the complete report through the official PW Consulting research portal. The full publication is designed to provide the depth and specificity that enterprise decision-makers require to move from strategic awareness to execution-ready planning.
In a market defined by technical specialization, concentrated competition, and evolving supply dynamics, the cost of incomplete information is high. The complete Thyristors Market research delivers the comprehensive, data-rich, and strategically oriented intelligence needed to navigate 2026 with clarity, confidence, and competitive edge.
For detailed analysis of this topic, please visit the official page: Thyristors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cs Beam and Hydrogen Maser Market Hits $40M in 2025, 6.98% CAGR to 2032
By PW Consulting, 2026-09-07
The Precision Imperative: Strategic Intelligence for the Caesium Beam and Hydrogen Maser Atomic Clocks Market 2026–2032
In an era defined by satellite navigation dependency, deep-space exploration, and resilient infrastructure, atomic timing has graduated from a niche metrology concern to a boardroom-critical strategic asset. The global Caesium Beam and Hydrogen Maser Atomic Clocks market is undergoing a structural shift, driven by sovereign PNT (Positioning, Navigation, and Timing) mandates, GNSS disruption threats, and the insatiable demand for microsecond stability across telecommunications, data center synchronization, and spaceborne ensembles. This introduction to our latest market research exposition distills the strategic contours of the 2026–2032 landscape, equipping executives with the analytical framework required to navigate a market poised for sustained expansion. All macroeconomic trajectories, competitive dynamics, and operational insights referenced herein are drawn from our comprehensive study; granular regional breakdowns, application-level revenue splits, and detailed sensitivity matrices are reserved for the full report, available at the source page.
System IP Market
Market Sizing and Growth Trajectory: A Decade of Measured Expansion
The market has demonstrated consistent, compounding growth from 2020 through the base year 2025, with revenue advancing from 25.0 million USD to 40.0 million USD. This trajectory reflects a maturing ecosystem where legacy frequency standards are being complemented—and in critical applications, superseded—by next-generation hydrogen maser and optical cesium beam architectures that deliver enhanced short-term stability, extended operational lifespans, and sovereign deployment compatibility. Looking forward, our forecast period from 2026 through 2032 projects the market to reach 63.1 million USD, anchored by a compound annual growth rate of 6.98 percent. This growth profile is not merely a function of incremental adoption; it is underpinned by structural catalysts including new manufacturing capacity, space mission deployments, standardization milestones, and the accelerating integration of primary reference clocks into defense, telecom, and utility networks that cannot tolerate GNSS outages.
Military Command and Control System Market
The growth cadence across the forecast window is particularly instructive for capital allocation and product roadmap planning. Revenue stepping from 42.06 million USD in 2026 to 46.89 million USD in 2027, then progressing through 48.89 million USD in 2028 and 53.1 million USD in 2029, signals an acceleration phase as facility expansions come online and deployment cycles mature. By 2030, the market is projected to approach 53.85 million USD, followed by 58.01 million USD in 2031 and 63.1 million USD in 2032. This arc indicates that demand is not flat or speculative; it is being pulled by concrete infrastructure modernization programs and the certification of new primary frequency references that recalibrate national metrology baselines. Decision-makers evaluating timing investments should align procurement cycles, capacity planning, and partnership strategies with this underlying momentum rather than treating atomic clocks as commoditized spare-parts purchases.
Food Chain Management Software Market
Competitive Dynamics: A Concentrated Arena with Differentiated Technology Plays
The competitive landscape is moderately concentrated, with the top three firms capturing approximately 40 percent of market revenue and the top five collectively accounting for around 50 percent. This concentration coexists with meaningful differentiation in product architecture, deployment footprint, and strategic positioning. Leading players are not competing solely on price; they are competing on frequency stability, holdover performance, lifecycle durability, certification alignment, and sovereign supply-chain resilience.
Microchip Technology Inc., headquartered in Chandler, Arizona, manufactures the 5071B cesium beam frequency standard and MHM-2020 active hydrogen maser atomic clocks, serving metrology, telecommunications, and satellite applications with accuracies as low as 5x10^-13. In April 2026, Microchip opened a new manufacturing facility in Tuscaloosa, Alabama, dedicated to the MHM-2020 active hydrogen maser, explicitly aimed at increasing production capacity and reducing lead times amid rising demand for independent timing systems. For organizations relying on resilient timing, this facility expansion signals a tangible shift toward scalable, domestically grounded maser production that can support national infrastructure protection against GNSS disruptions.
Oscilloquartz SA, based in Neuchâtel, Switzerland, produces optical cesium beam atomic clocks through the OSA 3230 series and hydrogen maser solutions with enhanced short-term stability via the ESTU module, targeting telecom, defense, and precision timing applications. Its technology footprint emphasizes stability enhancements that close the historical gap between cesium beam and hydrogen maser performance in short-term metrics—an increasingly relevant consideration for synchronization in data centers and critical infrastructure.
Safran Electronics & Defense, headquartered in Paris, France, develops and supplies the Space Hydrogen Maser (SHM) and cesium beam systems, with deployments tied to the ESA ACES mission for spaceborne atomic clock ensembles. In April 2025, the SHM powered the ESA ACES atomic clock ensemble aboard the ISS, achieving record stability for global timekeeping and deep-space applications. Later, in September 2025, an all-European Maser active hydrogen maser was deployed at the ESA New Norcia deep-space ground station in Australia, marking the first fully European ultra-precise maser operation for interplanetary missions. These milestones illustrate how space-grade maser technology is extending its reach from orbital ensembles to ground-based deep-space tracking, reinforcing sovereign timing capabilities and GNSS resilience.
Adtran Inc., headquartered in Huntsville, Alabama, provides Oscilloquartz optical cesium beam clocks with the ESTU module for enhanced stability, targeting data centers, power utilities, and defense PNT applications. In June 2025, Adtran launched the Oscilloquartz OSA 3200 SP and OSA 3250 enhanced primary reference clocks, which are cost-effective optical cesium beam solutions designed with a 10-year lifespan and improved holdover for telecom and infrastructure modernization. This product progression demonstrates how optical cesium beam architectures are being engineered to deliver hydrogen-maser-comparable short-term stability for Western defense and telecom PNT systems at a point on the value curve that broadens deployment eligibility.
- Microchip reinforces domestic maser capacity and lead-time reduction to meet independent timing demand.
- Oscilloquartz advances ESTU-enabled short-term stability across both cesium beam and maser lines.
- Safran anchors spaceborne and ground-station maser deployments for sovereign deep-space and GNSS resilience.
- Adtran accelerates optical cesium beam adoption in data centers, utilities, and defense with extended-lifespan, holdover-optimized designs.
Structural Shifts and Regulatory Catalysts
The market is being reshaped by a confluence of standardization, certification, and component-level developments that alter both the competitive baseline and the deployment economics of atomic timing. The certification of the NIST-F4 cesium fountain atomic clock as the new U.S. primary frequency standard in April 2025 represents a pivotal calibration reference for UTC traceability and metrology applications. By calibrating against hydrogen masers and replacing legacy HP 5071A models in national metrology labs, this standard elevates the performance bar and aligns metrological expectations with next-generation stability requirements. For commercial and defense buyers, such national standard shifts cascade into procurement specifications, calibration protocols, and compliance expectations.
On the component and capability side, the ESA ACES mission selection of Safran's Space Hydrogen Maser in April 2025 underscores the strategic premium placed on exceptional short-term frequency stability for spaceborne applications. Simultaneously, the September 2025 deployment of the all-European Maser at ESA New Norcia for sovereign deep-space tracking and GNSS resilience signals a policy-aligned push toward independent, ultra-precise maser operations beyond orbital missions. In parallel, Adtran's June 2025 launch of Oscilloquartz optical cesium beam clocks with the ESTU module offers hydrogen-maser-comparable short-term stability for Western defense and telecom PNT systems, broadening the palette of viable options where total cost of ownership and deployment practicality intersect with stability mandates.
These developments are not isolated events; they collectively define the market dynamics that executives must internalize. Standardization recalibrates the reference frame. Space missions and ground stations expand the application frontier. Component-level innovations narrow performance gaps between cesium beam and hydrogen maser families, enabling more flexible procurement strategies. Organizations that treat these as background noise risk misaligning their timing architectures with the evolving performance, compliance, and sovereignty criteria that now shape purchasing decisions.
Where Precision Meets Deployment: Applications and End-Market Pull
Although detailed application splits and regional magnitudes are intentionally reserved for the full report to preserve the granularity of our commercial intelligence, the directional pull across end markets is unmistakable. Telecommunications and data centers continue to anchor steady demand for primary reference clocks that sustain synchronization, reduce jitter, and support 5G and next-generation network architectures. Power utilities are integrating precision timing into grid synchronization, protection relaying, and phasor measurement under programs that prioritize resilience against timing disruptions. Defense and PNT applications are expanding as sovereign capability programs prioritize independent timing sources that can maintain operational continuity when GNSS signals are degraded or denied.
In the space domain, hydrogen maser and cesium beam systems are increasingly embedded in orbital ensembles, interplanetary tracking, and ground-station operations. The record-stability outcomes associated with recent ESA missions and the establishment of fully European maser operations at deep-space ground locations illustrate how space-grade timing is becoming integral to global timekeeping and deep-space mission architectures. These applications are not merely analytical curiosities; they represent durable demand vectors that interact with national research priorities, international partnership frameworks, and long-duration asset deployment cycles.
From a strategic standpoint, the convergence of telecom modernization, utility resilience, defense PNT mandates, and spaceborne timing creates a multi-vector demand environment. Buyers are less interested in clock instruments as standalone devices and more focused on integrated timing solutions that deliver stability, holdover, lifecycle durability, certification alignment, and supply assurance. That shift in buying logic has direct implications for product strategy, channel partnerships, and service-level definitions.
Strategic Implications for 2026 Decision-Makers
For executives steering capital allocation, R&D roadmaps, procurement strategies, and supply-chain resilience initiatives, the 2026 outlook for the Caesium Beam and Hydrogen Maser Atomic Clocks market carries several actionable implications. First, the projected 6.98 percent CAGR and the 63.1 million USD endpoint in 2032 indicate that timing is a growing, not stagnant, category. Organizations should plan for sustained procurement and integration activity rather than treating atomic clocks as static, one-time purchases.
Second, the concentration profile—approximately 40 percent for the top three and 50 percent for the top five—suggests that supplier selection has outsized impact on performance, lead times, and continuity. Given recent capacity expansions, product launches, and mission deployments, the field is evolving quickly. Strategic buyers should assess not only nominal specifications but also manufacturing readiness, calibration alignment, holdover characteristics, and the supplier's track record in mission-critical and sovereign deployments.
Third, the certification and standardization momentum—exemplified by the U.S. primary frequency standard update and ESA mission and ground-station maser deployments—means that compliance and traceability considerations are becoming more stringent and more consequential. Aligning internal specifications with evolving national and international references can reduce integration risk and improve the longevity of timing investments.
Fourth, the narrowing performance gap between optical cesium beam designs with enhanced modules and hydrogen maser architectures expands the decision space. Where short-term stability and holdover are paramount, hydrogen masers remain compelling; where cost-effectiveness, lifecycle duration, and deployment practicality are equally weighted, advanced cesium beam solutions merit serious evaluation. The strategic task is not to default to one technology family but to match architecture to application criticality, operating environment, and total cost of ownership.
Finally, sovereign infrastructure protection against GNSS disruptions is becoming a decisive demand driver. Capacity expansions dedicated to active hydrogen maser production, all-European maser deployments for deep-space tracking, and enhanced primary reference clocks tailored to defense and telecom PNT systems collectively indicate that timing independence is moving from a technical aspiration to a procurement priority. Organizations that anticipate this shift—by securing supply, validating holdover performance, and mapping timing dependencies across critical operations—will be better positioned to maintain continuity as the external timing environment becomes more contested and more regulated.
What the Full Study Delivers
This introduction is deliberately the strategic trailer: it establishes the market's growth arc, competitive concentration, technology differentiation, and regulatory catalysts, while preserving the deeper quantification and segmentation for the full research. The complete study unpacks operational intelligence that cannot be responsibly summarized without diluting its decision value. Among the elements covered in depth are demand drivers, restraints, and opportunities; segment-level dynamics across technology types, including Caesium Beam Atomic Clocks and Hydrogen Maser Atomic Clocks; regional market structures across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa; country-level demand contexts; competitive positioning, market share estimates, and company profiles; and detailed recent developments and strategic developments that map the sequence of product launches, facility expansions, space mission deployments, ground-station operations, and certifications shaping the market.
The report also integrates regulatory and standardization context, raw material and component considerations, and application-oriented demand narratives that tie timing performance to real-world operational outcomes in telecom, data centers, power utilities, defense PNT, and spaceborne ensembles. For analysts and executives, the value lies not only in the numbers but in the connective tissue: how capacity expansions interact with lead times, how certification changes cascade into procurement specs, how space missions and ground stations extend the application frontier, and how enhanced cesium beam modules alter the cost-stability trade-off landscape.
Closing Perspective
The Caesium Beam and Hydrogen Maser Atomic Clocks market is entering a phase where precision, sovereignty, and resilience converge. From 2020 through 2025, the market advanced from 25.0 million USD to 40.0 million USD; from 2026 through 2032, it is projected to reach 63.1 million USD at a 6.98 percent CAGR. These figures are more than indicators; they are signals of structural demand reinforced by facility expansions, space mission deployments, ground-station operations, and primary frequency standard certifications. The competitive arena is concentrated enough to matter and differentiated enough to reward careful architecture selection. The strategic question for 2026 is not whether atomic timing matters, but how organizations will align their timing investments with the performance, compliance, and continuity requirements now taking shape.
To access the full dataset, segmentation detail, regional and application-level intelligence, competitive estimates, and the complete chronology of strategic developments that underpin these conclusions, request the complete market research at the source page. The executive summary provided here is designed to help you evaluate the study's relevance to your planning cycle; the full report is designed to help you act on it with precision.
For detailed analysis of this topic, please visit the official page: Cs beam and Hydrogen Maser Atomic Clocks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Document Scanner Market Hits $4.6B in 2025, Nears $6.7B by 2032 at 5.35% CAGR
By PW Consulting, 2026-09-07
Strategic Intelligence in the Document Scanner Market: Navigating the 2026–2032 Landscape
The document scanner market has evolved from a peripheral hardware category into a critical enabler of digital transformation, regulatory compliance, and operational resilience. As organizations across government, healthcare, and enterprise sectors accelerate their shift toward paperless workflows, the strategic importance of scanning infrastructure has never been more pronounced. Our latest market research report, Document Scanner Market, delivers a comprehensive, data-driven assessment of this evolving landscape, providing executives, procurement leaders, and technology strategists with the actionable intelligence required to make informed decisions through 2032.
Fiber Optic Converters Market
This analysis is designed for decision-makers who require more than surface-level industry summaries. It maps historical performance, quantifies growth trajectories, dissects competitive positioning, and isolates the regulatory, technological, and operational forces that will reshape procurement strategies in the coming years. The following overview outlines the strategic value embedded in the full report, while preserving the granular segmentation, regional breakdowns, and company-level scoring that constitute the complete intelligence package.
High-end Ventilator Market
Market Trajectory and Structural Shifts (2020–2032)
The document scanner market has demonstrated consistent expansion over the past half-decade, with historical performance (2020–2025) establishing a reliable baseline for forward-looking planning. Revenue grew from approximately USD 3,982 million in 2020 to USD 4,645 million in 2025, reflecting steady adoption across enterprise back offices, public sector digitization initiatives, and healthcare record management. A modest contraction observed in 2024 was followed by a rebound in 2025, underscoring the market's sensitivity to procurement cycles, supply chain normalization, and shifting IT budget allocations.
At-Home Spirometer Market
Looking ahead, the forecast period (2026–2032) projects a compound annual growth rate (CAGR) of 5.35 percent, with market revenue expected to reach USD 6,680 million by 2032. This trajectory signals sustained demand, but more importantly, it highlights a structural transition: growth will increasingly be driven by workflow automation, software-integrated capture solutions, and compliance-mandated digitization rather than replacement cycles alone. Organizations that treat scanning hardware as a standalone purchase risk overlooking the broader ecosystem value—integration capabilities, data security protocols, and total cost of ownership models—that will define procurement success in this forecast window.
For enterprise strategists, this growth profile carries several implications. First, the steady expansion suggests that supplier competition will intensify, particularly in price-sensitive segments, making differentiation through software bundling, service-level agreements, and compliance alignment more critical. Second, the projected acceleration in later forecast years indicates that early movers who align their scanning infrastructure with broader digitization roadmaps will secure favorable positioning before capacity constraints or regulatory tightening reshape procurement timelines.
Core Operational and Regulatory Dynamics
The market's trajectory cannot be isolated from the operational and regulatory pressures that are actively reshaping scanning workflows. Several developments in the 2025–2026 window illustrate the complexity that procurement and IT leaders must now navigate.
Regulatory scrutiny around data handling and privacy has intensified across multiple jurisdictions. In the United States, the implementation of Executive Order 14117 brought new requirements for bulk data transfers to countries of concern, effective April 2025, necessitating careful vendor selection and data routing strategies for organizations managing cross-border document flows. Simultaneously, the Connecticut Data Privacy Act (CTDPA) enforcement became fully active in 2026, with an initial fine of USD 85,000 issued in 2025 signaling that compliance is no longer advisory but financially consequential. Under GDPR, organizations processing personal data in document scanning workflows must implement appropriate technical and organizational measures, including encryption and access controls, embedding privacy-by-design principles directly into capture pipelines.
On the operational side, labor efficiency and automated workflows are becoming the primary cost drivers at high scanning volumes. As organizations scale digitization programs, the marginal cost of manual handling, quality control, and exception management can quickly erode the perceived savings of digitization initiatives. This reality is pushing procurement teams to evaluate scanners not merely on throughput speed, but on their ability to integrate with intelligent document processing, metadata extraction, and workflow orchestration layers.
Industry incidents further illustrate the risks of misaligned procurement. The U.S. Internal Revenue Service's scanning operation, which processed 58.7 million pages of historical Forms 709 between December 2023 and early July 2025, was ultimately discontinued due to low volumes and quality issues. This case underscores that volume alone does not guarantee success; process design, vendor capability, and ongoing quality oversight are equally decisive.
Competitive Landscape and Strategic Positioning
The document scanner market is characterized by a concentrated yet diverse competitive field, where established imaging and office equipment manufacturers compete alongside specialized scanning vendors. The broader market structure reflects moderate concentration, with the top three players accounting for a significant share of revenue and the top five firms commanding a dominant portion of the market. This concentration creates both opportunities and constraints for buyers: scale economies and ecosystem integration are advantages, but procurement leverage must be exercised carefully to avoid lock-in or limited negotiation flexibility.
A closer examination of the leading participants reveals distinct strategic orientations that procurement teams should align with their operational priorities:
- Fujitsu focuses on advanced high-speed sheetfed document scanners paired with PaperStream technology, positioning its offerings around enterprise workflow automation and seamless integration. Its strength lies in organizations that require high-volume capture with robust software handoff to downstream processing systems.
- Canon delivers the imageFORMULA series, emphasizing high-speed duplex and flatbed document scanners optimized for office document management and multi-page scanning. Its portfolio suits environments where versatility, image quality, and straightforward deployment are prioritized.
- HP offers portable and desktop document scanners supported by WorkScan software, targeting mobile and office capture solutions. This positioning is relevant for distributed workforces, field operations, and organizations that require flexible capture points beyond centralized scanning rooms.
- Epson provides desktop and flatbed document scanners with automatic document feeder options and TAA-compliant models tailored for government and enterprise use. Recent product activity underscores its commitment to regulated procurement channels and broad industry applicability.
- Brother markets the ADS-series of compact and high-speed desktop document scanners with auto document feeders designed for business environments. Its emphasis on space-efficient, reliable desktop capture appeals to office-dense deployments.
- Plustek specializes in wide-format and professional document scanners, incorporating AI-enhanced scanning capabilities. This positions the company for specialized use cases where format flexibility and intelligent image processing add measurable value.
- Xerox delivers the DocuMate series of duplex document scanners integrated with enterprise document management systems, aligning hardware capture with broader information management ecosystems.
- Visioneer offers the Patriot and intelligent document scanners with OneTouch software for networked and mobile capture, emphasizing streamlined user workflows and connectivity across capture points.
These profiles illustrate that competitive differentiation in the document scanner market is increasingly defined by more than optical performance or feeder capacity. Software integration, compliance readiness, deployment flexibility, and alignment with downstream document management platforms now form the core of vendor evaluation. The full report expands on these positions with detailed segment-level revenue context, capability assessments, and procurement-relevant scoring that enable side-by-side comparison.
Recent Developments Shaping Procurement Decisions
Recent product and software activity provides a concrete window into how vendors are responding to market demands. In May 2025, Epson America launched TAA-compliant desktop document scanners, including the DS-530 II, DS-730N, and DS-870, specifically targeting federal government agencies. This move reflects the growing premium on regulatory alignment within public sector procurement, where TAA compliance can be a gatekeeping requirement rather than a secondary consideration.
Later in June 2025, Epson unveiled new flatbed document scanning solutions, the DS-1730 and DS-1760WN, broadening its reach across a wide range of industries. This expansion signals a strategic emphasis on versatility and multi-industry applicability, particularly for organizations that require reliable flatbed capture for bound documents, fragile materials, or non-standard formats.
In January 2026, Scanbot released version 8.0.0 of its Linux Document Scanner SDK for headless server environments. This software update highlights a parallel trend in the market: the rising importance of server-side, automated capture pipelines that operate without direct user intervention. As organizations scale digitization, SDK-level capabilities that support headless deployment, batch processing, and integration with enterprise server infrastructure become decisive factors in total solution evaluation.
These developments are not isolated product events; they are indicators of where the market is heading. Procurement strategies that account for compliance readiness, format versatility, and software-defined capture will be better positioned to absorb the operational and regulatory shifts expected through the forecast period.
Segmentation Architecture and Strategic Selection Criteria
The document scanner market is structured around multiple segmentation dimensions that collectively determine how organizations evaluate fit, cost, and deployment complexity. While the full report provides detailed revenue breakdowns by region, type, and application, understanding the strategic logic behind these segments is essential for effective procurement planning.
By device type, the market encompasses sheet-fed, portable, and flatbed scanners, each serving distinct operational profiles. Sheet-fed systems are typically associated with high-throughput office and back-office environments where continuous feed and speed are paramount. Portable scanners address mobile, distributed, and field-based capture needs, offering flexibility at the expense of some throughput and ergonomic trade-offs. Flatbed scanners serve use cases that require careful handling of non-standard media, bound documents, or materials that cannot be fed through a roller mechanism. The strategic selection among these types often depends less on isolated performance metrics and more on the composition of the document population, the frequency of capture, and the degree to which scanning must be decentralized.
By application, document scanning demand spans office environments, government operations, and healthcare settings. Each vertical imposes different requirements on throughput, compliance, integration, and auditability. Office deployments typically emphasize ease of use, multi-page handling, and integration with everyday productivity tools. Government use cases frequently introduce TAA compliance, security certifications, and integration with public-sector document management systems as non-negotiable criteria. Healthcare environments add layers of complexity related to sensitive data handling, workflow consistency, and adherence to privacy regulations, where capture infrastructure must align with broader information governance frameworks.
By region, market revenue is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, reflecting varied adoption maturity, regulatory environments, and procurement practices. Regional differences influence not only volume but also the relative importance of compliance, service availability, and total cost of ownership. The full report maps these regional dynamics with precision, allowing organizations to benchmark their expectations against localized market conditions rather than relying on global averages that may obscure critical nuances.
Strategic Value for 2026 Enterprise Decision-Making
The strategic value of this research lies in its ability to convert market complexity into procurement clarity. For enterprise decision-makers operating in 2026, the document scanner market is no longer a simple hardware acquisition category. It is a decision point that intersects with regulatory compliance, workflow automation, data security, service continuity, and long-term digitization roadmaps. The report is structured to support these intersecting priorities through several practical components.
First, it provides a rigorous historical foundation, tracing revenue performance from 2020 through 2025 to establish a reliable baseline against which forecast assumptions can be tested. This historical context is essential for organizations that are calibrating multi-year procurement plans or evaluating whether current market pricing and availability trends are consistent with broader industry patterns.
Second, the forecast period analysis (2026–2032) equips leaders with forward-looking growth expectations, enabling capacity planning, budget forecasting, and technology roadmap alignment. By quantifying the projected CAGR and endpoint revenue, the report gives executives a reference frame for evaluating whether immediate investments, phased rollouts, or vendor diversification strategies are appropriate for their specific operational context.
Third, the competitive landscape assessment translates vendor profiles into procurement-relevant insight. Rather than presenting a static directory of manufacturers, the report contextualizes each participant's strengths, deployment orientations, and ecosystem alignment so that buying teams can match vendor characteristics to their own operational requirements, compliance constraints, and integration needs.
Fourth, the inclusion of recent developments and industry context ensures that decision-makers are working with current signals rather than outdated assumptions. Product launches, software updates, regulatory enforcement actions, and operational case studies are woven into the analysis to illustrate how market forces are actively shifting procurement criteria. This temporal relevance is critical in a market where compliance requirements and software-defined capture capabilities are evolving faster than traditional hardware refresh cycles.
Finally, the segmentation framework supports targeted decision-making by clarifying how device type, application, and regional factors influence fit and value. The full report preserves detailed revenue splits and segment-level context that allow organizations to benchmark their requirements against market structure without relying on generic guidance. This level of specificity is particularly valuable for organizations that operate across multiple regions, manage diverse document populations, or must satisfy varied compliance and integration requirements within a single procurement program.
Why the Complete Report Is Essential
The overview presented here is deliberately structured to demonstrate the depth and strategic orientation of the research while preserving the detailed figures, segment-level breakdowns, regional revenue distributions, and company-specific scoring that constitute the complete intelligence package. Market structure, competitive positioning, and procurement strategy cannot be fully optimized on the basis of macro-level trends alone. They require precise segment context, comparative assessments, and operational benchmarks that are developed through the full analytical framework.
The complete report delivers that precision. It provides the granular market size context, segmentation detail, competitive evaluation, and regulatory mapping needed to support procurement decisions, technology planning, and strategic investment timing through 2032. For organizations that are aligning scanning infrastructure with broader digitization initiatives, evaluating vendor portfolios against compliance and integration requirements, or forecasting multi-year capacity and budget needs, the full analysis offers the evidentiary foundation required to move from general awareness to actionable strategy.
To access the complete Document Scanner Market research, including detailed segmentation data, regional revenue distributions, competitive scoring, and forecast assumptions, please visit the source page for the full report.
For detailed analysis of this topic, please visit the official page: Document Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


