



Category: IT & Electronics
PW Consulting Projects 19.5% CAGR for Lithium-ion Battery Recycling Market Through 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for 2026: Navigating the Lithium-ion Battery Recycling Market
Executive Overview: The Imperative for Precision Intelligence
The global energy transition is no longer just a policy aspiration; it is a supply chain reality. As electric vehicle adoption accelerates and stationary storage deployments multiply, the volume of end-of-life lithium-ion batteries is entering an inflection point. For corporate strategists, investors, and sustainability leaders, the question is no longer whether to engage with battery recycling, but how to position operations, partnerships, and capital allocation to capture value in a rapidly formalizing market.
PW Consulting's latest Lithium-ion Battery Recycling Market research is designed specifically for decision-makers operating in the 2026 landscape. This report does not merely aggregate historical figures; it translates trajectory, regulatory pressure, and competitive maneuvering into actionable frameworks. The analysis that follows is built to be read by executives who need to separate structural growth from cyclical noise, and who require validated intelligence to guide capacity planning, technology selection, and geographic expansion.
The market has already demonstrated remarkable momentum. Historical data from 2020 through 2025 reveals a sustained acceleration, with revenue climbing from 2.8 billion USD to 10.7 billion USD over that span. Looking forward, the trajectory suggests continued robust expansion, supported by a compound annual growth rate of 19.5 percent across the 2026 to 2032 forecast period. By 2032, this research projects the market will approach 37.5 billion USD. These are not abstract numbers; they represent a structural reallocation of capital, materials, and regulatory attention that will define competitive positioning for the remainder of the decade.
Why This Market Demands Specialized Intelligence
A Rapidly Evolving Value Chain
Battery recycling is not a monolithic activity. It spans collection logistics, discharge and disassembly, multiple metallurgical recovery pathways, and the reintroduction of refined intermediates into cathode and cell manufacturing. Each link in that chain carries distinct economics, technology risk, and regulatory exposure. The firms that succeed will be those that understand how these layers interact rather than those that optimize a single step in isolation.
The research recognizes this complexity. It maps the value chain from end-of-life battery intake through material recovery and back into production streams, highlighting where margins are created, where bottlenecks form, and where policy is reshaping the economics of recovery. For 2026 planning, this systems-level view is essential because capacity decisions made this year will lock in operational footprints that must withstand both feedstock variability and evolving compliance requirements.
Regulation as a Structural Driver, Not a Background Condition
Policy is now a primary determinant of market behavior. Across major jurisdictions, regulators are moving from voluntary guidance to enforceable standards that directly affect recycling economics. In the United States, the Infrastructure Investment and Jobs Act requires the EPA to develop battery collection best practices and labeling guidelines, with completion mandated by September 30, 2026. The EPA is also planning to propose new rules to improve the management and recycling of end-of-life lithium batteries, with a proposed rule expected in February 2026.
Europe is moving even faster on material recovery and recycled content. From 2026, the EU requires at least a 65 percent recycling rate for lithium-ion batteries, with the recovery rate for lithium increasing from 35 percent to 70 percent between 2026 and 2030. By 2031, batteries placed on the EU market must contain minimum levels of recycled content, including 6 percent lithium. In parallel, new European Commission rules published on July 4, 2025 establish requirements to calculate and verify recycling efficiency and material recovery rates.
These are not peripheral developments. They alter the cost structure of recovery operations, shift the value of specific recovered elements, and create compliance-driven demand for certified processes. The report integrates these regulatory trajectories into its market outlook so that leadership teams can evaluate exposure, opportunity, and contingency planning with a clear understanding of how compliance timelines intersect with commercial scaling.
Report Architecture: What Decision-Makers Will Find Inside
Granular Segmentation Without Losing Strategic Focus
The research is organized to support both portfolio-level strategy and operational decision-making. It segments the market along multiple dimensions, including geography, battery chemistry, recycling process, and source of end-of-life material. This structure allows readers to understand how growth is distributed across different pathways and where specific technologies or feedstock streams are gaining traction.
At the aggregate level, the segmentation data indicates that the Asia Pacific region represents the largest share of market revenue, followed by Europe and North America, with Latin America and the Middle East and Africa accounting for smaller but strategically relevant portions of the total. On the chemistry side, NMC-based batteries currently command the largest revenue share, with LFP and other chemistries forming meaningful but comparatively smaller components of the market. In terms of process, hydrometallurgical methods lead in revenue contribution, followed by pyrometallurgical and physical or mechanical approaches. By source, automotive end-of-life batteries represent the dominant revenue stream, with non-automotive sources contributing a substantial secondary share.
Importantly, this report avoids reducing these segments to isolated percentages. Instead, it explains the interplay between them: how chemistry mix influences process choice, how regional regulation shapes feedstock availability, and how source dynamics affect the economics of collection and pretreatment. That integrated framing is what makes the segmentation actionable rather than descriptive.
Technology and Process Evaluation for Capital Allocation
Choosing the right recovery approach is one of the most consequential decisions facing recycling investors and operators. Hydrometallurgical routes, pyrometallurgical routes, and physical or mechanical processes each carry different trade-offs in terms of material recovery rates, energy intensity, capital requirements, and sensitivity to feedstock composition. The report assesses these pathways in the context of current commercial deployments, emerging improvements, and the regulatory push toward higher lithium recovery and verified efficiency metrics.
For 2026 planning, this matters because process selection is increasingly tied to compliance and offtake confidence. As lithium recovery targets rise and recycled content requirements come into view, operations that can demonstrably meet higher recovery thresholds and provide traceable material streams will enjoy stronger positioning with downstream buyers. The research helps leaders weigh these considerations against capital timing, scaling risk, and regional feedstock characteristics.
Competitive Landscape: Who Is Moving, and How
The competitive environment is consolidating around firms that combine scale, technology differentiation, and strategic partnerships. The report profiles the companies most relevant to 2026 strategy, examining their operational posture, geographic focus, and recent commercial moves.
Among the firms analyzed are American Battery Technology Company, based in Reno, Nevada, which operates a commercial-scale recycling facility producing black mass and byproducts and is advancing a second 100,000 metric tonne-per-year facility with Department of Energy support. Ascend Elements, headquartered in Covington, Georgia, specializes in lithium recovery through its Hydro-to-Cathode technology and has achieved commercial-scale production of greater than 99 percent pure recycled lithium carbonate at its Georgia facility, with expansion plans extending to Poland. BatX Energies, based in Gurugram, India, provides hydrometallurgical recycling and critical minerals extraction services through its Uttar Pradesh plant and has secured agreements for high-voltage battery recycling and repurposing.
Ecobat, with headquarters in Dallas, Texas, operates as a global battery recycling provider and has commissioned three fully operational lithium-ion recycling plants in Germany, the United States, and the United Kingdom, each processing up to 10,000 tons annually of black mass. Altilium Metals, based in Plymouth, United Kingdom, develops proprietary EV battery recycling technology for the recovery of critical minerals including nickel MHP, lithium sulphate, and graphite, with its ACT 3 commercial facility under construction and supported by grant funding. Umicore, headquartered in Brussels, Belgium, reports recycling business group revenues of 947 million euros in 2025 and remains focused on battery materials processing at scale.
The landscape also includes Li-Cycle Corp, based in Toronto, Canada, which provides integrated recycling and refining services across multiple North American facilities; Call2Recycle, Inc., in Chicago, Illinois, which operates the nation's largest consumer battery stewardship and collection program and has partnered with recyclers such as American Battery Technology Company to expand domestic lithium-ion recycling channels; and Redwood Materials, based in San Francisco, California, which specializes in lithium-ion battery recycling and critical materials recovery and supports domestic supply chains with developments in South Carolina and medium-format battery processing.
Rather than presenting these profiles as static company summaries, the report situates them within broader strategic themes. It examines how partnerships, facility commissioning, and technology milestones are reshaping feedstock access, regional capacity, and the competitive bar for recovery quality. Recent developments included in the analysis illustrate this dynamic clearly: Ascend Elements achieved first commercial-scale production of greater than 99 percent pure recycled lithium carbonate from black mass at its Georgia facility in September 2025, enabling plans for more than 15 kilotons annually in the US and Europe by 2027. Ecobat commissioned three fully operational recycling plants in Germany, the US, and the UK in April 2025, processing up to 10,000 tons annually with expansion plans to 25,000 tons. American Battery Technology Company launched a landmark partnership with Call2Recycle in September 2025 to expand direct-to-consumer lithium-ion battery recycling in the US. In April 2026, Altilium Metals secured an 18.5 million pound grant for its ACT 3 facility, the UK's first commercial EV battery recycling plant in Plymouth, which is designed to recover nickel MHP, lithium sulphate, and graphite from up to 24,000 EV batteries annually.
Lithium-ion Battery Recycling Market
Strategic Implications for 2026 Decision-Making
Capacity Timing and Feedstock Realities
One of the central tensions in this market is the gap between announced capacity and the practical realities of feedstock collection, sorting, and pretreatment. Growth is real, but it is not uniformly distributed across regions, chemistries, or battery formats. The research provides the analytical scaffolding to assess where demand for recycled materials is most credible, which feedstock streams are likely to be most accessible, and how collection infrastructure is evolving to meet industrial and consumer sources alike.
For 2026, this means that capacity decisions should be evaluated not just against headline market size, but against the maturity of local collection channels, the chemistry mix in a given region, and the probability of securing consistent offtake at acceptable quality levels. The report's segmentation and competitive analysis are designed to support exactly this kind of calibrated planning.
Supply Chain Resilience and Domestic Processing
A recurring theme across recent industry activity is the drive to strengthen domestic and regional supply chains for critical materials. Recycled cathode materials, lithium compounds, and other recovered intermediates are increasingly viewed as components of supply security, not just sustainability initiatives. Firms such as Redwood Materials and American Battery Technology Company are explicitly building capacity that supports domestic value chains, while Ascend Elements is extending its footprint toward Europe.
The report examines how these supply chain ambitions interact with market economics and regulatory direction. It helps leaders understand where recycled materials can provide differentiated value in procurement strategies, where policy may further incentivize local processing, and how recyclers and battery users can structure relationships that reduce exposure to raw material volatility.
Concentration, Competition, and the Bar for Differentiation
The competitive environment is not yet an oligopoly, but it is cohesive enough that concentration matters. The research notes that the top three competitors account for approximately 32.5 percent of market revenue, while the top five reach about 42.8 percent. This level of concentration indicates that scale players are establishing meaningful positions, but substantial space remains for differentiated entrants, regional specialists, and technology-focused operators.
In practical terms, this means that competitive advantage in 2026 will depend on more than simply building capacity. It will depend on recovery quality, process reliability, compliance readiness, feedstock access, and the ability to demonstrate material traceability to downstream customers. The report's competitive analysis is structured to help readers identify where those differentiators are emerging and which strategic moves are most likely to create durable positioning.
Who Should Use This Research and How
This research is built for executives and advisors who need a credible, structured view of a market that is simultaneously high-growth and high-complexity. It is relevant to recycling operators evaluating capacity and process choices, to battery and automotive companies assessing supply chain resilience, to investors analyzing where capital can be deployed with the strongest risk-adjusted rationale, and to policy-adjacent professionals who need to understand the commercial implications of evolving compliance frameworks.
The report is organized so that different functions can extract what they need without losing sight of the whole. Strategy teams can use the segmentation and competitive analysis to frame market entry, expansion, and partnership decisions. Operations leaders can draw on the process evaluation and regulatory integration to inform technology and compliance planning. Corporate development groups can use the company profiles and recent developments to identify partnership targets and monitor competitive signaling.
Forecasting Discipline for a Market in Motion
Forecasts in fast-moving industries can easily become either too optimistic or too cautious. The research is designed to avoid both traps by grounding projections in historical trajectory, current commercial activity, and the regulatory calendar that will shape the market over the next several years. The forecast period from 2026 through 2032 is presented not as a single line, but as a framework within which leadership teams can test assumptions about feedstock availability, process economics, and regional policy implementation.
Lithium Ion Battery Market
This approach is especially important for 2026 decisions because the market is at a point where early-mover advantages can be consolidated or eroded depending on execution. Companies that understand the interplay of regulation, chemistry mix, process economics, and competitive behavior will be better positioned to time investments, negotiate offtake, and build relationships that hold value as the market matures.
Conclusion: Use the Preview, Then Lock In the Full Picture
The lithium-ion battery recycling market in 2026 is too strategically important to navigate on partial information. The revenue trajectory, the pace of regulatory change, the diversity of recovery technologies, and the competitive moves already underway all point to a market where disciplined intelligence will separate durable strategies from reactive ones.
This overview has outlined the scope, structure, and strategic logic of PW Consulting's latest research. It has provided the macro picture, highlighted the segmentation architecture, introduced the competitive landscape and recent developments, and connected the analysis to the decisions that matter this year. What it has not done is replace the full report. The complete research delivers the deeper segmentation detail, the integrated regulatory analysis, and the competitive context needed to turn these themes into specific plans.
For teams planning capacity, partnerships, procurement, or investment in 2026, the next step is clear: use this preview to identify the questions that matter most, then access the full report to obtain the validated market intelligence required to answer them with confidence.
For detailed analysis of this topic, please visit the official page: Lithium-ion Battery Recycling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Digital Pathology Market Hits $1.13B in 2025, Projected to Reach $2B by 2032
By PW Consulting, 2026-09-16
Digital Pathology Market 2026: Strategic Intelligence for the Next Wave of Diagnostic Transformation
The global digital pathology market is entering a defining inflection point. As laboratories, health systems, and life science organizations navigate shifting regulatory frameworks, evolving reimbursement pathways, and the maturation of artificial intelligence in histopathology, strategic decision-making requires more than surface-level trend spotting. PW Consulting’s newest Digital Pathology Market research delivers the structured intelligence that executives, investors, and product leaders need to position themselves ahead of the 2026–2032 cycle.
This market has demonstrated consistent expansion over the past half-decade, driven by the migration from conventional glass-slide workflows to digitized imaging ecosystems, the integration of computational pathology tools, and growing institutional demand for telepathology and collaborative diagnostics. The market’s trajectory reflects both long-term secular adoption and short-term catalyst events that reshape competitive positioning. Our latest analysis quantifies that momentum, maps the structural forces shaping commercialization, and isolates the operational levers that will determine market share in the years ahead.
For leadership teams making capital allocation, partnership, or market-entry decisions in 2026, the window to act on validated intelligence is narrow. The research is designed not as a retrospective snapshot, but as a forward-looking strategic instrument—connecting macro trajectory, competitive dynamics, regulatory inflection points, and segment-level deployment patterns into a single decision-ready framework.
Growth Trajectory and the 2026–2032 Outlook
The market’s historical expansion provides a clear baseline for understanding where adoption is accelerating and where friction persists. Between 2020 and 2025, the global digital pathology market progressed from approximately 760.0 million USD to 1130.0 million USD, reflecting sustained demand for whole-slide imaging scanners, digital image management infrastructure, and workflow optimization tools. The forecast period from 2026 through 2032 projects continued expansion, with the market expected to reach roughly 2001.0 million USD by the end of the forecast horizon. The compound annual growth rate during this forecast window is estimated at 8.6 percent, signaling durable, above-trend growth rather than a temporary adoption spike.
This trajectory matters because it shapes the timing of competitive moves. A market expanding at this pace over a seven-year forecast window rewards early architecture decisions—platform interoperability, integration with laboratory information systems, and alignment with clinical workflow. Organizations that treat digital pathology as a discrete product purchase rather than a fused operational system risk ceding the efficiency gains that drive long-term adoption. Our research quantifies the scale of this opportunity while deliberately leaving the detailed segment-level breakdowns for the full report, where regional deployment patterns, type-specific revenue structures, and application-level demand concentrations are mapped in operational detail.
What the Research Covers: Operational Depth for Decision-Makers
A market study becomes strategically valuable only when it translates numbers into action. Our Digital Pathology Market research is built around the practical needs of executives who must evaluate investment timing, competitive vulnerability, regulatory exposure, and commercial execution risks. The report combines macro-level market quantification with structured analyses that support near-term planning.
The research framework includes comprehensive assessment of the following dimensions, each presented with enough granularity to inform real operational decisions:
- Market size and growth modeling across historical and forecast periods, with explicit treatment of base-year anchoring and forward trajectory assumptions
- Structural analysis of demand drivers, adoption barriers, and the interplay between technology readiness and institutional procurement cycles
- Competitive benchmarking of leading instrumentation, software, and AI-enabled diagnostic platforms, including product positioning, workflow integration, and cleared indications
- Regulatory and reimbursement context, with focus on classification pathways, clearance activity, and payer monitoring that will affect commercialization cadence
- Workflow and deployment considerations that distinguish research-use setups from diagnostic-grade implementation requirements
- Strategic scenario discussion for manufacturers, laboratory operators, and technology providers evaluating partnership, expansion, or differentiation plays
The overarching goal is to give leadership teams a shared factual foundation. Too often, strategic discussions around digital pathology are fragmented by incomplete data, outdated regulatory assumptions, or anecdotal adoption stories. This report consolidates the relevant evidence into a decision-oriented structure so that strategy sessions can move faster and with greater confidence.
Competitive Landscape: Leaders, Platforms, and Strategic Posture
The digital pathology market is shaped by a mix of established medical technology companies, specialized imaging manufacturers, and emerging AI-centric platforms. Competitive intensity is rising as organizations race to secure cleared workflows, expand integration capabilities, and lock in laboratory customers through platform stickiness. Our research profiles the companies that are setting the pace in 2026 and explains how their strategic postures influence market structure.
Several incumbents are competing around end-to-end diagnostic ecosystems. Koninklijke Philips N.V. continues to emphasize its IntelliSite Pathology Solution as a connected offering spanning scanners, image management, and AI-driven workflow tools intended to support primary diagnosis and telepathology. Leica Biosystems Nussloch GmbH, operating under Danaher Corporation, positions its Aperio GT series scanners alongside integrated digital pathology management software designed for anatomic pathology workflows. Hamamatsu Photonics K.K. maintains a strong footprint through its NanoZoomer series slide scanners and complementary image management solutions, reinforcing the importance of hardware-to-software continuity in laboratory adoption. F. Hoffmann-La Roche Ltd. advances its VENTANA DP series scanners and the Roche Digital Pathology Dx system with a specific focus on in-vitro diagnostic use, highlighting the increasing significance of cleared diagnostic intent in commercial messaging.
Alongside these hardware-centric leaders, platform and AI-focused companies are reshaping how laboratories think about computational pathology. Proscia Inc. provides the Concentriq enterprise platform with AI-powered tools oriented toward cancer diagnostics and workflow optimization, positioning software orchestration as a core value driver. PathAI Inc. offers the AISight Dx cloud-native image management and AI platform, which has been cleared for primary diagnosis, reflecting the broader push toward cloud-native infrastructure and regulatory-validated decision support. Indica Labs advances its HALO AP Dx enterprise digital pathology platform alongside AI tools cleared for primary diagnosis, reinforcing the trend toward consolidated enterprise deployments. Other notable participants include Sectra AB with digital pathology imaging and management solutions integrated with scanners for clinical workflows, Tribun Health with its CaloPix image management system and web-based platform incorporating AI applications, Epredia through its digital pathology scanners and image management software, and INFINITT Healthcare Co., Ltd. with its web-based INFINITT DPS viewing and management system cleared for primary diagnosis.
Strategic analysis in the report goes beyond company descriptions. It examines how product portfolios map to workflow requirements, where integration risk sits across scanner-to-platform combinations, how cleared indications affect competitive positioning, and which organizational capabilities are becoming table stakes. The research also captures recent market-moving events, including multiple FDA 510(k) clearances during 2025 across platforms such as PathAI’s AISight Dx, PathPresenter’s clinical viewer, Indica Labs’ HALO AP Dx paired with Leica’s Aperio GT 450 DX scanner, Roche’s VENTANA DP 600 scanner clearance, and INFINITT’s integration of the Hamamatsu NanoZoomer S360MD scanner in North America. These events are not isolated headlines; they signal how quickly cleared diagnostic workflows are accumulating and how that accumulation influences purchasing confidence.
Regulatory, Reimbursement, and Adoption Dynamics
Market growth in digital pathology is inseparable from the regulatory and reimbursement environment. The distinction between research use and diagnostic use remains a defining commercial boundary. According to Digital Pathology Association regulatory guidance, manufacturers may market digital pathology technology for research use only unless the FDA has issued a clearance or approval for a specific intended use. At the same time, several manufacturers have obtained FDA 510(k) clearances for digital pathology systems, scanners, and software as medical devices under product codes QKQ and PSY. Importantly, as of the most recent industry reporting referenced in our research, no manufacturer has yet received FDA approval of digital pathology technology for primary diagnosis, even as more than 1200 AI-enabled medical devices have received FDA clearance overall, with only a very small number authorized for primary histopathology use. This regulatory asymmetry creates both opportunity and risk: it accelerates monitored adoption while demanding careful product positioning and compliance discipline.
Whole Slide Scanner Market
Reimbursement dynamics are equally consequential. The College of American Pathologists reports that new digital pathology codes were added to the CPT manual effective January 1, 2024, with continued payer monitoring extending into 2026. For organizations evaluating adoption or expansion, the practical implication is that the financial case depends not only on workflow efficiency and diagnostic confidence, but also on the stability and evolution of coding and payment frameworks. The report addresses these dynamics as active variables rather than fixed assumptions, because reimbursement maturation can materially change the rate of institutional investment.
These dynamics shape the pace of adoption in three ways. First, they influence procurement timelines, since clinical-grade deployment requires clearer regulatory and reimbursement confidence than research-only setups. Second, they affect vendor selection criteria, as laboratories favor platforms that align with intended-use clarity and demonstrate compatibility with emerging coding structures. Third, they inform partnership strategy, because collaboration between scanner manufacturers, software vendors, and AI developers can shorten the path to integrated diagnostic workflows. Our analysis treats these factors as interconnected drivers, not isolated background noise.
Strategic Priority Areas for 2026
As the market moves deeper into the forecast period, the strategic questions facing organizations become more specific. Growth is no longer a matter of whether digital pathology will expand, but how value will be captured across hardware, software, AI-enabled workflow tools, and service models. The following areas merit close attention when formulating 2026 decisions:
- Platform interoperability and data continuity, because fragmented image management and incompatible scanner ecosystems slow adoption and increase total cost of ownership
- Regulatory positioning, since cleared indications and intended-use language increasingly influence procurement eligibility and competitive differentiation
- Workflow integration, particularly the alignment of digital pathology infrastructure with existing laboratory operations, information systems, and clinical decision pathways
- AI commercialization strategy, given the widening gap between AI device clearances in general and the limited number of authorizations applicable to primary histopathology use
- Regional and segment-specific deployment planning, as adoption rates, procurement structures, and reimbursement conditions differ materially across environments
- Capital timing, because the forecast period’s growth trajectory rewards early platform decisions while penalizing reactive or narrowly scoped investments
The report is designed to support these decisions with evidence rather than conjecture. It provides the market scale, structural analysis, and competitive intelligence that executives need to evaluate where to invest, what to prioritize, and how to interpret market signals as they evolve.
Digital Pathology Market
Why the Full Report Matters Now
Executive summaries and high-level forecasts can establish direction, but they do not give organizations the segment-level clarity required for concrete planning. The complete PW Consulting Digital Pathology Market research goes further. It details regional market distribution, type-based demand splits between human and veterinary pathology, and application-level concentration across disease diagnosis, drug discovery, and training and education. It also quantifies market concentration dynamics, providing context on how competitive share is distributed among leading participants. These details are intentionally reserved for the full report because they directly inform budget allocation, geographic prioritization, product focus, and partnership evaluation.
For 2026 decision-making, that level of precision is not optional. A general growth narrative cannot tell a manufacturer whether its strongest opportunity lies in scanner adoption versus software-led workflow transformation. It cannot tell a laboratory operator whether to accelerate diagnostic-grade deployment or phase adoption around reimbursement maturation. It cannot tell an investor whether competitive advantage will come from platform consolidation, AI-enabled workflow differentiation, or regional execution speed. The full research is built to answer those questions with disciplined analysis and actionable structure.
Conclusion: Acting on Evidence in a Fast-Moving Market
The digital pathology market is expanding on the strength of durable clinical, technological, and operational forces, but the path to capture value is becoming more complex. Regulatory nuance, reimbursement evolution, AI clearance constraints, and platform integration requirements all influence who gains share and how quickly. PW Consulting’s latest market research provides the comprehensive view that leadership teams need to make informed decisions in 2026 and beyond.
If your organization is planning investments, evaluating competitive positioning, or preparing for the next phase of diagnostic digitalization, the full report offers the intelligence required to move from direction to execution. Detailed segmentation data, competitive profiling, regulatory context, and forward market sizing are available in the complete study. Access the full research to obtain the segmentation-level intelligence, company-level benchmarking, and strategic analysis needed to act with confidence.
For detailed analysis of this topic, please visit the official page: Digital Pathology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Face Recognition Device Market Hits USD 7.4 Million in 2025, Projected 13.33% CAGR to 2032
By PW Consulting, 2026-09-16
Beyond the Frame: Strategic Intelligence for the Face Recognition Device Market 2026-2032
The global landscape for biometric security is undergoing a structural transformation. What was once a niche technology confined to high-security facilities has now permeated mainstream commerce, public safety, and consumer electronics. For executives navigating this complex environment, understanding the trajectory of the Face Recognition Device Market is no longer optional it is a critical component of risk management and growth strategy. PW Consulting's latest comprehensive study offers a detailed roadmap through this evolving terrain, providing the granular intelligence necessary to make informed decisions in 2026 and beyond.
As we move past the preliminary adoption phase, the market is characterized by a shift from standalone hardware to integrated ecosystems. Organizations are no longer just buying cameras they are investing in platforms that offer analytics, cloud connectivity, and seamless integration with existing security infrastructure. This evolution demands a deeper understanding of market mechanics, competitive positioning, and regulatory headwinds that can alter the viability of specific use cases overnight. Our research is designed to cut through the noise, offering clarity on where value is being created and where risks are accumulating.
Market Trajectory and Structural Growth
The financial scale of the industry underscores its strategic importance. Valued at approximately 7.4 billion USD in the base year of 2025, the market has demonstrated consistent resilience and expansion over the past half-decade. Historical data from 2020 through 2025 reveals a steady climb from 3.96 billion USD, reflecting accelerating adoption rates across diverse sectors. Looking forward, the forecast period spanning 2026 to 2032 projects a robust compound annual growth rate of 13.33 percent.
This growth is not merely linear. The projection suggests an acceleration in value capture, with the market expected to reach 8.66 billion USD in 2026 and continuing its ascent to 17.7 billion USD by 2032. Such velocity indicates that face recognition technology is transitioning from a discretionary investment to a core component of digital infrastructure. For stakeholders, this trajectory implies that timing is crucial. Entering the market too late may mean facing entrenched competitors and higher integration costs, while entering without proper intelligence can lead to misallocation of capital in saturated segments.
The growth narrative is supported by underlying technological advancements that reduce hardware costs while enhancing algorithmic accuracy. However, this expansion is uneven. Different segments of the market are maturing at different speeds, influenced by regional regulatory frameworks, infrastructure readiness, and specific industry pain points. Our analysis dissects these variations without relying on superficial aggregates, ensuring that clients understand the specific drivers propelling growth in their respective domains.
It is important to note that while the overall market size offers a macro view, the real strategic value lies in understanding the composition of this growth. The revenue mix is shaped by a combination of hardware devices, embedded modules, and software integrated devices. Each of these categories offers different margin profiles, implementation challenges, and lifecycle expectations. Similarly, the application landscape spans surveillance and security, access control, attendance and authentication, and other emerging use cases. The interplay between these types and applications creates a complex matrix where a solution suitable for one vertical may be ill-suited for another.
Regulatory Dynamics and Operational Resilience
No strategic assessment of the face recognition market in 2026 can ignore the regulatory environment. The industry is operating under a microscope of global scrutiny, with policymakers increasingly focused on privacy, ethical usage, and digital sovereignty. These regulations are not just legal hurdles they are market shapers that define the boundaries of viable business models.
In Europe, the legislative landscape has become particularly stringent. The EU AI Act prohibits real-time remote biometric identification for law enforcement in publicly accessible spaces effective February 2025. This regulation fundamentally alters the value proposition for certain surveillance applications within the European market. Furthermore, the EU Parliament has defined tech sovereignty as the capacity to build resilience and security in digital infrastructure, including face recognition systems. This directive suggests a future where supply chain localization and data residency may become critical competitive advantages.
Across Asia, India has notified the Digital Personal Data Protection Rules 2025, which set requirements for Significant Data Fiduciaries processing biometric facial data. With phased compliance until May 2027, organizations operating in or targeting the Indian market must plan their data governance strategies well in advance. Conversely, in North America, regulatory approaches remain more fragmented but permissive in specific contexts. For instance, the NYPD facial recognition policy permits use for suspect identification from recorded cameras at robberies and burglaries as of February 2026. This divergence in regulatory philosophy creates a complex global compliance map where a unified global strategy may not be feasible.
These regulatory shifts require companies to build flexibility into their product Roadmaps. Solutions that rely heavily on real-time public surveillance may face headwinds in certain jurisdictions, while access control and authentication solutions may find fewer barriers to entry. Our report analyzes these dynamics to help clients anticipate compliance costs and adjust their market entry strategies accordingly.
Face Recognition Device Market
Competitive Landscape and Innovation Vectors
The market is populated by a diverse set of players, ranging from established defense and security conglomerates to specialized biometric technology firms. Market concentration remains relatively moderate, with the top three players holding approximately 24.6 percent of the market share and the top five holding around 26.2 percent. This fragmentation suggests that there is still room for differentiation and niche disruption, although scale and ecosystem integration are becoming increasingly important.
Key incumbents are actively shaping the market through targeted innovation and product launches. NEC Corporation continues to provide cloud-based face recognition platforms and hardware solutions tailored for large-scale public safety, law enforcement, and national ID systems. Their focus on government-grade reliability positions them strongly in high-stakes environments. Similarly, IDEMIA manufactures VisionPass facial recognition access control devices and multimodal biometric systems, securing identities in airports, banking, and government applications. Their multimodal approach leverages the synergy between different biometric markers to enhance security.
Thales Group offers advanced facial recognition and multimodal biometric solutions specifically designed for border control, law enforcement, and enterprise security. Their integration of biometric data into broader security ecosystems gives them a distinct advantage in complex infrastructure projects. On the technology engine side, Cognitec Systems GmbH develops market-leading FaceVACS face recognition engines and systems for enterprise and government video surveillance and identification. Their software-centric approach allows for flexibility in hardware deployment.
Other significant players include Aware, Inc., which provides specialized face recognition hardware and software components used in biometric systems and applications, and Ayonix Corporation, which manufactures facial recognition cameras and solutions for security and access control applications. In the surveillance domain, VIVOTEK Inc. offers surveillance cameras with integrated cloud-based facial recognition and profile management features. Iris ID produces the iCAM TD200 simultaneous iris and face recognition cameras compatible with existing systems, highlighting the trend toward multimodal hardware.
Recent developments illustrate the pace of innovation. In June 2025, VIVOTEK added cloud-based facial recognition with profile search and management, plus a Smart Privacy Switch, to their VORTEX xPro license for real-time identification. This update addresses both functionality and privacy concerns, a dual priority for modern deployments. In October 2025, Iris ID launched the iCAM TD200 simultaneous iris and face recognition camera plug compatible with hundreds of existing applications. This launch emphasizes interoperability and the reduction of friction in upgrading legacy systems.
These moves signal a market where differentiation is increasingly found in software capabilities, privacy features, and compatibility rather than hardware specifications alone. Companies that can offer seamless integration with existing infrastructure while providing robust privacy controls are likely to capture greater market share.
Strategic Applications and Deployment Horizons
Understanding where face recognition technology delivers the highest return on investment is critical for capital allocation. The market supports a wide array of applications, each with distinct growth drivers and adoption barriers. Surveillance and security remain a dominant force, driven by the need for proactive threat detection and evidence collection. However, the regulatory constraints in certain regions mean that deployment strategies must be carefully calibrated to local laws.
Access control represents another major pillar of demand. As organizations move away from key cards and passwords toward biometric authentication, the demand for reliable, fast, and contactless entry systems continues to grow. This shift is accelerated by health concerns and the desire for enhanced security hygiene. Attendance and authentication also form a significant segment, particularly in enterprise and educational settings where accurate tracking is required for payroll, safety, and resource management.
Beyond these core areas, there are emerging applications that warrant attention. The integration of face recognition into consumer devices, retail analytics, and personalized customer experiences is creating new revenue streams. However, these areas are also where privacy expectations are highest. Success in these domains requires not just technical capability but also a strong framework for data ethics and user consent.
Our report delves into the nuances of these applications, examining how different industries are prioritizing their biometric investments. We analyze the specific pain points that drive adoption in each vertical and identify the technical requirements necessary to meet those needs. This level of detail is essential for vendors looking to tailor their offerings and for enterprises seeking to optimize their security architectures.
Key Components of the Research Study
To navigate this complex environment, decision-makers need a toolkit that covers quantitative data, qualitative analysis, and forward-looking scenarios. Our Face Recognition Device Market research study is structured to provide exactly that. The report begins with a comprehensive executive summary that highlights the most critical findings and strategic implications. This is followed by a detailed methodology section that ensures transparency and reproducibility of the findings.
The core of the report provides a rigorous analysis of market size and growth projections. We break down the revenue data across the forecast period, allowing clients to model their own growth expectations against industry trends. The segmentation analysis explores the market by region, type, and application. While we present the macro trends here, the full report provides the detailed breakdown necessary for regional planning and product portfolio management. This includes an assessment of the historical performance from 2020 to 2025, which serves as a baseline for evaluating the validity of our forward-looking estimates.
A significant portion of the study is dedicated to the competitive landscape. We profile key companies, analyzing their product portfolios, strategic partnerships, and recent developments. This section helps clients benchmark their own capabilities against the market leaders and identify potential gaps in the marketplace. We also assess the market concentration dynamics, providing insight into the balance of power between large conglomerates and specialized niche players.
Facial Recognition Payment Devices Market
The regulatory analysis section is updated with the latest legislation and policy changes affecting the biometric industry. We provide a jurisdiction-by-jurisdiction overview of compliance requirements, helping organizations manage legal risk. Additionally, the report includes a technology trends chapter that examines the cutting edge of biometric algorithms, sensor technology, and data security protocols.
Finally, the study concludes with strategic recommendations for various stakeholders, including manufacturers, system integrators, and end-user organizations. These recommendations are grounded in the data and analysis presented throughout the report, offering actionable guidance for navigating the market in 2026 and beyond.
Conclusion: The Imperative for Intelligence
The Face Recognition Device Market is at a pivotal juncture. The combination of robust growth, technological innovation, and regulatory complexity creates both significant opportunities and substantial risks. Organizations that rely on outdated information or superficial market estimates are likely to misjudge the timing and scale of opportunities. Conversely, those that invest in deep, data-driven intelligence will be better positioned to capitalize on the market's expansion while mitigating compliance and reputational risks.
This overview provides a glimpse into the breadth and depth of our analysis, but the full picture requires access to the complete dataset and proprietary modeling. The specific regional dynamics, the precise valuation of each segment, and the detailed competitive benchmarking contained in the full report are essential for crafting a precise strategy. We invite you to explore the complete Face Recognition Device Market research study to gain the comprehensive intelligence needed to lead in this rapidly evolving industry.
For detailed analysis of this topic, please visit the official page: Face Recognition Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Agritourism Market Hits USD 9.01 Billion in 2025, Forecasts 11.9% CAGR to 2032
By PW Consulting, 2026-09-16
Agritourism Market Outlook 2026: Capitalizing on the Experience Economy via Strategic Intelligence
The convergence of agricultural production and experiential travel has evolved from a niche diversification tactic into a structural growth engine for rural economies. As hospitality consumers increasingly seek authenticity, provenance, and direct connection to land-based operations, agritourism has matured into a standalone commercial discipline. Our latest market research synthesizes historical trajectories, forward-looking demand signals, and competitive positioning to equip executive teams with the institutional intelligence required to navigate this rapidly shifting landscape. With the global market expanding from 5.8 billion USD in 2020 to a projected 10.43 billion USD in 2026, and an anticipated compound annual growth rate of 11.9 percent through 2032, the sector presents both remarkable expansion potential and complex operational trade-offs. Leaders who base capital allocation, partnership strategies, and market entry decisions on fragmented or retrospective data risk misjudging regional regulatory friction, consumer preference volatility, and the pace of infrastructure development. This analysis outlines how a disciplined, data-driven framework transforms uncertainty into executable strategy.
Executive Snapshot: Macro Trajectory and Structural Shifts
The agritourism sector has demonstrated consistent upward momentum over the past half-decade, reflecting a broader consumer migration toward localized, immersive, and mission-aligned travel. Revenue streams have expanded across direct-to-consumer farm interfaces, curated educational programming, and recreational event models, creating a diversified commercial ecosystem that rewards operators capable of balancing agricultural functionality with hospitality-grade service standards. The baseline forecast indicates continued acceleration, yet the pace and profitability of growth will vary significantly depending on regional tourism infrastructure, municipal zoning frameworks, seasonal capacity utilization, and the degree to which operators can integrate value-added processing into their visitor experience. Market concentration metrics further signal an industry in consolidation, where established players hold disproportionate share while emergent regional operators compete by specializing in high-touch experiences, targeted demographic segments, or hybrid agricultural-servitization models. Understanding where scale advantages concentrate, and where agile niche execution can outpace incumbents, is essential for portfolio planning and competitive benchmarking.
Report Architecture: How This Study Maps to Operational Decision-Making
A market intelligence briefing only delivers strategic value when it translates high-level trends into operational levers. This study is designed around that translation layer, moving systematically from macro sizing to actionable execution pathways. The research framework encompasses historical performance baselines, multi-year forecast modeling across primary commercial vectors, and a granular assessment of the competitive landscape. It evaluates how distinct experiential formats are monetized, how hospitality expectations are reshaping traditional farm operations, and how regulatory environments influence site development, liability exposure, and partnership viability. Readers will find structured sections covering demand drivers, consumer segmentation behaviors, capital deployment considerations, and the operational requirements of scaling agritourism from seasonal add-on activity to a year-round revenue architecture. The report deliberately avoids superficial market commentary and instead focuses on the mechanics of growth: visitor acquisition channels, experience design optimization, service capacity constraints, and the financial modeling required to sustain occupancy and repeat visitation. By anchoring analysis in measurable market signals rather than aspirational narratives, the study provides a repeatable methodology for stress-testing strategic options across different risk profiles and capital environments.
Agritourism Market
Competitive Landscape: Benchmarking Established Operators and Sector Archetypes
Agritourism is not a homogenous market. It operates as a layered ecosystem where luxury hospitality brands, specialized tour operators, educational programming providers, and regional farm consortia compete on different value propositions. Leading operators illustrate the strategic diversity available within the sector. High-end integrated resorts demonstrate how agricultural land can be positioned as a premium hospitality asset, combining working farm operations with curated culinary journeys, outdoor programming, and multi-day accommodation models that command elevated per-guest valuations. By contrast, escorted agricultural tour providers focus on connective infrastructure, linking international and domestic visitors to producer networks, rural tourism operations, and behind-the-scenes farming experiences that emphasize authenticity and direct producer engagement. Specialist tour firms extend this model further by offering inspection-oriented and bespoke itineraries designed for associations, professional audiences, and organizations seeking structured exposure to agricultural systems. Custom group travel providers layer programming around rural site visits for professionals, students, and sector enthusiasts, while dedicated agri-technical and educational tour operators build repeatable B2B and institutional channels through association partnerships and organizational programming.
These archetypes reveal distinct strategic postures. Luxury and integrated hospitality models compete on exclusivity, service depth, and land-based brand narrative. Tour and facilitation operators compete on access, logistics reliability, and curated producer relationships. Educational and institutional operators differentiate through content authority, program design, and repeatable group frameworks. Each model carries its own growth requirements, staffing demands, risk profile, and margin structure. Executive teams evaluating entry or expansion must assess where their organizational capabilities align within these competitive clusters, which consumer segments justify premium pricing, and which operational components can be sourced through partnerships rather than built in-house. The competitive analysis in this report maps these dynamics in detail, outlining positioning strategies, brand differentiation paths, and the implications of operating at different points along the experience spectrum.
Regulatory Friction and Structural Dynamics Shaping Deployment Timelines
Growth in agritourism is increasingly mediated by policy environments, land-use frameworks, and liability architectures. Regulatory signals are no longer peripheral; they directly affect site development schedules, operational scope, insurance cost structures, and the feasibility of scaling visitor-facing activities on agricultural land. Recent guidance published by regional agricultural authorities has begun to establish clearer baselines for value-added processing and agritourism operations, signaling a move toward more formalized compliance expectations. At the same time, local planning proposals addressing gatherings on farmland demonstrate how municipal priorities can reshape allowable visitor experiences, parking logistics, event frequency, and nighttime operations. Executive teams planning capital deployment must treat regulatory analysis as a core planning variable rather than a post-investment compliance task. Strategic advantage increasingly belongs to organizations that map jurisdictional variance early, incorporate permitting lead times into rollout roadmaps, and design flexible experience modules that can adapt to changing land-use parameters without sacrificing core revenue logic. On the policy side, broader legislative frameworks influencing program eligibility and income classification have begun altering the economics of farm-based diversification, particularly for operators heavily reliant on direct marketing and visitor revenue. These developments highlight the importance of scenario planning, where growth strategies account not only for demand-side opportunity but also for the administrative cadence and compliance cost embedded in different jurisdictions.
Operations Momentum and the Institutionalization of Agritourism
The sector is also maturing through organized industry activity that is accelerating knowledge transfer, peer benchmarking, and professionalization. Anniversary conventions, regional tourism workshops, and inaugural global conferences are creating venues where operators exchange practical insights on product development, seasonal planning, partnership formation, and experience economy integration. These gatherings reflect a broader shift from ad hoc farm diversification to coordinated industry building, where operators invest in staff training, guest journey design, and repeatable program structures rather than relying solely on informal rural charm. Alongside event-based momentum, select operators are launching dedicated retreat-style offerings that emphasize working-farm immersion, animal engagement, heritage storytelling, and natural setting experiences. Such launches underline the growing commercial appeal of multi-day stays and curated agricultural immersion, reinforcing the need for operators to think beyond day-visit revenue models.
Federal and regional economic data further support the migration toward experience-led farm revenue. Agritourism and recreational service income have expanded materially over the past decade, with meaningful participation spread across counties and median outcomes indicating broad-based, not merely outlier-driven, adoption. This trajectory suggests durable structural demand rather than a temporary travel cycle effect. Yet scale remains uneven. Margin quality, seasonality management, and the ability to convert first-time visitors into repeat guests continue to differentiate high-performing operators from those that merely capture transient foot traffic. The strategic question is therefore not whether demand exists, but how organizations build the operational discipline required to monetize it consistently across weather cycles, staffing constraints, and shifting consumer expectations.
Translating Market Intelligence into 2026 Decision-Making
For executives entering 2026, the practical challenge is prioritization under uncertainty. Capital can be allocated toward destination development, experience packaging, marketing acquisition, partnership expansion, or regulatory navigation, but each path carries different payback horizons and risk exposures. The strategic value of a comprehensive market study lies in its ability to compress that decision space by clarifying where growth is most defensible, which formats align with target demographics, and where competitive white space remains under-monetized. Organizations that build strategy on partial information often overinvest in visible but saturated demand channels while underweighting the operational complexity of service delivery, permitting, and year-round occupancy. Conversely, leaders who ground their planning in sector-specific sizing, segmentation dynamics, and competitive benchmarking can sequence investments more effectively, aligning capability building with the customer segments and experience formats most likely to sustain revenue resilience.
The report accompanying this article is designed to support that disciplined approach. It consolidates historical performance signals, forecast trajectories, competitive archetypes, and structural dynamics into a unified reference framework. By focusing on the mechanics of growth rather than isolated statistics, it enables leadership teams to evaluate entry timing, partnership strategy, experience portfolio design, and regional expansion with greater confidence. Agritourism is increasingly a strategic business discipline rather than a secondary farm activity, and the organizations that treat it accordingly will be better positioned to convert experiential demand into durable commercial advantage.
Strategic Conclusion and Next Steps
The agritourism market is moving into a phase where differentiation, operational precision, and regulatory fluency determine competitive outcomes more than raw destination appeal alone. The projected expansion curve through 2032 underscores the magnitude of the opportunity, while the competitive and regulatory context underscores the need for careful execution. Executive teams seeking to convert this opportunity into measurable performance should treat market intelligence as an active planning instrument, integrating sizing context, segmentation logic, competitor positioning, and policy dynamics into a coherent investment thesis. The full study provides the depth required to pressure-test those decisions across multiple growth scenarios and operational assumptions. We invite leadership teams, investors, and strategy functions to engage with the complete research package to align their 2026 planning with the market realities shaping this sector.
Worldwide Culinary Tourism Market
For detailed analysis of this topic, please visit the official page: Agritourism Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Face Recognition Market Hits $3.65B in 2025, Projects 14.5% CAGR to $9.36B by 2032
By PW Consulting, 2026-09-16
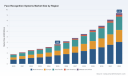
Navigating the Face Recognition Systems Market: Strategic Intelligence for Enterprise Decision-Makers in 2026
Executive Perspective
The face recognition systems market has transitioned from an emerging technology category into a foundational infrastructure layer for enterprise security, identity verification, and operational efficiency. As organizations across sectors reassess their technology portfolios in the wake of shifting regulatory frameworks and accelerated AI maturity, the need for precise, forward-looking market intelligence has never been more critical. This industry insight introduces our latest comprehensive study on the Face Recognition Systems Market, a research product designed specifically for executives who must align technology investment with strategic growth trajectories through 2032.
The macroeconomic trajectory underscores the magnitude of this opportunity. From a base valuation of $3.65 billion in 2025, the market is projected to exceed $9.36 billion by 2032, expanding at a compound annual growth rate of 14.5 percent. These figures represent more than raw revenue projections; they signal a structural shift in how enterprises deploy biometric identification, allocate capital toward hardware-software integration, and navigate an increasingly complex competitive landscape. The research accompanying this overview translates these high-level trends into actionable intelligence, enabling leadership teams to separate signal from noise and make informed commitments in a crowded technology ecosystem.
Macro Demand Landscape and Growth Drivers
Market expansion over the past half-decade has been consistently robust. Revenue climbed from $1.8 billion in 2020 through successive annual increases, surpassing the $3 billion threshold by 2024 and reaching $3.65 billion at the 2025 mark. The momentum is expected to maintain its upward trajectory, with forward estimates indicating sustained double-digit growth each year through the end of the forecast window. This growth profile reflects the compounding effect of multiple reinforcing demand drivers rather than reliance on a single deployment vertical.
Enterprise adoption is being accelerated by the convergence of three core catalysts. First, organizations are prioritizing physical access control and identity verification as part of broader zero-trust security architectures. Second, public sector programs continue to expand facial recognition deployments for border management, law enforcement support, and national identity initiatives, creating durable procurement pipelines that stimulate both hardware and software innovation. Third, algorithmic accuracy improvements, supported by standardized evaluation frameworks and computational advances, are lowering the perceived risk profile for enterprise consumers who previously hesitated due to performance or demographic bias concerns.
Hardware and computational requirements add another layer of strategic consideration for procurement teams. High-accuracy identification workflows increasingly depend on GPU or NPU acceleration to sustain performance at scale, while CPU-only configurations are generally constrained to lightweight models with reduced matching fidelity. Understanding where a given deployment falls on this hardware spectrum directly affects total cost of ownership, integration timelines, and long-term scalability. Our research examines these technical interdependencies in detail, providing IT architects and procurement leaders with the context needed to evaluate vendor proposals against realistic infrastructure assumptions.
Regulatory Architecture and Compliance Realities
Any forward-looking market strategy must account for the evolving regulatory environment that shapes procurement approvals, deployment boundaries, and data governance obligations. Regulatory activity across major jurisdictions has intensified, and the cumulative effect is reshaping how vendors position their platforms and how enterprises structure their risk assessments.
In the United States, the Facial Recognition Act of 2025 requires law enforcement agencies using facial recognition technology to undergo annual accuracy and bias testing conducted by NIST, establishing a new baseline for accountability in public sector deployments. State-level mandates add further complexity, such as Virginia law requiring approval for facial recognition technology utilization by local governments, effective July 1, 2026. These domestic requirements create a patchwork that enterprise vendors must navigate carefully, particularly when offering cross-jurisdictional services or multi-agency platforms.
International frameworks introduce additional compliance dimensions. The European Union AI Act classifies real-time facial recognition in public spaces for law enforcement as high-risk, with prohibitions unless authorized for important public security reasons, effectively shaping market participation rules for vendors operating in or serving EU territories. Meanwhile, China's Provisions on Security Management in the Application of Facial Recognition Technology took effect June 1, 2025, establishing data security requirements that influence product design, data handling protocols, and partnership structures within one of the world's largest deployment markets.
Our analysis treats regulatory dynamics not as peripheral background information but as strategic variables that affect pricing power, go-to-market timelines, and competitive differentiation. Companies that integrate compliance readiness into their product roadmaps and contract structures can convert regulatory complexity into barriers to entry, while those that treat it as an afterthought risk stalled deployments and reputational exposure.
Competitive Field and Differentiation Vectors
The competitive environment reflects a mix of specialized biometric technology providers, large industrial technology firms, and AI-native algorithm developers. Market concentration remains pronounced, which has direct implications for procurement leverage, partnership options, and the feasibility of vendor diversification strategies. Understanding the positioning of leading players helps organizations assess where consolidation pressure is strongest and where niche differentiation still creates room for specialized suppliers.
Several firms illustrate the diversity of competitive strategies currently shaping the market. Clearview AI provides facial recognition platforms and commercial access to large-scale image databases for law enforcement, border control, and investigative applications. Its recent track record includes a one-year contract valued at $225,000 with U.S. Customs and Border Protection for facial recognition services in border screening and tactical targeting, alongside a SOC 2 attestation with zero exceptions validating data security and privacy standards. These developments reflect a dual emphasis on operational scale and compliance credibility.
Face Recognition Device Market
NEC Corporation offers NeoFace facial recognition systems and platforms for public safety, law enforcement, and national ID programs. Its technology has been recognized as ranked the world's most accurate in the latest NIST FRTE 1:N identification test using a 12 million person database, an achievement that highlights the competitive importance of benchmark performance in government and high-stakes enterprise procurement. IDEMIA, headquartered in Paris, delivers biometric identification solutions including facial recognition for border control, law enforcement, and government identity programs, while Thales Group provides facial recognition and biometric systems for law enforcement, aviation security, and public safety applications. These two European-based organizations underscore the strategic role of government-adjacent identity infrastructure in sustained demand.
On the industrial and machine vision side, Cognex Corporation manufactures and sells machine vision and 3D vision systems integrated with facial recognition for industrial, security, and access control uses, demonstrating how recognition capability is increasingly embedded within broader automation ecosystems. Panasonic supplies facial recognition hardware and software solutions for surveillance, access control, and border security, reinforcing the hardware-software integration thesis across multiple deployment settings.
AI-native companies are pursuing differentiation through algorithmic precision and responsible deployment framing. Paravision develops and commercializes AI-powered facial recognition algorithms optimized for accuracy and ethical deployment in enterprise and security sectors, a positioning that aligns with growing procurement emphasis on bias performance and governance assurances. On the Asia-Pacific side, SenseTime Group offers facial recognition and AI vision systems deployed in smart cities, law enforcement, and public security applications, while Megvii Technology develops Face++ facial recognition technology and platforms for identity verification, security, and commercial use. Both illustrate how regional deployment ecosystems and large-scale public security programs shape product roadmaps and commercial scale.
Testing Benchmarks and Performance Standards as Market Signals
Independent evaluation frameworks increasingly function as market signals that influence purchasing decisions, vendor comparisons, and product development priorities. NIST activity in 2026 underscores the centrality of standardized testing to market confidence. In January 2026, NIST issued an FRTE 1:1 report with comprehensive accuracy metrics including demographic performance and provisional duration updates for algorithms submitted since September 2025. In May 2026, NIST released an updated FRTE 1:1 Verification report with participation statistics and performance benchmarks across algorithms. These recurring updates give procurement teams and technical evaluators a structured basis for comparing vendor claims against reproducible performance data.
For enterprise strategists, benchmark performance is not merely a technical metric; it is a procurement catalyst that can shorten evaluation cycles, support internal approval processes, and reduce perceived deployment risk. At the same time, performance claims must be evaluated in the context of specific use cases, population demographics, environmental conditions, and matching configurations. Our research dissects how testing outcomes translate into commercial messaging, where benchmark leadership translates into procurement advantage, and where gaps between test conditions and operational realities create opportunities for differentiated positioning.
Applied Deployment Domains and Segment Considerations
Demand is distributed across multiple functional applications, each with distinct performance requirements, procurement rhythms, and integration constraints. Access control remains a dominant use case, driven by organizations seeking to replace or augment physical credentialing systems with biometric verification that reduces credential leakage and streamlines entry workflows. Security and surveillance applications extend recognition capability into broader monitoring and situational awareness contexts, where throughput, false-positive tolerance, and operator support requirements shape system selection. Face identification use cases, including 1:1 verification and 1:N identification workflows, introduce different computational demands and accuracy expectations, and they often intersect with compliance frameworks that vary by jurisdiction and end-user type.
Technology architecture choices further influence competitive positioning and procurement decisions. Decision-makers must evaluate the trade-offs across recognition modalities and understand how each maps to cost, accuracy, and deployment environment. The shift from single-modality deployments to multi-layered recognition strategies is becoming more visible as organizations seek redundancy, improved resilience, and broader coverage across lighting, distance, and pose variation conditions. Segmentation choices also affect hardware procurement, integration complexity, and long-term maintenance commitments, all of which should be factored into enterprise budgeting and vendor evaluation.
What the Research Delivers
This study is structured to provide executive and technical audiences with actionable intelligence rather than abstracted trend summaries. The report combines quantified market sizing, forward forecasts, and segment-level analysis with qualitative assessments of competitive behavior, regulatory exposure, and technology adoption patterns. Readers will find detailed coverage of demand drivers, deployment contexts, hardware and algorithmic considerations, and the strategic implications of benchmark performance and compliance requirements.
The analysis is designed to support multiple decision contexts. Product leaders can use the findings to align roadmaps with demand concentration and performance expectations. Procurement teams can leverage the competitive and segment analysis to sharpen evaluation criteria and negotiation positioning. Investment and strategy functions can draw on the forecast trajectory and market concentration insights to assess growth pathways and consolidation risk. Policy-aware organizations can use the regulatory mapping to anticipate approval friction, data handling obligations, and the operational implications of jurisdiction-specific mandates.
Strategic Imperatives for 2026 and Beyond
The face recognition systems market presents a rare combination of expanding demand, performance-driven competition, and regulatory recalibration. For enterprises planning capital allocation and technology strategy in 2026, the strategic question is not whether facial recognition will continue to gain adoption, but how to engage with the market in a way that balances growth opportunity against compliance exposure, integration complexity, and competitive dependency.
Face Recognition Systems Market
Organizations that approach this market with structured intelligence can make more disciplined choices about vendor selection, deployment sequencing, hardware investment, and compliance readiness. They can also better anticipate where consolidation, benchmark leadership, and regulatory pressure will reshape supplier dynamics over the next several years. The full study expands on these themes with detailed market projections, segment analysis, competitive profiling, and scenario considerations intended to support concrete planning decisions.
This overview has been crafted to provide a credible, professional foundation for understanding the market's direction and the strategic stakes involved. To access the complete dataset, segment-level breakdowns, competitive mapping, and forward forecasts that support enterprise planning through 2032, we invite decision-makers to consult the full market research publication.
For detailed analysis of this topic, please visit the official page: Face Recognition Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Current Sensing Resistor Market to Reach $265.1 Million by 2032, CAGR 5.59%
By PW Consulting, 2026-09-16
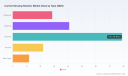
Strategic Intelligence Report: The Current Sensing Resistor Market Outlook 2026–2032
As the global electronics industry accelerates toward electrification and smarter power distribution, the role of precision current sensing has evolved from a passive compliance requirement to a critical enabler of system efficiency, safety, and performance. PW Consulting presents this executive briefing on the Current Sensing Resistor Market, drawing on comprehensive historical tracking from 2020 through 2025 and detailed forward-looking projections spanning 2026 to 2032. This analysis is designed to equip strategic leaders, procurement directors, and R&D planning teams with the contextual depth needed to navigate supply chain complexities, technology transitions, and competitive shifts in the coming years.
Market Trajectory and Structural Growth Signals
The historical record from 2020 to 2025 reveals a consistent upward trajectory in global revenue for current sensing resistors, reflecting sustained capital investment in power electronics, automotive electrification, and industrial automation. After reaching a baseline level in 2020, the market steadily expanded through 2022 and 2023, driven by early-cycle adoption in automotive battery management systems and data center power infrastructure. By 2024, demand acceleration entered a more pronounced phase, with 2025 closing the historical window at a significantly elevated revenue mark.
Our forecasting model projects continued expansion through 2032, with a compound annual growth rate of 5.59 percent across the full forecast horizon. The progression from the 2025 baseline into the mid-2020s suggests that incremental capacity additions, alongside the phasing in of next-generation powertrain architectures and industrial motor drives, will sustain revenue momentum. As the timeline extends further toward the early 2030s, the growth curve reflects the compounding effect of platform migrations in electric vehicles, the scaling of renewable energy inverters, and the continuous miniaturization of high-power shunt elements. It is important to note that these are structural, ecosystem-level signals: the detailed breakdown of how this growth distributes across specific regional corridors, product architectures, and end-use verticals remains a core deliverable of the full report.
Technology Transitions and the Shift Toward High-Density Shunt Architectures
A defining theme of the 2026–2032 period is the ongoing migration from conventional thick-film platforms toward higher-performance metal-based and sintered shunt technologies. Industry data points to sintered metal current sense chip resistors achieving power dissipation levels significantly above traditional thick-film equivalents while preserving low temperature coefficient of resistance. This material-level advancement allows designers to increase current-carrying capacity within shrinking board footprints, a constraint that has become central to automotive module packaging and compact industrial power supplies.
At the same time, metal foil and metal strip architectures continue to hold relevance where ultra-low TCR and long-term stability are non-negotiable, particularly in precision instrumentation and high-reliability automotive traction environments. Wirewound and thin-film solutions occupy adjacent niches, each carrying distinct trade-offs in inductance, power handling, and manufacturing economics. The strategic question for component engineers is no longer which technology dominates in absolute terms, but rather which platform aligns with a given application's thermal, electrical, and qualification requirements at acceptable total cost of ownership. The complete study maps these technology trade-offs against actual design requirements and quantifies the relative revenue share each type commands across the broader product landscape.
Competitive Landscape: Differentiation Through Qualification and Platform Strategy
The current sensing resistor market remains moderately fragmented, with top-three concentration levels indicating that while scale players exert meaningful influence, specialized mid-tier manufacturers retain significant footholds through technical differentiation and regional distribution strength. The competitive battleground has shifted decisively from pure price competition toward qualification readiness, power-density innovation, and application-specific portfolio breadth.
Bourns, Inc. has reinforced its automotive and power electronics positioning with the launch of its CSS4C-1216 Series 4-terminal current sense resistors, designed to meet AEC-Q200 expectations with up to 5 watts of power handling, low inductance, and a compact form factor. This family complements the company's Riedon shunt portfolio, which spans metal strip and thick-film elements tailored for EV battery management and industrial power conversion. In parallel, Vishay Intertechnology, Inc. has expanded its Power Metal Strip lineage with the WSLF1206 and WSBE families, delivering 5-watt capability within a 1206 footprint while maintaining low resistance values optimized for high-efficiency EV power systems and board-space-sensitive designs.
ROHM Co., Ltd. has drawn attention with its UCR10C Series sintered metal shunt resistors, which push rated power to 1.25 W within a 2012 metric size and carry AEC-Q100 qualification for automotive motor control and power electronics applications. This product direction underscores a broader industry trend toward sintered metal platforms as credible alternatives to traditional thick-film offerings in thermally constrained environments. TT Electronics has similarly advanced its SMT shunt portfolio with the LRMAK Series, a 4-terminal family qualified to AEC-Q200 standards, offering resistances down to 500 µΩ and up to 2 watts of power for automotive motor control and industrial current sensing.
Beyond these headline developments, the competitive fabric includes Ohmite Manufacturing Co., whose LVK and PCS Series address low-resistance, high-power, and chip current sense applications with precision thick-film and metal implementations. TE Connectivity Ltd. contributes CGS Series metal chip resistors and high-current shunts positioned for automotive and industrial sensing architectures. KOA Speer Electronics, Inc. maintains a focus on precision low-ohm applications through its KDV and PSJ2 Series metal film and power shunt offerings, while Caddock Electronics, Inc. emphasizes accuracy and stability in precision thick-film current sense resistors intended for instrumentation and power monitoring. In the European precision segment, Isabellenhütte Heusler GmbH & Co. KG supplies precision shunt resistors and metal-based current sensors engineered for high-accuracy demands in EV and power electronics environments.
Collectively, these players illustrate a market where product qualifications, package density, and application-specific support are becoming the primary vectors of differentiation. The full report provides a deeper comparative assessment of competitive positioning, recent product cadence, and the strategic implications of these launches for procurement prioritization and second-source planning.
Regulatory, Qualification, and Supply Chain Considerations as Strategic Filters
Automotive-grade qualification has emerged as one of the most consequential filters shaping demand patterns in the current sensing resistor segment. AEC-Q200 compliance is no longer a peripheral bonus; it is increasingly a prerequisite for participation in EV battery management, traction inverter, and frequency converter designs. This qualification dynamic is visible across multiple recent product introductions, from Bourns' CSS4C-1216 family to TT Electronics' LRMAK Series and Vishay's Power Metal Strip platforms, all of which are positioned with explicit automotive reliability expectations.
Environmental and material compliance further shapes the competitive field. Recent sintered metal shunt introductions, including ROHM's UCR10C Series, are fully lead-free and RoHS compliant, with automotive-grade temperature cycle durability integrated into the product claim set. For supply chain and compliance teams, these specifications reduce integration risk in regions with stringent environmental mandates and simplify multi-source qualification where suppliers must demonstrate equivalent regulatory alignment.
On the commercial side, material cost dynamics are beginning to influence device selection decisions. The emergence of sintered metal current sense chips capable of delivering up to 2x higher power dissipation than traditional thick-film equivalents while maintaining low TCR is prompting a reevaluation of thermal derating margins and board-area budgets. As these products mature into volume production, the cost-per-watt-per-cubic-millimeter calculus may tilt in favor of advanced shunt architectures in high-power applications, even if initial unit pricing remains elevated. The complete study dissects these shifting cost-performance trade-offs and their implications for make-versus-buy, design-in prioritization, and inventory strategy.
Current Sensing Resistor Market
Worldwide Precision Resistors Market
Findings and the Strategic Case for Detailed Market Intelligence
A market growing at a mid-single-digit CAGR over a seven-year horizon does not move by accident. It is propelled by interlocking forces: electrification roadmaps in automotive original equipment manufacturing, the scaling of industrial motor drives and renewable inverters, the push for higher power density in consumer and telecommunications power supplies, and the relentless requirement for more accurate current measurement in closed-loop control architectures. Each of these forces exerts a distinct pull on product type selection, qualification requirements, and regional sourcing patterns.
Yet the headline market trajectory only tells part of the story. The strategic decisions that separate resilient portfolios from vulnerable ones depend on operational intelligence: which product types are gaining share in which applications, how regional demand differs in cadence and qualification emphasis, which manufacturers are converting product launches into validated design wins, and how material and qualification constraints will reshape total cost structures. These are precisely the dimensions that our full Current Sensing Resistor Market research unpacks with granular segmentation, revenue allocations, and forward-looking scenario modeling.
For procurement leaders, the value lies in anticipating qualification shifts, identifying credible second sources before supply constraints materialize, and understanding where thermal-performance breakthroughs are likely to displace incumbents. For R&D and application engineering teams, the value lies in mapping technology trade-offs to actual system requirements and avoiding over-investment in architectures that are losing share in key verticals. For executive planning teams, the value lies in aligning capacity, tooling, and supplier relationships to the demand waves that the forecast period will bring.
PW Consulting's full market study transforms these strategic questions into structured answers. It integrates historical performance, projected revenue paths, segmentation detail across resin types, applications, and regional demand centers, and a competitive profile of the manufacturers reshaping the segment. The report is designed to be immediately usable: a reference foundation for design-in strategy, supplier evaluation, pricing negotiations, and long-range capacity planning.
To access the complete segmentation detail, competitive benchmarking, and full forecast tables that underpin this briefing, please visit the PW Consulting market research portal. The full edition extends well beyond these introductory findings, providing the quantitative and qualitative depth required to convert market trajectory into actionable corporate strategy.
For detailed analysis of this topic, please visit the official page: Current Sensing Resistor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Meal Kit Market Hits $39.44B in 2025, Forecast 8.4% CAGR to $69.37B by 2032
By PW Consulting, 2026-09-16
Strategic Compass for the Meal Kit Delivery Services Market: Navigating the 2026–2032 Growth Cycle
The global meal kit delivery services market is entering a decisive phase. As consumer habits around convenience, nutrition, and sustainability continue to reshape home cooking, market participants face a complex matrix of expansion opportunities, cost pressures, and compliance risks. This analysis frames the commercial landscape that will define enterprise strategy through the end of the decade, drawing on a comprehensive market research study designed to support high-stakes decision-making in 2026 and beyond.
Why 2026 Demands a Refined Market View
Meal kit delivery services are no longer an experimental convenience category. They have matured into a structural alternative to traditional grocery and dining-out behaviors. The sector is expanding against a backdrop of shifting household budgets, evolving dietary preferences, and increasing scrutiny of food safety and supply chain resilience. For executives, the central challenge is no longer whether demand exists, but how to position operations, pricing, and portfolio strategy amid volatility.
The most recent market data underscores the scale and momentum of this environment. The global meal kit delivery services market generated approximately USD 39.44 billion in revenue in 2025, up from roughly USD 19.61 billion in 2020. Over that same historical window, the market advanced through a sustained growth trajectory that carried valuations from USD 23.12 billion in 2021 to USD 35.4 billion in 2024, reflecting the category’s deepening penetration across consumer segments. Looking forward, the forecast period from 2026 to 2032 points to continued expansion, with the market projected to reach USD 42.87 billion in 2026 and advance toward USD 69.37 billion by 2032. The implied compound annual growth rate across the forecast horizon is 8.4 percent.
These headline figures matter because they frame the stakes. Growth at this pace is strong enough to justify bold investment, yet not so automatic that it absorbs operational missteps. A company that treats meal kits as a purely transactional offering risks losing share to competitors who integrate brand trust, recipe innovation, and supply chain discipline into a cohesive value proposition. Conversely, operators that align their roadmap to the structural drivers behind this expansion can convert category growth into durable competitive advantage.
Worldwide Pet Food Delivery Market
Macro Signals Shaping the Competitive Terrain
The market’s trajectory is being influenced by more than consumer sentiment alone. Inflationary pressure on raw materials, regulatory scrutiny around food safety, and heightened expectations for quality and transparency are reshaping the operating environment. These forces are not peripheral concerns; they directly affect margin structures, product design, and the credibility of brands that depend on recurring subscription behavior.
On the supply side, farm-level vegetable prices are predicted to increase 20.5 percent in 2026, with a prediction interval ranging from 3.6 percent to 42.7 percent. This degree of uncertainty complicates ingredient planning for providers that rely on fresh produce as a core component of their value proposition. Compounding this, retail fresh vegetable prices increased by 3.1 percent from March 2026 to April 2026 and were 11.5 percent higher in April 2026 than in April 2025. For meal kit companies, the implication is clear: input cost variability can quickly translate into pricing tension, recipe reformulation, or margin erosion if sourcing and hedging strategies are not built for volatility.
At the same time, food safety remains a defining trust factor. A multistate Salmonella outbreak linked to home delivery meals from Metabolic Meals resulted in 16 illnesses and 7 hospitalizations, with the CDC investigation closing after the outbreak was resolved. In a separate event, cheese ingredients included in certain HelloFresh brand meal kits were recalled in Canada due to Listeria monocytogenes contamination. These incidents illustrate how quickly a compliance or quality failure can disrupt brand perception and operational continuity. In a category built on recurring delivery and household trust, such events are not merely reputational setbacks; they are strategic risk signals that should inform vendor oversight, traceability investments, and recall readiness.
What the Research Report Delivers
This market research study is structured to move beyond broad narrative and into actionable intelligence. It is designed for strategy, product, sales, and investor teams that need a shared fact base for planning, prioritization, and external communication. The report brings together market sizing, segmentation logic, competitive profiling, and industry context in a format that supports both internal alignment and external stakeholder engagement.
The analysis covers historical performance from 2020 through 2025 and extends forecast perspective across 2026 to 2032. This dual lens helps organizations distinguish between cyclical fluctuations and structural trends, enabling more disciplined scenario planning. Rather than treating growth as a single line item, the report unpacks the categories, offerings, and meal types that constitute the market’s underlying architecture, allowing decision-makers to identify where demand is concentrated and where variance is likely to emerge.
Throughout the study, attention is given to the practical implications of the data. Market size is presented with the context needed to interpret momentum, while segmentation insights are framed to support portfolio decisions, market-entry logic, and resource allocation. The report also examines market concentration to illuminate the balance between established players and the room available for differentiation. The objective is to provide a stable analytical foundation on which operational strategy can be built.
How the Market Is Structured
The meal kit delivery services market is shaped by multiple overlapping demand drivers. Some consumers prioritize the experience of cooking from scratch with guided recipes and pre-portioned ingredients, while others seek speed and simplicity with minimal preparation. Dietary identity also plays a significant role, with a meaningful portion of demand oriented toward plant-based and vegetarian options, and a larger share anchored in non-vegetarian meals. These preferences influence not only product design, but also customer acquisition messaging, retention dynamics, and the cost profiles of different service models.
Offering formats split the market between services that emphasize cooking from ingredients and those oriented toward quicker, more immediate consumption. The balance between these approaches affects logistics, packaging, customer expectations, and margin potential. Meal type segmentation further differentiates demand, creating distinct strategic paths for brands that compete on variety, culinary authenticity, convenience, or health and sustainability credentials. Regionally, the market reflects varying levels of adoption, with differing consumer expectations around price sensitivity, distribution reach, and brand trust.
In concentrated markets, the behavior of leading providers often sets pace and expectations for the broader field. Concentration patterns can inform how aggressively new entrants can pursue differentiation, how incumbents defend share, and where partnerships or niche positioning may create viable openings. The report contextualizes these structural relationships without reducing them to oversimplified rankings, because competitive advantage in meal kits often depends on execution details that numbers alone cannot capture.
Competitive Landscape: Ten Profiles, Multiple Strategic Playbooks
The competitive field includes a diverse set of operators, each pursuing a distinct interpretation of what consumers should receive from a meal kit service. The companies profiled in the research represent a cross-section of business models, recipe philosophies, and distribution approaches that together define the current market rhythm.
- HelloFresh SE, headquartered in Berlin, Germany, provides meal kit delivery services with more than 100 weekly recipes, alongside add-ons, seasonal boxes, premium meals, and vending machine distribution. Its breadth of format and recipe volume points to a scale-oriented strategy that seeks to serve a wide range of household needs under one brand umbrella.
- Marley Spoon, based in Sydney, Australia, offers meal kit delivery services featuring gourmet recipes, budget plans, and collaborations such as with Martha Stewart. Its profile suggests a dual focus on elevated culinary appeal and accessible price points, using partnerships to extend brand reach and recipe credibility.
- Purple Carrot, headquartered in Santa Barbara, California, specializes in meal kit delivery services focused on plant-based and vegetarian options. Its narrower dietary emphasis positions it within a segment where mission alignment and ingredient storytelling can support loyalty and differentiation.
- Hungryroot, based in Chicago, Illinois, provides fresh meal kit delivery services with customizable recipes and ingredient sourcing. Customization and sourcing transparency indicate a model built around flexibility and consumer control, which can be especially relevant for households balancing dietary preferences with convenience.
- Sunbasket, located in Burlingame, California, delivers organic meal kit services with nutrient-dense recipes and sustainable ingredients. Its emphasis on organic and sustainability attributes aligns with consumers who treat food quality and sourcing as central purchase drivers.
- Gobble, headquartered in Columbus, Ohio, offers meal kit delivery services emphasizing quick and easy home cooking recipes. Its value proposition leans toward time savings and usability, appealing to consumers who want cooking engagement without extended prep burden.
- Freshly Inc., based in New York, New York, provides meal kit delivery services with fresh, pre-portioned ingredients for at-home meals. Its approach reinforces convenience and freshness as core purchase triggers, positioning the service as a practical bridge between groceries and ready-made dining.
- Dinnerly, headquartered in Denver, Colorado, delivers budget-friendly meal kit services with simplified recipes for everyday use. The focus on affordability and simplicity targets cost-conscious households and those seeking repeatable, low-friction meal routines.
- Green Chef, also based in Denver, Colorado, specializes in organic and plant-based meal kit delivery services. By combining organic positioning with plant-centric offerings, it operates at the intersection of health, dietary preference, and ingredient quality.
- Home Chef, located in Chicago, Illinois, offers meal kit delivery services with chef-created recipes and value options. Its combination of culinary identity and value-tiered choices reflects an effort to serve both experience-seeking and price-sensitive consumers.
- Tovala, headquartered in San Francisco, California, provides scan-to-cook meal kit delivery services with smart oven integration for precise heating. This model blends meal kits with connected appliance functionality, illustrating how hardware, software, and food service can converge around convenience and repeatability.
These profiles matter because they show that the market is not converging on a single formula. Some providers compete through scale, recipe variety, and multi-format distribution. Others compete through dietary specialization, sustainability claims, customization, or appliance-linked convenience. For a company planning its next move, the strategic question is less about which model is universally best and more about which combination of audience, operational capability, and brand promise can be sustained at scale.
From Consumer Preference to Operating Risk
Market growth does not happen in a vacuum. The same forces that expand demand can also expose weak points in execution. Ingredient inflation, for example, is not only a cost issue; it is a design issue. If farm-level input prices can swing materially within a single year, then menus, portion sizing, sourcing partnerships, and pricing architecture must be flexible enough to absorb change without eroding consumer trust. Brands that lock themselves into rigid recipes or uncompetitive price points may find themselves squeezed from both sides.
Food safety adds another layer of strategic urgency. The recall events involving HelloFresh and the Salmonella outbreak associated with Metabolic Meals demonstrate that meal kit providers operate in an environment where quality failures can become public quickly and carry both health and business consequences. In this context, operational discipline is a competitive asset. Traceability, supplier vetting, testing protocols, and recall procedures should be treated as part of the core value proposition, not as back-office compliance functions. Companies that institutionalize these practices are better positioned to protect retention and reduce the likelihood that a single incident derails growth momentum.
These dynamics also intersect with customer acquisition and retention economics. Meal kit services depend heavily on recurring engagement, which means the cost of disappointing a customer is multiplied over time. Quality, reliability, and transparent communication can therefore be viewed as retention investments with direct financial returns. In a market projected to grow from USD 42.87 billion in 2026 toward nearly USD 70 billion by 2032, the winners are likely to be those who combine expansion with consistency.
Using the Study to Inform 2026 Decisions
For organizations active in or entering this market, the study functions as a strategic decision-support tool. It helps leadership teams answer questions that are otherwise difficult to resolve with fragmented public information: where demand is accumulating, which segments carry the strongest growth logic, how competitive intensity varies across formats, and what external pressures may shape margin and operational planning in the near term.
The report’s historical and forecast structure supports a range of applications. Strategy teams can use it to evaluate expansion timing and geographic or segment prioritization. Product and operations teams can use it to frame menu architecture, sourcing resilience, and service-model trade-offs. Marketing and brand teams can use the segmentation context to sharpen positioning without relying on broad assumptions. Investors and advisors can use the concentration and growth outlook to assess market maturity and the durability of competitive claims.
Importantly, the study is designed to be actionable without being over-specified at the summary level. It provides the analytical scaffolding needed to make informed choices while leaving room for company-specific interpretation. The most valuable insights often emerge when broad market direction is combined with internal capabilities, customer data, and operational constraints. That is where the research is intended to be most useful: as a reliable base layer for strategic judgment.
What Remains in the Full Analysis
The overview above outlines the strategic context and structural themes that shape the meal kit delivery services market. It also demonstrates why 2026 is a pivotal year for planning: input-cost uncertainty, food safety scrutiny, and continued category expansion are all active at once. Yet the full report contains a deeper level of segmentation value, competitive benchmarking, and scenario-ready detail that cannot be fully reproduced in an executive summary.
Meal Kit Delivery Services Market
For teams that need to move from general market awareness to specific planning assumptions, the complete study provides the granularity required to support concrete decisions. The full analysis examines how the market breaks down across regions, offerings, and meal types, and it contextualizes those splits within the broader growth trajectory. It also expands the competitive and operational picture in ways that help organizations identify where to concentrate resources, where to defend position, and where to experiment responsibly.
If your objective is to align 2026 strategy with a market projected to grow at 8.4 percent through 2032, the complete research offers the evidence base needed to make that alignment precise rather than approximate. The full report is available on the PW Consulting market research page, where the detailed segmentation, competitive profiles, and supporting market context can be reviewed in full.
For detailed analysis of this topic, please visit the official page: Meal Kit Delivery Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Virtual Training Market Hits $24.8 Billion in 2025, Projected 10.8% CAGR to $50.78 Billion by 2032
By PW Consulting, 2026-09-16
Navigating the Virtual Training Revolution: Strategic Imperatives for 2026 and Beyond
The corporate learning landscape is undergoing a seismic shift. As organizations grapple with hybrid workforces, skill gaps, and the demand for safer, more scalable training environments, Virtual Training has moved from a novelty to a necessity. At PW Consulting, we have synthesized extensive primary and secondary research to deliver a comprehensive view of this transformative market. This article serves as a strategic preview of our latest market research, highlighting the critical intelligence decision-makers need to navigate the forecast period from 2026 to 2032.
Market Trajectory: A Decade of Accelerated Growth
The numbers tell a compelling story of adoption and investment. The virtual training market has demonstrated robust expansion over the historical period. Revenues climbed from 14.85 billion USD in 2020 to 24.8 billion USD in 2025, reflecting a compound annual growth rate that underscores the sector's resilience and strategic importance. As we look toward the forecast horizon, the trajectory accelerates further. Projected revenues are set to reach 27.16 billion USD in 2026, growing steadily to 34.24 billion USD by 2028, and ultimately approaching 50.78 billion USD by 2032.
This growth is not merely linear; it is driven by a sustained CAGR of 10.8 percent across the forecast period. For enterprise leaders, this signals that virtual training is becoming a core infrastructure component rather than a discretionary spend. The expansion reflects broader macroeconomic trends, including the digitization of workflows, the need for remote capability building, and the integration of immersive technologies into standard operational procedures. This report dissects the drivers behind these figures, offering a granular understanding of where capital is flowing and which segments are poised for the most significant upside.
Segmentation Dynamics: Where Value Is Concentrated
Understanding the architecture of the market is essential for allocating resources effectively. Our analysis breaks down the ecosystem into distinct categories, revealing how different technologies and applications are capturing value. In the technology domain, VR and AR training simulations dominate the revenue landscape, reflecting the high-impact nature of immersive learning experiences. This is complemented by a growing market for dedicated training software platforms that manage content delivery, learner analytics, and compliance tracking. Hardware components, while a smaller share of the total revenue mix, remain a critical enabler, particularly as standalone devices become more affordable and powerful.
Application-wise, the market is diversified but shows clear leaders. Corporate training represents a substantial portion of demand, driven by the need for upskilling employees in soft skills, safety protocols, and operational procedures. Educational institutions form another major pillar, leveraging virtual environments for remote labs, vocational training, and accessible learning modalities. Healthcare training is emerging as a high-growth vertical, utilizing immersive simulations for clinical practice and patient interaction scenarios. Government agencies are also increasingly adopting these solutions for defense, public safety, and civil service preparation. The report provides a detailed examination of these application verticals, analyzing adoption rates, key use cases, and the specific value propositions that resonate with each stakeholder group.
Geographically, the market exhibits distinct regional characteristics. North America continues to lead in revenue contribution, supported by high enterprise spending on digital transformation and a mature technology ecosystem. The Asia Pacific region shows dynamic growth potential, fueled by expanding manufacturing bases and increasing investment in workforce development. Europe maintains a strong presence, particularly in sectors requiring strict regulatory compliance and high-fidelity simulations. Latin America and the Middle East and Africa represent emerging opportunities, where infrastructure development and cost-effective training solutions are driving adoption. The full report delves into regional nuances, including local regulatory environments, competitive intensity, and growth catalysts specific to each geography.
Competitive Landscape: Innovators and Incumbents
The virtual training market is characterized by a mix of specialized innovators and established players expanding into immersive technologies. Our report profiles key companies that are shaping the industry, analyzing their strategic positioning, technological capabilities, and target markets.
Several firms are focusing on enterprise-grade solutions for industrial and safety applications. VR Vision, based in Australia, specializes in CGI and 360-degree VR training simulations for sectors such as energy, manufacturing, and utilities, integrating scalable learning management systems. Strivr, headquartered in the United States, has established a strong footprint by deploying custom XR training platforms at Fortune 500 scale, offering centralized headset management and content spanning soft skills, safety, and operations. Humulo addresses the need for compliant safety training with OSHA-aligned industrial VR simulations for manufacturing, warehousing, and government clients, utilizing a one-time licensing model. Transfr focuses on workforce development and credentialing, mapping VR simulations to industry standards like MSSC, OSHA, and NCCER to support career pathway initiatives.
Technical skills training is another area of intense activity. Interplay Learning targets skilled trades with VR training for HVAC, electrical, plumbing, and solar applications, bridging the gap between theoretical knowledge and hands-on practice. PIXO VR operates a safety training marketplace that leverages AI-assisted content creation, enabling enterprise and industrial users to develop customized training modules efficiently. In the healthcare domain, UbiSim provides immersive VR training simulations featuring interactive virtual patients, supporting nursing and clinical education with realistic scenario-based learning.
Broader simulation expertise also plays a role. CAE Inc., based in Canada, delivers high-fidelity simulation training systems for military, defense, and aviation sectors, bringing decades of simulation heritage to the virtual training space. YORD Studio, located in Australia, offers custom XR and AI-powered immersive training solutions across healthcare, manufacturing, and corporate sectors, emphasizing tailored experiences and advanced integration capabilities.
Recent developments highlight the pace of innovation and the increasing focus on trust and compliance. In February 2026, Facilitate confirmed full GDPR compliance for its no-code VR creation platform, which powers immersive training across energy, manufacturing, aviation, mining, healthcare, and higher education. This milestone strengthens data privacy protections for global customers. Concurrently, Facilitate achieved SOC 2 Type II certification, affirming the highest standards of data security, availability, and privacy for its VR training platform. These certifications build on earlier achievements, including SOC 2 Type I certification in May 2025, signaling a maturing ecosystem where security and regulatory adherence are becoming competitive differentiators.
Virtual Training Market
Product innovation continues to expand accessibility and functionality. In October 2025, Virtra introduced the V-One portable simulator, a compact all-in-one design for field-deployable VR training without the need for external screens. This reflects a trend toward hardware solutions that reduce logistical barriers and enable training in diverse environments. Meanwhile, industry analysis from YORD Studio in April 2026 notes that custom enterprise VR training deployments can scale with cloud-based environments, reducing overall training costs by up to 50 percent while maintaining consistent quality. Such insights underscore the economic rationale for adopting virtual training at scale.
Industry Dynamics: Navigating Evolving Pressures
The market is not static; it is shaped by regulatory, operational, and technological dynamics that require strategic attention. Data privacy and security are increasingly central to enterprise procurement decisions. The recent certifications by Facilitate illustrate how vendors are responding to the demand for robust data handling practices. As virtual training platforms collect sensitive learner data and integrate with corporate systems, compliance with frameworks such as GDPR and SOC 2 standards becomes a prerequisite for global deployment. Organizations must evaluate vendors not only on pedagogical effectiveness but also on their ability to safeguard data across borders and use cases.
Regulatory compliance within specific verticals also influences adoption patterns. For instance, OSHA-aligned VR safety training platforms require qualified evaluators for hands-on assessment components, even as they replace formal instruction and practice elements. This nuance highlights the hybrid nature of modern training programs, where virtual simulations augment rather than entirely replace human oversight in regulated environments. Decision-makers need to understand these compliance nuances to design programs that meet legal requirements while maximizing efficiency.
Infrastructure and cost dynamics are shifting the value proposition. Cloud-based environments enable scalable deployments that reduce per-learner costs and ensure consistent training quality across dispersed teams. Labor cost pressures and the need for rapid onboarding further amplify the appeal of virtual training solutions that can be updated quickly and delivered without geographic constraints. However, successful implementation requires careful planning around content development, hardware procurement, change management, and integration with existing learning ecosystems.
Strategic Applications: Turning Insight into Action
This market research is designed to be a practical tool for strategic decision-making. It goes beyond high-level trends to provide actionable intelligence across multiple dimensions. For C-suite executives and strategy leaders, the report offers a clear assessment of market size, growth trajectories, and investment priorities, helping to justify capital allocation and align training initiatives with broader business objectives.
For product and technology teams, the segmentation analysis and competitive profiling provide a blueprint for differentiation. Understanding which technology types and applications are gaining traction allows organizations to refine their roadmaps, prioritize feature development, and identify gaps in the current offering landscape. The profiles of key companies reveal diverse go-to-market strategies, from marketplace models and AI-assisted content creation to specialized vertical solutions and enterprise platform deployments.
Procurement and compliance officers will find value in the detailed examination of regulatory dynamics and vendor certifications. As data security and privacy become critical selection criteria, the report's coverage of certifications, compliance standards, and data handling practices supports informed vendor evaluation. The analysis of regional variations also aids in navigating local requirements and tailoring deployment strategies to specific markets.
Worldwide Virtual Networking Market
Operational leaders can leverage the insights on cost dynamics, scalability, and implementation best practices. The report explores how cloud-based environments, portable hardware, and modular content strategies contribute to cost efficiency and training consistency. It also addresses the practical challenges of integrating virtual training into existing workflows, managing change resistance, and measuring learning outcomes against business metrics.
Conclusion: Positioning for the Future
The virtual training market is entering a phase of sustained expansion, driven by technological maturity, economic incentives, and evolving workforce needs. With revenues projected to grow from 27.16 billion USD in 2026 to nearly 51 billion USD by 2032, the opportunity for organizations that act strategically is substantial. However, capturing this value requires more than simply adopting new tools; it demands a deep understanding of market structure, competitive dynamics, regulatory requirements, and operational realities.
This report from PW Consulting provides that understanding. It synthesizes macro-level data with micro-level analysis, offering a comprehensive view of where the market is headed and how leaders can position themselves for success. From segmentation trends and regional insights to company profiles and recent developments, the research is structured to support informed decision-making at every level of the organization.
For those ready to move beyond surface-level observations and gain access to the full intelligence suite, we invite you to explore the complete report. The detailed findings, including granular segmentation data, competitive benchmarking, and forward-looking scenarios, are available through our source webpage. Equip your strategy with the depth and precision needed to lead in the virtual training era.
For detailed analysis of this topic, please visit the official page: Virtual Training Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Privacy Management Software Market Hits $7.36B in 2025, Projected to Surge at 37.4% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Privacy Management Software Market: Strategic Intelligence for 2026 and Beyond
The privacy technology landscape has entered a decisive inflection point. Organizations are no longer treating compliance as a periodic checklist or a back-office function. Instead, privacy management has become a core operational capability, intrinsically linked to customer trust, risk mitigation, and scalable digital transformation. Our latest Privacy Management Software Market research report translates this structural shift into a clear, actionable intelligence framework designed specifically for enterprise strategy teams, procurement leaders, and technology architects planning their 2026 roadmaps.
Drawing on a rigorous historical baseline spanning 2020 through 2025, the analysis extends its forward-looking lens through 2032. Over the past five years, the sector has witnessed a remarkable acceleration in capital allocation and vendor maturation. Market revenue grew from 1.5 billion USD in 2020 to 7.36 billion USD in 2025, underscoring how quickly privacy has evolved from a niche regulatory response into a mainstream enterprise priority. The trajectory does not flatten in the near term. Forecasts project continued expansion to 10.21 billion USD in 2026, with sustained momentum carrying the market toward 68.04 billion USD by 2032. Driving this expansion is a forecasted compound annual growth rate of 37.4 percent, a figure that signals far more than incremental adoption. It reflects a fundamental redesign of how organizations discover, classify, govern, and operationalize data across increasingly complex regulatory and technological environments.
For decision-makers navigating 2026, these numbers translate into critical strategic realities. Budgets are no longer discretionary. Privacy software is transitioning into a foundational layer of enterprise architecture, demanding careful evaluation of integration pathways, automation maturity, and long-term vendor viability. The research report is built to cut through marketing noise and equip leaders with the analytical rigor required to allocate resources, prioritize implementation sequences, and future-proof compliance operations.
Privacy Management Software Market
Market Dynamics Reshaping Enterprise Priorities
No enterprise privacy strategy can be designed in isolation from the regulatory and operational pressures shaping today’s compliance environment. Enforcement intensity has become a defining market catalyst. According to the GDPR Enforcement Tracker, 2026 alone has already recorded 143 fines, contributing to a cumulative total of over €6.29 billion across 3,186 recorded actions since 2018. This enforcement cadence is not merely a legal statistic; it is a direct signal that supervisory authorities are operationalizing privacy obligations with escalating precision and financial consequence.
In parallel, regional regulatory bodies are expanding the scope of obligations beyond traditional data handling. The California Privacy Protection Agency issued its first enforcement advisory on data minimization in April 2024, paired with ongoing proposed updates to the CCPA and CPRA frameworks, including forthcoming rules on automated decision-making technology. These developments illustrate a broader trend: regulators are no longer only scrutinizing static compliance artifacts. They are increasingly focused on how organizations architect data flows, manage consent dynamically, and govern emerging data processing activities in real time.
The operational strain of this expanding landscape is measurable. The PwC Global Compliance Survey from 2025 reveals that 77 percent of companies report negative business impact stemming from compliance complexity across multiple growth areas. When privacy obligations intersect with product innovation, M&A activity, cross-border data transfers, and third-party ecosystems, fragmented toolsets and manual workflows quickly become strategic bottlenecks. This is precisely where modern privacy management software enters as a structural enabler rather than a reactive safeguard.
What the Research Delivers: Operational Intelligence, Not Surface-Level Forecasts
This report is engineered for practitioners who must convert market intelligence into tangible operational decisions. Rather than presenting static snapshots, the analysis provides a comprehensive examination of how privacy management software is deployed across enterprise workflows, how solution categories diverge in capability, and where integration complexity most frequently derails implementation timelines.
The research maps the functional architecture of the market across its dominant solution types. Organizations are increasingly investing in regulatory compliance management as a central orchestration layer, while data discovery and mapping capabilities serve as the foundational prerequisite for accurate inventory, classification, and downstream governance. Risk assessment and management modules are gaining traction as boards and audit functions demand quantified exposure frameworks, while consent and preference management, incident and breach response, and other emerging capabilities round out the operational continuum. The report also examines how these capabilities converge within applied use cases, including privacy impact assessment and reporting, data subject request fulfillment, vendor and third-party risk oversight, and governance around incident response.
Beyond functional taxonomy, the study delivers a granular view of deployment considerations, vendor evaluation criteria, and implementation readiness factors. It investigates how enterprises are aligning privacy platforms with existing data governance structures, security operations, and customer experience architectures. Readers will find structured analysis on procurement pathways, integration dependencies, scalability thresholds, and the operational maturity required to transition from fragmented point solutions to unified privacy orchestration.
Critically, the report is designed to support scenario planning. It frames adoption trajectories within the context of organizational size, data environment complexity, regulatory exposure, and internal capability maturity. This allows strategy teams to model investment pacing, prioritize capability acquisition, and anticipate where automation will deliver the highest return on compliance efficiency.
Competitive Landscape: Platform Evolution and the Rise of Agentic Automation
The vendor ecosystem has matured rapidly, with leading providers differentiating through automation depth, data connectivity breadth, and cross-jurisdictional compliance orchestration. Market concentration currently reflects a moderately dispersed landscape, with the top three providers accounting for 26.2 percent of revenue and the top five capturing 39.5 percent. This structure indicates both vigorous competition and room for specialized innovators to gain footholds in high-value operational niches.
Several established and emerging players define the current competitive frontier. OneTrust, headquartered in Atlanta, Georgia, has advanced as an AI-ready governance platform emphasizing privacy automation, consent management, data subject rights fulfillment, and multi-jurisdictional compliance workflows. BigID, based in New York, has positioned its data security and privacy platform around AI-driven discovery, classification, and governance for sensitive data spanning cloud, on-premises, and AI systems. TrustArc, operating from Walnut Creek, California, provides a privacy management and consent platform supported by certification capabilities, DPIA automation, and global compliance tooling. DataGrail, in San Francisco, offers an agentic data privacy platform focused on consent management, data subject rights fulfillment, and risk assessment workflows. Transcend, also based in San Francisco, functions as a compliance layer for customer data, delivering consent management, data subject request automation, and preference management. Ketch, likewise headquartered in San Francisco, delivers enterprise privacy orchestration software spanning consent, data subject access requests, data mapping, assessments, and AI-ready data governance. IBM contributes through its broader enterprise portfolio, with Guardium Data Protection supporting data discovery, classification, and compliance across hybrid environments aligned with frameworks such as GDPR, CCPA, and PCI.
Recent product movements underscore how quickly the market is shifting toward automation intensity and AI-augmented governance. In March 2026, BigID introduced a unified privacy management platform expansion covering preference portals, deletion workflows, and AI data governance across structured and unstructured data assets. A few months later, in May 2026, Ketch launched the Ketch Agent Network, a multi-agent AI orchestration layer designed to support agentic data mapping, risk management, and assessment workflows within privacy programs. These releases illustrate a broader industry trajectory: privacy software is no longer confined to policy documentation or manual task routing. The frontier is now defined by orchestrated, intelligent workflows that reduce manual burden, accelerate response cycles, and embed compliance logic closer to operational data systems.
Legal Practice Management Software Market
Strategic Implications for 2026 Decision-Making
The convergence of enforcement pressure, regulatory expansion, and automation-driven platform evolution creates a clear mandate for enterprise leaders. Privacy management software is no longer a tactical purchase; it is a strategic capability that directly influences operational agility, risk exposure, and cross-functional coordination. Organizations that approach procurement with fragmented intent risk compounding complexity, while those that evaluate platforms through the lens of architectural fit, automation depth, and long-term scalability are better positioned to convert compliance obligations into competitive advantage.
This research report provides the analytical scaffolding required to make those evaluations with confidence. It illuminates where market growth is concentrated, how solution capabilities are diverging, and what implementation maturity looks like in practice. It also frames the vendor landscape in a way that supports comparative assessment without reducing complex platforms to superficial feature checklists.
For executives planning 2026 investments, the most valuable insight is structural rather than numerical. The market is scaling at a pace that rewards early architectural clarity. Enterprises that define privacy orchestration requirements, data discovery dependencies, and automation priorities now will face fewer integration bottlenecks, lower total cost of ownership, and stronger alignment between compliance operations and business objectives. Delaying that clarity until after procurement often results in reactive vendor selection, overlapping toolsets, and diminished returns on compliance investment.
The complete analysis extends well beyond the macro trajectory and competitive snapshots outlined here. Detailed segmentation intelligence, vendor evaluation frameworks, deployment sequencing models, and forward-looking scenario insights are provided in the full report. Readers seeking a comprehensive, decision-ready view of the Privacy Management Software Market are encouraged to access the complete research on the source page, where deeper segmentation breakdowns, vendor profile comparisons, and implementation pathway guidance are available in full.
For detailed analysis of this topic, please visit the official page: Privacy Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Marine Tourism Hits $267B in 2025, Projects 6.5% CAGR to $414.6B by 2032
By PW Consulting, 2026-09-16
The Blue Horizon: Strategic Intelligence for the Marine Tourism Market in 2026
The global marine tourism sector stands at a critical inflection point. As we navigate the economic landscape of 2026, the industry is not merely recovering from past disruptions but is fundamentally reshaping its operational DNA. For stakeholders, investors, and enterprise leaders, understanding the nuance of this transformation is no longer optional—it is a prerequisite for survival and growth. PW Consulting's latest Market Research Report on the Marine Tourism Market offers a comprehensive lens through which to view these shifting tides, providing the granular intelligence necessary to steer strategic decisions through 2032.
This analysis serves as a strategic overview of the market dynamics, competitive forces, and regulatory pressures defining the sector. While we highlight the magnitude of the opportunity here, the full depth of our proprietary data—down to the specific growth vectors and regional nuances—is reserved for our detailed report. The following insights set the stage for why immediate access to this intelligence is vital for your 2026 planning cycle.
Market Trajectory: Navigating the Growth Curve
The marine tourism industry has demonstrated remarkable resilience and expansion over the last half-decade. Our longitudinal analysis tracks the market's evolution from 2020 through the base year of 2025, revealing a robust trajectory that defies broader economic volatility. In 2020, the market valuation stood at approximately 160.5 billion USD. Despite the headwinds of that period, the sector rebounded sharply, recording a valuation of 172.9 billion USD in 2022 and surging to 201.14 billion USD by 2023.
By the base year of 2025, the overall market size reached a significant milestone of 267.0 billion USD. This growth underscores a renewed consumer appetite for experiential travel and coastal leisure activities. Looking forward, the forecast period from 2026 to 2032 projects a continued upward climb. We estimate the market will value at 292.75 billion USD in 2026, eventually reaching 414.6 billion USD by 2032.
This expansion is driven by a Compound Annual Growth Rate (CAGR) of 6.5 percent. For enterprise strategists, this figure represents more than just numerical growth; it indicates a sustained period of investment opportunity and market consolidation. The steady rise from 2024's 228.87 billion USD to 2025's 267.0 billion USD suggests that the baseline for future projections is stronger than previously anticipated. However, capturing this value requires more than general optimism; it demands precise alignment with the high-growth segments identified in our full report.
Segmentation Insights: Where Value Converges
While the aggregate numbers are compelling, the true strategic value lies in understanding how value is distributed across different operational types and application streams. The market is not a monolith; it is a complex ecosystem where revenue concentration varies significantly by activity and service delivery.
Our segmentation analysis breaks down the market by type, revealing distinct performance tiers among activities such as Yachting and Sailing Tourism, Cruise Tourism, Water Sports, and Other Types. Similarly, revenue generation is dissected by application, including Passenger Ticket Sales, On-board Services and Amenities, and Other Revenue Sources. The disparity in revenue volumes across these categories highlights where the current capital flow is concentrated and where emerging opportunities may lie dormant.
Furthermore, geographic segmentation provides a heatmap of global demand. The market spans North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Each region presents unique regulatory environments, consumer behaviors, and infrastructural capabilities. For a multinational operator, understanding the relative weight of these regions is crucial for resource allocation. Our report details these regional splits without relying on broad assumptions, offering instead specific data points that correlate regional performance with local economic indicators.
To fully leverage these segmentation splits, stakeholders must look beyond the totals. The interplay between specific types and applications often reveals hidden efficiencies or untapped markets. We encourage readers to consult the complete segmentation tables in the full study to identify the specific niches that align with their core competencies.
Marine Tourism Market
Competitive Landscape: The Titans and the Challengers
The marine tourism market is characterized by a high degree of concentration, with a few dominant players exerting significant influence over pricing, standards, and consumer expectations. Our analysis identifies a core group of key companies that define the competitive perimeter. Understanding their strategic positioning is essential for any new entrant or existing player looking to expand market share.
In the cruise sector, major operators headquartered in Miami, Florida, United States, hold substantial sway. Carnival Corporation, through its multiple cruise lines including Carnival Cruise Line, provides large-scale marine-based passenger tourism experiences that cater to mass markets. Similarly, Royal Caribbean Group delivers contemporary marine tourism with a strong emphasis on family and adventure voyages, while Norwegian Cruise Line Holdings Ltd. distinguishes itself through Freestyle cruising and large ocean cruises. Across the Atlantic, MSC Cruises S.A., based in Geneva, Switzerland, operates Mediterranean and ocean cruises focused on marine tourism, leveraging its strong presence in European waters.
Contrasting the mass-market cruise giants are the specialized charter providers who cater to the high-end and recreational segments. Dream Yacht Worldwide, based in the United Kingdom, stands as a leading provider of yacht and boat chartering for recreational marine tourism and private charters. The Moorings, headquartered in the United States, supplies catamaran and yacht charters for specific marine tourism experiences. Complementing this landscape is Sunsail, also based in the United Kingdom, which provides sailing yacht and catamaran rentals. These companies illustrate the bifurcation in the market between volume-driven cruise operations and experience-driven charter services.
Worldwide Marine Interiors Market
The concentration of market power is notable. Data indicates a high level of consolidation among the top players, suggesting that barriers to entry remain significant for smaller operators unless they can carve out specialized niches. Our report provides a detailed profile of these companies, examining their recent moves, capacity expansions, and strategic pivots. Understanding the specific offerings and strategic focus of these entities allows competitors to identify gaps in the market offerings.
Industry Dynamics: Regulation, Sustainability, and Policy
The operational environment for marine tourism in 2026 is heavily influenced by regulatory frameworks and sustainability mandates. The industry is no longer operating in a vacuum; it is subject to intensifying scrutiny regarding its environmental footprint and its impact on coastal communities. This dynamic creates both compliance costs and strategic opportunities for leaders who can pivot early.
On the regulatory front, the FuelEU Maritime Regulation requires cruise ships to reduce greenhouse gas emissions by 2 percent in 2025 and aims for an 80 percent reduction by 2050. Crucially, this mandates LNG and shore-side electricity for new vessels starting 2026. This regulation directly impacts capital expenditure planning for fleet operators. Simultaneously, the EU Strategy for Coastal Communities, announced in February 2026, seeks to boost economic growth, competitiveness, resilience, and adaptation for coastal tourism through energy independence and nature restoration. These policies signal a shift where sustainability is becoming a license to operate rather than a optional marketing feature.
Beyond Europe, global initiatives are gaining traction. In June 2025, organizations including the World Sustainable Hospitality Alliance, World Travel and Tourism Council, Travalyst, and UN Tourism launched the Ocean Tourism Pact to protect ocean ecosystems and promote sustainable coastal and marine tourism. This multi-stakeholder approach indicates a growing consensus on the need for standardized sustainability practices across the industry.
Regional governments are also stepping up. In January 2026, the Saudi Red Sea Authority launched the Introductory Guide to Coastal Tourism Activities, a digital gateway streamlining regulations and procedures for the sector. This move aims to reduce bureaucracy and encourage investment in one of the region's key growth areas. Earlier, in May 2025, the Sri Lanka Tourism Development Authority launched the Marine Tourism Roadmap to promote sustainable coastal and marine tourism development. These policy launches suggest that emerging markets are actively seeking to structure their marine tourism sectors to attract responsible investment.
Furthermore, the EU Blue Economy Observatory notes that climate change poses profound impacts on coastal tourism, requiring strengthened environmental standards under the Blue Growth strategy. For strategists, this means risk assessment must now include climate resilience modeling. Our report integrates these regulatory and policy developments into a broader dynamics section, helping firms anticipate compliance costs and identify regions where policy support favors growth.
Strategic Imperatives for 2026 Decision Makers
As we move through 2026, the convergence of market growth, competitive pressure, and regulatory change creates a complex decision matrix. Leaders must balance the pursuit of the projected 6.5 percent CAGR with the realities of emission mandates and shifting consumer preferences.
First, investment decisions must be data-backed. With the market moving from 292.75 billion USD in 2026 toward 414.6 billion USD in 2032, capital deployment needs to be targeted. Blind expansion into high-concentration segments may yield diminishing returns. Our report provides the segmentation granularity required to identify high-yield avenues without exposing firms to unnecessary risk.
Second, competitive positioning must be re-evaluated. With the top five players holding a significant share of the market, smaller firms must leverage agility and specialization. Whether through niche charter services or focused regional operations, differentiation is key. Understanding the specific profiles of competitors like Carnival Corporation or Dream Yacht Worldwide allows for strategic positioning that avoids direct head-on collisions where possible.
Third, sustainability is now a strategic pillar. The regulatory timeline set by FuelEU Maritime and the EU Strategy for Coastal Communities means that environmental compliance is a medium-term financial imperative. Firms that integrate these requirements into their 2026 planning will secure a competitive advantage in terms of operational continuity and brand reputation. The Ocean Tourism Pact and various national roadmaps further indicate that partnerships and adherence to global standards will become increasingly valuable.
Conclusion: Accessing the Full Intelligence
The marine tourism market offers substantial rewards for those equipped with the right intelligence. The trajectory from 160.5 billion USD in 2020 to a projected 414.6 billion USD in 2032 demonstrates the sector's potential. However, realizing this potential requires more than surface-level understanding. It demands a deep dive into regional splits, application-specific revenue streams, and the intricate competitive dynamics defined by key industry players.
PW Consulting's Marine Tourism Market Report is designed to provide this depth. It moves beyond aggregate numbers to offer actionable insights on segmentation, competitive profiling, and regulatory impact. The summary provided here outlines the strategic landscape, but the specific data points—regional percentages, application splits, and detailed company analysis—are critical for formulating precise business strategies.
For decision makers aiming to secure a advantageous position in this evolving market, accessing the full report is the next logical step. We invite you to explore the complete dataset and strategic recommendations available on our platform. In a market defined by wave-like volatility and clear long-term growth, ensure your ship is steered by the best possible navigation tools.
For detailed analysis of this topic, please visit the official page: Marine Tourism Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


