



Category: Machinery & Automotive
PW Consulting: Commercial Kitchen Ventilation Market at USD 1,630M in 2025; 6.8% CAGR to 2032
By PW Consulting, 2026-07-22
Commercial Kitchen Ventilation Systems Market — Strategic Preview for 2026 Decision-Makers
As global foodservice footprints reconfigure in response to shifting consumption patterns, energy policy pressure, and tighter fire and health codes, commercial kitchen ventilation is moving from a commoditized mechanical discipline to a strategic lever for operators, designers, and investors. This preview synthesizes the core, decision-grade insights from PW Consulting’s full market study to outline why 2026 is a pivotal year for executives shaping product roadmaps, procurement strategies, and M&A agendas in the commercial kitchen ventilation systems market.
Commercial Kitchen Ventilation Systems Market
Market snapshot: growth trajectory and concentration
The commercial kitchen ventilation market has demonstrated resilient expansion through the early 2020s, growing from roughly USD 1.15 billion in 2020 to about USD 1.63 billion in 2025 (base year). Our forecast conservatively assumes a compound annual growth rate (CAGR) of 6.8% over the 2026–2032 period, guiding the market to an expected size of roughly USD 2.58 billion by 2032. These headline dynamics reflect a mix of new-build restaurant growth, intensified retrofit activity driven by energy codes, and accelerating adoption of demand-driven controls and integrated IAQ solutions.
Commercial Kitchen Ventilation Systems Market
Market structure remains moderately concentrated: the top three vendors account for a majority share of the organized market, and the top five reach a stronger, but not monopolistic, presence. This concentration profile creates a landscape where scale delivers advantages in distribution, OEM-manufacturing, and large project specification — while meaningful opportunities still exist for niche innovators and specialist installers to capture profitable share.
Commercial Kitchen Ventilation Systems Market
Why 2026 matters: strategic inflection points
- Regulatory tipping points — Several jurisdictions are moving beyond prescriptive ventilation requirements toward performance-based mandates that explicitly reward energy-saving technologies such as Demand Control Kitchen Ventilation (DCKV). Proposed code changes in leading states are poised to change procurement economics and lifecycle TCO calculations.
- Operational economics — Rising energy costs and operator focus on lifecycle cost are shortening payback thresholds for integrated DCKV, heat recovery, and make-up air solutions. For design firms and specifiers, measurable operating-cost reductions are becoming as persuasive as capex comparisons.
- Digital integration — The shift from stand-alone hardware to controls-enabled solutions (sensors, analytics, BMS integration) is enabling new service revenue models such as performance-as-a-service, predictive maintenance, and value-aligned retrofits.
- Retrofit momentum — Aging equipment fleets and renewed investment in off-premise and hybrid service formats (cloud kitchens, food trucks, commissaries) create a near-term retrofit wave that is tractable for suppliers with strong installation and service capabilities.
Regulatory and safety environment: constraints and catalysts
Multiple codes and standards are central to short-term decision-making. NFPA 96 and the FDA Food Code continue to define fire protection and public health requirements for exhaust systems, while model mechanical codes (e.g., the Uniform Mechanical Code) set installation safety baselines. At the same time, energy policy — including proposals from state energy regulators — is reframing ventilation as an energy efficiency opportunity rather than a simple compliance cost. For market participants this means two concurrent priorities: ensuring absolute compliance with safety and health standards, and proactively aligning product and service offers with energy-code trajectories that may mandate DCKV or equivalent performance in leading markets.
Technology and product trends shaping supplier advantage
- DCKV and sensor-driven ventilation: proven paybacks and expanding code acceptance are turning DCKV from “nice-to-have” to near-essential in many specifications.
- Integrated make-up air and energy recovery: as operators focus on total HVAC impacts, combined solutions that reduce building heating/cooling loads gain traction.
- Controls and connectivity: interoperability with building management systems and remote performance monitoring unlocks service margins and improves lifecycle performance.
- Fire suppression and grease management evolution: modular, easier-to-install systems reduce downtime and total installed cost — a decisive factor for fast service chains and commissaries.
Competitive landscape — capabilities that matter in 2026
The competitive set combines large OEMs with national footprints and specialized regional manufacturers and integrators. Leading players demonstrate distinct positioning:
- CaptiveAire Systems, Inc. — A scale manufacturer with broad product breadth across hoods, fans, and grease management. Its integrated product suite and nationwide distribution give it an advantage in large chain accounts and turnkey projects.
- Greenheck Fan Corporation — Strength lies in engineered fan systems, make-up air units, and energy recovery expertise. Greenheck’s technical reputation makes it a preferred partner for projects emphasizing HVAC integration and efficiency.
- Systemair AB — Emphasizes high-performance exhaust systems and smart airflow controls, positioning itself toward customers prioritizing air quality and advanced control strategies.
- Gaylord Industries — A leader in demand-control kitchen ventilation (DCKV) and custom hood fabrication; well-suited to retrofit and high-efficiency projects where precise modulation of airflow is a differentiator.
- FAST Kitchen Hoods and NAKS — Regional manufacturers that offer compliance-focused, quick-turn hood solutions and value to local installers who demand reliability and Code expertise.
- Chef’s Deal Restaurant Equipment — Evolving from equipment supply into engineered ventilation services with a December 2025 expansion that broadened its service portfolio to fully engineered systems and custom packages — an example of channel players moving upmarket by adding design-engineer-install capabilities.
- Melink Corporation — Known for Intelli-Hood controls and energy-focused solutions; represents the digital, analytics-enabled end of the market and provides a template for value-added software/services monetization.
These players illustrate the two primary value paths in the industry: OEM-led scale (product breadth and distribution) and solution-led specialization (controls, services, retrofit expertise). Both paths create attractive entry points for partnerships, white-labeling, and bolt-on acquisitions.
Strategic imperatives for 2026 decision-makers
- Product and offering strategy: prioritize modular, controls-ready platforms that simplify installation and allow incremental upgrades (sensor retrofits, connectivity modules). This reduces buyer friction and future-proofs installations against evolving codes.
- Commercial model innovation: develop service and subscription offers that monetize ongoing performance (energy savings sharing, preventative maintenance contracts, analytics-based service tiers).
- Distribution and installer economics: invest in certified installer networks and fast-response service teams. Retrofit projects reward vendors who can guarantee minimal downtime and reliable commissioning.
- Compliance as a sales lever: embed compliance assurance in sales collateral — demonstrable NFPA 96 and local code alignment accelerates specification and reduces procurement risk for chains and institutions.
- M&A and partnership playbook: pursue tuck-ins that add local installation density, DCKV/control software, or make-up air expertise. The current concentration suggests room for accretive acquisitions that improve route-to-market and aftermarket capabilities.
- Risk management: hedge raw-material and supply-chain volatility by qualifying alternate stainless and sheet-metal suppliers and by standardizing key components across product families to reduce SKU complexity.
What the report delivers — practical, executable tools
PW Consulting’s full market study is built for application by procurement, product, and corporate strategy teams. Key deliverables include:
- Validated market sizing and conservative-to-accelerated forecasts (2026–2032) with scenario sensitivity for energy policy accelerations.
- Regulatory impact analysis and a policy watch matrix identifying high-probability code changes and their adoption timelines.
- Commercial playbooks: pricing, installation cost models, and payback calculators tailored to new-build vs. retrofit economics.
- Vendor scorecards and capability maps to accelerate partner selection and M&A screening.
- Operational checklists for compliance, commissioning, and service contracts that reduce project risk and warranty exposure.
- Case studies and templates that allow rapid pilot design for DCKV retrofits and integrated make-up-air deployments.
To preserve the strategic value of this preview and to maintain a single, authoritative reference for buyers and advisors, granular segmentation data (region, product, application splits) and detailed vendor revenue figures are intentionally omitted from this public summary. The full dataset is included in the complete report and supports precise targeting, investment sizing, and competitive benchmarking.
How to use the analysis in 90 days
- Quarter 1 (Assessment): Run the provided payback and TCO models on a representative store cluster to quantify retrofit economics under current utility rates and projected 12–24 month energy price scenarios.
- Quarter 2 (Pilot & Partnerships): Launch a DCKV + analytics pilot with a controls provider and a local installer; use the report’s vendor scorecards to select partners and structure service-level agreements.
- Quarter 3 (Scale & Capitalize): Lock in supplier agreements with performance warranties and service SLAs; use the policy watch matrix to pre-emptively align spec sheets with likely code updates.
Closing — the strategic opportunity
The convergence of energy policy, digital controls, and retrofit demand creates a unique window for sellers and operators to transform ventilation from a compliance line item into a measurable contributor to operating margin and brand sustainability. With a mid-single-digit CAGR driving the market toward multi-billion-dollar scale, the companies that combine product durability, control intelligence, and a scalable service model will capture outsized returns.
For executives preparing 2026 budgets and strategic plans, the full PW Consulting report provides the granular analysis, executable tools, and vendor-level insights required to convert uncertainty into competitive advantage.
Next step
Access the complete study for the detailed regional/product/application splits, full vendor scorecards, and the downloadable financial models that support procurement decision-making and M&A diligence. PW Consulting’s research team is available to brief executive teams and to run a customized scenario analysis tailored to your operating footprint.
For detailed analysis of this topic, please visit the official page: Commercial Kitchen Ventilation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Powder Metallurgy Market Poised for 12.8% CAGR Through 2032
By PW Consulting, 2026-07-22
Powder Metallurgy Market — Strategic Outlook for 2026 Decision-Makers
Executive summary
As organizations recalibrate strategies for the 2026 operating environment, powder metallurgy (PM) is transitioning from a niche manufacturing technology to a mainstream industrial strategy enabler. Our PW Consulting market study — anchored on a 2025 base year and a 2020–2025 historical series — finds that the global powder metallurgy market expanded from USD 5.59 Billion in 2020 to USD 9.08 Billion in 2025 and is projected to reach approximately USD 21.25 Billion by 2032, implying a compound annual growth rate (CAGR) of 12.8% across the 2026–2032 forecast window. This trajectory reflects structural demand shifts: accelerated adoption of additive manufacturing, higher-material-performance requirements from electrification and lightweighting programs, and renewed investment in domestic production capacity.
Powder Metallurgy Market
For executives preparing budgets, capital allocations, or M&A roadmaps in 2026, this research frames where value will accrue, where risk is concentrated, and which strategic moves are likely to produce asymmetrical returns. The study intentionally demonstrates methodological rigor while reserving granular segment tables and proprietary models for the full report — a deliberate “trailer” approach designed to show depth while encouraging direct engagement for the complete dataset.
Powder Metallurgy Market
Why this research matters for decisions in 2026
-
Market momentum quantified: The acceleration from 2020–2025 and the 12.8% forecast CAGR drive a different investment calculus. Companies that treat PM as a sustained growth platform, rather than a tactical cost-out tool, will be positioned to capture premium margin pools tied to higher-spec alloy powders and integrated component solutions.
Powder Metallurgy Market -
Timing capital deployment: The report maps a near-term inflection in 2026–2028 where demand for advanced powders and sintered components tightens relative to legacy supply. This creates windows to secure offtake agreements, prioritize capacity expansions, or pursue opportunistic M&A at attractive multiples.
-
Risk-adjusted sourcing: Our supply-side intelligence and concentration metrics highlight that a handful of suppliers control a meaningful share of the market (CR3 ~50%; CR5 ~60%). For procurement leaders this is a call to design multi-tiered hedging strategies and to invest in supplier development or vertical integration selectively.
Dynamics shaping 2026 strategy
-
Technological convergence — additive manufacturing (AM) and traditional PM are increasingly co-evolving. Metal powder producers are bifurcating product roadmaps to serve both high-volume sintered parts and high-value AM/MIM applications. Our adoption curve models quantify the margin delta between these pathways and identify “hot” alloys where premiumization is most pronounced.
-
Regulation and geopolitics — trade measures and defense procurement clauses continue to impact demand patterns for refractory metals and critical powders. Companies active in defense or high-security supply chains must bake compliance and localization costs into pricing models. The study integrates publicly disclosed tariff actions and procurement policy shifts to produce region-agnostic stress tests for supplier viability.
-
Raw material volatility — feedstock cost swings and localized shipment disruptions (notably for MIM and AM segments) materially affect margins. Our price-sensitivity scenarios show which product families are most exposed and which business models (tolling, forward-buying, integrated refining) are effective mitigants.
-
Standards and qualification — ISO standards and industry-specific qualification cycles remain gating factors for OEM adoption. Speed-to-qualification is a competitive advantage; the report includes go-to-market timelines and certification cost curves for common customer verticals.
-
End-market pull — while automotive and industrial users remain large-volume consumers, aerospace, medical, and defense applications are driving higher-margin demand for specialty powders and traceable supply chains. Our sector-specific demand models highlight when and how these verticals will influence product mix and pricing.
Competitive landscape: who matters and why
The PM value chain is anchored by legacy and emerging players that play different strategic roles — raw powder producers, integrated component manufacturers, specialty alloy houses, and regional champions. Our competitive analysis synthesizes company-level capabilities, technology roadmaps, and recent corporate moves to illuminate likely consolidation and partnership paths in 2026.
-
Höganäs AB (Höganäs, Sweden) — Leading iron and alloy powder producer with a broad base in sintered components; positions itself as an enabler for high-volume precision parts.
-
Sandvik AB (Stockholm, Sweden) — Supplier to both PM and AM markets; its Osprey business has been a recognized technology brand in metal powders.
-
GKN Powder Metallurgy (Telford, UK) — Global footprint in metal powders and sintered components; strong OEM relationships in automotive and industrial sectors.
-
CNPC Powder (Shanghai, China) — Large-scale supplier with aggressive capacity expansion and integrated R&D initiatives targeting global markets.
-
JSC POLEMA (Tula, Russia) — Specialist in high-purity refractory powders with applications in demanding industrial and defense systems.
-
Advanced Technology & Materials Co., Ltd. (AT&M) (Beijing, China) — Focused on advanced, refractory, and functional powders for next-generation applications.
-
Molyworks Materials Corporation (Houston, TX, USA) — Niche supplier emphasizing sustainable, high-performance powders for PM and AM.
-
Rio Tinto Metal Powders (Vancouver, Canada) — Miner-to-powder producer that leverages upstream integration for alloy control and scale.
-
IperionX Limited (South Boston, VA, USA) — Titanium powder specialist pursuing low-carbon production processes and modular manufacturing.
-
Sterling Sintered Technologies (Winsted, CT, USA) — Precision sintered component maker with capabilities in high-precision applications.
-
Carpenter Technology Corporation (Philadelphia, PA, USA) — Specialty alloy producer supplying MIM, HIP, and AM markets with engineered powders.
-
Liberty House Group (United Kingdom) & CRS Holdings Inc. (United States) — Regional suppliers and strategic acquirers shaping supply availability across territories.
Recent corporate developments — such as the acquisition of a major MIM/AM powder business by Mimir (June 2026), CNPC Powder’s new production and R&D facility being constructed in California (June 2026), and IperionX commissioning large-scale press equipment at its Virginia campus (May 2026) — illustrate active repositioning among suppliers. These moves are consistent with the broader thesis that capacity, technology control, and near-market presence will be the competitive differentiators during the next three years.
What the full report delivers (practical, actionable deliverables)
-
Transparent market sizing and forecasting models (base year 2025, historic 2020–2025, forecast 2026–2032) with scenario permutations for slower/higher growth paths.
-
Demand-by-use-case frameworks and product-at-risk matrices to prioritize R&D, qualification, and commercialization investments.
-
Supply-chain maps including cost-to-serve, single-point-of-failure heatmaps, and supplier creditability scoring — designed to inform procurement contingencies and localization strategies.
-
Competitive playbooks: company profiles, capability scoring, strategic intent assessments, and M&A targets that align with buyer objectives.
-
Practical toolkits — playbooks for qualification acceleration, sample contracting terms for long‑lead alloy procurement, and a decision matrix to evaluate tolling vs. asset ownership.
-
Interactive dashboards (proprietary) for executives to test “what-if” inputs on pricing, raw material shocks, and contract structures.
Note: in keeping with our preview approach, the article above intentionally highlights themes and capabilities in the study while withholding detailed tables, region- and application-level splits, and proprietary unit economics. These elements are available in the full research package and are essential for transaction-level decision-making.
Recommended 90-day actions for executive teams in 2026
-
Run a supplier vulnerability assessment and secure dual-sourcing or tolling options for at-risk alloys within 30 days.
-
Prioritize capital deployment toward either capacity expansions in higher-margin powder classes or acquisition of downstream integration (component sintering/HIP) depending on your balance-sheet strength; use our quick-decision matrix to select the optimal path.
-
Commission a qualification sprint with one tier-1 OEM to accelerate entry into aerospace or medical channels if your powder portfolio includes high-purity or specialty alloys.
-
Re-examine contractual protections against feedstock price shocks and regulatory sourcing risk; implement hedging or indexation where appropriate.
Closing — how to use this intelligence
Powder metallurgy is maturing into a strategic battleground where technology leadership, supply-chain control, and customer qualification speed determine winners. Our report equips C-suite and business unit leaders with the macro view, the tactical tools, and the competitor insights necessary to make high-conviction decisions in 2026. If your objective is to prioritize capital, de-risk supply, or identify acquisition targets aligned with the projected USD 21+ Billion market by 2032, the full report contains the segment-level analytics and transaction-ready intelligence required to act with confidence.
To access the complete dataset, proprietary scenario models, and the full set of company profiles and M&A targets, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Powder Metallurgy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Road Bikes Market to hit USD 5.49B by 2032 at 4.85% CAGR
By PW Consulting, 2026-07-22
Road Bikes Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As firms rebase their 2026 strategies, the road bikes market presents a familiar paradox: structurally attractive long‑term growth underpinned by clear technical and regulatory inflection points that will separate winners from the rest. Our PW Consulting Road Bikes Market study synthesizes seven years of historical performance (2020–2025) and a detailed 2026–2032 forecast horizon to give executives the decision‑grade intelligence required to act with conviction. In macro terms, the addressable market has expanded steadily through 2025 (reaching USD 3.85 Billion in our base year) and is projected to resume a mid‑single‑digit expansion profile across the forecast window (CAGR 4.85%), reaching an estimated USD 5.49 Billion by 2032 — growth that rewards the companies that adapt their product, supply‑chain and commercial models to faster structural change.
Road Bikes Market
Why this report matters for 2026 planning
-
Timing: 2026 is not just another year. New technical rules, public policy debates and material cost volatility converge to compress execution risk — companies that hedge, innovate and reconfigure now will capture outsized returns.
Road Bikes Market -
Decision utility: The study is built as a toolkit for executives — not an academic exercise. It translates market trajectories into action: SKU rationalization priorities, supplier diversification roadmaps, pricing levers and M&A screening criteria calibrated to risk scenarios facing the sector.
Road Bikes Market -
Competitive clarity: The market shows moderate concentration (top‑three firms account for a meaningful share and the top five increase that concentration materially), implying attractive scale benefits but also room for specialist and D2C challengers. Our analysis pinpoints where economies of scale matter most — manufacturing, wheelsets and integrated cockpit systems — and where specialist differentiation (materials, aerodynamics, race compliance) continues to command premium pricing.
Macro dynamics shaping 2026 decisions
-
Regulatory shock windows: Two regulatory factors create immediate product‑planning implications. First, UCI’s 2026 fork internal width restrictions (maximum internal widths of 115mm front and 145mm rear) require manufacturers supplying professional and high‑performance segments to revalidate fork and wheel interfaces — a non trivial engineering and inventory risk for 2026 model year launches. Second, trade policy uncertainty — highlighted by a public comment period in late 2025 considering steep tariffs on bicycle metal content — introduces episodic sourcing cost risk and potential need for near‑term localization of key metalwork.
-
Raw material pressure: Industry participants report sustained raw materials inflation (steel, aluminum and carbon fiber increases in excess of 30% across recent years). That shift has compressed manufacturer margins and altered the calculus of material selection and platform engineering. Expect continued focus on carbon content optimization, hybrid material systems and value engineering to preserve margin while meeting performance targets.
-
Channel bifurcation: Direct‑to‑consumer players that own digital touchpoints and logistics efficiencies continue to apply pricing pressure on mainstream models, while heritage brands leverage team partnerships and premium positioning to defend margins in the top tiers. This dynamic forces different strategic responses across price tiers: scale + cost leadership at the mainstream end; engineered differentiation and brand premium at the top end.
-
Adjacent regulatory noise: Advocacy on e‑motorcycle/e‑bike classification and other category definitions (led by industry associations) can alter consumer perception and regulatory burdens across the broader bicycle market. Companies with diversified portfolios should monitor these debates — misclassification risks can distort demand and distribution access.
Competitive landscape — who matters and why
The market’s competitive fabric blends legacy marques, premium engineering specialists and direct‑to‑consumer disruptors. Each archetype drives different strategic outcomes:
-
Premium performance incumbents (Specialized, Trek, Cannondale, Cervélo, Pinarello, Bianchi, Factor, BMC, Scott): These players derive value from R&D, pro‑team exposure and materials expertise. Their immediate priorities for 2026 include validating new fork geometries to meet UCI rules, protecting margin against carbon price pressure and preserving race‑derived halo products that lift full‑line pricing.
-
Volume and scale players (Giant): Firms with integrated manufacturing footprints and system engineering capabilities can exploit continuous improvement — as illustrated by recent product updates that delivered measurable efficiency gains. Their playbook in 2026 will focus on incremental aerodynamic and component system optimizations to capture watts and cost advantages.
-
D2C value challengers (Canyon): Direct channels compress the dealer margin but offer tight customer data for rapid iteration and configuration economics. Such models force incumbent dealer networks to sharpen value propositions and selectively defend segments where in‑store service and fitting matter most.
-
Specialist innovators (Factor, Cervélo): These firms extract premium pricing from niche technical leadership — compliance with UCI changes and advances in carbon layup or fork integration are a competitive moat if executed faster and validated through performance outcomes.
Recent market signals validate these dynamics: Giant’s March 2026 Propel update claims an 18‑watt efficiency improvement through system refinements; Canyon and other brands shipped updated endurance and performance lines in mid‑2026; Bianchi’s multi‑year supply agreement announced in late 2025 underscores the strategic value of pro‑team partnerships for brand equity. Industry advocacy also remains active — trade groups filed comments opposing steep metal tariffs in late 2025, highlighting the adoption and policy risk that companies must manage.
Practical strategic moves for 2026
-
Product line triage and platform rationalization: Prioritize platform architectures that allow rapid compliance updates (e.g., fork interfaces) and modular component swaps. Rationalize SKUs where dealer complexity adds cost without commensurate return; redeploy saved engineering capacity to compliance and high‑margin innovations.
-
Supply‑chain risk mapping and hedging: Layer sourcing strategies with near‑term hedges on carbon and aluminum, expand second‑tier suppliers in low‑risk geographies, and evaluate partial nearshoring for metal sub‑assemblies if tariff scenarios materialize. Negotiate cost‑pass‑through clauses with strategic suppliers where feasible.
-
Commercial segmentation and channel design: Run a double test — pilot D2C models in select markets while preserving premium retail experiences where fit and service are material to conversion. Rework margin pools with dealers through data‑backed promotions and exclusive service bundles.
-
M&A and partnership playbook: Where scale is the barrier, pursue tuck‑ins that secure wheelset, cockpit or carbon layup capabilities. Where speed to compliance matters, consider engineering partnerships or targeted investments to accelerate UCI‑compliant fork designs.
-
Regulatory engagement: Proactively engage with trade associations and regulators to influence policy outcomes. Prepare contingency plans for tariff implementation and create rapid response teams to reprice and reconfigure supply chains.
What the PW Consulting report delivers (operational highlights)
-
Proprietary market model with annualized historicals (2020–2025) and a granular 2026–2032 forecast engine that supports scenario toggles for tariff, material cost and regulatory outcomes.
-
Competitor dossiers and product benchmarking for the industry’s leading brands, including engineering focus areas and go‑to‑market positioning.
-
Regulatory risk matrix that quantifies practical engineering and commercial impacts from UCI rule changes and potential trade measures.
-
Supply‑chain heatmaps and cost‑pass‑through stress tests to model margin sensitivity under multiple raw‑material price regimes.
-
M&A screening tool and a 12‑month playbook for integration or partnership scenarios, prioritizing capabilities that accelerate compliance and reduce unit cost.
-
Retail economics and channel optimization templates to test D2C rollouts versus protected dealer strategies.
How to use this preview and next steps
This preview is designed to accelerate your 2026 strategic planning. Use it to align executive priorities, stress‑test capital allocation decisions and refine product‑roadmap tradeoffs with clarity. If your immediate needs are tactical — for example, updating the 2026 model year fork architecture, negotiating supplier contracts, or validating a D2C pilot — the full PW Consulting Road Bikes Market report contains the segment‑level forecasts, supplier lists and scenario outputs required to operationalize those moves. We deliberately withhold full segment-level breakdowns in this preview to preserve the actionable value of the full study.
For leadership teams focused on decisive action in 2026, the report converts uncertainty into a set of prioritized, time‑bound initiatives: where to invest in engineering to protect premium pricing, where to consolidate SKUs to preserve margin, and how to structure supply arrangements that balance cost and resilience. Our clients use these deliverables to align R&D sprints, supplier negotiations, commercial pilots and M&A target lists over the next 12 months.
Final note — the signal you should not ignore
Mid‑single‑digit CAGR and an expected increase in absolute market size through 2032 create a favorable backdrop; but growth is not distributionally uniform. Regulatory windows (UCI fork limits and the trade policy debate), raw material inflation and channel economics will reallocate profit pools more than demand growth does. The 2026 planning cycle will be decisive: companies that combine engineering agility, disciplined portfolio management and proactive supply‑chain reconfiguration will convert nominal market growth into sustainable market leadership.
Access the full PW Consulting Road Bikes Market report for the segmented forecasts, supplier matrices, deal lists and the executable 12‑month playbook that your 2026 planning team needs. Our research will let you trade uncertainty for an actionable program — calibrated to the scenarios that matter.
For detailed analysis of this topic, please visit the official page: Road Bikes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sand Sieving Machine Market to Rise from USD 118.45 Million in 2025 to USD 175.78 Million by 2032 (2026–2032 forecast) at 5.8% CAGR — Asia‑Pacific Holds 51.25%, Vibratory Type Dominates with 68.7%
By PW Consulting, 2026-07-17
Sand Sieving Machine Market — 2026 Strategic Outlook (PW Consulting)
As infrastructure programs, urban growth and evolving sustainability standards reshape raw-material supply chains, sand sieving equipment has moved from a purely operational purchase toward a strategic investment. PW Consulting’s latest Sand Sieving Machine Market report (base year 2025, forecast 2026–2032) synthesizes five years of historical tracking with forward-looking scenario analysis to equip executives with the insights they need to make high-conviction decisions in 2026.
Sand Sieving Machine Market
Why this report matters for 2026 decision-making
Between 2020 and 2025 the global sand sieving machine market expanded from a modest base to a substantially larger market as demand for processed sand increased across construction, mining and industrial users. Our market model, grounded in granular equipment deployment and end-use construction flows, estimates the market at USD 118.45 Million in 2025 and projects growth to USD 175.78 Million by 2032, implying a steady compound annual growth rate of 5.8% through the forecast horizon.
Sand Sieving Machine Market
For 2026 strategy, three practical implications emerge from this macro trajectory: first, manufacturers and buyers should expect steady volumetric demand but rising margins pressure from commodity input swings; second, competitive advantage will accrue to suppliers who combine field-proven mechanical designs with service-driven aftermarket and digital value propositions; third, regulatory and material-replacement dynamics (notably restrictions on new natural sand extraction and the rise of manufactured sand) will continue to redirect procurement toward higher-precision sieving equipment.
Sand Sieving Machine Market
What the report delivers — practical, transaction-ready intelligence
-
Transparent market-sizing and scenario methodology: clear line-of-sight from historical installation data (2020–2025) through 2026 base assumptions to 2032 forecasts, with sensitivity runs for commodity-cost and regulation-driven demand shocks.
-
Demand-driver playbook: quantified levers and decision trees for procurement, including capex vs. leasing trade-offs, utilization thresholds for payback, and retrofit vs. greenfield sourcing considerations tailored to construction and industrial buyers.
-
Cost and pricing models: bottom-up manufacturing-cost templates that isolate steel and electro-mechanical content, plus a steel-price sensitivity module that models the impact of raw-material volatility on vendor margins and buyer TCO.
-
Technology and product benchmarking: side-by-side assessment of vibratory, rotary and manual sieving approaches against throughput, particle-precision, maintenance intensity and site adaptability—presented as decision matrices for different use cases.
-
Procurement & supplier-selection toolkit: RFP templates, scoring rubrics, warranty and spare-parts strategies, plus a field-service SLA playbook that addresses uptime requirements for concrete and industrial sand production.
-
Commercial battleground analysis: go-to-market maps, distribution channel diagnostics and aftermarket opportunity sizing—designed to help manufacturers prioritize investment across regions and channels.
-
Actionable case studies: real-world deployment examples that reveal common retrofit pitfalls, installation sequencing guidance, and measurable performance improvements tied to screening accuracy and material-reuse rates.
Competitive landscape — what incumbents and challengers mean for 2026
The supply side of the sand sieving market presents a mix of global engineering houses, specialized European technology providers, and price-competitive regional manufacturers. Each archetype implies different partnership and competitive strategies.
-
Global engineering leaders — Firms with heavy-equipment pedigree are notable for rugged, high-throughput vibrating screens and comprehensive lifecycle service capabilities. Their designs prioritize uptime, heavy-duty performance and integration into larger processing lines. For buyers focused on reliability and total cost of ownership across large-scale sites, these vendors often represent the lowest long-run risk.
-
Precision specialists — A smaller set of providers focus on high-accuracy screening technology for industries like ready-mix concrete and high-grade quartz. These systems command premium pricing where particle-size specification is mission-critical, and they open opportunities for focused aftermarket revenue around calibration and quality assurance.
-
Regional fabricators and value players — Local manufacturers offer lower capital entry points and rapid lead times, which is attractive for smaller contractors and fast-moving construction projects. Their competitive edge is cost, but buyers should balance that with serviceability and long-term performance trade-offs.
PW Consulting’s report profiles a curated set of vendors across these archetypes, detailing product portfolios, service footprints and strategic posture. The vendor set includes established heavy-engineering manufacturers, precision-screen suppliers, and prominent regional producers. We map product roadmaps to customer use-cases and highlight where suppliers are investing—mobile screening solutions for site mobility, high-accuracy classifiers for concrete-grade sand, and modular platforms that reduce maintenance downtime.
Recent market moves and structural headwinds
Two development themes will shape procurement and supplier strategy in 2026:
-
Product evolution toward mobility and accuracy: Leading vendors continue to refine mobile screening platforms for on-site flexibility and high-precision industrial classifiers for concrete production. These developments lower time-to-value for contractors while supporting tighter particle-size compliance.
-
Raw-material and regulatory pressure: Steel price volatility materially affects manufacturing economics—hot-rolled coil moved meaningfully higher in 2026, increasing input cost pressure on equipment makers. Concurrently, environmental restrictions on new sand extraction are accelerating demand for processed and manufactured sand, elevating the importance of precision sieving in the value chain.
Strategic playbook for 2026
Executives should translate the report’s insights into three immediate actions:
-
Reassess procurement criteria: Move beyond headline capital cost to a multi-dimensional evaluation incorporating uptime risk, spare-parts logistics, retrofit complexity, and energy consumption. Use the report’s procurement scorecards to standardize assessments across tenders.
-
Hedge supply-chain exposure: Incorporate steel-price scenarios into budgeting and consider supplier financing, local sourcing or modular designs that reduce steel intensity. Service agreements that include parts hedging can stabilize operating budgets.
-
Prioritize aftermarket and digitization: Vendors that bundle predictive maintenance, remote diagnostics and consumable supply contracts will capture disproportionate aftermarket value. Buyers should negotiate SLAs that align incentives for uptime and quality.
How executives should use this report
PW Consulting’s Sand Sieving Machine Market report is designed to be both a strategic compass and an operational workbook. Use it to:
-
Frame multi-year equipment investment plans and CAPEX phasing aligned to construction cycles;
-
Benchmark vendor claims during RFPs using our third-party technical scorecards and field case metrics;
-
Identify M&A and partnership targets—either precision specialists for capability build or regional fabricators for cost and speed-to-market;
-
Build internal TCO models that incorporate steel-price exposure, service contracts and productivity differentials documented in the report.
Methodology and credibility
The report combines a transparent mix of primary interviews, field-installation audits, supplier product literature and triage of public financial disclosures. Historical analysis covers 2020–2025, the report uses 2025 as its base year, and presents a probabilistic forecast for 2026–2032. The headline growth trajectory—a mid-single-digit CAGR across the forecast window—reflects both structural demand from construction and incremental replacement and upgrade cycles.
We intentionally present the market narrative and decision-ready recommendations here while reserving full segment-level tables, regional breakdowns and vendor financial models for the full report. That detailed intelligence includes the granular splits, downloadable templates, and appendices buyers and investors use to execute vendor selection and capital allocation with confidence.
Next steps
For procurement leads, corporate strategists and investors planning 2026 initiatives, PW Consulting’s comprehensive report provides the operational blueprints and calibrated market assumptions needed to act. To access the complete dataset, models and supplier appendices, please visit our report page or contact the PW Consulting industry desk to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Sand Sieving Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Adsorption Chillers Market Poised for Steady Growth at 3.6% CAGR Through 2032
By PW Consulting, 2026-07-17
Adsorption Chillers Market 2026 Outlook: Strategic Signals for Decision-Makers
Executive snapshot
As PW Consulting’s senior strategic advisor, I present a forward-looking synthesis of our Adsorption Chillers Market report that is designed to inform executive choices in 2026. The market for adsorption chillers — a niche yet strategically important segment within low-grade-heat recovery and sustainable cooling — shows steady expansion with an underlying compound annual growth rate (CAGR) of 3.6% across the 2026–2032 forecast window. Our topline sizing places global revenue at roughly USD 215.4 Million in the report base year (2025), having climbed from the 2020 baseline, and we project upward momentum through 2032 toward the mid-to-high two hundreds (USD 274.8 Million under the central scenario). This trajectory reflects an industry balancing steady demand, technology refinement, and episodic volatility tied to macro and regulatory inflection points.
Adsorption Chillers Market
Why this matters for 2026 planning
For firms evaluating capital allocation, product roadmaps, or M&A strategies in 2026, adsorption chillers are no longer a peripheral “sustainability play.” They represent a pragmatic lever for decarbonization and cost avoidance where waste-heat, solar-thermal, or cogeneration resources exist. Our analysis shows three practical reasons to prioritize adsorption-chiller strategies in 2026:
Adsorption Chillers Market
- Actionable returns from waste-heat integration: companies that can deploy adsorption chillers alongside low-grade heat sources (CHP, biomass, or solar thermal) capture operational savings while aligning with tightening environmental standards.
- Resilience through diversification: adsorption chillers offer a low-electricity, thermally driven cooling option that reduces exposure to grid volatility and peak-power tariffs—important as energy markets evolve.
- Regulatory and procurement tailwinds: increasing environmental regulations and green procurement criteria are accelerating adoption in industrial and commercial segments, creating near-term market pull that supports pilot-to-scale rollouts.
Market behavior and what the numbers hide (and reveal)
The topline market series in our report documents a non-linear growth path from 2020 to 2032. After a solid recovery following early-decade disruptions, the market stabilizes into a modest growth regime consistent with the stated 3.6% CAGR for the forecast period. Importantly, the topline masks heterogeneity across technology types, end-users, and geographies — heterogeneity that materially affects deployment economics and vendor selection. That heterogeneity is a strategic opportunity: firms with the right analytics can target high-ROI subsegments and avoid commoditized competitive battlegrounds. For confidentiality and to preserve the “trailer” principle of this release, we are intentionally withholding detailed subsegment figures here; the full report provides granular splits, sensitivity scenarios, and downloadable models that buyers and licensees can use for precise financial planning.
Adsorption Chillers Market
What the report delivers — practical, operational insights
Our Adsorption Chillers Market report is designed for executives and technical leads who must convert market intelligence into executable plans. Highlights include:
- Market sizing and validated forecasts (historical 2020–2025, base year 2025, forecast 2026–2032) with scenario analysis for downside, base, and upside pathways.
- Technology deep-dive examining silica gel and zeolite adsorption media, performance trade-offs, lifecycle reliability, and maintenance vectors that drive total cost of ownership.
- Integration playbooks for cogeneration, solar thermal, and industrial waste-heat sources — including practical checklists for site surveys, thermodynamic mapping, and CAPEX/OPEX phasing.
- Procurement and commercial models — template RFP language, expected lead times, and contractual considerations for performance guarantees tied to thermal input variability.
- Regulatory and policy mapping relevant to 2026 compliance risks and incentives, enabling faster approvals and access to green financing.
- Vendor landscape assessment with capability heatmaps, product archetypes, and a competitive scorecard to guide shortlisting for pilots and rollouts.
- Case studies and pilot evaluations demonstrating quantified energy and emissions benefits across representative industrial installations.
Competitive landscape — who to watch
The market exhibits moderate concentration: the top three vendors account for a meaningful share of revenue, and the top five further consolidate reach — a pattern we quantify in the full report and model for impact on procurement dynamics and pricing power. Several established vendors and emerging specialists, each with differentiated strengths, define the competitive set:
- Fahrenheit GmbH (Halle, Germany) — known for modular, zeolite- and silica-based systems targeted at industrial and commercial players seeking compact, scalable waste-heat solutions.
- Bry-Air (India) — offers a broad array of silica gel-water adsorption chillers across a wide capacity band and emphasizes waste-heat and solar-thermal utilization for process cooling across several heavy industries.
- InvenSor GmbH (Germany) — focuses on direct-coated zeolite units optimized for high-ambient-temperature contexts and constrained heating sources — a compelling proposition in several emerging markets.
- Mayekawa (Japan), Thermax (India), Hitachi (Japan), and Johnson Controls (YORK systems) — each leverages parent-company strengths (manufacturing scale, systems integration, or building controls) to offer adsorption-chiller solutions as part of broader energy or HVAC portfolios.
- Specialist and regional providers — SorTech AG, Berg Chilling Systems, Kawasaki Thermal Engineering, and a host of China and South Korea-based manufacturers — supply tailored capacity models and localized service networks important for distributed deployment.
Recent, verifiable market activity underscores vendor momentum: Johnson Controls received industry recognition for YORK-related absorption/adsorption technology in mid-2025; Bry-Air refreshed its product catalogue and market availability in early 2025 to emphasize waste-heat solutions; and Fahrenheit continued active modular system supplies through 2025. These moves signal vendor emphasis on product maturity, supply readiness, and market positioning ahead of project procurement cycles in 2026.
Key dynamics shaping 2026 choices
- Regulatory tightening: Environmental rules and sustainability procurement are shifting capital toward thermally driven cooling as a compliance and reputational tool.
- Raw-material and performance gains: Advances in adsorbent materials (silica gel and zeolite) materially improve reliability and cycle performance — reducing lifecycle cost and expanding viable use cases.
- Systems integration: The most compelling commercial propositions pair adsorption chillers with CHP, biomass, or solar-thermal inputs to elevate utilization and shorten payback windows.
Practical recommendations for 2026 decision-makers
Based on market sizing, vendor behavior, and technology dynamics, companies should prioritize the following actions in 2026 to capture value and mitigate risk:
- Run targeted pilots tied to controllable heat sources. Prioritize projects where thermal input is predictable — industrial waste-heat lines, CHP bleed streams, or dedicated solar-thermal arrays — and instrument them for performance verification over seasonal cycles.
- Secure supply and materials visibility. Engage early with adsorbent suppliers and vendors to understand lead times and quality controls for silica gel and zeolite. Consider dual-sourcing or off-take agreements for strategic installations.
- Design modular procurement strategies. Favor modular, scalable architectures that allow stepwise CAPEX deployment and reduce technology obsolescence risk as adsorbent improvements arrive.
- Embed performance contracting. When possible, negotiate vendor guarantees tied to kW cooling produced per unit of recovered heat and include clear maintenance and spare-parts commitments to protect uptime.
- Assess M&A and partnership plays. Given moderate market concentration, partnerships with specialist manufacturers or acquisitions of regional players can accelerate market entry and service footprint expansion.
- Invest in monitoring and analytics. Real-time thermal-to-cooling performance tracking not only protects ROI assumptions but creates a data asset for scaled rollouts and financing conversations.
Final note — the strategic value of the full report
This release is a condensed brief designed to highlight actionable themes and immediate implications for 2026. The full PW Consulting Adsorption Chillers Market report contains the granular subsegment breakdowns, scenario-modeled financials, vendor scorecards, and downloadable tools you will need to convert the strategic signals above into executable plans. For teams that must justify capital with detailed NPV, sensitivity analyses, and site-level economics, the full dataset and proprietary models are essential.
In an industry where material science improvements and integration strategies dictate winner-takes-most outcomes at specific use-cases, early movers who combine rigorous pilot validation, supplier risk management, and contract structures that align vendor incentives will capture outsized return on a market growing at a steady, investable pace. Reach out to PW Consulting to license the full report and the decision-grade models needed to accelerate your 2026 deployment roadmap.
For detailed analysis of this topic, please visit the official page: Adsorption Chillers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Gas & Liquid Separation Accumulator Market Poised for 5.25% CAGR Growth in 2026–2032
By PW Consulting, 2026-07-17
Gas & Liquid Separation Accumulators: Strategic Imperatives for 2026 — Preview from PW Consulting’s Market Report
PW Consulting’s new Gas & Liquid Separation Accumulator Market report provides a strategic compass for executive teams preparing 2026 budgets and medium-term capital plans. After analysing five years of historical performance (2020–2025) and developing a rigorous forecast through 2032, our base-case model shows the global market expanding from a 2025 revenue level of USD 179.65 Million to USD 257.13 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.25% across the forecast window. These headline metrics capture a market that is mature in core industrial end‑uses yet being reshaped by regulatory pressure, material cost dynamics, and evolving end‑market demand patterns — all of which carry immediate strategic consequences for suppliers, OEMs, and large end users.
Gas & Liquid Separation Accumulator Market
Market trajectory and macro drivers
The market’s path from 2020 through 2025 shows resilience amid episodic demand swings and supply‑side stress. While short-run variability reflected upstream capex cycles and pandemic-era disruptions, the structural growth drivers remain intact: continued energy production and processing activity, electrification/automation of hydraulic systems, and increased emphasis on pulsation control and energy recovery in heavy mobile and stationary applications. The forecast to 2032 incorporates these drivers alongside sensitivity to raw materials — primarily carbon steel for housings and specialized elastomers for bladders — whose cost and availability influence producer margins and pricing strategies.
Gas & Liquid Separation Accumulator Market
Regulatory frameworks are another defining force. Compliance requirements such as the European Pressure Equipment Directive (PED) and longstanding US standards (ASME Section VIII) continue to raise the bar for design validation, testing and documentation. For many manufacturers, certification is a de‑facto market access condition; for buyers it is an essential procurement constraint. Firms that internalize certification and testing capabilities as strategic assets will shorten time to market and win higher‑margin, compliance‑sensitive contracts.
Gas & Liquid Separation Accumulator Market
Strategic implications for corporate decision‑makers in 2026
- Product portfolio prioritization: With steady market growth at ~5.25% CAGR, firms should rationalize SKUs around high‑value use cases (energy storage, pulsation damping for oil & gas, and machinery retrofit markets) and sunset low‑volume, high‑cost variants.
- Certification as competitive advantage: Investing in in‑house testing or partnerships with accredited centers reduces bid cycle time for regulated tenders and supports premium pricing.
- Supply chain de‑risking: Hedging strategies for elastomers and critical steel grades, dual sourcing and secured long‑term contracts will protect margins as demand recovers and material markets exhibit volatility.
- Aftermarket and services monetization: Service, spare parts and turnaround support are defensive revenue pools with higher margins than OEM sales — strengthen contractual frameworks and digital service capabilities.
- M&A and capacity plays: Given a moderately concentrated supplier base, targeted acquisitions or capacity alliances can accelerate access to certification regimes, broaden product portfolios and serve as rapid market entry mechanisms.
Competitive landscape — capability map and tactical moves
The market is moderately concentrated: the top three players account for a meaningful share of revenue, while the top five consolidate a clear majority. This structure produces strategic implications for challengers and leaders alike. Market incumbents remain differentiated by engineering depth, certification breadth, global manufacturing footprints and service networks.
- HYDAC International GmbH (Sulzbach, Germany) — Known for elastomer bladder technology oriented to high‑frequency and mobile hydraulics. HYDAC’s engineering focus makes it a go‑to for complex system integrations and high cycle applications.
- Parker Hannifin Corporation (Cleveland, Ohio, USA) — Offers a broad portfolio across bladder, piston and diaphragm technologies and leverages ASME‑certified lines to capture regulated oil & gas and industrial contracts worldwide.
- Bosch Rexroth AG (Lohr am Main, Germany) — Positions accumulators as part of larger hydraulic power unit offerings; recent certification investments in regional testing hubs expand its serviceable market, especially in regions with tighter regulatory controls.
- Eaton Corporation plc (Dublin, Ireland) — Uses scale and channel reach to supply bladder accumulators across industrial and mobile segments, competing on global distribution and integrated solutions.
- Freudenberg Sealing Technologies (Tobul) (Bamberg, SC, USA) — Differentiates through sealing and materials expertise; cross‑application transfers (e.g., automotive to agricultural machinery) are an important source of incremental growth and product innovation.
- Accumulators, Inc. (Houston, Texas, USA) — A US‑centric manufacturer with focus on pulsation damping and energy storage solutions; competitive where proximity and rapid service are decision levers.
- Roth Hydraulics GmbH (Biedenkopf, Germany) — Broad product range; recent acquisition activity has expanded its US manufacturing and service presence, accelerating access to North American OEMs.
- PacSeal Hydraulics (USA) — Emphasizes ASME‑certified bladder accumulators and reliable delivery for hydraulic circuits; well positioned in regulated procurement environments.
Recent strategic moves illustrate the competitive dynamics: Roth Hydraulics’ acquisition to expand North American capacity, Bosch Rexroth’s increment in regional certification and testing, and Freudenberg’s technology transfer from automotive to agricultural machinery. These actions signal that scale and certification capabilities will be decisive in 2026‑era competitions.
What PW Consulting’s report delivers (practical components)
Beyond headline projections, the report is intentionally operational to enable immediate action by strategy, product and procurement teams. Key deliverables include:
- Bottom‑up market model with company‑level triangulation and multi‑scenario forecasts (base, upside, downside) to stress test budget assumptions.
- Capex and cost‑build templates for housings and bladders, including sensitivity to steel and elastomer price swings.
- Regulatory impact matrix mapping certification requirements (PED, ASME and regional variants) to product families and route‑to‑market constraints.
- Competitive benchmarking dashboards covering engineering capabilities, certification assets, manufacturing footprints and aftermarket reach.
- M&A target shortlists driven by capability gaps (testing labs, regional capacity, elastomer compounding access) and accretive revenue thresholds.
- Procurement playbook with hedging strategies, supplier scorecards and inventory policy recommendations for 2026 supply volatility.
- Product innovation radar highlighting material science advances, bladder coatings, and system‑level integration opportunities for energy recovery and predictive maintenance.
We deliberately surface the tools and insights corporate teams need to make confident 2026 choices while withholding granular regional and application splits in this release. That detailed segmentation, vendor share tables, and downloadable datasets are available in the full report for licensed subscribers.
Decision playbook — immediate to 36 months
- 0–90 days: Execute a supply‑chain stress test focused on elastomer and high‑grade steel exposure; identify two strategic suppliers and open long‑term procurement discussions. Audit certifications and identify product lines missing regulatory approvals that are blocking tenders.
- 3–12 months: Rebalance product portfolio toward higher margin, compliance‑intensive SKUs; pilot aftermarket service packages with top customers; initiate in‑market certification projects or JV agreements to compress approval timelines.
- 12–36 months: Pursue targeted M&A to acquire testing capacity or regional production; scale digital service offerings (remote diagnostics, predictive maintenance) tied to recurring revenue; implement price escalation clauses aligned to material indices.
Methodology, limitations and how to access the full dataset
Our analysis uses 2025 as the base year, examines historical performance across 2020–2025 and forecasts through 2026–2032. Methodology combines bottom‑up production and company revenue triangulation, supplier cost build‑ups, regulation overlays and primary interviews across OEMs, distributors and materials suppliers. Report limitations include short‑term uncertainty in raw material markets and the timing of regional regulatory updates; our multi‑scenario framework explicitly addresses these contingencies.
For procurement directors, product leaders, and corporate development teams, the core value of the report is pragmatic: it translates a predictable CAGR and multi‑year market growth into executable sourcing, product and M&A playbooks. To review granular regional and application splits, full vendor market shares, price curves and the downloadable financial model, please consult the full Gas & Liquid Separation Accumulator Market report available through PW Consulting’s publications portal.
Closing perspective
As 2026 planning cycles begin, the accumulator market presents both familiar and novel imperatives: steady structural growth paired with accelerating compliance and supply risks. Strategic winners will be those that convert regulatory and materials constraints into capabilities — certification hubs, secured elastomer supply, and aftermarket service platforms — while leveraging acquisitions and partnerships to plug capability gaps. PW Consulting’s report equips leadership teams to prioritize investments and execute with a clear view of risk‑reward tradeoffs; consider this release a tactical briefing that previews the toolkit you will need to translate market growth into profitable, defensible positions.
For detailed analysis of this topic, please visit the official page: Gas & Liquid Separation Accumulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Airplane Propellers Market to expand at 5.65% CAGR, rising from USD 386.55 Million in 2025 to USD 567.72 Million by 2032
By PW Consulting, 2026-07-17
Airplane Propellers Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
As aviation stakeholders prepare their 2026 strategies, PW Consulting’s latest Airplane Propellers Market research brief crystallizes the critical inflection points that will shape supplier, OEM, and investor decisions over the coming decade. Our analysis synthesizes market dynamics, technology trajectories, regulatory pressures, and competitive moves to convert market noise into action-ready intelligence—without trading away the granular market splits that drive subscription uptake.
Airplane Propellers Market
Why this brief matters for 2026 decision-making
The propeller systems market is transitioning from a niche supply chain to a strategically significant element of aircraft performance, cost management, and aftermarket monetization. PW Consulting’s base-year sizing and forecasted trajectory show a market moving from roughly USD 387 million in 2025 to nearly USD 568 million by 2032, growing at a steady compounded annual growth rate of 5.65%. That growth is underpinned by a combination of replacement demand, performance-driven retrofits, and new aircraft programs that favor modern composite and multi-blade architectures.
Airplane Propellers Market
For executive teams planning 2026 budgets or 3–5 year roadmaps, the brief provides the kind of prescriptive, finance-grade analysis that informs capital allocation: where to accelerate product R&D, which supplier risks to neutralize, how to structure aftermarket offers, and where M&A can create defensible scale. We present the evidence and the scenarios—while directing readers to the full report for the precise, transaction-critical split tables and model outputs.
Airplane Propellers Market
What’s under the hood: Practical modules in the report
-
Market sizing & forecast model: A transparent, scenario-driven forecast from 2020 through 2032, including base, upside, and downside pathways. The model ties unit-demand drivers to macro aviation activity and retrofit cycles, enabling CFOs to stress-test revenue projections across different fleet recovery and fuel-price scenarios.
-
Competitive economics & concentration analysis: A bottom-up view of manufacturing cost-drivers, capacity constraints, and profit pools—framed to identify where value migrates between OEMs, component suppliers, and MRO providers as propeller systems evolve.
-
Technology and certification roadmap: An assessment of composite vs. metallic blade architectures, multi-blade innovations, and the regulatory testing burden that now materially affects product launch timelines and CAPEX returns.
-
Supply-chain stress test and supplier-risk heatmap: A granular look at raw-material concentration (notably PAN-based high-modulus carbon fibers), conversion bottlenecks, and logistics vulnerabilities—paired with mitigation playbooks (hedging approaches, dual-sourcing strategies, and nearshoring scenarios).
-
Aftermarket and conversion program playbook: Play-by-play guidance on designing conversion offers, pricing strategies, and digital servicing platforms that capture higher-margin installed-base opportunities—built from benchmarked commercial cases and sensitivity analyses.
-
M&A and partnership screening toolkit: Transaction criteria and a ranked shortlist methodology to identify targets that meaningfully improve technology footholds, certification pipelines, or aftermarket reach.
-
Executive decision templates: Investment memos, go/no-go checklists for certification investments, and 24–36 month operational plans that turn market intelligence into executable programs.
Competitive landscape: leaders, challengers, and the aftermarket battleground
The propeller market remains shaped by an established cohort of specialist manufacturers with deep engineering heritage and certification portfolios. Global leaders continue to leverage broad blade libraries and long-established OEM relationships; regional and niche players emphasize customization, experimental and light-sport segments, and rapid adoption of advanced composites.
-
Hartzell Propeller Inc. (Piqua, Ohio) —A long-time leader in advanced propeller design, Hartzell’s product breadth and recent strategic actions are reshaping conversion economics. In April 2026 Hartzell expanded its Top Prop conversion program by adding over 150 models while implementing material price-based reductions on select lines (reported price decreases in some SKUs), and launched digital search tools to streamline customer conversion selection—moves that materially lower barriers to aftermarket upgrades and tighten competitive pressure across the installed base.
-
McCauley Propeller Systems (Wichita, Kansas) —A full-line manufacturer with deep OEM certifications, McCauley’s strength is its role as original equipment supplier for numerous airframes, making it central to any OEM-integrated performance or electrification programs.
-
MT-Propeller Entwicklung GmbH (Atting, Germany) —MT continues to push high-blade-count composite systems into mainstream retrofits. Its recent EASA STC approval for a 7-blade configuration on specific piston-turboprop models and its expansion into the Canadian market underscore a strategic focus on niche high-performance retrofits and regional expansion.
-
Dowty Propellers (Brockworth, UK) —Part of a major aerospace group, Dowty dominates certain large turboprop applications with integrated composite systems and in-house repair & overhaul capabilities—an important model for players seeking full lifecycle monetization.
-
Specialists and regional players: Sensenich, Airmaster, GT Propellers, Catto, Hoffmann, and WhirlWind represent a diverse set of strategies—from light-sport and experimental-focused fixed-pitch suppliers to bespoke composite designers—fueling a competitive aftermarket where customization and time-to-market matter.
Overall, the market exhibits moderate concentration: the top manufacturers command a significant share of revenue and aftermarket influence, while a long tail of specialists preserves innovation velocity and service flexibility. That structure creates both defensive and offensive playbooks for incumbents and entrants.
Key industry dynamics shaping 2026 strategies
-
Material supply tightness and cost volatility: The supply of aerospace-grade carbon fibers remains constrained by a small set of upstream producers, and conversion inefficiencies can amplify cost pressures. During energy-price spikes we have observed double-digit cost impacts on blade line items, creating margin sensitivity for composite-intensive offerings.
-
Certification complexity: EASA and FAA certification processes for new multi-blade composite systems are more demanding than historical metallic propeller approvals. Extended testing requirements translate into higher upfront development expenditure and longer lead times—factors that materially influence NPV calculations for new product programs.
-
Aftermarket conversion economics: Recent supplier-led conversion programs and aggressive pricing moves are compressing cycle times for retrofit adoption. The aftermarket is increasingly where volume and margin converge, but competing on price alone is a racetrack to eroding returns without concurrent service and digital capture models.
-
Product architecture evolution: Multi-blade composite systems and high-performance hybrid materials are enabling measurable increases in fuel efficiency and noise reduction for certain segments—changes that matter for operators chasing lifecycle operating cost reductions.
Strategic recommendations for 2026 (prioritized)
-
Secure raw-material continuity now: For manufacturers and vertical integrators, negotiate multi-year supply contracts, pursue qualified alternative suppliers, and evaluate partial vertical integration into conversion/layup capabilities. Hedging strategies should be tailored to account for episodic energy-driven price shocks.
-
Invest early in certification pipelines: Given the extended testing timelines, firms planning new composite or multi-blade launches in 2026–2028 must begin certification programs immediately. Time-to-certification is a gatekeeper for capturing retrofit cycles tied to fleet modernization windows.
-
Design aftermarket-first propositions: Replicate the conversion-program model with integrated digital tools, transparent pricing tiers, and bundled service offerings. The winners will be those who convert performance upgrades into recurring service revenue.
-
Prioritize targeted M&A and partnerships: Use acquisitions to plug certification gaps, add R&O (repair & overhaul) capability, or acquire niche blade tech. Strategic partnerships—especially with suppliers of advanced fibers and layup technicians—can accelerate time-to-market without all-up capital investment.
-
Optimize product portfolios for risk-adjusted returns: Apply our report’s cost-of-goods and scenario models to prioritize programs that deliver acceptable returns under both base and stress scenarios, particularly given raw-material volatility and certification cost exposure.
How PW Consulting’s brief accelerates your 2026 actions
This industry brief is built as a decision-support tool: each chapter maps directly to an executable element of your 2026 plan—from procurement clauses and certification calendars to aftermarket go-to-market and acquisition screening. For board presentations and investment committees, the brief supplies the empirical backbone and the slide-ready templates that translate strategic intent into budgets and KPIs.
The document intentionally positions high-confidence recommendations and the qualitative intelligence that senior teams need to act now—while reserving detailed split tables, company-level market-share ladders, and transaction-ready financial models for the full report. That approach ensures readers get immediate strategic value while preserving the detailed data that supports commercial and transactional decisions.
Final thought
Propeller systems are no longer a back-of-house commodity. They are a strategic lever for operators seeking immediate fuel and noise advantages, for OEMs aiming to differentiate platforms, and for investors hunting durable aftermarket revenue. PW Consulting’s Airplane Propellers Market brief equips executives to make 2026 decisions with clarity: secure supply, prioritize certification, monetize the retrofit opportunity, and position to lead the next wave of composite and multi-blade adoption.
For access to the full dataset, detailed regional and application splits, company market-share ladders, and our downloadable financial models, visit our report page to obtain the complete report and supplemental decision tools.
For detailed analysis of this topic, please visit the official page: Airplane Propellers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rack-mounted Full Liquid CDU Market Poised to Expand at a 9.85% CAGR Through 2032
By PW Consulting, 2026-07-15
Rack-mounted Full Liquid CDU Market: Strategic Imperative for 2026 — PW Consulting Insights
Executive snapshot
The rack-mounted full liquid Coolant Distribution Unit (CDU) market has moved from niche to strategic core infrastructure for next‑generation compute. Our proprietary modeling shows global revenue expanding from approximately USD 52.45 million in 2020 to USD 105.0 million in 2025, and we forecast continued acceleration through the coming investment cycle to reach roughly USD 203.45 million by 2032 — a compound annual growth rate (CAGR) of about 9.85% for the 2026–2032 forecast window. These macro trajectories reflect a structural shift: cooling is no longer a commoditized utility function but a mission‑critical enabler of density, performance and sustainability for AI, HPC and hyperscale estates.
Rack-mounted Full Liquid CDU Market
Why 2026 is a pivotal year for enterprise and infrastructure decisions
-
Density and thermal ceilings are converging with business demand. GPU and AI accelerators are creating localized heat fluxes that push air‑based approaches past practical limits; rack‑level liquid CDUs are now a mainstream engineering response rather than an experimental niche.
Rack-mounted Full Liquid CDU Market -
Standards and regulation are adding procurement and compliance weight. ASHRAE TC 9.9 guidance on isolating Facility Water Systems from Technology Cooling Systems, and impending addenda to Standard 127 that explicitly address liquid‑to‑liquid CDUs, are changing supplier qualification and test expectations.
Rack-mounted Full Liquid CDU Market -
Material and certification cost dynamics are shifting unit economics. External pressures such as the Kigali Amendment and associated HFC phase‑down are increasing certification scrutiny and supplier cost bases for thermal management subsystems — a factor that will influence total cost of ownership (TCO) calculations in 2026 RFPs.
-
Market structure is consolidating but remains contestable. The market shows moderate concentration: the top three suppliers together account for roughly 48.5% of market share, and the top five roughly 62.8%. That makes strategic positioning and partnerships decisive for both incumbents and challengers.
What the PW Consulting Rack-mounted Full Liquid CDU Report delivers
We designed this study to be immediately actionable for leaders making 2026 budgetary, procurement and infrastructure design decisions. Highlights include:
-
A defensible market sizing and forecast model (2020–2032) with sensitivity scenarios across thermal‑load trajectories and cooling‑system adoption curves.
-
Vendor benchmarking that cross‑references product capability (capacity, form factor, redundancy), operational characteristics (approach temperature, pump architecture, failover modes), and service models.
-
TCO and lifecycle cost models calibrated for a range of deployment archetypes — from hyperscale and colocation to enterprise/HPC — with drill‑downs on capex/opex tipping points.
-
Integration playbooks and engineering checklists covering hydraulic interfaces, leak containment, monitoring/telemetry standards, and facility water system (FWS) isolation strategies aligned to ASHRAE guidance.
-
Procurement tools including RFP language templates, acceptance test plans (ATP), and warranty/service contract comparators.
-
Risk and contingency mapping to support pilot design, roll‑out sequencing and spare parts strategy under supply‑chain stress scenarios.
Note: this press overview is intentionally high‑level. Detailed sub‑segment tables, regional breakdowns and unit‑level pricing matrices are withheld from this summary to protect the report’s proprietary analytics — full access is available via our report portal.
Competitive landscape: practical implications for 2026 strategy
The market comprises a mix of specialized liquid‑cooling scale‑ups, established thermal management OEMs, and systems integrators that bundle CDUs into broader offerings. Key players that illustrate strategic archetypes include:
-
CoolIT Systems (Calgary) — a specialist with in‑rack CHx products emphasizing liquid‑to‑liquid heat exchange for HPC and AI density. Their portfolio is representative of firms that focus on high‑efficiency, compact solutions for OEM partnerships and retrofit paths.
-
Supermicro (San Jose) — a platform OEM providing in‑rack and in‑row CDUs with redundancy and hot‑swap capability. Their approach demonstrates the strategic value of server/CDU co‑engineering in delivering turnkey, high‑availability racks.
-
DCX Liquid Cooling Systems (Warsaw) — represents the compact, high‑density European engineering approach with rack‑level CDUs designed for AI‑focused deployments.
-
LiquidStack (Carrollton) and Flex/JetCool (Austin) — examples of companies pushing scale and modularity, with LiquidStack offering very high capacity units and Flex launching modular solutions that emphasize rapid scaling in GPU‑dense projects.
-
Motivair (Schneider Electric), Dell Technologies, Asetek, nVent and Eaton — incumbents and systems suppliers integrating CDUs into broader thermal portfolios and channel networks, enabling cross‑sell into existing customer bases.
Recent product activity underscores a market in rapid productization: Flex announced a modular rack‑level CDU in September 2025; Motivair unveiled a scalable CDU in January 2026 aimed at multi‑MW architectures; and Dell promoted its PowerCool rack‑mount CDU for dense HPC in late 2025. These moves confirm two important trends — modular scalability and vendor ecosystems competing on full‑stack propositions rather than component specs alone.
Strategic implications by stakeholder
-
For hyperscalers and large cloud providers: prioritize interoperability and lifecycle service economics. Given the scale of deployments required to move overall market sizing forward, selection criteria should emphasize modular expansion, remote diagnostics, spare parts logistics, and compatibility with heat‑reuse strategies.
-
For colocation operators: room for differentiation exists in offering validated liquid‑cooling pods or “CDU‑as‑a‑service.” Operators that can standardize interfaces and offer SLAs that mitigate perceived operational risk will capture premium tenancy.
-
For enterprise IT and HPC shops: pilot early and quantify operational savings. The up‑front premium for liquid CDUs is often recouped through reduced chiller runs, higher inlet temps, and consolidation of floor space — but outcomes depend on site‑specific energy prices and reuse opportunities.
-
For investors and M&A strategists: look for tuck‑ins that add controls, monitoring and field service capability to CDU portfolios; consolidation is likely around vendors that can bundle hardware, software and service economics.
Standards, testing and procurement risk
Standards evolution is altering how vendors demonstrate performance. ASHRAE’s emphasis on FWS/TCS isolation and the inclusion of liquid‑to‑liquid CDU testing protocols in Standard 127 mean that procurement teams must update technical acceptance tests and supplier accreditation processes. Expect buyers to require third‑party test data and to treat conformance certificates as a gating criterion in 2026 tenders.
A practical buyers’ checklist for 2026
-
Define thermal‑load envelopes with conservative headroom for worst‑case density racks and transient events.
-
Specify interface and fail‑safe requirements tied to ASHRAE guidance; require vendor demonstration of FWS/TCS isolation strategies.
-
Demand telemetry and API access for CDU controls to integrate into site BMS/DCIM and for predictive maintenance workflows.
-
Insist on clear spares, service SLAs and defined ATP criteria to reduce operational ambiguity during pilot transitions.
-
Model lifecycle costs across multiple adoption scenarios (pilot, phased roll‑out, full conversion) and stress‑test against energy price and regulatory cost curves.
Investment signals and near‑term outlook
The market’s growth trajectory and the recent flurry of product launches point to several investable themes: modular, high‑capacity CDU architectures; integrated server‑CDU platforms that reduce integration risk; and software/service plays that monetize diagnostics and SLAs. Material cost headwinds and evolving testing norms increase the strategic value of firms with strong supply‑chain control, certification expertise, and proven field operations.
How PW Consulting helps
We help C‑suite and technical leaders translate these market signals into investment, procurement and deployment decisions. Our deliverables include customizable TCO models, vendor scorecards, ATP templates aligned to the latest ASHRAE guidance, and phased roll‑out playbooks validated by field pilots. For procurement teams, we provide RFP language and evaluation matrices that shortcut internal debate and accelerate vendor selection with defensible criteria.
Final note and call to action
Rack‑mounted full liquid CDUs are transitioning from technical curiosity to strategic infrastructure in 2026. The macro picture — a near‑doubling of market size from 2025 to 2032 at ~9.85% CAGR — underscores both the urgency and the opportunity. This release intentionally omits granular regional and application splits as well as the detailed vendor scoring that are included in the full report. To access the complete dataset, interactive models and supplier scorecards (including unit economics and per‑deployment case studies), visit our report portal and download the full Pw Consulting Rack‑mounted Full Liquid CDU Market report.
For detailed analysis of this topic, please visit the official page: Rack-mounted Full Liquid CDU Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Indirect Auto Finance Market to Expand at a 6.85% CAGR, Eyes USD 474.0 Billion by 2032PW Consulting: Worldwide Soundproof Ventilator Market at USD 698.24 Million in 2025, Poised to Reach USD 1,062.44 Million by 2032 at a 6.18% CAGR
By PW Consulting, 2026-07-15
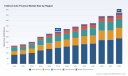
Indirect Auto Finance Market 2026 Strategic Outlook — PW Consulting Report Preview
As auto retailing and consumer credit dynamics converge, indirect auto finance remains a strategic battleground for banks, captives, independent finance companies and dealer partners. PW Consulting’s new Indirect Auto Finance Market report (base year 2025) synthesizes five years of historical performance, a rigorous scenario-driven forecast (2026–2032) and pragmatic, operational playbooks designed to inform board-level and business-unit decisions throughout 2026. The market reached an estimated USD 298.5 Billion in 2025 and, under our central scenario, grows at a compound annual growth rate (CAGR) of 6.85% to 2032 — pointing to sustained expansion, punctuated by material inflection points that demand proactive strategy and capital discipline.
Indirect Auto Finance Market
Why this report matters for 2026 decision-makers
-
Capital allocation: Align portfolio sizing, loss reserves and securitization strategies to a market that is expanding but facing affordability headwinds and regulatory scrutiny.
Indirect Auto Finance Market -
Distribution strategy: Reassess dealer relationship models (exclusive vs. broad networks, captive depth vs. non-captive reach) in light of shifting origination economics and rising dealer-sourced finance volumes.
Indirect Auto Finance Market -
Product design and pricing: Recalibrate underwriting overlays, pricing ladders and ancillary revenue levers for varying credit tiers and vehicle types under tighter macro affordability assumptions.
-
Digital transformation: Prioritize investments in dealer-facing digital workflows and direct-to-consumer touchpoints that shorten decision cycles and reduce origination cost-per-unit.
-
Regulatory readiness: Build compliance scenarios to respond quickly to proposed rulemaking and supervisory focus areas, minimizing disruption to origination pipelines.
Macro dynamics shaping the 2026 playing field
-
Dominance of dealer-originated channels: External research continues to show that the vast majority of auto loans still originate via dealer channels, underlining why dealer economics and intermediation fees remain critical levers for lenders and OEM finance arms.
-
Market share shifts: Independent analyses from early 2026 indicate banks and non-captive lenders are gaining share in dealer-originated indirect loans, changing competitive intensity across prime and near-prime pockets.
-
Regulatory momentum: Recent regulatory activity — including rulemaking proposals and interpretive shifts affecting disparate impact doctrines and nonbank oversight thresholds — raises compliance complexity for nonbank auto financers and for dealer-lender origination practices.
-
Affordability pressures: Industry forecasts point to a modest decline in overall originations in the near term due to affordability constraints; lenders must therefore balance growth ambitions with credit quality and liquidity resilience.
What the trajectory and headline numbers imply
The headline figures in our report provide a macro-level picture: after robust recovery and expansion through 2024–2025, the market is projected to continue growing across the forecast window, reaching a materially larger base by 2032. This pace—and the unevenness of growth through the forecast horizon—suggests that competitive advantages will accrue to organizations that can combine disciplined underwriting, flexible capital programs (warehouse lines and securitizations), and rapid dealer onboarding capabilities. Executives should treat the headline CAGR as a directional planning parameter and use our scenario toolsets to stress-test assumptions about interest rates, vehicle mix shifts and regulatory constraint scenarios.
Competitive landscape — incumbents, challengers and the concentration picture
The indirect channel remains a concentrated but contested arena. The market exhibits meaningful concentration at the top, underscoring the strategic influence of large banks and OEM captives. At the same time, non-captive players and specialty financiers continue to exploit niches — particularly in non-prime and underserved dealer networks — by offering differentiated credit overlays and faster fundings.
-
Ally Financial (Detroit, MI) — A leading non-captive provider with deep dealer relationships and strength in retail installment contracts and dealer floorplan products. Ally’s balance of scale and dealer reach remains a benchmark for competitors seeking national footprint.
-
Capital One Auto Finance (McLean, VA) — Known for competitive pricing and streamlined digital approvals, Capital One has invested in automating dealer decisioning and reducing time-to-funding, a model other banks are emulating.
-
OEM captives (examples include Toyota Financial Services, GM Financial, Ford Motor Credit, American Honda Finance) — Captives continue to leverage brand affinity and captive leasing to protect share in new-vehicle channels while optimizing captive-specific retention strategies.
-
Large banks (e.g., Chase Auto Finance, Wells Fargo Auto) — These institutions blend deposit-funding advantages with extensive branch and dealer networks; their priorities are profitability per account and cross-sell economics.
-
Independent financiers (e.g., Westlake Financial Services) — Independents focus on credit niches and speed, often partnering with independent dealers and leveraging underwriting flexibility to secure volumes where primes are constrained.
Strategic takeaway: market concentration creates high barriers in prime origination economics but leaves exploitable corridors for agile non-captive entrants and technology-enabled servicers. Our report’s competitor scorecards and capability matrices map these corridors without revealing proprietary client data.
Report deliverables — practical, executable and tailored for 2026
PW Consulting designed the report to be a decision-ready toolkit. Highlights include:
-
Scenario-driven financial models: Stress-tested origination, credit and liquidity models across conservative, central and aggressive market paths for 2026–2032, with configurable levers for interest rates, credit mix and dealer penetration.
-
Dealer economics playbooks: Step-by-step guides to optimize dealer compensation mixes, accelerate funding, and reduce chargebacks, including templates for revised dealer agreements and margin waterfalls.
-
Underwriting and portfolio management frameworks: Practical credit overlays, vintage-monitoring dashboards and early-warning indicators tailored to indirect origination features.
-
Regulatory readiness checklist: Actionable measures addressing recent policy developments and supervisory priorities, enabling rapid adaptation to potential changes in nonbank thresholds and fair-lending interpretations.
-
Technology and operations roadmaps: Prioritized investments in dealer portal modernization, straight-through processing, and decisioning engines that materially reduce origination unit costs.
-
M&A and partnership playbooks: Criteria-driven target screens and integration blueprints for capacity acquisitions, fintech partnerships and captive carve-outs.
-
Executive dashboards and board-ready briefing packs: Concise visualizations and talking points for communicating strategy, risk and return trade-offs to stakeholders.
Use-case driven decision pathways
The report is organized around concrete decision paths that executives face in 2026—examples below illustrate the type of guidance included:
-
Lender expanding into dealer-originated indirect lending: Sequence investments—1) pilot with selected dealer cohorts, 2) calibrate underwriting using early-performance data, 3) scale warehousing capacity conditional on vintage performance thresholds.
-
Captive seeking higher retention: Conduct margin-at-risk analyses to determine whether to shift mix toward leases or 48–60 month retail contracts; implement loyalty incentives at point-of-sale and optimize remarketing channels.
-
Bank assessing partnership with fintech decisioning vendor: Run a parallel production test to quantify approval lift, margin impact and chargeback behavior; incorporate fallback procedures to preserve dealer confidence.
-
Investor or buyer evaluating M&A targets: Use our proprietary KPI lexicon and valuation sensitivity tables to price target portfolios accounting for regulatory-change risk and anticipated origination cadence.
Regulatory and risk considerations you cannot ignore in 2026
Recent policy signals — from proposals narrowing the scope of disparate impact claims to adjustments in the definition of larger nonbank auto-finance participants — alter the compliance landscape materially. Combined with affordability headwinds that may reduce originations in the near term, these dynamics require lenders to adopt a more proactive compliance posture and to embed regulatory scenario planning into capital and product decisions.
How PW Consulting’s report supports immediate action
This preview is intentionally high-level to demonstrate the report’s strategic and operational depth without divulging proprietary segment-level metrics. Subscribers to the full report will receive:
-
Granular segment and regional dashboards (downloadable data tables and interactive charts).
-
Company-level benchmarking and discrete capability scoring for the industry’s major participants.
-
Full model access so teams can run bespoke scenarios aligned to their balance-sheet, regulatory posture and strategic targets.
Next steps
For boards and executive teams building 2026 strategies, PW Consulting’s Indirect Auto Finance Market report delivers the synthesis of market sizing, competitive assessment, regulatory foresight and operational playbooks necessary to act with confidence. To examine the segment-level data, competitor scorecards and to license our scenario model for internal use, access the report package and client portal for downloads and model access.
PW Consulting — our senior industry analysts remain available for briefings, tailored deep dives and implementation coaching to convert the report’s insights into measurable business outcomes for 2026.
For detailed analysis of this topic, please visit the official page: Indirect Auto Finance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 5.85% CAGR for Global Automotive Sound Insulation (NVH) Market in 2026–2032
By PW Consulting, 2026-07-15
Automotive Sound Insulation NVH Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting today publishes an in-depth industry briefing accompanying our flagship Automotive Sound Insulation NVH Market report (base year 2025, forecast 2026–2032). Built for boardrooms, product strategy teams, and supply-chain planners, this analysis translates the market’s macro trajectory into decision-ready insight for 2026. Our modelling shows the market expanding to approximately USD 14,190 Million in 2025, and continuing to grow at a compound annual growth rate (CAGR) of roughly 5.85% over the forecast period — with PW Consulting projecting the market to approach the low‑to‑mid USD 20 billions by the end of the 2032 horizon. These headline numbers frame the opportunity; the real value for executives lies in the operational levers and risk scenarios we translate from them.
Automotive Sound Insulation NVH Market
Why this report matters for 2026 planning cycles
- Investment prioritization: With moderate, sustained growth, capital allocation must balance near-term compliance-driven spend against longer‑term product differentiation. Our analysis isolates which material and component bets maximize ROI under three realistic demand scenarios.
- Product roadmap alignment: Electrification, lightweighting, and sustainability are reshaping acoustic requirements. The report maps NVH performance targets to material platforms so OEMs and Tier‑1s can prioritize R&D and qualification timelines for 2026 model launches.
- Supply‑chain resilience: We identify single‑source exposures, lead-time sensitivities, and concentration risks that become critical when regulatory deadlines and program launches converge mid‑decade.
- Compliance and certification planning: New noise regulations coming into force in 2026 change test protocols and compliance windows. The report converts legal timelines into executable test, validation, and supplier‑qualification schedules.
- M&A and partnership playbook: For corporate development teams, we provide a prioritized target screen and integration checklist focused on technology fill, geographic coverage, and cost synergies.
Data-driven insights shaping the 2026 agenda
Three structural forces underpin the market’s trajectory and should guide 2026 decisions:
Automotive Sound Insulation NVH Market
- Regulatory pressure compresses time-to‑spec: Tightening noise standards in key jurisdictions, including EU noise regulations phased through 2026 and updated UNECE weighting and testing (UN R51.03 Phase 3 effective mid‑2026), transform NVH requirements from a design preference into a compliance imperative. Our timeline modeling quantifies windows for design validation, pre‑production testing, and safety stock build to avoid production interruptions.
- Electrification redefines NVH engineering: While EV powertrains emit less broadband mechanical noise, they expose higher‑frequency, tonal, and cabin‑borne phenomena and make perceived sound quality more sensitive. That shift reallocates value from bulk mass‑based solutions toward tuned damping, engineered absorbers, and active/passive hybrid systems. The report layers noise source maps against typical vehicle architectures to identify where marginal NVH spend delivers the largest perceptual uplift.
- Sustainability and lightweighting converge with acoustic performance: Demand for recycled content, mono‑material recyclability, and lower gram weights is driving material innovation. Case studies in our report show how next‑generation fiber mats, engineered foams, and polymer composites close performance gaps while delivering weight and end‑of‑life improvements — but not without new cost and process constraints that buyers must manage.
Competitive landscape — where incumbents are placing their chips
The NVH value chain remains characterised by established global suppliers that combine materials science, system integration know‑how, and OEM program access. PW Consulting’s competitor profiles and strategic assessments emphasize capability gaps and adjacency plays:
Automotive Sound Insulation NVH Market
- Autoneum: Positioned as a leader in lightweight fiber‑based systems and sustainable carpets, Autoneum’s recent participation in major acoustics conferences and product showcases highlights a strategy focused on mono‑material concepts and high recycled‑content solutions — a play that targets both OEM sustainability mandates and interior acoustic optimization.
- BASF: A materials innovator in microcellular polyurethane elastomers and engineered foams, BASF’s offerings are strategically relevant for chassis-mounted NVH elements and modular acoustic blocks where durability and temperature resilience matter.
- 3M: With branded solutions such as Thinsulate and engineered damping layers, 3M remains a faster‑moving commercial partner for rapid prototyping and niche cabin acoustic applications where thin, manufacturable layers are needed.
- Dow: The company’s portfolio of olefin elastomers and system solutions supports cavity filling and tailored damping use cases; Dow’s strength lies in polymer systems that can be tuned for manufacturing constraints and cost targets.
- Vibracoustic: Focused on mounts, bushings, and suspension‑adjacent NVH, Vibracoustic has recently demonstrated how targeted mechanical isolation systems improve ride comfort for premium EV platforms, underscoring the shift toward tailored powertrain/vehicle‑level solutions.
- Sumitomo Riko, Henkel, ElringKlinger: These suppliers round out the ecosystem with rubber‑based insulators, adhesive damping systems, and sealing/structural components that collectively determine system‑level acoustic outcomes.
Recent market moves — public showcases, OEM program wins, and product launches — validate two tactical themes we highlight for 2026: suppliers are accelerating EV‑specific productization, and sustainability messaging is moving from R&D into validated, show‑ready systems. PW Consulting’s report contains company‑level scorecards and a strategic options matrix that translate these observations into partnership or competitive response strategies for OEMs and Tier‑1s.
What’s inside the PW Consulting report — practical deliverables
- Executive synthesis: A concise decision memo for C‑suite and business‑unit heads, orienting capital, procurement, and product agendas against regulatory and market timing.
- Market sizing and scenario forecasts: Base‑case and upside/downside scenarios (2026–2032) with sensitivity to EV penetration, regulatory tightening, and material substitution.
- Technology & materials map: Comparative performance matrices for foam, fiber, polymer, and hybrid systems; manufacturability and recycling constraints; and per‑vehicle cost delta modelling.
- Regulatory impact models: Compliance timelines and test‑protocol implications translated into validation calendars and inventory buffers.
- Supplier benchmarking: Capability heatmaps, margin corridor estimates, and readiness assessments for EV program participation.
- Commercial playbooks: Go‑to‑market templates, OEM negotiation levers, and procurement scoring tools to shorten qualification cycles.
- M&A and partnership screen: A prioritized list of targets and JV candidates with an integration checklist and estimated synergies.
- Risk register and mitigation plans: Practical contingency actions for raw‑material price shocks, regulatory delays, and single‑source failures.
How executives should use the report in 2026
- Procurement leadership: Use the supplier heatmaps and cost‑per‑vehicle models to renegotiate supply contracts with outcome‑linked KPIs that reflect acoustic performance and recyclability.
- Product and systems engineering: Map NVH targets to material selections using our materials performance tables to de‑risk prototype‑to‑production transfer within 2026 program timelines.
- Corporate development: Leverage our M&A screen to identify tuck‑ins that close capability gaps in EV‑specific NVH or that accelerate access to sustainable material platforms.
- Regulatory & compliance teams: Translate the regulatory calendars into procurement and validation milestones to ensure program sign‑offs before enforcement windows arrive.
Where the trailer stops — and what you’ll find in the full report
This briefing is intentionally strategic and directional. In keeping with our “trailer” principle, we present the macro market sizing, growth trajectory, and qualitative competitive dynamics to guide executive attention. To preserve the consultative value of PW Consulting’s primary research, granular breakdowns — including detailed regional and application splits, per‑company market share tables, and downloadable forecast models — are available exclusively in the full report and its accompanying data pack. Clients and subscribers can access the complete datasets, scenario workbooks, and supplier scorecards on the report landing page.
Final recommendation — a 90‑day action plan for 2026
- Day 0–30: Convene a cross‑functional NVH task force (procurement, engineering, regulatory, BD) and run PW Consulting’s quick‑sprint maturity assessment to identify critical gaps.
- Day 30–60: Prioritise 1–2 high‑impact material or supplier experiments (guided by our materials map) and secure qualification slots for 2026 model timelines.
- Day 60–90: Finalize commercial terms with preferred suppliers that incorporate performance KPIs and sustainability milestones; activate contingency sourcing where single‑source exposure exists.
PW Consulting’s Automotive Sound Insulation NVH Market report converts market momentum into executable decisions. For organizations preparing program‑level roadmaps, capital allocation requests, or M&A diligence through 2026, the report is designed to reduce uncertainty and compress time to action. Visit our report page to request the full study, download the data pack, or schedule a briefing with PW Consulting’s NVH practice.
For detailed analysis of this topic, please visit the official page: Automotive Sound Insulation NVH Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


