



Category: Machinery & Automotive
PW Consulting Forecasts 5.65% CAGR for Global Automatic Paint Booth Market Through 2032
By PW Consulting, 2026-07-15
PW Consulting Releases Strategic Market Brief: Automatic Paint Booth Market Set to Cross $1.25B by 2032 — A 2026 Playbook for Executives
PW Consulting today published a targeted strategic brief drawn from our full Automatic Paint Booth Market research, offering senior executives a pragmatic roadmap for capital allocation, supplier negotiation, and technology adoption as they plan for 2026. Our high‑fidelity market model shows the global automatic paint booth market expanding from an estimated USD 855.0 million in 2025 to roughly USD 1.254 billion by 2032, driven by a 5.65% compound annual growth rate across the 2026–2032 forecast window. After five years of steady recovery and reinvestment (our historical series runs 2020–2025), 2026 is shaping up as an inflection year for strategic investments.
Automatic Paint Booth Market
Why this brief matters for 2026 decisions
-
Timing and scale: The implied uplift between the 2025 base and early forecasts for 2026 indicates near‑term demand momentum that materially affects 2026 CAPEX schedules, vendor lead times, and spare‑parts provisioning. Boards and CFOs must convert that signal into actionable procurement timelines rather than defer projects to an uncertain later window.
Automatic Paint Booth Market -
Technology and regulatory alignment: Transition dynamics — notably the broad shift to waterborne coatings and tightening filtration/ventilation requirements — force an integrated view across engineering, EH&S, and operations. Booth specification is no longer a mechanical decision alone; it is a cross‑functional program with quantifiable ROI and compliance risk.
Automatic Paint Booth Market -
Market structure implications: The sector shows moderate concentration: the top three suppliers collectively control a meaningful but not dominant share, and the top five approach half the market, leaving tangible room for fast‑moving challengers and consolidation plays. This competitive balance alters negotiation leverage, partnership potential, and M&A timing for strategic acquirers.
What’s in the PW Consulting brief — operational, decision‑grade content
-
Market model & scenario suite — transparent base case plus upside/downside scenarios calibrated to macro construction/automotive cycles, materials inflation, and regulatory tightening. The model is delivered with an editable spreadsheet to stress‑test assumptions for your business.
-
CAPEX/OPEX playbooks — detailed templates to build total cost of ownership (TCO) analyses, covering capital layout, energy use profiles, filtration lifecycle, and labor impacts for installation and certification.
-
Vendor evaluation matrix — a standardized scorecard to compare suppliers across performance, service footprint, warranty structure, compliance support, and automation readiness (methodology disclosed; proprietary scores reserved for the full report).
-
Regulatory compliance checklist — practical steps to align installations with OSHA 29 CFR 1910.107 and EPA NESHAP requirements, including filter capture efficiency expectations, testing cadence, and documentation best practices.
-
Implementation playbooks and case studies — real‑world installation examples showing pathways to reduce cycle times, improve finish quality, and cut energy use; includes before/after KPI templates to quantify gains.
-
Procurement & contracting templates — RFQ language, warranty & spare‑parts clauses, and pricing indexation approaches to mitigate steel and filtration‑media volatility.
-
Technology roadmaps — clear guidance on where automation and robotics deliver the highest marginal returns, and when to prioritize energy recovery, heat management, and humidity control for waterborne processes.
Competitive landscape — strategic profiles and what they mean for buyers
The brief synthesizes supplier positioning across the global vendor set, concentrating on engineering capability, service networks, automation competence, and regulatory support. A snapshot of market players illustrates the strategic archetypes buyers will encounter:
-
Specialist code‑compliant manufacturers: Certain North American providers focus on safety and code compliance for automotive and heavy‑duty repair markets. These vendors win when strict local code adherence and quick aftermarket support are decisive procurement criteria.
-
High‑throughput systems suppliers: Long‑standing firms with experience in high‑production automotive and commercial finishing emphasize integrated prep/finish solutions that reduce cycle time and improve throughput metrics.
-
Automated and robotics integrators: Global engineering leaders offer end‑to‑end paint shop automation, including multi‑stage booths and robotic application systems. Their value proposition centers on repeatable quality and deep process engineering, often at the higher end of the CAPEX curve.
-
Energy‑efficient and modular innovators: Some manufacturers have differentiated on energy performance, modularity, and local serviceability — appealing for retrofit projects and sustainability targets.
Recent corporate moves underscore these strategic positions. In 2025 and early 2026, several vendors took actions that matter to procurement and M&A watchers: executive appointments following acquisition activity; documented case studies demonstrating energy and quality improvements from recent installations; planned exhibition and demonstration events showcasing next‑generation shop designs; and open‑house events that reveal the direction of large OEM‑scale automation. Each of these signals affects partner selection, benchmarking, and contractual warranty negotiations.
Regulatory, materials, and process dynamics that will shape 2026
-
Regulatory guardrails: OSHA standards for spray finishing and EPA NESHAP mandates create a compliance floor that influences design choices, filter selection, and ongoing test/verification costs. Capture efficiencies, ventilation standards, and documentation obligations must be accounted for in financial models.
-
Raw‑material volatility: Steel and filtration media price swings directly impact manufacturing margins and delivery costs. Buyers should consider indexed pricing mechanisms and longer lead‑time contracts for critical components.
-
Process migration: The sectorwide shift to waterborne coatings carries operational implications — precise temperature and humidity control become critical to maintain finish quality and reduce rework. Booths specified for solventborne operations can incur retrofit costs if not designed to support waterborne environments from the outset.
-
Sustainability and energy: HVAC and heat recovery choices materially affect lifecycle operating expense. Energy efficiency is now a procurement criterion as much as first‑cost; payback analyses must be embedded in 2026 approval processes.
Practical guidance for executives preparing 2026 programs
-
Run three scenarios in your board papers: conservative, base, and accelerated — explicitly stress‑testing filter costs, steel inflation, and a faster transition to waterborne coatings.
-
Prioritize modularity in new specifications. Modular booths reduce installation complexity and hedge against future process shifts (e.g., automation add‑on, humidity control upgrades).
-
Make service footprint a decisive procurement filter. Warranty language and local service availability materially affect downtime risk and TCO.
-
Lock in price indexation for long‑lead components where possible and build spare‑parts kits into initial orders to shorten repair lead times.
-
Commission a pilot for waterborne processes in 2026 to validate HVAC/humidity designs and quantify yield improvements before wide deployment.
-
Include compliance checkpoints tied to payment milestones to ensure installations meet OSHA and EPA expectations prior to final acceptance.
Why PW Consulting’s brief is a must‑read now
Our brief pairs a forward‑looking market model (with editable scenarios) with hands‑on implementation tools and competitive benchmarking. It is engineered to convert the market’s macro signals — a mid‑single‑digit CAGR and a market trajectory toward roughly USD 1.25 billion by 2032 — into specific 2026 actions: rephasing CAPEX, sharpening supplier selection, and embedding regulatory validation into procurement. We deliberately present firm intelligence on vendor strategies and market concentration, while withholding the granular subsegment shares and proprietary scoring that are bundled in the full report. That disciplined “preview” approach is designed to demonstrate methodological rigor and practical value while prompting direct engagement for the full dataset and interactive models.
To access the full report, the editable market model, and the vendor scorecards that operational teams can use immediately, please visit PW Consulting’s report page and download the full package. Our team is also available for bespoke briefings and scenario workshops tailored to procurement, operations, and M&A stakeholders who need to convert the 2026 market outlook into executable plans.
For detailed analysis of this topic, please visit the official page: Automatic Paint Booth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: L6 & L7 Quadricycles Market Hits USD 2,350 Million in 2025, Poised for Robust Expansion
By PW Consulting, 2026-07-15
L7 and L6 Quadricycles Market: Strategic Implications for 2026 — PW Consulting Executive Brief
As city planners, fleet operators, OEMs and investors set their strategic agendas for 2026, the L6 and L7 quadricycle segment presents a concentrated set of opportunities and execution challenges. Our new L7 and L6 Quadricycles Market report — the most comprehensive study published by PW Consulting to date — synthesizes macro trends, regulatory inflection points and competitor manoeuvres into an actionable playbook for decision-makers. The headline numbers are straightforward: the global market is measured in the low thousands of USD millions today and is forecast to expand at a compound annual growth rate of approximately 7.45% through the 2026–2032 horizon, crossing a material five-figure revenue milestone by the end of the decade. But the strategic story behind those figures is where 2026 decisions will be won or lost.
L7 and L6 Quadricycles Market
Why this market matters for 2026
-
Micro-mobility is maturing from a niche urban experiment into a portfolio component of transport and logistics strategies. L6/L7 quadricycles sit at the intersection of consumer micro-mobility, municipal fleet electrification and light commercial last-mile deliveries — giving OEMs and suppliers multiple addressable routes to growth.
L7 and L6 Quadricycles Market -
Regulatory clarity in core geographies (notably European harmonization of technical requirements and licensing regimes) has reduced a structural barrier to scale. That creates a time-sensitive window for companies that can rapidly align product compliance, distribution and service networks.
L7 and L6 Quadricycles Market -
Technology and supply chain shifts — particularly in battery cell chemistry, pack integration and electric powertrain modularity — are lowering unit costs and enabling differentiated value propositions (range, payload and total cost of ownership) that determine commercial fleet adoption.
What PW Consulting’s report delivers — practical intelligence, not theory
This release is designed as a decision-grade intelligence product for commercial leaders and investors. The report combines:
- Proprietary market-sizing and scenario modelling (base year 2025; forecast period 2026–2032) that quantifies baseline growth and stress-tested downside/upside pathways based on regulatory, macroeconomic and technology variables.
- A road-tested go-to-market framework for three distinct customer archetypes: urban consumer, municipal/commercial fleet and shared mobility operators. Each framework maps product spec trade-offs, channel strategy and service economics.
- Detailed supply-chain and supplier-benchmark maps focused on battery cells, BMS, electric drivetrains and lightweight chassis, with practical supplier shortlists and integration checklists.
- Deal playbooks for municipal procurement and large fleet contracts, including templated RFP elements, warranty structures and residual value clauses optimized for quadricycle characteristics.
- Competitive benchmarking and capability heatmaps for OEMs, tier suppliers and new entrants, covering manufacturing footprint, product portfolio breadth, electrification readiness and commercial channels.
- Regulatory risk matrix and compliance roadmap aligned to prevailing EU technical standards and licensing regimes — enabling legal/affairs teams to prioritize certification pathways in 2026.
- Financial modelling tools and pricing guidance calibrated to the segment’s cost curves and expected depreciation dynamics through 2032.
Market dynamics and critical inflection points
-
Electrification momentum: New-vehicle registrations have shown outsized electrified share in recent periods; OEMs that secure reliable battery supply and optimize pack integration will convert this tailwind into durable market share gains.
-
Use-case bifurcation: L6 products (lower-speed, license-light variants) continue to attract younger and urban-first consumers and shared fleets, while heavier L7 models are increasingly positioned for commercial and municipal roles where payload and higher top speed are decisive.
-
Procurement-led scaling: Large municipal and corporate fleet contracts are already shaping product roadmaps — winning such contracts requires capabilities in local service networks, telematics and total cost-of-ownership guarantees.
-
Consolidation and OEM entry: Strategic deals and acquisitions have accelerated in 2024–2025, reflecting incumbent OEM interest in micro-mobility and an acquisitive posture among established manufacturers seeking scale and technology access.
Competitive landscape — what the major players reveal about strategy
The competitive field combines legacy light-vehicle specialists, dedicated EV startups and mainstream OEMs adapting their small-vehicle platforms. Each archetype brings differentiated strengths and strategic implications for 2026:
-
Traditional European specialists (e.g., Ligier Group, Aixam/Polaris, Goupil Industrie, Automobiles Chatenet, Casalini) : These firms have entrenched distribution networks, product portfolios tailored to local licensing regimes and proven municipal-fleet references. Their playbook is incremental electrification, portfolio diversification and leveraging service networks to defend margins. Recent strategic partnerships and product refreshes show a dual focus on advanced propulsion and renewed design competitiveness.
-
Italian EV specialists (e.g., Tazzari EV) : Niche players offer lightweight, highly differentiated EV models with a premium urban-commute and lifestyle positioning. They can command higher margins but must scale dealer and aftersales ecosystems to support fleet adoption.
-
Mainstream OEMs and groups (e.g., Stellantis brands, Renault’s Mobilize, Piaggio) : These entrants bring economies of scale, access to broader dealer networks and integrated manufacturing capabilities. Their involvement accelerates category legitimacy for consumers and fleet buyers but also raises competitive intensity on pricing and feature content.
Several recent corporate moves underscore these dynamics: strategic partnerships to co-develop EV platforms and battery systems, municipal supply contracts that validate product fit for fleet duty, and targeted acquisitions aimed at consolidating European operations or accelerating electrification roadmaps. For 2026, the decisive advantage will accrue to firms that convert platform-level investments into demonstrable reductions in total cost of ownership and uptime for fleet customers.
Strategic imperatives for 2026 decision-makers
-
Prioritize fleet-ready productization: If your 2026 growth ambition includes municipal or last-mile commercial customers, treat telematics, modular battery swaps (or rapid charging integration) and service uptime guarantees as product features — not afterthoughts.
-
Secure battery supply and margin protection: Given the centrality of battery systems to unit economics and range, vertical or contractual hedges with cell suppliers should be part of near-term procurement strategies.
-
Design regulatory-first architectures: Harmonizing vehicle architecture to the technical limits and certification pathways of target markets will reduce time-to-market friction and avoid costly reworks.
-
Deploy differentiated go-to-market models: A blended strategy — direct sales to fleet customers, partnerships for municipal procurement, and selective dealer networks for retail consumers — will allow companies to capture multiple demand pools without overinvesting in single channels.
-
Focus M&A on capability gaps, not scale alone: Acquisitions that close technical or service-network gaps (battery integration, telematics, local assembly) will be higher-yielding than broad-scale consolidation aimed solely at revenue growth.
-
Measure success with TCO and uptime KPIs: For 2026 contracts, propose performance-linked pricing models where feasible — customers respond well to transparent TCO calculations backed by telematics-derived uptime guarantees.
Key risks and mitigation strategies
-
Regulatory divergence across non-EU geographies can undermine export strategies. Mitigation: invest in modular certification efforts and local compliance expertise.
-
Price competition from deep-pocketed OEMs risks margin compression. Mitigation: differentiate through service offerings, warranty structures and customer financing solutions.
-
Supply chain concentration for critical components (cells, semiconductors) creates operational risk. Mitigation: diversify supplier base and establish strategic inventory buffers tied to key production ramp milestones.
-
Perception and safety concerns could slow consumer adoption in some segments. Mitigation: invest in visibility campaigns demonstrating crashworthiness, real-world fleet uptime and total-cost savings.
How PW Consulting’s analysis accelerates 2026 action
Our report is structured to move teams from strategy to execution in months, not quarters. It pairs a rigorous macro forecast and scenario set with hands-on toolkits — procurement templates, RFP language, dealer-economics models and an operations readiness checklist customized for quadricycle characteristics. Executives who read the full report will be able to: prioritize product development investments, evaluate M&A targets with sector-specific scorecards, build credible bids for municipal tenders and design go-to-market pilots that de-risk national rollouts.
Next steps and how to access the full intelligence
This article provides an executive synthesis of the strategic landscape and recommended actions for companies planning 2026 investments. The full PW Consulting L7 and L6 Quadricycles Market report contains the complete dataset, granular scenario outputs, company scorecards and proprietary dealer/supplier shortlists that support rapid implementation. To review the detailed charts, segmentation analysis and tailored playbooks, please visit our official report page or contact PW Consulting’s automotive practice for a briefing and licensing options.
In a market expanding at a mid-single-digit to high-single-digit pace with clear pathways to scale for disciplined actors, the choices made in 2026 — about platforms, partnerships and procurement — will determine which companies lead the next chapter of urban and light commercial mobility.
For detailed analysis of this topic, please visit the official page: L7 and L6 Quadricycles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Aircraft Composite Enclosures Market to Rise from USD 166.7M in 2025 to USD 269.78M by 2032 at a 7.12% CAGR
By PW Consulting, 2026-07-13
Aircraft Composite Enclosures Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s latest market study on Aircraft Composite Enclosures delivers a decision‑grade intelligence package tailored for executives, procurement leaders, and product strategists charting moves in 2026. The sector has evolved from a niche enabler of lightweight housings into a strategic lever across avionics, embedded systems, and cabin electronics. This briefing summarizes the macro dynamics, competitive positioning and five pragmatic imperatives our full report provides — deliberately high‑resolution on strategy, while reserving the granular segment tables and company scorecards for report subscribers.
Aircraft Composite Enclosures Market
Market snapshot: growth, scale and trajectory
Composite enclosures for aircraft have posted robust expansion over the last half‑decade, with the market climbing from just under USD 100 million in 2020 to roughly USD 166.7 million in 2025. Our forecast baseline (2026–2032) projects continued expansion, growing to an addressable market in the high‑hundreds of millions by the late forecast years at a compound annual growth rate of 7.12%. The 2026 projection represents the first year of the forecast horizon and is an important inflection point for procurement and product investment plans.
Aircraft Composite Enclosures Market
Drivers sustaining this momentum include accelerating avionics electrification, broader adoption of carbon‑rich structural composites for enclosure applications (for weight and EMI advantages), and defense procurement cycles that favor composite solutions for shock and corrosion resistance. Simultaneously, raw material dynamics are creating both risk and tactical opportunity: epoxy resin prices in North America rose materially in early 2026 (to just over USD 4.00/kg in March), and aerospace‑grade carbon fiber pricing continues to span a wide range depending on grade and supply terms. These upstream pressures are already reshaping supplier negotiations and total cost models.
Aircraft Composite Enclosures Market
What PW Consulting’s report delivers — practical, executable intelligence
- Market sizing and forward scenarios: rigorous top‑down and bottoms‑up models for 2020–2032, with probabilistic scenarios that stress raw material volatility, certification timelines and defense procurement cadence.
- Commercial playbooks: procurement templates, supplier scorecards, and negotiation levers designed for securing long‑term carbon fiber and resin contracts while protecting margin.
- Design & certification roadmap: a step‑by‑step guide aligning composite enclosure design choices to FAA advisory guidance and test allowables, reducing certification rework and time‑to‑entry.
- Technology & product strategy: a comparative evaluation of enclosure materials (carbon, glass, hybrid), EMI shielding options, and modularity approaches, paired with R&D investment priorities and cost‑benefit templates.
- Competitive and M&A intelligence: profiles and strategic assessments of active incumbents and scale‑up targets, plus a prioritized list of acquisition targets and partnership archetypes based on our concentration and capability mapping.
- Supply‑chain resilience diagnostics: risk heatmaps, inventory policy recommendations, and contracting strategies that account for observed upstream consolidations and recent long‑term supply agreements.
Competitive landscape: capabilities, gaps and strategic postures
The aircraft composite enclosures market is characterized by a mix of large systems integrators, specialized composites houses, and vertically integrated aerospace suppliers. The top tier of competitors holds a material share of the market, creating an environment where partnerships and selective consolidation can accelerate capability access and scale.
- TE Connectivity — Positioned as a solutions partner for lightweight avionics packaging, TE’s strength is in integrating EMI shielding and interconnect functionality into composite housings. For OEMs prioritizing systems integration and rapid qualification, TE offers a lower‑execution‑risk path to fielding composite‑based enclosures.
- Collins Aerospace — As a Tier‑1 integrator with broad platform reach, Collins combines composite structural know‑how with systems engineering for both commercial and military platforms. Their advantage lies in end‑to‑end program delivery and defense program relationships.
- Carlisle Interconnect Technologies (Amphenol CIT) — Specializes in interconnects and high‑voltage enclosures, which positions them favorably for electrified aircraft systems that demand combined mechanical and electrical performance assurances.
- GE Aerospace — Not traditionally viewed first for aircraft enclosures, GE’s crossover wins (notably a 2026 order to supply composite enclosures for marine gas turbines on naval platforms) underscore how cross‑domain engineering can open adjacent aerospace opportunities, particularly in shock‑ and noise‑sensitive applications.
- Automated Dynamics (Trelleborg) — Focuses on custom enclosures for sensitive electronics where EMI shielding and structural integrity are critical. Their custom engineering model is attractive for defense prime contractors and bespoke commercial platforms.
- RAMPF Group, AIM Aerospace, and Kaman (Vermont Composites) — Represent a cluster of specialized composite fabricators providing tailored carbon and EMI‑shielded enclosure solutions; they are often chosen for niche technical requirements or where OEMs prefer diversified supply bases.
Recent industry actions reinforce these strategic directions: a high‑visibility supply contract awarded to a major engine/aerospace player in 2026 demonstrates cross‑sector demand for composite enclosures, while upstream partnerships between carbon fiber producers and downstream integrators are starting to stabilize supply and moderate price volatility for key users.
Five strategic imperatives for 2026
- Lock in raw‑material continuity now. Volatility in epoxy and carbon fiber markets has direct margin implications. Our playbooks recommend layered contracting (short‑term spot plus capped long‑term supply), strategic stock positioning and qualification of dual suppliers for critical grades.
- Embed certification and producibility early. Designing to FAA composite guidance and qualification allowables up front reduces iteration. Invest in common test matrices and supplier co‑development agreements to compress certification timelines and avoid late design changes.
- Adopt hybrid design philosophies. A modular approach — pairing carbon with selective glass or metal reinforcements where cost or repairability matters — balances performance with lifecycle serviceability and reduces exposure to the highest‑cost raw materials.
- Prioritize partnerships over capex where speed matters. For OEMs seeking rapid platform integrations, strategic alliances with Tier‑1s that bring EMI, interconnect and systems qualification capabilities deliver faster certification and lower program risk than building new in‑house capacity.
- Use scenario‑based procurement and pricing models. Our financial templates show how to stress‑test total cost of ownership under +/- 20% raw material moves. Procurement KPIs should shift from pure price per kg to price per certified unit delivered across lifecycle cost metrics.
Where returns are realized — use cases and ROI framing
Composite enclosures are not a cost line in isolation; they are an enabler of platform‑level performance improvements. Weight reductions translate to fuel and operational savings, EMI improvements lower field failure rates, and integrated enclosure/interconnect designs reduce installation labor and maintenance turnbacks. For defense primes and niche business‑jet integrators, the ROI window can be shortened further when composite enclosures enable multi‑platform commonality and simplified spares chains.
Practical ROI examples and sensitivity analyses are included in the full report, demonstrating payback timelines across common retrofit, line‑fit and new‑platform scenarios under differing fuel price and utilization assumptions.
What this means for 2026 decisions
If your 2026 roadmap includes product launches, supplier rationalization, or M&A, treat composite enclosures as a strategic system rather than a commodity box. Decisions on supplier selection, material sourcing and certification strategy will determine whether you capture the full systems‑level benefits or merely shift costs downstream. Our research shows that firms aligning procurement, design and certification deliver measurable program risk reduction and competitive time‑to‑market advantages.
Next steps — how PW Consulting helps
PW Consulting’s Aircraft Composite Enclosures Market report is purpose‑built to arm decision‑makers with the actionable analysis, templates, and vendor assessments needed to execute in 2026. The public summary above intentionally omits the granular regional, type and application splits and the vendor scorecards that our clients rely on for negotiations and deal diligence. Subscribers receive those datasets, customizable financial models, and a one‑day executive workshop to translate findings into a 90‑day action plan.
For executives preparing vendor RFPs, planning certification timelines, or assessing acquisition targets, the full report provides the high‑definition inputs required to make defensible, high‑impact choices in 2026. Contact PW Consulting to obtain access to the complete dataset, supplier scorecards and our scenario modelling tools.
For detailed analysis of this topic, please visit the official page: Aircraft Composite Enclosures Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Commercial Aircraft In-Seat Power Systems Market Poised to Reach USD 229.62 Million by 2032, Growing at a 4.85% CAGR
By PW Consulting, 2026-07-13
Commercial Aircraft In-Seat Power System Market — Strategic Outlook and Imperatives for 2026
PW Consulting’s latest market research on Commercial Aircraft In-Seat Power Systems delivers a forward-looking, executable playbook for airlines, OEMs, cabin systems suppliers, and investors preparing strategic decisions in 2026. Grounded in a comprehensive historical review (2020–2025) and a granular forecast through 2032, the study synthesizes market trajectory, regulatory drivers, supply-chain dynamics, and vendor capability mapping to convert market intelligence into boardroom-ready action.
Commercial Aircraft In Seat Power System Market
Market trajectory: recovery, near-term growth, and the mid‑term runway
The in‑seat power systems market has transitioned from pandemic-era contraction to steady expansion. Our base-year analysis (2025) captures market value after a multi‑year recovery, and the forecast period (2026–2032) models continued demand growth under multiple demand and regulatory scenarios. At the start of the forecast horizon, the market is projected to grow further year-on-year, with a compound annual growth rate of 4.85% across the 2026–2032 window, producing meaningful expansion by 2032. These macro metrics underpin the report’s scenario models that translate topline growth into linefit, retrofit, and serviceable‑unit demand for different fleet strategies.
Commercial Aircraft In Seat Power System Market
Why 2026 is a pivotal year for strategic decisions
-
Regulatory convergence and standards adoption: 2026 is shaping up as the year when universal USB‑C and high‑power delivery standards materially influence specification and certification timelines. Suppliers that secure early compliance and certification pathways will command tactical advantage in OEM linefit programs and large retrofit tenders.
Commercial Aircraft In Seat Power System Market -
Product differentiation becomes product survival: As seat‑level power moves from a premium feature to baseline passenger expectation, vendors must shift from “feature lists” to systems thinking — power architecture, thermal footprint, certification cost, and maintainability will determine win rates.
-
Supply‑chain inflection points: Material constraints and higher component costs force design tradeoffs (higher‑voltage distribution, conductor optimization). Procurement and engineering teams making sourcing and design choices in 2026 will lock in costs and obsolescence risk over multi‑year fleet programs.
Key dynamics shaping supplier and buyer decisions
-
Standards and regulation: A sustained regulatory push toward universal USB‑C standards and certification pathways is simplifying passenger experience but raising the engineering bar for thermal management and safety approvals for high‑power delivery (60–100W device support).
-
BYOD normalization: Bring‑Your‑Own‑Device behavior drives seat‑level power from optional add‑on to baseline infrastructure. This changes purchase economics—airlines must budget for broader deployments and lifecycle support rather than isolated premium rows.
-
Material and architecture innovation: Copper supply constraints are accelerating the transition to higher‑voltage distribution architectures that use less conductive material while maintaining power throughput. The net effect: re‑engineering investments now yield recurring weight, space, and installation efficiencies.
-
Form factor and efficiency mandates: Fuel‑efficiency and cabin‑weight requirements favor slimline converters and compact modules; designs that reduce cavity space and optimize mass per seat will benefit certification and installation cadences for both narrowbody and widebody fleets.
-
Retrofit economics vs. linefit planning: The report quantifies how retrofit windows, cabin downtime, and installation labor rates interact with device power density and modularity to shape ROI for retrofit campaigns. For many operators, staged retrofit programs aligned with scheduled maintenance deliver superior NPV vs. opportunistic installations.
Competitive landscape — who’s moving the market and why it matters
The vendor landscape combines large systems integrators with specialist module manufacturers. Established cabin and avionics suppliers retain strength through OEM relationships, systems integration capabilities, and global support footprints. At the same time, niche innovators are leveraging modular hardware and software interfaces to win retrofit and specialty contracts.
-
Astronics Corporation — A leading supplier with broad linefit and retrofit pedigree. Recent product introductions reinforce its strategy of offering high‑power USB‑C outlets and validated drop‑in modules for fleet commonality. Procurement teams should watch Astronics for mature integration packages and accelerated certification timelines.
-
Collins Aerospace — Provides tightly integrated cabin power and data‑port solutions, emphasizing IFE-seat integration. Collins’ advantage is systems depth and OEM relationships, useful for operators seeking one‑stop platforms that reduce supplier count and integration risk.
-
Panasonic Avionics — Coupling IFE capability with high‑power USB‑C delivery creates a bundled value proposition for widebody and premium narrowbody installations. Recent service entry of systems offering up to high‑watt charging underscores the premium integration route.
-
Burrana — Positioning its RISE platform as a modern cabin backbone reflects a strategy to compete on modularity and lifecycle services. Airlines favoring quick, lower‑disruption retrofits should evaluate Burrana’s positioning against incumbent integrators.
-
IFPL — A specialist with deep in‑seat module volume experience; its heritage in compact outlets and interface solutions makes it a logical partner for volume retrofit programs and custom passenger‑interface solutions.
-
Mid‑Continent / True Blue Power — Focused on TSO‑certified USB power systems and chargers, True Blue targets safety‑conscious buyers and niche cockpit/cabin power applications where certification pedigree is decisive.
-
KID‑Systeme and Astrodyne TDI — Represent specialized engineering capability in cabin electronics and power conversion modules, respectively. Their strengths are in customized solutions where standard packages do not fit operational constraints.
Recent vendor activity (product launches, trade show positioning, and first‑in‑service deployments) confirms an acceleration of commercial dynamics: new dual USB‑C outlets entering the market, platform positioning at major aircraft interiors shows, and first services of high‑watt solutions with airline customers. Buyers should treat these moves as signals of how vendors prioritize modularity, certification speed, and lifecycle support.
What the PW Consulting report delivers — practical outputs for 2026 decisions
This study is designed as a decision support kit rather than an academic compendium. Deliverables include:
-
Executive dashboard summarizing market size (base year 2025), forecast (2026–2032), and high‑level scenarios driven by regulatory and material inputs (CAGR for forecast period included).
-
Supplier benchmarking and procurement scorecards covering integration capability, certification velocity, retrofit readiness, TCO drivers, and aftermarket support models.
-
Actionable linefit vs retrofit decision trees and NPV models that reflect installation labor, cabin downtime, and module commonality.
-
Technology roadmap and component risk heatmaps: USB‑C power delivery thresholds, converter efficiency expectations, thermal management constraints, and alternative conductor strategies.
-
Supply‑chain playbook addressing sourcing strategies for copper alternatives, distributor hedging, and long‑lead item mitigation.
-
Implementation checklists for OEMs and airlines: procurement clauses, certification checkpoints, integration test plans, and supplier SLAs.
-
Customizable slide pack and briefing materials for investor, board, and procurement committees.
To preserve competitive value for subscribers, the report intentionally withholds publicly replicable granular segmentation tables in this press overview; detailed regional and application splits, vendor market shares, and unit‑price matrices are available in the full report.
Strategic recommendations for 2026 — where to act first
-
Lock USB‑C roadmaps into product and procurement specifications: Mandate compatibility and certification milestones in procurement RFPs to avoid costly retrofit rework as passenger expectations and regulations converge.
-
Architect for higher‑voltage distribution: Re‑evaluate power distribution topologies to capitalize on material efficiencies and reduce conductor mass while maintaining safety margins.
-
Prioritize modular, serviceable designs: Modular outlets and centralized converters reduce downtime and enable staged retrofits. Include maintainability and spare‑part availability as decision criteria.
-
Hedge supplier risk with dual‑sourcing and certification co‑investment: Where critical components face constrained supply, secure second‑source agreements and co‑fund certification pathways to reduce single‑vendor dependency.
-
Use retrofit windows strategically: Synchronize power upgrades with scheduled maintenance to optimize labor utilization and cabin downtime, improving ROI for retrofit programs.
-
Embed lifecycle cost metrics in CAPEX approvals: Move beyond unit price—use our TCO templates to incorporate certification, installation, weight penalty, and obsolescence risk.
How to use this research in your 2026 planning cycle
Procurement leaders, product teams, and investment committees can use the report as the foundation for three immediate actions in 2026:
-
Run a 90‑day supplier selection sprint using our procurement scorecard to shortlist candidates for linefit and large retrofit packages.
-
Model one or two retrofit scenarios using our NPV templates to determine the optimal scope and timing relative to maintenance events.
-
Initiate co‑engineering or certification partnerships with vendors that demonstrate both modular hardware and lifecycle support capabilities to lower time‑to‑service for new‑power specifications.
Next steps and how to engage
PW Consulting’s Commercial Aircraft In‑Seat Power System Market report combines market sizing (base year 2025), a 2026–2032 forecast with an explicit CAGR, vendor scorecards, and implementation tools designed for immediate use in procurement and product roadmaps. For executive briefings, customized scenario modeling, or to obtain the full report with detailed segment tables and supplier market shares, contact PW Consulting to schedule a briefing and receive subscriber access.
For detailed analysis of this topic, please visit the official page: Commercial Aircraft In Seat Power System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Organic Rankine Cycle Waste Heat-to-Power Market Poised to Reach ~USD 9.75 Billion by 2032, Growing at a 10.65% CAGR
By PW Consulting, 2026-07-13
Organic Rankine Cycle Waste Heat to Power: A 2026 Strategic Preview — PW Consulting Market Insight
As industrial decarbonization accelerates and energy economics reshape capex allocation, the Organic Rankine Cycle (ORC) waste heat to power (WHtP) market is entering a phase of strategic maturation. PW Consulting’s forthcoming market research report — based on a 2020–2025 historical review and a 2026–2032 forecast horizon — quantifies this shift and translates it into immediate decision rules for executives planning 2026 investments.
Organic Rankine Cycle Waste Heat To Power Market
Market snapshot: decisive momentum, measurable opportunity
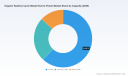
- The ORC WHtP market reached USD 4,800.0 Million in 2025 (base year) after a sustained multi-year recovery and expansion from 2020 levels, reflecting growing industrial deployments and maturing technology stacks.
- Our forecast projects a compound annual growth rate (CAGR) of 10.65% over 2026–2032, with the market more than doubling by the end of the forecast period. This trajectory reflects a mix of retrofit demand, greenfield integration, and accelerating deployments at energy-intensive industrial sites and compressor stations.
- Market concentration remains moderate: the top three OEMs account for roughly one quarter of the market, and the top five for just over one third. This structure favors both established leaders and nimble specialists pursuing vertical niches and regional anchors.
Why this matters for 2026 corporate strategy
For corporate strategy, 2026 is less about technological discovery and more about execution. Our analysis identifies three immediate strategic imperatives:
Organic Rankine Cycle Waste Heat To Power Market
- Prioritize bankable projects — accelerate projects where payback and operating profiles align with corporate risk appetite. Industrial payback windows in sectors like cement commonly fall in the 4–8 year range under current electricity price regimes; understanding site-specific duty cycles and heat-quality profiles is now the gating factor.
- Design for regulatory resilience — the regulatory landscape is shifting (notably through initiatives such as the EU Clean Industrial Deal). Equally important are pending chemical-policy developments (e.g., potential restrictions on certain PFAS/HFC working fluids) that will drive fluid selection, retrofit complexity, and long-term maintenance cost assumptions.
- Match scale and modularity to market entry strategy — the market growth profile favors modular ORC solutions for lower-temperature and distributed sources, while larger turbogenerator offerings capture centralized, high-grade waste heat opportunities. Procurement, financing and contracting models should reflect this duality.
What PW Consulting’s report delivers (practical, actionable content)
The report is constructed as an operational playbook for 2026 decision-makers. Key practical deliverables include:
Organic Rankine Cycle Waste Heat To Power Market
- Proprietary market-sizing and growth scenarios (2020–2032), with sensitivities to electricity pricing, carbon pricing, and heat-source availability that drive IRR and payback timelines.
- A decision matrix for technology selection by heat quality, operating hours and site constraints — designed for engineering, procurement, and corporate development teams to prioritize pilot vs. scale deployments.
- Standardized financial models (adjustable templates) to stress-test CAPEX/OPEX, O&M regimes, and alternative contracting structures (EPC, EPC+O&M, PPA, energy-as-a-service).
- Regulatory and fluid-transition risk mapping, including mitigation playbooks for transitioning away from at-risk working fluids and guidance on certification/compliance pathways.
- Commercial due diligence checklists for technology partners, OEM selection and M&A targets — covering IP posture, supply-chain concentration, service footprint and installed-base performance metrics.
Note: To preserve strategic value for subscribers and partners, detailed subsegment tables (regional, capacity and application splitouts) and granular company revenue allocations are presented in the full report only.
Competitive landscape — who to watch and why
The ORC WHtP competitive map blends global incumbents with specialized challengers. Our qualitative and comparative analysis centers on capabilities that matter for 2026: technology modularity, heat-source flexibility, installed-base support, and enterprise sales channels.
- Ormat Technologies Inc. (Reno, Nevada) — Strength: proven REG installations and integrated ORC converter technology. Strategic value: robust service footprint and project financing experience make Ormat a go-to partner for utility-scale industrial recovery where long-term O&M and performance guarantees are required.
- Turboden S.p.A. (Mitsubishi Heavy Industries Group, Brescia, Italy) — Strength: high-capacity ORC turbogenerators and project scalability. Strategic value: ability to deliver multi-megawatt plants and to win upstream-of-grid industrial contracts; recent commissioning of a large North American plant and additional compressor-station contracts underscore their aggressive capacity expansion in the region.
- Exergy International Srl (near Milan) — Strength: Radial Outflow Turbine (ROT) innovation and mid-range unit deployment experience. Strategic value: strong fit for cement and chemical sectors where bespoke turbine architectures improve lifecycle economics.
- ElectraTherm Inc. (BITZER Group) — Strength: low-temperature solutions (down to ~70°C) and modular Power+ generators. Strategic value: access to low-grade heat sources and simpler integration paths for brownfield plants and smaller industrial facilities.
- Orcan Energy AG, ENOGIA SAS, Calnetix Technologies, Alfa Laval AB — Collectively, these suppliers advance modularity, micro-ORC capability, high-speed turbo-generation, and heat-exchanger integration. Strategic value: they enable tailored solutions for maritime, micro-grid, and distributed industrial applications that larger vendors may under-serve.
Recent market movements sharpen competitive dynamics. Notably, Turboden’s commissioning of a multi-megawatt ORC plant in North America and subsequent contract awards for compressor-station projects illustrate demand concentration around baseload, turbine-exhaust recovery opportunities. Parallel deployments by tier-two innovators demonstrate a bifurcated market: large-scale industrial projects versus distributed, low-temperature micro-ORC plays.
Risk map and mitigation levers
- Regulatory / fluid risk: Anticipate restrictions on certain synthetic working fluids. Mitigation: accelerate qualification and pilot deployment of natural refrigerants and new working-fluid topologies; include contractual clauses for fluid replacement and performance guarantees.
- Project economics: Volatile electricity prices and operating hours drive payback variability. Mitigation: structure PPA or energy-as-a-service agreements, leverage merchant hedges, and prioritize high-capacity-factor sites (e.g., compressor stations, continuous-process plants).
- Supply chain & service: Specialized components (turbines, magnetic bearings) and localized service capacity can constrain uptime. Mitigation: secure multi-sourced supply agreements and invest in regional service hubs with performance SLAs.
- Market fragmentation: Moderate concentration implies room for partnerships, carve-outs, and niche plays. Mitigation: evaluate bolt-on acquisitions for service networks or technology gaps, and pursue strategic partnerships with heat-intensive industrial customers.
Operational playbook for 2026 execution
To convert the market opportunity into realized value in 2026, PW Consulting recommends a phased, risk-calibrated execution path:
- Phase 1 — Rapid screening: Use heat-mapping to identify top 5–10 candidate sites by heat availability, duty cycle, and permitting environment.
- Phase 2 — Proof of economics: Deploy pilot(s) with adjustable financial models and entry contracts (short-term PPA or EaaS) to validate performance and establish reference cases for CAPEX approval.
- Phase 3 — Scale & standardize: Lock in standardized procurement bundles, performance-based O&M contracts, and fluid-compliance roadmaps for rollout across an industrial estate or fleet.
- Phase 4 — Strategic expansion: Pursue M&A or JV opportunities to strengthen regional service footprints or acquire complementary micro-ORC/macro-ORC technology for product breadth.
How PW Consulting’s insight supports board-level decisions in 2026
Boards and C-suites require three types of confidence to commit capital in 2026: accurate market sizing, defensible technology choice, and executable commercial models. PW Consulting’s report synthesizes these into a single deliverable — combining validated market growth (CAGR 10.65%), scenario-tested financial templates, and supplier diligence frameworks — to reduce time-to-decision and de-risk early commitments.
Importantly, while this briefing highlights market scale and competitive direction, the full report contains the granular segmentation, regional and application-level analytics, and vendor revenue breakdowns required for procurement RFPs and capital approvals. Those detailed exhibits and model files are intentionally gated to preserve commercial value for subscribers.
Next step — where to get the full intelligence
PW Consulting’s Organic Rankine Cycle Waste Heat to Power Market report is positioned as the operational playbook for 2026. For procurement officers, project developers, corporate strategists and private equity teams evaluating entry or scale investments, the full report provides the actionable templates, segment analytics and vendor scorecards necessary to move from pilot to portfolio. Contact PW Consulting or visit our report page to access subscriber-only exhibits, downloadable financial models, and vendor diligence appendices.
For detailed analysis of this topic, please visit the official page: Organic Rankine Cycle Waste Heat To Power Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hybrid Cross Car Beam Market to Grow at 6.0% CAGR to USD 3,199.43 Million by 2032 — 2025 Base Market USD 2,127.8 Million, Asia‑Pacific Leading with USD 848.9M
By PW Consulting, 2026-07-13
Hybrid Cross Car Beam Market: Strategic Insights for 2026 — PW Consulting Report Preview
PW Consulting today releases a preview of its forthcoming Hybrid Cross Car Beam Market report, designed to equip automotive OEMs, Tier‑1 suppliers, materials providers, and strategic investors with immediately actionable intelligence as they set priorities for 2026. The preview highlights the programmatic value of the full study — rigorous market sizing, scenario-driven forecasts, technology and cost frameworks, supplier scorecards, and deal playbooks — while reserving the granular segment tables and proprietary worksheets for report subscribers.
Hybrid Cross Car Beam Market
Market Snapshot: A Clear Growth Trajectory
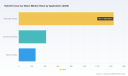
Our analysis frames hybrid cross car beams as a distinct growth corridor within automotive lightweighting and cockpit integration strategies. On a macro basis the global market is mature but expanding: PW Consulting’s topline modelling shows the market at approximately USD 2.13 billion in 2025 (base year) with an expected rise to roughly USD 3.20 billion by 2032. That trajectory corresponds to an underlying compound annual growth rate (CAGR) of about 6.0% across the 2026–2032 forecast horizon.
Hybrid Cross Car Beam Market
This expansion is neither speculative nor incidental. It is being driven by an intersection of regulatory pressure, OEM electrification roadmaps, materials innovation, and a demand for functional integration in cockpit architectures. The growth profile we quantify supports strategic allocation of R&D, capital, and sourcing resources in 2026 — but with important timing and differentiation nuances that the full report unpacks in detail.
Hybrid Cross Car Beam Market
Why 2026 Is a Strategic Inflection Point
-
Regulatory and emissions milestones are converging with vehicle electrification schedules. Manufacturers must show measurable CO₂ and mass reductions across product portfolios. Hybrid cross car beams have emerged as a high-ROI lever because they deliver structural performance while enabling component consolidation and weight savings.
-
Materials and process maturation: advanced thermoplastics, long‑fiber composites, and hybrid metal-plastic assemblies now offer repeatable crashworthiness, NVH performance, and manufacturability at scale. Leading implementations deliver step-change mass reductions compared with legacy steel solutions while enabling integration of functions such as airbag and HVAC mounts.
-
Supplier consolidation and platform strategies are accelerating. Our competitive concentration metrics show a market where the leading few suppliers capture a material share of demand, creating both barriers and opportunities for new entrants and niche specialists.
Strategic Implications for OEMs and Tier‑1s
For leaders charting their 2026 plans, the report emphasizes four strategic vectors:
-
Material Architecture Choices: Decide where to deploy metal-dominant hybrids versus high-performance thermoplastic or composite hybrids based on platform mass targets, cost-to-manufacture, recyclability objectives, and supplier capability.
-
Platform Commonization vs. Differentiation: Use modular hybrid beam designs to standardize production across platforms while preserving cockpit differentiation where brand experience matters.
-
Supply‑chain Resilience & Decarbonization: Move beyond single‑sourcing for critical materials, build validated second sources for reinforced thermoplastics, and quantify embodied carbon to align procurement with corporate sustainability goals.
-
M&A and Collaboration Timing: Prioritize partnerships and minority investments that accelerate access to proprietary compounds, recycled carbon feedstocks, or integrated manufacturing capabilities (e.g., metal inserts with overmolding lines).
What PW Consulting’s Full Report Delivers (Practical Contents)
The full report is constructed as a practitioner’s toolkit rather than an academic compendium. Highlights include:
-
Market sizing and topline forecasts (2020–2032) with scenario variations, sensitivity testing, and unit-volume overlays that support plant-level demand planning.
-
Technology and materials benchmarking: comparative performance matrices (mass, stiffness, crash energy management, cost, recyclability) for steel-hybrid, aluminum-hybrid, and composite-hybrid architectures.
-
Commercial models and costing templates: OEM/Tier‑1 level cost-to-produce estimators, margin waterfall analyses, and break‑even cases for in‑house versus outsourced production.
-
Supply‑chain maps and supplier profiles with capability heatmaps, qualification lead‑time forecasts, and risk assessments by geography and process dependency.
-
Regulatory impact assessments and lifecycle emissions modelling to quantify embedded carbon reductions achievable through hybrid replacements of traditional metal or magnesium components.
-
Deal playbooks and integration checklists for JVs, technology licensing, or targeted acquisitions — including sample term sheets and earn‑out structures tailored to mobility programs.
Each module is accompanied by downloadable worksheets and a “decision-simulator” that lets executives model trade-offs across mass, cost and CO₂ objectives — an invaluable aid for 2026 program prioritization.
Competitive Landscape — Who Matters in 2026
The market’s competitive fabric combines materials specialists, system integrators, and traditional metal‑forming Tier‑1s transforming their portfolios. Our qualitative assessment of leading players highlights the following strategic positions:
-
Röchling Automotive (Germany) — A materials-and-systems player focusing on metal-plastic hybrid beams that emphasize functional integration (e.g., integrated mounts) and part‑count reduction.
-
ElringKlinger (Germany) — Strong in thermoplastic injection solutions with localized metal reinforcement; a profile that maps especially well to EV cockpit architectures where multifunctionality and weight reduction are priorities.
-
FORVIA (Faurecia, France) — Deploys modular PA6‑GF compounds and platform‑level standardization to deliver demonstrable weight and emissions reductions while supporting cockpit customization strategies.
-
Envalior (Netherlands/Germany) and AKRO‑PLASTIC (Germany) — Critical upstream materials innovators providing high‑performance polyamides and carbon-fiber‑reinforced compounds that unlock 20–30% mass savings vs. steel in validated applications.
-
Magna, Gestamp, Benteler — Established Tier‑1s retooling metal-forming and joining capabilities to integrate hybrid solutions for electrified platforms, combining manufacturing scale with system integration know‑how.
Recent program wins and awards illustrate the pace of adoption: premium applications have already demonstrated performance parity and lifecycle benefits (for example, a carbon-fiber‑reinforced polyamide beam receiving industry recognition), and OEM product launches are now explicitly citing hybrid beams as a low‑carbon substitute for magnesium or heavier alloys. These exemplars underscore the tactical playbook for 2026: leverage validated high‑performance materials where they reduce program mass and cost, and deploy metal‑plastic hybrids where integration and cost‑efficiency are decisive.
Actionable Recommendations: A 2026 Playbook
-
Run prioritized pilot programs on two platform archetypes this year: one high‑volume mainstream vehicle and one premium/electrified model. Use the pilot to validate tooling amortization, cycle time, and crash behavior under production conditions.
-
Quantify embodied carbon in supplier selection. Project-level CO₂ reductions (e.g., replacing magnesium in targeted assemblies) can be multi‑tonne annually and materially affect fleet-level reporting.
-
Secure dual sourcing for core compound families (PA6/PA66 with long fiber or recycled CF options) to avoid single‑supplier bottlenecks and to retain negotiating leverage as volume ramps.
-
Negotiate performance‑based pricing tied to part mass and validated lifecycle emissions — an approach that aligns supplier incentives with OEM decarbonization goals.
-
Prioritize supplier partnerships that deliver systems expertise (insert overmolding, integrated mounting points) to maximize part consolidation and assembly labor savings.
-
Update crash and NVH validation timelines in powertrain shift programs (ICE → BEV) to ensure hybrid beams are validated within the vehicle’s homologation window.
How to Use This Report in Your 2026 Decision Cycle
-
0–90 days: Use the report’s supplier short‑list and capability heatmaps to begin RFIs and technical deep dives. Run initial cost and CO₂ delta scenarios for candidate platforms.
-
90–180 days: Execute pilot production runs and finalize supplier qualification. Deploy the report’s test protocol checklists and crash/NVH templates.
-
180–360 days: Integrate validated hybrid beams into program cost models, finalize sourcing agreements with performance and sustainability KPIs, and plan plant investments or contract manufacturing transitions aligned to launch schedules.
Concluding Note — Why PW Consulting’s Report Matters for 2026
Our preview underscores a strategic reality: hybrid cross car beams are no longer a lab curiosity — they are a program-level lever capable of delivering measurable mass, cost and CO₂ benefits within near‑term vehicle roadmaps. With an expected market expansion from the 2025 baseline to more than USD 3.1 billion by 2032 at roughly 6% CAGR, the economics favor decisive action in 2026. But the margin for error is narrow: material choice, supplier selection, validation cadence, and contractual structures will determine who captures the most value from this shift.
To access the full set of models, regional and application segmentation, supplier scorecards, and the decision-simulator toolset, please visit PW Consulting’s report page where the comprehensive Hybrid Cross Car Beam Market Report and subscription options are available. The full report contains the proprietary segmentation tables and downloadable worksheets referenced in this preview that will support near‑term program decisions and long‑term portfolio strategy.
For detailed analysis of this topic, please visit the official page: Hybrid Cross Car Beam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Wireless POS Terminal Market Poised for Robust 9.25% CAGR Through 2026–2032
By PW Consulting, 2026-07-13
PW Consulting Strategic Brief: Smart Wireless POS Terminal Device Market — 2026 Decision Playbook (Report Preview)
Executive snapshot
As enterprises plan hardware refreshes, channel expansions and service innovations for 2026, PW Consulting’s new market study on Smart Wireless POS Terminal Devices provides an evidence-based, execution-oriented foundation for strategic choices. Built on a comprehensive base year of 2025 and a 2026–2032 forecast horizon, the study synthesizes historical performance (2020–2025), a 9.25% compound annual growth rate view and forward-looking scenario analysis to help commercial, product and corporate development teams prioritize investments while managing regulatory and operational risk.
Smart Wireless Pos Terminal Device Market
Why this research matters to 2026 decision-makers
-
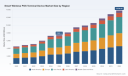
Market momentum: The smart wireless POS market has shown robust growth from its 2020 baseline through 2025 and is forecast to continue expanding at a mid-to-high single-digit CAGR. The 2025 whole-market benchmark and the 2032 projection included in our study illustrate a clear runway for vendors, integrators and enterprise buyers to rationalize multi-year hardware and services commitments.
Smart Wireless Pos Terminal Device Market -
Timing and window of opportunity: With product lifecycles, certification lead times and channel build-out measured in quarters, early 2026 is the practical decision point for vendors and large merchants who need to align procurement, certification and pilot programs to benefit from the next three product cycles.
Smart Wireless Pos Terminal Device Market -
Regulatory and security convergence: New security baselines such as PCI PTS 7.x and the ubiquity of EMV/NFC on Android SmartPOS are reshaping both product roadmaps and procurement checklists — making certification readiness a gating factor for market access in many geographies.
What the report delivers (practical, actionable modules)
PW Consulting’s report is designed as a practitioner’s toolkit rather than an academic compendium. At a glance, the deliverables include:
-
Market sizing & forecast model (2020–2032) with scenario toggles you can run in your own financial model.
-
Regulatory and certification roadmap (PCI PTS 7.x, EMV/NFC compliance, regional certification sequences) with task-level timing for product teams.
-
Vendor scorecards and a transparent benchmarking framework covering hardware, OS/platform, connectivity, lifecycle management and ecosystem partnerships.
-
Go-to-market playbooks for OEMs, ISVs, acquirers and value-added resellers — including channel economics, leasing models, and managed services packaging.
-
Technology prioritization matrix: tradeoffs between Android-based SmartPOS, mPOS integrations and ruggedized mini POS devices for mobile and fixed scenarios.
-
Supply-chain and component risk map — silicon, radios, and certification bottlenecks — with mitigation options (dual-sourcing, extended lifecycles, modular designs).
-
Deal and M&A screeners highlighting logical consolidation targets and partnership archetypes based on capability gaps and concentration dynamics.
-
Ready-to-use templates: PoC specification, RFP checklists, TCO calculators and procurement scorecards tailored for enterprise buyers and channel partners.
Competitive landscape — who matters and why
The market is characterized by a mix of global OEMs, platform-native entrants and specialized vertical players. The top-tier competitive picture shows moderate concentration: a multi-player leadership cluster controls a meaningful but not dominant share of the market, leaving room for challengers that combine software, services and differentiated hardware to scale quickly.
-
Ingenico (Paris) — Strengths in portable wireless hardware with proven security stacks and broad merchant acceptance; well-positioned where field services and retail mobility intersect.
-
Verifone (San Jose) — Deep global acquirer relationships and a wide product portfolio across mPOS and countertop segments; favorable for partners seeking integrated payments and enterprise-grade deployments.
-
PAX Technology (Shenzhen / North America HQ) — Rapid innovation on Android-based SmartPOS lineups, emphasizing hospitality and restaurant solutions; aggressive product cadence and competitive commercial programs make PAX a go-to for price/performance-driven rollouts.
-
Newland Payment Technology (Fuzhou) — Focus on globally certified Android devices and emerging market scale; a pragmatic option for international deployments requiring certification breadth.
-
Castles Technology (Taipei) — Compact wireless form factors and solid EMV/NFC implementations; appeals to channel partners focused on small footprint and low-cost installations.
-
NEXGO (Shenzhen) — Specialized in durable mini wireless POS with IP ratings for mobile environments; attractive for transportation and outdoor use cases.
-
Worldline (Bezons) — Recent launches of Android SmartPOS platforms for SMEs in Europe show a strategic pivot toward integrated payments + apps; its European distribution and bundled services create stickiness for small-to-medium businesses.
-
Square (Block) — Platform-first approach that transforms mobile devices into full POS systems; particularly disruptive in very small merchant segments and new commerce models.
-
Toast — Restaurant-first hardware and integrated management tools; a strong vertical playbook for F&B operators seeking close coupling of POS and operations software.
-
NCR Voyix — Provider of integrated wireless POS systems with a focus on large retail and hospitality chains; combines hardware, software and services for enterprise deployments.
Recent vendor moves illustrate the market’s tactical dynamics: major launches of Android SmartPOS builds in Europe, refreshed mini POS devices with rugged certifications, and trade-show demonstrations of next‑generation self-service integrations. These actions emphasize product differentiation around security, app ecosystems and vertical-fit solutions.
Regulatory, platform and security dynamics shaping vendor and buyer choices
-
Certification as a competitive gate: PCI PTS 7.x is increasingly a non-negotiable requirement for new wireless POS devices. Procurement timelines must accommodate certification lead times and post-certification lifecycle support for cryptographic modules.
-
Android SmartPOS adoption: With Android-based devices representing a substantial portion of devices sold globally as of 2023, vendors that can manage OS update cadence, app lifecycle and secure boot/attestation will outcompete hardware-only suppliers.
-
Contactless and EMV/NFC: Compliance with EMV and NFC standards is table stakes in major markets; the differentiator becomes how payment devices integrate customer-engagement apps, loyalty services and value-added business apps.
-
Connectivity stack: Multi-radio support (cellular, Wi‑Fi, Bluetooth) and offline‑first transaction continuity are critical for distributed, mobile and transport deployments.
Practical go-to-market plays for 2026
-
Vendors: Prioritize certification roadmaps, modular designs to shorten variant time-to-market, and bundled SaaS offerings to increase lifetime value. Use channel pilots to validate leasing and managed services economics before large-scale rollouts.
-
Acquirers & ISVs: Move from device-agnostic procurement to capability-driven sourcing: require proof of secure update paths, app sandboxing and local support footprints in RFPs.
-
Enterprises (merchants & operators): Use the report’s TCO templates to align procurement with real operational KPIs (transaction success rate, field-repair MTTR, firmware update OPEX) rather than focusing on headline device price.
How to use this report in your 2026 planning cycle
-
Quarter 1 — Strategy Alignment: Use the market sizing and scenario modules to set revenue and coverage targets; prioritize regions and verticals where certification and channel economics align.
-
Quarter 2 — Product & Supply Readiness: Run the certification and component-risk playbook; lock in suppliers for radios and secure elements; finalize ruggedization and OS update policies.
-
Quarter 3 — Pilots & Channel Activation: Deploy the PoC templates and RFP scorecards to pilot devices in representative merchant segments; iterate commercial terms with channel partners.
-
Quarter 4 — Scale or Exit Decisions: Leverage the M&A screens and vendor scorecards to decide on rollouts, strategic partnerships or divestitures ahead of the 2027 product cycle.
Final note — what you will find in the full report
This preview outlines the strategic frames and core issues executives must address in 2026. The full PW Consulting Smart Wireless POS Terminal Device Market report contains detailed, downloadable financial models, region- and application-level forecasts, vendor scorecards and executable playbooks (including ready-made RFPs and PoC templates) that are essential for transactional and strategic decision-making. For procurement teams, product leaders and M&A strategists who require the underlying datasets and segment-level intelligence, the report provides the granular inputs and scenario variants needed to convert insight into action.
Call to action
To obtain the complete report, interactive models and consulting engagement options, visit PW Consulting’s publications page or contact our industry practice. PW Consulting stands ready to support tailored workshops that convert these insights into a prioritized 12–36 month action plan aligned to your organizational objectives.
— PW Consulting, Senior Strategic Advisor & Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: Smart Wireless Pos Terminal Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aerial Target Drones Market Set to Expand at an 8.12% CAGR During 2026–2032, New Insight Reveals
By PW Consulting, 2026-07-13
Aerial Target Drones Market: Strategic Briefing for 2026 Decision-Makers
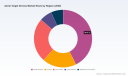
PW Consulting’s new Aerial Target Drones Market report delivers an evidence-based playbook designed to sharpen executive decision-making as defence programs and commercial counter-UAS use cases accelerate in 2026. The market has moved from an early, program-driven niche into a structurally expanding defense ecosystem: total industry revenue grew from roughly USD 4.13 billion in 2020 to USD 6.25 billion in 2025, and PW Consulting’s projection shows continued expansion into the forecast window (with the market poised to exceed USD 10.7 billion by 2032 at a compound annual growth rate of about 8.12%). For defense primes, system integrators, component suppliers and private-equity investors, that trajectory requires immediate reassessment of supply chains, product roadmaps, and go-to-market plays.
Aerial Target Drones Market
Why this report matters in 2026
-
Timing: 2026 is the inflection point for procurement and indigenization policies (notably in the U.S. and allied states). Programs that can demonstrate domestic sourcing, resilience to component choke points, and rapid integration into live-fire training cycles will capture outsized budget allocations.
Aerial Target Drones Market -
Scale: The business case is moving from bespoke platform sales to recurring production, sustainment, and services revenue. Buyers are shifting procurement criteria to total lifecycle cost and rapid replenishment capability, not just unit performance.
Aerial Target Drones Market -
Competitive consolidation: Market concentration metrics indicate a moderately concentrated market (CR3 ~48.5%, CR5 ~62.8%), meaning the leading suppliers already control a meaningful share of volume and platform-standardization opportunities. Late entrants must either underwrite rapid scale or secure unique mission capabilities to compete.
Key market dynamics and strategic implications
-
Regulatory reshaping: Recent policy actions—such as U.S. export-control clarifications in early 2026 and tightening domestic-content requirements embedded in defense budgetary guidance—will accelerate allied procurements while increasing compliance overhead for multinational suppliers. Companies should treat export and domestic-sourcing policies as program risks and competitive levers simultaneously.
-
Supply-chain fragility: System-level production is constrained by chokepoints in magnets, battery cells, and semiconductor supply. Vendors that secure alternative sources, long-lead contracts, or component stockpiles will gain near-term pricing and delivery advantage. For OEMs and tier-one suppliers, vertical integration of key subassemblies or strategic partnerships with component specialists will be a defensible response.
-
Shift to services and simulation: As live-fire training demand rises, there is higher willingness to procure bundled services (target launch, telemetry, data analytics, and post-exercise maintenance). Service-first pricing models lower barriers to adoption and create recurring revenue streams that materially change lifetime cash flow profiles versus pure platform sales.
-
Technology convergence: Advances in propulsion mixes (fixed, rotary, hybrid), signature management, and autonomous behaviors are enabling more realistic threat representation. Programs that combine high-fidelity threat emulation with repeatable logistics will be prioritized by training commands and test ranges.
Competitive landscape — what to watch
Our analysis profiles incumbent leaders and emerging challengers across system types and mission sets. Key players include established defense primes and specialist UAV manufacturers that together form the backbone of current procurements and technology development.
-
Kratos Defense & Security Solutions (San Diego, CA) — A high-volume supplier of subscale aerial target systems. Recent contract activity includes multiple U.S. Navy awards through early 2026, reinforcing Kratos’s production momentum and program delivery profile. Kratos’s product family and manufacturing footprint position it to serve both repeat-training cycles and larger Navy acquisition plans.
-
QinetiQ (Farnborough, UK) — Known for the Banshee range and support services, QinetiQ continues to secure follow-on sole-source support awards. Their global service model and live-fire range integration capability make them a go-to for customers seeking turnkey training solutions.
-
Griffon Aerospace (Madison, AL) — A supplier of widely used subscale platforms for air defense training and testing. Griffon’s depth in logistics and fleet sustainment supports customers requiring high sortie rates and quick turnaround.
-
Boeing (Arlington, VA) — Operating at the full-scale end of the spectrum, Boeing’s conversion programs for retired fighter assets remain a strategic option for certain weapon-testing and end-to-end lethality validation programs. Recent DoD awards to convert legacy fighters into aerial targets demonstrate the continuing role of full-scale target solutions.
-
AeroTargets International (USA) and Air Affairs Australia (part of QinetiQ) — Specialists with focused product lines for range-operator and counter-UAS missions. Their portfolios are attractive to buyers favoring modularity and rapid fielding.
-
Northrop Grumman, Lockheed Martin — Large primes maintain program-level relationships and systems-integration capabilities that can bundle target services into broader training and test-range modernization efforts.
Recent program milestones and contract awards further validate the market’s momentum: notable 2025–2026 actions show sustained procurement funding and collaborative development activity between OEMs and national suppliers. These actions are proxies for growing training demand and an emphasis on sovereign capability.
What the report contains — practical deliverables for executives
PW Consulting’s report is structured to be directly actionable for strategic planning, capture strategies, and investment diligence. Key contents include:
-
Modelled market-size and revenue-growth forecasts through 2032 with scenario sensitivity to policy, supply-chain, and procurement ramp assumptions.
-
Commercial and program-level buyer profiles, procurement timelines, and decision criteria for government and commercial range operators.
-
Competitive heat maps, capability matrices, and supplier benchmarking that reveal where incumbents hold defensible advantage and where gaps invite disruption.
-
Technology and R&D roadmaps assessing propulsion mixes, autonomy, and signature technologies—aligned with cost-to-performance breakpoints for customer segments.
-
Supply-chain risk assessment detailing critical component exposures and mitigation levers, including recommended supplier diversification and vertical-integration paths.
-
Go-to-market playbooks covering pricing, contracting strategies, sustainment-commercialization options, and partnership models designed to accelerate capture in 2026 program windows.
-
Deal flow and M&A checklists identifying targets by capability, production scale, and aftermarket footprint—prioritized for strategic or financial buyers.
To preserve competitive confidentiality and to comply with the “trailer” briefing approach, the report highlights sector-level segmentation and full modeling outputs but intentionally withholds raw subsegment tables and certain bidder-level pricing curves in this public release. Subscribers receive the complete, auditable datasets and build-your-own scenario workbooks.
How to use this intelligence in 2026
-
Procurement and Program Planning: Align near-term capacity expansions with the program ramps and compliance timelines embedded in your procurement forecasts. Prioritize suppliers that can demonstrate non-exposed component sources and validated production rates.
-
Partnerships and JVs: For companies lacking indigenous supply of key subsystems, pursue fast-track partnerships or equity stakes in Tier‑2 suppliers that solve magnet, battery or RF/avionics constraints.
-
Service-led commercialization: Convert platform relationships into services contracts (target-as-a-service, sortie-lifecycle support) to secure recurring revenue and higher lifetime margins.
-
M&A and divestment: Use the report’s valuation comparators and capability maps to identify high-leverage acquisition targets—particularly firms with sustainment footprints or unique signature-emulation technologies.
-
Regulatory and compliance readiness: Embed export-control and domestic-content audit trails into proposal responses. Compliance is increasingly a competitive differentiator in allied procurements.
Executive takeaway
In an industry moving from program-driven orders to program-of-record scale, strategic clarity will determine winners. The Aerial Target Drones market is expanding at an industry-level CAGR of just over 8% across the 2026–2032 forecast window, underpinned by predictable training demand, renewed investments in lethality testing, and policy-driven indigenization. Companies that act now—securing supply chains, shifting business models toward services, and locking early partnerships—can transform near-term growth into durable market leadership.
PW Consulting’s full report provides the detailed segment modeling, contract-level case studies, and scenario workbooks required to operationalize these recommendations. For decision-makers preparing budgets, capture plans or investment theses for 2026, the report is designed as an immediately deployable toolkit.
Next steps
-
Request the full dataset and scenario workbook to stress-test your 2026 roadmap against policy and supply-chain shocks.
-
Schedule a brief with PW Consulting’s lead analyst team to map a customized playbook for production scale, GTM execution, or M&A prioritization.
For detailed analysis of this topic, please visit the official page: Aerial Target Drones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Chromatography Cartridges Market to Hit USD 1,566.55 Million by 2032
By PW Consulting, 2026-07-13
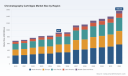
Chromatography Cartridges Market — Strategic Preview for 2026: Key Implications from PW Consulting’s New Report
PW Consulting’s latest market research on Chromatography Cartridges delivers a practice-oriented strategic playbook for companies making critical decisions in 2026. Built on a 2025 base year and a robust forecast through 2032, the study quantifies the market’s trajectory — demonstrating a disciplined recovery and expansion from roughly USD 682 million in 2020 to about USD 925 million in 2025, and projecting growth to approximately USD 1.57 billion by 2032 at a compound annual growth rate (CAGR) of 7.85% (2026–2032). For decision-makers, this represents an inflection window: volume growth is returning, but commercial advantage will accrue to firms that convert technical differentiation, supply resilience, and regulatory certainty into scalable go-to-market programs.
Chromatography Cartridges Market
Why this report matters for 2026 strategic decisions
-
Timing and resource allocation: The market’s mid-single-digit-plus CAGR through 2032 means near-term investments in capacity, quality systems and targeted R&D can still capture meaningful share — but timing matters. Firms that target the 2026–2028 window for commercialization of differentiated cartridges will face the most favorable demand and pricing dynamics.
Chromatography Cartridges Market -
Risk management: Raw material dynamics and regulatory scrutiny (especially for bioprocessing applications requiring GMP traceability) are shifting bargaining power upstream and altering the cost-of-goods profile. Procurement and supplier strategy developed now will materially affect margins and service levels in 2026 and beyond.
Chromatography Cartridges Market -
Portfolio prioritization: Not all cartridge formats and end-markets scale equally. The practical task for 2026 is to allocate R&D and commercial spend toward those modalities and value chains that amplify existing capabilities (e.g., prepacked flash cartridges, bioprocessing consumables, inert guard and specialty phases) while deferring or divesting lower-return segments.
What’s inside the PW Consulting report — practical, transaction-ready content
-
Market sizing & forward models: A validated top-down and bottom-up market model covering 2020–2032 with scenario runs (base, upside, downside) to stress-test capacity and pricing plans.
-
Demand-driver analytics: Quantitative and qualitative drivers across pharmaceutical, biotechnology, environmental and food safety applications, including addressable use-cases and adoption curves for preparative vs analytical cartridges.
-
Supply-chain & raw-material scenarios: Cost-impact models for silica and specialty media, supplier concentration mapping, and contingency playbooks for interruptions and input-price shocks.
-
Regulatory & quality playbook: Actionable checklists for GMP-compliant cartridge manufacturing, traceability templates, and audit preparation guidance for large-molecule purification customers.
-
Commercial playbooks: Channel strategy, pricing architecture, tender response frameworks, and customer segmentation with tailored value propositions for discovery, process development and manufacturing customers.
-
Competitive & M&A intelligence: Profiles and strategic positioning of leading suppliers, market concentration metrics, potential acquisition targets and a screening matrix for bolt-on vs capability acquisitions.
-
Operational improvements: Benchmarked KPIs for yield, cycle time, scrap and QC throughput; modular factory designs for scalable cartridge production; and CapEx sizing templates.
-
Decision-support deliverables: Financial model (driver-based), an executable 12–36 month roadmap, and an interactive dashboard for executive briefings.
Competitive landscape — actionable takeaways
The chromatography cartridges market sits at a moderate concentration level: the top three suppliers account for a meaningful minority of the market, while the top five enlarge that share to a majority. This structure favors both incumbents that can scale and specialist challengers that can exploit niches through product performance and superior customer service.
-
BUCHI Labortechnik (Switzerland) — Strength: prefilled flash cartridges in a wide range of sizes and bonded phases. Strategic implication: incumbency in purification-grade disposables makes BUCHI a logical partner for labs scaling up purification workflows; competitors should anticipate pressure on loading-capacity innovations and backpressure-optimized media.
-
Biotage (Sweden) — Strength: broad prepacked flash portfolio across normal and reversed phases with clear focus on drug-discovery throughput. Strategic implication: Biotage’s channel relationships in discovery labs mean pricing and service models (e.g., just-in-time supply of prepacked cartridges) will be a competing battleground.
-
Restek Corporation (USA) — Strength: guard and protection cartridges for HPLC/LC with inert options for metal-sensitive analytes. Strategic implication: Restek’s recent launches underscore demand for inert protection solutions; analytical labs and LC-MS workflows will drive adoption and upgrade cycles.
-
Sartorius AG (Germany) — Strength: process-scale and monolithic cartridges for bioprocessing. Strategic implication: For players targeting biologics and large-molecule purification, meeting GMP requirements and providing robust documentation chains are table-stakes that favor firms with bioprocess experience.
-
Agilent Technologies (USA) — Strength: HPLC columns and inert-series innovations for biotherapeutics. Strategic implication: Agilent’s investment in ultra-inert phases is a competitive signal — suppliers must respond with performance claims validated by independent data.
-
Waters Corporation (USA) — Strength: advanced protein and affinity cartridges for biopharma analysis. Strategic implication: Specialty cartridges for protein analytics represent a high-value attach opportunity for cartridge suppliers who can meet stringent purity and reproducibility targets.
-
Thermo Fisher Scientific (USA) — Strength: breadth across analytical to preparative applications. Strategic implication: Thermo Fisher’s scale and integrated offering create a benchmark for integrated consumable + instrument solutions.
-
Orochem Technologies (USA) — Strength: flexible manufacturing across flash, HPLC and preparative formats. Strategic implication: Contract-manufacturing and private-label opportunities are available for companies that can provide consistent quality at lower cost.
Recent product moves and sector dynamics to watch in 2026
-
New product introductions focused on inert performance and biotherapeutic-optimized phases (notable launches in late 2025) indicate an accelerating premiumization trend for cartridges that protect metal-sensitive analytes and support peptide/oligonucleotide workflows. Buyers should plan for validated comparison studies and incorporate upgrade paths into budget cycles.
-
Silica remains the dominant stationary phase. The industry continues to favor spherical silica for resolution and reproducibility; suppliers who can secure reliable spherical silica supply chains or novel media with comparable performance will gain a decisive cost and quality edge.
-
Regulatory tightening for bioprocessing cartridges — especially around GMP documentation and traceability — is not a distant regulatory scenario: it is already reshaping purchasing criteria. For 2026, expect larger biopharma buyers to require supplier certifications and audit readiness as preconditions for supply agreements.
Strategic recommendations for 2026 (practical, prioritized)
-
Accelerate GMP readiness for biologics-focused cartridge lines. Allocate budget in 2026 for traceability systems, validation studies and third-party audits to secure larger bioprocess contracts.
-
Lock in raw-material arrangements (spherical silica, specialty phases) with multi-year agreements or dual sourcing to reduce margin volatility and prevent supply disruption during forecasted demand upticks.
-
Invest selectively in inert-phase and protection cartridge technologies targeted at metal-sensitive and peptide/oligonucleotide workflows — these carry premium pricing and faster adoption by large labs.
-
Pursue bolt-on acquisitions or strategic partnerships to fill capability gaps (e.g., monolith production, affinity media) rather than greenfield builds where time-to-market matters.
-
Design a segmented go-to-market plan that distinguishes discovery, process development and manufacturing use-cases and ties product specifications to buyer KPIs (throughput, reproducibility, documentation).
How PW Consulting’s deliverables accelerate execution
Our report is engineered to move teams from insight to action. Beyond narrative analysis we deliver a driver-based financial model, supplier scorecards, a GMP readiness checklist, a go-to-market playbook, a shortlist of M&A targets plus scenario simulations tailored to client risk appetites. We also provide an executive workshop to convert report outputs into a 12–36 month operating plan — including prioritized investments and a measurable implementation timeline.
To preserve the strategic value of the dataset for our clients, detailed subsegment revenue splits and sensitive regional breakdowns are intentionally withheld from this press release. The full report includes those granular layerings, validation datasets and anonymized stakeholder interviews necessary for transaction diligence and commercial planning.
Next steps
For procurement leaders, R&D heads and corporate strategy teams preparing budgets and M&A pipelines for 2026, the PW Consulting Chromatography Cartridges report is a practical tool: it clarifies where to invest, where to partner, and where to hold off. Contact PW Consulting to request the full report package, arrange a briefing, or commission a tailored deep-dive that maps our models to your balance sheet and operational targets.
For detailed analysis of this topic, please visit the official page: Chromatography Cartridges Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Industrial Valves & Actuators Market to Expand at a 5.45% CAGR Through 2032
By PW Consulting, 2026-07-13
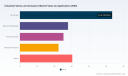
Industrial Valves and Actuators Market — Strategic Imperatives for 2026 Decision‑Making
PW Consulting’s latest market study (base year 2025; historical 2020–2025; forecast 2026–2032) frames the Industrial Valves and Actuators sector against a concrete growth trajectory: the global market expanded from roughly USD 118.5 billion in 2020 to USD 159.3 billion in 2025 and is projected to rise to about USD 231.0 billion by 2032, implying a compound annual growth rate of approximately 5.45% over the forecast window. The near‑term projection for 2026 sits above 2025 levels, providing a clear but measured expansion backdrop for boardroom decisions in the year ahead.
Industrial Valves And Actuators Market
Why this report matters for 2026 planning
Senior executives and investors face a convergence of structural and cyclical dynamics in 2026: accelerating electrification of actuation, persistent commodity and tariff volatility, renewed policy focus on critical infrastructure (including nuclear and water), and continued digitalization of process control. This report is designed as a decision‑grade resource that translates market direction into executable choices for portfolio managers, procurement heads, product leaders, and M&A teams.
Industrial Valves And Actuators Market
- Market trajectory establishes the “what” — a mid‑single digit CAGR gives room for strategic investments that compound over a multi‑year horizon rather than short‑term tactical plays.
- Industry fragmentation (measured concentration indicates material but not overwhelming leader dominance) signals opportunity for targeted consolidation, specialized product plays, and service differentiation.
- Practical tools in the report convert trend signals (e.g., electrification, automation) into prioritized actions for 12–36 month planning cycles.
What the report delivers — practical, operational intelligence
Beyond headline sizing and trajectory, PW Consulting’s study is built to be operationally useful. The core deliverables include:
Industrial Valves And Actuators Market
- Robust forecasting framework: transparent assumptions, scenario variants (base, upside, downside) and sensitivity tests that let leaders stress‑test capex and revenue plans against commodity and policy shocks.
- Go‑to‑market playbooks: segment‑level strategies (product, pricing, channel) and templated GTM roadmaps tailored to OEMs, engineered suppliers, and end‑users.
- Supply‑chain and procurement tools: supplier heatmaps, index‑linked contract templates, and a raw‑material sensitivity model that quantifies the P&L impact of steel and alloy price swings.
- M&A and partnership diagnostics: target screening matrices, integration risk heatmaps, and return thresholds calibrated to market concentration and growth vectors.
- Technology adoption maps: timing and economics for electrification, smart valve instrumentation, and digital service models (predictive maintenance, digital twins), including TCO comparators for actuator types.
- Regulatory and compliance playbook: country‑level risk overlays and a dynamic regulatory watchlist to guide localization, certification, and export strategies.
Note: this briefing intentionally omits granular split tables and segment‑level dollar/percentage disclosures — the full report provides detailed tabulations and proprietary segmentation accessible through PW Consulting’s report portal.
Competitive landscape — who matters and why
The sector is populated by global diversified industrials, specialist actuator firms, and engineered valve houses. Our competitive review synthesizes strategic positioning, technology bets, and go‑to‑market footprints for the industry’s principal players, including (but not limited to) Emerson Electric Co., Flowserve Corporation, Rotork plc, Bray International, Crane Co., SLB (Cameron), Baker Hughes, AUMA, IMI, Velan, SAMSON, KSB, AVK, Curtiss‑Wright, and Parker Hannifin.
- Emerson: deep automation and final‑control integration; strength is system level offerings that combine control valves with plant automation, enabling higher‑value service contracts.
- Flowserve: engineered valve leadership and broadened critical infrastructure exposure — recent acquisition activity is explicitly aimed at bolstering nuclear and traditional power markets.
- Rotork and AUMA: strategic anchors in electrification of actuation and remote asset management; these firms are key reference points for customers shifting from pneumatic/hydraulic to electric solutions.
- Specialist engineered suppliers (Bray, Velan, IMI, SAMSON): maintain strong positions in sector‑specific severe‑service and high‑specification markets where customization and certification create high barriers to entry.
- System and services players (Crane, Curtiss‑Wright, Parker): leverage diversified portfolios across defense, power, and process sectors to capture aftermarket and lifecycle revenues.
- Energy majors and OEMs (SLB, Baker Hughes): remain important because of integrated supply relationships in upstream/midstream environments.
Recent corporate developments underscore two structural themes: consolidation in engineered valves (example: a definitive acquisition announced in early 2026 that accelerates capability in critical power markets), and intensified financial reporting focus on electrification and wastewater projects from key actuator specialists. The Valve Manufacturers Association and related conferences continue to be focal points for new product disclosures and standards dialogue in 2026.
Key market dynamics to factor into 2026 decisions
- Commodity and trade policy exposure: steel and alloy cost inflation — steel prices have risen materially (industry reports noted hot‑rolled coil above USD 1,000/ton in 2026) — combined with elevated tariffs implemented in prior years continue to pressure margins and sourcing strategies.
- Tariff and localization pressure: Section 232‑style measures and associated policy responses have increased landed costs and encouraged near‑shoring or local manufacturing investments in select markets.
- Technology shift to electric actuation: rising adoption is driven by lower maintenance, energy efficiency, and better digital integration; this will reshape product roadmaps and aftermarket service models.
- Contracting practices adapting to volatility: index‑linked commodity contracts and longer‑term hedging are becoming standard procurement instruments to stabilize input cost exposure.
- Critical infrastructure opportunities: nuclear, water/wastewater, and grid/upstream energy projects are creating pockets of above‑market demand that favor certified, high‑service suppliers.
Recommended strategic moves for 2026
PW Consulting recommends a prioritized set of near‑term actions aligned to different corporate roles. Below are high‑level prescriptions — the report contains executable templates and scoring models to operationalize each recommendation.
- For OEMs and product teams: accelerate modular electrified actuator platforms and open API strategies to win digital services and reduce long‑term TCO for customers.
- For procurement leaders: adopt index‑linked sourcing contracts, diversify alloy sources, and qualify second‑tier suppliers in lower‑risk geographies to manage tariff risk.
- For M&A and corporate development: prioritize tuck‑ins that expand certified supply to critical infrastructure (nuclear, desalination, water) and targets that add remote monitoring or service capabilities.
- For investors: target mid‑market engineered suppliers with differentiated severe‑service capabilities and strong aftermarket revenue streams; use our M&A scorecard to quantify integration lift.
- For service organizations: productize predictive maintenance and retrofit electrification kits to monetize installed base conversion opportunities.
Risk checklist — what to monitor monthly
- Steel and alloy price indices and the status of tariff measures affecting 2025–2026 trade policy.
- Tender pipelines in nuclear, water, and power generation — watch for shifts in certification and compliance windows.
- Adoption velocity for electric actuators and smart valve instrumentation across major end‑markets.
- Supply‑chain disruptions and freight cost spikes that could compress lead times and drive premium pricing.
How PW Consulting’s study becomes a working asset for 2026
The full Industrial Valves and Actuators report is structured to be more than a reference: it is a toolkit. Clients can extract scenario worksheets to model CAPEX timing, apply supplier heatmaps to sourcing decisions, and use our M&A scoring rubric to prioritize integration candidates. The study’s appendices contain the granular segment tables, regional breakdowns, and unit‑level assumptions that underpin the executive summaries and playbooks.
This release purposefully leaves out the granular segment tables and exact regional/application splits — that level of detail is reserved for report subscribers and consulting clients who need the full dataset to operationalize strategy. To access the complete dataset, model files, and tailored briefings, please visit PW Consulting’s report page or contact our industry practice for a briefing.
Closing
2026 presents a window where disciplined strategic moves — aligned to electrification, selective consolidation, and procurement sophistication — will disproportionately determine winners and laggards over the next investment cycle. PW Consulting’s report converts market direction into executable options and risk‑adjusted pathways so that leaders can commit capital with conviction and agility.
For detailed analysis of this topic, please visit the official page: Industrial Valves And Actuators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


