



Category: Machinery & Automotive
PW Consulting: Industrial Exhaust Fan Market Poised to Reach USD 253.1 Million, New Report Finds
By PW Consulting, 2026-06-28
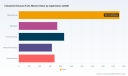
Industrial Exhaust Fan Market — Strategic Briefing for 2026 Capital Allocation
PW Consulting releases a focused strategic briefing derived from our full Industrial Exhaust Fan Market study (base year 2025). This briefing explains why 2026 is a decision point for manufacturers, OEM customers, private equity investors, and industrial end-users, and how our analytical toolkit translates market signals into executable capital and product plays. Our headline macro findings: the market reached USD 177.5 Million in 2025 and is moving into 2026 at an estimated USD 188.5 Million, with a forecast compound annual growth rate of 5.3% through the 2026–2032 window to a projected USD 253.1 Million by 2032.
Industrial Exhaust Fan Market
Why 2026 Is a Pivotal Year
Several contemporaneous forces converge in 2026 to compress timing for capital and product decisions:
-
Regulatory acceleration — regional ecodesign and efficiency mandates (notably a July 2026 implementation window in the EU and strengthened state-level rules in the U.S.) are shifting minimum performance baselines for industrial fans, repairability, and multi-load behavior.
-
Procurement and cost pressure — continued volatility in steel and aluminum pricing is increasing input cost variability and forcing procurement redesigns across supply chains.
-
Technical thresholds — buyer demand is migrating from baseline flow/pressure metrics to system-level energy performance (FEI/FEV regimes), lifecycle serviceability, and integrated controls.
Taken together, these dynamics create a narrow window in 2026 where manufacturers can convert technical compliance into commercial advantage — provided they align product roadmaps, supply chains, and commercial channels in the same quarter.
What PW Consulting’s Report Delivers — Practical Tools for 2026 Execution
Our full report is engineered as an operational playbook rather than an academic survey. Key practical deliverables include:
-
Supply-chain topology and risk heatmaps — visualizing tier‑1 to tier‑3 dependencies and single‑source exposures that amplify raw-material and logistics shocks.
-
BOM decomposition logic and configuration templates — a repeatable method for stripping a fan assembly into cost drivers, modular trade-offs, and upgradeable sub‑systems.
-
Yield-adjustment and cost-sensitivity models — scenario tools that quantify the P&L impact of yield improvements, material substitution, and tariff shocks without exposing confidential input values in this briefing.
-
Technology roadmap and certification matrix — a prioritized set of technology trajectories tied to compliance deadlines, design‑win lead indicators, and test-lab pass rates.
-
Aftermarket service and margin playbook — actions to convert installed base into recurring revenue while managing service-capacity constraints.
Each of these instruments is paired with executable decision triggers in the report (e.g., when to shift suppliers, when to prioritize product redesign, or when to pursue retrofit-as-a-service commercial pilots). We deliberately withhold the granular parameter values here to preserve the report’s proprietary value; the tools are designed to be run against your internal inputs or purchased as part of our advisory engagement.
Macro Dynamics & Market Shape (Data-driven Lens)
From 2020 through 2025 the market grows from USD 145.3 Million to USD 177.5 Million, reflecting steady expansion in capacity-driven end markets and a gradual premiumization toward higher-efficiency platforms. The forecast path into 2032 shows continued expansion to approximately USD 253.1 Million at a 5.3% CAGR — a trajectory that signals durable demand but also increasing expectations for product performance and compliance.
Market structure remains moderately fragmented: top-three players account for roughly 28.5% of market revenue and top-five for about 34.2%. This dispersion creates persistent opportunities for niche incumbents and new entrants that can secure design wins through certification, customization, or superior service economics.
Competitive Landscape — Dimensions That Decide Design Wins
Our competitive analysis focuses on strategic dimensions and observable behaviors rather than speculative position-takings. Across the vendor set, design wins and durable customer relationships are deterministically shaped by a handful of capabilities:
-
Engineering breadth and application depth — firms with wide portfolios (centrifugal, axial, roof-mounted) convert specification-led opportunities into wins when they also couple product breadth with repeatable test data.
-
Energy and compliance credentials — certification track record (AMCA/FEI/Type tests) and early compliance-aligned platforms materially shorten procurement cycles in regulated markets.
-
Manufacturing footprint and delivery predictability — lead-time reliability and regional service centers reduce Total Cost to Serve and are frequently decisive in retrofit tenders.
-
Material engineering and corrosion resistance — for harsh-chemistry customers, composite/FRP solutions and proven lifecycle performance are high-order buying criteria.
Representative players in the competitive set include recognized US and international manufacturers whose recent developments are consistent with the industry’s push toward certified, higher-efficiency platforms and expanded capacity. Examples of visible moves we track include software and product updates to support BIM/CAD workflows, new AMCA-certified fan platforms, and capacity expansions for axial manufacturing. These tactical moves confirm that leading vendors are investing along the dimensions above rather than changing the underlying industry economics.
To evaluate each supplier’s proximity to a sustainable moat, PW Consulting analyzes manufacturing economics, installed-base service footprints, and institutional relationships with large OEMs and engineering firms. For a closer look at our brand-by-brand scoring and comparative matrix, access the full report here: Access the full Industrial Exhaust Fan Market report .
Technology and Product Pathways to Watch in 2026
Technical evolution is incremental but strategically consequential. The most actionable technology pathways we monitor include:
-
System-level efficiency: integration of variable-speed drives and controls with fan/motor pairing to meet multi-load efficiency standards.
-
Materials engineering: use of corrosion-resistant plastics and coated alloys to extend life in chemical processing and coastal plants.
-
Modular design: componentized impellers and housings that reduce repair times and simplify certification workflows.
-
Digital enablement: remote diagnostics, FEI-trend analytics, and model-based service scheduling to monetize aftersales.
-
Manufacturing flexibility: regionalized assembly and additive manufacturing for low-volume, high-value impellers and shrouds.
Manufacturers that package certification readiness, aftersales digitalization, and flexible sourcing will both meet near-term compliance requirements and create long-term service revenue streams.
What This Means for CFOs, Heads of Operations, and Product Leaders
Practical strategic recommendations for 2026 resource allocation include:
-
Rapidly prioritize compliance-linked SKUs in product roadmaps to capture early adopter premiums and avoid de-listing risk in regulated sales channels.
-
Deploy BOM-focused cost-engineering pilots that preserve performance while addressing input-cost volatility — use our yield-adjustment model to size P&L exposure.
-
Rebalance supplier portfolios to mitigate single-source risk for critical castings and motors; where justified, fund near-shore capacity to shorten delivery cycles.
-
Accelerate service-centric offers (predictive maintenance, retrofit kits) to monetize installed base under tightening efficiency mandates.
Each of these actions can be scoped and quantified using the models contained in the full PW Consulting deliverable.
Methodology — How We Generate Actionable, Non-public Insight
PW Consulting’s conclusions rest on a layered-triangulation methodology designed to surface actionable signals well ahead of headline numbers. Our approach combines:
-
Patent and standards mapping to identify emerging technical trajectories and certification bottlenecks.
-
Confidential supplier and OEM interviews (under NDA), bill-of-material teardowns, and joint plant visits to validate cost and yield dynamics.
-
Proprietary customs and shipment analytics to infer regional demand shifts and lead-time exposures, cross-checked against public capex announcements and trade-show intelligence.
-
Independent lab test correlations and AMCA certification status to verify declared performance claims.
These elements are aggregated through our Layered Triangulation framework, which assigns confidence scores to each forecast element and makes the provenance of every significant estimate auditable within the full report.
Next Steps — Where to Get the Full Playbook
PW Consulting is publishing the comprehensive market model, company scoring matrix, and executable operations toolkit as part of the full Industrial Exhaust Fan Market report. For procurement teams, product leaders, and investors needing rapid scenario runs or bespoke advisory, the report is immediately actionable.
Access the full Industrial Exhaust Fan Market report and tools here: Access the full Industrial Exhaust Fan Market report . For tailored engagements, our advisory teams are available to run private workshops that map these findings to your organization’s financial and operational baseline.
For detailed analysis of this topic, please visit the official page: Industrial Exhaust Fan Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Pinch Valve Market to Grow at a 4.2% CAGR Through 2032 on Strengthening Industrial Demand
By PW Consulting, 2026-06-28
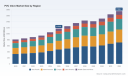
Pinch Valve Market: Strategic Imperatives for 2026 — PW Consulting Insights
In 2026, pinch valves occupy an outsized role in capital allocation decisions across water treatment, food & beverage, pharmaceuticals and chemical processing. Our new market study, anchored on base year 2025 and a forecast horizon through 2032, shows the global pinch valve market sitting at USD 635.0 Million in 2025 and tracking to a mid-single-digit compound annual growth rate (CAGR) of 4.2% over the 2026–2032 period. These headline figures mask important shifts in supply chains, regulatory exposure and technology economics that will govern winners and losers in the next 12–36 months.
Pinch Valve Market
Why 2026 Is a Turning Point
Corporate treasuries and engineering leadership are recalibrating in 2026 because three simultaneous forces change the payoff matrix for investments in valves and associated systems:
- Upward raw-material pressure on PVC resin and allied thermoplastics, driven by feedstock volatility and production turnarounds, is compressing supplier margins and increasing procurement risk.
- Certification and compliance expectations (notably potable-water listings and material-specific approvals) are now a gating factor for separate procurement funnels, raising switching costs for end users.
- Manufacturing modernization — from AI-driven predictive maintenance to automated assembly and inline testing — is creating a divergence in unit economics between digitally enabled firms and legacy operators.
Taken together, these trends make 2026 a year where procurement strategy, supplier selection and targeted capex in manufacturing yield disproportionate strategic value.
What Our Report Delivers — Practical Tools for 2026 Decisions
This report is deliberately operational. Rather than a surface-level narrative, PW Consulting provides toolkits executives can apply immediately to reduce cost, manage compliance and accelerate time-to-design-win:
- Supply-chain maps that identify single points of failure, critical sub-tier suppliers and alternate sourcing corridors suitable for rapid qualification during procurement disruptions.
- BOM decomposition logic and a cost-driver taxonomy that isolates the top 5 manufacturing inputs and process steps contributing to total landed cost, enabling targeted supplier negotiations and redesign opportunities.
- Yield-adjustment and tolerance-impact models that translate manufacturing defect curves into cash-flow scenarios and inventory buffers—critical for 2026 capacity planning.
- Technology roadmaps highlighting where pneumatic, manual and electric pinch valve architectures intersect with actuation, sealing materials and system-level integration — and how these intersections affect lifecycle costs and compliance paths.
- Scenario-based playbooks for regulatory compliance, including pathways to potable-water approval and material substitution strategies that preserve performance while reducing regulatory friction.
These deliverables are intentionally prescriptive in form but non-disclosive on granular numbers: they show the how and where to act, while core segmented data and distribution maps remain accessible in the full report for qualified users.
Competitive Landscape — Dimensions that Decide Design Wins
The pinch valve market today is shaped by firms that combine manufacturing competence with channel depth and certification portfolios. Our competitive framework evaluates players across four persistent dimensions that determine design wins and long-term margins:
- Product breadth and platform modularity — how quickly a supplier can offer configurable valve assemblies across sizes and elastomer options.
- Certification and materials credibility — NSF/ANSI and equivalent potable-water approvals are a decisive procurement filter in regulated end markets.
- Operational scale and vertical control — proximity to resin production, integrated molding capability and aftermarket service networks reduce disruption risk.
- Channel and OEM relationships — engineering support, joint-validation resources and spare-part logistics often outweigh incremental price differences when customers commit to multi-year projects.
Leading manufacturers — whether primarily thermoplastic specialists or integrated piping-system suppliers — are leveraging different combinations of these dimensions. Some focus on deep certification and application engineering to secure regulated water-treatment design wins; others optimize for cost and delivery through scale and channel partnerships. Recent product expansions and catalog updates across established vendors underscore an active competitive environment where incremental product and certification enhancements materially influence procurement shortlists.
To explore detailed competitive heatmaps and the company-by-company positioning that inform procurement and M&A choices, access the full analysis here: Download the full Pinch Valve Market report .
2026 Market Dynamics — Raw Materials, Regulation and Product Development
Two near-term dynamics require immediate executive attention:
- Raw material volatility: Price moves in PVC resin and allied feedstocks are now frequent and can materially change supplier bid profiles within quarters. Organizations that fail to bake feedstock scenarios into vendor contracts face margin erosion.
- Regulatory gating for potable-water and contact-sensitive applications: Certification requirements are not only a compliance checkbox but a sales enabler; having pre-certified elastomer seals and validated manufacturing lines shortens procurement cycles and increases win probability.
Manufacturers are responding with incremental product launches, catalog expansions, and certification updates. These are tactical steps that improve competitiveness in the short term, but strategic differentiation will depend on how firms link product breadth to service models and digital manufacturing capabilities.
Methodology — Why Our Conclusions Are Actionable
PW Consulting’s conclusions rest on a layered-triangulation approach designed for 2026 realities. Our method combines:
- Primary research: structured interviews with OEMs, tier‑1 and tier‑2 suppliers, distributors and certifying bodies, supplemented by site-level observations under NDA.
- Transactional and customs intelligence: anonymized shipment and build-data patterns that reveal where capacity is concentrated and how lead times shift during turnarounds.
- Patents, technical datasheets and product teardowns: reverse engineering of assemblies and material specifications to validate cost-driver hypotheses.
- Quantitative cross-checks: multi-source price curves, input-cost modeling and scenario stress tests to estimate resilience under feedstock and demand shocks.
We emphasize that much of the insight derives from data not widely published—procurement contracts, supplier performance KPIs and confidential engineering evaluation reports. Access to these sources follows rigorous ethical standards: interviews under NDA, anonymized transaction sets and reproducible analytical routines that produce defensible confidence intervals without exposing proprietary client information.
High-Impact Strategic Options for 2026
For executives allocating capital in 2026, our analysis prioritizes the following strategic options that yield the most immediate risk-adjusted returns:
- Prioritize supplier dual-sourcing and qualification for critical elastomers and molded components to reduce single‑point-of-failure exposure.
- Invest selectively in manufacturing digitization where yield gains and predictive maintenance shorten payback to within 24 months.
- Fast-track certification for core product lines in high-value regulated end markets to compress procurement cycles and create premium pricing pockets.
- Design BOM simplification programs focused on common elastomer families and actuation interfaces to reduce SKUs and improve procurement leverage.
- Embed ESG and material-recovery criteria into supplier scorecards to pre-empt compliance-driven re-sourcing in water and food sectors.
Each option maps to an implementation playbook in the full report, including resource estimates, typical timelines and the KPIs to monitor during a 12‑month rollout.
How PW Consulting Supports Implementation
Beyond diagnostics, PW Consulting offers turnkey support that accelerates decision-making in 2026:
- Due-diligence modules for M&A and strategic sourcing that combine our supply-chain maps with on-the-ground validation.
- Negotiation playbooks and modeled supplier contracts that incorporate feedstock pass-through clauses and performance-linked SLAs.
- Operational workshops that translate BOM and yield models into pilot projects for manufacturing modernization.
For procurement leaders and corporate strategists requiring the full dataset, granular segmentation and the company-level competitive appendices, please follow this link to obtain the comprehensive report: Download the full Pinch Valve Market report .
Final Note on Timing
2026 is not a typical planning year; it is a compression point where material cost swings, certification timelines and digital investments converge. Executives who move from descriptive market awareness to targeted, model-driven action in 2026 will capture efficiency and resilience advantages that compound over the forecast window to 2032. PW Consulting’s study is designed to convert market intelligence into executable decisions—without leaking the proprietary segment matrices that enable those choices at scale.
For detailed analysis of this topic, please visit the official page: Pinch Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Laser Interferometer Market to Expand at a 7.8% CAGR Through 2032, Fueling Surface Topology Demand
By PW Consulting, 2026-06-28
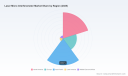
Laser Interferometer Market 2026: Strategic Imperatives for Capital Allocation
In 2026 the laser interferometer market sits at a critical inflection point. PW Consulting's latest market model shows aggregate global revenue expanding from USD 240.5 Million in 2020 to USD 345.3 Million in 2025, and continuing to grow to an estimated USD 369.2 Million in 2026, before reaching USD 578.4 Million by 2032. The forecast period (2026–2032) is characterized by a compounded annual growth rate (CAGR) of 7.8%. These headline metrics frame a market that is neither nascent nor saturated — it is maturing, consolidating, and undergoing rapid technological re‑platforming driven by semiconductor scaling, automation, and stringent metrology compliance demands.
Laser Interferometer Market
Market Trajectory and Strategic Drivers
The growth trajectory we model is shaped by several distinct, interlocking drivers that should inform 2026 capital allocation decisions:
- Precision demand from semiconductor and optics industries — advanced lithography and optical fabrication impose traceability and resolution requirements that elevate interferometer value beyond simple displacement sensing.
- Industry 4.0 automation — metrology is migrating from lab‑only to inline process control, favoring compact, ruggedized, and network‑ready interferometer platforms.
- Materials and manufacturing complexity — new optical materials and additively manufactured surfaces increase the use of interferometric surface topology and wavefront testing across industries.
- Trade and supply friction — reciprocal tariffs and supply‑chain concentration of critical components shift sourcing strategies and total cost of ownership considerations.
Collectively, these forces are shifting the market center of gravity in terms of demand origin and technology preference; the full regional and application distribution is detailed in our interactive segmentation maps in the full report.
Market Structure: Concentration and Competitive Implications
Consolidation is material: our concentration metrics show that the top three vendors account for 45.8% of the market, while the top five reach 68.3%. This structure creates an environment where scale and specialized IP both matter — large incumbents leverage installed bases and service networks, while focused innovators win new design slots through niche technical differentiation.
- Scale advantages: firms with broad calibration networks and service footprints reduce adoption friction for capital buyers that require traceable measurement chains.
- IP and algorithmic differentiation: vendors with proprietary phase‑measurement, vibration compensation, or integrated photonics technologies secure defensible pricing and repeated design wins.
- OEM integration and modularity: suppliers offering compact, interface‑friendly modules are preferred for inline and OEM embedding, accelerating unit adoption in automated lines.
Competitive Dimensions — What Matters for Design Wins
PW Consulting's competitive analysis focuses on the dimensions that determine procurement outcomes in 2026 rather than forecasting individual firm roadmaps. Key win criteria we see across procurement and OEM RFPs include:
- Traceability and standards compliance — demonstrable lineage to national metrology institutes and easy auditability in procurement.
- Environmental robustness — immunity to vibration, thermal drift, and vacuum/cleanroom compatibility for advanced production environments.
- Integration interfaces — digital, modular, and software APIs that reduce system integration effort and time‑to‑value.
- Service economics — predictable calibration cycles, remote diagnostics, and spare parts availability that minimize downtime risk.
- Compactness and power consumption — critical for embedded OEM applications, particularly where space and thermal budgets are constrained.
Examples in market practice underline these dimensions: providers with long histories in optical metrology typically leverage deep optical design and aspheric testing know‑how to win high‑precision optics contracts; firms centered on modular electronics and software make inroads in semiconductor fab tools where integration and digital telemetry matter. Recent product introductions and trade show activities corroborate this pattern: modular and lightweight interferometers, fiber‑based displacement systems for extreme environments, and vibration‑insensitive instruments are receiving outsized buyer attention.
For decision makers seeking detailed competitive diagnostic matrices and vendor scorecards, PW Consulting provides an interactive analysis that links market share dynamics to the specific competitive dimensions above — access the report to review the vendor benchmarking tools and procurement playbooks: Access the full Laser Interferometer Market report and interactive dashboards .
Practical, Actionable Deliverables in the Report
PW Consulting's Laser Interferometer Market research is built to convert insight into immediate action. Key deliverables targeted at 2026 pain points include:
- Supply chain topology maps that identify single‑point failures across optics, laser sources, and detector sub‑assemblies — enabling prioritized supplier diversification plans.
- BOM decomposition logic and teardown templates that reveal cost‑bucket drivers and substitution levers for commodity vs. proprietary components.
- Yield adjustment and metrology ROI models designed to quantify the incremental value of tighter in‑process measurement on first‑pass yield and scrap reduction.
- Technology roadmaps showing plausible adoption timelines for integrated photonics, white‑light absolute techniques, and vibration‑insensitive modalities — useful for product and R&D portfolio planning.
- Regulatory and traceability matrices that map applicable standards to procurement and calibration requirements, reducing compliance risk and audit cycles.
Each tool is packaged with an implementation guide that explains where the tool is most applicable (R&D validation, factory deployment, or aftermarket service) and how it integrates with purchasing and engineering workflows. The report intentionally refrains from prescribing single‑point technical parameters; instead, it provides the analytical scaffolding buyers and C-suite leaders need to test supplier claims and compare TCO scenarios under multiple 2026 market conditions.
Methodology and Data Rigor
PW Consulting's findings rest on a layered triangulation methodology designed to surface both public and non‑public signals with high fidelity. Our approach combines:
- Patent citation and technology lineage analysis to quantify innovation clusters and to map which firms own foundational phase‑measurement and compensation IP.
- Proprietary BOM teardowns and supplier interviews that identify component sources, margin drivers, and substitution opportunities in both OEM and aftermarket products.
- Multi‑node procurement interviews across fabs, calibration labs, and OEM design teams, complemented by on‑site observation at trade shows and product launches to validate adoption cues.
- Custom import/export flows and customs reconciliations to detect component concentration and tariff exposure, particularly relevant given rising reciprocal tariffs.
We respect confidentiality and commercial sensitivity: non‑public inputs are anonymized and cross‑validated before being incorporated into models. This blend of hard and soft data enables us to produce supplier scorecards, scenario CAPEX models, and design‑win probability matrices that are both auditable and actionable for board‑level decisions.
Strategic Guidance for 2026 Capital Decisions
Based on the market dynamics and tools above, executives and investment committees should consider the following priorities this year:
- Prioritize investments that reduce measurement uncertainty across critical process steps — these investments unlock downstream yield improvements and justify metrology CAPEX.
- Require supplier credentialing around traceability and standards compliance as a gating criterion in procurement to avoid retrofit and audit risk.
- Allocate R&D funding to modular, API‑enabled measurement platforms or to partnerships that accelerate integration into automated production lines.
- Hedge geopolitical and tariff risk by qualifying secondary suppliers for laser and precision‑optics subassemblies and by holding strategically selected buffer inventories for long‑lead items.
- Consider bolt‑on acquisitions to secure design wins in target verticals where a supplier’s installed base delivers asymmetric recurring service revenue.
These are pragmatic, execution‑oriented moves for 2026 that reduce operational risk while positioning organizations to capture the projected 7.8% CAGR over the forecast horizon.
Urgency and Next Steps
The market is moving from capability discovery to deployment scale; procurement cycles are tightening, and compliance obligations are increasing. Firms that wait for near‑term clarity risk ceding design slots and aftermarket service pools to competitors that have already validated integration pathways. For teams preparing 2026 budgets and strategic roadmaps, the PW Consulting report delivers the maps, models, and vendor playbooks necessary to make defensible capital calls.
To review the complete segmentation, interactive regional and application maps, and the full set of procurement tools and vendor benchmarks, consult the full report and dashboards here: Access the full Laser Interferometer Market report and interactive dashboards .
For detailed analysis of this topic, please visit the official page: Laser Interferometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Axial Piston Hydraulic Motor Market Poised to Expand at 4.8% CAGR Through 2032
By PW Consulting, 2026-06-28
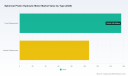
Axial Piston Hydraulic Motor Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting releases its Axial Piston Hydraulic Motor Market study with base year 2025, this briefing distills the report’s strategic utility for capital allocation, sourcing and product roadmap decisions in 2026. The market is now operating from a larger base — moving from USD 515.2 Million in 2020 to USD 650.0 Million in 2025 — and PW projects it to expand at a steady compound annual growth rate (CAGR) of 4.8% through the 2026–2032 forecast window. That steady expansion, combined with concentrated supplier economics (CR3: 48.0%, CR5: 53.0%), makes 2026 a pivotal year for reshaping cost structures and locking in design wins.
Axial Piston Hydraulic Motor Market
Why this report matters in 2026
Executives face three concurrent pressures in 2026: margin compression from raw material volatility, stricter global trade and ESG compliance, and accelerating digitization of manufacturing and testing. Our report translates these pressures into operational and portfolio actions by combining quantitative market outlooks with executable supply‑chain and engineering tools. Rather than a catalog of numbers, PW offers operational playbooks — built to be executed this year — that materially reduce time-to-win and mitigate near-term exposure to price and logistics shocks.
Axial Piston Hydraulic Motor Market
Market snapshot — concise macro context
Key macro takeaways you can act on immediately:
-
Market scale: From USD 515.2 Million in 2020 to USD 650.0 Million in 2025, with forecasts showing continued expansion to the late‑cycle target of USD 896.5 Million by 2032.
-
Growth trajectory: A mid-single-digit CAGR of 4.8% (2026–2032) indicates predictable demand growth, enabling multi‑year supplier contracts and capital investments to be planned with lower forecasting risk.
-
Concentration: The top three and top five suppliers account for 48.0% and 53.0% of the market respectively, highlighting both consolidation opportunities and potential single‑source risks.
Practical modules inside the report (how PW makes the market actionable)
The report was designed as a playbook for procurement, R&D and M&A teams. Notably, it includes:
-
Supply‑chain map with node‑level risk flags — showing where steel and alloy exposure sits in typical bill‑of‑materials (BOM).
-
BOM decomposition logic and cost‑to‑target worksheets — enabling engineering teams to model tradeoffs between material grades, tolerances and yield.
-
Yield‑adjustment and cost‑sensitivity models — to run scenario analyses without requiring internal data scientists to start from zero.
-
Technology roadmap with maturity curves — aligning hydraulic motor sub‑architectures to electrification, noise reduction and thermal management trends.
-
Compliance and ESG checkpoint list — practical controls for supplier audits, traceability expectations, and decarbonization levers.
Each module is accompanied by an execution checklist so teams can convert insights into 90‑ to 180‑day initiatives rather than conceptual strategies.
How these tools resolve 2026 pain points
-
Cost control: The BOM decomposition and yield models let teams simulate the effect of alloy price swings and process yield improvements on unit cost — critical given that ~38% of manufacturers reported steel/alloy price volatility through 2025.
-
Supply resilience: The supply‑chain map highlights mid‑tier nodes where logistics disruptions concentrate. Between 2023 and 2025, international logistics issues affected an estimated 18% of shipments; the report prioritizes alternative sourcing and buffer strategies targeted to those nodes.
-
Compliance & ESG readiness: The compliance checkpoint list aligns design and sourcing decisions with emergent 2026 trade and sustainability requirements, making audits predictable rather than adversarial.
-
Faster design wins: The technology roadmap clarifies which sub‑architectures (e.g., bent‑axis spherical piston variants with high‑pressure tolerance, low‑noise fixed displacement families) are likely to secure OEM design slots, and why.
Competitive landscape — dimensions that determine winners in 2026
Our competitive analysis focuses on the dimensions that create durable advantage and determine design wins — rather than attempting to forecast every firm’s 2026 playbook. Those dimensions include technical moat, channel access, integration capability, and program‑level supportability.
-
Parker Hannifin (United States): Technical moat from high‑pressure, thermal‑resilient spherical piston designs. Their advantage lies in proven high‑speed platforms and systems‑level engineering support — critical for OEMs specifying performance at elevated pressures.
-
HYDRO LEDUC (France): Strength in compact, low‑noise solutions and a product lineage adapted for e‑PTO mounting. Their recent XRe series launches indicate a positioning toward low‑pulsation applications where NVH and integration into electrified drivetrains are decisive.
-
Sunfab Hydraulics (Sweden): Differentiation through light‑weight, high‑starting‑torque units for mobile hydraulics. This profile makes them attractive to mobile OEMs prioritizing weight and cold‑start performance.
-
Ningbo Zhongyi (ZIHYD) (China): Cost and scale advantages in sphere‑piston portfolios for winch and slewing applications. Their value proposition is attractive where price and localized support networks matter.
-
Bezares S.A. (Spain): High‑performance bent‑axis offerings that compete on durability and integration into heavy‑duty hydraulics platforms.
-
Danfoss (Sauer‑Danfoss) (Denmark): Strength in variable displacement bent‑axis motors with system‑level controls — a key factor for OEMs seeking closed‑loop control and efficiency optimization.
Across these competitors, successful design wins will hinge on a short list of executable factors:
-
Demonstrable performance under duty‑cycle testing that matches OEM validation protocols.
-
Compactness and NVH performance for electrified or urban mobile platforms.
-
Supplier resilience and compliance traceability, especially for global OEMs operating under stricter trade and ESG rules in 2026.
-
Commercial supportability — warranty terms, spare parts logistics and local engineering presence.
For teams evaluating partners or targets, PW’s report anonymizes negotiated terms and program outcomes but flags which competitive dimensions each vendor leverages most effectively.
Methodology — why PW’s findings are actionable
PW Consulting uses layered triangulation to ensure reliability and relevance. Core inputs include:
-
Patent and standards mapping to identify technological trajectories and blockers.
-
Proprietary teardown labs and BOM reverse engineering to estimate cost structures and critical tolerances.
-
Supply‑chain interviews across OEMs, tier‑1s and logistics providers combined with customs flow analysis to map real routing and build contingency scenarios.
We cross‑validate these streams through a multistage quality process: source verification, statistical alignment with market flows, and validation workshops with end‑users. This approach is how PW derives non‑public directional insights (for example, supplier exposure to alloy grades or the likelihood of logistics disruption for specific node clusters) without publishing raw or commercially sensitive datasets.
Strategic imperatives for 2026 — recommended executive actions
-
Prioritize supplier contracts that include alloy‑price hedging clauses or collaborative yield improvement programs to mitigate volatile input costs.
-
Embed compliance and traceability requirements into RFQs to reduce audit friction and accelerate procurement cycles under 2026 trade rules.
-
Accelerate low‑noise and thermal‑management sub‑system investments for platforms targeting electrified drivetrains and urban applications.
-
Adopt the report’s BOM and yield models into product‑line budgeting to quantify ROI on manufacturing upgrades versus sourcing changes.
-
Use targeted M&A or joint‑development agreements to shore up gaps in local support or control of critical intermediate supply nodes highlighted in the supply‑chain map.
Next steps and how to access the operating playbook
PW’s report is intentionally structured to be a short‑cycle implementation resource for 2026. Teams that combine the report’s BOM models with supplier negotiations can expect to shorten procurement cycles and de‑risk pilot programs. For practitioners who require the full data tables, regional and application distribution charts, and downloadable Excel models, consult the full report at this link: Full report and operational toolkit .
PW Consulting stands ready to support scenario workshops, supplier negotiations and co‑development scoping sessions informed by the report’s modules. In a market where predictable growth collides with material and logistics volatility, the ability to convert insight into immediate operational action is the decisive advantage in 2026.
For detailed analysis of this topic, please visit the official page: Axial Piston Hydraulic Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Insights: Microtomes Market Poised to Reach USD 261.0 Million by 2032
By PW Consulting, 2026-06-28
Microtomes Market 2026: Strategic Imperatives for Capital Allocation and Operational Resilience
Now in 2026, the global microtomes market is at an inflection point. After steady expansion through the early 2020s, the market registers a 2025 size of USD 178.0 Million and is forecast to grow at a 5.5% CAGR across the 2026–2032 period, targeting an end-2032 market near USD 261.0 Million. This growth profile creates a window for disciplined capital deployment—but it also raises execution risk for organizations that underestimate regulatory, supply-chain and product-architecture complexity. Our Microtomes Market report is designed as a practical playbook for executives who must choose where to invest, where to partner, and where to tighten cost controls in 2026.
Microtomes Market
Why 2026 Requires Active Reassessment
Three structural shifts make 2026 the year to re-evaluate positions across the value chain:
Microtomes Market
- Clinical and research demand is converging around higher throughput, reproducibility and integration with digital pathology workflows; buyers are favoring systems that reduce end-to-end sample variability rather than lowest upfront price.
- Regulatory and ESG obligations are becoming financially material—new EU rules transfer a portion of disposal costs for disposable blades to producers, and existing EU MDR requirements tighten quality and traceability for histopathology consumables.
- Supply-side pressures—raw material volatility for blade steels and tungsten carbide, and the concentration of specialized subassembly suppliers—amplify the importance of BOM-level intelligence and alternate sourcing strategies.
Market Structure and Competitive Concentration
The sector displays moderate concentration: the top three players account for roughly 45.0% of market share, while the top five capture about 65.0%. This profile signals meaningful incumbent advantages—installed base, clinical validation pathways and global service networks—combined with niches where agile or cost-focused entrants can win. For capital allocators, this implies two primary routes to value: (a) doubling down on service/consumable ecosystems that create recurring revenue, or (b) targeting bolt-on capabilities and regional distribution to unlock underserved demand pockets.
Macro and Regulatory Context
Key external drivers shaping supplier economics and buyer preferences in 2026 include:
- Regulation: The European Union’s revised Medical Devices Regulation now requires certain disposable blade producers to fund a material share of disposal costs—this has immediate P&L implications for blade manufacturers and downstream pricing pressure for instrument OEMs.
- Raw materials: Blade performance and cost remain sensitive to high-grade stainless steel and tungsten carbide supply and pricing; manufacturing complexity (micro-grinding, coating) further differentiates cost curves.
- Digitization and automation: Integration with slide scanners, LIMS and digital pathology workflows elevates total cost of ownership (TCO) criteria beyond purchase price to serviceability and software interoperability.
- ESG and end-of-life liability: Buyers increasingly evaluate disposal costs, recyclability and supplier transparency as part of procurement decision matrices.
What the PW Consulting Report Delivers (Practical Tools for 2026)
We built the report to be executable by finance and operations teams. Key deliverables include:
- Supply-chain topology and risk heatmap — visualizes tiered suppliers, critical single-source nodes and contractual risk that affect lead times and cost sensitivity.
- BOM disassembly logic — a repeatable methodology to convert product-level design into cost buckets (precision tooling, blade systems, electronics, mechanical subassemblies) to support make-vs-buy decisions.
- Yield-adjustment and scenario models — practical models that translate manufacturing yields, scrap rates and blade change frequency into unit economics under different operating scenarios.
- Technology roadmap and interoperability matrix — maps expected adoption timelines for cryo, ultramicrotome and automation features and their downstream integration points with digital pathology platforms.
- Compliance-impact playbook — a stepwise compliance checklist and cost-implication framework aligned to contemporary EU MDR and disposal rules.
Each tool is paired with a “management activation guide” that explains how to deploy the deliverable in a 90–180 day operational cadence. Importantly, these tools tell practitioners what to test, where to hedge, and how to quantify trade-offs—without leaking proprietary performance thresholds that competitors could weaponize.
Competitive Dimensions: How Winners Will Secure Design Wins in 2026
From our primary research and triangulated intelligence, the decisive competitive vectors in 2026 are clear. Companies will win through combinations of the following moats and capabilities:
- Installed-base service networks and rapid field support—minimizes downtime for high-volume histopathology labs and is a major purchasing criterion for hospital systems.
- Consumable ecosystems—blade-consumable partnerships and bundled disposables create recurring margin and lock-in.
- Precision engineering and instrument longevity—tight tolerances and low maintenance profiles are critical for labs seeking predictable yields.
- Regulatory and quality documentation—speed to market in regulated geographies depends on robust technical files and post-market surveillance infrastructure.
- Software and systems interoperability—connectivity with slide scanners, LIMS and imaging pipelines is increasingly a gating factor for procurement.
Examples from the competitive set illustrate these dimensions without disclosing forecasted strategies. Long-standing OEMs known for comprehensive rotary portfolios leverage precision engineering and global service channels to defend institutional accounts. Suppliers emphasizing automation and disposable blade ecosystems win in higher-throughput clinical environments by reducing variability and TCO. German manufacturers remain synonymous with mechanical precision and channel depth in Europe, while select Chinese suppliers compete on lead-time flexibility and price, gaining traction in cost-sensitive segments.
Recent Industry Movements That Matter in 2026
Recent product launches and expansion activities validate how quickly the landscape is evolving:
- Late-2025 commercial introductions of new precision microtomes underscore ongoing product innovation and the premium placed on ergonomics and automation.
- Manufacturers expanding distributor footprints in Europe and the Middle East illustrate the continued importance of localized service and regulatory knowledge.
- Advances in ultramicrotome technology for electron microscopy are drawing cross-lab demand and creating adjacent revenue opportunities for OEMs that can bundle EM-capable systems.
Methodology: Why Our Findings Are Actionable
PW Consulting’s analysis rests on layered triangulation designed to surface non-public tactical signals while maintaining rigorous verification standards. Our methodology combines:
- Patent and citation analysis to detect emerging design patterns and supplier linkages;
- Bill-of-materials deconstruction from teardown labs and procurement invoice sampling to estimate component-level cost exposure;
- Structured interviews across OEM engineering, specialty blade manufacturers, regional distributors and leading pathology labs to validate commercial priorities;
- Proprietary data feeds including customs HS-line item analytics and service-part shipment patterns to map installed-base dynamics.
We apply multi-year cross-checks and sensitivity testing to ensure recommendations are robust to alternative market and regulatory scenarios. The report documents audit trails for our conclusions while withholding commercially sensitive raw inputs that are either proprietary or obtained under confidentiality.
Strategic Guidance for 2026 Decision Makers
For executives allocating capital or shaping go-to-market priorities in 2026, a concise set of strategic imperatives emerges from the research:
- Prioritize service and consumable revenue paths that reduce customer churn and increase lifetime value; model disposal and ESG costs into product pricing scenarios before finalizing procurement contracts.
- Secure diversified sources for blade-grade materials and validate second-source manufacturing for critical subassemblies to reduce single-node risk in supply chains.
- Invest selectively in software interoperability and API-based integrations to win design reviews in hospital procurement rounds increasingly centered on digital pathology workflows.
- Evaluate M&A or distribution partnerships that immediately strengthen regional service coverage rather than long R&D cycles—time-to-service is a competitive advantage in 2026.
- Run BOM-level pilot programs to quantify yield improvements and TCO before scaling capex—use our yield-adjustment templates to convert pilot outcomes into board-ready investment cases.
Next Steps and How to Access the Full Playbook
The summary above demonstrates the types of practical, executable intelligence PW Consulting provides. For teams preparing 2026 budgets or strategic roadmaps, the full report contains the visual maps, spreadsheet-ready models and supplier-panel insights necessary to translate market direction into invest/defend actions. To review the complete Microtomes Market report and obtain the downloadable toolset, please visit: Download the full Microtomes Market report .
PW Consulting’s research is calibrated for executives who require both strategic clarity and operational templates. In a market growing at a 5.5% CAGR amid tightening regulation and material cost dynamics, the right combination of supply-chain intelligence, BOM transparency and service-ecosystem strategy will determine who captures disproportionate share and profit over the next investment cycle.
For detailed analysis of this topic, please visit the official page: Microtomes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blow Guns Market Poised to Reach USD 390.0 Million by 2032, New Report Shows
By PW Consulting, 2026-06-28
Blow Guns Market — Strategic Briefing for 2026 Capital and Product Decisions
The global blow guns market is entering 2026 with measured expansion and higher strategic stakes for manufacturers, OEM purchasers, and industrial distributors. PW Consulting’s latest study benchmarks the market at USD 320.0 Million in the base year 2025 and models a steady trajectory through 2032 at a compounded annual growth rate (CAGR) of 3.2%, reaching approximately USD 390.0 Million by 2032. Historical momentum from 2020 through 2025 shows clear recovery and selective re‑rating across subsegments; our analysis translates these macro figures into decision-ready models for capital allocation, procurement, and product roadmaps.
Blow Guns Market
Why 2026 Is a Pivotal Year
Several coalescing forces make 2026 a window for decisive action rather than incremental adjustment:
-
Regulatory tightening on operator safety and pressure‑limiting design is driving immediate retrofit cycles and qualification requirements at OEM lines.
-
Manufacturers face renewed cost pressure from energy pricing and compressed air efficiency mandates, elevating the importance of low‑consumption nozzle technologies and system‑level yield improvements.
-
Procurement desks are recalibrating supplier portfolios amid moderate market concentration, making 2026 a year where design wins and distribution control materially shift supplier economics.
What PW Consulting’s Blow Guns Market Report Delivers
Our report is structured to convert market intelligence into executable programs. High‑value deliverables include:
-
Market sizing and high‑granularity forecasts across the 2026–2032 horizon, enabling NPV and scenario analysis for investment committees.
-
Supply‑chain maps that trace tier‑1 to tier‑3 component flows, identifying single‑source nodes and actionable decoupling levers for risk mitigation.
-
BOM decomposition logic and cost‑build templates that allow procurement and engineering teams to model targeted cost‑out programs without disrupting compliance pathways.
-
Yield adjustment and sensitivity models that quantify benefit paths from nozzle redesigns, compressor optimization, and preventive maintenance investments.
-
Technology roadmaps and a compliance matrix that align product development with OSHA pressure constraints and contemporaneous regional standards.
-
Commercial diligence tools — competitor scorecards, channel economics templates, and OEM qualification checklists — designed for M&A screening and supplier renegotiation.
Macro View: Growth and Structure
The market’s 3.2% CAGR masks structural nuance that matters for 2026 decisions. While aggregate volumes continue upward from USD 320.0 Million (2025) to an estimated USD 339.5 Million in 2026, the growth is uneven across product, channel, and use‑case. Importantly, market concentration metrics show a fragmented landscape (CR3 at 25.0% and CR5 at 30.0%), which creates both a runway for consolidation and localized pockets where premiumization and design‑led differentiation drive margin uplift.
Investors and product leaders should read that profile as an invitation: scale alone does not secure pricing power. Instead, control over compliance credentials, low‑energy nozzle designs, and OEM integration (design wins) becomes the primary pathway to above‑market returns in 2026.
Competitive Dimensions — What Wins in 2026
Across providers, PW Consulting evaluates competition along repeatable dimensions rather than speculative strategy plays. The essential vectors that determine advantage are:
-
Regulatory moat — validated designs that minimize downstream pressure and incorporate relief devices to meet OSHA requirements.
-
Design‑win capability — engineering resources and testing credentials that deliver OEM qualification and lock in aftermarket streams.
-
Energy and noise performance — quantified reductions in compressed air consumption and decibel ratings that translate to TCO improvements.
-
Channel depth — distribution footprints, industrial distributor agreements, and spare‑parts logistics that maintain uptime for end users.
-
Material and food‑safety competence — ability to deliver detectable, FDA‑compatible components for regulated industries.
Against these dimensions, market participants cluster by capability:
-
EXAIR Corporation: recognized for intelligent compressed‑air products and safety‑oriented designs that emphasize OSHA compliance and noise reduction.
-
Coilhose Pneumatics: a broad pneumatic accessory portfolio that competes on channel reach and ruggedness for industrial pros.
-
Prevost: ergonomics and modular coupling compatibility that appeal to assembly‑line ergonomics and interchangeability requirements.
-
Guardair Corporation: premium, OSHA‑compliant air guns with extended reach offerings favored in heavy industrial cleaning scenarios.
-
Silvent: high‑force, energy‑efficient guns with a strong focus on noise reduction and air‑consumption metrics.
-
KMS Company: tamperproof, corrosion‑resistant designs positioned for harsh environments and maintenance‑sensitive applications.
-
Festo: integrated air‑saving functions and modular nozzle interfaces that align with automated manufacturing systems.
These vendor profiles illustrate the competitive architecture rather than predict individual roadmaps. For procurement and corporate strategy teams, the question in 2026 is not whether a vendor is capable, but how their capabilities map to your design‑win, compliance, and TCO objectives.
Access the full Blow Guns Market report to review our interactive competitor matrices and supplier scorecards.
Technology Trajectories and Recent Signals
Technology evolution is pragmatic and incremental. Key innovation threads we track include:
-
Pressure‑limiting engineered nozzles and integrated relief devices to satisfy OSHA 1910.242(b) constraints and downstream blockage requirements.
-
Low‑consumption geometries and flow management to reduce compressed‑air draw and lifecycle energy cost.
-
Materials innovation for food‑safe, detectable plastics and corrosion resistance — recent product introductions in 2024 signal adoption acceleration in regulated sectors.
-
Noise attenuation and ergonomic form factors that reduce operator fatigue and meet quieter‑plant initiatives.
Example market signal: a 2024 launch of an X‑ray‑detectable food‑safe plastic blow gun demonstrates how niche regulatory needs create commercially significant product pockets. PW Consulting’s technology filters identify which innovations cross from niche to mass adoption, and when to prioritize capex for pilot programs versus full‑scale integration.
Practical Use Cases — Where Operators Should Focus in 2026
To translate insight into action, consider these short‑horizon programs:
-
Targeted BOM reengineering: use our decomposition templates to isolate commodity content and negotiate material premiums tied to detectable/food‑safe grades.
-
Compliance retrofit playbooks: prioritize nozzle retrofits and validated relief devices in lines where static cleaning remains a compliance risk.
-
Energy and compressor optimization pilots: pair nozzle swaps with system control logic to measure kWh and cost savings within 6–12 months.
-
Aftermarket and spare‑parts strategies: create service bundles around design wins to monetize maintenance cycles and improve customer retention.
Methodology — How PW Consulting Builds Confidence
Our conclusions rest on layered triangulation and primary validation. Core research techniques include patent and citation analysis to map proprietary nozzle and relief‑device inventions; multi‑tier BOM teardowns to isolate material, machining and assembly cost drivers; and a structured calibration process combining public filings, customs shipment flows, and proprietary procurement panels. We corroborate quantitative signals with NDA‑protected interviews and site visits to OEMs, major distributors, and tier suppliers to validate win‑rates, qualification lead‑times, and aftermarket dynamics.
Layered triangulation means no single data stream drives a conclusion. Instead, we reconcile supplier quotes, customs and shipment analytics, patent filings, and on‑the‑ground validation to produce defensible estimates and scenario models that are usable in board‑level investment deliberations.
Using This Report in 2026 Decision Cycles
For corporate leaders, the report is structured to plug directly into 2026 capital and procurement agendas. Typical use cases we support include:
-
M&A screening: identify bolt‑on targets that fill capability gaps (compliance, low‑consumption nozzles, or food‑grade materials) and compute accretion under conservative demand scenarios.
-
CapEx prioritization: rank product and process investments by payback given our yield‑adjustment models and energy savings trajectories.
-
Supplier consolidation and renegotiation: use BOM decompositions and channel economics to design win‑win contracts that lock volume while preserving margin for innovation partners.
To review the complete market distribution maps, interactive competitor scorecards, and the full set of modeling templates that underpin this briefing, please consult the full report at https://pmarketresearch.com/auto/blower-guns-market . PW Consulting’s analysts remain available to walk through model customizations tailored to specific product lines or procurement portfolios.
For detailed analysis of this topic, please visit the official page: Blow Guns Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: ELISA Market Set to Reach USD 3,188.9 Million by 2032, Reveals New Insight Report
By PW Consulting, 2026-06-28
ELISA Market 2026: Strategic Preview for Executives — Why the Next Capital Cycle Is Decisive
In 2026, the single‑channel Enzyme‑Linked Immunosorbent Assay (ELISA) reader market is at an inflection point. PW Consulting’s new market study — based on a 2025 base year and a forecast through 2032 — shows a resilient expansion driven by diagnostic demand, service‑led differentiation, and modular manufacturing upgrades. The global market size reaches USD 2,144.4 Million in 2026 and grows at a compound annual growth rate (CAGR) of 6.5% across the 2026–2032 forecast window. This briefing summarizes the report’s strategic value for 2026 capital allocation, while reserving the report’s detailed segment maps and discrete financials to the full publication.
Enzyme-Linked Immunosorbent Assay (ELISA) Market
Market Snapshot — Direction, Not Every Number
The market is expanding steadily after a recovery phase in the early 2020s; the structural drivers today are less about episodic public‑health spending and more about recurring clinical diagnostics, decentralization of testing, and ongoing demand from biopharma R&D. The market concentration is moderate: the top three firms account for roughly 55.0% of the market, while the top five represent about 68.0%, underscoring a competitive field where incumbents retain strong distribution and regulatory moats but face technology and cost pressures from lower‑cost vendors in emerging markets.
Enzyme-Linked Immunosorbent Assay (ELISA) Market
Why 2026 Matters for Strategic Capital Allocation
-
Regulatory inflection: FDA 510(k) clearance and ISO 13485 compliance remain gating items for clinical segmentation. Firms lacking streamlined regulatory pathways face longer time‑to‑revenue despite attractive unit economics.
-
Cost and labor pressure: Rising lab technician wages and supply‑chain fragility increase the importance of yield optimization and BOM engineering to protect margins.
-
Design and integration premium: Design wins are increasingly won on integration capability — optical performance plus firmware and LIMS interoperability — rather than raw price alone.
-
Reimbursement dynamics: Annual updates to clinical reimbursement schedules (e.g., Medicare CLFS) influence test adoption rates and can materially shift addressable volumes for certain assay classes within 12–18 months.
Principal Demand Drivers and Headwinds (2026 View)
-
Clinical diagnostic throughput growth, particularly for decentralized labs and specialty testing centers.
-
Pharmaceutical R&D adoption cycles linked to biologics and immunoassay validation workstreams.
-
Emerging‑market capital expansion, where lower‑cost instrument bundles compete on service and reagent ecosystems.
-
Regulatory and reimbursement volatility that creates timing risk for new product rollouts and procurement pipelines.
Actionable Tools in the Report — What Executives Receive
PW Consulting’s report goes beyond high‑level forecasting: it supplies disciplined, operational tools designed to be deployed in 2026 budget cycles. Among the deliverables are:
-
Supply‑chain maps that trace critical optics, detectors, and reagent consumable flows to second‑tier suppliers — enabling procurement teams to prioritize dual‑sourcing and hedge exposure.
-
BOM (Bill‑of‑Materials) decomposition logic that isolates cost drivers at the module level and models substitutability under different quality and compliance constraints.
-
Yield adjustment and factory ramp models that quantify the margin impact of modest improvements in production yield and cycle time.
-
Technology roadmaps that connect incremental optical and firmware upgrades to likely procurement decision windows and service contract opportunities.
Each tool is constructed to be knife‑edge practical: they are designed to guide sourcing negotiations, CAPEX prioritization, and service model redesign without exposing the underlying proprietary dataset in this briefing. For full charts and downloadable model templates, see the report.
Competitive Landscape — Dimensions of Advantage
Our competitive analysis emphasizes the dimensions that decide market outcomes in 2026 rather than publishing firm‑level revenue forecasts. The following competitive vectors determine which vendors win design placements and long‑term service revenue:
-
Regulatory moat — firms with established 510(k) pathways and European device certifications shorten procurement lead time for clinical customers.
-
Product performance moat — optical sensitivity, temperature stability, and kinetic measurement capability remain differentiators for higher‑value clinical and R&D use cases.
-
Service and reagent ecosystem — bundled reagent‑and‑maintenance offers increase lifetime customer value and favor vendors with broad distributor networks.
-
Cost and modularity — lower‑cost entrants succeed where buyers prioritize capital efficiency; modular platforms that allow incremental upgrades capture cross‑sell opportunities.
-
Design‑win enablers — LIMS/ERP interoperability, firmware update cadence, and certified training programs frequently tip procurement decisions in clinical and institutional tenders.
Leading companies profiled in the report — including established instrumentation vendors and regional challengers — compete along combinations of these vectors. Recent product catalog updates and firmware releases suggest incumbents are doubling down on optical and software enhancements while regional players focus on price and service bundles. For a company‑by‑company competitive matrix and recent development timeline, consult the full report.
Regulatory and Reimbursement Context (Why Timing Is Urgent)
-
FDA 510(k) clearance remains required in the U.S. for clinical use of single‑channel ELISA readers; this affects procurement cycles for hospital systems and national lab chains.
-
ISO 13485 certification is effectively mandatory for EU device manufacturers, influencing vendor selection and aftermarket service rights.
-
Annual reimbursement updates under national schedules (e.g., Medicare CLFS) can alter the economic case for certain assays within a fiscal year, creating windows of accelerated demand.
These dynamics make 2026 a watershed year: capital deployed now into regulatory readiness, modular upgrades, and supply‑chain resilience yields outsized returns compared with later catch‑up investments.
Methodology — Why Our Findings Are Actionable
PW Consulting applies a layered triangulation methodology to ensure both accuracy and actionability. Our approach blends patent and citation mapping, machine‑readable regulatory filings, proprietary procurement datasets, and over 100 anonymized executive interviews across OEMs, distributors, and clinical buyers. We validate instrument shipment trends against reagent purchase records and cross‑check pricing curves with distributor RFQs collected under confidentiality agreements.
For manufacturing and cost insights, we combine field BOM reverse‑engineering with in‑factory observations and single‑line yield models. This multi‑source triangulation enables us to infer non‑public supply‑risk exposures and probable margin sensitivity to small changes in BOM composition — insights we distill into executable supply‑chain mitigations in the full report.
Strategic Imperatives for 2026
-
Prioritize regulatory assets: accelerate 510(k) and ISO 13485 pathways for product lines intended for clinical use to protect addressable market share.
-
Invest in modular optics and firmware: aim for upgrades that preserve installed base connectivity and shorten design‑win cycles in institutional tenders.
-
Hedge critical suppliers: establish alternative sources for optics and detectors identified as single‑source risks in our supply‑chain maps.
-
Reposition commercial models: bundle instruments with reagents and service agreements to capture recurring revenue and reduce procurement churn.
-
Use price‑to‑value segmentation: allocate premium R&D budgets to high‑margin clinical/R&D applications and deploy leaner SKUs for emerging‑market channels.
A Tactical Note on Partnerships and M&A
M&A and strategic partnerships in 2026 are most likely to succeed where technology plugs a clear design‑win gap (e.g., a firmware/LIMS stack or an optics module) or where a distribution partner opens a high‑velocity national procurement channel. Our deal‑readiness checklist in the report helps executives evaluate whether a target offers a structural moat versus a short‑term sales boost.
Next Steps — Where to Get the Full Playbook
PW Consulting’s full report contains the complete segmentation maps, downloadable BOM and yield models, the competitive matrix with recent development annotations, and a companion deck for board‑level decision making. Access the comprehensive release, including executive templates and the supplier‑risk heatmap, at the official report page: Access the full ELISA market report .
Final Advisory — 2026 Planning Lens
In 2026, the single‑channel ELISA market rewards disciplined execution: firms that marry regulatory preparedness with pragmatic BOM engineering and service monetization will capture disproportionate share. PW Consulting’s report is explicitly structured to convert market insight into procurement actions, CAPEX prioritization, and M&A screening — a practical playbook for leaders who must commit capital in the current cycle.
For detailed analysis of this topic, please visit the official page: Enzyme-Linked Immunosorbent Assay (ELISA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Automotive Plastic Fuel Tank Market Poised to Reach USD 14.1 Billion by 2032
By PW Consulting, 2026-06-28
Automotive Plastic Fuel Tank Market 2026: Strategic Briefing for Capital Allocation and Product Strategy
PW Consulting’s latest market briefing sets out why 2026 is a pivotal year for investors, OEMs and Tier suppliers active in the automotive plastic fuel tank ecosystem. Our analysis synthesizes macro market sizing, regulatory inflection points, raw-material volatility and supplier competitive dynamics to deliver decision-grade insight—without disclosing the proprietary segment-level matrices contained in the full report. This preview outlines where value is aggregating, what operational levers matter most this year, and how the analytical toolset embedded in the full study will materially reduce execution risk for 2026 capital plans.
Automotive Plastic Fuel Tank Market
Market snapshot: steady expansion with structural offsets
Now in 2026, the global automotive plastic fuel tank market is on a steady growth trajectory that we model across 2026–2032. After a 2020–2025 historical baseline, total market revenue reaches approximately USD 11.3 Billion in 2026 and is projected to expand to about USD 14.1 Billion by 2032. This implies a mid-single-digit compound annual growth rate over the forecast window (CAGR ~3.9%).
Automotive Plastic Fuel Tank Market
Two simultaneous forces shape this pattern: demand-side resilience in ICE and hybrid segments supporting base volumes, and technology-driven margin pressure from regulatory and materials transitions that compress unit economics. For 2026 decision-making this combination implies predictable topline expansion but elevated execution risk on cost and compliance fronts—driving the case for tactically-timed capital and targeted R&D allocation.
Where the growth comes from (directional, not granular)
- Regulatory tightening on evaporative emissions is accelerating adoption of barrier-layer tanks and multi-layer constructions in developed markets.
- Hybridization (including plug-in hybrids) creates incremental specification complexity—pressurized designs and improved permeation control—raising BOM and validation effort per vehicle.
- Geographic shifts in vehicle mix and new model launches are concentrating volume gains in select platforms; the full report maps these shifts to OEM program timelines.
Dynamics shaping 2026 capital and operational priorities
Executives allocating capital in 2026 must balance three proximate dynamics that drive short-term returns and mid-term resilience:
- Raw-material volatility: HDPE price differentials are significant across regions and feed directly into per-unit economics. For example, HDPE spot levels in May 2026 were materially lower in North America versus Europe—creating both sourcing arbitrage and input-cost risk for globally positioned manufacturers.
- Emission and safety regulations: Progressive standards such as LEV III and evolving Euro emissions requirements are increasing technical spec floors for evaporative emissions and fire resistance, raising validation and tooling costs for compliance-ready tanks.
- Platform- and program-level complexity: PHEV pressurized tanks and tanks for alternative fuels (e.g., hydrogen-adjacent storage approaches) are adding engineering content and longer validation cycles, changing capital turn ratios for new-plant investments.
Practical decision levers in 2026
For executives the immediate set of levers to de-risk 2026 outcomes are operational and programmatic rather than purely strategic:
- Supply-chain redesign emphasizing regional polymer hedging and multi-sourcing to blunt localized HDPE price spikes.
- BOM rationalization and yield engineering that captures incremental margin from improved molding yield and reduced scrap on complex multi-layer constructions.
- Validation playbooks and Design-Win sequencing that prioritize early engagement on evaporative and pressurization requirements to shorten time-to-production.
Competitive landscape: how incumbents and challengers are differentiated
The supplier field in 2026 still exhibits a moderate level of concentration: the top three global vendors control roughly one-third of market volume while the top five sit at about half—conditions that create both cooperative program dynamics and fierce Design-Win competition. PW Consulting’s primary research and supplier fabric audits reveal that competitive advantage in 2026 clusters around a small set of dimensions:
- Manufacturing moat: scale in high-precision blow-molding, proprietary multi-layer co-extrusion technology and in-house tooling capabilities that shorten cycle time for high-barrier constructions.
- Program integration: suppliers that pair fuel tank supply with broader fuel-system or vehicle-platform integration secure higher switching costs and superior seat-time with OEM program managers.
- Validation and compliance competency: demonstrable track records on evaporative-emission test cycles, pressurization protocols for PHEVs, and regulatory acceptance in key markets are decisive for late-stage Design Wins.
Illustrative supplier dynamics observed in 2025–2026 (directional context only):
- Kautex leverages decades of blow-molding experience and integrated fuel-system offers to preserve program-level relationships in Europe and select global platforms.
- OPmobility (formerly Plastic Omnium) invests visibly in hydrogen storage and low-emission multi-layer systems—this generates strategic optionality for OEMs balancing ICE longevity and alternative-fuel roadmaps.
- TI Fluid Systems’ rebranding to TI Automotive after acquisition expands the combined entity’s portfolio strength, with validated pressurized solutions for PHEVs being a noteworthy commercial catalyst.
- Regional players such as YAPP and Yachiyo maintain cost-competitive positions and deep local OEM ties; these relationships often translate into early-stage platform supply opportunities.
These competitive motifs inform how PW Consulting assesses supplier partner suitability under different capital and program risk profiles—details and supplier-level scoring matrices are available in the full report and linked analysis tools.
Actionable tools included in the full PW Consulting report
The full study is structured around operational tools that translate analytical findings into execution-ready actions. Each tool is designed to be applied directly by procurement, program management and product engineering teams tackling 2026 priorities:
- Supply-chain map and sourcing heatmaps: visualize polymer exposure, single-source nodes and logistics chokepoints to support near-term hedging and tactical dual-sourcing decisions.
- BOM decomposition and cost-to-serve logic: an itemized methodology for isolating polymer, additives, tooling amortization and assembly labor—useful for scenario planning and supplier negotiations.
- Yield adjustment and sensitivity models: empirically-backed yield curves for multi-layer blow-molding, allowing finance and operations to simulate margin recovery from yield improvements or material substitutions.
- Technology roadmap and validation calendar: a calibrated timeline showing where EVOH layers, pressurized designs and hydrogen-adjacent approaches are most likely to be required across OEM program cycles.
Critically, these tools are purpose-built to answer 2026 pain points—cost control on volatile polymers, shortened validation windows for pressurized systems, and program-level compliance risk—without forcing stakeholders to reverse-engineer complex spreadsheets from raw data.
Methodology: layered triangulation and opaque-source validation
Our methodology combines quantitative market-sizing with qualitative program-level intelligence. Key pillars include patent-citation mapping, program-level tear-downs and a layered triangulation approach that cross-validates supplier-reported volumes, OEM launch calendars and customs/production-supply data to produce defensible estimates. Where formal program confidentiality limits disclosure, we use anonymized supplier-build histories and validation timestamping to reconstruct timelines and likely BOM impacts.
Beyond public filings, PW Consulting maintains a network of program engineers, tooling specialists and polymer analysts whose contributions—combined with proprietary patents and technical-readout parsing—allow us to infer non-public mobility of technology and validation status. This approach lets us identify high-probability program winners and quantify execution risk for capital projects without exposing confidential program data in the public summary.
Implications for investors and OEM/Tier leadership in 2026
For capital allocators and corporate strategists, the 2026 imperative is threefold:
- Prioritize investments that defensively hedge polymer exposure or create optionality via localized capacity or long-term offtake agreements.
- Invest in engineering and validation capability that shortens Design-Win to production timelines—this has outsized value for pressurized and multi-layer architectures.
- Use supplier-scoring that weighs program integration and compliance track record as heavily as price; short-term cost wins can yield longer validation and retrofit costs under stringent emissions regimes.
PW Consulting’s tools translate these implications into measurable actions—model-ready scenarios, supplier scorecards and a prioritized list of mitigation projects tailored for 2026 budgets.
Next steps and where to get the full intelligence
This briefing is a gateway to a detailed, execution-ready body of work designed for the 2026 decision cycle. The full Automotive Plastic Fuel Tank Market report contains the complete segmentation matrices, regional distribution maps, supplier scorecards and downloadable models referenced above.
Access the full Automotive Plastic Fuel Tank Market report here: Download the full report .
For detailed analysis of this topic, please visit the official page: Automotive Plastic Fuel Tank Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Pickup Truck Market to Expand at 5.2% CAGR Through 2032, Unlocking New Growth Avenues
By PW Consulting, 2026-06-28
Pickup Truck Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Brief
PW Consulting’s new Pickup Truck Market briefing is released in 2026 to equip C-suite leaders and corporate strategy teams with the actionable intelligence required to make high-stakes capital and operational choices this year. The global market has expanded steadily — from USD 155.0 Million in 2020 to USD 210.0 Million in 2025 — and is projected to reach USD 345.0 Million by 2032, reflecting a 5.2% CAGR across the 2026–2032 forecast window. This macro momentum coexists with intensifying regulatory and input-cost shocks, which together make 2026 a crucible year for defending margins, securing design wins, and re‑configuring supply chains.
Pickup Truck Market
Market Snapshot: Scale, Concentration, and Momentum
The pickup truck sector today combines steady demand growth with moderate industry concentration: the leading three OEMs account for roughly 55.0% of the market (CR3), while the top five capture about 65.0% (CR5). These concentration metrics underline the dual reality of scale advantages for incumbents and meaningful opportunities for differentiated entrants. The growth trajectory from 2020 through our base year 2025 — and the forecast through 2032 — is driven by both commercial fleet modernization and persistent consumer appetite for capability and lifestyle utility.
Why 2026 Is a Strategic Inflection Point
Several structural forces converge in 2026 that demand urgent attention from corporate planners:
- Trade and tariff volatility: recent policy actions impose material cost premiums on certain imported medium- and heavy-duty vehicle inputs, shifting the calculus for sourcing and regional production footprints.
- Rules‑of‑origin pressure: duty‑free eligibility frameworks now require higher regional content for critical metals, creating both compliance complexity and domestic sourcing opportunities.
- Material‑price and input shocks: new tariffs on derivatives of construction materials have raised build‑component volatility for truck bodies and beds, amplifying the need for BOM-level risk management.
- Electrification and powertrain diversification: OEMs are broadening portfolios across ICE, hybrid, PHEV, and BEV options — changing supplier ecosystems and aftermarket service profiles.
Structural Shifts and Growth Drivers
The briefing dissects the underlying vectors that will control share shifts through 2032. Key dynamics include:
- Electrification mix and platform modularity — not just EV volume, but how platform-level modular designs influence cost-per-vehicle and supplier bargaining power.
- Fleet telematics and commercialization — fleet electrification and telematics-driven uptime guarantees are reshaping total cost of ownership (TCO) expectations for commercial buyers.
- Localization and nearshoring — tariff regimes and rules‑of‑origin requirements are accelerating regional manufacturing and supplier clustering in priority markets.
- Software and systems integration — towing intelligence, fleet telematics, and over‑the‑air update capabilities are emerging as differentiators in Design Wins.
- Materials and yield management — volatility in raw materials and lumber derivatives increases the value of yield‑adjustment playbooks and supplier hedging strategies.
What the PW Consulting Report Contains — Practical Tools, Not Abstract Models
This report is built to be a working reference for 2026 execution teams, not just a descriptive market summary. The deliverables include:
- Supply‑chain topology maps that trace second‑ and third‑tier suppliers for key assemblies and critical raw materials.
- BOM disaggregation logic and cost-driver frameworks that let teams model variant costs by powertrain architecture and trim strategy.
- Yield adjustment models and sensitivity matrices for production ramp scenarios, calibrated to common assembly bottlenecks and supplier yield histories.
- Technology roadmaps that cluster propulsion, electrification, and software investments by time‑to‑market and capex intensity.
- Regulatory compliance playbooks aligned with trade regimes and rules‑of‑origin thresholds relevant for 2026 capital allocation.
Each tool is designed to be applied directly in boardroom trade‑offs: for example, the BOM logic helps prioritize component redesigns that yield the largest margin improvement per dollar of R&D spend; the supply‑chain maps identify where nearshoring reduces tariff exposure versus where it increases fixed cost. The report intentionally refrains from publishing proprietary parameter sets in public narrative — these are available in the interactive models within the full package.
Competitive Dynamics: How Leaders Compete for 2026 Design Wins
Our industry analysis emphasizes the competitive dimensions that determine who wins in 2026, rather than predicting specific strategic moves for each OEM. Across the incumbent and challenger set, success is being determined along a few repeatable vectors:
- Manufacturing scale and platform commonality — firms that leverage shared platforms across ICE, hybrid, and battery variants reduce incremental cost of technology transitions.
- Brand and dealer ecosystem — legacy familiarity and large dealer networks remain durable moats for mass adoption, especially in regions where serviceability is a buying criterion.
- Powertrain and software IP — proprietary towing and energy‑management systems create stickiness for commercial fleets that value uptime and TCO predictability.
- Supplier relationships and captive financing — control of critical sub‑assemblies or privileged access to battery packs and semiconductors translates to faster time‑to‑market.
- Premiumization pathways — differentiated interiors, Denali‑style trims, and lifestyle‑oriented compact pickups open non‑traditional profit pools.
Recent company developments illustrate these vectors in action: a leading OEM’s carbon‑heavy EV variant demonstrates how materials engineering and rear‑steering capabilities can become technical differentiators; another’s transparent pricing and production cadence announcement underscores the importance of aligning channel economics with launch plans; and full commercial rollouts of extended‑range electrified variants signal the move from pilot to scale for fleet applications. For deeper, company‑level scenario matrices and to see how these competitive dimensions map to likely 2026 outcomes, consult the full report: Access the full Pickup Truck Market report and models .
Methodology and Data Rigor
PW Consulting’s findings rest on a layered triangulation methodology designed to surface and validate non‑public signals. Our approach combines:
- Patent‑citation and IP landscaping to identify emergent technology clusters and supplier patent ownership.
- Teardown BOMs and lab-validated component cost studies reconciled against anonymized supplier invoices and customs shipment files.
- Primary interviews with OEM procurement leads, tier‑1 suppliers, and fleet managers, supplemented by anonymized telematics and aftermarket warranty data.
- Regulatory and trade‑policy modeling aligned to published statutes and customs rulings to simulate duty exposure under various sourcing scenarios.
We cross‑validate each data stream through a minimum of three independent sources (public filings, proprietary invoices, and field validation) before encoding results into our interactive models. Where access to proprietary datasets is necessary, PW Consulting leverages supplier consortium agreements and data‑sharing partnerships under strict NDAs to preserve confidentiality while enabling robust inference. This methodology is why our actionable tools — not merely conclusions — are trusted by clients needing to commit capital in 2026.
High‑Level Strategic Guidance for 2026 Capital Allocation
Based on our synthesis of market dynamics, competitors’ capability vectors, and trade‑policy risks, the briefing recommends prioritizing initiatives that deliver defensible upside within 18–36 months:
- Invest in modular platform upgrades and powertrain flex so a single assembly line can accommodate ICE, hybrid, and BEV variants with minimal capital churn.
- Accelerate supplier partnerships for critical components (batteries, power electronics, chassis modules) with contractual terms that share upside of yield improvements.
- Localize or nearshore key inputs where duty exposure and rules‑of‑origin requirements materially affect landed cost and compliance risk.
- Deploy yield‑improvement teams and digital twins at pilot plants to reduce ramp risk and limit margin dilution during launches.
- Prioritize software and telematics investments that monetize fleet uptime and enable subscription revenue, improving LTV economics for commercial accounts.
Next Steps and How to Use This Briefing
Executives using this briefing should treat the included playbooks and models as working artifacts: run scenario stress tests against your procurement catalogs, re‑price platform variants using our BOM framework, and backcast compliance exposures under alternative tariff regimes. For teams preparing board materials or capital requests in 2026, our modular deliverables make it straightforward to quantify trade‑offs between CAPEX, margin protection, and time‑to‑market.
To download the full dataset, interactive models, and granular scenario outputs that inform PW Consulting’s conclusions, follow this link: Get the full Pickup Truck Market report . The public brief intentionally highlights analytical depth while reserving our proprietary segment-level allocations and company scenario matrices for report subscribers and clients to preserve competitive integrity and drive direct engagement.
For detailed analysis of this topic, please visit the official page: Pickup Truck Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Insights: Float Level Switch Market Hits USD 555.0 Million in 2025, Signaling Robust Growth Ahead
By PW Consulting, 2026-06-28
Float Level Switch Market 2026: Strategic Imperatives for Capital Allocation and Operational Resilience
In 2026 the global float level switch market sits at a strategic inflection point. PW Consulting’s latest market study—anchored on a 2025 base year and a layered forecast to 2032—shows a market expanding at a steady 4.5% CAGR. Our analysis places the market at USD 555.0 Million in 2025 with a midpoint scenario projecting approximately USD 756.0 Million by 2032. These headline metrics understate the structural shifts under way: rising regulatory burden, raw‑material specificity, and concentrated competitive dynamics are together compressing tactical timelines for firms deploying capital, restructuring supply chains, or pursuing new design wins.
Float Level Switch Market
Why 2026 Is a Make‑or‑Break Year for Investors and OEMs
Multiple convergence factors make 2026 a high‑urgency year for both strategic investors and industrial equipment OEMs:
Float Level Switch Market
- Regulatory tightening across safety and EMC standards is increasing compliance costs for off‑the‑shelf components; suppliers must demonstrate IEC 61010‑1 and EN61326‑1 alignment for electrode‑type floatless switches, and ATEX remains non‑negotiable for hazardous area deployments.
- Raw‑material selection is no longer a cost‑only decision; corrosion resistance choices (SUS304 vs SUS316 vs titanium) materially affect product lifecycles, warranty exposure, and secondary processing steps in production lines.
- Market concentration is meaningful: the top three vendors hold a dominant share while the top five capture an even larger portion of supply—conditions that magnify the value of design‑win pipelines and channel partnerships.
Market Snapshot and Growth Drivers
The market’s trajectory reflects steady adoption across process industries and utilities. Growth is being driven by a combination of incremental replacement demand and strategic upgrades tied to digitalization and ESG compliance programs. Key demand drivers we observe include:
- Legacy asset upgrades to meet stricter environmental monitoring and wastewater control standards.
- Increased specification of corrosion‑resistant materials in aggressive chemistries, pushing suppliers to qualify higher‑grade alloys and alternative alloys.
- Manufacturers’ desire for plug‑and‑play devices that reduce integration time into PLC/SCADA systems—raising the bar for device interoperability and EMC performance.
What the PW Report Gives You (Teaser of Operational Toolset)
Our report is intentionally practical. Beyond market sizing and forecasts, clients receive an actionable toolkit designed for near‑term decisions in 2026:
- Supply‑chain topology maps that link tier‑1 manufacturers to critical subcomponent suppliers and logistics choke points.
- Bill‑of‑Materials (BOM) decomposition logic showing typical material mixes and processing steps that drive cost and lead time variability.
- Yield‑adjustment models that translate factory yield improvements into bottom‑line impact under multiple pricing scenarios—useful for negotiation and CapEx planning.
- A technology‑roadmap framework that sequences potential investments (materials, certification, sensing modalities) against regulatory milestones and customer buying cycles.
Each tool is designed to be applied rather than merely observed: procurement teams can model supplier consolidation vs. dual‑sourcing; R&D and quality functions can prioritize alloy qualifications; finance can stress‑test ROI under varying compliance cost trajectories.
Competitive Landscape: Dimensions of Advantage (Not Predictions)
PW Consulting examined incumbent suppliers and challengers across six key competitive dimensions—manufacturing scale, channel reach, certification breadth, BOM control, OEM relationships, and post‑sale service. Rather than publish firm‑by‑firm revenue forecasts, we map where each player's durable advantages lie and which variables determine future design wins.
- Manufacturing scale and vertical integration: Suppliers with tight control of critical subcomponents and in‑house finishing enjoy lower unit costs and faster qualification cycles for bespoke material grades.
- Certification and hazardous‑area expertise: Firms that consistently hold ATEX and IEC certifications reduce customer qualification friction in energy and chemical segments.
- Channel and system‑level relationships: Companies embedded in OEM bill‑of‑materials or with long‑standing distributor partnerships capture disproportionate replacement and spec‑write opportunities.
- Service and lifecycle programs: Warranty, calibration, and spare‑parts responsiveness are turning into secondary moats for suppliers competing on total cost of ownership.
Illustrative vendor context (selection): Omron’s mid‑2025 refinement of its electrode‑based portfolio signals a focused move to broaden operating environments; Endress+Hauser’s established process‑industry relationships emphasize reliability and service; specialized vendors emphasize customizable multi‑point float solutions that are attractive to industrial integrators. These observations are directional and demonstrate the types of competitive edges that matter—but the report preserves detailed firm‑level scenario outputs to clients only.
Regulatory and Materials Considerations That Drive Specification Choices
Two technical realities are reshaping procurement and engineering specifications in 2026:
- Electrode and float assemblies must satisfy both electrical‑safety and electromagnetic compatibility standards in industrial settings, raising testing and documentation requirements during supplier onboarding.
- Material selection (stainless grades or titanium) is increasingly tied to lifecycle costs and risk allocation; the procurement decision now routinely includes long‑run corrosion models and end‑of‑life treatments in tender documents.
Consequently, supply‑chain decisions are frequently being made by cross‑functional committees rather than single‑function buyers—raising the value of detailed BOM and compliance datasets when negotiating supply agreements.
Research Methodology and Sources of Competitive Insight
PW Consulting applies a layered triangulation methodology to ensure fidelity between observed market behavior and our quantitative outputs. Core elements include:
- Patent and technical literature mining to identify emerging sensing modalities and material innovations.
- Proprietary supplier mapping built from customs‑level trade flows, audited supplier disclosures, and targeted expert interviews across manufacturing, procurement, and test labs.
- Field audits and reverse BOM logic applied to representative product families to estimate material mixes and process steps used in high‑volume SKU groups.
We combine these data streams with multi‑round expert elicitation and internal benchmarking to generate calibrated estimates of lead times, cost buckets, and margin sensitivities. Our approach emphasizes reproducibility and defensibility: each non‑public datapoint in the model is cross‑checked through a minimum of two independent sources prior to inclusion.
Strategic Playbook for 2026
Based on our synthesis, PW Consulting recommends three priority moves for corporates and financial sponsors considering capital deployment in the float level switch space this year:
- Prioritize suppliers with demonstrable certification pathways and material qualifications; certification speed will be a gating factor for uptake in regulated end markets.
- Negotiate BOM transparency clauses and joint‑cost improvement programs to capture upside from yield and material substitutions without forfeiting intellectual property control.
- Structure investments to preserve optionality across sensing technologies—capacitive, vibrating fork, and magnetic floats are complementary in many portfolios, and hedging across modalities reduces single‑technology exposure.
These are strategic levers rather than prescriptive checklists; the right combination depends on an organization’s appetite for integration, regulatory exposure, and channel reach.
Implications for Capital Allocation
The market’s steady 4.5% CAGR masks pockets of faster change where certification, material substitution, and digital integration create outsized value. In 2026, allocating capital into suppliers or integrators that can shorten qualification cycles, demonstrate BOM clarity, and provide lifecycle services will likely produce superior returns compared to pure volume plays. Time to implement matters: longer procurement cycles and increasing compliance hurdles mean early movers capture design wins that set the replacement cadence for years.
Further Intelligence and Next Steps
PW Consulting’s full report contains the granular distribution maps, supplier scorecards, BOM templates, and scenario playbooks necessary to execute on the strategies above. To access the complete dataset, client‑grade models, and our full set of supplier profiles, please visit our report page: Access the full Float Level Switch Market report .
Concluding Perspective
2026 is a year where tactical execution and informed capital allocation intersect. The float level switch market offers stable growth, but the winners will be those who pair commercial reach with technical rigor—suppliers who secure certifications, optimize BOMs, and shorten OEM qualification cycles. PW Consulting’s analysis equips decision makers with the strategic lenses and operational tools to act now and capture emerging value without disclosing the granular segmentation intelligence reserved for our full report clients.
For detailed analysis of this topic, please visit the official page: Float Level Switch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


