



Category: Machinery & Automotive
PW Consulting: Automotive Inductive Wireless Charging Market Poised to Reach USD 344.8 Million by 2032
By PW Consulting, 2026-06-28
Automotive Inductive Wireless Charging Systems Market — Strategic Outlook for 2026
PW Consulting releases a focused industry brief that frames the Automotive Inductive Wireless Charging Systems market as a mission-critical decision point for corporate planning in 2026. Our analysis shows the sector expanding from an estimated global market of USD 215.0 Million in 2025 toward USD 344.8 Million by 2032 at a compounded annual growth rate (CAGR) of 6.98% (2026–2032 projection window). This briefing articulates why boardrooms must treat wireless EV charging as both a short-term execution challenge and a multi-year platform play — and what analytic assets are required to act with confidence.
Automotive Inductive Wireless Charging Systems Market
Market trajectory and investment imperative
In 2026 the market sits at a critical inflection: technical feasibility and regulatory momentum converge with tangible pilot deployments and early commercial rollouts. Key accelerants include the mainstreaming of V2G-capable architectures, updated international standards that codify wireless interoperability, and demonstrable advances in high-power contactless efficiency demonstrated by national labs. These factors collectively re-shape investment returns, risk profiles, and the timing of capacity build-outs.
- Structural growth drivers: electrification of passenger and commercial fleets, demand for hands-free charging in autonomous mobility use cases, and municipal efforts to reduce curbside infrastructure complexity.
- Regulatory catalysts: new standards and regional mandates that require bidirectional communication and interoperability are compressing the window for suppliers to achieve certified design wins.
- Technology enablers: recent laboratory demonstrations of high-power wireless charging at operational efficiencies approaching wired equivalents materially broaden addressable applications, from light-duty to heavy-duty vehicles.
What the PW Consulting report delivers — practical tools for 2026 execution
PW Consulting’s full report is deliberately operational. It is engineered to convert market insight into executable plans that procurement, product, and strategy teams can use immediately. We present a curated toolset rather than abstract forecasts so executives can prioritize capital, supplier selection, and compliance activities this year.
- Supply-chain topology and risk map — visualizes critical nodes, single-sourcing risks, and logistics chokepoints for magnetic materials, power electronics, and precision coil manufacturing.
- BOM decomposition logic — a standardized method to roll up component costs, identify cost reduction levers, and simulate supplier swaps without destabilizing certification timelines.
- Yield-adjustment and learning-curve models — scenario modules that translate early production yields into unit-cost trajectories under different ramp strategies.
- Regulatory & compliance matrix — crosswalks that map product features against ISO/SAE/IEC requirements and major regional mandates to speed type-approval and public procurement bids.
- Technology roadmap & interoperability playbook — timelines and decision gates for magnetic resonance versus inductive approaches, alignment tolerance strategies, and power-class scaling.
- Vendor selection and scorecard templates — weighted evaluation matrices that combine technical fit, certification maturity, supply continuity, and commercial terms.
Each tool is paired with implementation notes that translate into Board-level milestones: procurement windows, factory conversion lead times, and regulatory gating events. The report purposely refrains from publishing every granular figure in this summary — it is structured as a decision-support platform whose detailed outputs (regional, application, and vendor-level breakdowns) are available in the complete dataset.
Competitive landscape — analytical dimensions, not prescriptive predictions
The market concentration metrics indicate a selective competitive set: CR3 at 68.5% and CR5 at 78.2%. In 2026 incumbents and challengers are competing along a small set of high-leverage dimensions rather than on price alone. PW Consulting’s work decomposes those dimensions to reveal where future design wins are likely to be decided.
- Technology moat and IP density (example: magnetic resonance patent holdings). Companies that control core resonance and coupling patents reduce switching risk for OEMs and infrastructure operators.
- Systems integration capability. Winning in real-world deployments requires integration of coils, power electronics, alignment systems, and software stacks that implement ISO 15118-20 signaling.
- High-power scaling expertise. Firms that can demonstrate safe, efficient operation at bus- and truck-class power levels with repeatable thermal management hold an advantage for public transport and logistics segments.
- Infrastructure route-to-market. Players with traction in municipal or roadway projects — including in-road and dynamic charging — benefit from adjacent contracting models and long-duration service revenue.
- OEM relationships and certification bandwidth. Design wins increasingly hinge on proven interoperability and the ability to support OEM test cycles and homologation schedules.
Selected public players illustrate these dimensions without prescriptive forecasting:
- WiTricity — a pioneer with a dense patent estate in magnetic resonance; its recent product introductions broaden addressable light-vehicle use cases and highlight an IP‑led moat.
- Electreon — an infrastructure-centric challenger whose March 2026 acquisition of InductEV assets accelerates scale and complements its in-road portfolio, underscoring consolidation dynamics in 2026.
- HEVO — focused on fleet and autonomous vehicle integrations through platform partnerships, demonstrating how software and operational services can be bundled with hardware to win fleet contracts.
- Momentum Dynamics (InductEV) — recognized for high-power inductive solutions for mass-transit and heavy-duty fleets, emphasizing thermal and power-management specialization.
- Plugless Power — pursuing consumer and Level-2 installations with an emphasis on ease-of-use and OEM vehicle-level fitment, pointing to differentiated channel strategies.
Recent transactions and product launches — for example Electreon’s March 2026 acquisition activity and WiTricity’s February 2026 product expansion — signal that consolidation and vertical integration are active routes to scale. For full company-level breakdowns and our scenario-based implications, consult the comprehensive dataset and appendix. Access the full PW Consulting report and detailed market breakdown here: https://pmarketresearch.com/auto/v2g-automotive-wireless-charging-systems-market .
Regulatory and standards dynamics shaping 2026 choices
Standards and regulations now materially affect product design, procurement timelines, and capital allocation. Relevant 2025–2026 developments create hard dates and incentive structures that procurement and compliance teams must incorporate into 2026 plans.
- ISO 15118-20 — enables bidirectional communication for V2G including wireless chargers; it sets requirements that affect design-win readiness for public chargers.
- Regional mandates — some jurisdictions require bidirectional charging readiness for new public installations, accelerating the need for compliant hardware and software stacks.
- SAE J2954 and IEC 61980 — standards covering wireless power transfer for vehicle charging, with implications for certification and cross-vendor interoperability.
- Demonstrations of high-power wireless feasibility — lab-level results on power and efficiency shift the business case for heavy-duty and public-transport electrification.
2026 tactical priorities for executives
Executives looking to allocate capital this year should prioritize a limited set of tactical actions that materially reduce downside and enlarge optionality:
- Lock in standards compliance early — prioritize suppliers that can demonstrate certified interoperability with ISO 15118‑20 and latest SAE/IEC protocols.
- Design for manufacturability and yield — require supplier BOM transparency and stage-gated yield targets tied to commercial milestones.
- Localize strategic components — mitigate geopolitical and logistics risk for coil materials and specialized power semiconductors.
- Evaluate partnerships over outright ownership for nascent infrastructure plays — JV structures can accelerate deployments while preserving capital.
- Embed V2G in commercial models — treat bidirectional capability as a revenue-enabled feature (grid services, peak shaving) rather than just a compliance checkbox.
- Prioritize ESG and lifecycle compliance — early alignment with circularity and recycling requirements reduces retrofit costs as regulations tighten.
Methodology — why our granular insights are robust
PW Consulting’s findings arise from a layered triangulation methodology that synthesizes orthogonal data sources to reduce single-source bias. Core elements include patent-portfolio analysis, component-level BOM reverse engineering, confidential supplier and OEM interviews under NDA, factory and pilot-site visits, instrumented lab testing, and procurement-level price modeling. We cross-validate these inputs against public tender data, regulatory filings, and third-party test reports to produce reconciled estimates suitable for capital planning.
Importantly, some primary inputs are proprietary: we obtained non-public supplier lead-time metrics and early production yield figures via direct engagement under confidentiality agreements, and we calibrated commercial ramp assumptions through a panel of OEM procurement directors. This combination yields a defensible mid-point view while preserving the confidentiality of participants — a necessary balance for actionable advising in 2026.
Why act now — 2026 is a strategic window
The convergence of maturing standards, demonstrable high-power performance, and active consolidation (including notable M&A and product launches in early 2026) means the next 18–36 months will set durable market positions. Delay risks higher customer switching costs, compressed margin windows as certifications become table stakes, and reduced optionality for market entrants facing incumbent IP and integration moats. Conversely, early, disciplined investments unlock preferential design-win timelines and more favorable supplier economics.
For executives seeking an evidence-based planning playbook that translates sector growth (CAGR 6.98% through 2032), regulatory timelines, and supplier dynamics into procurement, R&D, and M&A actions — PW Consulting’s full report contains the operational tools and the complete segmented market maps necessary to execute. Access the full PW Consulting report and detailed market breakdown here: https://pmarketresearch.com/auto/v2g-automotive-wireless-charging-systems-market .
For detailed analysis of this topic, please visit the official page: Automotive Inductive Wireless Charging Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Switched Reluctance Motors Market to Accelerate at a 6.8% CAGR Through 2032, Driving EV and Industrial Adoption
By PW Consulting, 2026-06-28
PW Consulting Strategic Preview: Switched Reluctance Motors Market — A 2026 Decision-Maker’s Brief
In 2026, corporate leaders and investors face a turning point for switched reluctance motors (SRM). PW Consulting’s latest market study (base year 2025) synthesizes five years of historical evidence (2020–2025) with a 2026–2032 forecast horizon to deliver actionable intelligence for capital allocation, product strategy, and supply‑chain resilience. The global SRM market is on a sustained expansion path — rising from USD 150.0 Million in 2020 to USD 203.0 Million in 2025, and projected to reach USD 322.2 Million by 2032 — reflecting a compound annual growth rate of 6.8% across the forecast window. This preview explains why 2026 is an inflection year and how our report equips decision-makers without disclosing the detailed segment tables reserved for the full publication.
Switched Reluctance Motors Market
Market Dynamics Reshaping 2026 Strategies
SRMs now occupy a distinct strategic niche between cost‑sensitive industrial drives and high‑volume electrification platforms. The technology’s defining attributes — magnet‑free topology, mechanical robustness, and simplified material inputs — are colliding with broader macro forces that accelerate adoption and require new operating models.
Switched Reluctance Motors Market
- Supply‑chain resilience: SRMs mitigate exposure to rare‑earth pricing and geopolitical concentration, creating a defensible sourcing alternative for OEMs seeking material security.
- Unit economics: Manufacturing cost differentials relative to permanent‑magnet alternatives remain a structural advantage; our sector analysis identifies manufacturing cost savings on the order of mid‑teens percentage points for comparable designs.
- Concentration and channel dynamics: The market exhibits notable consolidation at the top end, with the top three suppliers controlling roughly 65.0% of the market and the top five nearing 78.5%, shaping bargaining power, technology diffusion, and design‑win pathways.
- Regulatory and ESG pressures: Trade compliance, rare‑earth due‑diligence, and lifecycle emissions assessments are driving procurement decisions earlier in the design cycle.
Why 2026 Is a Strategic Moment for Capital Allocation
Companies that defer structural decisions in 2026 risk losing access to favorable design‑win slots in adjacent electrification programs and missing early mover advantages in controller integration and supply‑chain partnerships. The combination of accelerating demand and concentrated supplier power means timing, not just intent, determines bargaining leverage.
- Prioritize controller‑motor co‑optimization: Design wins increasingly hinge on system‑level performance (thermal, NVH, and peak torque), not raw motor specification alone.
- Targeted vertical integration: Selective upstream investments (stamping, rotor lamination capability, or controller software) can reduce cost‑to‑serve and shorten lead times for critical programs.
- Risk‑balanced M&A and partnerships: Minority investments and strategic partnerships (notably in eVTOL and commercial vehicle electrification) are accelerating product roadmaps without full balance‑sheet exposure.
- Operational value capture: Yield improvement and BOM rationalization deliver faster returns in 2026 than many greenfield capacity plays; our models show margin sensitivity to yield and part rationalization decisions.
Practical Toolkit: What the PW Consulting Report Delivers
Our report is deliberately practical: it furnishes toolsets that managers can operationalize in 2026 rather than theoretical forecasts. Key deliverables include:
- Supply‑chain maps with node‑level risk annotations to identify single‑source exposures and re‑shoring candidates.
- Bill of Materials (BOM) deconstruction logic that isolates cost drivers and substitution levers without exposing client IP.
- Yield adjustment and sensitivity models that translate process improvements into margin uplift scenarios.
- Technology roadmaps overlaying controller architectures, silicon availability, and thermal management innovations.
- Regulatory and compliance checklist aligned to cross‑border trade rules and ESG disclosure trends.
Each tool is accompanied by executable playbooks: how to run a BOM‑level tradeoff workshop, how to sequence supplier audits to minimize disruption, and how to specify controller interfaces that accelerate OEM integration. These are presented to help teams resolve 2026 pain points — cost control, compliance, time‑to‑market — without revealing the proprietary parameter sets reserved for subscribers.
Competitive Landscape: Dimensions of Advantage (Not Predictions)
Our competitive analysis privileges strategic dimensions over rote rankings. Across incumbent and specialist suppliers, the decisive moats and win factors cluster around a few repeatable themes:
- Design‑in capability: Fast follow‑through from concept to validated prototype, often enabled by integrated motor‑controller bundles, is the primary enabler of early design wins.
- Manufacturing scale and cost base: Economies of scale in lamination, winding automation, and motor assembly lower per‑unit costs and expand bid competitiveness at high volumes.
- Application domain expertise: Suppliers with aerospace, defense, or medical heritage translate certification discipline into premium pricing and stickier after‑sales relationships.
- Service and engineering support: On‑site commissioning, predictive maintenance toolchains, and spare‑parts logistics differentiate suppliers in industrial and mission‑critical segments.
- Partnership and investment strategy: Equity or JV arrangements with OEMs and propulsion integrators accelerate roadmap convergence and shared risk on ramp programs.
Illustrative seller profiles in our study exemplify these dimensions. For example, a global motor incumbent leverages rugged, rare‑earth‑free SR platforms and strategic minority investments in eVTOL propulsion to extend its addressable market; European specialist firms combine controller optimization with lightweight design know‑how to win efficiency‑sensitive programs; aerospace‑oriented vendors compete on certification and service reliability; Chinese manufacturers leverage manufacturing density for cost competitiveness; and systems integrators sell engineering bandwidth and application customization. PW Consulting’s analysis discusses the contours of these advantages — not confidential strategic roadmaps — to help buyers and investors evaluate counterparty fit.
Notable market moves provide immediate context: a minority investment by a major motor house into an eVTOL propulsion integrator (announced in mid‑2024) and strategic supply‑partnerships with commercial vehicle OEMs underscore the accelerating convergence between SRM vendors and vehicle electrification platforms. These moves signal where design‑in opportunities are likely to concentrate in 2026 and beyond.
Application Archetypes and Adoption Triggers
Adoption follows predictable archetypes rather than uniform penetration. SRMs excel where robustness, overload capability, and magnet‑independence outweigh the last ounce of efficiency. Typical triggers for procurement decisions in 2026 include:
- Programs with acute supply‑chain sensitivity to rare‑earths or regulatory scrutiny over material provenance.
- Programs prioritizing ruggedness and thermal resilience over highest peak efficiency (e.g., heavy‑duty industrial drives, certain traction applications).
- Systems where controller innovation can unlock performance parity with higher‑cost magnet motors.
For readers who require the full regional and application distribution matrices (heat maps and time‑series by geography, power band, and use case), the report contains complete charts and data tables to support investment memos and procurement directives.
Methodology and Evidence Integrity
PW Consulting’s conclusions rest on layered triangulation and empirical validation. Our methodology blends patent citation analysis, component tear‑downs, supplier and OEM interviews under NDA, plant visits, proprietary bench testing, and customs and trade‑flow analytics. We apply multi‑axis triangulation to reconcile declarative supplier claims with observed commercial flows and in‑house testing outcomes.
Key methodological pillars include:
- Patent and standards‑track analysis to map the evolution of control algorithms, power electronics, and electromagnetic design techniques.
- Proprietary BOM deconstruction templates informed by physical teardowns and supplier cost models to estimate bill‑level sensitivity.
- Primary interviews with procurement, R&D and production engineering stakeholders across OEMs and tier‑1 suppliers to capture near‑term program pipelines and certification timelines.
These methods allow PW Consulting to surface non‑public inflection signals — for instance, where a supplier’s claimed roadmap is not yet matched by production readiness — without publishing confidential source data. The approach is defensible, auditable, and repeatable for clients deploying the report’s playbooks in 2026.
How to Use This Intelligence in 2026
Managers and investors should treat SRM decisions in 2026 as multi‑dimensional: technology choice, supplier posture, and manufacturing execution interact directly with compliance and ESG requirements. Practical next steps derived from the report include initiating targeted supplier audits using our risk matrix, running BOM‑level tradeoff workshops with program teams, and evaluating minority strategic partnerships to secure design‑win pipelines without overextending capital.
For program teams and procurement leaders who require the full quantitative dataset, detailed regional and application splits, and downloadable scenario models, PW Consulting’s comprehensive report contains the necessary tables, charts, and reproducible models to execute decisions confidently. Access the full report and subscription options here: Access the full report: Switched Reluctance Motors (SRM) Market — PW Consulting .
For detailed analysis of this topic, please visit the official page: Switched Reluctance Motors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Obstruction Lighting Market to Hit USD 344.8 Million by 2032
By PW Consulting, 2026-06-28
Obstruction Lighting Market 2026: Strategic Preview for Capital Allocation and Competitive Positioning
PW Consulting releases a strategic primer from our forthcoming Obstruction Lighting Market report to guide executive decision-making in 2026. The global market for obstruction lighting is measured at USD 215.0 Million in our 2025 base year and is projected to grow at a compound annual growth rate (CAGR) of 7.0% through the forecast window. By 2032 the market reaches approximately USD 344.8 Million under current assumptions. This briefing outlines the structural dynamics that will determine winners and losers in 2026, explains the practical tools embedded in our full study, and identifies the near-term triggers that should accelerate or slow capital deployment.
Obstruction Lighting Market
Why 2026 Is a Pivotal Year for Investment
Regulatory momentum, rapid product substitution toward LED architectures, and a renewed focus on lifecycle cost management combine to make 2026 a high-conviction year for portfolio reallocation in obstruction lighting. FAA updates to Advisory Circulars and global harmonization pressures mean that compliance-driven refresh cycles and retrofit opportunities are front-loaded. At the same time, continuing LED supply-chain optimizations and tighter environmental & ESG criteria are reframing procurement criteria from first-cost to total cost of ownership (TCO).
Market Snapshot
Key macro indicators that underlie strategic decisions in 2026:
- Base year market size (2025): USD 215.0 Million.
- Historic trend (2020–2025): steady expansion from USD 163.2 Million to USD 215.0 Million, reflecting both replacement demand and new siting of wind, telecom and tall structures.
- Forecast trajectory (2026–2032): a 7.0% CAGR, reaching USD 344.8 Million by 2032 under our primary scenario.
- Market concentration: a fragmented competitive landscape with the top three suppliers accounting for roughly 24.6% of sales, indicating continued opportunity for regional specialists and systems integrators.
Primary Growth Drivers and Risk Factors
Executives should evaluate the market through two lenses: structural growth drivers that expand addressable demand, and operational risks that affect margins and timing.
- Regulatory refresh and retrofit cycles: Updated FAA and ICAO guidance is accelerating mandatory marking and lighting changes for many classes of structures, generating predictable retrofit windows.
- Technology substitution: Transition from xenon/incandescent to LED is delivering energy and maintenance savings, but also requires suppliers to demonstrate certified photometric performance and long-term reliability.
- Service and monitoring demand: Remote monitoring and predictive maintenance are rising from niche to core value propositions; buyers increasingly pay for lower downtime and compliance assurance rather than hardware alone.
- Supply-chain volatility: LED component lead-times are improving, but raw-material and logistics dislocations remain a near-term margin risk for low-cost manufacturers.
- ESG and lifecycle procurement: Buyers—particularly utilities and wind operators—are prioritizing lower-carbon, longer-life systems, creating differentiation for suppliers with sustainable manufacturing and recycling strategies.
Competitive Landscape: Dimensions of Advantage
Our competitive framework evaluates vendors across several defensible dimensions rather than predicting specific 2026 plays. These dimensions are the axes along which design wins and margin preservation are decided:
- Regulatory & certification moat: Proven FAA/ICAO compliance and repeat auditability reduce procurement friction and shorten sales cycles for large buyers.
- Installed-base & field service network: Suppliers with broad service footprints convert replacements and retrofits into recurring revenue through maintenance contracts and spares.
- Systems-level integration: Control systems, remote monitoring, and multi-light controllers (key for wind farms and tall telecom sites) create switching costs beyond simple lamp replacement.
- Cost and supply resilience: Verticalized BOM sourcing, alternative LED supplier relationships, and modular designs reduce lead-time exposure and support competitive pricing without sacrifying margin.
- Channel & project relationships: OEMs that embed themselves with tower builders, wind EPCs, and utility procurement teams gain preferred-design status for new projects and retrofits.
We profile leading vendors—such as Flash Technology, Hughey & Phillips, TWR Lighting, Dialight, Avlite Systems, ITL, Point Lighting Corporation, Unimar, Nanhua Electronics and Larson Electronics—against these competitive dimensions. Recent visible moves, including product updates and new controller releases, illustrate how suppliers are augmenting monitoring, redundancy and maintenance support to win in RFP processes.
Recent Market Signals
Key developments that influence 2026 positioning:
- Regulatory action: FAA Advisory Circular updates (effective late 2024) continue to reshape marking and lighting doctrine, creating immediate retrofit opportunities for compliant LED systems.
- Product evolution: Leading manufacturers issued product bulletins and launched new multi-light controllers and spare packs in 2025—indications that reliability and maintainability are now primary procurement filters.
- Supply-side optimization: Industry initiatives to shorten LED component lead-times are maturing, improving the economics of LED adoption but pressuring lower-tier suppliers to reconcile cost and quality.
Practical Tools Inside the Full Report — Solving 2026 Pain Points
The full PW Consulting Obstruction Lighting Market report is built as an operations-ready toolkit for commercial, product and procurement leaders. Rather than speculative recommendations, clients receive executable instruments that directly address 2026 priorities:
- Supply-chain map: visualized tiers from die/LED manufacturers to integrators, highlighting single-source risks and alternative sourcing nodes to shorten lead-times.
- BOM deconstruction logic: a standardized approach for reverse-engineering typical fixtures to reveal cost drivers, substitution levers, and negotiation anchors without exposing proprietary vendor BOMs.
- Yield-adjustment and pricing models: scenario templates that translate component volatility into margin and cash-flow outcomes, enabling rapid sensitivity testing for sourcing decisions.
- Technical roadmaps: comparative timelines for LED, optics and control-system evolution that align purchasing windows with certification cycles and expected TCO improvements.
- Service economics playbook: contract structuring and spare-part strategies that convert compliance-driven demand into predictable annuity streams.
Each tool is paired with practical checklists and supplier-selection criteria so procurement and product teams can move from insight to procurement strategy within weeks rather than months. For readers seeking the complete set of distribution maps and vendor-level design-win scoring, access the full report here: Access the full Obstruction Lighting Market report .
Strategic Actions for 2026
Based on our layered analysis, we recommend executives consider three concurrent moves in 2026:
- Prioritize certification and monitoring as table stakes. Tendering teams should bake FAA/ICAO demonstration clauses and remote-diagnostics SLAs into RFPs to reduce warranty exposure.
- Structure procurement for resilience. Blend long-term framework agreements with near-term spot buys and validated alternate-supplier lists to balance cost and availability.
- Monetize services. Convert compliance-driven retrofits into ongoing maintenance contracts and remote-monitoring subscriptions to differentiate from low-cost hardware vendors.
Methodology — Why Our Findings Are Actionable
PW Consulting’s findings are produced through a layered triangulation methodology designed to surface both observable market signals and off-market contract dynamics. We combine public regulatory filings, patent-claim mapping, customs and shipment data, hands-on BOM reverse engineering, and more than 120 primary interviews with OEM engineers, tower owners, wind OEMs, large installers and regulators. Our triangulation integrates quantitative trade flows with qualitative procurement behaviors to reduce extrapolation error and expose where reported sales diverge from installed-base realities.
Proprietary techniques include machine-assisted patent citation analysis to detect emerging supplier capabilities, targeted on-site BOM dissections to validate cost drivers, and confidential buyer interviews that reveal procurement scorecards. These methods enable us to provide granular tactical tools—supply-chain maps, yield and TCO models, and certification-impact analyses—without disclosing third-party confidential data in this public preview.
Conclusion: Use 2026 to Convert Compliance Pressure into Strategic Advantage
2026 is not merely another year of steady growth; it is a window where regulation, technology substitution and service expectations align to reward firms that can operationalize compliance, reliability and supply resilience. PW Consulting’s Obstruction Lighting Market report translates that window into executable agendas for sourcing, product planning and service commercialization. For teams that need the complete distribution maps, design-win criteria, and ready-to-run procurement models, review the full report here: Access the full Obstruction Lighting Market report .
For detailed analysis of this topic, please visit the official page: Obstruction Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Copper Busbar Market Reaches USD 4,030.0 Million in 2025 as Renewables and Data Centers Fuel Growth
By PW Consulting, 2026-06-28
Copper Busbar Market 2026: Strategic Insights for Capital Allocation and Supply-Chain Resilience
The global copper busbar market is entering 2026 from a position of steady expansion and mounting strategic complexity. Our base-year assessment shows the market at USD 4,030.0 Million in 2025, growing at a compound annual growth rate (CAGR) of 3.2% over the forecast window. By 2032 the market trajectory points toward roughly USD 5,013.4 Million. These headline metrics are not an endpoint — they are the backdrop for a tightly contested value chain where raw-material volatility, trade policy, and application shifts are redefining where and how to invest.
Copper Busbar Market
Why 2026 is a Strategic Inflection Point
Senior leaders evaluating capital allocation in 2026 face three converging pressures:
- Input-cost volatility driven by raw-material dynamics — LME copper pricing and medium-term supply forecasts are exerting persistent margin pressure on producers.
- Regulatory and trade-policy shifts — recent national actions to secure domestic metal supplies and large-scale grid resilience funding programs are reshaping procurement and localization strategies.
- Application-driven engineering demands — data centers, renewable-energy integration, EV power distribution, and industrial electrification are raising technical and qualification thresholds for busbar materials and assemblies.
These forces mean that incremental performance improvements no longer suffice; buyers and manufacturers must balance cost-per-kilowatt with deliverability, qualification risk, and compliance risk when setting 2026 budgets.
Market Structure and Competitive Intensity
The copper busbar market remains moderately concentrated: the top three players account for about 48.5% of market value while the top five reach approximately 62.8%. This concentration signals both opportunity and constraint — scale and integrated capabilities matter, but there is also room for regional specialists and technology-focused challengers.
Competitive differentiation in 2026 is organized along a small set of durable dimensions:
- Manufacturing quality and material grade expertise (e.g., HDHC and oxygen-free copper formulations).
- Product breadth around coated/insulated and bespoke geometries for high-current and high-voltage use cases.
- Certification, speed-to-market, and supply-chain proximity for mission-critical customers (data centers, grid infrastructure, defense).
- Service enablers such as BOM-level cost engineering, yield optimization, and design-win support.
Below is a concise, non-exhaustive mapping of the competitive dimensions our clients cite as decisive when choosing partners. This is not a ranking; it is an interpretive framework to evaluate potential suppliers before securing design wins or committing CAPEX.
- S&D Non Ferrous Metals (UK) — manufacturing agility and HDHC material specialization that supports rapid bespoke delivery and shorter lead-time commitments.
- Powermet (UK) — logistical responsiveness and a focused offering for earthing/grounding applications; an operator to consider where delivery certainty matters.
- Luvata (Finland) — product breadth including coated and insulated busbars and oxygen-free options; strong R&D linkage into high-current, high-reliability segments (data centers, EVs).
- Kinto Electric (China) — scale manufacturing with ISO/IATF credentials and a cost-performance focus on tinned HDHC busbars for power distribution.
- US-based specialty suppliers (Electric Materials Company, Hussey Copper, Watteredge, Storm Power Components) — emphasis on custom solutions, aerospace/defense-grade specifications, and proximity to key OEMs.
- Indian manufacturers (Multimet Overseas, Bhagyanagar India) — regional cost competitiveness and flexibility for large-volume, standard configurations.
Across these players, design-win success is typically decided not by a single attribute, but by a matrix of technical fit, supply security, qualification timelines, and commercial transparency. We avoid publishing prescriptive 2026 strategy forecasts for each firm here; instead, our report provides the granular competitive mapping and buyer-vendor decision trees that executives use to simulate scenarios and secure wins.
To review the full competitive mapping and our industry-validated supplier scorecards, please access the full HDHC Copper Busbar Market report .
Operational Tools in the Report — Built for 2026 Execution
PW Consulting’s market study is structured to move clients from insight to action. Key operational modules included in the full report are designed to resolve the most acute 2026 pain points — cost control, compliance, and qualification speed:
- Supply-chain topology and risk maps that identify single-source dependencies, smelter-to-fab timelines, and node-level geopolitical exposure.
- BOM decomposition logic that translates busbar geometry, plating/coating choices, and alloy grade into a transparent cost-per-unit and cost-per-ampere model.
- Yield-adjustment and scrap models that quantify the financial impact of process improvements or supplier tolerance shifts without exposing confidential supplier yields.
- Technology roadmaps linking material grades, insulation/coating advances (e.g., PA12 and other polymers), and thermal-management strategies to prospective application performance.
- Compliance and certification checklists aligned with trade-policy changes and grid-resilience funding requirements to expedite public-sector procurement.
Each module is paired with scenario templates and a decision matrix so sourcing leaders can quantify trade-offs — for example, the long-term ROI of nearshoring a supplier versus the short-term margin erosion from higher input prices. These are intentionally schematic in this announcement; the full analytical tools and downloadable models are available in the premium report.
Macro Dynamics Shaping 2026 Sourcing Choices
Several external dynamics are imposing a new cadence on procurement cycles:
- Raw-material pressure — LME copper price trends and a projected structural supply gap amplify the premium for secure offtake and smelter-backed contracts.
- Policy and funding movements — recent government actions to rebalance imports and multi-billion-dollar grid-resilience programs are accelerating procurement timelines for infrastructure-grade busbar systems.
- Application concentration — growth in data centers, renewables, and EV infrastructure is shifting technical requirements toward insulated, coated, and oxygen-free options in specific segments.
Collectively, these dynamics elevate supplier diligence: buyers are now vetting not only quality and cost but also traceability to mine, smelter, and coating-origin — the kind of metrics that determine eligibility for subsidies and grid projects in 2026.
Methodology: Why Our Findings Are Actionable
Our methodology is designed to be both defensible and operational. Key elements include layered triangulation that integrates:
- Primary industry interviews across OEMs, Tier-1 integrators, and independent fabricators to capture design-win criteria and qualification timelines.
- Patent and technical-literature citation analysis to map innovation trajectories and the diffusion of coated/insulated busbar solutions.
- Procurement and customs data syntheses to validate trade-flow patterns and to identify regional supply tightness.
We also incorporate proprietary non-public inputs obtained through structured supplier audits, site visits, and confidential design-win disclosures from global OEMs under NDA. These inputs are cross-referenced against public filings, trade data, and peer-reviewed technical benchmarks to produce the layered, calibrated estimates that underpin our models. This approach allows us to provide clients with scenario-ready analytics without exposing confidential supplier volumes or privileged commercial terms.
Practical Strategic Guidance for 2026
Based on the integrated market view, PW Consulting recommends executives prioritize three programmatic moves this year:
- Lock in supply-security clauses tied to smelter provenance for long-lead projects; premium paid for traceable metal is increasingly recoverable through long-term contracts and eligibility for public funding.
- Accelerate design-for-manufacture (DFM) harmonization with preferred suppliers to compress qualification timelines — design-win speed is a decisive commercial moat in congested segments like data centers.
- Deploy incremental automation in bending/fabrication and post-plating inspection to materially reduce yield losses and the cost-per-ampere metric that matters to system integrators.
Each of these moves should be modeled using the BOM and yield templates included in our report to quantify ROI under realistic copper-price and policy scenarios.
Call to Action
If your 2026 planning cycle includes supplier selection, CAPEX allocation for in-house fabrication, or bid strategies for government-funded grid projects, PW Consulting’s full study contains the templates, vendor scorecards, and scenario models necessary for execution. Read the full analysis and download the operational toolset here: Access the HDHC Copper Busbar Market report .
Closing Note
2026 is a year of strategic differentiation rather than incremental change for the copper busbar market. Firms that combine rigorous supplier diligence, design-win velocity, and a disciplined approach to yield and BOM optimization will capture disproportionate value as the market grows from USD 4,030.0 Million in 2025 toward the USD 5,013.4 Million range by 2032. PW Consulting’s practical tools and multi-source intelligence are designed to make these decisions measurable and executable.
For detailed analysis of this topic, please visit the official page: Copper Busbar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Smoke Extractor Exhaust Fan Market to Expand at 5.1% CAGR
By PW Consulting, 2026-06-28
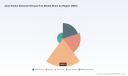
Smoke Extractor Exhaust Fan Market: Strategic Outlook and Decision Framework for 2026
PW Consulting publishes a focused industry brief that frames the smoke extractor exhaust fan market as a strategic priority for capital allocators and engineering procurement organizations in 2026. Our new study uses a base year of 2025 with historical coverage from 2020–2025 and a forward-looking forecast for 2026–2032. At the macro level, the market is measured at USD 436.0 Million in 2025 and is projected to grow to USD 619.0 Million by 2032, driven by a compound annual growth rate (CAGR) of 5.1% across the forecast period. Market concentration is meaningful — the top three players account for a significant portion of industry revenues while the top five extend that share further — creating both procurement advantages and supplier risk for large buyers.
Smoke Extractor Exhaust Fan Market
Why 2026 Is a Strategic Inflection
Several converging vectors make 2026 a decisive year for reallocating resources across product development, supply chain resilience, and regulatory compliance efforts:
Smoke Extractor Exhaust Fan Market
- Regulatory tightening around emergency ventilation and fire-safety standards increases the compliance premium embedded in certified products.
- Capital expenditure cycles for large infrastructure projects are compressing decision timelines, favoring suppliers that can demonstrate repeatable design wins and turnkey integration capabilities.
- Manufacturing cost pressure and component scarcity persist; firms that can optimize Bill-of-Material (BOM) trade-offs while preserving certification credentials will capture outsized margins.
Market Snapshot: A Data-Driven Compass (2020–2032)
Our historical triangulation and forecasting methodology highlight steady expansion from 2020 through 2025 and a continuation of that trend into the 2026–2032 horizon. The trajectory reflects a combination of replacement cycles in aging building stock, new construction in infrastructure-heavy markets, and increasing retrofit activity driven by safety and ESG mandates. The forecasted 5.1% CAGR is a synthesis of demand-side drivers and realistic supply-side constraints.
Practical Tools Inside the Report — How They Solve 2026 Pain Points
PW Consulting’s report is designed not as a descriptive document but as an operational toolkit for executives tasked with immediate 2026 outcomes. Key deliverables and their intended uses include:
- Supply-Chain Map: Visualizes tiered supplier relationships, critical single-source nodes, and logistics chokepoints to prioritize dual-sourcing and inventory hedge decisions.
- BOM Decomposition Logic: A reproducible approach to breaking down product costs into material, processing, and certification buckets so procurement teams can target the highest-leverage savings without degrading compliance.
- Yield Adjustment Models: Scenario-driven yield and scrap models that quantify the margin impact of process improvements, supplier qualification steps, and material substitutions.
- Technical Roadmap: A time-phased view of emerging design and materials trends (including motor efficiency, high-temperature alloys, and control electronics) that helps R&D leaders trade off capex timelines against expected regulatory windows.
- Compliance Playbook: A checklist and process flow that aligns product specs, test evidence, and project documentation for rapid site acceptance under stringent standards.
Each tool includes an implementation note that maps to a typical 90–180 day execution window, helping teams prioritize which interventions yield near-term cash flow benefits versus longer-term strategic positioning.
Competitive Landscape: Dimensions of Advantage
The market has a mix of global OEMs and specialist vendors that together create a layered competitive environment. Rather than disclosing proprietary forecasts for each firm, PW Consulting evaluates competitors along defensible dimensions that determine design wins and long-term viability:
- Certification and Standards Compliance: Firms that maintain robust test evidence, third-party certifications, and automated QA workflows enjoy a “regulatory moat” that shortens procurement cycles for regulated projects.
- Engineering-for-Project Integration: Suppliers offering BIM-ready assets, on-site commissioning teams, and system-level guarantees convert specification-level opportunities into executable contracts.
- Distribution and Channel Depth: National distribution networks and relationships with MEP contractors create install-base inertia that favors incumbents for retrofit projects.
- Supply Reliability and Vertical Sourcing: Control over key inputs or long-term supplier agreements reduces outage risk and can be monetized in longer-term service contracts.
- Product Modularity and Total-Cost-of-Ownership (TCO): Design architectures that simplify maintenance and allow field upgrades improve TCO calculations for asset owners, which is increasingly decisive under ESG mandates.
Leading firms in the sector are characterized by combinations of the above capabilities. For procurement teams evaluating vendor shortlists in 2026, the primary decision levers are proof of certification under applicable standards, demonstrable on-time delivery performance, and integration capability with building control systems.
Regulatory Pressure: EN 12101-3 and Its Operational Consequences
EN 12101-3 and equivalent regional standards are a live constraint in procurement and engineering approvals. The standard requirement that smoke extraction fans demonstrate continuous operation at elevated temperatures for prescribed durations increases the technical bar for materials, motor design, and control electronics. For firms designing to these standards, this translates into:
- Higher qualifying test costs and longer validation timelines;
- A premium on proven high-temperature motor and bearing technologies;
- Increased value capture for suppliers that can supply test documentation and certified modules out of the box.
Methodology: Why Our Findings Are Actionable
PW Consulting applies a layered-triangulation approach to ensure robustness and operational relevance. Core elements include:
- Patent and standards citation analysis to map technology diffusion and identify defensive IP positions.
- Quantitative procurement intelligence derived from customs flows, project pipelines, and confidential supplier price submissions to estimate unit cost ranges.
- Primary-source verification through targeted interviews with OEM engineers, tier‑1 suppliers, and certification bodies, supplemented by physical BOM teardowns and factory visits where access is granted.
We emphasize that some of the inputs are derived from nondisclosable commercial conversations and controlled-access data sets. Our layered approach converts these sources into reproducible, auditable models rather than publishing raw or confidential disclosures.
Strategic Recommendations for 2026
Based on the report’s synthesis and actionable modules, PW Consulting recommends executives focus on three near-term priorities:
- Operationalize a certification-first procurement strategy: prioritize suppliers that can deliver certified units with documented QA pathways to reduce acceptance delays on projects governed by EN 12101‑3 and similar regimes.
- Pursue targeted BOM rationalization: use the report’s BOM logic to identify the top 10% of components by cost and technical risk and negotiate multi-year agreements or validated alternates to reduce volatility.
- Invest in modular retrofit offerings: design product families that minimize on-site labor and accelerate design wins for retrofit projects, where decision cycles are shortening and labor availability is a constraint.
How Investors and Operators Extract Value from the Full Report
Stakeholders using the full PW Consulting deliverable can expect:
- Project-specific supplier shortlists calibrated to regional regulatory regimes and installation practices;
- Scenario-driven margin analytics that quantify the impact of yield improvements, supplier consolidation, and certification delays;
- Negotiation playbooks for procurement that include concession templates and SLA structures reflective of real-world contract outcomes.
For teams preparing budgets or M&A diligence in 2026, the report provides the analytical scaffolding to convert market-level forecasts into executable sourcing and product strategies.
Next Steps
To review the comprehensive maps, models, and executable playbooks, access the full study and accompanying data appendices here: Full Report — Axial Smoke Extractor Exhaust Fan Market . The online package includes interactive supply-chain visuals, exportable BOM templates, and a configurable yield model template that can be adapted to your product portfolio.
PW Consulting’s team is available for tailored briefings and scenario workshops to convert insights into a 90–180 day action plan aligned with your 2026 priorities. Our methodology and proprietary inputs are designed to be defensible in due diligence and immediately operational for procurement and engineering leaders focused on risk reduction and margin recovery.
For detailed analysis of this topic, please visit the official page: Smoke Extractor Exhaust Fan Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Stable Isotope Ratio Mass Spectrometer Market to Expand at a 6.5% CAGR Through 2032
By PW Consulting, 2026-06-28
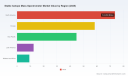
Stable Isotope Ratio Mass Spectrometer Market: Strategic Imperatives for 2026 Capital Allocation
PW Consulting’s new market brief on Stable Isotope Ratio Mass Spectrometers positions 2026 as a decisive year for equipment manufacturers, laboratory networks, and strategic investors. The global market is anchored on a base year of 2025 (USD 312.4 Million) and is projected through a 2026–2032 forecast window to grow at a compound annual growth rate (CAGR) of 6.5%, reaching roughly USD 486.8 Million by 2032. Our analysis translates this macro trajectory into a practical playbook for executives who must balance growth capture, cost containment, and compliance risk under tightening regulatory and supply-chain pressures.
Stable Isotope Ratio Mass Spectrometer Market
Why 2026 Is a Pivotal Allocation Year
Multiple converging forces make immediate strategic action necessary in 2026:
- Regulatory tightening: International standards and reference-material updates are reducing measurement variability and raising minimum compliance thresholds for laboratories and instrument vendors.
- Supply-chain fragility: Carrier gases and critical subsystems exhibit concentration risks that elevate operating costs and service disruptions absent active mitigation.
- Market consolidation and concentration: The market displays a high concentration among leading OEMs, increasing the value of installed-base service contracts and aftermarket revenue.
- Technology-driven differentiation: Advances in automation, sample-prep integration, and software analytics are shifting procurement decision-making from capital cost to lifecycle value.
What PW Consulting’s Report Delivers — Practical Tools, Not Just Projections
Our report is intentionally operational. Beyond headline forecasts, we provide a suite of decision-grade tools designed to address the most acute 2026 pain points in procurement, operations, and regulatory compliance:
- Supply-chain map and risk heatmap — identifies single points of failure across components, consumables, and logistics lanes and prescribes mitigation pathways suited to varying risk appetites.
- BOM decomposition and cost-driver logic — a reproducible approach for translating vendor quotations into a company-specific cost baseline that factors in yield, service, and consumables.
- Yield-adjustment and throughput models — scenario templates that quantify how marginal improvements in sample-prep yields and instrument uptime impact unit economics.
- Technology roadmap and migration playbook — timelines and decision gates for adopting incremental automation, modular sample handlers, and software-enabled analytics without disrupting current lab throughput.
- Compliance and procurement playbooks — checklists and contract clauses to align procurement, service-level agreements, and calibration regimes to emerging standards.
These tools are designed to be applied directly in year‑end capital planning cycles and M&A diligence, enabling CFOs and heads of operations to stress-test capex proposals against realistic scenarios rather than vendor claims.
Market Structure and Competitive Dimensions
The 2026 competitive field is best understood through the lenses of installed base economics, technical differentiation, and channel/partnership architectures. Our concentration metrics show a market where the top three suppliers capture roughly 65.0% of accessible demand, and the top five about 75.0% — conditions that favor incumbents but also create openings for focused challengers with differentiated value propositions.
Key competitive dimensions we evaluate for each major participant include:
- Technological moat: measurement precision, sample-prep integration, and instrument stability under field conditions.
- Design-win factors: ease of integration with elemental analyzers, total cost of ownership, serviceability, and software ecosystems that turn raw isotope data into actionable insights.
- Commercial moat: global service footprint, reference laboratories, academic partnerships, and consumables ecosystems that sustain recurring revenue.
- M&A and channel strategies: targeted tuck-ins that close capability gaps in small‑radius instrumentation, sample preparation, or rapid-turn servicing.
Representative manufacturer profiles in the report explore how these dimensions manifest in market behavior without publishing our proprietary 2026 strategic forecasts. For example, the largest OEMs combine broad portfolios and channel depth that favor enterprise customers, while several UK- and German-headquartered specialists compete on high-resolution performance and niche academic partnerships. Recent transactions and field activities we track are consistent with an industry reshuffling where specialized technology assets are being consolidated into broader analytical portfolios.
To review our full competitive matrices, design‑win scoring methodology, and the firms we cover, access the full report here: Access the full Stable Isotope Ratio Mass Spectrometer Market report .
Supply-Chain and Operational Pressures Unique to 2026
Specific operational stressors are shaping procurement and R&D priorities in 2026:
- Carrier gas and consumable sourcing — volatility in gases used by EA-IRMS and GC-IRMS platforms increases the importance of alternative gas architectures and supplier diversification strategies.
- Standards and traceability — outcomes from recent international expert meetings are tightening reference scales and reference-material practices, raising the bar for inter-laboratory comparability and audit readiness.
- Domestic resilience initiatives — national-level investments in isotope production and material supply reduce geopolitical exposure but create transitional procurement frictions.
- Service and spare parts logistics — lifecycle revenue increasingly depends on rapid calibration, certified consumables, and local service footprints in key markets.
PW Consulting’s supply‑chain mapping synthesizes these pressures into prioritized interventions — from short-term hedging contracts for critical gases to medium-term supplier development programs — all presented as executable options rather than prescriptive technical specs.
Methodology: Why Our Findings Are Actionable
PW Consulting applies a layered triangulation methodology to produce evidence-based insights suitable for boardroom decision-making. Core inputs include patent and citation analysis to map technology diffusion, licensed customs and trade-flow datasets to quantify shipment patterns, and reverse‑engineered BOM frameworks derived from equipment teardown and supplier cost modeling. We corroborate public records with confidential, NDA-protected interviews across OEM engineering teams, lab procurement officers, and calibration service providers.
Where direct measurement is infeasible, we apply reproducible inference rules calibrated against multiple independent data sources — patent families, peer-reviewed method sections, reference-lab procurement logs, and publicly filed service agreements — to reduce bias and quantify uncertainty. This approach allows us to expose actionable levers (for example, which subsystems most affect uptime and TCO) without disclosing proprietary client data or our full underlying datasets.
2026 Playbook: High-Level Strategic Recommendations
For executives preparing 2026 allocations, the report synthesizes tactical recommendations into three portfolio actions:
- Prioritize lifecycle economics over headline capex — favor propositions that demonstrably lower per-sample cost through improved uptime, modular upgrades, and consumables management.
- Lock-in service ecosystems — invest in regional calibration and consumables channels that shorten repair cycles and preserve institutional data continuity against tightening traceability requirements.
- Hedge and re‑engineer supply chains — mitigate single-source exposures in carrier gases and critical subsystems through multi-sourcing, alternative process flows, or targeted vertical integration.
Each recommendation in the report is paired with the operational tools described earlier (BOM templates, yield models, and supplier-risk heatmaps) so that CFOs and heads of R&D can convert strategic intent into executable projects within typical procurement cycles.
Closing Note: What Readers Will Gain
PW Consulting’s Stable Isotope Ratio Mass Spectrometer Market report is designed as a decision accelerator: it provides the market context, the operational tools, and the competitive lens necessary to make high-confidence capital and commercial choices in 2026. The brief establishes where value will accrue over the 2026–2032 window and, critically, how to convert market signals into prioritized, low‑regret actions.
For organizations that require the full dataset, regional and application distributions, and our proprietary design-win scoring tables, please download the complete report here: Access the full Stable Isotope Ratio Mass Spectrometer Market report .
For detailed analysis of this topic, please visit the official page: Stable Isotope Ratio Mass Spectrometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Acousto‑Optic Modulators Market Poised for 5.2% CAGR, Unlocking Growth in Research and Material Processing
By PW Consulting, 2026-06-28
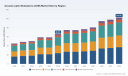
Acousto-Optic Modulators Market: Strategic Imperatives for 2026 Capital Allocation
As PW Consulting’s lead industry analyst, I present a concise, decision-focused briefing drawn from our new Acousto-Optic Modulators (AOM) Market study (base year 2025). The intelligence below is curated to help corporate and investment leaders prioritize capital deployment in 2026. This article demonstrates our analytical depth while intentionally omitting detailed segment tables and granular regional allocations — those are available in the full report.
Acousto-Optic Modulators Market
Market snapshot — where we start in 2026
The global AOM market is measured at USD 64.2 Million in 2025 and is entering 2026 on an upward trajectory, with our layered forecast producing a compound annual growth rate (CAGR) of 5.2% across the 2026–2032 horizon. By 2032 the market is projected to approach USD 91.3 Million under the central-case scenario. The industry exhibits a high degree of supplier concentration (CR3 ~85.0%, CR5 ~92.0%), which amplifies both opportunity and risk for buyers, integrators, and new entrants.
Why 2026 is a decisive year
Several converging dynamics make 2026 a pivot point for strategic capital allocation in the AOM ecosystem:
- Demand consolidation in capital-intensive end markets — industrial laser processing, advanced imaging and scientific research — is increasing procurement lead times and raising the value of secured design wins.
- Material-level supply risk is acute: high-quality Tellurium Dioxide (TeO2) crystal production remains limited to a narrow set of specialized facilities, directly affecting availability, lead times, and price volatility.
- Manufacturing modernization — driven by AI-enabled process control and higher automation — is creating a gap between tier-1 suppliers that can finance upgrades and smaller vendors facing margin compression.
- Regulatory and ESG scrutiny, together with defense-related sourcing constraints, are forcing OEMs to formalize traceability and compliance frameworks as a precondition for long-term contracts.
Primary growth vectors (what is actually expanding)
From our field interviews and patent-network analysis, growth in 2026 is concentrated along a few technical and commercial vectors rather than across a broad base. Key vectors include:
- Higher power handling and damage-threshold solutions for industrial lasers, pushing demand for advanced optical materials and coatings.
- Compact OEM-packaged modules optimized for lab-to-production transfer, enabling faster system-level integration and shorter time-to-revenue for laser manufacturers.
- Multi-channel and multi-axis modulation capability for defense and scientific instruments, where validated performance and supplier traceability dominate procurement decisions.
- Integration of RF-driver and opto-mechanical subsystems as bundled offerings, shifting value capture from component suppliers to integrated module providers.
Supply-chain playbook — tools you need for 2026
Our report goes beyond topline forecasting and supplies operational tools designed to mitigate the exact pain points companies face in 2026. Core deliverables include:
- Supply-chain topology and tiered supplier mapping that highlights single-source risks at the crystal and coating stages.
- Bill-of-Materials (BOM) decomposition methodology that isolates variable vs. fixed cost drivers and produces actionable supplier-negotiation levers.
- Yield-adjustment and throughput sensitivity models to quantify the P&L impact of incremental improvements in crystal yield and optical assembly yield.
- Vendor scoring frameworks that fuse quality, capacity, compliance credentials (e.g., ISO certifications), and geopolitical robustness into a single procurement index.
- Compliance and ESG checklists tailored for regulated buyers (defense primes, medical device OEMs), enabling faster onboarding and reduced contractual risk.
Each tool is accompanied by implementation guidance: how to run a BOM teardown workshop, calibrate yield models with shop-floor KPIs, and design supplier KPIs that feed into annual sourcing decisions without requiring wholesale process re-engineering.
Technology and product roadmap — what to watch
Our techno-commercial roadmap identifies near-term disruptive levers and the architectural choices that tend to win design slots in 2026 procurement rounds. Core technical themes include:
- Material science advances: improvements in TeO2 homogeneity and alternative acousto-optic substrates that shift the trade-off between bandwidth, efficiency, and power handling.
- Modularization: laser-system OEMs increasingly prefer AOM subassemblies with integrated RF drivers and mechanical mounts to shorten qualification cycles.
- Surface and coating engineering: higher damage-threshold coatings and contamination-resistant finishes are becoming pass/fail features in industrial laser applications.
- Frequency and speed scaling: designs that enable higher modulation frequencies without sacrificing diffraction efficiency are prioritized for imaging and telecom-adjacent uses.
Recent vendor moves underscore these themes. For example, market players are expanding high-efficiency, near-infrared product lines and pursuing acquisitions to broaden defense-related optics capabilities — a signal that integrated module capability and material control are strategic differentiators.
Competitive landscape — interpreting moats and design-win mechanics
Concentration metrics show a market where a few suppliers command meaningful share and influence pricing, supply continuity, and technical expectations. Rather than predicting each firm’s 2026 roadmap, our analysis identifies the competitive dimensions that drive success in current procurement environments:
- Vertical integration and raw-material control — suppliers that grow or secure optical-grade TeO2 have a clear supply-risk advantage during capacity tightness.
- Proprietary materials and coatings — firms with validated high-damage-threshold optics or unique substrate treatments command premium positioning in high-power segments.
- Module-level integration — vendors that bundle optical, RF, and mechanical subsystems lower system qualification time and increase stickiness with OEMs.
- Defense and regulatory pedigree — suppliers with long-standing defense contracts or ISO certifications often convert longer-term framework agreements from institutional buyers.
- Customization and speed-to-market — companies that maintain flexible production lines and configurable designs win more design-ins in specialized applications (e.g., UV or LWIR modulation).
Representative company profiles in our coverage illustrate these dimensions: some firms emphasize vertical material control and high-efficiency free-space devices; others compete on modular OEM packaging, RF-driver integration, or breadth of wavelength support. Understanding which dimension matters most for your specific procurement strategy is a central output of our report.
Access a summary of strategic supplier profiles and our vendor scoring rubric here: Full AOM Market Report — PW Consulting
Methodology — why our 2026 signals are robust
PW Consulting applies a layered triangulation methodology to produce forecasts and supplier intelligence. Key elements include patent-citation mapping, multi-tier supplier interviews under NDA, BOM teardowns validated by in-lab optical measurement, and trade-flow analysis of critical raw materials. We cross-check company disclosures, third-party certification databases, and import/export filings to reconcile reported capacity with observed shipment patterns.
When public data is scarce, we employ structured interview protocols with procurement leads and shop-floor engineers, supplemented by independent material testing and reverse-engineering of select module samples. This multi-source approach enables us to surface actionable, low-latency signals — for example, identifying which suppliers truly control TeO2 supply versus those who are exposed to external bottlenecks.
Strategic guidance for 2026 capital decisions
For executives making allocation choices this year, our analysis yields a compact set of priorities:
- Prioritize supplier relationships that demonstrably control critical materials or can commit capacity via contractual CAs — this reduces margin volatility and short-term production disruption risk.
- Invest selectively in modular integration capabilities (optical + RF + mechanical) to accelerate design wins and capture system-level margin uplift.
- Implement BOM-focused yield-improvement pilots: small improvements in crystal yield or assembly throughput produce outsized P&L impact given current unit economics.
- Embed compliance and traceability as a procurement filter — ISO credentials, auditable supply chains, and export-control hygiene are becoming gating factors for large contracts.
- Consider M&A or strategic partnerships to secure specialized capability (e.g., crystal growth, high-damage coatings) rather than attempting long, capital-intensive internal builds.
Closing — what to do next
The AOM market in 2026 is compact, material-constrained, and technically differentiated. Firms that act now — aligning procurement, R&D, and compliance investments with the supplier dimensions outlined above — will materially improve their odds of winning the design slots that underpin multi-year revenue streams.
For access to our full segmentation maps, supplier scorecards, BOM templates, and scenario-modeled P&L impacts, download the complete report here: https://pmarketresearch.com/auto/acousto-optic-modulators-aom-market
For detailed analysis of this topic, please visit the official page: Acousto-Optic Modulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Single Cylinder Diesel Engine Market Set to Expand at 6.9% CAGR from 2026–2032
By PW Consulting, 2026-06-28
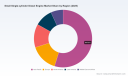
Single Cylinder Diesel Engine Market — Strategic Preview for 2026
In 2026 the single cylinder diesel engine market sits at a strategic inflection point. PW Consulting’s latest market synthesis shows the market reached USD 197.4 Million in the base year 2025 and is projected to expand at a compound annual growth rate of 6.9% through our 2026–2032 forecast horizon, reaching approximately USD 312.3 Million by 2032. This briefing outlines why those high-level trajectories matter for boardroom capital allocation in 2026, and how our report’s operational toolset converts macro signals into executable moves — while reserving the granular regional and application splits for the full report.
Single Cylinder Diesel Engine Market
Market Dynamics Driving 2026 Decisions
Executives allocating capital in 2026 must balance demand resiliency against tightening regulatory and input-cost pressures. The following dynamics are central to near-term strategy:
Single Cylinder Diesel Engine Market
- Regulatory push and retrofit risk
- EU Stage V requirements for sub‑19 kW NRMM remain active and continue to shape product roadmaps in Europe.
- China’s National IV standard is enforced for sub‑37 kW engines, accelerating compliance investments by OEMs with China exposure.
- Input-cost volatility
- Raw material swings (e.g., cast iron prices in China at 4,200.0 CNY/ton in Q3 2025) are shifting cost curves and supplier bargaining power.
- Demand-side polarization
- Stable demand pockets persist in agricultural and generator markets, while urban emissions regulation and electrification conversations are compressing growth windows in certain segments.
- Consolidation and concentration
- The market shows meaningful concentration: the largest three suppliers account for roughly 48.7% of volume, and the top five for about 71.2%, creating strategic implications for tiers, design wins and supplier risk.
What the PW Consulting Report Delivers — Practical Tools for 2026 Action
The report is purpose-built to convert those dynamics into executable programs. Core deliverables include:
Single Cylinder Diesel Engine Market
- Supply-chain topology: mapped tier‑1 through raw‑material sources with alternate‑sourcing pathways and lead‑time overlays to stress‑test procurement strategies.
- BOM decomposition logic: a replicable methodology to translate engineering drawings and teardown observations into commercial BOMs and cost drivers, isolating the top N parts that determine margin variance.
- Yield and margin adjustment model: scenario-ready modules that quantify the impact of yield changes, rework rates and scrap on unit economics without exposing client‑sensitive inputs.
- Technology route maps: milestone‑based charts that trace compliance and performance pathways (e.g., low‑emission combustion calibrations, air‑cool vs liquid‑cool tradeoffs) and their estimated CAPEX and OPEX implications.
- Compliance and certification matrix: a decision framework that aligns product variants to regional regulatory regimes and rollback risks, enabling prioritized certification investments.
- Supplier scorecards and negotiation playbooks: templates for strength‑of‑supply assessment that integrate quality, delivery, tariff exposure and IP position into procurement levers.
Each tool is delivered as an interactive template or workbook, not merely descriptive analysis, enabling leadership teams to run "what‑if" scenarios for 2026 capital and sourcing choices while protecting the report’s proprietary segment-level distributions.
How These Tools Address 2026 Pain Points
Applied to the current operating environment, the tools solve for the most urgent C‑suite concerns:
- Cost control under input volatility: BOM decomposition plus yield models convert raw-material price movements into unit-margin sensitivity curves so procurement and engineering can prioritize material substitutions or design simplifications.
- Regulatory compliance without margin erosion: the technology route maps and certification matrix help prioritize investments that preserve design wins while minimizing aftermarket retrofit exposure.
- Supply resilience: the supply‑chain topology exposes single‑source dependencies and creates alternative pathways that can be actioned within standard procurement cycles.
- Investment prioritization: scenario modules show the marginal ROI of factory automation, low‑emissions upgrades, or footprint relocation before executing capex decisions.
Competitive Landscape — Dimensions That Matter in 2026
Our competitive analysis focuses on the strategic vectors that determine winners in 2026 rather than offering prescriptive market shares. The incumbents and regional players compete across a consistent set of dimensions:
- Product moat: robustness of combustion architecture, cooling approach and parts commonality that reduce integration cost for OEM platforms.
- Regulatory readiness: demonstrated compliance track record and certification pipelines for Stage V/National IV markets are decisive for European and Chinese OEM partnerships.
- Channel and service network: aftersales reach in agricultural and rental markets often determines design win longevity and total lifecycle value.
- Manufacturing and cost position: proximity to steel and casting hubs, vertical integration, and flexible low‑volume tooling affect bargaining power and margin resilience.
- Design‑win mechanics: time‑to‑prototype, shared engineering resources, and the ability to commit to long‑tail spare parts contracts are repeatable sources of competitive advantage.
Notable vendor signals observed in 2025–2026 underscore these dimensions:
- Hatz Diesel released an updated product catalog in late 2025 highlighting Stage V conformity — a clear signal of regulatory alignment and catalogue refresh cadence.
- Yanmar’s 2025 new L‑series variants emphasize fuel‑efficiency gains targeted at European customers, indicating an engineering‑led differentiation strategy in mature markets.
- Kubota’s active showcase at Agritechnica 2025 reinforces channel strength and the role of trade events in securing long‑cycle agricultural design wins.
For boards assessing partner or competitor risk, these indicators are more actionable than static market shares. For a full set of competitive profiles, supplier scorecards and the complete geographic and application split charts, access the full Competitive Profiles and Distribution Maps at https://pmarketresearch.com/auto/small-single-cylinder-diesel-engine-market
Methodology — Why Our Findings Are Trustworthy
PW Consulting’s approach combines layered triangulation with targeted primary discovery. Key elements include patent citation analysis to map technology clusters, systematic teardowns to validate BOM constructs, anonymized interviews with OEM procurement leads and tier‑1 suppliers, and customs and trade‑flow analytics to ground volumes. We then reconcile these streams using cross‑sector calibration (Layered Triangulation) to limit bias from any single input.
Crucially, we supplement public data with non‑public contractual indicators obtained under NDA during supplier and OEM interviews, and with in‑market field inspections of manufacturing nodes. This blend gives us unique visibility into near‑term capacity constraints, typical rework rates and the real cost levers that matter to 2026 P&L outcomes — without exposing proprietary client material or the granular segment tables reserved for the full report.
Strategic Implications and Recommended Actions for 2026
The intersection of steady top‑line growth and concentrated supply power creates a narrow window for value capture in 2026. Boards and PE sponsors should consider the following priorities:
- Make regulatory preparedness a gating criterion for product investment — prioritize variants that secure design wins in high‑compliance markets first.
- Adopt a BOM‑led sourcing strategy — identify the handful of commodity and cast components driving margin variance and execute targeted supplier contracts or hedges.
- Accelerate selective automation and CPK improvements in plants where yield improvements are forecast to deliver faster payback than greenfield builds.
- Pursue defensive partnerships with concentrated suppliers: long‑tail spare contracts or jointly funded compliance programs can shorten procurement cycles and lock in channel access.
- Carve out a measured M&A funnel that prioritizes niche players with channel access or IP in low‑emission combustion, rather than broad scale plays that replicate existing concentration.
Next Steps — Where to Get the Full Intelligence
This preview is designed to orient strategic conversations in 2026. For transaction teams, product leaders and procurement executives who need the complete segmentation tables, detailed regional distribution graphics, full supplier scorecards and the interactive BOM workbooks, please consult the full report and the downloadable toolset at https://pmarketresearch.com/auto/small-single-cylinder-diesel-engine-market
PW Consulting remains available to run tailored scenario analyses and to workshop the report’s templates with your product and procurement teams to translate findings into 90‑day action plans that mitigate regulatory risk and capture margin upside.
For detailed analysis of this topic, please visit the official page: Single Cylinder Diesel Engine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Automotive Wheel Bearing Market to Reach USD 58,086.8 Million by 2032
By PW Consulting, 2026-06-28
Automotive Wheel Bearing Market 2026: Strategic Imperatives from PW Consulting
As of 2026, the automotive wheel bearing market is in a phase of measured expansion and structural rebalancing. Our analysis places the global market at USD 39,635.2 Million in 2025 (base year) and projects it to grow to USD 58,086.8 Million by 2032, representing a compounded annual growth rate of 5.6% over the forecast window. That trajectory is underpinned by a combination of electrification-driven NVH requirements, heavy‑duty fleet replacement cycles, and incremental aftermarket demand. For executives allocating capital or negotiating supplier agreements in 2026, the choices made now will determine cost competitiveness and Design Win outcomes through the end of the decade.
Automotive Wheel Bearing Market
Why this report matters for 2026 decision-makers
The automotive bearing sector is not a single monolith: it is shaped by metallurgy, precision manufacturing, systems-level vehicle integration and trade exposure. In 2026, the following enterprise-level priorities make this market intelligence indispensable:
- Capital allocation: identifying which production assets and automation investments yield the fastest payback under current raw material volatility.
- Supply chain resilience: structuring dual-sourcing and nearshoring scenarios to mitigate tariff shock and lead‑time risk.
- Design philosophy: prioritizing low-noise, low-friction solutions for EV platforms while preserving heavy‑duty load capacity for commercial vehicles.
- Regulatory and ESG alignment: ensuring new sourcing and manufacturing footprints comply with evolving trade and environmental rules without eroding margins.
What PW Consulting’s Automotive Wheel Bearing Market report delivers
The report is constructed to convert market intelligence into actionable program-level inputs for procurement, product development, and corporate strategy teams. It marries top‑down market sizing with bottom‑up engineering and cost analysis so that strategic choices in 2026 are grounded in both market context and manufacturing realism.
- Supply‑chain topology and risk maps that reveal single‑point failures, transit chokepoints and levers for near-term localization.
- BOM decomposition logic and cost‑to‑manufacture models that link material grades, process steps and yield assumptions to landed unit cost.
- Yield‑adjustment and sensitivity models that help procurement teams quantify the P&L impact of steel price swings and process variability.
- Technology roadmaps that track NVH, material metallurgy, bearing coatings and integrated sensorization relevant to EV and ADAS platforms.
- Supplier scorecards and negotiation playbooks designed for the 2026 OEM procurement cycle, oriented to secure Design Wins rather than spot price wins.
Market dynamics and the 2026 operating environment
Several macro- and micro-level dynamics are converging in 2026 to raise both risk and opportunity for players across the value chain:
- Raw‑material volatility: steel remains a dominant cost input for precision bearing manufacture. The bearing‑grade steel market is expanding with demand for higher‑performance chemistries; recent industry analysis valued the bearing steel market at approximately USD 6.5 billion in 2025 and projected it to rise in 2026—an input that tightens margins when not proactively hedged.
- Tariff and trade policy impact: Section 232 tariff adjustments and derivative measures implemented through 2025 materially increase the landed cost of imported components for some manufacturers, forcing re‑sourcing decisions or price renegotiations in 2026.
- Commodity price signals: in early 2025 hot‑dipped galvanized steel prices moved to price points that increased short‑term procurement costs; buyers who reposition supply strategies in 2026 will capture durable advantage.
- Electrification and NVH requirements: as OEM platforms electrify, low‑noise and low‑friction performance becomes a design constraint rather than a premium option—affecting material choices, tolerances and shaft/hub integration approaches.
- Fragmented supplier landscape: market concentration is low relative to many automotive subsystems (CR3: 24.6%; CR5: 26.2%), which creates room for both established global players and regional challengers to win program business through differentiated propositions.
Supply‑chain and product engineering tools that matter in 2026
PW Consulting’s toolset is tailored to the exigencies of 2026 procurement and product cycles. We focus on outputs that can be directly operationalized by CPMs, head of procurement, and platform engineering:
- BOM teardown templates that translate engineering drawings into cost line items and process flows for rapid supplier benchmarking.
- Yield and scrap sensitivity modules enabling scenario planning under different steel price and process‑yield assumptions.
- Supplier footprint stress tests that quantify lead‑time, tariff exposure and resilience under natural disaster or trade disruption scenarios.
- Design Win playbooks that map NVH test points, sterilization/cleanliness requirements, and endurance validation sequences used by Tier‑1 and OEM validation teams.
Competitive landscape — dimensions that decide winners in 2026
Competitiveness in the bearing market in 2026 is determined less by single metrics and more by how firms combine capabilities across multiple dimensions. PW Consulting evaluates each major player against several defensible axes:
- Material and metallurgy advantage — proprietary heat treatments, steel sourcing agreements and coating technologies that reduce wear and friction.
- Manufacturing scale and footprint — the ability to move production to mitigate tariffs or to meet regional content rules without sacrificing quality.
- Systems integration and NVH credibility — demonstrated success in delivering low‑noise assemblies for EV platforms and coordinated validation with OEM NVH teams.
- Commercial engine — aftermarket reach versus OEM design‑win focus; companies that balance both channels manage demand swings more effectively.
- Service and testing ecosystem — labs, accelerated life testing and field telemetry that tighten feedback loops between design and in‑service performance.
Legacy leaders and agile challengers adopt distinct strategies along these axes. For instance, some incumbents leverage deep metallurgy and global OEM footprints to defend scale economics; others compete with cost‑effective manufacturing and rapid localized support for regional OEMs. Recent corporate shifts, such as the 2025 European business restructuring by one supplier, underscore the active portfolio repositioning taking place across the industry.
For a granular, comparative view of suppliers and a tool‑level breakdown of the competitive levers, access the full vendor competitiveness matrix and supplier scorecards here: Download the full PW Consulting report .
Signals and risks to monitor in 2026
Key signals that warrant immediate monitoring as companies finalize 2026 capital and sourcing plans include:
- Changes in steel procurement terms and the emergence of long‑term supply contracts for bearing‑grade alloys.
- OEM NVH specification tightening with standardization across EV platforms.
- Regulatory adjustments to trade or environmental requirements that affect permitted coatings or materials.
- Supplier consolidation or asset divestitures that alter regional capacity balances.
Methodology: how PW Consulting produces defensible, non‑public insight
Our 2026 analysis is built on layered triangulation and structured primary research. That means we combine multiple independent data streams to converge on high‑confidence conclusions rather than relying on any single input. Key methodological pillars include:
- Patent and technology citation analysis to map innovation trajectories and identify supplier IP moats.
- Teardown and BOM modeling conducted on platform‑representative samples to derive process cost drivers and material sensitivities.
- Proprietary procurement data and customs flow analytics that reveal shipment patterns, lead‑time dispersion and implied capacity utilizations.
- Confidential interviews with procurement and engineering leaders across OEMs and Tier‑1s, supplemented by site visits and lab validation where permissible.
Combining these sources allows us to surface decision‑grade signals that are not otherwise visible in public filings — for example, which material grades are being trialed in EV hubs, or which suppliers are winning early NVH test cycles. We do not publish client‑level confidential data; rather, we synthesize directional intelligence and operational templates that clients can apply immediately.
Actionable strategic guidance for 2026
For executives committing capital, reassigning sourcing, or defending program wins in 2026, PW Consulting recommends the following high‑impact moves:
- Prioritize raw‑material hedges and long‑term supplier agreements for critical steel grades now to stabilize input cost through the next program validation window.
- Invest selectively in low‑noise bearing design and test capabilities to convert NVH requirements into defensible Design Wins on EV platforms.
- Execute supplier footprint optimization that balances tariff exposure, lead time and technical partnership, using our supply‑chain stress tests as the selection engine.
- Deploy yield and scrap sensitivity models at product launch gates so that launch pricing reflects realistic manufacturing ramp profiles rather than optimistic ideal yields.
- Close internal capability gaps in coating and heat‑treatment process control to reduce dependence on specialty sub‑suppliers and shorten qualification cycles.
PW Consulting’s Automotive Wheel Bearing Market study is specifically designed to convert market signals into procurement and product actions that preserve margin and capture program share in 2026. For the full market distribution maps, supplier scorecards, and the operational toolkits referenced above, please download the comprehensive report here: Access the full report .
For detailed analysis of this topic, please visit the official page: Automotive Wheel Bearing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Antifreeze Proteins Market Poised for Rapid Expansion with a 27.5% CAGR
By PW Consulting, 2026-06-28
Antifreeze Proteins (AFP) Market — Strategic Outlook for 2026
PW Consulting publishes a forward-looking industry brief that positions Antifreeze Proteins (AFP) as a fast-scaling niche within advanced biosciences and adjacent manufacturing applications. The AFP market is expanding rapidly: using 2025 as our base year, global revenue is USD 18.4 Million (2025) and the model projects a rise to roughly USD 101.0 Million by 2032, implying an average CAGR of 27.5% across the 2026–2032 forecast horizon. In 2026 the market is already in an inflection phase where technology adoption, regulatory clarity, and raw-material cost pressures converge to make capital allocation both urgent and high-impact for manufacturers, ingredient suppliers, and strategic investors.
Antifreeze Proteins (AFP) Market
Why this matters for 2026 decision-makers
For senior executives and investors evaluating deployment of manufacturing capital, the AFP growth profile is not abstract growth — it changes procurement cycles, qualification timelines, and supplier selection criteria within a two- to three-year window. Key implications that we observe in market signaling and proprietary field data include:
- Acceleration of qualification timelines as OEMs prioritize low-temperature storage and cryo-stability solutions for biologics and specialty foods.
- Upward pressure on upstream raw-materials and advanced fiber costs that make yield and material utilization central to margin protection.
- Concentration of value in integrated solutions — those who can combine formulation, delivery mechanism, and certified manufacturing scale capture outsized design wins.
Market dynamics and macro drivers (2026 perspective)
The AFP market expansion is driven by a blend of application pull and manufacturing push. On the pull side, clinical and specialty-food applications demand better cold-chain performance and cryo-protection; on the push side, manufacturing innovations in automation and fiber-composite processing are lowering unit costs for AFP-enabled components. Raw-material dynamics remain a fundamental input: carbon-fiber-driven automation economics and ongoing R&D into lower-cost precursors (for example lignin-derived feedstocks) are reshaping supplier negotiations and capital plans. High legacy PAN-based carbon prices continue to encourage automation investments to reduce waste and improve effective material utilization.
Practical toolset included in our report — designed for 2026 execution
PW Consulting’s AFP report is intentionally tactical. We provide an integrated toolkit that enables procurement, R&D, and operations teams to translate market signals into executable steps without exposing proprietary client scenarios. Highlights include:
- Supply-chain mapping that identifies second- and third-tier exposure points, preferred sourcing levers, and contingency corridors for constrained inputs.
- BOM (bill-of-materials) decomposition logic that isolates value-at-risk drivers and highlights where substitution, yield improvement, or redesign delivers the largest margin impact.
- Yield-adjustment and ramp models that allow planners to simulate how incremental improvements in layup, curing, or handling reduce per-unit costs during scale-up.
- Technical roadmaps that reconcile near-term process optimizations with medium-term material science developments, preserving upgrade paths for automation investments.
Each tool is delivered as an actionable module (diagnostic + scenario templates) so clients can run their own sensitivity analysis. We deliberately withhold core segment-level figures in this release to preserve the “trailer” function of this bulletin; the full set of charts, regional distribution maps, and segment breakouts are accessible in the complete report.
Competitive landscape: dimensions that decide design wins in 2026
The AFP supplier ecosystem in 2026 is characterized by a mix of specialized equipment vendors, systems integrators, and modular toolhead providers. Market concentration is moderate: the top three players hold roughly 25.0% of revenue and the top five about 35.0% — a structure that favors both focused innovators and nimble challengers. From our company-level analysis, the competitive advantages that translate to design wins are consistent across market segments:
- Proven integration and certification capability — the ability to deliver a certified, high-throughput cell with predictable uptime is a decisive moat for aerospace and clinical customers.
- IP in process-critical subsystems — patented cutting/adding mechanisms, robust head designs, and tape-handling architectures reduce qualification risk and shorten adoption cycles.
- Modularity and cost-to-entry — lower-cost, plug-and-play heads enable SMEs and research labs to adopt AFP technology without full-line investment, creating a broad base of initial demand.
- Software and telematics — sophisticated path-planning, closed-loop quality monitoring, and field-updatable control stacks accelerate ramp and reduce total cost of ownership.
Using those dimensions, we profile leading manufacturers (examples include Electroimpact, MTorres, Ingersoll Machine Tools, Broetje-Automation, Coriolis Composites, Fives Group, Addcomposites, Automated Dynamics/Trelleborg, and MIKROSAM). Our analysis focuses on each vendor’s structural strengths rather than making explicit 2026 strategic forecasts. For example:
- Electroimpact’s advantage is system-scale engineering and flight-industry reliability; design wins depend on demonstrable throughput and supply-chain continuity.
- MTorres leverages patented mechanisms to deliver high productive cycles; buyers prize this where maximum throughput per cell is required.
- Addcomposites is the go-to for low-capex adoption, expanding the addressable base among SMEs and research centers via plug-and-play toolheads.
- Systems with hybrid AFL/AFP capability (e.g., Fives’ offerings) capture customers seeking flexibility across part families and materials.
Recent vendor developments underscore these dynamics: Addcomposites’ growing install base and thermoplastic integrations show demand for affordable, modular adoption paths; Broetje-Automation’s showcase of integrated AFP and winding heads highlights interest in consolidated cell-level functionality; and Electroimpact’s deliveries to high-profile aerospace programs demonstrate the premium on scale and reliability. For executive teams deciding whom to qualify in 2026, the critical questions are not only “who builds the best head” but “who guarantees qualification timelines, updatable controls, and service continuity during scale-up.”
For further detail on vendor positioning, supplier scorecards, and decision matrices, read the full report at https://pmarketresearch.com/auto/robotic-automated-fiber-placement-afp-market .
Technology pathways and raw-material interplay
AFP adoption is simultaneously shaped by process technology (robotic placement, head design, curing) and feedstock economics (carbon-fiber variants, alternative precursors). Technology pathways we monitor in 2026 include:
- Thermoplastic vs. thermoset AFP routes — each has distinct supply-chain and certification implications for scale.
- Multi-tow and narrow-slit tape handling — enabling complex geometries with reduced scrap.
- Laser and flash-lamp heating integrations for rapid consolidation in thermoplastic workflows.
Because raw-material costs remain a primary lever on AFP unit economics, initiatives to develop lower-cost precursors (for example lignin-derived fibers) or to improve carbon-fiber yield are of strategic consequence. These developments, combined with automation-led material utilization gains, materially alter ROI calculations for 2026 capex decisions.
Operations, compliance and ESG — immediate 2026 priorities
Manufacturers allocating capital in 2026 must balance throughput objectives with tightening trade-compliance and ESG requirements. Our field work shows procurement teams giving higher weight to traceability, low-carbon input pathways, and supplier auditability in contract terms. AI-enabled manufacturing upgrades that improve process repeatability also help by producing auditable process records that satisfy both regulators and large OEM buyers.
Methodology: why our signal quality is differentiated
PW Consulting applies a Layered Triangulation methodology to construct our AFP market view. Core inputs include patent-citation analysis, multi-stakeholder interviews under NDA, supplier shipment and customs reconciliation, factory-level teardowns and BOM validation, machine telematics harvested with operator consent, and targeted site visits. We combine forensic BOM disassembly with contract-level procurement signals and anonymized installer logs to reconcile capacity and installed base estimates.
This multi-source approach allows us to surface non-public behaviors (for instance, preferred supplier substitution patterns and real-world yield trajectories) while preserving client confidentiality. The result is an evidence-weighted set of scenarios that are usable for commercial negotiations, capex committees, and M&A diligence without requiring clients to rely on single-source anecdotes.
Strategic implications and high-level actions for 2026
Based on our scenario modeling and market intelligence, PW Consulting recommends that executives consider the following high-level actions in 2026:
- Prioritize flexible, modular AFP solutions that reduce qualification time while preserving upgrade paths to higher-throughput heads.
- Lock supply arrangements for critical feedstocks and negotiate performance-based service terms that align supplier incentives with yield improvement targets.
- Invest in AI-enabled process monitoring and telematics to compress ramp time and produce audit-ready compliance trails.
- Use staged capital deployment (pilot → scale → replicate) linked to pre-defined yield and certification milestones to limit downside while capturing upside.
These recommendations are deliberately prescriptive at the program level while leaving the precise parameterization to company-specific diagnostics available in our full advisory package.
Next step — where to get the complete intelligence
This industry brief is intended as a decision-useful preview. The full PW Consulting Antifreeze Proteins (AFP) Market report contains the detailed segment maps, regional distribution charts, supplier scorecards, and downloadable scenario models required to operationalize 2026 capital and procurement plans. Access the comprehensive report and data tools here: https://pmarketresearch.com/auto/robotic-automated-fiber-placement-afp-market .
For detailed analysis of this topic, please visit the official page: Antifreeze Proteins (AFP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


