



Category: Machinery & Automotive
PW Consulting: Vehicle Telematics Market Hits $93.61B in 2025, Driven by 8.7% CAGR to $167.85B by 2032
By PW Consulting, 2026-09-16
Unlocking the Road Ahead: Strategic Intelligence for the 2026 Vehicle Telematics Landscape
The global automotive ecosystem is undergoing a profound transformation, driven by connectivity, data ubiquity, and an escalating demand for operational efficiency. At the center of this shift lies vehicle telematics, a technology once relegated to simple tracking but now serving as the central nervous system of modern mobility, fleet management, and insurance underwriting. As enterprises navigate the complexities of 2026, understanding the trajectory of this market is not merely an advantage; it is a strategic imperative.
Our latest comprehensive market research delves into the multifaceted dynamics of the vehicle telematics industry, offering a granular view of where value is being created, how competitive forces are aligning, and what regulatory headwinds lie on the horizon. This article serves as a strategic preview of the full report, highlighting the macroscopic trends and qualitative shifts that will define decision-making for the remainder of the decade. For senior leadership teams, the insights contained within this study provide the necessary framework to allocate capital, mitigate risk, and identify high-growth vectors in a rapidly consolidating landscape.
The Trajectory of Growth: A Macro View
The momentum behind vehicle telematics is undeniable. Following a robust historical performance from 2020 through 2025, the market has demonstrated resilience against supply chain disruptions and economic volatility. The total revenue generated across the sector has climbed steadily, reflecting an increasing integration of telematics hardware and software into both legacy and next-generation vehicle platforms. This growth is not accidental; it is the result of a structural shift where connectivity is no longer a premium feature but a baseline expectation for commercial and consumer vehicles alike.
Vehicle Telematics Market
Looking forward, the forecast period from 2026 to 2032 suggests a continued expansion trajectory. Market projections indicate that the industry is expected to advance toward a valuation exceeding 167 billion USD by the end of the forecast window. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 8.7 percent, signaling a healthy, sustained demand curve. Such growth rates are characteristic of an industry moving past its early adopter phase and entering a period of broad-scale integration and maturation.
This macroscopic growth narrative is supported by consistent year-over-year revenue increases. The baseline established in 2025 at approximately 93.61 billion USD serves as the springboard for the estimated 101.46 billion USD mark expected in 2026. As organizations plan their strategic roadmaps, aligning internal targets with these external market signals is crucial. The data suggests that the window for capturing market share remains open, but it is narrowing as technology standards converge and barriers to entry evolve.
Navigating Segmentation and Technological Shifts
While the overall numbers tell a story of growth, the composition of that growth reveals where the strategic opportunities lie. The market is characterized by a diverse array of solution types, ranging from embedded systems directly integrated into vehicle manufacturing to tethered and integrated aftermarket solutions. The prevalence of embedded technologies suggests a transition toward seamless, factory-installed connectivity that leverages OEM partnerships. This shift reduces installation friction and enhances data reliability, aligning with the broader industry move toward software-defined vehicles.
OBD Telematics Market
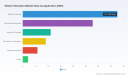
Application-wise, the demand drivers are multifaceted. Safety and security remain paramount, reflecting the industry's commitment to reducing accidents and enhancing asset protection. Meanwhile, fleet and asset management applications continue to drive significant volume, as logistics and transportation companies seek to optimize routes, monitor driver behavior, and reduce total cost of ownership. Beyond these core verticals, insurance telematics is reshaping risk assessment models, allowing for more granular pricing based on actual driving data rather than demographic proxies. Information, navigation, and infotainment systems further round out the ecosystem, enhancing the user experience and creating additional touchpoints for data monetization.
It is within these segments that the real strategic nuance exists. Organizations must understand not just the size of each segment, but the velocity of adoption and the specific pain points each application addresses. Our full report dissects these areas to identify which sub-sectors are poised for acceleration and which may face saturation earlier than anticipated.
Competitive Dynamics and the Path to Consolidation
The competitive landscape of the vehicle telematics market is both crowded and intensely competitive. A select group of key players commands a significant portion of the market share, indicating a trend toward concentration among established vendors with robust technology stacks and global reach. The top three players alone account for over half of the market share, while the top five extend their influence to cover approximately seventy percent of the total market. This level of concentration suggests that scale, technological differentiation, and ecosystem partnerships are becoming increasingly critical differentiators.
Leading the charge are companies that have expanded beyond simple tracking to offer holistic platforms. Geotab, headquartered in Mississauga, Canada, continues to set the pace with its comprehensive vehicle telematics platform, integrating GO devices, OEM-embedded solutions, and AI analytics capabilities through its Geotab Ace initiative. Their focus on supporting mixed fleets and electric vehicle data positions them well for the transition to electrification. Similarly, Samsara in San Francisco has built a formidable connected telematics platform that unifies GPS, driver safety tools, and diagnostics into a cohesive workflow for fleet visibility and risk management.
The competition is further heated by innovative entrants and established players pivoting strategies. Motive, also based in San Francisco, differentiates itself by integrating video signals with vehicle data, enabling more effective driver coaching and asset monitoring. Verizon Connect and Teletrac Navman provide robust equivalents with a focus on real-time GPS, maintenance alerts, and OEM integration strategies that bridge the gap between factory-fitted hardware and cloud analytics. Meanwhile, companies like Trimble and Omnitracs emphasize diagnostics, predictive maintenance, and route optimization, catering to the operational efficiency needs of heavy and commercial fleets.
Recent developments underscore the pace of innovation. In early 2026, LG Electronics unveiled a next-generation smart telematics solution that integrates the Telematics Control Unit and antenna into a single module, marking their first participation at MWC Barcelona and signaling a push toward design efficiency and enhanced connectivity. Earlier in 2025, Teletrac Navman launched an OEM Telematics integration for their TN360 platform, allowing seamless data access from factory-fitted hardware without aftermarket installation. These moves highlight the industry's focus on hardware integration and reducing installation complexity. Furthermore, strategic alliances are reshaping the value chain; for instance, Cambridge Mobile Telematics announced a partnership with TransUnion to leverage portable consumer driving scores, reinforcing the growing synergy between telematics data and broader financial and insurance ecosystems.
Regulatory Tailwinds and Headwinds
No discussion of vehicle telematics strategy in 2026 would be complete without addressing the regulatory environment. The industry is operating within a complex web of compliance requirements that vary significantly by geography. In the United States, federal rules now require affirmative certification for information and communications technology supply chain security in connected vehicles and telematics systems. This mandate aims to enhance resilience but imposes additional due diligence requirements on manufacturers and integrators. Additionally, the US International Trade Commission has extended its investigation into certain vehicle telematics and video-based safety systems, creating a period of regulatory uncertainty that organizations must monitor closely.
Across the Atlantic, the European Union has implemented stringent mandates affecting heavy vehicles. The second-generation smart tachograph V2 became mandatory for vehicles over 3.5 tonnes, with strict timelines for adoption and migration of first-generation units. The EU General Safety Regulation further mandates commercial vehicle telematics requirements, and the Data Act, effective from 2025, grants users access to raw vehicle data. This shift empowers end-users but challenges traditional data monopolies held by OEMs and platform providers. In North America, state-level legislation is also evolving; for example, North Carolina now requires insurer notice and consent before using vehicle telematics data, signaling a broader trend toward consumer privacy and data sovereignty.
For enterprises, these regulations are not just compliance hurdles but strategic variables. They influence product design, data handling protocols, and international expansion strategies. Our report provides a detailed mapping of these regulatory landscapes to help organizations anticipate compliance costs and leverage regulatory standards as competitive moats.
Strategic Imperatives for 2026 and Beyond
As the market moves toward 2032, the organizations that will thrive are those that can synthesize these various threads into a coherent strategy. The convergence of AI, video analytics, and embedded connectivity is creating new value propositions that go beyond basic tracking. Companies like Powerfleet and Geosavi are pushing the boundaries of video-based telematics and AIoT platforms, integrating SaaS solutions that offer deeper operational insights. Teltonika and Linxup are focusing on hardware durability and AI-enabled safety features, such as dash cameras for distracted driving detection.
For strategic planners and investors, the key questions revolve around where to place bets in this ecosystem. Should the focus be on the hardware layer, the software analytics layer, or the data marketplace? How will OEM integration strategies evolve as manufacturers gain more control over vehicle data? What is the impact of insurance telematics on consumer behavior and fleet procurement? Our full market research addresses these questions with detailed segmentation analysis, competitive benchmarking, and scenario planning.
The vehicle telematics market is at an inflection point. The growth rates forecast suggest a maturing industry with significant room for innovation, while the competitive and regulatory dynamics indicate that passive participation is no longer viable. Organizations need access to precise, actionable intelligence to navigate this terrain effectively. The full report provides the depth, data, and strategic context required to turn market complexity into competitive advantage. We invite you to explore the complete study to gain the insights necessary for informed decision-making in this critical sector.
For detailed analysis of this topic, please visit the official page: Vehicle Telematics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Intelligent Excavator Market to Hit $2.1B in 2025, Surge 24.54% CAGR Through 2032
By PW Consulting, 2026-09-16
The Intelligent Excavator Market: Strategic Intelligence for 2026 Decision-Makers
Executive Overview: Why This Study Matters Now
The heavy machinery sector is undergoing a structural transformation as connectivity, automation, and precision control redefine how earthmoving assets are deployed. Intelligent excavators now sit at the center of this shift, merging advanced electrohydraulic architectures, real-time sensor integration, and operator assistance systems into platforms that compress rework, improve grade accuracy, and elevate site safety. For executives evaluating capital allocation, fleet modernization, technology partnerships, and supply chain strategy, the Intelligent Excavator Market represents both a growth vector and a complexity trap. The difference between capturing value and being disrupted lies in the quality of the intelligence underpinning strategic choices.
This market research study, published by PW Consulting, delivers a comprehensive view of the intelligent excavator landscape across the 2020 to 2032 horizon. Drawing on a rigorous base year of 2025 and a structured forecast window extending through 2032, the report is designed to give leadership teams a disciplined foundation for 2026 planning. Rather than offering static snapshots, the analysis traces the trajectory from $0.7 million in 2020 to $2.1 million in 2025, and projects sustained expansion toward $9.76 million by 2032, supported by a compound annual growth rate of 24.54%. These macroeconomic signals frame a market that is scaling rapidly, but they also underscore the need for deeper, decision-grade insight into where value is being created and how competitive advantage is being secured.
This article previews the strategic architecture of the full study. It highlights the market dynamics, competitive configurations, and operational content that matter most to decision-makers, while deliberately leaving the granular segment breakdowns for the complete report. The goal is to demonstrate the scope and analytical depth available, and to guide leaders toward the full intelligence package where they can act with confidence.
Market Trajectory and the Shape of the Opportunity
Any credible strategy for intelligent excavators must begin with a clear picture of market scale and momentum. Over the historical window from 2020 through 2025, revenue expanded from $0.7 million to $2.1 million, reflecting the early acceleration of smart machine adoption across multiple end-use environments. The forecast period from 2026 to 2032 extends this expansion into a phase of more mature, systemic growth, with projected revenue rising from $2.69 million in 2026 to $9.76 million in 2032. This path is not merely a linear extrapolation; it reflects the compounding effect of technology penetration, regulatory pressure, and the operational economics of precision construction and extraction workflows.
At the heart of this projection sits a CAGR of 24.54%, a figure that signals both opportunity and planning discipline. Growth at this pace reshapes competitive positioning quickly, compresses the window for first-mover advantage, and requires organizations to make simultaneous bets across product configuration, dealer enablement, data services, and aftertreatment strategy. The full report unpacks the structural drivers behind this expansion, but for 2026 planning purposes, the central takeaway is clear: intelligent excavators are moving from niche differentiation to mainstream operational necessity.
The study also situates this growth within a concentrated competitive environment. With the top three players accounting for 53.8% of market revenue and the top five reaching 70.0%, scale, brand trust, and technology ecosystems matter. Concentration of this magnitude shapes everything from pricing dynamics and channel access to the willingness of end users to adopt new machine control platforms. Executive teams need to understand not just how large the market is, but how decisively incumbents and challengers are competing within it.
Intelligent Excavator Market
Industrial Dynamics: Forces Reshaping the Intelligent Excavator Landscape
Strategic planning in this market cannot be reduced to size and growth alone. The intelligent excavator space is being reshaped by simultaneous regulatory, operational, and cost pressures that influence product design, total cost of ownership, and procurement behavior. A thorough 2026 strategy must account for these forces as first-order variables rather than background noise.
Regulative evolution is a defining factor. Advanced emission norms such as EU Stage V, US Tier 4 Final, and China VI require sophisticated aftertreatment architectures including diesel oxidation catalysts, diesel particulate filters, selective catalytic reduction, and urea dosing systems. These requirements increase upfront equipment complexity and cost for manufacturers, while also influencing service intervals, maintenance expectations, and operator training. At the same time, stricter site safety standards are strengthening demand for smart features that support operator protection and operational compliance. In this context, intelligence is no longer limited to productivity; it is increasingly tied to risk reduction, regulatory readiness, and site governance.
Cost and labor dynamics add further strategic tension. Volatility in raw material pricing raises equipment costs and puts pressure on producer margins, forcing manufacturers and distributors to balance specification upgrades with commercial viability. Concurrently, shortages of skilled operators limit effective equipment utilization and project efficiency, especially in environments where precision digging and controlled earthmoving are essential. These constraints are not purely operational; they directly affect the appeal of intelligent features such as semi-automatic control, machine guidance, and automated tilt and rotation assistance, because such technologies can offset labor scarcity and reduce reliance on highly specialized manual proficiency.
Taken together, these dynamics create a market where technology, regulation, and workforce realities intersect. The full study examines how these forces influence segment behavior across regions, machine types, and application areas without exposing the granular splits here. For leadership teams, the strategic implication is that 2026 decisions should be modeled around total value rather than purchase price alone, factoring in compliance costs, operator availability, uptime expectations, and the potential for intelligent features to stabilize project execution.
Competitive Configuration: Leaders, Systems, and Recent Moves
Market concentration and product differentiation define the competitive battleground for intelligent excavators. The landscape includes global manufacturers, regional specialists, and technology providers whose machine control platforms increasingly matter alongside the hardware itself. PW Consulting's analysis maps this ecosystem through company profiles, solution architectures, and recent commercial activity, enabling leaders to see not only who competes, but how competition is being expressed.
Several firms stand out for their intelligent excavator propositions. SANY America offers intelligent excavator models including the SY335 medium hydraulic excavator with load-sensing hydraulic systems and advanced operator display, reflecting a product strategy that emphasizes hydraulic efficiency and machine visibility. Komatsu produces intelligent excavators such as the PC220LCi-12 featuring integrated sensors and 3D design data for precision grading and reduced rework, positioning data-driven accuracy as a core value proposition. Caterpillar provides intelligent excavator solutions with advanced electrohydraulic systems and touchscreen interfaces for efficient operation, reinforcing the role of control architecture and operator interface design. Volvo Construction Equipment manufactures smart excavator models with machine guidance, Dig Assist, and electrohydraulic controls for precision digging, aligning product capability with site-level productivity and operator support.
Regional and technology-focused players are equally important. Doosan offers smart excavators like the DX225LC-7X with 2D machine guidance, semi-automatic control, laser receiver, and e-fence virtual wall, highlighting the convergence of guidance technology and boundary management. Hyundai Construction Equipment supplies smart excavators such as the R130 SMART and R85A SMART equipped with intelligent control systems, extending the reach of connected machine architectures in competitive export and domestic markets. XCMG Construction Machinery develops intelligent excavators including remote-controlled models with self-learning functions, pointing toward automation and adaptive machine behavior as emerging differentiators. CASE Construction Equipment delivers intelligent excavator models with integrated real-time blade control and operator assistance systems, reinforcing precision and operator workflow integration. Leica Geosystems provides the Leica MC1 machine control platform with CoPilot for automatic tilt and rotation control on excavators to improve efficiency and accuracy, underscoring the strategic role of third-party machine control technology in shaping end-user outcomes.
Recent commercial activity illustrates how quickly this landscape is moving. In March 2026, SANY America formally introduced the SY335 medium hydraulic excavator featuring load-sensing hydraulics, ROPS/FOPS-certified cab, advanced operator display, and Cummins L9 Stage V/T4F engine at ConExpo-CON/AGG 2026. Around the same period, Komatsu showcased its PC220LCi-12 intelligent excavator with integrated sensors and 3D design data at CONEXPO-CON/AGG 2026 to support excavation to grade with greater precision and reduce rework. These moves are not isolated product announcements; they signal a competitive tempo in which intelligent capability, emissions compliance, and operator experience are being advanced in parallel.
For enterprise strategists, the competitive analysis in the full report goes beyond company descriptions. It connects product positioning to market structure, regional reach, and technology differentiation, helping leaders assess where partnership, procurement, or competitive response is most likely to create durable advantage. Detailed segmentation splits are reserved for the complete study so that leadership teams can explore the data with the context required to interpret it correctly.
Report Content: What Decision-Makers Will Find Inside
The full Intelligent Excavator Market study is structured for applied decision-making. It integrates market sizing, structural analysis, competitive profiling, and operational context into a single intelligence framework. The intent is to support planning in product strategy, procurement, channel development, technology investment, and risk management.
Key components of the report include:
- Market sizing from 2020 through 2032, anchored on a 2025 base year and expressed in USD million, with forecast projections that map the growth path from $2.69 million in 2026 to $9.76 million in 2032.
- A market concentration assessment showing the share held by leading players, helping executives understand competitive density and the relative weight of major incumbents.
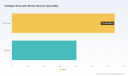
- Segment-level analysis across regions, machine types, and application areas, presented with the depth needed to identify where intelligent excavator demand is forming and how it is distributed.
- Company profiles and solution summaries for core participants, including attribute-level detail on machine control capabilities, operator interfaces, and technology differentiators.
- A review of recent developments and product activity, including launch and showcase events that reveal the current pace of innovation and market signaling.
- An integrated discussion of market dynamics, including emission regulation, safety standards, raw material cost volatility, and skilled labor constraints, tied directly to intelligent excavator planning.
Each section is designed to be actionable. For instance, the competitive section supports vendor evaluation and partnership selection; the dynamics section supports total cost modeling and compliance planning; and the sizing framework supports capacity, investment timing, and market entry decisions. By presenting the market as a connected system rather than a collection of isolated metrics, the study helps leaders align commercial strategy with the realities of how intelligent excavators are bought, specified, and used.
Strategic Implications for 2026 Planning
For leadership teams entering 2026, the intelligent excavator market presents a clear mandate: strategy must be informed by both growth ambition and structural complexity. The rapid expansion reflected in the forecast trajectory makes this a sector where delay can be costly, but the concentration profile and regulatory environment make it equally important to move with precision. A rushed investment in the wrong configuration, channel, or technology bundle can lock in disadvantage just as quickly as early commitment can secure advantage.
The study supports several core planning priorities. First, it helps organizations assess where intelligent functionality delivers the strongest operational return, particularly in contexts where grade accuracy, rework reduction, operator scarcity, and compliance requirements are most acute. Second, it provides a basis for evaluating competitive positions and technology ecosystems, enabling better judgments about procurement, supplier selection, and collaboration with machine control providers. Third, it frames the market in terms of total cost and risk, ensuring that emission compliance, aftertreatment complexity, raw material exposure, and operator availability are treated as strategic variables rather than isolated cost items.
Importantly, the report is built to support decisions at multiple levels. Executive teams can use it to set direction and prioritize investment; product and engineering leaders can use it to benchmark intelligent capabilities and identify differentiation opportunities; and commercial and procurement teams can use it to structure sourcing and market engagement with greater clarity. The analysis is broad enough to inform enterprise strategy and detailed enough to guide operational follow-through.
Conclusion: From Signal to Decision
The Intelligent Excavator Market is expanding at a pace that demands disciplined intelligence, not intuition alone. Growth from $0.7 million in 2020 to a projected $9.76 million by 2032, with a CAGR of 24.54%, signals a market in which technology-enabled excavators are becoming central to competitive construction, transportation, mining, and specialized applications. Yet scale alone does not tell leaders where to act. Concentration, regulation, cost volatility, operator scarcity, and product differentiation all shape the practical choices that determine success in 2026 and beyond.
This article has previewed the strategic architecture of the PW Consulting study: the macro trajectory, the dynamic forces, the competitive landscape, and the operational content designed for applied decision-making. What it has not done is reveal the full segment-level detail that makes the analysis directly usable for specific planning scenarios. That deeper intelligence resides in the complete report, where regional nuance, type-level comparison, application-level distribution, and company-level positioning are presented together with the analytical context needed to act on them.
For executives who need to move from signal to strategy, the full market research provides the structured view required to make 2026 decisions with confidence. The opportunity is substantial, the competitive tempo is accelerating, and the cost of incomplete information is rising. PW Consulting's Intelligent Excavator Market study is built to close that gap.
Excavator Market
For detailed analysis of this topic, please visit the official page: Intelligent Excavator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Centrifugal Pump Market Hits $215M in 2025, Projects 6% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Insights into the 2026 Centrifugal Pump Market Dynamics
Executive Overview
The global centrifugal pump industry stands at a pivotal juncture as we move through 2026. Driven by intensifying regulatory frameworks, evolving industrial demands, and a steady trajectory of growth, the market presents both significant opportunities and complex challenges for stakeholders. As strategic advisors, we recognize that understanding the nuanced shifts in this sector is no longer optional—it is imperative for sustainable competitive advantage. This article serves as an introduction to our comprehensive market research, designed to equip decision-makers with the intelligence required to navigate the forecast period from 2026 to 2032.
The industry has demonstrated resilience and consistent expansion over the past five years. Historical data indicates a steady climb in revenue, reflecting the essential nature of fluid movement across municipal, industrial, and infrastructure sectors. As organizations plan their capital expenditures and operational strategies for the remainder of the decade, having access to granular data regarding market sizing, growth rates, and segmentation is critical. Our latest study dissects these elements to provide a clear roadmap for investment and development.
Market Trajectory and Macro Economic Indicators
Analyzing the historical performance from 2020 through 2025 reveals a robust upward trend that sets the stage for the current forecast period. The market has consistently expanded, moving from a base of approximately 163.15 million USD in 2020 to an estimated 215.0 million USD in 2025. This growth underscores the fundamental reliance on centrifugal technology across diverse end-use industries. As we look forward, the momentum is expected to continue, with projections indicating the market will reach 227.68 million USD in 2026 and potentially ascend to 344.8 million USD by 2032.
The compound annual growth rate (CAGR) during the forecast period is estimated at 6.0 percent. This metric is vital for long-term planning, suggesting a steady, albeit competitive, expansion environment. For enterprises involved in manufacturing, distribution, or procurement, this growth rate signals a market that is mature enough to offer stability yet dynamic enough to reward innovation. However, capturing this growth requires more than just historical context; it demands an understanding of where the volume is shifting geographically and technically.
Our research delves deep into the specific valuation shifts expected over the next six years. While the aggregate numbers provide a high-level view, the true value lies in understanding the underlying drivers pushing these figures. We have mapped the revenue projections year-by-year to help stakeholders benchmark their internal growth targets against market realities. This longitudinal analysis highlights inflection points where market acceleration may occur due to regulatory changes or technological adoption curves.
Segmentation Dynamics: Type and Application
The market is broadly categorized by pump configuration and end-use application, each presenting distinct growth vectors. In terms of pump type, the landscape is divided primarily between single-stage and multi-stage configurations. The single-stage segment currently holds a significant portion of the market value, reflecting its widespread use in general industrial and municipal applications. However, the multi-stage segment is gaining traction, driven by the need for higher pressure and efficiency in specialized processes.
On the application front, the diverse range of industries utilizing centrifugal pumps ensures market stability. Water and wastewater management remains a cornerstone of demand, consistent with global infrastructure development goals. Beyond this, the oil and gas sector, chemical and petrochemical processing, and mining and metals industries contribute substantial revenue streams. Each application vertical has unique operational requirements regarding durability, flow rate, and compliance with safety standards.
Understanding the interplay between these segments is crucial. For instance, regulatory pressures in the water sector may accelerate the adoption of specific pump types, while harsh environments in mining may sustain demand for robust single-stage solutions. Our report provides a detailed breakdown of these segmentation splits without relying on generic industry assumptions. We analyze the value distribution across these categories to identify which areas offer the highest margin potential and which are becoming commoditized.
Regional Growth Vectors
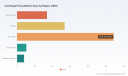
Geographically, the market exhibits varied growth patterns influenced by local industrialization rates, infrastructure spending, and regulatory environments. The Asia Pacific region represents a significant volume driver, reflecting rapid urbanization and industrial expansion. Europe continues to be a mature market where efficiency standards and sustainability mandates heavily influence procurement decisions. North America remains a key hub for technological innovation and high-reliability industrial applications.
Emerging regions in Latin America and the Middle East and Africa also contribute to the global revenue pool, often driven by specific infrastructure projects or resource extraction activities. While the aggregate global number is important, the strategic nuance lies in recognizing regional disparities. Supply chains, local competition, and import-export dynamics vary significantly across these territories. Our analysis maps these regional contributions to help companies tailor their market entry or expansion strategies effectively.
We have assessed the revenue contribution from each major region to highlight where the growth hotspots are located for the forecast period. This regional intelligence allows stakeholders to allocate resources more efficiently, avoiding saturated markets while capitalizing on emerging opportunities. The data provided in our full study offers a clear view of regional market sizes, enabling precise geographic targeting.
Regulatory Landscape and Industry Dynamics
One of the most critical factors influencing the centrifugal pump market in 2026 is the tightening regulatory environment. Governments worldwide are increasingly focusing on energy efficiency and carbon footprint reduction, directly impacting pump specifications and replacement cycles. In the United States, Department of Energy rules effective January 2025 set new energy-index thresholds. These regulations are accelerating the swap-out of inefficient single-stage centrifugal pumps, forcing manufacturers and end-users to reconsider their equipment portfolios.
Centrifugal Compressors Market
Similarly, the European market is preparing for significant changes. IE4 motor stipulations set to become effective in 2027 are expected to advance the adoption of variable-speed multi-stage centrifugal pumps. These regulations are not merely compliance hurdles; they are catalysts for technological upgrading. Companies that anticipate these shifts can gain a first-mover advantage by stocking compliant inventory or offering retrofit solutions before the deadlines hit.
These regulatory drivers are converging to shape the overall market dynamics. The push for energy efficiency is aligning with operational cost reduction goals, making high-efficiency pumps an attractive investment despite potentially higher upfront costs. Our report analyzes how these regulatory measures interact with market demand, estimating the potential impact on replacement rates and new installations. We explore the compliance landscape in detail, providing a risk assessment for non-compliance and an opportunity analysis for early adopters.
Competitive Landscape and Key Players
The market structure is characterized by a mix of global giants and specialized niche manufacturers. The top three companies hold a combined market share of 35.5 percent, while the top five account for 39.8 percent. This concentration suggests a competitive environment where large players dominate through scale and brand equity, but significant room remains for specialized firms to capture value through innovation and service excellence.
Several key companies define the current competitive landscape. Grundfos Holding A/S, based in Denmark, continues to be a major force in manufacturing energy-efficient centrifugal pumps for municipal, industrial, and building applications. Their focus on sustainability aligns well with current regulatory trends. Xylem Inc., headquartered in the United States, provides IoT-enabled centrifugal pumps for utilities, water treatment, and industrial sectors, representing the technological integration trend within the industry.
Flowserve Corporation specializes in large-scale, high-reliability centrifugal pumps for oil and gas, chemical, and power industries, catering to the high-end industrial segment. Sulzer Ltd, from Switzerland, offers precision centrifugal pumps for refining, chemicals, and water systems, maintaining a reputation for engineering excellence. KSB Group, based in Germany, produces automation-ready centrifugal pumps for industrial and infrastructure applications, highlighting the shift towards smart manufacturing integration.
In the Americas, Gorman-Rupp Company manufactures high-performance centrifugal pumps for municipal, industrial, and construction markets, maintaining a strong regional presence. Carver Pump Company builds military-grade centrifugal pumps for demanding industrial, marine, and process applications, serving niche high-durability needs. Ampco Pumps Company offers sanitary and industrial centrifugal pumps with ISO 9001:2015 compliance, focusing on quality assurance in sanitary sectors. Cornell Pump Company, also based in the United States, produces efficient, Made-in-USA centrifugal pumps for agriculture, municipal, and industrial use, recently celebrating its 80th anniversary with a focus on efficient by design pumps at ConExpo in April 2026. Finally, SPP Pumps from the United Kingdom specializes in engineered centrifugal pump packages and systems for industrial applications, offering customized solutions.
Our analysis goes beyond corporate profiles to examine recent developments and strategic moves. For example, Cornell Pump Company's recent milestone highlights the enduring value of domestic manufacturing and efficiency-focused design. We track how these companies are responding to regulatory pressures and technological shifts. The full report includes a detailed competitive benchmarking analysis, evaluating each player's market position, product portfolio strength, and strategic response to industry dynamics.
Centrifugal Pump Market
Strategic Implications for Stakeholders
For manufacturers, the key to success in 2026 and beyond lies in aligning product portfolios with regulatory roadmaps. Developing pumps that meet upcoming IE4 standards or DOE energy indices is not just about compliance; it is about future-proofing the product line. Investment in R&D for variable-speed drives and energy-efficient motor integrations will likely yield higher returns as customers seek to reduce operational expenditures.
For distributors and supply chain partners, understanding the segmentation shifts is vital. As multi-stage and variable-speed pumps gain share due to regulations, inventory strategies must adapt. stocking legacy single-stage models may become risky as replacement mandates take effect. Partners need to ensure they have the technical expertise to support the installation and maintenance of next-generation equipment.
End-users and industrial operators must consider the total cost of ownership rather than just the purchase price. With energy costs and regulatory penalties potentially rising, the economic case for high-efficiency pumps strengthens. Procurement strategies should factor in the lifespan of equipment relative to regulatory deadlines, ensuring that capital investments do not become stranded assets due to non-compliance.
Investors looking at the sector should focus on companies with strong R&D pipelines andadaptive supply chains. The concentration of market share among the top players indicates barriers to entry, but innovation can disrupt existing hierarchies. Companies that successfully integrate IoT capabilities or offer superior service models may outperform the average market growth rate.
Research Methodology and Value Proposition
Our market study is constructed using a robust methodology that combines top-down and bottom-up analysis. We utilize historical data to validate growth trends and apply stringent forecasting models to project future performance. The data is sourced from primary interviews with industry participants, supply chain partners, and regulatory bodies, supplemented by extensive secondary research.
The report provides actionable intelligence beyond mere market sizing. It includes detailed segmentation analysis, competitive profiling, and regulatory impact assessments. We examine the supply chain dynamics, identifying key bottlenecks and opportunities for optimization. The forecast period analysis is granular, allowing users to model different scenarios based on varying assumptions about economic conditions and regulatory enforcement.
By consolidating this information into a single comprehensive document, we save stakeholders the time and resources required to gather disparate data points. The insights provided are designed to support strategic planning, market entry decisions, investment analysis, and operational benchmarking. Every claim and projection is backed by data, ensuring that decision-makers can rely on the findings with confidence.
Conclusion and Next Steps
The centrifugal pump market in 2026 is defined by a convergence of steady growth, regulatory pressure, and technological evolution. With a projected CAGR of 6.0 percent and a market size expected to exceed 340 million USD by 2032, the sector offers substantial potential for those equipped with the right intelligence. The shift towards energy efficiency, driven by DOE rules and European IE4 stipulations, will reshape demand patterns, favoring advanced multi-stage and variable-speed solutions.
Navigating this landscape requires more than general industry knowledge. It demands precise data on segmentation values, regional contributions, and competitive movements. While this article provides a high-level overview of the market dynamics and key players, it intentionally omits specific segmentation percentages and detailed regional breakdowns to maintain the integrity of our proprietary research.
To fully leverage these insights for your strategic planning, we invite you to access the complete Centrifugal Pump Market report. The full study contains the detailed data tables, comprehensive company profiles, and in-depth regulatory analysis necessary to make informed decisions in this evolving market. Secure your copy today to ensure your organization remains ahead of the curve in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Centrifugal Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports BabyNes Market to Hit $269.26M by 2032 with 5.85% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Infant Nutrition Sector: Unlocking Value in the BabyNes Market Through 2032
The global infant nutrition landscape is undergoing a structural transformation, driven by shifting parental preferences, technological integration, and an increasing demand for convenience without compromising nutritional integrity. As we navigate the post-pandemic recovery and subsequent market stabilization, the BabyNes ecosystem has emerged as a focal point for strategic investment and product innovation. PW Consulting presents this comprehensive market research to equip industry leaders with the analytical rigor required to make informed decisions in 2026 and beyond. This report does not merely recount historical performance; it constructs a forward-looking framework that aligns market trajectories with actionable business strategies.
Understanding the macroeconomic currents shaping this sector is critical for any organization seeking to capture sustainable market share. Over the historical period from 2020 through 2025, the global BabyNes market demonstrated remarkable resilience, navigating supply chain disruptions and evolving regulatory environments to reach a robust valuation. The consistent upward trajectory reflects a fundamental shift in consumer behavior, where time-poor parents are willing to premiumize their purchasing decisions for systems that offer precision, hygiene, and ease of use. Building on this established foundation, our forecasting models project the market to advance steadily through the decade, supported by a compound annual growth rate of 5.85 percent. This sustained expansion signals a mature yet dynamic environment where early movers and agile adapters will disproportionately benefit from the widening addressable market.
Decoding the Market Trajectory: From Historical Baselines to Long-Term Forecasts
The historical data tells a compelling story of momentum. Starting from a baseline of 140.25 million USD in 2020, the market steadily accelerated, crossing the 150 million USD threshold in 2021 and solidifying its position with incremental but meaningful gains through 2022 and 2023. A notable inflection occurred in 2024, when revenue surged to 178.08 million USD, reflecting renewed consumer spending power and successful product launches that captured latent demand. By 2025, the market settled at 181.75 million USD, providing a stable launchpad for the forecast period. Looking ahead, our analytical models anticipate the market will breach the 190 million USD mark in 2026, followed by continuous appreciation that positions the sector at 269.26 million USD by 2032. This trajectory is not a linear extrapolation; it incorporates adjustment factors for macroeconomic volatility, competitive intensity, and technological adoption curves. For executives, this means that 2026 represents a critical inflection point where strategic positioning, capacity allocation, and partnership ecosystems will determine long-term profitability.
Product Portfolio Architecture and Application Segmentation
The BabyNes market is characterized by a diversified product architecture that caters to varying infant developmental stages and parental usage patterns. Our research dissects the product landscape into distinct categories, revealing how different system configurations drive adoption across consumer segments. The dominant product tier registers a substantial market footprint, underscoring the preference for integrated, advanced nutrition systems that combine automated preparation with tailored nutritional profiles. Secondary and tertiary product lines maintain meaningful presence, often serving niche requirements or acting as entry points for consumers transitioning into premiumized feeding routines. Understanding the relative weight and growth velocity of each product category is essential for manufacturers designing go-to-market strategies, pricing architectures, and inventory planning.
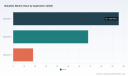
Application segmentation further illuminates how these systems are deployed across different consumer contexts. The primary application driver accounts for the largest utilization share, reflecting widespread adoption among mainstream parents seeking reliable, everyday solutions. Secondary applications capture a robust portion of the market, often aligned with specific lifestyle preferences or targeted demographic segments. Tertiary applications, while smaller in relative scale, represent high-potential growth pockets where specialized positioning and targeted marketing can yield outsized returns. Our report provides a granular examination of these application dynamics, enabling stakeholders to identify white spaces, optimize channel mix, and tailor messaging to the precise needs of each consumer cohort.
Geographic Distribution and Regional Strategic Priorities
The global footprint of the BabyNes market reveals distinct regional characteristics that demand tailored strategic responses. North America continues to command the largest regional share, reflecting entrenched premiumization trends, high digital adoption rates, and a well-established retail infrastructure that supports specialty infant nutrition products. Europe maintains a strong and stable position, shaped by stringent regulatory frameworks, strong consumer advocacy for infant health, and a cultural emphasis on evidence-based parenting solutions. The Asia Pacific region presents a compelling growth narrative, propelled by expanding middle-class demographics, increasing urbanization, and a rapidly modernizing retail ecosystem that accommodates innovative feeding technologies. Latin America and the Middle East and Africa regions, while smaller in current valuation, are emerging as frontier markets where early brand establishment and localized distribution strategies can secure long-term loyalty and market leadership.
These regional dynamics are not static. Currency fluctuations, import regulations, cultural attitudes toward formula preparation systems, and the pace of retail modernization all influence market penetration rates. Our analysis maps these variables against revenue distributions, providing a nuanced view of where capital should be deployed, which partners offer the most reliable market access, and how regulatory pathways may accelerate or constrain market entry. Decision-makers will find actionable intelligence on regional prioritization, allowing them to allocate resources efficiently and mitigate cross-border execution risks.
Competitive Landscape: The Imperative of Ecosystem Leadership
The competitive environment in the BabyNes market is defined by a handful of focused players who have invested heavily in proprietary technology, brand trust, and consumer education. Among the notable entities shaping this landscape is Gerber Products Company, headquartered in Arlington, Virginia. Gerber has strategically positioned itself through the BabyNes Advanced Nutrition System, a WiFi-enabled formula preparation machine paired with single-serve capsules engineered to align with infants' evolving nutritional requirements. This integrated approach exemplifies the broader industry shift toward closed-loop ecosystems that combine hardware precision with consumable convenience. By embedding connectivity and stage-specific formulations into a single user experience, such offerings raise the barrier to entry for generic competitors while strengthening brand lock-in among engaged parents.
The market concentration metrics reinforce the reality of a moderately fragmented yet competitively intense arena. The top three players collectively command approximately 25.3 percent of total revenue, while the top five expand that share to 29.7 percent. This concentration profile suggests that while market leadership is attainable, no single entity has achieved overwhelming dominance. The gap between the incumbents and the broader field presents strategic opportunities for challenger brands, private-label entrants, and technology-focused startups that can differentiate through innovation, pricing agility, or channel partnerships. Our competitive analysis delves into positioning strategies, product differentiation levers, and potential consolidation scenarios, offering a roadmap for both defending market position and pursuing aggressive expansion.
Structural Intelligence and Decision Support Framework
Beyond high-level sizing and segmentation, this report delivers a comprehensive operational toolkit designed to translate market intelligence into executable strategy. The research encompasses detailed technology assessment, including an evaluation of automation capabilities, connectivity features, and consumables supply chain dynamics that influence total cost of ownership and user retention. Consumer behavior analysis is woven throughout, examining purchase triggers, substitution patterns, and the role of digital engagement in driving trial and repeat usage. Pricing architecture is dissected across product tiers and regional contexts, revealing margin structures, promotional effectiveness, and the elasticity dynamics that shape revenue optimization.
Supply chain and manufacturing considerations receive dedicated attention, given the precision requirements of capsule-based systems and the logistical complexity of coordinating hardware production with consumable fulfillment. Regulatory compliance is mapped across key jurisdictions, highlighting labeling standards, ingredient restrictions, and certification pathways that can accelerate time-to-market or introduce friction for unprepared entrants. Distribution channel analysis covers retail, e-commerce, and direct-to-consumer models, assessing margin profiles, customer acquisition costs, and the strategic role of partnerships with pediatricians, parenting platforms, and premium baby retailers. Each of these dimensions is structured to support scenario planning, allowing leadership teams to stress-test assumptions and align operational capabilities with market realities.
Implications for 2026 Strategic Planning
As organizations finalize their 2026 roadmaps, the BabyNes market offers a unique convergence of growth potential and execution complexity. The projected revenue ascent to 193.97 million USD in 2026, followed by progressive expansion through 2032, underscores the importance of timely investment in product development, channel expansion, and consumer education. However, growth alone does not guarantee profitability. The moderate concentration levels indicate that competitive differentiation will remain a decisive factor, requiring brands to articulate clear value propositions that resonate with informed, digitally engaged parents. Companies that proactively address consumables replenishment dynamics, invest in user experience refinements, and build trust through transparent nutritional messaging will be better positioned to capture recurring revenue and reduce churn.
Strategic resource allocation should also account for the varying maturity profiles across regions and application segments. Markets with established premiumization habits may reward incremental innovation and brand reinforcement, while emerging regions may demand heavier investment in awareness building, distribution partnerships, and localized product adaptations. The interplay between hardware penetration and consumable attach rates further complicates forecasting, making it essential to model unit economics across the full product lifecycle. Our report provides the analytical scaffolding to navigate these complexities, enabling decision-makers to prioritize initiatives that deliver measurable impact and sustainable competitive advantage.
Anticipating Future Disruption and Technological Evolution
The trajectory of the BabyNes market will be shaped not only by current demand patterns but also by the pace of technological innovation and shifting parental expectations. Advances in sensor technology, machine learning-driven usage analytics, and integrated health monitoring could further elevate the value proposition of smart preparation systems, transforming them from convenience devices into comprehensive infant nutrition platforms. Simultaneously, sustainability considerations are gaining prominence, with consumers increasingly scrutinizing packaging materials, manufacturing footprints, and the environmental implications of single-use consumables. Brands that proactively address these themes through recyclable designs, efficient logistics, and transparent lifecycle communication will likely gain preference among environmentally conscious demographics.
Baby Clothing Market
Regulatory evolution will also play a defining role, particularly as health authorities refine guidelines around infant formula composition, preparation hygiene, and digital device safety. Proactive compliance planning and early engagement with regulatory bodies can convert potential constraints into competitive moats, especially for companies that invest in rigorous testing and evidence-based product claims. The convergence of health, technology, and convenience suggests that the boundary between traditional infant nutrition and digital health ecosystems will continue to blur, opening new avenues for partnership, data-informed personalization, and cross-category brand extension.
Why This Report Matters for Executive Decision-Making
In an environment where market information is abundant but actionable intelligence is scarce, this research distinguishes itself through depth, precision, and strategic relevance. The analysis avoids superficial summaries and instead provides a layered examination of market structure, competitive behavior, and consumer dynamics that can be directly integrated into product planning, commercial strategy, and investment prioritization. By combining historical validation with forward-looking forecasts, the report equips leadership teams with the confidence to make bold decisions while maintaining a disciplined approach to risk management. The inclusion of detailed segmentation insights, regional assessments, and competitive profiling ensures that stakeholders can move beyond aggregate numbers to uncover the specific levers that will drive performance in their respective contexts.
BabyNes Market
Access to granular data, scenario models, and operational benchmarks is essential for organizations that intend to act decisively in 2026. The complete report delivers this depth, offering a comprehensive view of market sizing, growth drivers, segmentation nuances, and strategic recommendations that are not fully captured in summary formats. We invite executives, strategy teams, and investment professionals to engage with the full research suite to secure the intelligence required for targeted market entry, portfolio optimization, and long-term value creation. The BabyNes market is poised for sustained expansion, but the rewards will accrue to those who combine analytical clarity with disciplined execution.
Access the Complete Strategic Intelligence Suite
The insights summarized here represent only a portion of the analytical content available in the full PW Consulting BabyNes Market Research report. To obtain the complete dataset, detailed segmentation breakdowns, regional revenue distributions, product-level dynamics, and actionable strategic frameworks, we encourage you to access the full report through our official research portal. The comprehensive version includes proprietary forecasting models, competitive benchmarking matrices, and implementation playbooks designed to support executive decision-making at every stage of market engagement. Secure your copy today and ensure your organization is equipped with the intelligence necessary to navigate the opportunities and complexities of the BabyNes market through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: BabyNes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Container Leasing Market Hits $9.8B in 2025, Projected to Reach $13.1B by 2032
By PW Consulting, 2026-09-16
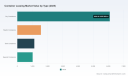
Strategic Horizons in the Container Leasing Market: Navigating Growth and Consolidation Through 2032
The global logistics infrastructure stands at a critical inflection point. As supply chains recalibrate following years of unprecedented disruption, the container leasing sector has emerged not merely as a support function but as a strategic lever for capital efficiency and operational resilience. PW Consulting is pleased to introduce our latest comprehensive study on the Container Leasing Market, designed to equip executive leadership and investment committees with the actionable intelligence required to navigate the forecast period from 2026 through 2032.
Railcar Leasing Market
This research is not a static snapshot of historical performance. It is a dynamic roadmap built upon rigorous analysis of market trajectories, competitive maneuvers, and macroeconomic shifts. For decision-makers evaluating capital allocation, fleet expansion, or partnership strategies in 2026, understanding the underlying mechanics of this industry is paramount. The following insights offer a preview of the strategic depth contained within our full report, highlighting the forces that will define value creation in the coming years.
Market Trajectory: From Recovery to Steady Expansion
The container leasing market has demonstrated remarkable resilience and growth over the past half-decade. Our analysis tracks revenue trends from 2020 through the base year of 2025, revealing a consistent upward trajectory despite volatile macroeconomic conditions. The market has evolved from a post-pandemic recovery phase into a period of stabilized expansion. Current valuations indicate that the industry has surpassed significant milestones, positioning itself for continued growth as global trade volumes normalize and optimize.
Looking forward, our forecast model projects a compound annual growth rate of 4.3 percent across the forecast horizon. This growth is not linear but is influenced by varying regional dynamics and sector-specific demands. By 2032, the market is expected to reach a substantially higher revenue baseline, reflecting both organic expansion and the compounding effect of strategic consolidations. For stakeholders, this implies that the window for acquiring assets at favorable valuations or securing long-term lease agreements may shift as demand pressures intensify in specific segments.
The revenue projection extends across multiple years, allowing clients to model cash flows and asset depreciation with greater precision. Our data suggests that while growth rates may fluctuate in the short term due to geopolitical or supply chain variables, the long-term fundamental demand for intermodal transport equipment remains robust. The transition from the base year into the forecast period highlights a market that is maturing, where efficiency and scale become increasingly decisive competitive advantages.
Industry Dynamics and Operational Headwinds
No strategic plan is complete without a clear understanding of the forces currently reshaping the operating environment. In 2025, the industry faced a unique confluence of challenges and opportunities. One of the most significant factors was the impact of geopolitical tensions on shipping routes. Attacks on shipping vessels in the Red Sea necessitated major rerouting, which in turn elevated demand for containers as supply chain disruptions forced companies to secure additional equipment to maintain throughput. This surge in demand during 2024 and 2025 altered inventory levels and utilization rates across the global fleet.
Paradoxically, while demand for equipment was elevated due to these disruptions, market leasing rates remained historically low throughout 2025 and into the beginning of 2026. This divergence presents a complex scenario for lessors and lessees alike. For shipping line customers, the reliance on leasing for new container additions decreased significantly amid elevated demand, suggesting a shift in procurement strategies or an increase in owned fleets during this period. Understanding why rates remained suppressed despite high demand is crucial for forecasting future pricing power and lease negotiation leverage.
Operational standards continue to dictate market participation. Containers must meet International Standards Organization criteria for size and gross weight rating to ensure standardization and facilitate container and vessel sharing across transporters. Compliance with these ISO criteria is not just a regulatory hurdle but a prerequisite for interoperability in a globalized network. Any analysis of market entry or fleet modernization must account for the capital intensity required to maintain these standards while adapting to evolving environmental regulations.
Furthermore, specific segments face distinct cost pressures. In the European chemical industry, high energy and feedstock costs, combined with regulatory and environmental pressures and weak downstream demand, have affected competitiveness and resulted in reduced production levels of tank containers. This dynamic illustrates how end-market health directly influences the manufacturing and availability of specialized leasing assets. For investors focused on niche segments such as tank containers, these upstream cost structures are vital indicators of future supply constraints and pricing potential.
Competitive Landscape: Consolidation and Specialization
The competitive structure of the container leasing market is characterized by high concentration and strategic differentiation. Our analysis indicates that the top three players command a significant share of the market, with the top five firms further solidifying their dominance. This concentration suggests that scale advantages in fleet management, depot networks, and customer relationships are difficult to replicate for smaller entrants. However, within this consolidated landscape, distinct strategies are emerging that define the leaders.
Triton International Limited stands as the world's largest lessor of intermodal containers. Headquartered in Hamilton, Bermuda, Triton owns and manages a fleet exceeding 7 million TEU as of December 31, 2025, supported by a global depot network spanning 47 countries. Their primary customers include major shipping lines, and their strategic footprint was recently enhanced when Triton entered an agreement to acquire Global Container International, adding approximately 0.5 million TEU to its fleet. This move underscores a strategy of aggressive capacity expansion to maintain market leadership.
Container Leasing Market
Textainer Group Holdings Limited represents another tier of dominance. Also based in Hamilton, Bermuda, Textainer manages a diversified fleet including dry, reefer, and tank types. In a landmark development during December 2025, Textainer completed the acquisition of Seaco Global. This combination brought their fleets to approximately 8.3 million CEU, making it the world's largest diversified container leasing platform. This consolidation signals a trend where lessors seek to broaden their asset mix to mitigate cycle risks and capture value across different container types.
Specialization remains a key theme for other major players. SeaCube Container Leasing Ltd., based in San Francisco, California, is the world's largest lessor of refrigerated containers. Their focus on cold-chain logistics solutions, portable cold storage, and management contracts differentiates them from generalist lessors. SeaCube has been actively expanding its cold-chain infrastructure, such as establishing a primary depot in Shafter, California, and partnering with The Wonderful Company to support refrigerated container presence in the California Central Valley. These moves highlight the growing importance of temperature-controlled logistics in the overall market mix.
Florens Asset Management Co. Ltd., operating out of Singapore, is one of the world's leading container lessors, leasing, managing, and selling containers worldwide to top 20 shipping companies. Their focus on flexible operating and finance leases allows them to cater to varied customer financial preferences. Recent leadership changes, including the appointment of a new Director and Chairman effective May 2025, suggest a strategic refresh aimed at navigating the next phase of growth.
Other significant participants include CAI International, a major intermodal container leasing provider emphasizing global fleet management and equipment services. Blue Sky Intermodal (UK) Ltd. offers long-term operating and finance leases of ISO marine containers to shipping lines, maintaining a strong presence in the European market. CARU Containers provides standard and specialized container leasing solutions globally, while Noble Container Leasing Limited, based in Hong Kong SAR, focuses on engineering innovation and environmental responsibility in marine container leasing and trading.
The tank container segment features its own set of leaders. Raffles Lease, headquartered in Singapore, is a leader in tank container leasing, providing flexible ISO tank container solutions with offices in key logistics hubs. Eurotainer, with European operations, is a global leader in ISO tank container leasing and logistics solutions, offering temperature-controlled, cryogenic, and food-grade tank containers with updated fleet designs. EXSIF Worldwide Inc. also claims status as a global leader in ISO tank container leasing, managing a fleet of over 70,000 tanks with strategic partnerships and 17 offices worldwide. The differentiation in this segment often revolves around specialized equipment capabilities and geographic reach to serve chemical and food-grade logistics.
Segmentation: Understanding Asset and Application Mix
To fully grasp the investment potential and risk profile of the container leasing market, one must look beyond aggregate numbers. The market is segmented by container type, application, and region, each presenting unique growth drivers and challenges. Our report dissects these segments to reveal where value is being generated.
By type, the market encompasses dry containers, reefer containers, tank containers, and special containers. Dry containers continue to represent the bulk of the fleet due to their versatility in general cargo transport. However, the reefer segment is gaining strategic importance as cold-chain logistics become critical for pharmaceuticals and perishable goods. Tank containers serve specialized liquid and gas transport needs, often tied to the chemical and energy sectors, while special containers cater to oversized or unique cargo requirements. The interplay between these types affects fleet utilization rates and residual values.
In terms of application, industrial product transport, consumer goods transport, food transport, and other categories drive demand. Industrial product transport typically correlates with manufacturing output and raw material movement. Consumer goods transport is linked to retail cycles and e-commerce growth. Food transport is sensitive to seasonal factors and cold-chain infrastructure availability. Understanding the mix of these applications within a lessor's portfolio is essential for predicting revenue stability across economic cycles.
Regional dynamics also play a crucial role. The Asia Pacific region remains a central hub for manufacturing and trade, influencing container flows significantly. North America and Europe represent mature markets with established logistics networks but face specific regulatory and cost environments. Latin America and the Middle East and Africa offer emerging opportunities driven by infrastructure development and trade route shifts. Our analysis provides detailed insights into how these regional factors interact with global fleet deployments without exposing specific valuation figures that require deeper consultation.
Strategic Imperative for 2026 Decision-Making
Why does this level of detail matter for your 2026 strategy? The answer lies in the intersection of market timing, asset specificity, and competitive positioning. The forecast period from 2026 to 2032 will likely see continued consolidation among major lessors as they seek to optimize fleet sizes and expand geographic coverage. Companies that understand the implications of recent acquisitions, such as those completed by Triton and Textainer, will be better positioned to anticipate shifts in supply availability and pricing power.
For shipping lines and logistics providers, the decision to lease versus buy is influenced by historical low leasing rates and the availability of owned assets. However, as the market 사이클 matures and demand pressures from geopolitical disruptions persist, the balance may tip. Our report provides the frameworks to evaluate these trade-offs under various scenarios. For investors, the high concentration of the market suggests that private equity and M&A activity will remain vibrant, particularly around specialized firms with strong niche positions in reefers or tank containers.
Environmental regulations and technological innovations are also reshaping the landscape. Newer fleet designs, such as those promoted by Eurotainer and Noble Container Leasing, focus on efficiency and environmental responsibility. These factors are increasingly influencing customer selection criteria and may impact the residual value of older assets. Decision-makers need to incorporate these lifecycle costs and compliance requirements into their long-term planning.
Furthermore, the volatility seen in 2025 regarding leasing rates versus demand highlights the importance of agile fleet management. Companies that can dynamically redeploy assets across regions or container types may capture opportunities that static models miss. Our research offers performance indicators and trend analysis to support such agility.
Accessing the Full Intelligence
This overview provides a foundation for understanding the strategic landscape of the Container Leasing Market. However, the nuances that drive precise valuation, risk assessment, and opportunity identification are contained within the full body of our research. PW Consulting's detailed report includes granular data on market sizing, segmentation splits, competitive profiling, and scenario-based forecasts that are essential for high-stakes decision-making.
We invite stakeholders to leverage this comprehensive intelligence to refine their strategies for 2026 and beyond. By accessing the complete study, you will gain the insights necessary to navigate the complexities of fleet management, capital allocation, and market entry in a consolidating and evolving global industry. The data presented here is a testament to the rigor of our analysis, but the full picture requires a deeper dive into the specific metrics and strategic recommendations available in our finalized market research publication.
For detailed analysis of this topic, please visit the official page: Container Leasing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Urine Analyzer Market Hits $532M in 2025, Projected to Reach $749M by 2032 at 5.1% CAGR
By PW Consulting, 2026-09-16
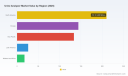
Strategic Intelligence for the Urine Analyzer Market: Navigating Growth and Consolidation Through 2032
The global urine analyzer market stands at a critical inflection point, where technological advancement, regulatory shifts, and evolving clinical workflows converge to reshape competitive dynamics. For executives, procurement leaders, and investment strategists, understanding the trajectory of this segment is no longer a tactical exercise but a core component of long-term capacity planning and portfolio optimization. Our latest market research report, covering the historical period from 2020 through 2025 and extending forecast insights to 2032, provides a rigorous, data-driven foundation for decision-making across healthcare systems, diagnostic networks, and medical device enterprises.
This strategic overview synthesizes the macro-level trends, structural shifts, and competitive intensities that define the urine analyzer landscape. It is designed to equip leadership teams with the contextual intelligence necessary to anticipate demand fluctuations, evaluate partnership opportunities, and align product roadmaps with emerging clinical and regulatory realities. While aggregate metrics offer a high-level view of market directionality, the full depth of segmentation, regional demand patterns, and application-specific growth vectors remains embedded within the complete report. Access to those granular intelligence layers is essential for precise capital allocation and market-entry strategy formulation.
Hematology Analyzer Market
Macro Market Trajectory and Demand Evolution
The urine analyzer sector has demonstrated consistent expansion over the past half-decade, driven by rising prevalence of chronic metabolic and renal conditions, increasing adoption of automated diagnostic workflows, and broader integration of urinalysis into routine preventive screening protocols. Historical revenue data reflects a sector that has moved steadily upward, with base-year valuation in 2025 establishing a clear foundation for forward momentum. Projections through 2032 indicate continued growth, supported by sustained capital investment in diagnostic infrastructure, expanding laboratory networks, and the gradual transition from manual or semi-automated processes to fully integrated digital platforms.
The compound annual growth rate across the forecast window underscores a moderately paced but structurally resilient expansion profile. Rather than exhibiting volatile spikes, the market reflects a measured adoption curve influenced by procurement cycles, regulatory clearance timelines, and institutional budgeting rhythms. For enterprise planners, this growth pattern signals the importance of phased deployment strategies, lifecycle pricing models, and service-contract architectures that align with multi-year adoption timelines. Understanding where volume concentration is likely to emerge, and which clinical environments will drive recurring reagent and consumables demand, requires the detailed breakdown available in the full research publication.
Urine Analyzer Market
Competitive Landscape and Strategic Positioning
The market exhibits a pronounced concentration dynamic, with a limited number of established manufacturers commanding dominant share positions. This consolidation pattern shapes pricing architecture, distribution leverage, and the pace at which new entrants can secure clinical validation and procurement contracts. The leading players have built competitive moats through integrated hardware-software ecosystems, proprietary fluidic and imaging technologies, and long-standing relationships with hospital networks and reference laboratories. At the same time, regional manufacturers are leveraging modular design, AI-assisted sediment recognition, and cost-optimized chemistries to capture share in price-sensitive procurement environments.
Several core enterprises define the current competitive architecture. Sysmex Corporation continues to emphasize workflow optimization through its UN-Series and UF-Series automated platforms, targeting laboratories that prioritize throughput consistency and seamless integration with existing laboratory information systems. ARKRAY, Inc. has focused its engineering efforts on fully automated chemistry and sediment analysis, with instruments such as the AUTION MAX AX-4060 and AUTION EYE AI-4510 designed to reduce manual review burdens while maintaining analytical rigor. Siemens Healthineers maintains a strong presence in point-of-care and mid-volume laboratory settings through semi-automated platforms like the CLINITEK Status+ and Advantus, catering to environments that require flexibility without sacrificing reliability.
Beckman Coulter reinforces its diagnostic portfolio with the DxU Iris Workcell and iQ200 Series, combining automated chemistry and microscopy capabilities to serve high-volume clinical laboratories seeking standardized, reproducible results. In Europe, 77 Elektronika Kft. has carved out a niche with the UriSed 3 PRO sediment analyzer and LabUMat 2 chemistry platform, emphasizing compact footprints and digital workflow integration. Erba Lachema s.r.o. offers the LAURA XL fully automated system alongside the LAURA Smart semi-automated option, addressing facilities that require scalable automation tiers. URIT Medical Electronic Co., Ltd. has expanded its modular AI-driven lineup with the US-2000 and US-1680 platforms, targeting laboratories that value configurable throughput and intelligent image interpretation. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. supports its broader diagnostics ecosystem with the EU-5300Pro and EH-2090, reinforcing its position in automated chemistry and sediment analysis across diverse clinical settings.
These competitive profiles illustrate a market where differentiation increasingly hinges on software maturity, image recognition accuracy, service responsiveness, and total cost of ownership rather than hardware specifications alone. The full report unpacks how these positioning strategies translate into regional share distribution, procurement preference patterns, and emerging vulnerability points for incumbents and challengers alike.
Technology Convergence and Regulatory Catalysts
Innovation in urine analysis is increasingly defined by the intersection of automation, digital imaging, and machine-assisted interpretation. Laboratories are moving toward platforms that minimize operator dependency, standardize sediment classification, and integrate results directly into electronic health record and laboratory information workflows. The shift toward AI-assisted sediment recognition, automated strip chemistry reading, and modular system architectures reflects a broader industry demand for reproducibility, traceability, and reduced turnaround times. For manufacturers, the strategic imperative is not simply to introduce new instruments but to deliver ecosystems that lower validation friction, simplify training, and provide actionable data outputs that clinicians can trust.
Regulatory developments are also reshaping the innovation landscape. In July 2025, the FDA granted Breakthrough Device Designation to the TOBY Test, a noninvasive, AI-powered tool designed for detecting bladder cancer. This milestone signals heightened regulatory openness to intelligent diagnostic approaches and may accelerate downstream interest in analytical platforms capable of supporting advanced biomarker and imaging workflows. Simultaneously, the April 2025 acquisition of Labrador Health by Healthy.io highlights a parallel evolution toward at-home quantitative testing and consumer-facing kidney health monitoring. These developments point to a longer-term expansion of urinalysis relevance beyond traditional laboratory boundaries, with implications for device design, data connectivity, and service delivery models.
For enterprise strategists, these signals suggest that product roadmaps must account for interoperability requirements, software validation pathways, and the potential integration of complementary diagnostic modalities. The complete research publication examines how these regulatory and technology shifts are likely to influence procurement priorities, clinical adoption thresholds, and competitive differentiation across the forecast period.
Operational and Strategic Implications for Decision-Makers
Translating market trajectory into actionable strategy requires a clear understanding of where demand is structurally expanding, which purchasing environments are most sensitive to automation economics, and how service and consumables revenue streams interact with instrument sales cycles. Hospital and clinic networks continue to represent a substantial share of utilization, driven by routine screening volumes, emergency department workflows, and integrated diagnostic pathways. Diagnostic laboratories remain central to the market’s growth equation, particularly as regional networks consolidate and seek standardized platforms that reduce inter-site variability. Additional application environments contribute incremental demand, often shaped by specialized testing requirements and decentralized care models.
From a competitive standpoint, the high concentration among leading manufacturers means that procurement negotiations, service-level agreements, and reagent pricing dynamics often favor organizations that can leverage volume commitments, multi-year contracts, and interoperability requirements. For emerging manufacturers and technology partners, market entry strategies must navigate validation timelines, distributor relationships, and the expectation of robust post-sale support. For investors and corporate development teams, the key question is not whether the market will grow, but how value will be distributed across hardware, software, consumables, and digital service layers over the next several years.
The full report provides the detailed segmentation architecture, regional demand contours, and application-specific revenue mappings required to answer those questions with precision. It also offers scenario-based considerations for capacity planning, portfolio prioritization, and partnership evaluation, enabling leadership teams to align operational decisions with the most probable market trajectories.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle demands a research foundation that balances historical validation with forward-looking scenario clarity. Organizations that rely on aggregated headlines or isolated product announcements risk misjudging procurement timing, overestimating near-term adoption velocity, or underappreciating the service and consumables economics that sustain manufacturer profitability. Our report is structured to eliminate that uncertainty by delivering a comprehensive view of market size evolution, competitive positioning, regulatory catalysts, and workflow-driven demand patterns.
Decision-makers across medical device strategy, diagnostic procurement, healthcare operations, and investment analysis will find the report particularly valuable for evaluating where to concentrate commercial resources, how to structure pricing and service models, and which technological competencies are likely to become table stakes in the coming years. The data framework supports internal scenario planning, competitive benchmarking, and market-entry feasibility assessments without requiring teams to piece together fragmented sources.
The complete intelligence package includes detailed segmentation breakdowns, regional demand distributions, application-level revenue mappings, and comparative profiles of the key enterprises shaping the market. These components are essential for transforming high-level growth awareness into executable strategy. To access the full dataset, segmentation architecture, and scenario analysis that underpin this overview, visit the source page for the complete Urine Analyzer Market research publication.
For detailed analysis of this topic, please visit the official page: Urine Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Imperatives in the Edge Protection System Market: A 2026 Outlook
Executive Summary: The Case for Precision Intelligence
As the global construction sector enters a phase of recalibrated growth, the Edge Protection System Market stands at the intersection of regulatory tightening, material cost volatility, and evolving site safety expectations. For corporate strategists, procurement leaders, and risk management executives, navigating this landscape requires more than generalized trends. It demands a structured, forward-looking view of how market size trajectories, segment performance, and competitive positioning will unfold through the end of the decade.
Our latest Edge Protection System Market research has been designed specifically for 2026 decision-making. It converts historical performance data, forecast modeling, and competitive intelligence into an actionable framework that supports capital allocation, supplier negotiation, product development prioritization, and geographic expansion strategies. This article serves as a strategic preview of the report's scope, analytical depth, and practical utility, while preserving the full dataset and granular breakdowns for clients who require it.
From Retrospective Tracking to Forward-Looking Strategy
Over the historical window of 2020 through 2025, the market demonstrated steady expansion supported by sustained demand for temporary work-at-height safety solutions across commercial, infrastructure, and industrial projects. Revenue moved from approximately 163.15 million USD in 2020 to an estimated 215.0 million USD in 2025, reflecting a pattern of resilient demand even as contractors navigated supply chain disruptions, labor constraints, and shifting project pipelines.
Looking ahead to the forecast period of 2026 through 2032, the market is projected to continue its upward arc, reaching an estimated 344.8 million USD by 2032. This trajectory implies a compound annual growth rate of 6.98 percent, a pace that signals more than cyclical recovery. It points to structural demand drivers tied to stricter site safety enforcement, increased adoption of modular and integrated protection solutions, and growing contractor emphasis on reducing on-site incident exposure.
For strategists, the significance of this growth path lies not only in its direction but in its composition. Growth is unlikely to be distributed evenly across product categories, end-use verticals, or geographies. Some segments will benefit from regulatory momentum and specification-driven purchasing. Others will face margin pressure from raw material cost volatility and intensifying competition. Understanding where value is created, where pricing power is eroding, and where adoption is accelerating is precisely the kind of intelligence that separates reactive planning from proactive positioning.
Edge Protection System Market
Why 2026 Decisions Require Segment-Level Clarity
The market's evolution through 2026 and beyond will be shaped by a combination of technical, regulatory, and commercial forces. Several dynamics deserve close attention as companies frame their near-term strategy:
- Regulatory and standards evolution is reshaping specification behavior. Updated product specification and test methods for temporary edge protection systems are elevating expectations around energy absorption, arrest functions, and performance verification. These changes are not abstract compliance issues; they influence which systems can be specified on demanding projects, how manufacturers differentiate their offerings, and how quickly new designs can gain market acceptance.
- Material cost pressure continues to affect installed economics. High steel and timber costs remain a relevant factor in the total installed cost of edge protection systems across global markets. For contractors and distributors, this affects bid pricing, supplier selection, and the attractiveness of alternative system designs. For manufacturers, it reinforces the importance of engineered efficiency, reusable components, and total-cost-of-ownership messaging.
- Safety adoption is increasingly linked to project procurement logic. In several major construction markets, temporary edge protection is no longer treated as an optional add-on but as a baseline expectation embedded in contractor qualifications, site planning, and insurance considerations. This shift expands addressable demand but also raises the competitive bar for product reliability, deployment speed, and integration with formwork or scaffolding workflows.
- Competitive intensity is rising among established and specialist players. The market remains relatively fragmented at the top, with a concentrated group of leading firms holding meaningful but not dominant share. That structure creates room for differentiation through product innovation, regional service capability, and partnership-driven distribution, while also making margin defense more dependent on value proposition than on scale alone.
Each of these forces affects a different part of the value chain. A company evaluating its 2026 roadmap needs to know not just that demand is growing, but which solution types are gaining share, which application areas are driving specification changes, and which regions present the strongest risk-adjusted opportunities. The full report addresses those questions with structured segmentation analysis that avoids broad generalizations and instead maps where growth is concentrated and why.
Wall Protection Market
What the Research Delivers: An Operational Toolkit
This study is built to support concrete strategic actions rather than high-level observation. Its architecture is intended to help teams translate market intelligence into procurement planning, product portfolio decisions, sales targeting, and competitive benchmarking. The report includes:
- A long-horizon market size and forecast framework that traces historical performance into the 2026 to 2032 period, giving executives a consistent baseline for scenario planning and investment prioritization.
- Segment-level analysis across type, application, and region that reveals how demand patterns differ by solution category, project environment, and geographic context. This allows readers to assess which segments are most exposed to regulatory tailwinds, material cost sensitivity, or competitive crowding.
- Competitive landscape profiling of leading participants across multiple headquarters markets, with attention to product focus, system integration strategies, and the kinds of applications each company is positioned to serve.
- Recent industry developments and standards-related updates that matter for procurement timing, product conformance, and specification risk, including emerging documentation and testing expectations affecting edge protection systems.
- Market concentration context that helps frame the balance between fragmented opportunity and consolidated influence, supporting realistic assessments of bargaining power, substitution risk, and market entry difficulty.
Importantly, the report is structured to support comparison and prioritization. Rather than presenting a single narrative line, it gives decision-makers a way to test assumptions against market evidence: Which solution categories are expanding most reliably? Which end-use environments are absorbing the highest value of protection work? Where do leading suppliers appear strongest, and where are gaps still present? These are the questions that determine whether a company's 2026 plan is robust under different demand and cost scenarios.
Competitive Landscape: Differentiation in a Fragmented Market
The edge protection sector includes a diverse set of manufacturers and suppliers spanning concrete, steel, timber, and modular construction applications. The marketplace is not defined by a single dominant architecture; instead, it features several companies competing on system design, integration with formwork and scaffolding, speed of deployment, and compliance with evolving safety expectations.
Leading participants illustrate the breadth of strategic approaches in the market. Some organizations emphasize rapid-deployment edge protection systems engineered for concrete, timber frame, and steel frame applications, often aligning product design with repeatability and site efficiency. Others integrate edge protection into broader formwork and scaffolding platforms, positioning safety as part of a unified workflow rather than a standalone purchase. A further group focuses on modular or mesh-based barrier solutions, perimeter safety screens, or roof-edge applications designed for specific project conditions.
Geographic diversity is also significant. Suppliers headquartered in the United States, Germany, Austria, France, Spain, the United Kingdom, Norway, Sweden, India, and China each bring different distribution strengths, regional specification relationships, and product specialization. In practice, this means the competitive picture varies by market: in some regions, integrated system providers may hold an advantage through incumbent project relationships; in others, specialist manufacturers may compete effectively through compliance leadership, lightweight design, or adaptability to local construction methods.
Strategic relevance comes from understanding how these players are likely to respond to the next phase of market development. Companies that can combine conformance with updated testing expectations, cost-effective material engineering, and flexible deployment models are better positioned to capture specification share. At the same time, the presence of multiple capable suppliers means that buyers have increasing leverage to compare total cost, lead time, and integration fit rather than accept a narrow set of options.
Recent activity underscores how quickly the compliance and product refresh cycle is moving. Updated standards documentation and revised product catalogs have already begun to reshape how suppliers present system classes and performance characteristics. For buyers, this creates both a conformance checklist and a competitive signal: manufacturers that move promptly to align documentation, testing, and system configuration with current specifications may gain an advantage in tenders and design reviews, while slower responders risk being excluded from increasingly specification-driven projects.
Using This Intelligence for 2026 Strategy Design
The strategic value of the full report lies in its ability to connect market structure to operational choices. Depending on a company's role in the value chain, the research can support several distinct decision paths:
- For manufacturers and product developers, segment trends and regulatory developments can inform portfolio focus, engineering priorities, and the relative merit of investing in modular, integrated, or application-specific designs.
- For distributors and procurement leaders, market size paths and competitive profiles can guide supplier diversification, inventory planning, and negotiation strategy in an environment where material costs and specification requirements both matter.
- For contractors and project organizations, the report can help clarify where safety system selection influences bid competitiveness, site risk posture, and compliance readiness, especially as standards-related expectations become more explicit.
- For investors and market entrants, concentration metrics, regional differences, and the mix of established and specialist competitors provide a realistic basis for assessing where differentiation is possible and where barriers are higher.
In each case, the goal is the same: reduce uncertainty enough to make better resource decisions without overgeneralizing from aggregate totals. The macro forecast provides the direction of travel. The segmentation, competitive, and standards context explains the mechanism beneath that direction. Together, they create a more reliable foundation for planning than headline growth figures alone.
Accessing the Full Strategic View
This preview has outlined the market's direction, the forces shaping its 2026 evolution, and the competitive logic that will influence decision-making through the forecast period. It has also described the operational scope of the research and the kinds of questions it is built to answer. What it has not done is release the full segmentation data, regional breakdowns, application splits, or company-level comparisons that make the analysis directly usable for internal planning.
Those details are reserved for the complete Edge Protection System Market report. They are structured to support detailed scenario work, supplier evaluation, and segment prioritization without requiring teams to reconstruct the underlying logic from broad market summaries. For executives and analysts who need to move from directional confidence to specific action, the full report provides the evidence base required to justify investment choices, procurement strategy, and competitive positioning in the year ahead.
In a market defined by changing specifications, material cost pressure, and rising expectations for site safety performance, the most valuable intelligence is not simply that growth is occurring, but where, why, and with what competitive implications. The complete research is designed to answer those questions in a format that supports disciplined 2026 decision-making across the construction safety value chain.
For detailed analysis of this topic, please visit the official page: Edge Protection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Intelligence for the Automotive Armrest Market: Navigating Growth Through 2032
The automotive interior landscape is undergoing a quiet but profound transformation. What was once considered a utilitarian component—fixed, functional, and largely overlooked—is now emerging as a critical touchpoint for comfort, sustainability, and modular design. As seating systems evolve from passive ergonomics to active user experiences, the automotive armrest has captured the attention of OEMs, tier suppliers, and aftermarket strategists alike. This shift is not merely aesthetic; it reflects deeper structural changes in vehicle architecture, consumer expectations, and regulatory frameworks. For executives navigating the 2026–2032 horizon, understanding the trajectory of this segment requires more than surface-level market estimates. It demands a disciplined, forward-looking analysis that connects material innovation, competitive consolidation, and regulatory pressure to actionable portfolio decisions.
Our latest research publication on the automotive armrest market is designed precisely for that purpose. Built on a rigorous historical baseline spanning 2020–2025 and extended through a comprehensive forecast window to 2032, the study provides a structured lens into how revenue, adoption patterns, and competitive positioning are being reshaped. The market has demonstrated consistent upward momentum over the past half-decade, with steady expansion across product architectures and material choices. As organizations prepare their strategic roadmaps for the 2026 fiscal year and beyond, this intelligence serves as a critical calibration tool—helping leaders separate cyclical noise from genuine structural inflection points.
Why 2026 Marks a Pivotal Inflection Point
The automotive supply chain enters 2026 under a fundamentally different operating environment than the one that defined the early 2020s. Electrification platforms continue to reconfigure interior packaging constraints, consumer preferences increasingly reward tactile comfort and personalized control surfaces, and regulatory bodies are tightening requirements around component safety, material sourcing, and lifecycle footprints. Within this context, armrest systems have moved from being treated as commodity trim pieces to becoming integrated elements of broader cockpit architecture.
Several forces converge to make this year particularly consequential for strategic planning. First, modular interior architectures are gaining traction across multiple vehicle segments, allowing sliding, folding, and adjustable configurations to be tested and deployed at scale. Second, the push toward lightweight, bio-sourced, and recycled material inputs is accelerating across seating supply chains, creating new performance benchmarks and procurement trade-offs. Third, regulatory developments—including UN Regulation No. 17 requirements for locking systems on comfort devices and updated safety guidelines issued by major oversight agencies in late 2024—are reshaping design validation cycles and compliance cost structures. These dynamics do not operate in isolation. They interact with manufacturing footprints, supplier partnerships, and regional demand rhythms in ways that can materially alter margin profiles and time-to-market assumptions. For decision-makers, the margin for guesswork has narrowed. What is needed is a research framework that connects macro trends to segment-level realities without over-simplifying the complexity on the ground.
A Research Framework Built for Execution
This market study is structured to bridge strategic inquiry and operational execution. Rather than presenting high-level aggregates in isolation, the report is organized around the dimensions that matter most to product planning, procurement, and competitive positioning teams. By integrating historical baselines with a forward-looking projection horizon through 2032, the analysis provides a continuous narrative that leaders can use to stress-test assumptions across multiple scenarios.
The report delivers actionable intelligence across several practical dimensions:
- Comprehensive sizing and trajectory analysis that contextualizes recent performance within long-term growth trends, helping organizations separate baseline expansion from segment-specific accelerations or decelerations.
- A structured breakdown of product architectures and functional configurations, enabling engineering and product teams to evaluate which form factors are gaining traction and under what usage conditions.
- Material and manufacturing pathway analysis that maps the shift toward sustainable inputs, recycled content, and lightweighting strategies, including the performance and cost implications of bio-sourced alternatives and energy-absorbing foam systems.
- Channel and go-to-market dynamics that distinguish how volume flows through integrated OEM supply relationships versus independent aftermarket ecosystems, with emphasis on the operational implications of each pathway.
- Competitive landscape profiling that examines how leading suppliers differentiate through seating system integration, modular console mechanisms, ergonomic component specialization, storage-enabled designs, and heated or comfort-enhanced variants.
- Regulatory and compliance context that translates safety standards and vestigial rule updates into practical implications for design validation, locking mechanisms, and component injury-risk considerations.
Each section is designed to answer the kinds of questions that surface in cross-functional planning sessions: where is demand consolidating, which material transitions are nearing commercial maturity, how are regional demand patterns reshaping sourcing priorities, and what does competitive differentiation look like when armrests are treated as part of a broader interior system rather than a standalone component. By presenting these insights in a cohesive framework, the study equips teams to move from observation to action with greater precision.
Automotive Headrest Market
Competitive Dynamics and the New Differentiation Playbook
The supplier landscape for automotive armrests is characterized by a mix of established interior specialists, seating system integrators, and regional players with deep manufacturing and engineering capabilities. Market concentration remains measured, with a handful of firms holding meaningful share and a broader field competing through engineering differentiation, regional partnerships, and material innovation. In such an environment, the ability to anticipate which competitive moves will compound over the next several years is as important as understanding current positioning.
Several leading companies illustrate the strategic directions currently shaping the market. Adient continues to expand its integrated seating systems capability, including armrest and console integration, reinforced by recent operational moves such as the acquisition of a seating foam plant that strengthens component production continuity and vertical coordination. FORVIA Faurecia has been advancing modular interior concepts, including on-demand center console systems with sliding mechanisms that enhance armrest and console functionality while incorporating sustainable materials and surface activation technologies. Grammer AG occupies a position centered on consoles and armrests for passenger vehicle interiors, with an emphasis on ergonomic components and complementary headrest solutions. TACHI-S Co., Ltd. brings manufacturing depth in seating assemblies that encompass armrest components as part of broader seat architectures. Piston Interiors focuses on practical feature differentiation, including fold-away options, storage integration, and durable latch systems for armrests and center consoles. Yanfeng Automotive Interiors extends its reach across door panels, floor consoles, and armrests, including comfort-oriented heated variants, reflecting the broader trend of treating interior surfaces as multi-functional user interfaces.
These profiles are not static. Competitive advantage is increasingly defined by how effectively suppliers can align engineering roadmaps with sustainability targets, modular design flexibility, and regional manufacturing responsiveness. The report maps these dynamics in greater detail, providing the comparative context needed to evaluate partnership opportunities, supply chain resilience, and technology adoption timing.
Recent industry developments reinforce how quickly the competitive landscape can shift. Strategic acquisitions that expand component production capability, alongside the unveiling of modular console systems with sliding armrest functionality, signal a broader movement toward integrated, adaptable interior architectures. These moves matter because they alter not only who competes, but how value is created—shifting emphasis from discrete part manufacturing toward system-level integration, comfort engineering, and material performance. For organizations assessing their own positioning, understanding the cadence and intent behind such moves is essential.
Regulatory, Material, and Operational Currents
No strategic assessment of this market is complete without addressing the operational currents that shape design choices, cost structures, and launch timelines. Regulatory requirements are one of the most influential of these currents. UN Regulation No. 17 introduces locking-system expectations for comfort devices when their presence could introduce additional injury risk, while updated oversight guidance issued in late 2024 has continued to refine how interior components are evaluated under evolving safety expectations. These frameworks do not merely impose compliance obligations; they influence architecture decisions, validation cycles, and the feasibility of certain mechanical configurations.
At the same time, material strategy is becoming a central competitive variable. Automotive seat armrest production increasingly relies on precise multi-step processes that incorporate bio-sourced and recycled inputs to reduce weight and CO2 footprint, while maintaining the durability and comfort performance expected by end users. In parallel, seat foam production continues to depend on high-density closed-cell materials engineered to meet energy-absorbing and non-flammability requirements relevant to occupant protection. Together, these material shifts create a more complex sourcing environment—one where sustainability, regulatory compliance, and functional performance must be balanced rather than treated as separate workstreams.
For procurement and engineering leaders, this means that armrest strategy is no longer confined to dimensional tolerances or cosmetic finishes. It extends into material traceability, energy-absorption performance, locking reliability, weight targets, and lifecycle impact. The research study provides the structured context needed to navigate these intersecting priorities, linking technical requirements to market-level implications.
Translating Intelligence into Strategic Action
As organizations prepare their 2026 planning cycles, the value of disciplined market intelligence lies in its ability to reduce uncertainty without oversimplifying reality. The automotive armrest market is expanding within a broader interior systems transformation, and the companies that succeed will be those that can interpret growth signals accurately, align product roadmaps with material and regulatory shifts, and position themselves relative to a competitive set that is increasingly defined by integration, modularity, and comfort engineering.
This study is designed to support that effort. It offers the historical grounding, forward-looking projections, and segment-level context necessary to evaluate investment priorities, sourcing strategies, product differentiation, and partnership structures. More importantly, it is built to help leaders ask better questions: which product configurations are gaining durable traction, where do material transitions create cost or performance trade-offs, how do regulatory developments shape design feasibility, and what competitive moves should be monitored as leading indicators rather than retrospective events.
Automotive Armrest Market
The complete analysis goes further, providing the detailed market sizing, trajectory modeling, competitive benchmarking, and segment-level context that decision-makers need to convert market signals into executable strategy. For teams responsible for seating systems, interior components, procurement planning, or competitive intelligence, the full report offers the depth required to act with confidence across the 2026–2032 horizon. Those seeking the complete dataset, regional and application-level breakdowns, material pathway comparisons, and in-depth competitive profiling are encouraged to access the full study directly through our research portal, where the complete intelligence package is available for download and internal distribution.
For detailed analysis of this topic, please visit the official page: Automotive Armrest Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Exterior Trim Market Hits $219 Billion in 2025, Forecast 4.2% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Future of Automotive Exterior Trim:2026 Strategic Insights and Market Trajectories
The automotive exterior trim market stands at a critical inflection point in 2026. As vehicle architectures evolve and consumer expectations shift toward enhanced aesthetics, sustainability, and functional integration, manufacturers and suppliers must navigate a landscape defined by both opportunity and volatility. This industry insight draws upon comprehensive market research to outline the strategic imperatives for stakeholders positioning themselves for the 2026-2032 forecast period. Understanding the macro dynamics, competitive pressures, and regulatory tailwinds is no longer optional—it is a prerequisite for capital allocation, product portfolio optimization, and supply chain resilience.
Macro Trajectory and Market Scale
The global automotive exterior trim market has demonstrated consistent expansion over the past half-decade. Historical analysis from 2020 through 2025 reveals a steady climb in total market value, moving from 175.0 billion USD to 219.0 billion USD. This trajectory underscores a market that has not only recovered from earlier supply chain disruptions but has accelerated beyond pre-pandemic benchmarks. Looking forward, the forecast period extending to 2032 projects continued growth, with the market expected to reach approximately 297.0 billion USD by the close of the decade. This expansion is underpinned by a compound annual growth rate of 4.2 percent, reflecting sustained demand across vehicle segments and geographic regions.
Automotive Exterior Trim Market
For enterprise leaders, these figures signal more than top-line growth; they indicate shifting allocation patterns, evolving material preferences, and the increasing importance of localized production strategies. The market's expansion is not uniform across all categories, and understanding where value is concentrating requires a granular view of type, application, and regional dynamics. However, the overarching message is clear: exterior trim is transitioning from a purely cosmetic component to a strategic interface that influences brand identity, aerodynamic performance, and regulatory compliance.
Segmentation Dynamics and Value Distribution
The market structure reveals a diversified ecosystem where multiple material types and application categories coexist. Plastic components command the largest share of the type segmentation, followed by metal and other materials, reflecting the industry's ongoing balancing act between cost efficiency, design flexibility, and weight reduction targets. In terms of application, bumpers and grilles represent significant portions of the market, while other exterior trim applications collectively account for a substantial portion of total revenue. This distribution highlights the breadth of opportunities beyond traditional high-visibility components, as manufacturers increasingly integrate trim elements into lighting housings, wheel arch extensions, and aerodynamic add-ons.
Regional analysis further complicates the picture. Asia Pacific remains the largest revenue contributor, reflecting the scale of vehicle production in the region and the rapid adoption of premium exterior features. North America and Europe follow, each with distinct regulatory environments and consumer preferences that shape demand. Latin America and the Middle East & Africa represent smaller but growing markets, often influenced by import dynamics and localized assembly strategies. The interplay between these regions creates a complex matrix where suppliers must tailor their offerings to meet varying standards for material composition, recyclability, and tariff exposure.
Competitive Landscape and Strategic Positioning
The market is moderately concentrated, with the top three players holding a combined share of approximately 52 percent and the top five capturing around 62 percent. This concentration suggests that scale, technological capability, and long-term OEM relationships provide meaningful barriers to entry. However, the remaining market share is distributed among a diverse set of regional and specialized players, creating ample room for differentiation through innovation, cost engineering, and niche application expertise.
Several industry leaders exemplify the strategies required to thrive in this environment. OPmobility, headquartered in Levallois, France, has expanded its footprint through integrated exterior and lighting solutions, reporting exterior and lighting revenue of 5,312 million EUR in 2025. Its focus on combining functional and aesthetic elements positions it well for vehicles where trim and lighting are increasingly co-designed. Toyoda Gosei Co., Ltd., based in Kiyosu, Aichi, Japan, leverages its polymer expertise and deep automotive heritage to deliver high-quality trim components that meet stringent durability and appearance standards. SMP Deutschland GmbH, located in Bötzingen, Baden-Württemberg, Germany, maintains a strong presence in the European market by emphasizing precision manufacturing and application-specific engineering.
Magna International Inc., from Aurora, Ontario, Canada, brings broad manufacturing scale and systems integration capabilities, enabling it to serve global OEM programs with complex trim assemblies. Flex-N-Gate Corporation, based in Urbana, Illinois, USA, has demonstrated agility in partnership-driven growth, recently supporting SEAT in the launch of the CUPRA Raval, a move that illustrates how trim suppliers can align with brand-specific design narratives. REHAU, headquartered in Rehau, Germany, continues to invest in material science and sustainable polymer solutions, aligning with industry-wide shifts toward recyclability. Polytec Group, from Hörsching, Upper Austria, Austria, and Adler Pelzer Group, based in Hagen, North Rhine-Westphalia, Germany, round out a competitive field that values specialized engineering, regional supply chain resilience, and close collaboration with vehicle manufacturers.
Industry Dynamics Shaping 2026 Decision-Making
Beyond the structural data, several real-time industry developments are reshaping the strategic calculus for 2026. Input costs for exterior trim remain sensitive to raw materials and semiconductor availability, creating cost volatility that requires proactive sourcing strategies and long-term supplier agreements. Tariff dynamics add another layer of complexity; additional tariffs on imported goods have been estimated to increase supplier cost of goods sold by roughly 9 to 12 million USD annually for affected operations. This reality emphasizes the importance of regionalized production, trade-compliant sourcing, and scenario planning around trade policy shifts.
Regulatory frameworks also play a decisive role. USMCA-compliant imports benefit from exemptions within automotive supply chains, providing a competitive advantage to suppliers structured to meet these requirements. This dynamic encourages strategic footprint decisions and partnership models that align with trade agreement criteria. Meanwhile, sustainability is moving from a compliance checkbox to a core design parameter. The SPE Automotive TPO forum in 2025 specifically addressed exterior trim with recycled content materials, signaling that OEMs and tier suppliers are increasingly evaluating trim solutions based on environmental credentials alongside traditional performance metrics.
Recent events further illustrate the pace of change. In February 2026, TMI announced the first winner selected for the 2026 TMI TRIM Road Tour, highlighting ongoing industry engagement around trim innovation and best practices. Earlier, in January 2026, Flex-N-Gate reinforced its market relevance through a partnership supporting SEAT's launch of the CUPRA Raval, demonstrating how strategic collaborations can accelerate product introductions and strengthen brand alignment. These developments, while discrete, reflect broader patterns of collaboration, showcase-driven innovation, and the need for suppliers to maintain visibility across the value chain.
What the Full Study Delivers
To translate these macro trends and competitive signals into actionable strategy, our comprehensive market study provides an in-depth examination of the automotive exterior trim landscape. The research is structured to support executive decision-making across multiple dimensions:
- Detailed market sizing and forecast models that trace revenue evolution from historical baselines through the 2032 horizon, with clear segmentation by type, application, and region.
- Competitive profiling of key players, including capability assessments, strategic focus areas, and recent developments that indicate future positioning.
- Analysis of material and cost dynamics, including raw material exposure, semiconductor dependencies, and tariff impacts on supplier economics.
- Regulatory and trade environment mapping, with particular attention to USMCA compliance, import exemptions, and regional policy shifts that affect supply chain design.
- Sustainability and material innovation tracks, covering recycled content adoption, TPO and polymer advancements, and OEM expectations for environmental performance.
- Application-level insights that go beyond aggregate figures to explore where value is created in bumpers, grilles, and other exterior trim categories.
- Scenario frameworks that help leaders test strategic options against varying assumptions around production volumes, input costs, and regional demand shifts.
This study is designed not merely as a data repository but as a decision-support tool. Each section connects market intelligence to operational implications, enabling teams to evaluate portfolio priorities, identify partnership opportunities, and anticipate structural changes before they become visible in quarterly results.
Automotive Interior Exterior Trim Market
Strategic Imperatives for 2026
As organizations plan their 2026 initiatives, several priorities emerge from the market intelligence. First, supply chain architecture must balance cost efficiency with resilience, particularly in light of tariff exposure and raw material volatility. Regionalized production and trade-compliant sourcing are no longer theoretical advantages; they are practical necessities for protecting margins. Second, material strategy requires continuous re-evaluation. The growing emphasis on recycled content and sustainable polymers means that suppliers must invest in formulation capabilities and validation processes that meet both performance standards and environmental targets.
Third, competitive differentiation will increasingly come from integration and co-design. Exterior trim is no longer a downstream add-on; it is part of a vehicle's aerodynamic, thermal, and aesthetic system. Suppliers that engage early with OEM design teams and offer modular, application-specific solutions will capture more value than those competing solely on price. Fourth, market intelligence must be continuous. The 4.2 percent CAGR and the projected growth to 297.0 billion USD by 2032 reflect a market that rewards foresight. Leaders who monitor segmentation shifts, competitive moves, and regulatory updates in real time will be better positioned to allocate capital and adjust execution plans.
Looking Ahead
The automotive exterior trim market in 2026 is defined by a blend of steady structural growth, intensifying competitive dynamics, and evolving regulatory and sustainability expectations. The data tells a story of expansion, but the real value lies in understanding where that expansion is concentrated, how costs are shifting, and which capabilities will separate winners from followers. Our full market study provides the depth required to move from observation to action, with detailed segmentation analysis, competitive assessments, and scenario-based guidance tailored for 2026 decision-making.
For executives and strategy teams seeking to navigate this landscape with precision, the complete report offers the granular intelligence necessary to shape product roadmaps, optimize supply chain configurations, and identify high-probability opportunities. The insights summarized here represent only the opening frame; the full study delivers the comprehensive intelligence needed to convert market awareness into strategic advantage.
For detailed analysis of this topic, please visit the official page: Automotive Exterior Trim Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hardness Testing Machine Market Hits $359.47 Million in 2025, Projects 6.5% CAGR to 2032
By PW Consulting, 2026-09-16
Unlocking Strategic Precision: The 2026 Hardness Testing Machine Market Outlook
In the high-stakes environment of global manufacturing, material integrity is not merely a technical specification; it is the foundation of safety, reliability, and brand reputation. As we navigate through 2026, the Hardness Testing Machine Market stands at a critical inflection point. The transition from traditional manual methods to automated, AI-integrated systems is reshaping how industries validate material properties. For stakeholders, investors, and operational leaders, understanding the trajectory of this market is essential for capitalizing on emerging opportunities and mitigating supply chain risks.
This insight serves as a strategic overview of our comprehensive market research report, designed to equip decision-makers with the intelligence needed to navigate the forecast period of 2026-2032. By analyzing historical trends and projecting future growth, we uncover the underlying forces driving demand and the competitive maneuvers defining the landscape.
Market Trajectory and Growth Dynamics
The global demand for precision testing equipment has demonstrated remarkable resilience and expansion over the past half-decade. Reflecting on the historical performance from 2020 to 2025, the market has evolved from a base of approximately 302.17 million USD to a projected 359.47 million USD in 2025. This steady accumulation of value underscores the indispensability of hardness testing across critical sectors.
Looking ahead, the growth trajectory accelerates. The market is poised to reach 390.32 million USD in 2026, marking a significant step up in valuation. Our forecasts indicate that this momentum will sustain, with the market size expected to surpass the 500 million USD threshold by 2030, eventually reaching 554.71 million USD by 2032. This expansion is driven by an estimated Compound Annual Growth Rate (CAGR) of 6.5 percent throughout the forecast period.
Such growth is not uniform; it is concentrated in specific technological advancements and regional industrial hubs. However, the overarching narrative is one of consistent upscale movement. Companies that align their product development and supply chain strategies with this 6.5 percent growth curve will find themselves better positioned to capture market share as the total addressable market expands.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a mix of established global giants and specialized regional players. Analysis of the concentration ratios reveals a fragmented yet competitive environment. The top three players hold a combined market share of approximately 24.6 percent, while the top five control around 26.2 percent. This indicates that no single entity dominates the entire ecosystem, leaving ample room for strategic differentiation and niche targeting.
Key industry leaders are leveraging distinct technological advantages to secure their positions. Buehler, based in Illinois, continues to push the boundaries with Wilson Vickers, Knoop, and Rockwell hardness testers equipped with advanced optical systems and DiaMet software. Their focus on optical precision highlights a trend towards digitizing measurement outcomes. Similarly, ZwickRoell from Germany offers a comprehensive portfolio covering metals, ceramics, plastics, and rubber, emphasizing versatility across material types.
In the North American sector, LECO Corporation and Mitutoyo maintain strong footholds with specialized Rockwell hardness testers, catering to high-volume industrial requirements. Innovation is also evident among European and Asian manufacturers. INNOVATEST in the Netherlands and Struers in the UK provide broad hardness testing solutions, while Chinese manufacturers like Laizhou Huayin Testing Instrument and Beijing Time High Technology focus on Brinell testers and related equipment, often targeting cost-sensitive segments.
Further diversifying the landscape, EMCO-TEST from Austria and Tinius Olsen from the USA contribute with general hardness testers and indentation hardness systems respectively. AFFRI Inc in Italy distinguishes itself with automatic hardness testing machines supporting multiple scales, addressing the need for throughput efficiency. Qualitest, operating out of the United Arab Emirates, offers a vast range of over 100 models spanning Rockwell to Vickers and portable units, highlighting the demand for variety. Foundrax in the UK rounds out the key players with a focus on Brinell hardness testing equipment.
Technological Advancements and Industry Dynamics
The momentum in this sector is heavily influenced by technological integration and regulatory compliance. The industry is witnessing a shift where artificial intelligence begins to revolutionize hardness testing. Recent updates from ZwickRoell in August 2025 highlighted advancements in AI for precision, signaling a move towards smarter, self-calibrating systems that reduce human error.
Portability and on-site capability remain critical drivers. In April 2025, Cisam-Ernst showcased portable hardness testers, including the Computest Lite compact wireless Rockwell hardness tester, emphasizing the need for quick on-site measurements in field conditions. Furthermore, exhibitions such as SAMPE China in June 2026 saw Tinius Olsen showcasing indentation hardness systems and automation solutions, reinforcing the link between testing equipment and broader manufacturing automation trends.
Compliance with international standards acts as both a barrier to entry and a trust signal. ISO standards such as ISO 6506-2:2017 and ISO 6508 specify requirements for both fixed location and portable hardness testing machines. Additionally, ASTM E18-24 Standard Test Methods for Rockwell Hardness of Metallic Materials, published in October 2025, keeps the regulatory framework current. ISO/TC 164/SC 3 continues to standardize indentation testing methods including Brinell, Knoop, Leeb, Rockwell, and Vickers hardness. Adherence to ISO 6508-2:2017 for verification and calibration procedures on various scales ensures that equipment meets rigorous force repeatability and hysteresis requirements. Manufacturers who integrate these standards directly into their product design gain a competitive advantage in regulated industries like aerospace and automotive.
Strategic Implications for 2026 Decision Makers
For executives and strategists, the data points to several actionable insights. First, the growth rate suggests that investment in capacity expansion or R&D for automated testing solutions is timely. Second, the fragmented market concentration implies that partnership or acquisition strategies could yield significant consolidation benefits. Third, the emphasis on standards suggests that compliance certification should be viewed as a marketing asset rather than a mere regulatory hurdle.
However, navigating this landscape requires granular data that goes beyond top-line figures. Understanding the specific revenue contributions of different testing types, the nuanced demand patterns across applications, and the regional intensity of consumption is vital for precise strategic planning. Our full report delves into these specifics, providing a detailed segmentation analysis that breaks down the market by type, application, and region without revealing the sensitive data here.
Hardness Testing Machine Market
Hardness Testing Device Market
Conclusion and Call to Action
The Hardness Testing Machine Market is on a clear upward path, fueled by industrial automation, stricter quality standards, and technological innovation. The window to optimize supply chains and product portfolios according to these trends is open now. To fully leverage the 6.5 percent CAGR and the projected 554.71 million USD market size by 2032, stakeholders need access to the complete intelligence package.
We invite you to explore the full depth of our research. The complete report provides the missing pieces of the puzzle, including detailed segmentation splits by region, type, and application, along with comprehensive company profiles and risk analyses. Equip your organization with the precise data needed to make informed decisions in 2026 and beyond. Access the full market intelligence today to secure your strategic advantage.
For detailed analysis of this topic, please visit the official page: Hardness Testing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


