



Category: Machinery & Automotive
PW Consulting: Server Cabinet Market Hits $330M in 2025, Projected 9.1% CAGR to 2032
By PW Consulting, 2026-09-16
The Strategic Imperative of Server Cabinet Infrastructure in the Age of AI
The modern data center is no longer merely a repository for digital information; it is the physical substrate of artificial intelligence. As computational workloads shift from general-purpose processing to high-density GPU clusters and AI training environments, the foundational infrastructure that houses these assets—the server cabinet—has emerged as a critical strategic component. For enterprise decision-makers, IT architects, and supply chain leaders, understanding the nuanced dynamics of the server cabinet market is no longer optional. It is a prerequisite for operational resilience, cost efficiency, and technological competitiveness.
PW Consulting's latest in-depth research on the Server Cabinet Market offers a comprehensive lens into this evolving landscape. This article serves as a strategic overview of the market's trajectory, highlighting the macroeconomic forces, competitive pressures, and technological shifts that define the sector. It is designed to contextualize the findings of our full report, providing executives with the necessary framework to appreciate the depth of intelligence available in the complete study.
The transition from traditional enterprise computing to AI-driven hyperscale environments has fundamentally altered the requirements for rack and cabinet systems. Power density, thermal management, and modularity are no longer secondary considerations; they are primary drivers of procurement strategy. As organizations plan their infrastructure roadmaps through 2032, the ability to anticipate market shifts, understand competitor moves, and evaluate regional supply dynamics will separate industry leaders from followers.
This analysis draws upon extensive historical data and forward-looking projections to map the growth trajectory of the sector. By examining the interplay between semiconductor value chains, raw material volatility, and the escalating demands of high-performance computing, we uncover the underlying currents shaping the market. The following sections detail the market size evolution, the competitive architecture among key players, and the dynamic forces driving demand.
Market Size and Growth Trajectory: A Decade of Expansion
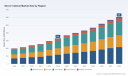
The server cabinet market has demonstrated consistent and robust growth over the past five years, reflecting the broader expansion of global data center capacity. Historical data from 2020 through 2025 reveals a steady upward trend, with the market expanding from approximately 200.0 million USD in 2020 to 330.0 million USD in 2025. This growth underscores the increasing reliance on structured physical infrastructure to support digital transformation initiatives across industries.
Looking ahead, the forecast period from 2026 to 2032 indicates continued acceleration. The market is projected to reach 368.91 million USD in 2026, with growth compounding annually at a CAGR of 9.1 percent. By the end of the forecast horizon in 2032, the market is expected to attain a revenue scale of 606.0 million USD. This trajectory suggests that demand for server cabinet solutions will remain resilient, driven by the proliferation of data-intensive applications and the ongoing construction of new data center facilities.
It is important to note that while the server cabinet market is a distinct segment, it operates within a broader enclosures ecosystem that has also shown significant expansion. Independent industry data points to the wider server rack cabinet enclosures market growing from 3.07 billion USD in 2025 to 3.37 billion USD in 2026, reflecting a CAGR of 9.93 percent. This broader context reinforces the notion that physical infrastructure investment is scaling in tandem with computational demands, validating the strategic importance of focused market intelligence.
For stakeholders, these figures are not merely statistics; they represent planning parameters. Capital expenditure budgets, procurement cycles, and capacity planning must all align with this growth rhythm. The consistency of the CAGR suggests that the market is maturing but still possesses ample room for expansion, particularly as new technological paradigms emerge.
Competitive Landscape: Dominance and Differentiation
The server cabinet market is characterized by a concentrated competitive structure, with a small group of established players commanding a significant share of the revenue pool. Market concentration data indicates that the top three companies account for 70.0 percent of the market, while the top five firms collectively hold 85.0 percent. This level of consolidation implies that incumbents possess substantial resources, established distribution networks, and deep technical expertise, creating high barriers to entry for new competitors.
Among the leading entities, several companies have distinguished themselves through specialized offerings tailored to the evolving needs of modern data centers. Vertiv Group Corp., headquartered in Ohio, USA, has positioned itself at the forefront of the AI infrastructure wave. The company focuses on integrated power and cooling solutions paired with modular high-density rack enclosures specifically engineered for AI and GPU workloads. Their recent product launches highlight a commitment to supporting power densities exceeding 50kW per rack, incorporating advanced thermal management and liquid cooling compatibility.
Eaton Corporation plc, based in Ireland, brings a different strength to the market. Their offering emphasizes advanced power management and reliability-focused server rack and cabinet systems. In an environment where uptime and energy efficiency are paramount, Eaton's approach appeals to enterprises seeking robust, mission-critical infrastructure. Meanwhile, Rittal GmbH & Co. KG, a German manufacturer, provides flexible modular racks and enclosures tailored to diverse deployment needs, offering adaptability for organizations with varied spatial and operational constraints.
Schneider Electric SE, headquartered in France, continues to be a major force with its NetShelter rack solutions, which integrate power, cooling, and monitoring capabilities into unified systems. This holistic approach simplifies management and reduces integration friction for large-scale deployments. On the North American front, L-com, based in Massachusetts, has focused on high-density networking equipment with 42U server rack cabinets available in multiple depth options. Their recent launch of new black and white variants with three depth configurations demonstrates responsiveness to specific networking density requirements.
Other notable players contribute specialized expertise to the ecosystem. Chatsworth Products, Inc., located in California, offers the ZetaFrame Cabinet System designed for high-density deployments and AI/HPC environments. AMCO Enclosures, in Illinois, provides custom electronic racks, cabinets, and shielded enclosures, catering to niche requirements that standard products may not address. Longhorn Reels, based in Texas, has gained attention for precision-engineered custom server rack systems for AI data centers, and recently expanded its manufacturing capabilities in early 2026 to meet the surging demands of AI data centers and chip manufacturing facilities. Martin Enclosures, in New Hampshire, emphasizes high-performance server racks and cabinets built in the USA, while RackSolutions offers high-quality racks and cabinets for data center and enterprise use across the country.
These companies are not merely competing on price; they are competing on technological capability, supply chain reliability, and alignment with the specific demands of next-generation computing. Recent developments illustrate this dynamic. Vertiv's October 2025 product launch addressed the need for high-density enclosures supporting over 50kW per rack with liquid cooling compatibility. L-com's January 2025 launch focused on depth options for high-density networking. Longhorn Reels' February 2026 expansion signaled the industry's response to the growing needs of AI and chip manufacturing.
Market Dynamics and Structural Shifts
The server cabinet market is being reshaped by a confluence of macro trends, regulatory influences, and material realities. Understanding these dynamics is essential for anticipating future demand patterns and supply chain risks.
Server Chassis Market
A primary driver is the rise of AI and high-density GPU deployments. Traditional server cabinets were designed for relatively modest power densities, but modern AI workloads require systems capable of handling extreme thermal loads and power delivery. The industry is increasingly demanding modular, high-power server cabinet systems exceeding 50kW per rack. This shift is not incremental; it represents a fundamental redesign of physical infrastructure. Cabinets must now accommodate advanced cooling solutions, including liquid cooling compatibility, and support the structural and electrical requirements of GPU-accelerated servers.
The semiconductor industry's role in this ecosystem cannot be overstated. According to a recent report from the Semiconductor Industry Association, semiconductors account for 95 percent of an AI Data Server Rack's value. This statistic highlights the deep interdependence between cabinet infrastructure and the broader semiconductor supply chain. As semiconductor availability, pricing, and technological advancements fluctuate, they directly influence the value proposition and design priorities of server cabinets. Procurement strategies must account for this linkage, as disruptions in chip manufacturing or supply can cascade into delays and cost pressures for cabinet deployments.
Raw material costs also play a critical role in shaping market dynamics. Server cabinet manufacturing relies on steel, aluminum, and advanced components, all of which are subject to price volatility. Company filings and sector analysis from 2025 indicate that rising material costs are tied to semiconductor supply chain volatility and broader macroeconomic factors. For manufacturers, managing input costs while maintaining competitive pricing requires sophisticated supply chain management and potentially hedging strategies. For buyers, understanding these cost drivers can inform negotiation tactics and long-term contracting decisions.
Regulatory and vertical-specific demands are adding another layer of complexity. Government and defense verticals are driving requirements for modular, scalable rack solutions that support secure, high-density computing environments. These sectors often impose stringent security, durability, and compliance standards, creating specialized demand pockets that reward manufacturers with the capability to deliver customized, certified solutions. As public sector investments in secure computing infrastructure grow, these requirements will increasingly influence overall market composition.
Segmentation Insights and Strategic Considerations
While the full report provides an exhaustive breakdown of market segmentation, certain high-level structures warrant attention for strategic planning. The market is analyzed across multiple dimensions, including regional distribution, product type, and application vertical. Each of these axes reveals important patterns regarding demand concentration, growth potential, and competitive positioning.
Geographically, the market exhibits distinct regional characteristics. Historical and projected data suggest that North America, Europe, and Asia Pacific represent significant revenue pools, with Latin America and the Middle East and Africa contributing additional, albeit smaller, shares. Regional dynamics are influenced by the location of hyperscale data center campuses, enterprise IT spending patterns, and local manufacturing or supply chain capabilities. Decision-makers operating across multiple regions must navigate differences in regulatory environments, logistics infrastructure, and competitive intensity. The complete report offers detailed regional analysis to support localization strategies and market entry evaluations.
In terms of product type, the market is segmented between open frame racks and enclosed cabinets. Enclosed cabinets typically command a larger share of the revenue, reflecting the growing need for security, thermal control, and organized cable management in modern facilities. Open frame racks remain relevant for specific use cases where airflow and accessibility are prioritized over enclosure. The balance between these types is shifting as deployment environments become more complex and space-constrained. Understanding the relative demand for each type helps inform product portfolio decisions and procurement specifications.
Server Cabinet Market
Application segmentation further illuminates where demand is originating. Hyperscale data centers, enterprise data centers, and colocation facilities each present unique requirements. Hyperscale operators prioritize scale, efficiency, and integration with advanced cooling and power systems. Enterprise data centers often balance performance with flexibility and existing infrastructure compatibility. Colocation providers must meet the diverse needs of multiple tenants while maintaining operational efficiency. The interplay among these application segments influences product design, service offerings, and pricing models. The full study delves into these application-level nuances, providing actionable guidance for targeting specific customer profiles.
Value of the Full Research for 2026 Decision-Making
As enterprises finalize their 2026 strategies and look toward the remainder of the decade, the Server Cabinet Market research from PW Consulting provides a critical decision-support tool. The insights contained in the full report go beyond high-level market sizing to offer granular, actionable intelligence that can inform procurement, product development, investment, and competitive positioning.
For procurement and operations leaders, the report delivers detailed segmentation data, including regional revenue splits, type-based market shares, and application-specific demand patterns. These figures enable precise demand forecasting, inventory planning, and supplier evaluation. By understanding which regions and applications are expanding most rapidly, organizations can align their sourcing strategies and prioritize high-growth opportunities.
For product managers and engineering teams, the competitive profiles and recent development tracking offer a window into the innovation landscape. Understanding the specific capabilities that competitors are bringing to market—such as high-density enclosures, liquid cooling compatibility, modular flexibility, and custom engineering—helps identify gaps and differentiation opportunities. The report's analysis of product launches, expansions, and strategic moves allows teams to benchmark their own roadmaps against industry trends.
For executives and investors, the market concentration data and macro dynamics provide context for assessing industry structure and risk. The high concentration among top players suggests that scale, brand, and technological leadership are valuable assets. At the same time, the presence of specialized manufacturers serving niche requirements indicates that targeted innovation can carve out sustainable positions. The integration of raw material cost dynamics, semiconductor value chain linkages, and regulatory drivers equips decision-makers with a holistic view of the forces that will shape profitability and growth.
The complete report also addresses the practical aspects of data interpretation, offering frameworks for translating market intelligence into strategy. Whether the goal is to evaluate market entry, assess competitor threats, optimize supply chain resilience, or align capital allocation with demand forecasts, the research provides the foundational data and analysis needed to act with confidence.
Conclusion: Navigating Infrastructure Transformation
The server cabinet market stands at the intersection of physical infrastructure and digital ambition. As AI workloads intensify, data centers expand, and computational demands push the boundaries of power and thermal management, the cabinet that houses the equipment is no longer a passive enclosure. It is an active enabler of performance, efficiency, and reliability.
The growth trajectory projected through 2032 reflects the sustained importance of this infrastructure layer. With a CAGR of 9.1 percent and a market scale extending beyond 600 million USD by the end of the forecast period, the sector offers both opportunity and complexity. Navigating this environment requires more than intuition; it demands rigorous, up-to-date market intelligence.
PW Consulting's comprehensive Server Cabinet Market research is designed to meet that need. By combining historical analysis, forward-looking projections, competitive profiling, and dynamic context, the report equips stakeholders with the insights required to make informed, strategic decisions. The full study reveals the detailed segmentation, regional breakdowns, and application-specific data that underpin the market's evolution, providing the depth necessary for precise planning.
For leaders who recognize that the future of computing is inseparable from the quality of its physical foundation, this research offers a clear path forward. Access the complete report to unlock the full spectrum of data, analysis, and strategic recommendations that will drive your organization's success in the years ahead.
For detailed analysis of this topic, please visit the official page: Server Cabinet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Box Making Machines Market Projected to Hit USD 344.8M by 2032 at 4.5% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence in the Box Making Machines Market: Navigating Growth Through 2032
The global packaging automation landscape is undergoing a decisive transformation. As supply chains demand faster turnaround times, greater customization, and tighter sustainability compliance, manufacturers are shifting from conventional batch production toward on-demand, right-sized box fabrication. Our latest market research delivers a comprehensive, data-backed examination of the Box Making Machines Market, offering executives the strategic clarity required to allocate capital, select equipment partners, and engineer resilient production architectures through 2032.
This report is not an academic exercise. It is an operational intelligence asset designed for procurement leaders, automation engineers, C-suite strategists, and investors seeking to align capital expenditure with measurable efficiency gains. By tracing historical performance, modeling forward trajectories, and dissecting competitive positioning, the study equips decision-makers with the frameworks needed to separate market noise from structural opportunity.
The Market Trajectory: From Historical Baselines to 2032 Forecasts
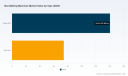
Understanding the Box Making Machines Market requires a clear view of its momentum. Drawing on historical performance from 2020 through 2025 and extending rigorous projections across the 2026-2032 forecast window, the analysis maps a market that has consistently expanded and is positioned for continued upward movement. The sector has crossed prominent valuation thresholds in recent years, reflecting sustained demand for flexible packaging lines, shorter production runs, and automated right-sizing capabilities.
Projected revenue growth through the end of the forecast period underscores the durability of this expansion. At the core of the modeling is a compound annual growth rate of 4.5 percent, a figure that translates historical resilience into forward visibility. For enterprise planners, this trajectory is not merely a headline statistic; it is a calibration tool. It informs facility expansion timelines, validates automation investments, and helps leadership distinguish between cyclical demand spikes and structural adoption curves.
The reports forecast architecture connects past performance to future scenarios using transparent, multi-factor modeling. Readers gain insight into how macroeconomic indicators, equipment adoption curves, and packaging-line modernization cycles converge to shape the medium-term outlook. Crucially, the analysis isolates the variables that matter for operational planning, allowing teams to build scenario plans around realistic growth envelopes rather than speculative extremes.
What distinguishes this research is its focus on decision-useful granularity beneath the aggregate numbers. Rather than leaving executives with a single growth figure, the study breaks down the market into the operational dimensions that actually drive procurement behavior, equipment selection, and regional deployment strategies. The objective is to convert macro-level momentum into concrete capital allocation logic.
Structural Drivers Reshaping Equipment Demand
The Box Making Machines Market is accelerating because the pain points it solves are becoming more acute across industries. Several interconnected dynamics are reshaping procurement priorities and redefining what operations teams expect from automated box fabrication equipment.
- On-Demand Right-Sizing as a Competitive Imperative : The traditional practice of boxing products into pre-set formats is giving way to precise, order-level box creation. Operations teams are prioritizing machines that can produce custom dimensions without excessive changeover time, reducing void fill, cutting material waste, and improving downstream logistics efficiency.
- Sustainability and Resource Recovery Compliance : Environmental regulation is no longer a peripheral concern. Compliance with resource recovery standards and broader sustainability mandates is actively steering buyers toward energy-efficient machines and corrugated box making systems designed to minimize waste streams. Equipment that supports lean material usage and streamlined production is increasingly viewed as a regulatory risk-mitigation asset, not simply a productivity tool.
- Material Complexity and Processing Requirements : Heavy-duty corrugated cardboard processing, including multi-ply configurations, demands specialized handling, creasing, and cutting technology. As converters and end-users work with thicker, more robust board grades, machine capability in vibration-based cutting, precision creasing, and material feeding becomes a decisive purchase criterion.
- Digital Integration and Workflow Automation : The boundary between box fabrication and broader packaging digitization is dissolving. Buyers are evaluating systems based on their ability to integrate with digital print workflows, automated sheet feeding, and centralized line control. End-to-end efficiency gains now depend on equipment that can operate as a coordinated node within a smart packaging cell.
These forces converge to create a market where equipment selection is increasingly strategic. Procurement is no longer about purchasing a standalone machine; it is about securing a flexible production capability that can adapt to changing order profiles, regulatory expectations, and material specifications. The report examines these dynamics in depth, linking each driver to the measurable purchasing behaviors and operational priorities they generate.
Competitive Architecture: Leading Players and Strategic Positioning
The competitive landscape for box making machines is defined by a blend of specialized automation providers, established packaging equipment manufacturers, and regional innovators tailoring solutions to specific production models. Our research evaluates key participants not simply by brand presence, but by technology orientation, application fit, and deployment footprint.
Several companies stand out for how they position their engineering philosophies around distinct production needs. AOPACK has built a portfolio around fully automatic on-demand corrugated box making machines, with model variations designed to support digital printing integration, vibrating knife cutting and creasing, and male-female creasing for short-run custom production. Their recent activity reflects a continued push into customized corrugated applications and broader market exposure through major exhibition platforms.
T-ROC Equipment LLC has positioned itself around heavy-duty on-demand automated box making systems, including automated box gluers and automatic sheet feeders, designed and manufactured in the United States for custom cardboard boxes. With a significant global installation base, the company demonstrates that durability and on-demand flexibility can be packaged together for operations that require consistent, high-stress throughput.
SCM Group emphasizes right-size box making machines with fanfold cardboard magazines, supporting single, multiple, and multi-layer configurations for just-in-time custom cardboard boxes in furniture and packaging applications. Bobst Group SA takes a different approach, focusing on high-volume flexo folder gluer systems that bring automation, digitalization, and end-to-end efficiency to corrugated and folding carton production. Panotec Srl contributes a modular, form-oriented perspective through automatic box forming machines built for standard model production and precise bottom flap folding, while also advancing flexible line integration.
Worldwide Straight Line Box Gluing Machines Market
Additional players such as Kraft Paper Systems extend the ecosystem with automatic box making and cutting solutions capable of processing endless corrugated material for on-demand output. The overall competitive picture reflects a fragmented, capability-driven market rather than a single dominant paradigm. Concentration metrics indicate a moderate level of consolidation, with top-tier players holding meaningful but not overwhelming share, leaving room for technology differentiation and application-specific specialization.
Recent corporate activity reinforces the speed of this evolution. Over the last year, the sector has seen a sequence of installation milestones, product launches, and exhibition debuts that signal accelerating commercialization. New machine releases have targeted small-lot production, modular line integration, and complex corrugated box handling, while field deployments have validated on-demand approaches in real converter environments. These developments are cataloged and contextualized in the report to help readers understand which product directions are gaining commercial traction and how competitors are translating engineering advances into market presence.
Report Architecture: What the Analysis Delivers
A market study is only as valuable as its usability. This report is structured to move from macro intelligence to operational guidance, ensuring that executives can extract concrete decision inputs rather than abstract trends. The analysis combines market sizing, segmentation evaluation, competitive profiling, technology mapping, and regulatory context into a single integrated reference.
At the structural level, the study presents detailed sizing across the full historical period and forecast window, with modeling that supports both baseline planning and sensitivity testing. Segmentation is explored across the dimensions most relevant to equipment evaluation, including type distinctions, application drivers, and regional deployment patterns. This segmentation is not presented as isolated percentages for casual browsing; it is framed as a strategic map that explains where demand concentration, purchasing priorities, and adoption barriers differ across use cases and geographies.
The report also provides company-level evaluations that go beyond descriptive profiling. Each key participant is assessed for product strategy, application emphasis, and operational relevance, giving readers a clearer sense of which suppliers align with specific production requirements. Technology discussions examine the mechanical and digital features that shape purchase decisions, from cutting and creasing methods to automation architecture and integration flexibility.
Equally important, the analysis embeds industry context where it actually affects buying behavior. Material handling requirements, sustainability mandates, and environmental compliance pressures are examined as market dynamics, not as background commentary. This approach helps leadership understand why certain machine specifications are becoming non-negotiable and how regulatory trajectories may influence total cost of ownership calculations over the forecast period.
To support execution, the report incorporates practical reference elements designed for direct business use. Decision-makers can leverage the study to evaluate equipment roadmaps, benchmark supplier capabilities, identify high-fit application segments, and plan regional deployment logic. The emphasis throughout is on actionable intelligence: reducing the distance between market data and operational decision-making.
Strategic Takeaways for 2026 Decision-Makers
For organizations planning capital investment, production-line modernization, or supplier selection in 2026, the Box Making Machines Market presents both opportunity and complexity. Growth is robust, but the value lies in identifying where that growth is most accessible and most aligned with operational objectives. The research equips leaders to make those judgments with greater precision.
The first strategic priority is aligning equipment capability with real production profiles. Companies that continue to evaluate box making machines solely on throughput may overlook the larger efficiency gains available through on-demand, right-sized production. The second priority is factoring sustainability and regulatory compliance into equipment economics early, rather than treating them as downstream concerns. Machines that support energy efficiency, waste reduction, and compliant material usage can materially improve the long-term viability of a packaging operation.
Box Making Machines Market
The third priority is vendor strategy. With multiple capable participants pursuing different engineering philosophies, procurement teams need a structured basis for comparison. The report supports that process by connecting company profiles to application fit, technology differentiation, and deployment track record. Instead of evaluating suppliers in isolation, decision-makers can assess them against the specific production scenarios they intend to serve.
Finally, the market trajectory suggests that timing matters. As adoption accelerates and equipment portfolios expand, organizations that establish clear automation requirements, integration standards, and material-handling specifications will be better positioned to secure fit-for-purpose solutions and avoid overinvestment in misaligned technology.
Access the Full Strategic Assessment
This overview highlights the scope, methodology, and strategic value of the full market research, but the complete intelligence architecture extends well beyond this introduction. The full report delivers detailed market sizing, extended forecast scenarios, segmentation analysis, competitive evaluation, technology mapping, and the operational context needed to turn data into decision-ready strategy.
For executive teams, procurement units, and investment stakeholders, the complete study provides the depth required to validate assumptions, compare pathways, and build credible medium-term plans. We invite you to access the full Box Making Machines Market research to obtain the comprehensive intelligence necessary for informed, forward-looking decisions through 2032.
For detailed analysis of this topic, please visit the official page: Box Making Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Auto Aluminium Wheel Market Hits $165M in 2025, Projected CAGR 2.8% to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Automotive Aluminium Alloy Wheels Market: Navigating 2026 and Beyond
Executive Overview
The automotive aluminium alloy wheels market stands at a critical inflection point in 2026. As original equipment manufacturers accelerate platform electrification, pursue aggressive lightweighting targets, and navigate an increasingly fragmented tariff and raw-material landscape, the strategic importance of wheel supply chain intelligence has never been higher. This report provides a comprehensive, data-driven roadmap for executives, product planners, procurement leaders, and investors who must align their portfolios with structural shifts rather than short-term market noise. By synthesizing five years of historical performance with a seven-year forward outlook, the analysis equips decision-makers with the contextual clarity required to allocate capital, prioritize engineering roadmaps, and recalibrate regional exposure.
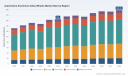
The market has demonstrated resilient recovery patterns following pandemic-era disruptions, with global revenue climbing from approximately 142.3 million USD in 2021 to a projected 175.3 million USD in 2026. Over the full forecast horizon through 2032, the sector is expected to expand at a compound annual growth rate of 2.8 percent, reflecting steady demand from passenger and commercial vehicle segments compounded by regulatory tailwinds and material substitution trends. While headline figures suggest moderate growth, the underlying dynamics reveal significant variation in profitability, capacity utilization, and competitive positioning across manufacturing processes, vehicle architectures, and geographic corridors. Understanding where margin compression concentrates and where premium differentiation can be sustained requires granular segmentation analysis that extends well beyond aggregate market sizing.
Market Trajectory and Structural Growth Drivers
Historical data from 2020 through 2025 illustrates a sector that has rebounded unevenly but decisively. After a brief contraction in 2023, revenue reaccelerated through 2024 and 2025, establishing a foundation for the 2026 to 2032 forecast window. The compound annual growth rate of 2.8 percent reflects a market transitioning from volume-led expansion toward value-driven optimization. Lightweight construction requirements, particularly within passenger vehicles and high-performance SUVs, continue to anchor baseline demand. Simultaneously, commercial vehicle fleets face mounting pressure to reduce total cost of ownership and meet fleet-level efficiency mandates, gradually shifting procurement preferences toward alloy wheels where durability and load ratings justify premium positioning.
The forecast trajectory accounts for both organic end-market growth and structural supply-side adjustments. Regional capacity additions, evolving OEM sourcing strategies, and the gradual reallocation of production toward low-pressure casting and forged architectures influence how value is distributed across the forecast period. Notably, the market does not follow a linear expansion curve; phases of capacity rationalization and technology adoption create inflection points that reward participants with flexible manufacturing footprints and disciplined raw-material hedging strategies. Executives evaluating regional exposure or plant utilization targets must therefore interpret growth projections through the lens of process maturity, contract visibility, and tariff-adjusted landed costs rather than relying on a single blended growth assumption.
Competitive Landscape and Strategic Positioning
The competitive environment is defined by a concentrated but highly differentiated supplier base. Global market structure analysis indicates a relatively modest concentration profile, with the top three participants capturing roughly 25.5 percent of total revenue and the top five reaching approximately 29.2 percent. This fragmentation reflects the coexistence of large-scale integrated producers, regional specialists, and aftermarket-focused brands that serve distinct customer segments with varying performance, aesthetic, and cost requirements.
CITIC Dicastal operates as the world's largest producer and exporter of automotive aluminium alloy wheels, supplying OEMs globally with high-volume cast and forged products. Its technological breadth spans LPDC, CPC, spinning, and forging processes, enabling scale advantages in high-volume passenger vehicle programs. Borbet, a family-owned German manufacturer, emphasizes quality, style, and off-road applications across light alloy wheels for cars, caravans, campers, and commercial vehicles. Ronal Wheels positions itself as a premier global supplier of forged and multi-piece alloy wheels, spanning passenger cars, SUVs, commercial vehicles, and premium or racing-oriented lines. Maxion Wheels and Iochpe-Maxion reinforce the southern hemisphere's strategic importance, with Maxion supplying steel and aluminium alloy wheels across passenger, commercial, and specialty segments through global production networks, while Iochpe-Maxion leverages its leadership in aluminium wheels and structural components with targeted expansion in South America for light-vehicle applications.
Aluminum Alloy Wheels Market
The aftermarket and performance segments introduce a parallel competitive layer. Enkei supplies major Japanese and global automakers with lightweight OEM and aftermarket alloy wheels, while American Racing delivers performance, custom, and vintage designs with strong aftermarket credibility. Wheel Pros functions as a designer and marketer of aftermarket alloy wheels that is actively expanding into forged and high-performance luxury segments. Alcoa Corporation maintains its position as a global leader in forged aluminium wheels, emphasizing sustainable, low-carbon solutions for premium and OEM applications. MAK Wheels rounds out the competitive field as an Italian manufacturer of custom alloy wheels for cars, SUVs, 4x4, and heavy-duty applications, with recent dedicated model development for major OEMs.
Recent product activity underscores the pace of innovation and brand differentiation. In early 2026, MAK Wheels introduced its 2026 collection, including the KULT and AURUM models dedicated to BMW and Mercedes-Benz programs alongside the LEGEND model developed for 4x4, heavy-duty, and camper applications. Earlier in 2025, MAK launched the Stark flagship alloy wheel targeting Volkswagen Group vehicles and broader SUV and car segments, while American Racing announced the TTF II drag-inspired wheel designed for high-performance trucks. These launches reflect a dual strategy across the industry: OEM program exclusivity that secures volume stability, and aftermarket or specialty positioning that supports premium pricing and brand affinity.
Demand Architecture Across Vehicles, Channels, and Processes
Demand segmentation analysis reveals how revenue is distributed across vehicle types, sales channels, and manufacturing methodologies, providing essential context for capacity planning and product mix optimization. Passenger vehicles account for the larger share of total market revenue, while commercial vehicles represent a substantial secondary pool driven by fleet durability, total cost of ownership considerations, and heavy-duty load requirements. The channel split between OEM and aftermarket demand further clarifies where volume stability and margin flexibility intersect. OEM relationships deliver multi-year program visibility but introduce price compression cycles and technical qualification burdens. Aftermarket demand offers faster response to design trends and regional customization, though it remains more exposed to discretionary spending cycles and retail channel dynamics.
Manufacturing process segmentation adds another layer of strategic relevance. Casting remains the dominant process by revenue, reflecting its cost efficiency and suitability for high-volume passenger vehicle programs. Forging contributes a meaningful share associated with strength-to-weight advantages and premium positioning, particularly in performance and light-duty commercial applications. Flow forming occupies a more specialized role, often bridging cost and performance objectives for targeted applications. Because each process carries distinct capital intensity, cycle time, material yield, and qualification requirements, participants must evaluate their process portfolios against the specific growth profile of their target segments rather than treating process capability as a generic competitive lever.
Automotive Aluminium Alloy Wheels Market
Operating Environment: Cost Volatility, Tariffs, and Regulatory Acceleration
The operating environment in 2026 and beyond is shaped by three interlocking forces: raw-material cost volatility, evolving trade policy, and tightening emission regulations. Aluminium prices represent a dominant share of production costs in automotive aluminium alloy wheels, and annual price fluctuations in the range of 18 to 22 percent continue to exert pressure on manufacturer margins. Suppliers without integrated procurement strategies, long-term supply agreements, or effective hedging programs face structural disadvantage when market conditions shift suddenly. Recruitment of low-carbon and recycled aluminium content is increasingly viewed as a dual-purpose response, supporting both cost resilience and sustainability commitments while opening access to 고객에게 preferred supplier status in OEM networks.
Trade policy developments have introduced new complexity to cross-border sourcing. Tariff actions on aluminium articles have raised the cost of imported wheels and parts, directly affecting landed-cost calculations for distributors, retailers, and OEM supply chains that rely on international procurement. At the same time, proposed and implemented tariff escalations on goods from key trading partners create uncertainty around supply continuity and shift the attractiveness of regional production footprints. Companies that previously optimized solely for unit cost must now incorporate tariff exposure, logistics flexibility, and customs-resolution timelines into their sourcing models. The result is a market in which tariff-aware capacity placement and dual-sourcing strategies are becoming baseline requirements rather than optional safeguards.
On the regulatory side, tightening CO2 emission targets for passenger cars are accelerating OEM demand for lighter aluminium alloy wheels as one component of broader fleet efficiency improvement programs. Weight reduction contributes directly to fuel economy and electric range performance, making alloy wheel specifications a tangible lever within multi-parameter engineering optimization. This regulatory push reinforces long-term demand for lightweight structures and supports premium positioning for suppliers that can demonstrate measurable weight savings, consistent quality, and compliance with OEM specifications. As vehicle architectures evolve, especially within electrified platforms, wheel design requirements may also shift toward thermal management, load distribution, and integration with suspension and braking systems, creating opportunities for suppliers with advanced engineering capabilities.
Sustainability, Recycling, and Strategic Capacity Evolution
Sustainability expectations are reshaping procurement priorities and capacity investment decisions. Recycled aluminium content in wheels is increasing as manufacturers seek to align with corporate environmental goals and customer-facing sustainability commitments. New production line investments in markets such as Mexico and Brazil are expanding capacity for low-pressure cast aluminium wheels while supporting the broader transition toward lower-carbon material inputs. This evolution is not merely a compliance exercise; it affects supplier qualification, brand positioning, and long-term cost structure as recycled material availability and processing efficiency improve.
For OEM-facing suppliers, sustainability credentials increasingly intersect with commercial competitiveness. Programs that can demonstrate traceability, reduced embedded carbon, and consistent mechanical performance are better positioned to win and retain high-value contracts. For aftermarket players, sustainability messaging can support premium pricing in segments where customers value environmental responsibility alongside aesthetics and performance. However, the operational reality is that sustainability investments must be paired with disciplined cost management and process reliability. Otherwise, the margin impact of raw-material volatility can quickly offset the strategic benefits of greener sourcing.
Strategic Implications for 2026 Decision-Making
Translating this landscape into actionable strategy requires a disciplined focus on several priority areas. First, portfolio alignment should distinguish between volume stability in OEM programs and margin opportunity in aftermarket and performance segments, ensuring that capacity and commercial resources reflect the distinct economics of each channel. Second, process configuration must be reviewed against segment growth profiles, with casting supporting high-volume cost competitiveness, forging enabling premium differentiation, and flow forming addressing targeted performance niches. Third, supply chain architecture should incorporate tariff-aware sourcing, regional flexibility, and raw-material risk management, given the persistent volatility of aluminium prices and the ongoing evolution of trade measures.
Fourth, sustainability and lightweighting should be treated as interconnected strategic priorities rather than separate initiatives. The same engineering capabilities that reduce weight can often be paired with lower-carbon material strategies and recycling pathways that strengthen OEM qualification and aftermarket positioning. Fifth, competitive intelligence should go beyond headline market shares to assess process mix, program pipeline visibility, regional footprint, and brand strength within specific vehicle types and customer segments. In a market where the top three participants collectively account for just over a quarter of revenue, the ability to capture differentiated value depends on precision positioning rather than scale alone.
What the Full Report Delivers
This summary frames the strategic questions that matter most entering 2026, but the complete report provides the detailed segmentation, competitive benchmarking, and scenario analysis required to convert direction into execution. The full study breaks down market size and growth trajectories by region, vehicle type, OEM versus aftermarket channels, and manufacturing process, enabling precise identification of where growth is concentrated and where margin pressure is most acute. It examines competitive positioning for key global suppliers, incorporating recent product launches, technology focus, and regional expansion patterns, while contextualizing operating dynamics through raw-material cost volatility, tariff developments, and regulatory demand drivers. The analysis also explores sustainability trends and capacity evolution, offering practical frameworks for evaluating sourcing strategy, product mix, and program prioritization.
For executives responsible for capital allocation, product planning, procurement, or market entry, the complete report functions as a decision-support tool that turns market complexity into structured insight. The full dataset, segmentation detail, and competitive profiles are available through the source market research page, where readers can access the complete intelligence package designed to support 2026 strategy formulation and execution.
For detailed analysis of this topic, please visit the official page: Automotive Aluminium Alloy Wheels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects 9.5% CAGR for High Speed Oven Market to Hit $7.88B by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the High Speed Oven Market: Navigating the 2026–2032 Growth Cycle
The commercial foodservice sector is undergoing a profound operational transformation, driven by acute labor constraints, rising real estate costs, and an unprecedented demand for rapid ticket-to-order fulfillment. In this volatile environment, the high speed oven market has emerged as a critical enabler of kitchen efficiency, bridging the gap between traditional cooking methodologies and the aggressive throughput requirements of modern quick-service and fast-casual operations. As we analyze the trajectory of this sector through 2032, our latest market research provides a comprehensive strategic blueprint for manufacturers, investors, and foodservice operators aiming to capitalize on a projected industry expansion. This article outlines the macro-economic foundations of the sector, highlights the competitive dynamics shaping vendor strategies, and details the actionable intelligence embedded within our full report.
The Macro Trajectory: A High-Growth Window Across 2026–2032
Market data spanning the evaluation period paints a clear picture of sustained acceleration. Following a robust historical baseline, the industry has entered a steep growth phase, with the overall market value reaching $4,370.0 million in 2025 before projected to chart $4,686.06 million in 2026. Our forecast models indicate that this momentum will compound consistently, pushing revenue toward $7,880.0 million by 2032. This represents a compound annual growth rate of 9.5 percent, a figure that significantly outpaces broader commercial kitchen equipment benchmarks and underscores a structural shift in how operators are designing their culinary workflows.
The valuation trajectory does not merely reflect cyclical demand; it signals a permanent reorientation of commercial cooking infrastructure. As high-throughput concepts proliferate and legacy kitchen footprints contract, speed cooking appliances are transitioning from supplementary tools to central production assets. Organizations that align their capital expenditure strategies with this growth pattern stand to secure meaningful first-mover advantages in supply chain positioning, channel partnerships, and menu innovation capabilities.
Market Structure and Demand Drivers Shifting the Landscape
Segmentation Dynamics and End-Use Priorities
The current market architecture reveals a balanced but rapidly evolving distribution of demand across equipment configurations and deployment environments. Operators are increasingly evaluating built-in installation formats against standalone countertop solutions, with the strategic choice heavily dependent on modular kitchen design, ventilation constraints, and throughput targets. Simultaneously, end-use applications are bifurcating between high-volume restaurant environments and a diverse array of other commercial deployments, including corporate cafeterias, educational dining facilities, retail food halls, and airport concessions. This diversification is critical, as it insulates the market from overreliance on a single dining segment and broadens the addressable customer base for manufacturers and distributors.
Geographic Expansion and Infrastructure Maturation
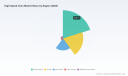
Regional adoption patterns are stabilizing around established commercial foodservice hubs while demonstrating clear upward pressure in emerging markets. North American and European territories continue to anchor substantial share, anchored by mature restaurant supply chains, stringent health and safety compliance frameworks, and widespread adoption of ventless and impingement cooking technologies. Meanwhile, Asia Pacific and Latin American markets are exhibiting accelerating deployment rates as quick-service brands expand internationally and local operators prioritize operational efficiency to offset rising commodity and labor costs. Middle Eastern and African regions, though smaller in absolute valuation, are carving out niche growth corridors driven by hospitality infrastructure projects and tourism-centric foodservice concepts.
Regulatory Compliance and Operational Cost Pressures
The commercial deployment of high speed ovens is strictly governed by a multi-layered certification ecosystem. Equipment destined for U.S. and Canadian commercial kitchens must satisfy UL and NSF safety and sanitation standards, while ETL certification remains mandatory for market entry across North America. Ventless configurations introduce an additional compliance layer, requiring catalytic converter certification to meet stringent emissions thresholds. Furthermore, energy efficiency frameworks, including Energy STAR and related efficiency certifications, are increasingly influencing procurement decisions, particularly for models that integrate convection, microwave, and broil capabilities in a single footprint.
Worldwide Build-in High Speed Oven Market
Beyond regulatory overhead, labor economics are the most potent demand catalyst in the current cycle. High speed ovens routinely deliver cook times up to 80 percent faster than conventional equipment, directly compressing staffing requirements and reducing dependency on highly specialized culinary labor. In an environment where wage inflation and recruitment volatility remain unresolved, this labor efficiency premium is no longer a convenience feature—it is a financial imperative that dictates capital allocation and menu engineering strategies.
High Speed Oven Market
Competitive Arena: Strategic Moves and Product Evolution
Market concentration remains firmly consolidated, with the top three participants commanding a combined 62 percent share and the top five firms extending that footprint to 65 percent. This structure rewards scale, technical differentiation, and robust service networks, while simultaneously raising the barrier for new entrants attempting to disrupt established channel relationships.
Several active manufacturers are currently defining the competitive tempo through targeted product evolution and strategic positioning. Prática Klimaquip, operating out of Minas Gerais, Brazil, has solidified its footprint in commercial rapid-cook applications with stackable configurations such as the FIT XL and Rocket Express, specifically engineered for pizza, wing, and quick-service workflows. The Middleby Corporation, leveraging its TurboChef Technologies subsidiary based in Elgin, Illinois, continues to deploy impingement-based rapid-cook architecture optimized for high-volume foodservice throughput. Hatco Corporation, through its Ovention Ovens brand in Milwaukee, Wisconsin, maintains a strong emphasis on 100 percent ventless impingement systems that integrate seamlessly into constrained kitchen footprints without extensive exhaust infrastructure.
Merrychef Ltd., headquartered in Elkhart, Indiana, remains a pioneer in high-speed oven technology, with its eikon and conneX series reflecting a consistent focus on streamlined kitchen operations and connectivity-driven workflow management. Panasonic Corporation, from its Osaka base, extends its commercial reach through convection-microwave-broil hybrids such as the NE-SCV3 series, targeting restaurants and cafes that require multi-functionality within a single appliance footprint. UNOX S.p.A. contributes a distinct European engineering perspective from Italy, offering commercial speed ovens such as the SPEED.Pro line that merge convection, steam, and microwave capabilities for versatile culinary outputs. Sharp Corporation has also entered the acceleration curve with its Celerity high speed oven, showcasing advanced thermal engineering capable of reducing whole-chicken cook times to roughly one-third of conventional methods. Additionally, Buffalo Equipment has expanded its proprietary portfolio by unveiling two new high-speed models, reinforcing the trend of domestic and regional manufacturers investing heavily in rapid-cook technology differentiation.
2026–2027 Product Cycle: Real-Time Market Signals
The competitive landscape is being actively reshaped by a concentrated wave of product launches, catalog updates, and application-focused messaging during mid-2026. Ovention Ovens recently refreshed its product catalog with detailed guidance on integrating high-speed ovens into modular kitchen designs and optimizing team workflow allocation. TurboChef simultaneously promoted its Bullet Oven for campus dining environments and high-volume service settings, emphasizing throughput efficiency and space-conscious deployment. Merrychef announced an expansion of its conneX high-speed oven range, positioning the new line as a solution for consolidated kitchen operations and reduced equipment sprawl. Buffalo Equipment followed with the unveiling of two new models within its branded cooking range, signaling continued investment in rapid-cook capacity across retail and foodservice channels. These concurrent developments reflect a broader industry pivot toward operational modularity, deployment flexibility, and menu-agnostic performance.
Inside the Report: Operational Intelligence and Decision Frameworks
Our full market research publication extends well beyond macro-valuation summaries to deliver a tactical decision-support architecture. The report systematically deconstructs market sizing across historical baselines and forward-looking forecast periods, enabling precise revenue modeling and capacity planning. It examines structural segmentation splits that illuminate how built-in versus countertop configurations are performing across distinct commercial environments, while also mapping end-use distribution between restaurant-grade deployments and alternative foodservice applications. Geographic coverage is analyzed through a lens of market maturity, infrastructure readiness, and regional adoption velocity, providing a nuanced view of where demand is stabilizing and where it is accelerating.
The competitive intelligence section profiles active market participants, mapping headquarters locations, technological specializations, and recent developmental activity. Recent product launches, catalog revisions, and targeted promotional campaigns are cataloged to reveal how vendors are responding to shifting operator requirements. Beyond hardware and vendor mapping, the report incorporates regulatory and certification pathways, ensuring that compliance planning is integrated directly into procurement and deployment strategies. Labor cost mitigation scenarios are quantified against conventional cooking benchmarks, and energy efficiency considerations are evaluated alongside certification requirements to provide a complete total-cost-of-ownership perspective. This multidimensional framework is designed to support capital planning, channel strategy formulation, competitive positioning, and menu engineering initiatives with minimal reliance on secondary interpretation.
Strategic Imperatives for Stakeholders
For equipment manufacturers and technology developers, the 9.5 percent growth trajectory and concentrated market share structure underscore the necessity of differentiated engineering, robust ventless and hybrid-cooking portfolios, and proactive compliance alignment. For foodservice operators and franchise groups, the immediate priority lies in evaluating kitchen reconfiguration opportunities that leverage 80 percent faster cook times to compress labor dependency, improve ticket throughput, and expand menu flexibility within constrained footprints. For investors and financial analysts, the diversification across end-use environments and regional growth corridors provides a clear framework for assessing exposure, identifying channel expansion opportunities, and monitoring vendor consolidation patterns. The data demonstrates that high speed ovens are transitioning from tactical kitchen tools to strategic infrastructure assets; companies that embed this reality into their planning cycles will be better positioned to navigate the operational and financial demands of the coming half-decade.
Conclusion: Accessing the Complete Strategic Blueprint
The high speed oven market is entering a phase of sustained, structurally driven expansion marked by technological consolidation, regulatory rigor, and intensifying competitive maneuvering. The aggregate market trajectory, segment dispersion patterns, vendor activity cycles, and compliance frameworks documented in our full research publication provide a comprehensive foundation for informed capital allocation, product planning, and operational optimization. While the overview presented here captures the essential strategic contours, the complete report contains granular sizing breakdowns, detailed vendor profiling, segment-level deployment dynamics, regional adoption mappings, and actionable scenario models that are essential for precise decision-making. To access the full intelligence suite and integrate these findings directly into your 2026 planning cycle, please visit the official market research portal and download the complete publication.
For detailed analysis of this topic, please visit the official page: High Speed Oven Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Karaoke Machines Market to Hit $344.8M by 2032 at 6.98% CAGR
By PW Consulting, 2026-09-16
Unlocking the Rhythm of Growth: Strategic Insights from the 2026 Karaoke Machines Market Intelligence Report
The global karaoke machine market is currently undergoing a significant transformation, driven by shifting consumer habits, technological integration, and evolving entertainment preferences. As we move through the 2025-2032 forecast period, the industry is poised for steady expansion, presenting both opportunities and challenges for stakeholders across the entertainment hardware value chain. This executive summary outlines the strategic landscape of the karaoke machines market, derived from a comprehensive market research study designed to inform high-level decision-making in 2026 and beyond.
For business leaders, understanding the trajectory of this market is no longer optional; it is a prerequisite for capital allocation, product development, and competitive positioning. The following analysis leverages historical data and forward-looking projections to frame the current state of play. However, to maintain the integrity of proprietary forecasting models, specific granular breakdowns regarding regional revenue shares and segment-specific dollar values are reserved for the full report. Here, we focus on the strategic implications of the broad trends reshaping the industry.
Market Trajectory and Historical Context
The market has demonstrated resilience and consistent growth over the past half-decade. Historical data from 2020 through 2025 indicates a clear upward trend in revenue generation. Starting from a base of USD 163.15 million in 2020, the market scaled gradually each year, reaching USD 194.68 million by 2024. This growth trajectory accelerated in 2025, with valuations hitting USD 215.0 million. Such performance underscores a robust demand environment that has outlasted initial pandemic-induced fluctuations, transitioning from a recovery phase to a growth phase.
Looking ahead, the forecast period from 2026 to 2032 suggests continued expansion. Projections indicate the market value will climb to USD 230.86 million in 2026 and further escalate to USD 344.8 million by 2032. This long-term outlook is supported by a Compound Annual Growth Rate (CAGR) of 6.98 percent. This rate of growth implies that the market is outpacing many traditional consumer electronics segments, fueled by innovations in wireless connectivity and portable form factors. For investors and manufacturers, this CAGR serves as a benchmark for evaluating potential returns on investment in manufacturing capacity or marketing spend.
Competitive Landscape and Key Players
The competitive environment is characterized by a fragmented yet dynamic mix of established manufacturers and agile tech innovators. The market concentration remains relatively moderate, with the top three companies holding a CR3 of 24.6 percent and the top five firms accounting for a CR5 of 26.2 percent. This indicates that while there are dominant players, a significant portion of market share is distributed among smaller or regional entities, leaving room for disruption.
Several key companies are defining the current standards of product quality and innovation. The Singing Machine Company, Inc., headquartered in Fort Lauderdale, Florida, remains a pivotal player. They manufacture a wide range of all-in-one karaoke machines, portable systems, and microphones. Their recent strategic moves include the launch of the Carpool Karaoke Mic 2.0 in June 2026, featuring dual microphones and improved wireless connectivity. This product launch highlights their focus on leveraging brand partnerships and enhancing user experience through hardware refinements.
Ikarao, based in New York, distinguishes itself through portable smart karaoke machines with built-in screens and KaraFun integration. Their presence at CES 2025, where they dazzled audiences with all-in-one karaoke technology, signals a strong commitment to integrating software ecosystems with hardware. Meanwhile, Tonor, headquartered in Hong Kong, focuses on wireless karaoke machines with LED lights and Bluetooth connectivity. Their release of the K20 Wireless Karaoke Machine in March 2026, which offered enhanced mood lighting and portable design, demonstrates an emphasis on aesthetic appeal and party functionality.
JYX, also based in Hong Kong, competes directly in the portable speaker and karaoke machine segment. Their introduction of the T17T and S8 models in November 2025, which boasted improved sound quality and longer battery life, reflects the industry-wide push towards mobility and endurance. These companies collectively illustrate the divergence in strategy, from premium branded partnerships to budget-friendly, feature-rich portable units. Understanding the specific strengths and go-to-market strategies of these competitors is essential for any firm looking to gain share in this ecosystem.
Market Segmentation and Demand Drivers
The market is segmented by type, application, and region, each offering distinct growth vectors. In terms of product type, the landscape is divided among portable, desktop, and other variants. The breadth of segmentation suggests that manufacturers cannot rely on a single form factor to capture the total market. Portable devices, in particular, have seen significant shipment increases, with data indicating an 18 percent rise in the first half of 2026 driven by demand for on-the-go entertainment.
Application-wise, the usage patterns have shifted noticeably. While commercial use remains a steady revenue stream, the share of karaoke machines used for home family gatherings surged in 2026. Internal data points to an increase from 52 percent in 2025 to 68 percent in 2026. This shift implies that product design and marketing should increasingly target home entertainment ecosystems rather than solely relying on commercial venue contracts. Portability, ease of setup, and aesthetic integration into home environments are becoming critical decision factors for consumers.
Regional dynamics also play a crucial role. The market spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique regulatory environments and consumer preferences. For instance, regulatory bodies such as the US Federal Communications Commission issued updated guidelines in April 2026 for Bluetooth karaoke devices to ensure safer audio output levels. Compliance with such regulations is a non-negotiable aspect of market entry and product certification in key jurisdictions. Ignoring these dynamics can lead to significant delays in product launches or recall risks.
Industry Dynamics and Operational Challenges
Navig 2026 requires a keen awareness of external pressures affecting supply chains and operations. One notable challenge is the cost volatility of raw materials. In the first quarter of 2026, prices for plastic and electronic components used in portable karaoke machines saw a 12 percent increase due to global semiconductor shortages. This cost pressure impacts margins for manufacturers who have not secured long-term supply contracts or diversified their supplier base. Strategic sourcing and inventory management are now critical components of operational planning.
Furthermore, the regulatory landscape is evolving. Beyond the FCC guidelines on audio output, manufacturers must stay abreast of varying safety standards and import-export regulations across different geographies. The fragmentation of regulations means that a product compliant in one region may require significant modification for another, impacting time-to-market and overall profitability.
Karaoke Machines Market
Slot Machines Market
Consumer habits continue to evolve alongside technology. The integration of wireless connectivity and app-based song libraries is no longer a luxury but an expectation. Devices that lack seamless connectivity or a robust library integration risk obsolescence. The trend towards smart features, as seen in recent product launches by key players, suggests that hardware specifications alone are insufficient to drive sales. The user experience, including interface design and library access, is becoming a primary differentiator.
Strategic Value of Comprehensive Market Intelligence
Given the complexity of these dynamics, relying on anecdotal evidence or outdated reports is a strategic risk. A dedicated market research report provides the granularity needed to make informed decisions. The full version of this study offers deep dives into segmentation splits, detailed company profiles with financial and operational highlights, and precise forecast models.
Access to the complete data allows stakeholders to identify high-growth niches within the broader market. For example, while aggregate numbers show growth, understanding the specific revenue contribution of portable versus desktop units, or the exact revenue distribution across regions, enables targeted marketing and production planning. It also allows for a more accurate assessment of competitor moves. While public announcements indicate product launches, the full report contextualizes these moves within market share shifts and pricing strategies.
Moreover, the report includes an in-depth analysis of industry barriers to entry, regulatory compliance checklists, and supply chain risk assessments. These operational insights complement the financial forecasts, providing a holistic view of the market environment. For investors, this translates to better risk-adjusted return profiles. For manufacturers, it means optimized product roadmaps. For distributors, it ensures inventory alignment with regional demand patterns.
The strategic value lies in the ability to anticipate rather than react. With the market projected to reach USD 344.8 million by 2032, the window for establishing a dominant position is open but narrowing. Companies that leverage detailed intelligence to navigate raw material cost fluctuations, comply with emerging regulations, and align product features with the 68 percent home-usage trend will be best positioned to capture value.
In conclusion, the karaoke machines market offers a compelling growth story backed by solid fundamentals and evolving consumer preferences. However, realizing the potential requires more than just observing the upward trend. It demands a nuanced understanding of the forces driving that trend, from semiconductor availability to FCC guidelines, and from competitive product launches to shifts in home entertainment habits. The roadmap to 2032 is clear, but the path to success depends on the quality of intelligence guiding your next move. To access the complete dataset, detailed segmentation analysis, and proprietary forecasts that underpin these insights, we invite you to explore the full report.
For detailed analysis of this topic, please visit the official page: Karaoke Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tray Sealing Machines Market to Reach $214M by 2032 with 4.36% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for 2026: Navigating the Tray Sealing Machines Market
As global food supply chains accelerate towards greater efficiency and sustainability, the machinery underpinning primary packaging has entered a phase of critical transformation. For strategic planners, procurement leaders, and capital investment committees, the Tray Sealing Machines Market represents more than a routine equipment upgrade. It is a leverage point for operational resilience, regulatory compliance, and margin optimization in an era defined by volatile input costs and tightening environmental mandates. Our latest market research study, covering historical performance from 2020 through 2025 and delivering a forward-looking forecast from 2026 to 2032, is designed to convert this complexity into actionable boardroom intelligence.
The precision of 2026 decision-making depends on a clear-eyed view of where the market has been, where it is structurally heading, and which competitive forces are actively reshaping the pricing, capability, and technology landscape. This article outlines the strategic architecture of our analysis and demonstrates why a disciplined, data-anchored approach to tray sealing equipment strategy is indispensable for the year ahead.
Mapping the Macro Trajectory: Growth, Cycles, and Structural Shifts
Over the past half-decade, the global tray sealing equipment sector has demonstrated steady, compounding expansion. Revenue generated across the market moved from 135.75 million USD in 2020 to 165.0 million USD by 2025, reflecting an environment where food processors, fresh produce suppliers, and ready-meal manufacturers have consistently prioritized throughput, hygiene, and packaging integrity. Looking forward, the market is projected to advance to 169.06 million USD in 2026 and continue its upward trajectory toward 214.0 million USD by 2032. This path is underpinned by a forecast compound annual growth rate of 4.36 percent, a figure that signals durable demand rather than a temporary cyclical spike.
For executives evaluating capex pipelines, this macro trajectory carries several implications. First, it confirms that demand for tray sealing technology is not confined to a single geography or a narrow application vertical. Growth is being distributed across mature industrial markets and high-velocity emerging production hubs, creating a diversified opportunity set that rewards manufacturers and end-users who can align capacity investments with regional demand signals. Second, the gradual but consistent climb in revenue highlights an industry that is absorbing new automation layers, tighter inline integration, and higher-specification materials processing without sacrificing accessibility for mid-tier operations.
It is important to recognize that forward forecasts are not linear extrapolations. The years ahead will be shaped by the interaction of equipment capability, film and material innovation, compliance timelines, and competitive intensity. Our research isolates these drivers and maps them against demand scenarios so that leadership teams can distinguish between baseline growth and high-leverage investment windows.
Industry Dynamics and the Regulatory-Operational Interface
The operational context surrounding tray sealing equipment has become materially more complex. Food safety compliance is no longer a static checklist; it is an evolving framework that directly influences equipment specification. Alignment with HACCP principles, FDA expectations, and EU food safety standards requires machinery that meets defined hygiene, material compatibility, and performance criteria. At the same time, the FDA Food Traceability Rule compliance date established at January 20, 2026 has sharpened the focus on equipment and processes that support accurate lot handling, line traceability, and data integrity across packaging operations.
On the sustainability and materials side, EU single-use plastics and extended producer responsibility regulations have accelerated collaboration between machine manufacturers, film suppliers, and food processors. This collaboration is pressing equipment designers to accommodate a broader range of substrates, seal formats, and environmental profiles without compromising line speed or package reliability. Complementing this, the EU Food Contact Materials Regulation continues to mandate migration limits and Good Manufacturing Practices for all packaging materials, reinforcing the need for sealing systems that can consistently deliver repeatable performance across variable material inputs.
The industry response to these dynamics is visible in the trade floor. At PPMA Total 2025, thirteen percent of exhibitor visitors identified tray-sealing equipment as their primary interest area, a clear indication that packaging engineering teams are reallocating attention and budget toward sealing technology as a core enabler of compliance, throughput, and waste reduction. This shift is not cosmetic; it reflects a structural re-prioritization in how food manufacturers think about primary packaging as a control point for quality, cost, and regulatory readiness.
Competitive Architecture and Recent Market Activity
The competitive set in the tray sealing equipment market is defined by a balance of scale, specialization, and regional operational strengths. Market concentration reflects a moderately consolidated environment, with the top three players holding a combined share of 42.8 percent and the top five reaching 48.2 percent. This structure creates a landscape where large incumbents provide broad platforms and integration depth, while focused competitors compete on speed, energy efficiency, format flexibility, and application-specific performance.
Leadership teams evaluating vendor selection or benchmarking their current installed base should pay close attention to how different manufacturers are positioning their offerings. Packaging Automation Ltd has advanced a fully electric high-speed automatic REV5 tray sealer engineered to deliver a 20 percent speed increase and 50 percent energy savings, a combination that speaks directly to the dual pressures of throughput and operating cost. JBT Marel has focused on automatic tray sealers suited to burgers, patties, and medium-capacity production lines, and further underscored this direction with the unveiling of the Proseal XTP automatic tray sealer for smart automation in medium-sized production. Reepack S.R.L. has emphasized automatic and semi-automatic tray sealers with snap-on lids and high-speed vacuum skin pack capability, while also showcasing the ReeMaster NextGen series for fresh food performance.
In the retail food packaging segment, ILPRA S.p.A. continues to advance the Speedy series for modified atmosphere packaging and skin pack operations. In volume-driven environments, Ishida Co. Ltd. has demonstrated the QX-800 and QX-500 high-throughput tray sealers, including a live demonstration of the QX-800 at PPMA Total 2025 centered on production efficiency. German engineering has remained highly relevant through Webomatic Maschinenfabrik GmbH, with automatic tray sealers that integrate weighing and packaging systems, and Multivac Sepp Haggenmüller GmbH & Co. KG, with automatic tray sealers built for fresh food and meat processing at high volume. In North America, Form Plastics, Inc. offers HHA600 and automatic and semi-automatic tray sealers for food packaging, while Cima-Pak provides the CiMatic automatic tray sealer for cost-effective small-to-large production runs, and Starview Packaging Machinery Inc. supports inline automatic and manual shuttle configurations through its AITS series.
Specialty and compact-format innovation remains active as well. Gruppo Fabbri Vignola S.p.A. has progressed its Magic 2.0 compact automatic tray-sealing machines with automatic format recognition, supporting changeover efficiency in mixed-SKU environments. Y-Fang Sealing Machine Ltd. rounds out the competitive field with tray sealing machines incorporating vacuum, gas flushing, and auto-dropping piston functionality for food packaging. Collectively, these developments illustrate a market in which incremental technology gains, application-specific engineering, and integration readiness are becoming the primary differentiators.
Inside the Research: What Strategic Buyers Will Gain
Our study is structured to function as an operational decision tool rather than a static market snapshot. It combines a rigorously constructed revenue timeline with a segmentation architecture that isolates how demand is distributed across machine type, application, and region. Executives will be able to use this framework to test capacity plans against realistic demand patterns, identify where automation upgrades are likely to yield the strongest return, and understand which application segments are driving the most intensive equipment specification.
The report also translates market dynamics into procurement and planning relevance. It examines the regulatory and compliance overlay that shapes equipment requirements, connects those requirements to real operational consequences, and maps them against the competitive offerings that are actively entering the market. Recent product launches and exhibition activity are integrated as leading indicators of where technology investment is flowing, enabling readers to anticipate feature migration, pricing pressure, and capability spillover across the competitive set.
Importantly, the study preserves analytical discipline by separating signal from noise. It does not merely aggregate announcements; it interprets them in the context of demand structure, buyer priorities, and installation economics. This makes it possible to identify where the market is genuinely expanding, where growth is concentrated, and where vendor positioning is creating new opportunities for end-users to renegotiate specifications, service terms, and total cost of ownership.
Why 2026 Demands a Disciplined Market View
The current moment rewards preparation over reaction. With compliance dates now active, sustainability and material regulations reshaping supplier relationships, and a competitive field continuously upgrading speed, automation, and energy performance, the window for strategic equipment planning is narrowing. Organizations that rely on fragmented sourcing intelligence or outdated cost assumptions risk under-specifying critical lines, overpaying for capabilities they do not use, or missing the appropriate moment to modernize before throughput and compliance pressures intensify.
Tray Sealing Machines Market
Bag Heat Sealing Equipment Market
Our analysis is built to reduce that uncertainty. It provides the quantitative backbone needed to size the market, the segmentation clarity needed to prioritize use cases, and the competitive context needed to evaluate vendors with greater confidence. By aligning these elements, the research supports decisions on whether to standardize across lines, where to invest in automation, how to assess regional supply dynamics, and which performance attributes should carry the most weight in a purchase or upgrade cycle.
How to Use This Intelligence
For leadership teams preparing 2026 capex reviews, plant modernization plans, and sourcing strategies, the value of this study lies in its ability to connect market structure to operational choice. The macro revenue path and growth rate provide a baseline for demand confidence. The segmentation framework allows teams to test where their product portfolio, production volume, and geographic footprint intersect with the strongest market pull. The competitive and regulatory overlay helps translate those intersections into specification priorities, vendor shortlists, and negotiation parameters.
To move from high-level direction to operational precision, decision-makers need access to the full segmentation detail, regional demand patterns, and application-level revenue splits that form the analytical core of the study. Those elements are essential for building investment cases, sizing line configurations, and benchmarking total cost of ownership across competing equipment pathways.
Accessing the Full Strategic Picture
This article is intended as a strategic primer, not the complete intelligence package. The full research report delivers the granular segmentation, detailed forecast tables, company-level competitive profiling, and regulatory-impact analysis required to make defensible 2026 and 2027 equipment decisions. For executives and planning teams who need to convert market direction into procurement action, the complete study provides the structured evidence base necessary to justify capital allocation, prioritize automation roadmaps, and align sourcing strategy with where the tray sealing equipment market is genuinely heading.
The market is expanding with discipline, the competitive field is advancing with purpose, and the compliance environment is raising the stakes for equipment selection. In that context, informed market intelligence is not optional. It is the foundation for choosing the right technology, the right partners, and the right timing.
For detailed analysis of this topic, please visit the official page: Tray Sealing Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Garbage Disposer Market to Reach $302.53 Million by 2032, 5.0% CAGR
By PW Consulting, 2026-09-16
Navigating the Garbage Disposer Market: Strategic Intelligence for 2026 and Beyond
The global waste management landscape is undergoing a structural transformation, driven by tightening environmental regulations, evolving consumer expectations, and rapid technological integration across residential and commercial kitchen ecosystems. At the center of this shift lies the garbage disposer market, a category that has quietly transitioned from a basic utility fixture to a strategically relevant component of sustainable infrastructure and appliance portfolios. As organizations map out capital allocation, product development pipelines, and regional expansion strategies for 2026, the need for precise, forward-looking market intelligence has never been more critical.
Our latest market research initiative delivers a comprehensive, data-grounded assessment of the garbage disposer industry, designed specifically to support executive decision-making, competitive positioning, and risk-managed growth planning. This overview outlines the strategic architecture of the study, highlights the macro-economic trajectory shaping the sector, and demonstrates how the full intelligence suite can be deployed to accelerate 2026 strategic execution.
Market Trajectory and Macro-Economic Context
The garbage disposer market has demonstrated consistent, measurable expansion over the past half-decade, reflecting broader trends in residential renovation, commercial kitchen upgrade cycles, and municipal waste diversion mandates. Historical performance from the early 2020s through the base year of 2025 reveals a steady revenue climb, supported by both replacement demand and incremental new installations across mature and emerging consumer markets.
Looking ahead, the forecast period spanning 2026 through 2032 projects a compound annual growth rate of approximately 5.0 percent. This trajectory is anchored by several converging forces: sustained housing and remodeling activity, growing adoption of high-rotation-speed disposal units that align with advanced wastewater treatment capabilities, and regulatory tailwinds that favor on-site food waste reduction over landfill dependency. Revenue forecasts across the horizon indicate a clear upward inflection, with market size expanding from the 2026 baseline toward a materially larger footprint by the early 2030s.
For strategic planners, this growth profile is not merely a top-line statistic. It signals a market that is scaling predictably enough to justify product investment and distribution expansion, yet dynamic enough to reward players who can accurately segment demand, anticipate regulatory shifts, and align product engineering with end-user performance expectations. Understanding where value is created across this expansion window is essential for prioritizing R&D budgets, setting pricing architectures, and determining go-to-market timing.
Structural Drivers Shaping Competitive Positioning
The contemporary garbage disposer market is being reshaped by a blend of environmental policy, infrastructure capability, and consumer preference evolution. Municipal solid waste management continues to face mounting pressure, with food waste representing a significant share of landfill volume and contributing disproportionately to methane emissions. This reality has elevated disposal units from convenience appliances to recognized components of broader waste diversion strategies.
Simultaneously, wastewater treatment infrastructure in many regions has advanced to the point where disposed food waste can be processed into renewable energy and nutrient-rich byproducts. This closed-loop potential strengthens the environmental case for disposer adoption and provides a regulatory and sustainability narrative that manufacturers, distributors, and commercial facility operators can leverage in their positioning. Government initiatives that promote sustainable waste management practices further reinforce procurement preferences for higher-rotation, higher-efficiency units capable of processing a broader range of organic waste with reduced clogging and maintenance overhead.
On the commercial and residential installation side, total project economics remain a critical decision factor. Professional replacement and installation workflows carry meaningful cost considerations, and end-user sensitivity to leak prevention, code compliance, and long-term reliability continues to influence brand selection and channel partnerships. These dynamics create an environment where product durability, service network strength, and installer education become differentiators as important as unit-level specification sheets.
For 2026 strategy teams, these drivers translate into several actionable imperatives: aligning product roadmaps with sustainability messaging that resonates with both regulators and end-users, evaluating pricing and installation-service bundling opportunities, and preparing for regulatory environments that may accelerate adoption in specific jurisdictions while constraining less efficient legacy technologies in others.
Competitive Landscape and Corporate Strategy Signals
The market features a diverse set of established appliance manufacturers, specialized disposal producers, and plumbing fixture brands that compete across residential and commercial segments. Competitive differentiation is increasingly rooted in technology integration, acoustic performance, connectivity and serviceability features, and the ability to embed disposal solutions within broader kitchen or facility equipment ecosystems.
Market concentration remains moderately fragmented, with leading players holding a combined share that leaves substantial room for regional specialists, niche innovators, and portfolio-integrated appliance brands to compete on specific value propositions. This structure encourages continuous feature evolution and creates a landscape where strategic partnerships, channel alignment, and brand positioning can be as impactful as volume production scale.
Several incumbents have demonstrated how targeted portfolio moves and product launches can recalibrate market expectations. InSinkErator, recognized as the world's largest manufacturer of food waste disposers, continues to emphasize multi-stage grinding architectures, sound-dampening engineering, and simplified connectivity features across its residential and commercial lines. Recent catalog and point-of-sale material releases have highlighted next-generation disposer designs alongside integrated hot water tap offerings, signaling a broader push toward kitchen experience enhancement rather than isolated appliance performance.
Whirlpool Corporation leverages its global production and distribution footprint by integrating food waste disposers into a wider kitchen appliance portfolio, enabling cross-selling opportunities and unified service narratives across installed bases. Anaheim Manufacturing Company operates through the Waste King brand, delivering a full line of residential and commercial disposers that emphasize durability and broad performance coverage. Moen Incorporated positions garbage disposals within its plumbing fixture ecosystem, aligning disposal offerings with faucet and sink configurations for residential kitchen projects. GE Appliances maintains continuous-feed disposal options within its home appliance lineup, drawing on brand recognition and install-base familiarity. Joneca Company, LLC focuses on high-quality residential and commercial disposers and adjacent kitchen appliance products, while Franke Management AG targets premium disposal solutions for European and global residential markets, underlining the importance of regional design expectations and finish integration.
On the commercial side, Salvajor specializes in commercial-grade garbage disposals and food waste systems, addressing high-throughput environments where reliability, service intervals, and compliance with commercial kitchen standards are decisive procurement factors.
These corporate profiles illustrate a market where competitive advantage is built through a combination of product engineering, channel strength, brand trust, and segmentation focus. For 2026 planning, the strategic question is not simply who holds share today, but which players are best positioned to capture demand shifts arising from regulatory momentum, installer preferences, and commercial facility upgrade cycles.
Beyond established players, the market is also being influenced by discrete operational events that signal where management attention is flowing. Recent catalog launches, updated point-of-sale materials, and product showcase initiatives indicate intentional efforts to reset buyer expectations around performance, aesthetics, and integrated kitchen solutions. These moves often precede broader pipeline changes, making them valuable leading indicators for competitive monitoring and benchmarking.
Garbage Disposer Market
Worldwide Kitchen Food Waste Disposal Machine Market
What the Full Research Study Delivers
This market study is structured to move beyond surface-level sizing and provide an operational intelligence framework that strategy, finance, and product teams can apply directly. The analysis integrates historical performance, forward forecasts, segmentation logic, competitive profiling, and industry context into a single decision-support architecture. The objective is to equip stakeholders with a clear line of sight from macro trends to segment-level implications, without relying on assumptions that rapidly age out of relevance.
The report unpacks the demand environment across residential and commercial use cases, examining how installation behavior, replacement cycles, end-user priorities, and commercial throughput requirements shape volume distribution. It evaluates the type-level composition of the market, highlighting how performance characteristics, material considerations, and application fit influence adoption patterns and price sensitivity. Regional analysis is presented with an emphasis on structural demand drivers, infrastructure readiness, and market maturity differentials, allowing planners to assess where growth is most durable and where execution risk is highest.
Competitive intelligence sections profile the major participants, mapping their product architectures, brand positioning, channel dynamics, and recent strategic actions. This enables benchmarking of feature sets, identification of whitespace opportunities, and assessment of how portfolio breadth or specialization affects competitive resilience. The study also incorporates regulatory and environmental context, including waste diversion statistics, methane emission dynamics, and the role of wastewater treatment capabilities in reinforcing the value proposition of modern disposers. Infrastructure and installation economics are addressed as practical planning inputs, ensuring that total cost-of-ownership considerations are reflected in market modeling rather than treated as afterthoughts.
Importantly, the research framework is designed to support multiple internal use cases. Corporate development teams can use it to evaluate partnership and acquisition targets. Product leaders can use it to prioritize feature investment and specification roadmaps. Sales and marketing organizations can use it to shape channel messaging and installer engagement programs. Finance and strategy functions can use it to stress-test revenue scenarios and align capacity planning with demand inflection points.
Implications for 2026 Strategic Decision-Making
As organizations finalize 2026 plans, the garbage disposer market presents a clear test of strategic discipline. Growth is forecast to continue at a steady pace, but the distribution of that growth across segments, regions, and application types will reward those who can translate market-level trends into targeted execution. The firms that outperform will be those that connect product performance, installer relationships, sustainability positioning, and commercial service reliability into a coherent value proposition.
Several strategic questions should guide internal planning. How does the organization intend to position against both portfolio-integrated appliance brands and specialized disposer manufacturers? Which performance attributes and installation-service factors most influence purchase decisions in the target segment, and how should messaging and channel incentives be structured around them? Where do regulatory and infrastructure trends create the strongest adoption pull, and how should go-to-market resources be weighted across regions with differing maturity levels? How should product engineering and warranty/service strategies evolve to reduce total cost-of-ownership concerns and strengthen long-term brand trust?
Addressing these questions requires market intelligence that is both credible and actionable. Macro-level sizing and growth expectations provide the strategic backdrop, but the real planning advantage comes from understanding the segmentation logic, competitive dynamics, and industry context that determine where share gains are achievable and where defensive positioning is necessary.
Accessing the Full Market Intelligence
This overview has outlined the strategic contours of the garbage disposer market and demonstrated how the full research study is designed to support 2026 decision-making across product, commercial, and corporate functions. The complete report provides the detailed segmentation analysis, competitor benchmarking, regional structural assessment, and scenario-ready forecasting that executives and planners need to move from broad trend awareness to precise strategic action.
Readers seeking the full dataset, segment-level breakdowns, company profiles, and forward-looking modeling can access the complete market research through our official publication channel. The comprehensive study is built to serve as a working intelligence asset throughout the planning cycle, enabling teams to validate assumptions, compare strategic options, and align execution with the most reliable view of market direction available.
For organizations preparing to invest, expand, reposition, or defend in the garbage disposer market, the difference between reactive planning and strategic advantage lies in the depth and reliability of the intelligence underpinning decisions. The full report delivers that foundation, and it is available now for teams ready to translate market insight into 2026 execution.
For detailed analysis of this topic, please visit the official page: Garbage Disposer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Deployable Military Shelter Systems Market to Reach $1.52 Billion by 2032 at 4.3% CAGR
By PW Consulting, 2026-09-16
Strategic Briefing: Navigating the Deployable Military Shelter Systems Market 2026–2032
The global landscape for deployable military shelter systems is undergoing a structural recalibration. As defense organizations prioritize expeditionary readiness, rapid deployment capabilities, and integrated field infrastructure, market participants must look beyond headline procurement budgets and understand the underlying demand architecture. Our newly released market research on deployable military shelter systems provides a precise, forward-looking intelligence framework designed to support capital allocation, product positioning, and competitive strategy through 2032. This briefing outlines the strategic value of the study for enterprise decision-makers operating in defense manufacturing, logistics, and government contracting ecosystems.
Market Trajectory and the Strategic Imperative for 2026
From 2020 through 2025, the market demonstrated consistent upward momentum, driven by sustained defense modernization programs, expanded field hospital requirements, and accelerated deployment cycles for joint operations. Revenue reached 1,133.51 million USD in the base year of 2025, reflecting both organic program growth and the compounding effect of infrastructure modernization mandates. The forecast period from 2026 to 2032 projects continued expansion at a compound annual growth rate of 4.3 percent, with market valuation expected to approach 1,522.0 million USD by the end of the horizon.
Worldwide Portable Shelter Market
This trajectory is not uniform across all operational environments or procurement timelines. Growth will be shaped by how quickly manufacturers can adapt shelter architectures to emerging mission profiles, integrate environmental control units, and align production capacity with shifting trade and materials policy. Decision-makers evaluating product roadmaps, capacity investments, or partnership strategies need granular visibility into how regional procurement rhythms intersect with demand concentration, deployment velocity, and lifecycle support expectations. The full research study maps these intersections with quantitative discipline, enabling teams to prioritize initiatives that align with verified demand signals rather than speculative assumptions.
Report Architecture: From Macro Trends to Execution-Ready Intelligence
This research is structured to move beyond descriptive market sizing and deliver actionable strategic intelligence. The analytical framework integrates historical performance data, forward-looking projections, and cross-referenced segmentation logic to present a cohesive view of market behavior. Key components include:
- Comprehensive market sizing and forecasting anchored in a transparent methodology, with base-year validation and scenario-adjusted projections across the full forecast window.
- Segmentation analysis that isolates the structural drivers of demand across shelter configurations, application domains, and regional procurement environments, without relying on simplified aggregate narratives.
- Competitive landscape profiling that maps incumbent positioning, product portfolio breadth, manufacturing footprint, and recent strategic moves influencing share dynamics.
- Regulatory and materials policy impact assessment, with specific attention to how evolving tariff structures and trade modifications alter cost baselines, sourcing strategies, and margin resilience.
- Deployment and procurement context covering operational requirements, lifecycle support models, and integration trends that influence purchasing decisions at the program level.
Each section is designed to support distinct decision functions. Executive leadership can use the forecast architecture to stress-test pipeline assumptions and capital deployment timing. Product and engineering teams can align shelter design priorities with the configurations showing the strongest operational pull. Commercial and business development functions can use the competitive and regional analysis to refine targeting logic, negotiation positioning, and channel strategy. Rather than presenting isolated statistics, the study connects structural indicators to decision consequences, giving organizations a practical foundation for strategy execution.
Competitive Landscape: Positioning, Differentiation, and Strategic Friction
The deployable military shelter systems market remains moderately concentrated, with a meaningful share held by established manufacturers that combine engineering heritage, scale production capability, and long-term defense program relationships. This concentration shapes both opportunity and constraint.Market entrants and incumbent players alike must contend with differentiated requirements across mission profiles, where shelter systems are evaluated not only on deployment speed and portability but also on climate control integration, modularity, durability under sustained field use, and compatibility with broader base-camp infrastructure.
Several leading organizations illustrate the competitive variety shaping today's market. HDT Global continues to emphasize expeditionary shelters, rigid wall systems, and integrated infrastructure, while also navigating high-profile internal transitions and live-training engagements that signal operational relevance and product maturation. Alaska Defense has built a recognizable position around rapidly deployable military shelters, base camps, and environmental control units, supported by approval-status systems and a substantial production record that reinforces scale credibility. Rubb UK contributes fabric-clad rapid-deploy buildings and aircraft shelters, highlighting the continuing relevance of flexible structural solutions within defense applications. Weatherhaven Global Resources broadens the competitive field with redeployable shelter systems and camp infrastructure designed for military, medical, and field operations across multiple geographies.
Additional participants deepen the competitive texture. UTS Systems focuses on rapid-deploying folding-frame shelters, tents, generators, and integrated turnkey offerings, underscoring the value of converged field-power and shelter solutions. Losberger De Boer extends into both temporary and permanent space solutions, aligning deployable military shelters with wider protected-space capabilities. CAMSS Shelters targets lightweight, portable military shelters and specialized medical packages, while Litefighter Tactical addresses individual and lightweight tactical shelter needs that complement larger system-level deployments. G3 Systems rounds out the competitive set with deployable infrastructure, containerized solutions, and through-life support models, reflecting an increasing emphasis on lifecycle service alongside hardware delivery.
Recent developments reinforce the operational and strategic stakes within this competitive set. HDT Global's transition to a new branding architecture and its training engagements with recognized military units point to product lineage evolution and continued field validation. G3 Systems' major contract award for deployable logistics infrastructure illustrates how large-scale program wins can reshape regional demand visibility and competitive expectations. These moves are not isolated milestones; they signal how manufacturers are shaping market presence through product repositioning, program capture, and demonstration of deployment readiness.
Regulatory and Materials Dynamics: Cost, Sourcing, and Margin Resilience
Market performance in this sector is increasingly intertwined with trade policy and materials cost dynamics. Recent adjustments to U.S. Section 232 measures on steel and aluminum have introduced renewed complexity for manufacturers dependent on metal-intensive shelter components, structural framing, and derivative product inputs. Tariffs were restored and subsequently increased, with further modifications extending coverage and altering how customs value is calculated for many derivatives. At the same time, targeted adjustments have created temporary reductions for select defense industrial base products and domestic manufacturing sectors, introducing a layered environment where sourcing decisions must account for both cost exposure and eligibility for relief.
For shelter system producers, these dynamics influence more than input pricing. They affect supplier selection, make-versus-buy analysis, invoice timing, and the competitive positioning of domestically sourced versus imported structural components. In a market where procurement cycles can be lengthy and program budgets tightly managed, cost volatility can alter bid competitiveness, margin planning, and the attractiveness of particular shelter configurations under different procurement scenarios. The research study incorporates these regulatory and materials pressures into its market dynamics assessment so that commercial leaders can evaluate how policy shifts may propagate through pricing strategy, sourcing mix, and regional demand interpretation.
Application and Configuration Realities: Where Demand Is Taking Shape
Demand for deployable military shelters is distributed across multiple operational functions, each with distinct performance criteria and procurement drivers. Command and control environments prioritize rapid setup, communications integration, and protected workspace that supports mission continuity. Medical unit deployments place heavier emphasis on climate management, hygiene, modularity, and the ability to scale or reconfigure as casualty and treatment requirements evolve. Accommodation needs focus on durability, occupancy efficiency, and redeployment readiness across repeated rotation cycles. Maintenance and logistics applications depend on sheltered workspace that supports equipment protection, parts handling, and sustained field-service operations.
These application requirements interact with configuration alternatives in ways that shape competitive positioning. Soft-wall shelters continue to serve use cases where rapid deployment, lower transport burden, and flexible footprint adaptation are prioritized. Rigid shelters address scenarios requiring greater structural durability, improved environmental isolation, and longer service life under sustained operation. Containerized shelters represent a growing orientation toward standardized logistics integration, intermodal handling, and hardened storage or workspace solutions that align with broader supply-chain thinking. The interplay between these configuration types and application needs is not static; it evolves with force posture, deployment tempo, and program-specific infrastructure strategies. Our study unpacks these relationships in detail, giving decision-makers a clearer view of where configuration preferences are strengthening and where substitution dynamics may influence future share patterns.
Regional Demand Architecture: Interpreting Procurement Geography
Regional demand patterns reflect differences in defense spending priorities, force structure, basing strategy, and local manufacturing or sourcing incentives. North America continues to represent a substantial demand base, shaped by sustained procurement activity and an established industrial base capable of supplying integrated shelter and camp infrastructure. European demand is influenced by multinational deployment requirements, force mobility priorities, and a competitive supplier environment that spans both domestic manufacturers and cross-border program participation. Asia Pacific demand reflects a broadening set of defense modernization and operational readiness initiatives, where procurement complexity and regional sourcing considerations can vary significantly by program. Latin America and the Middle East and Africa together represent additional demand pockets, often characterized by specialized project-driven requirements, humanitarian or disaster-response overlap, and selective procurement cycles rather than continuous high-volume ordering.
Reading regional demand accurately requires more than top-line geography splits. It demands an understanding of how procurement authorities evaluate shelter solutions, how local content expectations interact with import dependencies, and how program timing creates uneven demand waves across markets. The research study provides the regional context necessary to distinguish structural growth from program-specific spikes, helping organizations allocate engagement resources and production planning with greater precision.
Deployable Military Shelter Systems Market
Strategic Takeaways for 2026 Enterprise Decision-Making
For organizations operating in or adjacent to this market, the 2026 decision environment calls for disciplined prioritization. Several strategic implications stand out:
- Forecast confidence must be paired with configuration-level insight. Aggregate growth numbers are useful for orientation, but operational decisions depend on understanding which shelter types and application areas are accelerating, which are stabilizing, and where substitution risk may influence future demand.
- Competitive positioning increasingly depends on integration and lifecycle capability. Manufacturers that can demonstrate rapid deployment, environmental control compatibility, redeployment efficiency, and through-life support are better positioned to compete for complex program requirements.
- Materials and trade policy exposure should be treated as a strategic variable, not a background condition. Tariff volatility and derivative coverage changes can affect cost structures unevenly across product lines, so sourcing strategy and pricing architecture need proactive review.
- Regional engagement strategies should be calibrated to procurement rhythm rather than assumed continuity. Demand concentration, program timing, and local sourcing expectations differ enough across regions that a single go-to-market approach rarely fits all environments.
The full market research study converts these strategic themes into measurable, scenario-ready analysis. It provides the segmentation logic, competitive context, regulatory assessment, and forecast architecture needed to support product planning, commercial targeting, risk evaluation, and investment prioritization. For leadership teams preparing for the 2026 decision cycle and beyond, the study offers a defensible foundation for translating market signals into executable strategy.
Accessing the Full Intelligence Package
This briefing is intended to demonstrate the scope and analytical rigor of the research while preserving the detailed segmentation, regional breakdowns, and proprietary competitive assessment for the complete report. Organizations that require precise revenue splits, regional and application-level demand distribution, configuration share patterns, and expanded competitor profiling will find the full study structured to support direct strategic application. The complete dataset and interpretive analysis are available through the PW Consulting market research portal, where decision-makers can evaluate the full evidence base and integrate it into planning workflows.
The deployable military shelter systems market will continue to reward organizations that combine operational understanding with disciplined commercial analysis. By aligning strategy with verified demand structure, competitive reality, and policy-sensitive cost dynamics, enterprises can move from reactive positioning to informed market participation. We invite leadership teams, strategy professionals, and commercial operators to review the full research release for the detailed intelligence needed to support confident decisions across the 2026–2032 horizon.
For detailed analysis of this topic, please visit the official page: Deployable Military Shelter Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Brake Disc Market Hits USD 17.8 Billion in 2025, Projects 5.5% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Brake Disc Market: Strategic Intelligence for 2026 and Beyond
The global automotive braking sector stands at a critical inflection point. As original equipment manufacturers navigate shifting emissions mandates, electrification curves, and supply chain realignments, the brake disc has evolved from a commodity component into a strategically differentiated system. Our newly released Brake Disc Market research study is designed specifically for executive teams and strategy directors who require actionable intelligence to shape capital allocation, sourcing strategies, and product roadmaps throughout the 2026 to 2032 horizon.
Grounding this analysis in a disciplined historical baseline, the study tracks market evolution from 2020 through 2025 before projecting forward across a seven-year forecast window. By capturing the full arc of post-pandemic recovery, supply normalization, and technology transition, the report provides a robust analytical framework that moves well beyond superficial trend-spotting. Readers will find a structured evaluation of volume trajectories, material substitution patterns, and regional demand kinetics that together map the terrain executives must navigate in the coming planning cycles.
The 2026 Decision Landscape: Why This Research Matters Now
Strategic planning in the automotive component space has never demanded greater precision. The brake disc market is no longer governed solely by vehicle production indices; it is increasingly shaped by regulatory design rules, material cost volatility, and the engineering requirements of electrified powertrains. For leadership teams evaluating capacity expansions, supplier partnerships, or aftermarket portfolio positioning, the difference between a reactive posture and a proactive one lies in accessing a detailed, forward-looking intelligence framework.
Our analysis shows that revenue trajectories are advancing steadily through the forecast period, anchored by sustained demand across passenger vehicles, commercial transport networks, and the expanding two-wheeler segment. The compound annual growth rate underpinning these projections reflects a market that is maturing rather than surging, demanding disciplined segment selection and operational precision. This growth profile creates a nuanced strategic reality: broad-based expansion is possible, but the most significant value creation will accrue to firms that understand where demand is structurally strengthening, which material platforms are gaining engineering adoption, and how regulatory pressure is reshaping supplier economics.
Understanding the competitive structure is equally vital. The study maps a moderately concentrated landscape where leading suppliers command meaningful share, yet fragmentation persists across regional and application-specific niches. This configuration rewards firms that can differentiate through engineering capability, coating technologies, and integrated system offerings rather than competing purely on volume pricing. Executives seeking to enter new geographies, secure tier-one partnerships, or reposition aftermarket channels will find the structural analysis directly applicable to deal evaluation and risk assessment.
What the Report Delivers: A Practical Strategic Toolkit
This market study is built for practitioners who need more than aggregate projections. The report translates macroeconomic indicators into decision-grade frameworks across four interconnected analytical dimensions:
- Market sizing and trajectory modeling , anchored in a five-year historical dataset and extended through a comprehensive seven-year forward outlook, enabling scenario planning across base, accelerated, and constrained growth environments.
- Segmentation deep dives that examine structural demand drivers by vehicle category and material platform, highlighting where engineering adoption curves and regulatory pressure are reshaping procurement priorities.
- Competitive profiling of established tier-one suppliers and specialized performance manufacturers, mapping their strategic positioning, product architecture, and recent capability expansions to identify partnership and competitive threats.
- Industry dynamics assessment that evaluates the interplay between emissions regulation, raw material cost exposure, and electrification-driven design shifts, translating these forces into operational implications for sourcing, capacity, and R&D investment.
Throughout the report, data is presented with an emphasis on application rather than abstraction. Readers will find analytical structures designed to support supplier selection matrices, regional entry assessments, and portfolio prioritization exercises. The objective is to equip strategy teams with a shared reference point that can be integrated directly into quarterly planning, investment committee discussions, and product strategy reviews.
Competitive Architecture: Leaders, Specialists, and Shifting Positions
The brake disc supply landscape blends globally scaled automotive suppliers with specialized engineering firms competing on performance, weight reduction, and application-specific durability. A clear understanding of this architecture is essential for executives evaluating commercial partnerships, competitive benchmarking, or bolt-on acquisition targets.
Brake Disc Market
European engineering groups continue to anchor the premium and commercial segments through integrated system approaches. Suppliers such as Brembo and ZF have built portfolios that span standard passenger vehicle applications, high-performance platforms, and advanced safety-integrated brake architectures. Their strategic emphasis on modular system design and specialized material offerings positions them to capture value in applications where engineering differentiation matters more than unit-cost competition. Similarly, Robert Bosch and Continental maintain substantial presence through high-volume cast-iron platforms and ventilated disc solutions that align with mainstream passenger and light commercial production schedules.
Abrasive Disc Market
In the commercial vehicle domain, firms like Knorr-Bremse and Santa Brake highlight the specialized requirements of heavy-duty applications, where thermal management, wear resistance, and service-life durability drive procurement decisions. These players illustrate how segment-specific engineering specialization can sustain competitive advantage even in markets where production volumes are comparatively concentrated.
The performance and motorsport niche adds another layer of strategic relevance. Companies such as Wilwood Engineering, AP Racing, and SGL Carbon pursue lightweighting and extreme thermal performance through carbon-ceramic and advanced composite architectures. While these volumes remain niche relative to mainstream production, they exert disproportionate influence on material innovation pipelines and premium brand positioning. Surface Transforms and other carbon-ceramic specialists further illustrate how advanced material platforms are transitioning from racing-derived technology into select OEM applications.
Across the Asia-Pacific supply base, manufacturers including Aisin Seiki, Mando, Akebono Brake Industry, and ADVICS emphasize OE-quality consistency, global production scalability, and durability-optimized cast-iron platforms. Their growth trajectories reflect the broader realignment of automotive manufacturing networks and the expanding role of regional suppliers in global procurement architectures. MAT Foundry Group and NG Brakes add further dimension by targeting custom casting requirements and specialized motorcycle applications respectively, underscoring the breadth of opportunity beyond standardized volume production.
Recent company-level developments reinforce the strategic signal. In mid-2025, AP Racing expanded its technical documentation and product catalogue, strengthening its positioning in performance-parts transparency and specification-driven procurement. More recently, Brembo introduced a carbon-ceramic disc engineered for a flagship high-performance application, signaling continued investment in premium material platforms. Meanwhile, low-emission brake technology launches featuring specialized disc coatings have begun emerging across the supplier base, directly responding to tighter particulate matter constraints and OEM compliance timelines.
Forces Reshaping the Market: Regulation, Materials, and Electrification
No brake disc strategy can be formulated in isolation from the structural forces now governing component design and sourcing economics. Three interlocking dynamics deserve particular attention from leadership teams.
The first is the regulatory environment. Emissions frameworks introduced across major markets have begun imposing explicit constraints on brake particulate matter, a development that fundamentally alters the engineering priorities for disc surfaces and material interfaces. Coatings and specialized surface treatments are no longer optional enhancements in many premium and regulated segments; they are becoming compliance prerequisites. This shift changes the cost structure of standard disc configurations, accelerates qualification cycles for new coatings, and creates differentiation opportunities for suppliers that can deliver certified low-emission solutions without compromising thermal performance.
The second force is raw material exposure. Cast-iron and alloy inputs represent the dominant share of production operating costs across the brake disc manufacturing base, and price volatility in steel and related input markets continues to affect a substantial portion of global suppliers. This cost structure means that procurement strategy, hedging approaches, and casting efficiency are not back-office concerns; they directly influence margin resilience and competitive pricing power. The study evaluates how input cost sensitivity varies across segments and geographies, providing executives with context for negotiating long-term agreements, evaluating vertical integration options, and modeling scenario-based profitability.
The third dynamic is electrification. As electric vehicle adoption expands, brake system design is being recalibrated around regenerative braking behavior, reduced friction-use patterns, corrosion and surface-stability challenges, and the broader 경량화를 위한 재료 전환 압력. These factors do not eliminate demand for friction brake discs, but they reshape the performance requirements, replacement cycles, and material preferences that manufacturers must account for in product planning. Lightweight disc architectures and advanced composite platforms are gaining engineering attention precisely because they align with packaging constraints, range optimization goals, and performance expectations in electrified applications.
Using the Study for 2026 Strategic Execution
For executives preparing for the 2026 planning cycle, the value of this research lies in its direct applicability to four common strategic questions.
First, where should capacity and investment be prioritized? The report maps structural demand progression across the forecast window, allowing teams to distinguish between segments driven by volume expansion and those shaped by material upgrading, regulatory compliance, or performance differentiation. This distinction is essential for avoiding overinvestment in commoditizing niches while capturing higher-margin opportunities in coating-dependent or performance-oriented applications.
Second, how should supplier relationships and sourcing strategies be recalibrated? With input cost volatility affecting a meaningful share of the manufacturing base and regulatory requirements raising the importance of certified coatings, procurement leaders need a clear view of which suppliers can deliver cost stability, engineering compliance, and application-specific qualification speed. The competitive profiles and dynamics analysis provide a basis for renegotiating terms, qualifying alternates, or structuring joint development agreements.
Third, which geographies and application segments warrant deeper commitment? Regional demand patterns and application mix are shifting at different speeds. The study clarifies where growth momentum is most consistent and where operational complexity, competitive density, or regulatory exposure requires more cautious engagement. This enables leadership teams to sequence market entry, distribution expansion, or local production decisions with greater confidence.
Fourth, how should innovation pipelines and product roadmaps be aligned with market trajectory? The convergence of emissions compliance, electrification design requirements, and performance lightweighting is creating a multi-vector innovation environment. The report helps R&D and product strategy teams prioritize development resources by identifying where advanced material platforms, coating technologies, and system-integration capabilities are likely to command premium positioning versus where cost-efficient standardization will remain the dominant competitive logic.
Accessing the Full Intelligence Framework
This overview has outlined the strategic context, competitive architecture, and market dynamics that define the brake disc sector entering 2026. Yet the full analytical value of the study resides in the detailed segmentation structures, forward projections, competitive benchmarking depth, and scenario-based interpretations that cannot be fully captured in a summary article. For strategy directors, procurement leaders, and investment planners, those detailed dimensions are the difference between directional awareness and execution-ready intelligence.
The complete Brake Disc Market research study offers the granular frameworks, data-backed projections, and competitive assessments required to translate strategic intent into concrete 2026 decisions. Readers seeking the full market sizing logic, segmentation dynamics, supplier benchmarking detail, and regulatory impact analysis are encouraged to access the source report directly, where the complete intelligence architecture is available for internal planning, committee review, and strategic alignment.
For detailed analysis of this topic, please visit the official page: Brake Disc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Slurry Tankers Market Hits $1,450M in 2025, Growing at 7.8% CAGR Through 2032
By PW Consulting, 2026-09-16
Beyond Capacity: Strategic Intelligence for the Evolving Slurry Tankers Market
The global agricultural and industrial infrastructure landscape is undergoing a structural transformation, and few equipment categories illustrate this shift as clearly as slurry tankers. As precision farming, environmental compliance, and nutrient management consolidate into core operational imperatives, decision-makers require more than historical sales figures. They need forward-looking intelligence that maps capacity planning, regulatory exposure, competitive positioning, and regional demand trajectories into a single actionable framework. Our latest market research release does exactly that.
This analysis serves as a strategic preview of the full report. It demonstrates the analytical rigor, data architecture, and commercial relevance embedded in the study, while preserving the granular breakdowns that procurement leaders, investors, and OEM strategists will need to access directly. The objective is clear: equip executives with the confidence to act, while directing detailed segment-level intelligence to the complete publication for precise planning.
Market Trajectory and the Strategic Imperative for 2026
The slurry tankers market has demonstrated consistent expansion across the 2020 to 2025 historical window, moving from a baseline revenue footprint of approximately $1,050 million in 2020 to an estimated $1,450 million by 2025. This growth reflects more than cyclical agricultural demand. It signals a structural recalibration driven by tightening nutrient runoff regulations, the modernization of farm-scale logistics, and the industrial adoption of precision slurry handling systems.
Looking ahead, the forecast period from 2026 through 2032 projects a compound annual growth rate of 7.8 percent on a USD basis. By the close of the forecast horizon, the market is positioned to reach a substantially higher revenue threshold, underscoring a durable demand environment rather than a temporary upcycle. For corporate planners, this trajectory carries immediate implications. Capital allocation decisions made in 2026 will determine whether organizations capture early-mover advantages in high-growth configurations, align procurement with regulatory timelines, or risk exposure to capacity shortages and compliance gaps.
The strategic value of this research lies in its ability to translate macro growth into executable planning parameters. Executives reviewing the full report will find historical validation paired with forward-looking scenarios that account for policy shifts, technology adoption curves, and regional supply chain dynamics. Rather than treating market size as a static number, the study frames it as a living indicator of operational readiness across agriculture, industry, and adjacent application segments.
Regulatory Architecture and Competitive Dynamics
Market expansion in this category is not occurring in a vacuum. Environmental legislation has become a primary catalyst for equipment specification, procurement timing, and technology integration. Across multiple jurisdictions, regulators are mandating precision application, reducing ammonia emissions, and requiring comprehensive nutrient management planning. These mandates are reshaping demand patterns and accelerating the transition toward vacuum-assisted systems, GPS-enabled dosing controls, and advanced spreading implements.
In the European Union, the Nitrates Directive continues to anchor application limits, with enforcement across member states driving adoption of equipment capable of meeting stricter emission thresholds. National frameworks in Germany, Denmark, and the Netherlands have layered additional requirements, particularly in nitrate-vulnerable zones, where precision application equipment and trailing shoe injector compatibility are increasingly non-negotiable for new tanker procurement. These regulatory pressures are not merely compliance costs; they are redefining product specifications, influencing chassis design, and elevating the strategic importance of modular, upgrade-ready platforms.
Outside Europe, policy environments are equally consequential. In North America, concentrated animal feeding operation regulations are reinforcing the need for structured nutrient management planning, directly supporting slurry tanker demand in intensive dairy and livestock regions. In Canada, agricultural operations legislation has introduced planning thresholds that incentivize equipment adoption for larger-scale enterprises. The cumulative effect is a regulatory landscape that rewards manufacturers and fleet operators who proactively integrate precision technology, while creating friction for legacy configurations that lack adaptability.
These dynamics also shape competitive behavior. The market exhibits a measured concentration profile, with the top three players holding a combined share of approximately 28 percent and the top five approaching 42 percent. This structure indicates a landscape where established manufacturers maintain meaningful influence, yet sufficient fragmentation remains to reward differentiated engineering, localized service networks, and targeted product launches. For procurement and strategy teams, understanding where concentration ends and regional specialization begins is critical to supplier evaluation and risk mitigation.
What the Full Report Delivers: Scope, Structure, and Operational Utility
The complete market research publication is designed to move beyond high-level commentary and provide a structured intelligence toolkit. It combines historical validation, forward-looking forecast modeling, segmentation logic, and competitive profiling into a single reference framework. The report is organized to support multiple decision contexts, from capex planning and supplier selection to market entry analysis and product roadmap alignment.
Slurry Tankers Market
At the core of the study is a detailed segmentation architecture that isolates demand patterns across equipment configurations and end-use contexts. Buyers will find scenario-ready data that clarifies how different tanker formats are positioned across operational environments, and where capacity, maneuverability, and application precision intersect with commercial priorities. Regional analysis is presented to illuminate demand distribution, adoption maturity, and policy-driven variation across major geographic markets, allowing planners to identify where regulatory acceleration, farm modernization, or industrial slurry handling practices are most influential.
Slurry Pump Market
The forecasting methodology integrates historical performance with forward indicators to project revenue evolution across the 2026 to 2032 horizon. Rather than offering a single deterministic outcome, the research frames growth as a function of policy enforcement, technology refresh cycles, and regional investment pacing. This approach is particularly valuable for organizations that must justify multi-year equipment programs or evaluate the timing of fleet upgrades against compliance deadlines.
Operational utility extends to product specification trends as well. The report examines the growing importance of vacuum-assisted designs, chassis-independent architectures, lightweight axle configurations, and integrated spreading or dosing systems. These technical themes are mapped against practical considerations such as storage capacity ranges, emptying efficiency, material durability, and compatibility with precision nutrient application workflows. For engineering and procurement teams, this provides a structured way to compare vendor offerings against operational requirements and regulatory expectations.
Competitive intelligence is another central pillar. The publication profiles leading manufacturers and evaluates how product differentiation, regional footprint, and recent launch activity shape market positioning. This includes attention to design innovations, capacity ranges, certification status, and the strategic emphasis each company places on sustainability, precision application, or modular expandability. Recent launch activity is tracked to identify where product refresh cycles are accelerating and where feature upgrades are likely to influence purchasing decisions in the near term.
Competitive Positioning: Where Differentiation Is Being Won
The competitive environment in slurry tankers is increasingly defined by engineering specificity. Manufacturers are differentiating not only through capacity, but through design architectures that address crack prevention, pressure-vessel certification, full emptying performance, lightweight axle optimization, and integrated nutrient management workflows. These attributes are becoming decisive factors in fleet procurement, particularly where operators must balance efficiency, regulatory conformity, and long-term serviceability.
Several leading players illustrate the breadth of current market strategy. Major Equipment has built its positioning around custom-designed slurry tankers, emphasizing a patented bottom design intended to reduce cracking risk and support capacities that span from mid-range to large-volume configurations, often paired with vacuum pumps and spreaders. JEANTIL has focused on chassis-independent vacuum slurry platforms with PED-certified pressure vessels and multi-purpose spreading equipment, targeting precision application across a broad capacity spectrum. Garant Kotte operates with a strong German market presence, emphasizing lightweight axle systems, full emptying capability, and alignment with liquid manure technology standards across single- to four-axle formats.
Other participants reflect regional adaptation and application-specific refinement. Rigual has placed emphasis on truck-mounted and trailer-mounted configurations, combining spreading equipment with sustainable design principles and digital transformation initiatives aimed at high-volume farm slurry collection and transport. In New Zealand, Nevada Group has specialized in dairy effluent slurry tankers with varied axle configurations, pond stirrers, and nutrient management system integration. SlurryKat has pursued innovation in both vacuum and non-vacuum configurations, with product lines designed for efficient farm-to-field transfer and bespoke umbilical systems. JOSKIN S.A. has expanded its European manufacturing footprint around high-capacity galvanized and Alpina-series platforms, offering modular vacuum options and precision spreading implements across multiple production sites.
Recent launch activity reinforces the pace of product evolution. SlurryKat introduced a new tanker series showcasing advanced vacuum technology and precise dosing capabilities, while Giligroup expanded its portfolio with a large-capacity tanker integrated with an applicator aimed at improving spreading efficiency. SAMSON Group broadened its tanker range with a model emphasizing enhanced performance and container options, and Pichon Industries added multiple platform variations to strengthen capacity and application versatility. These releases are not isolated product updates; they are indicators of where manufacturers are placing strategic bets on compliance readiness, precision delivery, and fleet flexibility.
Strategic Use Cases: Turning Intelligence into Action
For executive teams, the full report is structured to support several high-stakes decisions. Procurement leaders can use segmentation and regional data to align tanker specifications with operational context, ensuring that capacity, axle configuration, and application technology match both field requirements and regulatory timelines. OEMs and component suppliers can leverage competitive profiling and product launch tracking to identify whitespace, anticipate refresh cycles, and calibrate engineering priorities against demand signals. Investors and analysts can use the forecast framework to assess market durability, evaluate concentration dynamics, and determine where regional policy momentum is most likely to influence revenue growth.
The study also supports scenario planning around compliance-driven demand. As precision application mandates tighten and nutrient management planning becomes more entrenched, organizations that understand where regulatory acceleration is strongest can sequence fleet renewal, prioritize vacuum-assisted or injection-compatible configurations, and reduce the risk of stranded legacy assets. The research makes these connections explicit by linking policy dynamics, regional enforcement variance, and equipment specification trends into a coherent planning narrative.
Conclusion: Navigate 2026 with Precision, Not Assumption
The slurry tankers market is entering a phase where growth, regulation, and technology adoption converge. Historical expansion has laid the foundation, the forecast period points to sustained momentum, and competitive differentiation is increasingly tied to precision engineering, compliance readiness, and regional adaptation. For organizations operating in agriculture, industry, or supporting equipment ecosystems, the question is no longer whether the market is expanding, but how to position assets, procurement, and product strategy in response.
This publication preview has outlined the strategic architecture of the research and demonstrated why the full report matters for 2026 decision-making. To access the complete segmentation data, regional demand breakdowns, competitive share detail, forecast scenarios, and manufacturing profiles needed for precise planning, readers should consult the full market research release. The intelligence required to act with confidence is there; the strategic advantage comes from using it early.
For detailed analysis of this topic, please visit the official page: Slurry Tankers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


