



Category: Machinery & Automotive
PW Consulting: Digital Servo Press Market to Hit $258.5M by 2032, Driven by 5.85% CAGR
By PW Consulting, 2026-09-16
Navigating the Digital Servo Press Landscape: Strategic Intelligence for 2026 Decision-Making
The Shift from Mechanical Inertia to Digital Precision
The industrial forming sector is undergoing a structural transformation that extends far beyond incremental equipment upgrades. As manufacturing operations confront tighter tolerance requirements, escalating energy costs, and the imperative for real-time production traceability, digital servo press technology has emerged as a critical enabler of next-generation fabrication workflows. Our latest comprehensive market study examines this transition not as a speculative trend, but as a measurable redefinition of how metal forming, precision assembly, and high-volume stamping operations are engineered, controlled, and scaled. The research is explicitly structured to equip executive teams, procurement leaders, and technology strategists with actionable intelligence ahead of the 2026 capital planning cycle.
Historical trajectory analysis reveals a market that has demonstrated consistent expansion across the 2020 to 2025 evaluation window, recovering from temporary supply-chain friction to close the base year at a documented valuation of 177.0 million USD. Projections for the forward assessment period, spanning 2026 through 2032, indicate sustained momentum with a forecasted compound annual growth rate of 5.85 percent. This trajectory reflects more than baseline replacement demand. It captures a fundamental shift in buyer behavior, where conventional mechanical presses are increasingly evaluated against digital architectures that offer programmable stroke profiles, closed-loop force monitoring, and integrated data streams compatible with modern production management ecosystems. The market sizing framework used throughout this study establishes the quantitative foundation for scenario modeling, yet the true strategic value lies in understanding the operational, regulatory, and competitive forces that will shape procurement decisions, partnership structures, and technology roadmaps over the next seven years.
Market Architecture and the Strategic Intelligence Embedded in the Report
The study delineates the digital servo press landscape across multiple analytical dimensions, each calibrated to support cross-functional alignment within manufacturing organizations. Supply-side segmentation examines equipment typologies, mapping how distinct mechanical configurations address specific forming requirements, load profiles, and integration constraints. Demand-side analysis traces deployment patterns across end-use verticals, highlighting where precision tolerances, energy efficiency mandates, and traceability requirements are accelerating technology adoption. Geographic distribution is assessed not merely as a volume indicator, but as a lens into regional regulatory environments, industrial policy incentives, localized service infrastructure, and supply-chain resilience considerations that directly influence total cost of ownership.
Beyond structural mapping, the report delivers operational frameworks that translate market signals into procurement and investment strategy. Readers will find detailed evaluations of control architecture requirements, including the role of Ethernet/IP and OPC-UA protocols in meeting traceability standards demanded by automotive and medical manufacturing environments. The analysis addresses energy-consumption dynamics, emphasizing how direct-drive servo configurations eliminate traditional clutch and brake flywheel assemblies, thereby aligning equipment selection with corporate sustainability targets and utility cost management. Labor productivity considerations are quantified through operational efficiency benchmarks, demonstrating how programmable motion control and integrated force monitoring can compress operational expenditures in high-volume stamping by up to thirty percent when compared against conventional press architectures. These insights are presented alongside deployment risk matrices, integration complexity assessments, and lifecycle cost comparison models designed to support capital allocation committees and engineering leadership teams.
Competitive Positioning: Leading Vendors and Recent Strategic Movements
The competitive environment is characterized by moderate concentration, with the top three firms collectively commanding approximately twenty-four point six percent of market revenue and the top five approaching twenty-six point two percent. This structure indicates a landscape where scale advantages coexist with meaningful space for specialized engineering differentiation, regional service expansion, and application-specific solution development. The report profiles the principal participants whose technological roadmaps and commercial activities are actively shaping procurement expectations and integration standards.
Digital Servo Press Market
Zani S.p.A., headquartered in Turate, Italy, continues to advance its Servo Master series, which leverages direct-drive servo motors to enable fully programmable motion control in cold metal forming applications. The company has reinforced its digital control footprint through a technology partnership with Siemens, integrating the SIMATIC S7-1500T controller to deliver complete digital control and Industry 4.0 compatibility. A subsequent introduction of the Servo Smart series extends this capability with enhanced flexibility for two hundred to four hundred ton servo press configurations. SEYI Machinery Industry Co., Ltd., based in Taiwan, focuses its SDG and SDE series on medium-to-large servo presses with fully digital control, targeting automotive and electric vehicle stamping workflows. The company has reinforced its global service posture through a Bajío facility establishment in Mexico, strengthening deployment support and after-sales infrastructure. AIDA Engineering, Ltd., operating from Japan, provides the DSF direct-drive servo press series, which incorporates IoT-enabled analytics for high-precision metal forming. The AIDA-America organization demonstrated integrated stamping line solutions at FABTECH 2025 in Chicago, reinforcing its focus on collaborative line-level deployment models. Promess Incorporated, located in Brighton, Michigan, specializes in fully electric EMAP servo presses that embed integrated force and torque monitoring, a configuration particularly aligned with precision assembly applications. MSA Factory Co., Ltd., another Japanese manufacturer, contributes the HE-DD digital servo press series, engineered for precision hot pressing and high-temperature forming requirements. Square Automation, based in Pune, India, delivers automatic servo press machines featuring AC servo motors and pressure-displacement monitoring, addressing assembly and forming needs within cost-sensitive and rapidly scaling production environments.
These vendor profiles are contextualized within a broader competitive analysis that examines product differentiation, service network density, control-system interoperability, and regional certification readiness. Rather than presenting static corporate summaries, the study maps each participant against deployment scenarios, integration complexity thresholds, and total-cost-of-ownership variables that manufacturing decision-makers routinely evaluate.
Industry Dynamics: Regulation, Sustainability, and Macro-Driven Demand Signals
The market environment is being shaped by intersecting regulatory, operational, and macroeconomic forces that directly influence equipment specification, compliance planning, and deployment sequencing. Industry 4.0 integration requirements have elevated the importance of real-time data analytics in servo press control architectures. Traceability mandates in automotive and medical manufacturing increasingly require interoperable communication layers that support seamless data exchange across production equipment, quality management systems, and enterprise resource planning platforms. Compliance with these standards is no longer optional for suppliers targeting regulated end markets.
Servo Press Market
Certification frameworks continue to function as critical market access thresholds. CE certification for servo press systems, originally established as a compliance baseline for European market entry, remains mandatory for operating within EU jurisdictions that enforce energy-efficiency standards and operational safety requirements. Equipment suppliers that have secured and maintained these certifications position themselves with reduced deployment friction in regulated Western European procurement cycles, while manufacturers evaluating new vendor relationships must weigh certification status alongside technical performance and lifecycle support commitments.
Sustainability and energy management considerations are increasingly embedded in equipment selection criteria. Direct-drive servo motor configurations remove traditional flywheel and clutch assemblies, delivering measurable reductions in baseline energy consumption and supporting corporate decarbonization initiatives. This architectural shift aligns capital equipment decisions with broader environmental, social, and governance commitments, particularly in regions where utility cost volatility and carbon reporting obligations are intensifying.
Demand-side expansion is being reinforced by sector-specific adoption curves. Automotive and electric vehicle battery production lines are accelerating investment in servo press technology, driven by requirements for energy-efficient, high-precision forming operations that can accommodate new material configurations and tighter assembly tolerances. The intersection of vehicle electrification, lightweight material adoption, and precision stamping requirements creates a sustained procurement tailwind for digital servo press deployments. At the same time, labor cost dynamics continue to influence operational economics. Programmable motion control reduces dependence on manual intervention for complex forming sequences, enabling more consistent output quality while compressing labor intensity in high-volume stamping environments.
Why This Study Is a Strategic Asset for 2026 Planning
The digital servo press market is not expanding uniformly. Growth is being concentrated in specific application verticals, regional industrial corridors, and control-architecture configurations that align with evolving regulatory expectations and manufacturing performance targets. For executives preparing capital allocation decisions, vendor evaluations, or technology roadmap updates for 2026, fragmented information and generalized industry commentary are insufficient. This study is engineered to replace speculation with structured analysis, enabling teams to evaluate market entry timing, specification priorities, partnership opportunities, and competitive vulnerabilities with greater precision.
The report provides detailed segmentation breakdowns, regional deployment intensity maps, end-use application demand profiles, vendor capability matrices, and forward demand projections that collectively support scenario planning and risk assessment. Readers will find actionable guidance on how control-system interoperability, certification status, service network density, and energy-efficiency architecture influence total cost of ownership across heterogeneous production environments. The accompanying strategic framework enables manufacturing leaders to align equipment selection with operational objectives, sustainability commitments, and compliance timelines, rather than reacting to vendor marketing narratives or isolated procurement benchmarks.
Complete segmentation data, regional revenue distributions, application-specific demand valuations, concentration metrics, and vendor capability comparisons are available in the full Digital Servo Press Market report. We encourage procurement directors, engineering executives, and strategy teams to access the complete intelligence package to support 2026 planning cycles, vendor evaluation matrices, and long-range technology investment decisions.
The transition from conventional forming equipment to digitally integrated servo press architectures is no longer a peripheral innovation pathway. It is a core determinant of production efficiency, compliance readiness, and competitive positioning in precision manufacturing. Organizations that equip their decision-making processes with rigorous, forward-looking market intelligence will be better positioned to navigate supplier selection, integration complexity, and deployment timing with confidence. The detailed analysis, scenario models, and competitive assessments contained in the full study provide the structured foundation required to convert market signals into operational advantage.
For detailed analysis of this topic, please visit the official page: Digital Servo Press Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Barcode Label Printer Market Hits $215M in 2025, Forecast 6.98% CAGR to $344.8M by 2032
By PW Consulting, 2026-09-16
# Navigating the Barcode Label Printer Market: Strategic Priorities for 2026 and Beyond
Executive Overview
The global barcode label printer market stands at a critical inflection point. As enterprises accelerate digital transformation initiatives, the demand for precise, high-volume labeling solutions has evolved from a logistical necessity to a strategic asset. Our latest comprehensive market research provides a detailed roadmap for navigating this landscape through 2032. Based on rigorous analysis of historical performance from 2020 to 2025 and forecast trajectories extending to 2032, this report is designed to equip C-suite executives, supply chain directors, and procurement leaders with the intelligence required to optimize capital allocation and technology stack decisions.
The market has demonstrated consistent growth over the past five years, recovering robustly from supply chain disruptions and expanding into new application verticals. The overarching narrative for 2026 is one of stabilization and technological integration. With the base year established at 2025, our projections indicate a steady climb in revenue, reflecting the ongoing digitization of inventory management, healthcare compliance, and retail operations. Understanding the magnitude of this growth is essential for budgeting and strategic planning in the current fiscal year.
Market Trajectory and Forecast Dynamics
Analyzing the historical data from 2020 through 2025 reveals a pattern of resilience and accelerated adoption. The market valuation has progressed from 163.15 Million USD in 2020 to an estimated 215.0 Million USD in 2025. This five-year growth trajectory sets the foundation for the forecast period covering 2026 to 2032. The Compound Annual Growth Rate (CAGR) during the forecast window is projected at 6.98 percent, signaling sustained demand rather than a temporary spike.
Looking ahead, the revenue projections suggest significant expansion opportunities. Starting from 237.98 Million USD in 2026, the market is expected to reach 344.8 Million USD by 2032. This growth is not uniform across all timeframes; it reflects varying adoption rates of advanced printing technologies and the maturation of regional markets. For decision-makers, this forecast underscores the importance of timing investments. Entering the market too conservatively may result in missed efficiency gains, while overly aggressive expansion without proper technological alignment could lead to stranded assets. The data provided in our full report breaks down these intervals to help stakeholders identify the optimal windows for procurement and infrastructure upgrades.
Segmentation Intelligence and Procurement Strategy
A key value of this research lies in its granular segmentation analysis, which moves beyond top-line numbers to reveal where value is being generated. The market is divided across several critical dimensions: Region, Type, Technology, and Application. While high-level figures provide a broad view, understanding the relative weight of each segment is vital for tailored strategy.
In terms of hardware types, the market distinguishes between Desktop, Industrial, and Mobile printers. Each category serves distinct operational needs, from office-based shipping to heavy-duty warehouse logistics. The revenue distribution across these types indicates where manufacturing focus and consumer demand are converging. Similarly, the technology landscape is split primarily between Thermal Transfer and Direct Thermal solutions. Each technology offers specific advantages regarding durability, cost, and print quality, influencing buyer preference in different sectors. Our report details the revenue splits for these segments to guide technology selection.
Application-wise, the market serves diverse industries including Manufacturing, Retail, and Healthcare. The variance in revenue contribution across these applications highlights which sectors are driving the most significant volume. For instance, heavy industry usage differs vastly from retail point-of-sale requirements. Regions also play a pivotal role, with market activity distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Understanding the regional revenue contributions allows global enterprises to localize their supply chain strategies and anticipate regional regulatory impacts. However, to maintain the integrity of this strategic overview without compromising proprietary data, specific segment percentages and exact regional revenue figures are reserved for the full detailed report. Stakeholders seeking to benchmark their current footprint against these specific splits should refer to the complete segmentation tables provided in the full document.
Worldwide Thermal Printer Market
Competitive Landscape and Innovation Trends
The competitive environment is characterized by a mix of established multinational corporations and specialized regional players. The market concentration is moderate, with the top three companies holding a combined market share of 24.6 percent and the top five reaching 26.2 percent. This fragmentation suggests that while key players dominate, there is ample room for niche innovation and regional customization.
Major incumbents continue to drive innovation through product launches and portfolio expansions. Zebra Technologies Corporation remains a focal point, particularly with their recent focus on industrial, desktop, and mobile printers enhanced with RFID capabilities. In April 2025, Zebra launched a new line tailored for warehouse and healthcare use, featuring faster print speeds and antimicrobial casings. This move signals a shift towards hygiene and connectivity in high-touch environments. Similarly, Honeywell International Inc. has pushed the boundary of portable printing with AI-driven features for real-time data processing, launched in September 2025, targeting industrial and warehouse environments where immediate data validation is critical.
Barcode Label Printer Market
Other significant players are adapting to specific market pressures. DYMO, under Newell Brands, expanded its product line in August 2025 to include eco-friendly label materials, responding to growing demand for sustainable products. This aligns with broader corporate sustainability goals that are becoming mandatory in many procurement contracts. BIXOLON Co., Ltd. showcased its end-to-end retail printing portfolio at the Retail Technology Show 2026 in London, emphasizing the importance of retail-specific solutions in the European market.
The landscape also includes robust offerings from SATO Holdings Corporation and TSC Auto ID Technology Co., Ltd., both focusing on high-speed and cost-effective solutions for harsh logistics conditions. Brother Industries, Ltd. and Seiko Epson Corporation continue to strengthen their positions in POS and shipping applications. Toshiba Tec Corporation, Citizen Systems Japan Co., Ltd., and GoDEX International Co., Ltd. round out the competitive field with specialized high-performance desktop and mobile printers. For a complete comparative analysis of product lines, headquarters, and specific strategic positioning of these eleven key companies, the full report provides detailed company profiles and competitor benchmarking matrices.
External Dynamics and Risk Factors
Strategic planning in 2026 must account for significant external pressures affecting supply chains and compliance. Regulatory changes are reshaping the requirements for barcode labeling. In December 2025, the North American Industry Guidance for Standard Case Code Labeling (Release 3.0) was finalized, providing best practices for GS1-128 barcode compliance in grocery and foodservice sectors. This regulation impacts manufacturers and distributors who must ensure their labeling hardware and software support these new standards to maintain market access.
Simultaneously, the U.S. Drug Supply Chain Security Act (DSCSA) continues to drive the mandatory use of barcode-enabled tracking systems in healthcare and pharmaceutical distribution. This regulatory tailwind ensures steady demand in the healthcare application segment but requires investment in compliant technology.
On the supply side, geopolitical and logistical challenges are influencing hardware costs. Escalating U.S.-China tech trade tensions, including BIS restrictions on semiconductor export controls, have increased material costs for rare earth elements used in barcode printer hardware by 10-15 percent since March 2025. This cost pressure may filter down to end-user pricing or compress margins for manufacturers. Furthermore, the Red Sea shipping crisis since March 2025 has extended transit times by 7-14 days and increased shipping costs by USD 500 to USD 1,500 per container. These disruptions affect component imports for barcode printers, potentially leading to lead time variability for enterprises placing large orders. Our full report includes a risk mitigation section that maps these dynamics against procurement timelines.
Conclusion and Strategic Call to Action
The Barcode Label Printer Market offers substantial growth potential backed by clear technological and regulatory drivers. With a projected market size reaching 344.8 Million USD by 2032 and a healthy CAGR, the sector presents viable opportunities for investment and operational improvement. However, realizing these benefits requires more than general market awareness; it demands precise data on segmentation, competitive positioning, and regional nuances.
This article has outlined the macro trajectory and key strategic themes, but the granularity required for executive decision-making is contained within the full research document. To access the complete breakdown of regional revenue splits, specific technology adoption rates, detailed competitor profiling, and comprehensive risk assessments, we invite you to download the full PW Consulting market research report. Equip your organization with the precise intelligence needed to navigate the complexities of 2026 and secure a competitive advantage in the evolving landscape of automatic identification and data capture.
For detailed analysis of this topic, please visit the official page: Barcode Label Printer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hand Trucks Market Hits USD 1,091M in 2025, Projected 3.85% CAGR Through 2032
By PW Consulting, 2026-09-16
Strategic Intelligence Report: The Hand Trucks Market 2026-2032 Outlook
Executive Overview: Navigating a Maturing Sector
The material handling sector stands at a critical juncture as we move through 2026. While often perceived as a commodity category, the hand trucks market represents a complex interplay of material costs, regulatory shifts, and evolving labor dynamics. For enterprise leaders, supply chain managers, and strategic planners, understanding the trajectory of this market is not merely about procurement—it is about securing operational resilience.
This analysis serves as an introduction to the PW Consulting latest comprehensive study on the Hand Trucks Market. The research is designed to equip decision-makers with the granular intelligence required to navigate the forecast period from 2026 to 2032. By examining historical performance trends and projecting future growth vectors, we provide a roadmap for capitalizing on market opportunities while mitigating exposure to volatile input costs and trade policy changes.
Our methodology combines rigorous primary research with advanced modeling techniques to ensure that the insights provided are actionable. In an environment where margin pressure is high and supply chain disruptions remain a constant threat, access to precise market intelligence is a competitive differentiator.
Market Trajectory and Economic Indicators
The historical data reveals a sector that has demonstrated resilience despite macroeconomic headwinds. Between 2020 and 2025, the global market for hand trucks navigated significant fluctuations in demand and supply chain stability. Starting from a base of approximately 935.5 million USD in 2020, the market exhibited a clear upward trajectory, reaching a valuation of 1091.0 million USD by 2025. This growth underscores the essential nature of manual material handling equipment across various industries.
Looking toward the forecast horizon, the momentum is projected to continue, albeit at a measured pace reflective of a mature industry. The market is anticipated to grow from 1167.27 million USD in 2026 to 1390.0 million USD by 2032. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 3.85 percent over the forecast period. While this growth rate may appear moderate compared to high-tech sectors, it represents substantial volume in absolute terms for manufacturers and investors focused on steady returns and market share consolidation.
It is important for stakeholders to interpret these figures within the context of broader economic conditions. The growth is not uniform across all timelines; there are expected variances as the market adjusts to new manufacturing capacities and shifting demand patterns. Understanding the timing of these peaks and troughs is crucial for capacity planning and inventory management.
Structural Segmentation and Value Chains
A deep dive into the structural composition of the market reveals distinct dynamics across material types, applications, and geographic regions. These segments do not perform in isolation; they are interconnected through supply chains and end-user requirements.
Hand Tools Market
Material Composition and Cost Drivers
The market is primarily divided by the construction material of the equipment. Steel remains a dominant force, reflecting its durability and cost-effectiveness for heavy-duty applications. Aluminum holds a significant position, valued for its lighter weight and corrosion resistance, particularly in scenarios where worker ergonomics and portability are priorities. Additionally, plastic and other composite materials constitute a portion of the market, often utilized for specific lightweight or specialized tasks. The choice of material is increasingly becoming a strategic decision influenced by raw material availability and tariff structures.
Application Verticals
Demand is driven by several key application verticals. Logistics and warehousing continues to be a primary consumer, driven by the need for efficient movement of goods within distribution centers. The retail sector represents another substantial chunk of demand, essential for stocking shelves and managing backroom operations. Furthermore, the industrial and construction sectors maintain consistent requirements for moving heavy equipment and materials on-site. Each vertical has unique specifications regarding load capacity, maneuverability, and durability, influencing the product mix required by manufacturers.
Regional Dynamics
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. North America and Asia Pacific represent significant portions of the global volume, reflecting strong industrial bases and logistics networks in these regions. Europe maintains a steady demand profile supported by established manufacturing and retail infrastructures. Emerging markets in Latin America and the Middle East and Africa offer growth potential, though often at different scales of maturity. Understanding the regional weighting is essential for companies looking to expand their footprint or optimize their supply chain logistics.
Competitive Landscape and Strategic Moves
The competitive environment is characterized by a mix of established manufacturers and specialized providers. Market concentration indicates a moderately fragmented landscape, with the top three players holding a combined share of 25.5 percent and the top five holding 38.2 percent. This structure suggests that while there are dominant players, there is still room for niche providers and regional specialists to thrive.
Key Industry Players
Several companies define the current competitive arena, each bringing distinct strengths to the table.
Hand Trucks Market
- Harper Trucks: Based in Wichita, Kansas, this manufacturer is a pivotal figure in the industry, producing a significant portion of hand trucks sold in the United States. Their focus on heavy-duty hand trucks and appliance dollies positions them as a leader in high-volume utility solutions.
- Magliner: Located in Standish, Michigan, Magliner distinguishes itself through innovation. With over 4,000,000 possible custom builds, they offer convertible designs and innovative configurations that cater to specific user needs, emphasizing flexibility and customization.
- Vestil Manufacturing: Operating out of Angola, Indiana, Vestil boasts a massive manufacturing footprint with over 1,000 product lines and extensive square footage. They are a key supplier of industrial material handling equipment, including hand trucks and carts.
- American Cart and Equipment: Since 1997, this Archbold, Ohio-based producer has focused on heavy-duty hand trucks and multi-mover carts, with a strong emphasis on appliance and specialty carts manufactured in the United States.
- B&P Manufacturing: With facilities in the United States, B&P has been manufacturing hand trucks and material handling equipment since 1943. Their ISO 9001:2015 certification underscores a commitment to quality management and consistent production standards.
- Wesco Industrial Products: Based in North Wales, Pennsylvania, Wesco produces American-made hand trucks, including industrial duty, convertible, aluminum, and stair-climbing models, integrating hand trucks into a broader material handling portfolio.
Recent Strategic Developments
The competitive landscape is dynamic, with recent activity signaling shifts in strategy and capacity. In early 2025, Magliner introduced next-generation convertible hand truck models and new powered stair-climbing units, signaling a move toward enhanced functionality and powered solutions. Later in the year, Harper Trucks expanded its presence with advanced manufacturing technology and new product innovations, reinforcing its commitment to production efficiency.
Moving into 2026, strategic partnerships and capacity expansions have come to the forefront. B&P Manufacturing entered into a partnership to expand distribution and market position, aiming to broaden its reach. Simultaneously, Wesco Industrial Products implemented capacity expansion to increase production of hand trucks and related equipment. Vestil Manufacturing also released new innovative products, including hydraulic skid steer booms and electric tuggers, which complement hand truck-compatible material handling solutions. These moves indicate a sector preparing for increased demand and looking to diversify product offerings.
Regulatory and Macroeconomic Pressures
No strategic analysis is complete without addressing the external forces shaping the market. Regulatory changes and raw material costs are currently significant variables that influence pricing, sourcing, and ultimately, profitability.
Tariffs and Input Costs
A critical factor for manufacturers and buyers alike is the status of raw material tariffs. Effective March 2025, US Section 232 tariffs on aluminum and steel imports increased to 25 percent. This adjustment has direct implications for input costs for hand trucks and material handling equipment. For companies reliant on imported metals, this creates pressure on margins unless mitigated through supply chain adjustments or pricing strategies. Conversely, it may provide a protective advantage for domestic manufacturers who source materials locally, potentially altering the competitive balance between domestic and imported goods.
Trade Policy and Antidumping Duties
Trade policy remains in flux. The International Trade Commission initiated a five-year review on February 2, 2026, to determine the revocation of the antidumping duty order on hand trucks and parts from China. The outcome of this review could significantly impact the flow of imports and the pricing dynamics within the US market. Stakeholders must monitor this development closely, as a revocation could lower costs for imported units, while a continuation would maintain the current protective barrier for domestic producers.
Safety Standards and Compliance
Compliance with safety standards is non-negotiable in industrial environments. ISO 3691-5:2014 provides safety requirements for pedestrian-propelled trucks, including hand trucks. With verification standards updated for industrial use, manufacturers and users must ensure that equipment meets these criteria to avoid liability and ensure worker safety. Adherence to these standards is not just a regulatory requirement but also a market expectation, particularly in large logistics and industrial contracts.
Strategic Implications for 2026 Decision Makers
Synthesizing the market size, competitive actions, and regulatory environment, several strategic imperatives emerge for organizations operating in or utilizing the hand trucks market in 2026.
- Supply Chain Diversification: Given the tariff environment and potential trade policy shifts, relying on a single source for materials or finished goods introduces risk. Diversifying suppliers across regions or investing in domestic manufacturing partnerships can buffer against tariff shocks and supply disruptions.
- Product Mix Optimization: The demand for customization and specialized applications is evident from competitor moves. Companies should evaluate whether their current product portfolios align with the needs of high-growth verticals like logistics and warehousing. Investing in convertible designs or powered accessories could open new revenue streams.
- Cost Management and Pricing Strategy: With input costs fluctuating due to metal tariffs, precise cost modeling is essential. Pricing strategies must account for potential volatility in steel and aluminum markets while remaining competitive. Understanding the regional cost structures can help in negotiating better terms with suppliers.
- Monitoring Regulatory Developments: The ongoing antidumping duty review and safety standard updates require active monitoring. Changes in these areas can alter the competitive landscape overnight. Proactive engagement with regulatory updates allows companies to adjust their sourcing and compliance strategies ahead of competitors.
- Capacity Planning: As competitors like Wesco and Harper Trucks expand capacity, market supply may increase. Understanding the timing of these expansions relative to demand growth helps in planning inventory levels and avoiding oversupply or stockouts.
Conclusion: The Value of Deep Intelligence
The hand trucks market is more than a simple transaction of goods; it is a sector influenced by global trade policies, material science, and industrial demand shifts. The data points from 2020 through the 2032 forecast provide a skeleton of growth, but the flesh and blood of strategy lie in the details. Knowing the aggregate market size is useful, but understanding the specific dynamics of steel versus aluminum demand, the nuances of regional regulatory impacts, and the strategic intent of key competitors is where real value is created.
PW Consulting latest report on the Hand Trucks Market delves into these specifics, offering a level of detail that general market summaries cannot provide. From granular segmentation analysis that respects the confidentiality of specific regional percentages to deep dives into the operational strategies of key players, this research is built for action.
For enterprises aiming to secure their supply chains, optimize procurement costs, or identify new market entries, the margin for error is small. The insights contained within this study are designed to reduce that margin. We invite you to access the full research document to unlock the complete suite of data, forecasts, and strategic recommendations tailored to your specific operational context.
For detailed analysis of this topic, please visit the official page: Hand Trucks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Railway Signaling Market to Hit $243.2M by 2032, 5.6% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Railway Signaling Market: Navigating Growth, Competition, and Digital Transformation Through 2032
Executive Overview: Why 2026 Demands a Renewed Strategic Lens
The global railway signaling sector stands at a critical inflection point. As infrastructure operators modernize aging networks, freight corridors expand capacity, and urban mobility systems demand higher throughput, signaling technology has evolved from a compliance-driven utility into a core enabler of operational efficiency and safety. Our latest market research provides a comprehensive, data-grounded assessment of this landscape, tracing market trajectories from the historical baseline of 2020 through 2025 and projecting forward across a seven-year forecast window ending in 2032. For executives, investors, and technology leaders, the study translates macroeconomic momentum into actionable strategic intelligence tailored to 2026 decision cycles.
Over the past half-decade, the market has consolidated steady growth, reaching a total revenue base of 166.8 million USD in 2025. The trajectory reflects not only incremental capacity additions but also the gradual migration toward digitally integrated control-command architectures. Looking ahead, the forecast period is anchored by a compound annual growth rate of 5.6 percent, a figure that captures sustained modernization spending, regulatory-driven upgrades, and expanding deployment across mainline, urban, and freight applications. Importantly, the projected revenue progression outlines a market that will cross the 170 million USD threshold in 2026 and continue scaling toward materially higher valuation levels by the close of the decade, positioning signaling as a durable, long-cycle investment theme rather than a fleeting capital-expenditure cycle.
Market Trajectory and Structural Dynamics
Understanding where the market is heading requires more than top-line numbers. Our research dissects the momentum behind growth by examining the interplay of technology transitions, procurement models, and regional demand patterns, while deliberately focusing on the strategic implications rather than premature data disclosure. Several structural dynamics shape the outlook for 2026 and beyond:
- Technology migration and interoperability mandates are accelerating investment in communications-based and computer-based train control architectures, as operators seek to reduce headways, improve scheduling precision, and align with harmonized European and national safety frameworks.
- Upgrading legacy wayside infrastructure remains a persistent cost consideration. High upfront implementation expenses for hardware, trackside installations, and integration work continue to influence project pacing, financing structures, and vendor selection, especially in capital-constrained environments.
- Public-sector investment commitments are creating visible demand pull. Government programs focused on signaling modernization are prioritizing safety enhancements, capacity release, and digital readiness, reinforcing a procurement environment where long-term service agreements and phased modernization plans compete with traditional asset replacement models.
- Regulatory harmonization is tightening the specification landscape. Evolving standards and safety-rule assessments for control-command and signaling subsystems are reshaping technical requirements, compliance pathways, and validation cycles, which in turn affect deployment timing and vendor differentiation.
- Operational digitization is blurring traditional boundaries between onboard and wayside systems. As operators pursue end-to-end visibility, predictive maintenance, and data-driven traffic management, signaling increasingly integrates with broader rail digital ecosystems, creating opportunities for solution providers that can bridge signaling, computing, and communications domains.
These dynamics do not operate in isolation. They interact with procurement calendars, fleet renewal cycles, and regional infrastructure priorities, producing a market in which growth is real but unevenly distributed across time horizons and project pipelines. The research unpacks these interactions so that leadership teams can anticipate where demand will crystallize, how procurement criteria are likely to shift, and which capability sets will be rewarded in competitive tenders.
Competitive Landscape: Leaders, Niches, and Strategic Positioning
The signaling market is defined by a concentrated set of established global players alongside specialized and regional participants that compete on technology depth, delivery capability, and local regulatory familiarity. Market concentration remains significant, with the top three participants collectively accounting for a substantial share of revenue and the top five extending that footprint further. This concentration indicates that scale, installed-base leverage, and multi-system expertise continue to matter, but it also leaves room for targeted differentiation through proprietary platforms, regional execution strength, and integration of acquired capabilities.
Several firms illustrate the strategic diversity shaping the competitive field:
- Knorr-Bremse has advanced its signaling presence through KB Signaling, combining conventional CCS platforms with wayside and onboard solutions acquired from Alstom North America. The group has emphasized integration of these assets into its broader portfolio, with a stated focus on market expansion and smart innovation.
- Siemens Mobility continues to push integrated signaling offerings, including its Signaling X suite and ETCS/Level 2 systems. Recent live demonstrations in metro operations have highlighted the practical maturation of its next-generation solution set in real operational environments.
- Alstom remains closely associated with ETCS Level 2 and digital signaling systems, reinforcing its role in mainline modernization programs where European interoperability and legacy migration are central procurement considerations.
- Hitachi Rail has strengthened its digital interlocking, ETCS, and train control capabilities, underlined by a framework agreement for digital signaling technology within a major Swiss railway digitalization program, signaling commitment to large-scale, multi-year deployments.
- Wabtec Corporation has expanded its digital intelligence and wayside signaling footprint through acquisition activity, notably incorporating Frauscher capabilities in train detection and wayside signaling, broadening its ability to serve integrated detection and control requirements.
- Thales Group maintains a strong position in control-command and signaling systems, competing on safety-critical integration, centralized traffic management, and compliance with regional specification frameworks.
- China Railway Signal and Communication Co. Ltd. continues to scale onboard and wayside signaling solutions, with recent financial disclosures and market-access developments highlighting progress in offering EU-compliant onboard solutions that can engage core European markets.
- Nippon Signal, Kyosan Electric, and Toshiba Infrastructure Systems and Solutions represent the depth of Japanese engineering capability in railway signal safety systems, interlocking, electromechanical solutions, and infrastructure signaling and control, each bringing specialized execution strengths in demanding operational contexts.
- L&T Technology Services contributes signaling and control systems solutions with an engineering-services orientation, supporting design, implementation, and system integration requirements across complex projects.
- Progress Rail Services extends signaling capabilities through its ECM/Progress Rail Signaling activities, aligning signaling systems with broader rail service and equipment ecosystems in specific operational segments.
Beyond the incumbents, the competitive map includes active market participation from technology and component specialists that support the signaling value chain. Recent trade show activity and product showcases have featured railway-ready computing platforms, onboard gateways designed for rail environmental and safety compliance, and advanced signaling technologies presented to industry audiences, reflecting a broader ecosystem in which silicon, computing, and communications providers increasingly intersect with traditional signaling vendors. This expanded ecosystem matters because signaling deployments are no longer purely electromechanical or standalone control systems; they depend on ruggedized onboard computing, deterministic communications, cybersecurity postures, and lifecycle software support.
Railway Equipment Market
Competitive positioning is therefore shifting from individual product superiority to integrated value propositions. Operators increasingly evaluate vendors on their ability to deliver interoperable architectures, manage multi-year upgrade roadmaps, support workforce transition, and provide assured aftermarket and service capabilities. In this environment, firms that can combine proven safety certification records with flexible deployment models and digital service offerings are best placed to convert technical capability into long-term contractual relationships.
What the Research Delivers: An Actionable Intelligence Framework
Our Railway Signaling Market research is structured to support concrete management decisions rather than general market awareness. The study moves from macro trajectory to operational detail, providing a decision-ready framework across multiple dimensions of the market. The report introduces:
- A historical and forecast revenue trajectory that contextualizes growth across the base year, the recent historical period, and the full forecast horizon, giving leadership teams a defensible basis for scenario planning, capacity modeling, and long-cycle investment appraisal.
- A technology and application lens that examines how distinct signaling categories and deployment contexts contribute to overall market structure, enabling readers to understand where value creation is concentrated and how demand drivers differ across mainline, urban, and freight operating environments.
- A regional demand map that profiles how market activity is distributed across major geographic zones, highlighting the relative scale of opportunity without reducing the analysis to narrow point estimates, and allowing executives to align go-to-market priorities with regional procurement calendars and infrastructure programs.
- A competitive profiling section that assesses the strategic posture, offering focus, and recent activity of key participants, including integration moves, framework agreements, product demonstrators, and market-access developments, so that readers can benchmark their position and identify where consolidation, partnership, or capability investment may be warranted.
- A market dynamics synthesis that addresses the constraints and accelerants shaping deployment velocity, including upfront implementation economics, government investment signals, regulatory specification trends, and the evolving role of digitalization in signaling architectures.
- Recent development tracking that contextualizes the latest financial releases, exhibition activity, framework contracts, and integration updates within the broader competitive narrative, providing a current-events anchor for strategic planning.
Throughout, the research emphasizes practical interpretation over raw enumeration. Rather than leaving readers with isolated statistics, the study connects market structure to procurement behavior, technology adoption timing, and competitive positioning. The objective is to equip stakeholders with a clear mental model of where the market is headed, what is driving movement, and how to prioritize actions in 2026 and the subsequent planning cycles.
Implications for 2026 Decision-Making
For organizations active in or adjacent to railway signaling, 2026 presents a year in which strategic clarity can convert into durable advantage. The research is designed to support several categories of decision-making:
- Capacity and investment planning: Leadership teams can use the forecast trajectory to align internal resource allocation, R&D emphasis, and regional business development with the periods and segments most likely to generate demand, while avoiding overcommitment to speculative near-term spikes.
- Portfolio and technology prioritization: By understanding which signaling approaches and deployment contexts are gaining traction, technology and product leaders can sharpen development roadmaps, rationalize legacy support commitments, and sequence innovation investments in line with operator migration pathways.
- Competitive positioning and partnership strategy: The profiling of leading and specialized participants helps identify where consolidation, selective acquisition, channel partnerships, or joint delivery models may strengthen market access, particularly in regions or application segments where local execution and compliance familiarity are decisive.
- Risk and constraint management: Recognizing the cost profile of hardware and infrastructure deployment, the influence of financing structures, and the role of safety certification and regulatory alignment allows executives to design more resilient project models and to anticipate objections in procurement processes.
- Market-entry and expansion timing: For firms evaluating new regions or application areas, the regional and application context provided in the study supports more disciplined entry sequencing, reducing the risk of premature commitments and enabling better alignment with public investment cycles and modernization roadmaps.
These implications are not abstract. They affect bidding strategies, workforce planning, supplier selection, system integration partnerships, and service-model design. The research is intended to reduce uncertainty in exactly those areas where ambiguity most often leads to delayed decisions, misallocated capital, or missed windows of competitive opportunity.
Conclusion: Turning Market Intelligence into Execution
The railway signaling market is expanding against a backdrop of modernization urgency, digital integration, and evolving safety and interoperability expectations. The combination of a solid recent historical base, a measured long-term growth rate, and a competitive field that blends global scale with specialized capability creates both opportunity and complexity. Success in 2026 will depend less on generic market awareness than on a precise understanding of where demand is forming, how procurement criteria are changing, and which capabilities will differentiate participating firms over the full forecast horizon.
This research is designed to provide that understanding. It offers a comprehensive view of market size, growth dynamics, competitive positioning, and operational context while preserving the depth of segment-level intelligence for stakeholders who require it for detailed planning. To access the complete dataset, regional and application breakdowns, and full company profiles that underpin the strategic conclusions summarized here, we invite you to explore the full report on our website. In a market where timing, specification alignment, and execution credibility shape outcomes, the additional granularity available in the complete study can make the difference between reactive positioning and deliberate strategic advantage.
Railway Signaling Market
For detailed analysis of this topic, please visit the official page: Railway Signaling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automatic Checkweighers Reach $397.5M in 2025, Projected to Hit $539.0M by 2032
By PW Consulting, 2026-09-16
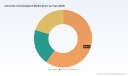
Strategic Imperatives in the Automatic Checkweighers Market: Navigating Growth Through Precision and Compliance
Executive Overview
In the modern manufacturing and packaging landscape, the automatic checkweigher has evolved from a simple weight verification tool into a critical node within quality assurance ecosystems. As regulatory frameworks tighten and consumer expectations for product consistency rise, the strategic deployment of these systems determines operational efficiency and brand integrity. This article examines the trajectory of the global Automatic Checkweighers Market, highlighting why robust intelligence is essential for decision-makers navigating the period from 2026 through 2032.
Understanding the macroeconomic indicators is the first step, but true competitive advantage lies in decoding the underlying drivers. Our latest research publication dissects these complexities to provide a roadmap for capital allocation, technology adoption, and supply chain optimization. The following analysis outlines the market structure, competitive intensity, and regulatory currents that define this sector, underscoring the necessity of detailed data for precise strategic planning.
Market Trajectory and Economic Foundations
The industry has demonstrated resilience and steady expansion over the past half-decade. Historical data indicates a consistent upward trend, with the market valuation rising from approximately 320.0 million USD in 2020 to an estimated 397.5 million USD by 2025. This historical performance sets a robust baseline for the forecast period. Looking forward, the market is projected to grow from 423.84 million USD in 2026 to 539.0 million USD by 2032.
This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 4.5% during the forecast window. While these aggregate figures provide a high-level view of health, they merely scratch the surface of the available intelligence. The value for enterprise strategists lies not in the total number, but in understanding which specific segments are driving this velocity. The report delves into breakouts that reveal where investment yields the highest returns, without exposing the granular percentages publicly. Decision-makers require knowledge of which specific types or applications are outpacing the average growth rate to prioritize their procurement strategies effectively.
Furthermore, the concentration of market power is a critical consideration. With the top three players holding a significant share and the top five commanding an even larger portion of the revenue, the market structure suggests a competitive environment where differentiation is key. Understanding the dominance of these key entities helps purchasers evaluate vendor stability and negotiate terms, while vendors themselves need to know the barriers to entry and the space available for mid-tier players to capture niche opportunities.
Segmentation Dynamics and Strategic Allocation
Effective market strategy requires a nuanced understanding of how demand is distributed across different categories. The landscape is primarily segmented by region, type, and application, each presenting distinct challenges and opportunities for stakeholders. While aggregate revenue is important, the allocation of resources across these dimensions determines the success of implementation.
Regarding regional distribution, North America and Europe have historically maintained substantial presence, reflecting mature industrial bases and stringent regulatory environments. However, the Asia Pacific region presents a compelling growth narrative driven by expanding manufacturing capabilities and increasing adoption of automation technologies. Latin America and the Middle East and Africa, while smaller in current valuation, represent emerging avenues for expansion. Our analysis breaks down the revenue contribution of each geography to identify where infrastructure development is accelerating demand for inline quality control solutions.
In terms of technology type, the market is divided among In-Motion, Static, and Combination systems. In-Motion checkweighers dominate the revenue landscape, catering to high-speed production lines where downtime is costly. Static systems serve specific applications requiring precise stationary weighing, while Combination systems offer integrated solutions that merge checkweighing with metal detection or other inspection technologies. The choice between these types depends heavily on the production speed and the specific quality control requirements of the facility. The report provides detailed assessments of the revenue split between these types to guide equipment selection based on operational throughput needs.
Application-wise, the Food and Beverage sector remains the primary driver of demand, accounting for the largest share of revenue. This is followed by the Pharmaceutical industry, which demands higher accuracy and compliance standards, along with Consumer Products and other sectors. Each application vertical imposes unique requirements on checkweigher specifications, such as hygienic design for food or data integrity for pharma. By analyzing the revenue distribution across these applications, companies can tailor their marketing efforts and product development roadmaps to the most lucrative verticals. For instance, the pharmaceutical segment may offer lower volume but higher margin potential compared to high-volume food processing.
Strategic Segments Covered in the Full Report:
- By Region: Detailed revenue analysis for North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
- By Type: In-depth evaluation of In-Motion, Static, and Combination checkweigher systems.
- By Application: Comprehensive breakdown of Food and Beverage, Pharmaceutical, Consumer Products, and Other sectors.
Competitive Landscape and Key Player Strategies
The market is characterized by the presence of established multinational corporations and specialized manufacturers who compete on precision, integration capabilities, and compliance certifications. The competitive intensity is high, with consolidation trends and strategic partnerships shaping the industry structure. Major players are not only competing on hardware specifications but also on software integration and after-sales support ecosystems.
Automatic Checkweighers Market
Mettler-Toledo International Inc., headquartered in Switzerland, continues to be a dominant force, particularly known for their C-Series and PlusLine dynamic checkweighers. Their strategy heavily emphasizes MID certification and seamless integration with metal detectors and X-ray systems, specifically targeting food packaging quality control. Recent activities, such as their demonstration of C33 PlusLine checkweighers and CM/CX combination systems at Anuga FoodTec 2025, highlight their commitment to enhancing inspection capabilities through integrated solutions.
Ishida Co., Ltd., based in Kyoto, Japan, competes with high-speed multi-lane capabilities through their DACS-GN and DACS-EL series. Their focus on MID approval ensures compliance for the European market, making them a strong candidate for global manufacturers operating under strict regulatory regimes. Similarly, Wipotec-OCS GmbH from Germany offers HC-A and HC-M dynamic checkweighers optimized for high-throughput food and industrial applications. Their March 2026 catalog release emphasizing modular integration for shipping cases underlines their focus on flexibility and logistics efficiency.
Other significant contributors include Anritsu Corporation, whose SSV-h series utilizes force-balance load cells for high accuracy in pharma and food industries, ensuring reliability in sensitive environments. Bizerba SE & Co. KG and Yamato Scale Co., Ltd. provide integrated solutions that blend checkweighing with metal detection and multihead weighing, respectively, catering to snack packaging and high-speed pharmaceutical lines. Minebea Intec GmbH rounds out the European presence with their Essentus performance series, focusing on combination systems for pharma and food safety. Loma Systems, based in the UK, reinforces the importance of compliance with their CW3 dynamic checkweighers, often exhibited alongside metal detection and X-ray solutions at events like Pack Expo East 2026.
Additionally, A&D Company, Limited and Thermo Fisher Scientific Inc. contribute to the ecosystem with high-precision industrial checkweighers and IoT-enabled static and dynamic systems. The presence of Thermo Fisher Scientific highlights a trend toward connectivity and data monitoring in pharmaceutical applications. The report provides a detailed competitive benchmarking of these ten key companies, analyzing their market share, product portfolios, and strategic moves to help stakeholders identify potential partners or competitors.
Regulatory Pressures and Industry Dynamics
Compliance is no longer optional; it is a primary driver of technology adoption. Regulatory mandates such as the Weights and Measures Act and various food safety standards require manufacturers to implement precise weighing solutions to prevent underfilling or overfilling. This regulatory pressure directly fuels demand for MID-certified devices and systems that can log data for audit trails.
Manufacturers are increasingly seeking solutions that offer inline quality control checks while helping them meet compliance requirements without slowing down production lines. For instance, the requirement for Measuring Instruments Directive approval in Europe influences procurement decisions for companies exporting to the EU. The integration of checkweighers with metal detectors and X-ray systems is also becoming standard practice to ensure comprehensive safety compliance, particularly in the food sector.
Recent industry developments underscore this focus on compliance and integration. Mettler-Toledo's emphasis on MID-certified dynamic checkweighers at trade shows demonstrates how vendors are aligning their product launches with regulatory needs. Similarly, Ishida's incorporation of MID approval in their DACS-GN series and Wipotec's support for high-speed applications with precision weighing technology meeting industry standards reflect a broader industry shift. Anritsu's SSV-h series meeting stringent accuracy standards and Loma Systems' design for food safety compliance further illustrate how regulation shapes product specifications. These dynamics suggest that vendors who can certify their equipment and simplify compliance reporting will gain a competitive edge in the coming years.
Strategic Implications for 2026 Decision-Makers
For executives and procurement leaders, the 2026 landscape demands a shift from reactive purchasing to proactive strategic planning. The data indicates that while the market is growing steadily, the value lies in selecting the right technology for the right application. Investing in static systems for high-speed lines may result in bottlenecks, whereas in-motion systems might be overkill for low-volume pharmaceutical batches.
Companies must also consider the total cost of ownership, including integration costs with existing sensors and control systems. The trend toward combination systems suggests that future-proofing facilities with modular equipment that can add metal detection or X-ray capabilities later is a prudent strategy. Furthermore, the geographic shifts in demand imply that supply chain logistics and local service support are critical factors when selecting vendors. Manufacturers operating globally need to ensure their partners have a presence and certification status relevant to their operating regions.
The concentration of the market also implies that negotiating leverage may vary depending on the vendor. Smaller players might offer more customized solutions or faster support, while larger incumbents provide stability and a broader portfolio. Understanding the specific market share and positioning of the top key companies allows businesses to benchmark their current vendors and explore alternatives that might offer better value or technological alignment.
Checkweighers Market
Conclusion and Call to Action
The Automatic Checkweighers Market is poised for steady expansion, driven by regulatory compliance, quality assurance demands, and industrial automation trends. However, navigating this landscape requires more than high-level growth rates. It demands a granular understanding of regional revenue splits, segmentation performance, and competitive maneuvering.
This article has highlighted the key themes and dynamics shaping the industry, but the full strategic picture requires access to comprehensive data. To unlock the complete intelligence necessary for informed decision-making, including detailed segmentation splits, historical data tables, and exhaustive competitor profiling, we invite you to access the full market research report. Equip your organization with the precise data needed to optimize investments and stay ahead in a competitive manufacturing environment.
Access the Full Automatic Checkweighers Market Report Here
For detailed analysis of this topic, please visit the official page: Automatic Checkweighers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LED Street Lighting Market to Hit $13.479B by 2032 with 5.28% CAGR
By PW Consulting, 2026-09-16
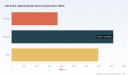
Navigating the Next Wave of Urban Infrastructure: Strategic Intelligence for the Global LED Street Lighting Market
As municipalities worldwide accelerate infrastructure modernization and sustainability mandates tighten, the global LED street lighting market stands at a critical inflection point. For executives, procurement leaders, and urban planners, understanding the trajectory of this market is no longer optional. It is a strategic imperative. PW Consulting is pleased to introduce our latest comprehensive market research, designed to equip decision-makers with the actionable intelligence required to navigate the forecast period from 2026 to 2032 and beyond.
Macro Trajectory and Revenue Context
The market has demonstrated consistent expansion over the past five years. Drawing from historical tracking between 2020 and 2025, revenue has climbed steadily from approximately 7.6 billion to nearly 9.4 billion USD. Looking forward, the forecast period positions annual revenue to surpass the 9.8 billion mark in 2026, with continued upward momentum projected through 2032. The compound annual growth rate for this forecast window is estimated at 5.28 percent, reflecting sustained demand drivers including municipal energy retrofit programs, aging infrastructure replacement cycles, and the integration of smart connected controls. These figures establish a clear baseline for capital allocation, partnership evaluation, and long-term portfolio planning. Rather than treating LED street lighting as a passive commodity replacement, organizations must recognize it as a dynamic market segment where technology refresh, regulatory alignment, and operational efficiency converge.
LED Lighting Market
Rising Input Costs and Material Market Realities
Cost volatility in raw materials introduces a layer of operational complexity that cannot be ignored in 2026 procurement strategies. Prices for essential metals and conductive materials have experienced notable pressure. Silver prices have risen sharply over the trailing twelve months, while copper has crossed significant thresholds in early 2026. These movements directly influence component manufacturing, fixture assembly costs, and supply chain pricing structures. For buyers and vendors alike, understanding how material cost fluctuations cascade through bill-of-materials, margin structures, and tender evaluations is essential. Forward-looking procurement requires scenario planning, multi-sourcing strategies, and a clear understanding of which cost drivers are transitory versus structurally embedded in the market.
Regulatory Momentum and Municipal Energy Mandates
Policy and regulatory frameworks continue to shape deployment velocity. In the United States, federal and state-level energy programs project that LED street lighting installations will dominate the majority of lighting installations by 2035, yielding annual energy savings exceeding 569 terawatt-hours. Such projections reinforce the financial case for early adoption and provide long-term visibility for manufacturers and system integrators. Meanwhile, structural shifts in other regions have created parallel opportunities. In Brazil, the transfer of public street lighting assets to municipalities created strong incentives for energy-efficient LED retrofits, particularly in markets facing elevated electricity costs. With a substantial share of municipalities now directly responsible for energy expenditures, the economic mechanics of lighting upgrades have shifted from centralized utility planning to localized budgetary decision-making. These regulatory transitions alter who controls procurement, how payback periods are evaluated, and which financing models gain traction.
What This Research Delivers: Operational Depth for Decision-Makers
Our market research is structured to move beyond headline figures and deliver operationally relevant intelligence. The publication provides a granular mapping of market segmentation, competitive positioning, and demand drivers across multiple dimensions. Readers will gain clarity on how product architectures are evolving under the broader shift toward LED-dominant installations, including the performance characteristics that municipal buyers now prioritize. The report examines application-specific deployment patterns across roadways, highways, and other municipal and utility contexts, explaining how usage environments influence luminaire specifications, optical requirements, and lifecycle expectations. Regional demand dynamics are contextualized to highlight where infrastructure budgets, electrification goals, and retrofit programs are most concentrated, enabling targeted market entry and expansion strategies. Crucially, the analysis integrates supply-side realities with end-user purchasing behavior, ensuring that revenue forecasts are anchored in market mechanics rather than extrapolated trends.
Competitive Landscape and Strategic Positioning
The market exhibits meaningful concentration among established players, with top-tier firms accounting for a substantial share of total industry revenue. This competitive density rewards companies that can differentiate through performance credentials, control integration, service ecosystems, and regional execution capability. Several core enterprises define the current competitive frontier. Acuity Brands delivers roadway luminaires and integrated smart controls tailored to municipal street and roadway applications. Signify Holding provides connected smart street lighting systems and a broad portfolio of road and street LED luminaires designed for urban infrastructure. Eaton Corporation contributes high-efficacy LED cobrahead and roadway luminaires for municipal street lighting projects, emphasizing reliable illumination performance. Cree Lighting manufactures high-efficiency LED street and roadway fixtures aimed at municipal and transportation applications. LEOTEK specializes in energy-efficient LED street light fixtures and complete citywide upgrade solutions, while Evluma manufactures energy-efficient LED roadway luminaire series for utilities and municipalities. TRT Lighting produces configurable LED street and highway lantern ranges for roadway applications. ZGSM manufactures high-efficacy LED street lights with tool-free maintenance for municipal roads, and Schréder provides full-spectrum outdoor lighting solutions including LED street luminaires for urban infrastructure. Together, these players illustrate a market where hardware performance, smart control interoperability, and municipal service readiness are increasingly decisive.
Recent Product Launches and Innovation Signals
Product introductions in early 2026 underscore the pace of technical refinement and market responsiveness. Evluma launched a new roadway luminaire series featuring modular design, broad lumen packages, high surge protection, and low-glare optics, targeting both utility and municipal applications. ZGSM introduced an updated cobra head LED street light series with high luminous efficacy, asymmetric distribution options, tool-free maintenance, and recognized certification for roads and urban applications. These releases signal several strategic themes. Modularity supports serviceability and component-level upgrades. Thermal and optical refinements address comfort and compliance requirements. Certification and distribution flexibility reduce friction in municipal qualification processes. For competitors and buyers alike, these launches are not isolated events; they are indicators of where performance thresholds are rising and how manufacturers are working to reduce total cost of ownership across installation, operation, and maintenance phases.
Implications for 2026 Corporate Strategy
For organizations operating in or adjacent to this market, the strategic implications are direct and time-sensitive. First, procurement and sourcing strategies must account for material cost volatility, particularly for metals and conductive components that influence fixture economics. Teams should evaluate contract structures, inventory buffers, and supplier diversification to protect margin stability. Second, product and portfolio planning should align with the growing emphasis on efficiency, optical quality, surge resilience, and maintainability. Specifications that once served as differentiators are increasingly becoming baseline expectations in municipal tenders. Third, smart control integration and interoperability are becoming strategic assets. Municipalities and utilities are looking beyond illumination output to network compatibility, remote management, and data-enabled maintenance. Vendors that can credibly support these requirements gain access to broader system-level engagements. Fourth, regional strategy should be informed by asset ownership models and energy cost structures. In markets where municipalities directly control lighting budgets and energy expenditures, the value proposition shifts toward measurable savings, rapid deployment, and lifecycle service support. In regions with centralized utility planning, standardization and compliance credentials may carry greater weight. Finally, competitive positioning requires clarity on whether a company competes on performance leadership, cost efficiency, regional reach, or integrated solutions. The market concentration profile indicates that scale and portfolio breadth remain important, but differentiation in specific application segments and service models can still create defensible positions.
Conclusion: From Observation to Actionable Intelligence
The LED street lighting market is evolving under the combined influence of infrastructure renewal, energy efficiency mandates, material cost dynamics, and rapid product innovation. For leaders tasked with capital planning, product strategy, partnership decisions, and regional expansion, high-level trends are necessary but insufficient. The full 2026 to 2032 forecast, segmentation analysis, competitive profiling, and regulatory context are essential to convert market awareness into executable strategy. PW Consulting's complete market research consolidates these dimensions into a single decision-ready framework, enabling executives to stress-test assumptions, identify priority opportunities, and align investments with the direction of demand. To access the full dataset, detailed segmentation breakdowns, competitive benchmarking, and strategic scenario guidance, we invite you to explore the complete report through our primary research portal. The strategic clarity required for 2026 begins with the right intelligence.
LED Street Lighting Market
For detailed analysis of this topic, please visit the official page: LED Street Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Carburetor Market Hits $415M in 2025, Forecasts 2.8% CAGR to 2032
By PW Consulting, 2026-09-16
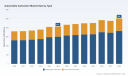
Strategic Intelligence for the Shifting Roads: Navigating the Automobile Carburetor Market in 2026 and Beyond
The global automotive landscape is undergoing a profound transformation, driven by electrification, stringent emission norms, and evolving consumer preferences. Yet, within this rapidly changing environment, the traditional internal combustion engine support systems, particularly the automobile carburetor market, continue to occupy a vital niche. For executives, investors, and strategic planners operating in the mobility and industrial machinery sectors, understanding the trajectory of this market is no longer optional—it is a critical component of risk management and opportunity capture.
PW Consulting is proud to introduce our latest comprehensive market research study focused on the Automobile Carburetor industry. This report is designed not merely as a historical retrospective but as a forward-looking strategic tool tailored for decision-makers navigating the complexities of the 2026 business environment. By synthesizing historical performance data with rigorous demand-side analysis and competitive intelligence, this study provides the clarity needed to allocate capital, refine product portfolios, and anticipate regulatory headwinds.
Market Trajectory and Historical Context
The Automobile Carburetor market has demonstrated resilience over the past half-decade, even as the broader automotive industry pivots toward advanced fuel injection technologies and electric powertrains. Our analysis covers historical performance from 2020 through 2025, providing a robust baseline from which future projections are calibrated. During this historical period, the market experienced steady growth, reflecting sustained demand in specific application segments where carburetor technology remains cost-effective or technically preferred.
Looking ahead, the forecast period spans from 2026 to 2032. Our projections indicate that the market will continue to expand, driven by specific growth corridors in emerging economies and specialized machinery applications. The compounded annual growth rate over this forecast horizon is estimated to be 2.8 percent. While this growth rate may appear modest compared to high-tech sectors, it underscores a stable demand profile within a contracting overall combustion engine market, highlighting the enduring value of legacy technologies in niche applications. Revenue projections are denominated in USD Millions, reflecting a globalized supply chain and diverse pricing structures across regions.
It is crucial for stakeholders to recognize that the market size at the base year, 2025, set the stage for the current fiscal planning cycles. The data suggests that while the broader transition to electrification poses long-term challenges, the immediate term offers opportunities for manufacturers who can optimize production efficiency and target high-margin segments. The detailed breakdown of these revenue streams across different types, applications, and geographic regions is meticulously documented within the full report, allowing clients to pinpoint exactly where value generation is concentrated and where stagnation risks lie.
Segmentation Landscapes and Application Niches
One of the core strengths of this study lies in its granular segmentation analysis. The market is not a monolith; it is composed of distinct product types and application verticals that behave differently under regulatory and economic pressures. The report dissects the market by type, distinguishing between diaphragm and float-feed technologies. Each type serves unique operational requirements, from fuel efficiency and maintenance ease to durability in harsh environments. Understanding the revenue contribution and volume dynamics of each type is essential for OEMs deciding on component sourcing strategies and for aftermarket players determining inventory mix.
Furthermore, the application landscape is thoroughly mapped. The analysis covers automotive usage, motorcycle segments, general machinery, and other specialized applications. Each application category presents a different risk-reward profile. For instance, while the automotive sector faces the most intense pressure from emission regulations, other sectors such as general machinery and specific motorcycle segments may offer longer lifecycles for carburetor integration. The report provides a comparative analysis of these segments, highlighting which areas are expected to maintain stability and which are subject to rapid disruption.
Geographic segmentation is another pillar of this research. The global market is fragmented across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region operates under different regulatory frameworks and economic conditions. Asia Pacific, for example, represents a significant volume center, while mature markets in North America and Europe may offer higher value per unit but face stricter compliance hurdles. The full report details the revenue distribution and growth outlook for each region, enabling clients to prioritize market entry or expansion strategies based on factual data rather than assumptions.
Competitive Landscape and Key Player Dynamics
The competitive environment within the Automobile Carburetor market is characterized by a mix of large integrated suppliers and specialized niche manufacturers. Our research identifies and profiles the key companies shaping the industry, providing a deep dive into their strategic positioning, product offerings, and recent operational moves. Understanding these players is vital for competitors, partners, and investors seeking to benchmark their performance or identify acquisition targets.
Among the leaders is Keihin, headquartered in Tokyo, Japan. As a leading global OEM supplier of carburetors and fuel systems for motorcycles and automobiles, Keihin has successfully navigated corporate restructuring following its integration into Astemo after the 2021 merger involving Honda and Hitachi. This integration allows for greater synergy in supply chain management and technology sharing, bolstering its position in the OEM channel.
Mikuni, also based in Tokyo, stands out as a specialist manufacturer catering to automobiles, commercial vehicles, powersports, and aftermarket applications. Their focus on versatility allows them to capture demand across multiple verticals. Meanwhile, in the United States, Walbro, headquartered in Prescott, Arizona, maintains a strong presence in carburetors for small engines, automotive, and aftermarket segments. Their ability to adapt fitment data and technical specifications ensures continued relevance in replacement markets.
The performance and motorsports segment is heavily influenced by Holley and Edelbrock. Holley, based in Bowling Green, Kentucky, is a well-known supplier of carburetors and related fuel systems for performance automobiles and the aftermarket. Edelbrock, located in Olive Branch, Mississippi, produces performance carburetors specifically tailored for automobiles and motorsports. These companies thrive on innovation in high-performance contexts, often setting trends that trickle down to broader consumer expectations.
Carburetors Market
Recent developments underscore the active nature of this competitive field. In June 2026, Holley released an update to their Performance Icons Sale catalog, introducing new high-performance carburetor and EFI systems for automobiles. Simultaneously, Mikuni announced the introduction of new racing carburetors and fuel pump rebuild kits for automotive and motorcycle applications in the same month. Prior to this, in May 2026, Walbro released updated fitment and technical information for automotive and small engine carburetors. These product launches and catalog updates signal a continued commitment to innovation and market responsiveness despite the broader industry shifts toward electrification.
Regulatory Pressures and Industry Dynamics
No strategic analysis of the automobile carburetor market is complete without addressing the regulatory environment. Emission standards are the single most significant force shaping the future of carburetor technology. Governments worldwide are tightening norms, pushing manufacturers toward advanced fuel injection systems. However, the transition is not instantaneous, and legacy markets remain significant.
In China, the Stage 6 emission standards for light-duty vehicles took effect on July 1, 2023, administered by the Ministry of Ecology and Environment. These standards require compliance for gasoline vehicles, including those utilizing carburetor technology, imposing stricter limits that challenge manufacturers to either innovate or exit specific segments. Similarly, in the United States, the California Air Resources Board issued criteria pollutant standards for the 2026 model year and subsequent years. These regulations mandate strict emission controls applicable to carburetor-equipped legacy vehicles, influencing both production and aftermarket strategies.
Automobile Carburetor Market
In Europe, the European Commission's Euro 7 emission regulations, which began phasing in from 2025, accelerate the shift away from carburetor systems in passenger cars toward advanced fuel injection. This regulatory wave creates a divergent landscape where compliance costs may become prohibitive for certain applications, while other regions with less stringent norms continue to rely on traditional technology. Our report analyzes how these regulatory dynamics interact with market demand, helping clients anticipate compliance costs and adjust their long-term roadmaps accordingly.
Report Structure and Strategic Utility
To ensure maximum utility for our clients, the full Automobile Carburetor Market report is structured into clearly defined sections. These include comprehensive market overviews, segmentation analysis by type, application, and region, detailed competitor profiling, and an examination of market drivers and restraints. The methodology employed combines top-down and bottom-up approaches to ensure accuracy in revenue estimation and growth projection.
The report also includes an analysis of market concentration metrics, providing insight into the competitive intensity of the sector. Understanding the concentration levels helps stakeholders assess barriers to entry and the potential for consolidation. Furthermore, the study offers forecasts that extend through 2032, allowing for long-term strategic planning. Each section is designed to answer specific business questions, from assessing the viability of continuing carburetor production lines to identifying potential partnership opportunities with key market players.
For executives requiring precise figures on regional revenue splits, segment-level growth rates, and specific company market shares, the full report provides the necessary depth. The executive summary available here offers a high-level strategic direction, but the complete document delivers the quantitative intelligence required for operational planning.
Conclusion: Making Informed Decisions in a Transitioning Market
The Automobile Carburetor market exists at the intersection of heritage technology and modern regulatory demands. For industry participants, the goal is not merely to survive this transition but to leverage the remaining opportunities within the combustion ecosystem while preparing for the future. The data indicates that while growth is steady, it is unevenly distributed across segments and regions. Success will depend on precise targeting of high-value niches and agility in responding to regulatory changes.
PW Consulting's Automobile Carburetor Market Report equips you with the knowledge to navigate this complexity. By accessing the full study, you gain access to detailed tables, charts, and data points that remain proprietary to this analysis. We invite you to review the complete findings to empower your strategic decisions for the 2026 fiscal year and beyond. Understanding the nuances of revenue distribution, competitive moves, and regulatory impacts is the first step toward securing a profitable position in this evolving industry.
For detailed analysis of this topic, please visit the official page: Automobile Carburetor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Pressure Transducers Market Hits $360M in 2025, Forecast 6.5% CAGR to $535M by 2032
By PW Consulting, 2026-09-16
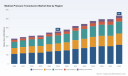
Strategic Imperatives in the Medical Pressure Transducers Market: Navigating Growth and Complexity through 2032
Executive Overview
The global medical pressure transducers market stands at a critical inflection point where clinical necessity, technological evolution, and regulatory scrutiny converge to shape procurement strategies and product development roadmaps. For healthcare manufacturers, distributors, and hospital systems alike, understanding the trajectory of this sector is no longer optional. It is a fundamental component of risk management and revenue optimization. Our latest comprehensive study on the Medical Pressure Transducers Market offers a granular look into the forces driving value creation and erosion across the forecast horizon.
As we move into 2026, decision-makers are faced with a landscape defined by steady expansion but increasingly complex operational challenges. The market has demonstrated resilience over the past five years, recovering from pandemic-related disruptions and stabilizing into a growth pattern driven by aging demographics, the rising prevalence of cardiovascular conditions, and the continued adoption of minimally invasive monitoring technologies. However, raw growth figures tell only half the story. The real strategic value lies in understanding where margin pressure is building, how regulatory shifts are altering time-to-market, and which geographic corridors offer the most sustainable competitive advantage.
This article serves as a strategic preview of our full market intelligence report. It highlights the macroeconomic trends, competitive dynamics, and regulatory undercurrents that define the sector today. We will outline the operational depth contained within the study and explain why access to the complete dataset is essential for formulating robust strategies in 2026 and beyond.
Market Trajectory and Macroeconomic Context
The financial architecture of the medical pressure transducers market reveals a consistent upward trajectory, underpinned by a compound annual growth rate that reflects both recovering demand and structural adoption of advanced monitoring solutions. Between 2020 and 2025, the market expanded from approximately 280 million USD to 360 million USD, signaling a recovery and acceleration phase that has set the stage for the forecast period.
Looking ahead to 2032, the revenue landscape is projected to reach 535 million USD. This growth path is not linear. The forecast period from 2026 to 2032 indicates varying velocities of expansion, with early forecast years showing measured acceleration before gaining momentum in the latter half of the decade. The overall CAGR of 6.5 percent suggests a mature but steadily expanding market, where volume growth is complemented by value-added features and premium product positioning.
It is crucial for stakeholders to recognize that these aggregate numbers mask significant variation across product types, clinical applications, and regional procurement environments. The interplay between established markets with high penetration rates and emerging markets with growing healthcare infrastructure creates a dual-speed environment. Companies that fail to differentiate their go-to-market strategies across these zones risk leaving revenue on the table or overinvesting in low-yield segments. Our full report deconstructs these layers to reveal the specific growth pockets and saturation risks that aggregate data obscures.
Segmentation Dynamics and Demand Drivers
Demand for medical pressure transducers is fundamentally tied to the criticality of hemodynamic monitoring and fluid management in acute care settings. The market is structured around distinct product configurations that serve different clinical workflows, ranging from single-channel solutions for straightforward monitoring to multi-channel systems designed for complex patient management. Each configuration carries different cost structures, manufacturing complexity, and clinical value propositions.
Applications span the spectrum of critical care and perioperative monitoring. Blood pressure monitoring remains a cornerstone application, driven by the ubiquity of invasive arterial pressure measurement in intensive care units and operating rooms. Respiration systems represent another significant demand center, particularly as ventilator management and respiratory support continue to evolve in complexity. Infusion pumps and related fluid delivery systems also rely heavily on accurate pressure sensing to ensure dosing accuracy and patient safety. Beyond these primary uses, specialized applications in surgical and interventional settings contribute to the broader demand picture.
Medical Pressure Transducers Market
From a regional perspective, the market exhibits a diversified footprint. North America continues to hold a substantial share, reflecting high healthcare spending, established critical care infrastructure, and a strong base of domestic manufacturers. Europe maintains a significant presence, though it faces unique regulatory and reimbursement dynamics that influence product adoption cycles. The Asia Pacific region represents a rapidly evolving landscape, where expanding hospital networks, growing medical tourism, and localized manufacturing initiatives are reshaping competitive dynamics. Latin America and the Middle East and Africa, while smaller in absolute terms, present growth opportunities tied to healthcare modernization efforts and increasing access to advanced monitoring technologies.
The strategic implication for 2026 is clear: a one-size-fits-all approach to product launches, pricing, and distribution is increasingly inefficient. Stakeholders must align their portfolios with regional clinical preferences, procurement cycles, and regulatory expectations. The detailed segmentation analysis in our full report provides the specific revenue allocations and growth rates that allow companies to prioritize investments with precision.
Competitive Landscape and Strategic Positioning
The competitive environment in the medical pressure transducers market is characterized by a mix of established multinational players and specialized manufacturers, each carving out niches through product differentiation, clinical evidence, and supply chain reliability. Market concentration metrics indicate that while the top players command meaningful share, the market remains sufficiently fragmented to allow for targeted strategic moves. The combined share of the top three and top five firms underlines the presence of scale advantages, yet also suggests room for agile competitors to capture value in specific applications or regions.
Several key companies define the current competitive benchmark. Edwards Lifesciences Corporation, based in Irvine, California, maintains a prominent position with its TruWave disposable pressure transducers, which are widely recognized for invasive hemodynamic monitoring applications. Their product lineage reflects a focus on integration with broader hemodynamic monitoring ecosystems, appealing to institutions that prioritize workflow compatibility and clinical standardization.
Smiths Medical, headquartered in Minneapolis, Minnesota, offers the TranStar disposable pressure transducer systems, which are designed for hemodynamic monitoring and emphasize reliability in high-acuity settings. Their portfolio underscores the importance of disposable systems in infection control and operational efficiency, a theme that resonates across modern critical care procurement criteria.
ICU Medical, Inc., located in San Clemente, California, provides the Transpac integrated and disposable pressure transducer systems tailored for critical care. Their offering highlights the convergence of sensor accuracy, ease of setup, and compatibility with existing monitoring platforms, factors that are increasingly weighted in hospital buying decisions.
Merit Medical Systems, Inc., based in South Jordan, Utah, contributes the Meritrans pressure transducers and Meritrans DTXPlus disposable systems, expanding the range of options available for procedural and critical care monitoring. Their presence illustrates how diversified medical device companies leverage pressure transducer portfolios to support broader interventional and diagnostic workflows.
Argon Medical Devices, Inc., operating from Plano, Texas, focuses on pressure monitoring lines and transducer kits for interventional procedures. Their specialization points to the growing demand for Procedural-specific monitoring solutions that address the unique requirements of catheterization labs, interventional radiology, and hybrid operating environments.
Competitive dynamics are further shaped by recent developments that signal shifts in accessibility and safety scrutiny. In September 2025, Shanghai Draeger Medical Instrument Co., Ltd. received FDA 510(k) clearance for an IBP transducer adapter cable compatible with multiple major brands, including Argon/BD/Ohmeda, Edwards, and Smiths/TranStar. This clearance highlights a trend toward interoperability and cross-compatibility, which can reduce dependency on single-vendor ecosystems and increase flexibility for hospital procurement teams. At the same time, Edwards Lifesciences' December 2025 adverse event report related to the TruWave disposable pressure transducer, documented in the FDA MAUDE database, serves as a reminder that post-market surveillance and device reliability remain critical differentiators. Incidents of this nature can influence purchasing confidence, quality assurance protocols, and risk management frameworks across the industry.
Regulatory and Operational Pressures Reshaping the Value Chain
Regulatory frameworks are exerting an increasingly pronounced influence on market entry timelines, cost structures, and product lifecycle management. The certification landscape has become more demanding, particularly within the European context. Analysts' insights indicate that the average certification timeline for the EU Medical Device Regulation 2017/745 has expanded from nine months to 18 months between 2021 and 2025. This elongation is accompanied by a cost increase ranging from 35 to 50 percent, placing greater strain on product development budgets and time-to-revenue expectations. For companies planning launches or refreshes in the European market, these shifts necessitate earlier regulatory engagement and more robust documentation strategies.
In parallel, FDA Class II clearance continues to govern the global blood pressure transducers market, ensuring biocompatibility and calibration accuracy. Compliance with these standards is a baseline requirement, but the competitive edge often lies in how manufacturers demonstrate consistency, traceable calibration practices, and post-market performance data. ISO 80601-2-34 governs transducer performance, yet actual calibration practices differ by hospital, manufacturer, and even individual clinician. This variability introduces both a quality assurance challenge and an opportunity for companies that can standardize calibration workflows, provide clear guidance, and reduce ambiguity in clinical settings.
On the supply side, the raw material procurement landscape adds another layer of complexity. The manufacturing of pressure transducers involves the pouring and processing of materials such as silicon, stainless steel, specialty alloys, and plastics sourced from various suppliers. Fluctuations in material availability, pricing, and supplier reliability can affect production continuity and cost margins. Companies that build resilient supplier networks, maintain strategic buffer stocks, and qualify alternative sources are better positioned to navigate supply chain disruptions without compromising delivery commitments.
These operational and regulatory factors combine to create a market environment where success is not solely determined by product performance but also by organizational agility, compliance readiness, and supply chain robustness. The detailed analysis in our report maps these dynamics against market segments and regional profiles, enabling stakeholders to anticipate bottlenecks and align resources accordingly.
What the Full Report Delivers for 2026 Decision-Making
The Medical Pressure Transducers Market study is designed to move beyond surface-level statistics and provide actionable intelligence for strategy formulation, portfolio planning, and competitive positioning. The report integrates demand-side analysis with supply-side dynamics, offering a 360-degree view of the market that supports both short-term tactical adjustments and long-term strategic investments.
Key components of the study include a comprehensive segmentation breakdown that isolates revenue contributions, growth rates, and trajectory patterns across product types, applications, and regions. Rather than presenting static snapshots, the analysis tracks the evolution of each segment over the historical period and projects forward through 2032, highlighting inflection points, saturation risks, and emerging demand pockets. This allows readers to identify which segments offer the most attractive risk-adjusted returns and which require defensive strategies or withdrawal considerations.
The competitive profiling section goes beyond corporate descriptions to assess market positioning, product differentiation, and strategic moves that indicate future intent. By mapping recent regulatory clearances, adverse event disclosures, and compatibility expansions, the report provides early signals of shifting competitive advantages and potential vulnerabilities. This level of detail helps manufacturers refine their value propositions, anticipate competitor responses, and identify partnership or acquisition opportunities that align with market needs.
Additionally, the study embeds regulatory and operational context into the market analysis, ensuring that growth projections are interpreted through the lens of real-world constraints. Certification timelines, cost escalations, calibration variability, and raw material procurement challenges are not treated as peripheral issues; they are integrated into the strategic narrative, showing how they influence product economics, launch sequencing, and regional prioritization. This approach enables readers to stress-test their plans against plausible scenarios and make more informed resource allocation decisions.
Ultimately, the report is structured to answer the questions that matter most to executives, product leaders, and commercial teams: Where is sustainable growth concentrated? Which competitive moves are most likely to disrupt current share distributions? How do regulatory and supply chain dynamics alter the profitability of different segments? And what specific actions should be prioritized in 2026 to capture value while mitigating exposure?
Conclusion: The Case for Comprehensive Market Intelligence
The medical pressure transducers market is entering a phase where growth is achievable but increasingly contingent on strategic precision. Aggregate expansion masks divergent segment trajectories, regional nuances, and shifting competitive threats that can materially affect outcomes if left unaddressed. Companies that rely on high-level summaries or outdated assumptions risk misallocating capital, misreading competitor intent, and underestimating the operational hurdles that shape market access.
Our full Medical Pressure Transducers Market report provides the depth, granularity, and forward-looking context required to navigate this environment with confidence. By revealing the specific revenue distributions, segment growth patterns, and competitive benchmarks that underpin the market's trajectory, the study equips stakeholders with the intelligence needed to optimize product portfolios, refine geographic strategies, and strengthen operational resilience.
Medical Pressure Sensors Market
For organizations preparing for 2026 and the forecast decade ahead, the difference between reactive positioning and proactive leadership lies in the quality of the information guiding critical decisions. Access to the complete market analysis ensures that strategy is built on evidence rather than inference, and that growth opportunities are pursued with clarity, discipline, and a realistic understanding of the landscape. We invite you to explore the full report to unlock the detailed insights that will inform your next strategic moves.
For detailed analysis of this topic, please visit the official page: Medical Pressure Transducers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Micromanipulators Market to Hit $152.8M by 2032 at 9.3% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the Micromanipulators Market: A 2026 Executive Preview
The global landscape for precision instrumentation is undergoing a structural transformation. As life science research accelerates and industrial manufacturing demands tighter tolerances, micromanipulators have evolved from niche laboratory utilities into critical enablers of high-value workflows. Our newly released Micromanipulators Market report provides a comprehensive strategic compass for executives navigating this rapidly expanding sector through 2032.
For decision-makers operating in 2026, understanding the trajectory of this market is not merely an academic exercise. It is a prerequisite for capital allocation, R&D prioritization, supply chain resilience, and competitive positioning. This introductory analysis distills the macro forces shaping the industry, outlines the analytical architecture of our full study, and demonstrates how procurement leaders, investors, and strategic planners can translate market intelligence into actionable advantage.
Market Trajectory and Structural Growth Signals
The micromanipulators market has demonstrated consistent upward momentum over the past half-decade. Valued at approximately 72.97 million USD in 2024 and closing at 81.5 million USD in 2025, the sector has entered a phase of accelerated expansion. Our forecasting model projects the market to reach 88.81 million USD in 2026, scaling steadily toward a projected 152.8 million USD by 2032. This progression reflects a compound annual growth rate of 9.3 percent across the 2026 to 2032 window, signaling sustained demand elasticity rather than short-term cyclical spikes.
Several converging dynamics are underpinning this trajectory. First, R&D investment across neurology, molecular biology, and semiconductor fabrication has intensified the need for high-precision positioning systems capable of sub-micron resolution. Second, the commercialization of assisted reproductive technologies continues to formalize micromanipulation as a standardized clinical workflow. Third, cost-structure innovations are reshaping procurement calculus. Recent sector analysis indicates that a low-cost electric micromanipulator assembled in Japan costs roughly one-fourth the price of a commercial hydraulic unit while requiring no regular maintenance, fundamentally altering the total cost of ownership equation for laboratories and mid-tier manufacturers.
Regulatory frameworks are reinforcing this demand. The International Glossary on Infertility and Fertility Care 2025 explicitly defines micro-operative assisted reproductive techniques utilizing micromanipulation for intracytoplasmic sperm injection and assisted hatching. Such nomenclature standardization is quietly driving procurement standardization across clinical and research institutions, embedding micromanipulators deeper into accredited operational protocols.
Micromanipulators Market
Segment Architecture and Application Intelligence
The market's revenue architecture is anchored by a clear hierarchy of technology types and application domains. Electric micromanipulators command the dominant share of overall revenue, reflecting a broader industry pivot toward automated, programmable positioning systems that integrate seamlessly with digital microscopy and electrophysiology workflows. Hydraulic systems maintain a meaningful presence, particularly in applications demanding exceptional force control and mechanical stability. Manual platforms, while occupying a smaller revenue footprint, continue to serve specialized research environments where tactile precision and low overhead costs remain decisive.
By application, cell micromanipulation represents the core demand engine, capturing the largest portion of total market revenue. This segment spans electrophysiology, patch clamp studies, microinjection, and assisted reproductive workflows, each requiring different combinations of resolution, throughput, and integration complexity. Industrial micromanipulation constitutes a substantial secondary pillar, driven by semiconductor testing, microassembly, and advanced materials characterization. The remaining revenue is distributed across adjacent application spaces that are increasingly intersecting with automated laboratory ecosystems.
Geographically, the market exhibits a multi-polar distribution pattern. North America leads as the largest revenue region, supported by dense concentrations of academic research institutions, biotechnology enterprises, and clinical facilities. Europe holds a strong secondary position, underpinned by robust public research funding and established medical technology manufacturing bases. Asia Pacific represents a fast-growing corridor, where expanding life science infrastructure and regional assembly economics are reshaping both supply and demand dynamics. Latin America and the Middle East and Africa together form an emerging periphery, where adoption is gradually accelerating as research capacity and clinical accessibility improve.
Competitive Landscape and Strategic Positioning
The competitive field is characterized by a moderate concentration structure. The top three players collectively account for approximately 38.5 percent of market revenue, while the top five extend their combined share to roughly 45.2 percent. This architecture suggests a market that is neither fully consolidated nor highly fragmented, creating strategic room for differentiated innovation, regional partnerships, and technology-led disruption.
Sensapex Oy, headquartered in Oulu, Finland, has built its reputation on patented ultraprecise micromanipulators and automated microscope workstations designed for electrophysiology and imaging, with in-house manufacturing reinforcing quality control and supply agility. Sutter Instrument, based in Novato, California, continues to serve the research community with precision manual and motorized micromanipulators optimized for electrophysiology and cell manipulation tasks. Scientifica Ltd, operating from East Sussex, UK, specializes in PatchStar micromanipulators and electromechanical systems tailored for patch clamp and electrophysiology applications, reflecting deep vertical integration into neuroscience workflows.
Siskiyou Corporation, located in Grants Pass, Oregon, delivers high-precision micromanipulators and micropositioners for microscopy and research applications, emphasizing mechanical reliability and modular compatibility. Narishige Group, based in Tokyo, Japan, offers the NTX series of hydraulic and motorized micromanipulators designed for cell manipulation and microinjection, combining established mechanical engineering heritage with evolving automation interfaces. World Precision Instruments, headquartered in Sarasota, Florida, remains a recognized provider of manual micromanipulators for electrode positioning in electrophysiology and neuroscience research. Leica Microsystems, from Wetzlar, Germany, integrates micromanipulator systems into broader microscopy and cell research platforms, leveraging ecosystem synergy rather than standalone instrument positioning. Eppendorf SE, headquartered in Hamburg, Germany, supplies high-precision micromanipulation and injection systems for life science applications, benefiting from strong brand recognition in sample handling and laboratory automation.
Recent corporate activity illustrates how quickly the battlefield is shifting. In mid-2024, Sensapex released Rev 2.0 documentation for its uMp micromanipulation system, including the uMp-TSC2 controller and uMp-3 and uMp-4 micromanipulators, reinforcing its focus on usability and system integration. In late 2024, New Scale Technologies delivered a Modular Insertion System to the Allen Institute for Neural Dynamics, enabling order-taking for next-generation silicon probe micromanipulation, a move that signals growing demand for specialized neural interface instrumentation. Looking into 2026 planning cycles, industry events such as SLAS Europe have already begun featuring sessions on manual micromanipulation in an era of lab automation, underscoring the tension between tactile expertise and automated throughput that will define procurement debates throughout the forecast period.
Operational and Strategic Content of the Full Report
Our complete study goes beyond top-line forecasting to deliver a practical decision-support framework. The report maps the full competitive matrix, profiles the strategic positioning of each major participant, and evaluates how product portfolios, distribution channels, and regional manufacturing footprints intersect with demand growth. It dissects the total cost of ownership differentials across technology types, offering procurement teams a structured approach to evaluating electric, hydraulic, and manual platforms against operational requirements rather than purchase price alone.
The analysis further examines how application-specific requirements create distinct purchasing criteria. Laboratories conducting cell micromanipulation prioritize resolution, repeatability, and integration with imaging or electrophysiology systems. Industrial users weigh throughput, environmental robustness, and compatibility with automated assembly or testing lines. Adjacent application segments introduce additional variables, including regulatory compliance, sterilization protocols, and software interoperability. By isolating these decision drivers, the report enables stakeholders to segment their own demand profiles and align vendor selection accordingly.
Regional expansion pathways are evaluated with attention to infrastructure maturity, research funding cycles, and local assembly economics. The study also addresses supply chain considerations, including component sourcing, service network density, and the implications of maintenance-free electric architectures for long-term operational budgets. Regulatory developments are tracked not as abstract policy commentary but as practical procurement catalysts, showing how evolving clinical definitions and laboratory standards influence purchasing standardization and vendor qualification.
Translating Insight into 2026 Decision Advantage
For executives planning capital deployment in 2026, the strategic implications are clear. First, technology selection should be evaluated through a total lifecycle lens rather than an upfront cost comparison. The growing availability of low-maintenance electric platforms is compressing the long-term cost gap between premium hydraulic systems and economical electric alternatives, particularly for organizations that value operational simplicity and reduced service overhead.
Second, application focus matters. Organizations centered on cell micromanipulation should prioritize vendors with strong integration ecosystems and documented performance in electrophysiology, imaging, and microinjection workflows. Industrial buyers should emphasize positioning repeatability, environmental tolerance, and compatibility with automation pipelines. A generic procurement approach risks overpaying for unnecessary capabilities or underinvesting in critical performance attributes.
Third, geographic strategy should align with regional research intensity and local supply dynamics. North America and Europe remain anchor markets with deep established demand, but Asia Pacific is expanding rapidly as research infrastructure scales and regional assembly options mature. Companies seeking growth should evaluate distribution partnerships, service coverage, and local compliance requirements with the same rigor applied to product development.
Fourth, competitive monitoring should focus on integration velocity and ecosystem breadth. As laboratory automation and neuroscience instrumentation advance, the winners are increasingly those who offer seamless software control, modular upgrade paths, and compatibility with next-generation probes and imaging platforms. Recent product releases and institutional deliveries indicate that the market is moving toward more specialized, workflow-embedded solutions rather than generic positioning tools.
Humanoid Five-finger Manipulators Market
Conclusion and Next Steps
The micromanipulators market is entering a defining growth phase. Steady macroeconomic expansion, application-driven demand intensity, cost-structure innovation, and evolving regulatory clarity are collectively reshaping how institutions evaluate precision positioning equipment. The 9.3 percent compound growth trajectory projected through 2032 reflects a market that is expanding on the strength of real operational needs rather than speculative adoption.
Yet the strategic value of this market cannot be captured through aggregate figures alone. Effective decision-making requires a granular understanding of technology trade-offs, application-specific purchasing criteria, regional expansion dynamics, and the competitive maneuvers that are currently reshaping vendor positioning. Our full Micromanipulators Market report delivers that depth, providing the structured intelligence needed to align procurement, R&D investment, and growth planning with the realities of a rapidly evolving sector.
For leaders who require precise segmentation data, detailed competitor benchmarking, and forward-looking scenario analysis, the complete study offers the unfiltered intelligence necessary to move from awareness to action. The 2026 decision window is open, and the organizations that equip themselves with comprehensive market intelligence will be best positioned to capture value as the micromanipulators market continues its ascent.
For detailed analysis of this topic, please visit the official page: Micromanipulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fatigue Machine Market to Hit USD 731.77M by 2032, 6.2% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Fatigue Machine Market: Navigating Growth and Competition Through 2032
The global landscape for fatigue testing equipment is entering a decisive phase of evolution. As manufacturing sectors face mounting pressure to ensure material durability, lifecycle reliability, and compliance with rigorous safety standards, the demand for precision fatigue machines has become a critical enabler of industrial resilience. PW Consulting’s latest market research on the Fatigue Machine Market offers a comprehensive, data-rich foundation for strategic planning in 2026 and beyond. This report is not merely a retrospective analysis; it is a forward-looking decision-support tool designed to help executives, procurement leaders, engineers, and investors navigate a market undergoing steady expansion, technological refinement, and intensifying competitive dynamics.
The fatigue machine market has demonstrated consistent upward momentum over the past half-decade. Historical valuation data from 2020 through 2025 reveals a clear trajectory of growth, with the market expanding from approximately $360 million to $483 million. This progression reflects sustained capital allocation toward materials testing infrastructure, driven by the needs of automotive validation, aerospace certification, civil engineering assessment, and advanced research applications. Looking ahead, the forecast period from 2026 to 2032 projects continued expansion, with the market anticipated to reach roughly $732 million by the end of the decade. The implied compound annual growth rate of 6.2 percent underscores a market that is not experiencing volatility-driven spikes, but rather a methodological, demand-led expansion rooted in engineering requirements and regulatory expectations. For enterprise decision-makers, this steady growth curve signals a market where long-term capacity planning, technology investment, and supply chain alignment can yield compounding strategic advantages.
Why This Research Matters for 2026 Decision-Making
Entering 2026, organizations operating in or adjacent to the fatigue testing ecosystem face a conjunction of forces that make high-quality market intelligence indispensable. On the demand side, industries are pushing harder against the boundaries of material performance. Lightweight composites, additively manufactured components, and next-generation battery structures are redefining validation protocols. On the supply side, input cost volatility and competitive pricing pressure are constraining margin expansion for equipment manufacturers, placing a premium on scale, integrated supply chains, and differentiated service capabilities. Simultaneously, evolving regulatory and quality standards are steering procurement decisions toward certified, specification-compliant fatigue testing equipment, making compliance architecture a core competitive variable rather than a back-office function.
In this environment, strategic choices made in 2026 will shape competitive positioning for years. Whether a manufacturer is evaluating capacity expansion, a laboratory is planning capital procurement, an automotive or aerospace supplier is defining testing partnerships, or an investor is assessing market entry and consolidation opportunities, the cost of incomplete intelligence is high. The PW Consulting study is structured to reduce that uncertainty. It provides a granular view of market sizing, segmentation behavior, competitive positioning, and the regulatory and technological currents shaping procurement patterns. By aligning these dimensions into a single analytical framework, the report enables leaders to move from reactive market observation to proactive portfolio and investment strategy.
What the Report Delivers: Operational Content and Analytical Depth
This market research is designed for execution, not just awareness. The report systematically unpacks the Fatigue Machine Market across multiple analytical layers, giving readers a clear map of where value is created, where competition is intensifying, and where strategic openings exist. Core components include:
Fatigue Machine Market
- A detailed historical and forecast revenue analysis covering the base year 2025 and extending through the 2026 to 2032 forecast horizon, allowing readers to benchmark current market conditions against projected growth pathways.
- Segmentation analysis that breaks down demand patterns by technology type, application domain, and geographic footprint, helping stakeholders identify which subsegments are accelerating, which are maturing, and where resource allocation should be prioritized.
- Competitive landscape profiling that examines the strategic posture, product capabilities, geographic presence, and recent activity of leading manufacturers, enabling readers to assess relative market strength and potential partnership or competitive threats.
- Market concentration insights that clarify the share structure among top performers, offering perspective on the balance between established scale players and emerging regional contenders.
- Industry dynamics coverage that integrates regulatory developments, standards symposia, product launches, and major test milestones into a cohesive view of the forces shaping purchasing behavior and technology roadmaps.
Each section is built to translate data into action. Rather than presenting isolated figures, the report contextualizes numbers within operational realities: how different frequency ranges align with specific testing requirements, how application segments differ in procurement cycles and specification sensitivity, and how regional demand profiles interact with local manufacturing capacity and certification ecosystems. For teams responsible for market entry, product positioning, pricing strategy, or long-term capacity planning, this structure provides a practical scaffold for decision-making.
Competitive Landscape: Scale, Specialization, and Strategic Moves
The fatigue machine market is characterized by a blend of globally established testing equipment manufacturers and regionally focused producers that compete on specialization, responsiveness, and cost architecture. Market concentration data indicates that the top three players hold approximately 38 percent of total revenue, while the top five account for roughly 50 percent. This distribution suggests a market where leadership is meaningful but not absolute, leaving substantial room for differentiated positioning by mid-tier and regional suppliers. In practical terms, this means competitive advantage often derives from technology focus, application expertise, service networks, and the ability to meet localized compliance requirements rather than from scale alone.
Several companies illustrate the strategic diversity shaping the market. MTS Systems Corporation, based in Eden Prairie, Minnesota, manufactures servohydraulic and electrodynamic fatigue and fracture testing systems for high-cycle, low-cycle, and thermo-mechanical fatigue applications across aerospace, automotive, and civil engineering. Its breadth of application coverage positions it as a comprehensive solutions provider for sectors where multi-axis and multi-environment validation is essential. ADMET, Inc., headquartered in Norwood, Massachusetts, develops expert and modular fatigue testing systems supporting high-cycle and low-cycle testing compliant with ASTM and ISO standards, emphasizing modularity and standards alignment that appeal to laboratories and industrial users seeking configurable setups. ZwickRoell Group, located in Ulm, Germany, offers dynamic fatigue testing machines, vibrophores, and automated systems for materials including metals, composites, and elastomers, with a clear focus on advanced material categories that are increasingly central to electrification and lightweighting strategies.
Instron, also based in Norwood, Massachusetts, provides fully integrated dynamic and fatigue testing systems using servohydraulic, servo-electric, and linear motor technologies for cyclic loading evaluation. Its technology versatility supports a wide range of test configurations, making it a strong reference point for organizations that prioritize integrated hardware and software ecosystems. Shimadzu Corporation, based in Kyoto, Japan, manufactures hydraulic and electromagnetic fatigue testing machines and servopulser systems for durability assessment under cyclic and sudden loads, reflecting a long-standing capability in precision mechanical testing instrumentation. On the regional side, Testron Group in Guangzhou, China, sells servo-hydraulic anchorage and industrial fatigue testing machines with advanced sensors for cyclic stress and vibration measurement, while Laryee Technology Co., Ltd., in Weifang, Shandong, provides computer-controlled servo-hydraulic and electronic fatigue testing machines for dynamic and static universal testing applications. Shanghai Bairoe Test Instrument Co., Ltd., also in Shanghai, manufactures fatigue testing machines including PLW-series systems for tension, compression, and cyclic loading on metals and non-metals. Together, these companies highlight a market where global technology leadership and regional manufacturing agility coexist, and where procurement decisions increasingly weigh both specification compliance and total cost of ownership.
Recent Developments Shaping Market Dynamics
Current market momentum is being reinforced by a series of high-visibility industrial and standards-related events. In December 2025, ASTM International held its Sixth Symposium on Evaluation of Existing and New Sensor Technologies for Fatigue, Fracture, and Mechanical Testing, inviting papers for related events and signaling sustained attention to the sensor and measurement layer that underpins reliable fatigue data. Earlier that year, in November 2025, the 23rd International ASTM/ESIS Symposium on Fatigue and Fracture Mechanics convened with invited presentations, further reinforcing the role of standards bodies in defining best practices and testing rigor. These gatherings matter because they shape the technical expectations that procurement teams ultimately translate into equipment specifications.
On the product and application front, ZwickRoell Group launched a next-generation biaxial testing system in February 2026, featuring enhanced load capacity for composite materials used in electric vehicle batteries. This launch is strategically significant because it aligns equipment capability with one of the fastest-evolving application demands in the market: the validation of battery-adjacent composite structures. In the aerospace domain, General Atomics Aeronautical Systems, Inc. completed full-scale fatigue testing of the MQ-9B Remotely Piloted Aircraft in January 2026, equivalent to 40,000 operating hours. Such milestones demonstrate the high-stakes nature of fatigue validation in certification-critical programs and reinforce the need for robust, traceable testing infrastructure. Meanwhile, MTS Systems Corporation exhibited at the SAE Japan exhibition in Yokohama in May 2025, showcasing materials testing solutions and underscoring the importance of regional engagement in technology demonstration and customer development.
Hardness Testing Machine Market
Market Dynamics: Standards, Cost Pressures, and Procurement Direction
The fatigue machine market does not evolve in a vacuum. Several structural dynamics are shaping how demand forms and how suppliers compete. First, evolving regulatory and quality standards are structuring procurement toward certified, specification-compliant fatigue testing equipment. As organizations face greater scrutiny on material reliability and component lifecycle performance, the compliance credentials of testing systems have become a decisive factor in purchasing decisions. This trend benefits manufacturers that can clearly demonstrate alignment with recognized standards and provide the documentation, calibration support, and validation traceability that regulated industries require.
Second, input cost volatility and competitive pricing pressure are constraining margin expansion for fatigue testing machine manufacturers. In this environment, scale manufacturers with integrated supply chains hold a structural advantage, since they can better absorb cost fluctuations, manage component availability, and maintain consistent delivery performance. For smaller or more fragmented producers, the strategic response often lies in focused application expertise, faster customization cycles, or regional service advantages that justify price differentials through total value rather than unit cost alone.
Third, the technical standards landscape continues to deepen. Guidance such as NASA-HDBK-5026, finalized in August 2024, provides direction for fatigue and fracture control requirements in additive manufactured parts. As additive manufacturing moves from prototyping into production-critical roles, testing protocols for these components are becoming more formalized. This has direct implications for fatigue machine demand, since additively manufactured parts often require specialized evaluation approaches that differ from conventional wrought or machined components. Markets that embrace advanced manufacturing are therefore likely to drive demand for testing systems capable of handling new geometries, material behaviors, and validation regimes.
Strategic Implications for 2026 and Beyond
For organizations planning their next moves, the strategic implications of this market are clear. Growth is projected to be durable rather than speculative, with the market moving from $504.79 million in 2026 toward $731.77 million by 2032. This trajectory rewards players that can align product portfolios with the most resilient demand drivers, particularly where regulatory expectations, advanced material adoption, and high-cycle validation requirements intersect. At the same time, the concentration structure of the market suggests that while leading firms command meaningful share, there is still substantial competitive space for companies that can differentiate through technology specificity, application focus, or regional execution.
Procurement teams should treat compliance and traceability as strategic procurement criteria, not optional features. Manufacturers and service providers should assess where margin pressure is most intense and where integrated supply chain strength can protect profitability. Investors and entry strategists should pay close attention to the application segments and technology types that are expanding fastest, since the aggregate growth figure alone does not reveal where the most attractive risk-adjusted opportunities reside. In all cases, the ability to connect market data to operational choices will separate informed strategy from generic positioning.
Conclusion: Turn Market Intelligence into Strategic Advantage
The Fatigue Machine Market is entering a period in which disciplined analysis can translate directly into competitive advantage. The combination of steady macroeconomic growth, evolving testing requirements, standards-driven procurement, and cost-side pressure on manufacturers creates a landscape where the right strategic moves can compound over time. PW Consulting’s latest market research provides the depth, structure, and forward-looking context needed to make those moves with confidence. To access the complete analysis, including detailed segmentation insights, company-level evaluations, and full forecast data, readers are encouraged to explore the full report through the source page. In a market defined by durability, precision, and long-cycle decision-making, comprehensive intelligence is the foundation of durable strategy.
For detailed analysis of this topic, please visit the official page: Fatigue Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


