



Category: Machinery & Automotive
Etch Equipment Market Analysis: Why 7.6% CAGR and Asia Pacific Dominance Redefine the 2026 to 2032 Outlook
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Semiconductor Etch Equipment Market
The semiconductor etch equipment market has entered a period of accelerated expansion, driven by the relentless demand for advanced logic and memory devices alongside increasingly intricate fabrication requirements. From 2020 through 2025, the global market has demonstrated consistent upward momentum, with revenue reaching an estimated 25.13 billion USD in the base year of 2025. Projections for the forecast period spanning 2026 to 2032 indicate a compound annual growth rate of 7.61 percent, positioning the market to exceed 41 billion USD by 2032. This trajectory reflects more than cyclical recovery; it signals a structural shift in how etching technologies are deployed across advanced packaging, high-bandwidth memory, and next-generation logic node development.
A critical examination of the market landscape reveals an industry at an inflection point. Three core challenges define the current environment. First, the technical demands of atomic-scale precision have outpaced conventional equipment capabilities, forcing manufacturers to rethink plasma control, chamber architectures, and process integration strategies. Second, the concentration of market power among a small group of dominant players leaves limited room for undifferentiated competition, compelling mid-tier and emerging suppliers to identify highly specialized niches or form strategic alliances. Third, geopolitical and regulatory dynamics have introduced profound uncertainty around cross-border equipment flows, particularly for advanced etch tools that intersect with sensitive manufacturing capabilities. Navigating these challenges successfully requires more than operational efficiency; it demands strategic foresight and precise market positioning.
PW Consulting Automotive & Machinery Research Center
Technology Drivers and Innovation Trajectories
The primary engine of market growth lies in the continuous push toward tighter feature sizes, three-dimensional device architectures, and novel materials. Etch systems must now deliver uniform material removal at angstrom-level precision while maintaining high throughput and minimizing defect density. This requirement has accelerated adoption of dry etch platforms, which now represent the overwhelming majority of market revenue due to their flexibility in handling complex conductor and dielectric processes. Advanced plasma control technologies, such as direct-drive systems and atomic layer etch capabilities, are becoming essential for manufacturers targeting cutting-edge memory stacks and gate-all-around transistor structures.
Recent product introductions illustrate this innovation wave. In early 2025, Lam Research Corporation unveiled Akara, a conductor etch tool designed with DirectDrive plasma control technology to enable atomic-scale precision for three-dimensional chipmaking. The launch reflects a broader industry emphasis on achieving process stability at dimensions where conventional capacitively coupled or inductively coupled plasma sources no longer provide sufficient control. At the same time, Tokyo Electron Limited announced plans to construct a new production building in Miyagi to expand its plasma etch systems manufacturing capacity. This investment underscores the strategic priority placed on scaling advanced etch hardware in response to sustained demand from high-performance logic and memory producers.
Collaborative innovation is also reshaping the technology frontier. Later in 2025, Lam Research entered a cross-licensing and collaboration agreement with JSR Corporation and Inpria Corporation to advance dry resist technology for atomic layer etching and deposition. Such partnerships highlight a growing recognition that breakthrough etch performance will increasingly depend on ecosystem-level integration rather than isolated equipment improvements. Partnerships linking equipment suppliers with materials developers and research institutions are likely to become more common as the industry addresses the complexity of next-generation patterning and etching sequences.
Plasma Etch System Market
Policy, Regulation, and Geopolitical Dynamics
Regulatory developments have emerged as a defining force in market behavior. The expansion of export controls and entity list actions has introduced new layers of complexity for equipment suppliers, particularly those with global customer bases. In December 2024, the U.S. Bureau of Industry and Security implemented a series of measures affecting advanced semiconductor manufacturing equipment. These actions included adding multiple categories of equipment, including certain etch tools, to the Commerce Control List, expanding the foreign direct product rule to cover foreign-produced equipment destined for China, and adding numerous entities to the Entity List to restrict access to advanced manufacturing technologies.
These policy shifts are not isolated administrative adjustments; they represent a restructuring of how advanced etch capabilities are distributed across global supply chains. For equipment makers, compliance requirements now influence product design, sales territories, service models, and technology roadmaps. For fab operators, procurement strategies must account for regulatory eligibility, spare parts availability, and the long-term viability of certain supply relationships. The practical effect is a bifurcation in market access, where advanced tools may face heightened scrutiny in specific destinations while demand elsewhere continues to grow unimpeded.
In April 2026, the bipartisan MATCH Act introduced further restrictions by prohibiting country-wide sales of cryogenic etch tools and deep ultraviolet immersion lithography systems to any destination within a country of concern. While the immediate impact centers on a limited set of tool categories, the legislation signals an intensifying policy environment where equipment capabilities are evaluated through national security lenses. Manufacturers operating in or serving markets subject to such rules must anticipate additional review mechanisms, potential licensing delays, and the possibility of further classification updates as technology thresholds evolve.
Dry Etching Equipment Market
Demand-Side Shifts and Supply Chain Realities
The demand landscape for etch equipment is being reshaped by changes in end-market composition. Logic chip production continues to command a larger revenue share than memory, reflecting sustained investment in advanced computing architectures, artificial intelligence accelerators, and custom silicon for data-intensive workloads. At the same time, memory demand remains robust, particularly for high-bandwidth memory and enterprise storage solutions that require sophisticated conductor and dielectric etch sequences. The revenue balance between conductor and dielectric processes illustrates the breadth of etch requirements, as both categories now depend on increasingly refined process control to support three-dimensional stacking, dense interconnect structures, and critical dimension scaling.
Supply chain considerations add another dimension of strategic importance. Equipment capacity expansions by major manufacturers indicate that demand expectations are strong enough to justify capital-intensive increases in production capability. However, the concentration of market share among a small number of leading firms means that supply constraints or capacity bottlenecks can have outsized effects on lead times and deployment schedules. For fabs planning advanced node transitions, securing equipment slots and aligning process qualification timelines has become a competitive necessity rather than a routine procurement step.
Material and process co-optimization further complicates supply dynamics. As etch requirements converge with advanced resist technologies, deposition tools, and metrology systems, the performance of etch equipment is increasingly tied to its compatibility with surrounding process modules. This interdependence encourages integrated procurement strategies and strengthens the value of long-term supplier relationships that can support co-development, joint debugging, and rapid process iteration.
Competitive Landscape and Strategic Positioning
The market structure is characterized by intense concentration, with a small number of companies commanding the majority of revenue. Such concentration typically correlates with high barriers to entry, including the need for deep process expertise, substantial R&D investment, global service infrastructure, and proven reliability in high-volume manufacturing environments. Within this framework, competitive advantage is increasingly defined not simply by scale, but by the ability to deliver differentiated process performance, broaden application coverage, and respond rapidly to evolving customer roadmaps.
Applied Materials, Lam Research, and Tokyo Electron stand out as central forces shaping market direction. Lam Research has pursued a multi-pronged strategy that blends product innovation, capacity expansion, research collaboration, and ecosystem partnerships. Its recent activities range from the Akara launch and the donation of a multi-chamber etch system to UC Berkeley's Marvell Nanofabrication Laboratory, to the cross-licensing agreement on dry resist technology. These moves position Lam at the intersection of advanced process development and future workforce and materials innovation, reinforcing its relevance across both high-volume production and frontier research.
Tokyo Electron's facility expansion in Miyagi signals a commitment to scaling plasma etch systems production, which supports its ability to meet growing demand while maintaining manufacturing quality. Such investments are strategically significant because they expand the company's capacity to serve multiple advanced logic and memory programs simultaneously, reducing the risk of localized supply disruptions and improving responsiveness to changing fab requirements.
Beyond the top-tier incumbents, a broader set of participants competes in specialized segments of the etch equipment market. Companies such as Oxford Instruments, SPTS Technologies, Plasma-Therm, ASML Holding, ULVAC, NAURA Technology Group, Hitachi High-Tech, and SAMCO operate across different technology niches, regional footprints, and application focuses. Oxford Instruments, for example, supplied its PlasmaPro 100 Cobra atomic layer etch system to Rigetti Computing for quantum device fabrication, highlighting how specialized etch capabilities can open pathways into emerging domains where precision and material compatibility are paramount. Such moves illustrate that competitive differentiation often comes from aligning tool capabilities with specific device technologies, advanced packaging formats, or novel material systems rather than competing directly in mainstream high-volume segments.
The competitive trend is therefore one of partial divergence. Leading suppliers continue to strengthen their broad platform positions through sustained R&D and global service reach, while smaller or specialized firms seek advantage through focused technology depth, regional proximity, custom integration, or support for niche application areas. Over time, this structure may encourage selective partnerships, technology licensing, or targeted acquisitions as larger players seek to fill capability gaps and specialized firms seek routes to scale.
Future Trends and Emerging Commercial Opportunities
Looking ahead three to five years, several interconnected trends are likely to shape market behavior and open commercial opportunities. First, atomic-scale and area-selective etch technologies will move from specialized demonstrations to broader production relevance. As device architectures become more three-dimensional and materials more diverse, the ability to etch with high selectivity and minimal damage will be critical for both conductor and dielectric processes. Equipment suppliers and fab operators that invest early in process integration, recipe development, and in-line metrology for these capabilities can capture value through improved yield, faster ramp cycles, and expanded application coverage.
Second, advanced packaging and heterogeneous integration will continue to expand the role of etch equipment beyond traditional front-end logic and memory fabrication. Tools that can handle precision structuring for interposer layers, through-silicon vias, microbumps, and stacked die arrangements will benefit from growing adoption of multi-die and chiplet-based designs. This trend creates opportunities for suppliers that can adapt etch platforms to packaging-intensive workflows and for fabs that can align etch process development with broader packaging roadmaps.
Third, regulatory and geopolitical divergence will encourage the development of regionalized supply strategies and compliance-oriented business models. Equipment suppliers may need to design product portfolios, service networks, and licensing approaches that accommodate different market access rules without sacrificing technological leadership. For customers, this environment increases the importance of supply resilience, long-term service agreements, and engineering support that can sustain operations even when sourcing options shift. Companies that proactively build flexible procurement and deployment strategies will be better positioned to manage compliance uncertainty while maintaining process continuity.
These trends do not come without risk. Technology transitions can face yield challenges, process integration complexity, and cost pressures that delay adoption. Regulatory frameworks may expand further or shift in scope, affecting equipment eligibility and cross-border support models. Capacity investments by leading suppliers may also reshape competitive dynamics, intensifying pressure on mid-tier players that cannot match scale or cannot clearly differentiate their offerings. Anticipating these risks requires scenario planning, close monitoring of policy developments, and a willingness to adjust product, sourcing, and partnership strategies as conditions evolve.
Strategic Considerations for Decision Makers
For semiconductor equipment manufacturers, the current environment rewards disciplined investment in process differentiation and ecosystem alignment. Priorities include advancing plasma control and atomic-scale etch capabilities, expanding production capacity in coordination with demand signals, and developing partnerships that extend technology reach into materials, resist systems, and advanced packaging workflows. Manufacturers should also evaluate how regulatory exposure may affect product design, market access, and service delivery, ensuring that compliance considerations are integrated into product planning rather than treated as an afterthought.
For investors, the market presents a landscape where growth is supported by structural demand but where competitive outcomes will depend heavily on execution, differentiation, and regulatory navigation. Investment evaluation should account for a company's ability to sustain R&D intensity, expand into application areas with durable demand, and manage geopolitical risk without losing technological edge. Visibility into equipment roadmaps, customer qualification pipelines, and regional exposure can help distinguish operators positioned for durable growth from those exposed to commoditization or access constraints.
For fab operators and procurement leaders, the key imperative is to align equipment strategy with long-term process roadmaps while safeguarding supply continuity. This includes mapping etch requirements across conductor, dielectric, logic, and memory workflows, securing early engagement with equipment suppliers for advanced tool evaluations, and building resilience into spare parts, service support, and qualification timelines. Given the concentration of the market and the complexity of advanced process integration, access to timely, granular intelligence can materially improve sourcing decisions, partnership selection, and capacity planning.
As the market continues to evolve, the value of detailed, up-to-date insight will only increase. A comprehensive research report can provide deeper segmentation data, company-level positioning profiles, regional dynamics, and scenario-based guidance tailored to specific strategic questions. Stakeholders seeking to refine equipment selection, assess competitive exposure, or plan investments around advanced etch capabilities may find that a more detailed source of analysis helps translate broad trends into concrete action.
For detailed analysis of this topic, please visit the official page: Semiconductor Etch Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electric Scooters Market: How 9.8% CAGR and Asia Pacific Growth Redefine Strategy
By PW Consulting, 2026-09-21
The Electric Scooters Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The electric scooters market has transitioned from a niche alternative to a structurally embedded component of urban mobility ecosystems. Revenue across the sector expanded from USD 24.32 billion in 2020 to USD 38.23 billion in 2025, with a projected trajectory toward USD 73.5 billion by 2032. This represents a compound annual growth rate of 9.81 percent, signaling consistent momentum rather than cyclical spikes. The growth profile reflects a market that has passed early experimentation and entered a phase where scale, reliability, and regulatory alignment determine commercial viability.
Several developments illustrate this maturation. At CES 2026, Segway-Ninebot and Apollo Scooters each introduced updated e-scooter lineups centered on extended-range battery architectures and enhanced smart connectivity. TVS Motor Company followed in March 2026 with the TVS X 2026 model in India, adding an ABS option and refined powertrain tuning for mainstream commuting. Meanwhile, Navee updated its GT3 Pro and ST3 Pro catalogs in April 2026 with new 48V battery packs and verified 30 to 40 mile range specifications. These releases share a common direction: manufacturers are shifting from feature novelty toward practical durability, standardized electrical systems, and measurable range performance.
Despite clear momentum, the market faces structural headwinds that will shape competitive outcomes over the next several years.
First, trade policy and tariff exposure are reshaping cost assumptions and sourcing strategies. U.S. Customs and Border Protection imposed a 100 percent tariff on electric scooters imported from China effective August 2024, with lithium-ion battery components for EVs subject to 25 percent duties starting in 2026. For companies that rely heavily on Chinese assembly or battery integration, this alters margin expectations and may accelerate regional production shifts, supplier diversification, or product redesigns aimed at tariff optimization.
Second, battery regulation and safety compliance are becoming more prescriptive. The PHMSA lithium battery guide updated in May 2024 extends watt-hour rating marking requirements for lithium-ion batteries over 100 Wh and sets quantity limits when batteries are packed with equipment, with a telephone number phaseout deadline of December 31, 2026. These requirements affect logistics, packaging, and product documentation, particularly for operators managing large fleets or cross-border distribution. Compliance is no longer a back-office task; it directly influences product design, shipment planning, and operational readiness.
Third, the market is navigating the tension between rapid deployment and long-term sustainability obligations. The EU Battery Regulation 2023 mandates a 70 percent battery material recovery rate through hydroelectrically compliant recycling for shared e-scooter fleets. This creates a forward-looking cost and operational consideration for commercial operators and manufacturers that supply fleet units. At the same time, China Customs reported lithium battery exports reached approximately 1.3 billion units in Q1 2026, a 30 percent year-on-year increase, with export value climbing to USD 23.95 billion. The scale of battery supply growth is real, but regulatory and environmental expectations are also intensifying, meaning availability alone does not guarantee compliant or cost-stable deployment.
Taken together, these challenges indicate that market leadership will increasingly depend on regulatory agility, supply chain flexibility, and product designs that can withstand both technical and policy scrutiny.
Key Drivers Shaping the Market
Technology Innovation and Range Performance
Battery and motor refinement remain the most visible drivers of adoption. Recent product cycles emphasize 48V architectures, hub motors with extended-range batteries, and integrated connectivity that supports diagnostics, usage tracking, and fleet management. The practical effect is not simply higher top speed, but improved everyday usability. Commuters and fleet operators increasingly evaluate scooters based on range consistency, charging convenience, and reliability across multiple cycles rather than peak power claims alone.
Electric Motorcycle and Scooter Market
This shift matters commercially because it changes the value proposition from novelty to utility. Products that deliver predictable range and lower maintenance burden are better positioned for personal commuting and commercial deployment alike. In parallel, the emergence of models with swappable batteries, telematics, and AI-optimized performance points toward a broader expectation: electric scooters are being treated as connected mobility assets rather than standalone consumer goods.
Policy and Regulatory Environment
Regulatory dynamics are now a core determinant of where and how electric scooters scale. The combination of import tariffs, battery transport rules, and recycling obligations creates a multi-layered compliance environment. For shared mobility operators, municipal permits, sidewalk and lane usage rules, and fleet caps can accelerate or constrain deployment more immediately than product availability. For manufacturers, differences in safety marking, battery handling rules, and regional certification requirements influence time-to-market and cost structure.
The policy environment also incentivizes certain product strategies. Where recycling and recovery requirements are strict, manufacturers and operators have stronger reasons to design for serviceability, battery replacement, and end-of-life material recovery. Where tariff exposure is high, there is added pressure to evaluate assembly locations, component sourcing, and localized inventory strategies. Policy is no longer a peripheral risk factor; it is becoming part of the product and operating model.
Demand-Side Shifts in Consumer and Enterprise Behavior
Demand is broadening on both the personal and commercial sides, but with different priorities. Personal users increasingly seek lightweight, foldable, or compact designs that fit multimodal commutes, last-mile connections, and limited storage environments. Commercial users, including fleet operators and urban mobility programs, prioritize durability, predictable operating costs, and integration with dispatch or connectivity platforms.
This divergence is important because it creates distinct product and service requirements. A scooter optimized for budget-conscious personal commuting does not automatically fit a shared fleet or municipal program. Conversely, ultra-light fleet units designed for micromobility programs may not meet the range or payload expectations of daily personal transport. The market is therefore moving toward more explicit segmentation in product design, service contracts, and deployment models.
Supply Chain and Cost Structure Evolution
Battery supply dynamics are a major force behind cost and capacity expectations. The Q1 2026 export data from China Customs underscores how central lithium battery availability has become to the broader electric mobility ecosystem. At the same time, the battery component duties scheduled for 2026 and the more prescriptive transport and marking rules indicate that cost advantages from battery sourcing are increasingly tied to compliance and logistics planning, not just unit pricing.
For manufacturers and operators, this means the cost equation is becoming more multidimensional. Raw material access, shipping rules, duty exposure, and recycling obligations all influence total cost of ownership. Companies that can align battery procurement, packaging, certification, and end-of-life planning are better positioned to maintain stable margins as the market scales.
Competitive Landscape and Leading Strategies
The market features a mix of established micromobility brands, regional manufacturers, and shared-mobility operators, each pursuing different strategic positions. The competitive frontier is not defined solely by volume; it is increasingly shaped by product architecture, connectivity, regulatory readiness, and deployment model specialization.
Among hardware-focused manufacturers, several patterns stand out. Segway-Ninebot continues to emphasize commuting and performance-oriented models with hub motors and extended-range batteries, and its recent CES 2026 introductions reflect a focus on updated battery technology and broader mobility integration. NIU International has built its position around lightweight scooters with integrated connectivity and long-range options, targeting urban mobility users who value smart features and portability. Yadea Technology Group extends the conversation beyond compact scooters into electric two-wheeler scooters and motorcycles with advanced battery and motor systems, broadening the addressable use case across personal and commercial applications.
In India, TVS Motor Company, Ather Energy, and Ola Electric illustrate a regional competitive dynamic centered on mainstream commuting, battery and motor refinement, and charging or swapping infrastructure. TVS’s Orbiter and Star Series e-scooters and the TVS X 2026 model emphasize 48V lithium-ion batteries and zero-emission daily commuting. Ather Energy’s Rizta and 450X models combine AI-optimized performance, swappable batteries, and telematics, aligning with last-mile and urban transport needs. Ola Electric’s S1 Pro and S1 X scooters focus on high-efficiency motors and fast-charging infrastructure for personal and fleet applications. Together, these players show how regional leaders can compete on a blend of product performance, ecosystem support, and localized deployment.
In the United States, a different competitive layer is forming around commuter reliability, performance variants, and budget-conscious options. Apollo Scooters’ Go and Go E2+ models emphasize solid tires and extended battery life for North American urban use, while its recent CES 2026 launches extend smart connectivity and improved 48V systems. Gotrax’s G4 Pro and G3 Plus models cater to buyers seeking 350W to 500W motors and foldable designs for lower-cost commuting. Navee, VMAX, InMotion, LexGo, and Kaabo address higher-performance or rugged-use segments with varied combinations of 48V systems, hub motors, dual-motor options, extended-range batteries, and off-road or long-distance capability. This diversification suggests that U.S. demand is not monolithic; it spans practical commuting, performance-oriented transport, and specialized terrain use cases.
Shared mobility operators add another dimension to the competitive landscape. Lime, Bird, Spin, and Veo focus on dockless fleet units, ultra-light program scooters, and custom fleet solutions for urban transportation authorities. Gogoro differentiates through a battery-swapping ecosystem designed for high-volume urban mobility. Their competitive advantage often lies less in vehicle novelty than in operational scale, city partnerships, compliance management, and fleet reliability.
The market is evolving along two complementary paths. One is consolidation and ecosystem building, where leading hardware manufacturers and platform operators strengthen connectivity, service networks, and battery or charging infrastructure. The other is fragmentation by use case, where brands specialize in personal commuting, commercial fleet deployment, performance riding, or municipal programs. New entrants can still gain traction by targeting a specific segment with clear performance, price, or compliance advantages, but they face a higher bar in a market where regulatory exposure, battery logistics, and brand trust increasingly influence purchasing decisions.
Future Trends and Strategic Opportunities
Trend 1: Product Design Will Align More Closely With Compliance and Lifecycle Management
As battery marking, transport, recycling, and tariff rules become more specific, electric scooters will be designed with compliance and serviceability in mind from the outset. This includes battery architectures that simplify replacement, documentation that supports transport requirements, and product strategies that accommodate material recovery expectations. For commercial operators, this trend creates opportunities in lifecycle management services, battery handling partnerships, and fleet designs that lower compliance friction over time.
The strategic implication is that compliance is becoming a competitive parameter. Companies that treat regulatory requirements as integral to product planning can reduce delays, avoid redesign costs, and position themselves more favorably in regulated markets.
Trend 2: Connectivity and Fleet-Ready Features Will Become Standard Rather Than Premium
The repeated emphasis on telematics, smart connectivity, battery diagnostics, and integrated mobility platforms indicates that data-enabled operation is moving toward the mainstream. This benefits shared fleets directly, but it also supports personal-use models by improving maintenance forecasting, range reliability, and user experience. Over the next few years, connectivity is likely to be less of a differentiator and more of a baseline expectation, particularly in commercial and municipal deployments.
Opportunities here include software-enabled services, predictive maintenance, fleet optimization, and integration with broader urban mobility platforms. For manufacturers, the challenge is to build these capabilities without overcomplicating the product or eroding cost competitiveness.
PW Consulting Automotive & Machinery Research Center
Trend 3: Regional Sourcing and Tariff-Aware Product Strategy Will Gain Importance
Tariff changes and battery component duties are likely to encourage more diversified sourcing, regional assembly considerations, and product planning that accounts for duty exposure. This does not necessarily mean a full exit from existing supply chains, but it does suggest greater scrutiny of where value is created and how exposure is managed. Companies that can balance cost efficiency with tariff and logistics resilience will be better positioned to maintain stable pricing and supply continuity.
At the same time, the strong growth in lithium battery exports highlights that supply availability is expanding, even as policy complexity increases. The opportunity lies in aligning procurement, certification, and distribution strategies so that scale benefits are not offset by compliance or duty-related costs.
These trends carry uncertainty. Regulatory timelines can shift, municipal deployment rules can change quickly, and battery supply conditions may vary by region and product category. Still, the direction is clear: the market is moving toward more standardized, compliance-aware, and connected products, with regional strategy playing a larger role in cost and scale planning.
Actionable Guidance for Decision-Makers
For Manufacturers
Design for compliance and serviceability early. Battery marking, transport rules, and recycling expectations are no longer late-stage considerations; they influence packaging, documentation, product architecture, and market access. Building these requirements into the product roadmap can reduce rework and accelerate rollout in regulated markets.
Clarify segmentation strategy. Personal commuting, commercial fleet use, and performance or rugged applications require different engineering priorities, pricing logic, and service models. A clearer segmentation posture helps avoid product overlap and supports stronger positioning in each segment.
Hoverboard Scooters Market
Plan for tariff-aware sourcing and regional flexibility. Evaluate how import duties and battery component obligations affect total cost and supply continuity. Where feasible, diversify sourcing, anticipate documentation needs, and model product strategies that can adapt if trade conditions change.
For Investors
Prioritize companies with clear regulatory readiness and lifecycle planning. In a market where compliance affects logistics, certification, and end-of-life handling, operational discipline can be as important as product features. Look for evidence that battery management, documentation, and recycling or recovery considerations are integrated into the business model.
Distinguish between hardware growth and ecosystem value. Shared mobility operators, battery-swapping providers, and connectivity-focused manufacturers may create value through service scale and deployment partnerships rather than unit volume alone. Investment theses should account for the specific path to profitability in each model.
Monitor regional divergence. Different markets are developing distinct demand profiles, policy environments, and sourcing constraints. Opportunity magnitude and risk vary significantly by region, so broad generalizations can obscure more useful segmentation-level insights.
For Procurement and Fleet Operators
Evaluate total cost of ownership with compliance and maintenance in mind. Purchase decisions should reflect not only sticker price and range claims, but also battery handling requirements, serviceability, documentation burden, and expected recovery or replacement pathways. Fleets that account for these factors early tend to face fewer operational disruptions later.
Match vehicle specifications to deployment reality. Ultra-light fleet units, commuter scooters, and performance-oriented models serve different use cases. Selecting the right specification for the route, user profile, and service model reduces wear, improves utilization, and supports more predictable operating costs.
Build supplier expectations around connectivity and support. Telematics, diagnostics, and service responsiveness can materially affect fleet reliability. Procurement criteria should weigh operational support and data capabilities alongside hardware specifications.
Conclusion
The electric scooters market is entering a phase where growth is increasingly tied to product reliability, regulatory alignment, and operational maturity. Revenue expansion from 2020 through 2025 and the projected trajectory toward 2032 point to sustained demand, but the most valuable opportunities will go to organizations that can navigate battery compliance, tariff exposure, and segmentation-driven product strategy while delivering practical range and connectivity benefits.
For decision-makers seeking deeper segmentation data, regional breakdowns, and customized strategic recommendations, the full PW Consulting research report provides a more detailed view of the market structure and forward scenarios.
For detailed analysis of this topic, please visit the official page: Electric Scooters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Spray Dryer Market 2026: Why 6.51% CAGR and Food & Dairy Applications Reshape Competition
By PW Consulting, 2026-09-21
The Spray Dryer Market at an Inflection Point: Strategic Trends and Commercial Opportunities Through 2032
The global spray dryer market has transitioned from a mature, steady-growth segment into a strategically contested space where capital intensity, regulatory tightening, and end-market demand shifts are reshaping competitive dynamics. Between 2020 and 2025, total market revenue expanded from approximately USD 4.6 billion to USD 6.6 billion, reflecting a compound annual growth rate of roughly 6.5 percent. Forward projections indicate that the segment will approach USD 8.3 billion by the end of the decade and surpass USD 10.2 billion by 2032. This trajectory is not merely a function of incremental capacity additions; it signals a structural revaluation of spray drying as a critical enabling technology across food, pharmaceutical, and specialty chemical production. For executives and investors, the central question is no longer whether demand will grow, but where margin pools will form, which technological pathways will win, and how regulatory and cost pressures will filter the competitive field.
Market Size, Growth Profile, and Structural Constraints
The revenue expansion observed over the past half-decade has been uneven, with a pronounced acceleration in the most recent years followed by a continued upward slope into the forecast window. The 2025 baseline of USD 6.59 billion anchors a forecast period that projects sustained mid-single-digit to high-single-digit growth through 2032. This scale places the market in a position where individual flagship installations can move the needle for equipment vendors, while recurring demand for retrofits, capacity expansions, and process upgrades creates a multi-layered revenue stream. The growth is broad-based across application areas, but the composition matters: food and dairy applications remain the largest revenue pool, pharmaceutical spray drying represents a high-value, compliance-intensive segment, and chemical and specialty applications contribute a smaller but strategically important share tied to ingredient engineering and material science.
Despite the favorable top-line trajectory, the industry faces structural friction that will define investment returns over the next several years. First, spray drying remains an energy-intensive process, and large-scale equipment often carries capital and operating costs that run into multiple millions of dollars. In an environment where industrial energy prices, carbon compliance, and total cost of ownership are scrutinized more closely, buyers are increasingly evaluating not just throughput but lifecycle economics. Second, effective operation demands trained personnel for maintenance, cleaning, and sanitation to preserve product quality and safety. As labor availability and skill constraints tighten in several industrial markets, the operational burden of complex drying lines becomes a hidden cost driver that influences procurement decisions and vendor selection. Third, the market exhibits meaningful concentration, with a small group of established players commanding a substantial share of revenue. This concentration creates both stability and friction: incumbents benefit from installed bases, service relationships, and scale, while newer or smaller entrants face higher barriers to displace them without a clear technology or cost advantage.
Food Dryer Market
Key Challenges and Turning Points
The market is currently navigating three interrelated turning points that will separate resilient operators from those left behind. The first is the growing tension between throughput ambition and sustainability expectations. Buyers are expanding production to capture demand in dairy powders, instant coffee, and emerging plant-based ingredients, yet they are simultaneously pressured to reduce energy intensity, water consumption, and waste. Equipment that cannot demonstrate measurable efficiency gains or that complicates compliance with environmental and quality standards risks becoming a liability rather than an asset. The second turning point is regulatory harmonization and its operational implications. Recent rule changes that align quality management expectations with recognized international standards for medical device and pharmaceutical manufacturing have raised the bar for documentation, validation, and process control. For spray dryer vendors and end-users alike, this means that engineering excellence alone is insufficient; systems must be designed, qualified, and operated within validated design spaces that satisfy increasingly rigorous oversight. The third turning point is the shift from standardized equipment purchases toward integrated, application-specific solutions. End-users are less interested in commoditized drying capacity and more focused on achieving consistent particle morphology, moisture control, and throughput stability tailored to their formulations. This shift rewards vendors who can combine atomization precision, automation, and process analytics into a coherent solution, while penalizing those who compete primarily on baseline specifications.
Key Drivers Shaping the Spray Dryer Market
Technological Innovation and Process Control
Technology differentiation is becoming the primary lever for margin protection and competitive separation. Advanced atomization methods, improved heat recovery, and tighter integration of process analytics are redefining what a spray dryer can deliver beyond simple drying. In pharmaceutical and high-value food applications, particle size distribution, bulk density, and reconstitution behavior are decisive quality attributes, and equipment that can hold these parameters within narrow tolerances commands a premium. The rise of automated control architectures and real-time monitoring is reducing variability and shortening qualification cycles, which matters enormously in regulated environments where design space optimization and process validation are mandatory. Recent equipment activity underscores this direction: a major supplier introduced an advanced pharmaceutical spray dryer to a prominent biologics manufacturer to strengthen product development and manufacturing capabilities, signaling how targeted technology deployment can open high-value account relationships. At the same time, laboratory and pilot-scale installations continue to play a strategic role, with research institutions and advanced materials groups commissioning new drying units to separate solids from liquids or suspensions into powder with greater efficiency and reproducibility. These smaller-scale deployments are not merely academic; they feed the innovation pipeline that later scales into commercial lines, making pilot equipment a leading indicator of where application technology will move next.
Policy, Regulatory Environment, and Quality Expectations
The regulatory backdrop is reshaping procurement criteria and vendor qualification processes. The effective integration of recognized quality management system standards for medical device manufacturers, including spray dryers used in pharmaceutical production, has elevated expectations for documentation, traceability, and validated operating envelopes. In parallel, guidelines emphasizing process validation and design space optimization for pharmaceutical spray drying require vendors and operators to demonstrate that their processes can consistently deliver quality outcomes within defined parameters. These requirements are not isolated compliance exercises; they influence capital planning, installation timelines, and the total cost of ownership. Buyers are increasingly factoring in the cost of qualification, the risk of rework, and the operational burden of maintaining auditable records. For equipment makers, this environment favors organizations that can embed quality-by-design principles into their hardware and software, provide robust validation support, and maintain long-term service relationships that help clients sustain compliance over multi-year lifecycles. The regulatory trend also raises the stakes for cross-border sourcing, as manufacturers evaluate whether equipment and support from different regions can meet the documentation and oversight expectations of the markets they serve.
PW Consulting Automotive & Machinery Research Center
Demand-Side Shifts in Consumer and Enterprise Behavior
Demand is being reshaped by both consumer-facing trends and enterprise formulation strategies. In food and dairy, the continued expansion of shelf-stable powders, instant formats, and functional ingredients sustains core demand, while the emergence of plant-based and alternative protein ingredients adds new complexity to drying requirements. Formulators are seeking powders with specific solubility, dispersibility, and sensory profiles, which pushes equipment selection toward systems that can handle sensitive materials without thermal degradation and that can be cleaned and reconfigured efficiently. In pharmaceuticals, the drive toward more complex biologics, specialized intermediates, and precise delivery forms increases the value of drying processes that preserve activity and deliver repeatable quality. Enterprises are also placing greater emphasis on supply chain resilience and regional production footprints, a shift that encourages capacity additions closer to end markets and favors vendors who can deliver localized engineering support, spare parts availability, and service responsiveness. The combined effect is a demand environment that values reliability, flexibility, and application expertise as much as raw capacity.
Supply Chain, Cost Structure, and Operational Realities
Cost structure is increasingly a strategic variable rather than a background condition. Because large-scale spray drying systems involve significant capital outlay and ongoing energy consumption, buyers are extending their evaluation windows to include installation risk, commissioning complexity, and long-term operating expense. Trained operators and maintenance teams are essential for regular cleaning, sanitation, and performance upkeep, which means labor skill constraints can directly affect availability and throughput. In this context, vendors that offer integrated automation, straightforward cleaning protocols, and predictable maintenance cycles can reduce hidden costs and improve customer economics. The supply side is also influenced by the geography of manufacturing and service networks. Established suppliers with strong regional presence can shorten lead times and improve responsiveness, while emerging manufacturers may compete on price or specialized features but must demonstrate reliability in execution and support to win and retain large accounts. Cost pressure does not necessarily compress the entire market uniformly; instead, it tends to bifurcate purchasing behavior, with some buyers optimizing for upfront price and others prioritizing total lifecycle value and risk reduction.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The market is anchored by a set of established companies that combine engineering heritage, application knowledge, and service infrastructure. A German-based group provides specialized spray drying solutions for dairy, food ingredients, pharmaceutical, and instant coffee production, emphasizing integrated plant designs and process know-how that extend beyond the dryer itself. A major U.S.-headquartered flow control and processing company offers spray dryer systems under a well-recognized brand for food, dairy, and pharmaceutical powders, with a focus on advanced atomization and process technology. A Swiss laboratory technology manufacturer manufactures laboratory and pilot-scale units for research, quality control, and small-scale pharmaceutical and chemical applications, positioning itself at the upstream end of the innovation and validation chain. A German engineering firm supplies customized industrial spray dryers for food, chemical, and starch industries, offering pilot to full-scale units built on decades of experience and a customization-first philosophy. A U.S.-based developer focuses on pulse atomization spray dryers aimed at energy-efficient drying across food, chemical, mineral, and pharmaceutical powders, differentiating through a specific energy-saving technology pathway. A Swiss packaging and processing solutions provider delivers automated spray drying systems for dairy, whey, and plant-based powders using wide-body technology, aligning drying equipment with broader integrated processing lines. A Chinese manufacturer produces milk and food spray dryers with precision engineering and automation tailored to dairy applications, reflecting the growing capability and regional demand base in Asia. A U.S. manufacturer supplies domestically produced spray dryers for starch, food, and industrial powder production, catering to customers that prioritize local engineering and supply chain continuity.
These companies are not competing on a single axis. Incumbents with broad application portfolios leverage installed bases, service networks, and cross-selling into upgrades and retrofits. Technology specialists compete by proving measurable advantages in energy efficiency, particle control, or process robustness. Laboratory and pilot-scale providers maintain a strategic foothold by supporting qualification, method development, and scale-up, which positions them as trusted partners when commercial projects move forward. The differentiation that matters most in the current environment is the ability to reduce variability, accelerate qualification, and support compliance over the life of the equipment, rather than simply offering competitive baseline pricing.
Worldwide Freeze Drier Market
Evolution of Market Structure
The competitive structure is evolving along two parallel tracks: consolidation of advantage among well-positioned incumbents, and selective entry by specialists targeting high-value niches. Concentration in the market remains significant, which means that large accounts often engage with a limited set of trusted suppliers for major capital projects. This dynamic reinforces the importance of reputation, reference installations, and the ability to deliver complex projects on schedule. At the same time, the demand for application-specific solutions and energy-efficient designs creates openings for companies that can demonstrate a clear performance edge or a compelling total cost proposition. Newer entrants and regional manufacturers are most likely to succeed where they can pair technical differentiation with reliable execution and after-sales support, rather than competing solely on hardware price. Over time, the market is likely to see further rationalization, with stronger players capturing share through integrated offerings and service-led relationships, while smaller players either niche down into specific applications or exit segments where scale and compliance costs are prohibitive.
Future Trends and Commercial Implications (2026–2032)
Trend One: Efficiency as a Default Requirement, Not a Bonus Feature
Energy intensity will move from a cost consideration to a design requirement. As buyers confront both operating expense pressure and sustainability expectations, spray drying systems that incorporate efficient heat recovery, optimized atomization, and lower standby losses will gain preference. This trend favors vendors that can quantify efficiency gains in operational terms and integrate those claims into a credible total cost narrative. Commercially, this creates opportunities for retrofits, control upgrades, and selective replacements that improve throughput per unit of energy, particularly in mature dairy and food ingredient facilities where marginal efficiency improvements translate directly into margin. The risk is that efficiency claims become a crowded field; differentiation will depend on verifiable performance data, installation reality, and the ability to maintain efficiency over time rather than only at commissioning.
Trend Two: Compliance-Integrated Equipment and Service Models
Regulatory expectations will continue to pull quality management deeper into equipment selection and operation. As pharmaceutical and related applications require validated design spaces, rigorous documentation, and consistent process control, the economic value of equipment that supports these requirements will rise. Vendors that can provide structured qualification support, auditable configuration management, and long-term service that helps clients sustain compliance will strengthen customer stickiness. This trend also encourages broader service and lifecycle contracts, where revenue is tied not only to hardware sales but to ongoing performance assurance and regulatory readiness. The uncertainty lies in the pace and specifics of regulatory evolution across regions, which can shift qualification burdens and affect project timelines. Companies that maintain regulatory flexibility and invest in documentation and validation capabilities will be better positioned to adapt.
Trend Three: Application-Specific Flexibility and Regional Capacity
Demand will increasingly reward flexibility and regional responsiveness over one-size-fits-all capacity. Formulators in food, dairy, and emerging plant-based segments will require systems that can handle varied materials, support cleaning and changeover, and produce consistent powder characteristics across batches. At the same time, supply chain resilience considerations will encourage capacity additions closer to end markets, particularly where regional production reduces logistics risk and improves service proximity. Commercially, this trend opens opportunities for modular designs, pilot-to-production pathways, and vendors that can deliver localized engineering and maintenance support. The principal risk is that excessive customization can raise cost and complexity; the winning approach will balance flexibility with standardized core architectures that keep qualification and maintenance manageable.
Strategic Actions for Decision Makers
For Manufacturers and Equipment Vendors
Invest in efficiency and compliance as core product attributes. Differentiation based solely on capacity or baseline features is increasingly insufficient; instead, develop demonstrable advantages in energy performance, particle control, automation, and validation support. Build service-led revenue streams that help customers sustain quality and efficiency over the lifecycle of the equipment, because recurring support relationships often determine long-term share more than the initial sale. Where regional demand is expanding, consider localized engineering and spare parts capabilities that reduce lead times and improve customer confidence, while retaining a standardized core platform to control cost and qualification complexity.
For Investors and Strategic Allocators
Focus on the segments and business models where regulatory and efficiency tailwinds concentrate value. Pharmaceutical and high-value food applications offer stronger pricing power for equipment and services that reduce variability and accelerate qualification, while volume-driven food and dairy segments reward efficiency improvements and lifecycle support. Evaluate companies not only by headline revenue but by their ability to win and retain complex accounts, support compliance, and convert installed bases into upgrades and service contracts. Monitor the pace of regulatory alignment and energy economics, as both will influence project timing, procurement criteria, and the relative attractiveness of technology-led versus price-led competition.
For Procurement and Operations Leaders
Extend the evaluation framework beyond purchase price to total lifecycle economics and risk. Include energy consumption, cleaning and sanitation burden, qualification and documentation requirements, spare parts availability, and service responsiveness in the decision process. Where compliance intensity is high, prioritize vendors that can provide structured validation support and predictable operating performance, because the cost of rework, downtime, or audit findings can outweigh marginal hardware savings. Consider phased adoption paths that use pilot or laboratory-scale units to de-risk formulation and process choices before committing to large-scale capital, especially when material sensitivity or particle quality is critical to the final product.
The spray dryer market is entering a period in which technical precision, regulatory readiness, and operating economics will determine competitive outcomes as clearly as capacity expansion ever did. The growth trajectory through 2032 is robust, but the distribution of value will favor organizations that can align equipment performance with the practical realities of energy cost, compliance, labor skill, and application flexibility. For leaders navigating capital allocation, vendor selection, or market entry, the most valuable intelligence is granular: segment-level demand shifts, technology adoption curves, regional service dynamics, and the evolving qualification burden in regulated applications. Detailed research that breaks down these dimensions by application, equipment type, and region can clarify where to commit capital, which vendors to qualify, and how to sequence investments for the next cycle of demand.
For detailed analysis of this topic, please visit the official page: Spray Dryer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Educational Toys Market: Why 8.47% CAGR and STEM Demand Redefine Growth Strategy
By PW Consulting, 2026-09-21
Navigating the Educational Toys Market: Strategic Trends and Opportunities Through 2032
The educational toys market has transitioned from a niche segment within the broader play industry to a strategic battleground where learning outcomes, developmental science, and consumer purchasing behavior intersect. Market sizing data places the sector at approximately 24.85 billion USD in 2024, reaching an estimated 27.24 billion USD in 2025, with a projected trajectory toward 48.23 billion USD by 2032. The compound annual growth rate across the 2026–2032 forecast window sits at 8.47 percent, signaling a steady but accelerating expansion that outpaces many traditional toy categories. This growth is not merely a function of population expansion; it reflects a structural shift in how parents, educators, and institutions define the value of play. Toys are increasingly evaluated through the lens of skill development, cognitive engagement, and alignment with early learning frameworks rather than pure entertainment appeal. For commercial players, this reframing creates both opportunity and complexity, as the market rewards differentiation and penalizes commoditization.
Several structural inflection points are reshaping how the educational toys sector evolves. First, the convergence of digital interactivity and tactile play has blurred category boundaries. Products that once fell neatly into arts, games, or motor skills categories now routinely blend physical manipulation with screen-informed feedback or app-supported scaffolding. This hybridization challenges traditional product segmentation and forces companies to reconsider how they position, bundle, and distribute offerings. Second, regulatory tightening around safety and traceability is introducing new compliance costs and design constraints. Rules targeting material hazards, electronic component certifications, and digital product documentation are reshaping development timelines and increasing the cost of non-compliance. Third, the market is maturing in a way that makes pure price competition less viable for long-term value creation. Retail channels and procurement teams are paying closer attention to learning efficacy, developmental appropriateness, and brand reputation, which elevates the importance of credible educational positioning over generic toy attributes.
Key Drivers Shaping Market Direction
Technology Innovation and the Hybrid Play Opportunity
Technology remains one of the most decisive forces shaping the educational toys landscape. Advances in low-cost sensors, durable electronic components, and interactive software have enabled manufacturers to embed guided learning mechanics into physical products without sacrificing the hands-on engagement that defines high-quality play. The result is a growing class of products that combine construction, movement, music, or puzzle-solving with feedback loops that adapt to a child's pace or learning goals. Recent product activity illustrates this direction. In January 2026, LEGO Education launched new STEM sets for children aged seven and above designed to encourage curiosity, experimentation, and scientific discovery. Earlier, in October 2025, STEMPlay Labs introduced Wonder Briks and PictoMath, patent-pending construction bricks and math tools aimed at embedding STEM learning into tactile play. May 2025 saw LeapFrog showcase updated educational concepts at Toy Fair, including the Strum & Count Wooden Guitar, signaling renewed interest in combining music and early numeracy through physical interaction. More recently, in May 2026, Smart Kids Planet expanded its age-specific STEM and educational lines for children ages 1 through 13, reflecting a broader industry push to align product complexity with developmental stages. These moves point toward a market where interactivity and educational scaffolding are increasingly expected, not optional.
Regulatory and Compliance Shifts as Strategic Factors
Regulatory change is no longer a back-office concern for educational toy companies; it is a strategic variable affecting product roadmaps, sourcing decisions, and market entry timing. In December 2025, the U.S. Consumer Product Safety Commission published its final rule on the Safety Standard for Toys, with specific requirements for water beads, effective March 12, 2026. The rule codifies requirements directly into 16 CFR Part 1250 rather than amending ASTM F963, creating a more prescriptive compliance pathway. Around the same time, the European Union published Toy Safety Regulation 2025/2509 on December 12, 2025, entering into force on January 1, 2026 and applying fully on August 1, 2030. Notably, the new EU framework introduces a digital product passport requirement for all toys, enhancing traceability and compliance documentation across the product lifecycle. These developments matter commercially because they raise the bar for product documentation, material disclosure, and hazard testing, especially for electronics, small components, and age-differentiated lines. Companies that treat compliance as a design input rather than a late-stage checkpoint are better positioned to reduce rework, protect brand reputation, and avoid recalls or enforcement actions.
Demand-Side Shifts in Parent and Educator Expectations
Consumer behavior is evolving in ways that increase the value of products perceived as developmentally useful. Parents and caregivers are more aware of early cognitive, motor, and social-emotional milestones, and they often evaluate toys as tools that support those outcomes. At the same time, educators and institutional buyers continue to look for resources that complement classroom objectives, especially in science, mathematics, and problem-solving. This dual pull has expanded the relevance of products that bridge home play and structured learning. It also raises expectations for age differentiation, clear instructional support, and durable design. Demand is less about novelty alone and more about sustained engagement that can justify repeated use and recommendation within parent networks, schools, and care settings. For manufacturers, this means that educational credibility, not just packaging claims, increasingly influences purchase decisions and repurchase behavior.
Supply Chain and Cost Structure Pressures
Cost dynamics continue to shape commercial strategy, particularly for products that combine electronics, plastics, wood, and packaging. Material price variability, component sourcing, and logistics overhead affect margin resilience, especially for companies managing broad SKU portfolios or launching multiple age-specific variants. At the same time, regulatory requirements can increase testing, documentation, and quality assurance expenses. The net effect is that cost efficiency must be pursued without eroding the tactile and learning qualities that distinguish educational toys from generic alternatives. Companies that standardize platforms, modularize features, or streamline compliance documentation can protect margins while still offering differentiated products. This is especially relevant for category leaders with global footprints, where scale advantages must be paired with disciplined product architecture to avoid complexity-driven cost creep.
PW Consulting Automotive & Machinery Research Center
Competitive Landscape and Differentiating Playbooks
The competitive field in educational toys is broad and varied, including large multinational toy companies, electronics specialists, construction-focused brands, and niche learning tool providers. Several established players define much of the category's direction through scale, brand recognition, and educational positioning. Mattel continues to offer a wide range of educational toys including construction sets, STEM learning products, and interactive play items, leveraging broad brand reach and distribution. LEGO System A/S and The LEGO Group remain closely associated with construction-based educational toys and STEM sets designed for scientific discovery and creativity, with products spanning early builders and older age groups. Hasbro contributes educational games, role-playing sets, and STEM-oriented toys for skill development, often bridging play patterns with learning outcomes. VTech manufactures electronic learning toys, interactive tablets, and educational software for early childhood development, while LeapFrog focuses on interactive electronic learning toys and books that combine technology with early education. Ravensburger offers wooden puzzles, board games, and STEM building sets for cognitive development, and Melissa & Doug specializes in wooden educational toys, puzzles, and open-ended play sets for preschoolers. Tomy develops educational construction toys, robotics, and STEM learning products, while Spin Master provides STEM and interactive educational toys, including licensed educational lines. MindWare emphasizes hands-on learning tools and manipulatives for science, math, and critical thinking. JAKKS Pacific manufactures educational electronic toys and interactive STEM products, and Osmo offers interactive tablet-based educational games and learning kits for ages 3 through 11.
These companies are not competing on the same dimension. Some win through brand equity, platform scale, and retail presence. Others differentiate through age-specific developmental framing, hybrid digital-physical experiences, or specialized learning content. The strategic advantage increasingly belongs to players that can connect product design to clear developmental outcomes while maintaining manufacturing discipline and compliance readiness. Recent activity shows how this differentiation is emerging in practice. The January 2026 STEM sets from LEGO Education target scientific curiosity for older children, while the 2026 expansion by Smart Kids Planet shows a deliberate push to cover ages 1 through 13 with age-appropriate STEM and educational lines. Meanwhile, the March 2026 recall by ZMC Group involving multiple light-up toys due to battery ingestion hazards serves as a reminder that safety failures can quickly undermine brand trust and commercial momentum. In a market where confidence in educational claims and product safety both matter, reputation management is inseparable from product strategy.
Educational Furniture Market
The structure of the competitive field appears to be moving along two simultaneous paths. On one hand, consolidation pressure exists where scale players can absorb compliance costs, extend distribution, and cross-sell across categories. On the other hand, fragmentation remains viable for specialists offering targeted age ranges, pedagogical framing, or unique material and play experiences. New entrants and smaller innovators are actively exploring patent-protected mechanisms, tablet-integrated kits, and construction-based math and science tools, suggesting that innovation is not confined to the largest players. For commercial leaders, the key strategic question is whether to compete through breadth and distribution, through deep category specialization, or through hybrid design that combines tactile play with guided learning features. Each path carries different margin profiles, compliance burdens, and go-to-market requirements.
Forward-Looking Trends and Commercial Implications
Looking across current market dynamics and recent product and regulatory activity, a few trends are likely to define the next three to five years. First, hybrid learning play will continue to expand as a mainstream expectation. Products that integrate construction, puzzle-solving, motor skill development, or musical interaction with structured learning feedback will be better positioned to capture demand from both home and school-adjacent buyers. The commercial opportunity lies in designing modular learning experiences that can scale across age groups without becoming overly complex or costly to manufacture and document.
Second, age-tiered product architecture will become more important as parents and educators seek developmentally appropriate options. The move toward lines that span early childhood through pre-teen years, as reflected in recent expansions, indicates that buyers value progression paths rather than one-off products. Companies that can map product complexity, safety requirements, and learning objectives to clear age brackets are likely to gain shelf and channel relevance. The risk is portfolio bloat: too many overlapping SKUs can dilute focus, increase compliance burden, and complicate inventory management.
Third, compliance and traceability will increasingly shape competitive readiness. The digital product passport direction in the EU and the tighter U.S. rules on specific hazards demonstrate that documentation and material control are becoming part of product competitiveness. Firms that invest early in traceability systems, standardized testing protocols, and clear hazard controls will have stronger launch velocity and lower exposure to enforcement or recall risk. The uncertainty here lies in how quickly full compliance timelines are enforced across regions and how retailers and procurement teams integrate these requirements into vendor evaluation.
Strategic Recommendations for Decision Makers
For manufacturers, the priority is to treat educational value and compliance as integrated design constraints rather than separate workstreams. Build product platforms that can support multiple learning objectives and age ranges without inflating SKU complexity. Where electronics or small components are involved, design hazard controls and documentation into the development process from the outset. Consider whether the brand should compete through breadth, specialized age segments, or hybrid interactive play, and ensure that product architecture, sourcing, and distribution are aligned with that choice.
For investors, the market's 8.47 percent CAGR and projected scale expansion toward the end of the decade suggest durable growth, but value capture will depend on execution quality. The strongest opportunities are likely in companies that can demonstrate clear developmental positioning, disciplined compliance readiness, and efficient product platforms. Due diligence should evaluate not only revenue momentum but also portfolio complexity, regulation exposure, safety track record, and the credibility of educational claims. Companies with repeated safety or compliance issues may face disproportionate reputational and commercial costs in a market where trust is a differentiating asset.
Education Software Market
For procurement teams and retail buyers, the emphasis should be on differentiating educational toys through learning support, age appropriateness, and safety documentation rather than price alone. Products that offer clear developmental progression and dependable compliance records are better suited to long-term shelf performance and parent trust. Evaluate supplier capabilities for traceability, testing, and post-launch support, since these factors increasingly influence channel and consumer confidence. Align category decisions with the expectation that educational toys are judged on sustained engagement and credible learning benefits, not short-lived novelty.
For leaders seeking to move faster with more granular visibility, detailed segmentation data, regional performance, and company-specific benchmarking can materially improve planning confidence. The broader trends are clear, but the execution advantages often come from subsegment insight: which age ranges are expanding most rapidly, where hybrid-versus-tactile trade-offs are shifting, and how compliance costs vary by product design and region. A complete research report can provide that depth, including detailed market splits, competitive positioning maps, and scenario-ready forecasts to support product, investment, and purchasing decisions.
For detailed analysis of this topic, please visit the official page: Educational Toys Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
High Precision Planetary Gear Reducers Market: How Asia Pacific’s 1772M Demand Reshapes Growth
By PW Consulting, 2026-09-21
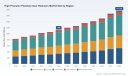
High Precision Planetary Gear Reducers: Strategic Trends and Commercial Opportunities in a Maturing Market
The high precision planetary gear reducer market has entered a phase of disciplined expansion, transitioning from a niche component supplier ecosystem to a critical enabler of next-generation motion control. Valued at approximately $1,140 million in 2025, the market has sustained a compound annual growth rate of 6.5% over the 2026–2032 horizon, with forward projections pointing toward $1,771 million by 2032. This trajectory reflects a fundamental shift in how industrial systems are engineered: precision gearing is no longer a passive power transmission element but an active determinant of throughput, energy efficiency, and operational reliability. The market’s evolution is shaped by tightening technical standards, accelerating automation adoption, and a competitive landscape where regional manufacturing footprints and application-specific engineering increasingly dictate commercial advantage.
For executives and investors, the opportunity lies not in capturing volume at any cost, but in aligning product architectures with the demand curves that will define the next decade. The following analysis maps the structural drivers, competitive dynamics, and actionable positioning strategies that will determine which players capture sustainable margin expansion and market relevance.
Market现状与核心挑战
The market’s current size and forecast profile reveal a sector that has survived the volatility of the early 2020s and is now consolidating around predictable, application-driven demand. Growth is no longer propelled by broad industrial recovery alone but by specific technology adoption cycles where precision gearing serves as a bottleneck or enabler. Three structural challenges define the current inflection point.
Precision Verification and Thermal Stability Requirements
Transmission performance is increasingly evaluated under dynamic operating conditions rather than static laboratory benchmarks. Updated international transmission precision guidelines now incorporate more stringent dynamic testing requirements under thermal equilibrium, raising the bar for validation protocols and forcing manufacturers to redesign testing infrastructure and quality assurance workflows. This shift compresses development cycles for new product lines, increases certification costs, and rewards suppliers who can demonstrate repeatable performance under sustained thermal loads. Companies that rely on legacy verification methods face higher rejection rates, longer customization lead times, and diminished credibility in applications where micro-backlash variations directly translate into positioning errors.
Automation Adoption as a Volume Amplifier
Global industrial robot installations surpassed 590,000 units in 2023, with over 62% of those installations incorporating high precision planetary gear reducers for torque control and precision motion. Simultaneously, the adoption of servo-based automation systems expanded by 13.4% in 2024, reflecting a broader structural preference for closed-loop motion control in both discrete manufacturing and process equipment. This demand surge is not uniform across sectors; it concentrates where cycle time reduction, repeatability, and footprint constraints justify the premium for precision gearing. The challenge for suppliers is to scale production without diluting engineering responsiveness, as standardization and application support become equally valuable as raw output capacity.
Geopolitical and Regional Manufacturing Realignment
Machine tool exports exceeded $10.7 billion in 2023, underscoring the continued strength of precision manufacturing exports in major industrial economies. Yet the same export momentum coincides with growing localization pressure in end markets, where lead time expectations, supply chain resilience, and total cost of ownership calculations are pushing buyers toward regional assembly and faster catalog fulfillment. Suppliers that depend on centralized production and long freight routes are encountering longer quotation-to-delivery windows, currency exposure, and reduced agility in responding to regional specification variations. The market is gradually rewarding localized capacity and modular product platforms that can be configured close to the point of use.
关键驱动因素分析
The market’s growth trajectory is being pulled by a small set of structural forces that interact with each other faster than historical forecasting models anticipated. Understanding these drivers is essential for prioritizing R&D investment, capacity strategy, and commercial positioning.
PW Consulting Automotive & Machinery Research Center
Technical Innovation and Materials Engineering
Precision gearing performance is increasingly determined by material selection, heat treatment consistency, and gear geometry optimization rather than by incremental scale gains. Manufacturers are moving toward carburized alloy steels and multi-planetary architectures that distribute load more evenly across tooth engagement surfaces, extending fatigue life and reducing torque ripple under variable loading. These design choices directly address the thermal stability requirements now embedded in updated precision guidelines, enabling gearboxes to maintain backlash characteristics across longer duty cycles. Innovation is also extending into lubrication management, sealing integrity, and housing stiffness, where marginal gains compound into measurable improvements in positioning accuracy and maintenance intervals. For suppliers, the commercial implication is clear: technical differentiation is shifting from catalog specifications to verifiable performance under real operating conditions, and the winners will be those who can translate materials engineering into documented reliability advantages.
Policy and Standardization Momentum
Standardization is no longer a passive compliance exercise; it is actively shaping purchasing criteria and supplier qualification. The updated transmission precision framework has elevated dynamic thermal testing from an advisory practice to a market expectation, which in turn creates a barrier for suppliers lacking rigorous validation capability. At the same time, automation adoption trends are being reinforced by broader industrial modernization objectives in multiple regions, where labor productivity, energy efficiency, and traceability requirements are pushing manufacturers toward integrated servo-mechanical systems. Policy environments that favor automation deployment, machine tool modernization, and local content preferences indirectly expand the addressable base for high precision reducers by accelerating the transition from conventional mechanical drives to precision motion control architectures. The strategic takeaway is that standardization and policy alignment are reshaping the qualification filter: suppliers that can demonstrate compliant test documentation, traceable manufacturing processes, and predictable delivery are gaining preferential access to tenders and long-term automation programs.
Demand-Side Behavior and Application Specificity
End-user behavior is shifting from generic specification purchasing toward application-tuned selection. In robotics, compact motion control demands low-backlash performance and minimal size, pushing suppliers toward integrated servo gear reducers that balance torque density with repeatability. In industrial manufacturing, the emphasis is on torque capacity, serviceability, and integration with higher-level control architectures, favoring product lines that can be configured for a range of ratios and mounting constraints. Semiconductor equipment applications impose a different set of requirements, where cleanliness, thermal steadiness, and micro-positioning reliability determine component selection more than absolute cost. This demand differentiation means that volume growth is increasingly segmented: suppliers that maintain a single generic product strategy face margin compression, while those that engineer for specific application envelopes can command pricing stability and deeper customer lock-in.
Supply Chain Structure and Cost Positioning
Cost structures are being reshaped by localization decisions and assembly sequencing. A notable example is the initiation of local assembly of P2.e planetary gear units in South Carolina, which reduced lead times for cataloged ratios to as short as six weeks. This move illustrates a broader trend: regional assembly capability is becoming a commercial differentiator because it shortens delivery cycles, reduces freight exposure, and improves responsiveness to specification adjustments without requiring full product redesign. At the same time, raw material consistency, heat treatment capacity, and precision machining availability remain binding constraints on output quality. Suppliers are responding by tightening upstream material sourcing, increasing in-house treatment capability, and standardizing modular ratio configurations to reduce custom engineering load. The cost implication is not simply lower unit pricing but lower total cost of ownership for buyers, which is increasingly the decisive factor in multi-year automation programs.
竞争格局与领先策略
The competitive landscape is characterized by moderate concentration, with the top three suppliers accounting for approximately 25% of market revenue and the top five extending to 35%. This distribution leaves substantial room for regional specialists, application-focused entrants, and integrated manufacturers to compete on engineering fit and delivery reliability rather than price alone. The market is not yet consolidating into a handful of dominant players, but it is stratifying around distinct value creation models.
Strategic Positioning Among Leading Suppliers
Leading companies have carved out defensible positions by aligning product architecture with specific application expectations. Neugart GmbH emphasizes low backlash and high rigidity across Economy and Precision Line series, targeting industrial motion control environments where repeatability and mechanical stiffness are paramount. Wittenstein SE competes on low-backlash servo gearboxes and hygienic design variants, positioning itself for demanding applications where cleanliness and precision must coexist. Apex Dynamics Inc. focuses on helical gearing for low backlash and high torque in servo applications, appealing to customers who prioritize torque transmission smoothness within compact envelopes. Harmonic Drive LLC markets zero-backlash planetary gearboxes engineered for robotics and precision actuation, reinforcing a performance-first positioning where elimination of mechanical play is the central value proposition. SEW-EURODRIVE GmbH & Co. KG offers high-torque planetary gear units with ratings up to 124 kNm, addressing industrial and servo applications where load capacity and durability determine system sizing. In parallel, several regionally anchored manufacturers are expanding their visibility through trade engagement and localized engineering support, signaling a market where regional presence, material specifications, and application demonstration increasingly influence procurement decisions.
Differentiation and Margin Protection
Sustainable differentiation in this market rarely comes from a single specification breakthrough; it emerges from the combination of precision validation, application support, and supply responsiveness. Suppliers that can document thermal-stable backlash behavior, provide modular ratio sets, and offer predictable delivery timelines are better positioned to protect margins than those competing primarily on unit price. Engineering services also matter: the ability to advise on mounting configurations, lubrication intervals, and integration with servo drives reduces implementation risk for buyers and increases switching costs. In practice, the most resilient players treat the gear reducer not as a standalone commodity but as part of an integrated motion solution, where documentation, testing evidence, and post-sale technical support reinforce the initial purchase decision.
Robot Joint Precision Reducers Market
Market Evolution: Integration, Fragmentation, and New Entrants
The landscape is evolving along two simultaneous tracks. On one hand, larger industrial drive and transmission groups continue to integrate planetary gearing into broader automation portfolios, leveraging existing distribution channels and application engineering teams. On the other hand, the market remains open to regional specialists and application-focused entrants who can win on precision claims, localized assembly, or domain-specific validation. New entrants are most likely to succeed where they can demonstrate measurable advantages in thermal stability, backlash control, or delivery speed, rather than attempting to compete across the full product spectrum. Consolidation is expected to remain selective, driven by the need to secure material supply, testing capability, and regional service coverage rather than by volume aggregation alone. The practical implication is that competitive advantage will increasingly belong to suppliers who can combine engineering credibility with agile commercial execution.
未来趋势预测
The next three to five years are likely to be defined by tighter performance verification, expanding application reach, and continued localization of supply. These trends create clear commercial opportunities, but they also introduce execution risks that demand disciplined planning.
Thermal-Validated Precision as a Baseline Expectation
Dynamic thermal testing and equilibrium-based verification are likely to move from guideline adherence to purchasing prerequisite. As end-users integrate gear reducers into high-duty-cycle automation systems, they will demand documented performance under sustained loads rather than nominal specifications. Suppliers that invest early in thermal validation infrastructure, repeatable test protocols, and transparent documentation will gain access to higher-value programs and reduce quotation-to-approval friction. The commercial opportunity lies in positioning precision verification as a risk-reduction asset for system integrators and original equipment manufacturers, not merely as a compliance cost. The risk, however, is that validation requirements raise the entry barrier and compress margins for suppliers that cannot efficiently scale testing throughput.
Worldwide Precise Servo Reducer Market
Robotics and Semiconductor-Driven Demand Expansion
Robotics will continue to be a primary volume driver, but high-precision planetary gear demand will increasingly be shaped by semiconductor equipment and advanced manufacturing systems that require micro-positioning reliability and thermal steadiness. This divergence means that growth will not be uniform; it will concentrate in applications where positioning accuracy directly affects yield, throughput, or equipment uptime. Suppliers that build application-specific engineering capabilities for these sectors can secure longer program cycles and more predictable demand. The upside is meaningful, but the downside risk is concentration risk: over-indexing on a single application without diversification can expose a supplier to cyclical downturns or technology substitution if alternative actuation methods gain traction.
Regional Assembly and Lead-Time Competition
Local assembly, modular ratio configuration, and regional distribution will become more important as buyers prioritize fast fulfillment and reduced supply chain uncertainty. The ability to deliver catalog ratios within short lead times is already reshaping purchasing expectations, and this pressure will likely intensify as automation programs accelerate and inventory strategies shift toward just-in-time readiness. Suppliers that establish regional assembly capability, standardize configurable product blocks, and maintain material consistency will be better positioned to capture demand in markets where delivery reliability equates to operational continuity. The associated risk is capital intensity and coordination complexity: regional capacity must be managed carefully to avoid fragmented production quality or excess inventory if demand forecasts shift.
决策者行动建议
Strategic choices in this market should be guided by the recognition that precision, delivery reliability, and application support are becoming as commercially significant as unit cost. The following recommendations are geared toward the main stakeholder groups evaluating exposure to high precision planetary gear reducers.
For Manufacturers and Product Companies
Engineer for application envelopes rather than generic catalogs. Prioritize thermal-stable backlash performance, modular ratio configurations, and documented validation evidence, because these attributes increasingly determine qualification success and pricing resilience. Invest in regional assembly or localized configuration capability where lead time expectations are compressing, and align material sourcing with consistent heat treatment and machining availability to protect quality at volume. Develop application-specific technical support that helps system integrators reduce integration risk, since post-sale engineering value is becoming a differentiator in multi-year automation deployments.
For Investors and Commercial Evaluators
Assess suppliers on verifiable precision capability, testing throughput, and regional delivery infrastructure rather than headline revenue alone. Favor companies that demonstrate modular product architecture, stable material supply, and the ability to shorten lead times for cataloged configurations, because these traits support margin stability and customer retention. Monitor application concentration as a risk indicator: businesses that are heavily dependent on a single sector should be evaluated against the potential for demand volatility or technology substitution, while diversified application portfolios typically offer more resilient growth profiles.
For Buyers and Procurement Teams
Shift evaluation criteria toward total cost of ownership, thermal-stable performance documentation, and delivery reliability. Request verification evidence under dynamic conditions, clarify ratio availability and lead-time expectations for cataloged configurations, and assess supplier capability to support integration with servo control architectures. Prioritize suppliers that can provide predictable delivery and application engineering assistance, because implementation risk and downtime avoidance often outweigh marginal unit price differences in precision automation programs.
For organizations seeking a deeper dive into segment-level sizing, regional dynamics, application demand curves, and competitive benchmarking, the full market research report provides detailed breakdowns and customized strategic recommendations that extend beyond the directional insights outlined here. Accessing that level of granularity can help align investment timing, product planning, and sourcing strategy with the specific demand drivers that will shape the next phase of market growth.
For detailed analysis of this topic, please visit the official page: High Precision Planetary Gear Reducers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Rotary Indexer Market 2026–2032: Why 5.49% CAGR Belies Real Demand Shifts
By PW Consulting, 2026-09-21
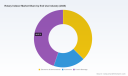
Rotary Indexer Market: Strategic Trends & Commercial Opportunities 2025–2032
The rotary indexer market has entered a decisive growth phase, transitioning from a niche automation component to a critical enabler of high-speed, precision manufacturing. Current market valuations reflect a mature yet expanding ecosystem, with revenue projections indicating a steady climb over the next seven years. The industry is characterized by a relatively fragmented competitive landscape, where no single player dominates the value chain, creating space for differentiated positioning and strategic consolidation. For executives and investors, the opportunity lies not merely in riding volume growth but in aligning product portfolios, supply chain resilience, and compliance frameworks with the shifting demands of digitally integrated factories.
At its core, the market is being reshaped by the intersection of automation economics, regulatory tightening, and the need for modular, adaptable motion control solutions. The following analysis maps the structural forces at play, the competitive dynamics defining winners and laggards, and the strategic moves that stakeholders should consider as the market matures through the late 2020s.
Market Snapshot & Core Challenges
The rotary indexer market has demonstrated consistent expansion over the past half-decade, with revenue trajectories pointing toward a multi-billion-dollar footprint by the early 2030s. Growth is underpinned by the broader industrial automation cycle, where manufacturers seek to compress cycle times, reduce labor dependency, and increase repeatability in high-mix environments. Yet the headline numbers obscure the operational friction that many market participants face.
Three challenges are particularly salient for decision-makers navigating this landscape.
1. Compliance fragmentation across regions. Rotary indexer deployments operate under a patchwork of safety and machinery standards. In North America, electrical safety and reliability expectations center on UL certification, while European installations must meet the Machinery Directive with CE marking. Chinese markets require GB/T 5226.1 certification, and Indian industrial deployments increasingly reference IS/ISO 12100 standards. This regulatory diversity raises the cost of market entry, complicates product certification pathways, and forces manufacturers to design for multiple compliance regimes rather than a single global footprint.
2. Supply chain volatility from geopolitical and trade pressures. Production schedules for rotary indexers are increasingly exposed to disruptions stemming from geopolitical tensions and trade restrictions. Component sourcing, lead time predictability, and logistics continuity have become strategic variables rather than purely operational concerns. For buyers, this translates into elevated inventory risk; for suppliers, it means rethinking sourcing strategies, regional assembly models, and buffer capacity.
3. The push for flexibility versus fixed-cycle efficiency. Traditional indexing solutions excel in high-volume, low-mix environments where cycle consistency is paramount. Yet many end-use sectors are pivoting toward higher mix variability, shorter production runs, and rapid reconfiguration. This demand shift pressures vendors to deliver indexers that can adapt without sacrificing precision, torque, or throughput—creating tension between mechanical simplicity and programmable adaptability.
Worldwide Fixed Rotary Index Tables Market
Key Demand Drivers
The market's trajectory is not incidental; it is being pulled forward by intersecting technological, regulatory, and demand-side forces that reshape how rotary indexers are specified, integrated, and valued.
PW Consulting Automotive & Machinery Research Center
Technology Innovation & Breakthroughs
The most visible shift is the integration of programmable controls, servo-driven architectures, and digital interfaces into rotary indexing platforms. Fixed-station and cam-driven designs continue to hold relevance where cycle repetition is high and predictability is the priority, but servo-driven and ring-drive variants are gaining traction in applications requiring variable division, dynamic load handling, and tighter coordination with broader PLC ecosystems. Advances in torque density, moment-load capacity, and motion control precision are expanding the addressable envelope for rotary indexers in heavier-duty and higher-accuracy contexts.
Beyond hardware, the trend toward seamless integration is redefining value. Indexers that can be configured for independent operation or embedded within larger automation cells are increasingly preferred by engineering teams that want to reduce integration friction. The emphasis is shifting from standalone component performance to system-level compatibility—signal compatibility, mounting modularity, and control interoperability.
Policy & Regulatory Environment
Regulatory frameworks are simultaneously a constraint and a catalyst. Safety mandates are pushing manufacturers toward more rigorous design validation, documentation, and certification processes. While this raises upfront engineering and compliance costs, it also creates a barrier that favors established players with mature quality systems and reduces the risk of costly field failures. In practice, compliance readiness is becoming a competitive differentiator, especially in regulated end markets where downtime, safety incidents, or audit findings carry significant financial and reputational consequences.
At the same time, regional certification requirements are encouraging localized engineering support and distribution partnerships. Vendors that can navigate multiple standards without fragmenting their product lines too thinly are better positioned to scale across jurisdictions without sacrificing margin or speed-to-market.
Demand-Side Shifts in Buyer Behavior
Procurement and engineering teams are no longer buying rotary indexers solely on cycle speed or base price. They are evaluating total cost of ownership, integration effort, serviceability, and the ability to adapt to future line reconfigurations. This is particularly true in assembly-intensive and packaging-heavy operations, where changeover frequency and line modularity directly affect operational economics.
There is also a growing preference for solutions that can support partially automated and buffer-oriented workflows, rather than forcing full-line automation where it is not yet justified. Pneumatic and hybrid configurations remain relevant in these contexts, offering a pragmatic balance between cost, simplicity, and incremental automation. The broader implication is that segmentation by product type is becoming less about mechanical taxonomy and more about matching solution profiles to specific automation maturity levels.
Supply Chain & Cost Structure Evolution
Cost dynamics are being reshaped by both component availability and the broader industrial automation supply base. Geopolitical tensions and trade restrictions are introducing uncertainty into sourcing and scheduling, prompting manufacturers to weigh single-source dependencies against multi-region resilience. This is encouraging a reevaluation of bill-of-materials strategy, regional stocking models, and the role of local assembly or finishing operations.
For end-users, the result is a more cautious procurement posture: longer lead-time planning, greater emphasis on supplier reliability, and increased willingness to pay for predictability and field support. For vendors, the imperative is to build supply chain transparency, safeguard critical component availability, and communicate lead-time expectations clearly—because reliability is increasingly as valuable as unit price in competitive bidding environments.
Competitive Landscape & Leading Strategies
The competitive field in the rotary indexer market is diverse, with players differentiated by technology focus, geographic reach, and integration capability. No single entity commands a dominant share, which means competitive advantage is increasingly derived from specialization, partnership networks, and the ability to deliver sector-specific solutions rather than from sheer scale alone.
Differentiated Positioning Among Leading Companies
Several firms illustrate the breadth of strategic approaches currently shaping the market.
- Motion Index Drives focuses on cam-driven rotary indexing tables and custom solutions for high-cycle automation, with emphasis on aerospace, automotive, and packaging applications. Its positioning leans toward engineered, application-specific designs where cycle fidelity and durability are paramount.
- Nexen Group emphasizes servo and ring-drive rotary indexers with high-torque and moment-load capacity, targeting precision industrial positioning where load handling and accuracy are central requirements.
- WEISS GmbH produces programmable and fixed-station rotary indexing tables with digital controls and integration capabilities, serving automotive, medical, and electronics assembly. Its recent activity underscores a dual strategy of market presence and technology collaboration.
- Destaco develops mechanical and servo rotary indexers, roller dials, and drives for assembly and packaging equipment, aligning its portfolio with the needs of equipment builders and end users in high-throughput environments.
- Sanko Automation manufactures hollow and fixed-station rotary indexing tables with programmable controls for factory automation, reflecting a growing pool of regionally anchored manufacturers serving broader automation demand.
- Centricity Automation offers servo rotary indexers aligned with PLC-integrated and independent high-precision assembly applications, positioning around control integration and precision execution.
- Taktomat GmbH supplies rotary indexers with fixed and flexible division for high-speed production lines, emphasizing throughput and division flexibility in fast-cycle contexts.
- TallMan Robotics designs shaft-output rotary indexers and cam index drives for engineered automation motion, targeting applications where tailored motion paths and mechanical integration matter.
- Festo offers pneumatic rotary indexing tables suited to partially automated and buffer systems, reinforcing a role for simpler, cost-effective motion solutions where full servoization is not yet warranted.
The strategic throughline is clear: suppliers are differentiating through a combination of motion architecture, control integration, and vertical application focus. Companies that can articulate where their strengths lie—high torque, programmability, speed, integration ease, or cost efficiency—are better positioned to defend margins and win specification decisions.
Market Evolution: Consolidation, Specialization, and New Entry
The market's relatively fragmented concentration leaves room for both consolidation and further specialization. On one path, larger automation groups or component conglomerates may seek to expand their motion control portfolios through acquisitions or partnerships, aiming to offer end-to-end indexing and handling solutions. On another, agile specialists will continue to carve out niches around programmable control, sector-specific compliance, or regional service networks.
New entrants are likely to emerge where they can combine cost-competitive manufacturing with credible control integration and compliance readiness. However, entry alone is insufficient; success will depend on navigating certification landscapes, establishing reliable supply chains, and demonstrating integration compatibility within existing automation ecosystems. The more enduring competition will be around ecosystem fit—how well an indexer aligns with the control architecture, safety requirements, and throughput expectations of the target application.
Forward Outlook: Three Trends to Watch
Looking ahead to the mid-to-late 2020s and into the early 2030s, three trends are likely to shape commercial outcomes in this market.
Trend 1: Programmable and Servo-Enabled Indexers Will Capture a Growing Share of New Installations
The pull toward flexible division, variable cycle control, and tighter integration with digital automation architectures will continue to shift specification preferences toward servo-driven and programmable platforms, particularly in assembly, electronics, and medical contexts where changeover and precision matter. This does not eliminate cam-driven or pneumatic solutions, but it reallocates growth toward architectures that support reconfiguration and coordinated motion. Commercial opportunity lies in offering scalable control options, clear migration paths from fixed to programmable modes, and integration support that lowers engineering burden for buyers.
Trend 2: Compliance Readiness Will Become a Market Access Discipline, Not a Back-Office Task
As safety and machinery standards continue to shape procurement decisions, vendors that treat certification and documentation as strategic capabilities will have an advantage in multi-region selling. This includes proactive alignment with regional requirements, consistent quality systems, and the ability to provide buyers with clear compliance evidence. For manufacturers, the upside is reduced friction in specification approvals and fewer delays in deployment; for buyers, the value is lower risk and faster commissioning. The uncertainty lies in the pace and variability of regulatory updates across jurisdictions, which can alter certification roadmaps without much warning.
Trend 3: Supply Chain Resilience Will Differentiate Suppliers in Competitive Bids
Geopolitical tension and trade restrictions are likely to remain structural factors rather than transient disruptions. Manufacturers that invest in diversified sourcing, regional inventory strategies, and transparent lead-time communication will be favored by procurement teams under pressure to protect production schedules. This creates a commercial opportunity for suppliers who can Demonstrate reliability as a deliberate capability—through regional assembly, buffer stock planning, and predictable delivery commitments—rather than treating it as a reactive fix. The risk is that resilience investments raise cost bases if not managed with disciplined operations and demand forecasting.
Strategic Moves for Decision-Makers
The rotary indexer market rewards stakeholders who align their actions with the structural shifts already underway. The following considerations are most relevant for manufacturers, investors, and procurement leaders.
For Manufacturers and Solution Providers
- Clarify your motion architecture positioning. Decide where you compete—high torque, programmability, speed, integration ease, or cost efficiency—and ensure product naming, documentation, and sales narratives reinforce that choice rather than diluting it across every possible feature.
- Strengthen compliance as a product attribute. Build certification pathways and documentation into the product development cycle so that multi-region deployment does not become a last-minute engineering scramble.
- Invest in integration-friendly design. Prioritize mounting modularity, control compatibility, and clear communication interfaces to reduce the engineering lift for equipment builders and end users.
- Plan supply chain resilience deliberately. Map critical components, evaluate regional sourcing options, and communicate realistic lead times as part of your value proposition.
For Investors
- Evaluate ecosystem fit over unit pricing. Companies that can embed their indexers into broader automation workflows—through integration support, compliance readiness, and service networks—are more likely to secure durable specification wins.
- Watch for consolidation signals around motion control. The fragmented concentration suggests potential for portfolio expansion through acquisition, particularly where buyers are seeking integrated handling and indexing capabilities.
- Assess exposure to regulatory complexity. Firms with mature quality systems and multi-region certification experience are better positioned to scale without being blocked by compliance delays.
For Procurement and Engineering Leaders
- Specify for total deployment cost, not just purchase price. Factor in integration effort, lead-time risk, field support, and reconfiguration flexibility when comparing alternatives.
- Align solution choice with automation maturity. Pneumatic and fixed-cycle options may be appropriate where partial automation or buffer systems are in use, while servo-driven and programmable platforms fit lines that require frequent reconfiguration or precise coordination.
- Engage suppliers early on compliance and integration requirements. Early alignment on safety standards, control compatibility, and documentation can materially reduce commissioning risk and schedule slippage.
Closing Perspective
The rotary indexer market is moving from component-level competition to solution-level value creation. Growth will continue, but the distribution of advantage will favor players who can combine motion performance with integration ease, compliance readiness, and supply chain reliability. For manufacturers, that means sharpening positioning and treating certification and resilience as strategic capabilities. For investors, it means looking beyond headline pricing to ecosystem fit and durability of specification wins. For procurement and engineering teams, it means specifying for deployment reality—total integration effort, reconfiguration potential, and predictable delivery—rather than chasing the lowest unit cost in isolation.
The commercial landscape will keep evolving as programmable architectures expand, regulatory expectations intensify, and supply chain considerations become a more explicit part of buying decisions. Stakeholders who map these forces to their own product strategies, investment theses, and sourcing criteria will be better positioned to capture the upside while managing the inherent uncertainty of a market in transition.
Rotary Encoders Market
For detailed analysis of this topic, please visit the official page: Rotary Indexer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Air Ambulance Market: Why 8.5% CAGR and Regional Shifts Reshape Strategic Growth Beyond 2026
By PW Consulting, 2026-09-21
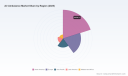
Navigating the Air Ambulance Market: Strategic Trends and Commercial Opportunities Through 2032
The air ambulance sector has entered a period of sustained expansion, with the broader market trajectory signaling a compound annual growth rate in the mid-single digits over the coming half-decade. Revenue has progressed from roughly $10.9 billion in 2020 to approximately $16.8 billion by 2025, and forward projections place the market near $17.9 billion in 2026 before climbing toward $29.6 billion by 2032. This growth is not merely a function of rising volume; it reflects structural shifts in how critical care is delivered, how reimbursement frameworks are settling, and how operators are reconfiguring networks to meet demand in rural, suburban, and specialized clinical corridors. For decision-makers evaluating exposure to medical transport, the opportunity lies in understanding where margin resilience is being built, where regulatory pressure is reshaping pricing, and which service models are gaining durability as healthcare systems consolidate.
Market Snapshot and Structural Challenges
The market's expansion over the past five years has been shaped by a combination of higher trauma and inter-facility transfer volumes, broader adoption of rotor-wing and fixed-wing assets, and growing reliance on dedicated medical transport for time-sensitive conditions. The revenue curve has moved steadily upward, with the most recent base-year figures anchored in the $16.5 billion range and the forecast period extending into the late 2020s and early 2030s. While the headline growth is encouraging, the sector is navigating a set of interconnected challenges that will determine which operators thrive and which face margin compression.
First, billing and reimbursement architecture has undergone a decisive reset. The enforcement of balance-billing prohibitions has removed a long-standing revenue lever for many operators, forcing a shift toward cost transparency, standardized documentation, and more disciplined contract negotiation with payers and health systems. Operators that once relied on patient balance billing to offset fixed fleet and clinical staffing costs are now operating with narrower pricing flexibility, making operational efficiency and contract structure increasingly determinative of profitability. Second, the cost of clinical labor remains a defining pressure point. Specialized flight nurses, paramedics, and critical care teams are required around the clock, and the premium for maintaining bedside-to-bedside ICU capability in the air has kept median single-transport costs elevated. In an environment where reimbursement is more constrained and predictable, the economics of standing up and sustaining 24/7 coverage depend heavily on utilization rates, base placement logic, and the ability to avoid empty repositioning flights. Third, regulatory oversight of safety, accreditation, and data reporting has tightened, adding compliance costs and operational discipline requirements that disproportionately affect smaller or under-capitalized operators.
These challenges are not merely headwinds; they are reshaping the competitive field. They reward operators with scale, diversified transport modes, hospital system partnerships, and membership or subscription frameworks that smooth revenue volatility. At the same time, they are elevating the importance of precise network design, fleet flexibility, and clinical staffing models that can scale without eroding margin.
Core Drivers Reshaping the Market
The market’s trajectory is being pulled by a set of mutually reinforcing drivers that go beyond simple volume growth. Understanding these forces is essential for anticipating where capital, partnerships, and operational investments will yield the strongest returns.
Technology and clinical capability advancement continues to alter what air medical transport can achieve in compact, high-altitude, and time-critical environments. Equipment miniaturization, improved portable monitoring, and more integrated cabin configurations are expanding the range of patients that can be moved safely by air without sacrificing ICU-level care. Fixed-wing operators in particular are benefiting from the ability to offer longer-range, higher-comfort transfers for complex cases, including burns, cardiac instability, and pediatric transports that require sustained critical care en route. Rotor-wing assets remain indispensable for rapid scene response and access to remote or congested terrain, but the broader trend is toward modality matching: choosing the right aircraft for the clinical profile, distance, and landing environment rather than defaulting to a single platform. This technical maturity supports higher-value transport contracts and strengthens the case for hospital-system partnerships that prioritize clinical outcomes alongside speed.
Policy and regulatory environment is now a primary determinant of revenue predictability and operating posture. The move toward prohibiting balance billing has fundamentally changed the commercial model, shifting attention to payee contracts, transparent cost coding, and the submission of detailed transport and clinical data to relevant authorities. Simultaneously, updated reimbursement schedules finalized in 2025 have introduced greater cost certainty for both independent and hospital-based operators, reducing the volatility that previously complicated fleet planning and staffing commitments. Safety oversight continues to standardize expectations around accreditation and operational reporting, which raises the barrier to entry but also rewards operators that can demonstrate consistent compliance and clinical quality. In practice, the regulatory environment is pushing the market toward a more contract-driven, outcomes-oriented model in which financial protection for patients and predictability for providers coexist.
Demand-side behavior and healthcare system evolution is accelerating the need for reliable, specialized air transport. As emergency departments, trauma networks, and specialty centers coordinate care across wider geographies, the volume of inter-facility relocations for higher-acuity patients is rising. Rural and underserved regions face persistent access gaps that air medical services help bridge, while membership and subscription programs have grown in relevance as patients and employers seek financial protection against high out-of-pocket exposure. For hospital systems, the strategic calculus includes not only transport speed but also network reliability, clinical continuity, and the ability to maintain specialized care pathways without maintaining large internal fleets. This demand dynamic supports partnerships that embed air transport into broader emergency and critical-care networks rather than treating it as an episodic service.
Cost structure and network optimization are becoming decisive competitive levers. The economics of air medical transport are heavily influenced by base placement, aircraft utilization, crew scheduling, and the mix of emergency versus inter-facility missions. Operators are increasingly prioritizing networks that reduce deadhead flights, improve crew productivity, and align assets with predictable demand corridors. Membership-based financial protection, where offered, can help stabilize revenue and reduce patient friction, while hospital-affiliated networks can improve mission density and scheduling predictability. The broader supply-side picture also rewards operators that can flex fleet composition in response to seasonal demand, regional coverage needs, and the varying clinical requirements of rotor-wing versus fixed-wing missions. Cost discipline, in this context, is not simply about cutting expense; it is about designing a network that converts fixed clinical and aviation costs into consistent, reimbursable utilization.
Competitive Landscape and Leading Strategies
The competitive field is concentrated enough that scale, network breadth, and contractual relationships matter, yet varied enough that differentiated operating models can still carve out durable positions. The market features a mix of large national providers, hospital-adjacent networks, membership-focused organizations, and specialized fixed-wing operators. Several recent developments illustrate how leading players are positioning themselves for the next phase of growth.
Worldwide Electric Ambulance Stretchers Market
Air Methods has been actively expanding its footprint through fleet growth, network partnerships, and long-term public-sector contracts. The operator’s plans to add nearly 50 aircraft signal a push to deepen nationwide coverage and improve response density, while partnerships with integrated health systems are designed to embed air transport within organized critical-care networks. A major multi-year contract with a Canadian territorial government and an airline partner underscores how public and quasi-public demand can provide revenue visibility and support fleet utilization. Collectively, these moves reflect a strategy centered on scale, network reliability, and diversified mission sources that blend emergency response, inter-facility transfers, and government-sponsored coverage.
Global Medical Response has built its positioning around integrated ground and air medical transport, emphasizing continuity between emergency response, inter-facility relocation, and clinical team deployment. This integrated model is strategically valuable because it allows the operator to route patients through the most appropriate transport mode based on clinical need, distance, and system coordination, rather than being locked into a single asset class. By aligning air and ground capabilities, the operator can improve utilization, reduce handoff friction, and offer health systems a more predictable transport pathway for both emergency and planned transfers.
PHI Air Medical operates a large rotor-wing network with broad geographic coverage and a strong emphasis on 24/7 critical care transport and membership programs. The membership dimension is notable because it addresses patient financial protection directly, reducing out-of-pocket exposure and potentially increasing willingness to use air transport when clinically appropriate. A wide base network and continuous availability support mission density, which is critical to the economics of standing up clinical crews and maintaining aircraft readiness. This combination of coverage scale, clinical continuity, and membership-based financial protection illustrates a model that balances service reliability with patient affordability.
REVA Air Ambulance has carved out a specialized role as a large dedicated fixed-wing jet operator focused on bedside-to-bedside ICU-level transport across North and South America. The fixed-wing specialization is strategically distinct because it serves longer-distance, higher-complexity transfers that may be less suited to rotor-wing assets, including critical care relocations that require sustained medical support over extended flight times. By concentrating on this segment, the operator aligns its fleet, clinical staffing, and operational processes with a specific demand profile, which can improve both clinical reliability and commercial positioning in cross-border and inter-regional care networks.
Acadian Companies and AirMedCare Network represent two additional strategic archetypes. Acadian’s air medical division provides helicopter and fixed-wing emergency and inter-facility transport in specific regional markets, illustrating how strong local presence and clinical reputation can anchor demand in rural and surrounding areas. AirMedCare Network, by contrast, emphasizes a membership-oriented model that provides financial protection and access to affiliated providers for both rotor-wing and fixed-wing transports. This network approach broadens access and creates a patient-facing financial layer that can complement the clinical and operational capabilities of affiliated carriers.
Taken together, the competitive landscape is evolving through a blend of consolidation and differentiation. Larger operators are pursuing scale through fleet expansion, partnership with health systems, and long-duration public or institutional contracts that improve visibility. At the same time, specialized and membership-based models are preserving distinct positions by serving specific clinical, geographic, or financial-protection needs. New entrants face a higher bar due to safety accreditation, clinical staffing requirements, and the need to secure dense, predictable mission flow, which tilts the field toward incumbents that can combine operational maturity with strategic partnerships. The most resilient strategies appear to be those that align transport modality with clinical demand, embed services within broader care networks, and manage financial exposure through contract structure or membership programs rather than relying on volatile patient billing.
Future Trends and Commercial Implications
Looking ahead three to five years, several trends are likely to shape where value is created and where risk concentrates. These trends are not abstract; they point to concrete opportunities for operators, investors, and healthcare organizations that can align their strategies with the market’s structural direction.
One likely trend is the continued deepening of health-system partnerships and network integration. As hospitals and emergency networks seek reliable pathways for time-sensitive and high-acuity transfers, air medical services that are formally embedded in regional care networks will be better positioned to secure predictable mission flow and contractual stability. The commercial implication is that operators with strong partnership economics, clear service-level commitments, and integrated clinical coordination will gain an advantage in both utilization and revenue predictability. The risk is that operators without dense network relationships may face more sporadic demand and greater reliance on spot-market pricing, which is increasingly less attractive under tighter reimbursement rules.
A second trend is the widening strategic divergence between rotor-wing and fixed-wing business models. Rotor-wing networks will continue to anchor rapid scene response and access in challenging terrain, but their economics will depend on base placement discipline, crew utilization, and mission density. Fixed-wing services will capture growing demand for longer-distance, higher-acuity transfers and cross-regional relocations, where clinical continuity and flight duration matter more than rapid deployment. Commercial opportunity lies in matching fleet strategy to demand rather than over-indexing on a single platform. Operators that can flex between modalities or specialize cleanly in one, with supporting clinical and scheduling infrastructure, will be better equipped to protect margins.
A third trend is the growing importance of financial-protection and membership frameworks alongside contract-based reimbursement. With balance billing constrained and patient cost sensitivity elevated, models that reduce out-of-pocket exposure and provide predictable transport access are likely to remain relevant. For operators, membership programs can smooth revenue and support utilization; for health systems and employers, they can reduce administrative friction and patient dissatisfaction. The uncertainty here lies in how these programs interact with evolving reimbursement schedules and payer contracts, and whether membership economics can scale without diluting clinical quality or network coverage.
PW Consulting Automotive & Machinery Research Center
A final area of attention is regulatory and compliance maturation as a competitive filter. As safety, accreditation, and data-reporting expectations become more standardized, operators with robust compliance systems and documented clinical outcomes will be better positioned for contracts with hospitals, government entities, and institutional payers. The upside is greater trust and contract eligibility; the downside is that compliance costs and operational discipline requirements will continue to pressure smaller or less-capitalized participants, potentially accelerating consolidation among those that cannot meet the bar.
Actionable Guidance for Decision-Makers
For executives and investors evaluating the air ambulance sector, the strategic priorities should center on network design, contract structure, and modality alignment rather than on volume growth alone.
For operators and manufacturers, the priority is to build fleet and staffing models that reflect real demand density and mission mix. This means evaluating base placement against likely call patterns, ensuring clinical crews are deployed with high utilization, and matching aircraft capability to the clinical profiles most common in each region. Where fixed-wing capability is being expanded, the supporting clinical protocols, crew training, and scheduling logic should be designed for longer-duration ICU-level transport. Where rotor-wing networks are the focus, the emphasis should be on rapid response coverage, base clustering that minimizes deadhead time, and partnership structures that increase mission predictability. Product and equipment decisions should also reflect the trend toward compact, integrated cabin configurations that support critical care without sacrificing safety or operational practicality.
For investors, the emphasis should be on operators and service models that demonstrate revenue visibility, contract maturity, and cost discipline under constrained billing conditions. Metrics that matter include mission utilization, base-level crew productivity, the mix of emergency versus inter-facility work, and the degree to which revenue is anchored by health-system partnerships, public-sector contracts, or membership frameworks. The market’s concentration profile suggests that scale advantages are real, but differentiated models can still create durable value if they serve a specific clinical, geographic, or financial-protection need. Investors should also monitor the evolving reimbursement environment, since cost certainty from updated schedules can improve planning while continued regulatory tightening may raise barriers to entry and operational costs.
For healthcare organizations, EMS leaders, and procurement stakeholders, the focus should be on selecting transport partners that can deliver clinical reliability, network coverage, and transparent cost structures. Evaluating providers should go beyond aircraft count to include accreditation posture, clinical staffing depth, ability to match modality to patient need, and the strength of integration with regional care pathways. For organizations in rural or underserved areas, the value proposition increasingly includes not only speed of access but also continuity of care, membership or financial-protection options, and the capacity to support both emergency and planned inter-facility transfers. Establishing clear service expectations and data-sharing arrangements can improve both clinical outcomes and commercial predictability.
As the market continues to evolve, the operators and investors that will capture the most durable value are those that treat air medical transport as part of an integrated critical-care network rather than as an isolated service line. Detailed segmentation, regional dynamics, and scenario-level cost structures can sharpen these decisions further, and readers seeking deeper coverage of the market’s sub-segments and competitive scenarios are encouraged to consult the full PW Consulting research report for more granular data and tailored strategic guidance.
Emergency Ambulance Market
For detailed analysis of this topic, please visit the official page: Air Ambulance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Linear Motors Market 2026: Why 7.25% CAGR and Automation Shift Reshape Growth
By PW Consulting, 2026-09-21
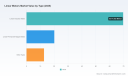
Navigating the Linear Motors Market: Strategic Shifts and Commercial Opportunities Through 2032
The linear motors market has entered a phase of disciplined expansion, characterized by steady revenue growth and shifting structural dynamics across industrial automation, material handling, and precision motion control. With a compound annual growth rate of 7.25 percent projected through 2032, the sector is transitioning from a niche positioning system to a core enabling technology for high-throughput, high-precision operations. Market valuation has climbed consistently over the past half-decade, reflecting both incremental adoption in mature automation environments and accelerated deployment in emerging high-speed manufacturing and logistics applications. The growth trajectory is not uniform, however. It is being shaped by competing force in technology maturation, supply chain reconfiguration, regulatory evolution, and changing cost tolerance among end users. For executives and investors evaluating positioning in motion control infrastructure, understanding where value is being created and where friction is accumulating has become a strategic necessity.
Market Structure and Core Challenges
The market’s expansion is underpinned by a clear shift in how motion systems are specified and integrated. Demand is increasingly favoring direct-drive architectures that reduce mechanical complexity, improve throughput consistency, and simplify maintenance cycles. This preference has elevated linear motors from component-level alternatives to foundational elements in automated lines, where precision, repeatability, and uptime directly influence operational economics. While the broad market continues to grow, three structural challenges are defining the current inflection point.
The first challenge is the tension between performance gains and acquisition economics. Linear motor systems offer clear advantages in cycle time, positioning accuracy, and mechanical footprint, but their upfront cost and integration complexity remain barriers for cost-sensitive facilities. Many operators are still weighing the total cost of ownership against conventional ball screw or belt-driven alternatives, especially in environments where throughput requirements are moderate or where changeover flexibility outweighs peak performance. This calculation is not static; it is being reshaped by labor availability, energy pricing, and the rising cost of downtime in high-mix production settings.
A second challenge is supply chain concentration around critical materials. High-performance permanent magnet linear motors rely on neodymium-iron-boron alloys, and refined material supply remains heavily concentrated in a single geographic source. The resulting price volatility has introduced cost uncertainty into product planning and margin management, particularly for manufacturers that depend on magnet-intensive designs. This dynamic is forcing a broader conversation about material alternatives, motor topology choices, and procurement strategies that can absorb commodity swings without compromising performance targets.
A third challenge is the skills gap in installation, commissioning, and ongoing optimization. Linear motor systems are not simply drop-in replacements; they often require updated control architectures, tuned motion profiles, and specialized troubleshooting capabilities. Facilities facing technician shortages or limited in-house motion engineering expertise may delay adoption or resort to conservative configurations that leave performance on the table. In effect, the market is growing not only because the technology is improving, but because organizations are learning how to deploy it efficiently and safely in real operating conditions.
Key Demand Drivers Reshaping the Market
Several forces are converging to sustain demand while also changing the terms of competition. The most consequential is the continued push toward faster, cleaner, and more repeatable motion in automation-intensive industries. Linear direct-drive solutions reduce mechanical play and wear associated with intermediate transmission components, which appeals to operators in semiconductor-related processing, precision assembly, and advanced material handling. As production lines become more modular and changeover frequency increases, the ability to maintain accuracy across rapid transitions is becoming a practical requirement rather than a premium feature.
Regulatory and safety expectations are also influencing adoption patterns. Functional safety requirements in high-risk environments are pushing motion system integrators to address certification and risk mitigation earlier in the design process. Recent firmware and safety monitoring upgrades for linear motor applications illustrate this shift, showing how safety compliance is becoming embedded into motion control platforms rather than treated as a separate add-on. In sectors where equipment must meet stringent safety integrity levels, this integration reduces deployment friction and expands the addressable use cases for direct-drive linear motion in demanding environments.
On the supply side, material and cost dynamics are reshaping product strategies. The dependence on rare-earth magnet supply chains has made pricing volatility a strategic concern rather than a periodic procurement issue. Manufacturers are responding by diversifying motor topologies, optimizing magnetic circuit design, and developing ironcore and ironless variants that can be matched more flexibly to application requirements. At the same time, regional sourcing considerations and long-term procurement agreements are becoming more important as buyers seek predictability in both cost and delivery. This is not simply a cost-cutting exercise; it is a structural adjustment to ensure continuity of high-performance offerings in a market where material constraints can directly affect product availability.
A further driver is the increasing integration of motion components with broader automation ecosystems. Linear motors are being evaluated less as isolated actuators and more as parts of coordinated systems that include drives, feedback devices, safety functions, and software-based motion orchestration. This trend rewards suppliers that can provide coherent integration paths, consistent interfaces, and documentation that supports faster commissioning. It also raises the stakes for fragmented supply chains in which mismatched components increase engineering overhead and slow line deployment.
Competitive Landscape and Strategic Positioning
The competitive environment is moderately concentrated, with no single provider dominating the entire market. Instead, value is distributed across firms with different technical orientations, regional footprints, and integration capabilities. The market structure favors companies that can combine precision hardware with practical deployment support, especially where end users are balancing performance, safety, and total cost of ownership.
Several strategic positions are emerging among leading participants. One is the high-quality direct-drive focus, where providers emphasize industrial linear servo motors, linear modules, and complete system-level offerings designed to simplify sourcing and reduce integration risk. This approach appeals to automation teams that prefer a single-source path for linear motion and want consistent engineering support across product families. Another position is breadth across motor technologies and motion control components, allowing suppliers to address a wide range of applications with brushless, linear stepper, linear induction, voice coil, and related solutions. This breadth can be advantageous in multi-application environments where requirements vary significantly from one station to another.
A third position centers on high-precision permanent magnet and multi-axis linear motion systems. In this segment, differentiation often comes from positioning accuracy, stage design, and the ability to support demanding single-axis or coordinated multi-axis motion. A related competitive approach is specialized customization for automation, robotics, and precision motion control, where ironcore and ironless designs are tailored to specific load, force, and environmental requirements. Meanwhile, some participants compete through kit-form or modular motor offerings that allow system builders to integrate linear motion into bespoke mechanical designs, trading off some turnkey convenience for flexibility.
PW Consulting Automotive & Machinery Research Center
The market is also being shaped by integrated automation providers that combine linear servomotors with broader control architectures. These firms often compete on interoperability, software-driven motion configuration, and the ability to support high-speed linear motion within a unified automation environment. In parallel, custom motor designers serve specialized research and industrial applications where off-the-shelf solutions cannot meet exact geometric or performance constraints. Together, these positions indicate a market that is neither fully commoditized nor narrowly specialized; it is stratifying around the value that different customers prioritize, whether that is turnkey simplicity, precision performance, customization, or ecosystem integration.
How the Landscape Is Evolving
The competitive field is evolving along several lines. One is increasing emphasis on safety-certified motion functionality, which is becoming a meaningful differentiator in applications where human interaction, high-speed handling, or hazardous processing creates elevated risk profiles. Another is the continued diversification of motor architectures in response to material costs and application variability, with suppliers expanding their portfolios to give buyers more options for balancing force density, heat management, and cost. A third is the growing importance of regional service, support, and deployment expertise, since the practical success of a linear motor installation often depends on local commissioning capability as much as on hardware specifications.
New entry and realignment are likely in segments where integration complexity can be reduced and where safety or precision requirements create barriers that are difficult to clear without established engineering depth. At the same time, consolidation pressure may build among smaller specialists if customers increasingly favor suppliers that can cover broader application scopes or offer more complete system-level support. The result is a market that rewards both focused technical excellence and the ability to reduce implementation risk for the buyer.
Forward Trends and Commercial Implications
Looking ahead to the next three to five years, three trends appear likely to shape commercial outcomes. The first is the continued migration of linear motors into higher-throughput automation and logistics workflows, supported by the broader push for faster changeover, reduced mechanical maintenance, and more predictable motion performance. As these systems prove themselves in repetitive, precision-sensitive tasks, adoption is likely to broaden beyond early-adopter environments and into more mainstream automation upgrades. The commercial implication is that demand will increasingly come from operators optimizing existing lines rather than only from brand-new installations, making retrofit compatibility and integration support more valuable.
The second trend is deeper embedding of safety and compliance functionality into motion platforms. As safety requirements become more explicit in high-risk automation settings, suppliers that can offer validated safety monitoring, robust feedback architectures, and clearer certification pathways will be better positioned to win projects where risk mitigation is a deciding factor. This creates an opportunity for providers to differentiate not just on force or speed, but on the trustworthiness of the entire motion chain in regulated environments.
The third trend is ongoing pressure and adaptation around material supply and cost structure. Permanent magnet dependency will continue to encourage design variation, procurement diversification, and application-specific motor selection. Commercial winners are likely to be those that can manage material exposure without sacrificing performance in their core use cases, and that can guide customers toward configurations that match actual operating needs rather than defaulting to the highest-force option in every case. At the same time, labor availability and skilled deployment capacity will remain a limiting factor in some markets, which means that ease of integration, documentation quality, and local support will increasingly influence purchase decisions.
These trends carry both opportunity and uncertainty. The upside lies in expanding use cases where precision, speed, and safety align with business priorities. The uncertainty lies in cost volatility, regulatory interpretation across regions, and the pace at which facilities can build or access the expertise needed to deploy linear motion systems effectively. Market growth will therefore be driven not just by technology readiness, but by the practicalability of organizations to absorb and operationalize it.
Linear Motion Systems Market
Strategic Actions for Decision-Makers
For manufacturers and motion system suppliers, the priority is to align product breadth with the real integration pain points of end users. That means investing not only in motor performance, but also in drive compatibility, feedback reliability, safety-related functionality, and application-oriented documentation. Differentiated value will come from reducing the time and risk required to move from specification to operational line, especially in environments where downtime and commissioning skill shortages are sensitive issues. Companies should also evaluate where portfolio diversification can protect against material volatility without diluting core performance strengths.
Linear Actuators Market
For investors, the market rewards businesses that can demonstrate repeatable deployment success and a defensible position around either precision, safety, integration, or application-specific customization. Commercial durability is increasingly tied to service networks, engineering support, and the ability to navigate material and compliance dynamics without constant margin disruption. Due diligence should therefore focus on how well a company can sustain performance in volatile input markets and how effectively it can help customers meet safety and integration requirements at scale.
For procurement and operations leaders, the practical task is to evaluate linear motor adoption as a system-level decision rather than a component swap. Total cost of ownership should account for integration effort, commissioning skill requirements, maintenance profile, and safety certification implications, not just initial hardware price. Where facilities face skilled-labor constraints, prioritizing suppliers with strong application support and proven integration pathways can reduce project risk and accelerate time to productive operation. Where performance requirements are high and safety integrity matters, the ability to meet compliance expectations within the motion system itself may be as important as raw thrust or speed specifications.
Market intelligence that captures segmentation dynamics, regional deployment patterns, application-level demand shifts, and supplier-level strategy can materially improve these decisions. Detailed income and volume trajectories, competitive positioning by segment, and scenario analysis around material costs and regulatory evolution provide the context needed to move from general market confidence to specific planning assumptions. For teams preparing capital allocation, product roadmap, or sourcing strategies, deeper structured research can help translate broad growth signals into actionable segment-level priorities and risk controls.
For detailed analysis of this topic, please visit the official page: Linear Motors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Global Vacuum Pumps Market
Market Landscape and Core Challenges
The global vacuum pumps market has demonstrated consistent expansion over the past half-decade, evolving from a niche industrial component sector into a critical enabler of advanced manufacturing and process industries. Historical data from 2020 through 2025 shows a trajectory of steady revenue accumulation, with the market crossing the $6.7 billion threshold in the base year. This growth reflects not merely cyclical demand but a structural shift in how vacuum technology is integrated into high-value production environments. Looking ahead to the 2026-2032 forecast period, the market is projected to sustain a compound annual growth rate near 5.74 percent, reaching approximately $9.9 billion by the end of the decade. This pace of expansion signals a maturing yet still dynamically growing sector, where value creation is increasingly tied to application-specific performance rather than generic equipment supply.
Beneath these aggregate figures, the market confronts several structural challenges that will define competitive outcomes over the next five years. One of the most pressing is the tension between performance requirements and sustainability mandates. End-users across semiconductor fabrication, pharmaceutical processing, and chemical refining demand higher pumping speeds, lower ultimate pressures, and greater process stability, while simultaneously facing pressure to reduce energy consumption and eliminate hazardous lubricants. This dual mandate forces manufacturers to rethink fundamental design philosophies, often requiring tradeoffs between initial capital expenditure and total cost of ownership that are difficult to justify without clear operational data.
A second challenge lies in the fragmentation of regulatory and standards environments across major geographies. Different regions are advancing divergent requirements around equipment certification, emissions control, and safety protocols. Manufacturers that operate globally must navigate overlapping compliance regimes, while regional players face the risk of losing export competitiveness if their product portfolios do not align with evolving international norms. This regulatory heterogeneity increases time-to-market for new models and raises the cost of maintaining multi-region product lines.
A third challenge emerges from supply chain volatility and component dependency. Critical subsystems such as specialized coatings, precision bearings, and control electronics remain concentrated among a limited set of suppliers. Any disruption in these upstream inputs can cascade into production delays, pricing pressure, and eroded customer confidence. At the same time, customers are increasingly scrutinizing supplier resilience and requesting transparency around sourcing strategies, adding another layer of complexity to procurement and partnership decisions.
For enterprise decision-makers, these challenges translate into a clear strategic imperative: success will depend on balancing technical differentiation with operational adaptability. Companies that treat vacuum pumps as commoditized hardware will find margins compressed by price competition and regulatory overhead. Those that embed pumps within broader process solutions, offer lifecycle performance guarantees, and maintain agile compliance frameworks are better positioned to capture premium segments of the market.
Key Demand Drivers and Structural Shifts
Technological Innovation and Application-Specific Engineering
Technological advancement remains the most potent force reshaping the vacuum pumps market. The industry has moved past the era where incremental mechanical improvements drove competitiveness. Today, differentiation comes from integrating dry pumping technologies, advanced materials, and smart control systems that optimize performance for specific operating environments. Dry vacuum solutions, in particular, have gained substantial traction in applications where contamination sensitivity, maintenance reduction, and environmental compliance are non-negotiable. The displacement of oil-sealed wet pumps in high-precision processes illustrates how technology shifts can redefine entire demand segments.
Recent industry activity underscores this trajectory. Edwards Vacuum showcased its focus on vacuum pump applications for plastics degassing at the K Show in September 2025, highlighting how vacuum technology is being adapted to improve material quality and processing efficiency in polymer manufacturing. In February 2025, The Busch Group presented its MINK MH series of vacuum pumps and blowers at the Hannover Trade Show, emphasizing modular, dry compression technology designed for flexibility across industrial processes. These demonstrations reflect a broader pattern: manufacturers are no longer competing solely on pumping capacity but on how well their equipment integrates into specific production workflows, reduces downtime, and addresses sector-specific contamination or safety requirements.
For businesses, the implication is clear. Investment in vacuum technology should be evaluated through the lens of process outcomes rather than equipment specifications alone. Decision-makers should assess whether a pump solution enables tighter process control, reduces cleaning or maintenance cycles, or supports higher throughput without compromising product integrity. Vendors that can articulate these operational benefits and provide validated performance data will increasingly capture preference in competitive procurement scenarios.
Policy, Regulatory, and Standards Evolution
Regulatory and standards developments are acting as both constraints and catalysts. In the United States, the tariff schedule under HS 84141015 has drawn attention to semiconductor vacuum pumps, particularly those associated with flat panel display manufacturing, altering cost structures and incentivizing supply chain reevaluation. Meanwhile, A2L refrigerant standards introduced in 2026 require certified spark-resistant vacuum pumps and recovery machines for HVAC applications, forcing manufacturers to update product designs and certification processes to remain eligible for servicing and installation contracts in this segment.
Automotive Vacuum Pump Market
Standards bodies are also playing a more visible role. The BSI MCE/8 committee has been developing UK input into ISO/TC112 vacuum technology standards, work that will influence how vacuum pumps are specified, tested, and compared across international markets. Concurrently, analysis from Eureka Patsnap in July 2025 pointed to vacuum pumps enhancing advanced catalytic converter production, suggesting that tightening environmental regulations around emissions control are indirectly expanding demand for high-performance vacuum equipment in automotive and industrial exhaust treatment processes.
On the safety and research infrastructure side, US BSL-3 laboratory design standards specify the use of central vacuum pumps in negatively pressurized rooms, creating a defined demand channel for specialized laboratory vacuum systems. Together, these regulatory and standards developments illustrate a market where compliance is not merely defensive but can open structured demand streams when manufacturers align their portfolios with emerging requirements early.
PW Consulting Automotive & Machinery Research Center
Strategic takeaway: monitoring regulatory calendars and standards work should be embedded into product planning and market entry strategies. Companies that anticipate certification needs, design for compliance modularity, and engage with standards committees position themselves to reduce retrofit costs and capture first-mover advantages in regulated application verticals.
Water Pumps Market
Demand-Side Shifts and End-User Behavior
End-user behavior is shifting from equipment purchase to performance partnership. Large semiconductor manufacturers, pharmaceutical producers, and chemical processors increasingly view vacuum systems as integral to yield, reproducibility, and regulatory audit readiness. This mindset drives demand for solutions that offer predictable maintenance intervals, remote monitoring capabilities, and documented process compatibility. Procurement teams are rewarding vendors that can provide application engineering support, rapid troubleshooting, and lifecycle cost transparency.
At the same time, smaller and mid-sized users are seeking compact, easy-to-integrate vacuum units that reduce installation complexity and lower operational overhead. This bifurcation is expanding the market across both premium and accessible segments, but it places pressure on manufacturers to maintain distinct product architectures and service models for different customer tiers. Failure to address both ends of this spectrum can result in lost share to specialized niche suppliers or to integrated competitors with broader solution portfolios.
Supply Chain and Cost Structure Dynamics
Cost structures in the vacuum pumps market are being reshaped by energy expectations, material costs, and the economics of after-sales service. Energy efficiency has moved from a secondary consideration to a core purchasing criterion, particularly in regions with high electricity costs or aggressive decarbonization targets. Pumps that maintain performance while reducing power draw can justify higher initial prices through lower operating expenses, but realizing this value requires trust in performance claims and access to operational data.
Material and component costs also influence pricing stability. Suppliers of precision components exert leverage over final product pricing, and fluctuations in raw material markets can compress margins if manufacturers cannot pass costs through efficiently. As a result, competitive players are investing in design standardization, strategic supplier relationships, and inventory buffering to reduce exposure. The cost of service and spare parts is equally important; customers increasingly evaluate total cost of ownership over a five-to-ten-year horizon, making service network density and parts availability significant differentiators.
For businesses, the supply chain lesson is twofold. First, evaluate vacuum pump investments with total lifecycle cost models that include energy, maintenance, downtime, and disposal or recycling considerations. Second, when selecting suppliers, assess not only product specifications but also the resilience of their component sourcing, the breadth of their service coverage, and their ability to provide consistent quality across batches and regions.
Competitive Landscape and Leading Strategies
The competitive environment in the vacuum pumps market is characterized by a moderate concentration of established players alongside a long tail of specialized and regional suppliers. With the top three firms holding roughly 45 percent of market value and the top five capturing around 57 percent, the landscape offers room for both focused differentiation and consolidation. The leading companies generally compete on a combination of technology heritage, application breadth, global service presence, and the ability to align with regional compliance requirements.
Edwards Vacuum, headquartered in Burgess Hill, United Kingdom, has built a reputation around high-performance vacuum solutions tailored for demanding process environments. Its recent activity at K Show 2025, demonstrating vacuum pump roles in plastics degassing, illustrates a strategy of aligning product demonstrations with specific industrial applications where vacuum quality directly affects end-product characteristics. This application-centric positioning helps the company move beyond generic equipment selling and into process improvement conversations with customers.
The Busch Group, based in Germany, has emphasized dry compression technology and modular product families. The February 2025 presentation of the MINK MH series at Hannover underscores a focus on flexibility, energy efficiency, and suitability for a range of industrial processes. By promoting series that can be configured for different duties, Busch targets customers who value scalability and reduced changeover complexity.
Atlas Copco, headquartered in Sweden, has reinforced its competitive standing through certification activity. In January 2026, the company obtained ISO 9001:2015, ISO 45001:2018, and ISO 14001:2015 certifications applicable to vacuum pumps production, marketing, and installation. This move signals a strategic emphasis on quality management, occupational health and safety, and environmental responsibility as elements of customer trust and global market access. Certification alignment can reduce friction in procurement evaluations, particularly for enterprise customers that require supplier compliance documentation as part of their vendor qualification processes.
Other notable players contribute to a diverse competitive field. Pfeiffer Vacuum and Leybold, both based in Germany, bring strong technical pedigrees in high-vacuum and process vacuum applications. Becker Pumps and KNF Neuberger offer specialized pump technologies for laboratory, medical, and industrial niches. Gast Manufacturing, based in the USA, maintains a presence in robust industrial vacuum solutions. VACUUBRAND focuses on laboratory and research-grade vacuum systems, while Alcatel Vacuum Technology, headquartered in France, serves segments requiring precision vacuum hardware. Together, these companies illustrate a market where specialization, regional strength, and application focus can coexist with broader-scale competition.
The market structure is evolving along two complementary paths. Consolidation is likely to continue where economies of scale in manufacturing, service networks, and R&D can be leveraged, particularly in high-volume industrial segments. At the same time, fragmentation is expected to persist or deepen in application-specific niches, where smaller firms with deep domain expertise can command premium positioning by solving narrow but critical problems. New entrants are most likely to succeed by targeting underserved application requirements, offering integrated monitoring or digital services, or providing regionally optimized cost structures that larger incumbents struggle to match without sacrificing margin.
For decision-makers evaluating vendor landscapes, the key question is not simply who is largest but who is most aligned with the application, compliance, and service requirements of the intended operating environment. Vendor assessments should weigh application engineering capability, regional certification coverage, service responsiveness, and the evidence base supporting performance claims.
Forward-Looking Trends and Commercial Implications
Trend 1: Process-Integrated Vacuum Solutions Become the Standard Expectation
Over the next three to five years, vacuum pumps will increasingly be evaluated as part of integrated process systems rather than standalone components. Customers will expect tighter coupling between pumping equipment, process controls, and monitoring analytics. This trend favors suppliers that can provide application-specific configurations, predictive maintenance features, and documentation that supports process validation. The commercial opportunity lies in moving up the value chain from equipment sales to solution provision, where revenue streams can include integration services, remote monitoring subscriptions, and performance-based maintenance agreements.
The risk associated with this trend is the requirement for deeper customer-facing engineering resources and data infrastructure. Suppliers that lack the capability to support integration and lifecycle services may find themselves competing primarily on initial price, a position that erodes profitability over time.
Trend 2: Sustainability and Efficiency Criteria Reshape Procurement Priorities
Energy efficiency, lubricant-free operation, and reduced maintenance burdens will become more prominent in purchasing decisions. Regulatory pressures and internal sustainability goals are pushing end-users to evaluate vacuum systems through operating cost and environmental impact lenses. Dry pump technologies and designs that minimize power consumption while maintaining process performance are well positioned for adoption in relevant segments. Manufacturers that can quantify energy savings, maintenance reductions, and waste reduction benefits will have stronger value propositions in competitive bids.
However, quantifying and communicating these benefits requires credible measurement methodologies and sometimes long-term validation. If claims are not backed by transparent data or if actual operating conditions diverge significantly from benchmark scenarios, customer trust can be damaged and future sales affected.
Trend 3: Regulatory and Standards Alignment Become Strategic Levers
As regulatory requirements and standards work continue to evolve across regions, companies that proactively align product development with emerging specifications will gain advantages in market access and customer qualification speed. The interplay of tariff considerations, refrigerant standards, laboratory safety norms, and international vacuum technology standards creates a landscape where compliance readiness can be a competitive differentiator. Firms that invest early in certification, design modularity for regulatory adaptation, and engagement with standards processes can reduce time-to-market for compliant products and lower the risk of retroactive redesigns.
The uncertainty here stems from the pace and direction of regulatory changes. Shifting requirements can alter cost structures or create temporary demand spikes for compliant equipment, but they can also raise barriers for suppliers with less flexible development processes. Businesses should treat regulatory forecasting as an ongoing input to product planning rather than a periodic compliance exercise.
Strategic Actions for Decision-Makers
For manufacturers and technology developers, the near-term priority is to sharpen application focus while maintaining enough architectural flexibility to adapt to regulatory and standards changes. Prioritize investments in dry and energy-efficient technologies where application sensitivity and operating cost pressure are highest. Strengthen application engineering and service capabilities that help customers realize performance benefits after installation, because post-sale performance realization increasingly influences repeat business and reference value. Where possible, design product families with modular compliance features so that regional certification or safety requirements can be met without full redesign cycles.
For investors, due diligence should extend beyond revenue growth projections to examine how well portfolio companies are positioned for the shift toward integrated solutions and lifecycle services. Assess exposure to regulatory-sensitive applications, the strength of service networks, the resilience of component sourcing, and the credibility of efficiency or sustainability claims. Companies with clear application differentiation, documented process value, and adaptable compliance strategies are generally better placed to defend margins and capture growth as the market expands toward the 2032 horizon.
For procurement and operations leaders, the emphasis should be on total cost of ownership modeling and vendor qualification that reflects modern usage requirements. Evaluate candidates not only on pumping specifications but also on energy performance, maintenance intervals, parts availability, regional certification coverage, and the quality of application support during commissioning. Where process sensitivity is high, request validated performance data under conditions that resemble actual operating environments. Building a shortlist based on lifecycle economics and service resilience can reduce operational risk and improve long-term reliability.
Given the pace of technological, regulatory, and application-level change, timely access to detailed segment data, competitive benchmarks, and scenario analysis can materially improve decision quality. A comprehensive research report can provide deeper segmentation views, regional breakdowns, company-level profiling, and procurement-relevant comparisons that go beyond the strategic themes discussed here. For teams working on market entry, capacity planning, vendor selection, or investment allocation, engaging with detailed market intelligence offers a practical way to reduce uncertainty and align strategy with the evolving structure of the vacuum pumps market.
For detailed analysis of this topic, please visit the official page: Vacuum Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Robot Tool Changers Market 2026: The Real Drivers Behind a 13.81% Growth Trajectory
By PW Consulting, 2026-09-21
The Strategic Shift in Robot Tool Changers: Navigating a High-Growth Market
Market Overview: A Sector Accelerating Under Industrial Automation Demand
The global market for robot tool changers has entered a phase of sustained expansion, driven by the broader adoption of industrial automation and the increasing need for flexible manufacturing systems. Valued at approximately 543.55 million USD in 2025, the market has demonstrated consistent growth over the past five years, rising from 284.67 million USD in 2020. This trajectory reflects a compound annual growth rate of 13.81 percent through 2032, signaling that tool changing systems are no longer peripheral components but strategic enablers of production efficiency. The market is projected to reach 1.35 billion USD by 2032, a figure that underscores the compounding effect of automation investments across multiple sectors.
This growth is not uniform across all geographies or applications. Demand is concentrated in regions with mature automation ecosystems and in industries where rapid changeover times directly impact throughput. The current market structure reflects a balance between established industrial robotics hubs and emerging manufacturing centers that are integrating robotic cells at an accelerating pace. While the numbers illustrate a clear upward path, the underlying dynamics reveal a market that is selectively rewarding players who can align product capabilities with shifting operational requirements.
Two structural shifts are reshaping the competitive baseline. First, the transition from fixed, single-purpose end-of-arm tooling toward modular, quickly interchangeable systems is becoming a default expectation rather than a premium feature. Second, the integration of tool changing mechanisms with collaborative robots and light automation cells is expanding the addressable use cases beyond traditional heavy manufacturing. These shifts are forcing suppliers to reconsider design priorities, safety alignment, and deployment speed.
Key Challenges and Inflection Points
Despite the favorable growth outlook, the market faces operational and strategic tensions that will determine which participants capture disproportionate value. Three challenges stand out as particularly consequential for decision-makers evaluating this space.
Safety Standardization as a Compliance and Design Gatekeeper
Updated global safety requirements, including ISO 10218-2:2025 for industrial robot systems and the continued relevance of ANSI/RIA R15.06-2012 Part 2 for completed machinery integration in the United States, are reshaping how tool changers are specified and deployed. These standards are not merely documentation exercises; they influence interface design, fail-safe behavior, detection of unintended contact, and system-level integration. Manufacturers that treat compliance as an afterthought risk costly redesign cycles, slower qualification processes, and reduced appeal to OEMs seeking plug-and-play compatibility. Conversely, suppliers that embed safety alignment into product architecture can shorten customer validation timelines and strengthen positioning in regulated environments such as medical device production, food processing, and automotive assembly.
Cost Pressures and Regional Supply Chain Realignment
Tool changer manufacturers are navigating a cost environment shaped by component pricing volatility and shifting trade dynamics. U.S. tariff policies, for example, are prompting localized supply chain adjustments among major manufacturers of robotic components. This restructuring affects lead times, sourcing strategies, and the economics of cross-border distribution. Companies that rely heavily on single-source components or centralized production footprints may face margin compression or delivery uncertainty. At the same time, customers are increasingly sensitive to total cost of ownership, including maintenance, downtime during changeovers, and the speed with which a new end-effector can be deployed. The market is therefore moving toward an environment where reliability and serviceability are as commercially important as the initial purchase price.
Balancing Automation Gains with Practical Deployment Complexity
A recurring tension in this market is the gap between the promise of faster changeovers and the reality of integration effort. Automatic tool changers can reduce manual intervention and improve cycle consistency, but they also introduce requirements around alignment, actuation reliability, air and electrical pass-throughs, and control coordination. For many mid-sized manufacturers, the decision is not simply whether to adopt automation but how much complexity they are prepared to absorb. This creates a split in demand: some buyers prioritize fully automatic solutions with integrated sensing and robust retention features, while others opt for manual or semi-automatic systems that are easier to retrofit and maintain. Suppliers that can reduce deployment friction, whether through modular configurations, clear compatibility roadmaps, or application-specific guidance, are better positioned to convert interest into installed base growth.
PW Consulting Automotive & Machinery Research Center
Core Drivers of Market Change
The expansion of the robot tool changer market is being propelled by a combination of technological progress, regulatory evolution, demand-side behavior, and supply chain restructuring. Understanding these drivers individually and in combination provides a clearer view of where growth is likely to concentrate.
Technological Innovation and Payload Flexibility
Product development is increasingly focused on broadening payload compatibility, improving retention reliability, and simplifying integration. Automatic systems are being designed with ISO-standard flange compatibility and modular configurations, allowing them to serve a wider range of robot platforms without extensive custom engineering. Pneumatic actuation remains a practical choice for many applications, especially where simplicity and robustness are valued, while sensing and end-effector accessories are increasingly used to support precision tasks and force-sensitive operations. The introduction of automatic tool changer lines aimed at reducing manual changeovers in machine tending automation illustrates how suppliers are targeting the practical pain points of repetitive loading and unloading. These developments matter because they lower the barrier to re-tooling and help manufacturers shift from dedicated single-product cells to more adaptable layouts.
Regulatory and Safety Environment
The regulatory backdrop is both a constraint and a catalyst. As safety requirements become more explicit and harmonized, customers are paying closer attention to certified integration paths and documented performance under failure conditions. This environment favors suppliers that can demonstrate consistent quality, traceable manufacturing practices, and alignment with recognized robot system standards. In practice, safety compliance is becoming part of the commercial argument: it reduces risk for integrators, supports faster approval in regulated industries, and can differentiate products in tenders where system reliability is a priority. The effect is most visible in sectors where uptime and repeatability are closely tied to product quality and audit readiness.
Demand-Side Behavior and Workforce Dynamics
On the demand side, manufacturers are responding to chronic labor shortages, the need for faster changeovers, and the desire to redeploy assets as product mixes change. Tool changers enable robots to switch between tasks without extensive downtime, which is particularly valuable in environments where batch sizes vary or where multiple operations are consolidated into a single cell. Collaborative robot applications are also expanding the user base, since lighter and more flexible tooling solutions can be introduced in spaces where traditional industrial robots would be impractical or overly complex. This demand behavior is widening the market beyond large-scale automotive and electronics operations into chemical processing, medical manufacturing, and food and beverage production, where hygiene, precision, and quick reconfiguration are increasingly important.
Supply Chain and Cost Structure Evolution
Supply chain dynamics are influencing both product strategy and customer purchasing behavior. As manufacturers of robotic components adjust to new tariff and sourcing realities, there is growing interest in regional availability, shorter logistics paths, and locally supported service networks. For tool changer suppliers, this creates an opportunity to compete not only on product features but also on responsiveness and continuity of supply. Customers in turn are weighing the stability of their supplier relationships more heavily, especially when a tool changer is embedded in a production line where downtime has a direct financial impact. The result is a market where service coverage, spare parts availability, and local engineering support can be decisive factors in winning and retaining business.
Competitive Landscape and Strategic Positioning
The robot tool changer market is moderately concentrated, with a small group of established players accounting for a significant share of revenue. This concentration reflects the importance of product maturity, application knowledge, and long-term customer relationships in a segment where reliability and compatibility are paramount. At the same time, the landscape is evolving as suppliers differentiate around payload class, actuation method, collaborative robot compatibility, and deployment speed.
Several companies illustrate distinct strategic approaches. Stäubli has positioned its offering around automatic tool changers with defined payload capacity and modular configurations, emphasizing compatibility with industrial robots and standardized flanges. Zimmer Group provides a broader portfolio that spans automatic, manual, pneumatic, and magnetic solutions, aligning its product range with the need for manufacturing flexibility and productivity across different operating environments. SCHUNK continues to emphasize pneumatically actuated automatic tool changers with integrated retention features for air-loss scenarios, alongside quick-change systems that support faster changeovers. These design choices reflect a shared focus on robustness and practical reliability, but they also reveal different priorities in how each company addresses failure modes and integration complexity.
In the collaborative and lighter-automation segment, other players have carved out niches by focusing on ease of deployment and end-of-arm tool compatibility. SMC Corporation manufactures pneumatic tool changers and grippers suited to collaborative robots and broader automation systems, while Destaco develops cobot end-of-arm tools and manual changeovers with pass-through air and electric ports for materials handling and manufacturing tasks. Robot System Products offers a tool changer family tailored to collaborative robots with automated exchange capabilities, and SmartShift Robotics promotes a universal tool changer system designed for fast deployment and redeployment of tools on robots. ATI Industrial Automation rounds out this competitive picture by specializing in robotic tool changers, multi-axis force and torque sensing, and end-effector accessories for industrial applications, highlighting the increasing importance of sensing and precise control in higher-value use cases.
Worldwide Tool Changers Market
The strategic lesson from this landscape is that differentiation is increasingly tied to the intersection of product design and deployment experience. Companies that combine compatible mechanical interfaces with clear guidance on integration, safety alignment, and maintenance are better positioned to win across both large industrial accounts and smaller automation projects. At the same time, the market shows signs of both consolidation and fragmentation. Incumbents with broad portfolios can leverage cross-selling and entrenched relationships, while smaller or more focused players can win in specific applications by addressing changeover speed, collaborative robot fit, or rapid redeployment needs. New entrants and product-line expansions are likely to persist as long as demand continues to grow and as long as manufacturers seek tools that can be adapted quickly to changing production requirements.
Recent Developments as a Signal of Direction
Recent activity in the market reinforces the emphasis on practical changeover reduction and machine tending automation. In May 2025, SCHUNK USA promoted its CPS automatic tool changer line as a solution for manual changeovers in machine tending automation. This type of development is notable because it targets a recurring operational bottleneck rather than a purely niche application. It also signals that automatic changeover systems are being marketed not only as high-end industrial upgrades but as accessible improvements for repetitive machine tending tasks. For competitors and buyers alike, such announcements highlight where commercial attention is moving: toward reliability in routine use, reduced intervention, and solutions that can be integrated without extensive reconfiguration of existing equipment.
Future Trends and Commercial Implications
Looking ahead to the next three to five years, three trends are likely to shape how the robot tool changer market evolves and where commercial opportunities emerge.
Trend 1: Broader Adoption of Automatic Changeover in Mid-Complexity Applications
Automatic tool changers will increasingly move beyond the largest, most heavily engineered installations and into mid-complexity environments where changeover frequency and labor constraints make manual intervention costly. As modular interfaces and standardized compatibility become more common, the effort required to specify and integrate automatic systems should decline. The commercial opportunity here lies in application-specific packages that address machine tending, light assembly, and repetitive load/unload tasks with minimal customization. The risk is that overstating automation benefits without accounting for integration readiness could lead to slower adoption in settings where maintenance capacity or control integration is limited.
Trend 2: Safety and Compliance as a Competitive Filter
Updated safety expectations will continue to act as a filter in procurement decisions, especially in regulated industries and in projects that require integration with completed machinery. Suppliers that proactively align product design with current standards and that can provide clear documentation and integration support will have an advantage in qualification speed and customer confidence. This trend creates opportunity for companies that can package compliance, reliability, and ease of integration into a coherent value proposition. The uncertainty lies in how quickly standards are adopted across regions and customer segments, since uneven uptake may create temporary fragmentation in approval requirements and system specifications.
Automatic Tool Change Spindle Market
Trend 3: Regional Supply Strategies and Service-Led Competition
As manufacturing of robotic components adjusts to tariff and sourcing pressures, regional availability and service continuity will become more important in supplier selection. Tool changer providers that can offer localized support, predictable lead times, and accessible spare parts will be better positioned to retain customers in cost-sensitive or uptime-critical environments. This trend favors businesses that treat after-sales capability as part of the core offering rather than a secondary function. The risk is that supply chain restructuring could temporarily disrupt availability or increase costs during transition periods, which may affect both suppliers and end users that depend on steady component flow.
Strategic Implications for Decision-Makers
For executives, planners, and investors evaluating this market, the most useful question is not whether growth will continue, but where the most defensible value can be created. The following considerations can help translate market dynamics into action.
For Manufacturers and System Integrators
- Prioritize compatibility and standardization in tooling selection. Systems that align with common flanges, actuation methods, and control interfaces reduce integration risk and make future reconfiguration easier.
- Treat safety alignment and documentation as part of product design rather than a final checklist. This can shorten qualification cycles, improve integrator confidence, and support expansion into regulated applications.
- Evaluate total cost of ownership beyond purchase price, including downtime during changeovers, maintenance complexity, and the speed of redeployment when production needs shift.
For Investors and Strategic Planners
- Pay attention to companies that combine product breadth with strong application support and service coverage, since these attributes tend to drive repeat business and reduce switching in a concentrated market.
- Monitor how suppliers are positioning around collaborative robots, machine tending, and quick redeployment, as these areas are expanding the user base beyond traditional heavy industrial automation.
- Assess exposure to regional supply chain shifts and component sourcing strategies, because tariff and logistics responses can influence margins, delivery reliability, and competitive positioning over time.
For Procurement and Operations Leaders
- Define requirements around changeover frequency, payload, failure-mode behavior, and integration constraints before evaluating specific products, so that selection reflects operational realities rather than feature lists alone.
- Consider how easily a tool changer can be maintained, recalibrated, and redeployed, especially if future production programs are expected to vary in scope or volume.
- Validate supplier support capabilities, including spare parts availability and engineering responsiveness, since service continuity can be as important as initial performance in production-critical environments.
Conclusion
The robot tool changer market is expanding in line with the broader shift toward flexible automation, but the real strategic story lies in how that growth is being shaped by safety requirements, deployment complexity, and supply chain adjustments. Over the next several years, value will likely accrue to suppliers and adopters who can combine mechanical reliability with practical integration, compliance readiness, and dependable support. For decision-makers, the most effective approach is to treat tool changing systems as long-term operational assets rather than interchangeable accessories, and to evaluate them against the specific changeover, payload, and integration demands of each application. Continued attention to product evolution, regulatory alignment, and regional supply dynamics will be essential for those seeking to capture the commercial opportunities embedded in this accelerating market. More granular segmentation, competitive benchmarking, and scenario analysis are available in the full market report for teams that need detail beyond the strategic overview.
For detailed analysis of this topic, please visit the official page: Robot Tool Changers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


