



Category: Machinery & Automotive
PW Consulting: Aviation Oxygen Systems Market (Base Year 2025) Poised to Hit USD 9,010.13 Million by 2032 at a 6.8% CAGR (2026–2032) — North America Leads with USD 2,126.23M
By PW Consulting, 2026-07-06
PW Consulting: Strategic Brief — Aviation Oxygen Systems Market Outlook 2026 (Executive Trailer)
As airlines, OEMs, defense integrators, and aftermarket players finalize budgets and capital plans for 2026, the aviation oxygen systems market presents a mix of steady expansion, regulatory-driven churn, and concentrated competitive dynamics. PW Consulting’s forthcoming full-length market study — based on a 2025 base year and a 2026–2032 forecast horizon — synthesizes macro growth, regulatory inflection points, and tactical go-to-market playbooks that executives will need to convert opportunity into defensible revenue and margin streams.
Aviation Oxygen Systems Market
Macro snapshot: measured growth, durable upside
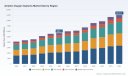
The global aviation oxygen systems market has demonstrated resilient recovery and multi-year expansion. From a market size of approximately USD 4.12 billion in 2020, the industry reached roughly USD 5.69 billion by the 2025 base year and is projected to surpass USD 9.01 billion by 2032. That trajectory corresponds to a compound annual growth rate (CAGR) in the mid-single digits — 6.8% in our core forecast — underpinned by fleet renewals, increased regulatory scrutiny of portable breathing equipment (PBE) and oxygen delivery devices, and broader aftermarket spending on life‑support systems.
Aviation Oxygen Systems Market
For strategy teams planning resource allocation in 2026, this is neither a hypergrowth story nor a static, commoditized market: it is a steady expansion with episodic regulatory and technology-driven windows that reward timely investment in MRO capacity, product compliance, and integrated system offerings.
Aviation Oxygen Systems Market
Why this matters for 2026 decision cycles
- Budget prioritization: With a predictable growth path and clear regulatory vectors, CFOs can justify targeted CapEx for certification and MRO expansion while preserving optionality for inorganic growth.
- Product roadmap alignment: R&D and product leaders should synchronize next‑generation offerings — from pulse‑dose delivery and low‑weight cylinder tech to on‑board oxygen generation systems (OBOGS) for specific platforms — with the regulatory calendar and fleet modernization timelines.
- Aftermarket and service-led differentiation: As operators seek to de-risk in-flight safety and reduce ground time, MRO and service contracts will be a major driver of aftermarket revenues in 2026 and beyond.
Regulatory environment: the near-term gating items
Regulation is an active and structural market force in aviation oxygen systems. Recent airworthiness directives and operational mandates affecting portable breathing equipment and maintenance practices have increased the compliance burden for operators and suppliers. FAA requirements for supplemental oxygen use by crew and for passenger oxygen deployment at defined flight levels remain foundational constraints that drive both equipment specifications and training/MRO cycles.
Additionally, oxygen purity and cylinder maintenance standards (including hydrostatic testing intervals) create recurring demand for certified repair stations, spare parts, and replacement units — all categories with differentiated margin profiles. These regulatory realities mean that companies that can demonstrate rigorous process control, documented traceability, and quick compliance turnarounds will capture outsized share in the aftermarket.
Competitive landscape — concentrated but dynamic
The market exhibits moderate concentration: the top three firms control a meaningful share of industry revenues, and the top five reach a clear majority. That structure creates a two-speed competitive field: larger incumbents focus on systems integration, OEM partnerships, and defense contracts, while agile specialists compete on niche products, aftermarket service, and certification speed.
- Aerox Aviation Oxygen Systems (Bonita Springs, FL) — strong footprint in portable and installed solutions plus recent MRO expansion through acquisition activity. Their move into certified repair capabilities materially alters their service economics and shortens lead times for operators.
- Safran Aerosystems Oxygen (AVOX Systems) (Lancaster, NY) — a global designer/manufacturer with a long legacy in passenger and crew oxygen hardware; recent regulatory actions impacting certain PBEs have elevated the visibility of their product family across operators and regulators.
- Collins Aerospace (RTX) (Charlotte, NC) — leverages scale in integrated cabin systems and PSU/oxygen integration, a go‑to partner for large commercial platforms where cross‑system integration wins contract awards.
- Precise Flight, Mountain High, Meggitt/Parker, Honeywell Aerospace — each firm brings domain specialization, from general aviation pulse‑demand systems to military OBOGS and modular airborne oxygen systems; these players are the primary competition in niche and mission‑critical segments.
Recent industry developments illustrate how competitive and regulatory events can immediately re‑rank suppliers. Notably, MRO capability expansion via acquisition and airworthiness directives targeting portable units have both reshuffled attention and created short‑term replacement demand. For market entrants and incumbents alike, those dynamics translate to concrete pressures: the need to prove compliance, maintain parts inventories, and manage certification pathways efficiently.
Report highlights — what the full study delivers (practical, executable content)
PW Consulting’s full report is intentionally operational. It is built for strategic and commercial teams that must make executable decisions in 2026 rather than academic forecasts. The core deliverables include:
- Proprietary market sizing and forecast model (2020–2032) with scenario toggles for fleet renewal pace, regulatory shock events, and defense procurement cycles;
- Risked financial archetypes for OEMs, MRO operators, and aftermarket suppliers that quantify unit economics, service margins, and inventory/certification capital requirements;
- Regulatory impact mapping that translates airworthiness directives and oxygen purity/maintenance rules into product‑level compliance roadmaps and time‑to‑market implications;
- Supplier capability matrix and sourcing playbook covering certification speed, geographic service coverage, lead times, and strategic MRO partnerships;
- Go‑to‑market options for both incumbents and new entrants: value‑based pricing models, bundled service contracts, digital monitoring/telemetry for predictive maintenance, and aftermarket growth strategies;
- Execution checklists for 100‑, 365‑ and 1,000‑day planning horizons to operationalize actions across R&D, regulatory, supply chain, and commercial teams;
- Downloadable data tables and an interactive dashboard supporting custom scenario analysis for board presentations and investment committees.
To preserve competitive confidentiality, the public executive summary intentionally omits the granular geographic and application splits — these are available in the full dataset and model package on the PW Consulting portal.
Strategic imperatives for each leadership agenda in 2026
- CEO/Board: Treat MRO capabilities and certification velocity as strategic assets. Consider tuck‑in acquisitions or partnerships that reduce time‑to‑service and widen addressable aftermarket.
- CFO: Reframe CapEx to include certification pipelines and inventory buffers for critical oxygen components. Evaluate service subscription and extended warranty structures to smooth revenue seasonality.
- Head of Product/R&D: Prioritize low‑weight, low‑cost pulse‑demand solutions for general and business aviation while accelerating resilience and fail‑safe designs for crew and military systems. Build certification milestones into product timelines.
- Commercial/Sales: Offer bundled compliance packages (equipment + installation + documentation + scheduled hydrostatic testing) to convert regulatory pain into recurring revenue.
- Supply Chain: Secure dual sources for critical components; optimize cylinder lifecycle management; and partner with certified repair stations to reduce lead times.
Opportunities and risks — a pragmatic view
- Opportunities: Aftermarket services, MRO, and compliance upgrades generate higher margin and recurring revenues; integrated systems (e.g., oxygen + PSU integration) create defensible OEM relationships; technology upgrades (OBOGS, smarter regulators) unlock premium pricing.
- Risks: Regulatory actions can create one‑off replacement demand but also raise certification costs and product obsolescence risk; supply chain fragility for specialty cylinders and valves can disrupt delivery schedules; consolidation among top suppliers can intensify procurement competition for smaller players.
How to use this study in 2026 planning
Executives should use the PW Consulting report to calibrate three decisions before the H1 2026 budget freeze:
- Which product lines receive accelerated investment (R&D and certification) versus which are transitioned to third‑party MRO partners?
- What service bundles and subscription pricing structures to pilot in Q2–Q3 2026 that convert regulatory compliance into recurring revenue?
- Which acquisition or partnership targets (MRO networks, certified repair stations, telemetry providers) to prioritize in order to reduce time‑to‑market and expand aftermarket control?
Next steps — where PW Consulting adds immediate value
PW Consulting offers an executive briefing package and bespoke scenario workstreams designed for rapid integration into 2026 planning cycles. Options include a 90‑minute board briefing, a custom five‑year P&L stress test with your product mix, and a certification acceleration playbook tailored to your manufacturing footprint.
Note: The public executive trailer is intentionally high‑level. The full report includes the granular market model, country and application splits, unit‑level cost assumptions, and a log of regulatory notices. Those datasets are essential for precise revenue forecasting, bid pricing, and capital allocation and are available to licensed subscribers.
Final thought
The aviation oxygen systems market in 2026 will reward disciplined operators who can marry technical compliance with aftermarket service excellence. With a clear mid‑single digit CAGR and predictable regulatory cycles, the path to differentiated returns is through certification velocity, service integration, and nimble supply chain management. PW Consulting’s full report equips leaders to make those choices with confidence — and converts regulatory complexity into strategic advantage.
For detailed analysis of this topic, please visit the official page: Aviation Oxygen Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Open Hole Packers Market to Expand at a 7.52% CAGR Through 2032
By PW Consulting, 2026-07-06
Open Hole Packers Market 2026 Strategic Preview — PW Consulting Insight Brief
Executive summary
As companies finalize 2026 budgets and strategic roadmaps, the Open Hole Packers market demands a recalibrated approach. PW Consulting’s latest market study — built on a 2020–2025 historical base and a 2026–2032 forecasting framework — shows a resilient recovery trajectory and a sustained growth profile driven by completion activity, technological substitution, and new energy end‑uses. The global market expanded materially through 2020–2025 and, with a 2026–2032 compound annual growth rate (CAGR) of 7.52%, is forecast to continue growing meaningfully through 2032. Our work quantifies that momentum, highlights where returns will concentrate, and—by design—preserves granular subsegment data for licensed subscribers seeking transaction‑grade diligence.
Open Hole Packers Market
Why this matters for 2026 planning
-
Capital allocation: Vendors and operators face choices between incremental product enhancements and larger bets on next‑generation chemistries and mechanical systems. Our analysis maps likely capex and opex tradeoffs and identifies where incremental spend is most likely to preserve or expand margins under multiple commodity and tariff scenarios.
Open Hole Packers Market -
Procurement strategy: Supply chain disruption and rising input costs — notably tariffs on OCTG and step‑up pressure on steel — will compress build‑to‑buy tradeoffs. We model supplier consolidation outcomes and provide procurement playbooks that are implementable within single procurement cycles.
Open Hole Packers Market -
Technology transition: From swellable elastomers to cementitious swell materials and expandable metal solutions, the next three years will see a bifurcation between proven hydraulics/mechanics and emergent solutions optimized for long‑life integrity and geothermal applications. Our scenario work helps prioritize pilots vs. scaled rollouts.
Market trajectory and structural characteristics
After a period of volatility in the early 2020s, the market reached a new baseline by 2025. PW Consulting’s topline projection shows meaningful expansion to 2032 under the central case, reflecting both traditional hydrocarbon completion cycles and nascent growth from non‑conventional applications (including geothermal). Importantly, the market is moderately concentrated: the top three participants account for just over half of industry revenue, and the top five capture a clear majority of value. That structure creates both stability and competitive friction — advantaging established OEMs while opening windows for focused challengers with differentiated technical propositions or lower total cost of ownership.
Competitive landscape — what to watch in 2026
Our competitive landscaping in the report profiles incumbent majors, independents, and specialist OEMs. Key strategic takeaways for 2026 include:
-
Broadservice integrators: Global service companies that bundle packer systems into completion suites will continue to leverage installed customer relationships and integrated field engineering to defend premium positions. Their playbook emphasizes reliability guarantees, logistics integration, and contractual frameworks that shift some performance risks to vendors.
-
Product specialists: Firms focused on specific technologies—swellable elastomers, inflatable systems, or hydraulic set designs—remain attractive targets for operators pursuing performance optimization in niche well architectures. These vendors can command margin premia when paired with rigorous field validation and service support.
-
Innovators and new entrants: Recent technical advancements (e.g., cementitious swell packers and high‑compression open hole designs tested for specific well diameters) underline the potential for rapid capability shifts. Companies that demonstrate field‑validated performance and predictable deployment economics will create buyer urgency and potential acquisition interest from larger service providers.
-
Geothermal and energy transition alignment: Projects adapting open hole packer systems for high‑temperature geothermal environments are an increasingly important differentiator. Suppliers that invest early in materials and testing for sustained high‑temperature performance will open incremental demand outside conventional oil and gas cycles.
Recent technical and market developments shaping 2026 decisions
-
Cementitious swell packers: Industry‑led work introduced at a prominent conference in late 2025 presents an alternative path to conventional elastomeric swells. This innovation promises improved long‑term integrity in select well conditions; however, it requires different installation practices and validation protocols. Operators should budget for controlled pilots and develop contractual acceptance criteria tied to downhole performance metrics.
-
High‑performance compression packers: Laboratory and field test publications in 2025 demonstrate optimized designs for larger diameter wells. These designs reduce staging complexity in some multistage operations but require adaptation of rig and completion tooling standards. Early adopters may realize cycle time reductions; widespread adoption will hinge on standardized connection systems and training programs.
-
Geothermal applications: Multi‑stage systems tailored for geothermal demonstration projects are moving from R&D to staged field deployments. Manufacturers and service companies engaging early with geothermal operators position themselves for a potentially high‑margin new end market as projects scale.
-
Input cost dynamics and tariffs: Policy changes and commodity price moves — including tariff actions that elevated OCTG import costs and upward pressure on hot‑rolled coil prices in 2025 — materially affect manufacturing economics. Our report quantifies break‑even sensitivity and offers hedging and sourcing strategies to mitigate near‑term margin erosion.
Operational intelligence: what’s in the report (practical, actionable content)
PW Consulting’s full report is structured for immediate operational use by strategy, procurement, R&D, and business development teams. Key practical deliverables include:
-
Market sizing and validated forecasting model — with scenario toggles for demand, capex cycles, and raw material shocks.
-
Supplier benchmarking and vendor risk matrix — covering technical capability, field support footprint, and manufacturing resiliency.
-
Procurement playbooks — negotiation levers, contract structures, and total cost of ownership templates for multi‑year supply agreements.
-
Technology adoption roadmap — recommended pilot designs, test acceptance criteria, and go/no‑go gates to de‑risk scale deployment.
-
Regulatory and tariff impact assessment — modeling the P&L and cash flow implications of tariff scenarios, and recommended mitigation levers.
-
M&A and partnership screening — target archetypes, valuation sensitivities, and integration risk checklists for 2026 transactions.
-
Case studies and field data summaries — anonymized operational results that illustrate performance deltas across major technology choices.
Risk factors and sensitivity analysis
Our sensitivity analysis makes clear that three levers will most strongly influence outcomes in 2026: commodity and input‑cost variance (notably steel), completion activity levels driven by oil and gas capex and alternative energy projects, and the pace of technology acceptance following field pilots. Tariff and raw material scenarios tested in the report demonstrate asymmetric impacts across supplier types — advantaging vertically integrated players in some scenarios and nimble, localized manufacturers in others.
Strategic prescriptions for executives
-
Operators: Prioritize selectivity in pilot deployment; require standardized performance KPIs and incentivize suppliers with risk‑share contracts that link fees to measurable downhole outcomes.
-
Vendors: Invest in modular designs and scalable manufacturing lines to reduce exposure to single‑point material price shocks. Strengthen service propositions and logistics capabilities to convert product differentiation into contractual stickiness.
-
Investors and M&A teams: Focus on targets that combine differentiated IP with demonstrable field validation and either a clear path to scale or a defensible niche in geothermal or high‑temperature completions.
Conclusion — the strategic value of the PW Consulting report
For leaders preparing decisions in 2026, the most valuable intelligence is actionable, scenario‑tested, and vendor‑aware. PW Consulting’s Open Hole Packers market study blends forward‑looking forecasting with implementation tools — from procurement playbooks to technology roadmaps — enabling teams to move from insight to execution quickly. While this brief highlights the strategic themes and high‑level market trajectory, our licensed report contains the transaction‑grade datasets, regional and application splits, and company‑level matrices necessary for underwriting deals and operational rollouts.
Next steps
To access the full suite of models, regional and application breakdowns, and proprietary company profiles that support these recommendations, please visit PW Consulting’s report portal or contact our advisory team to schedule a briefing. The 2026 planning window will reward disciplined pilots, tightened supplier agreements, and early moves into non‑traditional applications — those who act with calibrated speed and data will capture the outsized returns embedded in the market’s growth trajectory.
For detailed analysis of this topic, please visit the official page: Open Hole Packers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Industrial Valves & Actuators Market to Surge to USD 231.04 Billion by 2032, Backed by a 5.45% CAGR
By PW Consulting, 2026-07-06
Industrial Valves and Actuators Market 2026: A Strategic Preview for Corporate Decision-Makers
As capital budgets tighten and supply chains recalibrate in 2026, industrial players face complex choices about where to invest, which partnerships to pursue, and how to future‑proof product portfolios. PW Consulting’s latest Industrial Valves and Actuators Market study — anchored on a 2025 base and projecting through 2032 — distills the competitive, commercial, and operational signals executives need to make those choices with confidence.
Industrial Valves And Actuators Market
Market Snapshot — The Big Picture You Must Keep in Sight
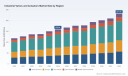
The sector has shown resilient growth across the 2020–2025 historical window and continues on an upward trajectory into the forecast period. Our model starts from a robust 2025 base and projects the market forward at a steady compound annual growth rate of 5.45% through 2032. Under our central case the market climbs materially across the decade, reflecting continued demand for automation, electrification of actuation, and heavy investment in infrastructure and energy transition projects.
Industrial Valves And Actuators Market
Two concentration metrics also matter for strategic positioning: the three‑firm concentration ratio (CR3) and five‑firm concentration ratio (CR5) sit at approximately 28.5% and 41.8% respectively — an industry structure that combines global platform players with a long tail of specialized, regional and service‑oriented firms. That dynamic creates distinct opportunities for scale players to capture system solutions and for niche vendors to monetize expertise and aftermarket services.
Industrial Valves And Actuators Market
Why This Report Matters for 2026 Decision Cycles
- Capital allocation and portfolio strategy. With steady market growth but mounting input‑cost pressures, the report provides the evidence base you need to prioritize R&D, electrification programs, and aftermarket investments over low‑margin OEM commoditization.
- Supply chain and sourcing optimization. Elevated steel pricing and durable tariffs on hot‑rolled coil have reset the math for where to source castings and machined bodies. Our scenarios quantify the sensitivity of margins to raw‑material inputs and offer practical hedging and nearshoring strategies.
- M&A and alliance screening. The market’s moderate consolidation metrics and recent strategic transactions create windows for bolt‑on acquisitions and platform expansion. The study identifies the target profiles that most improve scale or technical breadth.
- Commercial and pricing playbooks. As buyers seek digital integration and lower lifecycle cost, the report maps the willingness‑to‑pay curve for smart actuation, service contracts and retrofit offerings, enabling differentiated pricing strategies.
- Risk and compliance planning. Regulatory shocks and trade policy shifts are now recurring strategic risks; our analysis translates these into quantified scenarios to stress‑test investments and manufacturing footprints.
What’s Inside the Report — Practical, Execution‑Oriented Deliverables
Designed for C‑suite and business‑unit leaders, the PW Consulting study balances rigorous forecasting with concrete operational playbooks. Key deliverables include:
- Proprietary market model and scenario suite (base, upside, downside) through 2032, with sensitivities for commodity pricing, electrification adoption, and capital market cycles.
- Go‑to‑market frameworks for OEMs and aftermarket service providers, including customer segmentation, margin waterfalls, and channel economics.
- Manufacturing footprint decision tool that evaluates total landed cost, tariffs exposure, lead time targets, and service coverage trade‑offs.
- Technology adoption roadmaps that quantify near‑term opportunities from electric actuators, digital actuators, and integrated valve‑instrumentation packages, plus guidance on product platform rationalization.
- Supply‑chain playbook addressing index‑based commodity contracts, strategic inventory policy, and supplier qualification standards for high‑value components.
- Deal origination templates and valuation heuristics tailored to valves and actuation assets, supporting rapid screening of acquisition targets.
- Operational best practices for aftermarket growth — warranty design, remote diagnostics commercialization, and parts log‑management to lift lifetime revenue per installed unit.
Note: To preserve strategic advantage and encourage direct engagement, this summary intentionally omits the granular regional and application split tables and detailed subsegment revenue points available in the full report on our site.
Competitive Landscape — How the Leading Players Are Positioning
The competitive field blends diversified industrial groups, specialist actuator manufacturers, and integrated automation firms. Several firms are particularly noteworthy for their strategic moves and product positioning:
- Emerson Electric Co. — Leveraging a broad portfolio spanning Fisher control valves to Bettis actuators and smart valve technologies, Emerson continues to push integrated automation as a differentiator for end‑to‑end process control customers.
- Flowserve Corporation. — A focus on engineered valves and severe‑service applications, complemented by actuator platforms, positions Flowserve to capture high‑value segments; its recent acquisition activity underscores a push to strengthen offerings in critical infrastructure sectors.
- Rotork plc. — Specializes in intelligent actuation, and its emphasis on electrification and wastewater projects highlights the growing premium for digital and energy‑efficient solutions.
- Bray International, Crane Co., Velan, KSB, SAMSON, AVK — These manufacturers compete across complementary niches (butterfly valves, isolation valves, water and gas markets) and often win through modular product design and local service networks.
- SLB (Cameron) and Baker Hughes — Energy‑focused players provide upstream and midstream valve systems where stringent performance and certification requirements favor established OEMs.
- Specialist actuator suppliers (Parker Hannifin, AUMA) — They are capturing the shift to electric actuation and motion control integration with OEMs and systems integrators.
Recent corporate developments offer directional clarity: Flowserve’s strategic acquisition activity in early 2026 consolidates engineered valve capabilities; Rotork’s 2025 results emphasize electrification and wastewater project wins; Emerson’s full‑year messaging underscores automation tie‑ins as a growth lever. Industry forums — such as the Valve Forum organized by the Valve Manufacturers Association — continue to spotlight technological advances, including gas‑charged hydraulic actuators for nuclear applications, which remain an important niche with high entry barriers.
Key Industry Dynamics to Watch in 2026
- Raw‑material price volatility and trade policy. Elevated hot‑rolled coil prices and persistent tariffs are reshaping total cost of ownership. Manufacturers will need active procurement strategies and closer supplier partnerships.
- Electrification of actuation. Demand is accelerating for electric actuators because of lower maintenance, energy efficiency, and better digital integration. This trend has implications for product roadmaps and aftermarket services.
- Service‑first revenue models. As installed bases age, recurring revenue from predictive maintenance, retrofit kits and remote diagnostics will outpace unit sales growth for many firms.
- Consolidation vs. specialization. Moderate market concentration enables M&A for scale benefits, while niche expertise remains valuable for safety‑critical and severe‑service applications.
- Regulatory and certification complexity. Nuclear, offshore, and power segments impose strict requirements that favor suppliers with proven compliance and qualification records.
Actionable Recommendations for 2026 Executives
- Reprioritize R&D spend toward electric and digitally enabled actuation; quantify lifecycle TCO advantages and embed those narratives into commercial propositions.
- Stress‑test manufacturing networks for tariff and freight scenarios; where economics permit, pursue nearshoring or localized machining centers for high‑weight components.
- Accelerate aftermarket offerings — instrumented service contracts and retrofit kits deliver margin and lock in installed base revenue.
- Pursue targeted M&A that closes capability gaps (e.g., severe‑service valves, digital actuation software) rather than broad scale buys that dilute focus.
- Adopt commodity‑indexed procurement and strategic safety stocks to smooth margin volatility while negotiating supplier performance and innovation commitments.
How PW Consulting Empowers Your 2026 Decisions
Our report pairs predictive market modeling with executable playbooks designed for rapid implementation. If you are evaluating capex plans, M&A targets, product investment trade‑offs, or supply‑chain rework for 2026, PW Consulting provides the scenario modeling, commercial heuristics, and operational templates to translate strategy into deliverable outcomes.
For executives who need the complete dataset — including regional and application-level breakdowns, granular segment forecasts, and the full competitive benchmarking matrix — the full report is available through our publication portal. The high‑resolution tables and company scorecards are intentionally gated: they are designed to support confidential decision processes and to provide subscribers with the fine‑grained intelligence required to act decisively.
Contact PW Consulting to schedule a briefing and a customized scenario walk‑through. Our analysts can map the report’s outputs to your asset base, P&L sensitivities, and strategic milestones to create a prioritized action roadmap for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Industrial Valves And Actuators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Asia Pacific Commands USD 19,064.5 Million Share of Automotive Interior & Exterior Trim Market in 2025
By PW Consulting, 2026-07-06
Automotive Interior & Exterior Trim Market — A 2026 Strategic Preview for Decision-Makers
PW Consulting’s latest market intelligence release on the Automotive Interior & Exterior Trim market arms executives with the directional clarity required for high-stakes 2026 decisions. Our analysis, built on a rigorous base year of 2025 and a forecast window spanning 2026–2032, shows a resilient expansion trajectory: the global market, measured in USD million, stood at approximately USD 43,590 million in 2025 and is projected to reach roughly USD 60,110 million by 2032, reflecting a compounded annual growth rate (CAGR) of about 4.7% across the forecast horizon. These headline figures matter because they frame the investment, sourcing and M&A calculus for OEMs, tier-1 suppliers and private equity players entering or reshaping their positions in 2026.
Automotive Interior Exterior Trim Market
Why this report matters to business leaders in 2026
- Recovering but structurally evolving demand: The trim market’s steady mid-single-digit CAGR masks important structural inflections — from material mix shifts to new functional architectures — that will determine which players capture disproportionate value.
- Margin pressure and cost dynamics: Volatility in resin and polymer markets — notably polypropylene price spikes felt in early 2026 — have immediate P&L implications for trim manufacturers and their OEM customers. Our scenario models quantify the margin sensitivity of different product families to feedstock swings.
- Regulatory and sustainability inflection points: Revised regulatory targets for recycled content and end-of-life vehicle rules are reshaping material selection, supplier qualification and long-term sourcing agreements. The timing and specificity of compliance programs will be decisive in 2026 procurement cycles.
Core takeaways — what senior executives need to know now
1) Macro growth is sufficient to support targeted investments, but not all bets are equal. The market’s growth path creates room for scale-building moves, yet the value pool is concentrating in segments that blend material innovation, system integration and sustainable credentials. Our analysis surfaces which product-to-architecture combinations are likely to outpace headline market growth — without disclosing proprietary segment-level datapoints reserved for subscribers.
Automotive Interior Exterior Trim Market
2) Raw material dynamics will drive short-term strategy. Price spikes in key polymers have already forced OEMs and suppliers to revisit contract terms, inventory policies, and specification tolerances. Actionable tactics — such as hedged offtake, multi-sourcing, and validated alternative materials — are laid out in the report’s operational playbooks.
Automotive Interior Exterior Trim Market
3) Regulatory clarity creates competitive advantage. With new recycled-content mandates now embedded in regional regulations, companies that accelerate validated circular material streams, closed-loop partnerships, and design-for-recyclability protocols will avoid costly requalification cycles and can command premium positioning with sustainability-conscious OEM platforms.
Competitive landscape — players, moves and implications
The industry remains a mix of global system integrators and specialized suppliers. Market concentration metrics indicate a moderately consolidated top tier (CR3 ~28.5% and CR5 ~42.8%), which implies that while a handful of global integrators set technical and commercial norms, there remains substantial opportunity for nimble tier-2 suppliers and regionally strong players to capture niche value.
- Magna International Inc. — A global integrator with deep capability in body exteriors and interior systems. Magna’s emphasis on sustainable materials and full-vehicle solutions positions it to compete on platform-level content and cross-border OEM programs.
- Grupo Antolin — Known for headliners, door panels and ornamental surfaces, Antolin’s recent positive order intake and solid first quarter results signal healthy demand for interior aesthetic and functional components.
- Yanfeng Automotive Interiors — A cockpit and smart-surface specialist that leverages scale in instrument panels and center consoles; Yanfeng’s footprint provides a strategic bridge between design innovation and high-volume execution.
- Toyota Boshoku — With traditional strength in seating-related trim and an expanding third-party OEM focus, Toyota Boshoku pairs production scale with visible sustainability initiatives showcased at design events and through renewable-energy projects at manufacturing sites.
- Lear Corporation — A seating and e-systems leader recently recognized by a major OEM for seating excellence, underscoring the interdependence of trim quality and seat-system performance.
- Adient & Toyoda Gosei — Both bring focused expertise on seating surfaces and functional decorative components, offering complementary capabilities to larger system players and OEM programs.
- Continental, DRÄXLMAIER, IAC Group — These firms balance material science, luxury finishing and cockpit integration; they are active in premium and technology-led content where differentiation and margin capture are higher.
Recent industry transactions and corporate developments are reshaping the competitive map. A notable 2026 transaction created a standalone interiors supplier out of a previously larger automotive conglomerate, a development that could accelerate consolidation and create attractively scaled targets for strategic buyers. Meanwhile, supplier awards and profitability upticks among incumbents validate programs tied to next-generation vehicle launches.
Report deliverables — what PW Consulting provides (practical, operational, proprietary)
PW Consulting’s report is built for action. Core components include:
- Validated macro market sizing (2020–2025 historical, 2026–2032 forecast) with sensitivity bands and scenario projections to stress-test investment thresholds.
- Competitor benchmarking with capability maps and supplier scorecards that compare engineering breadth, program execution, sustainability credentials and margin profiles.
- Regulatory impact analysis that translates recycled-content mandates and end-of-life rules into sourcing pathways, compliance timelines and requalification cost estimates.
- Raw-material shock models that quantify margin exposure and recommend procurement strategies — from hedging and long-term contracts to validated material substitutions.
- Operational playbooks: design-for-recyclability checklists, tooling and process KPIs, plant footprint optimization frameworks, and integration checklists for EV-specific cabins and smart surfaces.
- Deal and partnership playbook for M&A and JV activity, supported by target screening criteria, valuation benchmarks and integration risk matrices.
To honor our “trailer” approach, the full, granular segmentation tables, regional splits and product-level revenue schedules are reserved for subscribers and include PW Consulting’s proprietary demand models and supplier-by-platform maps.
Actionable strategic recommendations for 2026
- Implement a two-tier material risk strategy: (a) short-term cost defense via pricing collars and selective inventory buffering against resin volatility; (b) medium-term resilience by certifying recycled-content material streams and qualifying secondary suppliers.
- Prioritize product architectures that de-risk regulations and shorten change cycles: modular trim assemblies and standardized interfaces reduce qualification timelines for material switches and supplier changes.
- Pursue focused M&A or strategic alliances to fill capability gaps in smart surfaces and integrated cockpit modules — assets that are increasingly rewarded with higher content per vehicle.
- Rebalance footprints to align production with platform sourcing decisions: allocate capacity to plants that serve high-growth OEM programs and where renewable energy or circular-material feedstock is accessible.
- Embed sustainability metrics into supplier scorecards and commercial terms: link recycled-content targets to pricing incentives and shared R&D roadmaps to accelerate compliance and brand differentiation.
- Invest in digital engineering: accelerate use of digital twins, materials simulation and lifecycle assessment tools to cut validation cycles and reduce prototype iterations.
Concluding perspective
The Automotive Interior & Exterior Trim market in 2026 offers a compelling growth trajectory, but realizing the upside demands disciplined strategic moves that reconcile near-term cost volatility with medium-term structural shifts toward sustainable, integrated interiors. PW Consulting’s new report synthesizes quantitative forecasts with executable guidance — from procurement tactics and plant strategy to M&A playbooks and sustainability implementation — enabling executives to convert market growth into durable competitive advantage.
For full access to the proprietary segment breakdowns, regional forecasts, supplier scorecards, and our scenario-modeled implications for specific program investments, consult the complete PW Consulting report and downloadable datasets. Our team stands ready to support bespoke strategy workshops, target screen sessions, and integration roadmaps tailored to your 2026 agenda.
For detailed analysis of this topic, please visit the official page: Automotive Interior Exterior Trim Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hybrid Cross Car Beam Market Poised for 6.0% CAGR in 2026–2032 as Automakers Accelerate Lightweighting
By PW Consulting, 2026-07-02
Hybrid Cross Car Beam Market: Strategic Intelligence for 2026 Decision-Makers
PW Consulting’s latest market study on the Hybrid Cross Car Beam Market (base year 2025) delivers a compact yet rigorous briefing tailored for executive teams preparing strategic moves in 2026. The sector has moved from a niche lightweighting technology into a mainstream architectural lever for OEMs and Tier-1s seeking mass CO₂ reductions, platform standardization and cockpit functional integration. Our analysis shows the market reached approximately USD 2,127.8 Million in 2025 and is forecast to continue expanding through the 2026–2032 horizon at a mid-single-digit compound annual growth rate (CAGR) of 6.0%, reaching a market size in the vicinity of USD 3,199.4 Million by 2032. At the same time, market concentration is material: the top three suppliers account for roughly 48.5% and the top five roughly 62.3% of market value, creating both opportunity and competitive barriers for new entrants.
Hybrid Cross Car Beam Market
Why this report matters for 2026 strategic planning
- Actionable foresight: We translate macro growth trajectories into concrete decision triggers for product roadmaps, procurement, and partnership strategies.
- Material-technology pairing: The report synthesizes the latest evidence on thermoplastics, metal-thermoplastic hybrids and high-performance composite solutions, helping you prioritize material choices against weight, cost and recyclability metrics.
- Risk-adjusted supplier view: Given the market’s mid-concentration profile, supplier selection and dual-sourcing strategies materially affect time-to-market and margin capture; our vendor assessment framework quantifies those trade-offs.
- Regulatory alignment: The study connects lightweighting gains to emissions targets and compliance timelines so procurement and engineering roadmaps can be aligned with corporate sustainability commitments.
What the PW Consulting report contains (practical deliverables)
- Integrated market model: A bottom-up forecast covering 2020–2032 with scenario levers for EV penetration, material substitution and regulatory tightening. The model is provided in spreadsheet form so teams can test bespoke assumptions.
- Go-to-market playbooks: Step-by-step plans for OEMs and Tier‑1s on piloting hybrid beam solutions, specifying testing protocols, qualification gates and supplier KPIs to fast-track implementation within a 12–24 month window.
- Materials and manufacturing dossier: Comparative performance matrices for key material families (metal-thermoplastic hybrids, glass- and carbon-reinforced polyamides, aluminum hybrids and hybrid composites), including manufacturability, cycle time, joining techniques and end-of-life considerations.
- Supplier scorecard and M&A signals: A pragmatic framework to evaluate strategic fit, technological differentiation and capacity constraints across incumbent and emerging suppliers—designed to help corporate development and procurement teams prioritize partnerships or acquisition targets.
- Cost and LCA reference curves: Normalized unit-cost trajectories and lifecycle-emissions profiles for typical design permutations. Note: detailed segment-level tables and proprietary split values are included in the full report and gated to protect competitive insight.
- Case-study playbacks: Real-world examples of design-to-production journeys, highlighting trade-offs made by OEMs and the performance outcomes observed in early fleet programs.
Market dynamics shaping 2026 strategies
- Electrification as accelerator. EV architectures are amplifying the value of multifunctional cross car beams that combine structure, mounting interfaces and tooling simplification. This trend is a primary demand driver embedded in our 6.0% CAGR baseline.
- Sustainability and regulation. OEMs are increasingly quantifying component-level CO₂ benefits. Notably, recent industry moves—such as a major OEM’s low‑carbon hybrid beam design intended to replace magnesium components—are projected to yield significant annual CO₂ reductions, underscoring the strategic importance of material substitution beyond weight savings.
- Materials innovation. High-performance thermoplastics and recycled-carbon-fiber-reinforced polyamides now enable meaningful mass reductions (industry sources indicate material-driven weight savings in the 20–30% range versus traditional steel configurations) while improving integration of functions like airbag mounts and HVAC channels.
- Manufacturing convergence. Hybrid designs leverage a mix of metal forming, local metal reinforcements and thermoplastic injection techniques—allowing a balance between structural integrity and part consolidation that reduces assembly complexity and cost.
- Cost and supply risk. While the technology premium over conventional beams is narrowing, raw material availability and price volatility for specialty resins and carbon fiber remain a procurement risk—requiring hedging, long-term offtakes or strategic investments in recycling capabilities.
Competitive landscape: positioning and implications
The market is evolving from material experimentation to commercialization, and a diverse set of players are staking differentiated positions. Our qualitative competitive analysis of leading suppliers—based on technology approach, go-to-market strategy and recent product milestones—yields practical insights for partnering and procurement.
Hybrid Cross Car Beam Market
- Röchling Automotive (Germany): Focuses on hybrid metal–plastic beams that emphasize lightness and functional integration. Strategic implication: ideal partner for OEMs seeking complex functional consolidation beyond pure mass reduction.
- ElringKlinger (Germany): Develops thermoplastic injection-molded beams with local metal reinforcement, positioned for e‑mobility applications where integration and low weight are critical. Strategic implication: strong technical fit for EV platforms pursuing high integration and repeatable manufacturing cycles.
- FORVIA (Faurecia) (France): Pursues modular hybrid beams to enable platform standardization and cockpit customization, touting quantifiable weight and emissions reductions. Strategic implication: suppliers with modular architectures can accelerate OEM platform harmonization programs.
- Envalior (Netherlands/Germany) & AKRO‑PLASTIC (Germany): Material specialists supplying high-performance polyamides and carbon-fiber-reinforced compounds. Strategic implication: material selection is a strategic lever—early engagement with material suppliers can reduce qualification timelines and cost curves.
- Magna International (Canada), Gestamp (Spain), Benteler (Germany): Tier‑1 integrators and metal-structure specialists offering hybrid and aluminum solutions for electrified platforms. Strategic implication: their scale and integration capabilities make them natural partners for OEMs scaling production volumes.
Recent industry milestones—such as a multi‑party award-winning hybrid beam used in a premium EV program and OEM disclosures about large annual CO₂ reductions from hybrid designs—signal that technical maturity and sustainability narratives are converging to accelerate procurement decisions. For suppliers and investors, this combination creates windows to capture share—but timing and partner selection will be decisive.
Hybrid Cross Car Beam Market
Strategic recommendations for 2026
- Prioritize pilot programs that couple material trials with LCA measurement: Run at least two parallel pilots (one thermoplastic‑metal hybrid, one composite-hybrid) to de‑risk supplier choices and generate quantified CO₂ and cost outcomes for board-level sustainability reporting.
- Embed supplier scorecards in procurement RFQs: Include metrics for material traceability, recycled-content pathways and qualification cycle time to make supplier selection a function of total cost and regulatory readiness—not just unit price.
- Build modular platform interfaces: Design cross car beam mounting and functional interfaces with modularity in mind to maximize reuse across vehicle architectures and compress time-to-market for derivative models.
- Hedge raw‑material exposure via strategic partnerships: Secure preferred supply agreements for advanced resins and recycled carbon feedstocks, and consider minority investments or joint ventures with materials specialists to smooth cost and capacity risk.
- Monitor concentration and consolidation signals: With the top suppliers capturing a meaningful share of the market, prepare contingency plans for capacity constraints and consider proactive M&A or supplier development to ensure volume ramp support.
- Integrate cost and LCA into business cases: Require that any cross car beam decision includes unit-cost projections and lifecycle emissions outputs from our reference curves to align procurement with corporate Net Zero targets.
Conclusion — how PW Consulting helps
For executives preparing strategic moves in 2026, the hybrid cross car beam market presents both clear growth potential and complex trade-offs across materials, manufacturing and supplier ecosystems. Our report combines a transparent market model (2020–2032), tactical playbooks, supplier intelligence and LCA-ready cost curves to accelerate confident decision-making. The public briefing above highlights the scope and strategic implications; the full PW Consulting report contains the detailed segment tables, regional and application splits, and the interactive forecast model necessary to convert insight into action.
Access the full study to obtain the proprietary segmentation, downloadable models and supplier scorecards that will enable your team to operationalize a winning hybrid beam strategy in 2026.
For detailed analysis of this topic, please visit the official page: Hybrid Cross Car Beam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wind Turbine Gearbox & Direct Drive Market to Grow at a 5.85% CAGR, Report Finds
By PW Consulting, 2026-07-02
Wind Turbine Gearbox And Direct Drive System Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest industry study on the Wind Turbine Gearbox and Direct Drive System Market provides an executive-grade intelligence package timed for critical 2026 decisions. Built on a 2020–2025 historical base with 2025 as the base year and a detailed forecast to 2032, the report quantifies an expanding global market (base-year 2025 market size: USD 32,920.0 Million) and models growth through 2032 (2032 projection: USD 49,272.95 Million) at a compound annual growth rate (CAGR) of 5.85% across the 2026–2032 forecast horizon. This briefing highlights why the work is strategically valuable to OEMs, Tier-1 suppliers, investors, and policy teams — while preserving the report’s proprietary segment-level intelligence that is accessible through the full report.
Wind Turbine Gearbox And Direct Drive System Market
Why this study matters for 2026 strategy
-
Timing matters: 2026 will be a pivot year for capital allocation and technology bets in wind power. Turbine scale, cost pressures, evolving supply-chain policy interventions, and serviceable-life optimisation converge into decisions that lock-in technology choices for a decade.
Wind Turbine Gearbox And Direct Drive System Market -
Actionable risk quantification: Our modelling translates raw risks — from rare-earth market concentration to tariffs and material cost swings — into scenario-adjusted cost-of-energy and total life-cycle cost impacts, enabling CFOs to stress-test project economics before breaking ground.
Wind Turbine Gearbox And Direct Drive System Market -
Supplier strategy: The market shows mid-to-high consolidation at the top; PW’s competitive analysis decodes which OEMs and gearbox/direct-drive suppliers are positioned to win in onshore, near-shore and deep-water offshore segments, and where aftermarket and service revenue can materially offset thin equipment margins.
Summary of core market dynamics
-
Growth drivers: Continued deployment of onshore capacity, a pronounced shift toward large-capacity offshore platforms, and the rising adoption of high-capacity direct drive designs are the primary growth engines. These structural drivers are captured in our baseline and upside scenarios.
-
Technology tension: The gearbox ecosystem continues to innovate with higher torque density and lighter designs, while direct-drive (gearless) solutions push efficiency, serviceability improvements, and PMDD adoption. Companies are splitting R&D and commercial go-to-market between refined gearbox platforms and larger, direct-drive units for megawatt-class offshore projects.
-
Supply chain & materials: Rare earths (notably neodymium and dysprosium) remain a concentrated supply risk that disproportionately impacts the cost profile of PMDD systems. Steel and component tariffs introduced in key markets are creating new sourcing and localisation calculations for 2026 procurement strategies.
-
Market structure: Top-tier manufacturers command a meaningful share of global supply and aftermarket services. This concentration creates both price-setting dynamics and opportunities for niche players that can demonstrate superior lifecycle performance or rapid local service coverage.
What PW Consulting’s report delivers — practical, transaction-focused intelligence
-
Scenario-calibrated market sizing: Full-market trajectories (USD, revenue unit: Million) across 2026–2032 with base-year transparency and alternative scenarios keyed to tariff shocks, rare-earth price stress, and accelerated offshore buildout.
-
Component-level cost curves: CapEx and OpEx breakdowns for gearbox and direct-drive architectures, inclusive of manufacturing, transport, installation, and typical service intervals — built to support project-level financial modelling.
-
Procurement playbook: A decision tree for supplier selection, insourcing vs. local assembly, and strategic inventory positioning under different tariff and freight regimes.
-
Supply-chain maps and bottleneck heatmaps: Identifies critical nodes (materials, test rigs, specialised machining capacity) and shows how capacity shortfalls translate into project delays and cost escalation.
-
Technology roadmaps and TRL assessments: Comparative analysis of gearbox platform upgrades (e.g., torque-density improvements) versus direct drive innovations (PMDD longevity, generator designs), with expected commercial windows and TRL timelines.
-
Aftermarket & service monetisation: Benchmarks for service revenue, failure-mode economics, remanufacture vs replace decisions, and repowering case studies that illuminate long-term margin opportunities.
-
M&A and JV screening: A pragmatic target list and valuation sensitivities for consolidation plays, bolt-on aftermarket acquisitions, and manufacturing capacity partnerships designed for near-shore localization.
-
Regulatory impact modelling: Quantified impacts of recent policy actions (including investigations and tariff rollouts) on landed equipment costs and supplier competitiveness in key buyer markets.
Competitive landscape — who to watch and why
Market leadership is shaped by a mix of multinational drivetrain specialists, OEMs with integrated generator strategies, and regional gearbox producers. The competitive set includes legacy gearbox leaders that continue to iterate on modular, high-torque-density platforms, and direct-drive proponents pushing PMDD and gearless architectures for high-reliability offshore service. Recent strategic moves underline these dynamics:
-
Winergy (Flender) — product-led differentiation: The REVO high-torque-density gearbox concept launched in late 2025 demonstrates gearbox suppliers’ focus on torque-to-weight optimisation, directly addressing cost-per-MW barriers on larger turbines.
-
Goldwind — longevity and scale in direct drive: The Ultra Series direct-drive models unveiled in 2025 emphasize extended design life and offshore readiness, signaling OEM commitments to PMDD for long-duration asset classes.
-
ZF — validation capability: The commissioning of a 30 MW test rig in 2025 shows how vertical test capacity is becoming a competitive moat; rig access allows faster validation cycles for new gearbox and integrated powertrain concepts.
-
Mingyang and other OEMs — megawatt push: Installations of very large direct-drive machines illustrate how OEMs are taking technical risk to secure high-yield offshore sites — but with implications for supply chain scale-up and component stress profiles.
-
Regional manufacturers (China, Japan, Europe) — dual strategies: Many regional players balance high-volume gearbox supply with service offerings; their agility in local markets makes them natural partners for developers facing tariff or localisation requirements.
Regulatory and raw-material headwinds — implications for 2026 planning
-
Trade policy uncertainty: Section 232-style investigations and expanded tariff coverage for steel, aluminium and wind components reshaped landed cost assumptions in 2025–2026. Procurement teams must model localized sourcing and tariff pass-through scenarios to protect project IRRs.
-
Rare-earth concentration risk: With magnet supply and processing concentrated, price and availability volatility need to be a primary input to technology choice. Our sensitivity runs show that under stressed rare-earth pricing, lifecycle costs for PMDD architectures can swing materially versus gearbox alternatives.
How executives should use this intelligence in 2026
-
De-risk major CAPEX decisions: Use the report’s scenario outputs to determine whether to accelerate orders, redesign procurement windows, or shift to modular, serviceable drivetrain architectures that reduce exposure to single-source components.
-
Choose technology with eyes open: Match turbine-class and site (wind regime, logistics, O&M access) to drivetrain choice using the report’s TRL timelines and lifecycle cost comparisons rather than vendor pitch decks alone.
-
Design supplier relationships strategically: Consider conditional contracting that embeds performance guarantees, service-level agreements, and shared inventory strategies to manage tariff and freight volatility.
-
Pursue aftermarket capture: Service & remanufacture economics in the report highlight opportunities to monetise aftermarket windows, especially where OEMs cannot guarantee local response times or parts availability.
-
Adopt an adaptive procurement hedging plan: Implement raw-material hedges, dual-sourcing options, and staged order release mechanisms to preserve optionality as market signals evolve.
Conclusion — the strategic opportunity in 2026
The gearbox and direct-drive market sits at an inflection: technology maturation, supply-chain politics, and a push to higher-capacity turbines are creating winners and losers. Our report gives decision-makers the quantitative scaffolding and qualitative signals to take confident actions in 2026 — whether that is to accelerate orders for validated platforms, invest in localised manufacturing, hedge raw-material exposure, or pursue aftermarket consolidation. PW Consulting’s proprietary segmentation, supplier scoring, and scenario analyses translate the headline growth (CAGR 5.85% to 2032) into the actionable steps that preserve margin, manage risk, and capture upside.
For detailed segmentation, company-level benchmarking, downloadable data tables, and the full set of proprietary forecasts and scenario outputs, access the complete Wind Turbine Gearbox And Direct Drive System Market report from PW Consulting. The full report contains the granular intelligence required to convert this briefing into executable 2026 strategies.
For detailed analysis of this topic, please visit the official page: Wind Turbine Gearbox And Direct Drive System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Interior & Exterior Trim Market Hits USD 43,590 Million in 2025; Forecast to Grow at 4.7% CAGR Through 2026–2032
By PW Consulting, 2026-07-02
Automotive Interior & Exterior Trim Market: Strategic Imperatives for 2026 — A PW Consulting Brief
As OEMs and suppliers navigate the confluence of electrification, sustainability mandates, raw-material volatility, and shifting consumer expectations, the automotive interior and exterior trim market emerges as a critical battleground for margin protection, product differentiation, and regulatory compliance. PW Consulting’s latest market study — covering historical performance from 2020–2025 and offering a forward-looking forecast through 2032 — delivers the strategic insights executives need to shape decisions in 2026 and beyond. The global market, measured in USD Million, remains on a steady expansion path with a compound annual growth rate (CAGR) of 4.7% over the forecast period, underscoring durable demand even as structural change accelerates.
Automotive Interior Exterior Trim Market
Why this report matters for 2026 decision-makers
- Tactical sourcing and cost management: With documented resin-price shocks and input-cost pass-through pressures in early 2026, purchasing and procurement leaders must redesign contracts and hedging approaches. Our analysis quantifies sensitivity to polymer price moves and presents tailored sourcing scenarios for short-, medium- and long-term horizons.
- Materials and sustainability readiness: Revised regulatory targets in key markets are raising the bar for recycled-content adoption in vehicle trim. The report translates policy changes into product-level implications and a pragmatic roadmap for achieving compliance without sacrificing supplier margins or aesthetics.
- Portfolio and product strategy: Interior and exterior trim is no longer a commoditized component set. New requirements for smart surfaces, integrated electronics, and premium tactile experiences create monetization paths that require calibrated R&D and industrial investments — we outline prioritized feature sets and go-to-market sequencing.
- M&A and vertical-integration playbooks: Market concentration metrics show meaningful room for consolidation-led scale. Our deal-readiness framework helps corporate development teams evaluate targets, structure earn-outs, and model synergies while preserving customer continuity.
Macroeconomic and market context
PW Consulting’s topline findings place the market on a positive trajectory from the 2025 baseline into the 2032 horizon. The CAGR of 4.7% reflects a combination of technology-led upscaling (smart trim, integrated cockpits), ongoing replacement demand in mature markets, and robust vehicle production in certain emerging markets. This growth is, however, unevenly influenced by three cross-cutting dynamics that every 2026 plan must account for:
Automotive Interior Exterior Trim Market
- Raw-material volatility: Polypropylene (PP) and other resin price swings have reintroduced cost uncertainty in 2026, with notable contract increases and feedstock-driven pressure that impact dashboards, door panels, and exterior moldings. Our report provides sensitivity matrices to model the P&L impact of different resin-price trajectories and recommends strategic procurement levers.
- Regulatory tightening on recycled content: The revised EU End-of-Life Vehicles (ELV) Directive and analogous initiatives elsewhere are creating binding recycled-content targets for new vehicles. We translate these regulatory requirements into material-mix decisions and highlight high-probability compliance pathways, including mechanical recycling partnerships and chemical-recycling pilots.
- Technological convergence and premiumization: Demand for integrated functionality (e.g., haptics, UV/IR-aware coatings, smart surfaces) is driving content-per-vehicle growth in selected segments. Suppliers that combine systems expertise with materials science are best positioned to capture this incremental content.
What the report contains — operational, actionable intelligence
Beyond headline market sizing and a forecast through 2032, this study is expressly designed to be operational for C-suite and business-unit decision-makers. Key deliverables include:
Automotive Interior Exterior Trim Market
- Proprietary market-sizing methodology and forecast scenarios (base, upside, downside) calibrated to production-shift assumptions and policy environments.
- Supplier economics models — unit-cost build-ups for representative interior and exterior modules, including raw-material, labor, tooling amortization, and logistics components.
- Raw-material sensitivity analyses and procurement playbooks that model the P&L impact of resin-price spikes and propose contractual structures (indexed agreements, collars, multi-year supply frameworks).
- Regulatory-impact mapping that converts high-level compliance targets into product-design constraints and cost implications, with mitigations tailored to OEMs and tier suppliers.
- Competitive landscaping and capability-mapping across leading suppliers, with a supplier-decision matrix to guide outsource vs. insource choices and strategic partnership selection.
- M&A playbook and integration checklist covering valuation multiples, synergy capture, operational due diligence, and post-merger retention of key OEM contracts.
- Commercial-closing toolkits — negotiation templates, warranty exposure calculators, and contract clauses that protect margin in a volatile input market.
Competitive landscape: strategic implications for suppliers and OEMs
The supply base for trim remains diversified, with leading global players occupying strong positions across modules and geographies. Market concentration metrics show room for scale-led moves: the top three suppliers together represent a meaningful but not dominant share of the market (CR3 ~28.5%), while the top five raise that share further (CR5 ~42.8%). This structure creates strategic choices for both sides of the value chain.
- Integrated system suppliers (e.g., Magna International Inc., Yanfeng Automotive Interiors): These firms leverage breadth — offering complete body interiors, cockpits, instrument panels, and trim systems — to win platform-level awards. Their advantage lies in systems integration and the ability to internalize incremental electronics and smart-surface content. For OEMs, partnering with such suppliers can speed time-to-market for complex interiors; for competitors, differentiation requires focused R&D investments or niche specialization.
- Interior specialists (e.g., Grupo Antolin, DRÄXLMAIER Group): Their depth in headliners, door panels, and premium surfaces positions them well for OEM programs focused on tactile quality and sustainability. Recent positive order intake and financial performance from some players highlight sustained OEM demand for high-quality interior solutions.
- Seating-focused firms with trim capabilities (e.g., Lear Corporation, Adient plc, Toyota Boshoku): Seat systems remain a high-content area where surface materials and mechanisms converge. Awards and recognition for seating and E-Systems underscore the strategic value of integrated seating+trim offerings, especially as interior differentiation shifts toward occupant experience.
- Tier suppliers with diversified portfolios (e.g., Continental AG, Toyoda Gosei, IAC Group): These organizations offer modular flexibility and can support rapid localization strategies for OEMs. Their capability to adapt product mixes across regions is an asset in environments of demand variability.
Recent industry moves underscore the dynamic nature of the landscape. Notable transactions and developments in 2025–2026 — including major corporate divestments and capital transactions — are reshaping competitive positioning and creating new standalone platforms in the interiors space. Industry awards and investment in sustainability projects also highlight the premium suppliers place on both performance recognition and decarbonization efforts.
How executives should use this intelligence in 2026
PW Consulting recommends a three-part agenda for manufacturers, suppliers, and investors planning for 2026:
- Stabilize margins through procurement redesign: Implement tiered contract structures with indexation for volatile resins, establish multi-supplier strategies for critical polymers, and negotiate flexibility clauses tied to feedstock indices. Use our sensitivity models to set internal trigger points for hedging or price renegotiation.
- Accelerate sustainable-materials adoption on a cost-validated path: Prioritize recycled-content pilots in non-visible components to build supply-chain scale, while preparing validated substitutes for high-visibility surfaces through co-development with material innovators. The report’s regulatory-impact pathways help reconcile compliance timelines with cost targets.
- Differentiate via systems and premium feature roadmaps: Invest selectively in integrated electronics, haptics, and smart-surface technologies that raise content-per-vehicle in targeted segments. For suppliers, bundle capabilities that are hardest to replicate; for OEMs, structure supplier tiers to reward innovation that materially improves perceived interior value.
Limitations and how to get the full picture
This briefing deliberately emphasizes strategic implications and operational playbooks while withholding certain granular sub-segmentation tables and region- or application-level numerical breakdowns that are included in the full PW Consulting report. The complete study contains detailed regional and application splits, unit-cost models, supplier scorecards, and downloadable Excel models that allow you to run bespoke scenarios for your business.
Next steps
For commercial teams, procurement leaders, and corporate development groups preparing 2026 plans, PW Consulting offers tailored briefings and custom scenario workshops that apply the study’s core models to your specific product mix, supplier roster, and exposure to material-price risk. Schedule a strategy session with our automotive interiors team to convert market insights into a prioritized action plan aligned to your 2026 objectives.
To access the full report and the proprietary datasets that underpin our forecasts and operational tools, please visit the PW Consulting publications page or contact our Automotive Practice lead for an executive briefing.
For detailed analysis of this topic, please visit the official page: Automotive Interior Exterior Trim Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Polariscope Strain Viewer Market Set to Grow at a 5.35% CAGR During 2026–2032
By PW Consulting, 2026-07-02
Polariscope Strain Viewer Market: Strategic Imperatives for 2026 — PW Consulting Executive Brief
PW Consulting’s Polariscope Strain Viewer Market report (base year 2025) is released as a concise strategic playbook for executives making capital, procurement, R&D and M&A decisions in 2026. Our analysis synthesizes historical performance (2020–2025) with scenario-driven forecasts across 2026–2032, showing a steady expansion in market value from a 2025 baseline and a projected compound annual growth rate (CAGR) of approximately 5.35% over the forecast horizon. That trajectory underpins practical recommendations for supply chain reconfiguration, product strategy, and regulatory alignment that are immediately actionable this year.
Polariscope Strain Viewer Market
Why this report matters for 2026 decision‑makers
- Timing: Capital budgeting cycles and Line-of-Business procurement plans initiated in 2026 must reflect measured growth and mid‑single digit expansion across the market to avoid over- or under-investment.
- Risk management: The market is neither a pure commodity nor fully consolidated — leading vendors hold meaningful share, requiring suppliers and buyers to evaluate concentration risk and substitution options.
- Regulatory compliance and validation: Polariscope instruments play a direct role in meeting glass and PET inspection standards; integrating this technology with QA processes reduces compliance risk and speeds market acceptance.
- Innovation payoff: Incremental product enhancements (notably in computerized and inline systems) are shifting value from hardware-only sales to bundled software, analytics and services — an important signal for product roadmaps and aftermarket strategies.
Market trajectory and macro drivers
Our topline forecast places market value on a clear upward path from the 2025 base: the industry is projected to expand meaningfully through 2032, reaching a materially higher size by the end of the forecast period. The calculated CAGR of 5.35% reflects a balance of steady demand in established applications (such as container and preform inspection) and a rising adoption curve for automated and computerized solutions. Key demand drivers include tighter quality controls in packaging, regulatory emphasis on strain and annealing tests for glass containers, and incremental replacement cycles driven by digitization of laboratory and production-line inspection.
Polariscope Strain Viewer Market
Competitive dynamics show moderate concentration; the top three players account for a substantive share of the market, and the top five consolidate a clear majority position. That structure creates room for differentiated entrants that can compete on specialization, software-enabled services, or regional distribution partnerships.
Polariscope Strain Viewer Market
Segmentation intelligence — what this brief reveals and what the full report contains
To preserve strategic value for clients and subscribers, this brief highlights segmentation themes without disclosing granular splits. The full report contains detailed segmentation across regions, product types (portable, bench, computerized) and application verticals (PET preforms, plastic components, glass manufacturing, and others), accompanied by historical trend lines and scenario-based forecasts. Here we summarize the implications:
- Product differentiation is increasingly important: portability, illumination quality, and computerized analytics determine procurement preferences across production and lab environments.
- Application-led demand persists: inspection regimes in PET preform and bottle production continue to generate steady equipment replacement and upgrade cycles.
- Geographic nuance matters: growth pockets exist beyond headline markets, and regional procurement cycles and standards enforcement create heterogeneity that matters for local go-to-market strategies.
What the report delivers — practical, executable content
PW Consulting built this report as a toolkit for executives, not a theoretical paper. Deliverables include:
- A buyer’s decision matrix for selecting polariscope hardware vs. computerized systems, incorporating operating environment, throughput, and validation needs.
- TCO and procurement models in USD for short, medium and long replacement cycles — calibrated to present-value terms and sensitive to service and software licensing models.
- Regulatory alignment playbooks that map instrument selection to relevant standards and test protocols, including annealing and strain testing references.
- Vendor scorecards derived from primary interviews and hands-on testing, covering product robustness, calibration support, software features, and aftermarket service performance.
- Five scenario demand forecasts (base, high-tech adoption, regulatory acceleration, economic slowdown, and supply disruption) to stress-test capex plans through 2032.
- Case studies illustrating rapid deployment models, inline integration lessons, and validation templates for quality teams.
Competitive landscape — strategic takeaways
The market is populated by global players and specialized manufacturers whose product portfolios span portable, bench-top and computerized strain viewers. PW Consulting’s assessment of several core vendors yields these insights:
- Presto Stantest Pvt. Ltd. (India) — a diversified portfolio with models tuned for PET preform and bottle inspection; strength in established market relationships and application-focused product variants.
- Pacorr Testing Instruments Pvt. Ltd. (India) — notable for a focus on PET preform QC; recent product updates emphasize residual stress analysis and usability for production-line checks, signaling an incremental shift toward specialized features for beverage packaging manufacturers.
- Strainoptics, Inc. (USA) — positions itself on laboratory-grade polarimeters and on-line systems; recent product announcements expand ASTM-compliant measurement capabilities, appealing to glass laboratories and high-precision R&D facilities.
- Luceo Co., Ltd. (Japan) — concentrated on high-precision strain measurement across glass, plastics and semiconductor substrates, offering options attractive to manufacturers requiring tight measurement tolerances.
- Labtron Equipment Ltd. (UK) and Suzhou PTC Optical Instrument Co., Ltd. (China) — exhibit complementary strengths in illumination hardware, bench systems, and cost-competitive offerings for local markets and OEM channels.
Recent product activity underlines two converging trends: (1) incumbent vendors are enhancing features that improve detection sensitivity and operator ergonomics, and (2) there is increasing emphasis on computerized, standards-compliant solutions that facilitate traceability and audit readiness. Notably, product updates rolled out in early-to-mid 2026 from multiple vendors target PET preform quality control and ASTM‑aligned laboratory measurement — a development that should be a focal point for procurement and QA teams.
Regulatory and standards tailwinds
Inspection instruments such as polariscopes are embedded in compliance workflows. Our Dynamics section explicitly maps instrument usage to regulatory guidance and standards, including annealing and strain testing guidelines that form part of container safety protocols. Additionally, visual testing standards for transparent materials and fusion-welded joints influence buyer specifications in manufacturing and laboratory contexts. For compliance leaders, the actionable consequence is clear: selecting instruments that support recognized test methods reduces audit friction and shortens validation timelines.
Strategic recommendations for 2026
- Recalibrate procurement timelines to reflect a moderate-growth market: prioritize staged investments in computerized systems where traceability and analytics deliver measurable QA gains.
- Require vendor scorecards and TCO models as part of RFQs: include lifecycle service, calibration, and software update costs to avoid underestimating total ownership.
- Implement pilot programs for inline and automated inspection: run controlled trials to quantify defect-catch rate improvements and throughput impacts before scaling.
- Integrate instrument selection with regulatory mapping: mandate ASTM/ISO alignment clauses in supplier contracts for any instruments used in validated workflows.
- Monitor concentration risk visible in the competitive landscape: diversify supply sources in procurement plans to mitigate vendor-specific disruptions and preserve negotiating leverage.
- Consider partnerships or M&A to acquire analytics and software expertise rather than building from scratch; capture value from services and data monetization over the equipment lifecycle.
What you will find in the full Polariscope Strain Viewer Market report
The full PW Consulting report is intentionally comprehensive and operational. Subscribers can expect:
- Granular historical and forecast tables by region, type and application (with downloadable datasets).
- Detailed vendor benchmarking with qualitative and quantitative scoring, primary interview excerpts, and procurement negotiation playbooks.
- Scenario-based financial models, including sensitivity analyses for price erosion, adoption acceleration and regulatory tightening.
- Appendices with test-method crosswalks, validation checklists, and sample SOPs for integrating polariscope measurements into QA programs.
Final note — the strategic edge in 2026
The Polariscope Strain Viewer market is maturing: steady growth, evolving product sophistication and standards-driven demand create a landscape that rewards disciplined strategy. PW Consulting’s Polariscope Strain Viewer Market report is designed to convert market intelligence into immediate operational decisions for procurement teams, quality leaders, product managers and M&A strategists. For organizations that need to align budgets, accelerate digital inspection capabilities, or validate compliance posture in 2026, the full report delivers the granular inputs and executable playbooks required to act with confidence.
Access the full Polariscope Strain Viewer Market report and supporting datasets on the Polariscope Strain Viewer Market page to unlock region- and application-level breakdowns, vendor scorecards and the models referenced in this brief.
For detailed analysis of this topic, please visit the official page: Polariscope Strain Viewer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 6.45% CAGR for Oil Tank Sight Glasses Market Through 2026–2032
By PW Consulting, 2026-07-02
Oil Tank Sight Glasses Market — Strategic Outlook for 2026: PW Consulting Insights
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I am pleased to introduce our latest intelligence briefing on the Oil Tank Sight Glasses market. This release accompanies our full market research report and is structured to equip executive teams with the context, frameworks, and decision levers that matter most as they plan for 2026. The briefing distills the macro trajectory and competitive dynamics while intentionally withholding certain line‑by‑line segment tables to encourage deeper engagement with the full report.
Oil Tank Sight Glasses Market
Executive snapshot: a market on a steady upward trajectory
The Oil Tank Sight Glasses market has shown consistent expansion through the recent historical window, growing from approximately USD 142.35 Million in 2020 to USD 215.0 Million in our base year of 2025. Under the assumptions and scenarios modeled in our report, the market is projected to maintain a compound annual growth rate (CAGR) of 6.45% across the 2026–2032 forecast period, reaching an aggregate size in the vicinity of USD 333.0 Million by 2032. For decision-makers, this is not a story of explosive disruption but a steady, engineering‑led expansion driven by maintenance modernization, regulatory reinforcement, and incremental product innovation.
Oil Tank Sight Glasses Market
Why 2026 is a strategic inflection point
- Regulatory and standards alignment: Industry guidance — for example, API 610 recommendations and DIN specifications for sight glass materials and dimensions — continues to influence procurement and OEM specifications. Firms that align product design and QA to evolving standards gain specification wins in regulated end markets.
- MRO modernization cycles: Many end‑users are transitioning from reactive to condition‑based maintenance. Sight glasses, while a small physical component, serve a disproportionate role in enabling visual condition monitoring and integrating with sensorized pods for predictive diagnostics.
- Material and supply chain stressors: Borosilicate glass remains the preferred material for performance-critical applications; supply, lead times, and quality control of specialty glass are therefore material business risks that need active management in 2026 procurement strategies.
- Consolidation and channel strategies: Market concentration metrics show leading vendors account for a meaningful share of supply—enough to influence pricing and distribution dynamics, but not so concentrated as to prevent new entrants or niche innovators from winning business with differentiated value propositions.
What our report delivers — practical, transaction‑ready intelligence
PW Consulting’s full Oil Tank Sight Glasses report is purposely operational. It is built around the questions procurement heads, product managers, and MRO leaders will be asking in 2026. Key deliverables include:
Oil Tank Sight Glasses Market
- Market sizing and validated growth scenarios calibrated to 2026 planning horizons, including sensitivity analyses that isolate demand drivers across maintenance modernization, regulatory replacement cycles, and retrofit programs.
- Supply‑side mapping: manufacturers, specialty glass suppliers, machining and assembly partners, plus an overlay of typical lead times and quality checkpoints for borosilicate and polymer alternatives.
- Decision frameworks for specification selection that tie material choice, pressure/temperature ratings, and inspection modalities to total cost of ownership (TCO) and risk exposure.
- Procurement playbooks: RFx language templates, recommended qualification tests, and a short checklist to harmonize vendor audits with DIN/API compliance expectations.
- Commercial scenarios and pricing playbooks for supplier consolidation, private label programs, and aftermarket spare stocking models optimized for working capital.
- Risk and contingency plans covering supply disruptions, regulatory shifts, and rapid substitution pathways (e.g., when polymer sight glasses are selected over glass for safety or weight reasons).
These elements are packaged with exhibit‑quality guidance (whose granular tables and subsegment financials are reserved for the full report) so executives can translate insights into 90‑day and 18‑month roadmaps.
Competitive landscape — who to watch and why
The market comprises a mix of global engineered‑product manufacturers, niche sight glass specialists, and component suppliers that bridge OEM and aftermarket channels. Notable firms profiled in the report include established names with differentiated go‑to‑market and technical strengths:
- Alfa Laval (Lund, Sweden): A leader in hygienic and process‑industry sight glass solutions, Alfa Laval’s offerings emphasize borosilicate glass applications and DIN‑aligned specifications. Their strength lies in deep process expertise and upstream relationships with food, beverage, and biopharma customers where material purity and distortion‑free inspection are critical.
- Douglass (Nashville, USA): Focused on tank level monitoring and process sight glass equipment for industrial oil & gas and allied sectors. Douglass competes effectively in markets that prioritize robust, field‑serviceable designs and well‑established distribution in North America.
- Luneta (USA): Specializes in advanced 3D sighting and condition monitoring pods; their use of Tritan copolyester positions them for durable visibility solutions where impact resistance and long‑term clarity are valued.
- Elesa (Monza, Italy): Offers a broad materials palette (technopolymer through stainless steel) and thermal options up to high temperatures with ATEX configurations, differentiating on ruggedness and certifications for hazardous environments.
- Des‑Case (USA): Known for BS&W bowls and visual oil analysis hardware; a portfolio oriented to lubrication specialists and storage tank operators. Recent catalog refreshes have reinforced their presence in maintenance‑centric buying decisions.
- Zight / United Glass LLC & GREATGLAS, Inc. (USA): Manufacturers of borosilicate tubular and circular gauge glasses, providing custom lengths and high‑pressure variants—important for engineered OEM and retrofit projects.
- PresSure Products Company (PPC) (USA): A full‑spectrum sight glass and flow indicator provider, notable for breadth across industrial segments and replacement parts distribution.
Recent product availability and catalog activity among incumbents indicate ongoing investments in portfolio refresh and channel readiness—signals that 2026 procurement teams will see active competition on lead times, custom configurations, and aftermarket support.
Strategic opportunities and tactical recommendations for 2026
Below are priority moves we recommend for corporate decision‑makers building 2026 plans. These are actionable and tied to measurable outcomes—capex avoidance, reduced downtime, or improved MRO turn rates.
- Adopt a materials-first specification approach: Standardize sight glass material classes by criticality (safety/pressure/temperature) and enforce supplier qualification that includes borosilicate batch traceability where required by standards.
- Bundle procurement to secure capacity: Where possible, negotiate multi‑year supply agreements with tiered pricing tied to volume bands and guaranteed lead times to mitigate specialty glass lead‑time risk.
- Design for maintainability: Favor modular sight glass assemblies that reduce mean time to repair (MTTR) and enable field replacement of wear components without depressurizing systems where safe and compliant to do so.
- Invest in inspection + analytics: Pair visual sight glasses with low‑cost optical sensors or condition monitoring pods to accelerate the transition from time‑based maintenance to condition‑based programs—this yields quantifiable reductions in unscheduled downtime.
- Rationalize SKUs across sites: Implement SKU consolidation where feasible to lower inventory carrying costs and improve part availability; use the provided RFx templates to align suppliers on unified part numbering and configuration control.
- Use standards as a competitive lever: Require DIN/API alignment in supplier contracts and use documented compliance as a selection criterion—this reduces specification drift and latent quality disputes.
- Prepare for retrofit waves: Identify legacy installations where retrofit sight glasses with upgraded materials or integrated sensors deliver immediate uptime and safety benefits; quantify ROI using the TCO templates in the report.
Risk matrix — what keeps procurement and engineering teams awake at night
- Supply concentration of specialty glass: Single‑source exposures for borosilicate components can create bottlenecks. Mitigations: dual‑sourcing, strategic inventory, and backward integration options.
- Regulatory tightening or testing changes: New audit requirements or tighter material certifications can drive unexpected replacement cycles. Mitigation: maintain active standards monitoring and compliance roadmaps.
- Substitution pressures: Polymer alternatives can erode glass incumbency in lower‑risk applications. Mitigation: clear decision rules for material appropriateness and pilot evaluation programs.
How to use this briefing for your 2026 planning
This briefing is designed to be immediately operational: incorporate the playbook items above into your Q1 procurement roadmap, allocate a small cross‑functional team (engineering + procurement + reliability) to run a six‑week supplier qualification sprint, and use the report’s RFx templates to accelerate contracting cycles. For firms preparing capital budgets, our TCO and ROI exhibits convert part selection choices into P&L impacts and working capital requirements—critical inputs for 2026 capex approval packages.
Next steps — receive the full report and proprietary exhibits
PW Consulting’s full Oil Tank Sight Glasses Market report contains the detailed subsegment financials, regional/application breakouts, vendor scorecards, and downloadable procurement templates referenced in this briefing. We intentionally withheld line‑by‑line segment tables in this public summary to protect the proprietary analytics and to ensure a focused review with our advisory team.
To obtain the complete report, vendor benchmarking spreadsheets, and a tailored one‑hour briefing for your leadership team that maps findings to your asset and supply base, please visit our report page or contact your PW Consulting representative.
Prepared by: PW Consulting — Senior Strategic Advisor & Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: Oil Tank Sight Glasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Linear Arm Sorter Market Set to Expand from USD 223.45 Million in 2025 to USD 379.65 Million by 2032 at a 7.85% CAGR
By PW Consulting, 2026-07-02
Linear Arm Sorter Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive Summary
The global linear arm sorter market has moved from fragmented experimentation to strategic deployment. After expanding from approximately USD 142.35 Million in 2020 to USD 223.45 Million in 2025, the market is positioned to grow at a compound annual growth rate (CAGR) of 7.85% over the 2026–2032 forecast horizon, reaching a materially larger addressable size by 2032. For executives planning capital allocation, supply-chain design, or automation roadmaps in 2026, these macro dynamics demand immediate translation into procurement, vendor and integration strategies.
Linear Arm Sorter Market
Why This Market Matters in 2026
-
Operational leverage in constrained labor markets: Persistent labor shortages and rising personnel costs continue to accelerate adoption of automation for repetitive, sortation-intensive workflows. Linear arm sorters offer a compact, flexible sortation footprint that fits both brownfield retrofits and new greenfield operations.
Linear Arm Sorter Market -
Cost pressure reshapes total cost of ownership (TCO): Elevated raw material prices—exacerbated in some regions by tariffs on steel and aluminum—are increasing upfront capital expenditure for sortation systems. Decision-makers must balance higher acquisition costs against long-term labor savings, throughput gains, and serviceability.
Linear Arm Sorter Market -
Modularity and software-led differentiation: Vendors who couple proven mechanical platforms with robust control software and open integration APIs are creating disproportionate value. Sortation accuracy, dynamic destination mapping and maintenance diagnostics are now buyer priorities as much as mechanical throughput ratings.
What 2026 Decisions Should Prioritize
-
Make TCO, not CAPEX, the primary procurement metric. Build scenario models that capture steel-tariff-sensitive supply costs, multi-year maintenance schedules, spare-parts logistics and expected labor substitution benefits over a 5–7 year horizon.
-
Insist on modularity and independent unit operation. Systems that enable partial maintenance and unit-level failover reduce downtime risk in high-mix e-commerce environments and lower lifecycle service costs.
-
Require software and integration roadmaps. Sorting hardware that ships with proprietary, extensible software stacks—offering dimensioning, weighing and real-time sort control—shortens commissioning times and reduces integration risk with warehouse execution systems (WES) and warehouse management systems (WMS).
-
Adopt a supplier-risk lens. Market concentration data shows a middling level of consolidation among top vendors. While this concentration reduces supplier fragmentation, it also raises the importance of vendor financial health, spare-parts lead times and local field-service presence—factors that bear directly on resilience.
-
Plan for hybrid deployments. Combining different sorter types—mechanical, pneumatic and electric-driven designs—lets operators match cost and throughput characteristics to SKU profiles and peak-season variability. Pilot hybrid lines before large-scale rollouts to validate control logic across system types.
Competitive Landscape: Strengths, Signals and Strategic Moves
The vendor landscape comprises a mixture of regional specialists and platforms that emphasize cost-effective, entry-level automation for e-commerce and parcel sortation. Key vendor archetypes include low-cost swing-arm manufacturers, engineering-driven European systems integrators, and newer entrants integrating ASRS and broader intralogistics offerings. Notable firms profiled in our research demonstrate differentiated go-to-market approaches.
-
Falcon Autotech (Noida, India) — Offers a Gen 3.0 linear arm sorter platform designed for low-to-medium volume e-commerce and logistics centers. Their configuration approach couples mechanical sortation with in-house software capabilities, and their recent strategic partnership to expand ASRS deployments in the Americas signals an ambition to move beyond regional niches toward integrated intralogistics solutions.
-
Nido Automation (Mumbai, India) — Positions a pragmatic, cost-focused swing-arm solution as an accessible entry point for organizations with moderate throughput requirements. Ongoing product catalog updates and planned trade-show participation underline a sales push targeting tiered service providers and regional integrators.
-
Leador Tech (China) — Emphasizes smooth redirection mechanics and independent unit operation for cost efficiency in parcel handling. Their engineering choices reflect a focus on maintainability and predictable uptime for high-mix operations.
-
GEBHARDT Intralogistics Group (Germany) — Brings European engineering heritage to standardized format sorting, positioning its ArmSorter as an entry-level automated sorter for standard parcel geometries with robust build and service networks in mature markets.
-
Damon Group (China) — Focuses on low-speed, structurally simple swing-arm sorters that prioritize high precision and reliability for cost-sensitive deployments.
Recent vendor developments—such as product catalog refreshes, trade-show strategies and transcontinental partnerships—indicate two concurrent trends: (1) vendors are broadening capability stacks to capture higher-value system integration work and (2) regional players are pursuing international channel expansion to diversify demand exposure. These moves affect negotiation dynamics, spares logistics and long-term support contracts.
Segment Dynamics & Technology Trajectories
Three dominant technical approaches—pneumatic, electric and hybrid systems—continue to coexist. Each presents trade-offs across throughput, energy consumption, unit cost and maintainability. Key technology trajectories to watch in 2026:
-
Electrification and precise motion control: Electric-driven linear arms are improving energy efficiency and offering finer control for fragile or irregular parcels, making them attractive where damage risk or mixed-SKU handling is a priority.
-
Hybridization for flexibility: Hybrid architectures combine pneumatic simplicity with electric control for targeted performance gains without fully exposing buyers to higher capex.
-
Embedded intelligence and edge diagnostics: Vendors that invest in predictive maintenance, embedded sensors and deterministic control systems reduce mean time to repair and create value through higher realized throughput.
-
Supply-chain resilience through design-for-cost: Increased tariffs and raw material volatility are driving a re-evaluation of heavy steel structures toward mixed-material frames, local sourcing strategies, and design choices that minimize custom fabrication.
What the PW Consulting Report Contains (Practical, Executable Content)
The report is built as an operational playbook for procurement, operations and strategy teams. Highlights include:
-
A transparent market model and forecast with scenario sensitivity to raw material tariffs, labor-cost inflation and peak-season volume shocks.
-
A concise vendor assessment framework—covering technology fit, service footprint, financial resilience and software openness—to support RFP development and scorecards.
-
Use-case driven deployment playbooks that map sorter types to business requirements (e.g., parcel geometry, throughput bands, retrofit vs. new build), together with commissioning and acceptance-test templates.
-
Practical TCO calculators and contractual clauses for spare parts, SLAs and upgrade paths to mitigate escalation risk tied to commodity pricing and component shortages.
-
Implementation risk matrices and contingency plans for multi-site rollouts, including vendor transition strategies and spare-parts warehousing recommendations.
In line with our “trailer” approach, the report demonstrates methodology, scenarios and strategic prescriptions while withholding certain granular segmentation figures and proprietary submarket breakouts that are available on the full report page. This ensures decision-makers can validate approach and receive guidance while protecting sensitive forecasting inputs used in consultative engagements.
Implications for Buyers, Integrators and Investors
-
Buyers should transition from single-metric procurement (price or throughput alone) to multi-criteria contracting that weights lifecycle costs, software interoperability and spare-parts logistics.
-
Systems integrators must expand software capabilities and API-first integration services to capture higher-margin recurring revenue tied to optimization and analytics.
-
Investors will find differentiated upside in vendors that successfully bundle mechanical reliability with software-driven support services and regional installation networks—especially where strategic partnerships accelerate entry into underserved markets.
How to Use These Insights in 90 Days
-
Run a rapid TCO pilot comparing two vendor types across a 5-year horizon, including sensitivity to a 25% increase in steel input costs.
-
Issue an RFI that demands API-level integration and predictive-maintenance roadmaps, then shortlist vendors based on field-service footprint and software openness.
-
Design a two-phased rollout: pilot a hybrid sorter line in a single high-mix SLA lane, validate KPIs, then scale using modular blocks to limit capex exposure.
Final Word — Strategic Value of the PW Consulting Report
For 2026, the primary strategic risk is not whether to automate but how to automate in a way that protects margins, preserves operational agility and mitigates supply-chain exposure. PW Consulting’s Linear Arm Sorter Market report equips leaders with a decision-grade market model, vendor evaluation tools, and executable playbooks tailored to those priorities. The analysis balances quantified market sizing and forecast trajectories with pragmatic procurement and integration frameworks—while reserving proprietary subsegment detail for report subscribers and advisory clients.
To access the full dataset, scenario models and tailored advisory options, visit our report page or contact PW Consulting’s intralogistics practice. Our team can help convert the market intelligence in this brief into a prioritized 12–24 month automation roadmap aligned to your operational KPIs.
For detailed analysis of this topic, please visit the official page: Linear Arm Sorter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


