



Category: Machinery & Automotive
PW Consulting Predicts 5.5% CAGR for Diesel Engines Market Through 2032 as Asia Pacific Drives Growth
By PW Consulting, 2026-06-26
Diesel Engines Market 2026: Strategic Imperatives for Capital Allocation and Product Roadmaps
As of 2026, the global diesel engines market sits at a critical inflection point. PW Consulting’s latest Diesel Engines Market report (base year 2025) quantifies a market of USD 79.3 Million and projects a steady trajectory to approximately USD 115.2 Million by 2032, representing a compound annual growth rate of 5.5% across the 2026–2032 forecast horizon. This briefing highlights the concrete strategic value our report delivers to executives planning capital allocation, product development, and compliance strategies throughout 2026 — while preserving the deeper, decision-enabling detail inside the full report.
Diesel Engines Market
Why 2026 is a Pivotal Year for Decisions
Several simultaneous forces converge in 2026 to create near-term urgency for boardrooms and corporate development teams:
Diesel Engines Market
-
Regulatory compression: Finalized heavy-duty NOx limits scheduled for 2027 in key markets force OEMs and Tier 1 suppliers to finalize technology choices now to avoid costly rework and missed design-win cycles.
-
Technology bifurcation: OEMs are balancing incremental internal combustion improvements (thermal efficiency, aftertreatment) with nascent disruptive paths (high-pressure ammonia, dual-fuel systems), creating competing R&D priorities.
-
Supply-side pressure: Components and sub-assemblies exhibit concentrated risk nodes that translate into near-term cost exposure unless addressed through targeted sourcing, hedging, or local content strategies.
-
Commercial timing: Platform launches and fleet demonstration campaigns in 2025–2026 mean purchasers and fleet operators will make multi-year procurement commitments that lock in emissions baselines and total cost of ownership assumptions.
Report Deliverables: Actionable Tools for 2026 Execution
Our report moves beyond descriptive market sizing. It delivers tactical instruments senior leaders can apply immediately to reduce execution risk in 2026:
-
Supply-chain topology maps that identify single-source nodes, lead-time sensitivities, and geo-political exposure so procurement teams can prioritize near-term supplier qualification and dual-sourcing efforts.
-
BOM decomposition logic that isolates the top cost drivers within an engine build — enabling targeted cost-out programs, negotiation levers, and commodity hedging scenarios without overhauling product architecture prematurely.
-
Yield-adjustment and factory ramp models that translate small changes in process yield into financial outcomes, helping operations leaders decide between CAPEX to expand capacity and OPEX to improve output quality.
-
Technology roadmaps and decision matrices that align emissions, fuel-flexibility, and fuel-efficiency levers to realistic R&D timelines and regulatory checkpoints across major markets.
-
Compliance-cost scenario tools that quantify the incremental cost of compliance pathways (aftertreatment, SCR calibration, dual-fuel adaptation) under multiple regulatory and fuel-price assumptions.
How These Tools Resolve 2026 Pain Points
Each instrument in the report is designed to connect immediately to an executive decision in 2026:
-
Procurement teams use the supply-chain map to de-risk single suppliers before long-lead orders are placed for 2027-compliant platforms.
-
Product leaders use BOM decomposition to prioritize which sub-systems (e.g., injectors, turbochargers, aftertreatment modules) offer the highest return from targeted investment.
-
Manufacturing teams run yield-adjustment scenarios to determine whether incremental automation or revised QA gates deliver faster ROI than increasing shift or overtime capacity.
-
Strategy teams apply the roadmap and compliance-cost models to sequence platform investments so that capital committed in 2026 maximizes design-win potential while preserving retrofit flexibility.
Competitive Landscape: Dimensions That Matter in 2026
The market structure is moderately concentrated (CR3: 32.1%; CR5: 42.5%), indicating meaningful global players alongside regional champions. For 2026 strategy, the critical competitive dimensions we track — and that determine who secures Design Wins — are:
-
Regulatory engineering and rapid certification capability: ability to deliver validated emissions performance on SET/FTP cycles under 2027 NOx thresholds.
-
Platform depth and modularity: platforms that scale across power bands and fuel types reduce OEM integration cost and shorten time-to-market for variants.
-
Aftermarket and service network: total cost of ownership is decided across the life of assets; broad spares and service footprints are decisive in fleet procurement.
-
Thermal efficiency and fuel flexibility IP: higher thermal efficiency and multi-fuel readiness are growing differentiators for industrial and heavy-duty segments.
-
Supply-chain and manufacturing scale advantage: local production, supplier co-location, and controlled BOM costs lower tender prices and improve resilience.
These dimensions explain why established and emerging players gravitate toward different strategic behaviors in 2026:
-
Cummins’ emphasis on 2027-compliant platforms and cross-country demos illustrates an engineering-led moat focused on certification speed and real-world validation.
-
Caterpillar’s new C13D platform showcases a power-density and fuel-flexibility play that targets OEMs requiring heavy-duty robustness and downstream integration with large equipment portfolios.
-
Chinese incumbents are leveraging manufacturing scale and rapid innovation cycles (including breakthroughs in thermal efficiency and alternative fuels) to lock in commercial-vehicle wins at home and in adjacent markets.
-
Specialist suppliers (compact engine makers, marine-focused firms, large-bore producers) concentrate on domain-specific advantages—compactness, integrated marine systems, or dual-fuel capability—that translate into OEM partnerships rather than mass-market share.
Design Wins: The Tactical Checklist
Winning an OEM design slot in 2026 typically requires demonstrating at least three of the following:
-
Validated emissions compliance under target cycles
-
Measurable fuel-efficiency gains in representative duty cycles
-
Modular packaging for simplified integration and maintenance
-
Robust aftermarket and global support proposition
-
Competitive BOM cost supported by secure sourcing and lead-time guarantees
When suppliers fail to check these boxes, they face delayed launches or costly engineering change orders in the field—outcomes our models quantify for clients.
Technology Paths: Practical Prioritization for 2026
Given the competing pathways—incremental efficiency gains, advanced aftertreatment, dual-fuel architectures, and alternative-fuel combustion (e.g., ammonia)—our roadmap tool helps firms to set investment gates that preserve optionality without overcommitting capital.
-
Near-term (0–24 months): focus on aftertreatment integration and thermal-efficiency measures that unlock compliance with the least disruption to manufacturing and supply chains.
-
Medium-term (24–48 months): validate multi-fuel readiness and platform modularity to support variant launches and customer-specific configurations.
-
Longer-term (48+ months): selectively invest in disruptive pathways (e.g., high-pressure ammonia combustion) only where regulatory and fleet economics justify higher staging risk.
Evidence and Methodology
Our conclusions are grounded in a layered triangulation methodology designed to surface non-public commercial signal with traceable provenance. Key components include:
-
Patent and engineering-document mapping to identify emergent sub-system architectures and claim timelines in R&D pipelines.
-
On-site supply-chain audits and OEM supplier interviews, cross-referenced with customs shipment analytics to validate production footprints and supplier concentration.
-
Fleet telematics anonymized extracts and maintenance logs from large operators to benchmark real-world fuel consumption and aftertreatment performance across duty cycles.
-
Independent teardown labs that apply BOM cost modeling and yield sensitivity analysis to reconcile claimed specifications with manufacturable designs.
By layering these sources and reconciling divergent signals through time-stamped cross-validation, our analysis isolates high-confidence strategic insights while preserving commercially sensitive granular data for clients who require it. Where public disclosures exist (product launches, regulatory notices), we map those against our proprietary signals to measure implementation velocity and risk.
Practical Guidance for Executives in 2026
Executives allocating capital in 2026 should consider the following actions informed by our tools:
-
Prioritize investments that directly reduce certification and integration risk for 2027-compliant platforms.
-
Use BOM and supplier-topology outputs to negotiate fixed-price supply windows for high-exposure components.
-
Adopt modular platform strategies where feasible to preserve aftermarket revenue streams while compressing variant development cycles.
-
Establish staged R&D gates for alternative fuel projects, using fleet pilots to de-risk scale-up decisions rather than approving full production CAPEX in one step.
-
Evaluate M&A or strategic partnerships to close gaps in service networks or rapid certification capability rather than attempting expensive organic expansion under tight timelines.
Competitive Developments to Watch
Recent 2025–2026 developments underscore the importance of aligning product and go-to-market timing with regulatory cycles:
-
Cummins’ 2027 X15 demonstrations and earlier B7.2 platform updates show a deliberate pathway to certify and field-test next-generation heavy- and medium-duty platforms.
-
Caterpillar’s C13D platform transition into production in 2026 highlights the commercial push for power-dense, fuel-flexible platforms among heavy-equipment OEMs.
-
Innovations such as a high-pressure direct-injection ammonia engine introduced by a major Chinese manufacturer are raising strategic questions about long-term fuel architecture choices.
These moves are signals of how incumbents and regional champions are hedging technology and commercial risk—information our report unpacks in a way that clients can convert into procurement and R&D actions.
Access the full Diesel Engines Market report and detailed distribution maps here: https://pmarketresearch.com/auto/diesel-engine-market
Closing Perspective
For 2026, the principal strategic requirement is to reduce the option-value loss that comes from premature or misaligned commitments. PW Consulting’s Diesel Engines Market report provides the analytical instruments to do that: rigorous market sizing, supplier and BOM transparency, engineered compliance scenarios, and a technology prioritization framework. Leaders who use these tools are positioned to convert the market’s projected 5.5% CAGR into durable competitive advantage rather than exposure to regulatory and supply shocks.
For detailed analysis of this topic, please visit the official page: Diesel Engines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Robust 5.9% CAGR for the Marine Composites Market
By PW Consulting, 2026-06-26
Marine Composites Market — Strategic Outlook for 2026
The global marine composites market is at an inflection point in 2026. After a period of steady recovery and capacity realignment from 2020–2025, the market reached approximately USD 5.6 Billion in 2025 and is on a projected growth path to roughly USD 8.3 Billion by 2032, reflecting a compound annual growth rate (CAGR) of 5.9% across the 2026–2032 forecast window. For boards, procurement committees, and corporate strategy teams allocating capital in 2026, these macro dynamics create both near-term execution challenges and multi-year opportunities—especially for firms that can translate technical capability into certified, producible designs and resilient supply chains.
Marine Composites Market
Why 2026 Is a Strategic Decision Year
Several contemporaneous factors converge in 2026 to compress the window for decisive action:
Marine Composites Market
- Regulatory tightening: international and flag-state standards—such as IEC 60945 and updated classification requirements from DNV—are raising the bar on environmental and EMC performance for marine systems. In addition, recent advisory updates (including NVIC-style guidance) are increasing scrutiny on qualified electronic charting and integrated bridge systems.
- Cost-to-compliance pressure: manufacturers face rising scrutiny on lifecycle emissions and traceability as ESG reporting begins to affect tender outcomes for commercial and passenger vessels.
- Technology modularization: demand for lower-weight, higher-performance composite laminates is intersecting with the need to integrate certified electronics and sensor suites into hull structures without sacrificing manufacturability or serviceability.
Consequently, 2026 is a year when capital allocation decisions—whether for plant upgrades, material qualification programs, or strategic supplier partnerships—will materially affect competitive positioning through the remainder of the decade.
Marine Composites Market
Market Structure and Competitive Concentration
The marine composites market exhibits a moderate concentration profile: the top three suppliers account for approximately 32.4% of the market, while the top five capture about 44.8%. This structure creates a dual strategic landscape. On one hand, buyers retain meaningful leverage with a diverse supplier base; on the other, leading vendors can exercise scale economies on prepreg and resin development, certifications, and capital-intensive automated layup cells.
Actionable Frameworks in the Report
PW Consulting’s latest study is explicitly designed to convert macro trends into executable actions for 2026. The report delivers a suite of practical diagnostic and planning tools that are immediately usable by procurement, engineering, and corporate development teams:
- Supply-chain topology maps that identify critical single points of failure across resin, fiber, and specialty additive flows, and that flag regulatory choke points for export control and classification compliance.
- Bill-of-Materials (BOM) decomposition logic that separates cost drivers into raw-material, processing, and certification buckets—enabling scenario-based cost modeling under alternative sourcing strategies.
- Yield-adjustment and throughput models tailored for common layup and infusion processes, allowing teams to quantify the trade-offs between cycle-time reductions and marginal scrap rates without divulging proprietary factory parameters.
- Technology roadmaps that trace material evolution (from glass-dominant systems toward increased carbon and hybrid constructs) and outline the certification milestones firms must achieve to support a tiered product rollout in regulated markets.
Each tool is accompanied by playbooks that focus on 2026 pain points—cost control under volatile resin pricing, certification sequencing under compressed product timelines, and compliance-driven traceability. The outputs are deliberately operational: procurement can run supplier stress tests; engineering can size qualification test matrices; and finance can model staged CAPEX tied to roll-out milestones.
Competitive Dynamics and Ecosystem Players
Understanding competitive dynamics requires evaluating not only composite material specialists but also adjacent ecosystem players whose certified subsystems affect boat integrators’ design choices. Our ecosystem mapping incorporates leading marine electronics vendors whose certification and form-factor trends materially influence composite hull design and systems integration.
Competitor Dimensions — What Really Matters
Across the supplier set we track, competitive advantage is built on a few repeatable dimensions rather than one-size-fits-all metrics. PW Consulting’s analysis highlights these vectors as decisive in 2026:
- Regulatory moat: firms that maintain active DNV/IEC/NMEA certifications reduce integration risk for shipyards and yacht OEMs—this reduces time-to-market for new composite designs and increases likelihood of design wins.
- Integration depth: companies that offer systems (panel PCs, displays, embedded controllers) with documented environmental hardening and cable-routing interfaces simplify the OEM’s packaging problem inside composite structures.
- Service and field-proven reliability: for passenger and commercial applications, demonstrated mean-time-between-failure and rapid field-repair workflows are as persuasive in procurement boards as headline performance specs.
- Supply resilience: suppliers with multi-region manufacturing footprints and tested alternate sourcing for long-lead components provide a tangible mitigation against geopolitical and logistics shocks.
Examples of ecosystem players we track include vendors that specialize in marine-certified electronics (from ruggedized panel PCs to sunlight-readable displays). Their recent product upgrades and industry recognitions reflect the broader trend: tight coupling of component certification and hull-level acceptance criteria. These dynamics create windows of opportunity for composites firms that can co-develop validated integration architectures with certified subsystem vendors.
Technology and Certification Pathways
In practice, the fastest route to procurement success in 2026 is a mapped pathway that aligns compound material selection with certification milestones and supplier readiness. Key elements include:
- Early-stage co-validation protocols with certified subsystem vendors to de-risk penetrating installations and to streamline type-approval timelines.
- Controlled material substitution strategies that maintain homologation status while reducing mass or cost.
- Traceable supply-chain provenance for resins and fibers to satisfy both classification societies and corporate ESG requirements.
These are not theoretical prescriptions. PW Consulting’s deliverables include templates and checklists that enable engineering teams to convert pathway elements into test plans and procurement contracts—helping decision-makers avoid costly rework and certification delays in 2026.
Methodology: How PW Consulting Captures Hard-to-Access Signals
Our methodology is designed to produce predictive, verifiable, and action-ready insights for corporate decision-makers. The study uses Layered Triangulation: we reconcile patent analytics, production-plant audits, and buyer-side interviews against transactional supplier data and classification records. This multi-source approach permits high-confidence inferences about both cost structures and likely certification timelines—without relying on single-source declarations.
Concretely, PW Consulting combines: (a) cross-referenced patent citation mapping to identify emergent layup and resin technologies; (b) proprietary supplier-scan tools that monitor certification filings and equipment upgrades; and (c) structured interviews with Tier-1 buyers and class society technical officers. These layered inputs allow us to surface non-public signals—such as planned capacity shifts and implicit lead-time risks—while preserving supplier confidentiality and limiting exposure of sensitive contract-level data.
Strategic Recommendations for 2026
For corporate leaders allocating capital and shaping product roadmaps in 2026, PW Consulting recommends a three-track approach:
- Protect immediate tender-readiness: prioritize certification sequencing and certified subsystem co-validation agreements to defend near-term revenue streams.
- Build optionality at the material and supplier level: implement BOM scenarios and dual-sourcing pilots that can be switched on under supply stress without incurring recertification penalties.
- Invest selectively in automation that reduces per-unit labor intensity and improves reproducibility of complex laminates—targeted investments deliver measurable yield benefits within 12–24 months.
Each recommendation is anchored to the report’s practical toolset: supply-chain maps, yield-adjustment models, and BOM decomposition logic—so teams can move from strategy to execution in quarter-scale timelines.
What Stakeholders Will Gain
Readers who act on the report will be able to:
- Quantify the impact of certification sequencing on time-to-revenue for new composite products.
- Stress-test supplier portfolios for 2026 regulatory and logistics shocks.
- Calibrate CAPEX on automation and qualification with scenario-based ROI models that account for evolving material mixes and product weight targets.
Next Steps and How to Access the Full Intelligence
PW Consulting’s Marine Composites Market report is deliberately deep on actionable frameworks and diagnostic assets while reserving granular company-level projections and full regional/application splits for subscribers. To review the complete segmentation maps, BOM templates, and supplier-level appendices, access the full report at https://pmarketresearch.com/auto/marine-computers-market.
For boards and strategy teams preparing capital plans or supplier RFPs in 2026, the combination of market-sizing (USD 5.6 Billion in 2025; ~USD 8.3 Billion by 2032 at a 5.9% CAGR), concentration metrics (CR3 32.4%, CR5 44.8%), and the operational playbooks in this study will materially reduce execution risk and accelerate compliant product launches under tightened regulatory scrutiny.
For detailed analysis of this topic, please visit the official page: Marine Composites Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lead Frames Market to Expand at 4.8% CAGR from 2026 to 2032
By PW Consulting, 2026-06-26
Lead Frames Market: Strategic Intelligence for 2026 Capital Decisions
PW Consulting publishes a focused intelligence brief on the Lead Frames market that frames 2026 as a watershed year for capital allocation, compliance alignment, and product architecture choices. Our new study benchmarks the industry on a historical base (2020–2025), sets 2025 as the reference year, and models a 2026–2032 forecast horizon. At the macro level, the global market stands at USD 3,420.0 Million in 2025 and is projected to grow toward an estimated USD 4,540.0 Million by 2032, representing a compound annual growth rate (CAGR) of 4.8% across the forecast window. This release presents the strategic takeaways senior executives need now—without giving away the full segment-by-segment maps reserved for the full report.
Lead Frames Market
Executive snapshot — Why 2026 demands action
2026 brings converging pressures that make deferred decisions costly: tighter trade compliance regimes, accelerated ESG reporting, and industry-wide adoption of higher-precision process controls. In this environment, lead frame manufacturers and their OEM customers must reconcile three imperatives simultaneously:
- Protect margin while absorbing raw-material and tooling volatility;
- Demonstrate compliance to evolving ISO/ASTM and industry-specific standards that increase audit frequency and technical scrutiny;
- Invest selectively in automation and digital test integration that improve yield and shorten design cycle time.
Our report quantifies the market trajectory that underpins these imperatives and links them to actionable program-level interventions for 2026.
Market structure and concentration
The Lead Frames market remains consolidated at the top: the three largest vendors account for approximately 57.2% of market share and the top five reach roughly 72.5%. This concentration creates both strategic openings and barriers for mid-tier players—opportunities for niche specialization and risks for firms that fail to scale aftermarket services or secure Design Wins with strategic OEMs.
Key demand drivers and structural shifts
Demand in 2026 is being shaped by a mix of secular and cyclical forces. Our analysis highlights:
- Packaging evolution in semiconductor and discrete device ecosystems, where finer pitch, thinner profiles, and multi-die assemblies increase technical OEM specifications for lead frames;
- Supply chain resilience programs that prioritize validated second-source suppliers, localized tooling pools, and inventory buffers to mitigate logistics disruptions;
- Regulatory and standardization pressures—including a wave of audits tied to ANSI, ISO and ASTM verification protocols—that raise the bar for traceability and test documentation;
- Investment in test-and-measurement integration—manufacturers that pair deterministic process controls with inline verification are reducing scrap and accelerating time-to-market.
For exact regional weightings and application mixes that drive these trends, readers are directed to the geographic and application distribution charts in the full study.
Practical tools in the report — turning insight into programs
PW Consulting’s study is engineered to move teams from insight to implementation. The report includes operational tools and frameworks designed for 2026’s priorities:
- Supply chain topology maps that identify single points of failure and alternate routing options;
- Bill-of-Materials (BOM) teardown logic and a procurement cost model for scenario-driven cost reduction;
- Yield-adjustment models calibrated to process variants (stamping vs. etching) and to common defect modes, enabling targeted capital deployment for yield improvement;
- Technology roadmaps that juxtapose near-term process optimizations with medium-term platform investments (automation, inline metrology, digital twins);
- Compliance checklists tied to ISO/ASTM/ANSI verification points and a template for audit-ready traceability documentation;
- Supplier scorecards and a “cost-to-serve” matrix to rationalize second-source strategies and negotiate contractual SLAs.
Each tool is accompanied by implementation notes describing common pitfalls—e.g., over-indexing on unit cost while ignoring lifecycle service expense—and by case-based scenarios showing how the model de-risks investment choices in 2026.
Competitive dimensions: what wins look like in 2026
Our competitive analysis treats the ecosystem broadly—covering lead-frame manufacturers, advanced materials suppliers, and test-equipment vendors whose capabilities materially affect qualification speed and yield. Instead of predicting individual company roadmaps, we assess the competitive vectors that determine who wins Design Wins and who captures aftermarket value:
- Technology moat: firms that own proprietary stamping dies, micro-etch recipes, or coating chemistries gain defensibility versus pure-service providers;
- Quality and verification: vendors with integrated metrology and documentation platforms reduce OEM qualification cycles and score highly in supplier audits;
- Installed-service network: rapid onsite support and regional warehousing lower OEM switching costs and increase retention;
- Integration with OEM design flows: suppliers that co-develop with customers—providing DFMEA inputs, CAD-ready netlists, and turnkey prototyping—are more likely to secure multi-year contracts;
- Scale vs. specialization: the market supports both scale-driven firms and focused niche players—success depends on clarity of route-to-market and go-to-service models.
In the adjacent test-equipment landscape, vendors such as Instron, MTS Systems, ZwickRoell, Shimadzu, TA Instruments and others play a pivotal role by enabling stringent QC regimes. Their competitive edges vary from high-force hydraulic platforms to electrodynamic high-cycle systems and high-accuracy tabletop machines. For manufacturers, the choice of test platform is a strategic decision that affects capital cadence, facility layout, and compliance posture.
Recent product launches—such as Shimadzu’s May 2025 upgrade to its Autograph AGS-V Series and TA Instruments’ January 2025 introduction of the ElectroForce Apex 1—illustrate how incremental improvements in force measurement accuracy and dynamic characterization accelerate supplier qualification and lower lifecycle test costs. For deeper vendor benchmarking and platform selection criteria, see our supply-side vendor profiles and decision matrix.
To explore our vendor-by-vendor capability matrix, visit Lead Frames Market — full report .
Regulatory and standards impact
Regulation is not a background noise in 2026; it is a front-line determinant of capital plans. Standards such as ANSI MH16.1-2023 and prevailing ISO/ASTM verification requirements reshape the certification burden and increase the need for auditable test trails. The report maps which process modifications reduce audit risk and which investments produce the fastest return in terms of reduced qualification time.
Methodology — why our findings are actionable
PW Consulting’s methodology is structured to ensure credibility and practical relevance. Our layered triangulation approach blends patent and standards-citation analysis, Customs and procurement transaction flows, and proprietary BOM teardowns. We augment these quantitative anchors with structured interviews across 60+ supply-chain nodes—including toolmakers, contract manufacturers, and OEM procurement executives—to reconcile public filings with real-world execution patterns.
Critically, we validate supplier cost estimates through secondary market-price datasets and spot-checked quotations under non-disclosure arrangements. Where available, we incorporate confidential operational metrics shared under mutual NDAs to model yield-curve sensitivities. This hybrid of public and privileged inputs is what enables us to present executable roadmaps rather than theoretical scenarios.
Practical playbook for 2026 capital allocation
For leadership teams planning 2026 investments, the study prescribes a prioritized playbook:
- Short-term (0–12 months): deploy yield-focused retrofits and inline QC to arrest scrap and accelerate audit-readiness;
- Medium-term (12–36 months): rationalize supplier base while securing second-source tooling agreements and upgrading traceability systems for ISO/ASTM alignment;
- Strategic (36+ months): evaluate selective automation and digital test-bench investments that create persistent cost advantage and accelerate new package design cycles.
Each recommendation is accompanied by a decision checklist and scenario ROI tables so executives can fast-follow investments that protect margin and reduce supplier risk.
Next steps and how to access the full intelligence
The preview above outlines the strategic axes we believe will determine winners and losers in 2026. For the complete breakdown—including regional and application distribution maps, segment-level forecasts, vendor capability matrices, and the downloadable implementation toolkits—access the full PW Consulting report at https://pmarketresearch.com/auto/load-frames-market . The full report contains the granular charts and scenario workbooks necessary to operationalize a 2026 program.
PW Consulting stands ready to support bespoke workshops, on-site supplier audits, and financial modelling to translate the report’s insights into executable program plans aligned with your organization’s risk appetite and growth targets for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Lead Frames Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Conveyor Systems Market Poised for Expansion with a 5.8% CAGR Through 2032
By PW Consulting, 2026-06-26
Conveyor Systems Market 2026: Strategic Imperatives for Capital Allocation and Operational Resilience
PW Consulting publishes a focused industry briefing derived from our full Conveyor Systems Market report. The global conveyor systems market is in a clear growth phase: total market value rises from USD 4.0 Billion in 2020 to USD 5.3 Billion in our base year 2025, and is forecast to reach approximately USD 7.8 Billion by 2032 at a compound annual growth rate (CAGR) of 5.8%. This briefing explains why that trajectory matters for 2026 decision-making, what proprietary tools we use to turn signals into actions, and where executives should prioritize scarce capital and management attention while we intentionally withhold core segmented outputs to encourage access to the comprehensive research.
Conveyor Systems Market
Why 2026 is a Pivotal Year for Conveyor Investments
2026 is characterized by persistent raw-material-driven cost pressure, accelerating automation adoption in logistics and packaging, and heightened regulatory and ESG scrutiny on manufacturing footprints. These forces combine to make conveyor systems not merely a purchase item but a strategic lever for cost control, compliance, and throughput enhancement.
Conveyor Systems Market
-
Cost pressure: Ongoing tariffs and regional premiums on aluminum and tinplate steel continue to elevate input costs for can manufacturing and associated handling equipment, making lifecycle cost analysis and supplier hedging central to procurement decisions.
Conveyor Systems Market -
Automation shift: Buyers are accelerating investments in conveyor-driven automation to unlock labor productivity and reliability gains—especially where material handling is a bottleneck to higher-line speeds and smaller-batch runs.
-
Compliance & ESG: Food-safety sanitation, recyclability of components, and traceability requirements are turning conveyor design into a compliance task as much as an efficiency project.
Market Trajectory: What the Macros Mean for Strategy
The market’s steady expansion to USD 5.3 Billion in 2025 and projected USD 7.8 Billion by 2032 (CAGR ~5.8%) reflects structural demand rather than a temporary cycle. Three strategic inferences follow:
-
Upgrade vs. Replace: Firms should triage assets into upgrade candidates that can accept modular automation retrofits and legacy systems that require replacement due to hygiene or throughput constraints.
-
Supplier consolidation risk: Market concentration metrics (CR3 ~52.8%, CR5 ~68.4%) indicate meaningful position advantages for leading OEMs; buyers must balance the technical benefits of incumbents against supply-risk exposure.
-
Geographic and application shifts: Growth is uneven by geography and end-use. PW Consulting’s full report maps where demand intensifies and why—information that is material for capital planning and that we reserve for the source document.
Practical Tools in the Report — Solving 2026 Pain Points
The report is intentionally operational. For 2026 priorities—cost control, compliance, and uptime—we deliver a toolkit designed for execution rather than abstract forecasts. Key modules include:
-
Supply chain map and critical-path heatmap: Visualizes tier-1 and tier-2 supplier concentration, lead-time variability, and single-sourcing exposure to support procurement contingency planning.
-
BOM decomposition logic and cost-to-build templates: A structured approach to disaggregating vendor quotes into raw-material, labour, and markup layers to enable more effective negotiation and total-cost modeling.
-
Yield-adjustment and throughput models: Scenario-ready tools that translate incremental equipment or software investments into expected line-speed and yield improvements, calibrated to real-world failure modes.
-
Technology roadmap and migration pathways: A decision matrix for migrating from traditional belt/roller designs to modular, sanitation-forward, or smart-belt systems that preserves backwards compatibility where possible.
Each module is accompanied by playbooks showing how to apply outputs inside capital-expenditure approvals, RFPs, and compliance audits. We deliberately avoid publishing the core tables and segmented payoff curves here to preserve the tactical advantage available only through the full report.
Competitive Dynamics — Where Design Wins and Moats Exist
We analyze suppliers through the lens of four competitive dimensions: product differentiation (materials, belt technology), systems integration capability (line-level integration and controls), modularity/reconfigurability (speed of changeover), and commercial terms (warranty, lifecycle service). Leading firms cluster into distinct strategic archetypes:
-
Vertical integrators and full-line providers: Companies that bundle conveyors with upstream/downstream equipment (e.g., washers, dryers, processing lines) create stickiness through systems-level service contracts and faster time-to-line acceptance.
-
IP-driven component specialists: Firms with proprietary belt technologies or unique transfer solutions secure design-win advantages in sensitive applications (e.g., tight transfers to reduce spoilage), effectively creating a product moat.
-
Modular systems vendors: Providers focused on quick-reconfiguration, sanitation-first designs, and platformized modules win in the flexible-packaging and contract-manufacturing segments that demand frequent changeovers.
-
Service and aftermarket leaders: Companies that pair predictive maintenance, spare-part logistics, and yield-improvement services monetize installed bases and reduce customer TCO.
Our report profiles multiple players across these archetypes—highlighting how recent moves change competitive positioning without disclosing the confidential strategic projections included in the paid study. For instance, CPM’s 2026 portfolio expansion into chain drag and bucket elevators shifts them toward full-line integrator behavior; component specialists emphasize IP on belt architectures; and modular vendors double down on sanitation and reconfigurability. These shifts alter bidders’ calculus in RFPs and the balance of negotiation power in 2026.
Regulatory and Supply Risks: What Boards Must Monitor Now
Persistent trade measures—such as elevated U.S. tariffs and regional premiums on aluminum and tinplate steel—are materially affecting input-cost curves in 2026. That dynamic increases the importance of:\
-
Dual-sourcing and nearshoring strategies to limit exposure to import tariff volatility.
-
Design-for-cost initiatives that substitute materials or reduce bill-of-material complexity without compromising sanitation requirements.
-
Contract clauses that index long-lead purchase orders to raw-material prices or provide force-majeure clarity around tariff-induced supply disruptions.
Our supply-chain heatmaps and BOM templates are configured to translate tariff scenarios into forward-looking margin impacts and capital prioritization guidance.
Methodology — Why Our Findings Are Actionable
PW Consulting’s conclusions are the product of layered triangulation combining public and proprietary sources. Primary inputs include patent and standards analysis to identify technology roadblocks; customs and shipment records to detect flow shifts; structured interviews with OEM executives and tiered suppliers; and physical teardowns and BOM reconstructions to validate cost structures.
We apply a multi-step validation protocol: cross-referencing field-level observations with supplier financials, matching patent claims to observed product features, and stress-testing models against alternative macro scenarios. This methodology uncovers near-term signals—such as emergent design patterns, supply chokepoints, and aftermarket-service expansion—that are not visible through public filings alone. Specific datasets and triangulated segment tables are contained in the full report.
Practical Recommendations for 2026 Decision-Makers
For executives and investors confronted with tight capital budgets in 2026, PW Consulting recommends a prioritized agenda:
-
Immediate: Run a fast BOM-variance exercise on 10% of your highest-throughput lines to quantify tariff and input-cost exposure and identify short-term retrofit candidates.
-
Near-term (90–180 days): Tender modular automation pilots for high-variability SKUs where reconfigurability returns justify CAPEX.
-
Mid-term (6–18 months): Secure multi-year parts and service agreements with at least two aftermarket-capable suppliers to reduce single-supplier failure risk.
-
Governance: Add supply-chain tariff scenario reviews to quarterly capital-allocation committees and require vendor total-cost-of-ownership templates in RFP responses.
Accessing the Full Intelligence
PW Consulting deliberately uses this briefing as a “trailer”: it demonstrates analytical depth while reserving the segmented payoff curves, granular regional/application distributions, and company-level strategic forecasts for the full study. To review the complete set of tables, heatmaps, and executable playbooks, read the full report at https://pmarketresearch.com/auto/can-conveyor-systems-market.
Closing Perspective
In 2026, conveyor systems are no longer commodity capex items; they are enablers of cost control, compliance, and agility. Market momentum—reflected in steady growth from USD 4.0 Billion in 2020 to USD 5.3 Billion in 2025 and a continuation to roughly USD 7.8 Billion by 2032—creates opportunity, but that opportunity is asymmetric. Those who pair capital with the right supplier archetype, use disciplined BOM and yield analytics, and embed tariff-aware sourcing into governance will disproportionately capture upside. PW Consulting’s full report gives leaders the granular decision tools to do exactly that.
For detailed analysis of this topic, please visit the official page: Conveyor Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Battery Thermal Management System Market Poised to Reach USD 9.8 Billion by 2032 with a 12.5% CAGR
By PW Consulting, 2026-06-26
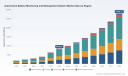
Automotive Battery Thermal Management System Market — 2026 Strategic Brief
As of 2026, the Automotive Battery Thermal Management System (BTMS) market is operating at an inflection point. After expanding from USD 2.5 billion in 2020 to USD 4.3 billion in 2025, the market is now tracking a 12.5% compound annual growth rate (CAGR) into our forecast horizon and is projected to approach roughly USD 9.8 billion by 2032. That trajectory reflects both structural demand from vehicle electrification and an acceleration of regulatory, materials and software-driven forces that are reshaping supplier economics and OEM program decisions.
Automotive Battery Thermal Management System Market
Key market dynamics shaping 2026 decision-making
The drivers that matter this year are less about single-vehicle features and more about systems-level choices that determine capital efficiency and program risk. Clients we advise are prioritizing several converging trends:
-
Regulatory pressure and data traceability: New battery lifecycle rules and passport requirements are forcing OEMs to re-evaluate BTMS architectures to support lifecycle documentation and second-life use cases.
-
Safety and functional compliance: Faster adoption of higher ASIL requirements and international transport restrictions are increasing the technical bar for thermal and monitoring subsystems.
-
Cost and materials shifts: Battery pack price deflation and chemistry shifts (notably LFP penetration) are changing the relative value of thermal performance versus per-kWh pack cost — creating trade-offs between up-front spend and lifecycle risk.
-
Software and intelligence: AI-enabled diagnostics, prognosis and thermal controls are migrating performance value from pure hardware to hardware-software co-design, favoring suppliers with combined semiconductor, software and systems capabilities.
-
Supply-chain concentration and supplier differentiation: Design wins increasingly depend on supply-chain transparency, proven manufacturing yields and integration into OEM validation cycles rather than only component performance on paper.
Why 2026 is a decisive year for capital allocation
With market size already at USD 5.0 billion in 2026 and a sustained double-digit CAGR, capital committed this year will disproportionately influence total addressable share through 2032. The urgency arises from three linked pressures:
-
First-mover cost advantage: Early bets on scalable thermal platforms and validated BOM roadmaps allow volume suppliers to compress per-unit cost before competitors replicate architectures.
-
Regulatory timing: Compliance requirements and transport limitations that take effect in 2026–2027 create hard deadlines for qualifying modules in global vehicle programs.
-
Design-win windows: OEM program timelines—shortened through platformization and zonal electrical architectures—mean suppliers that can demonstrate integrated BMS/BTMS proof-points secure longer-term production volume.
What PW Consulting's BTMS report delivers (practical, execution-focused tools)
Our new market study is deliberately operational. It packages strategic insight into a set of executable instruments for 2026 program and portfolio decisions:
-
End-to-end supply-chain map: A verified tiered supplier network that identifies single-source risks, capacity choke-points and alternative sourcing routes.
-
BOM teardown and cost-to-produce logic: A guided decomposition approach that maps component cost drivers and assembly labor sensitives to help finance and sourcing model supplier-side negotiations.
-
Yield-adjustment and scenario cost models: Parametric models that convert yield improvements, chemistry choices and localization steps into per-vehicle cost outcomes under multiple OEM ramp scenarios.
-
Technology roadmap and migration pathways: Comparative matrices that position liquid cooling, air-cooling, phase-change options and hybrid concepts against program-specific constraints (pack density, duty cycle, thermal runaway mitigation).
-
Compliance and qualification playbook: Checklists and gate criteria aligned to international safety standards, battery passport needs and upcoming transport restrictions to shorten qualification cycles.
-
Partner-selection scoring and negotiation templates: Decision frameworks that weight technical fit, manufacturing footprint, IP position and software/cloud capabilities to prioritize strategic suppliers for design-win pursuit.
Each tool is crafted for translation into board-level decisions — not as theoretical analysis but as templates and processes teams can deploy to compress time-to-qualification and reduce program-level financial uncertainty.
Competitive landscape — dimensions that determine design wins
Our competitive analysis focuses on the capabilities and moats that actually produce production programs. Across the supplier universe, we see five decisive dimensions:
-
System-level integration: Suppliers that combine sensors, power electronics, and control firmware reduce OEM validation burden and shorten integration cycles.
-
Functional-safety and standards credentials: Proven ASIL-rated platforms, pre-validated firmware and documented qualification processes materially improve selection odds.
-
IP and semiconductor leverage: Access to advanced power semiconductors, precision monitoring ICs and sensor IP is a differentiator as thermal control shifts to software-driven, fine-grained management.
-
Manufacturing and supply resilience: Near-term capacity, multi-sourcing strategies and logistics control are becoming competitive filters — not just cost factors.
-
Software and cloud services: Predictive diagnostics, lifecycle telemetry and integration with battery passports are now bid components in many OEM RFQs.
We map these dimensions against representative players to highlight where each firm has structural strengths without attempting to publish proprietary program forecasts. Examples of directional signals that reinforce these dimensions include strategic partnerships and platform launches: a recent exclusive low-voltage battery systems partnership announced by a European systems supplier highlights trend towards integrated low-voltage solutions; extensions of semiconductor-to-software collaborations illustrate the push to AI-enabled BMS capabilities; and launch of pre-validated R-BMS platforms confirms the market premium on reducing OEM validation time. These developments are discussed in-depth in the report alongside comparative supplier archetypes.
Access the full competitive maps and company profiles to validate supplier fit for your 2026 programs.
Methodology — how PW Consulting generates proprietary, actionable insight
Our findings are founded on layered triangulation and reproducible methods designed to surface non-public program indicators while meeting client confidentiality constraints. Core elements include:
-
Patent and citation analysis to track where engineering effort is concentrated and to identify emerging protective IP positions.
-
Physical BOM teardowns and validation runs performed across representative pack architectures to quantify component mixes and assembly flows.
-
Supplier audit data and an expert panel of OEM validation engineers to corroborate manufacturing capability claims and yield assumptions.
-
Proprietary procurement and freight datasets, anonymized contract sampling, and customs flows to detect sourcing shifts and capacity constraints.
-
Machine-learning–augmented models that reconcile price signals, production yields and ramp schedules into probabilistic scenario outputs.
Combining these layers enables us to surface leading indicators — for example, supplier tool orders or firmware release cadences — that are seldom visible in public filings yet materially influence design-win probabilities. The report documents our calibration steps so that clients can reproduce sensitivity analyses under their specific program assumptions.
Actionable recommendations for 2026 (executive checklist)
For executives allocating capital this year, our advisory experience and scenario testing point to a compact set of high-leverage actions:
-
CFOs and strategy teams: Prioritize funding for platforms that demonstrably lower time-to-qualification and contain validated yield-improvement roadmaps rather than modular feature add-ons that defer manufacturing risk.
-
Product leaders: Adopt co-design contracts that bind thermal hardware and BMS software providers to shared performance and diagnostic SLAs, reducing integration rework.
-
Sourcing and procurement: Execute dual-sourcing strategies for critical thermal components and secure early supplier process audits to protect ramp timelines.
-
Compliance and legal teams: Integrate passport and transportation constraints into early-stage design gates to avoid retrofit costs and shipment delays.
-
R&D and operations: Invest selectively in AI-enabled thermal control capabilities that can shift value from costly hardware improvements to closed-loop control and predictive maintenance.
Next steps — how to use this analysis
PW Consulting’s BTMS report is designed as an operational guide for teams that must convert strategy into executable program plans in 2026. If your objective is to optimize program economics, accelerate qualification cycles, or evaluate supplier trade-offs under regulatory constraint, the full dataset and playbooks enable rapid scenario testing tailored to your fleet, chemistry and geographic footprint assumptions.
For immediate access to the full suite of competitive profiles, supply-chain maps, BOM templates and scenario models, visit our detailed report page: https://pmarketresearch.com/auto/automotive-battery-monitoring-and-management-system-market .
For detailed analysis of this topic, please visit the official page: Automotive Battery Thermal Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
From USD 11,000.0 Million in 2025 to USD 15,839.0 Million by 2032 — PW Consulting Forecasts 5.5% CAGR for Butterfly Valves Market
By PW Consulting, 2026-06-26
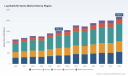
Butterfly Valves Market — Strategic Briefing for 2026
As PW Consulting’s senior industry analyst, I present a focused, action-oriented briefing designed to support executive decision-making in 2026. This release previews the strategic insights from our full Butterfly Valves Market study (base year 2025) and explains why calibrated capital allocation and supply‑chain restructuring are urgent for organizations active in fluid control today. We show the analytical structure and practical toolset of the report while deliberately withholding detailed segment-level distributions to encourage direct access to the full dataset and interactive maps.
Butterfly Valves Market
Executive snapshot
The global butterfly valves market is operating from an expanded base: the 2025 market size stands at USD 11,000.0 Million, and our forecast horizon (2026–2032) carries the industry forward at an annualized pace consistent with a 5.5% CAGR. Under this growth trajectory, the market is projected to reach approximately USD 15,839.0 Million by 2032, with 2026 acting as the first year of renewed investment cycles and regulatory recalibration.
Why 2026 is an inflection year
Several converging forces make 2026 a decisive moment for asset owners, OEMs and large distributors:
- Raw‑material volatility: late‑2025 to early‑2026 saw sharp moves in stainless steel and nickel pricing and broader metal input inflation, placing direct pressure on BOM costs and supplier margins.
- Regulatory and ESG uplift: tightening water‑quality and emissions compliance is reshaping procurement specifications and validation cycles across water/wastewater, power and industrial sectors.
- Automation and digitization push: buyers increasingly demand actuated, sensor‑ready valves that integrate with plant OT/IT stacks, creating new opportunity but also forcing legacy providers to retrofit product lines.
- Concentration dynamics: the market exhibits mid‑to‑high concentration with the top three suppliers accounting for roughly 55.0% of industry revenue and the top five near 60.0%, which sustains both pricing power and selective consolidation risk.
These dynamics drive the timing and scale of capital allocation decisions: whether to invest in local manufacturing, secure long‑lead critical materials via forward contracts, or accelerate product development for compliance-driven markets.
Practical tools inside the full report
PW Consulting’s study is structured as an operational playbook, not merely a desk survey. The deliverables are engineered for execution teams and include the following modules (examples):
- Supply‑chain topology and tiered supplier maps that link geographical nodes with critical subassembly risk scores.
- BOM decomposition logic with configurable levers for material substitution, finish specification and torque/actuation trade‑offs.
- Yield‑adjustment and scrap models that translate shopfloor process parameters into expected cost per unit under alternate scenarios.
- Technical roadmaps showing credible technology pathways from resilient seated designs to lined and high‑performance architectures, with maturation timelines and likely cost/benefit inflection points.
- Vendor scorecards and RFP templates designed to extract design‑win commitments and post‑sale service levels that are measurable in contracts.
Each tool is accompanied by implementation guidance: where to apply the lever, the typical stakeholder owners (procurement, engineering, operations), and the common pitfalls we have observed in field engagements. The report intentionally refrains from publishing fixed parameter values for proprietary models; instead, it supplies the analytic framework and calibrated inputs to run scenario analyses for your specific supply base.
Competitive landscape — dimensions that determine wins in 2026
Rather than predicting single‑firm outcomes, our report unpacks the structural dimensions that drive market success. These competitive vectors determine which players capture design wins and sustain aftermarket revenue:
- Certification and compliance moats — companies that secure sector‑specific approvals (e.g., potable‑water certifications) fast‑track procurement inclusion in municipal and OEM tenders.
- Material and metallurgy capabilities — control over alloy sourcing and casting/forging processes reduces vulnerability to raw‑material shocks and shortens time‑to‑scale for upgraded product lines.
- Actuation and systems integration — partners who offer plug‑and‑play actuators, smart positioners and digital diagnostics win specifications in modernized plants.
- Aftermarket and service networks — local presence for maintenance and spare parts is increasingly decisive for long‑term lifecycle revenues.
- Cost and delivery reliability — consistent lead times and predictable pricing during commodity cycles enable suppliers to be preferred partners for large projects.
Applying these dimensions to the competitive set yields clear implications:
- Companies with strong potable‑water certifications and established municipal relationships are advantaged in public sector tenders.
- Manufacturers with integrated actuation offerings or close OEM partnerships are better positioned to capture specification shifts toward digital valve assemblies.
- Regional low‑cost producers retain price leverage but must demonstrate compliance and aftermarket reach to unlock utility and power sector demand.
For practical, company‑level scoring by dimension — and how these scores translate into realistic design‑win probabilities for 2026 procurements — consult the detailed competitor matrices in the full report. Access the full dataset and distribution maps here: Download the full report .
Technology pathways and procurement levers
The technology section reframes product decisions as portfolio choices. We map three actionable pathways and the procurement levers that support each:
- Cost resilience pathway — prioritize material substitutions, standardized actuator interfaces and near‑term yield improvements on existing lines.
- Differentiation pathway — invest in high‑performance disc metallurgy, test‑certified sealing systems and extended warranties tied to remote diagnostics.
- Compliance and digitization pathway — couple certified materials with smart actuation and traceability systems to meet ESG and regulatory audits.
For each pathway the report supplies calibrated trade‑off matrices — indicating when incremental R&D or CapEx is likely to yield margin recovery versus when procurement contracts or hedging should be the preferred control.
Methodology — how PW Consulting builds actionable advantage
Our findings are the result of layered triangulation and primary validation executed during 2025–2026. Methodological pillars include:
- Patent and standards analysis to identify non‑obvious design protections and certification timelines.
- Hands‑on BOM reverse engineering and material assay work with sample components to benchmark supplier cost positions without disclosing proprietary line‑items.
- Customs and shipment flow analytics to map true supplier footprints and lead‑time variability across trade lanes.
- Targeted interviews with OEM procurement heads, plant engineering teams and distributor channel managers to validate adoption barriers for new valve types.
- Operational site visits and bench test data to calibrate yield and durability assumptions used in our cost models.
We emphasize the provenance of our inputs — many data points are synthesized from sources that are not publicly consolidated (customer contracts, factory yields, certified lab assays). The report documents the provenance and confidence intervals for every major assertion so that decision-makers can trace recommendations back to verifiable evidence.
Strategic priorities for capital allocation in 2026
Based on our integrated analysis, leadership teams should consider the following prioritized actions in 2026:
- Define a short list of supply‑chain continuity projects (dual‑sourcing or secured allotments for critical alloys) to insulate margins against metal price shocks.
- Mandate a 12–18 month program to convert the highest volume valve SKUs to modular actuator interfaces to accelerate digital retrofits.
- Deploy targeted CapEx to raise first‑pass yields in high‑variance casting operations rather than broad cost-cutting across all plants.
- Accelerate service and spare‑parts investments in priority regions where regulatory compliance is driving faster replacement cycles.
- Evaluate selective M&A to close capability gaps (automation, testing labs, regional service centers) rather than broad horizontal consolidation.
These priorities are calibrated to the current macro context — material inflation, ESG compliance costs and a market concentration profile that favors selective scale plays.
Next steps and how to obtain the full intelligence
PW Consulting’s full Butterfly Valves Market report contains the proprietary segmentation maps, interactive supplier dashboards and plug‑and‑play Excel models required to test all scenarios against your own portfolio. The public summary here is intentionally selective to preserve the strategic value of the underlying analytics while demonstrating the depth of our work.
To review the complete dataset, company scoring matrices and the operational toolkits described above, access the full report and interactive appendices: Download the full report .
For detailed analysis of this topic, please visit the official page: Butterfly Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vertical Turbine Pumps Market Set to Expand at a 5.2% CAGR—New Insights Reveal Shifting Regional Demand
By PW Consulting, 2026-06-26
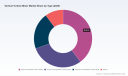
Vertical Turbine Pumps Market — Strategic Briefing for 2026: Where CapEx, Compliance and Design Wins Converge
PW Consulting publishes a forward-looking strategic briefing derived from our new Vertical Turbine Pumps Market study (base year 2025). The market is now a mature, yet dynamic, segment: total industry revenue rises from USD 200.0 Million in 2020 to USD 250.0 Million in 2025 and is forecast at a compounded annual growth rate (CAGR) of 5.2% through 2032, reaching roughly USD 355.0 Million. This briefing explains why 2026 is a high-stakes year for capital allocation — particularly for buyers, OEMs and tier‑1 suppliers wrestling with energy efficiency mandates, global trade compliance and the first wave of AI-enabled shopfloor modernization.
Why 2026 Changes the Investment Calculus
Three converging forces make 2026 pivotal:
- Regulatory tightening: Water treatment and municipal specifications increasingly mandate adjustable G-values and variable speed drive (VSD) compatibility for vertical turbine flocculators and mixers, elevating retrofit and replacement demand.
- Operational cost pressure: Energy and maintenance cost reduction remain top priorities for utilities and industrial operators, driving preference toward high-efficiency, CFD‑optimized impeller geometries and variable-speed systems.
- Technology-enabled differentiation: Design wins are shifting from price to lifecycle value — accepted suppliers now must demonstrate integration capabilities across controls, predictive maintenance and compliance reporting.
For corporate strategists, the implication is clear: allocate investment toward technologies and supply chains that de-risk compliance and deliver verifiable lifecycle operating cost benefits. Delay risks losing design‑in opportunities to competitors that pair mechanical performance with digital monitoring and compliance evidence.
Market Outlook (2026–2032)
The market trajectory through 2032 reflects steady growth and selective acceleration. After the 2020–2025 expansion to USD 250.0 Million, PW Consulting’s forecast anticipates continued expansion in 2026 and beyond, underpinned by municipal upgrades, industrial water reuse projects and targeted OEM product refresh cycles. By 2032 the addressable market reaches approximately USD 355.0 Million.
- Growth drivers include replacement cycles in legacy plants, retrofit activity for energy efficiency, and increased adoption of VSD‑enabled vertical turbine solutions in both municipal and industrial segments.
- Risks to the baseline include trade-restriction scenarios, raw-material inflation shocks and a slower-than-expected adoption of remote compliance monitoring in certain geographies.
What the Numbers Mean for Decision Makers
Quantitative growth provides the backdrop, but strategic action derives from qualitative shifts in buyer requirements: vendors must demonstrate verifiable performance gains (not just headline efficiency), and purchasing organizations must adapt procurement frameworks to value OPEX reductions and compliance readiness as primary decision criteria.
Operational Playbook in the Report — Practical Tools, Not Platitudes
Our report is intentionally engineered for practitioners. Rather than high‑level forecasts alone, the deliverable contains actionable diagnostics and models that directly address 2026 pain points:
- Supply‑chain topology maps showing critical single‑sourcing risks, lead‑time clusters and strategic nodes for nearshoring or dual‑sourcing decisions.
- Bill‑of‑Materials (BOM) deconstruction logic that ties component cost drivers to yield and reliability metrics, enabling scenario planning for price inflation and vendor substitution.
- Yield‑adjustment models and sensitivity matrices for manufacturing and field reliability that translate line‑item yield improvements into fleet‑level OPEX savings.
- Technology roadmaps that align impeller aerodynamics, materials selection and motor/control choices with regulatory thresholds and lifecycle TCO metrics.
These tools are presented as decision support engines — configured to run “what‑if” scenarios for CapEx timelines, retrofit prioritization and supplier re‑qualification. To preserve strategic value for subscribers, the report deliberately withholds detailed segment allocations in public excerpts; full distribution charts and the interactive scenario workbook are available in the full report at Access the full Vertical Turbine Mixer Market report .
Competitive Landscape — Dimensions that Decide Design Wins
Market concentration remains low-to-moderate; CR3 and CR5 indicatives show a fragmented field where specialist engineering and localized service footprints often trump scale. In this environment, winning specifications depends on a small set of competitive dimensions:
- Engineering differentiation: CFD-validated impeller designs and proven low-shear geometries secure wins in coagulation and flocculation stages.
- Systems integration: OEMs that can combine mechanical hardware with VSDs, controls and compliance reporting win longer contracts and recurring service revenue.
- Service network and lead times: Local aftermarket support and rapid spares provisioning are decisive in municipal procurement frameworks.
- Regulatory alignment: Conformance with regional engineering standards (e.g., Ten States, national water compliance rules) shortens vendor evaluation cycles.
Selected competitive profiles from our study illustrate how these dimensions play out in practice:
- Meurer Research Inc. (MRI), Colorado, USA — Positions through CFD‑optimized flocculator/mixer designs and self‑cleaning features; competitive edge lies in application-focused performance claims and use of variable speed drives to meet adjustable G‑value requirements.
- InoxMIM, Spain — Differentiates on low‑shear, axial flow mixer designs suited to homogeneous mixing; wins come from matching hydrodynamic profiles to process requirements.
- Hayward Gordon (EBARA HG), Ontario, Canada — Leverages custom engineering and a strong industrial sales channel in mining and chemical applications; moat includes heavy‑duty design heritage and acceptance in demanding environments.
- Napier‑Reid, Ontario, Canada — Focuses on adaptable vertical shaft solutions with modular impeller options; strength is flexibility in configuration and field retrofits.
- IERS Machinery, China — Competes on unit‑cost and configurable impeller diameters; key for buyers seeking cost‑efficient solutions for solid‑liquid mixing in environmental applications.
- Mixtec, South Africa / Global — Offers bespoke vertical turbine mixers with depth in fluid dynamics expertise and regional service capabilities.
- Chemineer (NOV), USA — Brings industrial-grade turbine agitator experience, attractive to process industries that prioritize robust top‑end performance and aftermarket support.
These profiles are illustrative of the dataset and analytical layers in our study. PW Consulting refrains from publishing detailed 2026 strategic forecasts for each vendor in this briefing; however, our subscribers receive scorecards that quantify each vendor across the competitive dimensions above, and identify the most likely design‑win vectors in priority procurement categories. Learn more via our full release: Access the full Vertical Turbine Mixer Market report .
Regulatory and Standards Context — Compliance as a Growth Vector
Regulatory guidance is shaping technology adoption. Two observable dynamics influence procurement in 2026:
- Water treatment standards increasingly require adjustable G‑value control paths via VSDs to optimize flocculation across seasonal and source‑water variability; procurement teams prioritize compatibility with these requirements.
- Engineering codes such as Ten States remain reference points for municipal projects; demonstrating alignment expedites approvals and reduces specification risk.
Consequently, suppliers that pre-validate performance envelopes against these standards secure faster path-to-market and lower procurement friction.
Methodology — Why Our Findings Are Actionable
PW Consulting’s study applies multi-layered triangulation to ensure both depth and actionable fidelity. Core methods include:
- Patent and technical literature mining to map innovation trajectories and infer where R&D investment is concentrated.
- Confidential primary interviews with OEM product managers, procurement leads at utilities, authorized service partners and Tier‑2 component suppliers across major geographies.
- Physical teardown logic and BOM decomposition performed in partnership with manufacturing partners to link component costs and failure modes to system‑level OPEX outcomes.
- Proprietary data fusion using customs flows, tender databases and field performance telemetry (where available) to validate revenue and shipment estimates.
These methods allow us to obtain previously unpublicized supplier-level insights (for example, supplier lead‑time concentration and validated service footprint maps) without disclosing confidential sources. The layered calibration process delivers confidence intervals on forecasts and highlights where client-level due diligence should focus in 2026.
Strategic Imperatives for 2026
For C-suite leaders and procurement heads, PW Consulting recommends four immediate actions:
- Reframe procurement metrics to incorporate lifecycle OPEX and compliance readiness as primary selection criteria, not secondary add-ons.
- Prioritize supplier relationships with demonstrable systems‑integration capabilities (motor‑control‑analytics) to capture long‑term service revenues.
- Use BOM deconstruction to identify short‑run substitution candidates and to build a prioritized list for dual‑sourcing or nearshoring pilots.
- Invest in pilot projects that combine VSD retrofits with predictive maintenance to quantify lifecycle savings within a 12–18 month window.
Early movers who act in 2026 will convert regulatory and energy pressures into competitive advantage through lower total cost of ownership and reduced procurement cycle times.
Next Steps — Where to Get the Full Analysis
This briefing highlights the analysis dimensions, tools and strategic framing from PW Consulting’s full Vertical Turbine Pumps Market study. For subscribers and executive teams planning capital allocation cycles in 2026, the full report provides interactive distribution maps, supplier scorecards, and an executable scenario workbook that links technical choices to P&L outcomes. Access the full Vertical Turbine Mixer Market report here: Access the full Vertical Turbine Mixer Market report .
For detailed analysis of this topic, please visit the official page: Vertical Turbine Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Outboard Electric Motors Market Poised for Rapid Shift — 8.5% CAGR Expected
By PW Consulting, 2026-06-26
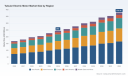
Outboard Electric Motors Market — 2026 Strategic Preview
PW Consulting’s new market study sets a 2026 strategic frame for corporate decision-makers evaluating the Outboard Electric Motors Market. Using 2025 as the benchmark year, the market has expanded from USD 500.0 Million in 2020 to USD 700.0 Million in 2025 and is projected to reach USD 1,230.0 Million by 2032 at a compound annual growth rate (CAGR) of 8.5%. These macro trajectories underline a window of strategic urgency in 2026: supply-chain positioning, design-win pacing, and compliance investments made now will materially influence competitive outcomes across the next investment cycle.
Outboard Electric Motors Market
Market snapshot — what is moving the needle in 2026
The market’s current growth is not a single-thread story. PW Consulting identifies a set of concurrent drivers reshaping capital allocation and operating priorities for suppliers, OEMs, and investors.
Outboard Electric Motors Market
-
Propulsion electrification acceleration — battery energy density improvements and inverter efficiency gains are expanding the reachable use cases for electric outboards, moving beyond niche leisure crafts to larger commercial applications.
Outboard Electric Motors Market -
Regulatory and certification pressure — tighter emissions and safety standards in key export markets are forcing earlier product re-certification and increased test-cycle investments.
-
Raw-material and component volatility — copper and specialty steels remain primary cost levers; contemporary supply shocks translate quickly into BOM-level margin pressure for high-torque models.
-
Aftermarket and service as differentiation — customers increasingly judge vendors on integration of telematics, remote diagnostics, and warranty servicing, which alters the lifetime value calculus for buyers and suppliers.
What PW Consulting’s report delivers — practical tools for 2026 execution
This study is designed as an operational toolkit rather than a purely descriptive paper. The deliverables are centered on items that directly de-risk procurement, design, and go-to-market decisions in 2026:
-
Supply-chain map with tiered supplier scoring — visibility into upstream criticality, dual-sourcing options, and substitution pathways for constrained components.
-
BOM decomposition logic and costing templates — a repeatable method to convert teardown observations into structured cost models that support scenario-based margin planning.
-
Yield adjustment and manufacturing variance models — process-sensitive levers that translate factory yield improvements into unit-cost reductions, useful for CAPEX prioritization.
-
Technology roadmap and certification matrix — cross-referencing motor architectures, power electronics, and control stacks against required regional compliance regimes (TUV, CE, UKCA, UL, RoHS) to prioritize R&D and test timelines.
-
Design-win playbooks — playbooks focused on integration testing, interface agreements, and field-validation protocols that shorten sales cycles with marine OEMs and fleet operators.
Each tool is accompanied by a practical usage guide demonstrating how teams translate findings into 12–24 month action plans to address cost pressure and compliance deadlines without revealing the proprietary subsegment numbers contained in the full report.
Competitive landscape — concentration and competitive dimensions
The Outboard Electric Motors Market exhibits moderate concentration: the top three players account for a meaningful share of the market and the top five for a still larger share (CR3: 47.0%; CR5: 54.0%). Rather than repeating private company forecasts, PW Consulting’s analysis decodes the competitive dimensions that determine winners in 2026 and beyond.
-
Defensible moats — successful incumbents combine product IP (motor design, motor-control firmware), channel exclusives with OEM boatbuilders, and certified manufacturing footprints that lower technical and regulatory entry costs for buyers.
-
Design-win determinants — reliability demonstrated through accelerated life testing, ease of electrical and mechanical integration, telematics compatibility, and a predictable warranty ecosystem are the primary gates for first-tier contract awards.
-
Adjacent actuator and control-system suppliers — the report benchmarks a group of adjacent suppliers and smart-actuator specialists (examples include Somfy Group, Nice S.p.A., JIECANG, Dooya and others) whose recent product and certification activities signal broader industry priorities around energy-efficient designs, multi-protocol IoT compatibility, and factory-level quality improvements.
-
Scale vs. specialization trade-offs — market entrants face a strategic choice: scale manufacturing to compete on unit cost or pursue deep specialization (high-efficiency PM motors, precision control) to win premium applications and recurring service revenues.
For a detailed, company-level competitive matrix and modeled scenarios of design-win probability by OEM segment, Access the full Outboard Electric Motors Market report.
Supply-chain risk, materials, and certification noise
The industry context in 2026 is characterized by a tightly coupled chain between materials, certifications, and capital deployment decisions. Key constraints and considerations:
-
Raw material exposure — copper wire and high-grade silicon steel sheet prices directly affect production economics, particularly for high-torque and higher-power-density variants.
-
Electronics chokepoints — power semiconductors and bespoke motor-control ICs have become lead-time drivers for product launches.
-
Certification and cross-border compliance — meeting divergent safety and environmental standards (TUV, CE, UKCA, UL, RoHS) is non-trivial and often requires early-stage test planning tied to engineering sprints.
-
Mitigation levers — the report details practical supply-side mitigations such as modular BOM strategies, hedging frameworks, pre-qualified secondary suppliers, and test-center partnerships.
Technology trajectories — where R&D budgets should flow in 2026
PW Consulting maps three technology thrusts that will decide product competitiveness in the near term:
-
Electromechanical efficiency improvements — emphasis on permanent magnet topologies and optimized winding techniques to increase range per kWh and reduce motor mass for equivalent output.
-
Integrated power electronics and thermal management — packaging that reduces system-level losses and simplifies vessel integration is a compelling purchase criterion for OEMs.
-
Digital-native service models — telematics, predictive maintenance, and over-the-air calibration become differentiators for fleet and commercial buyers who value uptime.
Recent industry moves — for example, product and technology updates from suppliers focusing on energy-efficient actuation, multi-protocol IoT compatibility, and manufacturing quality improvements — corroborate these priorities. PW Consulting’s technical roadmaps align R&D milestones with the certification timelines that matter to export-led manufacturers.
Methodology — how PW Consulting constructs high-confidence insights
Our research rests on layered triangulation designed to increase confidence where public data is incomplete. The approach integrates:
-
Patent and standards-analysis to map where technical differentiation exists and where freedom-to-operate constraints may arise.
-
Component-level teardowns and BOM modeling to convert physical observations into cost and yield models that reflect real manufacturing choices.
-
Proprietary customs and shipment analytics combined with confidential interviews (NDAs in place) with OEM procurement and tier‑1 suppliers to validate shipment patterns and lead-time signals.
-
Factory visits and quality-control sampling to test declared yields and observe process bottlenecks directly.
This multi-source calibration allows PW Consulting to produce directional and scenario-based guidance — including proprietary risk scores and supplier heat maps — without exposing the underlying confidential interview content or the proprietary subsegment allocations contained in the full dataset.
Actionable strategic guidance for 2026
Based on our synthesis, executives should prioritize a limited set of interventions this year:
-
Recalibrate procurement to lock secondary suppliers for copper and power electronics and embed price-adjustment clauses tied to transparent indices.
-
Front-load certification programs and design for compliance to avoid costly late-stage rework on cross-border models.
-
Invest selectively in digitalized test rigs and IoT integration to secure early design wins with fleet buyers who prize operational data.
-
Consider bolt-on M&A to acquire specialized motor-control IP or channel relationships where organic development timelines exceed time-to-market constraints.
-
Make ESG and lifecycle-cost arguments central to commercial pitches — total cost of ownership beats headline unit price in most fleet procurement decisions.
PW Consulting’s Outboard Electric Motors Market study is built to move teams from descriptive to prescriptive actions in 2026. To examine the full distribution charts, the supplier-level heat maps, and the company-by-company scenario outputs that inform recommended board-level choices, Access the full Outboard Electric Motors Market report.
For detailed analysis of this topic, please visit the official page: Outboard Electric Motors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Elastic Rail Fastening System Market Valued at USD 3,558.0 Million in 2025, Poised for Further Expansion
By PW Consulting, 2026-06-23
Elastic Rail Fastening System Market — Strategic Briefing for 2026
PW Consulting publishes a focused industry briefing to inform capital allocation and operational choices in 2026 for executives, investors and OEMs active in the elastic rail fastening systems ecosystem. Our analysis shows the global market is operating at scale — USD 3,558.0 Million in 2025 and advancing into 2026 at roughly USD 3,607.5 Million — with a steady compound annual growth rate (CAGR) of 4.35% across the 2026–2032 forecast window. Market concentration is meaningful: the top three suppliers control approximately 41.8% of revenue, and the top five about 58.6%, a structure that shapes procurement dynamics, pricing power and design‑win strategies.
Elastic Rail Fastening System Market
Executive snapshot: what matters in 2026
-
Growth vector: Demand is being driven by a mix of new line construction, targeted upgrades for heavy‑axle and high‑speed categories, and network-level asset renewal programs that emphasize lifecycle cost over upfront price.
Elastic Rail Fastening System Market -
Standards and compliance: EN 13481 (including the new Category E for very high axle loads) and AREMA laboratory protocols are the operational thresholds buyers and suppliers must clear — noncompliance risks contract delays and warranty exposure.
-
Input cost volatility: Steel and spring‑steel processing remain the dominant material story; energy and logistics shocks materially affect margin for clip manufacturers and can force rapid re‑pricing or contract renegotiation.
-
Consolidation effects: Moderate concentration magnifies the value of design wins and local production footprints; securing early specification inclusion now yields outsized returns over multi‑year lifecycle contracts.
Why this report is strategically valuable for 2026 decision making
-
Time sensitivity: With standards tightening and major procurement cycles kicking off in several markets, late movers face higher technical and commercial barriers to entry; the report helps prioritize where to deploy capital and engineering resources this calendar year.
-
Risk reduction: Readers receive an operationally focused view — not just topline forecasting — that pinpoints where supply chain fragilities and material cost exposure will impact project margins and delivery schedules.
-
Commercial leverage: The combination of concentration metrics and supplier‑level behavioral analysis allows procurement teams to design contract clauses and test acceptance criteria that reduce warranty and interface risk.
Practical tools included in the full PW Consulting report
The report is deliberately tool‑oriented: it is designed to be used during procurement cycles, R&D prioritization and M&A screening rather than as a high‑level narrative. Highlights of the practical content include:
-
Supply chain map that traces material and sub‑component flows from steel mills through specialty spring processors, heat‑treat suppliers, and final assembly nodes.
-
BOM (bill of materials) deconstruction logic that isolates cost drivers (material, processing, testing, logistics) and shows where small improvements in yield or scrap reduction have outsized unit‑cost impact.
-
Yield adjustment and sensitivity models that translate factory yield rate changes, raw‑material price swings and energy costs into per‑clip margin outcomes — enabling targeted CAPEX and process improvement business cases.
-
Technology roadmaps and failure‑mode matrices that tie specific fastening topologies to service life, fatigue behavior and maintenance frequency — useful for O&M contracting and whole‑life costing.
-
Design‑win playbook that documents interface tolerances, test evidence expectations and procurement decision triggers buyers typically use when choosing a fastening supplier for heavy‑haul, high‑speed or transit projects.
How these tools address immediate 2026 pain points
-
Cost control: BOM decomposition plus yield models let manufacturers and owners quantify the ROI of process upgrades (heat‑treat, coating, trimming) rather than relying on generic productivity targets.
-
Compliance and acceptance: Standards crosswalks and test‑protocol templates shorten lab validation cycles and reduce rework during tenders that reference EN 13481 or AREMA Chapter 30.
-
Design portability: A standardized design‑win checklist reduces the time to qualify new suppliers into global projects where interface compatibility is the gating factor.
Competitive landscape — the dimensions that determine winners
PW Consulting evaluates incumbent and emerging suppliers through the lens of competitive dimensions rather than publishing prescriptive 2026 forecasts for each firm. The decisive factors we see in 2026 are:
-
Engineering IP and testing capability: Suppliers with proprietary clip geometries and in‑house test laboratories convert technical advantage into shortened qualification timelines.
-
Manufacturing footprint and localization: Proximity to major projects plus local content credentials materially improve bid competitiveness in regulated markets.
-
Integrated offering: Suppliers that bundle fastenings with sleepers, turnouts or slab solutions often win on logistics simplicity and warranty alignment.
-
Cost and scale: Large, vertically integrated producers can absorb raw‑material volatility for longer periods, enabling more aggressive short‑term pricing during intense tender cycles.
-
Standards track record and credentials: Prior performance on EN/AREMA testing and documented lifecycle studies remains a primary differentiator in award decisions.
These dimensions are visible across the industry spectrum — from global platforms to regional specialists. Recent contract awards and partnerships underscore the interplay between engineering capability and execution footprint: for example, Vossloh’s recent contract awards for major line works and Progress Rail’s partnership to integrate composite ties with fastening solutions are indicative of how design scope and supply integration are shaping the competitive agenda (Vossloh — April 2026; Progress Rail — April 2026).
Technology, materials and supply chain dynamics
-
Material reliance: Spring steel remains the critical input due to its fatigue and tensile requirements; any disruption in supply, energy or processing capacity quickly propagates into lead‑time risk.
-
Manufacturing upgrades: AI‑assisted process control and inline metallurgical monitoring are becoming differentiators for suppliers seeking higher margin through yield improvement rather than pure price competition.
-
ESG and trade compliance: Local content rules, anti‑dumping scrutiny and lifecycle carbon calculations increasingly influence procurement specifications; manufacturers without traceable upstream data are disadvantaged.
-
Standards evolution: The expanded EN 13481 category set for heavy axle loads and AREMA laboratory expectations push product development cycles toward higher‑performance alloys and stricter QA protocols.
Methodology — how PW Consulting builds confidence in non‑public insights
PW Consulting applies a layered triangulation methodology to construct firm, actionable intelligence. Our approach combines patent‑citation analytics, tender and customs flow parsing, contract and certification audits, and structured interviews with engineering teams across OEMs, Tier‑1 suppliers and infrastructure owners. Where permissible, we validate physical properties through metallurgical testing and factory walkthroughs under NDA.
Key elements of our rigor include:
-
Patent analysis to map technology diffusion and identify proprietary geometries and heat‑treat methods that correlate with superior fatigue performance.
-
Multi‑node triangulation: cross‑referencing supplier quotes, tender award language, and in‑field sensor data to reconcile declared capacities and actual delivery performance.
-
Confidential procurement interviews and supplier site engagements conducted under formal non‑disclosure agreements; these provide the behavioral context (lead times, spoilage rates, warranty disputes) that public filings do not capture.
Actionable recommendations for 2026
-
Prioritize supplier qualification that couples technical testing (EN/AREMA) with traceable upstream material provenance; this reduces late‑stage acceptance risk.
-
Model hedging or indexed contracts for spring‑steel exposure; use the report’s yield and sensitivity tools to size hedges versus CAPEX for process upgrades.
-
Accelerate pilot programs that embed inline metallurgical monitoring and AI process control where yield improvement pays back within 12–24 months.
-
Evaluate strategic partnerships or bolt‑on acquisitions to obtain localized manufacturing capacity in regulated markets where local content or rapid response is a contract award criterion.
Next steps and how to access full deliverables
PW Consulting’s full Elastic Rail Fastening System Market report contains detailed regional and application splits, interactive BOM worksheets, supplier scorecards and the complete technology roadmap—information we intentionally gate to preserve client value and to enable direct engagement on implementation. For immediate access to the complete dataset, modeling files and our vendor‑selection templates, visit our project page: Access the Elastic Rail Fastening System Market report .
Closing perspective
2026 is a year of operational inflection for the rail fastening sector: standards tightening, material volatility and procurement cycles are combining to make timely, data‑driven decisions materially value‑accretive. PW Consulting’s operational toolset and triangulated market intelligence are designed to convert market visibility into defensible actions — whether the objective is to win design slots, stabilize margins or accelerate manufacturing modernization.
For detailed analysis on this topic, please visit the official page:
Elastic Rail Fastening System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Metal Dryer Market Poised for Steady Expansion — 4.4% CAGR Forecast Through 2032
By PW Consulting, 2026-06-23
Metal Dryer Market 2026: Strategic Preview for Capital Allocation and Operational Resilience
PW Consulting publishes a focused industry briefing drawn from our comprehensive Metal Dryer Market study (base year 2025). This briefing highlights the strategic imperatives that will shape capital allocation, procurement, and compliance decisions in 2026. It is designed as a high-value executive primer — revealing the framework, directional trends, and competitive dimensions while reserving detailed segment tables and company-level forecasts for the full report.
Metal Dryer Market
Why 2026 Is a Pivotal Year
After five years of uneven recovery, the market for metal dryers has reached 1,942.2 Million USD in 2025 and continues to expand, with PW Consulting modeling a rise to 2,023.5 Million USD in 2026. Over the 2026–2032 forecast window the sector compounds at a steady 4.4% CAGR, reaching 2,625.4 Million USD by 2032. These macro trajectories reflect both demand-side recovery in metal processing and supply-side adjustments driven by tariffs, steel-price volatility, and accelerating regulatory scrutiny.
Metal Dryer Market
For corporate decision-makers, 2026 is therefore a year to convert strategic intent into executable programs: rebalancing supplier networks, accelerating efficiency projects, and locking in certifications and design wins that are becoming harder to obtain as compliance complexity increases.
Key Market Dynamics Shaping 2026 Decisions
- Tariff and trade pressure: Expanded tariffs on steel/aluminum derivatives in 2025 are re-shaping procurement cost structures and forcing localized sourcing decisions.
- Raw material volatility: Steel price swings and component availability are increasing lead times and capex variability for dryer OEMs and fabricators.
- Technology-driven differentiation: Modular, energy-efficient platforms and adaptability to recycling and battery-related metal streams are emerging as commercial differentiators.
- Service economics: Aftermarket service, spare-parts assurance, and process qualification support are as important as initial equipment cost for long-term TCO.
What the PW Metal Dryer Report Provides (Practical Tools)
The full PW report is intentionally operational. It equips teams with tools they can apply directly during 2026 strategic cycles without disclosing sensitive segment-level disclosures in this preview:
- Supply chain maps that trace component origin, sub-tier concentration, and tariff exposure across manufacturing footprints.
- BOM decomposition logic and benchmarking templates that allow procurement teams to model cost drivers and identify substitution levers.
- Yield-adjustment and process-efficiency models to quantify the lift from targeted CAPEX and tuning projects in a plant-by-plant view.
- Technology roadmaps that align dryer architectures (e.g., conveyorized, helix, spray) with emerging application requirements such as battery recycling and high-temperature metallurgical flows.
- Compliance and certification playbooks that translate regional regulatory shifts into actionable steps for design validation and product positioning.
How Those Tools Solve 2026 Pain Points
Each deliverable is framed for immediate application in 2026 priorities:
- Cost control — BOM and supplier-mapping accelerate negotiation cycles and expose low-risk material substitutions that reduce exposure to steel-price and tariff moves.
- Capex sizing — yield and TCO models enable capital committees to compare retrofit options vs. greenfield investments using consistent KPI sets.
- Compliance-readiness — the certification playbook trims time-to-market by identifying pre-validated suppliers and test programs aligned with new regulatory requirements.
- Commercial defense — technology roadmaps and service economics models identify the most durable sources of margin (e.g., modular platforms, retrofit kits, service contracts).
Competitive Landscape: Dimensions That Matter (not Predictions)
Our competitive analysis focuses on structural competitive dimensions rather than giving away firm-level forecasts. Across OEMs and system integrators, PW Consulting evaluates capabilities along a set of core vectors that determine future design wins and margin capture:
- Manufacturing footprint and tariff exposure — proximity to key metal inputs and ability to de-risk supply chains through alternate plants.
- Product platform modularity — how easily a base dryer design can be adapted for different process chemistries or throughput classes.
- Certifications and test capability — possession of recognized test protocols shortens customer validation cycles in regulated end markets.
- After-sales infrastructure — warranty, spare parts distribution, and field services that convert one-time sales into long-term revenue streams.
- IP and engineering depth — patents, process know-how, and simulation models that create technical switching costs for customers.
Illustrative company positions in the competitive frame (examples, not exhaustive): Despatch Industries leverages specialized high-performance ovens and established test certification programs; legacy builders like The Grieve Corporation and Blue M emphasize proven industrial track records and customizable platforms; Best Technology and Baron Blakeslee focus on parts-dryer specialization with robust field-oriented controls; ANDRITZ is advancing recovery- and recycling-oriented dryer technologies. Recent public moves — Despatch’s ASTM testing capability update (Oct 2025) and ANDRITZ’s helix and modular spray-dryer introductions (Mar–Apr 2026) — validate that certification and adaptable architectures are current commercial battlegrounds.
Market Structure and Concentration
The market displays moderate concentration: the top three players account for 38.5% of value and the top five reach 52.7% (CR3 = 38.5%, CR5 = 52.7%). This structure favors specialist OEMs with deep service networks, but also leaves niches where agile entrants can win with differentiated value propositions — particularly in modularity, energy-efficiency, and regulatory alignment.
Methodology: Why Our Findings Are Actionable
PW Consulting’s conclusions rest on a layered triangulation methodology designed to surface not-previously-published operational intelligence. Core elements include patent and technical-publication mining, customs and shipment analytics, a structured program of confidential supplier and end-user interviews, on-site verification under NDAs, and reverse-engineered BOM estimations using material-cost modeling.
We cross-validate qualitative intelligence (e.g., supplier capability statements, field service logs) with quantitative signals (shipping flows, historical pricing, and publicly filed financials) and validate scenarios through engineering simulation where applicable. This mixed-method approach is why our models consistently align with material realities that matter to procurement, engineering, and M&A teams.
Strategic Guidance for 2026
- Prioritize supplier diversification for high-exposure BOM nodes before contractual windows close; the tariff backdrop and steel volatility are compressing negotiation timelines.
- Invest selectively in retrofit programs that improve yield or energy efficiency; the TCO uplift often outperforms greenfield replacements when measured against the 4.4% sector CAGR and near-term demand uncertainty.
- Lock technical and certification prerequisites early for target markets where compliance is a gating factor — certification-led design wins are an increasingly decisive advantage.
- Consider service-led growth: packages that combine installation, predictive maintenance, and spare parts can shift margin mix favorably in an otherwise stable demand environment.
Where to Find the Detailed Evidence
This briefing intentionally omits granular regional and application splits and full firm-level 2026 strategy forecasts. PW Consulting’s complete Metal Dryer Market report contains the segmented distribution maps, per-region exposure dashboards, detailed BOM templates, and company-by-company strategic scenarios that boards and investment committees require. Access the full dataset and operational annexes here: Full Metal Dryer Market Report — PW Consulting .
Final Note for Executives
2026 is a calibration year — the market is neither hypergrowth nor static. The 4.4% CAGR through 2032 signals steady demand, but the strategic landscape is defined by compliance complexity, material-cost volatility, and an intensifying premium on modular, serviceable platforms. Executives who pair rigorous supply‑chain diagnostics with targeted CAPEX and certification programs will convert market stability into durable advantage.
For detailed analysis on this topic, please visit the official page:
Metal Dryer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


