



Category: Machinery & Automotive
PW Consulting: Automotive Auxiliary Heater Market Hits $2.2B in 2025, Thriving for 2032
By PW Consulting, 2026-09-16
Navigating the Thermal Edge: Strategic Intelligence for the Automotive Auxiliary Heater Market 2026-2032
The automotive auxiliary heater market stands at a critical inflection point where thermal comfort, emissions compliance, and electrification converge to reshape aftermarket value chains and OEM procurement strategies. As vehicle architectures grow increasingly complex and regional operating conditions demand reliable cabin and engine preconditioning, auxiliary heating systems have evolved from convenience accessories to mission-critical components. Our newly published Automotive Auxiliary Heater Market study delivers a granular, forward-looking intelligence package designed specifically to support enterprise decision-making through 2032. This overview highlights the strategic architecture of the research, the competitive forces shaping pricing and technology roadmaps, and the regulatory tailwinds that will dictate margin structures and market entry timing in the coming years.
Market Trajectory and Base-Year Dynamics
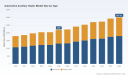
Over the past half-decade, the sector has demonstrated resilient demand expansion anchored by cold-climate markets, commercial fleet operational requirements, and the gradual migration of passenger vehicles toward supplementary heating architectures that complement main powertrains. The market’s baseline valuation for 2025 rests at approximately 2.2 billion USD, signaling a sustained recovery and incremental share capture following the volatility of the early 2020s. Historical performance from 2020 through 2024 reveals a compound trajectory marked by moderate but consistent growth, with annual valuations progressing from 1.8 billion USD to roughly 2.05 billion USD before crossing the 2.2 billion USD threshold in the base year.
Automotive Seat Heater Market
Looking ahead, the forecast horizon from 2026 to 2032 projects a compound annual growth rate of 4.5 percent, steering the market toward a 3.0 billion USD milestone by 2032. These directional figures provide a stable macroeconomic scaffold for capacity planning, channel investment, and portfolio prioritization. Yet, aggregate valuations alone do not reveal the operational leverage points that executives need. Our analysis dissects demand concentration across product architectures, application verticals, and geographic corridors without flattening the nuance that actually guides sourcing, localization, and pricing strategy. The report quantifies how revenue is structurally distributed across air-based and water-based heating modalities, how passenger car and commercial vehicle segments command differing margin profiles, and how regional demand intensity drives localization requirements for assembly, service networks, and regulatory compliance.
Equally important is the competitive concentration backdrop. The top three participants collectively account for roughly one-third of market revenue, while the top five expand that share to just under half. This fragmented-but-tiered structure creates a strategic environment where scale advantages matter, but differentiation through technology, service ecosystems, and regional compliance capabilities can still yield outsized share gains. The study examines supplier positioning, channel influence, and OEM dependency patterns to help firms anticipate pricing pressure, negotiate component roadmaps, and identify partnership opportunities before the next consolidation wave.
Automotive Auxiliary Heater Market
Why This Study Matters for 2026 Decision-Making
Entering 2026, executives face a set of interlinked imperatives: aligning product portfolios with electrification mandates, managing customs and duty exposure in cross-border supply chains, preparing for evolving safety and emissions oversight, and timing capacity investments against uncertain demand pacing. This report is engineered to convert those uncertainties into a sequenced decision framework. Rather than offering static sizing tables, the research maps the operational levers that determine commercial outcomes in real market conditions.
- Strategic sizing and scenario planning that translate baseline and forecast valuations into capacity, inventory, and capex decisions calibrated for 2026-2032
- Segment-level demand characterization across heater types, vehicle applications, and regional corridors to prioritize where to allocate engineering resources and commercial efforts
- Competitive benchmarking of incumbent manufacturers and emerging entrants, including product line breadth, OEM relationships, and recent innovation cadence
- Regulatory and trade exposure assessment that connects safety oversight, duty classification, and environmental standards to landed-cost modeling and market-entry sequencing
- Technology transition mapping that tracks the shift from fuel-operated heating platforms toward electric and hybrid auxiliary architectures, with implications for component sourcing and service reliability
The analytical depth is designed to support cross-functional teams. Procurement leaders can use the supplier landscape and concentration metrics to stress-test sourcing strategies and negotiate long-term agreements with a clearer view of rival capacity. Product and engineering teams gain visibility into how application requirements and regional operating conditions influence performance expectations and warranty profiles. Commercial and market-development teams receive the segmentation and regional context needed to determine where to localize distribution, service, and technical support. And strategy leaders can integrate the regulatory and trade dimensions into investment sequencing, prioritizing markets where duty exposure, safety compliance, and emissions definitions create either friction or first-mover advantage.
Competitive Landscape and Innovation Cadence
The supplier ecosystem is anchored by a small group of technically sophisticated incumbents, each with distinct positioning across OEM channels, application segments, and heating architectures. Webasto, headquartered in Gilching, Germany, has built a broad portfolio spanning OEM diesel fuel-operated parking heaters such as the Air Top, Thermo Top, and Thermo Plus series, alongside electric PTC auxiliary heaters serving passenger cars, commercial vehicles, buses, and heavy-duty trucks. The company’s recent activity signals a deliberate push toward higher-power electric heating platforms and smarter parking heat solutions. In April 2026, Webasto launched modular PTC air heaters delivering up to 2,100 watts of heating power tailored for electric commercial vehicles, reinforcing the strategic pivot toward electrified thermal management. In October 2025, the firm announced the Thermo Top Evo Smart parking heater for passenger cars with up to 5 kW heating capacity and extended warranty options, a move that emphasizes user convenience and post-sale value. Earlier in March 2025, Webasto showcased the Air Top Pro 25 fleet heater at Work Truck Work in Indianapolis, underscoring continued attention to commercial vehicle applications.
Eberspächer, based in Esslingen, Germany, maintains a complementary but distinct footprint with OEM fuel-operated air heaters, notably the Airtronic series, and pre-heater solutions targeting passenger cars, commercial vehicles, and special-purpose applications. Valeo, headquartered in Poissy, France, concentrates its auxiliary heater offering on OEM diesel auxiliary heaters under the Thermo+ series, with a particular emphasis on commercial vehicles and buses. Espar, operating from Germany, rounds out the core group with OEM fuel-operated parking heaters and auxiliary heaters designed for commercial vehicles, vans, and trucks. Together, these players illustrate the dual tension shaping the market: incumbents must defend share in established fuel-operated segments while simultaneously expanding electric and modular offerings to align with fleet electrification and changing emissions expectations.
The study examines how these profiles translate into competitive dynamics. It evaluates product differentiation through heating power ranges, control intelligence, warranty structures, and application focus. It also assesses how recent launches and trade-show presentations indicate where each supplier is directing engineering investment, which customer segments they are prioritizing, and how their roadmaps may influence pricing and availability over the forecast period. By mapping innovation cadence alongside channel reach, the report helps decision-makers anticipate where competition will intensify, which OEM relationships may shift, and where niche application expertise can serve as a durable moat.
Market Dynamics: Regulation, Trade, and Technology Shifts
Market outcomes in this sector are increasingly shaped by oversight, classification, and definitional clarity as much as by pure demand growth. Safety monitoring remains a persistent factor. In 2025, NHTSA safety recalls affected Valeo Thermo+ auxiliary heaters installed in commercial buses, alongside electric auxiliary heaters in certain BMW models. These events illustrate how component reliability, integration complexity, and fleet operating conditions can quickly convert technical performance into reputational and compliance risk. For OEMs and Tier-1 suppliers, such developments reinforce the need for rigorous validation protocols, traceability, and service readiness.
Trade policy adds another layer of strategic complexity. In February 2026, US Customs classified auxiliary heater units under HTS 8419.50.50 with a 4.2 percent ad valorem duty rate. This classification has direct implications for landed-cost modeling, sourcing geography, and inventory placement. Companies that rely on cross-border components or finished-unit importation must revisit duty exposure, evaluate assembly localization options, and assess whether regional value creation can improve cost competitiveness while reducing tariff risk. Our report incorporates these trade dimensions into market-entry and supply-chain analysis so that commercial teams can quantify cost sensitivity and align procurement with logistics strategy.
Regulatory classification is also sharpening. The EPA CHDV program manual released in July 2025 explicitly defines an auxiliary heater as a supplementary heating system for the passenger compartment, engine, or both. This definition carries operational significance because it clarifies reporting boundaries, operational scope, and compliance expectations. Meanwhile, Federal Motor Vehicle Safety Standards 571.301 require compliance for auxiliary heating systems in school buses, as reflected in Nevada Minimum School Bus Standards for 2026. These requirements matter because they influence which applications demand more stringent safety engineering, which customer segments will tolerate higher validation costs, and where service and support models must be adapted to meet public-sector procurement expectations.
Beyond regulation, technology adoption is shifting demand composition. Webasto has reported increasing adoption of electric auxiliary heaters in commercial vehicles as fuel-powered vehicles are phased out. This trend signals a structural transition in the commercial segment that will influence heater architecture mix, component sourcing, and supplier roadmaps. Electric auxiliary heaters are not simply substitutes; they change thermal management logic, integrate more tightly with vehicle electrical systems, and may modify warranty requirements and service practices. Understanding the pacing of this transition is essential for firms deciding whether to invest in fuel-operated capacity, electric heating platforms, or hybrid offerings that hedge across multiple powertrain paths.
What the Report Delivers in Practice
The study is structured to move from strategic context to actionable intelligence. It opens with market sizing and growth dynamics, grounding executives in baseline and forecast valuations while establishing the 4.5 percent CAGR trajectory as the analytic spine for scenario work. From there, it progresses into segmentation-driven analysis that reveals how revenue is distributed across heater types, application categories, and regional markets. These characterizations are presented in a way that highlights where demand intensity, margin potential, and competitive pressure converge, without flattening the market into overly simplified aggregates.
The competitive section profiles key participants and evaluates their offerings, recent developments, and strategic focus areas. It incorporates product launch activity, trade-show positioning, and technology direction to help readers infer where investment is flowing and which segments may face greater rivalry. The dynamics section integrates regulatory, trade, and technology factors into a single operating lens, so that compliance risk, duty exposure, and electrification transition are treated as interrelated business drivers rather than isolated footnotes. The report also addresses concentration metrics and supplier influence to inform negotiation posture and partnership strategy.
Throughout, the analysis is designed for practical use. Commercial teams can leverage segmentation context to prioritize geographies and applications. Engineering and product teams can align heater architecture roadmaps with application requirements and electrification trends. Procurement and supply-chain leaders can factor duty classification, recall risk, and supplier concentration into sourcing and inventory strategies. Executives can combine the forecast scaffolding with regulatory and competitive intelligence to time investments, define market-entry sequencing, and calibrate portfolio commitment against uncertainty.
How to Use This Intelligence
The emphasis of this research is on decision readiness. The market outlook provides the numerical foundation, but the strategic value lies in how that foundation connects to real operating choices. Firms evaluating capacity expansion can use segmentation and regional insights to determine whether to invest broadly or concentrate resources in the most favorable demand corridors. Suppliers weighing product architecture can use the technology-transition signals and recent launch patterns to decide whether to expand electric offerings, refine fuel-operated platforms, or pursue modular systems that can be configured across multiple vehicle categories. OEM-adjacent businesses can use the recall and compliance context to strengthen validation, service readiness, and documentation processes that reduce downstream risk.
For market-entry planning, the report’s combination of concentration data, competitive profiles, and regulatory detail helps identify where incumbents are strong, where customer requirements may be underserved, and where classification or duty exposure alters the cost equation enough to influence localization choices. For portfolio strategy, the interplay between passenger car and commercial vehicle applications, along with the shifting balance between air-based and water-based heater types, supports a more precise allocation of engineering and commercial resources than aggregate market size alone would allow.
Where to Go Next
This overview provides the strategic frame, but the full intelligence package contains the segment-level detail, competitive analysis, regulatory mapping, and scenario scaffolding required to convert direction into execution. To access the complete market study, including the segmentation structures, supplier positioning, and operating-context analysis that underpin the 2026-2032 outlook, visit the source report page. There you will find the full dataset, qualitative insights, and decision-support materials needed to align your strategy with the market’s next phase of growth.
For detailed analysis of this topic, please visit the official page: Automotive Auxiliary Heater Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: RFID Smart Cabinet Market to Hit $1.18B by 2032, 9.5% CAGR
By PW Consulting, 2026-09-16
Navigating the RFID Smart Cabinet Revolution: Strategic Intelligence for 2026 Enterprise Decision-Making
Executive Overview
The enterprise landscape is undergoing a profound transformation driven by the need for real-time visibility, operational efficiency, and stringent regulatory compliance. At the forefront of this shift is the RFID Smart Cabinet market, a specialized yet rapidly expanding sector within the broader Internet of Things (IoT) and asset tracking ecosystem. As organizations across healthcare, manufacturing, and logistics strive to eliminate inventory blind spots, smart cabinets equipped with Radio Frequency Identification (RFID) technology have emerged as a critical infrastructure component.
This article serves as a strategic primer for executives and industry analysts evaluating the RFID Smart Cabinet market. It synthesizes key macro-economic trends, competitive dynamics, and regulatory drivers that define the current landscape. While this overview provides a high-level perspective on market momentum and structural forces, a comprehensive understanding of specific growth vectors, regional nuances, and detailed segment analysis requires access to the full proprietary research dataset. The following insights are designed to highlight the strategic imperative for action in 2026 while underscoring the depth of intelligence available through our complete market study.
Macro Market Trajectory: From Recovery to Accelerated Expansion
The trajectory of the RFID Smart Cabinet market over the past half-decade illustrates a robust recovery and acceleration pattern. Historical data from 2020 through 2025 demonstrates a consistent upward trend in revenue generation, reflecting increasing enterprise adoption rates and the maturation of RFID technology. The market has moved beyond early adoption phases into a period of scaled deployment, where the value proposition of automated inventory management is now widely recognized across multiple verticals.
Looking forward, the forecast period spanning 2026 to 2032 indicates a continued period of significant growth. Market projections suggest that the industry is poised to reach new revenue milestones, driven by the integration of advanced IoT capabilities and the pressing need for supply chain digitization. The compound annual growth rate (CAGR) during this forecast window remains a key indicator of market health, signaling sustained investor confidence and technological innovation. This growth is not merely linear; it represents a structural shift in how high-value assets are managed, tracked, and secured within enterprise environments.
For strategic planners, these macro trends suggest that delaying investment in smart cabinet infrastructure could result in competitive obsolescence. The momentum is clear: the market is expanding, and the baseline for operational efficiency is being raised by early adopters who are leveraging real-time data to optimize workflows. However, navigating this expansion requires more than just recognizing the growth trend; it demands a granular understanding of where value is being created and how market share is distributed among key players.
Key Industry Dynamics and Regulatory Drivers
The expansion of the RFID Smart Cabinet market is not happening in a vacuum. It is heavily influenced by a confluence of regulatory mandates, technological cost reductions, and operational necessities. Understanding these dynamics is essential for assessing risk and opportunity in the current investment cycle.
- Healthcare Compliance Mandates: The healthcare sector remains a primary driver of demand. Regulatory frameworks such as the U.S. FDA Unique Device Identification (UDI) mandate enforce strict requirements for medical device tracking. This directly increases the demand for RFID smart cabinets in hospital inventory compliance, ensuring that supplies are not only tracked but also auditable in real-time. Furthermore, Joint Commission standards require real-time inventory tracking for high-value medical assets, driving adoption of RFID smart cabinets in U.S. hospitals. These compliance pressures transform smart cabinets from a luxury into a necessity for risk management.
- Cost-Effectiveness and Scalability: A critical enabler of widespread deployment is the cost structure of underlying RFID components. Passive UHF RFID tag costs are projected to range from $0.05 to $0.15 per unit in high volume for 2026. This reduction in unit cost enables scalable smart cabinet deployments, allowing organizations to tag individual items within cabinets without prohibitive expense. This economic shift lowers the barrier to entry for smaller facilities while enhancing the ROI for large-scale health systems.
- Standardization and Interoperability: Reliable tracking relies on adherence to global standards. ISO 18000-63 and EPCglobal Gen2 protocols govern RFID smart cabinet operations in industrial and healthcare environments. Compliance with these standards ensures that hardware and software from different vendors can interoperate, reducing vendor lock-in risks and facilitating smoother integration into existing enterprise resource planning (ERP) and supply chain systems.
- Supply Chain Digitization: Broader initiatives by the FDA and Joint Commission compliance mandates for supply chain digitization accelerate RFID smart cabinet installations in healthcare facilities. The push for end-to-end visibility means that point solutions are no longer sufficient; cabinets must communicate seamlessly with broader logistics networks, creating a demand for connectors and APIs that enhance system integration.
These dynamics create a complex operating environment. While regulatory pressure pushes adoption, the ability to scale efficiently depends on technology costs and interoperability. A deep dive into the specific impact of these factors across different regions and application verticals is necessary to formulate a targeted entry or expansion strategy. The full market report provides a detailed breakdown of how these dynamics interact to shape revenue potential in specific contexts.
Segmentation Landscape: Beyond the Aggregate Numbers
While the overall market size tells a story of growth, the true strategic value lies in understanding the segmentation splits that define revenue distribution. The market is primarily segmented by region and application, each presenting unique opportunities and challenges.
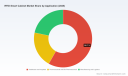
In terms of application, the Healthcare and Hospitals sector represents a dominant share of the market revenue, reflecting the high value of medical supplies and the strict regulatory environment. However, Pharmaceutical and Bio-Pharmaceutical applications, as well as Manufacturing and Logistics, constitute significant and growing portions of the ecosystem. Each segment has distinct requirements regarding temperature sensitivity, asset value, and workflow integration. For instance, pharmaceutical storage demands rigorous environmental monitoring alongside inventory tracking, whereas manufacturing logistics may prioritize tool control and access management. Recognizing which segment aligns with an organization's core competencies or target customer base is a critical step in strategic positioning.
Geographically, the market exhibits varying levels of maturity and opportunity. North America currently holds a substantial portion of market revenue, driven by advanced healthcare infrastructure and early adoption of compliance technologies. Europe follows as a significant market, with increasing regulatory alignment and industrial IoT adoption. The Asia Pacific region presents a dynamic growth environment, characterized by rapid industrialization and expanding healthcare facilities. Latin America and the Middle East and Africa, while currently smaller in absolute revenue terms, offer emerging opportunities as digitization efforts gain traction in these regions.
It is important to note that while the aggregate revenue figures provide a sense of scale, the specific percentage contributions and dollar values for each region and application segment are subject to complex variables including local regulatory frameworks, infrastructure readiness, and competitive intensity. Accessing the detailed segmentation data within the full report allows stakeholders to identify high-growth pockets that may not be visible from top-level aggregates.
Competitive Landscape: Innovation and Consolidation
The competitive environment in the RFID Smart Cabinet market is characterized by a mix of specialized solution providers, large-scale technology integrators, and component manufacturers. The market concentration indicates a moderately fragmented landscape, where innovation and niche specialization often drive success alongside broader ecosystem plays.
Several key companies define the current competitive benchmarks. Terso Solutions, Inc. specializes in RAIN RFID-enabled smart cabinets and enclosures for real-time inventory tracking of high-value medical supplies, pharmaceuticals, and temperature-sensitive assets. Similarly, IDENTI Medical develops patent-protected RFID smart cabinets with UHF RFID, cloud integration, and business intelligence software for hospital inventory management and supply chain visibility. These players focus heavily on the healthcare vertical, leveraging compliance needs as a lever for adoption.
In the industrial and manufacturing space, companies like Nexess Solutions offer IoT and RFID smart cabinets such as the NexCap XL for automated tool control, asset tracking, inventory management, and access control in industrial, aerospace, and pharmaceutical environments. CribMaster and Snap-On Incorporated also compete in this space, with CribMaster manufacturing AccuCab automated RFID-enabled tool cabinets for industrial and MRO inventory control, and Snap-On offering AutoCab FX and AutoLocker FX RFID smart cabinets for tool and equipment management.
Component and technology providers play a crucial role in enabling these solutions. Impinj, Inc. supplies RAIN RFID chips, readers, and solutions optimized for smart cabinet applications in enterprise inventory and asset tracking. Alien Technology, LLC manufactures RFID tags and systems that integrate into smart cabinet platforms for real-time tracking. Avery Dennison Corporation provides RFID tags and printers for labeling and integration into smart cabinets, forming the backbone of the tagging infrastructure.
Recent developments highlight the pace of innovation. In early 2026, Terso Solutions launched a new generation of RFID smart cabinets specifically for automated tracking of medical supplies and temperature-sensitive high-value assets. Impinj introduced next-generation RAIN RFID chips and readers optimized for smart cabinet applications, enabling higher read accuracy and faster inventory processing. Avery Dennison expanded RFID-enabled inventory management solutions for healthcare and industrial environments, enhancing smart cabinet integrations with real-time asset tracking and cloud analytics. Furthermore, strategic partnerships are reshaping the landscape; a notable example includes a high-level strategic partnership announced between Zebra Technologies and SATO Holdings to co-develop next-generation RFID-enabled smart cabinet solutions.
Other notable participants include LogiTag Systems, which provides RFID smart cabinets and medical supply management solutions for automated inventory control, charge capture, and compliance in healthcare facilities. Mobile Aspects manufactures RFID-enabled smart cabinets for surgical supplies, high-value device tracking, and clinician workflow automation in hospitals. Invengo Technology supplies RFID smart cabinet systems with tags, readers, and software platforms for asset management and inventory in healthcare and industrial applications. TAGSYS RFID develops RFID solutions including smart cabinets and readers for inventory tracking and access control. SATO Holdings Corporation provides RFID-enabled smart cabinet solutions integrated with printers and readers for retail and healthcare inventory management. Stanley Healthcare offers RFID smart cabinet systems for healthcare inventory and supply chain management. Techcode manufactures metal RFID smart cabinets with advanced UHF RFID integration for furniture and storage solutions. Grifols integrates RFID smart cabinets into plasma and medical supply inventory systems.
Understanding the specific strengths, partnerships, and product roadmaps of these competitors is vital for positioning. The full research report offers a detailed competitive analysis, including market share estimates and strategic profiling, which is essential for competitive intelligence and partnership evaluation.
Server Cabinet Market
Strategic Implications for 2026 Decision-Makers
As enterprises plan their capital expenditures and technology roadmaps for 2026 and beyond, the RFID Smart Cabinet market presents both opportunities and complexities. The convergence of regulatory pressure, cost reductions, and technological maturity creates a favorable environment for deployment. However, success depends on selecting the right partners, understanding the specific needs of the target segment, and ensuring integration with broader digital ecosystems.
Decision-makers must look beyond the initial hardware cost and consider the total value of ownership, including software analytics, cloud integration, and long-term support. The ongoing product launches and partnerships indicate that the technology is evolving rapidly, offering higher accuracy and better connectivity. Staying informed about these developments through continuous market intelligence is crucial for maintaining a competitive edge.
RFID Smart Cabinet Market
The strategic value of this market research lies in its ability to convert raw data into actionable insights. By understanding the macroeconomic trends, the specific drivers in healthcare and industrial segments, and the competitive moves of key players, organizations can make informed decisions about investment, expansion, and innovation.
Conclusion
The RFID Smart Cabinet market is at an inflection point, driven by essential compliance needs and the broader shift towards Industry 4.0 and connected healthcare. The projection of significant market growth through 2032 underscores the long-term viability of this technology sector. However, navigating this landscape requires more than general awareness; it demands precise data and deep analytical context.
This overview has highlighted the key growth drivers, regulatory influences, and competitive forces shaping the industry. To transform these insights into a concrete strategy, stakeholders are encouraged to access the full market research report. The complete study provides the detailed segmentation data, regional analysis, and comprehensive competitor profiles necessary to validate assumptions and identify specific growth opportunities. In a market moving at this pace, having access to the most current and granular intelligence is the most valuable asset an organization can possess.
For detailed analysis of this topic, please visit the official page: RFID Smart Cabinet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: High-Speed Centrifugal Blower Market at $633M in 2025, Forecast 2.9% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the High-Speed Single-stage Centrifugal Blower Market: Strategic Intelligence for 2026 Decision Makers
The industrial air and gas handling sector stands at a critical inflection point. As manufacturing processes become increasingly energy-intensive and environmental regulations tighten globally, the demand for efficient, reliable, and high-performance fluid movement solutions has never been more pronounced. At the heart of this transformation lies the High-Speed Single-stage Centrifugal Blower Market, a specialized segment that serves as a critical enabler for wastewater treatment, industrial gas processing, and emerging clean energy applications.
For executives, investors, and strategic planners operating in 2026, understanding the nuances of this market is no longer optional—it is a prerequisite for sustainable growth. This article serves as a strategic primer, drawing from our comprehensive market research report to illuminate the key dynamics, competitive forces, and growth trajectories that will define the sector through 2032. While we outline the broader landscape here, the full depth of our quantitative analysis and granular segmentation remains a vital resource for those seeking to secure a competitive advantage in this evolving industry.
Market Trajectory and Macroeconomic Context
The High-Speed Single-stage Centrifugal Blower Market has demonstrated resilience and steady expansion over the past half-decade. Analyzing the historical performance from 2020 to 2025 provides a robust baseline for forecasting future demand. The market revenue, denominated in USD Million, has shown a consistent upward trend, reflecting the underlying growth in industrial infrastructure and environmental compliance requirements across key global regions.
Looking forward, the forecast period spanning 2026 to 2032 suggests a continued progression. The compound annual growth rate (CAGR) indicated for this forecast window points to a moderate yet steady expansion. This growth is not merely a function of volume but is increasingly driven by the replacement of older, less efficient technologies with high-speed single-stage solutions that offer superior aerodynamic performance and lower lifecycle costs. For stakeholders, this trajectory implies a market that is mature enough to offer stability but dynamic enough to reward those who can navigate technological shifts and regional demand variations effectively.
Technology Drivers and Application Dynamics
The core value proposition of high-speed single-stage centrifugal blowers lies in their ability to deliver high flows at precise pressures with minimal energy consumption. This capability is essential across several key verticals. In the realm of sewage treatment, these blowers are indispensable for aeration processes, where energy efficiency directly correlates with operational expenditure. Similarly, in off-gas desulfuration and other industrial gas handling applications, the ability to manage variable flow requirements while maintaining system integrity is paramount.
Recent developments in the sector highlight a clear industry focus on efficiency and integration. For instance, major players have launched new ranges specifically targeting energy reduction in wastewater applications, aligning with stricter EU energy efficiency standards. These regulatory pressures are not just constraints; they are catalysts for innovation, forcing manufacturers to refine impeller designs, bearing technologies, and control systems. The integration of magnetic levitation and air-foil bearings represents a significant technological leap, reducing maintenance needs and enhancing reliability in continuous operation environments.
However, the market is not without its headwinds. Sector analysis indicates that material costs, particularly for aluminum and steel, alongside skilled labor shortages for high-speed impeller manufacturing, continue to influence overall blower pricing and availability. Supply chain resilience and local manufacturing capabilities are becoming strategic differentiators. Companies that can balance cost efficiency with quality certification, such as ISO 9001 and API standards, are better positioned to capture market share in a regulated environment.
Competitive Landscape and Strategic Positioning
The competitive arena for high-speed single-stage centrifugal blowers is characterized by a mix of established global industrial giants and specialized manufacturers with deep technical expertise. The market concentration, as reflected by CR3 and CR5 metrics, suggests a fragmented yet competitive landscape where differentiation is key. No single entity dominates completely, allowing for niche players to thrive by focusing on specific applications or regional strengths.
High-Speed Single-stage Centrifugal Blower Market
Leading companies such as Howden (Chart Industries) and Gardner Denver continue to set benchmarks with integrally geared turbo blowers and magnetic-bearing models optimized for large turndown ranges. Their recent product launches and partnerships underscore a commitment to R&D and geographic expansion. For example, Howden's launch of high-efficiency centrifugal blower ranges targeting energy reduction demonstrates the industry's response to regulatory and operational pressures. Similarly, expansions by companies like Greenheck into new corporate campuses signal long-term confidence in market growth.
On the other hand, manufacturers based in China, such as Shandong Zhangqiu Blower and Shenyang Blower Works Group Corporation, leverage lower labor and material costs to offer competitive solutions for wastewater treatment and industrial gas handling. Their export capabilities and domestic-leading designs present both a challenge and an opportunity for global incumbents. Meanwhile, specialized firms like APG-Neuros and Hoffman & Lamson focus on delivering energy savings through advanced air-bearing technologies and plug-and-play installations, catering to customers who prioritize ease of integration and operational savings.
Strategic partnerships are also reshaping the landscape. Recent collaborations aimed at strengthening distribution networks, such as those seen in the Mid-Atlantic region, highlight the importance of local presence and service support. Acquisitions of manufacturing facilities to expand production capacity further indicate that supply security is a top priority for companies aiming to meet rising demand without compromising on lead times.
Regional Perspectives and Growth Opportunities
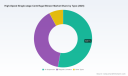
While global demand is rising, the distribution of market value varies significantly by region. North America and Asia Pacific represent substantial portions of the market revenue, driven by robust industrial activity and infrastructure investments. Europe, while a mature market, remains critical due to stringent environmental regulations that accelerate the replacement of legacy systems. Latin America and the Middle East & Africa, though smaller in relative terms, offer emerging opportunities as industrial capacities expand in these regions.
Understanding the specific demand drivers in each region is essential for tailoring go-to-market strategies. In developed markets, the focus is often on retrofitting and upgrading existing installations to meet energy standards. In developing markets, new infrastructure projects and capacity expansions drive initial equipment sales. Our detailed analysis delves into these regional nuances, providing actionable intelligence on where to allocate resources for maximum impact.
Why This Report Matters for 2026 Strategy
In an environment defined by rapid technological change and regulatory complexity, generic industry overviews are insufficient. Decision-makers need access to precise data on market size, segmentation trends, and competitive movements to formulate effective strategies. This report is designed to bridge the gap between high-level market knowledge and actionable strategic insight.
- Comprehensive Segmentation Analysis: Gain clarity on how revenue is distributed across different blower types, applications, and regions without getting lost in aggregated data.
- Competitive Intelligence: Understand the product portfolios, recent developments, and strategic moves of key players to identify gaps and opportunities in the market.
- Risk and Opportunity Assessment: Evaluate the impact of raw material costs, labor availability, and regulatory standards on pricing and supply chain stability.
- Forecasting Accuracy: Utilize our detailed forecast data from 2026 to 2032 to plan capacity, investment, and R&D initiatives with greater confidence.
The insights contained within this research are tailored for stakeholders who require more than just headline numbers. Whether you are evaluating market entry, assessing competitor threats, or optimizing your product roadmap, the granular data provided in the full report is essential for validating assumptions and mitigating risks.
Conclusion: Empowering Decision-Making in a Dynamic Market
The High-Speed Single-stage Centrifugal Blower Market is poised for continued evolution, driven by the dual engines of industrial efficiency demands and environmental compliance. For organizations operating in this space, staying informed is the first step toward staying ahead. While the overview presented here highlights the critical themes and trends shaping the sector, the full extent of our analysis offers the depth required for precise strategic planning.
Centrifugal Compressors Market
We invite you to explore the complete market intelligence provided in our full report. By accessing the detailed segmentation data, comprehensive company profiles, and forward-looking forecasts, you can equip your team with the knowledge needed to navigate the complexities of 2026 and beyond. The investment in accurate, timely market intelligence is an investment in your organization's ability to thrive in a competitive global landscape.
For detailed analysis of this topic, please visit the official page: High-Speed Single-stage Centrifugal Blower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Railroad Tie Market Hits $488.65M in 2025, Poised to Reach $655.95M by 2032 at 4.23% CAGR
By PW Consulting, 2026-09-16
Navigating the 2026 Railroad Tie Landscape: Strategic Intelligence for Infrastructure Leaders
The global railroad infrastructure sector stands at a critical inflection point as we enter 2026. Operators, suppliers, and investors alike are confronted with a complex matrix of aging assets, evolving environmental regulations, and shifting material preferences that will define capital allocation decisions for the next decade. Understanding the underlying market mechanics is no longer a passive exercise—it is a strategic imperative. Our latest comprehensive study on the Railroad Tie Market delivers the granular intelligence required to navigate this terrain with confidence.
Worldwide Composite Railroad Tie Market
This report is designed not merely as a statistical overview, but as a decision-support framework for executives who must balance operational reliability with long-term sustainability. By synthesizing historical performance data with forward-looking projections, the analysis equips stakeholders with the clarity needed to anticipate supply chain disruptions, evaluate competitive positioning, and align procurement strategies with emerging regulatory mandates. The insights presented here are drawn from rigorous primary research and validated industry datasets, ensuring that every recommendation rests on a foundation of verifiable market reality.
Macro Market Trajectory: Growth Anchored in Infrastructure Renewal
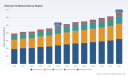
The railroad tie market has demonstrated consistent resilience over the past half-decade, driven by sustained capital expenditure on rail network maintenance and expansion. From a baseline valuation of approximately USD 392 million in 2020, the sector has advanced through a series of incremental yet meaningful increments, reaching an estimated USD 458 million by 2024 and climbing to roughly USD 489 million in 2025. This trajectory reflects a compound annual growth rate of 4.23 percent across the forecast horizon extending through 2032, positioning the market to surpass the USD 655 million threshold by the end of the projection period.
Such growth is not accidental. It is intrinsically linked to the ongoing modernization of rail infrastructure across multiple geographies, where aging wooden sleepers are gradually being replaced or supplemented by longer-lasting alternatives. The steady upward curve underscores a market that is maturing rather than experiencing volatile spikes, offering planners a predictable environment for budgetary forecasting. However, the aggregate figures only tell part of the story. Beneath the headline numbers lie nuanced shifts in material adoption, regional procurement patterns, and application-specific demand drivers that require deeper excavation to inform precise strategic moves.
Decoding Market Structure: Segment Dynamics and Material Shifts
Material Preferences in Transition
The composition of the railroad tie market reveals a clear hierarchy of material adoption, yet the edges of this hierarchy are where the most strategic opportunities reside. Traditional wooden ties continue to command a substantial share of overall revenue, reflecting their entrenched role in legacy networks and the sheer scale of ongoing replacement cycles. Concrete alternatives have carved out a significant and growing footprint, particularly in heavy-haul and high-speed corridors where durability and load-bearing capacity are non-negotiable. Steel and emerging composite solutions occupy more specialized niches, but their relevance is expanding as operators seek to mitigate decay-related maintenance costs and comply with increasingly stringent environmental standards.
What makes this material landscape particularly compelling for 2026 decision-makers is the pace at which performance expectations are evolving. Field data and industry benchmarks indicate that conventional wooden crossties typically deliver between eight and twelve years of service life in high-decay environments. By contrast, advanced composite formulations are now demonstrating operational lifespans exceeding fifty years under comparable conditions. This differential is not merely a technical footnote—it translates directly into total cost of ownership, track availability metrics, and long-term asset planning. Procurement teams that understand the cost-benefit calculus across these material categories will be better positioned to negotiate favorable terms and justify capital expenditures to internal stakeholders.
Application and Regional Nuances
Demand generation within the railroad tie ecosystem is heavily influenced by the operational profile of the end-user. Mainline passenger and freight train operations remain the dominant application driver, absorbing the bulk of annual production output. Subway and urban transit networks represent a secondary but strategically important demand channel, where space constraints, noise considerations, and rapid deployment requirements shape material selection. Beyond these core segments, specialized industrial and temporary track applications contribute incremental volume while introducing distinct specification requirements.
Geographically, the market exhibits pronounced concentration patterns that reflect historical infrastructure investment cycles, regulatory environments, and local sourcing capabilities. North America continues to represent the largest revenue contributor, underpinned by extensive Class I railroad networks and ongoing maintenance programs. Europe follows as a mature market with strong emphasis on high-speed rail modernization and environmental compliance. The Asia Pacific region, while currently smaller in absolute terms, presents dynamic growth potential tied to expanding rail corridors and urban transit development. Latin America and the Middle East/Africa markets, though more modest in scale, offer targeted opportunities for suppliers that can navigate localized logistics and specification requirements. Detailed regional and application breakdowns are mapped comprehensively within the full report to enable precise market-entry and expansion planning.
Competitive Landscape: Incumbents, Innovators, and Strategic Moves
Established Players and Supply Chain Anchors
The competitive architecture of the railroad tie market is characterized by a mix of large-scale manufacturers, specialized treatment providers, and national distributors. Firms such as Koppers Inc. and Stella-Jones Inc. have long anchored the North American supply chain, leveraging extensive sawmill sourcing networks and pressure-treatment capabilities to serve Class I, regional, and short-line railroads. Their scale and established relationships provide a baseline of supply reliability that network operators depend upon for routine replacement programs.
On the concrete and composite side, Vossloh AG has built a global reputation for prestressed concrete ties and synthetic sleepers tailored to heavy-haul and high-speed applications. L.B. Foster Company, through its concrete product subsidiary, holds a significant share of the North American concrete tie supply, reinforcing the material's growing relevance in mainline infrastructure. Gross & Janes Corporation and Nisus Corporation contribute specialized pressure-treated wood solutions, with the latter emphasizing copper naphthenate formulations designed to extend service life in demanding field conditions. These companies illustrate how incumbent players are adapting their portfolios to address both traditional performance expectations and emerging longevity requirements.
Innovation Entrants and Sustainability-Driven Investment
A distinct cohort of composite-focused manufacturers is reshaping the competitive perimeter by targeting the intersection of durability and environmental stewardship. TieTek LLC, operating under Axion International, specializes in composite ties manufactured from recycled materials, offering sustainable alternatives that reduce reliance on virgin timber and creosote-based treatments. Evertrak has similarly positioned itself in the recycled-plastic and fiberglass composite space, with its flagship models engineered for extended lifespans in high-decay zones. IntegriCo Composites Inc. expands this segment further by producing composite railroad ties from recycled feedstocks across dedicated manufacturing facilities.
Railroad Tie Market
Strategic capital flows are reinforcing this innovation axis. In early 2025, Sumitomo Corporation of Americas announced a strategic investment and formalized partnership with Evertrak to support production scalability and expand sustainable composite tie manufacturing for North American railroads. Such moves signal growing institutional confidence in composite technologies and suggest that financing environments are increasingly favorable for manufacturers that can demonstrate both performance superiority and circular-economy alignment. Additionally, broad-line suppliers such as A&K Railroad Materials, Inc. and POHL Railroad Materials Corporation LLC continue to play essential roles in distribution and sourcing, maintaining comprehensive catalogs of new and used ties that support diverse procurement needs across the network.
Market Concentration and Competitive Implications
The competitive dynamics of the railroad tie market are further contextualized by its concentration profile. With the top three firms accounting for approximately 21.5 percent of market revenue and the top five reaching roughly 24.8 percent, the sector exhibits a moderately fragmented structure. This configuration carries strategic implications: while no single entity dominates outright, established players benefit from scale advantages in treatment capacity, distribution networks, and long-term contracting leverage. Meanwhile, niche innovators can pursue differentiation through material performance, sustainability credentials, and specialized application targeting. For buyers, this balance means that supplier diversification, qualification processes, and performance benchmarking are essential to securing both cost competitiveness and supply resilience.
Regulatory and Operational Currents Shaping 2026 Strategy
Performance Standards and Environmental Compliance
Regulatory evolution is becoming a decisive force in material specification and disposal practices. In August 2025, the U.S. Federal Railroad Administration developed performance-based specifications for concrete railroad tie freeze-thaw durability, a move designed to ensure track longevity and tighten manufacturing process control. This specification framework directly influences procurement standards, quality assurance protocols, and supplier qualification criteria for concrete tie programs across North American networks.
Environmental considerations are simultaneously reshaping the end-of-life landscape for treated wood ties. The U.S. Department of Transportation's Federal Railroad Administration issued a request for information in 2023 examining potential uses and options for the disposal or repurposing of used creosote-treated railroad ties, reflecting broader concerns about hazardous substance management. At the state level, New Hampshire's Department of Environmental Services implemented requirements in September 2025 mandating proper disposal options for creosote-treated ties to prevent environmental release. These regulatory threads collectively push operators and suppliers toward more transparent disposal pathways, extended service life solutions, and alternative materials that reduce long-term environmental liability.
Raw Material Capacity and Supply Realism
On the supply side, industry capacity data provides important context for procurement planning. Railroad crossties account for the majority of North American wood tie production capacity, which exceeds 24 million units annually, while current industry output stands at just over 19 million ties. This gap between nameplate capacity and realized output highlights both latent production potential and the operational constraints—labor availability, raw material logistics, treatment facility throughput—that influence actual delivery timelines. For network planners, understanding this capacity dynamic is essential when forecasting replacement schedules, negotiating supply agreements, and modeling cost trajectories under varying operational scenarios.
Strategic Takeaways for 2026 Decision-Makers
The railroad tie market in 2026 rewards organizations that approach procurement and investment through a multi-dimensional lens. Several strategic priorities emerge from the current landscape:
- Align material selection with total cost of ownership rather than upfront unit pricing, factoring in service life differentials, maintenance frequency, and disposal compliance costs.
- Evaluate supplier portfolios for both scale reliability and innovation capability, recognizing that established treatment and manufacturing networks remain critical while composite and sustainability-focused entrants are gaining traction.
- Incorporate regulatory developments into specification frameworks early, particularly performance-based durability standards and environmental disposal mandates that will influence eligibility, reporting, and liability exposure.
- Monitor capacity utilization and regional sourcing dynamics to anticipate lead-time variability and identify opportunities for dual-sourcing or localized supply partnerships.
- Leverage strategic investment activity as a signal of where institutional capital is converging, using partnership and funding announcements to inform competitive benchmarking and technology adoption roadmaps.
These considerations are not isolated tactics; they form an integrated approach to navigating a market where material performance, regulatory pressure, and supply chain realism intersect. Organizations that embed these priorities into their planning cycles will be better equipped to manage risk, capture efficiency gains, and position their rail infrastructure assets for long-term operational excellence.
Accessing the Full Strategic Intelligence
The insights summarized here represent a high-level orientation to the railroad tie market's structure, dynamics, and strategic levers. Yet the depth required for enterprise-level decision-making extends well beyond aggregate trends. The complete report delivers detailed segment-level revenue trajectories, application-specific demand breakdowns, regional procurement analyses, and granular competitive profiling that enable precise market-entry assessments, supplier negotiations, and capital planning. It also maps the interplay between regulatory timelines and material adoption curves, offering scenario-based frameworks that help leaders stress-test procurement strategies against evolving compliance requirements and performance expectations.
For executives and strategy teams preparing for 2026 and the forecast window through 2032, the full study provides the empirical foundation necessary to convert market awareness into actionable advantage. To access the complete dataset, competitive deep-dives, and operational recommendation frameworks, we invite you to explore the full report through our official publication channel. There, you will find the detailed tables, methodology notes, and scenario analyses that transform these strategic themes into executable intelligence tailored to your organization's specific rail infrastructure objectives.
For detailed analysis of this topic, please visit the official page: Railroad Tie Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Civil Helicopter MRO Market Hits $9.7B in 2025, Projects 6.5% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence Brief: The Civil Helicopter MRO Market Outlook 2026–2032
The civil helicopter maintenance, repair, and overhaul (MRO) sector stands at a pivotal inflection point as we move into 2026. Driven by accelerating fleet utilization rates, evolving regulatory frameworks, and sustained investment in rotorcraft modernization, the market has transitioned from a post-pandemic recovery phase into a period of structured, high-velocity growth. For executives, investors, and operational leaders across the aviation value chain, understanding the trajectory of this market is no longer optional. It is a strategic imperative.
This analysis serves as a strategic preview to PW Consulting's newly released Civil Helicopter MRO Market Research Report , a comprehensive intelligence asset designed to equip decision-makers with the granular insights, competitive mapping, and forward-looking projections necessary to navigate the next seven years of industry evolution. The following overview highlights the macro-scale dynamics, competitive realities, and regulatory currents shaping the landscape, while demonstrating why this research has become an essential tool for institutional strategy in 2026 and beyond.
Market Trajectory: Sustained Expansion Anchored in Historical Momentum
The civil helicopter MRO market has demonstrated remarkable resilience and consistent upward momentum over the past half-decade. Drawing on a robust historical dataset spanning 2020 through 2025, the sector has recorded steady year-over-year revenue expansion, culminating in a baseline valuation of approximately $9.7 billion in the most recent full-year cycle. This trajectory reflects not only the restoration of civil aviation activity but also the deepening integration of helicopter assets into critical infrastructure: emergency medical services, offshore energy support, law enforcement, and an expanding array of commercial passenger and cargo logistics networks.
Forecasting models projecting through 2032 indicate that this growth will not merely continue but accelerate in structural complexity. The market is anticipated to surpass the $10.2 billion threshold in 2026, with compound annual growth rates stabilizing at approximately 6.5 percent over the forecast horizon. By the close of the projection window in 2032, total market valuation is projected to approach the $15 billion mark. This sustained expansion is underpinned by several converging forces: the aging of incumbent rotorcraft fleets that demands increasingly intensive heavy maintenance cycles, the modernization of avionics and propulsion systems that introduces new service categories, and the geographical diversification of civil helicopter operations into emerging markets where aerial mobility solutions are gaining institutional adoption.
For corporate strategists, these figures represent more than macroeconomic indicators. They signal a market in which capacity planning, service-line prioritization, and regional footprint decisions will yield disproportionate competitive advantages. Organizations that align their MRO investments with the cadence of fleet age profiles and regulatory timelines will be positioned to capture disproportionate shares of high-margin maintenance cycles, while those that rely on backward-looking utilization models risk strategic misalignment.
Structural Segmentation: Where Value Is Created and Captured
The civil helicopter MRO ecosystem is not a monolith. It is a layered constellation of service categories, each with distinct demand drivers, technical requirements, and margin profiles. Market intelligence reveals that airframe heavy maintenance continues to command the largest share of industry revenue, reflecting the capital-intensive nature of structural inspections, corrosion mitigation, and comprehensive rotorcraft airframe overhauls. Engine maintenance constitutes the second-largest pillar of the market, driven by the operational imperative to sustain powerplant reliability and the growing trend of engine life-extension programs that defer prohibitive replacement costs. Component maintenance, encompassing dynamic systems, avionics, transmissions, and rotor assemblies, represents a rapidly evolving segment where precision engineering and digital diagnostics are increasingly reshaping service delivery models.
Alongside these technical divisions, the application landscape reveals a pronounced tilt toward commercial operations, which account for the dominant portion of MRO spending across the civil rotorcraft sector. Private and corporate helicopter fleets contribute a substantial secondary stream of demand, characterized by more customized service requirements, shorter turnaround expectations, and a higher willingness to invest in premium maintenance packages that preserve asset values and operational flexibility. Understanding the interplay between these service lines and application categories is critical for firms evaluating capacity allocation, pricing architecture, and partnership strategies.
The regional distribution of MRO activity further underscores the importance of geographically informed strategy. North America remains a foundational market, anchored by dense fleets, mature regulatory environments, and a robust network of certified repair stations. Europe follows as a structurally significant region, supported by stringent EASA compliance frameworks and a growing emphasis on cross-border rotorcraft operations. Asia Pacific represents an increasingly dynamic frontier, where expanding public safety mandates, resource-sector helicopter demand, and emerging commercial rotorcraft programs are catalyzing new MRO investments. Latin America and the Middle East and Africa, while currently smaller in aggregate scale, are experiencing targeted growth driven by energy-sector operations, crisis-response capabilities, and localized fleet modernization initiatives.
Military Helicopter MRO Market
A complete picture of these segmentation dynamics, however, requires more than high-level categorizations. It demands detailed breakdowns of demand elasticity, service-cycle durations, regional certification pathways, and the margin implications of each maintenance modality. This is precisely the level of granularity embedded within the full research deliverable.
Competitive Landscape: OEM Dominance, Independent Agility, and Strategic Differentiation
The civil helicopter MRO market is characterized by a moderately concentrated competitive environment, where a handful of large-scale players command meaningful market share while a diverse field of specialized independents competes on technical agility, regional proximity, and niche service capabilities. Market concentration metrics indicate that the top three participants collectively control roughly 38 percent of industry revenue, while the top five extend their combined footprint to approximately 48 percent. This structure suggests a market that rewards both scale efficiencies and specialized differentiation, with room for agile entrants to secure sustainable positions through certified capabilities, strategic partnerships, and targeted service expansions.
At the OEM tier, Airbus Helicopters maintains a formidable presence through its integrated HCare service portfolio, which spans heavy maintenance, dynamic component repair, blade restoration, avionics upgrades, and continuing airworthiness management organization (CAMO) support. Operating across more than thirty sites and ninety-three MRO centers globally, the OEM leverages its manufacturing heritage, proprietary technical data, and expansive service network to anchor long-term fleet support relationships. Its recent emphasis on preserving MRO expertise amid digital transformation signals a strategic recognition that technological modernization must be paired with the retention of high-caliber engineering and maintenance talent.
Within the independent MRO segment, several firms have established strong reputations for operational excellence and regulatory compliance. StandardAero and Heli-One, both Canadian-based specialists, deliver comprehensive airframe maintenance, repair, overhaul, and component support services for civil and commercial rotorcraft fleets worldwide. Their scale, technical certifications, and global service footprints position them as critical capacity providers for operators seeking independent, cost-competitive alternatives to OEM channels. Rotortrade, headquartered in Atlanta, has emerged as a highly adaptive independent provider, combining full-service maintenance, CAMO oversight, and FAA Part 145 certification with avionics integration capabilities, including its recognized dealership status with Garmin. Eurotech, based in Italy, operates as an EASA Part 145 certified MRO center delivering comprehensive maintenance and overhaul services for civil rotorcraft, while Saudia Technic, anchored in Riyadh, has expanded its capabilities to encompass comprehensive helicopter maintenance and overhaul services for civil and commercial aircraft, reflecting broader regional investment in aviation infrastructure.
The competitive landscape is not static. Recent developments illustrate how targeted investments and regulatory certifications are reshaping service capabilities in real time. In late 2025, Rotortrade officially launched its U.S. MRO facility, securing full FAA Part 145 certification and enabling return-to-service approvals for FAA-regulated rotorcraft—a move that materially expands its domestic service reach. The following year, in early 2026, the company's Latrobe facility was appointed an official Garmin dealership, broadening its certified avionics integration capabilities under existing FAA approvals. These developments highlight a broader industry pattern: independents are increasingly differentiating through specialized certifications, strategic technology partnerships, and facility expansions that align with regional regulatory frameworks and operator demand.
Simultaneously, the inaugural Vertical MRO Conference, held in Kelowna, British Columbia, drew over five hundred rotorcraft MRO professionals for education sessions and industry exhibitions, underscoring the growing institutional focus on knowledge exchange, technical standards, and cross-company collaboration within the rotorcraft maintenance community. For market participants, these gatherings are more than networking events; they are barometers of emerging best practices, supplier relationships, and regulatory expectations that will shape competitive dynamics in the years ahead.
Regulatory Dynamics and Industry Currents: The Compliance-Led Evolution of MRO Strategy
Regulatory evolution is one of the most powerful forces reshaping the civil helicopter MRO market. In the United States, the FAA Modernization of Special Airworthiness Certification (MOSAIC) final rule, published in mid-2025, introduced a series of phased compliance milestones that directly affect pilot training, maintenance rules, and the regulatory classification of certain aircraft categories. The staggered effective dates—spanning pilot training and maintenance rule updates in late 2025 through the removal of the light-sport aircraft definition from federal aviation regulations in mid-2026—require MRO providers and fleet operators to adapt their compliance frameworks, training pipelines, and service protocols with precision and foresight.
Parallel regulatory developments have reinforced the importance of structured safety management. U.S.-registered Part 145 repair stations that also hold EASA Part 145 certification were required to implement formal safety management systems by the end of 2025, aligning North American and European maintenance standards with increasingly rigorous risk-management expectations. More recently, the FAA has emphasized a long-term industry goal of achieving zero fatal civil helicopter accidents, publishing enhanced guidance that includes updated Airman Certification Standards for rotorcraft-helicopter series, replacing older practical test standards with more rigorous competency frameworks. These regulatory currents do not merely impose compliance obligations; they reshape the competitive landscape by rewarding organizations that invest early in proactive safety cultures, standardized training, and digitally enabled compliance tracking.
Beyond regulation, the market is responding to broader operational and technological currents. Eurotech's certification by Robinson Helicopter Company as an Authorized Robinson Helicopter Dealer for 2026 exemplifies how manufacturer-aligned authorizations are becoming strategic differentiators, validating MRO providers' adherence to specific technical standards and unlocking access to dedicated service ecosystems. Meanwhile, advances in predictive maintenance analytics, digital airworthiness documentation, and component lifecycle tracking are gradually transforming traditional MRO workflows from reactive repair models into data-informed service architectures. Organizations that integrate these capabilities into their operational models will be better positioned to reduce turnaround times, optimize parts inventory, and deliver the transparency that modern operators increasingly demand.
The Strategic Value of Comprehensive Market Intelligence in 2026
For enterprises operating in or adjacent to the civil helicopter MRO ecosystem, the complexity of the market environment in 2026 demands more than generalized industry awareness. It requires a structured, evidence-based intelligence foundation that integrates historical performance data, forward-looking projections, segmentation analysis, competitive profiling, and regulatory foresight into a single, coherent decision-support framework.
Civil Helicopter MRO Market
PW Consulting's Civil Helicopter MRO Market Research Report has been designed to meet this need. The study draws upon extensive primary and secondary research to deliver a multi-dimensional view of the market across its full forecast horizon. It provides detailed analysis of revenue trajectories, service-line dynamics, regional demand patterns, and the strategic moves of key market participants, enabling readers to benchmark their positioning, identify whitespace opportunities, and anticipate shifts in competitive intensity. The report also examines the practical implications of regulatory changes, technological adoption curves, and fleet lifecycle dynamics, translating high-level trends into actionable strategic considerations for capacity planning, partnership evaluation, and market-entry or expansion decisions.
Importantly, the intelligence contained within this research is structured to support a range of operational and strategic functions. For MRO service providers, the analysis offers a basis for calibrating investment in facility capacity, certification pathways, and specialized service lines. For OEMs and component manufacturers, it illuminates downstream demand patterns and the service-interface opportunities that accompany fleet modernization. For financial stakeholders and investors, it provides a disciplined framework for evaluating growth trajectories, margin drivers, and the competitive vulnerabilities that may influence long-term returns. For fleet operators and aviation authorities, it delivers context on service availability, regulatory alignment, and the evolving standards that shape procurement and compliance strategies.
Navigating the Next Seven Years with Confidence
The civil helicopter MRO market is entering a phase defined by sustained growth, regulatory refinement, and intensifying competitive differentiation. The macroeconomic trajectory is clear: revenue expansion will continue at a robust pace, fleet age profiles will drive increasing demand for heavy maintenance and component overhaul, and regional demand centers will continue to diversify as rotorcraft operations expand into new operational contexts. Yet the precise allocation of opportunity across service categories, geographic zones, and competitive tiers remains a question that can only be answered through detailed, research-backed analysis.
In an environment where strategic agility depends on accurate foresight, access to comprehensive market intelligence is not merely an informational advantage—it is a foundational element of operational resilience and growth planning. The full Civil Helicopter MRO Market Research Report provides the depth, structure, and analytical rigor required to make informed decisions with confidence. Readers seeking the complete segmentation breakdowns, detailed company profiles, regional demand mappings, and forward-looking scenario analysis are encouraged to access the full report through the source webpage, where the complete intelligence suite is available for institutional review and strategic application.
For detailed analysis of this topic, please visit the official page: Civil Helicopter MRO Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blood Products Market to Hit $66.2M by 2032, Reflecting 4.7% CAGR Amid Regional Shifts
By PW Consulting, 2026-09-16
Strategic Intelligence for Blood Products Leaders: Navigating the 2026 Market Landscape
Executive Overview
The global blood products market is entering a critical inflection point. With historical momentum carrying the industry from 38.15 billion USD in 2020 to an estimated 48.0 billion USD in 2025, and a projected trajectory toward 66.2 billion USD by 2032, the sector is poised for sustained, measured expansion. Our newly released research framework dissects this evolution with precision, delivering the analytical depth required for enterprise-level strategy, capital allocation, and competitive positioning in the coming cycle.
For executives, investors, and operational leaders, the years ahead will not be defined by simple top-line growth. Instead, success will hinge on understanding structural shifts in donor economics, reimbursement architectures, regulatory cadence, and manufacturing capacity deployment. This report is engineered to translate macro trends into actionable intelligence, allowing decision-makers to stress-test strategies against realistic demand scenarios, supply constraints, and competitive maneuvering.
The 2026–2032 Trajectory: A Market Built on Stable Demand, Shaped by Execution
The forecast window reflects a compound annual growth rate of 4.7 percent, a figure that signals resilience rather than volatility. Demand fundamentals remain anchored in clinical necessity: surgical interventions, trauma response, oncology protocols, and chronic hematologic management continue to drive consistent consumption. Yet growth is no longer a passive outcome of population aging or procedural volume alone. It is increasingly contingent on operational efficiency, fractionation throughput, cold-chain integrity, and the ability to scale plasma-derived therapies without compromising quality or compliance.
Notably, the projection curve does not follow a linear stretch. The data anticipates a period of consolidation and recalibration, where capacity investments, regulatory approvals, and donor recruitment dynamics will differentiate high-performing players from those merely riding baseline demand. Companies that align manufacturing footprints, collection networks, and product portfolios with regional healthcare financing models will capture disproportionate value. Those that rely solely on historical utilization patterns will face margin compression, supply bottlenecks, or competitive displacement.
Our analysis maps these inflection points across the full forecast horizon, isolating the operational levers that determine whether volume growth translates into sustainable profitability. The report does not stop at aggregate figures; it examines how pricing structures, procurement consolidation, and clinical adoption pathways interact to shape realizable revenue in each phase of the cycle.
Decoding the Competitive Arena: Integrated Networks, Specialized Technologies, and Strategic Capacity Plays
The competitive landscape is defined by a mix of vertically integrated plasma manufacturers, specialized technology providers, and large-scale blood services organizations. Each group occupies a distinct strategic position, and the dynamics between them are shifting as capacity investments accelerate and pathogen reduction technologies gain broader clinical adoption.
Grifols and CSL Behring continue to anchor the upper tier of plasma-derived therapies, leveraging vertically integrated collection and fractionation networks to supply hematology, critical care, and rare disease portfolios. Their scale advantages are counterbalanced by the operational complexity of maintaining donor throughput, fractionation yield, and regulatory compliance across multiple jurisdictions. Terumo Blood and Cell Technologies, meanwhile, operates at the intersection of automation and component production, providing apheresis platforms, processing systems, and storage technologies that influence how blood centers and hospitals manage collection efficiency and product consistency.
On the services and distribution side, Vitalant exemplifies the large-scale U.S. blood services model, delivering whole blood, platelets, plasma, cryoprecipitate, and specialty products across hospital networks. Its operational footprint highlights the importance of regional supply resilience, donor engagement, and logistics optimization in a market where inventory management and shelf-life constraints remain perennial challenges.
Specialized technology and plasma-focused players add another layer of strategic complexity. Cerus Corporation’s pathogen reduction systems address a persistent vulnerability in transfusion medicine, inactivating viruses and bacteria in platelets and plasma to enhance safety margins. Octapharma, Biotest, and Kedrion Biopharma each emphasize plasma-derived medicines and collection infrastructure, with product portfolios spanning coagulation factors, immunoglobulins, and therapies for rare and chronic conditions. Their strategies illustrate a broader industry pattern: differentiation is increasingly achieved through specialized protein fractionation, targeted disease areas, and ownership or control of collection assets.
Recent corporate activity reinforces the strategic stakes. Kedrion Biopharma’s allocation of substantial investment to expand production capacity in Italy signals confidence in regional plasma throughput and fractionation scale. Grifols has moved forward with new manufacturing construction in Spain, reinforcing its commitment toEuropean capacity and supply continuity. Cerus Corporation’s multi-year supply agreement with a major French blood establishment underscores the commercial traction of pathogen reduction platforms in institutional procurement. Additionally, the 2026 International Plasma Protein Congress, held with record participation, reflects intensifying industry focus on plasma protein therapeutics, regulatory alignment, and cross-border supply coordination. Together, these developments illustrate a market where capacity, safety technology, and institutional partnerships are converging as decisive competitive variables.
Operational Realities That Shape Margins: Donor Economics, Reimbursement, and Regulatory Discipline
Behind every market projection lies a set of operational realities that determine whether growth is profitable, sustainable, and defensible. Donor economics remain one of the most consequential cost drivers. In the United States and select markets, donor compensation commonly falls within a range of 50 to 100 USD per visit, and collection-related expenses can represent more than half of finished plasma-derived product costs. This structure means that collection efficiency, donor retention, center utilization, and labor deployment are not back-office concerns; they are direct determinants of cost of goods and margin resilience.
At the same time, hospital reimbursement models introduce a distinct pricing dynamic. Many healthcare systems operate under fixed bundled reimbursement rates for patient care episodes, which encompass blood products as part of hospitalization without separate product-level billing. This architecture compresses direct price visibility for manufacturers and distributors, while shifting commercial emphasis toward reliability, quality assurance, inventory availability, and total cost-of-care efficiency. For suppliers, the implication is clear: competitive advantage arises from demonstrating consistent supply, minimizing waste, and aligning product offerings with clinical pathways rather than pursuing isolated list-price leverage.
Regulatory oversight adds another layer of discipline. Blood establishments are required to register and list products under FDA frameworks, with inspections occurring at least every two years to verify compliance with collection, testing, and processing standards. Updated clinical usage guidance, such as revisions to red blood cell preparation and component handling specifications, further shapes how products are manufactured, stored, and deployed. These requirements elevate the importance of quality systems, audit readiness, and documentation rigor. In practice, they reward organizations that embed compliance into operational design rather than treating it as a periodic checkpoint.
Labor intensity compounds these factors. Plasma collection networks rely on large workforce deployments across hundreds of centers to sustain high-frequency donor operations and fractionation throughput. The operational implication is twofold: scaling capacity requires careful workforce planning, training, and center-level productivity management, while disruptions in staffing or donor availability can quickly propagate into fractionation schedules and supply continuity. The companies that manage these variables most effectively will be best positioned to convert demand into revenue without eroding margins.
Blood Plasma Derivatives Market
What’s Inside the Research: Practical Intelligence for Strategy and Execution
This report is designed as an operational companion for executive decision-making, not a static market snapshot. It integrates demand trajectories, competitive positioning, regulatory context, and cost-structure dynamics into a coherent strategic framework. The analysis spans the forecast period from 2026 through 2032 and is anchored in a historical baseline that captures the market’s evolution from 2020 to 2025.
The research delivers detailed segmentation intelligence across product categories, application areas, and regional demand patterns, allowing readers to identify where growth concentrates, where throughput constraints emerge, and where procurement behavior differs by healthcare system. It examines product-level demand drivers, including red blood cell utilization in trauma and surgical care, platelet requirements in supportive treatment protocols, and the broader category of specialty and plasma-derived components. It also maps application-level consumption patterns across trauma and surgery, cancer treatment, and blood disorders, linking clinical utilization to supply planning and commercial strategy.
Beyond volume and segmentation, the report provides actionable competitive analysis. It evaluates the strategic posture of leading manufacturers, plasma collection organizations, technology suppliers, and blood services providers, highlighting how vertical integration, automation, pathogen reduction, and capacity expansion shape market positioning. The competitive framework is paired with recent corporate developments, regulatory milestones, and industry gathering activity to show how strategic intent is translating into infrastructure investment, supply agreements, and institutional partnerships.
A distinct emphasis is placed on operational economics and market mechanics. The analysis addresses donor compensation structures, collection cost weight within finished product economics, hospital reimbursement architecture, regulatory inspection cadence, and the labor footprint required to sustain high-frequency plasma collection and fractionation. These factors are integrated into a broader assessment of margin sensitivity, supply resilience, and procurement behavior, enabling readers to evaluate not just where the market is going, but how value is created and defended along the way.
Blood Products Market
To support practical decision-making, the report also includes scenario-based interpretation tools that help leadership teams test strategic assumptions against changing demand intensity, capacity deployment timelines, and competitive response patterns. The goal is to provide clarity on priorities: where to invest, where to optimize, where to partner, and where to differentiate.
Why This Report Matters for 2026 Decision-Making
The 2026 decision environment demands more than high-level forecasts. It requires an understanding of how donor economics, reimbursement models, regulatory oversight, and capacity investments interact to shape competitive outcomes. It requires clarity on which product and application segments will absorb incremental demand, which regions will see the most pronounced shifts in procurement behavior, and which strategic moves will separate market leaders from followers.
This research is built for that purpose. It provides the structural insight needed to align product strategy, supply chain planning, and commercial positioning with realistic market conditions. It helps organizations anticipate where margin pressure may emerge, where safety technology and compliance rigor will influence purchasing decisions, and where capacity expansion will alter supply dynamics. It also serves as a reference point for investment evaluation, partnership assessment, and long-range planning in a market where execution quality increasingly determines returns.
The full report contains the detailed segmentation breakdowns, regional demand mapping, competitive profiles, operational cost analysis, and strategic scenario interpretation needed to convert market intelligence into concrete action. For teams responsible for portfolio strategy, operations, procurement, or investment planning, the complete dataset and interpretive framework are essential for building resilient 2026 and beyond strategies.
Explore the full research suite to access the complete segmentation intelligence, competitive landscape analysis, and operational dynamics assessment that underpin the findings outlined here.
For detailed analysis of this topic, please visit the official page: Blood Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Commercial Ice Machine Market to Hit $332M by 2032 on 7.45% CAGR
By PW Consulting, 2026-09-16
Beyond Thermal Output: Strategic Intelligence for the 2026 Commercial Ice Machine Market
The commercial ice machine sector has quietly transitioned from a commoditized utility play to a capital-intensive, regulation-sensitive infrastructure decision. Across foodservice, healthcare, and retail environments, ice systems are no longer evaluated solely on daily production capacity. Facility managers, procurement officers, and capital equipment planners now weigh energy compliance, refrigerant transitions, sanitation certification, and total cost of ownership against volatile supply chain conditions. As we move deeper into the 2026–2032 forecast window, the organizations that will secure margin protection and operational continuity are those making their ice equipment decisions with granular, forward-looking intelligence rather than historical benchmarks.
PW Consulting’s newly released Commercial Ice Machine Market research is structured as a decision-grade intelligence asset. It moves past surface-level market commentary to deliver executable procurement roadmaps, competitive positioning frameworks, and regulatory readiness checklists. The following overview outlines what the study covers, why the 2026 decision window is structurally distinct, and how leadership teams can translate market velocity into risk-adjusted capex and opex strategy. The core segment valuations, regional breakouts, and proprietary forecasting layers are reserved for the full report, where the complete analytical architecture can be navigated without dilution.
A Market in Structural Expansion: Why 2026 Is a Pivotal Inflection Point
The commercial ice machine market has demonstrated consistent expansion over the past half-decade, with revenue compounding from approximately USD 130.5 million in 2020 to an estimated USD 200.0 million in 2025. The trajectory reflects more than post-pandemic normalization. It signals a durable alignment between hospitality recovery, healthcare sanitation mandates, retail cold-chain sophistication, and industrial cold processing requirements. Looking forward, the forecast period extends through 2032, with market revenue projected to surpass the USD 330 million threshold by the close of the outlook window. This expansion is supported by a CAGR of 7.45 percent, a pace that places ice equipment alongside other commercial kitchen and facility infrastructure categories experiencing sustained institutional demand.
Commercial Ice Machine Market
Ice Cream Machine Market
For enterprise planners, a double-digit compound growth trajectory carries a specific strategic implication: delay is expensive. Capacities installed in 2026 will remain in operation well into the next decade, and the operating environment those machines face will be shaped by tightening energy expectations, evolving refrigerant policy, and heightened sanitation enforcement. The report uses the full 2020–2032 timeline to frame not just where the market has been, but which cohorts of demand are structurally permanent versus which are cyclical. Decision-makers are given a calibrated view of how near-term procurement cycles interact with long-lived asset exposure, enabling more disciplined budgeting across multi-year capex programs.
Competitive Architecture: Concentration, Positioning, and the Strategic Playbook
The commercial ice equipment landscape is not a fragmented free-for-all. Market concentration metrics underscore a consolidated environment in which a relatively small group of manufacturers commands the majority of share. The report examines this structure through the lens of competitive moats, channel leverage, and innovation cadence rather than simple shipment rankings. With CR3 levels at 65.0 percent and CR5 levels at 85.0 percent, competitive dynamics are defined by brand trust in sanitation-critical environments, dealer and service network density, and the ability to deliver certified, energy-optimized platforms across multiple ice formats.
Several established players anchor this ecosystem. Hoshizaki America, headquartered in Fayetteville, Georgia, manufactures commercial ice machines across flaker, nugget, and cube configurations, with a consistent emphasis on NSF-listed models and energy-efficient options. The company’s recent 2026 product calendar reinforces this positioning: an updated commercial product brochure released in April highlighted improved energy efficiency and hygiene options across 2026 model years, followed in May by an expanded cube ice portfolio under the new IM CUBE series, which incorporates UV sanitization alongside energy and water savings. Such moves illustrate a broader industry pattern in which premium differentiation is increasingly tied to integrated sanitation and resource efficiency rather than production volume alone.
Manitowoc Ice, based in Manitowoc, Wisconsin, focuses on engineered commercial ice machines for foodservice, hospital environments, and high-volume applications, supported by dealer networks that extend service reach and installation fidelity. In May 2026, the company continued its refrigerant transition toward R290 while advancing supply chain optimizations designed to enhance commercial ice machine performance. This trajectory reflects the operational reality that after-sales reliability, parts availability, and service responsiveness often matter as much as the hardware specification itself.
Scotsman Ice Systems, operating from South Carolina, is recognized globally as a leading manufacturer of commercial ice machines, offering modular and countertop models with a clear focus on foodservice reliability. Ice-O-Matic, also U.S.-based, specializes in commercial ice machines and dispensers built around modular designs tailored to restaurants and institutions. Grant Ice Systems manufactures industrial and commercial units, including nugget and flake types designed for high-capacity requirements. Follett Ice delivers commercial ice machines and dispensers with integrated technology aimed at foodservice operations, while Maxx Ice offers self-contained and premium indoor/outdoor commercial ice machines, several with Energy Star listings. Summit Appliance produces commercial ice makers certified to NSF-12, with production ranges spanning from 55 lb to 210 lb. Outside the U.S. incumbent core, Naixer Ice, based in China, serves as a global supplier of commercial ice makers with NSF certification and product catalogs designed for international distribution. Morris Thermal rounds out the competitive field by producing custom industrial ice makers with Tube-Cube and Nugget technologies suited to food processing and high-volume use.
The report does not stop at company profiles. It maps how these players compete across product families, service architectures, and compliance readiness, and it highlights where concentration creates pricing discipline versus where niche innovation can still open addressable pockets. This structure is especially valuable for procurement teams evaluating not only unit cost but the strategic risk of vendor lock-in, parts dependency, and long-term service support across dispersed locations.
Regulatory Dynamics, Certification Realities, and the 2026 Compliance Landscape
One of the most consequential layers of the 2026 decision environment is regulatory and certification pressure. Commercial ice machines sit at the intersection of energy policy, refrigerant mandates, and food safety standards, making compliance a design constraint rather than an optional add-on. As of May 2026, commercial ice machines must meet ENERGY STAR performance specifications or equivalent performance thresholds if not labeled as such. In parallel, Florida Water Star has required these standards for appliances, tying water and energy efficiency into broader building and equipment approval frameworks. For multi-site operators with exposure to these jurisdictions, the implication is straightforward: efficiency performance is becoming a purchasing prerequisite, not merely a sustainability talking point.
Refrigerant transitions are equally influential. In November 2025, Hoshizaki transitioned 66 of its ice maker models to R-600a and R-290 refrigerants, achieving over a 99 percent reduction in global warming potential. This shift reflects a wider industry migration toward lower-GWP alternatives and demonstrates how OEMs are redesigning platforms to align with both federal direction and customer expectations around environmental footprint. The EPA SNAP rule further shapes the market by allowing specific refrigerants, including HFC-32, R-454A, R-454B, R-454C, R-455A, R-457A, and R-516A, for use in new commercial ice machines under defined conditions. Compliance with these pathways requires vendors and buyers alike to track approval conditions and equipment eligibility, especially as state-level timelines and federal requirements interact.
Certifying bodies add another layer of non-negotiable scrutiny. NSF/ANSI Standard 12 certification is mandatory for all U.S. commercial ice machines sold in foodservice to ensure sanitation and food safety compliance. This requirement creates a structural barrier to entry for unverified equipment and makes certification status a baseline procurement filter. On the regulatory timing side, the Washington Department of Ecology issued an interpretive statement in December 2024 delaying the HFC prohibition effective date for automatic commercial ice machines to align with federal 2026–2027 requirements. The interplay of federal and state regulatory calendars means that what appears to be a single compliance decision often requires multi-jurisdiction validation. The report organizes these dynamics into actionable categories so that facility and procurement leaders can map equipment selection to the specific standards that govern their locations and use cases.
What the Report Delivers: An Operational Intelligence Framework
PW Consulting’s Commercial Ice Machine Market study is designed for teams that need more than directional market commentary. The deliverable combines macroeconomic trajectory, product-form dynamics, application-driven demand behavior, regional performance context, and competitive profiling into a coherent planning tool. The research architecture is built around several practical components.
- Historical baseline and forecast modeling spanning 2020 through 2032, providing a continuous revenue view that supports budgeting, capacity planning, and trend validation across multiple forecast vintages.
- Product-form analysis across cube, flake, nugget, and other configurations, examining how production footprint, ice characteristics, and operational use cases drive adoption across foodservice, healthcare, retail, and industrial settings.
- Application-based demand mapping that distinguishes between high-volume commercial foodservice requirements, healthcare sanitation-sensitive environments, retail point-of-use needs, and broader institutional or industrial deployments.
- Regional context that situates market performance across major geographies without forcing simplistic generalizations, helping multinational operators and domestic chains calibrate rollout priorities based on infrastructure maturity, regulatory exposure, and demand density.
- Competitive profiling of leading manufacturers and emerging suppliers, including product positioning, certification posture, and recent innovation or catalog activity, enabling side-by-side evaluation of vendor options and service implications.
- Regulatory and certification tracking that consolidates ENERGY STAR expectations, SNAP-listed refrigerant pathways, state-level interpretive actions, and NSF/ANSI Standard 12 requirements into a usable compliance overview for procurement teams.
- Decision-support frameworks that translate market information into purchasing criteria, replacement-cycle logic, and vendor-selection checklists aligned to operational continuity and total cost of ownership.
This structure is intentionally practical. It is not a static market snapshot but a tool that supports recurring decisions: whether to replace aging units now or stage the transition; how to weigh efficiency-certified platforms against upfront cost; which product formats align with specific site profiles; and how to interpret competitive moves such as refrigerant migrations, UV sanitization integration, and modular design refinements. By tying these considerations to a single research baseline, the report reduces the risk of fragmented decision-making across departments that often evaluate equipment from different angles.
Why the Full Intelligence Set Matters for 2026 Procurement and Planning
Strategic procurement in a market growing at a mid-to-high single-digit CAGR is not simply a matter of identifying the cheapest compliant unit. The real decision space includes service network coverage, spare-parts availability, energy-cost exposure over the machine’s service life, regulatory drift, and the operational consequences of choosing a platform that may not align with future certification or efficiency expectations. In a market where a concentrated group of manufacturers controls a substantial share, vendor selection also carries concentration risk and dependency considerations that should be weighed explicitly rather than inferred from spec sheets alone.
The report is built to support that level of evaluation. It gives teams a structured way to interpret market momentum, segment behavior, competitive responses, and compliance shifts without relying on fragmented sources or outdated assumptions. The full study preserves the detailed segment valuations, regional performance context, application-level demand breakdowns, and forward forecasting layers that enable scenario-based planning. Those components are essential for organizations that need to justify capex against auditable market evidence, compare vendors on a consistent basis, and anticipate how regulation and technology will reshape operating economics through 2032.
Navigating the Market with Proven Strategic Intelligence
The commercial ice machine market in 2026 rewards teams that plan with precision. Growth is real, concentration is high, and the regulatory environment is actively reshaping product design and procurement criteria. In that context, the difference between reactive replacement and strategic deployment is information quality. PW Consulting’s Commercial Ice Machine Market research is intended to provide that information in a form that procurement, operations, and finance leaders can use immediately.
The complete report includes the full market sizing arc, segment-level insight, regional performance context, competitive analysis, and the compliance and certification frameworks that define viable equipment selection in the current period. For organizations preparing multi-site deployments, lifecycle replacements, or technology refresh cycles, the full intelligence set offers the depth required to make decisions with confidence rather than approximation. The core data, scenario-ready forecasts, and category-specific evaluations are available through the complete study, where the analytical detail and proprietary market architecture can be reviewed in full.
For detailed analysis of this topic, please visit the official page: Commercial Ice Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Centrifugal Chiller Market to Grow at 6.21% CAGR, Reaching $483.9M by 2032
By PW Consulting, 2026-09-16
Navigating the Next Decade: Strategic Intelligence in the Global Centrifugal Chiller Market
The commercial and industrial HVAC landscape is undergoing a structural transformation driven by stringent energy codes, the explosive growth of digital infrastructure, and a regulatory pivot toward low-global-warming-potential (GWP) refrigerants. For executives, facility owners, and engineering leaders, understanding the centrifugal chiller segment is no longer a technical afterthought—it is a capital allocation imperative. At PW Consulting, we have synthesized a multi-year historical record and a forward-looking forecast to illuminate where value will accrue between 2026 and 2032. This research is designed not as a static snapshot, but as a decision-grade instrument for portfolio planning, infrastructure investment, and competitive positioning.
Our baseline analysis anchors on a measured historical trajectory from 2020 through 2025, capturing the market's recovery and maturation phases. The global revenue base expanded from approximately 263.05 million USD in 2020 to 319.5 million USD by 2025, reflecting resilient demand across commercial campuses, heavy industrial processes, and the rapid densification of cooling requirements in technology-driven environments. Looking ahead, the forecast period to 2032 maps a sustained upward curve, with compounded annual growth projected at 6.21 percent. This trajectory signals more than incremental expansion; it indicates a market structurally re-rating around efficiency, refrigerant compliance, and application-specific engineering. Decision-makers who internalize these macro signals early will be better positioned to align procurement cycles, capacity planning, and technology roadmaps with the market's directional momentum.
The Architecture of the Study: From Macro Signals to Operational Playbooks
A credible market study must bridge the gap between aggregate forecasting and the granular realities of engineering, procurement, and operations. Our Centrifugal Chiller Market research is organized to support that translation. Rather than presenting a single headline number, the report decomposes the market along dimensions that matter to buying committees and capital planners: technology architecture, application contexts, and regional deployment patterns. These lenses allow readers to test assumptions about where capacity is being installed, which operating profiles dominate spend, and how regional regulatory climates influence product specification.
The study's operational value lies in its scaffold of decision-support content. Each section is constructed to answer a concrete planning question:
- Where does historical volatility end and structurally driven growth begin, enabling more reliable budgeting for multi-year capital programs?
- Which technology pathways—air-cooled versus water-cooled configurations—carry distinct risk-return profiles under evolving ambient conditions and efficiency mandates?
- How do application contexts such as commercial facilities, industrial operations, and data center environments shape load profiles, redundancy requirements, and lifecycle cost calculus?
- What regional dynamics influence project timing, specification preferences, and supply chain readiness across major demand centers?
By integrating these dimensions, the report gives stakeholders a structured way to compare scenarios rather than a single deterministic path. That distinction matters in a market where project lead times, refrigerant transitions, and efficiency targets can shift procurement economics within a single budget cycle.
Competitive Intensity and the Battle for Specification
The centrifugal chiller segment features a concentrated set of global manufacturers, each competing on thermodynamic performance, refrigerant readiness, and application-specific engineering. Our market concentration analysis indicates that the top three firms collectively account for roughly 60 percent of revenue, while the top five capture approximately 75 percent. This concentration reflects both the technical barriers to entry in large-capacity, high-efficiency chiller design and the importance of service networks, certification track records, and long-term operational credibility in winning institutional assignments.
Centrifugal Compressors Market
Within this landscape, several established players continue to advance product portfolios that directly address efficiency mandates and refrigerant compliance. Johnson Controls has emphasized its YK, YZ, YMC2, and YK-HT magnetic bearing centrifugal chillers, engineered for energy savings, low-GWP refrigerant compatibility, and large-capacity data center applications. Carrier has focused on the AquaEdge 19DV and AquaForce series, pairing variable-speed drives with sustainability-oriented features for commercial and industrial use. Trane Technologies offers CenTraVac and Series R magnetic bearing units positioned for high efficiency and space savings across commercial, industrial, and data center applications. Daikin Applied promotes its Magnitude WMT, WME-D, and WME series oil-free magnetic bearing chillers with two-stage compressors and low-GWP refrigerants. Mitsubishi Heavy Industries contributes efficient centrifugal platforms for energy saving and environmental protection in large commercial and industrial installations. LG Electronics brings its H Series 2-stage centrifugal chillers with inverter technology and AHRI 550/590 certified performance to the equation. In parallel, regional and specialized manufacturers extend the competitive field: Ecochillers from Guadalajara offers oil-free centrifugal chillers using low-GWP refrigerants and custom magnetic-bearing models for industrial and commercial applications, while Smardt Chiller Group from Dorval provides oil-free centrifugal units designed for laboratories, food, and pharmaceutical environments with ISO 9001 certification.
The strategic implication for buyers is that specification competition is intensifying at the edges of performance, refrigerant compliance, and application fit. For vendors, differentiation increasingly depends on demonstrating measurable lifecycle advantages under real operating conditions rather than headline capacity claims alone. Our report situates each company's positioning within the broader demand structure, helping readers interpret where competitive pressure is likely to influence pricing, service models, and technology roadmaps over the forecast period.
Latest Market Movements: Product Innovation Meets Regulatory Realities
Recent developments in the segment underscore how quickly product roadmaps and compliance requirements are converging. In February 2026, Johnson Controls previewed the high-density compact YORK YK-HT two-stage economized centrifugal chiller at the AHR Expo, highlighting a wide operating range from a single driveline, zero water consumption capability, and lift performance up to 110°F for data centers and large campuses. Announced in October 2024, Daikin Applied introduced the Magnitude WME-D magnetic bearing oil-free centrifugal chiller with a two-stage compressor and low-GWP R-515B refrigerant. These milestones are not isolated product launches; they are signals of how manufacturers are adapting to denser load profiles, water availability constraints, and refrigerant phase-down expectations.
These product movements intersect with a hardening regulatory and technical environment that shapes procurement specifications and performance validation. ASHRAE 90.1-2022 requires non-standard rating condition adjustments for water-cooled centrifugal chiller packages using the K adj equation to meet minimum full-load kW/ton and IPLV efficiencies. AHRI 550/590 certification is mandatory for all listed centrifugal chiller performance ratings, including full-load and integrated part-load values. In the United States, low-GWP refrigerants are mandated for new centrifugal chillers beginning January 2025, prompting manufacturers to expand compliant model lines; Johnson Controls, for example, extended YVAM air-cooled models to support compliance. At the technology level, magnetic bearing architectures in centrifugal chillers eliminate oil lubrication, reducing maintenance costs and enabling operation at condenser temperatures up to 30°F below chilled water setpoint.
Together, these forces create a market environment in which efficiency targets, refrigerant readiness, and certified performance documentation are becoming baseline expectations rather than premium differentiators. Organizations that anticipate these requirements in their specification language and vendor evaluation criteria will encounter fewer delays and lower residual compliance risk during project execution.
Where Decision-Makers Gain Edge: How to Use This Research
The strategic value of this study is highest when it is used to inform multi-layered decisions rather than a single purchase event. For capital planners and facility executives, the forecast structure supports capacity planning by clarifying the pace and shape of market growth across the 2026–2032 window. For engineering and specification teams, the segmentation framework provides a structured way to align chiller type and application context with operating goals, redundancy needs, and environmental constraints. For competitive strategy and sourcing functions, the company profiles and concentration metrics offer a lens into where market power resides and how vendor portfolios are evolving in response to regulatory and performance pressures.
Because the segment is moving on multiple vectors simultaneously—technology advancement, refrigerant compliance, certification rigor, and application growth—decision-makers benefit from a research asset that connects these vectors rather than treating them separately. The report is designed to support that integrative view. It helps teams frame questions such as whether a project's load profile favors a magnetic bearing platform, how regional specification norms affect product selection, and which company portfolios are most aligned with an organization's compliance timeline and operational priorities.
What Is Inside and How to Access the Full Intelligence
The complete study delivers a comprehensive map of the centrifugal chiller market across the 2020–2032 horizon, combining historical revenue context with a detailed forward forecast. It examines market size and growth trajectories, breaks down demand by technology type and application context, and reviews regional dynamics that influence deployment patterns and specification preferences. It further profiles leading manufacturers, evaluates recent product and compliance-driven developments, and integrates the regulatory and technical standards that shape performance validation. Market concentration metrics provide additional context on competitive structure and supplier power.
To preserve the analytical integrity of the forecast model and protect the proprietary structure of our segmentation work, certain detailed split values and regional or application-level breakdowns are reserved for the full report. The summary presented here is intended to demonstrate methodological rigor and strategic relevance while encouraging deeper engagement with the complete dataset. Readers who require precise segment sizing, regional distribution details, application-level revenue context, and company-level positioning data will find those capabilities fully developed in the final document.
Centrifugal Chiller Market
For teams tasked with navigating 2026 planning cycles, the Centrifugal Chiller Market research offers a structured baseline for scenario testing, procurement timing, specification alignment, and competitive benchmarking. By combining macro growth signals with practical decision frameworks, it helps organizations move from general market awareness to targeted action. To access the full report, including detailed segmentation figures, complete company profiles, and the underlying forecast methodology, please visit the source page to retrieve the complete intelligence package.
For detailed analysis of this topic, please visit the official page: Centrifugal Chiller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Cryogen Free Dilution Refrigerators Market to Hit $290M by 2032 at 8.5% CAGR
By PW Consulting, 2026-09-16
The Strategic Imperative: Navigating the Cryogen Free Dilution Refrigerators Market in 2026
In the rapidly evolving landscape of deep-tech infrastructure, the ability to maintain ultra-low temperatures without the logistical burden of liquid cryogens has shifted from a scientific aspiration to a commercial imperative. As we stand at the threshold of a new forecast period spanning 2026 to 2032, the demand for Cryogen Free Dilution Refrigerators is no longer niche. It is becoming a foundational element for industries pushing the boundaries of quantum mechanics, material science, and low-temperature detection.
This article serves as a strategic preview to our latest comprehensive market research. Our analysis is designed not merely to report numbers, but to equip enterprise leaders, investment strategists, and technology procurement officers with the intelligence required to make critical decisions in 2026. The transition toward cryogen-free systems represents a fundamental shift in operational expenditure, laboratory design, and scalability. Understanding the trajectory of this market is essential for any organization positioning itself within the quantum ecosystem or advanced research sectors.
Our recent market intelligence indicates a robust growth trajectory. The global market value, measured in USD Million, has demonstrated a consistent upward trend from a base valuation of 135.0 in 2020. By 2025, this figure has climbed to 182.0. Looking forward, the forecast suggests sustained momentum, with projections reaching 197.46 in 2026 and escalating toward 290.0 by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 8.5 percent over the forecast period. These figures are more than indicators of sales volume; they represent the increasing capital allocation toward technologies that eliminate the reliance on liquid helium, thereby reducing operational costs and environmental constraints.
The strategic value of this research lies in its granularity. While the top-line figures establish the market's vitality, the true decision-making power comes from dissecting the drivers behind this expansion. Enterprise leaders need to understand where the growth is concentrated, which technological specifications are driving procurement, and how the competitive landscape is solidifying. Our report delves into these layers, offering a roadmap for navigating the complexities of the supply chain and the technological requirements of end-users.
Market Dynamics and Growth Drivers
The expansion of the Cryogen Free Dilution Refrigerators market is inextricably linked to the broader advancements in quantum technologies. As quantum computing moves from experimental physics to engineering reality, the infrastructure supporting it must be reliable, scalable, and accessible. The shift away from liquid cryogen-dependent systems is driven by the need for continuous operation and reduced maintenance overhead. Laboratories and industrial facilities are increasingly prioritizing systems that offer stability without the logistical challenges of cryogen delivery and storage.
Our analysis highlights that the demand is not uniform across all temperature specifications. The market segmentation by base temperature reveals distinct preferences aligned with specific application needs. Systems capable of achieving base temperatures below 10mK dominate the current revenue landscape, reflecting the stringent requirements of high-fidelity quantum computing and sensitive qubit operations. However, there is significant traction in the segments covering base temperatures between 10-20mK and above 20mK. These ranges cater to a broader array of scientific instruments and material testing environments where ultimate cooling power is balanced against cooling capacity and system footprint.
Furthermore, the application landscape is diversifying. While quantum computing remains the primary catalyst for market value, material science research and low-temperature detection systems are significant contributors. The versatility of cryogen-free dilution refrigerators allows them to serve as multi-purpose platforms within advanced research facilities. This diversification mitigates risk for manufacturers and provides procurement officers with more options depending on their specific thermal and vibration requirements. The forecast period suggests that these applications will continue to mature, driving volume and encouraging further innovation in cooling power and integration capabilities.
Competitive Landscape and Strategic Positioning
The market structure for Cryogen Free Dilution Refrigerators is characterized by a mix of specialized innovators and established scientific instrument manufacturers. Our report provides an in-depth profiling of key companies that are defining the competitive standards. Understanding the positioning of these players is critical for enterprises evaluating supply chain resilience and technology partnerships.
Among the leaders is Bluefors Oy, headquartered in Helsinki, Finland. Bluefors has established a strong reputation for manufacturing measurement systems integrated with dilution refrigerators, including their LD and XLD series. Their focus on ultra-low temperature cooling to the millikelvin range makes them a pivotal partner for quantum computing initiatives requiring high stability. Similarly, Quantum Design Oxford, based in the United Kingdom, offers the Proteox series, which includes various models like ProteoxS and Proteox5mK. Their product line demonstrates a commitment to modular flexibility, catering to diverse experimental setups within the European and global markets.
Worldwide Wet Dilution Refrigerator Market
In the Netherlands, Leiden Cryogenics B.V. distinguishes itself through a specific engineering focus on low vibration and high cooling power. This specialization is crucial for experiments where mechanical noise can interfere with sensitive measurements, positioning Leiden as a provider for high-precision scientific applications. Meanwhile, Cryomech, Inc., operating out of Syracuse, New York, integrates dilution refrigerators with pulse tube and Gifford-McMahon cryocoolers. This integration capability highlights a trend toward compact, self-contained systems that minimize external dependency.
American manufacturers also play a significant role. Janis Research Company, located in Woburn, Massachusetts, focuses on scientific research applications, providing robust systems for academic and industrial labs. Montana Instruments Corporation, based in Bozeman, Montana, contributes to the market with He3/He4 systems, ensuring a breadth of technological approaches are available to consumers. The market concentration data indicates a competitive but not overly monopolized environment, with the top three players holding a significant yet balanced share of the market. This structure suggests opportunities for new entrants or niche players who can offer superior customization or specific performance metrics.
Operational Insights and Report Content
To support strategic decision-making, our comprehensive report goes beyond market sizing. It offers a detailed examination of the supply chain, regulatory environments, and technological barriers. Procurement leaders will find value in the comparative analysis of system integration costs versus long-term operational savings. The shift to cryogen-free technologies involves higher upfront capital investment but promises significant reductions in recurrent expenditure related to cryogen replenishment and logistics. Our financial models elucidate this break-even dynamic, helping CFOs and procurement officers build a business case for adoption.
The report also addresses the geographical nuances of market adoption. While we maintain confidentiality on specific regional revenue splits in this summary, our full analysis maps the intensity of demand across key global hubs. This includes an assessment of the infrastructure readiness in North America, Europe, and the Asia Pacific region. Each region presents unique challenges regarding installation support, service networks, and local research funding priorities. Understanding these regional dynamics is essential for companies planning global expansion or supply chain localization.
Additionally, the research includes a detailed breakdown of the application-specific requirements. Whether the end-use is quantum computing, material science, or low-temperature detection, the thermal load profiles and vibration tolerance levels differ. Our report categorizes these needs, providing a matrix that matches system specifications to application demands. This allows technology managers to avoid over-specifying equipment, thereby optimizing budget allocation without compromising performance.
Strategic Recommendations for 2026
As enterprises prepare their strategies for 2026, several key actions emerge from our analysis. First, there is a clear imperative to prioritize partnerships with manufacturers who offer robust service and support networks. The complexity of dilution refrigerators means that downtime can be costly. Evaluating vendors based on their service reach and technical support capabilities is as important as evaluating the hardware specifications.
Second, organizations should consider the scalability of their cooling infrastructure. The forecast growth suggests that demand will not only increase in volume but also in complexity. Investing in systems that can be upgraded or integrated into larger modular setups will provide long-term flexibility. This is particularly relevant for quantum computing firms that anticipate scaling from prototype to production environments.
Third, monitoring the technological evolution in cooling power is essential. The market is seeing a push toward higher cooling powers at millikelvin temperatures. Systems that can handle higher thermal loads without sacrificing base temperature stability will become increasingly valuable. Our report identifies which companies are leading this technological charge and what timelines to expect for next-generation releases.
Conclusion and Call to Action
The Cryogen Free Dilution Refrigerators market is at a pivotal juncture. The convergence of quantum technology advancements, the need for sustainable laboratory operations, and the maturity of cryocooler technology is creating a fertile environment for growth. The projected increase from 197.46 million in 2026 to nearly 290.0 million by 2032 underscores the significance of this sector in the broader high-tech economy.
However, capitalizing on this opportunity requires more than a superficial understanding of market trends. It demands deep intelligence into competitive moves, segmentation nuances, and regional dynamics. Our full report provides the complete dataset, including detailed segmentation splits, regional revenue analysis, and comprehensive company profiles that are not fully disclosed in this overview. For decision-makers committed to securing a competitive advantage in 2026 and beyond, accessing the complete intelligence is a strategic necessity.
Cryogen Free Dilution Refrigerators Market
We invite you to explore the full study to gain the granular insights needed to navigate this complex market. The detailed breakdown of segmentation by region, type, and application, along with the proprietary analysis of market concentration and future outlook, is available in our complete publication. Equip your organization with the knowledge to make informed investments and strategic partnerships in the evolving world of ultra-low temperature infrastructure.
For detailed analysis of this topic, please visit the official page: Cryogen Free Dilution Refrigerators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Parking Meter Market to Reach $7.64M by 2032, Growing at 3.76% CAGR
By PW Consulting, 2026-09-16
Navigating the 2026 Parking Meter Market: Strategic Intelligence for Long-Term Growth
The global parking infrastructure sector stands at a critical inflection point. Municipalities are no longer treating curb management as a static revenue function; they are redesigning it as a dynamic, data-driven component of urban mobility. For executives, procurement leaders, and investment committees operating in this space, the difference between reactive positioning and proactive strategy lies in the quality of intelligence available at the planning table. PW Consulting’s latest Parking Meter Market research was constructed precisely for that moment. It translates macro-level trajectory, competitive fragmentation, and operational shifts into an actionable framework for decisions that will shape portfolios through 2032 and beyond.
Why 2026 Demands a Refined View of the Curb Economy
Over the past half-decade, the market has moved from incremental hardware upgrades to systemic re-architecting. Historical revenue data from 2020 through 2025 illustrates a steady expansion, moving from a base of 4.87 million USD to 5.9 million USD by 2025. That progression reflects more than population growth or inflationary pass-through. It captures a concerted shift in how cities price access, how operators manage enforcement, and how payment ecosystems have migrated from isolated coin mechanisms to integrated, remotely managed platforms.
The forecast horizon through 2032 projects continued expansion, with the market anticipated to reach approximately 7.64 million USD by the close of the period. The implied compound annual growth rate of 3.76 percent may appear measured on the surface, yet in a capital-intensive, regulation-sensitive hardware and software market, that pace carries disproportionate strategic weight. It signals durable demand for modernized metering infrastructure, sustained municipal procurement cycles, and a widening aperture for smart-curb integrations that bridge on-street and off-street revenue streams. The real question for leadership teams is not whether the market will grow, but which segments, geographies, and operational models will capture the disproportionate share of that growth.
Structural Insights Embedded in the Research
A market of this character cannot be navigated through aggregate headlines alone. The report dismantles the overall trajectory into the operational and commercial dimensions that actually drive procurement cycles, deployment priorities, and vendor selection. It examines how metering solutions are bifurcated between single-space and multi-space architectures, why the balance between those configurations is shifting as cities pursue centralized management and dynamic pricing, and how on-street versus off-street applications create distinct demand profiles for hardware durability, payment flexibility, and enforcement integration.
Regional dynamics receive dedicated scrutiny because municipal procurement, labor environments, and digital-payment maturity differ sharply across territories. The research maps how established markets with entrenched metering networks are approaching replacement cycles, while emerging municipal adoption patterns in other regions are reshaping the deployment pipeline. Rather than presenting static splits, the analysis ties geographic variation to underlying drivers—regulatory frameworks, municipal budgeting rhythms, national purchasing agreements, and the pace of cashless adoption—to help decision-makers anticipate where demand will concentrate and where competitive pressure will intensify.
Equally important, the report addresses market structure. With a CR3 concentration of 38.4 percent and a CR5 concentration of 55.2 percent, the competitive landscape is neither a monolithic oligopoly nor a purely fragmented field. That middle-ground structure matters. It indicates the presence of influential incumbents with differentiated smart-curb portfolios, alongside a set of regional and specialized players that compete on manufacturing provenance, contract accessibility, and integration depth. For organizations evaluating partnerships, tenders, or organic product roadmaps, understanding where concentration genuinely exerts pricing and distribution power—and where it does not—is essential to resource allocation.
Competitive Architecture: Who Shapes the Field and How
The strategic value of vendor intelligence lies in recognizing not only who competes, but how their offerings map to municipal requirements and end-user expectations. The report profiles a cross-section of companies whose portfolios define the current competitive frontier.
- IPS Group, headquartered in San Diego, California, anchors its position on single-space meters coupled with real-time data capture, remote management, and an integrated smart parking ecosystem. Its trajectory reflects a broader industry movement toward curb platforms that extend beyond the meter itself into centralized management and enforcement workflows.
- J.J. MacKay Canada Limited, based in Ajax, Ontario, emphasizes parking meter solutions supported by national purchasing contracts and a product catalog designed for both on-street and off-street applications. Its approach highlights how procurement leverage and catalog breadth can shape municipal buying patterns, particularly where coordinated purchasing frameworks reduce administrative friction.
- Parking BOXX Inc., operating from Beaverton, Oregon, focuses on parking control systems, pay stations, and equipment tailored to surface lots and garages, complemented by cloud management software. Its positioning underscores the continued relevance of off-street revenue environments and the importance of software layers that unify multi-site operations.
- POM Inc., headquartered in Russellville, Arkansas, manufactures electronic parking meters that integrate coin, smart card, and mobile payments within a USA-based production environment. For buyers where supply-chain provenance, certification rigor, and diversified payment acceptance are decisive, that combination carries strategic weight.
- METRIC Group Ltd, based in Swindon, United Kingdom, provides parking terminals, pay-and-display machines, and management systems for on-street and off-street use. Its product breadth reflects the European preference for versatile terminal architectures that can be configured across varied municipal contexts.
- LocoMobi Inc., located in Toronto, Ontario, advances smart transportation and parking management systems with mobile payments and an AI-powered cloud portal. Its recent activity demonstrates how cloud-first management, manufacturing localization, and city-wide deployments are becoming interlocking pillars of competitive differentiation.
- Ventek International, based in the United States, specializes in automated pay stations and digital parking meters oriented toward revenue collection and on-street enforcement. Its emphasis on automation and enforcement alignment speaks to the operational priorities of agencies seeking to protect revenue integrity.
- Hectronic GmbH, headquartered in Bonndorf, Germany, builds smart parking machines with smartphone-like touch interfaces and cashless payment solutions, reinforced by high-security bank authentication. That orientation highlights a market segment where payment trust, user experience, and compliance rigor converge.
- SKIDATA AG, from Sankt Johann im Pongau, Austria, delivers digital curbside parking solutions, including the Skiosk family and integrated mobility systems. Its approach illustrates how app-based payment flows and license-plate recognition enforcement can reduce hardware dependency while expanding the functional scope of curbside management.
These profiles are not isolated snapshots. The report contextualizes them against recent developments that signal where each organization is strengthening its competitive stance. IPS Group’s November 2025 website relaunch elevated its parking and curb management narrative around an integrated smart parking ecosystem. LocoMobi’s September 2025 announcement of full manufacturing relocation to Canada, followed by its April 2026 commissioning of city-wide meters and its WorldStream cloud portal in Barrie, Ontario, reflects a deliberate alignment of production geography, cloud infrastructure, and municipal-scale deployment. ParkChicago’s January 2026 launch of app and pay boxes for on-street parking with mobile pay options illustrates how municipal programs continue to push mobile payment adoption into the field. Together, these movements reveal a competitive environment where product launches, manufacturing decisions, and city-wide installations are being used to consolidate market presence rather than merely announce features.
Parking Meter Market
Operational and Regulatory Forces Reshaping Deployment Decisions
A forecasting model alone cannot capture the forces that alter procurement timing, vendor selection, and total cost of ownership. The research weaves in current operational realities that are actively shifting the decision calculus for municipalities and their suppliers.
Regulatory and procurement events are already redrawing local timelines. The closing of Boston’s parking meter implementation services bid in February 2026, for example, is a reminder that municipal tenders do not merely purchase hardware; they reset competitive access, define integration expectations, and influence regional demand pipelines. For organizations tracking pipeline visibility, such events are early indicators of where deployment capital will flow and which capabilities will be required to win.
Supply-chain provenance and purchasing structures are equally consequential. POM’s ISO 9001-certified USA manufacturing facility in Russellville, Arkansas, and MacKay Meters’ national purchasing contract via OMNIA Partners for US customers demonstrate two distinct routes to procurement advantage. One route competes on certified domestic production and quality assurance; the other competes on aggregated purchasing power and contract accessibility. Both matter because municipal buyers increasingly weigh operational continuity, compliance assurance, and administrative efficiency alongside unit pricing.
Water Meter Market
Payment security and enforcement technology are also redefining the value proposition of metering hardware. Hectronic’s emphasis on high-security bank authentication for cashless payments points to a segment where transaction trust and fraud resistance are becoming procurement criteria in their own right. Meanwhile, SKIDATA’s digital curbside approach, which leverages app payments and license-plate recognition enforcement to reduce hardware costs, illustrates an alternative trajectory in which software, enforcement, and mobile payment layers absorb functions traditionally assigned to physical meter arrays. For decision-makers, these are not merely product variations; they are competing philosophies about how revenue integrity and operational cost should be balanced.
Transforming Intelligence into 2026 Decision-Qualifying Action
Market research earns its place in executive planning only when it connects directly to the choices teams face in the near term. The Parking Meter Market report is structured to support that transition. It gives leadership a defensible basis for questions that determine pipeline quality, product-roadmap alignment, and risk exposure:
- Which application environments—on-street or off-street—are likely to command the most resilient demand under current municipal budgeting and enforcement priorities, and what capability gaps must be closed to compete in each?
- How should organizations interpret the balance between single-space and multi-space deployments as cities pursue centralized management, dynamic pricing, and integrated enforcement?
- Where does market concentration genuinely influence pricing, channel access, and replacement cycles, and where do regional and specialized players retain enough differentiation to compete on contract structure, manufacturing provenance, or integration depth?
- What do recent product launches, manufacturing relocations, and city-wide installations signal about the capabilities that will separate winning vendors from the rest of the field over the next several procurement cycles?
- How should teams weight payment flexibility, cloud management, enforcement integration, and security authentication when evaluating total cost of ownership rather than headline hardware price?
In a market where the average growth trajectory is steady but the underlying drivers are diverse, the organizations that outperform will be those that allocate capital and R&D against the most durable demand signals rather than the loudest product announcements. That requires visibility into how regional procurement patterns, application-level deployment needs, and competitive positioning interact across the forecast horizon. It also requires an honest appraisal of where concentration shapes the market and where fragmentation creates openings for differentiated offerings.
Accessing the Full Intelligence Architecture
Aggregate figures and company profiles provide the surface of the analysis, but the strategic granularity that supports tender strategy, product planning, and investment prioritization resides in the full report. The complete research offers a structured dissection of market size evolution across historical and forecast years, a deeper examination of how type, application, and regional dynamics interact to shape demand, and detailed competitive profiling that ties each company’s offering to the operational problems municipal buyers are actively trying to solve. It also connects recent product launches, manufacturing moves, and procurement events to the forward-looking implications they carry for pipeline visibility and competitive access.
For teams preparing 2026 decisions—whether those decisions involve vendor selection, geographic expansion, product roadmap adjustments, or partnership strategy—the full report functions as a decision-support backbone rather than a static market snapshot. It is designed to be referenced in planning cycles, procurement reviews, and investment committees where the cost of misreading the market is measured in lost contracts, misallocated development spend, or exposure to shifting regulatory expectations.
The Parking Meter Market is expanding with measured consistency, but the competitive and operational context surrounding that expansion is evolving rapidly. Municipalities are rethinking curb revenue as part of broader mobility strategies. Vendors are aligning manufacturing, cloud platforms, and enforcement integrations to capture that shift. Payment security, procurement contracts, and digital enforcement are becoming decisive evaluation criteria. In that environment, strategic advantage belongs to those who can see not only how large the market is, but how its structure, concentration, and dynamics are likely to behave across the 2026–2032 horizon. The full research delivers that view.
For detailed analysis of this topic, please visit the official page: Parking Meter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


