



Category: Machinery & Automotive
PW Consulting: Ozone Analyzer Market to Reach $422.64M by 2032 at 6.0% CAGR
By PW Consulting, 2026-09-16
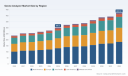
Executive Preview: Navigating the Ozone Analyzer Market in 2026 and Beyond
The global landscape for environmental monitoring and industrial safety is undergoing a significant transformation. As regulatory frameworks tighten and industrial processes become increasingly automated, the demand for precise gas detection and water quality assurance has never been more critical. At PW Consulting, we have compiled a comprehensive strategic analysis of the Ozone Analyzer Market, designed to equip stakeholders with the intelligence needed to navigate the forecast period from 2026 to 2032.
This article serves as an executive preview of our latest research. It outlines the macroeconomic trajectory, the shifting competitive terrain, and the regulatory forces shaping the industry. However, to ensure that our clients make decisions based on the most granular and actionable data, we have intentionally reserved specific segmentation breakdowns and detailed financial models for the full report. This preview establishes the strategic context, demonstrating why access to the complete intelligence suite is vital for 2026 planning.
Market Trajectory and Macroeconomic Context
The ozone analyzer sector is experiencing steady expansion, driven by heightened awareness of environmental compliance and the adoption of ozone-based disinfection technologies. Our analysis tracks market performance from historical baseline years through the current forecast horizon. The data indicates a consistent upward trend in revenue, reflecting both increased unit sales and a shift toward higher-value monitoring solutions.
For the base year 2025, the market established a significant valuation benchmark, setting the stage for accelerated growth in the coming years. The trajectory suggests that by 2032, the total market revenue will reach new heights, underpinned by a compound annual growth rate that underscores the sector's resilience. This growth is not merely linear; it reflects structural changes in how industries monitor ozone concentrations, moving from manual sampling to integrated, real-time digital monitoring systems.
Understanding the aggregate market size is only the first step. The true value for enterprise decision-makers lies in understanding the velocity of this growth across different technological and geographic vectors. While the overall top-line figures indicate a healthy market, the dispersion of value across different segments reveals where the highest margins and fastest adoption rates are occurring. Our full report dissects these layers to identify high-opportunity zones without exposing the company to the risks of generalized industry data.
Technological Segmentation and Application Drivers
The market is diversified across various technological methodologies and end-use applications. In terms of technology, UV photometric methods continue to hold substantial weight due to their precision and regulatory acceptance. Electrochemical solutions also represent a significant portion of the market, particularly where cost-effectiveness and portability are prioritized. The balance between these technologies is shifting as industries demand higher sensitivity and lower maintenance overhead.
Application-wise, the demand is broad but concentrated in specific sectors. Water treatment remains a cornerstone driver, with the Drinking Water Industry and Sewage & Industrial Process Water sectors accounting for a substantial share of adoption. However, growth is also notable in the Cosmetics and Pharmaceutical Industries, where ozone is used for sterilization and process purity. Environmental and Health Industries further contribute to the demand landscape, focusing on ambient air quality monitoring.
Strategic Note: While the broad categories are visible, the specific revenue contribution of each segment varies significantly by region and by vendor capability. Identifying which application segment offers the highest return on investment in a specific geographic territory requires the detailed segmentation matrices provided in the full PW Consulting study. General industry averages often mask local disparities that can make or break a product launch strategy.
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a mix of established multinational corporations and specialized niche players. Market concentration indicates a moderate level of consolidation, with the top five competitors holding a significant share of the total market revenue. This structure suggests that while there is room for innovation and entry, scale and regulatory certification are becoming increasingly important barriers to entry.
Ozone Generator Market
Key players are differentiating themselves through technology specialization and regulatory compliance. For instance, Teledyne API focuses on UV absorption analyzers such as the Model T400 and T703 series, which are EPA-approved for regulatory compliance. Similarly, 2B Technologies offers ambient and industrial UV-based ozone monitors certified as Federal Equivalent Methods (FEM), making them critical vendors for air quality and generator monitoring sectors.
Other notable entities include Aeroqual, known for portable and fixed ozone gas sensors for perimeter and indoor air quality applications, and HORIBA, which utilizes NDUV technology for ambient ozone monitors in air quality control. Acoem provides precise ambient air ozone measurements with the Serinus 10 analyzer, while BMT MESSTECHNIK GmbH specializes in high-concentration ozone analyzers with temperature and pressure compensation for industrial settings.
In the water treatment space, Hach integrates portable and process ozone analyzers with water treatment monitoring systems, whereas Sailhero targets marine and environmental ozone monitoring instruments. Thermo Fisher Scientific contributes instruments for environmental and laboratory air quality testing, and Eco Sensors focuses on environmental ozone sensors for air quality monitoring. IN USA, Inc. offers UV absorption ozone analyzers for high-concentration gaseous phase monitoring in safety and industrial applications, and Ozone Solutions Inc. provides monitoring systems for semiconductor, water, and industrial applications.
Strategic Note: Evaluating the specific market share and growth rate of each of these competitors requires the detailed competitor benchmarking section of our report. Knowing who leads the market is different from knowing which player is gaining share in high-growth segments like semiconductor manufacturing or pharmaceutical sterilization.
Regulatory Dynamics and Industry Developments
Regulatory frameworks are a primary catalyst for market demand. The U.S. Environmental Protection Agency (EPA) has implemented regulations that promote the use of ozone for disinfection, enhancing market growth in related monitoring solutions. Furthermore, the EPA is supplementing proposals to clarify the intended scope under the Protection of Stratospheric Ozone listing of substitutes. These regulatory actions create a compliance imperative for industries, driving the need for accurate, certified monitoring equipment.
Beyond regulation, industry standards are evolving. Trends in the ozone aging tester market emphasize ISO and ASTM standards for automation and certification in testing solutions. This shift toward standardized, automated testing increases the reliability of data and encourages the adoption of advanced analyzers that can integrate with broader quality management systems.
Recent industry activity also signals shifting dynamics. In May 2025, RainHarvest Systems launched new Pro Series and M Series ozone generator lines with integrated monitoring capabilities for water purification applications. Such product launches indicate a trend toward integrated systems where generation and monitoring are coupled, reducing installation complexity and improving reliability for end-users.
Strategic Value of the 2026-2032 Forecast Period
The forecast period from 2026 to 2032 represents a critical window for strategic investment. The market is expected to grow from a valuation of approximately 324.23 Million USD in 2026 to over 422.64 Million USD by 2032. This growth trajectory offers opportunities for capacity expansion, M&A, and product portfolio optimization. However, capturing this value requires precise timing and segmentation strategy.
Early movers who can align their product offerings with emerging regulatory requirements in North America, Europe, and Asia Pacific will gain a competitive advantage. The regional divergence in growth rates means that a one-size-fits-all strategy is inefficient. Some regions may prioritize ambient air quality monitoring due to urban pollution concerns, while others may focus on industrial process water due to manufacturing expansion.
Ozone Analyzer Market
Our full report provides the necessary depth to tailor strategies to these regional nuances. It includes detailed analysis of supply chain dynamics, pricing trends, and technology adoption curves that are not visible in high-level summaries. For executives planning capital allocation in 2026, understanding these granular drivers is essential to mitigate risk and maximize ROI.
Report Contents and Operational Utility
The PW Consulting Ozone Analyzer Market study is designed for operational utility. It goes beyond macro trends to provide actionable intelligence. The report covers:
- Detailed Segmentation Analysis: Breakdown by type, application, and region with historical and forecast data to identify high-growth pockets.
- Competitive Benchmarking: Profiled assessments of key market players, including their strategic moves, product portfolios, and regional footprints.
- Regulatory Impact Assessment: Analysis of how current and upcoming EPA regulations and ISO/ASTM standards affect demand and compliance costs.
- Market Concentration Metrics: Insights into CR3 and CR5 dynamics to understand competitive intensity and pricing power.
- Risk Factors and Opportunities: Identification of potential market headwinds and strategic avenues for growth.
Each section is crafted to answer specific strategic questions. For product managers, the segmentation data informs R&D priorities. For sales leaders, the regional breakdowns guide territory planning. For investors, the growth projections and competitive landscape assessments support valuation and due diligence processes.
Conclusion: The Case for Deep Intelligence
The Ozone Analyzer Market is poised for sustained growth, driven by regulatory tailwinds, technological advancements, and expanding industrial applications. However, the complexity of the market landscape means that surface-level data is insufficient for high-stakes decision-making. The difference between a successful market entry and a missed opportunity often lies in the details of segmentation performance and competitor positioning.
This preview highlights the structural elements of the market and the strategic importance of the 2026-2032 period. Yet, the specific data points that enable precise targeting and risk assessment are contained within the full PW Consulting report. We invite stakeholders to access the complete study to gain the comprehensive intelligence required to lead in this evolving sector. By leveraging deep-dive insights, enterprises can align their strategies with the most lucrative opportunities and navigate the regulatory complexities with confidence.
For detailed analysis of this topic, please visit the official page: Ozone Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Vacuum Pump Market to Hit $3.04B by 2032 with 6.5% CAGR
By PW Consulting, 2026-09-16
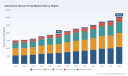
The Automotive Vacuum Pump Market: Strategic Intelligence for 2026 and Beyond
The automotive industry is navigating a structural transformation defined by electrification, stringent emissions regulations, and evolving safety architectures. At the intersection of braking performance, engine management, and thermal integration, the automotive vacuum pump market has emerged as a critical subsystem category. This report provides a comprehensive, decision-ready analysis of market trajectory, competitive positioning, and technology migration patterns across the forecast period from 2026 to 2032.
Our baseline assessment situates the market within a broader historical context spanning 2020 through 2025. Over this six-year window, the global market advanced from 1,520.0 million USD to a projected 1,950.0 million USD in 2025, reflecting sustained adoption of electric vacuum pumping solutions, integration into brake-by-wire architectures, and demand from hybrid and electric vehicle platforms. Looking forward, the forecast window projects continued expansion, with the market reaching 2,121.39 million USD in 2026 and progressing toward 3,043.56 million USD by 2032. This trajectory implies a compound annual growth rate of 6.5 percent, underscoring a market that is not merely growing in absolute terms but is also evolving in capability, supplier concentration, and application complexity.
For executive teams, product planners, procurement leaders, and investment analysts, these figures are not isolated statistics. They represent a signal of where value is moving within the powertrain and chassis subsystems landscape. The market is no longer defined by a linear replacement cycle. Instead, it is being reshaped by regulatory mandates, electrified brake architectures, and the need for on-demand vacuum generation in engine-off and start-stop conditions. Understanding this shift is essential for 2026 planning cycles, supplier negotiations, platform allocation decisions, and long-term portfolio strategy.
Why This Study Matters for 2026 Decision-Making
Strategic decisions made in 2026 will be judged against how well organizations anticipated the convergence of electrification, braking safety, and emissions compliance. The automotive vacuum pump market is no longer a peripheral component category. It sits at the core of brake assist reliability, hybrid energy management, and advanced driver assistance functionality. This research is designed to help leaders cut through short-term noise and focus on durable structural drivers.
The study translates market growth into actionable intelligence. Rather than presenting numbers in isolation, the analysis ties valuation trends to product substitution patterns, architecture shifts, and supplier capability profiles. Decision-makers can use this framework to assess where demand is most likely to intensify, which performance attributes will differentiate winning products, and how supplier ecosystems are consolidating or expanding around key vehicle programs. The report also supports scenario planning by linking technology deployment logic to real-world operational requirements such as low-noise operation, thermal load management, and rapid vacuum buildup during engine-off phases.
Equally important, the report provides context for regulatory and safety developments that influence purchasing and engineering priorities. On-demand vacuum generation has become a relevant factor in meeting CO2 reduction targets, supporting downsized engine architectures, and ensuring brake assist continuity in hybrid and electric applications. At the same time, market participants have had to respond to field performance concerns, including notable recall actions that highlighted the importance of robust vacuum pump reliability in certain brake assist conditions. These events reinforce the strategic value of better data, tighter quality oversight, and more resilient supplier selection.
What the Report Delivers in Practice
This market research is built for operational use. It goes beyond headline figures and provides a structured foundation for product planning, competitive benchmarking, and market entry evaluation. The study is organized to support practical decision-making across multiple functional areas:
- Market sizing and forecast logic that connects historical performance with forward-looking demand assumptions across the 2026 to 2032 period
- Technology segmentation analysis that examines how different pump architectures are positioned across vehicle categories and subsystem requirements
- Application-level demand mapping that identifies where vacuum pumps are most critical within brake systems, engine management, HVAC systems, and emission control domains
- Regional demand context that highlights where volumes are developing and how regional vehicle mix, electrification pace, and OEM sourcing strategies shape opportunity
- Competitive landscape profiling that evaluates major incumbents and emerging contributors by technology focus, geographic footprint, and program relevance
- Recent product and deployment developments that track how suppliers are translating engineering intent into market-facing launches and modular platform strategies
- Regulatory and safety context that frames how compliance requirements and field performance issues influence design priorities and sourcing confidence
The report is intentionally constructed to support both strategic and tactical use cases. Product planners can assess where to allocate development resources. Procurement teams can better understand concentration risk and alternative sourcing options. Commercial teams can identify which applications and regions are likely to generate the strongest demand momentum. Investors and analysts can use the framework to interpret supplier commentary, program wins, and technology migration signals with greater precision.
Competitive Landscape and Technology Leadership
The competitive structure of the market reflects a concentrated but diversified supplier base. Market concentration metrics indicate that the top three participants account for approximately 25.8 percent of market revenue, while the top five participants represent about 35.2 percent. This structure suggests that while scale incumbents remain influential, there is meaningful room for specialist suppliers, regional players, and technology-focused entrants to compete on performance, integration, and program access.
Several European and Asian suppliers are defining the current pace of innovation. Continental AG has been advancing electric vacuum pump solutions for brake systems in passenger cars, commercial vehicles, and hybrid applications, with integration pathways into zone control and brake-by-wire architectures. Robert Bosch GmbH has expanded its electric vacuum pump platform across global SUV programs that rely on brake-by-wire for stable vacuum independent of engine operation, while also supporting modular deployments with adaptive control and regenerative braking compatibility. MAHLE GmbH has focused on high-efficiency electric vacuum pumps with integrated thermal management modules suited to 48V mild-hybrid and electric vehicle architectures.
Valeo SA supplies electric vacuum pumps for brake assist and emissions control in micro-hybrid and electric vehicles, including OEM supply relationships with major Asian manufacturers. Hella GmbH & Co. KGaA provides electric vacuum pump solutions for power brake boosters, including auxiliary and diaphragm-type models for hybrid and internal combustion engine braking systems. Rheinmetall Automotive AG, through its Pierburg division, supplies high-efficiency electric vacuum pumps for hybrid passenger vehicles, optimized for low noise, rapid buildup, and on-demand operation during engine-off phases.
From an Asia-Pacific and emerging-market perspective, Denso Corporation develops diaphragm-type electric vacuum pumps for hybrid and internal combustion engines with adaptive control intended to improve braking and fuel efficiency. Aisin Seiki Co., Ltd. supplies electric vacuum pumps for automotive brake systems integrated with advanced driver assistance and efficiency-related systems. Ningbo Tuopu Group Co., Ltd. produces electric vacuum pumps as part of intelligent brake systems, supporting mass production and OEM supply for passenger and commercial vehicles. Youngshin Precision Co., Ltd. manufactures electric vacuum pumps for automotive braking systems with an emphasis on quality and global OEM supply. Johnson Electric develops electric vacuum pumps for automotive applications including brake assist and hybrid systems. Advik Hi-Tech Pvt Ltd manufactures and supplies advanced electric vacuum pumps for passenger cars and commercial vehicles, including 48V ABS-related applications for hybrid and electric use.
The competitive picture is not static. Recent activity through early 2025 shows how supplier roadmaps are being executed in practice. In January 2025, Advik Hi-Tech unveiled a broader range of automotive components, including advanced electric vacuum pumps for passenger cars and commercial vehicles. Also in January 2025, Robert Bosch GmbH expanded deployment of its electric vacuum pump platform across multiple global SUV programs using brake-by-wire for stable vacuum independent of engine operation. In March 2025, Continental AG unveiled a high-performance electric vacuum pump for passenger internal combustion engines in Europe, featuring adaptive vacuum control for power efficiency and regenerative braking support. In April 2025, Pierburg under Rheinmetall Automotive launched an electric vacuum pump in Germany designed to reduce CO2 emissions and enhance hybrid and brake systems. In the same month, Denso Corporation launched a diaphragm-type electric vacuum pump in Asia-Pacific with adaptive vacuum control for hybrid and internal combustion engines to improve braking and fuel efficiency.
Vacuum Pumps Market
These developments matter because they demonstrate a shift from generic component supply toward application-specific optimization. Suppliers are increasingly designing for engine-off reliability, low parasitic loss, noise reduction, and integration with electrified brake and chassis control systems. That shift has direct implications for sourcing strategy, validation requirements, and long-term supplier partnerships.
Demand Drivers and Market Dynamics
The market's forward momentum is anchored in several reinforcing dynamics. First, electrification and hybridization continue to reshape vacuum requirements. In hybrid and electric vehicles, vacuum can no longer be assumed from a running engine in all operating conditions. Electric vacuum pumps enable on-demand brake vacuum generation, which supports brake assist performance and helps vehicle programs comply with CO2 reduction targets while maintaining safe and predictable braking behavior in downsized and electrified powertrains.
Second, brake-by-wire and advanced driver assistance deployment are increasing the importance of stable vacuum management during engine-off and start-stop events. In 2025, deployments of electric vacuum pumps in brake-by-wire systems have provided stable vacuum for advanced driver assistance functionality during those transitions. This is not merely an efficiency consideration; it is a safety and architecture consideration that influences which pump technologies are selected for next-generation vehicle programs.
Third, integration into 48V mild-hybrid architectures has created new design priorities. Electric vacuum pumps in these systems can reduce thermal load and parasitic losses while maintaining brake booster performance. At the same time, high-efficiency electric vacuum pumps for hybrid passenger vehicles are being optimized for low-noise operation and pulse-width-modulated control to minimize energy draw during intermittent engine phases. These engineering refinements indicate a market that is moving toward higher-performance, more tightly integrated solutions rather than commoditized replacements.
Fourth, safety and reliability scrutiny remains an important market factor. Field events such as the NHTSA recall action in August 2025, which addressed vacuum pump failure that could reduce brake assist performance under specific conditions, highlight the consequences of performance variability in critical brake systems. For sourcing and engineering teams, this reinforces the need for thorough validation, robust quality processes, and supplier selection criteria that account not only for cost and volume, but also for long-term durability and system-level reliability.
These dynamics collectively shape the market's next phase. Demand is not simply increasing; it is becoming more selective. Vehicle programs are increasingly evaluating vacuum pump solutions in the context of electrified braking architectures, thermal constraints, acoustic targets, and regulatory expectations. Suppliers that can demonstrate adaptive control, low energy consumption, rapid vacuum buildup, and integration-ready packaging are better positioned to participate in higher-value programs.
Where the Market Appears to Be Heading
Based on the trajectory documented in this study, the market is likely to continue expanding as vehicle electrification deepens and brake architectures become more dependent on electronically managed vacuum support. Growth is expected to be distributed across multiple application domains, with brake systems and engine management remaining central demand anchors while HVAC and emission control applications contribute additional volume and differentiation opportunities. The relative importance of electric vacuum pumps is expected to rise as hybrid and electric vehicle content increases and as braking safety requirements become more tightly integrated with advanced driver assistance and chassis control logic.
Regional variation will continue to influence market outcomes. Vehicle mix, electrification pace, OEM sourcing preferences, and regulatory exposure differ materially across regions, and these differences shape where demand scales most quickly and which supplier capabilities are most valued. The report examines these regional patterns without reducing them to simplistic rankings. Instead, it situates each region within the broader context of vehicle production, technology adoption, and program timing.
The competitive environment is also likely to evolve through a combination of consolidation, technology specialization, and program-level competition. Incumbents with strong brake system integration and global OEM relationships will continue to play a leading role, while regional and specialist suppliers may gain traction where they can demonstrate differentiated performance in noise, efficiency, packaging, or application-specific control. The market concentration structure suggests that scale matters, but it does not guarantee advantage unless supported by product relevance and reliability.
How to Use This Research in 2026 Planning
This report is intended to support concrete decisions rather than generic market awareness. In 2026, organizations can use the findings to align product roadmaps with demand where it is most likely to grow, assess supplier portfolios against performance and integration requirements, and anticipate how regulation and safety expectations will shape validation and sourcing criteria. The study also supports more disciplined interpretation of supplier announcements, program wins, and technology launches by placing them in a broader market context.
Automotive Vacuum Pump Market
For teams comparing opportunities across applications or regions, the report provides a structured basis for evaluating where vacuum pump demand is most strategically relevant and which technology attributes are gaining importance. For teams managing supplier relationships, it offers a framework for assessing concentration, differentiation, and program readiness. For analysts and investors, it provides a market narrative that connects sizing, growth, and competitive action to underlying automotive trends rather than short-term cycles.
Conclusion
The automotive vacuum pump market is entering a phase in which growth and technology transformation are intertwined. Historical expansion from 2020 through 2025 and the projected path toward 2032 indicate a market that is responding to electrification, brake system modernization, and emissions-driven design constraints. The market is not simply getting larger; it is becoming more performance-sensitive, more application-specific, and more dependent on supplier capability in areas such as adaptive control, thermal integration, and reliability under engine-off conditions.
This report translates that complexity into a usable strategic framework. It combines market sizing, segmentation logic, competitive profiling, and recent industry developments with the regulatory and safety context that influences sourcing and engineering decisions. For organizations preparing for 2026 and beyond, the value of the study lies in its ability to connect market movement with decision-relevant insight.
For the complete dataset, detailed segmentation analysis, regional demand breakdowns, application-level valuation, and full supplier profiles, please access the full report through the source page. The executive summary presented here is designed to demonstrate the scope and analytical depth of the study while preserving the proprietary segmentation and directional intelligence that support informed commercial, engineering, and investment decisions.
For detailed analysis of this topic, please visit the official page: Automotive Vacuum Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dump Trucks Market Hits $5.3B in 2025, Poised for 6.0% CAGR Through 2032
By PW Consulting, 2026-09-16
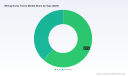
Navigating the Tides of Heavy Haulage: Strategic Insights for the Mining Dump Trucks Market (2026-2032)
The global mining dump trucks market stands at a critical inflection point. As we move into 2026, the convergence of operational efficiency demands, decarbonization mandates, and shifting geopolitical resource strategies is redefining the heavy-duty hauling landscape. For executives, investors, and strategic planners in the mining and construction machinery sectors, understanding the trajectory of this segment is not merely about tracking equipment sales; it is about anticipating the backbone of global material transport infrastructure. This article serves as a strategic primer, drawing from our latest comprehensive market research to outline the macro-economic forces, competitive dynamics, and technological disruptions that will define the forecast period from 2026 to 2032.
Our recent analysis indicates that the market is poised for steady expansion, driven by sustained commodity prices and the need to replace aging fleets with higher-capacity, more efficient machinery. However, beneath the surface of aggregate growth lies a complex web of segmentation, regional variance, and intensifying competition. This overview highlights the strategic value embedded in our full report, offering decision-makers a glimpse into the depth of intelligence available to navigate the coming years.
Electric Dump Truck Market
Macro-Economic Trajectory: Growth Drivers and Forecast Horizon
The financial backbone of the mining dump trucks sector demonstrates resilience. According to our latest data, the overall market revenue, denominated in USD billions, has exhibited a consistent upward trend over the historical review period from 2020 to 2025. Starting from a baseline of 3.96 billion in 2020, the sector navigated through global supply chain disruptions and economic volatility to reach 5.3 billion by 2025. This historical performance sets a robust foundation for the forecast period extending through 2032.
Projecting forward, the market is expected to expand from approximately 5.79 billion in 2026 to 7.97 billion by 2032. This trajectory corresponds to a Compound Annual Growth Rate (CAGR) of roughly 6.0 percent over the forecast horizon. For strategic planners, this suggests that while the market is mature, it is far from stagnant. Growth is being fueled by increased mining output in key resource-rich regions, the modernization of older haulage systems, and the introduction of trucks with higher payload capacities that reduce the total number of trips required per ton of material moved.
Mining Dump Trucks Market
It is crucial for stakeholders to recognize that these headline numbers represent the aggregate value of a highly specialized ecosystem. The revenue streams are not uniform across all equipment types or end-use applications. Understanding where the value is generated requires a granular examination of the product mix and the specific operational contexts in which these machines are deployed. Our full report dissects these layers to reveal which segments are outpacing the average growth rate and which are facing headwinds.
Market Segmentation: The Strategic Divide
The structure of the mining dump trucks market is defined by distinct categorical splits that influence procurement strategies and capital expenditure decisions. Our analysis categorizes the market primarily by vehicle type, application, and geographic region. Each division carries unique implications for manufacturers and mining companies alike.
Type and Application Dynamics
In terms of vehicle architecture, the market is split between rigid and articulated configurations. Rigid dump trucks dominate the landscape for large-scale surface mining due to their durability and load-bearing capacity, while articulated models remain essential for terrains requiring greater maneuverability, such as quarrying and certain underground operations. The balance between these two types is shifting slightly as mining sites become larger and more mechanized, favoring rigid haulers for primary haulage routes.
Application-wise, the demand is heavily skewed toward open-pit metal mining, which remains the primary driver of heavy haulage volume. Coal and lignite mining continues to be a significant segment, although its growth trajectory is influenced by regional energy transition policies. Meanwhile, quarrying and aggregates represent a steady, albeit smaller, portion of the market, driven by infrastructure development demands. The interplay between these applications dictates the specifications required by OEMs, from engine power to ground pressure and mobility features.
Regional Landscape
Geographically, the market is distributed across five key regions: North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Asia Pacific currently commands a substantial share of the market volume, reflecting the region's intensive mining activities and infrastructure investments. North America and Europe follow, with mature markets focused on fleet renewal and efficiency upgrades. The Latin America and Middle East and Africa regions offer emerging opportunities tied to specific resource discoveries and operational expansions. However, the relative weight of each region fluctuates based on commodity cycles and regulatory environments.
Detailed breakdowns of these segments, including precise revenue contributions and growth rates for each category, are critical for target market analysis. Our complete study provides the specific split values necessary for accurate regional and segment-level forecasting, enabling clients to allocate resources where the return on investment is highest.
Competitive Landscape: Concentration and Key Players
The mining dump trucks market is characterized by a high degree of concentration, which has significant implications for pricing power, innovation cycles, and supply chain resilience. Our research highlights a market environment where a select group of established giants controls a vast majority of the share. The top three companies collectively hold a CR3 of approximately 65 percent, while the top five expand this concentration to 85 percent. This oligopolistic structure suggests that market entry barriers are high, and competitive advantage is derived from technological differentiation, service networks, and total cost of ownership (TCO) performance rather than price competition alone.
Profiles of Dominant Forces
Several key companies define the competitive arena, each with distinct strategic positions:
- Caterpillar Inc. (Peoria, Illinois, USA): A perennial leader, Caterpillar continues to set the benchmark with its off-highway and mining dump trucks. Their Cat series, including the iconic 797F, exemplifies rugged engineering designed for heavy-duty hauling in the most demanding mining environments. Their strength lies in a comprehensive global service network and a reputation for reliability.
- Komatsu Ltd. (Tokyo, Japan): Komatsu is heavily invested in electrification and efficiency. Their electric drive mining trucks, such as the 930E-5 and 980E series, are tailored for large-scale open-pit operations. The company is also pushing the boundaries of alternative propulsion technologies.
- Hitachi Construction Machinery Co., Ltd. (Tokyo, Japan): Focusing on rigid dump trucks like the EH AC-5 series, Hitachi supports large-scale mining resource transport. They are expanding their manufacturing footprint, with decisions to begin full-scale production of dump trucks at specific facilities during the forecast period, signaling capacity growth.
- BelAZ (Zhodino, Belarus): As one of the world's largest manufacturers of heavy-duty mining dump trucks, BelAZ is known for massive payload capacity. Their 75710 series represents the upper echelon of haulage capability, serving operations that require moving immense volumes of ore.
- Volvo Construction Equipment AB (Gothenburg, Sweden): Volvo offers a mix of rigid haulers and articulated dump trucks. Notably, their strategy is evolving; recent announcements indicate a shift in focus toward rigid hauler innovation, with plans to close certain articulated hauler business lines to streamline their portfolio.
- Liebherr-International AG (Bulle, Switzerland): Liebherr serves high-payload hauling needs with series like the T 264, T 274, and T 282. They are actively integrating advanced systems into their diesel-electric trucks, including trolley-assist technologies that improve efficiency on specific mine routes.
- XCMG Group (Xuzhou, Jiangsu, China): XCMG is expanding its footprint with off-highway wide-body and electric drive dump trucks. Their XDE series targets open-pit mining, and recent deliveries in Oceania highlight their growing international reach.
- SANY Group (Changsha, Hunan, China): SANY provides off-highway mining trucks, including their SKT and SRT series. They compete in both wide-body and articulated applications, leveraging China's manufacturing scale to offer competitive solutions.
- Terex Corporation (Norwalk, Connecticut, USA): Through its Terex Trucks brand, the company focuses on rigid dump trucks built for tough mining conditions, emphasizing durability and flexibility.
- GHH Group GmbH (Germany): GHH specializes in articulated dump trucks for underground mining and tunneling, addressing niche but critical operational needs where space and maneuverability are paramount.
The strategic interactions between these players, including potential partnerships, product launches, and market share shifts, are analyzed in depth within our report. Understanding the specific offerings and strategic moves of each competitor is essential for positioning new products or assessing supplier risk.
Industry Dynamics: Technology, Regulation, and Strategic Shifts
The period from 2026 to 2032 will be defined by rapid technological evolution and regulatory pressure, particularly regarding emissions and operational efficiency. Several recent developments underscore the direction of the industry:
- Electrification and Alternative Fuels: The push for decarbonization is accelerating. Komatsu initiated proof-of-concept tests in early 2025 for the world's first large dump truck equipped with a hydrogen combustion engine, signaling a potential future beyond diesel-electric and battery-electric solutions. This highlights the experimentation phase occurring across the sector.
- Trolley-Assist and Efficiency Systems: Liebherr delivered a new generation of diesel-electric mining haul trucks equipped with trolley-assist systems to Collahuasi mine operations in early 2026. Such technologies allow trucks to draw power from overhead lines on gradients, significantly reducing fuel consumption and emissions during high-load segments of the haul cycle.
- Production and Portfolio Adjustments: Hitachi Construction Machinery decided to begin full-scale production of dump trucks in fiscal year 2026 at its dedicated manufacturing facility, expanding its capacity and market presence. Conversely, Volvo CE announced plans to close its Rokbak articulated hauler business by Q3 2026, redirecting focus to rigid hauler innovation. This indicates a strategic consolidation where companies are exiting segments that do not align with their core competencies or future technology roadmaps.
- Global Supply and Delivery: XCMG Group delivered a batch of XDE260 double-bridge rigid dump trucks for open-pit mine operations in Oceania in late 2024. This exemplifies the increasing competitiveness of non-traditional major players expanding into key markets outside their home regions.
These dynamics illustrate that the market is not static. Regulatory frameworks in various jurisdictions are tightening regarding particulate matter and greenhouse gas emissions, forcing manufacturers to innovate. Simultaneously, mining companies are under pressure to reduce their carbon footprints, creating demand for trucks that can operate with lower specific fuel consumption or alternative energy sources. Our report evaluates how these factors influence procurement cycles, total cost of ownership calculations, and long-term fleet planning.
Strategic Implications for 2026 Decision-Makers
For executives and strategic planners, the data points and dynamics outlined above point to several key considerations for 2026 and beyond. First, the high market concentration suggests that supply chain security and long-term service agreements with major OEMs are critical. Relying on a narrow supplier base carries risk, but the dominance of top players also ensures a level of technological sophistication and support infrastructure that smaller vendors may struggle to match.
Second, the growth trajectory of 6.0 percent CAGR should not be interpreted as a uniform opportunity. The value is unevenly distributed. Segments aligned with metal mining and regions with active infrastructure and mining projects will likely outperform others. Procurement strategies must be segmented accordingly, balancing the need for high-capacity rigid trucks for primary haulage with articulated solutions for secondary or complex terrain tasks.
Third, technology adoption is becoming a differentiator. The moves toward hydrogen combustion, trolley-assist, and electric drive systems are not just regulatory compliance measures; they are potential sources of operational cost savings and competitive advantage for mining companies. However, the right technology depends on the specific mine layout, gradient, and logistics. A generalized approach will not suffice.
Our full market research report provides the detailed intelligence required to act on these insights. It offers precise segmentation data, competitive benchmarking, and scenario analysis that allows organizations to model the impact of different strategic choices. From detailed revenue splits by type and application to region-specific growth forecasts, the report is designed to support capital allocation, product development, and market entry decisions with confidence.
In an industry where equipment lifecycles are long and capital investments are substantial, foresight is a valuable asset. The mining dump trucks market of 2032 will look different from that of 2026, shaped by the strategic decisions made today. We invite stakeholders to delve deeper into our findings to secure a comprehensive understanding of the opportunities and challenges ahead.
For detailed analysis of this topic, please visit the official page: Mining Dump Trucks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Isolated DC-DC Converter Market Hits $719.5M in 2025, 9.3% CAGR to 2032
By PW Consulting, 2026-09-16
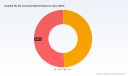
Navigating the 2026–2032 Inflection Point: Strategic Intelligence for the Isolated DC-DC Converter Market
The isolated DC-DC converter market is undergoing a structural transformation that extends well beyond incremental component sales. Over the past five years, the sector has consolidated around reliability, safety compliance, and modular efficiency, while demand signals from industrial automation, medical infrastructure, and next-generation power architectures have accelerated product roadmaps across major manufacturers. As enterprises map capital allocation, supply chain resilience, and technology adoption for 2026 and beyond, understanding where this market is heading—and why—is no longer optional. It is a strategic prerequisite for competitive positioning.
Our latest market research on the Isolated DC-DC Converter Market offers a comprehensive view of the industry’s trajectory from the 2020–2025 historical window through the 2026–2032 forecast period. Built for decision-makers who need actionable intelligence rather than superficial summaries, the study integrates macro revenue trends, segmentation dynamics, competitive profiles, and technology-driven regulatory pressures into a single analytical framework. This article previews the strategic logic behind the research and explains how it can inform enterprise planning in 2026.
Market Trajectory and Structural Momentum
Historical revenue performance from 2020 through 2025 demonstrates a consistent expansion path for isolated DC-DC converters, with market size growing from approximately $552.48 million in 2020 to $719.5 million in 2025. That progression reflects more than cyclical recovery; it signals durable demand anchored in safety-critical power conversion, industrial electrification, and distributed power architectures. The momentum continues into the forecast period, with projected revenue reaching $776.48 million in 2026 and advancing toward $1,337.14 million by 2032.
The forecast implies a compound annual growth rate of 9.3% across the 2026–2032 window, underscoring an industry that is scaling while simultaneously facing tighter performance, certification, and integration requirements. For enterprise planners, this trajectory matters because growth at this pace rarely distributes evenly across segments, geographies, or product categories. The strategic opportunity lies in identifying where the growth concentrates, which applications drive the largest value pools, and how regulatory and technology shifts reshape purchasing priorities.
Why 2026 Is a Decisive Planning Year
Several forces converge to make 2026 a pivotal year for isolated DC-DC converter strategy. On the demand side, industrial and automation deployments continue to favor isolated topologies that protect control electronics from high-noise environments and enable safe galvanic separation. Medical equipment manufacturers are reinforcing isolation requirements for patient-connected and safety-critical systems, which increases the importance of certified, application-specific converter platforms. At the same time, communications and networking infrastructure are driving demand for compact, high-efficiency modules that support evolving equipment density and thermal constraints.
On the supply and technology side, manufacturers are pushing bidirectional bus converters, modular zonal architectures, and compact SMD transformer solutions that broaden design flexibility. These advances are not merely product updates; they represent a shift in how engineers think about power distribution in complex systems. Enterprises that wait for settled standards or mature price curves may find themselves reacting to competitors who already align procurement, engineering, and product strategy around these emerging topologies.
The report is designed to help organizations anticipate rather than react. It frames the market in terms that matter to product planning, procurement, and investment decisions: where demand is strongest, how type preferences and application requirements shape purchasing, and what regulatory and certification expectations mean for design cycles and qualification costs.
Competitive Intensity and Portfolio Differentiation
The competitive landscape is defined by established manufacturers with differentiated product families, technical positioning, and regional service capabilities. The study profiles leading companies and evaluates how their portfolios map to the broader market structure.
Texas Instruments Incorporated maintains a broad isolated DC-DC converter portfolio that spans from ultra-low-power isolation devices to higher-power 48-V input solutions. Its product breadth supports customers who need flexibility across multiple power budgets and isolation levels. CUI Inc. focuses on encapsulated and DIN-rail isolated converters, including series built for higher power and renewable energy-related isolation requirements, which positions the company strongly in industrial and infrastructure use cases. Bel Fuse Inc. provides eighth-brick and high-power isolated DC-DC converters, with products targeted at networking, telecom, and computing applications where efficiency and footprint constraints are critical.
Isolated DC-DC Converter Market
Vicor Corporation has emphasized modular isolated DC-DC bus converters and bidirectional conversion concepts that align with modern 48-V zonal architectures, an area that has captured significant engineering attention for next-generation vehicle and high-performance power systems. RECOM Power GmbH continues to serve industrial, medical, and harsh-environment applications with compact SMD and modular solutions supported by international safety certifications, which makes it relevant in markets where compliance documentation and qualification rigor are purchasing prerequisites. Murata Manufacturing Co., Ltd. contributes reinforced-isolation converters for communication interfaces and PoE-compliant applications, reinforcing the market’s importance in signal-isolated and network-connected equipment.
Recent company developments illustrate how quickly the competitive narrative is evolving. In 2026, Vicor Corporation received a Product of the Year recognition for a bidirectional isolated DC-DC bus converter linked to 48-V zonal architectures in next-generation electric vehicles, highlighting how modular isolation concepts are gaining visibility beyond traditional industrial applications. RECOM Power GmbH expanded its discrete DC/DC converter components and SMD transformer offerings to support more flexible isolated power design. Earlier moves by Bel Fuse Inc. and Murata Manufacturing Co., Ltd. introduced high-efficiency 600-W isolated converters for networking and telecom, and a 1-W reinforced-isolation converter series for communication and analog front-end applications, respectively. These releases show that the market is being shaped by a combination of power scaling, isolation rigor, and application-specific optimization.
Regulatory and Application-Grade Pressures as Market Drivers
Regulations and safety standards are no longer peripheral concerns in isolated DC-DC converter purchasing decisions. They increasingly shape qualification timelines, design choices, and acceptable sourcing strategies. The report examines the practical implications of reinforced insulation expectations under UL62368 for operator protection in medical and industrial equipment, as well as the minimum 1500-VDC isolation expectations associated with IEC 60601-1 and IEC 62368-1 for patient-connected or safety-critical medical and laboratory applications.
In high-voltage environments, reinforced insulation to 200 Vrms, with basic insulation expectations around 250 Vrms, is part of UL62368 recognition considerations for module operation in demanding settings. For transportation and industrial deployments exposed to vibration and environmental stress, standards such as EN 61373 and EN 45545-2 introduce testing requirements that affect component selection, system qualification, and supplier evaluation. Together, these requirements raise the strategic importance of suppliers who can provide documented compliance, repeatable certification support, and design-in guidance.
The market research treats regulatory pressure not as a static checklist but as a dynamic factor influencing which product families gain traction, how design cycles evolve, and where certification readiness becomes a competitive advantage. For procurement and engineering leaders, this is critical because compliance risk can affect time-to-market, system acceptance, and long-term support obligations.
What the Report Delivers for Enterprise Decision-Makers
The study is structured to support multiple internal audiences, from strategy and investment teams to engineering, procurement, and product management. Its value lies in translating market data into planning-relevant questions and decision criteria.
The report includes:
- An integrated historical and forecast view of market size and growth, enabling organizations to benchmark internal expectations against the broader industry trajectory.
- Segmentation analysis that clarifies how the market is structured by product type, application, and region, helping teams identify where demand depth and differentiation are strongest.
- A competitive landscape evaluation that profiles major manufacturers, their product focus, and recent product and recognition developments, supporting supplier assessment and sourcing strategy.
- An examination of regulatory dynamics and application-grade requirements, including reinforced insulation and safety-critical isolation expectations, which helps align procurement with compliance realities.
- Market concentration context, including top-player share indicators, which supports assessments of competitive risk, pricing power, and supplier diversification strategies.
- Forward-looking interpretation of technology and architectural shifts, such as modular bus converters and bidirectional conversion concepts, relevant to roadmap planning and design-in decisions.
Importantly, the research is designed to avoid superficial number-dropping. Instead, it connects revenue trends with the operational questions that matter in 2026: which applications are expanding fastest, how type preferences vary across industrial, medical, consumer, and other end-use contexts, and how geographic demand patterns influence sourcing and localization decisions. Detailed segment values and regional breakdowns are presented within the full study so that strategy teams can build precise internal models without relying on incomplete or generalized estimates.
Worldwide Synchronous Buck Converter Market
How to Use This Insight in 2026 Planning
For organizations planning product portfolios, the research supports a more disciplined reading of where isolated DC-DC converter demand is likely to grow and what kind of products will be preferred in those applications. For procurement and supply chain teams, it clarifies the competitive structure and concentration dynamics that affect sourcing risk, supplier negotiation, and qualification strategy. For investment and business development teams, it provides a framework for evaluating where innovation is being rewarded, where regulatory requirements are raising barriers, and where consolidation or differentiation may reshape the competitive field.
The market is large enough to attract broad participation, yet specialized enough that application knowledge and compliance capability still matter. That combination creates both opportunity and risk. Companies that treat isolated DC-DC converters as a commodity component may underestimate the strategic weight of isolation class, certification support, and architecture fit. Companies that align their planning with the market’s real segmentation and competitive dynamics are better positioned to secure qualified supply, shorten design cycles, and capture demand in the applications that matter most.
Get the Full Strategic Picture
This overview highlights the strategic logic behind the Isolated DC-DC Converter Market research and why it is relevant for 2026 decision-making. The complete study goes further, providing the segment-level detail, competitive analysis, and forward-looking interpretation needed to build robust internal plans. For teams that require precise market sizing, application-driven segmentation, geographic context, and a structured view of the competitive landscape, the full report delivers the depth necessary to support confident strategy.
Access the complete market research to obtain the full forecast, segmentation data, company profiles, regulatory analysis, and practical planning frameworks built for enterprise use.
For detailed analysis of this topic, please visit the official page: Isolated DC-DC Converter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gyrocopter Market Hits $166M in 2025, Projected to Reach $271M by 2032 at 7.3% CAGR
By PW Consulting, 2026-09-16
Strategic Horizons in the Gyrocopters Market: A 2026 Executive Perspective
Navigating a Maturing Aerial Mobility Sector
The global gyrocopters market stands at a pivotal inflection point as it enters 2026. Over the past half-decade, the industry has transitioned from a niche recreational curiosity into a structured, certification-driven segment of light aviation. Our latest comprehensive research study maps this transformation across a seven-year forecast window, providing executives, investors, and operational strategists with the analytical rigor required to navigate an increasingly complex competitive landscape. The sector has demonstrated consistent expansion, with market revenue climbing steadily from approximately 120.0 million USD in 2020 to a projected 166.0 million USD in 2025. This trajectory reflects not only sustained enthusiast demand but also the gradual institutionalization of gyroplane operations across commercial, training, and specialized aerial applications. As we project forward through 2032, the market is anticipated to follow a disciplined growth curve, reaching an estimated 271.0 million USD by the end of the forecast period. This represents a compound annual growth rate of 7.3 percent, a figure that underscores both the resilience of the underlying demand drivers and the incremental but meaningful structural shifts currently reshaping procurement, certification, and operational deployment strategies.
For corporate decision-makers, the strategic question is no longer whether gyrocopters will gain broader operational relevance, but rather how to position portfolios, supply chains, and go-to-market frameworks to capture value in a market that is simultaneously expanding and fragmenting. The 2026 edition of our market intelligence report is designed precisely to answer that question. Rather than offering a superficial snapshot, the study dissects the operational, regulatory, and competitive forces that will determine which manufacturers, distributors, training providers, and service integrators will capture disproportionate share in the coming years. Executives who approach this sector with the same analytical discipline applied to higher-volume aviation segments will uncover asymmetric opportunities in certification pathways, regional deployment strategies, and application diversification that less prepared competitors will overlook.
Macro Trajectory and the Architecture of Growth
Examining the historical baseline from 2020 through 2025 reveals a market that has matured with remarkable consistency. The progression from 127.81 million USD in 2021 to 133.62 million USD in 2022, followed by a step-up to 143.2 million USD in 2023 and 156.04 million USD in 2024, reflects an ecosystem that has moved beyond post-pandemic recovery dynamics and into a phase of structural consolidation. By 2025, the market had reached 166.0 million USD, setting a robust foundation for the forecast horizon. The projected climb to 183.95 million USD in 2026, 194.71 million USD in 2027, and 203.03 million USD in 2028 indicates sustained momentum, while the larger forward estimates of 213.91 million USD in 2029, 229.39 million USD in 2030, 251.46 million USD in 2031, and 271.0 million USD in 2032 suggest that the market is positioning itself for a more meaningful acceleration as certification frameworks mature and application diversification takes hold.
This growth architecture is not merely a function of unit volume expansion. It reflects a broader recalibration of how gyrocopters are perceived within the light aviation ecosystem. Historically constrained by fragmented certification regimes and limited commercial applicability, gyroplanes are increasingly being evaluated through the lens of operational efficiency, short-field performance, and lower total cost of ownership relative to comparable fixed-wing or rotary alternatives. The 7.3 percent CAGR embedded in our forecast reflects the compounding effect of these dynamics: incremental regulatory clarity, expanding pilot licensing pathways, and a growing recognition of gyrocopter utility in training, tourism, and specialized commercial operations. For strategists, the implication is clear. Market expansion will not be evenly distributed across all participants. Companies that align their product roadmaps, service networks, and compliance capabilities with the contours of this growth curve will be best positioned to translate macro momentum into durable competitive advantage.
The 2026 Decision Framework: Why This Study Matters
The strategic value of this research lies in its deliberate alignment with the operational realities facing executive teams in 2026. Market entry, portfolio optimization, supplier selection, and partnership structuring all require a granular understanding of how demand is distributed across applications, how regional maturity differs, and how regulatory evolution is reshaping the commercial viability of gyroplane operations. Our report is structured to provide exactly that decision-grade intelligence. It moves beyond high-level sizing to examine the operational mechanics that drive procurement cycles, the certification milestones that unlock new revenue streams, and the competitive maneuvers that are redefining market positioning across Europe, North America, and emerging regional markets.
Executives evaluating investment in gyrocopter-related ventures, whether through direct manufacturing, distribution agreements, training infrastructure, or service-network development, will find the study particularly relevant. The forecast window through 2032 allows leadership teams to model scenario-based outcomes, stress-test assumptions around certification timing, and identify the inflection points where early positioning yields disproportionate returns. Equally important, the report is designed to function as a living reference for ongoing strategic planning. By synthesizing historical performance, forward-looking projections, and the latest regulatory and product developments into a single analytical framework, the study equips decision-makers with the contextual depth required to move from reactive market monitoring to proactive strategy formulation.
Helicopter Simulator Market
Regulatory Catalysts and the Reconfiguration of Market Dynamics
The regulatory environment has emerged as one of the most consequential drivers of market evolution. Recent policy developments across major aviation jurisdictions are systematically reducing the friction that historically constrained gyrocopter commercialization. In December 2025, the European Union Aviation Safety Agency issued ED Decision 2025/022/R, which introduced updated flight crew licensing requirements for private pilot licenses under a newly defined air mobility category specifically tailored to gyrocopters. This regulatory clarification is significant because it streamlines the pathway for pilot certification, reduces ambiguity around operational eligibility, and aligns gyroplane training with broader light aviation mobility frameworks. For manufacturers and training organizations, the decision expands the addressable base of qualified pilots and strengthens the commercial case for scaled deployment.
On the other side of the Atlantic, the Federal Aviation Administration’s July 2025 modernization of Special Airworthiness Certification rules amended the regulatory framework governing the manufacture, certification, operation, maintenance, and alteration of light-sport aircraft, with explicit inclusion of gyrocopters. This update is expected to enhance procedural clarity for builders and operators, reduce compliance uncertainty, and facilitate more predictable certification timelines. Together, these regulatory shifts are not merely administrative adjustments; they are structural enablers that lower barriers to commercial adoption and encourage more disciplined investment in product development, service infrastructure, and operational scaling. The cumulative effect is a market environment in which certification competence, rather than novelty, becomes the primary differentiator.
Beyond jurisdictional rule-making, certification milestones at the manufacturer level are further reshaping competitive dynamics. Leading producers have increasingly pursued dual certification pathways that bridge recreational and commercial operational categories, enabling aircraft to be deployed across a broader set of use cases. The pursuit of recognized airworthiness standards, including alignment with ASTM and EASA frameworks, has become a strategic imperative for companies seeking to validate product credibility, expand market access, and support operators who require regulatory certainty for commercial deployment. These certification developments are not isolated technical achievements; they are market signals that indicate where the industry is heading and which capability sets will be most valuable in the years ahead.
Competitive Architecture and the Battle for Positioning
The competitive landscape is defined by a concentrated but strategically diverse set of manufacturers, each pursuing distinct positioning strategies across performance, certification, regional presence, and application focus. Market concentration metrics indicate a notably fragmented top tier, with the top three participants collectively holding approximately 25.5 percent of revenue and the top five reaching roughly 32.4 percent. This distribution suggests a market in which no single entity exerts dominant control, leaving substantial room for differentiated positioning, regional specialization, and application-specific innovation.
AutoGyro, headquartered in Friedrichshafen, Germany, remains the largest gyrocopter manufacturer globally and has built its reputation on a broad portfolio that includes the MTOsport, Cavalon, Calidus, and related models. With over 2,000 aircraft delivered worldwide, the company’s strategic advantage lies in its comprehensive certification footprint, spanning UK BCAR Section T, ASTM, EASA Part 27, and FAA Primary Category approvals. This multi-jurisdictional certification capability positions AutoGyro to serve both recreational and commercially oriented operators, while its ongoing product updates and certification refreshes signal a deliberate effort to maintain regulatory and market relevance. The company’s scale and certification breadth make it a benchmark against which competitors measure their own market-access strategies.
Magni Gyro, based in Besnate, Italy, represents a different strategic archetype. With a fifty-year heritage in ready-to-fly gyroplanes, the company emphasizes safety, reliability, and performance across both work and leisure applications. Its lineup, including the M26 Victor and M16 Extreme, reflects a focus on operational dependability and long-standing manufacturer credibility. Magni’s participation in major industry events, such as its showcase at the France Air Expo 2026 in Lyon, underscores a continued commitment to visibility, customer engagement, and product demonstration in key European markets. For buyers and partners, Magni’s value proposition centers on institutional experience and a disciplined approach to engineering and operational consistency.
ELA Aviation, operating from Córdoba, Spain, has carved out a distinct performance-oriented position. Its product range, encompassing the Business Class, Sport Line, and Professional line gyrocopters including the Eclipse EVO, REVO, and ELA-07, is associated with industry-leading short takeoff distances and high-speed certified autogyro performance. This engineering emphasis on operational efficiency and performance extremes appeals to operators who prioritize field flexibility and speed characteristics. ELA’s positioning demonstrates how product differentiation around measurable flight performance can serve as a powerful competitive lever in a market where operational utility is increasingly scrutinized.
Aviation Artur Trendak, headquartered in Jaktorów, Poland, occupies a strategically important position in the European manufacturing base. As a leading producer of piston-powered gyrocopters, its Taifun series, often paired with Rotax 916 engines, has achieved remarkable domestic market penetration, with approximately 90 percent of Polish registered gyrocopters attributed to Trendak models. The company’s side-by-side configurations for commercial and leisure applications illustrate a flexible approach to use-case design. Trendak’s dominance in its home market highlights the importance of regional manufacturing credibility, localized support ecosystems, and product familiarity in driving sustained adoption.
Airgyro Aviation, based in Utah, USA, extends the competitive field into the North American context by offering U.S.-based warranty coverage, certified gyrocopters built on Trendak-derived designs with Rotax engines, and a localized support, training, and service network outside Poland. This model reflects a strategic emphasis on reducing geographic and service barriers for North American buyers, aligning product availability with regional after-sales expectations. Airgyro’s approach illustrates how cross-border manufacturing relationships can be combined with localized service infrastructure to address market-specific procurement and operational concerns.
Beyond Unit Economics: Application Diversity and Strategic Optionality
One of the most strategically significant dimensions of the market is the widening spectrum of applications across which gyrocopters are being evaluated. Demand is no longer confined to a single use case. Instead, it spans recreational and training operations, tourism and aerial tours, and commercial or agricultural deployments, each with distinct procurement drivers, regulatory considerations, and service expectations. Training and recreational demand continues to form a foundational pillar of the market, supported by evolving licensing pathways and a growing base of qualified pilots. Tourism and aerial tour operators represent a second major demand cluster, where short-field capability, low operating cost, and passenger experience considerations intersect to create viable business models in suitable geographic markets. Commercial and agricultural applications, while currently smaller in relative scale, offer some of the most compelling long-term optionality, particularly where operators seek efficient, cost-sensitive aerial platforms for specialized tasks.
The strategic implication for market participants is that application diversification is becoming a central competitive variable. Manufacturers and service providers that can align product configurations, certification profiles, and support structures with multiple application pathways will be better positioned to buffer against cyclical demand shifts and capture value across different customer segments. Conversely, strategies that remain overly dependent on a single application vertical may face greater exposure to regulatory, economic, or operational disruptions. Our report examines these application dynamics in detail, helping executives understand where demand is most structurally supported, where marginal growth is likely to emerge, and how competitive positioning should adapt to capture cross-application opportunities.
Report Scope: The Operational Intelligence You Will Gain
This study is structured to deliver actionable intelligence rather than abstract market commentary. It provides a comprehensive assessment of market sizing, growth trajectories, and the structural factors shaping demand across the 2026 to 2032 forecast period. The analysis integrates historical performance data from 2020 through 2025 with forward-looking projections, enabling leadership teams to benchmark past trends against anticipated market evolution. Beyond aggregate sizing, the report examines how competitive forces, regulatory developments, and application-level demand are interacting to shape procurement behavior and market access strategies.
Readers will gain a clear understanding of the competitive architecture, including manufacturer positioning, certification strategies, regional presence, and the extent to which market concentration is influencing pricing, service expectations, and product differentiation. The study also explores the regulatory catalysts currently reconfiguring the operating environment, translating policy updates into practical implications for product planning, certification investment, and commercial deployment. Importantly, the analysis is designed to support scenario-based strategic planning. Executives can use the framework to evaluate market entry timing, partnership structures, regional expansion priorities, and product-roadmap alignment with emerging demand patterns. The report is intended to serve as a decision-support instrument for executives who need to move from high-level market awareness to precisely calibrated strategic action.
Why 2026 Is the Right Moment to Act
The convergence of regulatory clarity, certification maturation, application diversification, and sustained revenue growth makes 2026 a strategically sensitive year for gyrocopter market participants. Companies that delay strategic positioning until the market’s growth trajectory becomes unmistakably obvious will likely face higher entry costs, tighter competitive windows, and reduced flexibility in supplier and partnership selection. Those that act now can shape their market presence proactively, aligning product offerings, service capabilities, and compliance investments with the structural trends that will define the next several years of industry development.
Gyrocopters Market
Our full market research report provides the depth, granularity, and strategic framing required to make those decisions with confidence. It is built for executives who require more than headline figures and generic growth narratives. If your objective is to understand where value is being created, which competitive capabilities matter most, and how to structure your approach for the 2026 through 2032 window, the complete study offers the comprehensive intelligence necessary to move forward with precision. We invite you to access the full report to explore the detailed segmentation, regional breakdowns, competitive assessments, and forward-looking scenario analysis that will support your next strategic move.
For detailed analysis of this topic, please visit the official page: Gyrocopters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Compressor Blades Market Hits $12.5 Billion in 2025, Forecasts 5.2% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Next Phase of Growth: Strategic Intelligence for the Compressor Blades Market
In an era defined by rapid technological evolution and stringent regulatory oversight, the compressor blades sector stands at a critical inflection point. As propulsion systems demand higher efficiency, lighter weight, and enhanced durability, manufacturers and investors must move beyond surface-level trends to grasp the underlying structural drivers shaping the industry. This article outlines the strategic value of our latest market research, offering a preview of the comprehensive intelligence designed to support confident decision-making throughout the forecast horizon.
The global compressor blades market has demonstrated consistent expansion over the past half-decade, reflecting steady demand across aerospace and industrial energy sectors. Drawing on a robust historical dataset spanning 2020 through 2025 and extending forward to 2032, our analysis establishes a clear trajectory of sustained growth. The market has evolved from a baseline of 9.57 billion USD in 2020 to an estimated 12.5 billion USD in 2025, with projected revenues reaching 17.82 billion USD by 2032. This expansion corresponds to a compound annual growth rate of 5.2 percent across the forecast period, underscoring a mature yet dynamically evolving industry landscape.
Worldwide Gas Turbine Turbine Blades Market
Such macroeconomic momentum is not uniform; it is propelled by intersecting technological, regulatory, and operational forces that require nuanced strategic interpretation. Our research dissects these drivers to reveal where capital allocation, supply chain optimization, and product development efforts will yield the highest marginal returns. Rather than presenting static figures, the report contextualizes growth within real-world operational constraints, procurement cycles, and engineering imperatives that define competitive advantage.
Decoding Market Architecture Through Actionable Segmentation
To translate broad market trajectories into executable strategy, our report constructs a multidimensional segmentation framework that isolates the structural components of demand. The analysis examines compressor blade categories differentiated by operational pressure profiles, highlighting how high-pressure variants and low-pressure alternatives serve distinct engineering requirements and procurement cycles. Each category carries unique material specifications, manufacturing tolerances, and lifecycle considerations that influence pricing dynamics, lead times, and aftermarket opportunities.
Similarly, the application landscape is dissected across aviation engines, industrial gas turbines, and turbocharger systems. These segments operate under divergent performance benchmarks, regulatory environments, and replacement cadences. By mapping demand intensity, technological readiness, and procurement predictability across these applications, the report equips strategists with the clarity needed to prioritize product roadmaps and market entry initiatives without relying on oversimplified generalizations.
Regional dynamics are explored with equal rigor, examining how established aerospace hubs, emerging manufacturing corridors, and defense procurement centers contribute to overall market momentum. The geographic breakdown illuminates disparities in supply chain maturity, local content requirements, and infrastructure readiness, enabling organizations to calibrate their operational footprint and risk exposure accordingly. Throughout this analysis, the report deliberately reserves granular percentage splits and region-specific revenue figures for the full dataset, ensuring that strategy teams engage with the complete intelligence package before committing to allocation decisions.
Competitive Landscape: Concentration, Differentiation, and Strategic Positioning
The compressor blades industry exhibits a moderately consolidated structure, with the top three players commanding approximately 45.6 percent of market revenue and the top five collectively controlling 62.3 percent. This concentration reflects the high barriers to entry inherent in precision aerospace manufacturing, including advanced metallurgy capabilities, certified quality management systems, and long-cycle customer relationships. Yet beneath this consolidated core lies a diverse ecosystem of specialized manufacturers, repair providers, and component integrators that compete on precision, lead time, and niche engineering expertise.
Our competitive analysis profiles a broad spectrum of incumbent leaders and specialized operators, mapping their strategic positioning across commercial aviation, military propulsion, and industrial applications. Organizations such as GKN Aerospace, Rolls-Royce Holdings, and Safran S.A. anchor the high-end aerospace segment, leveraging advanced composites, titanium alloy production, and integrated gas turbine designs to sustain performance leadership. RTX Corporation and Pratt & Whitney reinforce their positions through engine program integration, spanning commercial platforms and military series such as the F100 family, while MTU Aero Engines and IHI Corporation extend their reach across both aircraft and industrial gas turbine applications.
The competitive field also includes precision manufacturers and supply chain specialists that enable agility and cost efficiency across a range of platforms. Howmet Aerospace, Chromalloy, Hi-Tek Manufacturing, TURBOCAM International, Moeller Aerospace, Doncasters Group, Farinia Group, Stork B.V., Blades Technology, Pacific Sky Supply, and Collins Aerospace each contribute distinct capabilities, from titanium alloy precision machining to aftermarket repair and component substitution services. Mitsubishi Heavy Industries rounds out the landscape with dual-use aero and industrial competence. By evaluating these players through lenses of technology ownership, vertical integration, geographic reach, and aftermarket competency, the report reveals where consolidation pressure may intensify, where partnership opportunities are most viable, and where new entrants could capture niche share.
Importantly, the report does not merely catalog competitors; it assesses the strategic implications of their product architectures, procurement dependencies, and capacity utilization patterns. This enables executives to benchmark their own positioning, identify vulnerability in single-source dependencies, and evaluate potential consolidation or joint development scenarios with a clear understanding of market concentration dynamics.
Regulatory Pressures and Operational Dynamics Reshaping Demand
Beyond structural segmentation and competitive positioning, the compressor blades market is increasingly shaped by regulatory mandates, sustainment contracts, and in-service durability considerations. Recent regulatory activity illustrates how safety-driven interventions can rapidly alter demand patterns and procurement timelines. In November 2025, the FAA announced plans to mandate the replacement of specific V2500 high-pressure compressor stage 3 rotor blades to address durability issues identified in operational service. This enforcement trajectory highlights the direct link between airworthiness oversight and replacement demand, reinforcing the importance of aftermarket readiness, traceability, and rapid response manufacturing capabilities.
Parallel defense procurement activity further illustrates the interplay between regulatory programming and component demand. In August 2025, the Defense Logistics Agency Aviation issued contract SPRTA1-25-R-0356, requiring procurement of compressor blade sets for F100-229 engines with delivery scheduled by May 31, 2026. Shortly thereafter, in January 2026, the Air Force Sustainment Center solicited support for TF33 first-stage compressor blade repair, with a due date in early February 2026. These actions underscore the persistent demand generated by military sustainment cycles, engine modernization programs, and the operational necessity of maintaining readiness across legacy and current-generation platforms.
These developments are integrated into the report’s market dynamics section, where regulatory trajectories, procurement calendars, and durability-driven replacement cycles are analyzed as strategic levers rather than isolated events. Organizations that internalize these patterns can better align production scheduling, inventory positioning, and repair network investments with the rhythm of mandated replacements and defense procurements. The research deliberately abstracts away from exposing specific contract values or segment-level percentages, preserving the analytical edge of the full report while demonstrating its relevance to near-term operational planning.
What the Full Study Delivers: A Practical Toolkit for Decision-Makers
While this overview signals the strategic scope of the research, the complete study provides an operational toolkit designed for cross-functional deployment. The report integrates historical performance analysis with forward-looking scenario modeling, enabling teams to test assumptions around capacity expansion, material sourcing, and aftermarket service growth. Decision-makers gain access to a structured examination of manufacturing technologies, including precision machining, titanium alloy processing, and composite integration, alongside an evaluation of how these capabilities influence cost structures, cycle times, and qualification pathways.
The study also maps supply chain architecture across raw material inputs, subcomponent fabrication, assembly, and repair ecosystems. By illuminating concentration risks, lead-time variability, and regional sourcing constraints, the report helps organizations design more resilient procurement strategies and evaluate vertical integration or supplier diversification options. In addition, the analysis includes an assessment of aftermarket dynamics, where replacement cycles, repairability thresholds, and airworthiness compliance converge to shape recurring revenue opportunities and service-level commitments.
Strategists will also find dedicated attention to product development implications. The report evaluates how performance requirements across aviation engines, industrial gas turbines, and turbocharger applications influence airfoil design, cooling architectures, and material selection, translating engineering priorities into commercially relevant investment guidance. Throughout, the research maintains a disciplined focus on actionable insight, ensuring that every analytical module connects to a decision context—whether that involves capacity planning, market entry, partnership evaluation, or risk mitigation.
To preserve the integrity of this intelligence and encourage rigorous strategic application, certain granular data points are reserved for the full report. This includes segment-specific revenue contributions, regional value splits, detailed company-level capability matrices, and proprietary scenario outputs. The intent is not to withhold value, but to ensure that the depth of analysis is experienced in its complete form, allowing executives and analysts to draw conclusions with full context rather than fragmented snapshots.
Compressor Blades Market
Strategic Imperatives for 2026 and Beyond
As organizations enter the 2026 planning cycle, the compressor blades market presents a landscape where disciplined intelligence can differentiate resilient strategies from reactive maneuvers. The convergence of steady top-line growth, concentrated competition, regulatory-driven replacement demand, and sustainment procurement creates a multi-layered environment that rewards analytical precision. Companies that align their product portfolios with durability mandates, fortify their supply chains against regional and material constraints, and calibrate their aftermarket capabilities to replacement cycles will be best positioned to capture value across the forecast window.
This research is designed to support that alignment. By combining macro trajectory analysis with segment-level architecture, competitive dynamics, regulatory context, and operational supply chain evaluation, the report delivers a comprehensive vantage point for strategy formulation. The 5.2 percent compound annual growth pathway to 2032 is not merely a headline figure; it is a signal of sustained demand intensity that must be interpreted through the lenses of application specificity, pressure-class differentiation, and geographic readiness.
For leadership teams seeking to translate market momentum into concrete plans, the full study offers the structured evidence base required to reduce uncertainty and accelerate decision velocity. We invite executives, strategy directors, and industry analysts to engage with the complete dataset, where the detailed segmentation splits, proprietary competitive assessments, and forward scenario tools are available in their entirety. In a market where precision, compliance, and timing determine outcomes, comprehensive intelligence is not an optional enhancement—it is the foundation of durable competitive strategy.
For detailed analysis of this topic, please visit the official page: Compressor Blades Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sodium Hypochlorite Generator Market to Hit USD 239M by 2032, 8.7% CAGR
By PW Consulting, 2026-09-16
Navigating the Sodium Hypochlorite Generator Market: Strategic Intelligence for 2026 Decision-Makers
As global industries accelerate the transition toward decentralized and sustainable water treatment solutions, the sodium hypochlorite generator market has emerged as a critical battleground for infrastructure investment, public health modernization, and operational resilience. For executives, municipal planners, and industrial operators navigating the 2026 landscape, understanding the trajectory of on-site chemical generation is no longer a technical exercise—it is a strategic imperative. PW Consulting’s latest market intelligence study dissects the forces shaping this sector, offering a rigorous, data-backed framework to align capital allocation, supply chain strategy, and regulatory compliance with the decade ahead.
The market has already demonstrated remarkable momentum over the past half-decade. Valued at approximately 90.6 million USD in 2020, it has consistently expanded through successive years, crossing the 116.5 million USD threshold by 2023 and climbing to an estimated 134.0 million USD in 2025. This historical trajectory underscores a structural shift rather than a cyclical fluctuation. Looking forward, our forecast model projects sustained expansion through the end of the decade, with revenue expected to approach 239.0 million USD by 2032. The implied compound annual growth rate of 8.7 percent reflects deepening adoption across water utilities, industrial facilities, and commercial operations that are actively seeking to mitigate supply chain vulnerabilities, reduce reliance on bulk chemical transport, and improve on-site disinfection reliability. These macro figures, while compelling, represent only the surface of a highly nuanced landscape. The true strategic advantage lies in understanding how regional deployment patterns, capacity tiering, application-specific demand, and shifting compliance requirements intersect to create asymmetric opportunities for early movers.
The 2026 Decision Matrix: Why Traditional Procurement Models Are Falling Short
For years, water disinfection procurement followed a familiar playbook: order bulk sodium hypochlorite, manage storage and handling risks, and absorb the volatility of chemical shipping and seasonal supply bottlenecks. The 2026 operating environment has rendered that model increasingly fragile. Infrastructure modernization initiatives are accelerating, and public and private operators alike are recognizing that on-site electrolysis systems offer a compelling alternative to centralized chemical logistics. The strategic calculus has shifted from simple cost-per-gallon comparisons to total lifecycle value, encompassing regulatory compliance, worker safety, environmental footprint, and resilience against transport disruptions.
Utilities and industrial facilities are now evaluating generator deployments through a multi-dimensional lens. Municipal operators must weigh NSF/ANSI/CAN 61 certification pathways for drinking water applications against evolving state-level procurement standards, while industrial managers must align system capacities with fluctuating production schedules and brine feedstock availability. Meanwhile, commercial and recreational operators are exploring compact generation units that can deliver consistent disinfection without the logistical overhead of chemical delivery. The procurement cycle has lengthened, the technical evaluation criteria have multiplied, and the competitive field has matured. Organizations that approach this transition with fragmented vendor comparisons or outdated cost models risk overcommitting to suboptimal configurations. The market demands a structured, forward-looking evaluation framework—and that is precisely what our research delivers.
Decoding the Competitive Arena
The sodium hypochlorite generator market is characterized by a concentrated yet strategically active competitive landscape. CR3 firms account for approximately 35 percent of market revenue, while the top five players collectively command around 45 percent. This concentration reflects the technological barriers to entry, the capital intensity of electrolytic system development, and the lengthy qualification cycles required to secure municipal and industrial contracts. Yet the market remains dynamic, with established players continuously refining system architectures, expanding application portfolios, and responding to emerging compliance mandates.
Among the most prominent participants, De Nora, headquartered in Milan, Italy, has built a recognized portfolio around its ClorTec® on-site low-strength sodium hypochlorite generators, alongside the CECHLO-MS high-strength systems that leverage electrolytic brine electrolysis for demanding disinfection environments. The company’s dual focus on low-strength and high-strength architectures positions it to serve both routine municipal water treatment and specialized industrial applications where concentration precision matters.
Xylem Inc., based in Chicago, Illinois, has established a strong presence through its OSEC® branded on-site hypochlorite generation systems, including the B-Plus, B-Pak, and L series. These platforms are engineered for municipal, aquatics, and industrial water disinfection, and their electrolytic process design aligns with utilities seeking to transition away from bulk chemical handling. Xylem’s integration of generation technology within broader water infrastructure offerings gives it a distinctive value proposition for operators pursuing end-to-end system optimization.
Sodium Hypochlorite Generator Market
Ecolab Inc., headquartered in St. Paul, Minnesota, brings a different dimension to the market through its eChlorine® electrolytic sodium hypochlorite generation systems. Designed for on-site production at the point of use, these systems have found particular traction in healthcare and hospitality environments where localized disinfection control, safety, and operational flexibility are paramount. Ecolab’s service-oriented model and cross-sector expertise allow it to address compliance and hygiene requirements that extend beyond traditional water treatment boundaries.
Electrolytic Technologies, operating in the United States, rounds out the competitive core with its Klorigen™ systems, which generate high-strength sodium hypochlorite in the 10 to 15 percent range alongside chlorine gas for municipal water and wastewater disinfection as well as industrial applications. This dual-output capability reflects a differentiated engineering approach that appeals to facilities seeking integrated disinfection chemistry rather than isolated hypochlorite production.
The competitive field is not static. Recent procurement activity and industry engagement signal where demand is crystallizing and where regulatory attention is intensifying. In March 2026, the City of Westminster issued a request for proposals for the purchase and delivery of two on-site sodium hypochlorite generation systems, illustrating how mid-sized municipal operators are moving from evaluation to execution. In November 2025, the City of Tampa’s Water Department completed construction of a new on-site sodium hypochlorite generation facility to produce liquid bleach on-site for disinfection, underscoring the growing momentum behind utility-scale deployments. Meanwhile, the Chlorine Institute scheduled its 2026 Annual Meeting with a focused agenda on sodium hypochlorite manufacturers and on-site chemical generator compliance, signaling that industry standardization and regulatory alignment will remain central themes throughout the forecast period.
Sodium Hypochlorite Market
Regulatory Realities and Infrastructure Tailwinds
No strategic assessment of this market can be separated from the regulatory and infrastructure context that shapes procurement decisions. On-site generation is not merely a technology substitution; it is an operational model change that intersects with drinking water certification, environmental verification, and standards development. The NSF/ANSI/CAN 61 certification framework applies to on-site generated sodium hypochlorite systems used in drinking water treatment, and compliance with these requirements has become a baseline expectation for municipal procurement teams evaluating system reliability and public health protection.
Parallel to certification requirements, the EPA Environmental Technology Verification program has confirmed the performance of on-site hypochlorite generation systems for primary and residual disinfection, reinforcing the technical credibility of electrolytic approaches in environments where consistent disinfection efficacy must be demonstrated. These verification pathways are increasingly referenced in procurement documentation and technical evaluation scores, making them a practical consideration rather than an abstract regulatory footnote.
Beyond drinking water, evolving standards and compliance expectations are shaping adjacent markets. The EN 18087:2026 standard sets requirements for in-situ chlorine dioxide generation from sodium chlorite, reflecting broader momentum toward on-site chemical generation and stricter controls over disinfection chemistry handling. While this standard addresses a different chemical pathway, it illustrates the regulatory trajectory: authorities are formalizing performance, safety, and operational expectations for decentralized generation systems, and manufacturers able to align their architectures with emerging standards will gain a distinct advantage in qualification processes.
Infrastructure dynamics further reinforce demand. Utility infrastructure upgrades are driving demand for on-site generators as operators seek to replace bulk chemical deliveries with more resilient, locally controlled production. This trend is reinforced by the practical realities of brine electrolysis systems, which use diluted salt solution as the primary electrolyte feedstock. The relative availability and logistical simplicity of salt-based feedstocks, combined with the reduction in hazardous chemical transport, make on-site generation an increasingly attractive option for facilities reevaluating their supply chains. These dynamics do not operate in isolation; they interact with regional procurement cycles, utility capital planning horizons, and industrial production requirements, creating a complex but navigable landscape for organizations that have access to granular, forward-looking intelligence.
Inside the PW Consulting Research Framework
Our study is structured to convert market complexity into actionable decision support. Rather than presenting abstract trends, the report maps the operational, financial, and competitive parameters that executives and technical leaders must evaluate before committing to on-site generation investments. The analysis covers the full forecast window from 2026 through 2032, anchored in a verified historical base that traces market development from 2020 onward. This temporal span allows readers to distinguish between short-term procurement cycles and longer structural shifts, ensuring that investment theses are calibrated to realistic adoption timelines.
The report examines capacity segmentation patterns, differentiating between lower-capacity systems designed for localized or intermittent disinfection needs and higher-capacity architectures suited to continuous utility-scale or large industrial operations. These capacity tiers are not merely technical specifications; they determine footprint requirements, brine handling logistics, maintenance cadences, and the economics of scale that vary significantly across deployment contexts. Our analysis unpacks how these capacity splits influence procurement strategy, vendor selection criteria, and total cost of ownership across different operational profiles.
Application-level demand is similarly dissected. Municipal water and wastewater disinfection remains a foundational driver, but the market also encompasses industrial process disinfection, food industry hygiene applications, and swimming pool and recreational water treatment. Each application segment carries distinct compliance expectations, 화학 concentration requirements, and operational rhythms. By mapping these application dynamics without oversimplifying them, the report equips decision-makers to identify where their organization’s operational profile aligns with the strongest demand signals and where cross-segment learning can accelerate evaluation timelines.
Regional deployment patterns are analyzed with attention to market maturity, procurement pacing, and infrastructure readiness. Rather than reducing regional variation to static share percentages, the research contextualizes how North American, European, Asia Pacific, Latin American, and Middle East and Africa markets differ in terms of utility modernization cadence, regulatory emphasis, and the pace at which bulk chemical delivery models are being supplemented or replaced by on-site production. This regional framing is critical because the same generator architecture may present very different risk-return profiles depending on the local procurement environment and infrastructure context.
Competitive positioning is evaluated through a combination of technology architecture, application coverage, geographic reach, and recent procurement momentum. The report does not stop at company descriptions; it examines how incumbent players are leveraging their system portfolios, service networks, and compliance credentials to shape procurement outcomes, and where gaps in application coverage or regional presence may create openings for new entrants or strategic partnerships. Recent project completions, RFP activity, and industry meetings are integrated into this analysis to connect high-level competitive positioning with real-world procurement behavior.
How to Translate This Intelligence Into 2026 Action
The strategic value of this research lies in its applicability to concrete decision points. For capital planners, the forecast trajectory and segmentation framework support scenario-based budgeting, helping organizations align procurement timing with capacity availability and financing cycles. For technical evaluation teams, the report’s treatment of certification pathways, brine electrolysis feedstock considerations, and performance verification provides a structured basis for vendor qualification and specification development. For commercial and corporate strategy leaders, the competitive concentration data, company profiles, and recent procurement signals offer a lens for assessing partnership opportunities, differentiation potential, and market entry timing.
Organizations that treat on-site sodium hypochlorite generation as a commodity procurement decision risk underestimating the operational and compliance nuances that determine long-term success. Those that approach it as a strategic infrastructure investment, grounded in robust market intelligence, are better positioned to select the right system architecture, align procurement with regional readiness, and anticipate the regulatory developments that will shape qualification standards in the years ahead.
The complete PW Consulting market research study delivers the detailed segmentation data, regional deployment context, application-level demand mapping, and competitive intelligence required to build a decisive 2026 strategy. We invite executives, procurement leaders, and technical decision-makers to access the full report, where the macro trajectory outlined here is expanded into the granular, actionable intelligence necessary to navigate this market with confidence.
For detailed analysis of this topic, please visit the official page: Sodium Hypochlorite Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: UPVC Window And Door Market Hits $28.4B In 2025, Projected 6.4% CAGR To $43.61B By 2032
By PW Consulting, 2026-09-16
Strategic Horizons: Navigating the UPVC Window and Door Market in 2026 and Beyond
Executive Overview
The global construction and renovation landscape is undergoing a significant transformation, driven by stringent energy efficiency regulations, urbanization trends, and a growing emphasis on sustainable building materials. Within this evolving ecosystem, Unplasticized Polyvinyl Chloride (UPVC) windows and doors have emerged as a cornerstone solution for manufacturers, contractors, and homeowners alike. Our latest market intelligence report offers a comprehensive deep dive into this sector, providing the strategic clarity necessary for informed decision-making throughout the 2026-2032 forecast period.
This analysis serves as a strategic preview of our full market research publication. While we highlight the macro-economic trajectories and competitive forces shaping the industry, the complete dataset—including granular segmentation splits, precise regional revenue shares, and detailed financial modeling—remains an exclusive resource for our clients. Understanding the broad contours of the market is the first step; mastering the specific data points is where competitive advantage is forged.
Market Trajectory and Macro Economic Indicators
The UPVC window and door market has demonstrated robust resilience and growth over the past five years. Historical data from 2020 through 2025 indicates a consistent upward trend, reflecting the material's increasing adoption in both replacement markets and new construction projects. The market valuation, expressed in USD billions, has progressed steadily, signaling strong underlying demand fundamentals.
Looking ahead, the forecast period from 2026 to 2032 projects a continued expansion phase. Industry analysts anticipate a Compound Annual Growth Rate (CAGR) that underscores the sector's vitality. This growth is not merely linear but is influenced by shifting demographic patterns, infrastructure spending, and regulatory pushes toward energy conservation. The trajectory suggests that by the early 2030s, the market will reach significantly higher valuation thresholds, presenting substantial opportunities for stakeholders who position themselves correctly during the current cycle.
Key macro indicators suggest that the industry is moving past a phase of volatility into a period of structured growth. However, realizing the full potential of this growth requires more than just observing top-line numbers. It demands an understanding of how different product types, application sectors, and geographic regions contribute to the aggregate figure. Our full report dissects these layers, providing the specificity needed to allocate capital efficiently and identify high-yield segments.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a mix of established global players and agile regional specialists. Concentration metrics indicate a moderately consolidated environment where top-tier manufacturers hold significant influence. The CR3 and CR5 ratios suggest that while a few key players dominate the landscape, there remains ample room for differentiation through technology, design, and regional presence.
UPVC Window and Door Market
Leading manufacturers are actively maneuvering to secure their positions through capacity expansion, strategic partnerships, and innovation in profile systems. Major entities such as VEKA Group, Rehau, aluplast, and Deceuninck continue to set benchmarks in PVC profile systems and energy-efficient solutions. These companies are not merely competing on price but are engaging in sophisticated value-chain integrations. For instance, recent collaborations have focused on sustainability initiatives, such as partnerships aimed at promoting green construction practices and enhancing the lifecycle efficiency of window systems.
Regional dynamics also play a crucial role in competitive strategy. In North America, companies like United Window & Door are expanding production capacities to meet local demand, reducing reliance on imported profiles and strengthening supply chain resilience. Simultaneously, in Asia Pacific, manufacturers like Fenesta and LG Hausys are leveraging local manufacturing advantages to cater to booming residential and commercial sectors. TWR Group in the UK and other fabricators are also adapting their offerings to meet specific trade and commercial requirements.
Recent developments highlight the pace of change. Facility expansions involving significant capital investment have been announced to accommodate growing order books. Product launches introducing new systems, such as tilt-turn solutions and triple-track patio doors, indicate a focus on diversifying portfolios to capture niche demands. Furthermore, partnerships regarding finishes and materials suggest an industry-wide push toward aesthetic customization and performance enhancement. Understanding the specific timing and impact of these moves is critical for benchmarking one's own strategy against the market leaders.
Industry Dynamics: Cost Structures and Regulatory Pressures
One of the most critical factors influencing margin stability and pricing strategies is the cost of raw materials. UPVC profile costs account for a substantial portion of manufacturing expenses, making resin price fluctuations a key risk variable. Recent market intelligence indicates divergent trends across major regions. In Europe, PVC resin prices have seen upward pressure, impacting cost structures for profile manufacturers. Conversely, in markets like India, price adjustments have followed global supply chain realignments, presenting a different cost environment. These disparities create complex challenges for multinational strategists who must navigate varying input costs while maintaining competitive pricing.
Regulatory frameworks are equally influential. Government initiatives aimed at affordable housing and energy efficiency are acting as primary demand drivers. In the European Union, plans emphasizing renovation-first approaches and stringent energy efficiency standards are accelerating the replacement of old fenestration systems with high-performance UPVC alternatives. Industry associations have welcomed these developments, recognizing the potential for increased market volume. However, regulatory shifts also bring compliance complexities. For example, changes in logistics schemes regarding PVC window profile transport pallets require operational adjustments.
In emerging markets, protectionist measures are gaining traction. Industry bodies in regions like India have appealed for import controls on uPVC profiles to safeguard domestic manufacturing interests. Such policy developments can alter competitive dynamics overnight, favoring local producers while potentially restricting supply options for assembled goods. Monitoring these regulatory signals is essential for risk mitigation. Our detailed report provides a nuanced analysis of how these dynamics vary across sectors and regions, offering actionable insights on navigating the regulatory maze.
Segmentation and Application Opportunities
The market is multifaceted, segmented by window and door types, applications, and geography. While the aggregate market size provides a high-level view, the real strategic value lies in understanding the performance of specific segments. Product diversity ranges from casement and sliding systems to tilt and turn configurations and French doors. Each type serves different functional and aesthetic needs, commanding different market shares and growth rates. For example, energy-efficient tilt-turn systems are gaining traction in markets with strict thermal performance codes, while sliding systems remain popular in space-constrained residential settings.
Application-wise, the residential sector typically constitutes the largest share of demand, driven by housing starts and renovation activities. Commercial applications follow, fueled by office complexes, hospitality projects, and institutional buildings. Industrial applications, while smaller in volume, offer specialized requirements regarding durability and security. The interplay between these segments determines the overall health of the market. A slowdown in residential construction might be offset by a surge in commercial retrofitting, depending on economic conditions.
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique challenges and opportunities. Developed markets may focus on replacement cycles and energy upgrades, while developing markets might see higher volume from new infrastructure projects. Our complete analysis breaks down these regional nuances without relying on broad generalizations, providing the specific intelligence needed to tailor go-to-market strategies.
Strategic Value for 2026 Decision Making
For executives and strategists, the ability to anticipate market shifts is paramount. The 2026 landscape offers both risks and rewards. On one hand, rising raw material costs and regulatory changes pose challenges to margin management and compliance. On the other hand, government incentives for energy efficiency and housing create clear demand pull. Navigating this environment requires more than intuition; it requires data-backed precision.
PVC Window Profile Market
Our market research report is designed to equip leaders with the tools necessary to make decisive moves. Whether it is evaluating potential mergers and acquisitions, planning capacity expansions, or refining product portfolios, the data provided serves as a foundational asset. The report goes beyond static numbers to offer context on how competitive moves, such as new facility openings or strategic partnerships, are reshaping the battlefield.
Furthermore, understanding the concentration of market power helps in assessing barriers to entry and the viability of niche strategies. Companies can identify gaps where innovation can disrupt incumbent players or where consolidation might be beneficial. The insights into recent developments—such as specific product launches and investment rounds—provide a real-time view of where competitors are placing their bets. This intelligence allows organizations to align their own roadmaps with emerging trends rather than reacting to them after the fact.
The forecast period through 2032 offers a long-term horizon for planning. Stakeholders can model various scenarios based on the projected CAGR and market valuation trends. This long-view perspective is crucial for capital-intensive decisions in manufacturing and distribution. By integrating macro trends with segment-specific data, organizations can build robust strategies that are resilient to short-term volatility while capitalizing on long-term growth vectors.
Conclusion
The UPVC window and door market stands at a pivotal juncture. The convergence of economic recovery, regulatory support for energy efficiency, and technological innovation in profile systems creates a fertile ground for growth. However, realizing this potential requires a sophisticated understanding of the market's inner workings.
This article has provided a high-level overview of the market's trajectory, competitive forces, and dynamic pressures. To access the complete landscape of intelligence discussed herein—including precise segmentation data, detailed regional breakdowns, and exhaustive company profiles—we invite you to explore our full market research report. The detailed intelligence contained within is designed to transform uncertainty into strategic clarity, empowering your organization to lead rather than follow in the years ahead.
For detailed analysis of this topic, please visit the official page: UPVC Window and Door Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Adiabatic Coolers Market to Hit $872M by 2032, 7% CAGR (2026-2032)
By PW Consulting, 2026-09-16
Navigating the Adiabatic Coolers Market: Strategic Intelligence for 2026 and Beyond
The global industrial and commercial cooling landscape is undergoing a fundamental shift. As energy costs rise and environmental regulations tighten, organizations are increasingly turning to adiabatic cooling technologies to balance thermal management requirements with sustainability mandates. PW Consulting's latest market research on the Adiabatic Coolers Market provides a comprehensive strategic roadmap for decision-makers navigating this evolving sector. This analysis synthesizes historical performance data, forward-looking projections, and competitive dynamics to equip stakeholders with actionable intelligence for the 2026-2032 forecast period.
Understanding the trajectory of this market requires more than surface-level observations. The transition from traditional evaporative systems to adiabatic solutions represents a structural change in how industries approach heat rejection, water conservation, and energy efficiency. Our research delves into the underlying drivers, constraints, and opportunities that will define competitive positioning over the next several years.
Market Trajectory and Growth Dynamics
The adiabatic coolers market has demonstrated consistent expansion over the past half-decade, reflecting broader trends in industrial automation, data center proliferation, and commercial building optimization. Historical analysis from 2020 through 2025 reveals a market that has matured significantly, with revenue scaling from approximately 385 million USD to 542 million USD. This growth trajectory underscores the accelerating adoption of water-saving cooling technologies across multiple sectors.
Looking forward, our forecasts indicate sustained momentum through 2032. The market is projected to reach 595.48 million USD in 2026, continuing its upward path to approximately 872.0 million USD by the end of the forecast horizon. This progression reflects a compound annual growth rate of 7.0 percent, signaling robust demand underpinned by technological advancements and regulatory tailwinds. However, growth is not uniform across all segments or regions, and strategic allocation of resources requires nuanced understanding of where value is being created.
Several macroeconomic and operational factors are converging to accelerate this expansion:
- Rising energy prices are driving facility managers to prioritize systems that reduce electrical consumption while maintaining cooling capacity
- Water scarcity concerns in key industrial regions are making low-water-use cooling solutions increasingly attractive compared to conventional evaporative alternatives
- Environmental regulations, including California's Title 24 requirements for CO2 CDUs in supermarket systems effective 2026, are introducing compliance considerations that influence equipment selection and system design
- The Cooling Technology Institute's development of thermal performance certification programs for adiabatic fluid coolers, anticipated to launch under CTI Standard 201, is expected to enhance transparency and standardization in performance claims
Competitive Landscape and Key Players
The adiabatic coolers market exhibits notable concentration, with the top three firms capturing approximately 65 percent of total revenue and the top five accounting for roughly 75 percent. This consolidated structure suggests mature competitive dynamics where scale, technological differentiation, and regional presence play critical roles in market share retention. Our research provides detailed profiling of the companies shaping this landscape, examining their product portfolios, strategic positioning, and recent developments.
In the United States, several established players continue to drive innovation in adiabatic cooling solutions. SPX Cooling Technologies, headquartered in Overland Park, Kansas, offers the Marley and Recold Adiabatic Series, which combines water-saving benefits with energy efficiency for commercial and industrial refrigeration applications. Baltimore Aircoil Company, based in Jessup, Maryland, has gained attention for its TrilliumSeries Adiabatic Cooler and hybrid systems designed for efficient cooling with reduced water and energy consumption. EVAPCO, also located in Baltimore, Maryland, has expanded its eco-Air Series with the Titan, recognized as the largest adiabatic cooler in its lineup, featuring pumpless recirculation and pre-cooling capabilities for process cooling applications.
European manufacturers are equally active in advancing adiabatic cooling technology. MITA Cooling Technologies, based in Italy, provides adiabatic dry coolers with pre-cooling systems tailored for industrial HVAC and energy-efficient operation across Europe and the Americas. Kelvion, headquartered in Germany, offers adiabatic condensers and dry coolers utilizing spray or pad systems capable of achieving 10°C air cooling. Torraval Cooling, from Spain, focuses on compact adiabatic coolers and subcooler series designed to deliver quick return on investment for refrigeration applications. Frigel, based in Florence, Italy, specializes in intelligent process cooling equipment, including adiabatic systems for plastics and broader industrial applications. GEA Group, located in Düsseldorf, Germany, provides process cooling systems with adiabatic solutions for food processing and industrial heat rejection.
Alfa Laval, headquartered in Lund, Sweden, rounds out the competitive field with its Abatigo Adiabatic Liquid Coolers, which incorporate patented pre-cooling sections suitable for data centers and industrial use. These companies represent the vanguard of adiabatic cooling innovation, and our report includes in-depth assessments of their strategic moves, product launches, and market activities.
Recent developments highlight the pace of innovation in this sector. EVAPCO released the Titan in September 2025 as the largest adiabatic cooler in its eco-Air Series, signaling continued investment in scaling capacity for demanding applications. Baltimore Aircoil Company demonstrated its TrilliumSeries Adiabatic Cooler at the 2025 AHR Expo, reinforcing its commitment to showcasing hybrid cooling solutions at major industry events. Meanwhile, the Cooling Technology Institute has been developing a thermal performance certification program for adiabatic fluid coolers, with anticipated launch in the first half of 2025 under CTI Standard 201, covering forced and induced draft adiabatic fluid coolers for water or aqueous glycol solutions. These milestones illustrate the dynamic nature of the market and the importance of staying informed about product evolution and standardization efforts.
Segmentation Insights and Application Trends
The adiabatic coolers market spans multiple technology types and application verticals, each with distinct growth drivers and adoption patterns. Our research segments the market by type, application, and region to provide a granular view of where demand is concentrated and how it is evolving.
Worldwide Adiabatic Demagnetization Refrigerators (ADR) Market
By technology type, the market includes dry air coolers and liquid coolers, both of which serve critical roles in industrial and commercial cooling architectures. Dry air coolers have gained prominence in applications where water conservation is a priority, while liquid coolers remain essential for processes requiring precise temperature control and high thermal capacity. The segmentation analysis reveals how these technologies are being deployed across different end-use scenarios and what factors influence procurement decisions.
In terms of application, industrial and commercial sectors represent the primary demand drivers. Industrial applications, encompassing process cooling, manufacturing heat rejection, and large-scale facility management, account for the dominant share of market revenue. Commercial applications, including data centers, commercial buildings, and retail refrigeration systems, are expanding as organizations seek to comply with energy codes and reduce operating expenses. The interplay between these application segments and regional deployment patterns provides valuable context for market entry strategies and product positioning.
Regional dynamics further shape the competitive environment. North America and Europe represent mature markets with established infrastructure and regulatory frameworks that favor energy-efficient cooling solutions. Asia Pacific, Latin America, and the Middle East and Africa present emerging opportunities where industrialization, data center growth, and climate conditions are driving demand for advanced cooling technologies. Our report examines these regional variations in detail, identifying where growth is accelerating and what barriers exist to adoption.
Strategic Value for 2026 Decision-Making
In an environment characterized by rapid technological change, regulatory uncertainty, and intensifying competition, access to reliable market intelligence is not a luxury—it is a strategic necessity. PW Consulting's Adiabatic Coolers Market report is designed to support decision-makers across multiple functions, from product development and investment planning to competitive positioning and risk assessment.
For executives evaluating market entry or expansion opportunities, the report provides a foundational understanding of market size, growth trajectories, and segmentation dynamics. This macro-level perspective enables informed resource allocation and helps identify the most promising avenues for investment. For product managers and engineering teams, detailed technology assessments and competitive benchmarking offer insights into feature differentiation, performance standards, and emerging customer requirements. Procurement and supply chain leaders can leverage the analysis to anticipate price trends, evaluate supplier landscapes, and mitigate risks associated with raw material costs and component availability.
The report also addresses the regulatory and compliance dimensions that are increasingly shaping purchasing decisions. With standards such as CTI Standard 201 gaining prominence and regional requirements like California's Title 24 imposing new constraints on adiabatic gas coolers in supermarket systems, organizations must navigate a complex compliance landscape. Our research synthesizes these regulatory developments and their implications for product design, system integration, and market access.
Key areas where this research delivers strategic value include:
- Identifying high-growth segments and regions where competitive intensity is still developing, enabling first-mover advantages
- Understanding the technological differentiators that matter most to customers, from pre-cooling capabilities to material specifications such as 304L stainless steel tubing and aluminum fins
- Assessing the impact of water-use considerations on equipment selection, as adiabatic models use water only when ambient conditions and load require it, offering flexibility in operating modes for utility savings
- Evaluating the competitive positioning of key players based on their product portfolios, geographic reach, and recent strategic initiatives
- Anticipating the effects of certification programs and regulatory changes on market dynamics and compliance costs
Why This Research Matters Now
The adiabatic coolers market is at an inflection point. Technological improvements, regulatory shifts, and evolving customer expectations are converging to create both opportunities and challenges for market participants. Organizations that proactively understand these dynamics will be better positioned to capitalize on growth, manage risks, and build sustainable competitive advantages.
Adiabatic Coolers Market
Our report goes beyond high-level summaries to deliver the depth and granularity required for confident decision-making. It integrates historical data, current market conditions, and forward-looking projections into a cohesive analytical framework. By examining the strategies of leading companies, the evolution of technology types, and the forces shaping regional demand, the research provides a comprehensive view of the market ecosystem.
Stakeholders who rely on fragmented information or outdated assumptions risk misallocating resources, missing emerging opportunities, or underestimating competitive threats. PW Consulting's market research equips organizations with the intelligence needed to make informed choices about product development, market expansion, partnership strategies, and investment priorities.
Accessing the Full Intelligence Package
This article provides a strategic overview of the adiabatic coolers market and highlights the core themes explored in our comprehensive research report. However, the full depth of our analysis—including detailed segmentation data, regional breakdowns, competitive assessments, and methodological rigor—requires access to the complete publication. The nuanced insights that drive strategic decisions are embedded throughout the report, and we encourage stakeholders to obtain the full document to ensure they have the most complete picture of market dynamics.
As the adiabatic cooling sector continues to evolve, staying ahead of trends and understanding the competitive landscape will be essential for sustained success. PW Consulting is committed to delivering market intelligence that meets the highest standards of accuracy, relevance, and actionable value. For organizations seeking to navigate the complexities of the 2026-2032 period with confidence, our adiabatic coolers market research offers the foundation for informed, strategic action.
For detailed analysis of this topic, please visit the official page: Adiabatic Coolers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Precision Industries Forecasts Cold Heading Machine Market to Hit $4.69B by 2032 With 4.01% CAGR
By PW Consulting, 2026-09-16
Navigating the Cold Heading Machine Market: Strategic Intelligence for 2026 and Beyond
The cold heading machine market stands at a critical inflection point. As manufacturing precision demands escalate and fastener production scales to meet complex industrial needs, decision-makers require more than surface-level forecasts. They need actionable intelligence that connects machine specifications, regional supply chains, application-specific demand drivers, and competitive positioning into a coherent strategic narrative. This introduction frames the Cold Heading Machine Market research report by PW Consulting, a comprehensive study designed to equip C-suite executives, procurement leaders, and strategic planners with the clarity needed for 2026 decision-making and multi-year investment planning.
Why This Research Matters Now
Cold heading remains one of the most efficient manufacturing processes for producing high-volume fasteners, pins, and precision components. The ability to form metal at or near room temperature—without the thermal degradation risks of hot working—offers distinct advantages in dimensional accuracy, material grain structure, and production economics. Yet the machines that execute these processes are evolving rapidly. Multi-die configurations, advanced automation integration, and tighter tolerance capabilities are reshaping procurement criteria across automotive, electronics, industrial equipment, and aerospace supply chains.
Our study delivers a rigorous, data-grounded assessment of the market across a structured historical window and a forward-looking forecast horizon. The analysis spans from 2020 through 2025, capturing the market's recent trajectory, and extends through 2032 to illuminate long-term demand pathways. For 2026 strategists, this temporal range is invaluable: it isolates the post-2025 recovery signals, quantifies the direction and pace of growth, and exposes the structural shifts that will define competitive advantage in the years ahead.
The market measured in this report is expressed in Million USD. From a 2025 base year assessment of 2,923.01 Million USD, the forecast period projects a market that advances to approximately 3,709.16 Million USD in 2026, climbs steadily through the late 2020s, and reaches 4,685.24 Million USD by 2032. The overall compound annual growth rate across the 2026–2032 forecast window registers at 4.01 percent. These macro figures anchor the study, but they are only the starting point. The real strategic value lies in how this growth decomposes across machine types, end-use applications, and geographic corridors—and in the operational insights the report surfaces beneath the headline numbers.
Report Architecture: What Decision-Makers Will Find Inside
This study is structured for immediate practical use. Rather than presenting a static collection of charts, the research is organized around the strategic questions that procurement directors, plant managers, and market entry strategists face when evaluating cold heading equipment investments.
Market Sizing and Historical Trajectory
The report reconstructs the market's behavior from 2020 through 2025, a period marked by shifting production priorities, supply chain adjustments, and variability in capital expenditure cycles. By tracing the path from 3,558.00 Million USD in 2020 through to the 2025 base year assessment, the study identifies the inflection points that shaped buyer behavior and supplier responses. Readers will gain a clear picture of how demand fluctuated, where resilience emerged, and which segments absorbed capacity during softer periods.
Forecast Framework and Growth Drivers
Beyond 2025, the analysis projects a market that regains momentum and expands at a measured, sustained pace. The forecast portion of the report links this trajectory to concrete demand catalysts: fastener volume requirements tied to vehicle electrification and lightweighting, electronics miniaturization driving precision component needs, industrial equipment refurbishments and expansions, and aerospace program ramp-ups. Each driver is mapped to the machine categories and regional demand pools it influences, giving strategists a framework for scenario planning rather than a single-point prediction.
For those evaluating capacity additions, replacement cycles, or technology upgrades, the forecast window through 2032 provides a multi-year canvas. The progression from the 2026 baseline toward the 2032 endpoint reveals where growth concentrates, which years carry the steepest incremental demand, and how the market's composition is expected to evolve. This temporal granularity is essential for aligning procurement lead times, capital budgeting cycles, and production planning with market realities.
Segmentation for Targeted Strategy
One of the study's core strengths is its segmentation architecture. Market demand is analyzed across machine type, end-use application, and geographic region, enabling readers to isolate the pockets of opportunity most relevant to their strategic posture. Whether a company focuses on single-die precision lines or multi-die high-throughput systems, whether its customer base skews toward automotive components, electronics, industrial equipment, or aerospace, and whether it targets mature production hubs or emerging manufacturing corridors, the segmentation layer provides the lens needed to prioritize resources and tailor value propositions.
Importantly, the report avoids the reductive approach of presenting isolated regional or application shares without context. Instead, it situates each segment within the broader demand ecosystem, explaining how subsegments interact, where substitution dynamics occur, and which structural factors will accelerate or temper growth in specific pockets of the market over the forecast period.
Competitive Intelligence and Firm-Level Insights
Market growth is meaningless without understanding who captures it. The competitive landscape section profiles the leading entities shaping the cold heading machine sector, offering readers a grounded view of supplier capabilities, geographic footprints, and market positioning. The study examines established manufacturers and specialized suppliers that collectively define the industry's current architecture, including National Machinery LLC, headquartered in Tiffin, Ohio, recognized globally for advanced cold and warm forming machinery, process technology, and customer support for precision cold forming solutions; Hariton Machinery Company, Inc., based in New York, which supplies new and used cold header machines, multi-station headers, and related cold heading equipment; SACMA Group of Limbiate, Italy, known for cold heading machines including the KSP series headers for fastener production; Chun Yu Group, operating through Chun Zu Machinery Industry Co. Ltd in China, producing cold heading machines and forming equipment for the fastener industry; GFM GmbH Steyr of Steyr, Austria, supplying high-performance cold heading machines and forming systems; Hatebur Umformmaschinen AG of Grenchen, Switzerland, a manufacturer of precision cold heading and forming machines; Asahi Sunac Corporation of Japan, providing cold heading machine solutions for fastener and precision parts production; Wrentham Tool Group LLC of Massachusetts, specializing in cold heading tools and equipment for machine manufacturers; Sakamura USA Inc., a U.S.-based distributor and provider of Sakamura cold heading machines; and HUBEI TRI-RING METALFORMING EQUIPMENT CO. of China, manufacturing metalforming and cold heading equipment.
Beyond firm profiles, the report examines recent market activity that signals evolving competitive intensity. For example, Krevere's participation in the International Fastener Show IFS 2026 in Shanghai, where it showcased cold heading machines including the KRBF-64S model, illustrates the ongoing product introductions and trade presence that keep the competitive environment in motion. Such developments matter for procurement teams tracking supplier innovation cycles and for strategists assessing which players are actively expanding their visibility in key regional venues.
Market Dynamics: Structural Forces Shaping the Landscape
Understanding where the market is going requires grasping the forces that constrain and accelerate it. The report disentangles these dynamics into several interconnected themes.
Cost Efficiency, Precision, and Process Evolution
Cold heading's enduring appeal rests on its ability to deliver high-volume output with tight tolerances and favorable material utilization. As downstream industries push for lighter components, higher strength-to-weight ratios, and greater consistency in fastener performance, machine builders have responded with designs that improve strike accuracy, reduce secondary operations, and integrate process monitoring. The study examines how these technological and process trends are translating into buyer preferences, what trade-offs exist between single-die and multi-die configurations in different production contexts, and where automation and tooling advancements are reshaping total cost of ownership calculations.
Cold Forging Machine Market
Regional Manufacturing Footprints and Demand Geography
The market does not grow uniformly across the globe. Production capacity, fastener consumption patterns, and industrial policy environments differ markedly by region, and these differences shape both demand and competitive entry strategies. The research maps how demand pools align with regional manufacturing strength and where export-oriented equipment flows intersect with local production needs. For organizations evaluating market entry, supplier localization, or regional capacity deployment, this geographic lens is essential for avoiding misallocated investment and for identifying where near-term volume and long-term structural demand diverge.
Cold Heading Machine Market
The study covers the full regional spectrum, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, situating each within the broader demand architecture rather than treating them as isolated silos. Readers will understand not just which regions carry significant volume, but how regional dynamics—industrial base maturity, trade flows, and application mix—interact with machine type and end-use segmentation to create distinct strategic environments.
Standards, Safety, and Compliance as Operating Parameters
Machinery procurement and deployment do not occur in a regulatory vacuum. The report integrates the standards and safety frameworks that shape equipment specification, installation, and operation. ISO 4954-1:2024 specifies requirements for non-alloy and alloy steels intended for cold heading and cold extruding delivered as wire rods and wire, establishing a material-grade reference that ties directly to cold heading process performance. EN 10263:2017 serves as the standard reference for cold heading steel wire grades, including boron-alloyed and alloyed steels, further anchoring material selection to machine capability and output quality. On the safety side, the U.S. Occupational Safety and Health Administration enforces ANSI B11.7-2020 safety requirements for cold headers and cold formers, a framework that remains active and relevant for operators and equipment purchasers alike.
These standards are not peripheral details; they influence machine design expectations, supplier qualification, operator training, and the risk profile of capacity investments. By incorporating this compliance layer, the report equips readers to assess supplier offerings and project requirements with a fuller understanding of the operational environment in which cold heading equipment must perform.
Competitive Concentration and Market Structure
The distribution of market share among leading participants provides a window into the industry's competitive architecture. The study notes that the top three firms collectively account for approximately twenty-five percent of market revenue, while the top five reach roughly thirty percent. This concentration profile suggests a market where scale advantages, technological differentiation, and regional reach matter, but where meaningful headcount of specialized suppliers also persists. For strategists, this balance between concentration and fragmentation has implications for supplier negotiation leverage, partnership selection, and the feasibility of displacing incumbents in targeted segments.
The report examines how this structure is likely to evolve as growth accelerates through the forecast period, where consolidation pressure may intensify, and which types of firms—broad-line manufacturers, application specialists, or regionally anchored suppliers—are best positioned to capture incremental share. Rather than offering a static snapshot, the analysis connects concentration data to the strategic behaviors that will shape competitive outcomes over time.
Translating Insights into 2026 Action
Strategic reports derive their value from how they inform decisions. This study is built with that principle at its core. Across procurement, capacity planning, competitive positioning, and market entry, the research provides a framework for converting market intelligence into concrete action.
For procurement teams, the segmentation and competitive analysis clarify which machine types align with specific application requirements and which suppliers offer credible capability in those niches. The standards and safety context supports more rigorous equipment qualification, reducing the risk of downstream fit or compliance issues. For capacity planners and plant executives, the historical trajectory and forecast pathway inform timing decisions—when to accelerate replacement cycles, where to concentrate automation investments, and how to sequence expansions against anticipated demand increments. For market strategists evaluating expansion or new product lines, the regional and application lenses identify where demand momentum is strongest and where competitive barriers are most navigable.
Crucially, the report's structure is designed to support scenario thinking rather than point forecasts alone. By revealing how demand drivers, machine categories, and regional dynamics interact, it enables decision-makers to test assumptions, stress-test investment plans, and align internal timelines with external market rhythms.
What the Full Study Delivers
This introduction previews the analytical rigor and strategic relevance of the complete Cold Heading Machine Market research. The full report extends this foundation with detailed segmentation analytics, deeper competitive profiling, granular demand-driver mapping, standards and safety integration, and forward-looking scenario considerations that together form a comprehensive decision-support toolkit. It is written for executives who need to move beyond headline market figures and into the operational and strategic detail that determines whether a 2026 investment, procurement decision, or market move lands effectively.
The complete analysis, including the full segmentation breakdowns, firm-level evaluations, regional demand contexts, and the nuanced interpretation of growth drivers across the 2026–2032 horizon, is available through the full report. Readers seeking the precise figures, segment-level decompositions, and the complete competitive landscape assessment are encouraged to access the source study to obtain the complete intelligence package.
In a market where precision, timing, and supplier selection carry outsized consequences, the difference between reactive planning and strategic advantage comes down to the quality of the intelligence underpinning decisions. This research is designed to deliver exactly that—grounded in data, attentive to dynamics, and oriented toward the actions that matter in 2026 and the years that follow.
For detailed analysis of this topic, please visit the official page: Cold Heading Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


