



Category: market research
PW Consulting Report Projects Worldwide Shut-off Valves Market to Reach 51628.75 Million USD by 2032 with 4.6 CAGR
By PW Consulting, 2026-09-02
Strategic Intelligence for the Next Decade: Inside the Worldwide Shut-off Valves Market Outlook 2026–2032
In an era defined by supply chain volatility, evolving regulatory standards, and the relentless push toward energy transition, industrial infrastructure decisions made in 2026 will echo through balance sheets well into the 2030s. Shut-off valves remain the silent workhorses of global fluid control, yet their strategic importance has never been higher. From cryogenic LNG isolation to high-pressure chemical processing and resilient municipal water networks, the ability to reliably start, stop, and regulate flow directly impacts operational safety, capital efficiency, and environmental compliance. PW Consulting’s newly released Worldwide Shut-off Valves Market research delivers a meticulously structured intelligence framework designed specifically for executives, procurement leaders, and strategy planners who must navigate this complex landscape with precision.
Worldwide Shut-off Valves Market
This report is not a retrospective spreadsheet exercise. It is a forward-looking strategic compass, calibrated to the 2026–2032 forecast period, built on historical performance data spanning 2020–2025, and anchored in the operational realities that will shape procurement, capacity planning, and competitive positioning over the next seven years. Below, we outline the analytical architecture, the macro-economic trajectory, the competitive forces at play, and the critical industry dynamics that executives must internalize before finalizing their 2026 investment and sourcing roadmaps.
Worldwide Shut-off Valves Market
A Market at an Inflection Point: Macro Trajectory and Strategic Implications
The global shut-off valves market has demonstrated steady, compounding growth over the past half-decade, expanding from approximately $30.1 billion in 2020 to an estimated $37.7 billion in 2025. This trajectory reflects more than cyclical recovery; it signals structural demand driven by aging infrastructure replacement, accelerated LNG export capacity build-out, and renewed investment in water security and industrial automation. Looking ahead, the market is projected to reach approximately $38.9 billion in 2026, climbing steadily toward $51.6 billion by 2032, translating to a compound annual growth rate of 4.6 percent across the forecast horizon.
Worldwide Shut-off Valves Market
For corporate strategists, a 4.6 percent CAGR in a mature industrial component category is highly meaningful. It indicates that growth will not come from a single booming sector but from a confluence of steady replacements, capacity expansions, and technological upgrades across multiple end-use verticals and geographies. The implication is clear: companies that treat shut-off valves as commoditized procurement items risk missing the margin and reliability advantages embedded in application-specific engineering, certification compliance, and lifecycle service integration. Conversely, organizations that align their valve sourcing and internal manufacturing strategies with the structural demand shifts outlined in this forecast will be better positioned to secure supply continuity, optimize total cost of ownership, and capture premium positioning in severe-service segments.
The historical data also reveals a market that has consistently absorbed macroeconomic shocks without losing its upward momentum. Supply chain friction, raw material price fluctuations, and regional demand recalibration have periodically altered short-term procurement timing, but the underlying secular drivers have remained intact. For 2026 planning, this suggests that volatility should be anticipated and priced into inventory strategies, contract structures, and supplier diversification plans rather than treated as an anomaly to be avoided.
Decoding the Report Architecture: What Executives Will Find Inside
PW Consulting’s Worldwide Shut-off Valves Market study is engineered to convert complex market signals into actionable executive intelligence. The report is structured to serve multiple decision-making functions simultaneously, from high-level portfolio planning to granular sourcing and competitive benchmarking. Readers will encounter a layered analytical framework that moves systematically from macro-market sizing to segment-level dynamics, competitive positioning, and forward-looking scenario considerations.
At the core of the publication is a comprehensive market sizing model that traces historical revenue performance from 2020 through the base year of 2025, then extends into a detailed seven-year forecast spanning 2026 to 2032. All figures are presented in USD million, enabling direct integration into corporate financial models, procurement budgets, and investment appraisal workflows. The forecast methodology accounts for historical growth elasticity, application-driven demand cycles, regional investment pacing, and the compounding effect of regulatory and technological catalysts.
Beyond the top-line numbers, the report delivers structured segmentation analyses that map revenue distribution across product types, application verticals, and geographic regions. These breakdowns are not presented as static tables but are contextualized within the operational logic of each segment: which valve architectures align with severe-service requirements, how end-use industries prioritize reliability versus cost, and why certain regions are experiencing accelerated infrastructure modernization. The segmentation discussion is deliberately designed to help buyers and manufacturers identify where demand concentration is forming, where substitution risks are emerging, and where specification upgrades are creating margin opportunities.
The report also integrates a competitive landscape evaluation that profiles leading global manufacturers, examines their product portfolios and brand architectures, and tracks recent strategic moves including product launches, certification milestones, trade show showcases, and major supply contracts. This competitive intelligence is paired with an analysis of market concentration, providing context on the degree of fragmentation versus consolidation and what that implies for pricing power, supply resilience, and partnership strategy.
Operational and technical buyers will find particular value in the section dedicated to market dynamics and external catalytic factors. Here, the analysis weaves together macro-economic indicators, regulatory updates, raw material trends, labor cost trajectories, and trade policy developments that are actively reshaping valve procurement and manufacturing economics. Rather than treating these factors as isolated news items, the report situates them within the broader cost structure, compliance pathway, and sourcing strategy that procurement leaders must navigate in 2026 and beyond.
The Competitive Arena: Leading Manufacturers and Recent Strategic Moves
The shut-off valve market is characterized by a mix of established multinational engineering groups, specialized valve manufacturers, and regional players with strong distribution and service networks. Market concentration sits at a moderate level, with the top three players collectively capturing approximately 18.45 percent of total revenue and the top five accounting for roughly 27.3 percent. This fragmentation indicates that while scale and global service capability provide clear advantages, there remains meaningful room for specialist manufacturers and regionally anchored suppliers to compete on application expertise, customization, lead-time reliability, and localized support.
Several global manufacturers dominate the upper tier of the competitive landscape, each leveraging distinct brand portfolios, engineering pedigrees, and sector-specific certifications to secure position in demanding end markets. Emerson Electric Co., headquartered in St. Louis, Missouri, maintains a strong presence through its Fisher and Vanessa valve brands, serving automated and manual shut-off applications across oil & gas, power generation, and chemical processing. Flowserve Corporation, based in Irving, Texas, competes aggressively in severe-service environments, offering Logix and Valtek valve platforms engineered for refining and petrochemical duty cycles. Schlumberger NV, now operating under the SLB identity and headquartered in Houston, Texas, supplies Cameron and Plexco shut-off valves tailored to upstream production and pipeline isolation requirements. Baker Hughes Company, also Houston-based, manufactures Velan and PMV valve lines optimized for LNG, power generation, and subsea service conditions. Crane Co., operating from Stamford, Connecticut, delivers Crane and Xomox shut-off valves designed for corrosive media and high-pressure industrial processes.
Additional competitive strength comes from specialized and regionally influential manufacturers. Pentair plc, headquartered in London, provides Anderson Greenwood and Crosby pressure relief and shut-off valve solutions for oil & gas and refining applications. Velan Inc., based in Montreal, Quebec, specializes in forged and cast shut-off valves for nuclear, fossil power, and petrochemical plant environments. KSB SE & Co. KGaA, located in Frankenthal, Germany, offers Sisam and Isorol valve platforms for water, wastewater, and broader industrial fluid control. Weir Group plc, from Glasgow, Scotland, provides Cavco and Isogate shut-off valves for mining slurry handling and power generation isolation. Metso Outotec, headquartered in Helsinki, Finland, supplies Neles valve solutions for pulp and paper, mining, and oil & gas automation applications. AVK Holding A/S, based in Galten, Denmark, manufactures gate and butterfly shut-off valves for water distribution and wastewater systems. Mueller Water Products, Inc., operating from Atlanta, Georgia, produces resilient wedge gate shut-off valves for municipal water and fire protection networks.
Recent Corporate Activity as a Window into 2026 Priorities
Recent corporate developments make the strategic priorities of these manufacturers highly visible. In October 2025, Emerson Electric Co. launched the ASCO Series 259 programmable solenoid shut-off valves, targeting enhanced safety performance in hydrogen applications, a clear signal of how the energy transition is reshaping product roadmaps and specification requirements. In September 2025, Flowserve Corporation showcased the Logix 3730MD actuator-integrated shut-off valves at ADIPEC 2025 in Abu Dhabi, emphasizing the growing convergence of valve hardware and intelligent actuation for severe-duty refining and petrochemical service. In June 2025, KSB SE & Co. KGaA received API 6D certification for new high-pressure shut-off valves designed for LNG pipelines, illustrating the certification-driven barrier to entry that is increasingly shaping competitive eligibility in cryogenic and high-pressure hydrocarbon transport. In April 2025, Velan Inc. secured a contract to supply 500 forged steel shut-off valves for a Canadian nuclear refurbishment project, highlighting the recurring demand uplift from fleet aging and long-lead nuclear infrastructure renewal. In March 2025, Neles, operating under Valmet, introduced the Neles Easyflow J4 series butterfly shut-off valves with improved torque performance, reflecting the ongoing push toward higher efficiency, reduced actuation load, and improved operability across industrial fluid control applications.
These developments are more than product announcements; they are indicators of where engineering investment, compliance attention, and end-user demand are converging. For procurement teams and strategy planners, tracking this cadence of innovation and certification activity is essential to anticipating specification changes, avoiding obsolescence risk, and aligning sourcing strategies with manufacturers that are actively investing in the service conditions most relevant to their portfolios.
Forces Reshaping Demand, Cost, and Compliance in 2026
Market growth does not occur in a vacuum. The 2026–2032 forecast period is being shaped by a set of interacting dynamics that influence everything from material costs and labor availability to regulatory compliance and regional trade exposure. Executives who internalize these forces will be better equipped to structure resilient supply agreements, justify specification upgrades, and anticipate margin pressure points before they affect project economics.
Regulatory and Standards-Driven Quality Shifts
One of the most consequential developments for shut-off valve procurement is the enforcement of the API 6D 25th Edition, which mandates enhanced valve seat testing for shut-off valves in hydrocarbon service and became effective in July 2025. This standard update elevates the technical bar for seat integrity, leak performance, and verification protocols in hydrocarbon transport and processing applications. For buyers, the practical implication is that valves previously accepted under earlier compliance regimes may require re-qualification or replacement in certain service conditions. For manufacturers, the requirement increases testing cadence, documentation rigor, and certification overhead, which can influence lead times and pricing structures for severe-service valve lines. Understanding where API 6D compliance becomes a qualification gate is now a central consideration for procurement strategy in oil & gas, refining, and midstream pipeline applications.
Raw Material Economics and Supply Chain Exposure
Cost structures across valve manufacturing are being pressured by raw material price movements tied to logistical disruption and regional demand shifts. Stainless steel 316 prices rose 12 percent to $2,800 per metric ton, influenced in part by supply chain disruptions stemming from Red Sea shipping issues, according to USGS Mineral Commodity Summaries reported in January 2026. For valve manufacturers and buyers alike, stainless steel is a foundational input for corrosion-resistant body and trim designs, particularly in chemical, petrochemical, water treatment, and marine-adjacent service environments. Sustained material cost elevation can compress margins on standard-grade valves while increasing the strategic value of long-term supply agreements, standardized material Specs, and design optimization that reduces specialty alloy dependency where service conditions allow.
Labor Cost Inflation in Specialized Fabrication
Beyond materials, skilled labor economics are reshaping manufacturing cost baselines. The US Bureau of Labor Statistics reported that skilled valve fabricator wages increased 4.8 percent year-over-year to $32.50 per hour in 2025. This labor cost trajectory reflects both tight availability of certified welders, machinists, and assembly technicians and the broader competition for industrial craftsmanship in regions with active energy, infrastructure, and industrial plant investment. For market participants, this trend reinforces the importance of automation where feasible, design-for-manufacturability considerations, and supplier partnerships that demonstrate workforce stability and production discipline.
Macro Demand Catalysts Linked to Energy and Infrastructure
On the demand side, structural energy trade patterns continue to influence valve specification and volume requirements. The IEA forecasts 2.2 percent annual growth in global LNG trade through 2028, a trajectory that is expected to drive demand for cryogenic shut-off valves across liquefaction, shipping, regasification, and pipeline transmission infrastructure. This macro driver is particularly relevant for manufacturers and buyers operating in LNG-adjacent supply chains, where low-temperature material selection, seat design, and actuation integrity under cryogenic duty are non-negotiable engineering requirements. The forecast underscores why the shut-off valve market’s growth path is closely tied not only to traditional process industries but also to the expanding global gas trade and associated midstream investment cycle.
Trade Policy and Regional Cost Exposure
Regulatory and trade policy developments are also introducing new cost and sourcing considerations. The EU Carbon Border Adjustment Mechanism imposes 20 to 35 percent tariffs on steel imports used in valve manufacturing starting January 2026. This policy shift directly affects the landed cost of steel-dependent valve production for market participants with European manufacturing footprints or European market exposure. For global buyers, it introduces an additional layer of regional cost asymmetry that can influence make-versus-buy decisions, supplier geography selection, and inventory timing strategies. Companies with European operations or European procurement commitments should factor CBAM-related cost exposure into medium-term sourcing scenarios and evaluate supplier diversification or localized procurement pathways where feasible.
Why This Intelligence Is Critical for 2026 Decision-Making
The strategic value of this report lies in its ability to connect macro-market trajectory with the operational realities that executives face when allocating capital, qualifying suppliers, and planning for regulatory or technical transitions. A 4.6 percent CAGR over seven years may appear moderate, but in a market of this scale and complexity, the compounding effect represents billions of dollars in cumulative demand across segments, regions, and applications. The real decision-making advantage comes from understanding where growth is concentrating, which specification and compliance shifts are redefining qualification criteria, how raw material and labor cost dynamics are pressuring cost structures, and which manufacturers are actively investing in the service areas most relevant to a company’s portfolio.
Procurement leaders can use the segmentation and competitive intelligence to structure sourcing evaluations that go beyond unit price and incorporate certification readiness, severe-service engineering capability, regional supply resilience, and lifecycle support. Strategy and business development teams can leverage the demand trajectory and dynamic factor analysis to anticipate capacity investment timing, identify adjacency opportunities, and align internal manufacturing or distribution plans with the regions and applications where demand momentum is strongest. Risk and compliance stakeholders can integrate the regulatory and trade policy updates into scenario planning, ensuring that valve qualification pathways and sourcing footprints remain robust under evolving standards and tariff regimes.
Most importantly, the report is designed to reduce uncertainty in a category where uncertainty is costly. Valve specification errors, compliance gaps, material shortages, and supplier capacity bottlenecks can cascade into project delays, operational downtime, and unplanned capital expenditure. By grounding 2026 planning in a structured, data-informed view of market scale, segment dynamics, competitive positioning, and external catalysts, organizations can move from reactive procurement to proactive strategy.
Positioning for the 2026–2032 Cycle
The worldwide shut-off valves market is entering a phase where steady top-line growth is being reshaped by technical, regulatory, and geopolitical forces that demand attention at the executive level. Historical expansion from 2020 through 2025 has established a solid base, and the forecast path through 2032 points to continued, broad-based demand creation across energy, water, industrial processing, and infrastructure applications. Yet the companies that will extract the greatest value from this cycle are those that treat the market as a strategic ecosystem rather than a commodity purchasing category.
That means aligning valve specifications with the service conditions that matter most, anticipating compliance and certification shifts before they become procurement blockers, building supplier relationships with manufacturers that are actively investing in hydrogen, LNG, severe-service, and water-sector applications, and incorporating raw material, labor, and trade-policy dynamics into cost and sourcing models. It also means recognizing that moderate market growth can still produce significant competitive differentiation when paired with application expertise, reliable supply assurance, and intelligent specification strategy.
PW Consulting’s Worldwide Shut-off Valves Market research provides the analytical foundation to make those decisions with confidence. The full publication delivers the detailed segmentation breakdowns, regional demand mappings, application-level revenue distributions, competitive profiling, and dynamic scenario context that executives need to translate market intelligence into procurement strategy, investment planning, and competitive positioning.
For organizations preparing their 2026 capital, procurement, and growth strategies, the complete market intelligence is available through the full report. We invite strategy leaders, procurement executives, and industry planners to access the comprehensive market study for the full segmentation detail, region-by-region demand context, application-level analysis, and competitive benchmarking that will support precise, evidence-based decision-making across the 2026–2032 forecast horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Shut-off Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Motor Control Drivers Market to Surpass USD 11319 Million by 2032 With 7.45 Percent CAGR
By PW Consulting, 2026-09-02
Executive Preview: Navigating the 2026 Global Motor Control Drivers Market Landscape
The worldwide motor control drivers market has entered a decisive inflection point as of 2026. What was once characterized by incremental performance improvements has now evolved into a multidimensional battleground shaped by architectural innovation, supply chain recalibration, and rapidly shifting end-user demand. For engineering leaders, procurement strategists, and corporate planners, the imperative is no longer to simply track historical trajectories. Strategic advantage now hinges on anticipatory intelligence that maps where value will concentrate over the next decade. In this environment, high-resolution market intelligence has transitioned from a supplementary research product to a foundational input for capital allocation, roadmap planning, and competitive positioning.
Worldwide Motor Control Drivers Market
This preview outlines the strategic contours of our latest Worldwide Motor Control Drivers Market study. Designed for executive decision-making, the publication synthesizes multi-year historical performance with a rigorously modeled forecast window through 2032. Rather than functioning as a static data repository, the report delivers an actionable framework for interpreting market velocity, assessing competitive exposure, and aligning product portfolios with structural demand shifts. The following sections explore the macro trajectory, segmentation dynamics, competitive undercurrents, and operational variables that will define the sector’s evolution.
Worldwide Motor Control Drivers Market
The Macro Trajectory: Structural Growth and Forecast Calibration
The sector’s baseline trajectory reflects sustained, compounding expansion that has consistently outpaced broader industrial electronics benchmarks. Historical momentum across the base analysis window demonstrates a clear acceleration pattern. The global market advanced from approximately 4.65 billion USD in 2020 to roughly 6.85 billion USD by 2025, with a pronounced step-change occurring between 2021 and 2023 as design cycles matured across automotive electrification and automation platforms. The projected outlook reinforces this upward structural trend. Forecast modeling places the addressable revenue at approximately 7.44 billion USD in 2026, climbing steadily toward 8.47 billion USD by 2028 and approaching a double-digit billion threshold by 2031. By the close of the forecast horizon in 2032, the market is positioned to reach an estimated 11.32 billion USD.
Worldwide Motor Control Drivers Market
This expansion is anchored by a forward CAGR of 7.45 percent, a rate that signals durable demand absorption rather than speculative hype. The trajectory is not uniform across all product categories or customer verticals. Instead, it reflects differentiated pull from high-value applications where efficiency, thermal performance, and functional safety requirements directly dictate component selection. Our modeling framework isolates the underlying drivers of this growth curve, separating cyclical procurement noise from structural adoption pathways. For organizations evaluating capacity planning, pricing architecture, or technology investment timelines, the forecast baseline serves as a disciplined reference point against which internal projections can be stress-tested. The report further contextualizes this macro path against demographic shifts in industrial capital expenditure, automotive powertrain transitions, and the broader integration of precision motion control into everyday electronic systems. By anchoring strategy in a quantified, forward-looking baseline, leadership teams can reduce reliance on anecdotal forecasting and anchor resource deployment in validated demand signals.
Segmentation Dynamics and Structural Demand Shifts
A central strategic challenge in this space is translating aggregate growth into actionable segmentation intelligence. The market does not expand uniformly; rather, it fragments along motor architecture, geographic demand concentration, and end-user deployment patterns. Our analysis dissects these dimensions to reveal where design wins are accumulating, where pricing power is shifting, and where supply constraints may alter competitive advantage over the forecast period.
Motor Architecture and Application Reallocation
The composition of the market by motor type reflects the ongoing migration toward architectures that deliver higher torque density, lower acoustic signature, and improved energy efficiency. Brushless DC driver solutions currently represent the most substantial application share, underscoring a broad design preference for maintenance-free, high-efficiency topologies that align with modern industrial and automotive specifications. Stepper motor drivers maintain a significant and resilient position, driven by precision positioning requirements in automation, medical instrumentation, and specialized consumer equipment. Brushed DC and AC motor driver categories continue to serve entrenched use cases, particularly in cost-sensitive deployments and legacy industrial platforms where reliability and simplicity remain paramount. The report examines how these architectural shares are evolving under the influence of silicon advancements, integrated control functions, and shifting system-level specifications, offering engineering and product teams a granular view of where roadmap investments should be concentrated.
Demand Concentration Across End-Use Verticals
End-user demand distribution further shapes the strategic calculus for component suppliers, system integrators, and OEMs. Automotive applications currently account for the largest revenue concentration, reflecting the proliferation of electronic motor management modules across passenger vehicles, electric powertrain subsystems, and advanced driver-assistance functions. Industrial automation follows as a structurally vital segment, sustained by factory modernization initiatives, robotics deployment, and the replacement of aging motion control infrastructure. Consumer electronics continues to generate consistent pull, particularly in smart appliances, personal care devices, and compact electromechanical assemblies. Healthcare and medical deployments occupy a specialized but high-margin niche, where signal integrity, reliability, and regulatory compliance command premium design requirements. The study captures how these vertical demand patterns interact with regional manufacturing footprints, procurement cycles, and certification timelines. Importantly, the analysis avoids static share reporting; instead, it frames demand reallocation as a dynamic process influenced by product refresh cycles, electrification mandates, and automation intensity across industries.
Geographic Demand Architecture
Regional demand patterns reveal a market that is broad-based yet asymmetrically concentrated. Asia Pacific maintains the highest revenue footprint, driven by dense manufacturing ecosystems, rapid consumer product turnover, and large-scale industrial integration programs. Europe and North America contribute substantial and stable demand bases, characterized by stringent performance requirements, deeper adoption of safety-critical motor control, and stronger alignment with advanced automotive and high-end automation applications. The rest-of-world segment reflects growing but still developing demand patterns, particularly in regions where industrialization programs, infrastructure expansion, and regional electronics assembly are accelerating. The report contextualizes geographic distribution not merely as a revenue map but as a structural factor influencing sourcing strategy, qualification timelines, logistics exposure, and tariff or trade-policy sensitivity. This geographic lens is essential for organizations evaluating facility placement, distribution partnerships, and localized product support strategies.
Competitive Landscape: Incumbent Advantage and Strategic Positioning
The motor control drivers market is defined by a competitive environment in which scale, portfolio depth, and integration capability often determine design-in velocity. Market concentration metrics indicate that the top three participants command approximately 38.4 percent of total revenue, while the top five collectively hold about 52.15 percent. This level of concentration suggests that major incumbents retain meaningful influence over pricing, reference design ecosystems, and qualification pathways, yet sufficient fragmentation remains to reward specialized innovation and region-specific execution.
Several globally active semiconductor and component leaders shape the competitive architecture. Texas Instruments maintains a broad portfolio anchored by integrated motor drivers and gate drivers for brushed DC, stepper, and brushless DC configurations, with a consistent emphasis on compact form factors, efficiency, and integrated protection features across industrial, automotive, and consumer uses. Infineon Technologies contributes through its MOTIX family, spanning half-bridge, full-bridge, and three-phase gate driver solutions, complemented by system-in-package architectures that address the demand for power efficiency and functional safety in automotive and industrial platforms. STMicroelectronics offers a wide range of motor control ICs, including its xSPIN stepper driver line with microstepping and integrated motion profiles, alongside brushless and brushed DC drivers targeting industrial automation, automotive, and consumer electronics. ON Semiconductor provides motor driver ICs focused on automotive and industrial applications, emphasizing high-current H-bridge designs, brushless DC capabilities, energy efficiency, and thermal management. NXP Semiconductors positions its motor control solutions around integration with microcontrollers, delivering gate drivers and power stages that support software-defined vehicle architectures and industrial motor drives.
Additional participants extend the competitive field with differentiated strengths. Analog Devices contributes precision motor control ICs and gate drivers frequently paired with sensing and processing subsystems for high-performance applications. Renesas Electronics emphasizes motor control MCUs with integrated drivers and high-speed networking interfaces tailored to industrial and automotive environments. ROHM Semiconductor offers brushless DC and stepper driver ICs with low power consumption and integrated protection suited to consumer and industrial devices. Microchip Technology provides motor driver and controller ICs incorporating MCUs for brushed, stepper, and brushless motors across automotive and industrial segments. Allegro MicroSystems specializes in sensorless motor driver ICs and gate drivers with strong emphasis on current sensing and safety for automotive and industrial applications. Toshiba Electronic Devices & Storage continues to supply motor control driver ICs focused on supply chain resilience across brushed and brushless DC motor applications. Monolithic Power Systems delivers integrated solutions with high efficiency for consumer, industrial, and automotive motor control. Diodes Incorporated addresses cost-sensitive deployments with motor driver ICs for DC and stepper motors in consumer and industrial electronics. Power Integrations contributes high-voltage motor driver ICs with integrated protection for industrial and appliance use. Vishay Intertechnology supplies discrete and integrated solutions, including MOSFETs and drivers for power motor control. Melexis rounds out the competitive field with automotive-grade motor driver ICs featuring integrated Hall-effect sensing for brushless DC motors.
The report evaluates these players across multiple strategic dimensions: portfolio completeness, integration depth, regional coverage, application-specific qualification paths, and the capacity to support system-level design cycles. Rather than treating competitive assessment as a simple vendor ranking, the study maps how positioning differences influence win rates in complex procurement environments and how smaller specialists can compete through niche excellence, supply agility, or application-specific engineering support.
Recent Market Developments and Emerging Industry Dynamics
The strategic context for motor control drivers in 2026 is heavily influenced by active product introductions, partnership activity, and supply-chain policy shifts. These developments do not merely represent news flow; they continuously reshape design priorities, qualification timelines, and sourcing risk profiles.
In early 2026, Infineon Technologies introduced the first MOTIX system-in-package integrating an MCU and power stage for compact 12V DC motor control in automotive applications, signaling a broader push toward highly integrated solutions that reduce board complexity while preserving functional performance. Shortly thereafter, Infineon and Flex announced a zone controller development kit at CES 2026, combining MOTIX motor control solutions with Flex’s system integration expertise to advance software-defined vehicle architectures. In the preceding year, Renesas Electronics released new motor control MCUs with industry-leading performance and high-speed networking interfaces optimized for motor control, while NXP Semiconductors introduced mixed-signal MCUs with a high-speed math acceleration unit for advanced motor control in industrial, robotics, and precision application environments. These developments collectively illustrate the industry’s movement toward tighter integration between control logic, power delivery, and networking capability, with direct implications for reference design strategy, software ecosystems, and automotive platform roadmaps.
Beyond product activity, structural supply and policy variables are increasingly shaping strategic planning. Early 2026 saw semiconductor and electronic component prices, including analog and power management ICs relevant to motor drivers, experience upward pressure linked to AI-driven demand and raw material cost increases. At the same time, lead times for microcontrollers, power management ICs, and specialty analog devices extended toward 30 to 42 weeks amid tightening supply, reinforcing the need for proactive inventory planning and diversified sourcing approaches. Regulatory developments have added further complexity. U.S. policy actions involving Section 232 investigations and potential import adjustments on processed critical minerals and derivative products, including materials used in power semiconductors for motor control, have introduced national security considerations into supply chain deliberations. In parallel, export controls on advanced semiconductors and manufacturing equipment have continued to influence the availability and sourcing pathways for high-performance motor control components. Additional trade dynamics, including export controls on gallium and germanium tied to semiconductor production, have heightened attention on material security across power IC and driver supply chains.
Rather than treating these factors as isolated events, the study integrates them into a cohesive operational assessment. The report examines how policy exposure, material cost volatility, and extended lead times interact with regional sourcing footprints, qualification cycles, and design-in velocity. This integrated perspective enables organizations to anticipate disruption points, evaluate dual-sourcing feasibility, and align product roadmaps with realistic supply constraints.
What the Study Delivers for Executive Decision-Making
The Worldwide Motor Control Drivers Market study is structured to function as a decision-support system rather than a passive market overview. Its content is designed to answer the operational and strategic questions that senior leaders face when planning capacity, prioritizing technology investments, and positioning products within a competitive and supply-sensitive environment.
The publication provides a comprehensive segmentation architecture that maps motor type, end-user verticals, and geographic demand patterns into a unified analytical framework. It includes historical performance tracking across the base period from 2020 through 2025 and a forward forecast period spanning 2026 to 2032, allowing readers to trace momentum shifts and calibrate expectations for near-term and longer-term planning. Rather than presenting segmentation data as static snapshots, the study examines interaction effects: how motor architecture preferences shift across end-user categories, how regional demand intensity influences sourcing strategy, and how application requirements reshape portfolio priorities over time.
The competitive analysis section integrates company profiles, portfolio positioning, and recent strategic developments to create a practical map of design-in competition. It evaluates how major players differ in integration strategy, application focus, and regional reach, while also identifying spaces where specialized participants can secure durable competitive advantage. The inclusion of recent product launches, partnership activity, and platform-level initiatives provides a forward-looking view of where reference designs, ecosystem support, and software-defined architectures are likely to influence procurement outcomes.
Operational and policy context is woven throughout the report rather than isolated in separate commentary. Supply chain volatility, lead-time elongation, material cost pressure, export-control implications, and critical-mineral policy considerations are assessed for their potential impact on cost structures, qualification timelines, and regional sourcing exposure. This operational lens is particularly valuable for organizations that must balance performance requirements with supply reliability and pricing resilience.
Importantly, the study is built to support internal alignment. Engineering teams can use the segmentation architecture to validate roadmap priorities. Procurement and supply chain leaders can reference the operational dynamics to stress-test sourcing strategies and lead-time assumptions. Corporate strategy and business development teams can use the competitive mapping and demand trajectory to prioritize market entry, partnership discussions, and resource allocation. By consolidating these perspectives into a single analytical framework, the report reduces the need for cross-functional data reconciliation and accelerates time-to-decision.
Why 2026 Is a Pivotal Year for Strategic Intelligence
The convergence of product integration, policy-sensitive supply chains, regional demand asymmetry, and application-level demand reallocation means that 2026 represents more than another forecasting cycle. It is a year in which design decisions, capacity commitments, and partnership strategies will have compounding effects across the downstream market. Organizations that rely on generic industry narratives or delayed market signals risk misaligning their portfolios with the actual trajectory of demand and competition.
The Worldwide Motor Control Drivers Market study is designed to close that intelligence gap. It provides calibrated historical context, forward-looking modeling, competitive positioning analysis, and operational scenario considerations in a format intended for direct strategic application. The preview presented here highlights the scope and depth of the research while preserving the detailed segmentation figures, regional revenue distributions, application splits, and company-specific benchmarks for the full publication. Those elements are available in the complete report and are essential for precise planning, pricing calibration, and competitive benchmarking.
For teams preparing for the next phase of product strategy, supply chain configuration, and market expansion, the complete study offers the granularity needed to convert macro direction into operational execution. We invite readers to access the full Worldwide Motor Control Drivers Market report to obtain the detailed data, segmentation breakdowns, and company-level analysis required for confident, evidence-based decision-making in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Motor Control Drivers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Precision Fiber Microtome Market to Grow from $142.5 Million in 2025 to $211.44 Million by 2032 Driven by 5.81% CAGR Fueled by Asia Pacific and Textile Fiber Analysis
By PW Consulting, 2026-09-02
Executive Preview: Navigating the Precision Fiber Microtome Market in 2026
The precision fiber microtome has evolved from a niche laboratory accessory into a critical instrument for quality assurance, material characterization, and regulatory compliance across textiles, advanced materials, and forensic science. As laboratories confront tighter tolerances, rising throughput expectations, and increasingly complex fiber chemistries, the instruments used to produce accurate cross-sectional specimens have become a strategic procurement decision. This article distills the core findings of our newly released Worldwide Precision Fiber Microtome Market study, highlighting why the 2026–2032 forecast window carries outsized strategic importance and how decision-makers can leverage disciplined market intelligence to outperform in a consolidating, standards-driven landscape.
Worldwide Precision Fiber Microtome Market
The analysis that follows is deliberately positioned as a strategic preview. We expose the structural forces, competitive logic, and operational realities shaping the sector, while reserving the granular segmentation data, regional breakouts, and detailed product-type splits for the full report. The objective is straightforward: give executives, procurement leaders, and R&D strategists enough analytical depth to recognize the value of the complete dataset, and to understand how that intelligence maps directly to capital allocation, vendor selection, capacity planning, and compliance readiness in 2026 and beyond.
Worldwide Precision Fiber Microtome Market
Why 2026 Is a Strategic Inflection Point
The market's trajectory over the past half-decade reflects more than incremental laboratory equipment replacement. Historical revenue figures tell a clear story of accelerating adoption: the worldwide market climbed from approximately 108.45 million USD in 2020 to 142.5 million USD in 2025. That progression is not a straight-line expansion. It embeds a shift in how organizations approach fiber microscopy, cross-sectional metrology, and specimen repeatability across both routine testing and advanced research workflows.
Worldwide Precision Fiber Microtome Market
For 2026, the forward projection reaches roughly 153.96 million USD, with the forecast window extending through 2032 and culminating near 211.44 million USD. The compound annual growth rate across the 2026–2032 period is estimated at 5.81 percent. At first glance, that growth rate may appear measured; in the context of precision laboratory instrumentation, it signals durable, structurally supported demand rather than cyclical procurement surges. The implication for enterprise planning is significant: 2026 represents the year in which organizations that still treat fiber microtomy as a back-office testing function begin to reassess it as a capability that influences compliance confidence, R&D velocity, and supplier qualification.
Several intersecting dynamics make this period especially consequential:
- Standards-aligned testing is becoming a procurement prerequisite rather than an optional best practice.
- Laboratories are under pressure to reduce operator variability and increase specimen reproducibility across fiber types with differing mechanical properties.
- Advanced materials development is expanding the universe of samples that require precise cross-sectional preparation, extending demand beyond traditional textile workflows.
- Competitive intensity among instrument manufacturers is increasing, compressing the window for buyers to differentiate on technical support, calibration protocols, and long-term total cost of ownership.
These forces do not merely influence equipment purchases. They reshape sourcing strategies, laboratory capital budgets, and the criteria used to evaluate instrument vendors. That is exactly why a multi-year forecast grounded in current market conditions is not optional intelligence; it is a planning anchor.
Structural Demand Drivers: What Is Fueling Sustained Growth
The durability of demand in this segment is tied to the central role of fiber cross-section analysis in situations where surface-level inspection is insufficient. A properly prepared cross-sectional specimen enables microscopy-based evaluation of contour, diameter, medulla structure, cuticle integrity, pigment distribution, and dye penetration. When those attributes directly influence material acceptance, regulatory documentation, or product claims, the preparation instrument becomes a governance tool as much as a testing tool.
Three demand vectors stand out in the current landscape:
- Compliance and standards adherence. Multiple international frameworks govern how fiber specimens are prepared and examined. Instruments designed to support repeatable cross-sectional production under recognized methods reduce audit friction and improve inter-laboratory consistency. This is especially relevant for organizations that must demonstrate conformity across supply chains, export markets, or accreditation reviews.
- Throughput and repeatability expectations. Laboratories are increasingly measured on both accuracy and consistency. Operators handling diverse fiber samples require specimen preparation that can be reproduced across shifts, across sample batches, and across instrument users. Equipment that supports micrometer-adjustable sectioning and predictable cut quality is gaining preference over ad hoc manual approaches.
- Expansion of analytical Scope. While textile testing remains a foundational use case, broader material characterization needs are pulling instrumentation into adjacent workflows. Research teams examining composite fibers, engineered textiles, and specialized polymers increasingly depend on clean cross-sections to support microstructural interpretation and dimensional measurement.
The practical consequence is that procurement decisions are no longer limited to unit price or basic functionality. Buyers are evaluating calibration support, specimen consistency, compliance documentation, service responsiveness, and alignment with existing laboratory accreditation requirements. That shift raises the strategic importance of understanding who supplies what, how products differ in capability, and where the market is heading in terms of feature expectations and service models.
Competitive Landscape: Consolidation, Differentiation, and Regional Balance
The precision fiber microtome market is not fragmented in the manner of commoditized laboratory supplies. Market concentration data indicates that the top three players hold approximately 42.5 percent of revenue, while the top five account for roughly 58.15 percent. That level of concentration suggests a market where established players maintain strong positions through product standards alignment, regional service networks, and long-standing laboratory relationships, while still facing pressure from specialized manufacturers targeting cost sensitivity, localized support, and application-specific workflows.
Competitive differentiation in this sector tends to emerge around several recurring themes:
- Standards compliance posture and the clarity of documentation supporting recognized test methods.
- Mechanical precision, repeatability, and ease of producing specimens within targeted thickness ranges.
- Regional availability and the practical speed of service, calibration, and user support.
- Product range breadth spanning conventional rotary and sliding configurations alongside more specialized variants.
- Positioning for either cost-conscious laboratory adoption or higher-throughput, standards-heavy environments.
When we examine the principal suppliers shaping this market, distinct strategic profiles become visible. SDL Atlas, based in Rock Hill, South Carolina, offers the Precision Fiber Microtome (Model F214), designed for producing accurate fiber cross sections for microscopic examination, measurement, and identification in textile testing, with compliance alignment to standards including ASTM D2130 and ISO 137. Its market relevance is closely tied to organizations prioritizing established U.S.-based instrumentation and recognized textile testing conventions.
Wira Instrumentation, operating from the United Kingdom, provides the Wira Precision Fibre Microtome for quick and repeatable production of accurate fiber cross-sectional specimens suitable for microscopic analysis of contour, cuticle, medulla, pigment, and dye penetration, aligned with ISO 137, ASTM D2130, and BS 2043. Its positioning emphasizes repeatability and specimen fidelity for detailed microscopic evaluation, which appeals to laboratories where analytical consistency is central to reporting confidence.
UTS (Uts Testers), headquartered in Zhangzhou, Fujian, China, manufactures the Precision Fiber Microtome F007B (and F007A) for producing fiber cross sections for microscopic examination and identification, supported by CE, ISO 9001, and ISO 17025 certifications. This profile reflects the growing importance of manufacturers that combine competitive pricing with documented quality management and accreditation-aligned operations.
Radical Scientific Equipments Pvt Ltd, based in Ambala Cantt, Haryana, India, produces the Precision Fiber Microtome RMT-55 for accurate cross-sectional specimens of fibers with thickness capabilities from 200 µm for microscopic examination and diameter determination, compliant with ASTM D2130, ISO 137, and BS 2043. Its relevance highlights how regional manufacturing hubs are serving laboratory demand with standards-conscious instrumentation and practical specimen preparation ranges.
DaRong Tester supplies the Precision Fiber Microtome Y(B)172 for cutting fiber cross-section slices of specified thickness used in various fiber analyses. Anytester (Hefei) Co., Ltd. offers the HY172 Precision Fiber Microtome for fiber cross sections used in microscopic examination, measurement, and identification. Apple Electroniks, based in Vadodara, Gujarat, India, manufactures and exports fiber microtome models for producing accurate fiber cross sections for microscopic examination. Collectively, these suppliers illustrate a competitive field in which multiple manufacturers serve overlapping application needs, and where buyers differentiate vendors not only by instrument design, but also by regional access, support reliability, certification posture, and total cost of ownership over the instrument lifecycle.
Standards, Regulatory Alignment, and the Hidden Cost of Inconsistency
One of the most underappreciated strategic issues in this market is the operational cost of non-aligned specimen preparation. When fiber cross-section analysis supports accepted test methods, the instrument and the preparation workflow must produce specimens that are interpretable, reproducible, and defensible. The most commonly referenced standards in this space include ISO 137, ASTM D2130, and BS 2043, which underpin consistent microscopic examination of fiber properties such as diameter, contour, and medulla.
This matters for enterprise decision-making for several reasons:
- Accreditation and audit readiness often depend on documented specimen preparation procedures and instrument traceability.
- Cross-site or multi-vendor testing programs require comparability, which is harder to achieve when specimen quality is inconsistent.
- Supplier qualification can hinge on the ability to demonstrate repeatable fiber cross-sectional analysis rather than nominal conformance.
- R&D teams working with new fiber architectures need preparation methods that preserve structural detail rather than introducing cutting artifacts.
In practice, compliance is not simply a documentation exercise. It is an operational discipline that depends on instrument capability, user training, calibration habits, and the availability of service support when specimens must meet defined tolerances. The market's standards alignment, therefore, is not a static feature; it is a competitive variable that influences procurement confidence and long-term laboratory reliability.
Regional and Application Context Without the Noise
Market expansion is not distributed uniformly. Asia Pacific holds the largest regional share, followed by North America and Europe, with Latin America and the Middle East and Africa representing smaller but meaningful demand pools. That distribution reflects the geography of textile manufacturing, advanced materials development, forensic infrastructure, and laboratory procurement patterns. It also highlights a practical reality for vendors and buyers alike: regional access to supply, service, and standards-aligned support can matter as much as instrument specifications.
On the application side, demand is anchored by textile fiber analysis and material science research as primary use cases, with forensic investigation and optical fiber testing contributing additional demand streams. The strategic insight here is not merely which applications are largest, but how they interact. Textile testing drives volume and standards-focused procurement. Material science research drives capability expectations and microstructure interpretation needs. Forensic work introduces evidentiary consistency concerns. Optical fiber testing adds specialized measurement requirements. Organizations operating across multiple application domains should therefore evaluate instruments not only for a single lab function, but for how well the same preparation platform supports varied specimen requirements without sacrificing repeatability.
We are intentionally leaving the detailed segmentation values and regional or application-level monetary values out of this preview. Those splits matter heavily in execution, but their full value is realized only when paired with product-type mix, regional procurement behavior, and competitive sourcing logic. That level of granularity is built into the complete report and is best used for scenario modeling, market entry planning, and vendor evaluation matrices.
What the Full Report Delivers for Enterprise Decision-Makers
The complete Worldwide Precision Fiber Microtome Market study is designed as an operational intelligence asset rather than a high-level market summary. It connects the macro growth narrative to the practical decisions that laboratory leaders, procurement teams, and strategy groups face in 2026. The report is structured to support concrete actions: capital planning, supplier benchmarking, application-portfolio alignment, and risk-aware procurement.
Inside the full analysis, readers can expect coverage that supports decision-making across several dimensions:
- A multi-year market size and growth trajectory grounded in historical performance and forward projection, enabling baseline planning through 2032.
- Segmentation detail across product types and applications, allowing teams to understand where demand intensity and differentiation are concentrated.
- Regional market context that helps align sourcing, support expectations, and geographic procurement strategy.
- Competitive profiling of leading suppliers, including product positioning, compliance alignment, and operational characteristics relevant to lab selection.
- Market concentration and competitive structure analysis that clarifies where consolidation pressure exists and where vendor options remain broad.
- Standards-relevant context that ties instrumentation choices to compliance and repeatability requirements.
The emphasis throughout is on useable intelligence. The report is intended to help stakeholders answer questions such as: Where is demand structurally emerging, and how should that influence equipment roadmaps? Which supplier profiles fit a cost-sensitive laboratory versus a compliance-heavy testing environment? How should an organization weigh product-type characteristics against application needs and regional support realities? These are the kinds of questions that determine whether market growth simply happens around an organization or is actively leveraged for operational advantage.
Strategic Implications for 2026 Planning
For organizations planning laboratory investment, vendor relationships, or capability expansion in 2026, the precision fiber microtome market presents a clear strategic message: demand is durable, competitive intensity is rising, and procurement decisions are increasingly tied to standards alignment, repeatability, and lifecycle support. In that environment, the organizations that outperform are not necessarily the ones that spend the most, but the ones that make procurement decisions with a full view of market structure and supplier differentiation.
Several planning actions follow naturally from this landscape:
- Treat instrument selection as a multi-year capability decision rather than a single-purchase transaction. Consider calibration, service availability, compliance documentation, and specimen reproducibility alongside initial cost.
- Align procurement criteria with the actual application mix. A lab serving primarily textile testing may weight different features than one supporting broader material science or forensic workflows.
- Factor regional access into vendor evaluation. Supply continuity, support responsiveness, and localized service can materially affect total operating cost and laboratory uptime.
- Use market concentration insight to manage sourcing risk. Understanding where purchasing power sits and where alternative suppliers remain viable supports more resilient procurement strategies.
- Incorporate compliance as an operational design requirement. Instruments that support standards-aligned specimen preparation reduce downstream friction and strengthen defensible testing outcomes.
This is precisely where the full report adds value. The macro numbers, growth rate, and competitive concentration provide orientation, but the practical advantage comes from knowing how those forces break down across product types, applications, regions, and supplier profiles. That breakdown enables more precise scenario planning and more confident purchasing decisions.
Conclusion: The Case for Deeper Intelligence
The Worldwide Precision Fiber Microtome Market is moving through a phase in which growth is supported by standards-driven testing, repeatability expectations, and expanding application needs. The 2026–2032 forecast window offers a credible basis for long-range planning, and the concentration structure of the market signals that supplier selection is increasingly consequential. This preview has outlined the strategic logic behind that trajectory and the competitive environment shaping it, while intentionally leaving the detailed segmentation values, regional splits, and application-level breakdowns for the full dataset.
For executives and laboratory strategists, the appropriate next step is to treat this sector not as a static equipment category, but as a capability market in which informed procurement can improve compliance confidence, testing consistency, and operational resilience. The complete report provides the depth required to turn that strategic understanding into concrete decisions.
To access the full Worldwide Precision Fiber Microtome Market research, including detailed segmentation, regional analysis, competitive profiles, and the complete 2026–2032 forecast framework, please visit the source page for the complete study.
For detailed analysis of this topic, please visit the official page: Worldwide Precision Fiber Microtome Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Releases Global Mechanical Float Level Sensors Market Report Highlighting 5.2 Percent Growth Towards 927 Million by 2032
By PW Consulting, 2026-09-02
Strategic Sizing in Critical Liquid Measurement: The 2026 Outlook for the Global Mechanical Float Level Sensors Market
In an industrial landscape increasingly defined by operational resilience, regulatory stringency, and supply chain recalibration, the ability to accurately monitor fluid levels remains a non-negotiable prerequisite for process safety and efficiency. Mechanical float level sensors, with their proven reliability, straightforward mechanical architecture, and adaptability across diverse media, continue to occupy a vital niche within the broader instrumentation ecosystem. Our latest research initiative, the Worldwide Mechanical Float Level Sensors Market study, provides decision-makers with a comprehensive, data-grounded roadmap for navigating the 2026–2032 forecasting horizon. This article distills the strategic intent behind the research, outlines the methodology and actionable frameworks embedded within the full report, and demonstrates how executives, engineering leaders, and procurement strategists can translate macro-level intelligence into precise commercial and operational advantages.
Worldwide Mechanical Float Level Sensors Market
The mechanical float level sensor segment has matured into a market where incremental innovation, material engineering, and regional compliance requirements dictate competitive positioning. Rather than relying on fragmented vendor claims or ad hoc benchmarking, organizations now require a unified intelligence architecture that maps historical demand trajectories, projects forward-looking revenue curves, and dissects the structural drivers shaping procurement, product development, and market entry strategies. The study addresses precisely this need, offering a disciplined examination of how mechanical float technologies are evolving in response to industrial automation trends, hazardous-environment compliance, and the ongoing shift toward durable, corrosion-resistant construction materials.
Worldwide Mechanical Float Level Sensors Market
The Numbers Behind the Narrative: Mapping Market Trajectory from 2020 to 2032
Any serious strategic assessment begins with a clear understanding of scale and momentum. The global mechanical float level sensors market has demonstrated steady, compounding growth over the past half-decade, reflecting sustained demand from water infrastructure, chemical processing, food and beverage manufacturing, and energy-related operations. Historical revenue progression from 2020 through 2025 illustrates a market that has consistently expanded beyond baseline expectations, culminating in a base-year valuation of approximately 650.0 million USD in 2025. This trajectory is projected to continue its upward course throughout the 2026–2032 forecast window, with annualized growth compounding at a rate of 5.2 percent.
Worldwide Mechanical Float Level Sensors Market
By 2032, the aggregate revenue outlook suggests a market size approaching 926.89 million USD, signaling a durable expansion cycle that will be shaped by sustained capital investment in process industries, infrastructure modernization programs, and the ongoing replacement of legacy level-detection equipment with more robust mechanical alternatives. For strategic planners, this trajectory is not merely a top-line projection; it represents a structural invitation to reassess product portfolios, distribution footprints, and pricing strategies against a backdrop of predictable but non-linear demand growth.
Importantly, the study avoids superficial aggregation. Instead, it contextualizes the headline figures within the operational realities that drive them: the replacement cycles of aging municipal and industrial fluid-handling systems, the influence of raw material price volatility on manufacturing margins, and the shifting balance between standardized catalog products and engineered custom solutions. Decision-makers who internalize these dynamics can anticipate where demand will concentrate, how pricing power will fluctuate across material categories, and which application verticals will generate the most resilient order flows during periods of macroeconomic uncertainty.
Strategic Pillars of the Research: What Decision-Makers Will Find Inside
The full research deliverable is structured to bridge the gap between high-level market intelligence and day-to-day strategic execution. It moves beyond descriptive sizing to provide a suite of actionable frameworks designed for cross-functional application. Chief among these are the segmentation architectures that break down demand patterns across material specifications, end-use environments, and regional deployment characteristics, enabling stakeholders to isolate the most commercially relevant growth vectors without becoming lost in undifferentiated aggregates.
In the materials dimension, the analysis examines how construction choices—ranging from stainless steel to plastic and polymer formulations, alongside other specialized material configurations—shape performance expectations, procurement costs, and lifecycle durability. This material-level dissection is particularly critical in an environment where input cost fluctuations, such as the recent pricing behavior observed in stainless steel markets across Northeast Asia and broader global trading hubs, directly influence manufacturer margin structures and end-user total cost of ownership calculations. The report maps these material-driven dynamics to regional supply conditions, enabling procurement and product strategy teams to anticipate cost shifts and align sourcing strategies accordingly.
The application-focused analysis further enriches the strategic picture by evaluating how different industrial verticals drive distinct purchasing behaviors, compliance requirements, and performance tolerances. Water and wastewater management, chemical and petrochemical processing, food and beverage production, oil and gas operations, and a range of ancillary sectors each impose unique demands on mechanical float level sensing equipment. The study unpacks these vertical-specific requirements, highlighting where certification mandates, media compatibility considerations, and environmental conditions converge to create differentiated demand pockets. Rather than presenting broad generalizations, the research isolates the operational parameters that determine which sensor architectures thrive in which environments, allowing engineering and commercialization teams to prioritize development resources with precision.
Equally central to the report’s value proposition is its treatment of regional deployment patterns. By delineating how demand distributes across major geographic zones, the study equips market entry strategists, distribution planners, and manufacturing footprint designers with the intelligence required to align capacity allocation with realistic revenue potential. This regional lens is particularly valuable for organizations evaluating expansion into emerging industrial corridors or reassessing exposure to mature markets undergoing regulatory or infrastructural transitions.
Beyond segmentation, the research integrates a forward-looking examination of market dynamics and regulatory tailwinds. The ongoing emphasis on functional safety, hazardous-location compliance, and instrumentation certification continues to reshape procurement specifications across process industries. Standards governing safety instrumented systems, along with certifications applicable to explosive or corrosive environments, are no longer peripheral considerations; they are central to specification writing, vendor qualification, and long-term asset reliability. The report situates these regulatory currents within the broader commercial landscape, illustrating how compliance-driven procurement creates both barriers to entry and opportunities for manufacturers that have invested early in certified, application-ready mechanical float solutions.
The Competitive Arena: Navigating a Fragmented but Dynamic Landscape
The mechanical float level sensors market is characterized by a moderately concentrated competitive structure, with a consolidated group of established manufacturers holding meaningful but not dominant shares of total industry revenue. The market concentration metrics indicate that the top three players account for approximately 28.5 percent of aggregate market value, while the top five collectively represent roughly 35.2 percent. This distribution suggests a landscape in which scale, technical differentiation, and regional servicing capabilities matter significantly, but where specialized niche players and application-focused engineers can still capture substantial value through customization, rapid responsiveness, and deep vertical expertise.
Several core companies define the current competitive baseline. DwyerOmega, headquartered in Michigan City, Indiana, has built a reputation around float switch sensors engineered for precise level detection across industrial, agricultural, and commercial environments, leveraging mechanical float technology as a core differentiator. SOR Inc., based in Lenexa, Kansas, positions itself in the heavy-industrial segment with rugged float level switches and displacer level switches designed for demanding pressure and temperature regimes, including top-mounted and custom configurations tailored to extreme operating conditions. Rochester Sensors, operating from Coppell, Texas, supplies swing float arm and related float-based measurement solutions spanning industrial, marine, and refrigeration applications, and benefits from global manufacturing capabilities that broaden its deployment reach.
WIKA, with its German engineering heritage in Klingenberg, manufactures vertical, horizontal, and mechanical float switches engineered for a wide array of liquid media, with particular emphasis on handling foaming, turbulence, corrosion, and high-pressure scenarios. Madison Company, located in Branford, Connecticut, specializes in single-point and continuous float level sensors and switches built around reed switch technology, serving industrial and OEM applications with UL and CE certifications that support specification confidence across regulated markets. APG Sensors, based in Logan, Utah, focuses on mechanical float switches including stem-mounted multi-point, miniature, and cable-suspended models, with product lines oriented toward pump control and alarm functions. SMD Fluid Controls, also in Connecticut, delivers OEM custom float switches, vertical and horizontal mechanical float switches, and multi-level sensors tailored to industrial liquid measurement requirements.
Additional participants further deepen the competitive mosaic. KOBOLD Instruments, with U.S. operations coordinated from Pittsburgh, Pennsylvania, supplies magnetic float level switches for reliable level detection across industrial settings. ACT Sensors provides float switches and liquid level sensors under rigorous quality control protocols, serving OEM, MRO, process, and environmental end-users. FPI Sensors, headquartered in Dallas, Texas, produces standard and custom multi-level float sensors, side-mount configurations, and continuous measurement float-type switches designed for varied installation geometries and measurement precision needs.
Recent corporate activity reinforces the strategic significance of this competitive field. In October 2025, Rochester Sensors was acquired by Amphenol Corporation, a move that expanded its global capabilities in liquid level measurement and strengthened its position across float-based technology portfolios. More recently, in February 2026, ACT Sensors published an engineering guide focused on stainless steel float switches for harsh environments, underscoring the ongoing product emphasis on durability, material integrity, and application-specific mechanical float solutions. These developments illustrate a market in which consolidation, capability expansion, and technical documentation strategies are being deployed simultaneously to capture specification share and reinforce customer confidence.
For strategists, the competitive analysis within the report goes beyond company profiling. It evaluates how these manufacturers position themselves relative to certification portfolios, material specialization, custom engineering capabilities, and regional service infrastructure. By mapping the competitive baselines against the segmentation and regional frameworks, the study enables organizations to identify where incumbents are strongest, where gaps exist, and where partnership, acquisition, or targeted product development may yield disproportionate strategic returns.
Material Economics, Regulatory Currents, and the Evolution of Mechanical Float Technology
The commercial viability of mechanical float level sensors is inseparable from the material and regulatory environment in which they are designed, manufactured, and deployed. Stainless steel remains a dominant construction material for durable housings and float bodies, and its pricing behavior carries direct implications for manufacturing cost structures and end-market affordability. Recent market data points to modest monthly increases in stainless steel futures, supported by seasonal demand patterns and regional cost variations tied to alloying element inputs such as nickel and chromium. These price movements are not abstract commodity signals; they translate into tangible shifts in sensor production economics, influencing pricing strategies, margin management, and the relative attractiveness of alternative material formulations in cost-sensitive applications.
Regulatory compliance continues to act as a powerful demand shaper. Mechanical float switches are widely designed for hazardous locations, with manufacturers offering configurations aligned to ATEX, IECEx, UL, and CSA certification frameworks to ensure safe operation in flammable or explosive environments. Additionally, several float level switch products are certified to IEC 61508 for use in SIL1 and SIL2 safety instrumented systems, reinforcing their role in process industries where functional safety is a contractual and operational imperative. These certification pathways are increasingly embedded in procurement specifications, meaning that manufacturers without robust compliance documentation risk exclusion from high-value bidding processes, while those with established certification portfolios can command specification preference and nuanced pricing advantage.
Technological evolution within the mechanical float segment is also being guided by the need to address challenging process conditions. Foaming media, turbulent flow regimes, corrosive chemical environments, and high-pressure installations all demand careful engineering of float geometry, sealing mechanisms, and mounting configurations. The research captures how these application-driven engineering requirements influence product architecture decisions, and how manufacturers are responding through both standardized high-performance lines and bespoke custom solutions. In parallel, the growing emphasis on quality assurance, documented testing protocols, and application-specific engineering guides reflects an industry-wide push toward greater transparency and reliability assurance, particularly among OEM and MRO buyers who depend on predictable sensor performance to safeguard downstream operations.
Translating Market Intelligence into 2026 Strategic Action
The overarching purpose of this research is to convert macro-level market visibility into executable strategy. For product leaders, the segmentation and material analyses provide a basis for prioritizing development roadmaps, deciding where to invest in stainless steel robustness versus polymer-based cost efficiency, and determining which application verticals warrant dedicated engineering support. For commercial and distribution teams, the regional and competitive frameworks offer guidance on where to concentrate sales resources, how to position certified product lines against incumbent strengths, and where custom OEM partnerships may unlock higher-margin revenue streams. For procurement and supply chain strategists, the material pricing context and compliance landscape illuminate where sourcing flexibility, inventory buffering, and supplier qualification criteria should be calibrated to manage cost volatility and specification risk.
The study also supports scenario-based planning. Because the forecast window extends through 2032, decision-makers can test how variations in capital expenditure cycles, infrastructure investment pacing, regulatory adoption speed, and raw material cost trajectories might alter demand distribution across applications and regions. This forward-looking capacity is especially valuable in a market where replacement demand, expansion projects, and compliance-driven upgrades each contribute differently to overall growth, and where a single well-timed strategic move can secure multi-year specification loyalty.
To fully leverage these insights, organizations need access to the complete analytical architecture behind the headline figures. The full report contains the detailed segmentation breakdowns, regional demand distributions, competitive positioning matrices, material cost impact assessments, and application-specific specification trends that transform market overview into operational intelligence. It is precisely in these deeper layers of analysis that the granularity required for confident strategic action resides.
Conclusion: Positioning for Durable Growth in a Resilient Segment
The worldwide mechanical float level sensors market is entering a period of sustained expansion underpinned by steady compound growth, diversified application demand, and a competitive landscape that rewards both technical differentiation and compliance readiness. The trajectory from a 650.0 million USD base in 2025 toward a projected 926.89 million USD by 2032 at a 5.2 percent CAGR reflects more than numerical progression; it signals a market where strategic positioning, material engineering, certification strength, and regional execution will determine which organizations capture durable share and which merely follow. Our research is designed to equip stakeholders with the structured intelligence necessary to make those determinations with confidence.
For executives and analysts seeking the full complement of market sizing, segmentation depth, competitive profiling, and dynamics mapping, the complete Worldwide Mechanical Float Level Sensors Market research provides the comprehensive foundation required for informed 2026 planning and beyond. Accessing the full report will unlock the detailed regional, application, and material-level intelligence that transforms high-level market awareness into decisive strategic action.
For detailed analysis of this topic, please visit the official page: Worldwide Mechanical Float Level Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Projects Worldwide Commercial Vehicle Coolant Market to Reach USD 7,044.11 Million by 2032 with a 4.65% CAGR
By PW Consulting, 2026-09-02
Navigating the Heat: Strategic Intelligence for the 2026 Commercial Vehicle Coolant Market
The Critical Intersection of Thermal Management and Fleet Performance
In the contemporary landscape of global logistics and heavy-duty transportation, the internal combustion engine remains the workhorse of the industry, even as electrification pathways begin to emerge. Within this ecosystem, the cooling system is not merely a peripheral component but a central determinant of engine longevity, fuel efficiency, and regulatory compliance. As we move into 2026, the Worldwide Commercial Vehicle Coolant Market is undergoing a significant transformation driven by tighter emission norms, evolving raw material economics, and a competitive landscape that demands precise strategic positioning.
Worldwide Commercial Vehicle Coolant Market
The recent market research released by PW Consulting provides a comprehensive lens through which stakeholders can view these dynamics. This analysis is not simply a retrospective of past revenue streams; it is a forward-looking instrument designed to guide capital allocation, product development, and supply chain strategy over the forecast period extending to 2032. Understanding the thermal fluids that protect multi-million dollar assets is now a prerequisite for meaningful participation in the heavy-duty sector.
Worldwide Commercial Vehicle Coolant Market
Market Trajectory and Valuation Overview
The macroeconomic signals for the commercial vehicle coolant industry indicate steady, resilient growth. Based on historical data tracking from 2020 through 2025, the market has established a robust baseline, with revenue valuations climbing consistently year-over-year. The upward trajectory observed in the base year suggests that demand is inelastic relative to minor economic fluctuations, largely because coolant replacement and maintenance are non-discretionary for fleet operators seeking to avoid catastrophic engine failure.
Worldwide Commercial Vehicle Coolant Market
Looking ahead, the forecast period from 2026 to 2032 projects a continued expansion in market valuation. The Compound Annual Growth Rate (CAGR) during this window reflects a mature yet growing market condition, hovering around a mid-single-digit percentage. This growth is not accidental; it is underpinned by the increasing complexity of engine architectures and the extended service intervals that modern coolants promise. As fleet managers prioritize total cost of ownership (TCO) reductions, the shift toward higher-quality, extended-life formulations is driving volume value even if unit volumes remain stable.
For strategic planners, the key takeaway from the valuation data is the reliability of the growth curve. While specific regional or product-based revenue figures are detailed within the full proprietary dataset, the overarching trend confirms that the market is outpacing general industrial growth rates. This implies that dedicated investment in coolant technology or distribution networks offers a hedge against volatility in other automotive sectors, particularly as light-duty electric vehicle adoption disrupts traditional fluid markets while heavy-duty diesel and natural gas engines continue to rely heavily on advanced liquid cooling solutions.
Segmentation Dynamics: Technology and Chemistry
The market is not a monolith. It is fractured along lines of chemistry, technology, and application requirements. The choice of coolant chemistry is increasingly dictated by engine manufacturer specifications and environmental regulations. Historically, conventional inorganic additive technologies dominated due to cost and familiarity. However, the industry is witnessing a decisive shift toward organic and hybrid technologies that offer superior corrosion inhibition and longer service life.
Organic Acid Technology (OAT) and Hybrid Organic Acid Technology (HOAT) are gaining significant traction in the commercial sector. These formulations are essential for modern engines operating at higher thermal efficiencies and temperatures. The demand for extended-life coolants reduces the frequency of maintenance stops, a critical metric for fleet operators where downtime equals lost revenue. Conversely, traditional Inorganic Additive Technology (IAT) remains relevant in specific legacy applications and regions where cost sensitivity outweighs performance benefits, though its market share is gradually contracting in premium segments.
The chemistry base itself also presents strategic considerations. Ethylene glycol remains the dominant base fluid due to its thermal performance characteristics and cost-effectiveness at scale. However, propylene glycol and glycerin-based alternatives are carving out niches, particularly where toxicity concerns or specific environmental regulations influence procurement decisions. The interplay between raw material pricing—such as the fluctuations observed in Northeast Asia for ethylene glycol and European markets for propylene glycol—and final product pricing is a critical variable for margin management. Strategic buyers must monitor these commodity indices closely, as supply chain resilience in the chemical sector directly impacts the stability of coolant production costs.
Regional Dynamics and Supply Chain Considerations
Geographically, the market exhibits distinct characteristics that require tailored entry or expansion strategies. The demand distribution is heavily influenced by industrial activity, vehicle parc age, and regulatory enforcement intensity. In the Asia Pacific region, rapid industrialization and a massive existing fleet of commercial trucks drive significant volume. This region represents a substantial share of global revenue, reflecting the sheer scale of logistics and construction activity. However, pricing pressures and local manufacturing capabilities in this region mean that global players must compete aggressively on performance and supply reliability.
North America and Europe constitute mature markets where the focus shifts from pure volume growth to value enhancement and technological differentiation. In these regions, stringent emission standards such as EPA Phase 2 greenhouse gas regulations and Euro VI norms are primary drivers. These regulations necessitate coolants that can support engines designed to minimize emissions while managing higher thermal loads. Consequently, the demand here is skewed toward premium, specification-approved products that guarantee compliance and protect warranty requirements.
Emerging regions in Latin America and the Middle East and Africa present different challenges and opportunities. Infrastructure variability, import dependency, and climatic conditions influence coolant specifications. In hotter climates, heat transfer efficiency is paramount, while in regions with long supply chains, storage stability and shelf life become critical purchasing criteria. A successful global strategy requires recognizing that a single product portfolio cannot satisfy the disparate needs of these diverse markets without local adaptation and robust distribution partnerships.
Competitive Landscape: Giants and Specialists
The competitive environment is characterized by a mix of global chemical giants, oil majors with extensive lubricant portfolios, and specialized manufacturers focusing on heavy-duty performance. The market concentration indicates a moderately consolidated landscape, where a few key players command significant influence, but there remains ample room for specialized entrants who can offer superior technical support or niche formulations.
Leading chemical and energy companies are leveraging their vertical integration to secure supply chains and innovate formulations. Companies such as BASF SE and ExxonMobil Corporation are prominent figures, utilizing their extensive R&D capabilities to develop coolants that meet the rigorous demands of heavy-duty diesel and alternative fuel engines. BASF, with its strong heritage in chemical synthesis, supplies ethylene glycol-based and advanced formulations that cater to extended-life requirements. ExxonMobil, through its Mobil Delvac brand, integrates coolant solutions into a broader heavy-duty engine care portfolio, appealing to fleets that prefer a single vendor for fluids.
Similarly, Chevron Corporation and Shell plc maintain strong positions through established brand equity in the lubricant sector. Chevron's Delo line and the joint venture Arteco provide dedicated solutions for on-road and off-road applications, while Shell's Rotella ELC HD targets the growing diversity of engine fuels, including natural gas and LNG. These oil majors benefit from existing relationships with fleet operators and service centers, allowing for effective cross-promotion and bundling of products.
TotalEnergies SE and BP p.l.c. also compete vigorously in this space, leveraging their global footprint to service commercial vehicle applications across multiple continents. BP's Castrol brand, for instance, provides another tier of premium formulation options. Beyond the oil majors, there are specialized entities that focus intensely on the coolant niche. Prestone Products Corporation, Old World Industries (PEAK brand), and Valvoline Inc. offer specialized heavy-duty formulations that emphasize ease of use, such as precharged systems or nitrited-free options designed to simplify maintenance protocols for fleet managers.
Furthermore, the landscape includes engine manufacturers and regional players who influence specifications. Cummins Inc., for example, provides coolants optimized specifically for its own heavy-duty diesel engines, creating a closed-loop ecosystem where compliance with engine maker specifications is a barrier to entry for generic products. Regional players like Sinopec Lubricant Company in China and Fuchs Petrolub SE in Europe ensure that local preferences and manufacturing capabilities are met, often competing on price and proximity to the end user.
Recent Strategic Movements and Product Innovation
The competitive intensity is visible in recent product launches and marketing campaigns observed throughout late 2025 and heading into 2026. Innovation is no longer static; it is accelerated by the need to differentiate in a market with high concentration among top players.
In October 2025, the PFX Group, representing a unified front of Prestone, Recochem, and KOST USA, made a significant appearance at the AAPEX show. Their unified presence and the launch of the campaign "The Future Runs on Prestone" signaled a strategic consolidation of marketing efforts to reinforce market leadership. This move highlights the importance of brand synergy and the showcasing of breakthrough products to capture attention in a crowded marketplace. Such campaigns are designed to remind fleet operators that coolant is a technology product, not a commodity.
Shell followed a product-centric strategy in early 2025, introducing the Shell Rotella ELC HD. This launch was timed to address the need for a single coolant solution that could handle heavy-duty diesel, gasoline, natural gas, and LNG engines. This versatility is a key value proposition for mixed fleets that are transitioning fuel types but want to minimize inventory complexity. By reducing the number of SKUs a fleet must manage, suppliers can lock in long-term contracts.
Later in the cycle, Old World Industries expanded its PEAK brand portfolio with additions like PEAK TITANIUM and PEAK ECOSHIELD. These launches demonstrate a continuous push to fill gaps in the product matrix, ensuring coverage for various vehicle classes and environmental conditions. The strategic intent here is clear: dominate the shelf space by offering a solution for every potential engine configuration and warranty requirement.
Regulatory and Environmental Tailwinds
No strategic analysis of this market is complete without addressing the regulatory framework. The commercial vehicle sector is under immense pressure to reduce emissions, and this pressure cascades down to fluid specifications. The U.S. EPA Phase 2 greenhouse gas emission standards for medium- and heavy-duty vehicles are a primary catalyst. These standards drive manufacturers to design engines that operate at higher temperatures and efficiencies, which in turn require coolants with enhanced thermal stability and corrosion protection.
Similarly, global standards such as Euro VI and Bharat Stage VI equivalents impose strict limits on pollutants. To meet these limits, engine aftertreatment systems are more sensitive to contamination. Coolants that degrade or introduce contaminants into the system can compromise emissions equipment, leading to warranty claims and regulatory non-compliance. Therefore, the requirement for superior corrosion inhibition and extended service intervals is not just a performance preference; it is a compliance necessity.
For market participants, this regulatory environment creates a moat around advanced formulations. Generic coolants that do not meet the latest specification updates risk obsolescence. The cost of failure—in terms of engine damage or regulatory fines—far exceeds the price differential of a premium coolant. This dynamic supports the pricing power of companies that can certify their products against the latest Original Equipment Manufacturer (OEM) standards.
Strategic Imperatives for 2026 Decision Makers
As organizations plan their capital and operational strategies for the remainder of the decade, several imperatives emerge from the data and competitive analysis. First, supply chain security for key raw materials is paramount. With volatility observed in glycol pricing across different regions, vertical integration or long-term supply agreements can protect margins. Relying solely on spot markets exposes manufacturers to price shocks that can erode profitability during peak demand seasons.
Second, technical differentiation must be communicated effectively. With market concentration indicating that top players hold significant share, new entrants or regional challengers must compete on more than price. They need to demonstrate clear value in terms of engine protection, ease of application (such as precharged units), or compatibility with mixed fleets. The recent marketing campaigns by major groups suggest that the industry is moving toward educating the buyer on the technological value of the fluid, rather than treating it as a simple replacement part.
Third, regulatory foresight is a competitive advantage. Companies that anticipate the next round of emission standards and develop coolants ready for those engines will secure early adoption by manufacturers and large fleets. Waiting for regulations to force the market shift often results in losing share to competitors who were prepared in advance.
Finally, data-driven decision-making is essential. The complexity of the market, with its various segments, regions, and product types, requires granular intelligence. Relying on high-level estimates is insufficient for pricing strategy, capacity planning, or M&A evaluation. Access to detailed historical data, precise forecast models, and competitor benchmarking is necessary to navigate the nuances of the commercial vehicle coolant market effectively.
Conclusion: The Value of Deep Intelligence
The Worldwide Commercial Vehicle Coolant Market represents a stable yet dynamic opportunity within the broader automotive and industrial fluids sector. It is a market where performance, regulation, and chemistry converge. For stakeholders looking to invest, expand, or optimize their position in 2026 and beyond, surface-level understanding is a liability. The interplay of raw material costs, OEM specifications, and regional regulatory pressures creates a complex web that requires expert navigation.
This market research report serves as a critical tool for decoding that complexity. It moves beyond general industry narratives to provide the specific data points and analytical frameworks necessary for robust strategic planning. While the macro trends indicate a positive outlook with steady growth through 2032, the real value lies in the detailed segmentation and competitive intelligence that allows for precise execution. Understanding who holds the market share, which technologies are gaining traction, and how raw material dynamics are shifting enables leaders to make informed choices that protect assets and capture revenue.
To fully leverage these insights for your organization's specific context, we invite you to access the complete dataset and detailed segmentation analysis available through our official channels. The depth of information contained within the full report exceeds the scope of this overview, offering the granular precision required for high-stakes decision-making in a competitive global environment.
For detailed analysis of this topic, please visit the official page: Worldwide Commercial Vehicle Coolant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Projects Worldwide Hot Melt Glue Bottle Sticker Labelling Machine Market to Reach $1.03 Billion by 2032, Driven by 5.12% CAGR and Asia Pacific's $318.63 Million Revenue Share in 2025
By PW Consulting, 2026-09-02
Strategic Intelligence in the Hot Melt Glue Bottle Sticker Labelling Machine Market: A 2026 Leadership Blueprint
Executive Overview
The global market for hot melt glue bottle sticker labelling machines has evolved into a critical infrastructure layer for modern packaging operations. As production lines face mounting pressure to deliver higher throughput, tighter label alignment, and seamless compliance with food safety standards, engineered adhesive labelling equipment has transitioned from a peripheral utility to a strategic capital investment. Our latest Worldwide Hot Melt Glue Bottle Sticker Labelling Machine Market research synthesizes historical performance, forward-looking projections, and competitive intelligence into a single decision-ready framework. This report is designed to help executive teams navigate equipment selection, capacity planning, and supplier partnerships with precision during a period of sustained industrial modernization.
Worldwide Hot Melt Glue Bottle Sticker Labelling Machine Market
The market trajectory over the past half-decade reflects a steady expansion anchored in automation mandates, beverage volume growth, and the broader shift toward wrap-around label architectures that enhance shelf presence while maintaining operational efficiency. Forward-looking projections through the early 2030s indicate continued value creation, albeit with intermittent normalization phases that reward manufacturers who align procurement cycles with technology refresh windows. By examining the interplay between machine architecture, end-use demand, and raw material economics, this analysis provides the contextual depth required to evaluate long-term equipment roadmaps rather than reactive purchasing decisions.
Worldwide Hot Melt Glue Bottle Sticker Labelling Machine Market
Market Architecture and Growth Trajectory
Historical revenue data from the early 2020s establishes a clear baseline for understanding how this equipment segment has matured under varying macroeconomic conditions. Total market revenue moved from a mid-2020 starting point into a pronounced acceleration phase during the post-pandemic recovery window, as packaging facilities prioritized line upgrades to reduce manual intervention and improve label consistency. The market crossed into new revenue thresholds by the mid-2020s, reflecting sustained capital expenditure in beverage and food processing environments where high-speed labelling is now a baseline expectation rather than a premium feature.
Worldwide Hot Melt Glue Bottle Sticker Labelling Machine Market
Our forecast horizon extends through the early 2030s and maps a compound annual growth rate of approximately 5.12 percent, indicating resilient demand drivers even as equipment supply chains normalize and procurement cycles become more disciplined. The projected revenue path demonstrates a gradual but confident upward slope, with moderate market adjustments along the way that typically coincide with fleet renewal cycles, regional capacity rebalancing, and shifting preference toward modular labeling stations. For leadership teams evaluating multi-year capex plans, this growth profile supports phased investment strategies rather than single-point procurement, especially in facilities that must balance throughput gains with maintenance overhead and adhesive consumption efficiency.
The revenue architecture also emphasizes the importance of total cost of ownership thinking. While sticker price comparisons remain common in early-stage sourcing, operational outcomes such as label waste reduction, glue application precision, changeover speed, and compatibility with existing conveyor ergonomics increasingly determine which platforms deliver durable returns. This research situates those operational variables within a broader market context so that engineering, procurement, and operations leaders can evaluate equipment proposals against realistic productivity benchmarks.
Regional and Application Demand Layers
Demand across the hot melt bottle labelling equipment space is shaped by distinct regional manufacturing intensities and application-specific throughput requirements. Asia Pacific continues to represent the most substantial revenue contribution, driven by concentrated beverage production, expanding FMCG packaging capacity, and sustained investment in high-speed line modernization. Europe maintains a strong second position, supported by established industrial ecosystems, rigorous packaging standards, and a mature base of equipment integrators that serve both domestic producers and export-oriented facilities. North America contributes meaningful demand as well, particularly in markets where beverage innovation, retail shelf competition, and traceability expectations push manufacturers toward more precise labelling automation. Latin America and the Middle East and Africa collectively represent growing demand corridors, often characterized by selective modernization projects, import substitution initiatives, and incremental capacity additions in beverage and household product packaging.
Application-driven demand provides another essential lens for understanding where labelling machine investments generate the strongest operational justification. Beverage packaging remains the dominant use case, reflecting the continuous pressure to improve label finish quality, manage high line speeds, and maintain adhesive performance on varied bottle substrates such as PET, glass, and specialized containers. Food processing follows as a significant downstream segment, where hygiene, traceability, and rapid format changeovers influence equipment specification. Personal care and cosmetics represent a more specialized demand layer, where brand presentation, label conformity, and small-batch flexibility can matter as much as raw speed. Household chemicals and pharmaceutical applications contribute additional demand, each bringing distinct compliance considerations and container geometry challenges that affect glue application strategy, label tension control, and reject handling.
Because these demand layers interact differently across regions and production scales, a single procurement template rarely fits all facilities. The report maps these layers into practical evaluation criteria so that planning teams can align machine type selection, line integration scope, and adhesive compatibility with the specific throughput profile of their product portfolio.
Machine Typology and Operational Fit
Two machine architectures dominate the hot melt glue bottle sticker labelling landscape, each serving distinct production philosophies. Rotary labelling machines account for the larger revenue share, reflecting their suitability for continuous high-speed operations, consistent wrap-around application, and integration into fully automated packaging lines. Their design orientation favors throughput stability, repeatable label positioning, and efficient handling of reel-fed or pre-cut label formats depending on the station configuration. In environments where bottle volumes are high and format variation is moderate, rotary systems often provide the most direct path to scaling output without sacrificing label placement accuracy.
Linear labelling machines represent a complementary but strategically important share of the market. They are particularly relevant in facilities that prioritize flexibility, lower initial footprint, or frequent changeovers among container sizes and label formats. Linear configurations can be advantageous in mid-volume production settings, pilot lines, and operations where product mix variability is a defining characteristic. Their value proposition often centers on adaptability, easier access for maintenance tasks, and simpler integration into existing conveyor layouts that may not support rotary indexing at the same mechanical complexity level.
Selecting between rotary and linear platforms is rarely a question of absolute superiority. Instead, it requires matching machine topology to line architecture, container geometry, adhesive behavior, and expected production cadence. The report examines these trade-offs through an operational lens, helping decision-makers compare not only theoretical speed ratings but also changeover duration, label registration consistency, glue consumption patterns, and downstream quality control implications.
Supply Chain Economics and Input Market Signals
Adhesive input economics play a meaningful role in the operating economics of hot melt labelling systems. Hot melt adhesives used in bottle labeling, particularly EVA-based formulations, have maintained average price levels in the range of approximately 2,400 to 2,700 dollars per metric ton as of mid-2025. While equipment selection is often evaluated on mechanical performance, ongoing adhesive procurement costs influence total operating expense and can affect the relative attractiveness of different application methods, nozzle configurations, and glue management systems. Facilities that track adhesive usage closely often gain an advantage by optimizing application thickness, reducing waste from mislabels, and aligning glue temperature control with container throughput.
Broader packaging consumption trends also reinforce the strategic relevance of this equipment category. The packaging segment accounts for the largest share of hot melt adhesive consumption, estimated at roughly 35 to 38 percent in 2025, with labeling and carton sealing among the principal drivers. This structural demand supports continued interest in labelling equipment that can perform reliably under sustained production schedules while minimizing rework. For procurement teams, that means machine uptime, adhesive compatibility, and ease of cleaning or maintenance are not secondary concerns; they are integral to the cost structure of the labelling operation itself.
In addition to material costs, regulatory and traceability pressures continue to shape equipment specification. Automation in labeling equipment supports compliance with food safety regulations and traceability requirements in the beverage and food packaging industries. As a result, many buyers now evaluate labelling machines not only for speed and finish quality, but also for integration with line-level data capture, reject management, and inspection workflows that help maintain documentation and reduce risk in sensitive product categories.
Competitive Field and Strategic Positioning
The competitive landscape in hot melt glue bottle sticker labelling equipment is shaped by a mix of specialized labelling manufacturers, broader packaging line providers, and regional equipment houses that serve high-volume beverage and container production. Understanding how these players differ in technology focus, application coverage, and service model is essential for building a resilient sourcing strategy.
P.E. Labellers S.p.A., based in Porto Mantovano, Italy, offers precut hot melt machines and stations as well as roll-fed solutions for wrap-around labeling on bottles and containers using hot melt glue technology. The company’s presence at major packaging events in 2026, including WARSAK PACK and INTERPACK, highlights continued emphasis on flexible labelling machines and hot melt stations, signaling active engagement with customer demand for adaptable labelling configurations.
Krones AG, headquartered in Neutraubling, Germany, provides hotmelt labeling technology including Contiroll for wrap-around reel-fed labels and Canmatic for high-flexibility wrap-around labeling with hotmelt on bottles. As a provider with broad packaging line expertise, Krones positions its labelling technology within a wider system integration context, which can be relevant for facilities seeking coordinated equipment ecosystems rather than standalone labelling units.
Zhangjiagang Sunswell Machinery Co., Ltd., located in Zhangjiagang, Jiangsu, China, manufactures hot melt glue labeling machines for wrap-around plastic or paper labels on PET bottles, glass bottles, and other containers, with high-speed capabilities up to 36,000 bph. This high-throughput positioning makes the company relevant for large-scale beverage lines where speed and container variety must be managed concurrently.
Accutek Packaging Equipment Companies, Inc., based in Vista, California, USA, specializes in hot glue labelers including Labelette HG, SG, and RL-HG 540 models for applying paper or plastic labels to cylindrical containers and bottles using hot melt glue. Its focus on cylindrical container labeling and modular model options supports operations that need targeted solutions for specific bottle profiles and label materials.
TECH-LONG, based in China, produces hot melt adhesive labeling machines for bottles and containers as part of its liquid packaging equipment lineup. Its broader liquid packaging context can be advantageous for buyers who want labelling equipment aligned with filling, capping, and downstream handling processes.
Higee Machinery, also from China, offers rotary and other hot melt glue labeling machines, including BOPP roll feed configurations for mineral water bottles and high-speed production lines. This positions the company as a relevant source for operators focused on continuous water and beverage packaging with roll-fed label supply strategies.
Beyond equipment suppliers, adhesive technology providers also influence machine performance and application viability. TEX YEAR Adhesive Technologies Corp. showcased hot melt adhesive solutions at Pack Expo Las Vegas in September 2025, including clean recycle bottle labeling applications compatible with labeling machines. This kind of cross-sector engagement underscores how adhesive formulation, bottle substrate characteristics, and labelling equipment behavior must be evaluated together to achieve reliable performance, especially when recyclability and surface cleanliness become procurement priorities.
Market concentration data indicates that competitive dynamics remain moderately fragmented at the top while still reflecting meaningful consolidation among leading suppliers. This structure suggests that buyers can often find differentiated offerings across specialized and integrated providers, but should also assess supplier stability, aftermarket support, and technology roadmap alignment when making long-term equipment commitments.
Recent industry activity reinforces the sense that labelling technology continues to evolve through trade engagement, application demonstrations, and incremental product refinement. Participation in major exhibitions, live demonstrations of hot melt stations, and focus on flexible labelling machines signal that suppliers are investing visibly in customer-facing validation of performance claims. For buyers, these events provide opportunities to compare application behavior under realistic throughput conditions and to question how different machine designs handle label waste, glue management, and format switching.
Operating Pressures That Shape Equipment Decisions
Several interconnected trends continue to influence how manufacturers evaluate hot melt glue labelling machines. Demand for high-speed, precise labeling solutions in the food and beverage sector is being driven by the need for efficient packaging lines and brand differentiation on bottles. This dual pressure means that equipment must deliver both operational efficiency and visual quality, since label placement, adhesion consistency, and surface finish increasingly contribute to shelf impact and consumer perception.
At the same time, automation in labeling equipment supports compliance with food safety regulations and traceability requirements in the beverage and food packaging industries. Facilities that operate in regulated environments therefore consider not only mechanical reliability but also the ability to integrate labelling stations into broader quality control and data workflows. This expands the evaluation criteria beyond the labelling machine itself to include compatibility with inspection systems, reject routing, and production data capture.
Raw material pricing and adhesive consumption patterns add another layer of operational realism. Because packaging remains the largest consumption segment for hot melt adhesives, labelling equipment that supports efficient application and reduced mislabel waste can materially affect ongoing operating costs. Leadership teams benefit from evaluating glue management capabilities, temperature control, and nozzle or station design as part of the broader cost equation, rather than treating adhesive expense as an externality.
These dynamics collectively suggest that the most successful procurement strategies will be those that treat labelling equipment as a production system component rather than an isolated machine purchase. That means aligning equipment choices with container mix, throughput targets, regulatory exposure, adhesive procurement strategy, and the anticipated pace of line modernization over the forecast period.
What the Report Delivers for Decision-Makers
This research is structured to support practical decision-making across strategy, procurement, operations, and market development functions. Rather than providing only macro-level commentary, the report moves into operational detail so that readers can translate market direction into actionable evaluation criteria. The core deliverables include:
- A consolidated market size and forecast framework that places historical performance and forward projections in one view, enabling multi-year planning and scenario comparison.
- Segment-level Market split analysis covering machine type, application, and regional demand patterns so that teams can identify where growth momentum is strongest and where equipment fit must be tailored to local production realities.
- Competitive profiling of key equipment providers and relevant adhesive technology participants, including headquarters context, solution focus, and recent trade activity that signals current commercial emphasis.
- Market concentration context to help assess competitive intensity, supplier selection options, and the implications of a moderately consolidated leadership tier.
- Industry dynamics coverage that links adhesive input pricing, packaging-driven adhesive consumption, traceability and food safety compliance, and high-speed brand differentiation into a single operating environment assessment.
- Practical decoding of rotary versus linear machine fit, with attention to throughput, changeover, label format strategy, container geometry, and integration requirements.
- Forecast-period considerations that help leadership teams anticipate fleet renewal timing, capacity rebalancing, and the influence of intermittent market normalization on procurement scheduling.
The report also connects these elements to decision workflows. For capital planning teams, the emphasis is on aligning equipment selection with line architecture and total cost of ownership. For sales and business development teams, the value lies in understanding where demand is expanding and which machine architectures and application segments offer the most relevant entry points. For operations leaders, the focus shifts to glue management, label quality consistency, uptime, and integration with inspection or traceability workflows. By bridging these perspectives, the research is intended to reduce the gap between market intelligence and on-the-ground equipment decisions.
How to Use This Intelligence in 2026 Planning
The forecast period through the early 2030s presents a planning environment defined by steady structural demand, evolving production standards, and a competitive supplier base that continues to refine hot melt labelling solutions for high-speed and flexible packaging scenarios. In this setting, market intelligence is most valuable when it helps organizations anticipate, rather than react to, equipment lifecycle decisions.
For manufacturers scaling beverage, food, personal care, household chemical, or pharmaceutical packaging lines, the strategic question is not simply whether to invest in hot melt labelling capability, but how to sequence that investment so it supports current throughput needs while preserving flexibility for future container mixes and regulatory expectations. For equipment distributors, system integrators, and service providers, the opportunity lies in mapping supplier capabilities to regional demand patterns and in framing solutions around operational outcomes that resonate with plant-level priorities. For adhesive and materials stakeholders, the relevant insight is how labelling equipment design and application behavior influence consumption patterns and compatibility with emerging bottle and label formats.
Because the market combines clear growth momentum with periodic normalization and differentiated regional application demand, precise segment-level intelligence is essential for avoiding overgeneralization. A market-wide growth figure can justify strategic attention, but successful execution depends on understanding which machine types, applications, and regional demand layers are most relevant to a specific business unit or production site.
Closing Perspective
The Worldwide Hot Melt Gluie Bottle Sticker Labelling Machine market is positioned at the intersection of packaging automation, brand presentation, and operational compliance. Its growth reflects broader industrial priorities: faster lines, more consistent label application, stronger traceability, and tighter control over material usage. Yet the real value for leadership teams lies in converting that broad trajectory into concrete equipment strategies that fit specific container profiles, production cadences, and cost structures.
This report is designed to provide that strategic clarity. It combines market sizing, segmentation, competitive context, input-market signals, and recent industry activity into a unified analytical framework that supports capital planning, supplier evaluation, and regional demand assessment. To access the complete segmentation data, company profiles, forecast breakdowns, and operational evaluation tables that underpin these conclusions, please visit the full report page for the Worldwide Hot Melt Glue Bottle Sticker Labelling Machine Market. The detailed intelligence there is structured to help your team move from market overview to decision-ready evidence with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Hot Melt Glue Bottle Sticker Labelling Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Worldwide Achromatic Waveplate Market to Grow at 6.81% CAGR Through 2032 from 2025 Base Year Size of USD 226.8 Million
By PW Consulting, 2026-09-02
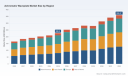
Strategic Intelligence Inside the Worldwide Achromatic Waveplate Market Through 2032
The global achromatic waveplate market has entered a phase of steady structural expansion, driven by converging demands across photonics research, life sciences instrumentation, industrial metrology, and advanced defense systems. For executive teams mapping capital allocation, procurement strategy, and R&D roadmaps through 2032, the timing of this market inflection matters. A comprehensive worldwide assessment of the achromatic waveplate sector is no longer a nice-to-have reference document. It is a decision-grade intelligence asset that connects historical trajectory, medium-term forecasts, and competitive positioning into a single operational framework.
Worldwide Achromatic Waveplate Market
This overview outlines what the latest market research delivers, why its architecture matters for 2026 planning cycles, and how procurement leaders, optical engineers, and strategy teams can use the findings without reading a report cover to cover. The goal is not to repeat every number here. The goal is to show the analytical depth, segmentation logic, and competitive context that make the full study actionable, while reserving the most precise breakdowns for the complete publication.
Worldwide Achromatic Waveplate Market
A Market Built on Precision, Bandwidth, and Material Constraints
Achromatic waveplates occupy a specialized but indispensable position inside optical systems. By compensating for polarization shifts across wide spectral ranges, they enable repeatable performance in laser delivery, interferometric measurement, biomedical imaging, and quantum-optics testbeds. Yet the category is not monolithic. The balance between cemented and air-spaced designs, the choice between polymer and crystalline substrates, and the tolerance stack-up required by each end-use application all shape cost structures, lead times, and adoption rates.
Worldwide Achromatic Waveplate Market
Recent industry signals point to a clear recognition of these trade-offs. Material science notes continue to emphasize that quartz and magnesium fluoride-based birefringent crystals dominate fabrication where dispersion matching is critical and low retardance error across broad bandwidths is required. At the same time, polymer-based options offer practical advantages for certain visible-to-NIR applications, but their continuous-wave power limits remain a defining constraint compared with crystalline alternatives. Standardization activity adds a further layer of discipline, with substrate surface figure tolerances and retardance uniformity specifications now embedded in the quality expectations of OEM optics and system integrators.
These dynamics create a market that grows not simply because more instruments are being sold, but because specifications are becoming stricter, spectral coverage requirements are widening, and power handling limits are redefining where each technology can be deployed. The result is a market structure where differentiation is earned through engineering precision, coating quality, and application-specific thermal and mechanical robustness.
From Historical Momentum to 2032: What the Trajectory Tells Decision-Makers
The publicly visible top-line trajectory tells a story of consistent expansion with a forecast interval that rewards early positioning. Historical revenue progression across the 2020–2025 window shows steady year-over-year growth, culminating in a 2025 baseline that establishes a materially higher starting point for the forecast decade. From that base, the forward outlook extends through 2032, with the compound annual growth rate signaling durable mid-single-digit momentum rather than a short-lived spike.
For strategy teams, this matters because the market is large enough to justify dedicated supply and engineering attention, yet specialized enough that late movers can lose access to preferred configurations, lead times, and qualified supplier relationships. A 2026 planning horizon is especially important. It sits at the intersection of post-pandemic instrumentation refresh cycles, expanding life-sciences optical workflows, and renewed attention to laser-based manufacturing inspection. Companies that wait until demand is fully visible in their own order books may find themselves reacting to pricing pressure or allocation risk rather than shaping it.
Importantly, the forecast is not a single curve. It reflects how regional demand concentration, application mix, and type preference interact over time. The full study unpacks these interactions in detail. What can be said here is that the overall growth path is supported by a market structure where large segments coexist with highly specialized niches, and where product selection often determines whether a buyer remains in a standard catalog environment or moves into custom engineering arrangements.
What the Report Delivers: An Operational Map, Not Just a Spreadsheet
A market study earns its place on a strategy team’s desk when it translates macro data into decision logic. The achromatic waveplate research is structured to do exactly that. It starts with the baseline and forecast figures, then connects them to segmentation pathways that reveal where growth concentrates, where specifications diverge, and where supplier positioning matters most.
The report covers the following operational dimensions:
- Market sizing anchored to a clearly defined historical window and extended through the forecast period, enabling year-by-year comparison for budgeting and scenario planning.
- Segmentation by region, type, and application, organized to show where revenue concentrates and how buyer requirements differ across end-use environments.
- A competitive landscape that places major manufacturers in context, including geographic footprint, product focus, and the kinds of technical differentiation that shape procurement choices.
- Industry context elements that influence purchasing, qualification, and design decisions, such as material constraints, manufacturing limits, standardization expectations, and control-related considerations for specialized end uses.
- Recent company developments that indicate where product roadmaps are moving, including expanded wavelength coverage, improved thermal stability, and new retardance uniformity claims.
This structure matters because optical component buyers rarely make decisions on price alone. They evaluate thermal behavior, spectral coverage, coating performance, mechanical tolerances, and whether a supplier can support custom or high-power variants when standard options fall short. A market research report that captures these decision drivers is far more useful than one that only tracks aggregate revenue.
Segmentation as a Procurement and Innovation Compass
Segmentation is where insight becomes operational. In the achromatic waveplate category, the three principal segmentation axes—region, type, and application—each answer a different strategic question.
Regional segmentation reflects where demand is already institutionalized and where growth is likely to accelerate as local photonics ecosystems mature. It also highlights how supply chains, export considerations, and customer qualification practices vary from one geography to another. That variation matters for manufacturers planning production footprint, inventory placement, and service coverage, and it matters for buyers assessing lead-time risk and regional availability.
Type segmentation separates cemented achromatic waveplates from air-spaced designs. This distinction is not simply a catalog classification. It speaks to assembly method, alignment stability, bandwidth behavior, and suitability for different operating environments. The balance between these two types reveals how much of the market is satisfied by standardized high-volume building blocks versus designs where spacing and mechanical architecture are part of the performance envelope.
Application segmentation shows how demand splits across optical research and laser systems, medical and life sciences, industrial inspection and metrology, and defense and aerospace. Each segment imposes its own priorities. Research and laser environments often emphasize spectral breadth, repeatability, and interoperability with configurable setups. Life sciences applications may prioritize consistency, ease of integration, and compatibility with imaging or diagnostic platforms. Industrial metrology depends on ruggedness, calibration stability, and sustained performance under repeated inspection cycles. Defense and aerospace requirements can add additional layers of qualification, traceability, and, in certain cases, control-related scrutiny.
The full report develops these segments in depth. That depth is valuable because the same aggregate growth number can conceal very different buying behavior across segments. A procurement leader needs to know not only that the market is expanding, but which applications are expanding fastest, which designs are becoming more common in those applications, and where the bottleneck risks lie.
Competitive Landscape: Differentiation, Not Just Density
The competitive set in this market includes manufacturers with distinct technical identities. Some specialize in true zero-order designs using quartz and mica for broadband polarization control from ultraviolet to near-infrared wavelengths. Others focus on polymer-based and crystalline options optimized for visible-to-NIR and telecommunications bands with strong retardance uniformity. Additional players bring Fresnel rhombs, multi-order waveplates, and custom-engineered solutions into laser systems and interferometry. A few concentrate on extended spectral coverage and custom designs for higher-wavelength applications, while others supply coated zero-order components aimed at ultrafast laser and microscopy workflows.
This diversity is a practical advantage for buyers, but it also means that supplier selection is a strategic choice rather than a commodity transaction. The market does not reward uniform competition; it rewards specialization. Companies that can demonstrate measured control over retardance error, thermal stability, surface figure tolerance, and power handling are positioned to command preference in demanding applications. Companies that compete primarily on catalog breadth may serve broader but less performance-intensive demand.
Recent developments reinforce this competitive logic. One manufacturer introduced achromatic half-waveplates for a specific wavelength range with improved temperature stability, a move that directly addresses integration risk in environments where thermal drift can degrade optical performance. Another showcased broadband achromatic retarders at a major photonics event with demonstrations tied to quantum computing, signaling where next-generation application pull may emerge. A third released polymer-based achromatic waveplates with tight retardance variation claims for visible-to-NIR use, expanding the practical range of standardized options for visible-spectrum workflows.
These product movements matter because they indicate where the market is being shaped in real time. For strategy and procurement teams, they are early indicators of supply direction, technical emphasis, and potential future lead-time dynamics. The full report places these developments within a broader competitive context, including how major players are differentiated by geography, product philosophy, and application focus.
Market Structure and What Concentration Implies
Concentration metrics provide a useful lens on how consolidated or distributed the market really is. A market with meaningful but not extreme concentration tends to offer buyers a workable set of alternative suppliers while still rewarding scale, technical consistency, and established qualification pipelines. That structure is visible in the broader optical components space, where a handful of established manufacturers capture a substantial share, but specialized niches remain open to focused competitors.
For buyers, this balance creates both opportunity and caution. Opportunity exists because multiple credible sources can often support standard requirements, reducing single-source dependency for many applications. Caution is warranted because the suppliers that dominate the higher-specification segments often control the designs, process know-how, and qualification history that demanding end uses require. The full study maps this structure in greater detail, giving teams a clearer sense of where competition is genuine and where qualification barriers raise the effective entry threshold.
Demand-Side Forces Shaping 2026 and Beyond
Several forces are likely to influence purchasing behavior and product strategy as the forecast period unfolds. The continued spread of laser-based instrumentation across research and industrial settings supports recurring demand for polarization control components that perform reliably across wide spectral ranges. Expansion in life sciences and medical optics adds another layer of demand, especially where imaging, diagnostic, and analytical systems require consistent optical behavior with low maintenance burden.
Industrial inspection and metrology represent a different demand profile. Here, the emphasis is often on repeatability under production conditions, environmental resilience, and integration with automated measurement workflows. As manufacturing quality expectations rise, the need for stable optical components that do not become the limiting factor in measurement precision can grow steadily.
Defense and aerospace applications add additional complexity. In those environments, performance requirements, qualification standards, and control-related considerations may influence not only component choice but also sourcing patterns and documentation expectations. Buyers in those segments often evaluate suppliers not only on specification sheets, but on traceability, process discipline, and the ability to support controlled or specialized deployments when applicable.
All of these forces point in the same direction: demand is expanding, but it is also becoming more specification-sensitive. That is exactly why broad market sizing must be paired with segmentation and competitive context to be useful.
How Strategy, Procurement, and R&D Teams Can Use the Report
The value of a market research report is highest when it is used to answer concrete questions. For strategic planning, the study can inform whether to treat the achromatic waveplate category as a steady-supply input, a technology-watch area, or a procurement domain where supplier development and dual-sourcing deserve active attention. For procurement, it can help separate applications where standard components are sufficient from those where custom engineering, enhanced coatings, or higher power handling should be negotiated early. For R&D and optical engineering teams, it can provide a market-backed view of where material and design constraints are most likely to shape product selection.
A practical approach is to use the report as a framework for three decisions:
- Where to standardize: Identify segments and applications where catalog-grade achromatic waveplates can reliably meet requirements without unnecessary customization.
- Where to qualify: Determine which end uses demand tighter specification control, higher power tolerance, or more demanding thermal and mechanical stability, and align supplier qualification accordingly.
- Where to watch: Track recent product introductions and application demonstrations that indicate where specifications, wavelength coverage, and performance claims are evolving fastest.
This approach reflects the report’s broader intent: to give teams a structured way to interpret market size, segmentation, and competitive behavior without forcing every decision into a single generic narrative.
Why the Full Study Matters Now
The worldwide achromatic waveplate market is moving with enough consistency, technical specificity, and application diversity that informed teams need more than a headline figure. They need a mapping of where growth is concentrated, how type and application choices shape demand, which suppliers are differentiating themselves through engineering and product strategy, and which industry constraints—material limits, manufacturing bottlenecks, tolerance standards, and control considerations—are influencing real buying behavior.
Because the category combines broad enabling use with narrow performance requirements, the difference between a good decision and a weak one often comes down to knowing which segment you are really operating in. That is the level of detail this research is built to support.
Next Steps for Decision-Makers
If your team is responsible for optical component sourcing, photonics investment planning, or technology roadmap alignment in 2026, the full market research provides the segmentation, competitive context, and forward trajectory needed to move beyond generic assumptions. It is designed to help you connect market growth with procurement strategy, supplier evaluation, and application-specific specification planning in one integrated view.
To access the complete market size breakdowns, segmentation detail, competitive profiles, and supporting industry context, refer to the full Worldwide Achromatic Waveplate Market study and review the sections most relevant to your operational priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Achromatic Waveplate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Global EVA Infusion Bag Market to Reach 1.44 Billion USD by 2032 Driven by 7.06 Percent CAGR
By PW Consulting, 2026-09-02
Strategic Intelligence for the Healthcare Supply Chain: The Worldwide Ethylene-vinyl Acetate Infusion Bag Market Outlook
The global medical device landscape is undergoing a significant material transformation. As healthcare providers increasingly prioritize patient safety and biocompatibility, the shift away from traditional polyvinyl chloride (PVC) components toward advanced polymers has become a central theme in infusion therapy. Within this transition, Ethylene-vinyl Acetate (EVA) infusion bags have emerged as a critical component for sterile compounding, parenteral nutrition, and specialized drug delivery. For executives navigating the complex interplay of regulatory compliance, supply chain resilience, and clinical demand, understanding the trajectory of this market is not merely an operational task—it is a strategic imperative.
Worldwide Ethylene-vinyl Acetate (EVA) Infusion Bag Market
PW Consulting is proud to introduce our latest comprehensive research initiative: the Worldwide Ethylene-vinyl Acetate (EVA) Infusion Bag Market study. This report is designed to equip stakeholders with the actionable intelligence required to make informed decisions throughout the forecast period extending to 2032. By analyzing historical performance from 2020 through the base year of 2025, this study provides a robust framework for projecting future growth, identifying competitive threats, and capitalizing on emerging opportunities in the non-PVC medical bag segment.
Worldwide Ethylene-vinyl Acetate (EVA) Infusion Bag Market
Market Trajectory and Macro Economic Indicators
The financial architecture of the EVA infusion bag market demonstrates a clear upward trajectory, reflecting the broader adoption of safer medical materials across global health systems. According to our analysis, the market generated substantial revenue in the base year of 2025, building upon a consistent growth pattern observed over the previous half-decade. The data indicates that the industry has moved beyond initial niche adoption into a phase of mainstream integration within hospital pharmacies and compounding centers.
Worldwide Ethylene-vinyl Acetate (EVA) Infusion Bag Market
Our forecast models project a steady compound annual growth rate through the end of the decade. This growth is not merely a function of inflation but is driven by tangible increases in healthcare consumption, specifically in the areas of total parenteral nutrition and specialized drug administration. The revenue projections suggest that by the early 2030s, the global market value will have expanded significantly compared to historical baselines. For strategic planners, this implies that demand for EVA solutions will continue to outpace general medical supply growth, necessitating proactive capacity planning and supply chain diversification.
The historical data reviewed in the study highlights a period of consolidation and expansion. From 2020 to 2025, the market saw fluctuations that correlated with global healthcare disruptions and subsequent recovery phases. However, the long-term trend remains positive. Stakeholders reviewing the complete financial tables in our full report will observe specific revenue milestones reached in each forecast year, providing a granular view of when market thresholds are expected to be crossed. These figures are essential for budgeting, long-term contracting, and investment justification.
Segmentation Dynamics and Technical Specifications
Understanding the market requires a deep dive into how products are categorized and utilized. The EVA infusion bag market is not monolithic; it is defined by specific technical configurations that serve different clinical needs. Our research dissects the market based on chamber architecture and application verticals, revealing distinct consumption patterns that influence procurement strategies.
Chamber Configuration
A primary differentiator in this market is the design of the infusion container. The industry is currently divided between single-chamber and multi-chamber solutions. Single-chamber bags are predominantly used for compounding sterile preparations where flexibility in volume is required. These are often utilized for large-volume solutions and specific nutrient admixtures. Conversely, multi-chamber bags offer a pre-mixed or dual-compartment design that simplifies the preparation process for total parenteral nutrition, reducing the risk of contamination during mixing. Our analysis indicates that both segments hold significant market share, but their growth drivers differ. Single-chamber solutions are often favored for their adaptability in hospital pharmacy compounding, while multi-chamber systems are critical for standardized nutrition delivery in acute care settings.
Application Verticals
The demand for EVA bags is closely tied to the therapeutic areas they serve. The report segments the market by application, focusing heavily on Total Parenteral Nutrition, Chemotherapy, and Antibiotics and Specialized Drugs. Total Parenteral Nutrition remains a cornerstone of demand, as EVA materials provide the necessary chemical resistance and flexibility for lipid and amino acid storage. In oncology, the requirements are even more stringent. Chemotherapy applications demand materials that are not only sterile but also capable of handling hazardous drug compounds without leaching plasticizers. The segment dedicated to antibiotics and specialized drugs further underscores the versatility of EVA film in maintaining drug stability. Detailed analysis of volume distributions across these applications is available in the full dataset, allowing clients to assess which therapeutic areas offer the highest growth potential for their specific product portfolios.
Global Regional Performance
Geographic diversity plays a crucial role in the supply and demand balance of EVA infusion bags. Our study maps the market across key regions, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique regulatory environments, healthcare infrastructure levels, and procurement behaviors.
Developed markets in North America and Europe currently represent significant portions of the global revenue, driven by high adoption rates of non-DEHP and latex-free products. Regulatory pressures in these regions have accelerated the phasing out of PVC components, creating a sustained demand for EVA alternatives. Meanwhile, the Asia Pacific region is characterized by rapid healthcare infrastructure expansion and increasing manufacturing capabilities. This region is not only a growing consumption market but also a hub for production, influencing global pricing dynamics. Emerging markets in Latin America and the Middle East and Africa are also showing incremental growth as healthcare access improves and standards of care evolve.
It is important to note that while regional revenue contributions vary, the strategic importance of each region differs based on a company's supply chain footprint. For manufacturers, understanding where production costs are optimized versus where demand is highest is key to margin management. The full report provides a detailed breakdown of regional market values without compromising the competitive sensitivity of specific local pricing data.
Competitive Landscape and Key Industry Players
The market is characterized by a mix of global medical device giants and specialized manufacturers focused on polymer solutions. Market concentration metrics indicate a moderately consolidated environment, where top players hold significant influence but leave substantial room for specialized competitors. Our report profiles key companies that are setting the standard for quality, compliance, and innovation in the EVA space.
Baxter International Inc.
Headquartered in Deerfield, Illinois, Baxter remains a dominant force in the infusion therapy sector. Their strategy involves offering compatible EVA empty bags for their ExactaMix and ExactaMix Pro compounders. These solutions range from 250 mL to 5000 mL, catering to sterile compounding of parenteral nutrition and large-volume solutions. A key strategic move by Baxter is the emphasis on non-DEHP, latex-free designs with photoprotective options validated for their compounders. In late 2024, Baxter released an updated sell sheet highlighting an expanded EVA bag portfolio, including photoprotective single-chamber bags compliant with USP <671>. This move underscores a strategy focused on supply resiliency through multiple manufacturers and ensuring compatibility with their existing compounding ecosystem.
B. Braun Medical Inc.
With headquarters in Melsungen, Germany, and a strong US presence in Bethlehem, Pennsylvania, B. Braun provides the Pinnacle line of single and dual-chamber EVA formulation containers. Their 3-in-1 mixing containers, available in capacities including 250 mL and 3000 mL, are optimized for TPN compounding. The company emphasizes a PVC/DEHP-free design that ensures safe mixing and delivery of amino acids and lipids. Their positioning reflects a commitment to safety and ease of use in clinical settings, targeting hospitals that prioritize integrated compounding systems.
The Metrix Company
Based in Dubuque, Iowa, The Metrix Company focuses on the Secure EVA line of 2-port and legless empty bags. These products range from 50 mL to 2000+ mL and are designed for compounding and admixture. By offering sterile, non-DEHP, and latex-free options with PVC ports and tubing configurations, Metrix serves a niche but vital segment of the market that requires customizable port configurations for specific pharmacy workflows.
AdvaCare Pharma
Operating with headquarters in Phoenix, Arizona, and manufacturing capabilities in China and India, AdvaCare Pharma produces medical-grade EVA infusion bags for fluid storage and administration. Their focus on ISO and CE-certified facilities highlights the importance of global compliance standards. AdvaCare emphasizes biocompatible, flexible designs tailored for global markets, positioning themselves as a reliable partner for international distribution and contract manufacturing.
Regional Specialists and Emerging Players
Beyond the multinational corporations, several regional players are shaping the market dynamics. Kapsam Health Products in Turkey offers transparent and light-protected dual-chamber variants for TPN, addressing specific regional needs for parenteral nutrition. CellBios Healthcare & Lifesciences in Chennai, India, supplies InfuLine EVA bags ranging from 50 mL to 5000 mL, supporting OEM partnerships and various port configurations, which highlights the growing manufacturing capacity in India. European suppliers such as Valmed and Haemotronic S.p.A. in Italy specialize in EVA bags for infusion and TPN applications, maintaining a strong presence in the non-PVC medical bag segment within Europe.
The competitive analysis in our full report goes beyond company profiles to examine recent developments, supply chain vulnerabilities, and partnership trends. For instance, understanding the implications of Baxter's 2024 portfolio update on supplier dependency is crucial for buyers seeking to negotiate contracts.
Industry Dynamics: Regulation, Materials, and Sterilization
The operational environment for EVA infusion bags is defined by strict regulatory frameworks and material science requirements. Manufacturers must navigate a complex landscape to ensure their products are viable for clinical use.
Regulatory Compliance and Safety
EVA infusion bags are commonly produced as non-DEHP, latex-free alternatives to PVC. Compliance with USP Class VI biocompatibility and ISO 10993 standards for biological evaluation is mandatory for market entry in many jurisdictions. These regulations ensure that the materials do not elicit adverse biological responses when in contact with pharmaceutical solutions. Our report details how different competitors meet these standards and the potential regulatory risks associated with non-compliance in key markets.
Material Advantages
Medical-grade EVA film is selected for its flexibility, clarity, chemical resistance, and lower risk of plasticizer leaching compared to PVC. These properties are critical for maintaining the integrity of sensitive drug formulations, particularly in chemotherapy and lipid-based nutrition. The material dynamics section of our study explores how film quality variations can impact shelf life, storage requirements, and clinical outcomes.
Sterilization Processes
EVA infusion bags support common sterilization methods including Ethylene Oxide (ETO), Gamma, or Steam. Final products are typically supplied sterile for single-use applications. The choice of sterilization method can influence production costs and supply chain logistics. For example, gamma sterilization requires specific infrastructure, while ETO involves aeration processes. Our analysis considers how these technical requirements affect manufacturer capabilities and lead times.
Usage Clarification
It is important for strategic purchasers to understand the specific role of EVA bags. They serve primarily as empty compounding containers or for specific TPN and chemotherapy delivery. They are not typically prefilled with standard IV solutions like saline or dextrose, which often use other materials. This distinction affects inventory management and procurement categories within hospital supply chains. Understanding this nuance prevents category management errors and ensures accurate forecasting.
Strategic Implications for 2026 and Beyond
As we move into the 2026 fiscal year, the implications of this market research extend across multiple functions of the enterprise. For procurement leaders, the data supports negotiations for long-term supply agreements, leveraging visibility into future demand spikes driven by aging demographics and increased chronic disease management. For product development teams, the segmentation data highlights opportunities to innovate around specific chamber types or port configurations that align with unmet clinical needs.
For investors and market analysts, the concentration metrics and company profiles provide a clear view of market barriers to entry and the competitive moats held by established players. The projected growth rate suggests that capital allocation toward EVA-specific manufacturing capabilities or distribution partnerships could yield significant returns. Furthermore, the regional breakdown allows multinational corporations to identify underpenetrated markets where local regulatory hurdles are being overcome.
Risk management is another critical area illuminated by this study. Supply chain disruptions in the medical device sector have highlighted the need for diversified sourcing. By understanding which companies supply which regions and how sterilization dependencies affect production, organizations can build more resilient supply networks. The report's insights into regulatory standards also help compliance teams anticipate future changes in material safety requirements, allowing for proactive adaptation rather than reactive compliance.
Conclusion and Access to Full Intelligence
The Worldwide Ethylene-vinyl Acetate Infusion Bag Market is at a pivotal juncture. The convergence of material science advancements, regulatory shifts toward non-PVC solutions, and growing clinical demand creates a robust environment for growth. However, navigating this landscape requires more than general industry knowledge; it demands precise data, detailed competitive profiling, and forward-looking forecasts.
PW Consulting's full market research report offers the depth required to transform these insights into action. While this overview highlights the macro trends, segmentation logic, and key players, the complete study contains detailed revenue tables, specific volume shares, granular regional breakdowns, and comprehensive strategic recommendations. These elements are essential for building robust business cases and securing stakeholder approval for strategic initiatives.
We invite industry leaders, procurement directors, and strategic planners to access the full report to unlock the complete dataset. By leveraging this intelligence, your organization can position itself to capitalize on the growth trajectory of the EVA infusion bag market, ensuring operational excellence and strategic advantage through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Ethylene-vinyl Acetate (EVA) Infusion Bag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports 7.42 Percent CAGR for Worldwide Retinal Vein Occlusion Therapeutics Market Growth from 2026 to 2032
By PW Consulting, 2026-09-02
Navigating the Retinal Vein Occlusion Therapeutics Market: Strategic Intelligence for 2026 and Beyond
Executive Perspective
As we navigate the fiscal year 2026, ophthalmology-focused organizations face a critical juncture in the retinal vein occlusion therapeutics landscape. The convergence of extended dosing regimens, regulatory approvals for higher-concentration formulations, and the early emergence of biosimilar competitors has fundamentally altered the competitive calculus. PW Consulting’s Worldwide Retinal Vein Occlusion Therapeutics Market study delivers a precision-engineered intelligence framework designed to support product strategy, commercial planning, and partnership evaluation across the forecast horizon of 2026 through 2032.
Worldwide Retinal Vein Occlusion Therapeutics Market
The market under analysis represents a specialized but rapidly evolving segment within intravitreal pharmacotherapy. Driven by aging demographics, improving diagnostic pathways, and a shifting standard of care toward durable vascular endothelial growth factor inhibition, the global revenue trajectory reflects both structural growth and episodic regulatory inflection points. Our latest publication synthesizes multi-year historical observation with forward-looking scenario modeling to equip decision-makers with actionable commercial context rather than isolated numeric snapshots.
Worldwide Retinal Vein Occlusion Therapeutics Market
Market Trajectory and Structural Expansion
The global market for retinal vein occlusion therapeutics has demonstrated consistent upward momentum across the historical observation window ending in 2025, with revenue measured in millions of U.S. dollars. The baseline trajectory reflects a compound annual growth rate of approximately 7.4 percent across the forecast period extending to 2032. This growth profile is not linear; it embeds periods of accelerated adoption following label expansions, regulatory clearances, and formulation upgrades, alongside intervals of pricing recalibration and payer-driven utilization management.
Worldwide Retinal Vein Occlusion Therapeutics Market
Historical revenue progression through the mid-2020s establishes a clear baseline of sustained commercial scaling. As the forecast phase begins in 2026, the revenue curve continues its upward arc, reflecting anticipated product cycle maturation, incremental indication support, and broader geographic penetration. Our analysis captures these inflection dynamics in granular time-series formats, allowing commercial teams to align procurement planning, sales force deployment, and market access negotiations with the rhythm of regulatory and reimbursement cycles rather than relying on static annual projections.
Importantly, the expansion narrative is shaped less by any single therapeutic breakthrough and more by cumulative shifts in treatment durability, patient compliance expectations, and payer tolerance for intravitreal intervention frequency. The market structure favors therapies that can reduce treatment burden while preserving anatomical and functional outcomes. As a result, commercial strategy in 2026 must prioritize placement within care pathways that reward extended dosing intervals, integrated monitoring models, and evidence generation capable of supporting formulary persistence.
Therapeutic Architecture and Segment Positioning
The therapeutic landscape for retinal vein occlusion is anchored by two principal clinical pathways: branch retinal vein occlusion and central retinal vein occlusion. Each pathway carries distinct edema persistence profiles, treatment-response variability, and real-world monitoring expectations. The commercial composition of the market reflects the relative prevalence of these presentations, but also the way approved formulations are positioned across ophthalmology practices, retina subspecialty clinics, and integrated health systems.
Anti-vascular endothelial growth factor agents constitute the dominant therapy class and have established themselves as the procedural backbone for managing macular edema secondary to venous occlusion. Their dominance is reinforced by standardized treatment protocols, robust real-world experience, and a growing body of comparative evidence. Corticosteroid-based options maintain a meaningful secondary role, particularly in contexts requiring alternative mechanisms of action or in patients with specific tolerability considerations. A smaller residual category encompasses other therapeutic approaches that serve niche or adjunctive functions within select practice settings.
Our segmentation analysis goes beyond aggregate revenue distribution to examine how therapy-class positioning shifts across clinical contexts, prescribing habits, and formulary architectures. We map the interaction between approved indications, dosing flexibility, and real-world adherence patterns, enabling teams to identify where competitive substitution risk is highest and where differentiation opportunities remain underleveraged. This perspective is especially relevant as extended-interval formulations enter the market and reshape expectations around injection frequency and clinic throughput.
Competitive Dynamics and Strategic Footprints
The competitive architecture of this market is characterized by a high degree of concentration. A small group of multinational therapeutic companies and regional partners controls a substantial share of commercial activity, reflecting the capital intensity of ophthalmic development, the regulatory burden associated with intravitreal products, and the importance of established ophthalmology relationships. At the same time, the arrival of biosimilar entrants and the geographic expansion of differentiated dosing regimens have introduced new pressures into the incumbent positioning model.
F. Hoffmann-La Roche Ltd. and its U.S. affiliate Genentech continue to anchor a prominent position through faricimab-svoa and ranibizumab, both approved for macular edema following retinal vein occlusion. Faricimab’s dual-pathway mechanism and evolving labeling have become central to Roche’s differentiation narrative, especially after recent label support for extended treatment duration beyond six months. Regeneron Pharmaceuticals maintains a strong commercial footprint through aflibercept and the higher-concentration aflibercept formulation designed for longer dosing intervals. The approval and rollout of the extended-interval version for macular edema following retinal vein occlusion signals a deliberate strategy to reduce treatment burden and reinforce market presence among retina specialists.
Bayer AG plays a significant role in ex-U.S. markets, co-promoting and distributing aflibercept-based products across selected territories. Its recent regulatory milestones in the United Kingdom and European Union illustrate how regional market access pathways can amplify product availability and expand the addressable patient base. AbbVie, through its Allergan portfolio, continues to provide a corticosteroid intravitreal implant option for macular edema following retinal vein occlusion, preserving a strategic alternative for clinicians managing chronic or refractory edema patterns. Novartis contributes to the ranibizumab footprint across multiple regions, reinforcing the longevity and global familiarity of this anti-VEGF reference asset.
In Asian markets, Santen Pharmaceutical and Chugai Pharmaceutical extend the competitive mosaic by commercializing and regionally developing key assets, including aflibercept and faricimab-based offerings. Their localized commercialization strategies and regional regulatory navigation are critical components of the global supply-and-access picture, particularly where ophthalmology practice patterns, reimbursement models, and formulary structures diverge from Western markets.
Against this backdrop, the early approval and commercial entry of aflibercept biosimilars introduces a structural shift in the medium-term competitive environment. Biosimilar entrants approved for retinal vein occlusion indications expand the pool of available options, intensify pricing scrutiny, and challenge incumbents to defend share through clinical differentiation, service infrastructure, and access partnerships. Our report assesses these forces not as isolated events but as interlocking dynamics that will influence contract negotiations, tender positioning, and specialist adoption behavior across the forecast horizon.
Regulatory Momentum and Dosing Paradigm Shifts
The most consequential commercial disruptor in the 2025 to 2026 window has been the succession of regulatory approvals and label updates targeting longer treatment intervals. The introduction and approval of higher-concentration aflibercept for macular edema following retinal vein occlusion, followed by European Commission authorization and United Kingdom regulatory clearance, represents a coordinated step toward reducing injection frequency while preserving therapeutic coverage. In parallel, updated labeling for faricimab has extended the acknowledged treatment horizon beyond six months, reinforcing the clinical narrative of durability and flexibility.
These developments carry strategic implications beyond the clinical conversation. Dosing interval extension influences clinic capacity planning, patient adherence expectations, transportation burden, and downstream payer evaluations of total cost of care. In many reimbursement environments, the perceived value of a therapy is increasingly tied to its ability to reduce visit frequency without compromising outcomes. Commercial teams that anticipate this shift can construct more defensible market access narratives, align sales education with workflow efficiencies, and position their assets within integrated care models that reward reduced treatment burden.
Simultaneously, the approval of biosimilar alternatives for retinal vein occlusion indications signals the beginning of a broader competitive layering process. While biosimilar entry does not automatically translate into immediate share displacement, it changes the reference price landscape and expands the set of options available to procurement committees and ophthalmology groups. The strategic response from incumbents is likely to involve a combination of evidence reinforcement, service-level differentiation, and selective contracting. Our research evaluates how these bargaining dynamics could evolve across different purchasing contexts and regional access systems.
Geography, Access Pathways, and Regional Variation
Market performance across regions reflects more than population scale. It is shaped by ophthalmology workforce distribution, reimbursement design, imaging availability, injection-site infrastructure, and the maturity of retina subspecialty referral networks. North American commercial activity remains heavily influenced by specialist-driven prescribing, payer formulary architecture, and the interaction between anti-VEGF utilization patterns and procedural reimbursement frameworks. European markets introduce additional complexity through varied national access pathways, regional health technology assessment expectations, and localized pricing negotiations.
Asia Pacific and other emerging regions present a different strategic profile. Growth potential is tied to improving diagnostic reach, expanding ophthalmology capacity, and the localization of access arrangements. Japanese pharmaceutical activity, in particular, reflects deliberate regional development and commercialization of key assets, supported by local clinical practice norms and regulatory pathways. Latin American and Middle East and Africa markets represent smaller but strategically important footholds where access programming, import and distribution logistics, and affordability considerations shape adoption ceilings.
Our study examines these regional differences through a commercial lens rather than a purely epidemiological one. We analyze how regional access systems influence formulary inclusion, how purchasing entities evaluate durable dosing claims, and where local partnership models can accelerate market entry or strengthen distribution resilience. This regional perspective is essential for organizations planning cross-market rollouts, capacity investments, or licensing and distribution arrangements.
Report Scope and Operational Utility
The Worldwide Retinal Vein Occlusion Therapeutics Market research is designed as an operational intelligence instrument. It provides time-series market sizing across the historical and forecast windows, detailed segmentation coverage by condition presentation and therapy class, and region-level commercial context that supports resource allocation and prioritization. The report integrates competitive profiling, recent regulatory and label developments, and reimbursement context to help teams connect market sizing with execution planning.
Key modules include market size progression across the forecast period, therapy-class positioning and substitution dynamics, condition-type segmentation aligned with clinical practice patterns, regional revenue context and access-system variation, and competitive landscape mapping focused on the companies that shape prescribing and formulary behavior. The study also incorporates recent regulatory and labeling developments into the competitive narrative, enabling teams to assess near-term momentum and anticipate shifts in utilization expectations.
We have structured the report to support multiple internal workflows. Product strategy teams can use the segmentation and competitive sections to refine positioning and lifecycle planning. Commercial and market access teams can draw on the regional and reimbursement context to calibrate messaging and contracting assumptions. Business development and licensing teams can leverage the competitive concentration analysis and recent approval cadence to evaluate partnership timing and asset attractiveness.
Implications for 2026 Decision-Making
Strategic planning in 2026 should begin with three operational priorities. First, organizations must align product narratives with the market’s increasing emphasis on treatment durability and reduced visit burden. Second, teams should incorporate biosimilar entry into pricing, contracting, and service differentiation assumptions rather than treating biosimilars as a distant competitive concern. Third, regional rollout and access planning should account for the uneven pace of regulatory adoption, the variation in reimbursement environments, and the importance of local ophthalmology relationships.
The forecast period through 2032 presents both opportunity and complexity. Growth will be supported by continued adoption of anti-VEGF-based care pathways and by the expansion of longer-interval treatment options, but it will also be moderated by pricing pressure, access-system scrutiny, and the competitive layering introduced by biosimilar alternatives. Organizations that build their plans around scenario-aware forecasting, evidence-aligned differentiation, and regionally informed access strategy will be better positioned to convert market expansion into durable commercial outcomes.
Accessing the Full Intelligence Framework
This article has outlined the strategic contours of the worldwide retinal vein occlusion therapeutics market and highlighted the decision-making themes most relevant to 2026. It provides a professional preview of the market’s trajectory, competitive structure, therapeutic architecture, and regional access dynamics, but the complete analytical depth, time-series breakdowns, and segmentation-level intelligence are available only through the full PW Consulting market study.
For teams responsible for product planning, commercial execution, access negotiation, or partnership evaluation, the complete report offers the level of detail required to move from directional confidence to precise execution. Readers seeking the full dataset and proprietary segmentation analysis are encouraged to visit the PW Consulting source page to obtain the complete Worldwide Retinal Vein Occlusion Therapeutics Market research and integrate its intelligence into their 2026 strategic planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Retinal Vein Occlusion Therapeutics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Forecasts 5.18% CAGR Boost for Worldwide High-Mast Lighting Market to USD 1925.05 Million by 2032
By PW Consulting, 2026-09-02
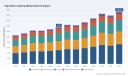
Illuminating the Future: Strategic Intelligence for the Global High-Mast Lighting Market 2026-2032
The global high-mast lighting sector stands at a critical inflection point. As municipalities, transportation authorities, and industrial operators balance aging infrastructure against the imperative for energy-efficient, smart-enabled illumination, understanding the underlying market mechanics is no longer optional—it is a strategic necessity. This article introduces PW Consulting's latest Worldwide High-Mast Lighting Market research report, a comprehensive analytical instrument designed to equip executives, procurement leaders, and investors with the foresight required to navigate the 2026-2032 forecast period. The study does not merely track historical revenue flows; it decodes the structural shifts, regulatory triggers, and competitive maneuvers that will define capital allocation and market share in the years ahead.
Worldwide High-Mast Lighting Market
Macroeconomic Trajectory and Historical Context
The market has demonstrated remarkable resilience and steady expansion over the past half-decade. Historical data reveals a progression from approximately 1,055.4 million USD in 2020 to a baseline valuation of 1,350.0 million USD in 2025. This growth trajectory underscores the sector's transition from isolated infrastructure projects to a systematic, globally integrated market driven by urbanization, transportation network upgrades, and the ongoing retrofit of legacy lighting systems. Looking forward, the forecast period projects continued expansion, with revenue expected to reach roughly 1,440.85 million USD in 2026 and climb to an estimated 1,925.05 million USD by 2032.
Worldwide High-Mast Lighting Market
These figures reflect a Compound Annual Growth Rate (CAGR) of approximately 5.18 percent, signaling a mature yet steadily accelerating environment rather than a speculative boom. For strategic planners, this moderate growth rate masks significant underlying volatility in input costs, regional procurement cycles, and technology substitution rates. Our analysis isolates the specific demand drivers that sustain this CAGR, distinguishing cyclical infrastructure spending from structural shifts in luminaire technology. A deeper examination of the annual revenue breakdown reveals the precise inflection points where past performance transitions into future opportunity, a nuance essential for accurate budgeting and forecasting.
Worldwide High-Mast Lighting Market
Technology Substitution: The LED Transition and Optical Performance
The technological backbone of the high-mast segment is undergoing a definitive transformation. LED high-mast systems have emerged as the dominant architecture, with historical and projected revenue flows heavily concentrated in this category. Traditional HID and conventional lighting solutions continue to serve specific legacy applications, but their market footprint is contracting as efficiency mandates tighten and total cost of ownership calculations favor solid-state illumination. The displacement of older technologies is not a binary event; it is a phased migration influenced by regional procurement policies, foundation replacement economics, and the integration of lowering devices that facilitate maintenance access at extreme heights.
Forward-looking buyers must evaluate not only the luminaire itself but the entire system ecosystem. Modern high-mast deployments increasingly require compatible electrical distribution networks, wireless control interfaces, and structural configurations that accommodate side-mounted optical assemblies aligned with updated equipment standards. Our report dissects how these technical requirements are reshaping supplier portfolios, influencing specification-grade purchasing, and creating new barriers to entry for manufacturers lacking integrated engineering capabilities. Readers seeking a complete mapping of technology adoption curves across application types and geographic corridors will find the full segmentation analysis indispensable.
Regional Demand Architecture and Procurement Realities
Geographic demand for high-mast lighting is distributed across a diverse matrix of infrastructure priorities, climatic conditions, and regulatory frameworks. Asia Pacific, North America, Europe, the Middle East and Africa, and Latin America each present distinct procurement rhythms, competing public works agendas, and varying tolerances for capital expenditure cycles. Certain regions exhibit accelerated highway modernization programs that directly translate into high-mast specification volumes, while others prioritize port security upgrades, correctional facility illumination, or sports venue redevelopment. The interplay between regional steel availability, foundation construction costs, and engineering compliance requirements creates a highly localized market texture that generic industry surveys often overlook.
Strategic decision-makers operating across multiple jurisdictions require more than aggregate regional revenue figures. They need actionable intelligence on how transportation departments are revising standard plans, how military and defense agencies are structuring tenders, and how municipal lighting authorities are integrating lowering mechanisms and wireless controls into existing networks. Our regional analysis contextualizes procurement patterns against real-world project announcements and standard plan revisions, providing a practical lens for evaluating market entry timing and competitive positioning. The complete decomposition of regional dynamics, including project pipeline indicators and infrastructure spending alignments, is detailed in the full report.
Regulatory Catalysts and Industry Standardization
Regulation remains one of the most potent forces shaping the high-mast lighting landscape. The recent publication of ANSI C136.25-2025, the American National Standard for Roadway and Area Lighting Equipment, introduces specified guidance relevant to high-mast side-mounted luminaires and associated system components. This standard, alongside evolving transportation department specifications, directly influences luminaire design, optical distribution requirements, and installation protocols. Simultaneously, agencies such as Caltrans have updated their 2025 Standard Plans to refine electrical system details, including high-mast camera poles and related lighting configurations, signaling a tightening of technical compliance expectations across U.S. infrastructure programs.
Beyond equipment standards, procurement cycles provide real-time confirmation of sustained demand. Recent solicitations, including a U.S. Department of Veterans Affairs procurement for LED high-mast fixtures, Indian Army tenders for LED-compliant high-mast lighting towers, and state-level installation programs by transportation departments, illustrate how public-sector budgeting directly feeds into the commercial market. Each tender and standard revision represents a data point in a broader pattern of infrastructure modernization that our research tracks systematically. Understanding the cadence of these regulatory and procurement events is critical for aligning production schedules, sales territory planning, and distributor partnerships.
Raw Material Economics and Structural Cost Dynamics
The economics of high-mast deployment extend far beyond luminaire pricing. Structural integrity demands engineered steel poles capable of withstanding high wind loads, variable soil conditions, and the mechanical stresses of lowering mechanisms. Consequently, hot-rolled coil steel prices, manufacturing grades, and regional supply chain stability exert considerable influence on total project economics. Recent market observations indicate that U.S. hot-rolled coil prices have experienced upward movement, with spot pricing reflecting tighter supply dynamics and persistent demand from infrastructure and industrial sectors. Simultaneously, Midwest HRC steel futures have traded in a range that suggests stabilization expectations heading into 2026, though volatility remains a factor for long-term capital planning.
These material cost fluctuations interact with labor, foundation construction, and installation expenses, creating a complex cost structure that buyers and suppliers must monitor continuously. Transportation agency unit price lists and regional procurement data offer valuable benchmarks for tracking structural and foundation cost trends. Our report integrates raw material forecasting with segment-level cost modeling, enabling executives to anticipate margin pressures, evaluate pricing strategies, and assess the financial viability of new product introductions. A granular assessment of cost drivers across pole specifications, foundation designs, and installation labor profiles awaits in the full dataset.
Competitive Landscape and Strategic Positioning
The high-mast lighting market features a concentrated competitive field characterized by a mix of structural manufacturers, luminaire specialists, and integrated system providers. Competitive concentration metrics indicate a relatively fragmented environment, with leading firms collectively holding modest market share, which implies that differentiation, regional service coverage, and specification capture remain decisive competitive levers. Several established players anchor the market with distinct strategic profiles. Valmont Industries delivers tapered steel high-mast structures and poles engineered for roadway, port, airport, and industrial applications, offering configurations that support fixed mounting and lowering device arrangements with galvanized finishing options. CHM Lighting, operating as Carolina High Mast, focuses on specification-grade systems built entirely in America, encompassing steel towers, LED luminaires, lowering devices, electrical distribution, and wireless controls.
Millerbernd Manufacturing Company serves transportation infrastructure networks with high-mast solutions optimized for fewer poles while satisfying DOT and FAA requirements, frequently incorporating lowering devices for maintenance and reliability. Acuity Brands, through its Holophane heritage, maintains a substantial global installed base of high-mast LED lighting systems and lowering devices deployed across highways, ports, correctional facilities, and industrial settings. Cooper Lighting Solutions, operating under the Eaton umbrella, supplies LED high-mast fixtures emphasizing high output, efficiency, safety, and optical performance for roadway and area applications. Signify, formerly Philips Lighting, provides LED high-mast systems for large-area illumination spanning transportation, sports, and industrial domains, leveraging global scale and optical engineering expertise.
Additional participants reinforce the market's competitive depth. Hubbell Lighting integrates high-mast and area lighting within a broader outdoor and roadway portfolio, offering complementary system capabilities. American LitePole manufactures tapered steel high-mast poles tailored for airports, shipping terminals, heavy industry, and sports applications, emphasizing structural engineering for wind, soil, and load conditions. Access Fixtures produces galvanized steel high-mast light poles using American-grade steel for commercial, industrial, and sports applications, with height capabilities extending well beyond 235 feet. Yangzhou Yunteng Lighting Group Co., Ltd. contributes manufacturing capacity for high-mast poles and lighting systems with an established production footprint serving global markets. The coexistence of vertically integrated manufacturers, specification-focused luminaire brands, and regional pole specialists creates a multi-layered competitive environment where partnership strategy and technical compliance often determine project outcomes. A complete analysis of competitive positioning, product differentiation, and strategic alliances appears in the full report.
Application Sectors and Deployment Priorities
High-mast lighting finds deployment across a portfolio of demanding environments where illumination intensity, structural height, and operational reliability are non-negotiable. Roadways and highways represent a foundational application category, driven by lane expansion, intersection safety programs, and nighttime visibility requirements. Ports and terminals rely on high-mast systems to support cargo operations, security surveillance, and operational continuity in zones exposed to heavy equipment and demanding environmental conditions. Airports require lighting configurations that meet stringent FAA guidelines and support runways, taxiways, and perimeter security, often requiring coordinated maintenance access via lowering mechanisms.
Sports facilities depend on high-mast illumination to deliver uniform field coverage, fan experience quality, and broadcast-ready lighting standards, creating a recurring refresh cycle tied to venue development and league specifications. Industrial and commercial areas deploy high-mast systems to illuminate large footprints including logistics parks, manufacturing campuses, and storage yards, where safety, security, and energy efficiency converge. Each application sector carries unique procurement triggers, technical specifications, and maintenance considerations. For organizations evaluating where to concentrate sales resources, product development, or service infrastructure, a detailed application-level analysis is essential. The full report provides an in-depth breakdown of application demand patterns, project pipeline indicators, and specification trends that clarify which sectors offer the strongest near-term growth alignment.
Strategic Framework for 2026 Decision-Making
Translating market intelligence into action requires a structured strategic framework. For manufacturers and suppliers, the 2026-2032 window presents opportunities to align product roadmaps with regulatory timelines, optimize supply chain resilience against raw material volatility, and expand specification capture through technical differentiation. For system integrators and project developers, understanding the interplay between luminaire technology, pole engineering, lowering device compatibility, and wireless control integration can unlock higher-margin service offerings and reduce installation risk. For investors and financial analysts, disentangling structural growth from cyclical infrastructure spending is vital for evaluating valuation assumptions and identifying companies positioned to capture disproportionate share gains.
Our research methodology is designed to support these decisions with operational precision. The report delivers comprehensive market sizing anchored in historical data and extended through a rigorously modeled forecast period, supported by segmentation that maps technology adoption, application dynamics, and regional demand architecture. Competitive profiling extends beyond corporate descriptions to examine strategic positioning, product capability alignment, and procurement visibility. Industry context analysis integrates recent regulatory publications, tender activity, standard plan revisions, and raw material cost trends into a cohesive narrative that connects macro conditions to commercial outcomes. This integrated approach ensures that readers can move from awareness to execution, whether the objective is market entry, capacity expansion, partnership formation, or risk assessment.
Navigating the Intelligence Gap
High-level summaries inevitably omit the granular dimensions required for precise execution. The full market model contains the specific revenue segmentation, regional breakdown, application distribution, and competitive concentration metrics that allow teams to test scenarios, calibrate forecasts, and prioritize investment. It also links real-time procurement events and regulatory updates to forward-looking demand projections, bridging the gap between news and strategy. Accessing the complete dataset enables readers to validate assumptions, benchmark internal performance against market trajectories, and identify underserved segments or geographies with high growth probability.
As infrastructure modernization accelerates and LED substitution matures into a system-level transformation, the organizations that succeed will be those equipped with precise, forward-looking intelligence rather than retrospective aggregates. PW Consulting's Worldwide High-Mast Lighting Market research report delivers that intelligence in a format built for executive use, procurement planning, and strategic positioning. For decision-makers operating in 2026 and beyond, the difference between reactive adaptation and proactive advantage lies in the depth of insight available at the outset of the planning cycle.
Conclusion and Research Access
The high-mast lighting market in 2026 is defined by measured growth, accelerating LED integration, tightening equipment standards, and sustained public-sector procurement across transportation, security, sports, and industrial applications. Strategic success will depend on the ability to interpret these dynamics with precision, anticipate cost and regulatory pressures, and align commercial strategies with the granular realities of regional demand and competitive differentiation. This report has been developed to provide exactly that capability. Readers seeking the complete market sizing, full segmentation detail, competitive analysis, and forward-looking scenario modeling are invited to access the full research publication, where the underlying data and methodology are presented in full operational context.
For detailed analysis of this topic, please visit the official page: Worldwide High-Mast Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


