



Category: market research
PW Consulting Report: Worldwide Robotic Vacuums Filter Market to Reach USD 2365.64 Million by 2032 with 12.31% CAGR
By PW Consulting, 2026-09-02
Strategic Intelligence for Sustainable Growth in the Global Robotic Vacuums Filter Market
The consumer robotics sector stands at a critical inflection point. As households increasingly integrate autonomous cleaning systems into daily routines, the peripheral ecosystem that sustains these devices has evolved from an afterthought into a primary revenue driver. Among these consumables, filtration components occupy a unique strategic position: they dictate air quality performance, influence brand loyalty through replacement cycles, and serve as a tangible differentiator in a saturated appliance landscape.
Worldwide Robotic Vacuums Filter Market
Our newly released Worldwide Robotic Vacuums Filter Market study provides enterprise leaders with a comprehensive, data-grounded roadmap into this rapidly scaling niche. Covering historical performance from 2020 through 2025 and projecting forward across the 2026-2032 forecast horizon, the research translates macroeconomic trends, technological shifts, and competitive maneuvers into actionable intelligence. This article outlines the strategic rationale behind the report, previews the analytical architecture it delivers, and demonstrates why decision-makers should treat filtration not as a commodity line item, but as a core growth lever.
Worldwide Robotic Vacuums Filter Market
The Macro Trajectory: Scale, Velocity, and Structural Expansion
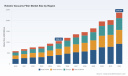
The global market for robotic vacuum filters has demonstrated consistent, compounding growth over the past half-decade. Between 2020 and 2025, total revenue expanded from approximately $587.31 million to $1,050.25 million, reflecting an era of accelerated consumer adoption, product iteration, and heightened awareness of indoor environmental quality. Looking ahead, the trajectory accelerates further. The market is projected to reach $1,202.88 million in 2026 and continue climbing through the end of the forecast window, culminating at $2,365.64 million by 2032.
Worldwide Robotic Vacuums Filter Market
This expansion corresponds to a compound annual growth rate of 12.31%, a velocity that outpaces many adjacent home appliance categories. The sustained growth curve is not merely a function of unit sales; it is structurally reinforced by product design changes. Manufacturers are integrating higher-grade filtration architectures as standard specifications rather than premium add-ons, lengthening replacement intervals while simultaneously elevating the perceived necessity of genuine or certified accessories. For strategic planners, this signals a transition from sporadic, price-driven procurement to recurring, value-linked consumption patterns.
Currency standardization in USD million throughout the analysis ensures cross-market comparability, allowing executives to benchmark regional performance, channel profitability, and category attractiveness without conversion distortion. The dataset spans the full product lifecycle, enabling teams to model pipeline demand, inventory planning, and aftermarket capture simultaneously.
Why 2026 Demands a Filter-First Strategic Lens
Several converging forces make 2026 a decisive year for organizations operating along the robotic vacuum value chain. Product roadmaps unveiled at major industry events have publicly emphasized next-generation filtration architectures, from multi-cyclone H13 systems to upgraded washable media and enhanced allergen containment. These engineering payloads directly influence OEM sourcing requirements, aftermarket compatibility matrices, and channel pricing strategies.
Simultaneously, regulatory and standards evolution is reshaping filter positioning. The Asthma & Allergy Friendly® certification framework developed by Allergy Standards Limited introduced a specific benchmark for robotic vacuum cleaners, focusing explicitly on allergen removal and particle containment through filtration subsystems. As consumer sensitivity to indoor air quality and pet-related particulate matter intensifies, certified filters are transitioning from optional marketing claims to baseline customer expectations. Companies that map certification pathways early gain a measurable edge in retail placement, premium pricing justification, and compliance readiness.
Geopolitical and trade dynamics further complicate the supply landscape. Ongoing U.S. import tariffs and export controls on semiconductors originating from China have begun rippling into component pricing and logistics costs for Chinese-made robotic vacuum filters and associated electronics. These cost pressures are reshaping margin structures, procurement sourcing, and distribution channel economics. Organizations relying on single-source manufacturing footprints or rigid channel agreements face heightened exposure. Strategic resilience now depends on visibility into cost drivers, alternative sourcing pathways, and regional pricing elasticity.
The macro message for 2026 is clear: filtration is no longer a passive consumable. It is a performance anchor, a competitive moat, and a margin-critical component that reflects broader shifts in product design, consumer health awareness, and trade policy.
Report Architecture: What Decision-Makers Will Gain
The Worldwide Robotic Vacuums Filter Market report is engineered for executive, product, procurement, and strategy functions. It synthesizes historical baselines, forecast trajectories, segmentation behavior, competitive positioning, and environmental dynamics into a single, navigable analytical framework. Beyond headline figures, the study delivers operational granularity that supports scenario planning, market entry evaluation, and portfolio optimization.
Core Analytical Components
- Comprehensive historical tracking from 2020 through 2025, establishing baseline growth patterns, inflection points, and category performance trends across the full revenue stack.
- Forward-looking forecasts spanning 2026 to 2032, enabling multi-year demand modeling, capacity planning, and investment prioritization aligned with structural market expansion.
- Segmentation analysis across filter type, sales channel, and regional performance, revealing where volume concentrates, where premium positioning thrives, and which pathways demonstrate the strongest growth momentum.
- Competitive landscape profiling with detailed manufacturer assessments, product portfolio mapping, logistics footprints, and strategic positioning across OEM and aftermarket segments.
- Environmental dynamics coverage, including standards evolution, allergen certification frameworks, tariff and trade exposure, and indoor air quality consumer trends influencing filter specification and purchasing behavior.
- Real-time development tracking capturing product launches, trade show exhibitions, and capability announcements that signal near-term shifts in filtration architecture and channel messaging.
- Strategic synthesis modules designed to translate data into actionable perspectives for pricing strategy, channel expansion, supply chain diversification, and brand differentiation.
Practical Applications Across Functions
For corporate strategy teams, the dataset supports market attractiveness scoring and resource allocation decisions. Product managers can evaluate which filter categories align with premium positioning and which channel pathways demonstrate the fastest volume conversion. Procurement and supply chain leaders can stress-test sourcing models against regulatory exposure, regional cost structures, and demand volatility. Commercial and sales directors gain a reference framework for channel mix optimization, retail execution planning, and aftermarket loyalty programs.
Importantly, the research is structured to support bottoms-up scenario building. Executives can isolate specific segment interactions, examine channel overlap, and model how product specification changes influence replacement cadence and consumable capture. This level of analytical transparency transforms the report from a static market summary into a living decision-support instrument.
Competitive Landscape: Who Shapes the Filter Ecosystem
The robotic vacuum filter landscape is defined by a blend of appliance OEMs, dedicated filtration specialists, and multi-brand aftermarket suppliers. Strategic positioning varies significantly: some players leverage proprietary ecosystem lock-in through official consumables, others compete on compatibility breadth and price accessibility, while specialized manufacturers focus on filter-grade performance, OEM partnerships, and certification readiness.
Appliance and Robotics OEMs with Integrated Filter Programs
iRobot Corporation, headquartered in Bedford, Massachusetts, remains a defining reference point for the category. Its Roomba ecosystem is supported by proprietary replacement HEPA-style and high-efficiency filters engineered as official consumables for its robotic vacuum lineup. This approach ties filter performance directly to brand experience, reinforcing user trust in suction consistency and allergen management while sustaining recurring revenue streams.
Roborock Technology Co., Ltd., based in Beijing, has established itself as a major producer of premium robotic vacuums. Its official portfolio includes washable and HEPA filters designed for models across the Saros and Qrevo series, reflecting a strategy that balances performance filtration with long-term user maintenance flexibility.
ECOVACS Robotics, operating from Suzhou, supplies dedicated replacement filters and HEPA filtration systems for its globally distributed DEEBOT consumer robot vacuums. Recent exhibition activity has highlighted next-generation models built around advanced filtration configurations, signaling continued investment in air-quality performance as a core product attribute.
SharkNinja Operating LLC, from Needham, Massachusetts, offers replacement HEPA and multi-layer filters engineered for its PowerDetect and AI Ultra series. The company's filter design philosophy emphasizes layered capture performance alongside compatibility with its broader robotic vacuum portfolio.
Anker Innovations, through its Eufy brand with operational ties to Bellevue, Washington, provides compatible HEPA filters and replacement filter kits for its Omni and Clean series. Its market approach blends accessible pricing with reliable filtration compatibility, targeting mass-market adoption and aftermarket continuity.
Specialist Robotics, Filtration, and Aftermarket Players
Narwal Robotics, headquartered in Shenzhen, focuses on robot vacuums and mops while integrating multi-cyclone H13 filtration systems into select models such as Flow 2. Its product direction underscores a growing emphasis on high-grade filtration as a differentiating engineering feature rather than a baseline accessory.
On the component and aftermarket side, Nanjing Blue Sky Filter Co., Ltd. operates as a dedicated filter manufacturer supplying OEM and replacement HEPA filters compatible with major ecosystems, including Ecovacs, Roborock, iRobot, and Shark. Its positioning illustrates how independent filter specialists bridge brand ecosystems while expanding consumer choice and supply redundancy.
Hifine concentrates on OEM supply of high-quality H13/H14 HEPA filters and robotic vacuum cleaner parts for both commercial and residential applications. Its capability set highlights the growing importance of filter-grade specification in downstream product performance claims and certification pathways.
techTongBo functions as a manufacturer and wholesaler of replacement parts, including HEPA filters for a broad roster of robotic vacuum brands. Its distribution breadth demonstrates how aftermarket aggregators serve price-sensitive channels and multi-brand compatibility demand.
Midea Group, through its Eureka affiliate, produces robotic vacuums alongside aftermarket accessories such as bags, belts, and replacement filters, reflecting a diversified portfolio strategy that combines appliance innovation with consumable continuity.
Strategic Interpretation of Competitive Positioning
Together, these players reveal a dual-layered market structure. At the premium end, OEMs anchor filter performance to product identity, using proprietary specifications to protect brand equity and recurring revenue. In parallel, specialized and multi-brand filter suppliers broaden compatibility, support price-sensitive purchasing behavior, and increase supply chain optionality. For enterprises, this duality creates both risk and opportunity: channel conflict must be managed, but so does the chance to capture aftermarket share, negotiate OEM partnerships, or position certification-ready filters as a trust signal.
Recent 2026 activity reinforces the direction of travel. At CES 2026, ECOVACS showcased its latest DEEBOT models, including the T90 PRO OMNI and X12 Family, with advanced filtration configurations. Narwal Robotics unveiled its next-generation Flow 2 robot vacuum featuring a multi-cyclone H13 filtration system. Roborock exhibited the Saros 20 series and Qrevo Curv 2 Flow models with updated filtration capabilities. Each announcement signals intensified engineering focus on particulate capture, user-maintainable media, and filtration performance as a visible product attribute.
Market concentration data further contextualizes competitive intensity. The top three firms account for approximately 42.15% of total market revenue, while the top five expand that share to 58.4%. This concentration pattern indicates a market with clear leadership anchors, but also substantial runway for challenger brands, aftermarket specialists, and regional players to compete through differentiation in filter grading, compatibility breadth, certification alignment, and channel execution.
Market Dynamics: Forces Reshaping Demand, Pricing, and Sourcing
Regulatory and Standards Catalysts
Filtration performance is increasingly governed by consumer health expectations and formal certification benchmarks. The Asthma & Allergy Friendly® standard developed by Allergy Standards Limited introduced a robotic vacuum-specific framework focused on allergen removal and particle containment through filter mechanisms. As HEPA-type filtration becomes more standard across product tiers, compliance-oriented filter design and transparent performance messaging are shifting from differentiators to table stakes. Companies that align product specifications and aftermarket offerings with recognized standards can strengthen retail credibility, support premium pricing, and reduce consumer skepticism around filtration claims.
Consumer-Driven Performance Expectations
Across residential segments, HEPA filtration in robotic vacuums is increasingly standard to address consumer concerns about allergens, indoor air quality, and pet hair containment. This expectation is especially pronounced in households with pets, allergy-sensitive occupants, and higher-density urban living environments where airborne particulate management carries heightened perceived value. For filter suppliers and OEMs alike, this translates into greater scrutiny of filter media quality, replacement cycle transparency, and compatibility assurance. Products that fail to communicate filtration credibility risk erosion in repeat purchase behavior and cross-channel credibility.
Trade, Tariff, and Supply Chain Implications
The pricing and component cost environment for Chinese-origin robotic vacuum filters and associated electronics is being reshaped by U.S. import tariffs and export controls on semiconductors. These dynamics influence not only absolute cost, but also sourcing strategy, lead-time planning, and regional margin distribution. Enterprises dependent on concentrated manufacturing footprints or single-channel logistics may encounter volatility in landed cost and inventory availability. Conversely, organizations that diversify sourcing, evaluate alternate component pathways, and model tariff-adjusted pricing can improve resilience while maintaining competitive positioning.
Channel Evolution and Postmarket Economics
Distribution dynamics continue to evolve as e-commerce platforms, direct-to-consumer programs, and offline retail stores compete for consumable share. The balance between digital discovery, subscription-style replenishment, and in-store accessibility shapes how filters are discovered, trusted, and purchased. Enterprises must evaluate channel-specific pricing tolerance, packaging expectations, and authenticity assurance strategies to sustain aftermarket capture. Products positioned as genuine, certified, or high-efficiency alternatives can command differentiated value when supported by credible channel execution and clear compatibility communication.
Strategic Priorities for 2026 and Beyond
The convergence of product innovation, standards maturation, and supply chain complexity creates a clear mandate for proactive market engagement. Leaders who treat filtration as a strategic subsystem rather than a routine consumable will be better positioned to capture recurring revenue, protect brand credibility, and navigate cost volatility. Practical priorities include aligning filter specifications with recognized certification frameworks, stress-testing sourcing models against tariff and semiconductor exposure, expanding compatibility intelligence to support both OEM and aftermarket positioning, and designing channel strategies that reinforce authenticity and repeat purchase behavior.
Forward-looking scenario planning will increasingly depend on granular visibility into segment interactions, channel profitability, and certification-aligned product architecture. The organizations that succeed will be those that integrate filtration strategy into broader portfolio decisions, pricing frameworks, and supply resilience plans.
Next Steps: Accessing the Full Intelligence Package
The Worldwide Robotic Vacuums Filter Market report provides a complete analytical foundation for enterprise teams responsible for product strategy, commercial execution, procurement resilience, and competitive positioning. It combines historical baselines, forecast trajectories, segmentation insights, competitor profiling, and environmental dynamics into a single decision-support framework. Detailed segment breakdowns, channel-level performance patterns, and proprietary competitive assessments are available within the full report, enabling leadership teams to move from high-level market awareness to precise, executable planning.
For executives preparing 2026 investment decisions, channel strategies, and product roadmaps, this research offers the data density and strategic framing required to act with confidence. Access the complete intelligence package to explore segment details, competitive mapping, and forward-looking scenarios tailored to your organization's strategic priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Robotic Vacuums Filter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Permanent Magnet Turbo Blower Market Poised to Surpass USD 1,500 Million by 2032 with 7.85 Percent CAGR
By PW Consulting, 2026-09-02
Navigating the Permanent Magnet Turbo Blower Market in 2026: Strategic Imperatives for Industrial Leaders
The global industrial landscape is undergoing a profound transformation driven by efficiency mandates, sustainability goals, and the relentless pursuit of operational excellence. At the heart of this shift lies the permanent magnet turbo blower, a technology that has evolved from a niche application to a cornerstone of modern fluid handling and aeration systems. As enterprises plan their capital expenditure and technology roadmaps for 2026 and beyond, understanding the trajectory of this market is not merely an academic exercise—it is a strategic imperative. This article serves as an executive preview of PW Consulting's latest comprehensive study, Worldwide Permanent Magnet Turbo Blower Market, offering a high-level view of the forces shaping the industry while highlighting the depth of intelligence available in our full report.
Worldwide Permanent Magnet Turbo Blower Market
For decision-makers in wastewater management, heavy industry, and environmental engineering, the pressure to reduce energy consumption while maintaining output is intensifying. Traditional rotary lobe blowers and aging centrifugal systems are increasingly viewed as liabilities in an era defined by volatile energy costs and stringent regulatory frameworks. The permanent magnet turbo blower, with its ability to deliver oil-free air, variable speed control, and remarkable efficiency gains, represents a viable path forward. However, navigating the procurement landscape requires more than a superficial understanding of specifications. It demands a clear view of market sizing, competitive positioning, technological trends, and the macroeconomic variables that influence total cost of ownership. Our research is designed to provide exactly that clarity, serving as a foundational document for strategy teams, procurement leaders, and engineering directors.
Worldwide Permanent Magnet Turbo Blower Market
Market Trajectory and Growth Dynamics
The global permanent magnet turbo blower market has demonstrated robust growth over the past half-decade, reflecting a broader industrial shift toward high-efficiency electromechanical drive systems. Our analysis covers historical performance from 2020 through the base year of 2025, extending into a detailed forecast period spanning 2026 to 2032. This longitudinal view allows stakeholders to contextualize current market conditions against past cycles and project future demand with confidence. The data indicates a clear upward trajectory, with the market expanding from approximately 662.45 million USD in 2020 to an estimated 940.5 million USD in 2025. This expansion underscores a sustained adoption curve as industries across multiple sectors retire legacy equipment in favor of advanced turbo blower solutions.
Worldwide Permanent Magnet Turbo Blower Market
Looking ahead, the forecast period reveals continued momentum. By 2026, the market is projected to reach approximately 1035.93 million USD, signaling a pivotal year of growth as new installations accelerate and replacement cycles mature. The compound annual growth rate over the forecast horizon is estimated at 7.85 percent, reflecting steady demand driven by infrastructure modernization, environmental compliance, and industrial automation. While the overall figures speak to the aggregate opportunity, the true strategic value for our clients lies in understanding the nuanced drivers behind this growth. In our full report, we dissect the revenue streams and volume projections to reveal where the opportunities are concentrated, which application verticals are outpacing others, and how regional demand patterns are shifting in response to local policy and investment climates. We deliberately withhold the specific percentage splits and regional breakdowns in this overview to encourage a deeper dive into the proprietary intelligence that supports informed sourcing and market entry decisions.
The growth narrative is not merely about unit volume; it is about value migration. As turbo blowers become more sophisticated—integrating magnetic levitation, air foil bearings, and high-speed permanent magnet synchronous motors—the value proposition shifts from initial capital cost to lifecycle efficiency. Organizations that recognize this shift are positioning themselves to capture cost savings and operational resilience. Our market sizing analysis provides the baseline figures necessary to benchmark internal projects against industry-wide adoption rates, but the report goes further by modeling scenarios that account for varying adoption speeds across different end-user industries. This enables readers to stress-test their investment theses against a range of plausible futures.
Sector Dynamics and Technological Drivers
The adoption of permanent magnet turbo blowers is propelled by a convergence of technological maturity and operational necessity. In municipal and industrial wastewater treatment, aeration remains the single largest consumer of electricity, often accounting for a significant majority of a plant's total energy bill. Sector analysis from 2025 highlights that facilities are increasingly specifying magnetic levitation or permanent magnet turbo blowers for aeration duties, citing energy savings ranging from 30 to 45 percent compared to traditional Roots blowers. This efficiency delta is transformative for operators seeking to reduce operating expenditures while meeting discharge standards. The ability to modulate airflow precisely via variable frequency drives (VFDs) further enhances process control, allowing plants to adapt to fluctuating inflow conditions without sacrificing treatment quality.
The engineering community is also responding to the demand for reliability and maintenance reduction. Magnetic levitation bearings and air foil bearing systems eliminate mechanical contact, drastically reducing wear and extending service intervals. This is particularly valuable in harsh industrial environments where downtime is costly and access to rotating equipment is limited. Companies like RAETTS, APG-Neuros, and Howden have been at the forefront of integrating these technologies, offering plug-and-play solutions that combine high-efficiency motors with advanced suspension systems. For instance, the CubusTurbo models from Howden and the air-bearing systems pioneered by APG-Neuros exemplify the trend toward turnkey installations that minimize commissioning complexity. In our detailed report, we analyze the technical differentiators across bearing types and motor configurations, helping procurement teams evaluate which architecture aligns best with their specific duty cycles and environmental constraints.
Supply chain dynamics are another critical variable influencing market behavior. The permanent magnets used in high-speed turbo blowers rely heavily on neodymium-iron-boron (NdFeB) sintered grades, a material class subject to both commodity price fluctuations and geopolitical supply considerations. Recent data indicates that neodymium prices have experienced volatility, with values reaching approximately 995,000 CNY per ton in early April 2026. Such fluctuations can impact the cost structure of blower manufacturers and, by extension, the pricing available to end-users. In response, supply chain diversification efforts are accelerating as companies seek to mitigate risk and secure raw material access. Our report incorporates these dynamics into a broader cost and pricing analysis, providing insights into how material trends may affect project budgets over the forecast period and what mitigation strategies manufacturers and buyers are employing.
Regulatory environments also play a pivotal role in shaping demand. Energy conservation standards and efficiency metrics are continually evolving, prompting industries to reassess their equipment lifecycles. In the United States, proposed energy conservation standards for fans and blowers have undergone significant regulatory review, including discussions around metrics such as the Fan Energy Index. These regulatory developments signal a long-term direction toward higher efficiency, even if specific rulemaking timelines may shift. The industry has adapted by advancing motor and impeller designs that exceed existing benchmarks, ensuring compliance while delivering operational benefits. Our study evaluates the regulatory landscape across key markets, identifying how compliance requirements may drive procurement priorities and influence the relative attractiveness of different blower technologies in the coming years.
Competitive Landscape and Key Players
The permanent magnet turbo blower market is characterized by a diverse array of manufacturers, each bringing distinct technological heritage, regional presence, and product specialization to the table. Market concentration metrics indicate a moderately fragmented landscape, with the top three players holding approximately 38.5 percent of the market and the top five accounting for roughly 56.4 percent. This structure suggests that while leading incumbents command significant share through established reputations and installed bases, there remains ample room for innovation and regional dominance by specialized players. Understanding the positioning of these entities is essential for buyers evaluating vendor capabilities and for competitors assessing market entry or expansion strategies.
Aerzen, headquartered in Germany, stands as a leading high-speed turbo blower manufacturer with a heritage dating back to 1911. The company offers energy-efficient solutions for aeration and industrial applications, including models compatible with advanced drive technologies. Sulzer, based in Switzerland, provides HST turbocompressors that combine magnetic bearings with high-efficiency permanent magnet synchronous motors, targeting low-pressure industrial and wastewater aeration applications. Kaeser, also from Germany, manufactures turbo blowers featuring high-speed permanent magnet motors with wear-proof magnetic bearings designed for oil-free pressurized air in industrial processes. These European firms represent a strong tradition of engineering excellence and are frequently specified in projects demanding high reliability and integration with existing plant infrastructure.
In Asia, companies such as RAETTS from China specialize in air bearing and maglev turbo blowers that integrate permanent magnet ultra-high-speed motors with high-precision impellers and suspension bearings. Their focus on high-efficiency wastewater and industrial use reflects the rapid industrialization and infrastructure investment driving demand in the region. Dereike, likewise based in China, offers DPT series permanent magnet high-speed turbo blowers catering to applications including automobile equipment and industrial drying. Jaguar Compressors supplies the ZTB series as part of a broader compressor and blower portfolio, while Huifeng Motors, with expertise since 1989, manufactures permanent magnet turbo blowers including models with ceramic bearings. These players contribute to a competitive dynamic where price, performance, and localized service networks play crucial roles in winning projects.
North American participants bring a strong emphasis on integration and application-specific solutions. Lone Star Blower, with over 5,000 installations, manufactures gearless high-speed turbo blowers with direct drive foil bearing permanent magnet motors and integrated VFDs for air and pressure applications. Hoffman & Lamson, part of Gardner Denver, offers high-speed turbo blowers ranging from 400 to 700 HP, equipped with permanent magnet synchronous motors, VSD, and water jacket cooling for demanding industrial uses. Xylem, through its Sanitaire TurboMAX line, provides single-stage centrifugal turbo blowers with permanent magnet synchronous motors and VFDs optimized for wastewater aeration. APG-Neuros, based in Canada, pioneered air-bearing turbo blowers with permanent magnet synchronous motors and has established an extensive presence in North American wastewater treatment projects. These firms illustrate how regional expertise and application knowledge can differentiate offerings in a competitive marketplace.
Additional contributors include Kay International from India, which produces turbo blowers with high-speed permanent magnet motors, air foil bearings, and 100 percent oil-less systems for high-efficiency industrial applications. Pedro Gil from Spain offers TPG turbo blowers with high-efficiency permanent magnet synchronous motors and VSD for industrial processes. Dutair from the Netherlands develops turbo blowers with permanent magnet motors optimized for electric and magnetic properties at high revolutions. GL-TURBO operates as a global manufacturer with facilities in multiple countries, serving industrial markets with a broad product range. Howden, based in the UK, supplies centrifugal blowers including CubusTurbo models with active magnetic bearing technology and high-efficiency designs, further enriching the global competitive mix.
Recent industry activity underscores the vibrancy of this competitive landscape. At WEFTEC 2025, multiple manufacturers showcased innovations and new product lines. Kaeser exhibited updated magnetic bearing turbo blower models, including the ZS6 up to 500 horsepower, highlighting advancements in high-power applications. Howden presented the CubusTurbo plug-and-play turbo blower with active magnetic bearing motor technology and high efficiency, emphasizing ease of installation and operational performance. Kawasaki introduced a new MACTurbo magnetic bearing turbo blower product line, expanding its portfolio for industrial users. Meanwhile, procurement actions are equally telling. In June 2025, the City of Chehalis, in collaboration with HDR Engineering, issued a pre-qualification for magnetic bearing turbo blowers, referencing a prior Sulzer 150 HP installation and planning for 2026 deliveries. Such developments illustrate how technology demonstrations and municipal procurement cycles converge to shape the near-term market. In our full report, we provide a detailed competitive analysis that maps each company's product portfolio, strategic moves, and market share dynamics, enabling readers to benchmark their options and anticipate competitor responses.
Report Scope and Operational Value
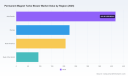
The Worldwide Permanent Magnet Turbo Blower Market research from PW Consulting is structured to deliver actionable intelligence across multiple dimensions. Beyond the macro revenue figures and growth rates highlighted here, the report offers a granular dissection of market segments that is critical for targeted strategy development. We analyze demand by region, breaking down the revenue contributions from Asia Pacific, Europe, North America, and the Rest of the World to reveal where growth is most pronounced and where mature markets may offer stability versus emerging opportunities. By application, we examine the distribution across municipal wastewater treatment, industrial wastewater treatment, cement and mining, food and beverage, and chemical and pharmaceutical sectors, providing context on which verticals are driving adoption and why. By bearing type, we differentiate between air foil bearing and magnetic levitation bearing technologies, outlining their respective advantages, typical use cases, and market penetration. These segmentation insights are essential for companies looking to prioritize sales efforts, refine product roadmaps, or identify gaps in the competitive landscape.
The report also includes a comprehensive competitive profiling section. For each key company, we provide a detailed overview of product offerings, technological strengths, geographic footprint, and recent strategic developments. This enables readers to compare vendors on attributes that matter most to their procurement criteria, such as efficiency ratings, bearing technology, motor specifications, and integration capabilities. We further analyze the competitive dynamics to assess barriers to entry, differentiation strategies, and potential consolidation trends. For procurement teams, this section serves as a vendor evaluation framework; for investors and strategists, it offers a lens into which players are gaining momentum and which face challenges in a tightening market.
Operational utility is a core design principle of our research. The report contains market sizing and forecast data in USD millions, complete with historical baselines and forward-looking projections, allowing finance and planning teams to build business cases aligned with industry trends. We also include qualitative analysis of market drivers, restraints, and opportunities, contextualized with regulatory developments, raw material dynamics, and macro trends. This holistic approach ensures that decision-makers understand not just the numbers, but the stories behind them. For example, our discussion of neodymium price volatility and supply chain diversification efforts provides a practical lens for assessing procurement risk, while our review of wastewater sector efficiency requirements helps engineering teams justify technology upgrades. The report is designed to be referenced throughout the planning cycle, from initial concept to vendor selection and post-deployment performance benchmarking.
Strategic Applications for 2026 Decision-Making
As enterprises approach 2026, the permanent magnet turbo blower market presents multiple pathways for strategic advantage. For manufacturers and suppliers, the growth trajectory offers an opportunity to capture share by differentiating on technology, service, and total cost of ownership. Understanding the segment-level demand patterns allows companies to allocate resources efficiently, focusing on applications and regions with the highest potential return. For example, the strong presence of municipal wastewater treatment as a primary end-user industry suggests that partnerships with engineering firms and municipalities can be highly rewarding, particularly when supported by proven installations and energy savings evidence. Similarly, industrial sectors such as cement, mining, and food and beverage are increasingly exploring turbo blowers for process air and drying applications, creating cross-industry demand that diversified suppliers can address.
For end-users, including municipalities, industrial operators, and engineering consultants, the market research provides a foundation for procurement strategy. With the forecast indicating continued market expansion through 2032, the timing of capital investments matters. Early engagement with preferred vendors, evaluation of bearing type trade-offs, and consideration of lifecycle costs rather than upfront price can lead to significant operational benefits. The availability of magnetic levitation and air foil bearing systems, combined with permanent magnet synchronous motors and VFD integration, gives buyers a range of options to match specific process requirements. Our report's segmentation data, when fully reviewed, helps buyers map their project profiles to the most suitable technology and vendor, reducing the risk of mismatched specifications and ensuring that efficiency targets are met.
Supply chain and risk management considerations are equally important in 2026 planning. The reliance on rare earth elements for permanent magnets means that raw material trends can influence pricing and availability. Organizations that monitor these dynamics and engage with suppliers who have diversified sourcing strategies are better positioned to manage cost volatility. Furthermore, regulatory developments, even those that may be withdrawn or revised, signal the direction of future standards and can influence long-term equipment selection. By incorporating these factors into decision-making, organizations can build resilience into their asset portfolios and avoid stranded investments.
Conclusion: A Call to Deepen Intelligence
The permanent magnet turbo blower market stands at a pivotal juncture, characterized by robust growth, technological advancement, and intensifying competition. The figures we have shared point to a market exceeding 1 billion USD in 2026 and growing steadily toward nearly 1.6 billion USD by 2032, with a compound annual growth rate of 7.85 percent. These numbers, however, are only the surface of a much richer story. The true value for strategic decision-makers lies in understanding the segment-level nuances, competitive dynamics, and external factors that will shape outcomes in specific regions and applications. Our full report, Worldwide Permanent Magnet Turbo Blower Market, delivers that depth. It provides the detailed segmentation splits, company-by-company profiles, scenario-based forecasts, and operational insights that transform high-level trends into executable strategy.
In an environment where energy efficiency, compliance, and reliability are non-negotiable, access to precise and current market intelligence is a competitive asset. PW Consulting's research is built to support that need, offering a rigorous foundation for procurement, product planning, and market strategy. We invite you to explore the complete study to unlock the full scope of data and analysis available. By doing so, you equip your organization with the clarity required to navigate the permanent magnet turbo blower market with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Permanent Magnet Turbo Blower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Highlights Worldwide Sulphur Hexafluoride Market to Reach 444.54 Million USD by 2032 with 5.02 CAGR
By PW Consulting, 2026-09-02
Navigating the Paradox of Growth and Regulation: Strategic Insights into the Global Sulphur Hexafluoride Market (2026-2032)
The global market for Sulphur Hexafluoride (SF6) stands at a critical inflection point. As the most potent greenhouse gas known to science, SF6 presents a unique paradox for industry leaders: it is indispensable for high-voltage electrical insulation and semiconductor manufacturing, yet it faces escalating regulatory scrutiny driven by its extreme global warming potential. For stakeholders operating in this sector, the ability to navigate the tension between persistent industrial demand and tightening environmental compliance will define competitive advantage over the next decade.
Worldwide Sulphur Hexafluoride (SF6) Market
PW Consulting's latest Worldwide Sulphur Hexafluoride (SF6) Market research report offers a comprehensive strategic roadmap for this complex landscape. By analyzing historical performance from 2020 through the base year of 2025 and projecting trends through 2032, this study provides the granular intelligence required to make informed capital allocation, supply chain, and compliance decisions. This article serves as an executive overview of the market dynamics, competitive structures, and regulatory currents shaping the SF6 industry, highlighting the strategic necessity of deep-dive intelligence in an era of rapid policy change.
Worldwide Sulphur Hexafluoride (SF6) Market
Market Trajectory: Sustained Expansion Amidst Compliance Costs
The historical data underscores the resilience of SF6 demand despite growing environmental awareness. In 2020, the global market generated revenue of USD 245.1 Million. This figure climbed steadily over the subsequent five years, reflecting the ongoing electrification of global infrastructure and the expansion of semiconductor fabrication capacities. By 2024, market revenue had reached USD 319.08 Million. The base year, 2025, recorded a valuation of USD 315.51 Million, indicating a market that is maturing but still fundamentally robust.
Worldwide Sulphur Hexafluoride (SF6) Market
Looking forward, the forecast period from 2026 to 2032 suggests a trajectory of moderate but consistent growth. The market is projected to reach USD 331.14 Million in 2026, continuing to expand towards USD 444.54 Million by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 5.02 percent. For strategic planners, this CAGR is a critical metric; it suggests that while alternative technologies are being developed, the latency in grid infrastructure replacement cycles and the specific performance requirements of high-tech manufacturing will sustain SF6 demand for the foreseeable future.
However, the revenue curve is not without volatility. The slight dip observed between 2024 and 2025 in the historical data warrants attention. While the overall trend is upward, this fluctuation may reflect early-stage adjustments in procurement strategies as utilities and manufacturers begin to internalize the costs of compliance with emerging regulations. Understanding the drivers behind such fluctuations is essential for accurate forecasting, and our full report deconstructs these variances to separate cyclical noise from structural shifts.
Regulatory Dynamics: The Defining Force of the Decade
No analysis of the SF6 market is complete without a rigorous examination of the regulatory environment. The industry is currently navigating a patchwork of regional regulations that are fundamentally altering the cost structure and availability of SF6 gas-insulated equipment (GIE). These regulations do not merely suggest compliance; they mandate operational changes that will reshape procurement cycles and equipment lifecycles.
In North America, the regulatory landscape has become particularly stringent. The California Air Resources Board (CARB) has been implementing amendments since 2022 that phase out the acquisition of new SF6 gas-insulated equipment starting in 2025. This phaseout is accompanied by strict emissions limits and inventory requirements. For utilities and industrial operators in California, this means that new capital expenditures on SF6-based infrastructure are increasingly restricted, pushing the market toward maintenance of existing assets or exploration of alternative gases.
Similarly, the New York State Department of Environmental Conservation (DEC) finalized Part 495 regulations in December 2024. These regulations introduce a voltage-based phaseout of SF6 GIE beginning in 2027. Furthermore, they establish a systemwide emissions limit of 1 percent starting in 2030. These timelines are critical for project planners. A project scheduled for deployment in 2028 in New York must now account for potential restrictions on SF6 equipment that would have been permissible just a few years prior. The compliance burden extends beyond equipment procurement to include detailed reporting and emissions tracking, adding layers of operational complexity.
At the federal level, the US EPA continues to refine reporting requirements under the Greenhouse Gas Reporting Program. Regulatory updates published in early 2025 detailed changes to Subpart DD, affecting reporting thresholds and calculation methods for SF6 and other insulating gases. These updates require facilities to maintain precise records of gas usage and leaks, with significant implications for audit readiness and potential penalty exposure.
In Europe, the EU F-gas regulations continue to drive the development and adoption of SF6 alternatives. With policies actively encouraging the use of mixtures such as fluoronitrile (C4F7N) for high-voltage equipment, European manufacturers are under pressure to innovate or transition their product lines. While these alternatives are not yet universally applicable across all voltage ratings and applications, the regulatory direction is clear: the long-term viability of pure SF6 in high-voltage applications is being systematically reduced in key Western markets.
Strategic Implications for Industry Stakeholders
The convergence of steady market growth with aggressive regulatory phase-downs creates a nuanced strategic environment. Companies cannot rely solely on historical demand patterns to guide future investments. Instead, they must adopt a segmented approach that acknowledges regional disparities and application-specific constraints.
For utilities and power distributors, the immediate challenge lies in asset management. As regulations like New York's Part 495 come into effect, the lifespan and maintenance protocols of existing SF6-based switchgear and circuit breakers become critical. Operators must balance the desire to extend the life of current infrastructure with the need to prepare for eventual phaseouts. This involves investing in advanced recycling and recovery systems to minimize emissions and ensure compliance with tightening leak limits. The market for SF6 recycling and reclamation services is likely to grow in parallel with primary gas sales, offering a avenue for service-based revenue models that mitigate regulatory risk.
In the semiconductor manufacturing sector, the reliance on high-purity SF6 for etching and cleaning processes remains high. Unlike the electrical transmission sector, the semiconductor industry faces different technical barriers to substitution. Here, the market growth is tied more closely to the expansion of fabrication capacity globally, particularly in regions with less stringent immediate phase-down mandates. However, multinational semiconductor firms must navigate a complex web of supply chain disclosures and carbon footprint reporting, making the purity and sourcing of SF6 a matter of corporate sustainability reporting as well as technical performance.
Magnesium smelting and other niche applications also contribute to the demand profile, though they represent a smaller fraction of the total market. For these sectors, the strategic focus is often on cost efficiency and supply security. Fluctuations in raw material costs, particularly sulfur and fluorine derivatives, can impact pricing stability. Understanding the supply chain dynamics for these feedstocks is essential for maintaining margin stability in cost-sensitive industries.
Competitive Landscape: Consolidation and Specialization
The SF6 market is characterized by a moderate level of concentration, with the top three companies holding approximately 42.5 percent of the market share and the top five accounting for 61.8 percent. This structure suggests an oligopolistic environment where large, established players dominate, but there remains room for specialized competitors to capture niche segments or regional markets.
Global industrial gas giants form the backbone of the supply chain. Companies such as Solvay SA, based in Belgium, and Linde plc, headquartered in Ireland, are prominent suppliers of high-purity SF6. Solvay produces both electronic-grade and technical-grade SF6, including specific high-purity grades like N5.0 (99.999 percent) tailored for semiconductor manufacturing and electrical insulation. Linde offers similar high-purity solutions for power transmission and distribution equipment, leveraging its massive global distribution network to serve utility-scale clients.
Air Liquide, based in France, and Air Products and Chemicals, Inc., from the United States, are also key players. Air Liquide supplies SF6 for electrical insulation in high-voltage equipment and electronics manufacturing, while Air Products focuses on utility and industrial applications, including gas-insulated switchgear and circuit breakers. These large entities benefit from economies of scale and diversified portfolios, allowing them to absorb some of the volatility associated with regulatory shifts and raw material price changes.
Specialized and regional suppliers play a vital role in filling specific gaps within the market. Concorde Specialty Gases, Inc., based in the United States, stands out as a leading global supplier of virgin, recycled, and custom-blended SF6 gas. Their focus on recycling systems and services for utilities positions them well in a regulatory environment that prioritizes emissions reduction and gas recovery. Similarly, Hudson Technologies provides full-service SF6 supply, recycling, recovery, and compliance services, catering directly to the needs of utilities facing stricter reporting and leakage requirements.
In the electronics sector, companies like Advanced Specialty Gases and Matheson Tri-Gas, Inc. supply specialty SF6 gases for electronics and power industries. Electronic Fluorocarbons, LLC (EFC Gases & Advanced Materials) offers high-purity SF6 with tight control of moisture and impurities, which is critical for demanding semiconductor applications. These suppliers compete on technical specifications and quality assurance rather than just volume.
The Asia Pacific region, which contributes a significant portion of the global market volume, hosts important producers such as Showa Denko K.K. (Resonac Holdings Corporation) and Kanto Denka Kogyo Co., Ltd. in Japan, as well as Fujian Yongjing Technology Co., Ltd. in China. These companies serve domestic and export markets for electrical and electronics sectors. As manufacturing capacity continues to shift towards Asia, the influence of these regional players on global supply dynamics is expected to grow. A-Gas, operating in the United Kingdom and Australia, and SicgilSol India Private Limited in India further illustrate the geographic spread of suppliers, ensuring regional availability but also highlighting the fragmented nature of distribution networks outside the major global hubs.
Segmentation Insights: Grades, Applications, and Regions
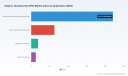
Understanding the market requires a clear view of how demand is distributed across different grades, applications, and regions, though the specific percentage splits reveal strategic priorities that vary by geography. The market is primarily divided into Technical Grade and Electronic Grade SF6. Technical Grade dominates the volume side, catering heavily to electrical transmission and distribution, as well as magnesium smelting. Electronic Grade, while smaller in total volume, commands higher value due to the stringent purity requirements of the semiconductor industry. The balance between these two grades is a key indicator of market health; shifts in the ratio can signal changes in demand from the power sector versus the high-tech manufacturing sector.
By application, Electrical Transmission and Distribution remains the largest consumption avenue. This segment includes gas-insulated switchgear, circuit breakers, and other high-voltage equipment. The growth here is tied to grid modernization and expansion projects worldwide. However, this is also the segment most exposed to regulatory phase-downs in regions like California and New York. Semiconductor Manufacturing represents the second major pillar, driven by the relentless demand for advanced chips. This application is less susceptible to immediate equipment phaseouts but faces pressure regarding carbon footprint accounting and supply chain sustainability. Magnesium Smelting and Other Applications make up the remainder, providing stability but less growth momentum compared to the primary sectors.
Regionally, the market is distributed across Asia Pacific, North America, Europe, and the Rest of the World. Asia Pacific is a major hub for both consumption and production, reflecting the concentration of electronics manufacturing and rapid infrastructure development. North America and Europe are mature markets where growth is increasingly driven by replacement cycles and maintenance rather than greenfield expansion, partly due to the regulatory environment. The Rest of the World segment captures emerging demand in other developing economies. Each region presents a distinct risk-reward profile based on its regulatory timeline and industrial growth rate. Detailed regional analysis is crucial for companies deciding where to allocate sales resources or establish new distribution centers.
For manufacturers and suppliers, knowing the specific revenue contributions of each segment is vital for product portfolio management. For instance, if the regulatory pressure on electrical transmission grows faster than anticipated, companies with a heavier weighting in Electronic Grade or Semiconductor applications may be more resilient. Conversely, suppliers specializing in recycling and recovery services may find new growth opportunities as the regulations on emissions tighten. Our full report provides the precise segmentation data necessary to model these scenarios accurately.
Feedstock and Supply Chain Considerations
The production of SF6 relies on specific raw materials, primarily sulfur, which serves as the feedstock reacted with fluorine. Fluorine is often derived from hydrofluoric acid processes. This supply chain linkage means that the SF6 market is indirectly exposed to the dynamics of the chemical and mining sectors. Fluctuations in the availability or price of sulfur and fluorine derivatives can impact production costs and margins.
In a market where pricing power is influenced by both oligopolistic supply structures and regulatory compliance costs, supply chain resilience is a strategic asset. Companies that can secure stable feedstocks or integrate vertically may hold a competitive edge. Additionally, the logistics of handling high-purity gases require specialized infrastructure, creating barriers to entry that protect incumbent suppliers but also limiting the speed at which new competitors can enter the market. Understanding these supply chain constraints is essential for risk management, particularly in regions where infrastructure development is lagging behind industrial demand.
Conclusion: The Imperative for Deep Intelligence
The SF6 market in 2026 and beyond is defined by a dual narrative of necessity and restriction. Industries cannot function without the unique dielectric properties of SF6 in many high-voltage and semiconductor applications, yet they must operate within an increasingly tight regulatory framework that penalizes emissions and limits new equipment installation. The projected growth to USD 444.54 Million by 2032 suggests that demand will persist, but the path to that revenue will be shaped by compliance strategies, regional variations, and the success of alternative technologies.
Strategic decision-making in this environment requires more than top-line figures. It demands an understanding of the specific regulatory timelines, the competitive capabilities of key suppliers, the nuances of grade-specific demand, and the vulnerabilities in the supply chain. Partial data can lead to misallocated resources or compliance failures. The full PW Consulting Worldwide Sulphur Hexafluoride (SF6) Market report provides the comprehensive intelligence needed to navigate this complexity. From detailed segmentation analysis to granular competitor profiling and regulatory impact assessments, this research equips stakeholders with the tools to optimize their market position.
For executives planning capital investments, supply chain adjustments, or product development roadmaps, the depth of insight contained in this study is indispensable. To access the complete dataset, including precise regional breakdowns, application-specific revenue figures, and detailed forecasts through 2032, we invite you to explore the full report. In a market where margins are influenced by regulation as much as by supply and demand, precise intelligence is the ultimate competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Sulphur Hexafluoride (SF6) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Global Sunlight Readable LCD Market to Reach US$12 Billion by 2032 with 7.5% CAGR
By PW Consulting, 2026-09-02
Navigating Visibility: Strategic Insights into the Global Sunlight Readable LCD Market
In an era where digital interfaces must perform flawlessly regardless of environmental conditions, the demand for displays that maintain clarity under direct sunlight has transitioned from a niche requirement to a strategic imperative. As outdoor connectivity expands, industrial automation intensifies, and vehicular interfaces become more complex, the ability to render crisp, legible information in high-luminance environments is no longer optional—it is a competitive differentiator. Our latest research, the Worldwide Sunlight Readable LCD Market study, delivers a comprehensive blueprint for stakeholders navigating this high-growth sector through 2032.
Worldwide Sunlight Readable LCD Market
The report is designed not merely as a statistical snapshot, but as a decision-making toolkit for executives, product strategists, supply chain planners, and investors. By synthesizing historical performance with forward-looking projections, the analysis equips organizations with the contextual intelligence needed to allocate capital, prioritize R&D, and position portfolios against shifting macroeconomic and geopolitical currents.
Worldwide Sunlight Readable LCD Market
Market Trajectory and the Strategic Rationale for 2026 Decision-Making
The global market for sunlight readable LCD displays has demonstrated consistent expansion over the past half-decade, reflecting a broader industry shift toward ruggedized, high-visibility human-machine interfaces. Based on historical tracking from 2020 through the base year of 2025, the sector has moved from a measured baseline into a phase of accelerated momentum. The total market valuation, tracked in millions of USD, climbed steadily across the historical window, establishing a robust foundation for the forecast period extending from 2026 through 2032.
Worldwide Sunlight Readable LCD Market
Looking ahead, the compound annual growth rate is projected at 7.5 percent, signaling a trajectory that outpaces many conventional display segments. This growth is not incidental; it is structurally anchored in the proliferation of outdoor digital signage networks, the digitization of industrial and marine control systems, and the increasing integration of high-brightness panels into transportation and automotive platforms. The forecast model maps a clear upward arc, with market valuation expected to cross the 7,500 million mark in 2026 and continue climbing toward the 11,900 million range by the close of the forecast window.
For enterprises making 2026 commitments, this trajectory carries immediate implications. Capacity planning, component sourcing, and product roadmap alignment must account for a market that is both expanding and maturing simultaneously. The window to establish supply agreements, lock in technology partnerships, and capture early-mover positioning in emerging application verticals is narrowing. Organizations that treat this growth phase as a discretionary opportunity rather than a structural shift risk ceding ground to competitors who are already recalibrating their strategies around high-brightness display ecosystems.
Technological Architecture and the Core Segmentation Landscape
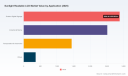
The sunlight readable LCD segment is defined by a distinct set of engineering approaches, each optimized for different luminance targets, environmental tolerances, and cost-performance thresholds. The market is shaped primarily by three technology pathways that dominate commercial and industrial deployments. Optical bonding has emerged as a critical enabler for applications demanding maximal contrast retention and reduced parasitic reflection, particularly in environments where screen readability directly impacts operational safety or user experience. Transflective LCD architectures remain highly relevant for scenarios where power efficiency and ambient-light adaptability must be balanced against peak brightness requirements. High-brightness LED backlit solutions continue to serve as the workhorse for installations requiring sustained luminance levels exceeding standard indoor display thresholds, with engineering teams increasingly refining backlight uniformity and thermal management to extend lifecycle reliability.
Complementing these technology vectors, the application landscape is organized around several high-impact verticals. Outdoor digital signage represents a substantial share of demand, driven by the global expansion of public information networks, retail activation platforms, and transit-oriented displays that must operate continuously under variable illumination conditions. Industrial and marine applications form another cornerstone of the market, where equipment manufacturers rely on sunlight readable panels for control stations, navigation interfaces, and heavy-asset monitoring systems deployed in unshielded or semi-routed environments. Transportation and automotive use cases add further complexity, as original equipment manufacturers and tier suppliers integrate high-visibility displays into instrumentation clusters, external communication panels, and specialty vehicle interfaces. A smaller but strategically important remainder of demand flows through adjacent sectors that require tailored form factors, extended temperature ranges, or specialized optical coatings.
Technology selection in this environment is rarely a purely engineering decision. It is a commercial calculation that weighs upfront module economics against long-term performance integrity, maintenance exposure, and the reputational cost of field failures. The market study dissects these trade-offs across multiple dimensions, enabling readers to benchmark technology suitability against specific deployment constraints rather than relying on generic luminance specifications.
Competitive Ecosystem: Differentiation, Scale, and Strategic Positioning
The competitive landscape for sunlight readable LCDs is characterized by a mix of established display specialists, regional manufacturing powerhouses, and highly focused niche providers. Leadership in this space is measured not only by production capacity but by the ability to deliver consistent optical performance, ruggedized form factors, and application-tailored integration support. Several companies have defined their market identity around high-brightness engineering expertise and domain-specific deployment knowledge.
Among the companies profiled in the report, Litemax has positioned itself as a pioneer and leader in high-brightness sunlight readable LCD displays, with product lines engineered to sustain luminance well beyond standard indoor thresholds and proprietary backlight technology designed for durability in direct sunlight. Its focus spans industrial, outdoor, marine, and digital signage applications, reflecting a portfolio aligned with high-visibility operational environments. Maclight Display operates as a specialist in custom TFT LCD modules, maintaining dedicated sunlight readable and high-brightness TFT lines across a wide size range and offering transflective options for industrial and commercial clients. Risingstar, active in the sector since 2009, manufactures high-brightness sunlight readable LCD displays with extreme luminance capabilities and broad size scalability, concentrating on OEM and ODM engagements for outdoor, transportation, and harsh-environment applications.
Further contributions to the competitive mix come from companies such as Chenghao Optoelectronics, which supplies sunlight readable TFT displays with high brightness ranges and targeted module configurations for outdoor, industrial control, and automotive auxiliary uses. AbraxSys, based in the United States, manufactures rugged sunlight readable LCD monitors and custom displays built for military, marine, oil and gas, and extreme-environment deployments, leveraging optical bonding and anti-reflective coatings to support demanding field conditions. Xenarc Technologies produces rugged high-brightness LCD monitors and touchscreens, including IP69K-rated models optimized for industrial, vehicle, and outdoor applications. CDTech contributes with high-brightness sunlight readable TFT LCDs for outdoor applications, offering custom-sized and bar-type panels supported by patented cutting technology and wide-temperature performance. Wisevision focuses on sunlight readable LCD solutions for industrial and outdoor use, while General Digital engineers sunlight readable and NVIS-compatible LCD displays with custom LED backlights for military, avionics, marine, and outdoor specialty markets.
The competitive narrative is not static. Recent industry activity underscores how rapidly technology roadmaps and application guidance are evolving. In March 2026, Anders Electronics published technical guidance on designing sunlight-readable displays for dynamic outdoor applications, emphasizing IPS-TFT architectures, Mini-LED integration, and system-level techniques for public information and industrial systems. This type of design-oriented discourse signals a broader shift from component-level competition toward solution-level differentiation. Earlier, in November 2025, Risingstar LCD highlighted advancements in high-brightness sunlight-readable screen technology that combine advanced LED backlights with anti-reflective features for extreme lighting conditions, reinforcing the industry's focus on optical performance under stress.
Market structure also reflects meaningful concentration. The report's concentration metrics indicate that a relatively small group of leading players commands a substantial portion of total revenue, while a broader tier of specialized manufacturers competes on customization, regional proximity, and application-specific engineering. For procurement leaders and partnership strategists, this concentration profile matters: it shapes negotiation leverage, supply assurance expectations, and the availability of second-source options in critical deployments.
Supply Chain Realities, Material Foundations, and Regulatory Overhang
High-brightness display manufacturing does not exist in a vacuum. The sector's performance is intertwined with raw material availability, substrate economics, component sourcing, and a gradually intensifying regulatory environment. On the materials side, the underpinnings of large-format and high-brightness panel production remain sensitive to substrate market dynamics. Broader industry data underscores the strategic weight of glass substrates in display ecosystems, with the global LCD glass substrates market valued at 14.6 billion USD in 2025 and projected to reach 24.1 billion USD by 2034. Within that landscape, the 8.5-generation substrate glass segment—critical for large-format LCD panel production including high-brightness variants—was valued at 757 million USD in 2025 and is projected to reach 1,757 million USD by 2034. These material trajectories influence yield economics, panel scaling options, and the cost structure that ultimately feeds into finished sunlight readable modules.
Beyond materials, regulatory and trade developments are reshaping supply chain calculus. Ongoing U.S.-China trade measures and export controls on advanced semiconductor equipment and related technologies continue to influence global display supply chains, including components used in high-brightness LCD backlights. Analysts observed in early 2026 that U.S. considerations for potential tariffs on display technology were being discussed as part of broader efforts to reduce reliance on China-dominated supply chains. At the same time, China implemented and partially suspended export controls on certain rare earth elements and critical materials used in display components and phosphors during 2025, with suspensions extending into 2026. These overlapping policy signals create a environment where sourcing strategy, inventory buffering, and supplier diversification are no longer back-office functions but central elements of product risk management.
The report integrates these dynamics into a practical framework, helping readers distinguish between transient disruptions and structural realignments. Understanding where material dependencies intersect with trade exposure enables organizations to model scenarios more realistically, particularly when planning multi-year commitments in high-brightness display programs.
What the Worldwide Sunlight Readable LCD Market Report Delivers
This study is built to convert complex market signals into actionable intelligence. Rather than offering a superficial overview, the report immerses readers in the operational details that decision-makers need when evaluating entry timing, portfolio expansion, supplier selection, or investment thesis validation. The analysis combines quantitative trajectory mapping with qualitative assessment of technology readiness, application momentum, and competitive maneuvering.
Readers will find structured insight into the forces shaping demand across outdoor, industrial, marine, transportation, and adjacent application spaces, along with the technology choices that underpin those demand patterns. The study frames the market through a lens that connects engineering differentiation with commercial outcomes, enabling teams to evaluate where brightness, durability, optical bonding, transflective design, or LED backlight strategy creates the strongest value capture in specific use cases.
Equally important, the report situates the competitive set within a realistic landscape of scale, specialization, and concentration. By examining the profiles, application focuses, and recent technology developments of core market participants, the analysis helps readers identify not only who is competing, but how they are competing and where vulnerabilities or opportunities may emerge. This is especially valuable for organizations assessing partnership structures, second-source strategies, or regional sourcing shifts in response to evolving trade and materials conditions.
The study also addresses the forward-looking dimension of market behavior. forecast modeling extends through 2032, giving stakeholders a multi-year view that supports capacity investments, product planning cycles, and strategic budgeting. By integrating historical performance with projected growth, the report offers a credible basis for scenario planning rather than a single-point prediction. Organizations can use the framework to test assumptions about adoption speed, technology migration, and vertical-specific demand intensity.
The Strategic Imperative for Executives and Product Leaders
The sunlight readable LCD market is entering a phase where growth, technology refinement, and supply chain complexity converge. For executives, this creates both opportunity and exposure. The opportunity lies in aligning product portfolios, sourcing strategies, and development roadmaps with a segment that is expanding at a meaningful pace and serving applications where display performance has direct operational and safety implications. The exposure arises from moving too slowly in a market where concentration, materials sensitivity, and regulatory volatility can alter cost structures and availability faster than traditional planning cycles anticipate.
In 2026, strategic advantage will belong to organizations that treat sunlight readable display capability as a core engineering and commercial competency rather than a specification checkbox. That means evaluating suppliers on more than brightness claims, understanding how technology pathways map to application risk profiles, and building supply architectures that can absorb material and trade shocks without compromising program timelines. It also means recognizing that competition is increasingly expressed through integration expertise, customization capability, and domain-specific reliability rather than price alone.
Accessing the Full Intelligence Picture
The Worldwide Sunlight Readable LCD Market report is designed as a working resource for teams that need depth, not headlines. It provides the analytical scaffolding required to make informed decisions about technology investment, supplier engagement, market entry, and portfolio optimization in a segment where visibility is both a literal and strategic requirement.
To explore the complete segmentation analysis, detailed market trajectory data, competitive profiles, regional and application-level insights, and the full set of forecast projections, readers are encouraged to access the full report on the PW Consulting source page. The complete study offers the granular intelligence necessary to convert market momentum into disciplined, evidence-based strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Sunlight Readable LCD Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports 6.78% CAGR for Worldwide Sheet Metal Tube Lifter Market Valued at 432.56 Million USD in 2025 to Reach 684.66 Million by 2032
By PW Consulting, 2026-09-02
Strategic Horizons in the Worldwide Sheet Metal Tube Lifter Market: A 2026 Decision-Making Compass
The global industrial landscape is undergoing a profound transformation, driven by an relentless pursuit of operational efficiency, workplace safety, and ergonomic excellence. Within this shifting paradigm, the sheet metal tube lifter market has emerged as a critical nexus for manufacturing sectors ranging from automotive assembly to aerospace fabrication. As companies navigate the complexities of 2026 and look toward the decade ahead, understanding the trajectory of this specialized equipment sector is no longer optional—it is a strategic imperative. The recently released Worldwide Sheet Metal Tube Lifter Market research study by PW Consulting offers a comprehensive lens through which executives, procurement leaders, and strategic planners can decode the forces shaping this industry.
Worldwide Sheet Metal Tube Lifter Market
This market research initiative is not merely a compilation of statistics; it is a decision-support tool engineered for the volatile realities of modern supply chains and production environments. By synthesizing historical performance data with rigorous forward-looking analysis, the report provides a foundational understanding of where capital should be allocated, which technologies are gaining traction, and how competitive dynamics are evolving. For stakeholders aiming to secure a competitive advantage in metal processing, fabrication, and material handling, this study serves as an essential blueprint for navigating the opportunities and risks of the coming years.
Worldwide Sheet Metal Tube Lifter Market
Market Trajectory and Growth Catalysts
The numerical backbone of any market analysis reveals the scale and momentum of industry expansion. Historical data from 2020 through 2025 illustrates a consistent upward trajectory in global revenue generation for sheet metal tube lifters, reflecting the widespread adoption of automated material handling solutions. Following a period of recovery and recalibration in the early 2020s, the market has demonstrated resilience and accelerating growth. The total revenue base has expanded steadily, underpinned by the ongoing modernization of manufacturing facilities and the substitution of manual handling processes with vacuum-based lifting technologies.
Worldwide Sheet Metal Tube Lifter Market
Looking forward, the forecast period spanning 2026 to 2032 projects a robust growth path for the sector. The analysis anticipates a compound annual growth rate (CAGR) of 6.78 percent over this forecast horizon, signaling sustained demand driven by industrial automation trends. By the close of the forecast window, the global market is expected to surpass significant revenue milestones, reflecting the cumulative effect of capacity expansions, technological advancements, and increasing penetration in emerging industrial markets. This growth is not linear but is instead shaped by distinct regional idiosyncrasies, application-specific demands, and product-level innovation cycles that the full report dissects in granular detail.
Several macro-level forces are fueling this expansion. The increasing emphasis on ergonomic workplace design is compelling manufacturers to invest in vacuum tube lifters that reduce operator strain and minimize injury risks associated with manual material handling. Simultaneously, the push toward higher throughput and precision in metal fabrication—particularly in sectors utilizing laser cutting, plasma processing, and automated assembly lines—is accelerating the integration of specialized sheet metal lifters. Regulatory frameworks mandating safer handling practices and the broader industry shift toward Industry 4.0 automation further reinforce the structural demand for these solutions. Steel, as the primary raw material and core component, anchors the manufacturing ecosystem, with vacuum pads and structural elements frequently relying on steel plates and profiles to ensure durability and load-bearing reliability.
Segmentation Architecture and Application Versatility
A critical dimension of the market's complexity lies in its segmentation. The worldwide sheet metal tube lifter market is demarcated by product type, application domain, and geographic footprint, each presenting unique growth vectors and competitive considerations. On the product front, the landscape encompasses standard vacuum tube lifters, heavy-duty sheet lifters engineered for high-capacity operations, and high-temperature resistant lifters designed for thermally challenging environments. The interplay between these categories reflects the diverse requirements of end-users, from general-purpose material handling to specialized applications demanding extreme durability or precision.
Application-wise, the market serves a broad spectrum of industrial verticals. Metal fabrication and warehousing represent a substantial share of demand, as these sectors rely heavily on efficient loading, unloading, and positioning of sheet metal substrates. Automotive manufacturing constitutes another major pillar, leveraging vacuum tube lifters to streamline the handling of body panels, structural components, and thin-gauge sheets within high-volume production lines. Aerospace and defense applications contribute a distinct demand profile, often requiring lifters that meet stringent safety, precision, and material compliance standards. Beyond these core segments, a variety of other industrial applications continue to adopt vacuum lifting technologies, expanding the addressable market and fostering cross-industry innovation.
Regional dynamics further complicate and enrich the market picture. Europe, Asia Pacific, North America, and the Rest of World each present distinct market characteristics shaped by local manufacturing footprints, regulatory environments, labor cost structures, and levels of automation maturity. Europe and Asia Pacific, for instance, stand as significant contributors to global revenue, reflecting the dense concentration of metal processing industries and the early adoption of ergonomic handling solutions in these regions. North America follows a closely contested trajectory, while other regions demonstrate variable growth patterns influenced by industrialization pace and infrastructure development. The report delves into these regional nuances without oversimplifying, offering decision-makers a nuanced view of where demand is crystallizing and how regional competitive postures differ.
Competitive Landscape and Strategic Positioning
The competitive architecture of the sheet metal tube lifter market is characterized by a mix of established multinational specialists and agile regional players, each vying for market share through technology differentiation, application-specific engineering, and strategic outreach. Market concentration metrics indicate that the top three companies command approximately 38.45 percent of the market, while the top five collectively hold around 52.12 percent, suggesting a moderately consolidated environment where scale, brand reputation, and technological prowess play decisive roles.
Among the key participants, ANVER Corporation stands out as a leading US manufacturer of vacuum material handling technology, with a portfolio that includes vacuum tube lifters and specialized solutions for curved loads such as tubing, bars, pipes, and sheet metal. Its positioning in the North American market underscores a focus on versatility and application breadth. In Europe, Schmalz GmbH has carved a strong niche as a specialist in vacuum automation and handling, offering products like the JumboErgo and JumboFlex vacuum tube lifters designed for ergonomic handling of flat sheet metal workpieces up to 300 kg, alongside the VacuMaster series for heavier sheets and plates. The company's continuous engagement with industry events—most recently exhibiting at MODEX 2026 to showcase vacuum tube lifters including JumboFlex—highlights its commitment to visibility and customer engagement in the material handling sector.
TAWI, part of the Piab Group and headquartered in Sweden, contributes a multifunctional approach with vacuum tube lifters capable of handling wood and metal sheets with capacities up to 270 kg. Its equipment supports ergonomic lifting, tilting, and rotation, appealing to users who require flexibility in material positioning. TAWI's participation in trade events such as MACH 2026 further cements its presence in the metal-working applications space. Meanwhile, Albert Fezer Maschinenfabrik GmbH (FEZER), a family-run German manufacturer, offers ergonomic vacuum lifting equipment including solutions for sheet metal plates and pipes/tubes, with models like VacuBoy for sheet metal handling and VacuMobiLift for flexible applications. FEZER's exhibition at LogiMAT 2026 in Stuttgart reflects the ongoing emphasis on showcasing vacuum lifting solutions tailored to sheet metal among other applications.
The competitive field also includes Righetti Vacuum Lifters from Italy, which provides a dedicated range for horizontal handling of sheet metal, steel, stainless steel, aluminium, and other non-ferrous materials, with a particular focus on loading and unloading laser cutting machinery. Its showcase of new suction lifters at GIS Expo 2025 illustrates the iterative innovation cycle that defines the market. In Asia, Shanghai Herolift Automation Equipment Co., Ltd. represents the growing capabilities of Chinese manufacturers, offering vacuum lifting devices and tube lifters specifically for sheet metal, including pneumatic models for steel plates and loading/unloading of laser/plasma cutting machines. Crosby Airpes, based in Spain with subsidiaries across Europe, the USA, and China, rounds out the landscape by designing and manufacturing sheet lifters that emphasize fast leg adjustment and side force application, catering to safe and efficient handling of steel plates and sheet metal.
These companies operate in an environment where product performance, reliability, and alignment with customer workflows are paramount. Competitive differentiation is increasingly achieved through ergonomic design, integration capabilities with existing automation systems, and responsiveness to regional regulatory and safety requirements. The full market research report provides a deeper competitive benchmarking framework, enabling readers to assess vendor capabilities against their own operational priorities.
Market Dynamics and Structural Drivers
Beyond segmentation and competition, the market is shaped by an interplay of structural dynamics that influence adoption rates, pricing trajectories, and technology evolution. A primary driver is the accelerating adoption of automation and ergonomic solutions in metal processing and fabrication industries. As manufacturers seek to improve efficiency and operator safety, vacuum tube lifters have become integral to workflows that demand repeatable, precise, and injury-free material handling. This shift is reinforced by regulatory expectations for ergonomic and safety standards compliance, which aim to reduce workplace injuries associated with manual handling in manufacturing settings.
Raw material considerations also exert influence on the market's development. Steel remains the primary raw material and core component for sheet metal tube lifters, with vacuum pads and structural elements often utilizing steel plates and profiles. Fluctuations in steel availability, pricing, and supply chain stability can therefore have ripple effects on manufacturing costs and product design strategies. Companies that manage these input dependencies effectively gain a competitive edge in cost control and production continuity.
Technological innovation continues to redefine product capabilities. Enhancements in vacuum pad materials, control systems, and load-sensing technologies are enabling lifters to handle a wider range of materials and thicknesses with greater adaptability. The convergence of vacuum lifting with broader automation ecosystems—including robotic integration and digital workflow monitoring—opens new avenues for value creation. As the market matures, end-users are increasingly looking for solutions that not only lift but also integrate into smart factory architectures, facilitating data-driven optimization of material handling processes.
The Strategic Value of the 2026 Intelligence Package
In an environment where capital allocation decisions carry long-term implications, access to granular, forward-looking intelligence is a decisive advantage. This Worldwide Sheet Metal Tube Lifter Market research study is designed to equip stakeholders with the insights needed to make informed choices across multiple dimensions of business strategy. For procurement and operations leaders, the report illuminates product type preferences, application-specific requirements, and regional demand patterns that can guide vendor selection and equipment specification. For strategic planners and investors, the analysis of market size evolution, CAGR projections, and competitive concentration offers a framework for evaluating growth potential and market entry timing.
The report's structure is built to support practical decision-making. It explores historical revenue performance, forecast trajectories, and the segmentation splits that define the market's internal architecture. It examines the roles of key companies, their strategic activities, and the broader industry context that shapes competitive behavior. By integrating trade show participation and product showcase data, the study captures the pulse of ongoing innovation and market engagement, helping readers anticipate emerging trends and technology shifts.
Importantly, the research maintains a disciplined focus on actionable intelligence without diluting complexity into oversimplified narratives. Decision-makers are encouraged to explore the full report to access detailed segmentation data, regional breakdowns, and application-level analysis that can be tailored to specific organizational contexts. The executive summary provided here serves as a strategic preview—a testament to the depth of analysis available—while the complete study delivers the comprehensive intelligence required for precise planning and execution.
Conclusion: Positioning for the Next Wave of Industrial Lifting
The worldwide sheet metal tube lifter market stands at a pivotal juncture, where ergonomic imperatives, automation adoption, and competitive innovation converge to create a dynamic growth environment. With a projected CAGR of 6.78 percent through 2032 and a market base that has demonstrated consistent expansion from 2020 to 2025, the sector offers substantial opportunities for organizations that can align their strategies with structural demand drivers. At the same time, the market's segmentation complexity, regional variations, and competitive concentration demand a nuanced approach to market participation and investment.
PW Consulting's in-depth market research study provides the analytical rigor and strategic clarity necessary to navigate this landscape with confidence. By leveraging historical context, forward-looking forecasts, competitive profiling, and industry dynamics, stakeholders can transform uncertainty into a structured pathway for growth. Those who engage with the full breadth of this research will be better positioned to identify high-value applications, select capable technology partners, and deploy sheet metal tube lifting solutions in ways that enhance safety, efficiency, and operational resilience. In the evolving world of industrial material handling, insight is the cornerstone of advantage—and this study is designed to deliver exactly that.
For detailed analysis of this topic, please visit the official page: Worldwide Sheet Metal Tube Lifter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Forecasts Worldwide Automatic Straw Briquetting Machine Market to Reach USD 942.77 Million by 2032 Growing at 7.8% CAGR
By PW Consulting, 2026-09-02
Strategic Intelligence for the Renewable Energy Transition: Inside the 2026 Automatic Straw Briquetting Machine Market
The global transition toward renewable energy sources has fundamentally altered the landscape of industrial machinery, placing automatic straw briquetting machines at the forefront of biomass energy conversion. As agricultural residues accumulate in unprecedented volumes, the demand for efficient, automated compaction technologies has surged. PW Consulting is pleased to introduce our latest comprehensive market study, Worldwide Automatic Straw Briquetting Machine Market, designed to equip stakeholders with the actionable intelligence required to navigate this evolving sector through 2032. This report serves not merely as a data repository, but as a strategic compass for capital allocation, product development, and competitive positioning in a market characterized by rapid technological iteration and shifting regulatory frameworks.
Worldwide Automatic Straw Briquetting Machine Market
The strategic value of this research for 2026 enterprise decision-making cannot be overstated. Organizations operating within the biomass supply chain, from machinery manufacturers to end-user energy producers, face a complex matrix of variables. These include fluctuating raw material costs, tightening carbon emission mandates, and an increasingly fragmented competitive field spanning multiple continents. Our analysis provides a granular view of these dynamics, enabling clients to anticipate market shifts rather than merely reacting to them. By understanding the underlying drivers of demand and the specific technological preferences emerging across different regions, decision-makers can optimize their operational strategies and capture growth opportunities that remain opaque to less specialized observers.
Worldwide Automatic Straw Briquetting Machine Market
Market Trajectory and Growth Dynamics
The historical performance of the automatic straw briquetting machine market demonstrates a consistent upward trajectory, reflecting the growing prioritization of waste-to-energy solutions. From 2020 to 2025, the market revenue expanded significantly, driven by heightened awareness of sustainable fuel alternatives and the economic viability of processing agricultural residues. The baseline data indicates a robust expansion from approximately 382.45 Million USD in 2020 to 557.28 Million USD in 2025. This growth pattern underscores the accelerating adoption rates as industries seek to decouple from fossil fuel dependencies.
Worldwide Automatic Straw Briquetting Machine Market
Looking forward, the forecast period from 2026 to 2032 projects continued momentum. The market is expected to reach 620.09 Million USD in 2026, escalating to 942.77 Million USD by 2032. This expansion corresponds to a Compound Annual Growth Rate of 7.8 Percent over the forecast horizon. Such growth rates suggest that the sector is moving beyond niche adoption into mainstream industrial application. For stakeholders, this implies that the window for establishing market leadership is narrowing. Early movers who secure supply chain advantages and technological patents now will likely dictate the terms of competition in the latter half of the decade.
Several macro drivers are fueling this expansion. The global availability of agricultural residues, estimated at over 1 billion tons annually, presents a vast feedstock opportunity. Converting this abundant material into dense bio-fuel briquettes reduces waste and offers a sustainable alternative to carbon-intensive fuels. Furthermore, energy efficiency and carbon emission reduction mandates in power, cement, and heating sectors are encouraging the use of biomass briquettes from straw as a sustainable fuel source without chemical additives. Regulatory pressure is no longer a peripheral concern but a central operational requirement, compelling industries to integrate briquetting solutions to remain compliant and competitive.
Technological Segmentation and Operational Efficiency
The market is diversified by technology type, each offering distinct advantages depending on the scale of operation and the specific characteristics of the feedstock. Hydraulic systems currently represent a significant portion of the market revenue, valued for their ability to compress straw into dense briquettes without additives. These systems are increasingly designed to integrate into production lines with minimal supervision, supporting revenue from bio-fuel sales for power plants and boilers. Mechanical piston and screw press technologies also maintain substantial market presence, catering to varying throughput requirements and budget constraints.
Recent procurement analysis highlights critical supply chain considerations that impact equipment costing. Global stainless steel prices rose 12 to 18 Percent year-over-year into early 2026, impacting procurement timelines and costs for hydraulic components in automatic straw briquetting equipment. Additionally, steel, the primary structural material for briquetting machine frames, presses, and molds, experienced volatility with U.S. Midwest hot-rolled coil prices stabilizing around 800 to 815 USD per short ton in late 2025. Understanding these material cost fluctuations is essential for pricing strategies and margin protection. Manufacturers who can mitigate these input cost risks through vertical integration or long-term supplier contracts will possess a distinct competitive advantage.
The shift toward automation is another critical trend. Modern systems are moving beyond simple compression to include complete automated lines with conveyors, lubrication systems, and control cabinets. This level of integration reduces labor dependency and ensures consistent briquette quality, which is vital for downstream combustion efficiency. As energy producers demand higher reliability from their fuel sources, the capability to offer turnkey automated solutions becomes a key differentiator in the sales process.
Regional Demand Patterns and Application Diversity
Geographically, the market exhibits varied growth drivers shaped by local agricultural outputs and energy policies. Asia Pacific currently holds the largest revenue share, reflecting the region's massive agricultural base and increasing industrialization. Europe follows with significant demand, driven by stringent environmental regulations and established biomass energy infrastructure. North America, Latin America, and the Middle East and Africa collectively represent growing markets where investment in renewable energy infrastructure is accelerating.
Application-wise, the primary demand stems from biomass power generation, which utilizes the dense briquettes to produce electricity and heat. Industrial boilers and furnaces constitute another major segment, where briquettes serve as a coal substitute to lower carbon footprints. Residential heating and animal feed production also contribute to the market, though to a lesser extent. It is important to note that detailed regional revenue percentages and specific application breakdowns are part of the proprietary intelligence within the full report, as these figures require nuanced interpretation based on local currency fluctuations and policy changes.
The diversity of applications means that equipment manufacturers must often customize their offerings. A machine suitable for a large-scale power plant may differ significantly from one designed for residential heating pellets. This customization requirement creates barriers to entry for generic manufacturers but offers high margin potential for those capable of engineering specialized solutions. Our report delve into how different players are navigating these segmentation challenges to maximize their addressable market.
Competitive Landscape and Key Player Strategies
The competitive environment is characterized by a mix of established European engineering firms and rapidly scaling manufacturers from Asia. Market concentration indicates that the top three players hold approximately 38.45 Percent of the market, while the top five control around 52.12 Percent. This indicates a moderately consolidated market where scale matters, but niche players can still thrive by focusing on specific regions or technology types.
C.F. Nielsen, headquartered in Baelum, Denmark, stands as a prominent example of engineering excellence in this space. The company offers mechanical briquetting presses with capacities ranging from 200 kg/h to over 3,500 kg/h suitable for agricultural residues including straw. With over 7,000 presses sold globally, their strategy emphasizes tailor-made solutions for biomass waste-to-energy conversion. In December 2025, C.F. Nielsen supplied multiple briquetting presses for what is described as potentially the largest briquetting plant, processing wood residues with applicability to biomass streams, involving new technology developments. This move signals their intent to lead in large-scale infrastructure projects.
RUF Briquetting Systems, based in Zaisertshofen, Germany with US operations in Ohio, specializes in hydraulic straw briquetting systems. Their machines compress straw into dense briquettes without additives and integrate into production lines with minimal supervision. With over 5,500 units in operation worldwide, RUF is actively expanding its visibility. Scheduled participation in the International BIOMASS Conference & Expo in March 2026 and planned attendance at the ReMA2026 Convention & Exposition in April 2026 demonstrate their commitment to showcasing briquetting systems including biomass/straw solutions to a global audience.
In the Asian manufacturing sector, Hebei Tiantai Biomass Energy Development Co., Ltd. from Shijiazhuang, Hebei Province, China, manufactures high-capacity biomass briquetting presses up to 10 t/h explicitly handling straw, hay, and agricultural residues. They offer complete automated lines with conveyors, lubrication systems, and control cabinets for fuel briquette production, with machines exported to over 30 countries. Other notable contributors include GEMCO Energy, which supplies punching-type automatic straw briquetting machines using two-stage compression for high-density briquettes from wheat/rice straw, and KX Machinery, which offers industrial straw briquette machines with dual-shaft designs emphasizing low energy consumption.
Regional players such as Ronak Engineering in India and Ecostan also produce straw briquetting machines as part of agro-waste solutions, including automatic and semi-automatic biomass models. Meanwhile, companies like WEIMA Maschinenbau GmbH in Germany and Biomasser Group in Poland provide modular turnkey solutions for transforming straw and hay residues into natural briquettes. The competitive dynamic is not just about price but about reliability, after-sales support, and the ability to adapt machinery to local feedstock variations. Detailed competitor benchmarking, including capacity comparisons and market share estimations by region, is extensively covered in the full report to assist in strategic planning.
The Strategic Imperative for 2026 and Beyond
Investing in the automatic straw briquetting machine market requires more than just observing growth numbers. It demands an understanding of the interplay between raw material volatility, regulatory shifts, and technological evolution. The 7.8 Percent CAGR is not a guarantee of uniform growth; it represents an average across a complex system where some regions and segments will outperform while others may face headwinds. For instance, while renewable energy demand drives adoption, supply chain disruptions regarding steel and hydraulic components can compress margins unexpectedly.
Our research Methodology ensures that these nuances are captured. We analyze not only the sold but the operational efficiency and integration capabilities of the systems. We look at how companies are responding to specific regulatory mandates in power, cement, and heating sectors that encourage the use of biomass briquettes. We also assess how the over 1 billion tons of globally available agricultural residues are being logistically managed to feed these machines efficiently. This holistic view is critical for investors and manufacturers who need to assess the long-term viability of specific market entries.
Furthermore, the report addresses the risks associated with market concentration. With the top five players holding over 52 Percent of the market, new entrants must identify gaps in service, technology, or geography to succeed. Alternatively, existing players must defend their positions through continuous innovation. The recent developments, such as major plant deliveries and significant trade show presences, indicate that competition is heating up. Stakeholders need to know who is expanding capacity, who is introducing new technology, and how these moves will affect pricing and availability in their specific target markets.
Navigating the Intelligence Gap
While this overview highlights the macro trends and key players, the full depth of the Worldwide Automatic Straw Briquetting Machine Market report provides the specific data points necessary for execution. Decision-makers require precise segmentation data, detailed competitor profiles, and scenario-based forecasts to build robust business plans. The general trends discussed here form the foundation, but the detailed breakdowns enable the precise calculations needed for ROI analysis and strategic positioning.
For example, understanding the exact revenue contribution of hydraulic versus mechanical systems in specific regions can dictate product sourcing decisions. Knowing the specific growth rates of biomass power generation versus industrial boilers in emerging markets can guide marketing spend. These details are crucial for avoiding costly missteps. Our team has compiled extensive primary and secondary research to ensure these insights are accurate and timely.
In conclusion, the automatic straw briquetting machine market represents a significant opportunity within the broader renewable energy sector. The convergence of regulatory pressure, raw material abundance, and technological maturity creates a favorable environment for growth. However, capitalizing on this opportunity requires sophisticated intelligence. PW Consulting's latest study offers that intelligence, structured to support high-level strategic decisions. We invite industry stakeholders to explore the full findings of the report to gain the comprehensive view necessary to thrive in this dynamic market landscape. The data available in the public domain only tells part of the story; accessing the complete dataset ensures that your strategy is built on the most accurate and detailed information available.
The implications for supply chain managers, product developers, and executive leadership are profound. Aligning corporate strategy with the detailed insights provided in our full analysis will enable organizations to mitigate risks associated with raw material price volatility and competitive pressure. As the market moves toward the 942.77 Million USD mark by 2032, the companies that succeed will be those that leverage deep market intelligence to navigate the complexities of global biomass energy conversion.
For detailed analysis of this topic, please visit the official page: Worldwide Automatic Straw Briquetting Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Forecasts Worldwide Paddle Dryers Market to Reach $1,243.2 Million by 2032 with a 5.28% CAGR
By PW Consulting, 2026-09-02
Strategic Imperatives in the Global Paddle Dryer Market: Navigating Growth, Efficiency, and Competitive Dynamics (2026–2032)
The worldwide paddle dryer market stands at a critical inflection point. Between 2020 and 2025, the sector expanded from a base of approximately 672.4 million USD to a projected 867.2 million USD in 2025, reflecting steady industrial adoption across environmental, chemical, and process-intensive sectors. Looking ahead, the forecast period from 2026 to 2032 signals a trajectory of disciplined expansion, with the Technology Diffusion Parameter (TDP) projected to reach 1,243.2 million USD by 2032. This translates to a compound annual growth rate (CAGR) of 5.28%, a figure that underscores not explosive volatility, but rather the maturation of indirect drying technologies into mainstream process engineering. For executives, procurement directors, and capital allocation strategists, this market is no longer a niche utility. It has become a strategic lever for energy optimization, regulatory compliance, and supply chain resilience.
Worldwide Paddle Dryers Market
Our latest Worldwide Paddle Dryers Market research report is designed to convert these macro-trends into executable intelligence. Rather than offering static size estimates, the analysis is structured around the operational realities that will shape 2026 corporate decisions. The following overview previews the depth of coverage, the analytical frameworks applied, and the market dynamics that demand executive attention. Certain granular splits are deliberately withheld here; accessing the full report provides the complete segmentation architecture required for regional expansion, capacity planning, and vendor evaluation.
Worldwide Paddle Dryers Market
Market Trajectory and the 2026 Decision Window
The historical arc from 2020 through 2025 reveals a market that has consistently absorbed demand from multiple end-use verticals while navigating macroeconomic pressures in raw materials and energy pricing. Revenue growth over this period was neither linear nor speculative; it was anchored by tangible process upgrades in wastewater treatment, chemical manufacturing, and food processing. The 2026 baseline of approximately 906.5 million USD marks the beginning of a forecast window where capital expenditure rationalization and sustainability mandates will intersect. Decision-makers entering 2026 must reconcile two competing realities: the need for immediate throughput and thermal efficiency improvements, and the long-term obligation to reduce energy intensity and emissions footprints.
Worldwide Paddle Dryers Market
Paddle dryers have positioned themselves as a practical response to this tension. Their indirect heat transfer architecture minimizes direct exposure to combustion or waste-heat losses, enabling operators to achieve measurable reductions in energy consumption. Industry benchmarks indicate that typical energy usage for these systems ranges from 120 to 180 kilowatt-hours per ton of material processed, delivering up to 30% savings compared to conventional direct or rotary drying approaches. For facilities operating under tight margin structures or facing rising utility costs, this efficiency differential is not marginal; it is decisive. The forecast period through 2032 will therefore be characterized by a shift from pilot-scale evaluations to full-capacity deployments, particularly in regions where regulatory tightening around emissions and wastewater residuals is accelerating.
Stratégically, the 5.28% CAGR should not be interpreted as a passive growth rate. In capital-intensive equipment markets, mid-single-digit expansion typically reflects a consolidation of best practices, a widening pool of qualified installers, and an increasing tolerance for engineered drying solutions across previously price-sensitive segments. For 2026 planning, this means the market will reward organizations that align dryer selection with process chemistry, material handling constraints, and total cost of ownership rather than upfront price alone. The report dissects these trade-offs through scenario-based assessments that model capacity utilization, maintenance cycles, and feedstock variability, enabling leadership to evaluate purchase timing, retrofit feasibility, and supplier partnerships with greater precision.
Segmentation Architecture and What It Means for Capital Allocation
A durable equipment strategy begins with a clear understanding of how demand is distributed across technology types, applications, and geographic footprints. The market segmentation framework in the report is built to expose the structural drivers behind procurement behavior, while avoiding the trap of over-indexing on any single vertical. The analysis separates the market into twin-shaft and single-shaft configurations, reflecting a fundamental divergence in mechanical design, residence time control, and material shear tolerance. Twin-shaft systems dominate the revenue share, a pattern that aligns with their broader applicability in continuous processing environments where counter-rotating agitators provide consistent indirect heat transfer and effective solids movement. Single-shaft variants, while smaller in aggregate contribution, retain strategic relevance for batch-oriented operations and specialized heat-sensitive applications where precise thermal control and vacuum integration are paramount.
Application segmentation further illuminates where process engineers are directing investment. Sludge and wastewater treatment continues to anchor demand, driven by tightening discharge standards and the push toward Class A biosolids compliance. Chemical and petrochemical processing represents a substantial secondary pillar, where paddle dryers support solvent stripping, thermal treatment, and materials handling across corrosive or toxic streams. Food and beverage processing, pharmaceutical and life sciences manufacturing, and mining and minerals complete the application matrix, each bringing distinct requirements around material purity, surface finish, sterilization, and containment. The report does not merely list these verticals; it maps them to procurement triggers such as regulatory deadlines, capacity expansions, feedstock changes, and energy cost volatility. Decision-makers can use this mapping to prioritize capital deployment and to identify which application clusters present the fastest path to operational ROI in their specific operating environment.
Geographic distribution is analyzed with the same intent. The segmentation data reveals a clear hierarchy in deployed capacity across major regions, with Pacific Asia, Europe, North America, and the Latin American and Middle Eastern/African corridors each contributing distinct volumes to the global total. Rather than treating these figures as static market shares, the report interprets them through the lens of industrial density, regulatory intensity, and local content expectations. Organizations evaluating export opportunities, local assembly strategies, or competitive positioning will find the geographic breakdown instrumental for sizing addressable demand, assessing logistical constraints, and calibrating market entry sequencing. To preserve analytical integrity, the full segmentation splits, regional sub-breakdowns, and application-level revenue compositions are provided within the complete report, where they can be cross-referenced against site-level risk factors and procurement calendars.
Competitive Landscape: Strategic Positioning and Technology Differentiators
The paddle dryer market is moderately fragmented, with a collective concentration that suggests room for both specialized niche players and cross-industry engineering groups. The top three competitors command approximately 22.15% of market revenue, while the top five extend to roughly 34.6%. This structure indicates that no single manufacturer controls the entire value chain, but a handful of engineering houses hold disproportionate influence over benchmark designs, service networks, and technology roadmaps. For procurement leaders, this means vendor selection is less about finding a single dominant supplier and more about aligning technical fit, compliance readiness, and lifecycle support with the specific process environment.
Several manufacturers have established particularly recognizable positions. Komline-Sanderson, headquartered in the United States, has built its reputation around biosolids and sludge drying solutions that produce Class A compliant outputs under EPA 503 regulations. Its dual counter-rotating agitator architecture emphasizes indirect heat transfer for municipal and industrial applications, making it a frequent reference point for wastewater authorities seeking regulatory compliance alongside throughput reliability. In Europe, ANDRITZ AG, including its Gouda lineage, offers a broad portfolio of indirect contact drying systems that support heating, cooling, reacting, solvent stripping, and related thermal operations. The Gouda platform is frequently cited for its compact footprint, enclosed design suited to toxic materials, and emphasis on energy efficiency and solvent recovery, which aligns closely with chemical, environmental, food, and pharmaceutical process requirements.
GEA Group, based in Germany, supplies paddle drying technology through its process engineering divisions, with a strong orientation toward thermal drying solutions in food, beverage, pharmaceutical, and chemical sectors. Its integration into larger process lines often positions the equipment as part of a broader unit operation strategy rather than a standalone purchase. Heinkel Drying and Separation Group, also German, maintains a recognized presence in vacuum and contact drying, specifically targeting chemical and pharmaceutical applications where controlled atmospheres and surface-sensitive materials require disciplined thermal management. Hosokawa Micron, operating from Japan with significant United States activity, contributes powder processing expertise, offering paddle dryers and related mixing systems that appeal to operators needing consistent particle handling in chemical, pharmaceutical, and food streams.
In the vacuum and specialty drying segment, several firms have carved out application-specific reputations. BACHILLER Mixing and Drying Technology in Spain produces vacuum paddle dryers, including SANIDRY and SHV series, with batch contact dryer configurations tailored to chemical and pharmaceutical operations. GMM Pfaudler, with operations spanning India and Switzerland, offers MAVAPAD vacuum paddle dryers engineered for energy-efficient drying of active pharmaceutical ingredients and pure chemistry applications, using materials such as stainless steel, Hastelloy, and special alloys to meet cGMP and FDA expectations. Kilburn Engineering, based in India and developed in technical collaboration with Nara Machinery Japan, focuses on organic and inorganic granular and powdery materials, particularly where heat-sensitive characteristics demand careful temperature control and enhanced heat transmission. Nara Machinery itself, with German operations and Japanese origins, emphasizes heat transmission drying across organic and inorganic applications, often complementing its equipment with engineered collaborations for specialized material handling.
Additional contributors round out the competitive field. Italvacuum and 3V Tech provide vacuum and process equipment solutions for pharmaceutical, chemical, and industrial drying contexts. Bepex and Yasujima maintain relevance in industrial drying and processing, while Chinese manufacturers such as Changzhou Primary Equipment, AIPAK, and Shandong Tianli Energy supply indirect conduction heating devices and blade/paddle dryer systems for paste, powder, and thermally stable materials. AS Engineers, also based in India, emphasizes durability, energy efficiency, and custom designs for food, chemical, and adjacent industries. This diverse ecosystem ensures that buyers can typically find a configuration aligned with their material properties, containment needs, and budget parameters, but it also increases the importance of disciplined specification and comparative evaluation.
Recent developments in the competitive space reinforce the market's operational tempo. In mid-2025, several manufacturers and suppliers demonstrated active engagement with end users and exhibition audiences. Changzhou Shinma Drying Engineering appeared at the 26th Healthy Natural Raw Materials and Food Ingredients Exhibition in Shanghai, highlighting hollow paddle dryer equipment and energy-saving drying solutions aimed at the healthy food industry. SINOTHERMO successfully delivered a customized vacuum paddle dryer for FEP powder processing and also participated in a 2025 environmental exhibition in Japan, showcasing paddle dryer technologies within a broader environmental solutions portfolio. These events signal that manufacturers are not only refining product lines but also aligning demonstrations and delivery timelines with near-term project pipelines. The report captures these developments not as isolated news items, but as indicators of regional market momentum, product emphasis, and the speed at which engineered solutions are moving from specification to commissioning.
Industry Dynamics Shaping 2026 Procurement and Engineering Decisions
Beyond company profiles and segmentation patterns, several structural dynamics will influence how organizations buy, install, and operate paddle dryers over the forecast horizon. One of the most consequential is equipment construction and material selection. Paddle dryers are predominantly fabricated from stainless steel grades such as 304, chosen for corrosion resistance and durability in direct contact with process materials. This baseline specification matters because material costs directly affect both capital pricing and lead times. In early 2025, global stainless steel prices for 304 cold-rolled coil in Asia hovered around 1,875 USD per tonne on a CIF East Asia basis, with pricing influenced by nickel and chromium fluctuations. Nickel, a critical alloy component, was expected to stabilize within a range of approximately 15,000 to 20,000 USD per metric ton during 2025. For procurement teams, these input dynamics create a planning environment where timing, alloy specification, and supplier inventory positions can meaningfully affect landed cost and project schedules.
Energy efficiency and process multifunctionality represent another defining dynamic. Paddle dryers are engineered to transfer heat indirectly, a design that reduces direct thermal losses and supports up to 30% energy savings relative to conventional dryer types. This efficiency profile is increasingly valuable in facilities where utility costs, carbon intensity targets, or heat recovery opportunities shape operating economics. At the same time, certain platforms extend beyond drying alone. For example, select paddle dryer systems support integrated operations such as heating, cooling, reacting, roasting, cooking, calcining, sterilizing, melting, and solvent stripping, while also enabling solvent recovery and reduced odor emissions. When a single unit can perform multiple process functions, capital efficiency improves because fewer separate pieces of equipment are required, floor space is conserved, and process continuity can be maintained with fewer transfer steps. This multifunctionality is especially attractive in chemical and environmental applications where material handling complexity, containment requirements, and regulatory scrutiny are elevated.
The broader operational context also favors indirect drying in specific scenarios. Materials that are heat-sensitive, abrasive, or prone to oxidation often benefit from the controlled thermal environment and enclosed agitation that paddle dryers provide. Vacuum-capable configurations add another layer of flexibility, lowering boiling points and enabling gentler drying profiles for pharmaceutical ingredients and specialty chemicals. These dynamics do not apply uniformly across all applications, which is precisely why the report avoids prescriptive generalizations. Instead, it structures the analysis around decision trees that match material characteristics, throughput targets, containment constraints, and utility availability to appropriate dryer architectures. This approach helps organizations avoid over-specifying or under-specifying equipment, both of which carry significant financial and operational consequences.
What the Report Delivers: Operational Intelligence for 2026 Planning
The Worldwide Paddle Dryers Market research is built to support real-world decision-making, not just high-level sizing. The document combines market estimation with practical engineering and commercial guidance, enabling readers to translate forecast data into procurement timing, capacity planning, and competitive positioning. Key components include a detailed segmentation analysis that distinguishes between dryer types, application verticals, and geographic markets; historical performance tracking for the 2020–2025 period to establish baseline momentum; and a forecast model extending through 2032 that isolates growth drivers, potential dampeners, and structural inflection points.
The competitive assessment goes beyond company names and headquarters. It examines how manufacturers differentiate through equipment architecture, material compatibility, containment options, regulatory alignment, and service coverage. This allows readers to compare suppliers on dimensions that actually affect installation success and long-term reliability. The report also integrates industry context on raw material inputs, energy consumption benchmarks, and process multifunctionality, linking these factors to total cost of ownership and project feasibility. Where relevant, recent trade activity, product deliveries, and exhibition participation are woven into the narrative to reflect near-term market sentiment and project velocity.
Importantly, the report is organized so that executives can extract actionable insights without wading through undifferentiated data. Scenario considerations address how shifts in feedstock availability, energy pricing, regulatory schedules, and regional demand intensity could alter investment timing. Procurement guidance highlights where specification precision, alloy selection, vacuum integration, and service agreements can create measurable value. Market entry and expansion considerations are framed around regional demand distribution, local content expectations, and the practical requirements of commissioning indirect drying systems in varied industrial environments. The full segmentation splits and application-level compositions are provided in the complete report to support quantitative modeling, budgeting, and regional prioritization.
Why 2026 Demands a Disciplined View of Paddle Dryer Investment
As organizations move into 2026, the paddle dryer market offers a rare combination of steady growth, maturing technology, and meaningful operational leverage. The projected 5.28% CAGR and the trajectory toward over 1.2 billion USD by 2032 suggest that indirect drying will continue gaining ground in applications where energy intensity, material sensitivity, and regulatory compliance intersect. At the same time, the moderate concentration of market revenue among leading engineering houses, combined with a broad base of specialized manufacturers, means that buyer advantage will come from rigorous specification, comparative evaluation, and alignment with long-term process goals rather than from chasing the lowest initial bid.
This report is intended to provide the intelligence required to make those choices confidently. It situates the macro outlook within the operational realities of sludge treatment, chemical processing, pharmaceutical manufacturing, food and beverage production, and minerals handling. It connects equipment design choices to energy performance, material compatibility, and process integration. It frames competitive differentiation in terms that matter to engineering and procurement teams. And it preserves the detailed segmentation and regional breakdowns for readers who need the full quantitative architecture to support capital planning, tender preparation, and market strategy.
For executives and project leaders preparing for 2026 commitments, the central message is straightforward: paddle dryer investment is no longer a purely mechanical procurement decision. It is a strategic choice about thermal efficiency, compliance readiness, process flexibility, and supply chain capability. Accessing the complete Worldwide Paddle Dryers Market research will provide the detailed data, segmentation depth, and competitive mapping necessary to align those choices with corporate objectives and to move from informed consideration to decisive action.
For detailed analysis of this topic, please visit the official page: Worldwide Paddle Dryers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Wafer Heaters Market for Semiconductor Equipment to Reach $1.52 Billion by 2032, Poised for 8.62% CAGR Led by Asia Pacific
By PW Consulting, 2026-09-02
Navigating Thermal Precision: Strategic Insights into the Worldwide Wafer Heaters for Semiconductor Equipment Market
In the high-stakes ecosystem of semiconductor manufacturing, thermal stability is not merely a technical requirement; it is a foundational determinant of yield, throughput, and ultimately, profitability. As chip architectures grow more complex and production tolerances tighten, the components responsible for managing heat within processing chambers have transitioned from commoditized accessories to critical strategic assets.
Worldwide Wafer Heaters for Semiconductor Equipment Market
PW Consulting is proud to introduce our latest comprehensive analysis, the Worldwide Wafer Heaters for Semiconductor Equipment Market report. This study is designed specifically for executive leadership, supply chain strategists, and investment analysts seeking to navigate the evolving thermal components landscape through 2032. The following overview outlines the strategic value embedded within this research, offering a preview of the market trajectory, competitive intensity, and operational dynamics that will define decision-making in 2026 and beyond.
Worldwide Wafer Heaters for Semiconductor Equipment Market
Market Trajectory and Growth Dynamics
The global demand for precision thermal solutions has demonstrated remarkable resilience and expansion over the past half-decade. Our analysis tracks the market's evolution from 2020 through the base year of 2025, projecting a detailed forecast period extending to 2032. This longitudinal view allows stakeholders to distinguish between temporary fluctuations and structural growth trends.
Worldwide Wafer Heaters for Semiconductor Equipment Market
From a macroeconomic perspective, the market has progressed from a revenue baseline of approximately 568 million USD in 2020 to a projected valuation of 849.79 million USD in 2025. This historical performance underscores the semiconductor industry's consistent investment in process optimization. Looking forward, the growth trajectory remains robust. The compound annual growth rate (CAGR) is estimated at 8.62 percent throughout the forecast period. By 2032, the market is anticipated to reach a valuation of 1,515.92 million USD.
This growth is not linear. There are subtle shifts in momentum between forecast years. For instance, the transition from 2027 to 2028 shows a moderated increase compared to the surge expected between 2029 and 2030. Such nuances are critical for capacity planning. A strategic reader will recognize that these variations often correlate with fab construction cycles and capital expenditure phases in key manufacturing hubs. Understanding these inflection points allows companies to time their inventory strategies and R&D investments more effectively than competitors who rely on generic industry news.
However, these aggregate figures only tell part of the story. The true strategic value lies in understanding the underlying drivers propelling this expansion. The market is being reshaped by a convergence of regulatory incentives, material science constraints, and geopolitical realignments.
Industry Dynamics and Operational Headwinds
Several macro-level forces are currently compressing or expanding margins within the wafer heater supply chain. Our report dissects these dynamics to provide a clear picture of risk exposure.
Regulatory Tailwinds and Regional Shifts
Policy interventions are significantly altering demand patterns. The expansion of semiconductor manufacturing capabilities in the United States, driven by legislation such as the CHIPS Act, has catalyzed domestic demand for precision thermal components. New and upgraded fabrication facilities require high-performance heating solutions to meet local production standards. This shift is not just about volume; it is about compliance and integration with domestic supply chains. Companies that can align their distribution and manufacturing footprints with these regulatory incentives are positioned to capture disproportionate market share.
Supply Chain Volatility and Material Constraints
On the supply side, the industry faces tangible constraints. High-purity aluminum nitride (AlN) ceramic, a primary material for advanced wafer heaters, faces supply chain constraints due to limited global sources of precursor materials. This exposure creates price volatility and potential disruptions that can ripple through the value chain. For procurement leaders, this means that single-source dependency is a heightened risk. The market intelligence provided in our report evaluates which suppliers have secured stable raw material pipelines and which are vulnerable to commodity fluctuations.
Lead Times and Manufacturing Innovation
Time-to-market is another critical pressure point. Lead times for complex multi-zone ceramic heater geometries in semiconductor electrostatic chucks currently range widely, impacting equipment assemblers' schedules. However, there is industry movement aimed at mitigation. Efforts using additive manufacturing are being explored to reduce these lead times significantly. Companies that adopt these advanced fabrication techniques early will gain a competitive advantage in delivery speed and customization flexibility. Our analysis benchmarks current lead time expectations against emerging manufacturing technologies.
Regulatory Compliance and Standards
Technical compliance remains a non-negotiable barrier to entry. Semiconductor equipment components including heaters must comply with stringent SEMI standards for safety, quality, particle levels (Semi F70), and bend radius (Semi E49) in high-purity gas and wafer processing applications. Adherence to these standards is not merely about certification; it is about ensuring process integrity. Our research details the compliance landscapes that key vendors navigate, highlighting the operational overhead required to maintain eligibility for top-tier equipment integration.
Geopolitical Fragmentation Risks
Beyond economics and materials, geopolitics plays an increasing role. Geopolitical tensions and export controls on advanced semiconductor equipment and components risk fragmenting global supply chains for wafer heaters and related thermal solutions. For multinational corporations, this introduces complexity in logistics and vendor selection. The report assesses how these tensions might bifurcate the market, creating distinct regional ecosystems with different pricing structures and availability profiles.
Technology Segmentation and Application Drivers
The wafer heater market is not monolithic. It is segmented by technology type, application process, and geography. While specific regional breakdowns and exact revenue splits for each segment are reserved for the full dataset, the structural composition of the market is vital for understanding where innovation is concentrated.
Type Segmentation
Ceramic wafer heaters dominate the technological landscape, driven by their thermal properties and compatibility with high-temperature processes. Metallic wafer heaters continue to hold a significant position, particularly where durability and specific thermal conductivity profiles are required. There is also a niche segment for composite and other heaters that serve specialized or emerging applications. The choice between ceramic and metallic often comes down to the specific thermal uniformity requirements and the chemical environment of the processing chamber.
Application Segmentation
In terms of process integration, Chemical Vapor Deposition (CVD) and ALD applications represent a substantial portion of the demand. These processes require precise thermal control to ensure film quality and uniformity. Etching and Ashing processes also drive significant volume, as thermal management is critical during material removal stages. Lithography and Track Processes, along with Metrology and Ion Implantation, form the remaining demand base. Each application imposes different constraints on the heater design, such as zone control, cooling integration, and response time. Understanding which application segment is growing fastest allows component manufacturers to tailor their R&D roadmaps.
Regional Dynamics
Geographically, the market is distributed across major industrial regions. Asia Pacific, North America, Europe, and the Rest of World each present unique demand profiles shaped by local fab capacity, local supply chain maturity, and regional manufacturing standards. The concentration of demand in specific regions influences logistics costs and after-sales support requirements. Our full report provides a detailed heatmap of these regional intensities, allowing strategists to identify underserved markets or oversaturated zones.
Competitive Landscape and Strategic Positioning
The market exhibits a moderate to high level of concentration. The top three companies account for a significant portion of the revenue, while the top five control an even larger share. This concentration suggests that scale and technological moats are essential for survival. Smaller players must differentiate through customization, speed, or niche application expertise to compete against the incumbents.
Key Market Participants
Our report profiles nine key companies that define the current competitive environment. Each brings a distinct value proposition to the table.
- Cast Aluminum Solutions: Based in the United States, this firm designs and manufactures custom high-uniformity pedestal heaters and wafer heaters for semiconductor chambers. They utilize cast-in aluminum 356 alloy or interference fit construction for processes including deposition, CMP, and photolithography. They support 200/300 mm wafers with exceptional uniformity up to 450°C, offering integrated sensors and SEMI-standard packaging.
- Fralock: Located in Valencia, CA, Fralock offers advanced multilayer Aluminum Nitride (AlN) ceramic wafer disc and pedestal heaters for high-temperature CVD semiconductor processing. Their solutions feature multi-zone heating, embedded RTD sensors, and patented hermetically-sealed stem-to-platen designs up to 380 mm diameter, catering to extreme thermal cycling needs.
- THERMOCOAX: Based in France, THERMOCOAX specializes in custom pedestal and chuck heaters, mineral insulated cable heaters, and full assembly thermal solutions for ALD, PVD, and CVD wafer processing in vacuum environments. They provide multi-zone heating up to 900°C with high uniformity and contamination-resistant encapsulation using custom materials including Inconel and stainless steel.
- Kyocera: A major presence from Kyoto, Japan, Kyocera produces high-purity (>99.9%) aluminum nitride (AlN) wafer heaters for semiconductor processing chambers. They leverage high thermal conductivity and plasma resistance for φ200/300 mm equipment with excellent thermal uniformity, representing a strong material science focus.
- Durex Industries: With over 45 years of experience, this US manufacturer produces custom cast-in electric heaters for semiconductor wafer processing and transistor fabrication. They are known for providing innovative thermal solutions for critical manufacturing processes, emphasizing long-term reliability.
- Watlow: Based in the United States, Watlow supplies layered heaters, precision bonded assemblies, high-performance metal sheath heaters, sensors, and controls optimized for wafer processing in semiconductor equipment. Their focus includes improving yield, throughput, and thermal performance through integrated control systems.
- ARi Industries: Headquartered in Addison, IL, ARi Industries is a US manufacturer of mineral insulated (MI) wafer heaters, heater cables, and custom heating solutions (up to 1000°C) for thin-film deposition systems including CVD, PVD, and ALD in semiconductor manufacturing.
- Tempco Electric Heater Corporation: Also based in Wood Dale, IL, Tempco produces cast-in semiconductor manufacturing heaters including pedestal heaters, bake platen heaters, and high-temperature platens with integrated cooling for wafer processing, wave solder, and reflow applications.
- Thermal Circuits: This US-based firm manufactures conductive heater assemblies and silicon wafer chuck heaters for critical etch, deposition, and plasma etch processes in semiconductor and wafer handling applications, focusing on conductive efficiency and process stability.
Competitive Dynamics
The presence of such specialized players indicates a market where technical differentiation is paramount. For example, the distinction between cast-in aluminum solutions and high-purity ceramic solutions represents a fundamental choice in thermal management strategy. Companies like Fralock and Kyocera lean heavily into ceramic capabilities for high-temperature CVD, while others like Cast Aluminum Solutions and Tempco maintain strong positions in metallic casting technologies.
THERMOCOAX and ARi Industries highlight the importance of mineral insulated solutions for high-temperature vacuum environments. Meanwhile, Watlow and Thermal Circuits emphasize integrated assemblies and control capabilities. Understanding the specific strengths of these competitors allows mid-sized suppliers to find gaps in the market—such as underserved temperature ranges or specific wafer sizes—and allows large players to assess consolidation opportunities.
Strategic Value for 2026 Decision Making
Why is this report essential for planning in 2026? The semiconductor equipment cycle is moving faster than ever. Decisions made today regarding vendor selection, capacity expansion, or technology adoption will impact production capabilities three to five years down the line.
For Procurement and Supply Chain Leaders
The data on market concentration and supplier profiles enables a risk-adjusted sourcing strategy. Knowing which companies dominate the ceramic segment versus the metallic segment helps in diversifying the supplier base. Furthermore, insights into lead times and raw material constraints allow for more accurate inventory buffering and contract negotiation.
For Product Strategy and R&D
The segmentation data highlights where the thermal demands are shifting. If CVD and ALD applications are driving the majority of growth, R&D resources should be allocated to improve uniformity and temperature limits in those specific processes. The report provides the context needed to prioritize development projects that align with market demand rather than internal assumptions.
For Investment and M&A Analysts
The growth trajectory and competitive concentration offer clarity on market consolidation potential. With a significant portion of revenue controlled by the top five players, there may be opportunities for acquisition of niche technology leaders who offer complementary capabilities, such as additive manufacturing for heater geometries or specialized sensor integration. The forecast period through 2032 provides a long-term view for valuation modeling.
Conclusion: Accessing the Full Intelligence
The Worldwide Wafer Heaters for Semiconductor Equipment Market is at a pivotal juncture. Growth is sustained by fundamental industry needs, but the path is complicated by supply chain constraints, regulatory shifts, and geopolitical tensions. Success in this environment requires more than general market awareness; it demands precise, segmented intelligence.
This overview has outlined the macro trajectory, the key industry dynamics, and the competitive players that define the landscape. However, the detailed segmentation splits, exact regional revenue distributions, and granular application-specific forecasts constitute the core strategic asset of this study. These data points are essential for building precise financial models and operational plans.
PW Consulting invites you to access the full report to unlock these detailed insights. The complete study provides the comprehensive dataset required to navigate the thermal components market with confidence, ensuring that your organization is positioned to capitalize on the growth trends projected through 2032. Do not rely on approximations when precision is the core commodity of this industry.
For detailed analysis of this topic, please visit the official page: Worldwide Wafer Heaters for Semiconductor Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Projects Worldwide RBC Processor Market to Reach 821.16 Million USD by 2032 with 6.52 Percent CAGR
By PW Consulting, 2026-09-02
Navigating the Global RBC Processor Market: Strategic Intelligence for 2026 and Beyond
The global landscape of red blood cell (RBC) processing is undergoing a period of significant transformation, driven by clinical demand, regulatory evolution, and technological advancements. As stakeholders prepare for the 2026 fiscal year, understanding the trajectory of this market is not merely an academic exercise; it is a strategic imperative. PW Consulting is proud to introduce our latest comprehensive study, the Worldwide RBC Processor Market Market Research, a definitive resource designed to empower decision-makers with actionable intelligence. This report delves into the complexities of the industry, mapping growth trajectories from the base year of 2025 through the forecast period extending to 2032. By synthesizing historical data with forward-looking projections, this analysis provides a crucial foundation for capital allocation, product development, and competitive positioning.
Worldwide RBC Processor Market
The Evolution of Market Value and Growth Trajectories
Understanding the macroeconomic context of the RBC processor market is the first step in strategic planning. The industry has demonstrated consistent resilience and expansion over the past half-decade. Historical data from 2020 through 2025 indicates a pattern of steady revenue generation, reflecting the indispensable role of blood processing technologies in modern healthcare systems. As we move into the forecast period of 2026 to 2032, the momentum is expected to accelerate, underpinned by a compound annual growth rate (CAGR) of 6.52 percent. This growth rate is not arbitrary; it is a calculated projection based on the convergence of demographic shifts, increased surgical volumes, and a heightened focus on blood safety and efficiency.
Worldwide RBC Processor Market
For context, the market value, measured in USD Millions, has seen a notable progression. Starting from a baseline in 2020, the sector expanded through 2021 and 2022, navigating global supply chain challenges while maintaining growth. By 2023, the market size reached new heights, continuing through 2024 and solidifying in 2025. Looking ahead, the forecast suggests a robust expansion curve. While specific regional disbursements and application-specific allocations are reserved for the full detailed dataset within the complete report, it is evident that the aggregate revenue is set to reach significant milestones by the end of the forecast window in 2032. This top-line growth creates opportunities for manufacturers to scale operations and for investors to identify high-potential segments within the value chain.
Worldwide RBC Processor Market
Segmenting the Opportunity: Technology and Application Dynamics
The RBC processor market is not a monolith; it is a complex ecosystem comprised of distinct technological categories and application verticals. Our research dissects these components to reveal where value is being created and where inefficiencies are being targeted for innovation. One primary axis of segmentation involves the type of processing system. The landscape includes specialized equipment designed for automated washing, cell salvage, and the critical process of deglycerolization for frozen blood products. Each system type addresses specific clinical needs, from optimizing inventory management in blood banks to supporting complex therapeutic procedures in hospital settings.
Another critical dimension is the application sector. The demand for RBC processors is distributed across various healthcare entities, each with unique procurement cycles and technical requirements. Hospitals and surgical centers represent a major force in driving volume, given the immediate need for processed blood during procedures. Blood banks operate with different criteria, focusing on storage longevity and preparation for future transfusion. Additionally, academic and research institutes contribute to the ecosystem, often piloting new protocols that eventually trickle down to clinical practice. The interplay between these segments creates a dynamic environment where technology adoption rates vary. For instance, the adoption of automated washing systems versus traditional methods can significantly impact throughput and safety profiles, influencing purchasing decisions across these different entities.
Regional Landscape and Concentration
Geography plays a pivotal role in the distribution and consumption of RBC processing technology. The market exhibits a varied density of activity across different continents. North America has historically maintained a strong position in terms of revenue contribution, reflecting advanced healthcare infrastructure and high adoption rates of automated technologies. Europe follows as another significant contributor, driven by stringent regulatory standards and robust public health systems. The Asia Pacific region presents a different set of dynamics, characterized by rapid healthcare modernization and growing populations requiring increased transfusion services.
Latin America and the Middle East and Africa also constitute parts of the global footprint, though with different scale and growth vectors. In analyzing these regional dynamics, it is important to look beyond simple revenue splits. Regulatory environments, reimbursement policies, and the prevalence of specific blood disorders all influence how these regions interact with the market. Furthermore, the market structure itself indicates a level of consolidation. The competitive landscape is shaped by a mix of established global players and emerging regional manufacturers. Concentration ratios suggest that a significant portion of the market value is captured by a few key entities, highlighting the importance of scale and technological differentiation in maintaining market share. Understanding these concentration levels is vital for new entrants assessing barriers to entry and for incumbents planning defensive or offensive strategies.
Competitive Landscape and Key Industry Players
The strength of any market analysis lies in its ability to profile the entities driving innovation and market share. The RBC processor market is dominated by several key companies that have established strong footholds through product reliability, regulatory compliance, and strategic partnerships. Among the leading organizations is Haemonetics Corporation, headquartered in Boston, Massachusetts. Haemonetics is recognized for its ACP 215 Automated Cell Processor, a system that supports automated glycerolization, deglycerolization, and washing of red blood cells. This technology is particularly vital for supporting frozen RBC processing and the storage of rare blood types in blood banks, addressing critical needs in inventory management and transfusion safety.
Terumo Blood and Cell Technologies, based in Lakewood, Colorado, is another pivotal player. Their Spectra Optia Apheresis System provides support for automated red blood cell exchange procedures, which are essential for therapeutic applications such as the management of sickle cell disease. This capability highlights the shift towards therapeutic apheresis as a growth driver within the broader processing market. Similarly, Fresenius Kabi, with operations in Bad Homburg, Germany, supplies the Amicus Separator. This system is utilized for therapeutic apheresis, including RBC exchange, and component collection, demonstrating the versatility required in modern processing equipment.
The landscape is also expanding geographically with entities like Sichuan Nigale Biotechnology Co., Ltd. from Chengdu, China. Nigale manufactures the NGL BBS 926 Blood Cell Processor and oscillator, offering capabilities for glycerolization, washing, and processing alongside compatible disposable apheresis sets. This illustrates the growing contribution of Asian manufacturers to the global supply chain, potentially influencing pricing dynamics and regional availability. Together, these companies represent the core of the competitive environment, each leveraging specific technological strengths to address different facets of RBC processing needs.
Regulatory and Technical Dynamics Shaping the Market
Regulatory frameworks and clinical guidelines heavily influence the adoption and utilization of RBC processing technologies. Recent developments underscore the importance of compliance and validation in this sector. For example, the United States Department of Defense Joint Trauma System Clinical Practice Guideline, issued in August 2024, highlights the use of the Haemonetics ACP 215 Automated Cell Processor. This system is FDA 510(k)-cleared as a closed processing system for deglycerolized red blood cells suspended in AS-3 additive solution. The guideline notes that these processed cells are approved for transfusion up to 14 days post-processing, a critical parameter for military and trauma care settings where extended storage and safety are paramount.
Furthermore, industry standards set by associations continue to evolve. In December 2025, the AABB issued Association Bulletin #25-02, addressing the status of the discontinued COBE 2991 cell processor and the validation of alternative deglycerolization protocols. This bulletin points to the necessity of transitioning to validated systems, such as the Haemonetics ACP 215, for handling frozen red cell concentrates. Such regulatory updates create immediate demand signals for replacements and upgrades within blood banks and processing facilities. Additionally, scientific literature published in early 2025 detailed protocol validations for manually glycerolized frozen red cell concentrates using closed-system processors, demonstrating reduced hemolysis. These findings reinforce the clinical value of automated systems in improving patient outcomes.
On the technical side, the underlying methodologies remain foundational. Glycerol at 40% w/v concentration is the primary cryoprotectant used in the Meryman method for freezing red blood cells prior to long-term storage at -80°C. This is followed by deglycerolization washing with hypertonic and isotonic saline solutions. Understanding these technical requirements is essential for manufacturers developing compatible equipment and consumables. The precision required in these processes drives the need for advanced automation and quality control features, which in turn fuels market innovation and differentiation among competitors.
Strategic Implications for 2026 Decision Makers
As organizations navigate the 2026 landscape, the insights provided by this market research offer several strategic advantages. For manufacturers, the forecast period presents opportunities to align product roadmaps with emerging regulatory requirements and clinical preferences. The data suggests a sustained demand for automated systems that enhance safety, reduce manual intervention, and optimize storage utilization. Understanding the concentration of the market allows companies to identify gaps where innovation can disrupt established norms or where consolidation might be advantageous.
For investors and financial analysts, the growth trajectory and segment dynamics provide indicators for valuation and risk assessment. The CAGR of 6.52 percent offers a benchmark for performance expectations, while the segmentation data helps in identifying which technology types or application sectors may offer higher growth elasticity. The regional breakdown, detailed in the full report, aids in assessing geographic risk and identifying high-potential markets for expansion. Hospital administrators and procurement officers can utilize the findings to benchmark their current equipment against industry standards, ensuring their facilities are equipped to handle evolving blood processing requirements efficiently.
Moreover, the report serves as a tool for risk mitigation. By understanding the competitive pressures and regulatory shifts, stakeholders can anticipate changes in supply chain dynamics or compliance costs. The detailed profiles of key companies provide context on the capabilities and strategies of major competitors, enabling better strategic positioning. Whether the goal is to invest in new capacity, acquire existing assets, or simply optimize current operations, having access to granular, validated data is crucial for avoiding costly missteps.
Accessing Comprehensive Intelligence
This overview provides a snapshot of the strategic landscape surrounding the Worldwide RBC Processor Market. However, the full depth of analysis available in the complete PW Consulting report goes much further. The complete study includes exhaustive data tables, detailed segmentation breakdowns by region, type, and application, and specific case studies that illustrate real-world implementation challenges and solutions. It offers a level of granularity that allows stakeholders to model scenarios and test hypotheses with confidence.
To leverage the full strategic value of this research for your 2026 planning cycles, we invite you to access the complete report through our source webpage. There you will find the comprehensive dataset, including the specific revenue figures, detailed market concentration analysis, and the full scope of recent industry developments that shape this dynamic sector. Equip your organization with the precise intelligence needed to navigate the complexities of the global RBC processor market and capitalize on the opportunities ahead.
For detailed analysis of this topic, please visit the official page: Worldwide RBC Processor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Kraftliner Market to Reach USD 63,417.35 Million by 2032 Growing at 4.3 CAGR
By PW Consulting, 2026-09-02
Strategic Imperatives in the Global Kraftliner Market: A 2026 Decision-Maker's Guide
The worldwide kraftliner market stands at a critical inflection point as the industry moves through 2026. Driven by accelerating demand for sustainable packaging, shifting trade dynamics, and significant capacity adjustments across key regions, the sector presents both substantial opportunities and complex challenges for stakeholders. Understanding the nuanced interplay of macroeconomic trends, competitive maneuvers, and raw material volatility is no longer optional—it is a strategic imperative for executives navigating the corrugated packaging value chain. PW Consulting's latest Worldwide Kraftliner Market study provides the comprehensive intelligence required to make informed decisions in this evolving landscape.
Worldwide Kraftliner Market
This analysis is designed to equip leadership teams with a clear view of the market's trajectory from the base year of 2025 through the forecast period extending to 2032. By synthesizing historical performance data with forward-looking indicators, this report serves as an essential tool for capital allocation, supply chain optimization, and competitive positioning.
Worldwide Kraftliner Market
Market Trajectory and Growth Dynamics
The kraftliner market has demonstrated resilience and steady expansion over the past half-decade. Historical data from 2020 to 2025 reveals a market that has navigated economic fluctuations while maintaining a positive growth curve. In 2020, the global market generated revenue of approximately 38.45 billion USD. This figure climbed to 40.59 billion USD in 2021 and reached 42.83 billion USD in 2022. Although a transient contraction was observed in 2023 with revenue at 42.34 billion USD, the market swiftly rebounded, surpassing previous highs to achieve 46.49 billion USD in 2024. By the base year of 2025, the market solidified its position at 47.23 billion USD.
Worldwide Kraftliner Market
Looking ahead, the forecast period from 2026 to 2032 projects sustained expansion. Starting at an estimated 48.67 billion USD in 2026, the market is anticipated to grow consistently, reaching 52.69 billion USD by 2027 and 53.65 billion USD by 2028. Growth continues as the market approaches the end of the forecast window, with valuations expected to hit 53.71 billion USD in 2029, rise to 57.72 billion USD in 2030, and further accelerate to 61.79 billion USD in 2031, ultimately reaching 63.42 billion USD in 2032. This trajectory reflects a Compound Annual Growth Rate (CAGR) of 4.3 percent over the forecast period. Such steady growth underscores the fundamental demand drivers embedded in global packaging needs, particularly as industries pivot away from single-use plastics and toward renewable fiber-based solutions.
It is important to note that while the aggregate growth story is robust, performance varies significantly across different dimensions of the market. Our full report dissects these variations with granular precision, offering insights into how specific segments contribute to the overall revenue pool. Decision-makers relying on top-line figures alone risk missing critical nuances in regional demand shifts or application-specific growth pockets that can define competitive advantage.
Structural Composition and Segment Opportunities
The market structure is defined by distinct classifications that influence pricing power, production strategies, and end-user engagement. One primary dimension of analysis involves the type of kraftliner produced. The market encompasses unbleached kraftliner, white-top kraftliner, and coated kraftliner. Each variant serves different functional requirements and command different value propositions within the supply chain. Unbleached grades remain a cornerstone for high-strength applications, while white-top and coated varieties cater to premium branding and specific barrier needs. Understanding the relative market share and growth potential of each type is crucial for mills deciding on production mixes and for converters seeking cost-effective material sourcing.
Geographically, the market exhibits diverse maturity levels and growth rates. Key regions including Asia Pacific, North America, Europe, Latin America, and the Middle East and Africa collectively drive global volume. Asia Pacific represents a significant portion of market activity, reflecting the region's manufacturing intensity and consumption patterns. North America and Europe remain vital markets characterized by established infrastructure and stringent sustainability mandates. Latin America and the Middle East and Africa offer emerging opportunities, often linked to local resource availability and developing logistics networks. Navigating these regional landscapes requires a sophisticated understanding of local trade policies, logistical constraints, and customer preferences. Our study provides a detailed breakdown of regional dynamics, enabling clients to identify where to expand, consolidate, or optimize their footprint.
Application segmentation further illuminates demand drivers. Major sectors utilizing kraftliner include food and beverages, e-commerce and logistics, industrial and heavy duty applications, consumer goods, and agricultural produce. The food and beverage sector continues to be a dominant force, driven by safety regulations and the need for protective packaging. E-commerce and logistics represent a rapidly evolving segment, where the surge in online retail necessitates durable yet sustainable shipping solutions. Industrial and heavy duty applications rely on the strength characteristics of kraftliner, while consumer goods and agricultural produce sectors utilize the material for specific handling and preservation requirements. Each application vertical faces unique regulatory and economic pressures that impact volume and specification requirements. The report delves into these application-specific trends, helping stakeholders align their product offerings with the most promising end markets.
Competitive Landscape and Strategic Positioning
The global kraftliner market is characterized by a moderately concentrated competitive environment. While large multinational players hold significant sway, the market structure allows for regional specialists and integrated producers to compete effectively. Our analysis indicates a CR3 of 18.4 percent and a CR5 of 28.5 percent, suggesting that while top-tier companies are influential, the market remains fragmented enough for diverse strategic plays. This structure encourages innovation and regional responsiveness but also demands sharp competitive intelligence to anticipate moves by key incumbents.
Several major corporations shape the industry's direction. International Paper, headquartered in Memphis, Tennessee, stands as a major global producer of virgin kraftliner and containerboard. Their extensive production capacity in North America and internationally focuses heavily on high-strength unbleached kraft linerboard, positioning them as a critical supplier for robust packaging solutions. Similarly, Smurfit WestRock, with headquarters in Dublin and Atlanta, has emerged as a leading integrated producer following its 2024 merger. Operating large-scale virgin and recycled fiber mills across Europe and North America, they are a key force in sustainable packaging solutions.
In Europe, Mondi Group, based in London, maintains a significant presence with investments in containerboard mills, including notable upgrades at their Świecie facility in Poland. These investments offer high-performance virgin and recycled kraftliner grades tailored for corrugated applications. SCA, the Sweden-based independent producer, is a leader in Europe using Nordic fresh fiber. Their major capacity at the Obbola mill, ramping towards 725 kt/year, focuses on high-quality renewable kraftliner for packaging, reinforcing their position as a top independent producer in the region.
North American dynamics are also shaped by Georgia-Pacific LLC, a large-scale manufacturer supplying unbleached grades with substantial production capacity. DS Smith Plc, another London-based entity, plays a key role in recycled and virgin containerboard, integrating kraftliner production with corrugated packaging operations across multiple countries. In the Nordic region, Stora Enso Oyj and UPM-Kymmene Corporation from Helsinki emphasize renewable packaging materials and Nordic fiber resources respectively, catering to global markets with sustainable alternatives. Metsä Board, also from Finland, produces high-quality kraftliner with capacity increases, including at their Kemi mill, targeting premium packaging applications.
On the other side of the globe, Nine Dragons Paper Holdings Limited, based in Hong Kong and China, is a major Asian producer with significant capacity focused on both domestic and export markets. Klabin S.A. in São Paulo, Brazil, leads in Latin America, utilizing eucalyptus and pine fibers for high-strength packaging grades. In the United States, Packaging Corporation of America (PCA), located in Lake Forest, Illinois, is a major producer supplying unbleached grades, with a recent focus on price realization. Sappi Limited, headquartered in Johannesburg, South Africa, manufactures specialty and packaging papers including kraftliner grades for global markets, adding to the diverse supplier base.
Understanding the strategic positioning of these companies is vital. Our report analyzes their historical performance, capacity expansions, and regional strengths to provide a map of the competitive terrain. This allows clients to benchmark their own strategies and identify potential partnership or acquisition opportunities.
Industry Dynamics and Operational Realities
The operational environment for kraftliner producers and consumers is influenced by a variety of real-time factors ranging from raw material costs to regulatory shifts and capacity adjustments. Raw material pricing remains a primary concern for margin management. Kraft pulp prices, a critical feedstock for virgin kraftliner, stood at approximately 5,038 to 5,040 CNY per ton in late April 2026, showing recent monthly declines amid evolving supply dynamics. This volatility requires producers to maintain agile procurement strategies.
In the Nordic region, pulpwood prices have fallen around 20 percent from peak levels in Q2 2025, with further decreases expected in 2026 due to improved wood availability from storms. This reduction in input costs could alleviate pressure on European producers, potentially influencing pricing strategies and margin recovery. Meanwhile, in the United States, Northern bleached softwood kraft pulp (NBSK) prices were assessed around 1,590 USD per ton in March 2026, reflecting ongoing volatility in softwood fiber costs that are critical for premium kraftliner production. These disparities in regional raw material costs create distinct competitive advantages for mills located in different geographies.
Capacity changes are also reshaping the supply landscape. The US containerboard industry experienced significant capacity closures in 2025, including nearly 1.9 million tons from key kraftliner mills. These closures have impacted supply and pricing dynamics, potentially tightening availability in certain market pockets. Conversely, strategic expansions continue elsewhere. Mondi completed a 95 million Euro investment at their Świecie containerboard mill in Poland in October 2024, increasing Kraftliner production capacity by 55,000 tonnes per annum with quality and sustainability upgrades. Additionally, SCA is ramping up output on the Obbola kraftliner machine as planned, positioning itself as the number one independent producer in Europe with a strong Nordic fresh fiber focus. There is also industry interest in capacity conversion, such as Norske Skog examining the conversion of PM6 at Saugbrugs for kraftliner production to strengthen their packaging focus.
Trade flows and regulatory environments add further complexity. US kraftliner exports to China dropped sharply due to tariffs, with May 2025 shipments at only 4,000 tonnes compared to prior monthly averages of 45,000 tonnes. This disruption forces a reevaluation of export strategies and regional supply balances. Furthermore, corporate pricing actions signal market confidence and cost pass-through capabilities. For instance, SCA announced a 100 Euro per tonne price increase on all Kraftliner grades in Europe, effective April 1, 2026, reflecting their focus on high-quality renewable products.
These dynamics highlight the need for continuous monitoring. A static view of the market is insufficient when raw material indices, capacity announcements, and trade policies shift frequently. Our report captures these moving parts, providing context on how they interact to influence market equilibrium.
Methodological Rigor and Actionable Intelligence
PW Consulting's Worldwide Kraftliner Market research is built on a foundation of rigorous methodology designed to deliver actionable intelligence. The study goes beyond high-level summaries to provide detailed segmentation analysis across region, type, and application. For each segment, the report examines historical performance, current market status, and future growth potential. This granularity allows businesses to pinpoint exactly where their products fit and how those segments are likely to evolve.
The competitive landscape section offers in-depth profiles of key companies, analyzing their product portfolios, capacity footprints, recent developments, and strategic moves. By understanding the strengths and weaknesses of competitors, clients can identify gaps in the market or areas for differentiation. The report also tracks recent developments, such as price announcements, capacity expansions, and project evaluations, ensuring that the intelligence remains current and relevant for immediate decision-making.
Our approach integrates macroeconomic indicators with industry-specific data points. This ensures that forecasts are grounded in both broader economic realities and the specific technical and operational nuances of the kraftliner market. For example, the analysis considers how raw material price trends correlate with regional capacity changes and how regulatory pressures in specific regions might alter demand patterns. This holistic view reduces the risk of strategic blind spots.
The report is structured to address the specific questions that executives face. Which regions offer the best growth potential relative to risk? How should procurement strategies adapt to raw material volatility? What are the implications of competitor capacity expansions on local pricing power? By answering these questions with data-backed insights, the study serves as a decision-support tool that can be directly integrated into strategic planning processes.
Strategic Roadmap for 2026 and Beyond
As we navigate through 2026, the kraftliner market offers a landscape rich with opportunity for those equipped with the right intelligence. The projected growth to 63.42 billion USD by 2032 indicates that demand will continue to expand, driven by the structural shift towards sustainable packaging and the enduring need for reliable containerboard. However, realizing value in this market requires more than passive participation. It demands proactive strategy formulation based on a deep understanding of segment dynamics, competitive pressures, and operational variables.
For producers, the focus must be on optimizing capacity utilization, managing raw material exposure, and differentiating through quality and sustainability credentials. The ability to navigate price volatility and respond to capacity shifts, such as the closures in the US or expansions in Europe and Asia, will define profitability. For converters and end-users, securing stable supply chains and locking in competitive pricing will be critical, especially as regional disparities in supply and demand widen. Understanding where capacity is coming online and where it is retiring allows for better sourcing strategies and risk mitigation.
Investors and stakeholders also benefit from a clear view of market concentration and growth vectors. Knowing that the market is moderately concentrated with a CR5 of 28.5 percent helps in assessing the potential for consolidation or the viability of new entrants. Identifying high-growth applications like e-commerce and logistics versus mature segments allows for targeted capital deployment. Regional insights enable strategies that leverage local advantages while hedging against regional downturns.
PW Consulting's Worldwide Kraftliner Market study provides the foundational knowledge necessary to execute these strategies. By offering a detailed view of the market from 2020 through 2032, including the critical base year of 2025 and the forecast period, we enable clients to plan with confidence. The report's comprehensive coverage of trends, drivers, challenges, and competitive moves ensures that no critical factor is overlooked.
To fully leverage these insights and access the complete dataset, detailed segmentation analysis, and exhaustive competitor profiles, we invite you to explore the full report. The depth of information available in the complete study is designed to transform market understanding into strategic action, ensuring your organization is well-positioned to capitalize on the opportunities within the global kraftliner market.
For detailed analysis of this topic, please visit the official page: Worldwide Kraftliner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


